{Regarding the recognition of a separate provision of the second paragraph of subparagraph 14.1.212 of paragraph 14.1 of Article 14 as amended by Law No. 71-VIII of December 28, 2014, namely: “goods specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code”, as not complying with the Constitution of Ukraine (is unconstitutional), see Decision of the Constitutional Court No. 3-р(II)/2025 of January 21, 2025 }
{Regarding the recognition of individual provisions as constitutional, see Decision of the Constitutional Court No. 5-р(II)/2025 of 26.11.2025 }
{As amended by Laws No. 4835-IX of 07.04.2026 No. 4894-IX dated 28.05.2026 3 No. 4967-IX dated 03.09.2026 }
{In the text of the Code:
the words "central body of the state tax service", "central body of the state tax service of Ukraine" in all cases are replaced by the words "central body of executive power, ensuring the formation of state financial policy" in the corresponding case;
the words "Ministry of Finance of Ukraine" in all cases are replaced with the words "central executive body that ensures the formation of state financial policy" in the corresponding case;
the words "body of the State Treasury of Ukraine", "body of the State Treasury" in all cases and numbers are replaced by the words "body that carries out treasury services of budget funds" in the corresponding case and number;
the words "state customs service body" in all cases are replaced by the words "customs body" in the corresponding case;
the words "specially authorized central executive body in the field of customs affairs" in all cases are replaced by the words "central executive body implementing state policy in the field of customs affairs" in the corresponding case;
the words "central executive body that ensures the implementation of state economic policy" in all cases are replaced by the words "central executive body that ensures the formation of state policy in the field of economic development" in the corresponding case;
the words "central executive body for land resources" in all cases and numbers are replaced by the words "central executive body implementing state policy in the field of land relations" in the corresponding case and number in accordance with Law No. 5083-VI of 05.07.2012 }
{In the text of the Code:
the words "in the state tax service body" in all cases and numbers are replaced by the words "in the controlling body" in the corresponding case and number, and the words "state tax service body, customs body", "state tax service body", "tax service body", "tax body", "state tax service", "customs body" in all cases and numbers - by the words "controlling body" in the corresponding case and number;
the words "central executive body implementing state tax policy and central executive body implementing state policy in the field of customs affairs", "central executive body implementing state tax policy", "central executive body ensuring the formation of state financial policy", "central executive body implementing state policy in the field of customs affairs" in all cases are replaced by the words "central executive body ensuring the formation and implementation of state tax and customs policy" in the corresponding case;
the words "taxes, fees (mandatory payments)" in all cases and numbers are replaced by the words "taxes, fees, payments" in the corresponding case and number in accordance with Law No. 404-VII of 04.07.2013 }
{In the text of the Code, the words "disabled person", "disabled child", "public organizations of disabled people" in all cases and numbers are replaced, respectively, by the words "person with a disability", "child with a disability", "public associations of disabled people" in the corresponding case and number in accordance with Law No. 344-IX of 05.12.2019 }
{In the text of the Code, except for Section XVIII - 2 "Tax Police", the words "central executive body that ensures the formation and implementation of state tax and customs policy" in all cases are replaced by the words "central executive body that ensures the formation and implementation of state financial policy" in the corresponding case;
the words "central executive body implementing state tax and customs policy", "central executive body implementing state tax and customs policy" in all cases are replaced by the words "central executive body implementing state tax policy" in the corresponding case in accordance with Law No. 466-IX of January 16, 2020 }
{In the text of the Code, the words "councils of united territorial communities established in accordance with the law and the perspective plan for the formation of community territories", "and councils of united territorial communities established in accordance with the law and the perspective plan for the formation of community territories", "or councils of united territorial communities established in accordance with the law and the perspective plan for the formation of community territories" in all cases and numbers are excluded in accordance with the Law No. 2330-IX dated 06/21/2022 }
{In the text of the Code, the words "taxpayer registration card registration number or series and passport number" in all cases and numbers are replaced by the words "taxpayer registration card registration number or series (if any) and passport number" in the corresponding case and number in accordance with Law No. 2888-IX of 12.01.2023 }
{In the text of the Code, the words "in the territories temporarily occupied by the armed formations of the Russian Federation" are replaced by the words "in the territories of Ukraine temporarily occupied by the Russian Federation" in accordance with Law No. 3050-IX of 11.04.2023 }
{In the text of the Code, the words "Laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Trust Services" in all cases are replaced by the words "Laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" in the corresponding case in accordance with Law No. 2918-IX of 07.02.2023 }
{In the text of the Code, the words "The Law of Ukraine "On State Regulation of the Production and Circulation of Ethyl Alcohol, Cognac and Fruit Alcohol, Alcoholic Beverages, Tobacco Products, Liquids Used in Electronic Cigarettes, and Fuel" are replaced with the words "The Law of Ukraine "On State Regulation of the Production and Circulation of Ethyl Alcohol, Alcoholic Distillates, Alcoholic Beverages, Tobacco Products, Liquids Used in Electronic Cigarettes, and Fuel" in accordance with Law No. 3193-IX of 29.06.2023 }
{In the text of the Code, the words "rehabilitation institution" in all cases and numbers are replaced by the words "rehabilitation institution" in the corresponding case and number in accordance with Law No. 3553-IX of 16.01.2024 }
{In the text of the Code, the word "whole" in all cases and numbers is replaced by the word "single" in the corresponding case and number in accordance with Law No. 3813-IX of 18.06.2024 }
1.1. The Tax Code of Ukraine regulates relations arising in the field of collection of taxes and fees, in particular, it determines an exhaustive list of taxes and fees collected in Ukraine and the procedure for their administration, taxpayers of taxes and fees, their rights and obligations, the competence of regulatory authorities, the powers and obligations of their officials during the administration of taxes and fees, as well as liability for violation of tax legislation.
{Paragraph one of clause 1.1 of Article 1 as amended by Law No. 466-IX of January 16, 2020 }
This Code defines the functions and legal basis for the activities of the supervisory bodies specified in paragraph 41.1 of Article 41 of this Code, and the central executive body that ensures the formation and implementation of state financial policy.
{Clause 1.1 of Article 1 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 , No. 721-VII of 16.01.2014 - expired on the basis of Law No. 732-VII of 28.01.2014 ; as amended by Law No. 767-VII of 23.02.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
1.2. The rules for taxation of goods moving across the customs border of Ukraine are determined by this Code, except for the rules for taxation of goods with customs duties, which are established by the Customs Code of Ukraine and other laws on customs matters.
{Clause 1.2 of Article 1 as amended by Law No. 4915-VI of 07.06.2012 }
1.3. This Code does not regulate the issue of repayment of tax liabilities or collection of tax debt from persons subject to judicial procedures defined by the Code of Ukraine on Bankruptcy Procedures , from banks subject to the provisions of the Law of Ukraine "On the System of Guaranteeing Deposits of Individuals" , conducting comprehensive audits to identify financial accounts and repay obligations to pay a single contribution to mandatory state social insurance (except for the specifics of the functioning of a single account, reporting on the amount of the accrued single contribution), fees for mandatory state pension insurance from certain types of business transactions.
{Clause 1.3 of Article 1 as amended by Laws No. 404-VII of 04.07.2013 , No. 1200-VII of 10.04.2014 , No. 190-IX of 04.10.2019 , No. 323-IX of 03.12.2019 , No. 466-IX of 16.01.2020 }
1.4. Establishment and cancellation of fees for mandatory state pension insurance for certain types of economic transactions, their amounts and collection mechanisms are carried out in accordance with the Law of Ukraine "On the Fee for Mandatory State Pension Insurance".
{Article 1 is supplemented by paragraph 1.4 in accordance with Law No. 1200-VII of 10.04.2014 }
3.1. The tax legislation of Ukraine consists of the Constitution of Ukraine ; this Code; the Customs Code of Ukraine and other laws on customs matters in terms of regulating legal relations arising in connection with the taxation of customs operations on the movement of goods across the customs border of Ukraine (hereinafter referred to as the laws on customs matters); effective international treaties, the binding consent of which has been granted by the Verkhovna Rada of Ukraine and which regulate taxation issues; regulatory legal acts adopted on the basis of and in implementation of this Code and laws on customs matters; decisions of the Verkhovna Rada of the Autonomous Republic of Crimea, local self-government bodies on local taxes and fees, adopted in accordance with the rules established by this Code.
{Clause 3.1 of Article 3 as amended by Law No. 4915-VI of 07.06.2012 }
3.2. If an international treaty, the binding consent of which has been granted by the Verkhovna Rada of Ukraine, establishes rules other than those provided for in this Code, the rules of the international treaty shall apply.
3.3. The procedure for administering taxes, fees, customs payments, a single contribution to mandatory state social insurance (hereinafter referred to as the single contribution) and other payments in accordance with the legislation, the control over compliance with which is entrusted to the regulatory authorities, is determined exclusively by tax legislation, legislation on the collection and accounting of the single contribution.
{Article 3 is supplemented by paragraph 3.3 in accordance with Law No. 3813-IX of 18.06.2024 }
Article 4. Basic principles of tax legislation of Ukraine↑
4.1. The tax legislation of Ukraine is based on the following principles:
4.1.1. universality of taxation - each person is obliged to pay taxes and fees established by this Code, laws on customs matters, the payer of which he is in accordance with the provisions of this Code;
4.1.2. equality of all taxpayers before the law, prevention of any manifestations of tax discrimination - ensuring the same approach to all taxpayers regardless of social, racial, national, religious affiliation, form of ownership of a legal entity, citizenship of an individual, place of origin of capital;
4.1.3. the inevitability of the occurrence of liability defined by law in the event of a violation of tax legislation;
4.1.4. presumption of legality of taxpayer decisions in the event that a provision of a law or other regulatory legal act issued on the basis of a law, or if the provisions of different laws or different regulatory legal acts imply an ambiguous (multiple) interpretation of the rights and obligations of taxpayers or regulatory authorities, as a result of which there is an opportunity to make a decision in favor of both the taxpayer and the regulatory authority;
4.1.5. fiscal sufficiency - the establishment of taxes and fees taking into account the need to achieve a balance between budget expenditures and revenues;
4.1.6. social justice - setting taxes and fees in accordance with the ability of taxpayers to pay;
4.1.7. efficiency of taxation - the establishment of taxes and fees, the volume of revenues from the payment of which to the budget significantly exceeds the costs of their administration;
4.1.8. neutrality of taxation - the establishment of taxes and fees in a manner that does not affect the increase or decrease in the competitiveness of the taxpayer;
4.1.9. stability - changes to any elements of taxes and fees cannot be made later than six months before the beginning of the new budget period in which the new rules and rates will be in effect. Taxes and fees, their rates, as well as tax benefits cannot be changed during the budget year;
4.1.10. uniformity and convenience of payment - establishing deadlines for paying taxes and fees, based on the need to ensure timely receipt of funds to budgets for budget expenditures and the convenience of their payment by payers;
4.1.11. a unified approach to establishing taxes and fees - determining at the legislative level all mandatory elements of the tax.
4.2. National, local taxes and fees, the collection of which is not provided for by this Code, are not subject to payment.
4.3. Tax periods and deadlines for paying taxes and fees are established based on the need to ensure timely receipt of funds to budgets, taking into account the convenience of fulfilling the tax obligation by the payer and reducing the costs of administering taxes and fees.
4.4. The establishment and abolition of taxes and fees, as well as benefits for their payers, are carried out in accordance with this Code by the Verkhovna Rada of Ukraine, as well as the Verkhovna Rada of the Autonomous Republic of Crimea, village, settlement, and city councils within the limits of their powers determined by the Constitution of Ukraine and the laws of Ukraine.
{Clause 4.4 of Article 4 as amended by Law No. 909-VIII of 12/24/2015 }
4.5. When establishing or expanding existing tax benefits, such benefits shall apply from the following budget year.
{Article 4 is supplemented by paragraph 4.5 in accordance with Law No. 5503-VI of 20.11.2012 }
Article 5. Correlation of tax legislation with other legislative acts↑
5.1. The concepts, rules and provisions established by this Code and the laws on customs matters shall apply exclusively to the regulation of relations provided for in Article 1 of this Code.
5.2. If the concepts, terms, rules and provisions of other acts contradict the concepts, terms, rules and provisions of this Code, the concepts, terms, rules and provisions of this Code shall apply to regulate taxation relations.
5.3. Other terms used in this Code and not defined herein shall be used in the meaning established by other laws.
6.1. A tax is a mandatory, unconditional payment to the relevant budget or to a single account, levied on taxpayers in accordance with this Code.
{Clause 6.1 of Article 6 as amended by Law No. 190-IX of 04.10.2019 }
6.2. A fee (charge, contribution) is a mandatory payment to the relevant budget or to a single account, levied on fee payers, with the condition that they receive a special benefit, including as a result of legally significant actions taken in favor of such persons by state bodies, local self-government bodies, other authorized bodies and persons.
{Clause 6.2 of Article 6 as amended by Law No. 190-IX of 04.10.2019 }
6.3. The totality of national and local taxes and fees collected in accordance with the procedure established by this Code constitutes the tax system of Ukraine.
Article 7. General principles of establishing taxes and fees↑
7.1. When setting a tax, the following elements must be determined:
7.1.1. taxpayers;
7.1.2. object of taxation;
7.1.3. tax base;
7.1.4. tax rate;
7.1.5. procedure for calculating tax;
7.1.6. tax period;
7.1.7. deadline and procedure for paying tax;
7.1.8. deadline and procedure for submitting reports on tax calculation and payment.
7.2. When establishing a tax, tax benefits and the procedure for their application may be provided for.
7.3. Any issues related to taxation are regulated by this Code and cannot be established or changed by other laws of Ukraine, except for laws that contain exclusively provisions on amendments to this Code and/or provisions that establish liability for violation of tax legislation.
7.4. The elements of the tax defined in paragraph 7.1 of this article, the grounds for granting tax benefits and the procedure for their application are determined exclusively by this Code.
8.1. In Ukraine, national and local taxes and fees are established.
8.2. National taxes and fees include those established by this Code and mandatory for payment throughout the territory of Ukraine, except for cases provided for by this Code.
8.3. Local taxes include taxes and fees that are established in accordance with the list and within the limits of the rates determined by this Code, by decisions of village, settlement, and city councils within the limits of their powers and are mandatory for payment on the territory of the relevant territorial communities.
{Clause 8.3 of Article 8 as amended by Laws No. 71-VIII of 12/28/2014 , No. 909-VIII of 12/24/2015 }
{Clause 9.1 of Article 9 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 71-VIII of 12/28/2014 }
9.2. Relations related to the establishment and collection of customs duties are regulated by customs legislation, unless otherwise provided for by this Code.
9.3. The transfer of national taxes and fees to the state and local budgets is carried out in accordance with the Budget Code of Ukraine .
9.4. The establishment of national taxes and fees not provided for by this Code is prohibited.
10.2 - 1. Local councils must establish a single tax and property tax (in terms of transport tax and land tax, except for land tax for forest lands).
{Clause 10 of Article 10 as amended by Law No. 2628-VIII of 11/23/2018 }
10.3. Local councils, within the powers defined by this Code, resolve issues in accordance with the requirements of this Code regarding the establishment of property tax (in terms of tax on real estate other than land) and the establishment of fees for parking spaces for vehicles, tourist tax and land tax for forest lands.
{Clause 10.3 of Article 10 as amended by Law No. 2628-VIII of 23.11.2018 }
10.4. The establishment of local taxes and fees not provided for by this Code is prohibited.
10.5. Local taxes and fees are credited to the relevant local budgets in accordance with the Budget Code of Ukraine .
{Article 10 as amended by Law No. 71-VIII of 28.12.2014 }
11.1. Special tax regimes are established and applied in cases and in accordance with the procedure determined exclusively by this Code.
11.2. Special tax regime - a system of measures that determines a special procedure for taxation of certain categories of business entities.
11.3. A special tax regime may provide for a special procedure for determining tax and fee elements, exemption from payment of certain taxes and fees.
11.4. Tax regimes not defined as such by this Code shall not be recognized as special regimes.
Article 12. Powers of the Verkhovna Rada of Ukraine, the Verkhovna Rada of the Autonomous Republic of Crimea, village, settlement, city councils regarding taxes and fees↑
{Title of Article 12 as amended by Law No. 909-VIII of 12/24/2015 }
12.1. The Verkhovna Rada of Ukraine establishes nationwide taxes and fees on the territory of Ukraine and determines:
12.1.1. list of state taxes and fees;
12.1.2. a list of local taxes and fees, the establishment of which falls within the competence of village, settlement, and city councils;
{Subclause 12.1.2 of Clause 12.1 of Article 12 as amended by Law No. 909-VIII of 24.12.2015 }
12.1.3. provisions specified in paragraphs 7.1 , 7.2 of Article 7 of this Code regarding state taxes and fees;
12.1.4. provisions specified in paragraphs 7.1, 7.2 of Article 7 of this Code regarding local taxes and fees.
12.2. The powers of the Supreme Council of the Autonomous Republic of Crimea include:
12.2.1. establishment on the territory of the Autonomous Republic of Crimea of a rental fee for the use of subsoil for the extraction of minerals (except for the rental fee for the use of subsoil for the extraction of minerals of national importance), a rental fee for the use of subsoil for purposes not related to the extraction of minerals, within the limits of their maximum rates determined by this Code;
{Subclause 12.2.1 of clause 12.2 of Article 12 as amended by Law No. 71-VIII of 28.12.2014 }
12.2.2. change in the amount of rental rates provided for in subparagraph 12.2.1 of this paragraph, within the limits of its maximum rates determined by this Code, in the manner established by this Code;
{Subclause 12.2.2 of Clause 12.2 of Article 12 as amended by Law No. 71-VIII of 28.12.2014 }
12.2.3. determining the amount and granting additional tax benefits within the limits of the amounts received by the budget of the Autonomous Republic of Crimea in accordance with Article 69 of the Budget Code of Ukraine .
12.3. Village, town, and city councils, within the limits of their powers, shall make decisions on the establishment of local taxes and fees and tax benefits for the payment of local taxes and fees by July 15 of the year preceding the budget period in which the established local taxes and/or fees are planned to be applied, and on amendments to such decisions.
{Paragraph one of clause 12.3 of Article 12 as amended by Laws No. 909-VIII of 12/24/2015 , No. 466-IX of 01/16/2020 }
For the period of martial law or a state of emergency in Ukraine in territories where the relevant village, settlement, and city councils temporarily do not exercise their powers, decisions on establishing local taxes and/or fees and/or granting tax benefits for paying local taxes and/or fees shall be made by the relevant military administrations and military-civilian administrations in accordance with the procedure provided for by this Code for village, settlement, and city councils.
{Clause 12.3 of Article 12 is supplemented with a new paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
The decision of the bodies specified in part three of Article 33 of the Civil Protection Code of Ukraine (except for heads of business entities) on the mandatory evacuation of the population is the basis for the mandatory adoption by the relevant local government body or military administration or military-civilian administration (in territories where the relevant village, settlement, city councils temporarily do not exercise their powers) within the territories for which the decision on the mandatory evacuation of the population has been made, of decisions on the establishment of tax benefits for the payment of land fees (land tax and rent for land plots of state and municipal ownership) and tax on real estate other than land plots for individuals and legal entities.
{Clause 12.3 of Article 12 is supplemented with a new paragraph in accordance with Law No. 3603-IX of 02/23/2024 ; with amendments made in accordance with Law No. 3706-IX of 05/09/2024 - the norms apply from 03/16/2024 }
The requirements of subparagraph 4.1.9 of paragraph 4.1 and paragraph 4.5 of Article 4, subparagraphs 12.3.3 , 12.3.4 and 12.3.7 of paragraph 12.3, subparagraph 12.4.3 of paragraph 12.4 and paragraph 12.5 of Article 12 of this Code, the laws of Ukraine "On the principles of state regulatory policy in the sphere of economic activity" , "On state aid to economic entities" and part four of Article 15 of the Law of Ukraine "On access to public information" do not apply to such decisions of local self-government bodies, military administrations or military-civilian administrations and/ or decisions on amendments to such decisions.
{Clause 12.3 of Article 12 is supplemented with a new paragraph in accordance with Law No. 3603-IX of 23.02.2024 }
Local self-government bodies, military administrations or military-civilian administrations are obliged to submit to the supervisory authorities at the location of land plots, land shares (shares), residential and/or non-residential real estate, as of the first day of the relevant quarter, information on decisions on establishing tax benefits for payment of land (land tax and rent for land plots of state and municipal property) and real estate tax other than land plots, for individuals and legal entities, adopted on the basis of decisions of the bodies specified in part three of Article 33 of the Civil Protection Code of Ukraine (except for heads of business entities), on mandatory evacuation of the population.
{Clause 12.3 of Article 12 is supplemented with a new paragraph in accordance with Law No. 3603-IX of 02/23/2024 ; with amendments made in accordance with Law No. 3706-IX of 05/09/2024 - the norms apply from 03/16/2024 }
Such information is provided electronically in the manner and form approved by the Cabinet of Ministers of Ukraine.
{Clause 12.3 of Article 12 is supplemented with a new paragraph in accordance with Law No. 3603-IX of 23.02.2024 }
12.3.1. The establishment of local taxes and fees is carried out in accordance with the procedure specified in this Code.
12.3.2. When making a decision to establish local taxes and/or fees, the object of taxation, the payer of taxes and fees, the rate, the tax period and other mandatory elements defined in Article 7 of this Code shall be determined in compliance with the criteria established by Section XII of this Code for the relevant local tax or fee.
{Subclause 12.3.2 of Clause 12.3 of Article 12 as amended by Law No. 466-IX of 16.01.2020 }
12.3.3. Village, town, city councils shall send, within ten days from the date of adoption of decisions, but no later than July 25 of the year preceding the budget period in which the established local taxes and/or fees and tax benefits for the payment of local taxes and/or fees are planned to be applied, to the regulatory body in which the payers of the relevant local taxes and/or fees are registered, in electronic form information on rates and tax benefits for the payment of local taxes and/or fees in accordance with the procedure and form approved by the Cabinet of Ministers of Ukraine, and copies of the decisions adopted on the establishment of local taxes and/or fees and on amendments to such decisions.
If the decision of a local government body on the establishment of local taxes and/or fees, as well as tax benefits for their payment, does not specify its validity period, such a decision is valid until a new decision is made.
No later than August 25 of the current year, the supervisory authorities shall compile summarized information on the amount and date of establishment of local tax rates and/or fees in the relevant territories, as well as on tax benefits established in the relevant territories, and submit it in electronic form to the central executive body implementing state tax policy.
the Budget Code of Ukraine, controlling bodies submit reports to local governments by revenue source:
on the amounts of accrued and paid taxes and/or fees, the amount of tax debt and excessively paid taxes and/or fees to local budgets in the relevant territories - monthly, no later than the 10th of the month following the reporting month;
on the amounts of written-off bad tax debt; amounts of installment and deferred monetary obligations and/or tax debt of taxpayers that must be paid to local budgets in the relevant territories; amounts of tax benefits provided, including losses of budget revenues from their provision - quarterly, no later than 25 days after the end of the reporting quarter.
Reporting by taxpayers is provided by the supervisory authority at the request of a local government authority within 20 days from the date of receipt of the request.
{Paragraph seven of subparagraph 12.3.3 of paragraph 12.3 of Article 12 as amended by Law No. 1914-IX of 11/30/2021 }
The procedure for providing reporting by taxpayer to local governments is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph eight of subparagraph 12.3.3 of paragraph 12.3 of Article 12 as amended by Law No. 1914-IX of 11/30/2021 }
The central executive body implementing state tax policy shall, no later than September 25 of the current year, publish on its official website summarized information on the amount and date of establishment of local tax and/or fee rates in the relevant territories, as well as on tax benefits established in the relevant territories.
The local government body, within ten days from the date of approval of the technical documentation on the normative monetary valuation of land, shall send in electronic form to the controlling body and the central executive body implementing state policy in the field of land relations, information on the normative monetary valuation of land in the manner and form approved by the Cabinet of Ministers of Ukraine.
The procedure for exchanging information between local governments and the central executive body implementing state policy in the field of land relations is determined by the Cabinet of Ministers of Ukraine.
The central executive body implementing state policy in the field of land relations shall, no later than July 15 of the current year, publish on its official website summarized information on the conducted normative monetary valuation of lands.
{Subclause 12.3.3 of Clause 12.3 of Article 12 as amended by Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 466-IX of 16.01.2020 }
12.3.4. The decision on the establishment of local taxes and fees shall be officially published by the relevant local government body by July 25 of the year preceding the budget period in which the established local taxes and/or fees or changes are planned to be applied (planning period). Otherwise, the norms of the relevant decisions shall be applied no earlier than the beginning of the budget period following the planning period.
{Subclause 12.3.4 of Clause 12.3 of Article 12 as amended by Law No. 466-IX of 16.01.2020 }
12.3.5. If, by July 15 of the year preceding the budget period in which it is planned to apply local taxes and/or fees, the village, settlement, city council has not adopted a decision to establish the relevant local taxes and/or fees that are mandatory in accordance with the provisions of this Code, such taxes and/or fees shall be levied based on the provisions of this Code using the rates that were in effect until December 31 of the year preceding the budget period in which it is planned to apply such local taxes and/or fees.
{Subclause 12.3.5 of clause 12.3 of Article 12 as amended by Laws No. 71-VIII of 12/28/2014 , No. 909-VIII of 12/24/2015 , No. 466-IX of 01/16/2020 }
12.3.6. The central executive body that ensures the formation and implementation of state financial policy shall approve the forms of tax declarations (calculations) for local taxes and fees in accordance with the procedure established by this Code, and, if necessary, shall provide methodological recommendations for their completion.
{Subclause 12.3.6 of Clause 12.3 of Article 12 as amended by Law No. 1797-VIII of 21.12.2016 }
12.3.7. Village, town, and city councils are not allowed to establish individual preferential rates of local taxes and fees for individual legal entities and individuals - entrepreneurs and individuals - or to exempt them from paying such taxes and fees.
The effect of the first paragraph of this subparagraph does not apply to the adoption by village, settlement, city councils, military administrations and military-civilian administrations of decisions to establish tax benefits for the payment of local taxes and/or fees on the basis of taxpayers' applications to recognize land plots as unsuitable for use due to the potential threat of their contamination by explosive objects (with the mandatory indication of the cadastral numbers of such land plots), as well as to make changes to such decisions.
{Subclause 12.3.7 of clause 12.3 of Article 12 is supplemented by the second paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
Decisions on establishing tax benefits for the payment of local taxes and/or fees based on taxpayers' applications for recognizing land plots as unsuitable for use due to the potential threat of their contamination by explosive objects must be made for each calendar year separately, provided that there are relevant applications from taxpayers, and for a period not exceeding the end of the current calendar year.
{Subclause 12.3.7 of clause 12.3 of Article 12 is supplemented by the third paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
{Subclause 12.3.7 of Clause 12.3 of Article 12 as amended by Law No. 909-VIII of 24.12.2015 }
12.3.8. For the period of martial law or a state of emergency, village, town, and city councils have the right to make decisions on the establishment of local taxes and/or fees and tax benefits for the payment of local taxes and/or fees without applying the procedures provided for by the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity". In the event of the introduction of martial law or a state of emergency in certain localities of Ukraine, the provisions of this subparagraph apply exclusively to the representative bodies of territorial communities of the relevant administrative-territorial units on the territory of which martial law or a state of emergency has been introduced.
{Clause 12.3 of Article 12 is supplemented by subparagraph 12.3.8 in accordance with Law No. 2142-IX of March 24, 2022 }
12.4. The powers of village, settlement, city councils, military administrations and military-civilian administrations regarding taxes and fees include:
{Paragraph one of clause 12.4 of Article 12 as amended by Laws No. 909-VIII of 12/24/2015 , No. 3050-IX of 04/11/2023 }
12.4.1. setting rates of local taxes and fees within the rates specified by this Code;
{Subclause 12.4.1 of clause 12.4 of Article 12 as amended by Law No. 71-VIII of 28.12.2014 }
12.4.2. determination of the list of tax agents in accordance with Article 268 of this Code;
12.4.3. making a decision on establishing local taxes and fees, changing their rates, the object of taxation, the procedure for collecting them, or providing tax benefits, which entails a change in the tax obligations of taxpayers and which takes effect from the beginning of the budget period.
{Subclause 12.4.3 of Clause 12.4 of Article 12 as amended by Law No. 466-IX of 16.01.2020 }
{Subclause 12.4.4 of clause 12.4 of Article 12 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
12.4.5. providing information to the supervisory authorities on the location of land plots regarding allocated land plots in kind (on the ground) to owners of land shares (shares) based on decisions of the local government body with the provision of copies of the following documents:
a document that certifies the identity and confirms the citizenship of Ukraine (citizen's passport);
the registration number of the taxpayer's registration card;
cadastral plan of the land plot from the land management project regarding the organization of the territory of land plots (shares);
certificate of the right to a land share (share) (if available).
Such information is provided in electronic form in accordance with the procedure and form approved by the Cabinet of Ministers of Ukraine.
{Clause 12.4 of Article 12 is supplemented by subparagraph 12.4.5 in accordance with Law No. 1914-IX of 30.11.2021 }
12.4.6. providing information to the supervisory authorities at the location of land plots regarding decisions to establish tax benefits for the payment of local taxes and/or fees, adopted on the basis of taxpayers' applications for recognizing land plots as unsuitable for use due to the potential threat of their contamination by explosive objects. Such information is provided electronically in accordance with the procedure and form approved by the Cabinet of Ministers of Ukraine, within 10 calendar days from the date of adoption of the relevant decision with the mandatory indication of the cadastral numbers of the land plots for which the relevant decision was adopted.
{Clause 12.4 of Article 12 is supplemented by subparagraph 12.4.6 in accordance with Law No. 3050-IX of 11.04.2023 }
12.5. An officially published decision on the establishment of local taxes and/or fees, as well as a change in the amount of their rates, the object of taxation, the procedure for collecting or providing tax benefits, or on amendments to such decisions is a regulatory legal act on taxation with local taxes and fees, which enters into force taking into account the deadlines provided for in subparagraph 12.3.4 of this article.
{Paragraph one of clause 12.5 of Article 12 as amended by Law No. 466-IX of January 16, 2020 }
Payers of local taxes and fees may use the consolidated information posted on the official website of the central executive body implementing the state tax policy when determining their tax obligations. Such payers shall be exempt from liability if an error is found in the consolidated information posted on the official website, which contains discrepancies between the data of the controlling bodies and the data of the officially published decision on the establishment of local taxes and/or fees or on amendments to such decisions. In such a case, the penalties and fines provided for by this Code for violations of tax and other legislation, the control over compliance with which is entrusted to the controlling bodies, caused by such an error shall not apply to such taxpayers, and there are no grounds for holding the taxpayer and/or its officials liable.
{Clause 12.5 of Article 12 supplemented by the second paragraph in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
13.1. Income received by a resident of Ukraine (except for individuals) from sources outside Ukraine is taken into account in full when determining its object and/or tax base.
13.2. When determining the object and/or tax base, expenses incurred by a resident of Ukraine (except for individuals) in connection with receiving income from sources outside Ukraine shall be taken into account in the manner and amounts established by this Code.
13.3. Income received by a resident individual from sources outside Ukraine shall be included in the total annual taxable income, except for income that is not subject to taxation in Ukraine in accordance with the provisions of this Code or an international treaty, the binding consent of which has been granted by the Verkhovna Rada of Ukraine.
13.4. Amounts of taxes and fees paid outside Ukraine shall be included when calculating taxes and fees in Ukraine according to the rules established by this Code.
13.5. To obtain the right to credit taxes and fees paid outside Ukraine, the payer is obliged to obtain from the state body of the country where such income (profit) is received, authorized to levy such tax, a certificate on the amount of tax and fee paid, as well as on the base and/or object of taxation. The specified certificate is subject to legalization in the relevant country, the relevant foreign diplomatic institution of Ukraine, unless otherwise provided for by the current international treaties of Ukraine.
14.1. In this Code, the following terms are used with the following meanings:
14.1.1. aval - a bill of exchange guarantee, according to which the bank assumes responsibility to the bill of exchange holder for the payment of the tax bill by the drawer, which is issued by affixing the bank's guarantee inscription on each copy of the tax bill;
14.1.1 - 1. administration of taxes, fees, customs payments, a single contribution to compulsory state social insurance (hereinafter referred to as the single contribution) and other payments in accordance with the legislation, control over compliance with which is entrusted to the regulatory authorities (hereinafter referred to as taxes, fees, payments) - is a set of decisions and procedures of regulatory authorities and actions of their officials that determine the institutional structure of tax and customs relations, organize the identification and accounting of taxpayers and single contribution payers and objects of taxation, provide service to taxpayers, organize and control over the payment of taxes, fees, payments in accordance with the procedure established by law;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.1 - 1 in accordance with Law No. 404-VII of 04.07.2013 }
14.1.1 - 2. right-of-use asset - an asset recognized by the lessee in accordance with the requirements of international financial reporting standards, which represents the lessee's right to use the underlying asset during the lease term;
{Clause 14.1 of Article 14 is supplemented by subparagraphs 14.1.1 - 2 in accordance with Law No. 2628-VIII of 23.11.2018 }
{Subclause 14.1.2 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.3. depreciation - systematic distribution of the cost of fixed assets, other non-current and intangible assets that are depreciated over the period of their useful life (operation);
14.1.4. excise tax - an indirect tax on the consumption of certain types of goods (products) defined by this Code as subject to excise duty, which is included in the price of such goods (products);
{Subclause 14.1.4 of clause 14.1 of Article 14 as amended by Laws No. 5519-VI of 06.12.2012 , No. 71-VIII of 28.12.2014 }
14.1.5. alcoholic beverages - products obtained by alcoholic fermentation of sugar-containing materials or made on the basis of food alcohols with an ethyl alcohol content of more than 0.5 percent by volume, which are specified in commodity headings 2203, 2204, 2205, 2206 (except for "live" fermentation kvass), 2208 according to the UKT FEA , as well as with an ethyl alcohol content of 8.5 percent by volume and more, which are specified in commodity headings 2103 90 30 00, 2106 90 according to the UKT FEA ;
{Subclause 14.1.5 of clause 14.1 of Article 14 as amended by Laws No. 1621-VII of 07/31/2014 , No. 71-VIII of 12/28/2014 , No. 2245-VIII of 12/07/2017 }
14.1.6. excise warehouse is:
a) specially equipped premises in a limited area (hereinafter referred to as premises) located in the customs territory of Ukraine, where, under the control of permanent representatives of the controlling body, the excise warehouse manager carries out his economic activities by producing, processing (refining), mixing, bottling, packaging, packing, storing, receiving or issuing, as well as selling ethyl alcohol, vodka and alcoholic beverages;
b) premises or territory in the customs territory of Ukraine where the excise warehouse manager carries out his economic activities by producing, processing (refining), mixing, bottling, loading and unloading, storing, and selling fuel.
Not an excise warehouse:
a) premises of separate divisions of the excise warehouse manager, which are used by him exclusively for packaging, packing, storage, receipt or issuance of vodka and alcoholic beverages marked with excise tax stamps, shipped from the excise warehouse, as well as for wholesale and/or retail trade in accordance with the license obtained by the excise warehouse manager;
b) premises or territory, each of which has a total capacity of containers for loading, unloading and storing fuel that does not exceed 200 cubic meters, and a business entity (except for a single tax payer of the fourth group) - the owner or user of such premises or territory - receives fuel during the calendar year in volumes not exceeding 1,000 cubic meters (excluding the volume of fuel received through fuel dispensers at fuel retail outlets for which appropriate licenses have been obtained), and uses fuel exclusively for the needs of its own consumption or industrial processing and does not carry out operations to sell and store fuel to other persons.
The criterion defined by this subparagraph regarding the total capacity of containers for loading, unloading and storing fuel does not apply to containers of business entities that are managers of at least one excise warehouse;
{Subclause 14.1.6 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
c) premises or territory, regardless of the total capacity of the containers located for loading, unloading and storing fuel, the owner or user of which is a business entity - a payer of a single tax of the fourth group, which receives fuel during the calendar year in volumes not exceeding 10,000 cubic meters (excluding the volume of fuel received through fuel dispensers in places of retail fuel trade for which appropriate licenses have been obtained), and uses fuel exclusively for its own consumption and does not carry out operations to sell and store fuel to other persons;
d) fuel tank as a container for storing fuel directly in a vehicle or equipment or device;
{Paragraph nine of subparagraph 14.1.6 of paragraph 14.1 of Article 14 as amended by Law No. 391-IX of 18.12.2019 }
e) premises or territory, including that of the taxpayer, where exclusively fuel in consumer containers with a capacity of up to 5 liters inclusive, received from the manufacturer or the person who filled it into such containers, is stored or sold;
{Subclause 14.1.6 of clause 14.1 of Article 14 is supplemented by the tenth paragraph in accordance with Law No. 391-IX of 18.12.2019 }
{Subclause 14.1.6 of Clause 14.1 of Article 14 as amended by Laws No. 71-VIII of 28.12.2014 , No. 5503-VI of 20.11.2012 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 2628-VIII of 23.11.2018 }
14.1.6 - 1. mobile excise warehouse - a means of transport (automobile, railway, sea, river, air, main pipeline) on which fuel or ethyl alcohol is transported and/or stored in the customs territory of Ukraine.
A vehicle acquires the status of a mobile excise warehouse during the period of its use for:
a) movement of fuel or ethyl alcohol sold through the customs territory of Ukraine (except for fuel or ethyl alcohol moved through the customs territory of Ukraine by transit or internal transit, as defined in subparagraph "a" of paragraph 2 of part two of Article 91 of the Customs Code of Ukraine);
b) storage of fuel or ethyl alcohol in it on the customs territory of Ukraine;
c) import of fuel or ethyl alcohol into the customs territory of Ukraine, on which excise tax has been paid or under the conditions specified in Article 229 of this Code.
A vehicle in which fuel or ethyl alcohol is transported and/or stored, the ownership of which belongs to several managers of a mobile excise warehouse, is several mobile excise warehouses, the number of which is equal to the number of owners of fuel or ethyl alcohol transported and/or stored in such a vehicle.
{Subclause 14.1.6 - 1 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
A vehicle in which fuel or ethyl alcohol is transported and/or stored, the ownership of which is transferred from one business entity to another, is considered another mobile excise warehouse.
{Subclause 14.1.6 - 1 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
The following are not considered mobile excise warehouses:
{Paragraph eight of subparagraph 14.1.6 - 1 of paragraph 14.1 of Article 14 as amended by Law No. 391-IX of 18.12.2019 }
a vehicle used by a business entity that is not an excise warehouse manager and excise tax payer to move its own fuel or ethyl alcohol within the customs territory of Ukraine for its own consumption or industrial processing;
{Paragraph of sub-clause 14.1.6 - 1 of clause 14.1 of Article 14 as amended by Law No. 391-IX of 18.12.2019 }
vehicle fuel tank;
{Paragraph of sub-clause 14.1.6 - 1 of clause 14.1 of Article 14 as amended by Law No. 391-IX of 18.12.2019 }
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.6 - 1 in accordance with Law No. 2628-VIII of 23.11.2018 }
14.1.7. appeal of decisions of regulatory bodies - appeal by a taxpayer of a tax notice - a decision on determining the amounts of the taxpayer's monetary obligation or any decision of a regulatory body in accordance with the procedure and terms established by this Code under administrative appeal procedures, or in court;
14.1.8. auction (public auction) - a public method of selling assets in order to obtain maximum revenue from the sale of assets at a specified time and in a specified place;
14.1.9. residual value of fixed assets, other non-current and intangible assets for the purposes of Section III - the amount of the residual value of such assets and assets, which is determined as the difference between the original cost and the amount of calculated depreciation in accordance with the provisions of Section III of this Code;
{Subclause 14.1.9 of Clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.10. barter (exchange) transaction - a business transaction that involves making payments for goods (works, services) in non-monetary form within the framework of a single contract;
14.1.10 - 1. Multilateral CRS Agreement - a multilateral agreement of competent authorities on the automatic exchange of information on financial accounts (Multilateral Competent Authority Agreement on Automatic Exchange of Financial Account Information (MCAA CRS), concluded in accordance with Article 6 of the Convention on Mutual Administrative Assistance in Tax Matters;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.10 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
14.1.10 - 2. Multilateral CbC agreement (for the purposes of Article 39 of this Code) - a multilateral agreement of competent authorities on the automatic exchange of reports on a country-by-country basis (Multilateral Competent Authority Agreement on the Exchange of Country-by-Country Reports), concluded in accordance with Article 6 of the Convention on Mutual Administrative Assistance in Tax Matters;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.10 - 2 in accordance with Law No. 2970-IX of 20.03.2023 }
14.1.10 - 3. QCAA Agreement (for the purposes of Article 39 of this Code) - an agreement concluded between the competent authorities of Ukraine and a foreign jurisdiction that are parties to a valid international treaty containing provisions on the exchange of information for tax purposes, which provides for the automatic exchange of reports by country of an international group of companies between Ukraine and such foreign jurisdiction (Qualifying Competent Authority Agreement), including the Multilateral CbC Agreement;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.10 - 3 in accordance with Law No. 2970-IX of 20.03.2023 }
14.1.11. bad debt - debt that meets one of the following criteria:
a) debt on obligations for which the statute of limitations has expired;
b) overdue debt of a deceased individual, in the absence of inherited property that can be seized;
c) overdue debts of persons who have been legally recognized as missing or declared dead;
{Sub-clause "d" of sub-clause 14.1.11 of clause 14.1 of Article 14 was excluded on the basis of Law No. 2245-VIII of 07.12.2017 }
e) a debt of a person overdue for more than 180 days, the amount of the creditor's total claims for which does not exceed the minimum amount of undisputed claims of the creditor established by law for the initiation of bankruptcy proceedings, and for individuals - a debt that does not exceed 25 percent of the minimum wage (per year) established as of January 1 of the reporting tax year (in the absence of a legally approved bankruptcy procedure for individuals);
{Sub-paragraph "g" of subparagraph 14.1.11 of paragraph 14.1 of Article 14 as amended by Law No. 655-VIII of 17.07.2015 ; as amended by Law No. 1791-VIII of 20.12.2016 ; as amended by Law No. 1797-VIII of 21.12.2016 }
e) an asset in the form of corporate rights or non-debt securities, the issuer of which has been declared bankrupt or has been terminated as a legal entity in connection with its liquidation;
e) the amount of the remaining lottery prize fund as of December 31 of each year;
h) overdue debt of an individual or legal entity that has not been repaid due to the insufficiency of the property of the specified person, provided that actions to enforce the collection of the debtor's property have not led to the full repayment of the debt;
{Sub-clause "e" of sub-clause 14.1.11 of clause 14.1 of Article 14 as amended by Law No. 655-VIII of 17.07.2015 }
g) debt, the collection of which has become impossible due to force majeure circumstances, natural disaster (force majeure circumstances), confirmed in accordance with the procedure prescribed by law;
h) debts of business entities declared bankrupt in accordance with the procedure established by law or terminated as legal entities in connection with their liquidation;
{Subclause 14.1.11 of clause 14.1 of Article 14 is supplemented by subparagraph "z" in accordance with Law No. 655-VIII of 17.07.2015 }
i) debt of an individual that remained unpaid to the mortgagee after the execution of a foreclosure on the mortgaged object by means of an out-of-court settlement based on an agreement in accordance with Article 36 of the Law of Ukraine "On Mortgage", if the law or agreement provides that after the completion of such out-of-court settlement, any subsequent claims of the mortgagee regarding the performance of the main obligation by the debtor - an individual are invalid;
{Subclause 14.1.11 of clause 14.1 of Article 14 is supplemented by subparagraph "i" in accordance with Law No. 1383-IX of 13.04.2021 }
i) the person's debt under a consumer credit agreement or other agreement, canceled in accordance with paragraphs 12 and 16 of Section IV "Final and Transitional Provisions" of the Law of Ukraine "On Consumer Crediting".
{Subclause 14.1.11 of clause 14.1 of Article 14 is supplemented by subparagraph "i" in accordance with Law No. 2823-IX of 01.12.2022 }
Bad debts of banks and non-bank financial institutions may include the amount of debt on a financial loan, including the amount of principal debt and/or the amount of accrued income, for which the delay in repayment of the amount of debt (part thereof) is more than 360 days, except for debt on financial loans of individuals:
{Subclause 14.1.11 of clause 14.1 of Article 14 is supplemented by a paragraph in accordance with Law No. 1791-VIII of 20.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
related to such creditor;
{Subclause 14.1.11 of clause 14.1 of Article 14 is supplemented by a paragraph in accordance with Law No. 1791-VIII of 20.12.2016 }
who are in an employment relationship with such a creditor;
{Subclause 14.1.11 of clause 14.1 of Article 14 is supplemented by a paragraph in accordance with Law No. 1791-VIII of 20.12.2016 }
who were in an employment relationship with such a creditor, and the period between the date of dismissal of such persons and the date of forgiveness of their debt does not exceed three years";
{Subclause 14.1.11 of clause 14.1 of Article 14 is supplemented by a paragraph in accordance with Law No. 1791-VIII of 20.12.2016 }
{Subclause 14.1.11 of clause 14.1 of Article 14 as amended by Laws No. 3609-VI of 07.07.2011 , No. 657-VII of 10.24.2013 ; as amended by Law No. 71-VIII of 12.28.2014 }
14.1.12. basic freight rate - the amount of freight, including the costs of loading, unloading, reloading and warehousing (storage) of goods, increased by the amount of costs for the voyage of the vessel or other means of transport, paid (reimbursed) by the charterer in accordance with the concluded chartering agreement;
14.1.13. goods, works, services provided free of charge:
a) goods provided under gift contracts, other contracts that do not provide for monetary or other compensation for the value of such goods or their return, or without concluding such contracts;
b) works (services) performed (provided) without a claim for compensation for their cost;
c) goods transferred to a legal entity or individual for safekeeping and used by it;
14.1.14. bioethanol - dehydrated ethyl alcohol, which is produced from biomass or from raw ethyl alcohol for use as a biofuel or biocomponent and belongs to commodity heading 2207 according to the UKT FEA ;
{Subclause 14.1.14 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
14.1.15. buildings - land improvements consisting of load-bearing and enclosing or combined (load-bearing and enclosing) structures that form above-ground or underground premises intended for the residence or stay of people, the placement of property, animals, plants, the preservation of other material values, and the conduct of economic activity;
14.1.16. production subsidy from the budget - financial assistance from the state provided to a business entity on an irrevocable basis in order to strengthen its financial and economic situation and/or to ensure the production of goods, performance of work, provision of services;
14.1.17. budgetary institution - within the meaning given in the Budget Code of Ukraine ;
14.1.18. budget reimbursement - reimbursement of the negative value of value added tax based on confirmation of the legality of the amounts of budget reimbursement of value added tax based on the results of the payer's audit;
{Subclause 14.1.18 of clause 14.1 of Article 14 as amended by Law No. 1797-VIII of 21.12.2016 }
{Subclause 14.1.19 excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.20 excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.21 excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.21 - 1. Import of goods into the customs territory of Ukraine, export of goods outside the customs territory of Ukraine - a set of actions related to the movement of goods across the customs border of Ukraine in any way in the appropriate direction, in accordance with the Customs Code of Ukraine ;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.21 - 1 . in accordance with Law No. 4915-VI of 07.06.2012 }
14.1.22. drawer for the purposes of Section VI of this Code - a business entity - a producer who receives:
from the excise warehouse ethyl alcohol for the production of alcoholic beverages specified in Article 225 , as well as for the production of certain types of products specified in Clause 229.1 of Article 229 of Section VI of this Code;
from an oil refining enterprise or imports petroleum products, substances used as components of motor fuels, into the customs territory of Ukraine for their use depending on the direction determined by paragraphs 229.2-229.8 of Article 229 of Section VI of this Code;
{Paragraph three of subparagraph 14.1.22 of paragraph 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
{Subclause 14.1.22 of clause 14.1 of Article 14 as amended by Law No. 3609-VI of 07.07.2011 }
14.1.23. bill of exchange holder for the purposes of Section VI - the controlling authority at the place of registration of the drawer;
14.1.24. large taxpayer - a legal entity or a permanent establishment of a non-resident in the territory of Ukraine, whose income from all types of activities for the last four consecutive tax (reporting) quarters exceeds the equivalent of 50 million euros, determined at the weighted average official exchange rate of the National Bank of Ukraine for the same period, or the total amount of taxes, fees, payments paid to the State Budget of Ukraine, the control over the collection of which is entrusted to the controlling bodies, except for customs payments, for the same period exceeds the equivalent of 1.5 million euros, determined at the weighted average official exchange rate of the National Bank of Ukraine for the same period;
{Subclause 14.1.24 of clause 14.1 of Article 14 as amended by Law No. 404-VII of 04.07.2013 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
{Subclause 14.1.25 of clause 14.1 of Article 14 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
14.1.26. wine products - natural grape wines, natural fortified wines, champagne, sparkling, carbonated, vermouth, brandy, grape must and other wine materials, cognacs, other alcoholic beverages from grapes, fruits and berries;
14.1.26 - 1. intermediate products - wines and other fermented beverages (including mixtures of fermented beverages and mixtures based on fermented beverages) with an actual strength of more than 1.2% vol., but not more than 22% vol., classified under codes 2204 , 2205, 2206 00 (wines and other fermented beverages without added ethyl alcohol, not elsewhere specified; wines and other fermented beverages with added ethyl alcohol) according to the UKTZED;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.26 - 1 in accordance with Law No. 3878-IX of 18.07.2024 }
{Subclause 14.1.27 excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.28. produced products - the total volume of products extracted in accordance with the production sharing agreement and delivered to the metering point;
14.1.28 - 1. production of excisable goods (products) - a technological process, including mixing, the implementation of which, as a result of changing the form, properties or composition of raw materials, semi-finished products or finished products, leads to the production of excisable goods (products, including raw materials), giving such goods other properties, which leads or does not lead to an increase in the volume of such goods;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.28 - 1 in accordance with Law No. 909-VIII of 24.12.2015 }
14.1.29. renewable energy sources - sources of wind, solar, geothermal energy, wave and tidal energy, hydropower, biomass energy, gas from organic waste, gas from sewage treatment plants, biogases;
14.1.30. separate subdivisions - in the meaning defined by the Civil Code of Ukraine . For Section IV of this Code - in the meaning defined by the Commercial Code of Ukraine ;
{Subclause 14.1.30 of clause 14.1 of Article 14 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1797-VIII of 12/21/2016 }
14.1.31. alienation of property - any actions of a taxpayer, as a result of which such taxpayer, in accordance with the procedure prescribed by law, loses the right of ownership of property belonging to such taxpayer, or the right to use, in particular, natural resources, which, in accordance with the procedure prescribed by law, were provided to him for use;
{Subclause 14.1.31 of clause 14.1 of Article 14 as amended by Law No. 404-VII of 04.07.2013 }
14.1.32. safekeeping - a business transaction carried out by a taxpayer and providing for the transfer, in accordance with storage agreements, of material assets for storage to another individual or legal entity without the right to use such entity in economic turnover with the subsequent return of such material assets to the taxpayer without changing their qualitative or quantitative characteristics;
{Subclause 14.1.32 of Clause 14.1 of Article 14 as amended by Law No. 404-VII of 04.07.2013 }
{Subclause 14.1.33 excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.33 - 1. Own agricultural products - agricultural products (agricultural goods) falling under the definition of groups 1-24 of the UKT FEA, if such products are grown, fattened, caught, collected, manufactured, produced, processed directly by the producer of these products - the owner, tenant or user on other terms (including on emphyteusis terms) of land plots classified as agricultural land, or on toll-free terms.
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.33 - 1 in accordance with Law No. 1914-IX of 30.11.2021 }
14.1.34. owners of land plots - legal entities and individuals (residents and non-residents) who, in accordance with the law, have acquired ownership rights to land in Ukraine, as well as territorial communities and the state with respect to communal and state-owned lands, respectively;
14.1.35. hydrocarbon raw materials - oil, natural gas (including petroleum (associated) gas, gas (methane) from coal deposits, shale gas, central-basin type gas, gas from tight rock reservoirs), gas condensate, which is a commercial product;
{Subclause 14.1.35 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 24.05.2012 }
14.1.36. economic activity - the activity of a person related to the production (manufacture) and/or sale of goods, performance of work, provision of services, aimed at generating income and carried out by such a person independently and/or through its separate divisions, as well as through any other person acting in favor of the first person, in particular under commission agreements, mandate and agency agreements;
14.1.37. economic activity of a mining enterprise for the extraction of minerals for the purposes of Section IX of this Code - the activity of a mining enterprise, which includes the processes of extraction and primary processing of minerals;
{Subclause 14.1.37 of Clause 14.1 of Article 14 as amended by Laws No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 }
{Subclause 14.1.37 - 1 of clause 14.1 of Article 14 was excluded on the basis of Law No. 767-VII of 23.02.2014 }
14.1.38. monetary obligation in international legal relations - the obligation of a taxpayer to pay the appropriate amount of funds to the budget of a foreign state in the manner and within the time limits specified by the legislation of such foreign state;
14.1.39. taxpayer's monetary obligation - the amount of funds that the taxpayer must pay to the relevant budget or to a single account as a tax obligation and/or other obligation, control over the payment of which is entrusted to the regulatory authorities, and/or a penalty (financial) sanction imposed on the taxpayer in connection with his violation of the requirements of tax legislation and other legislation, control over compliance with which is entrusted to the regulatory authorities, as well as sanctions for violation of legislation in the field of foreign economic activity and a penalty;
{Subclause 14.1.39 of clause 14.1 of Article 14 as amended by Laws No. 3609-VI of 07.07.2011 , No. 190-IX of 04.10.2019 , No. 466-IX of 16.01.2020 }
14.1.40. goodwill (value of business reputation) - an intangible asset, the value of which is determined as the difference between the market price and the book value of the assets of the enterprise as a single property complex, which arises as a result of the use of the best management qualities, a dominant position in the market of goods, services, new technologies, etc. The value of goodwill is not subject to amortization and is not taken into account when determining the expenses of the taxpayer in respect of whose assets such goodwill arose;
14.1.41. toll-based raw materials - raw materials, materials, semi-finished products, component parts, energy carriers that are the property of one business entity (customer) and are transferred to another business entity (producer) for the production of finished products, with subsequent transfer or return of such products or part thereof to their owner or, on his behalf, to another person.
{Paragraph two of subparagraph 14.1.41 of paragraph 14.1 of Article 14 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
14.1.42. state land cadastre data - a set of information and documents on the location and legal regime of land plots, their assessment, land classification, quantitative and qualitative characteristics, distribution among land owners and land users, prepared in accordance with the law;
14.1.43. debtor - a person who, as a result of past events, has incurred a debt to another person in the form of a certain amount of funds, their equivalent or other assets;
14.1.44. deposit (deposit) - funds provided by individuals or legal entities to a resident, designated by a financial organization in accordance with the legislation of Ukraine, or a non-resident for a term or on demand and with interest on the terms of issuance on demand or return upon expiration of the term established by the contract. Deposits may be attracted in the form of issuance (issue) of savings (deposit) certificates. The rules for deposit transactions are established: for bank deposits - by the National Bank of Ukraine in accordance with the legislation; for deposits (contributions) to other financial institutions - by a state body designated by law;
14.1.44 - 1. government securities - bonds of domestic and foreign government loans and treasury obligations of Ukraine, placed by the central executive body that ensures the formation and implementation of state financial policy and/or implements state budget policy in the field of management of state debt and state-guaranteed debt;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.44 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Laws No. 2146-VIII of 07.09.2017 , No. 1016-IX of 01.12.2020 }
14.1.45. derivative - a document certifying the right and/or obligation to purchase or sell securities, tangible or intangible assets, as well as funds in the future on the terms specified therein. The procedure for issuing and trading derivatives is established by law.
{Paragraph one of subparagraph 14.1.45 of paragraph 14.1 of Article 14 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 2628-VIII of 11/23/2018 }
Derivatives include:
14.1.45.1. swap - a civil law agreement to exchange payment flows (cash or non-cash) or other assets calculated on the basis of the price (quotation) of the underlying asset, including interest rates, within the amount specified in the contract on a specific payment date (settlement date) during the term of the contract;
{Subclause 14.1.45.1 of subparagraph 14.1.45 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
14.1.45.2. option - a civil law contract, according to which one party to the contract receives the right to purchase (sell) the underlying asset, and the other party assumes an unconditional obligation to sell (purchase) the underlying asset in the future during the term of the option or on a specified date (exercise date) at the price of the underlying asset determined at the time of concluding such a contract. Under the terms of the option, the buyer pays the seller an option premium;
14.1.45.3. forward contract - a civil law contract under which the seller undertakes to transfer the underlying asset to the buyer's ownership at a specified time in the future on certain terms, and the buyer undertakes to accept the underlying asset at a specified time and pay for it the price specified in such contract. A forward contract is executed by delivering the underlying asset and paying for it with funds or by making monetary settlements between the parties to the contract without delivering the underlying asset.
{Paragraph one of subparagraph 14.1.45.3 of subparagraph 14.1.45 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
All terms of a forward are determined by the parties to the contract at the time of its conclusion.
Forwards are concluded and traded outside the organizer of trade in standardized futures contracts;
{Subclause 14.1.45.3 of subparagraph 14.1.45 of clause 14.1 of Article 14 as amended by Law No. 1797-VIII of 21.12.2016 }
14.1.45.4. futures contract (futures) - a standardized term contract under which the seller undertakes to transfer the underlying asset to the buyer's ownership at a specified time in the future (the date of fulfillment of obligations under the futures contract) on the terms specified in the specification, and the buyer undertakes to accept the underlying asset and pay for it the price determined by the parties to the contract on the date of its conclusion.
A futures contract is executed according to its specification by delivering the underlying asset and paying for it with cash or by making monetary settlements between the parties to the contract without delivering the underlying asset.
The fulfillment of obligations under futures is ensured by creating appropriate conditions by the organizer of trading in standardized futures contracts;
14.1.46. entertainment activities - economic activities of legal entities and individual entrepreneurs, consisting in conducting lotteries, as well as entertainment games, participation in which does not involve the receipt by its participants of monetary or property prizes (winnings), in particular billiards, bowling, bowling, board games, children's video games, etc.;
14.1.47. additional benefits - funds, tangible or intangible assets, services, other types of income paid (provided) to a taxpayer by a tax agent, if such income is not a salary and is not related to the performance of employment duties or is not a remuneration under civil law contracts (agreements) concluded with such a taxpayer (except for cases expressly provided for by the norms of Section IV of this Code);
14.1.48. salary for the purposes of Section IV of this Code - basic and additional salary, other incentive and compensation payments paid (provided) to the taxpayer in connection with employment relations in accordance with the law;
14.1.49. dividends - a payment made by a legal entity, including an issuer of corporate rights, investment certificates or other securities, in favor of the owner of such corporate rights, investment certificates and other securities certifying the investor's ownership right to a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit calculated according to accounting rules.
For tax purposes, dividends are also treated as:
a payment in cash or non-cash form made by a legal entity in favor of its founder and/or participant(s) in connection with the distribution of net profit (part thereof);
amounts of income in the form of payments for securities (corporate rights) paid in favor of a non-resident specified in subparagraphs "a", "c", "d" of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, in controlled transactions in excess of the amount that complies with the "arm's length" principle;
the value of goods (works, services), except for securities and derivatives), purchased from a non-resident specified in subparagraphs "a", "c", "d" of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, in controlled transactions exceeding the amount that corresponds to the "arm's length" principle;
the amount of underestimation of the value of goods (works, services) sold to a non-resident specified in subparagraphs "a", "c", "d" of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, in controlled transactions compared to the amount that corresponds to the "arm's length" principle;
payment in cash or in kind made by a legal entity in favor of its founder and/or participant - a non-resident of Ukraine in connection with a decrease in the authorized capital, redemption by a legal entity of corporate rights in its own authorized capital, withdrawal of a participant from a business partnership or other similar transaction between a legal entity and its participant, in an amount that leads to a decrease in the retained earnings of the legal entity";
{Subclause 14.1.49 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
14.1.50. bioethanol-based additives - biocomponents of motor fuel obtained by synthesis using bioethanol or by mixing bioethanol with organic compounds and fuel obtained from hydrocarbon raw materials, in which the bioethanol content meets the requirements of regulatory documents and which belong to biofuels;
14.1.51. mining - a set of technological operations for the extraction, in particular from deposits at the bottom of water bodies, and movement, including temporary storage, to the surface of part of the subsoil (rocks, ore raw materials, etc.) containing minerals and special types of work on mining, which include underground gasification and smelting, chemical and bacterial leaching, dredging and hydraulic development of placer deposits, hydraulic transport of rock deposits at the bottom of water bodies;
{Subclause 14.1.51 of clause 14.1 of Article 14 as amended by Law No. 1914-IX of 11/30/2021 }
14.1.52. long-term life insurance contract - a life insurance contract for a period of five years or more, which provides for a lump sum or annuity payment if the insured person survives until the expiration of the insurance contract or an event stipulated in the insurance contract, or reaches the age specified in the contract. Such a contract may not provide for partial payments during the first five years of its validity, except for those made in the event of insured events related to the death or illness of the insured person or an accident that resulted in the insured person being diagnosed with group I or II disability or the person under the age of eighteen being diagnosed with disability. In this case, the taxpayer - employer may not be a beneficiary under such life insurance contracts;
14.1.52 - 1. voluntary health insurance contract - an insurance contract that provides for insurance payments made to health care institutions in the event of an insured event related to the insured person's illness or accident. Such a contract must also provide for a minimum term of one year and the return of insurance payments exclusively to the insured in the event of early termination of the contract;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.52 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
14.1.52 - 2. supplementary pension insurance contract - an insurance contract that provides for the insurer's obligation to make insurance payments (payments) and/or payments in the form of an annuity in the event that the insured person reaches the retirement age specified by the insured person in the insurance contract in accordance with the legislation, taking into account that such retirement age cannot be less than 10 years from the retirement age that gives the right to a pension under mandatory state pension insurance. Early termination of the contract before the insured person reaches the retirement age specified in the contract is impossible, except in the cases of: the presence of a medically confirmed critical health condition (cancer, stroke, etc.) or the insured person being diagnosed with group I or II disability; departure of the insured and/or the insured person for permanent residence outside Ukraine; death of the insured person. The beneficiary under such a contract may only be the insured person or heirs in accordance with the legislation. The specifics of changing the insurer under a supplementary pension insurance contract are established in accordance with the law;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.52 - 2 in accordance with Law No. 71-VIII of 28.12.2014 }
14.1.53. a document of a foreign state, pursuant to which the amount of tax debt is collected in international legal relations - a decision of a competent authority of a foreign state on the accrual of tax debt to the budget of such state, which, at the request of the specified competent authority in accordance with an international treaty of Ukraine, is subject to execution on the territory of Ukraine;
14.1.54. income with a source of origin from Ukraine - any income received by residents or non-residents, including from any types of their activities on the territory of Ukraine (including payment (accrual) of remuneration by foreign employers), its continental shelf, in the exclusive (maritime) economic zone, including, but not exclusively, income in the form of:
a) interest, dividends, royalties and any other passive (investment) income paid by residents of Ukraine or permanent establishments of non-residents in Ukraine;
{Subparagraph "a" of subparagraph 14.1.54 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
b) income from the provision of property located in Ukraine, including rolling stock of transport assigned to ports located in Ukraine, to residents or non-residents for rent (use);
c) income from the sale of movable and immovable property, income from the alienation of corporate rights, securities, including shares of Ukrainian issuers;
d) income received in the form of contributions and premiums for insurance and reinsurance of risks in the territory of Ukraine;
e) income of resident insurers from insurance of risks of resident policyholders outside Ukraine;
e) other income from activities, including those related to the full or partial assignment of rights and obligations under agreements on the distribution of products in the customs territory of Ukraine or in territories under the control of regulatory authorities (in customs control zones, in specialized licensed customs warehouses, etc.);
e) inheritances, gifts, winnings, prizes;
g) wages, other payments and remunerations paid in accordance with the terms of the employment and civil law contract;
g) income from entrepreneurial and independent professional activities;
h) income from the alienation of rights to extract and develop mineral deposits, mineral sources and other natural resources;
{Subclause 14.1.54 of clause 14.1 of Article 14 is supplemented by subparagraph "z" in accordance with Law No. 466-IX of 16.01.2020 }
i) profits from the alienation of shares, interests, corporate or other similar rights in foreign companies, organizations established in accordance with the legislation of other states (foreign legal entities), which meet the following conditions:
1) at any time during the 365 days preceding the sale or other alienation, the value of shares, interests, corporate or other similar rights of a foreign legal entity is 50 percent or more formed at the expense of shares, interests in a Ukrainian legal entity that belong to the said foreign legal entity directly or indirectly, and
2) at any time during the 365 days preceding the sale or other alienation, the value of shares, interests in a Ukrainian legal entity is 50 percent or more formed at the expense of real estate located in Ukraine and owned by such Ukrainian legal entity or used by such Ukrainian legal entity on the basis of an operating or financial lease (leasing) agreement or a similar agreement, and such use must be reflected in the accounting of such legal entity as an asset, including an asset with the right of use, in accordance with the requirements of national accounting regulations (standards) or international financial reporting standards;
{Paragraph three of subparagraph "i" of subparagraph 14.1.54 of paragraph 14.1 of Article 14 as amended by Law No. 1117-IX of 17.12.2020 }
{Subclause 14.1.54 of clause 14.1 of Article 14 is supplemented by subparagraph "i" in accordance with Law No. 466-IX of 16.01.2020 }
i) profits of non-residents from the alienation of shares, corporate rights in the authorized capital of a legal entity - a resident of Ukraine, provided that at any time during the 365 days preceding the sale or other alienation, the value of such shares, corporate rights was formed by 50 percent or more at the expense of real estate located in Ukraine and owned by such legal entity - a resident of Ukraine or used by such legal entity - a resident of Ukraine on the basis of an operating or financial lease (leasing) agreement or a similar agreement, and such use must be reflected in the accounting of such legal entity as an asset, including an asset from the right of use, in accordance with the requirements of national accounting regulations (standards) or international financial reporting standards.
{Paragraph fifteen of subparagraph 14.1.54 of paragraph 14.1 of Article 14 as amended by Law No. 786-IX of July 14, 2020 ; paragraph one of subparagraph "i" of subparagraph 14.1.54 of paragraph 14.1 of Article 14 as amended by Law No. 1117-IX of December 17, 2020 }
The value of shares, interests, corporate or other similar rights (for the purposes of the second subparagraph of subparagraph "i" and subparagraph "i" of this subparagraph) and real estate (for the purposes of the third subparagraph of subparagraph "i" and subparagraph "i" of this subparagraph) is determined on the basis of the book value (residual) according to accounting data as the highest amount at any time during the 365 days preceding the sale or other disposal, and is subject to comparison with the value of other property (assets) according to the book value (residual) according to accounting data of such legal entity;
{Paragraph of subparagraph 14.1.54 of paragraph 14.1 of Article 14 as amended by Law No. 786-IX of 14.07.2020 }
14.1.55. income received from sources outside Ukraine - any income received by residents, including from any types of their activities outside the customs territory of Ukraine, including interest, dividends, royalties and any other types of passive income, inheritance, gifts, winnings, prizes, income from the performance of work (provision of services) under civil law and labor contracts, from the provision to residents for rent (use) of property located outside Ukraine, including rolling stock of transport assigned to ports located outside Ukraine, income from the sale of property located outside Ukraine, income from the alienation of investment assets, including corporate rights, securities, etc.; other income from any types of activities outside the customs territory of Ukraine or territories not controlled by regulatory authorities;
{Subclause 14.1.56 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.56. electronic address - the taxpayer's electronic address, consisting of an identifier, the "@" sign and the domain name, used by the taxpayer for correspondence with state, including regulatory, bodies and communicated by entering the electronic address into the taxpayer's account data, in particular in the electronic account;
{Sub-clause 14.1.56 is included in clause 14.1 of Article 14 in accordance with Law No. 1797-VIII of 21.12.2016 }
14.1.56 - 1. electronic identification - the procedure for using personal identification data in electronic form, which uniquely identify an individual, legal entity or representative of an individual or legal entity. Technologies permitted for use for identifying taxpayers in the taxpayer's electronic account are determined by the central executive body that ensures the formation and implementation of state financial policy;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.56 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
14.1.56 - 2. electronic office - a set of information and telecommunication systems of the central executive body implementing state tax policy, intended for interaction between taxpayers and state, including regulatory, bodies on the implementation of rights and obligations defined by this Code and other laws, control over compliance with which is entrusted to regulatory bodies, and regulatory legal acts adopted on the basis of and in implementation of this Code and other laws, control over compliance with which is entrusted to regulatory bodies.
Interaction is implemented through:
a portal solution for taxpayer users, the work in which is carried out online (via the Internet in real time) and does not require the mandatory use of a specialized client application;
portal solution for users - government agencies, including regulatory ones;
application programming interface (API), which allows you to implement the full functionality of the electronic office;
other means, databases, registers maintained in electronic form, information, telecommunications, information and telecommunications systems of the central executive body implementing state tax policy.
The procedure for the functioning of the electronic office is determined by the central executive body that ensures the formation and implementation of state financial policy;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.56 - 2 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 786-IX of 14.07.2020 }
14.1.56 - 3. electronic cigarette - a product that can be used for consumption (inhalation) of vapors formed as a result of heating liquids containing or not containing nicotine by the components of such a product. Electronic cigarettes can be disposable or reusable;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.56 - 3 in accordance with Law No. 466-IX of January 16, 2020 }
14.1.56 - 4. liquids used in electronic cigarettes - liquid mixtures of chemicals, containing or not containing nicotine, used to create vapor in electronic cigarettes and contained, in particular, in cartridges, refill containers and other containers;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.56 - 4 in accordance with Law No. 466-IX of January 16, 2020 }
14.1.56 - 5. electronic services - services that are provided via the Internet, automatically, using information technology and mainly without human intervention, including by installing a special application or add-on on smartphones, tablets, television receivers or other digital devices. Such services, in particular, but not exclusively, include:
a) supply of electronic copies, provision of access to images, texts and information, including, but not limited to, subscription to electronic newspapers, magazines, books, provision of access and/or downloading of photographs, graphic images, video materials;
b) providing access to databases, including the use of search engines and directory services on the Internet;
c) supply of electronic copies (electronic digital information) and/or provision of access to audiovisual works, video and audio works on demand, games, including the supply of services for participation in such games, the supply of services for access to television programs (channels) or their packages, except for access to television programs simultaneously with their broadcasting via a television network;
d) providing access to informational, commercial, entertainment electronic resources and other similar resources, in particular, but not exclusively, those hosted on information sharing platforms or video materials;
e) the provision of distance learning services on the Internet, the conduct and provision of which does not require human participation, including by providing access to virtual classrooms, educational resources in which students complete tasks online, and grades are given automatically, without human participation (or with minimal human participation);
e) provision of cloud services in terms of providing computing resources, storage resources or electronic communications systems using cloud computing technologies;
e) supply of software and updates to it, including electronic copies, provision of access to them, as well as remote maintenance of software and electronic equipment;
h) provision of advertising services on the Internet, mobile applications and other electronic resources, provision of advertising space, including by placing banner advertisements on websites, web pages or web portals.
For the purpose of applying this subparagraph, the following transactions shall not be included in the electronic services referred to in the first paragraph of this subparagraph:
supply of goods/services, the order (reservation) of which is carried out via the Internet, using mobile applications and other electronic resources, and the actual supply is carried out without using the Internet (in particular, accommodation services, car rental, catering services for the supply of products, passenger transport services and other similar services);
supply of goods and/or other services other than electronic services, which include electronic services, if the cost of electronic services is included in the total cost of such goods/services;
provision of distance learning services on the Internet, if the Internet is used exclusively as a means of communication between the teacher and the student;
supply of copies of works in the field of science, literature and art on material media;
providing consulting services by e-mail;
provision of Internet access services;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.56 - 5 in accordance with Law No. 1525-IX of 03.06.2021 }
14.1.56 - 6. electronic resident (e-resident) - a foreigner who has reached the age of 18, is not a tax resident of Ukraine, has received the relevant qualified electronic trust services and information about whom is entered into the "E-resident" information system;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.56 - 6 in accordance with Law No. 2654-IX of 06.10.2022 }
14.1.57. environmental tax - a national mandatory payment levied on the actual volumes of emissions into the atmosphere, discharges of pollutants into water bodies, waste disposal, the actual volume of radioactive waste temporarily stored by its producers, the actual volume of radioactive waste generated and the actual volume of radioactive waste accumulated before April 1, 2009;
{Subclause 14.1.57 of clause 14.1 of Article 14 as amended by Laws No. 422-VII of 04.07.2013 , No. 1191-VII of 08.04.2014 }
14.1.58. issue income - the amount of excess of proceeds received by the issuer from the issue (issue) of its own shares (other corporate rights) and investment certificates over the nominal value of such shares (other corporate rights) and investment certificates (during their initial placement), or over the repurchase price during subsequent placements of investment certificates and shares of investment funds;
14.1.59. housing and communal enterprises - business entities that directly produce, create and/or provide housing and communal services (applies to Section IX of this Code);
{Subclause 14.1.59 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.59 - 1. Common Reporting Standard CRS - a common standard for reporting and due diligence for financial account information, which includes comments thereto (Common Standard on Reporting and Due Diligence for Financial Account Information (CRS), approved by the Council of the Organization for Economic Cooperation and Development on July 15, 2014 (as amended and supplemented);
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.59 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
14.1.60. unified register of tax invoices - a register of information on tax invoices and adjustment calculations, which is maintained by the central executive body implementing state tax policy, in electronic form in accordance with electronic documents provided by value added tax payers;
{Subclause 14.1.60 of clause 14.1 of Article 14 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 1797-VIII of 21.12.2016 }
14.1.60 - 1. Unified register of excise invoices - a register of information on excise invoices, which is maintained by the central executive body implementing state tax policy, in electronic form in accordance with electronic documents provided by excise tax payers;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.60 - 1 in accordance with Law No. 909-VIII of 24.12.2015 }
14.1.60 - 2. Total amount of tax liabilities on excise tax on cigarettes - the annual amount of tax liabilities on excise tax (including excise tax on retail trade in excisable goods) of all excise tax payers on goods under codes 2402 20 90 10 , 2402 20 90 20 according to the Ukrainian Classification of Economic Activities, sold by manufacturers in the customs territory of Ukraine and imported by importers into the customs territory of Ukraine, specified in excise tax declarations for January - December of the reporting year, per 1,000 pieces.
The central executive body implementing the state tax policy shall determine, based on excise tax declarations, and publish on its official website no later than March 1 of the year following the reporting year, the total amount of excise tax liabilities on cigarettes, the weighted average retail selling price of cigarettes, and the indicator (in percentages) characterizing the share of the total amount of excise tax liabilities in the weighted average retail selling price of cigarettes.
The share of the total amount of excise tax liabilities in the weighted average retail selling price of cigarettes is calculated using the following formula:
Frequency = ∑ tax obligations / Weighted average price x 100%, where
Part - the share of the total amount of tax liabilities in the weighted average retail selling price of cigarettes;
∑ tax liability - the total amount of tax liabilities for excise tax on cigarettes (including excise tax on retail trade in excisable goods);
Weighted average price - weighted average retail selling price of cigarettes (including excise tax on retail trade in excisable goods).
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.60 - 2 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 3878-IX of 18.07.2024 }
{Subclause 14.1.61 of clause 14.1 of Article 14 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
{Subclause 14.1.62 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.63 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.64 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.65 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.66 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.67 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.68 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.69 of clause 14.1 of Article 14 was excluded on the basis of Law No. 408-VII of 04.07.2013 }
{Subclause 14.1.70 of clause 14.1 of Article 14 was excluded on the basis of Law No. 408-VII of 04.07.2013 }
14.1.71. normal price - the price of goods (works, services) determined by the parties to the contract, unless otherwise established by this Code. Unless proven otherwise, it is considered that such normal price corresponds to the level of market prices. This definition does not apply to transactions recognized as controlled in accordance with Article 39 of this Code.
{Paragraph one of subparagraph 14.1.71 of paragraph 14.1 of Article 14 as amended by Law No. 72-VIII of 28.12.2014 }
If prices (mark-ups) for goods (works, services) are subject to state regulation in accordance with the law, the price established in accordance with the rules of such regulation is considered to be the usual price. This provision does not apply to cases where a minimum selling price or indicative price is established. In such a case, the usual price is the price determined by the parties to the contract, but not lower than the minimum or indicative price.
{Paragraph two of subparagraph 14.1.71 of paragraph 14.1 of Article 14 as amended by Law No. 609-VIII of July 15, 2015 }
If an appraisal is required during a transaction, the value of the appraisal object is the basis for determining the normal price for tax purposes.
{Paragraph three of subparagraph 14.1.71 of paragraph 14.1 of Article 14 as amended by Law No. 609-VIII of July 15, 2015 }
During an auction (public bidding), the price established based on the results of such an auction (public bidding), the mandatory conduct of which is provided for by law, is considered to be the usual price.
If the supply of goods (works, services) is carried out on the basis of a forward or futures contract, the usual price is the price that corresponds to the forward or futures price on the date of conclusion of such contract.
{Paragraph five of subparagraph 14.1.71 of paragraph 14.1 of Article 14 as amended by Law No. 609-VIII of July 15, 2015 }
If the sale (alienation) of goods, including property pledged by the borrower to secure the creditor's claims, is carried out in a compulsory manner in accordance with the law, the usual price is the price formed during such sale;
{Subclause 14.1.71 of clause 14.1 of Article 14 as amended by Law No. 408-VII of 04.07.2013 }
14.1.71 - 1. The usual price of property, works, services when determining the tax base by residents of the City of Diya - taxpayers who pay corporate income tax under special conditions, when carrying out transactions that are subject to taxation in accordance with Clause 135.2 of Article 135, Clause 137.10 of Article 137 and Clause 141.9 - 1 of Article 141 of this Code (except for determining the tax base in the case of carrying out controlled transactions), is determined at the level of the contract price, but not lower than the purchase price of property (works, services), and for non-current assets - not lower than the book (residual) value according to accounting data, as of the beginning of the calendar month during which the sales (alienation) and liquidation operations of such non-current assets are carried out.
For property (except for non-current assets), works, services produced (created, provided) by the taxpayer, the normal price is determined at the level of the contract price, but not lower than the production cost, which is calculated according to accounting rules in accordance with the principles, methods and procedures specified in the taxpayer's accounting policy. If such principles, methods and procedures are not specified in the accounting policy, the controlling body independently calculates the production cost in accordance with national accounting regulations (standards) or international financial reporting standards.
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.71 - 1 in accordance with Law No. 1946-IX of 14.12.2021 }
14.1.72. land tax - a mandatory payment levied on owners of land plots and land shares (shares), as well as permanent land users (hereinafter referred to as the tax for the purposes of Section XII of this Code);
{Subclause 14.1.72 of Clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.73. land users - legal entities and individuals (residents and non-residents) who use land plots of state and municipal property:
on the right of permanent use;
on lease terms;
{Subclause 14.1.73 of clause 14.1 of Article 14 as amended by Law No. 1914-IX of 11/30/2021 }
14.1.74. land plot - a part of the earth's surface with established boundaries, a specific location, a specific (economic) purpose and with defined rights in relation to it;
14.1.75. land improvement - the results of any measures that lead to a change in the qualitative characteristics of a land plot and its value. Land improvements include material objects located within the boundaries of a land plot, the movement of which is impossible without their depreciation and change of purpose, as well as the results of economic activity or the conduct of a certain type of work (change in relief, soil improvement, placement of crops, perennial plantings, engineering infrastructure, etc.);
14.1.76. agricultural land - land provided for the production of agricultural products, the implementation of agricultural research and educational activities, the placement of relevant production infrastructure, including the infrastructure of wholesale markets for agricultural products, or intended for these purposes;
14.1.77. agricultural land for the purposes of Chapter 1 of Section XIV of this Code - land provided for the production of agricultural products;
{Subclause 14.1.77 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.78. residential and public development lands - land plots within settlements that are used for housing development, public buildings and structures, and other public facilities;
14.1.78 - 1. railway transport lands - railway transport lands include the lands of railway right-of-way under the railway track and its equipment, stations with all buildings and structures of energy, locomotive, wagon, track, freight and passenger facilities, signaling and communications, water supply, sewage; under protective and reinforcing plantings, service, cultural and household buildings and other structures necessary to ensure the operation of railway transport;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.78 - 1 in accordance with Law No. 3609-VI of 07.07.2011 }
14.1.79. significant mineral reserves - mineral reserves, the size of which exceeds insignificant mineral reserves;
14.1.80. identical goods (works, services) - goods (works, services) that have the same main characteristics characteristic of them.
In this case, identical goods are understood to mean goods that have the same characteristics as the goods being valued, including such as:
physical characteristics;
quality and reputation in the market;
country of manufacture (origin);
producer;
14.1.81. investments - business transactions that involve the acquisition of fixed assets, intangible assets, corporate rights and/or securities in exchange for funds or property. Investments are divided into:
a) capital investments - business transactions involving the acquisition of buildings, structures, other real estate, other fixed assets and intangible assets subject to depreciation in accordance with the norms of this Code;
b) financial investments - business transactions involving the acquisition of corporate rights, securities, derivatives and/or other financial instruments. Financial investments are divided into:
direct investments - economic transactions involving the contribution of funds or property in exchange for corporate rights issued by a legal entity when they are placed by such entity;
portfolio investments - business transactions involving the purchase of securities, derivatives and other financial assets for funds on the stock market or commodity exchange market;
c) reinvestments - economic transactions involving capital or financial investments at the expense of profits received from investment transactions;
14.1.81 - 1. investment profit for the purposes of Section IV of this Code - income in the form of a positive difference between the income received by the taxpayer from transactions with securities, taking into account the exchange rate difference, derivatives and corporate rights issued in forms other than securities, and the costs of acquiring such investment assets;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.81 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
14.1.82. investment component - funds provided for in the tariff for the production, transmission and supply of electricity, production, transportation and supply of thermal energy, as well as transportation, storage and supply of natural gas to the licensee as part of the profit remaining at the disposal of the business entity for targeted financing of expenses related to the restoration, reconstruction, modernization of fixed assets (including measures to improve safety and compliance with environmental standards) and the construction of new facilities of fuel and energy complex enterprises, the list of which is established by the Cabinet of Ministers of Ukraine;
{Subclause 14.1.82 of clause 14.1 of Article 14 as amended by Law No. 657-VII of 24.10.2013 }
14.1.83. The term "investor" for taxation purposes in accordance with Section XVIII of this Code is used in the meaning given in the Law of Ukraine "On Production Sharing Agreements" .
When concluding a multilateral agreement, investors determine the operator of the agreement, who is entrusted with the functions stipulated by the Law of Ukraine "On Production Sharing Agreements" , including keeping records and paying tax obligations in accordance with the procedure specified in the agreement.
{Paragraph two of subparagraph 14.1.83 of paragraph 14.1 of Article 14 as amended by Laws No. 422-VII of 04.07.2013 , No. 1690-VII of 07.10.2014 }
In the event that a non-resident investor establishes a permanent representative office in the territory of Ukraine to execute an agreement, the representative office is considered an investor (operator) for tax purposes.
{Paragraph three of subparagraph 14.1.83 of paragraph 14.1 of Article 14 as amended by Law No. 1690-VII of 07.10.2014 }
In the articles of this Code regulating taxation upon the execution of a production sharing agreement, the term "investor (operator)" means "investor" upon the execution of a production sharing agreement with the participation of one investor and "investor and/or operator" upon the execution of a multilateral production sharing agreement with the participation of several investors, depending on the terms of such multilateral agreement.
{Paragraph four of subparagraph 14.1.83 of paragraph 14.1 of Article 14 as amended by Law No. 1690-VII of 07.10.2014 }
{Subclause 14.1.83 of clause 14.1 of Article 14 as amended by Law No. 5412-VI of 02.10.2012 }
14.1.84. other terms for the purposes of Section III are used in the meanings defined by the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", national accounting regulations (standards) and international financial reporting standards put into effect in accordance with the legislation.
{Subparagraph 14.1.84 of paragraph 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.85. engineering - provision of services (performance of work) for drawing up technical tasks, project proposals, conducting scientific research and feasibility studies, performing engineering and reconnaissance work on the construction of facilities, developing technical documentation, designing and developing engineering and technological facilities, providing consultation and author's supervision during installation and commissioning work, as well as providing consultations related to such services (work);
14.1.86. collective investment institutions (hereinafter referred to as CII) - investment funds and mutual funds of investment companies, corporate investment funds and unit investment funds established in accordance with the legislation;
14.1.86 - 1. information system "E-resident" - an information system that is an integral part of the Unified State Web Portal of Electronic Services, within the framework of which information about an electronic resident (e-resident) is collected, accumulated, processed, protected, recorded and provided;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.86 - 1 in accordance with Law No. 2654-IX of 06.10.2022 }
14.1.87. mortgage housing loan - a financial loan provided to an individual by a bank or other financial institution in accordance with the law for a period of at least five full calendar years to finance expenses related to the purchase of an apartment (room) or a residential building (part thereof) or the construction of a residential building (part thereof), which are provided for the ownership of the borrower, with the lender accepting such housing (land located under such a residential building, including a personal plot) as collateral;
14.1.88. mortgage certificate (including mortgage participation certificate and fixed-income mortgage certificate) - a mortgage security secured by mortgage assets or mortgages in accordance with the law;
14.1.88 - 1. conditions for mineral raw materials of a subsoil object (site) for the purposes of Section IX of this Code - a set of technical, technological and financial and economic requirements for the conduct of economic activities of a mining enterprise for the extraction of minerals, which ensure the rational use of the subsoil object (site), including economically efficient extraction of minerals by types of commodity products of the mining enterprise, which is developed and approved for a period of 5 years in accordance with the procedure established by the legislation on the regulation of mining relations;
{ Clause 14.1 of Article 14 is supplemented by subclause 14.1.88 - 1 in accordance with the Law No. 1914-IX dated 30.11.2021 }
14.1.89. consolidated mortgage debt - obligations under mortgage loan agreements, reformed by the lender in accordance with the law;
14.1.89 - 1. the term "cooperative payments" is used in the meaning given in the Law of Ukraine "On Cooperation" ;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.89 - 1 in accordance with Law No. 5412-VI of 02.10.2012 ; as amended by Law No. 657-VII of 24.10.2013 }
14.1.90. corporate rights - the rights of a person whose share is determined in the authorized capital (property) of a business organization, which include the rights of this person to participate in the management of the business organization, to receive a certain share of the profit (dividends) of this organization and assets in the event of its liquidation in accordance with the law, as well as other rights provided for by law and statutory documents;
{Subclause 14.1.90 of clause 14.1 of Article 14 as amended by Law No. 1797-VIII of 21.12.2016 }
14.1.91. minerals - natural mineral formations of organic and inorganic origin in the subsoil, including any groundwater, as well as man-made mineral formations in places of disposal of production waste and losses of products of processing of mineral raw materials, which can be used in the field of material production and consumption directly or after primary processing;
{Subclause 14.1.92 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.93. funds - hryvnia or foreign currency;
14.1.94. compensatory products - part of the produced products that is transferred to the ownership of the investor as compensation for his expenses;
14.1.94 - 1. quoted prices (for the purposes of Article 39 of this Code) - prices for a raw material in the relevant period, obtained on the international commodity market, which include, in particular, the results of exchange trading, prices obtained from recognized agencies with transparent reporting on prices, statistical agencies or from government pricing agencies, where such indices are used as a reference (benchmark) by unrelated persons to determine prices in transactions between them. The quoted price is defined as the price (average price) and/or range of prices for a certain date or period of time;
{ Clause 14.1 of Article 14 is supplemented by subclause 14.1.94 - 1 in accordance with the Law No. 466-IX dated 16.01.2020 }
14.1.95. creditor - a legal entity or individual who has claims confirmed in accordance with the established procedure regarding monetary obligations to the debtor, including regarding the payment of salary arrears to the debtor's employees, as well as regulatory authorities - regarding taxes and fees;
14.1.96. bodies used for vehicles defined in commodity heading 8703 according to the UKT FEA - bodies that have already been installed on vehicles or more than one year has passed since the date of manufacture;
14.1.96 - 1. exchange rate difference for the purposes of Section IV of this Code - a positive difference between the official exchange rate of a foreign currency to the hryvnia established by the National Bank of Ukraine on the day of purchase and on the day of sale (repayment, other disposal) of a security, if such a security is denominated in a foreign currency;
{ Clause 14.1 of Article 14 is supplemented by subclause 14.1.96 - 1 in accordance with the Law No. 1797-VIII dated 21.12.2016 }
14.1.97. leasing transaction (except for transactions on the chartering (charter) of sea vessels and other means of transport) - transfer of fixed assets into possession and use to individuals and/or legal entities (lessees) for a fee and for a specified period.
{Paragraph one of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 1605-IX of 07/01/2021 }
Leasing transactions are carried out in the form of operating leasing (rent), financial leasing, and leaseback transactions.
{Paragraph two of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
Leasing operations are divided into:
a) operating lease (lease) - a transaction of a legal entity or individual (lessor/lessor), under which the lessor/lessor transfers to another entity (lessee/lessee) fixed assets purchased or manufactured by the lessor/lessor, on terms other than those provided for by financial leasing;
{Paragraph four of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
b) financial leasing - a business transaction of a legal entity (lessor) under which the lessor transfers to the lessee property that is the main asset and purchased or manufactured by the lessor, as well as all risks and rewards associated with the right to own and use the financial leasing object.
{Paragraph five of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
The terms "financial leasing" and "financial rental" are identical for the purposes of this Code.
{Subparagraph 14.1.97 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 1605-IX of 01.07.2021 }
Leasing is considered financial if at least one of the following conditions is met:
{Paragraph seven of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
the leased object is transferred for a period during which at least 75 percent of its original cost is depreciated, and the lessee is obliged, on the basis of the leasing agreement and during its term, to purchase the leased object with the subsequent transfer of ownership from the lessor to the lessee at the price specified in such leasing agreement;
{Paragraph of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1605-IX of 07/01/2021 }
the book value (residual) of the leased object at the time of the expiration of the leasing agreement provided for by such agreement is no more than 25 percent of the initial value of the price of such leased object, effective at the beginning of the lease agreement;
the amount of leasing payments specified in the leasing agreement at the time of conclusion of such agreement is equal to or exceeds the initial cost of the leasing object;
{Paragraph ten of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
Property transferred for leasing, manufactured to the order of the lessee and after the expiration of the leasing agreement cannot be used by persons other than the lessee, based on its technological and quality characteristics.
{Paragraph eleven of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
The term "financial leasing term" should be understood as the term stipulated in the leasing agreement, which begins on the date of transfer of the risks associated with the storage or use of the property, or the right to receive any benefits or rewards associated with its use, or any other rights arising from the rights to own, use or dispose of such property, to the lessee and ends on the expiry date of the leasing agreement, including any period during which the lessee has the right to make a sole decision to extend the leasing term in accordance with the terms of the agreement.
{Paragraph twelfth of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
Regardless of whether a business transaction is regulated by the norms of this subparagraph or not, the parties to the contract have the right, when concluding the contract (transaction), to define such a transaction as an operating lease without the right to further change the status of such a transaction until the expiration of the relevant contract;
c) leaseback - a transaction carried out by an individual or legal entity and involving the sale of fixed assets to a financial institution (lessor) with the simultaneous return of such fixed assets by such individual or legal entity (lessee) under operating lease (rent) or financial lease;
{Paragraph fourteen of subparagraph 14.1.97 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
{Paragraph fifteen of subparagraph 14.1.97 of paragraph 14.1 of Article 14 was excluded on the basis of Law No. 1605-IX of 01.07.2021 }
{Paragraph sixteen of subparagraph 14.1.97 of paragraph 14.1 of Article 14 was excluded on the basis of Law No. 1605-IX of 01.07.2021 }
14.1.97 - 1. lease of housing with redemption - a business transaction of a legal entity (lessor), under which the lessor, in accordance with the lease of housing with redemption agreement, transfers to the other party - an individual (tenant) property rights to real estate, the construction of which is not completed, and/or housing for a fee for a long-term (up to 30 years) term, after the expiration of which or early, provided that the rental payments are paid in full and there are no other encumbrances and restrictions on such housing, the housing passes into the ownership of the tenant. Lease of housing with redemption may provide for the assignment of the right to claim payments under the lease of housing with redemption agreement;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.97 - 1 in accordance with Law No. 1605-IX of 01.07.2021 }
14.1.97 - 2. rental of residential premises - a transaction that involves the provision of a residential building, apartment or part thereof by its owner to the tenant for possession and use for a specified period for targeted use for a rental fee;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.97 - 2 in accordance with Law No. 1605-IX of 01.07.2021 }
14.1.98. forest lands - land plots on which forest plots are located;
14.1.99. license - within the meaning given in the Commercial Code of Ukraine ;
14.1.100. Lombard transaction - a transaction carried out by an individual or legal entity to obtain funds from a legal entity that is a financial institution, in accordance with the legislation of Ukraine, against the collateral of goods or currency values. Lombard transactions are a type of collateralized loan;
14.1.101. lottery - a mass game, regardless of its name, the terms of which provide for the drawing of a prize (winning) fund between its players, the prize (winning) in which is of a random nature and the territory of which is not limited to one room (building). Lottery activities are regulated by a special law. Games held free of charge by legal entities and individual entrepreneurs and aimed at advertising their goods (paid services), promoting their sale (provision) are not considered to be lotteries, provided that the organizers of these games spend their profit (income) on their holding;
14.1.102. duty-free shop - an establishment trading in goods that are under the customs regime of duty-free trade in accordance with Chapters 22 and 60 of the Customs Code of Ukraine ;
{Subclause 14.1.102 of clause 14.1 of Article 14 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 4915-VI of 07.06.2012 }
14.1.103. parent companies - legal entities that own other legal entities or exercise control over such legal entities as related parties;
14.1.103 - 1. parent company of an international group of companies (for the purposes of Article 39 of this Code) - a member of an international group of companies that simultaneously meets the following criteria:
directly or indirectly owns the corporate rights of other participants in the international group of companies (or actually controls such participants), and the share of such ownership is sufficient to include the financial statements of such other participants in the international group of companies in the consolidated financial statements of such international group of companies in accordance with international financial reporting standards or other internationally recognized financial reporting standards, or the preparation of consolidated financial statements would be mandatory for such company if the shares (corporate rights) of one of the participants in the relevant international group of companies were traded on a national and/or foreign organized stock market (stock exchange);
the financial statements of such a participant are not subject to inclusion in the consolidated statements of any other participant in the international group of companies in accordance with international financial reporting standards or other internationally recognized financial reporting standards;
{ Clause 14.1 of Article 14 is supplemented by subclause 14.1.103 - 1 in accordance with the Law No. 466-IX dated 01/16/2020 ; as amended by Law No. 2970-IX dated 03/20/2023 }
14.1.104. paid parking areas - the area of the territory (land) owned by the territorial community or the state, on which, in accordance with the decision of the local government body, paid parking of vehicles is carried out;
14.1.105. property - within the meaning given in the Civil Code of Ukraine ;
14.1.106. maximum retail prices - prices set for excisable goods (products, taking into account all types of taxes (fees). Excise tax on excisable goods sold by retail entities is not included in the maximum retail price.
Maximum retail prices for excisable goods (products) shall be established for tobacco products, tobacco, industrial tobacco substitutes and liquids used in electronic cigarettes by manufacturers or importers of goods (products) by declaring such prices in accordance with the procedure established by this Code. Retail trade entities may not sell excisable goods for which maximum retail prices are established at prices higher than the maximum retail prices increased by the amount of excise tax on retail trade of excisable goods. The retail selling price of excisable goods for which maximum retail prices are set (excluding excise tax on the sale of excisable goods by retail business entities) cannot be less than the minimum excise tax liability for the payment of excise tax on tobacco products established on the date of production of such goods, multiplied by a coefficient of 1.45, and for tobacco products for which only a specific excise tax rate is established - less than the specific excise tax rate established on the date of production of such goods, multiplied by a coefficient of 1.45. The maximum retail price for excisable goods (products) established by manufacturers or importers for tobacco products, tobacco, and industrial tobacco substitutes cannot be less than the retail selling price calculated in accordance with this subparagraph.
{Paragraph two of subparagraph 14.1.106 of paragraph 14.1 of Article 14 as amended by Laws No. 1914-IX of 11/30/2021 , No. 4115-IX of 12/04/2024 - for the effect of the amendments, see paragraph 2 of Section II}
{Subclause 14.1.106 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.107. excise tax stamp - a special sign for labeling alcoholic beverages, tobacco products and liquids used in electronic cigarettes, classified as strict accounting documents, which confirms the payment of excise tax, the legality of the import and sale of these products on the territory of Ukraine;
{Subclause 14.1.107 of clause 14.1 of Article 14 as amended by Law No. 466-IX of 16.01.2020 }
14.1.108. marketing services (marketing) - services that ensure the functioning of the taxpayer's activities in the field of market research, stimulation of sales of products (works, services), pricing policy, organization and management of the movement of products (works, services) to the consumer and after-sales service of the consumer within the framework of the economic activity of such a taxpayer. Marketing services include, among others: services for placing the taxpayer's products at points of sale, services for studying, researching and analyzing consumer demand, entering the taxpayer's products (works, services) into sales information databases, services for collecting and distributing information about products (works, services);
14.1.109. labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes - affixing an excise tax stamp to a bottle (packaging) of an alcoholic beverage, a pack (packaging) of a tobacco product or a container (packaging) with liquid used in electronic cigarettes, in accordance with the procedure established by the Cabinet of Ministers of Ukraine regarding the production, storage and sale of excise tax stamps;
{Subclause 14.1.109 of clause 14.1 of Article 14 as amended by Law No. 466-IX of 16.01.2020 }
{Subclause 14.1.110 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.110. electronic office methodologist - central executive body implementing state tax policy;
{Sub-clause 14.1.110 is included in clause 14.1 of Article 14 in accordance with the Law No. 1797-VIII dated 21.12.2016 }
{Subclause 14.1.111 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.111. methodological error of the electronic office - non-compliance of the methodology and/or algorithms of the electronic office with the provisions of tax legislation, which leads to an error, including in the calculation of the object of taxation, the amount of tax, the amount of overpayment of tax, the amount of fines, penalties, calculation formula indicators used in electronic administration systems, other indicators that affect the rights and obligations of taxpayers;
{ Sub-clause 14.1.111 is included in clause 14.1 of Article 14 in accordance with the Law No. 1797-VIII dated 21.12.2016 }
14.1.112. mineral raw materials for the purposes of Section IX of this Code - commodity products of a mining enterprise, which are the result of the economic activity of a mining enterprise in the extraction of minerals in compliance with the established conditions for mineral raw materials of a subsoil object (site) by types of commodity products of a mining enterprise;
{Subclause 14.1.112 of Clause 14.1 of Article 14 as amended by Laws No. 1166-VII of March 27 , 2014 , No. 1797-VIII of December 21, 2016 ; as amended by Law No. 1914-IX of November 30, 2021 }
14.1.113. customs payments - taxes that, in accordance with this Code or customs legislation, are collected during the movement or in connection with the movement of goods across the customs border of Ukraine and control over the collection of which is entrusted to the controlling authorities;
14.1.113 - 1. customs regimes - used in the meaning given in the Customs Code of Ukraine ;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.113 - 1 in accordance with Law No. 4915-VI of 07.06.2012 }
14.1.113 - 2. international postal items, international express items, unaccompanied baggage, personal belongings, hand luggage, accompanied baggage - are used in the meanings given in the Customs Code of Ukraine ;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.113 - 2 in accordance with Law No. 4915-VI of 07.06.2012 }
14.1.113 - 3 . international group of companies (for the purposes of Article 39 of this Code) - two or more legal entities or entities without the status of a legal entity that are tax residents of different jurisdictions (states, territories) (in particular, if at least one of such entities is a tax resident of one foreign jurisdiction (state, territory), which carries out economic activities through a permanent establishment in another jurisdiction (state, territory) and are interconnected by criteria of ownership or control in such a way that, according to international financial reporting standards or other internationally recognized financial reporting standards, the preparation of consolidated financial statements is mandatory or the preparation of consolidated financial statements would be mandatory if the shares (corporate rights) of one of such participants of the international group of companies were traded on a national and/or foreign organized stock market (stock exchange);
{ Clause 14.1 of Article 14 is supplemented by subclause 14.1.113 - 3 in accordance with the Law No. 466-IX dated 01/16/2020 ; as amended by Law No. 2970-IX dated 03/20/2023 }
14.1.114. minimum excise tax liability - the minimum amount of tax liability for payment of excise tax on cigarettes and cigarillos, cigarillos, expressed in a fixed amount per 1000 cigarettes of the same name sold in the customs territory of Ukraine or imported into the customs territory of Ukraine;
{Subclause 14.1.114 of Clause 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 14.1.114 - 1 of clause 14.1 of Article 14 is excluded on the basis of the Law No. 2725-VIII dated 16.05.2019 }
14.1.114 - 2. minimum tax liability - the minimum amount of tax liability for the payment of taxes, fees, payments, control over the collection of which is entrusted to the regulatory authorities, related to the production and sale of one's own agricultural products and/or to the ownership and/or use (lease, sublease, emphyteusis, permanent use) of land plots classified as agricultural land, calculated in accordance with this Code. The amount of minimum tax liabilities determined for each of the land plots, the right to use which belongs to one legal entity or individual, including an individual entrepreneur, is the general minimum tax liability;
{ Clause 14.1 of Article 14 is supplemented by subclause 14.1.114 - 2 in accordance with the Law No. 1914-IX dated 30.11.2021 }
14.1.115. overpaid monetary obligations - amounts of funds that on a certain date were credited to the relevant budget or to a single account in excess of the accrued amounts of monetary obligations, the payment deadline for which has come on such date;
{Subclause 14.1.115 of clause 14.1 of Article 14 as amended by Law No. 190-IX of 04.10.2019 }
14.1.116. non-state pension provision - pension provision provided by non-state pension funds, insurance organizations and banks in accordance with the Law of Ukraine "On Non-State Pension Provision" and/or by insurance organizations under lifelong pension insurance contracts in accordance with the Law of Ukraine "On Compulsory State Pension Insurance" and/or by insurers under supplementary pension insurance contracts in accordance with subparagraph 14.1.52 - 2 of paragraph 14.1 of Article 14 of this Code;
{Subclause 14.1.116 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.117 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.118. insignificant mineral reserves - mineral reserves determined according to criteria established by the Cabinet of Ministers of Ukraine;
14.1.119. non-forest lands - land plots occupied by shrubs, communications, agricultural lands, waters and swamps, low-productive lands, etc.;
{Subclause 14.1.120 of clause 14.1 of Article 14 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
14.1.121. non-profit enterprises, institutions and organizations - non-profit enterprises, institutions and organizations that are not payers of corporate income tax in accordance with Clause 133.4 of Article 133 of this Code;
{Subclause 14.1.121 of clause 14.1 of Article 14 as amended by Law No. 652-VIII of 17.07.2015 }
14.1.122. non-residents are:
a) foreign companies, organizations, partnerships and other associations of persons established in accordance with the legislation of other states, their branches, representative offices and other separate divisions located in the territory of Ukraine, registered (accredited or legalized) in accordance with the legislation of Ukraine, as well as legal entities without the status of a legal entity, established in accordance with the legislation of foreign states or territories that are not residents of Ukraine, in accordance with the provisions of this Code;
{Subparagraph "a" of subparagraph 14.1.122 of paragraph 14.1 of Article 14 as amended by Law No. 2970-IX of March 20, 2023 }
b) diplomatic missions, consular offices and other official representations of other states and international organizations in Ukraine;
c) individuals who are not residents of Ukraine.
If, in accordance with the requirements of an international treaty concluded by Ukraine containing provisions on the exchange of information for tax purposes, the binding consent of which has been granted by the Verkhovna Rada of Ukraine, or an interdepartmental treaty concluded on its basis and this Code, a financial agent is obliged to verify and establish the resident state of the owner or controlling person of the account holder, the provisions of this subparagraph shall apply to the extent that they do not contradict the rules of the international treaty.
{Subclause 14.1.122 of clause 14.1 of Article 14 is supplemented by the fifth paragraph in accordance with Law No. 323-IX of 03.12.2019 ; as amended by Law No. 2970-IX of 20.03.2023 }
For the purposes specified in subparagraph 162.1.2 of paragraph 162.1 of Article 162 of this Code, a separate category of non-resident individuals are prisoners of war - persons entitled to this status in accordance with Article 4 of the Geneva Convention relative to the Treatment of Prisoners of War of August 12, 1949 and Article 44 of the Protocol Additional to the Geneva Conventions of August 12, 1949, and Relating to the Protection of Victims of International Armed Conflicts (Protocol I), of June 8, 1977;
{Sub-clause 14.1.122 of clause 14.1 of Article 14 is supplemented by the sixth paragraph in accordance with the Law No. 4536-IX dated 16.07.2025 }
14.1.122 - 1. non-residents with offshore status - non-residents located in the territory of offshore zones, except for non-residents who have provided the taxpayer with an extract from legal documents, legalized in accordance with the procedure established by law, which indicates the usual (non-offshore) status of such non-resident;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.122 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
14.1.123. non-agricultural lands - economic roads and tracks, field shelterbelts and other protective plantings, except for those classified as forestry lands, lands under farm buildings and yards, lands under the infrastructure of wholesale markets for agricultural products, lands of temporary conservation, etc.;
14.1.124. new vehicle - a vehicle that does not have state registration certificates from authorized bodies, including foreign ones, which give the right to operate it;
14.1.124 - 1 new well (for the purposes of implementing the provisions of Section IX of this Code) - a well, drilling of which was started from the surface of the land (zero meter level according to the well design) after January 1, 2018, which is confirmed by the act of commissioning the drilling rig;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.124 - 1 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 2611-VIII of 08.11.2018 }
14.1.125. normative monetary valuation of land plots for the purposes of Section XII , Chapter 1, Section XIV of this Code - capitalized rental income from a land plot, determined in accordance with the legislation by the central executive body implementing state policy in the field of land relations;
{Subclause 14.1.125 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.125 - 1. standard of expenses for payments to insurance intermediaries - the maximum permissible amount of any payments (remuneration) to insurance intermediaries and other persons for services provided in connection with the conclusion (prolongation) of insurance contracts, established for the purposes of this Code according to the methodology determined by the authorized body carrying out state regulation in the field of financial services markets, in agreement with the central executive body that ensures the formation and implementation of state financial policy;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.125 - 1 in accordance with Law No. 2628-VIII of 23.11.2018 }
14.1.126. volume of extracted hydrocarbon raw materials:
a) for the purposes of Section IX - the volume of oil, natural gas (including associated (petroleum) gas), gas condensate within the meaning given in subparagraph 14.1.128 of this Article, which, in accordance with the procedure specified in the rules for the extraction of hydrocarbon raw materials, is recorded immediately after the points of their preparation using instrumentation;
{Subparagraph "a" of subparagraph 14.1.126 of paragraph 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
b) for the purposes of Section XVIII - produced products within the meaning given in the Law of Ukraine "On Production Sharing Agreements" . In cases where produced products are accounted for and used by the investor as fuel or raw materials, the volume of extracted hydrocarbon raw materials is determined in accordance with the procedure provided for in subparagraph "a" of this paragraph;
{Subclause 14.1.126 of clause 14.1 of Article 14 as amended by Laws No. 5412-VI of 02.10.2012 , No. 1166-VII of 27.03.2014 }
14.1.127. cargo volume - the volume under the contract between the carrier and the consignor, which is subject to transportation (movement) by means of pipeline transport in accordance with the essential terms (volumes, terms and relevant routes) of the relevant contract for the provision of transport services;
14.1.128. volume of extracted minerals (mineral raw materials) - the volume of commodity products of a mining enterprise, the types of which are established by the approved conditions for mineral raw materials of a subsoil object (site), which, in accordance with Accounting Regulation (Standard) 9 "Reserves", is accounted for by a mining enterprise as reserves - assets, the value of which can be reliably determined, for which there is a probability of their owner - a business entity receiving economic benefits associated with their use as goods, and which consist of: raw materials intended for servicing other than those classified in section B of KVED DK 009:2010 , production, including through the execution of business contracts for services with toll raw materials, and administrative needs; finished products manufactured at a mining enterprise, including through the execution of business contracts for services with toll-based raw materials, intended for sale and meeting the technical and quality characteristics stipulated by the contract or regulatory legal act;
{Subclause 14.1.128 of clause 14.1 of Article 14 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 1914-IX of 11/30/2021 }
14.1.129. residential real estate objects - buildings registered in accordance with the legislation as residential real estate objects, summer houses and garden houses;
{Subclause 14.1.129 of Clause 14.1 of Article 14 as amended by Law No. 2600-IX of 20.09.2022 }
14.1.129.1. Buildings registered in accordance with the legislation as residential real estate objects, as well as their components that are independent real estate objects, in particular, include:
{Paragraph one of subparagraph 14.1.129.1 of subparagraph 14.1.129 of paragraph 14.1 of Article 14 as amended by Law No. 2600-IX of 20.09.2022 }
a) residential building - a capital-type building, constructed in compliance with the requirements established by law, other regulatory legal acts, and intended for permanent residence in it. Residential buildings are divided into estate-type residential buildings and apartment-type residential buildings of various storeys. Estate-type residential building - a residential building located on a separate land plot, which consists of residential and auxiliary (non-residential) premises (hallway, kitchen, corridor, veranda, toilet, pantry, premises for an autonomous heating system, laundry, etc.);
{Paragraph two of subparagraph 14.1.129.1 of subparagraph 14.1.129 of paragraph 14.1 of Article 14 as amended by Law No. 2600-IX of 20.09.2022 }
b) an extension to a residential building - a part of the building located outside the contour of its capital external walls and which has one (or more) common capital wall with the main part of the building;
c) apartment - an isolated dwelling in a residential building, intended and suitable for permanent residence;
d) cottage - a one- or one-and-a-half-story house of small living space for permanent or temporary residence with a personal plot;
e) rooms in multi-family (communal) apartments - isolated accommodation in an apartment in which two or more tenants live;
14.1.129.2. garden house - a house for summer (seasonal) use, which in terms of standardization of building area, external structures and engineering equipment does not comply with the standards established for residential buildings;
14.1.129.3. country house - a residential building for use throughout the year for the purpose of country recreation;
{Subclause 14.1.129 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.129 - 1. non-residential real estate objects - buildings, their components, which are not residential real estate objects. Non-residential real estate objects include:
{Paragraph one of subparagraph 14.1.129 - 1 of paragraph 14.1 of Article 14 as amended by Law No. 2600-IX of 20.09.2022 }
a) hotel buildings - hotels, motels, campsites, boarding houses, restaurants and bars, tourist centers, mountain shelters, holiday camps, holiday homes;
b) office buildings - financial service buildings, administrative and residential buildings, buildings for office and administrative purposes;
c) commercial buildings - shopping centers, department stores, shops, covered markets, pavilions and halls for fairs, car service stations, canteens, cafes, snack bars, bases and warehouses of trade and catering enterprises, buildings of consumer service enterprises;
d) garages - garages (above-ground and underground) and covered car parks;
e) industrial buildings and warehouses;
e) buildings for public performances (casinos, gambling houses);
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.129 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
14.1.130. unit area of taxable land plot:
within the boundaries of a settlement - 1 (one) square meter (sq. meter);
outside the settlement - 1 (one) hectare (ha);
14.1.131. homogeneous (similar) goods (works, services) - goods (works, services) that are not identical, but have similar characteristics and consist of similar components, as a result of which they perform the same functions compared to the goods being evaluated and are considered commercially interchangeable.
To determine whether goods are homogeneous (similar), the following characteristics are taken into account:
quality and business reputation in the market;
the presence of a trademark;
country of manufacture (origin);
producer;
year of production;
new or used;
expiration date;
{Subclause 14.1.132 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.133 of clause 14.1 of Article 14 was excluded on the basis of Law No. 2888-IX of 12.01.2023 }
14.1.134. transaction with toll raw materials - an operation for the processing (processing, enrichment or use) of toll raw materials (regardless of the number of customers and performers, as well as stages (operations)) in order to obtain finished products for an appropriate fee. Transactions with toll raw materials include operations in which the customer's raw materials at a specific stage of its processing account for at least 20 percent of the total cost of the finished products;
14.1.135. taxation for the purposes of Section IX of this Code - taxation of rent for the use of subsoil for the extraction of minerals, taxation of rent for the use of subsoil for purposes not related to the extraction of minerals, taxation of rent for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, taxation of rent for the special use of water, taxation of rent for the special use of forest resources, taxation of rent for the transportation of oil and oil products through main oil pipelines and oil product pipelines, transit transportation of ammonia through pipelines through the territory of Ukraine;
{Subclause 14.1.135 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Laws No. 909-VIII of 12/24/2015 , No. 3721-IX of 05/21/2024 }
14.1.136. rent for the purposes of Section XII of this Code - a mandatory payment for the use of a land plot of state or municipal property under lease terms;
{Subclause 14.1.136 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 1914-IX of 11/30/2021 }
14.1.137. collection authority - a state body authorized to take measures to ensure the repayment of tax debt within the limits of the powers established by this Code and other laws of Ukraine;
14.1.137 - 1. authorized person of the regulatory body - an official (service) person of the regulatory body, authorized by the head of such body to perform certain of its functions in accordance with the procedure provided for by this Code;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.137 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
14.1.138. fixed assets - tangible assets, including reserves of minerals provided for use of subsoil plots (except for the cost of land, unfinished capital investments, public roads, library and archival funds, tangible assets, the cost of which does not exceed 20,000 hryvnias, non-production fixed assets and intangible assets), which are designated by the taxpayer for use in the taxpayer's business activities, the cost of which exceeds 20,000 hryvnias and gradually decreases due to physical or moral wear and tear and the expected useful life (operation) of which from the date of commissioning is more than one year (or the operating cycle, if it is longer than a year);
{Subclause 14.1.138 of clause 14.1 of Article 14 as amended by Laws No. 655-VIII of 07/17/2015 , No. 466-IX of 01/16/2020 }
14.1.139. person for the purposes of Section V of this Code - any of the following persons:
a) a legal entity established in accordance with the law in any organizational and legal form, including an enterprise with foreign investments, which:
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 05/24/2012 }
or is a payer of taxes and fees established by this Code, except for the single tax;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 05/24/2012 }
or is a payer of a single tax at a rate that includes payment of value added tax;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 05.24.2012 ; as amended by Law No. 5083-VI of 07.05.2012 ; as amended by Law No. 5503-VI of 11.20.2012 }
or is a payer of a single tax at a rate that includes value added tax as part of the single tax, and voluntarily switches, in accordance with the procedure established by this Code, to paying a single tax at a rate that includes value added tax;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 05.24.2012 ; as amended by Law No. 5083-VI of 07.05.2012 ; as amended by Law No. 5503-VI of 11.20.2012 }
b) an individual entrepreneur who:
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 24.05.2012 }
or is a payer of taxes and fees established by this Code, except for the single tax;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 05/24/2012 }
or is a payer of a single tax at a rate that includes payment of value added tax;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 05.24.2012 ; as amended by Law No. 5083-VI of 07.05.2012 ; as amended by Law No. 5503-VI of 11.20.2012 }
or is a payer of a single tax at a rate that includes value added tax as part of the single tax, and voluntarily switches, in accordance with the procedure established by this Code, to paying a single tax at a rate that includes value added tax;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 05.24.2012 ; as amended by Law No. 5083-VI of 07.05.2012 ; as amended by Law No. 5503-VI of 11.20.2012 }
c) a legal entity, an individual, an individual entrepreneur who imports goods into the customs territory of Ukraine;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4834-VI of 24.05.2012 }
d) permanent representation;
{Paragraph of sub-clause 14.1.139 of clause 14.1 of Article 14 as amended by Laws No. 4834-VI of 05/24/2012 , No. 5503-VI of 11/20/2012 }
e) investor (operator) in accordance with a production sharing agreement, who is responsible for maintaining tax records for value added tax under the production sharing agreement;
{Subclause 14.1.139 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 5412-VI of 02.10.2012 ; with amendments made in accordance with Laws No. 422-VII of 04.07.2013 , No. 1690-VII of 07.10.2014 }
e) a non-resident person who does not have a permanent representative office and supplies electronic services to individuals, including individual entrepreneurs who are not registered as value added tax payers, in the customs territory of Ukraine, including by providing access to electronic services through an electronic interface, providing technical, organizational, informational and other capabilities that are implemented using information technologies and systems, for establishing contacts and concluding agreements between sellers and buyers and/or supplies such electronic services under intermediary agreements on his own behalf, but on behalf of the electronic service provider.
{Subparagraph 14.1.139 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 1525-IX of 03.06.2021 }
The provisions of this subparagraph do not apply to non-residents who:
{Subparagraph 14.1.139 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 1525-IX of 03.06.2021 }
provide electronic services under intermediary agreements, if the invoices (receipts) provided to customers of electronic services specify a list of such electronic services and their actual provider;
{Subparagraph 14.1.139 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 1525-IX of 03.06.2021 }
exclusively process payments for electronic services and do not participate in the provision of such electronic services;
{Subparagraph 14.1.139 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 1525-IX of 03.06.2021 }
provide electronic services directly through their permanent representative office in Ukraine.
{Subparagraph 14.1.139 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 1525-IX of 03.06.2021 }
For tax purposes, two or more persons who carry out joint activities without forming a legal entity are considered a separate person within the scope of such activities.
Accounting for the results of joint activities is carried out by the taxpayer authorized to do so by the other parties in accordance with the terms of the agreement, separately from accounting for the economic results of such taxpayer.
For tax purposes, economic relations between participants in joint activities are equated to relations based on separate civil law contracts.
The procedure for tax accounting and reporting on the results of joint activities is established by the central executive body that ensures the formation and implementation of state financial policy;
{Paragraph sub- item 14.1.139 of item 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
{Subclause 14.1.139 of clause 14.1 of Article 14 as amended by Law No. 4014-VI of 04.11.2011 }
14.1.139 - 1. a person authorized to carry out procurement in the healthcare sector - within the meaning given in the Fundamentals of the Legislation of Ukraine on Healthcare .
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.139 - 1 in accordance with Law No. 532-IX of March 17, 2020 }
14.1.140. official exchange rate (exchange rate) - within the meaning given in the Law of Ukraine "On the National Bank of Ukraine" ;
14.1.141. blended motor fuel - types of fuel obtained as a result of mixing fuel obtained from petroleum raw materials with bioethanol and additives based on bioethanol, biodiesel or other biocomponents, the content of which meets the requirements of regulatory documents for blended motor fuel;
14.1.141 - 1. fuel - petroleum products, liquefied gas, alternative motor fuel, mixed motor fuel, substances used as components of motor fuels, other goods specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.141 - 1 in accordance with Law No. 909-VIII of 24.12.2015 }
14.1.141 - 2. partnership - an association of two or more persons, created in accordance with the legislation of a foreign jurisdiction on the basis of or pursuant to an agreement to conduct business for the purpose of making a profit or achieving another common goal;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.141 - 2 in accordance with Law No. 2970-IX of 20.03.2023 }
14.1.142. mobile source of pollution - a vehicle, the movement of which is accompanied by the emission of pollutants into the atmosphere;
14.1.143. transmission devices - land improvements created to perform special functions of transmitting energy, matter, signal, information, etc. of any origin and type over a distance (power lines, pipelines, water pipes, heat and gas networks, communication lines, etc.);
14.1.144. beer - a foamy alcoholic beverage saturated with carbon dioxide with an alcohol content of more than 0.5% vol., obtained as a result of fermentation of beer wort with brewer's yeast, belonging to commodity group 2203 00 according to the UKT FEA;
{Subclause 14.1.144 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 3553-IX of 01/16/2024 ; as amended by Law No. 4115-IX of 12/04/2024 }
14.1.144 - 1. document for the purposes of this Code - a document created in paper or electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" , the preparation and/or submission and/or sending of which is provided for by this Code, other regulatory legal acts adopted on the basis of and in implementation of this Code, and/or is related to the exercise of the rights and obligations of the taxpayer and/or regulatory authorities in accordance with the provisions of this Code;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.144 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 ; with amendments made in accordance with the Law No. 2725-VIII dated 16.05.2019 }
14.1.144 - 2. non-alcoholic beer - a carbonated foamy beverage with an alcohol content of 0.5% vol. or less, obtained as a result of fermentation of beer wort with brewer's yeast, which belongs to commodity heading 2202 according to the UKT FEA;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.144 - 2 in accordance with Law No. 4115-IX of 04.12.2024 }
14.1.145. excisable goods (products) - goods by codes in accordance with the UKT Foreign Economic Activity, for which excise tax rates are established by this Code;
{Subclause 14.1.146 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.146 - 1. Reportable Account - a financial account that meets the definition of the term "U.S. Reportable Account" under the FATCA Agreement and/or is defined as a Reportable Account under the rules of the CRS Common Reporting Standard for the purposes of the CRS Multilateral Agreement;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.146 - 1 in accordance with Law No. 323-IX of 03.12.2019 ; as amended by Law No. 2970-IX of 20.03.2023 }
14.1.147. land payment - a mandatory payment as part of the property tax levied in the form of land tax or rent for land plots of state and municipal property;
{Subclause 14.1.147 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
14.1.148. excise tax stamp fee - a fee paid by domestic producers and importers of alcoholic beverages, tobacco products and liquids used in electronic cigarettes to cover the costs of production, storage and sale of excise tax stamps. The amount of the excise tax stamp fee is established by the Cabinet of Ministers of Ukraine;
{Subclause 14.1.148 of clause 14.1 of Article 14 as amended by Law No. 466-IX of 16.01.2020 }
14.1.149. rent payer for the purposes of Section IX of this Code - rent payer for the use of subsoil for the extraction of minerals, rent payer for the use of subsoil for purposes not related to the extraction of minerals, rent payer for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, rent payer for the special use of water, rent payer for the special use of forest resources, rent payer for the transportation of oil and oil products through main oil pipelines and oil product pipelines, transit transportation of ammonia through pipelines across the territory of Ukraine;
{Subclause 14.1.149 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Laws No. 909-VIII of 12/24/2015 , No. 3721-IX of 05/21/2024 }
14.1.150. primary processing (enrichment) of mineral raw materials for the purposes of Section IX of this Code, as a type of economic activity of a mining enterprise, includes a set of operations: collection, crushing or grinding, drying, sorting by any physical properties of crushed or ground rocks or mineral formations using any technological sorting processes that ensure the mining enterprise obtains marketable products, the types of which are established by the approved conditions for mineral raw materials of the subsoil object (site);
{Subclause 14.1.150 of Clause 14.1 of Article 14 as amended by Laws No. 1166-VII of 03/27/2014 , No. 71-VIII of 12/28/2014 , No. 1797-VIII of 12/21/2016 ; as amended by Law No. 1914-IX of 11/30/2021 }
{Subclause 14.1.151 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.151 - 1. pre-sale preparation for the purposes of Section IX of this Code, as a type of economic activity of a mining enterprise, includes technological operations that are selected by the mining enterprise to ensure: fulfillment of the terms of contracts for the supply of commodity products of the mining enterprise or compliance with the requirements for consumer properties of commodity products of the mining enterprise (briquetting, agglomeration and/or pelletization (with or without heat treatment); packaging, including bottling);
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.151 - 1 in accordance with Law No. 1914-IX of 30.11.2021 }
14.1.152. repayment of tax debt - a reduction in the absolute value of the amount of such debt, confirmed by a relevant document;
14.1.153. tax claim - a written claim of a regulatory authority to a taxpayer regarding the repayment of the amount of tax debt;
14.1.154. tax debt in international legal relations - a monetary obligation, taking into account penalties, fines if any, and expenses related to its collection, unpaid within the established period, which, on the basis of a relevant document of a foreign state, is the subject of collection that may be applied in accordance with an international treaty of Ukraine;
14.1.155. tax lien - a method of securing payment by a taxpayer of a monetary obligation and penalties not paid by such taxpayer within the period specified by this Code. Tax lien arises on the grounds established by this Code.
In the event of a taxpayer's failure to fulfill a monetary obligation secured by a tax lien, the collection agency shall, in accordance with the procedure specified by this Code, levy a levy on the property of such taxpayer that is the subject of the tax lien;
14.1.156. tax liability - the amount of funds that a taxpayer, including a tax agent, must pay to the relevant budget or to a single account as a tax or fee on the basis, in accordance with the procedure and within the time limits specified by tax legislation (including the amount of funds specified by the taxpayer in the tax bill and not paid within the time limit established by law), and/or the amount of funds generated at the expense of tax benefits that were used by the taxpayer for purposes other than their intended purpose or in violation of the procedure for their provision established by this Code and/or the Customs Code of Ukraine ;
{Sub -clause 14.1.156 of clause 14.1 of Article 14 as amended by Laws No. 190-IX of 04.10.2019 , No. 466-IX dated 16.01.2020 }
14.1.156 - 1. tax liability (for the purposes of Section V of this Code) - the total amount of value added tax received (accrued) by the taxpayer in the reporting (tax) period, and/or the amount of funds generated at the expense of tax benefits that were used by the taxpayer for purposes other than their intended purpose or in violation of the procedure for their provision established by this Code;
{ Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.156 - 1 in accordance with the Law No. 466-IX dated 16.01.2020 }
14.1.157. tax notification-decision - a written notification to the regulatory authority (decision) about the taxpayer's obligation to pay the amount of the monetary obligation determined by the regulatory authority in cases provided for by this Code and other legislative acts, the control over the implementation of which is entrusted to regulatory authorities, or to make appropriate changes to the tax reporting;
14.1.158. tax notice in international legal relations - a written notification to the regulatory authority about the taxpayer's obligation to pay the amount of a monetary obligation determined by a document of a foreign state, according to which such amount of a monetary obligation is repaid in accordance with an international treaty of Ukraine;
14.1.158 - 1. tax notice to a non-resident person - a notice that is provided to a non-resident and includes:
1) tax notice to a non-resident person registered as a value added tax payer - a notice in electronic form sent by the central executive body implementing state tax policy, on the obligation of a non-resident person to pay the amount of monetary liability for value added tax determined in accordance with this Code;
2) tax notice to a non-resident person not registered as a value added tax payer - a written notice of the obligation of a non-resident person to register as a value added tax payer in accordance with Article 208-1 of this Code, which is sent by the central executive body implementing state tax policy to the competent body of a foreign state for informing the non-resident person;
3) tax notice to a non-resident person about violation of CRS requirements - a written notice about the obligation of a non-resident person to pay the amount of the monetary obligation and/or fulfill other requirements of Article 39 - 3 this Code insofar as it relates to the implementation of the CRS Multilateral Agreement and the CRS Common Reporting Standard;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1. 158 - 1 in accordance with Law No. 1525-IX of 03.06.2021 ; as amended by Law No. 2970-IX of 20.03.2023 }
{Subclause 14.1. 158 - 2 of clause 14.1 of Article 14 was excluded on the basis of Law No. 2970-IX of 20.03.2023 }
14.1.159. related parties - legal and/or natural persons, and/or entities without legal personality, the relationship between which may affect the conditions or economic results of their activities or the activities of the persons they represent, taking into account the following criteria:
{Sub -clause 14.1.159 of clause 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
a) for legal entities:
one legal entity directly and/or indirectly (through related parties) owns corporate rights of another legal entity in the amount of 25 percent or more (except for international financial organizations that, in accordance with international treaties of Ukraine, are granted privileges and immunities, and business entities in which such international financial organizations own a significant stake of 75 percent or more);
{Paragraph two of subparagraph "a" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
the same legal entity or individual directly and/or indirectly owns corporate rights in each such legal entity in the amount of 25 percent or more;
{Paragraph three of subparagraph "a" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
one and the same legal entity or individual makes decisions on the appointment (election) of single-person executive bodies of each such legal entity;
the same legal entity or individual makes a decision on the appointment (election) of 50 or more percent of the composition of the collegial executive body or supervisory board of each such legal entity;
at least 50 percent of the collegial executive body and/or supervisory board of each such legal entity are composed of the same individuals;
single-person executive bodies of such legal entities are appointed (elected) by decision of the same person (owner or body authorized by him);
a legal entity has the authority to appoint (elect) a sole executive body of such a legal entity or to appoint (elect) 50 or more percent of the composition of its collegial executive body or supervisory board;
the ultimate beneficial owner (controller) of such legal entities is one and the same individual;
{Subparagraph "a" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
the powers of the sole executive body of such legal entities are exercised by one and the same person;
{Subparagraph "a" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
the sum of all credits (loans), repayable financial assistance from one legal entity (except for banks and international financial organizations that, in accordance with international treaties of Ukraine, are granted privileges and immunities, and business entities with a significant stake of 75 percent or more in which such international financial organizations are the owners) and/or credits (loans), repayable financial assistance from other legal entities guaranteed by one legal entity (except for banks and international financial organizations that, in accordance with international treaties of Ukraine, are granted privileges and immunities, and business entities with a significant stake of 75 percent or more in which such international financial organizations are the owners), in relation to another legal entity, exceeds the amount of equity by more than 3.5 times (for financial institutions and companies that conduct exclusively leasing activities - by more than 10 times). In this case, the amount of such credits (loans), repayable financial assistance and equity is determined as the arithmetic average value (at the beginning and end of the reporting period). The provisions of this paragraph do not apply to the amount of credits (loans) attracted under state guarantees;
{Paragraph of subparagraph "a" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by Laws No. 609-VIII of 07/15/2015 , No. 2245-VIII of 12/07/2017 , No. 466-IX of 01/16/2020 }
income (revenue) of a resident legal entity from the sale of products (goods, works, services) (net of indirect taxes) to an individual non-resident legal entity or an individual foreign entity without the status of a legal entity (including a non-resident conducting business through a permanent establishment in Ukraine) during a calendar year constitutes 75 percent or more of the income (revenue) of such a resident legal entity from the sale of products (goods, works, services) (net of indirect taxes) to all non-residents, provided that such income constitutes 50 percent or more of the total amount of income of such a legal entity from the sale of products (goods, works, services) (net of indirect taxes), determined according to accounting rules;
{Subparagraph "a" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 is supplemented by a paragraph in accordance with Law No. 3813-IX of 18.06.2024 }
the value of products (goods, works, services) purchased by a legal entity - a resident from another separate legal entity - a non-resident or a separate foreign entity without the status of a legal entity (including from a non-resident conducting business through a permanent establishment in the territory of Ukraine) during a calendar year is 75 percent or more of the value of products (goods, works, services) purchased by such an entity from all non-residents, provided that the amount of such purchase transactions is 50 percent or more of the total value of products (goods, works, services) purchased by such a legal entity - a resident;
{Subparagraph "a" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 is supplemented by a paragraph in accordance with Law No. 3813-IX of 18.06.2024 }
b) for an individual and a legal entity:
an individual directly and/or indirectly (through related parties) owns corporate rights of a legal entity in the amount of 25 percent or more;
{Paragraph two of subparagraph "b" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
an individual has the right to appoint (elect) a sole executive body of such a legal entity or to appoint (elect) at least 50 percent of the composition of its collegial executive body or supervisory board;
an individual exercises the powers of a sole executive body in such a legal entity;
an individual has the authority to appoint (elect) a sole executive body of such a legal entity or to appoint (elect) 50 or more percent of its collegial executive body or supervisory board;
the individual is the ultimate beneficial owner (controller) of the legal entity;
{Subparagraph "b" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
the sum of all credits (loans), repayable financial assistance from an individual provided to a legal entity, and/or any credits (loans), repayable financial assistance from other individuals provided to a legal entity, which are provided under the guarantees of this individual, exceed the amount of equity by more than 3.5 times (for financial institutions and companies engaged exclusively in leasing activities - by more than 10 times). In this case, the sum of such credits (loans), repayable financial assistance and equity is determined as the arithmetic average value (at the beginning and end of the reporting period);
{Paragraph of subparagraph "b" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by Law No. 609-VIII of 15.07.2015 }
c) for individuals - husband (wife), parents (including adoptive parents), children (adults/minors, including adopted children), full and half-brothers and sisters, guardian, custodian, child under guardianship or trusteeship.
All corporate rights owned (directly and/or indirectly) by a legal entity in another legal entity are the sum of the shares of corporate rights that:
directly owned by such legal entity in another legal entity;
owned by any of the related parties of such legal entity in another legal entity.
For the purposes of determining whether an individual directly and/or indirectly owns corporate rights of 25 percent or more in a legal entity, all corporate rights owned (directly and/or indirectly) by an individual are the sum of the shares of corporate rights that:
{Paragraph five of subparagraph "c" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
directly and/or indirectly owned by such an individual in a legal entity through the possession of corporate rights;
{Paragraph six of subparagraph "c" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
belong to any related persons of such individual in the specified legal entity (excluding persons related to such individual through direct and/or indirect ownership of corporate rights).
{Paragraph seven of subparagraph "c" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by the Law No. 466-IX dated 16.01.2020 }
If an individual is recognized as related to other persons in accordance with subparagraph 14.1.159 of this paragraph, such persons are recognized as related to each other.
{Sub-paragraph "c" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2245-VIII of 07.12.2017 ; with amendments made in accordance with the Law No. 466-IX dated 16.01.2020 }
In the event of business transactions by entities without the status of a legal entity with a related party of any of the participants in the joint activity agreement, the size of whose contributions to the joint property is 25 percent or more, the entities without the status of a legal entity (joint activity agreement) and such a related party of any of the participants in such an agreement shall be recognized as related.
{Subparagraph "c" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
The size of the share of ownership of corporate rights is calculated in the case of:
indirect ownership (in one chain) - by multiplying the ownership shares by corporate rights;
ownership across multiple chains - by summing the shares of ownership of corporate rights in each chain.
In the event that the share of ownership of corporate rights of each person in the next legal entity in the chain is 25 percent or more, all persons in such a chain are related (regardless of the results of multiplication).
{Paragraph of subparagraph "c" of subparagraph 14.1.159 of paragraph 14.1 of Article 14 as amended by Laws No. 2245-VIII of 07.12.2017 , No. 3813-IX of 18.06.2024 }
Direct or indirect participation of the state in legal entities is not a basis for recognizing such legal entities as related. Such taxpayers may be recognized as related on other grounds provided for in this subparagraph.
In the presence of the circumstances specified in the first paragraph of this subparagraph, legal entities and/or individuals who are parties to a business transaction have the right to independently recognize themselves as related persons for tax purposes on grounds not provided for in subparagraphs "a" - "c" of this subparagraph.
{Paragraph of sub-clause 14.1.159 of clause 14.1 of Article 14 as amended by Law No. 609-VIII of 15.07.2015 }
The supervisory authority, based on the results of the inspection or in court, may prove the connection of persons based on facts and circumstances that one legal entity or individual exercised actual control over the business decisions of another legal entity, an entity without the status of a legal entity and/or that the same individual or legal entity exercised actual control over the business decisions of each legal entity and/or entity without the status of a legal entity.
{Paragraph of sub-clause 14.1.159 of clause 14.1 of Article 14 as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 3813-IX dated 18.06.2024 }
{Subclause 14.1.159 of clause 14.1 of Article 14 as amended by Law No. 408-VII of 04.07.2013 ; as amended by Law No. 657-VII of 24.10.2013 ; as amended by Law No. 72-VIII of 28.12.2014 }
14.1.160. pension contribution - funds deposited in a non-state pension fund, insurance organization or on a pension deposit account in a banking institution within the framework of non-state pension provision or paid to the Accumulative Pension Fund of the mandatory state pension insurance (hereinafter referred to as the Accumulative Fund) in accordance with the law. For taxation purposes, a pension contribution is not the only contribution to the mandatory state social insurance;
14.1.161. pension contribution - funds deposited into a pension deposit account opened in a banking institution under a pension deposit agreement in accordance with the law;
14.1.162. penalty - an amount of money in the form of interest accrued on the amounts of tax liabilities and/or on the amounts of fines (financial) sanctions not paid within the time limits established by law, as well as accrued in other cases and in accordance with the procedure provided for by this Code or other legislation, the control over compliance with which is entrusted to regulatory authorities;
{Subparagraph 14.1.162 of paragraph 14.1 of Article 14 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
14.1.163. first registration of a vehicle - registration of a vehicle carried out by authorized state bodies of Ukraine for this vehicle in Ukraine for the first time;
14.1.164. plan - schedule of documentary on-site inspections - a list of taxpayers subject to scheduled inspections by regulatory authorities in the relevant period of the calendar year;
14.1.165. tax, taxpayer, taxation, taxable profit for the purposes of Section III of this Code - corporate profit tax, corporate profit tax payer, taxation by corporate profit tax, taxable profit;
14.1.166. tax, taxpayer, taxation, taxable income for the purposes of Section IV of this Code - personal income tax, personal income tax payer, taxation by personal income tax, taxable income of an individual;
14.1.167. excluded;
14.1.167. REPO transaction - a transaction of purchase (sale) of securities with an obligation to resell (purchase) them after a specified period at a pre-agreed price, carried out on the basis of a single REPO agreement. For the purposes of this Code, the period between the dates of execution of the first and second parts of the REPO transaction (REPO term) may not exceed one year;
{Sub-clause 14.1.167 is included in clause 14.1 of Article 14 in accordance with Law No. 3609-VI of 07.07.2011 }
{Subclause 14.1.168 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.169 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.170. tax deduction for individuals who are not business entities - a documented amount (value) of expenses of a resident taxpayer in connection with the purchase of goods (works, services) from residents - individuals or legal entities during the reporting year, by which his total annual taxable income received as a result of such reporting year in the form of wages and/or in the form of dividends is allowed to be reduced, in cases specified by this Code;
{ Subparagraph 14.1.170 of paragraph 14.1 of Article 14 as amended by Law No. 1946-IX of 14.12.2021 }
14.1.171. tax information - within the meaning defined by the Law of Ukraine "On Information" ;
14.1.172. tax advice - individual tax advice and general tax advice provided in accordance with the procedure provided for by this Code;
{Subclause 14.1.172 of clause 14.1 of Article 14 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 1797-VIII of 12/21/2016 }
14.1.172 - 1. individual tax consultation - an explanation of the regulatory authority provided to the taxpayer regarding the practical use of certain norms of tax and other legislation, control over compliance with which is entrusted to the regulatory authority, and registered in the unified register of individual tax consultations;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.172 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
14.1.172 - 2. FATCA Agreement - Agreement between the Government of Ukraine and the Government of the United States of America to improve the implementation of tax rules and the application of the provisions of the US Foreign Account Tax Compliance Act (FATCA);
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.172 - 2 in accordance with Law No. 2970-IX of 20.03.2023 }
14.1.173. excluded;
14.1.173. generalizing tax advice - the publication of the position of the central executive body that ensures the formation and implementation of state financial policy, regarding the practical use of individual norms of tax and other legislation, control over compliance with which is entrusted to regulatory authorities, which is formed based on the results of generalizing individual tax advice provided by regulatory authorities to taxpayers, and/or in the event of the identification of circumstances indicating the ambiguity of individual norms of such legislation;
{Sub-clause 14.1.173 is included in clause 14.1 of Article 14 in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 655-VIII of 17.07.2015 , No. 1797-VIII of 21.12.2016 }
{Subclause 14.1.174 of clause 14.1 of Article 14 was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
14.1.175. tax debt - the amount of an agreed monetary obligation not paid by the taxpayer within the period established by this Code, and the outstanding penalty accrued in accordance with the procedure specified by this Code;
{Subclause 14.1.175 of clause 14.1 of Article 14 as amended by Laws No. 3609-VI of 07.07.2011 , No. 1797-VIII of 21.12.2016 }
14.1.176. tax bill endorsed by a bank (tax receipt) (hereinafter referred to as a tax bill for the purposes of Section VI of this Code) - a promissory note endorsed by a bank, issued by the drawer: to receive ethyl alcohol from an excise warehouse, to receive petroleum products, substances used as components of motor fuels from an oil refinery, or to import petroleum products into the customs territory of Ukraine and is a security for the fulfillment of the obligation to pay the amount of excise tax within the period specified in Articles 225 , 229 of this Code;
{Subclause 14.1.176 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
{Subclause 14.1.176 - 1 of clause 14.1 of Article 14 was excluded on the basis of Law No. 407-VII of 04.07.2013 }
14.1.177. tax post - a post established on the territory of enterprises where products are produced using excisable goods for which a zero tax rate is established, as defined in Article 229 of this Code. Permanent direct control at the tax post is carried out by permanent representatives of the controlling authority at its location;
{Subclause 14.1.177 of clause 14.1 of Article 14 as amended by Law No. 1638-VII of 12.08.2014 }
14.1.178. value added tax - an indirect tax that is charged and paid in accordance with the provisions of Section V of this Code;
{Subclause 14.1.179 of clause 14.1 of Article 14 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
14.1.180. tax agent for personal income tax - a legal entity (its branch, department, other separate subdivision), a self-employed person, a representative office of a non-resident legal entity, an investor (operator) under a production sharing agreement, which, regardless of the organizational and legal status and the method of taxation by other taxes and/or the form of accrual (payment, provision) of income (in monetary or non-monetary form), are obliged to calculate, withhold and pay the tax provided for in Section IV of this Code to the budget on behalf and at the expense of the individual from the income paid to such person, maintain tax records, submit tax reports to regulatory authorities and be liable for violation of its norms in accordance with the procedure provided for in Article 18 and Section IV of this Code;
{Subclause 14.1.180 of clause 14.1 of Article 14 as amended by Law No. 5412-VI of 02.10.2012 }
14.1.181. tax credit - the amount by which a value added tax payer has the right to reduce the tax liability for the reporting (tax) period, determined in accordance with Section V of this Code;
14.1.182. erroneously paid monetary obligations - amounts of funds that on a certain date were received by the relevant budget and/or a single account from legal entities (their branches, departments, other separate subdivisions that do not have the status of a legal entity) or individuals (that have the status of business entities or do not have such status) that are not payers of such monetary obligations, and in cases provided for by Article 35 - 1 of this Code;
{Subclause 14.1.182 of clause 14.1 of Article 14 as amended by Law No. 190-IX of 04.10.2019 }
14.1.182 - 1. technical error - any error, defect or defect in the operation of the components of the electronic office, electronic signature or other means of electronic identification, which leads to inconsistency of the methodology and/or algorithms of the operation of the electronic office and is not a methodological error;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.182 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2725-VIII of 16.05.2019 ; as amended by Law No. 786-IX of 14.07.2020 ; as amended by Law No. 2918-IX of 07.02.2023 }
14.1.182 - 2. technical failure - any violations in the operation of the components of the electronic office, which are not methodological and/or technical errors, including their complete stoppage, which makes it impossible for the taxpayer to interact with the supervisory authority;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.182 - 1 in accordance with Law No. 786-IX of July 14, 2020 }
14.1.183. personnel provision service - a commercial or civil law agreement, according to which the person providing the service (resident or non-resident) sends one or more individuals to another person (resident or non-resident) to perform the functions specified in this agreement. The agreement on the provision of personnel may provide for the conclusion by the said individuals of an employment agreement or employment contract with the person to whose disposal they are sent. Other terms of the provision of personnel (including the remuneration of the person providing the service) are determined by agreement of the parties;
{Subclause 14.1.184 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.185. supply of services - any transaction that is not a supply of goods, or another transaction for the transfer of rights to intellectual property rights and other intangible assets or the granting of other property rights in relation to such intellectual property rights, as well as the provision of services consumed in the process of performing a certain action or carrying out a certain activity.
For the purpose of taxation of the supply of services, in particular, there are:
a) reaching an agreement to refrain from a certain action or from competing with a third party or granting permission for any action subject to the conclusion of a contract;
b) provision of services by decision of a state authority or local government body or by compulsion;
c) the provision of services to another person free of charge;
d) transfer of the results of work performed and services provided to a taxpayer authorized under the agreement to keep records of the results of joint activities without the formation of a legal entity, as well as their return by such taxpayer after the end of joint activities;
e) transfer (contribution) of performed work and services provided as a contribution to joint activities without the formation of a legal entity, as well as the return of services;
e) provision of services for placing the relevant trademark sign or the product or service itself in a film, series or television program that are visual (viewers only see the product or trademark sign, the product or trademark is mentioned in a character's conversation; the product, service or trademark is organically woven into the plot and is part of it);
14.1.186. tax; taxation; taxpayer; taxable transaction for the purposes of Section V of this Code - respectively, value added tax; taxation by value added tax; value added tax payer; transaction subject to value added tax;
14.1.187. tax, taxpayer, taxation, tax rate for the purposes of Section VI of this Code - excise tax, excise tax payer, taxation by excise tax, excise tax rate;
{Subclause 14.1.188 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.189 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.190. purchaser of excise tax stamps - a business entity that, in accordance with the legislation of Ukraine, is a payer of excise tax on alcoholic beverages, tobacco products and liquids used in electronic cigarettes;
{Subclause 14.1.190 of clause 14.1 of Article 14 as amended by Law No. 466-IX of 16.01.2020 }
14.1.191. supply of goods - any transfer of the right to dispose of goods as the owner, including the sale, exchange or donation of such goods, as well as the supply of goods by court order.
For the purpose of applying the term "supply of goods", electrical and thermal energy, gas, steam, water, air, refrigerated or conditioned, are considered goods.
The following are also considered to be the supply of goods:
a) the actual transfer of tangible assets to another person on the basis of a financial leasing agreement (return of tangible assets under a financial leasing agreement) or other arrangement under which payment is deferred, but ownership of the tangible assets is transferred no later than the date of the last payment;
b) transfer of ownership of tangible assets by decision of a state authority or local government body or in accordance with legislation;
c) any of the specified actions of the taxpayer in relation to tangible assets, if the taxpayer had the right to attribute the tax amounts to a tax credit in the event of the acquisition of the specified property or part thereof (free transfer of property to another person; transfer of property within the taxpayer's balance sheet that is used in the taxpayer's business activities for its further use for a purpose unrelated to the business activities of such taxpayer; transfer within the taxpayer's balance sheet of property that was planned for use in taxable transactions for its use in transactions that are exempt from taxation or not subject to taxation);
d) transfer (contribution) of goods (including non-current assets) as a contribution to joint activities without the formation of a legal entity, as well as their return;
{Sub-paragraph "g" of subparagraph 14.1.191 of paragraph 14.1 of Article 14 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
e) liquidation by a taxpayer at his own request of non-current assets held by such taxpayer;
e) transfer of goods under a contract under which a commission (remuneration) is paid for the sale or purchase.
The cases when fixed assets or non-productive assets are liquidated due to their destruction or destruction due to force majeure circumstances, as well as in other cases when such liquidation is carried out without the consent of the taxpayer, including in the case of theft of non-current assets, or when the taxpayer provides the supervisory authority with a relevant document on the destruction, dismantling or transformation of non-current assets in another way, as a result of which the non-current asset cannot be used for its original purpose, are not considered to be supplies of goods;
Transactions for the sale, in accordance with the criminal procedural legislation of Ukraine, of goods defined by Part Seven of Article 293 of the Customs Code of Ukraine, carried out by persons specified in Clause 180.2 - 2 of Article 180 of this Code, shall not be considered as the supply of goods;
{Subclause 14.1.191 of clause 14.1 of Article 14 is supplemented by the twelfth paragraph in accordance with Law No. 3474-IX of 21.11.2023 }
{Subclause 14.1.192 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.193. permanent establishment - a permanent place of business through which the economic activity of a non-resident in Ukraine is fully or partially carried out, in particular: a place of management; a branch; an office; a factory; a workshop; a facility or structure for the exploration of natural resources; a mine, an oil/gas well, a quarry or any other place of extraction of natural resources; a warehouse or premises used for the delivery of goods, a server.
For tax purposes, the term "permanent establishment" includes:
{Paragraph two of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
a) a construction site, a construction, assembly or installation facility or related supervisory activities, if the total duration of work related to such site, facility or activity (within the framework of a single project or related projects) carried out by a non-resident through employees or other personnel hired by him for such purposes exceeds 12 months;
{Paragraph three of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
b) the provision of services by a non-resident (except for services for the provision of personnel), including consulting services, through employees hired by him for such purposes, if such activities are carried out (within the framework of a single project or a project related to it) in Ukraine for a period or periods the total duration of which exceeds 183 days in any twelve-month period;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
c) persons who, on the basis of a contract, other transaction or in fact have and usually exercise the authority to negotiate the essential terms of transactions, as a result of which a non-resident concludes agreements (contracts) without a significant change in such terms, and/or to conclude agreements (contracts) on behalf of a non-resident, if the specified activity is carried out by the person in the interests, at the expense and/or for the benefit of exclusively one non-resident and/or persons related to him - non-residents;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
d) persons who, on the basis of a contract, other transaction or in fact, have and usually exercise the authority to hold (store) stocks (goods) belonging to a non-resident, from whose warehouse supplies of stocks (goods) are made on behalf of the non-resident, except for residents - holders of a temporary storage warehouse or a customs warehouse.
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
For the purposes of applying subparagraphs "a" and "b" of this subparagraph, when calculating the total period during which a non-resident carries out activities in Ukraine, the following shall be added to the full consecutive or non-consecutive calendar months of the duration of the project (or related projects), performance of works or provision of services by a non-resident in Ukraine:
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
the duration of the non-resident's activity in Ukraine, carried out over several consecutive or non-consecutive periods, which individually are less than a full calendar month, but in the aggregate exceed 30 days, and
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
the duration of the activities of related persons of this non-resident in Ukraine, if such activities are closely related to the activities of the non-resident defined in subparagraphs "a" and "b" of this subparagraph, and are carried out during several consecutive or non-consecutive periods that are equal to a full calendar month or that are individually less than a full calendar month, but in the aggregate exceed 30 days.
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
For the purposes of applying subparagraphs "c" and "d" of this subparagraph, the presence of actual authority by a person to carry out activities that have the characteristics of a permanent establishment in the interests, at the expense and/or for the benefit of a non-resident may, in particular, but not exclusively, be evidenced by:
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
provision by a non-resident of mandatory instructions (including by means of electronic communication or by transfer of electronic media) and their execution by the person;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
the person's possession and use of the corporate email address of a non-resident and/or his/her related persons for communication with the non-resident and/or with third parties with whom the non-resident has already concluded or will subsequently conclude contracts or other transactions;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
the exercise by a person of the right to own or dispose of stocks (goods) or other assets of a non-resident in Ukraine or a significant part thereof on the basis of the relevant instructions of the non-resident;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
the presence of premises rented by the individual in his/her own name for the storage of property purchased at the expense of a non-resident or which belongs to a non-resident or third parties and is subject to transfer to third parties at the direction of the non-resident, or for other purposes determined by the non-resident.
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
A non-resident is not considered to have a permanent establishment in Ukraine if he carries out economic activities through a resident intermediary, but at the same time the provision by the resident of agency, trust, commission and other similar intermediary services for the sale or purchase of goods (works, services) for the account, in the interests and/or for the benefit of the non-resident is carried out within the framework of the resident's main (ordinary) activity and on ordinary terms. If a resident intermediary acts exclusively or almost exclusively for the account, in the interests and/or for the benefit of one or more non-resident persons who are related persons, such intermediary cannot be considered to act within the framework of the main (ordinary) activity in relation to any of the related non-resident persons, and is recognized as a permanent establishment of such non-resident in Ukraine or each non-resident person, if such non-residents are related persons.
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
A permanent establishment is not:
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
a) use of buildings or structures exclusively for the purpose of storing, displaying goods or products belonging to a non-resident;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
b) storage of stocks (goods or products) belonging to a non-resident solely for the purpose of storage or demonstration;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
c) storage of stocks (goods or products) belonging to a non-resident, exclusively for the purpose of processing by another enterprise;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
d) the maintenance of a permanent place of business solely for the purpose of purchasing goods or merchandise or for collecting information for a non-resident;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
e) placing at the disposal of individuals within the framework of the implementation of agreements on personnel services;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
e) maintenance of a fixed place of business for any other purpose.
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
The maintenance of a fixed place of business solely for the purpose of carrying out any combination of activities mentioned in subparagraphs "a" - "e" of this subparagraph, provided that such activities (their combination) are of a preparatory or auxiliary character for such non-resident, shall not constitute a permanent establishment.
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
A permanent establishment of a non-resident in Ukraine is also recognized if activities in Ukraine are carried out by several non-residents - related persons, if such activities in aggregate go beyond the scope of activities of a preparatory or auxiliary nature for such a group of non-residents - related persons. In such a case, a permanent establishment is recognized for each such non-resident - related person. This paragraph applies only if the activities of such non-residents - related persons in Ukraine constitute, in aggregate, complementary functions of a closely related business process.
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
Recognition of a person as a controlling person in accordance with the provisions of Article 39-2 of this Code does not constitute a permanent establishment;
{Paragraph of subparagraph 14.1.193 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 14.1.193 of clause 14.1 of Article 14 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 71-VIII of 28.12.2014 }
14.1.194. permanent representative (representatives) of the controlling body at the excise warehouse - an official appointed by order of the controlling body at the location of the excise warehouse, who exercises constant direct control over compliance with the established procedure for production, processing (reworking), mixing, bottling, packaging, packing, storage, receipt or issuance of excisable goods (products) in accordance with the procedure approved by the central executive body that ensures the formation and implementation of state financial policy;
{Subclause 14.1.194 of clause 14.1 of Article 14 as amended by Law No. 1797-VIII of 21.12.2016 }
14.1.195. employee - an individual who directly performs a labor function by his own labor in accordance with an employment agreement (contract) concluded with the employer in accordance with the law;
14.1.196. profitable production for the purposes of Section XVIII of this Code - a part of the produced production that is distributed between the investor and the state and is defined as the difference between the produced and compensatory production;
14.1.197. conducting a lottery - an economic activity that includes accepting payment for participation in a lottery (bets), conducting drawings of the lottery prize (winning) fund, paying out winnings (issuing prizes), as well as other operations that ensure the conduct of the lottery;
14.1.198. seller of excise tax stamps - regulatory authorities;
14.1.199. products for the purposes of Section XVIII of this Code - minerals of national and local importance (mineral raw materials) extracted (produced) during the development of mineral deposits;
14.1.200. prize (winning) fund - a set of winnings (prizes), namely funds, property, property rights, which are subject to payment (issuance) to players in the event of their winning in the lottery in accordance with the published conditions of its issuance and holding;
{Subclause 14.1.201 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.202. sale (sale) of goods - any transactions carried out under purchase and sale agreements, barter, delivery and other commercial, civil law agreements that provide for the transfer of ownership rights to such goods for a fee or compensation regardless of the terms of its provision, as well as transactions for the free provision of goods. Transactions for the provision of goods within the framework of contracts for commission (consignment), surety, custody (responsible storage), mandate, trust management, operational leasing (rent), other civil law agreements that do not provide for the transfer of ownership rights to such goods are not considered sales of goods;
14.1.203. sale of work results (services) - any transactions of an economic, civil law nature for the performance of work, provision of services, granting the right to use or dispose of goods, including intangible assets and other objects of property that are not goods, subject to compensation for their value, as well as transactions for the free provision of work results (services). Sale of work results (services) includes, in particular, granting the right to use goods under operating lease (rent) agreements, sale, transfer of rights in accordance with copyright or license agreements, as well as other methods of transferring copyright objects, patents, trademarks for goods and services, other objects of intellectual property rights, including industrial property;
14.1.204. a promissory note endorsed by a bank is a security that certifies the unconditional monetary obligation of the drawer or his order to the bank to pay a certain amount to the holder of the note upon maturity.
A bill of exchange certifies the unconditional monetary obligation of the drawer to pay the corresponding amount of funds to the State Budget of Ukraine and is a tax obligation determined by the drawer independently and agreed upon from the date of registration of the bill of exchange by the controlling body at the location of the drawer, and if the legislation provides for a deferral of payment of customs payments, from the date of customs clearance of the goods under the relevant regime;
14.1.205. adjacent territory - the territory around an apartment building, determined on the basis of relevant urban planning and land management documentation within the relevant land plot on which the apartment building and its buildings and structures are located, and necessary for servicing the apartment building and ensuring the satisfaction of the residential, social and household needs of owners (co-owners) and tenants (lessees) of apartments, as well as non-residential premises located in the apartment building;
{Subparagraph 14.1.205 of paragraph 14.1 of Article 14 as amended by Law No. 4834-VI of 24.05.2012 }
14.1.206. interest - income paid (accrued) by the borrower in favor of the lender as a fee for the use of funds or property borrowed for a specified or indefinite period.
Interest includes:
a) payment for the use of funds or goods (works, services) received on credit;
b) payment for the use of funds attracted to the deposit;
c) payment for the purchase of goods in installments;
d) payment for possession and use of property under financial leasing agreements (excluding the part of the leasing payment provided as compensation for part of the cost of the financial leasing object);
{Paragraph six of subparagraph 14.1.206 of paragraph 14.1 of Article 14 as amended by Law No. 1605-IX of 01.07.2021 }
e) the landlord's remuneration (income) as part of the rental payment under a housing lease agreement with redemption, paid by an individual to a taxpayer in whose favor the right to receive such payments has been assigned.
Interest is accrued as interest on the principal amount of the debt or the value of the property or as fixed amounts. If funds are raised by selling bonds, treasury bills or savings (deposit) certificates issued by the borrower, or by taking into account bills of exchange and carrying out transactions to purchase securities with repurchase, the amount of interest is determined by accruing it to the face value of such a security, paying a fixed premium or profit, or by determining the difference between the placement (sale) price and the redemption (repurchase) price of such a security.
Payments under other civil law contracts, regardless of whether they are set in absolute (fixed) prices or as a percentage of the contract amount or other cost base, are not interest;
14.1.207. metering point - a point at which, in accordance with a production sharing agreement, the measurement of produced products and their division into compensatory and profitable products is carried out;
{Subclause 14.1.208 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.209. point of receipt (departure) and destination - a point that for the relevant cargo is defined as a border crossing point, transshipment complex, point of temporary storage of cargo, including underground natural gas storage, on the territory of Ukraine before its movement outside the state, point of cargo processing on the territory of Ukraine before the movement of cargo outside its borders;
{Subclause 14.1.210 of clause 14.1 of Article 14 was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
{Subclause 14.1.211 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.212. sale of excisable goods (products) - any operations on the customs territory of Ukraine that involve the shipment of excisable goods (products) under purchase and sale agreements, barter, delivery and other commercial, civil law agreements with or without transfer of ownership rights, for payment (compensation) or without such, regardless of the terms of its provision, as well as free shipment of goods, including from toll raw materials, sale by retail business entities of excisable goods.
{Paragraph one of subparagraph 14.1.212 of paragraph 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
Sale of fuel or ethyl alcohol for the purposes of Section VI of this Code - any operations of physical transfer (release, shipment) of fuel or ethyl alcohol with or without transfer of ownership of such fuel or ethyl alcohol, for a fee (compensation) or without such fee in the customs territory of Ukraine from an excise warehouse/mobile excise warehouse:
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented by the second paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2628-VIII of 23.11.2018 }
to the excise warehouse;
{Paragraph of sub-clause 14.1.212 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
to a mobile excise warehouse;
{Paragraph of sub-clause 14.1.212 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
for own consumption or industrial processing;
{Paragraph of sub-clause 14.1.212 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
to any other persons.
{Paragraph of sub-clause 14.1.212 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
The concept of "sale of ethyl alcohol" applies exclusively to business entities engaged in the production of ethyl alcohol.
{Paragraph of sub-clause 14.1.212 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
The following operations for the physical transfer (release, shipment) of fuel on the customs territory of Ukraine are not considered to be the sale of fuel:
{Paragraph of sub-clause 14.1.212 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
in consumer containers with a capacity of up to 5 liters (inclusive), except for operations involving the sale of such fuel by its producers;
{Paragraph of sub-clause 14.1.212 of clause 14.1 of Article 14 as amended by Law No. 2628-VIII of 23.11.2018 }
when using fuel by business entities that are not managers of an excise warehouse/mobile excise warehouse, which is transferred (released, shipped) by the excise tax payer to such business entities exclusively for the needs of their own consumption or industrial processing.
{Paragraph of subparagraph 14.1.212 of paragraph 14.1 of Article 14 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 391-IX of 12/18/2019 }
During the period of the legal regime of martial law or a state of emergency, the following are not considered fuel sales:
{Subparagraph 14.1.212 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2120-IX of March 15, 2022 }
operations on the physical transfer (release, shipment) of fuel on the customs territory of Ukraine, carried out in connection with the forced alienation or seizure of such fuel for the needs of the state in accordance with the Law of Ukraine "On the Transfer, Forced Alienation or Seizure of Property under the Legal Regime of Martial Law or a State of Emergency", provided that in the future its previous owner or a person authorized by him will not take measures to obtain compensation for the forcibly alienated or seized fuel;
{Subparagraph 14.1.212 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2120-IX of March 15, 2022 }
operations on the physical transfer (release, shipment) of fuel on the customs territory of Ukraine, carried out in connection with its transfer to the Armed Forces of Ukraine and voluntary formations of territorial communities, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Protection Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their formations, military units, subdivisions, institutions or organizations formed in accordance with the laws of Ukraine, maintained at the expense of the state budget, for the needs of ensuring the defense of the state, local self-government bodies, as well as in favor of the central executive body that ensures the formation and implementation of state policy in the field of civil defense, civil defense forces and/or health care institutions of state, municipal property, and/or structural units on health care issues of regional, Kyiv and Sevastopol city state administrations without prior or subsequent reimbursement of their cost;
{Subparagraph 14.1.212 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2120-IX of March 15, 2022 }
operations for the physical transfer (release, shipment) of fuel in the customs territory of Ukraine as humanitarian aid in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Subparagraph 14.1.212 of paragraph 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 2120-IX of March 15, 2022 }
Own consumption also includes fueling operations under contract agreements, provided that the following conditions are met:
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
a) customers under contract agreements do not sell fuel to other persons, except for the sale of benzene outside the customs territory of Ukraine under the export customs regime;
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
b) refueling is carried out in the fuel tank of machines, mechanisms, machinery and equipment for the agro-industrial complex, the fuel tank of special-purpose vehicles or the fuel tank of special equipment or devices that:
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
intended for work on agricultural or forest lands, on lands provided to mining enterprises for the extraction of minerals and the development of mineral deposits, as well as for road construction work;
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
belong to other persons;
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
perform work during the term of the contract exclusively on the lands specified in this clause that are owned or used by the customer;
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
c) vehicles that refuel the fuel tank of machines, mechanisms, machinery and equipment for the agro-industrial complex, the fuel tank of special-purpose vehicles or the fuel tank of special equipment or devices specified in subparagraph "b" of this subparagraph must be equipped with flow meters at each point of fuel dispensing in bulk from such a vehicle.
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
Sale by retail entities of excisable goods - sale of beer, alcoholic beverages, tobacco products, tobacco, industrial tobacco substitutes and liquids used in electronic cigarettes, directly to citizens and other end consumers for their personal non-commercial use, regardless of the form of payment, including for bottling in restaurants, cafes, bars, and other catering facilities.
{Paragraph of subparagraph 14.1.212 of paragraph 14.1 of Article 14 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Laws No. 1791-VIII of 12/20/2016 , No. 466-IX of 01/16/2020 }
For the purposes of taxation with excise tax on the sale of excisable goods by retail business entities, spoiled, destroyed goods, or goods whose presence or location is not confirmed by such business entity, including goods whose shortage was identified based on the results of an inventory conducted by a retail business entity (including at the request of the regulatory authority, provided in accordance with subparagraph 20.1.9 of paragraph 20.1 of Article 20 of this Code during an inspection by the regulatory authority), shall be deemed to have been sold directly to citizens and other end consumers for their personal non-commercial use. This provision shall not apply to cases provided for in paragraph 216.3 of Article 216 of this Code;
{Subclause 14.1.212 of clause 14.1 of Article 14 is supplemented by a paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
Transactions for the sale of excisable goods, in accordance with the criminal procedural legislation of Ukraine, as defined in Part Seven of Article 293 of the Customs Code of Ukraine, carried out by persons specified in Clause 212.2 - 1 of Article 212 of this Code, shall not be considered the sale of excisable goods;
{Subparagraph 14.1.212 of paragraph 14.1 of Article 14 is supplemented by paragraph twenty-four in accordance with Law No. 3474-IX of 21.11.2023 }
14.1.213. residents are:
a) legal entities and their separate entities, which are established and conduct their activities in accordance with the legislation of Ukraine, located both on its territory and abroad;
b) diplomatic missions, consular offices and other official representations of Ukraine abroad that have diplomatic privileges and immunities;
c) resident individual - an individual who has a place of residence in Ukraine.
If an individual also has a place of residence in a foreign state, he is considered a resident if such an individual has a permanent residence in Ukraine; if an individual also has a permanent residence in a foreign state, he is considered a resident if he has closer personal or economic ties (center of vital interests) in Ukraine. If the state in which an individual has a center of vital interests cannot be determined, or if an individual does not have a permanent residence in any of the states, he is considered a resident if he is present in Ukraine for at least 183 days (including the day of arrival and departure) during the period or periods of the tax year.
A sufficient (but not exclusive) condition for determining the location of the center of vital interests of an individual is the place of permanent residence of his family members or his registration as a business entity.
If it is impossible to determine the resident status of an individual using the previous provisions of this subparagraph, the individual shall be considered a resident if he or she is a citizen of Ukraine.
If, contrary to the law, an individual who is a citizen of Ukraine also has the citizenship of another country, then for the purpose of taxation with this tax, such an individual is considered a citizen of Ukraine who does not have the right to offset taxes paid abroad, as provided for by this Code or the norms of international agreements of Ukraine.
If an individual is a stateless person and the provisions of paragraphs one to four of this subparagraph do not apply to him, then his status is determined in accordance with the norms of international law.
A sufficient basis for determining a person as a resident is their independent determination of their primary place of residence in the territory of Ukraine in accordance with the procedure established by this Code, or their registration as a self-employed person.
If the term "resident" is used in the relevant cases in Section IV of this Code, this term means "resident individual".
{Paragraph twelfth of subparagraph 14.1.213 of paragraph 14.1 of Article 14 is excluded on the basis of the Law No. 1797-VIII dated 21.12.2016 }
For the purposes of this subparagraph, the acquisition of the status of electronic resident (e-resident) by an individual is not considered a sufficient condition for determining the location of the center of vital interests of an individual;
{Sub -clause 14.1.213 of clause 14.1 of Article 14 is supplemented by the thirteenth paragraph in accordance with Law No. 2654-IX of 06.10.2022 }
14.1.213 - 1. Register of heads of taxpayers - debtors - a register of information about heads of legal entities or permanent representative offices of non-residents, in respect of whom, according to a court decision, a temporary restriction on the right to travel outside Ukraine has been applied due to the presence of such legal entities or permanent representative offices of non-residents of an outstanding tax debt in the amount and within the terms specified by this Code.
The central executive body implementing state tax policy maintains and publishes such a Register in open access on its official web portal.
The procedure for maintaining the Register of Heads of Taxpayers-Debtors is approved by the central executive body that ensures the formation and implementation of state financial policy.
The following data shall be entered into the said Register:
taxpayer name and code according to the Unified State Register of Taxpayers of a legal entity or a permanent representative office of a non-resident;
surname, first name, patronymic (if any) of the head of the legal entity or permanent representative office of the non-resident debtor (according to information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations, provided in accordance with the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations");
date and number of the court decision that has entered into legal force, which establishes a temporary restriction on the right to travel outside Ukraine;
the amount of tax debt as of the date of the court decision;
the amount of tax debt as of the current date;
the date of commencement of the temporary restriction;
the expiry date of the temporary restriction;
grounds for the termination of the temporary restriction;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.213 - 1 in accordance with Law No. 1914-IX of 30.11.2021 }
{Subclause 14.1.214 of clause 14.1 of Article 14 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
{Subclause 14.1.215 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.216. recycled gas - natural gas that is returned (injected) into one or more oil and gas deposits of such a field (well) to maintain the necessary reservoir pressure or reservoir energy in them in accordance with the project for industrial or pilot-industrial development of the field (deposit), as well as the comprehensive project for its development, approved in accordance with the procedure established by law.
{Paragraph one of subparagraph 14.1.216 of paragraph 14.1 of Article 14 as amended by Laws No. 5083-VI of 05.07.2012 , No. 466-IX of 16.01.2020 }
The source of recycled gas may be natural gas: extracted by the subsoil user from a section of oil and gas-bearing subsoil provided to him for use, for which the relevant project provides for the return of such gas to the subsoil; extracted on a subsoil section other than the one specified above, controlled by the subsoil user and transferred (with the payment of an appropriate rental fee) by him for use in such a field; purchased by the subsoil user from third parties for use in such a field;
14.1.217. rent - a state tax levied for the use of subsoil for the extraction of minerals; for the use of subsoil for purposes not related to the extraction of minerals; for the use of the radio frequency spectrum (radio frequency resource) of Ukraine; for the special use of water; for the special use of forest resources; for the transportation of oil and oil products through main oil pipelines and oil product pipelines, transit transportation of ammonia through pipelines across the territory of Ukraine;
{Subclause 14.1.217 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Laws No. 909-VIII of 12/24/2015 , No. 3721-IX of 05/21/2024 }
14.1.218. market of goods (works, services) - the sphere of circulation of goods (works, services), which is determined based on the ability of the buyer (seller) to purchase (sell) goods (works, services) without significant additional costs in the territory closest to the buyer (seller);
14.1.219. market price - the price at which goods (works, services) are transferred to another owner provided that the seller wishes to transfer such goods (works, services), and the buyer wishes to receive them on a voluntary basis, both parties are mutually independent legally and factually, have sufficient information about such goods (works, services), as well as the prices that have developed on the market of identical (and in their absence - homogeneous) goods (works, services) under comparable economic (commercial) conditions;
14.1.220. year of manufacture of a vehicle - the calendar date of manufacture of the vehicle (day, month, year); for vehicles whose calendar date of manufacture cannot be determined - January 1 of the year of manufacture specified in the registration documents;
14.1.221. tax risk (compliance risk) - the probability of failure by a taxpayer to fulfill the tax obligation to register as a taxpayer, register for certain types of taxes, submit (timely submit) tax reports, declare (completely declare), pay (timely and fully pay) tax liabilities, other tax obligations, failure by a taxpayer to fulfill other legislation, control over compliance with which is entrusted to regulatory authorities;
{Subparagraph 14.1.221 of paragraph 14.1 of Article 14 as amended by Law No. 3813-IX of 18.06.2024 }
14.1.221 - 1. compliance - a system of measures and procedures carried out by the supervisory authorities, defined by subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, in order to increase the level of voluntary fulfillment of tax and other obligations by taxpayers in accordance with the requirements of tax and other legislation, control over compliance with which is entrusted to the supervisory authorities, and to reduce the likelihood of tax risk (compliance risk);
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.221 - 1 in accordance with Law No. 3813-IX of 18.06.2024 }
14.1.222. employer - a legal entity (its branch, department, other separate subdivision or its representative office) or a self-employed person who uses the hired labor of individuals on the basis of concluded employment agreements (contracts) and is obliged to pay them wages, as well as to calculate, withhold and pay personal income tax to the budget, contributions to the payroll fund, and other obligations stipulated by law.
For the purposes of Section IV of this Code, an employer is considered to be a legal entity (its branch, department, other separate subdivision or its representative office), a permanent representative office of a non-resident or a self-employed person who accrues (pays) income for the performance of work and/or the provision of services under a civil law contract if it is established that the relationship under such contract is actually employment;
14.1.223. waste disposal - permanent (final) residence or burial of waste in specially designated places or facilities (waste disposal sites, storage facilities, landfills, complexes, structures, subsoil areas, etc.), for the use of which permits have been obtained from authorized bodies;
{Subclause 14.1.223 of clause 14.1 of Article 14 as amended by Laws No. 4834-VI of 05.24.2012 , No. 5083-VI of 07.05.2012 }
14.1.224. excise warehouse manager - a business entity that has received a license for the right to produce ethyl alcohol and alcoholic beverages, registered as an excise tax payer, or a business entity - an excise tax payer that carries out production, processing (refining), mixing, bottling, loading and unloading, storage, and sale of fuel at an excise warehouse and has documents confirming the right of ownership or use of premises and/or territory related to the excise warehouse;
{Subclause 14.1.224 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 2628-VIII of 23.11.2018 }
14.1.224 - 1. manager of a mobile excise warehouse - a business entity - an excise tax payer who is the owner of fuel or carries out activities related to the production of ethyl alcohol and who, using a vehicle, regardless of who owns such a vehicle:
sells or stores fuel or ethyl alcohol;
imports fuel into the customs territory of Ukraine on which excise tax has been paid or under the conditions specified in Article 229 of this Code.
When transferring ownership of fuel or ethyl alcohol transported and/or stored in a vehicle from one business entity to another, the manager of the mobile excise warehouse changes.
{Subclause 14.1.224 - 1 of clause 14.1 of Article 14 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
A business entity (carrier, forwarder) that transports fuel or ethyl alcohol is not the manager of a mobile excise warehouse;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.224 - 1 in accordance with Law No. 2628-VIII of 23.11.2018 }
14.1.225. Royalty - any payment, including a payment paid by a user of copyright objects and (or) related rights in favor of collective management organizations, in accordance with the Law of Ukraine "On Effective Management of Property Rights of Rightholders in the Field of Copyright and (or) Related Rights", received as a consideration for the use or for granting the right to use an object of intellectual property rights, namely any literary works, works of art or science, including computer programs, other recordings on information carriers, video or audio cassettes, cinematographic films or films for radio or television broadcasting, broadcasts (programs) of broadcasting organizations, other audiovisual works, any rights protected by a patent, any registered trademarks (marks for goods and services), intellectual property rights to a design, secret drawing, model, formula, process, intellectual property rights to information regarding industrial, commercial or scientific experience (know-how).
{Paragraph one of subparagraph 14.1.225 of paragraph 14.1 of Article 14 as amended by Law No. 1914-IX of 11/30/2021 }
Royalty payments received from:
as remuneration for the use of a computer program, if the terms of use are limited to the functional purpose of such program and its reproduction is limited to the number of copies necessary for such use (use by the "end consumer");
for the purchase of copies (instances) of intellectual property objects, including in electronic form, for use according to their functional purpose for final consumption or for resale of such a copy (instance);
for the acquisition of things (including information carriers) in which are embodied or on which are contained the objects of intellectual property rights specified in the first paragraph of this subparagraph, for the use, possession and/or disposal of a person;
for the transfer of rights to objects of intellectual property rights, if the terms of the transfer of rights to the object of intellectual property rights grant the person receiving such rights the right to sell or otherwise alienate intellectual property rights or to publish (disclose) secret drawings, models, formulas, processes, intellectual property rights to information regarding industrial, commercial or scientific experience (know-how), except for cases where such publication (disclosure) is mandatory under the legislation of Ukraine;
for the transfer of the right to distribute copies of software products without the right to reproduce them or if their reproduction is limited to use by the end user;
{Subclause 14.1.225 of clause 14.1 of Article 14 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 2245-VIII of 07.12.2017 }
14.1.226. self-employed person - a taxpayer who is an individual entrepreneur or carries out independent professional activities, provided that such person is not an employee within the framework of such entrepreneurial or independent professional activities.
Independent professional activity - participation of an individual in scientific, literary, artistic, artistic, educational or teaching activities, activities of doctors, private notaries, private executors, lawyers, arbitration managers (property administrators, rehabilitation managers, liquidators), auditors, accountants, appraisers, engineers or architects, a person engaged in religious (missionary) activities, other similar activities, provided that such a person is not an employee or an individual entrepreneur (except for the case provided for in paragraph 65.9 of Article 65 of this Code) and uses the hired labor of no more than four individuals;
{Paragraph two of subparagraph 14.1.226 of paragraph 14.1 of Article 14 as amended by Laws No. 4212-VI of 12/22/2011 , No. 1791-VIII of 12/20/2016 , No. 466-IX of 01/16/2020 }
14.1.226 - 1. service for payers - provision of administrative, consulting, reference, information, electronic and other services related to the implementation of the payer's rights and obligations in accordance with the requirements of tax and other legislation, control over compliance with which is entrusted to the regulatory authority;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.226 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
14.1.227. average number of employees - the number of employees in legal entities, determined according to the methodology approved by the central executive body that ensures the formation of state policy in the field of statistics, taking into account all employees and persons working under civil law contracts and part-time for more than one calendar month, as well as employees of representative offices, branches, departments and other separate units in the equivalent of full-time employment, except for employees who are on leave due to pregnancy and childbirth and on leave to care for a child until the child reaches the age prescribed by law;
{Subclause 14.1.227 of clause 14.1 of Article 14 as amended by Laws No. 4014-VI of 04.11.2011 , No. 4834-VI of 24.05.2012 , No. 5083-VI of 05.07.2012 }
14.1.227 - 1. weighted average retail selling price of cigarettes - the price calculated from the sum of the total cost of all cigarettes (taking into account all taxes, including the amount of excise tax on retail trade in excisable goods) sold by manufacturers in the customs territory of Ukraine and imported by importers into the customs territory of Ukraine for the period from January 1 to December 31 inclusive of the reporting year, divided by the sum of the total number of cigarettes sold by manufacturers and imported by importers for the same period, determined in the excise tax declarations for January - December of the reporting year, calculated per 1,000 pieces;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.227 - 1 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 3878-IX of 18.07.2024 }
14.1.227 - 2. syndicated financial loan - funds provided by several resident banks and/or non-resident banks, or non-residents qualified as a banking institution in accordance with the legislation of the non-resident's country of residence, or residents and/or non-residents who have the status of non-banking financial institutions in accordance with the relevant legislation, as well as a foreign state or its official agencies, international financial organizations and other non-resident creditors (members of the creditor syndicate) within the framework of one credit agreement in certain shares to legal entities for a specified period for targeted use and at interest. Payment of income to members of the creditor syndicate may be made through an agent, a nominee holder (nominal owner) or an intermediary in relation to such income;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.227 - 2 in accordance with Law No. 2245-VIII of 07.12.2017 }
{Subclause 14.1.228 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.229. specially designated parking lots - an area of territory (land) owned by a territorial community or the state, which is determined by local government bodies with the establishment of rules regarding responsibility for the safety of vehicles.
Specially designated parking lots may include municipal garages, parking lots, parking lots (buildings, structures, parts thereof) that are built at the expense of the local budget for the purpose of organizing vehicle parking.
Garages, parking lots, the owners or users of which are payers of land tax or rent for land plots of state and municipal property, as well as land plots belonging to adjacent territories, do not belong to specially designated parking lots;
14.1.230. stationary source of pollution - an enterprise, workshop, unit, installation or other immovable object that retains its spatial coordinates for a certain time and emits pollutants into the atmosphere and/or discharges pollutants into water bodies;
14.1.231. reasonable economic reason (business purpose) - a reason that can be present only if the taxpayer intends to obtain an economic effect as a result of economic activity.
The economic effect, in particular, but not exclusively, involves the increase (preservation) of the taxpayer's assets and/or their value, as well as the creation of conditions for such increase (preservation) in the future.
{Subclause 14.1.231 of clause 14.1 of Article 14 is supplemented by the second paragraph in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 786-IX of 07.14.2020 }
For tax purposes, a transaction made with non-residents is considered to have no reasonable economic reason (business purpose) if:
{Subclause 14.1.231 of clause 14.1 of Article 14 supplemented by the third paragraph in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 786-IX of 07.14.2020 }
the main purpose or one of the main purposes of the transaction is non-payment (incomplete payment) of taxes and/or a reduction in the amount of taxable income of the taxpayer;
{Subclause 14.1.231 of clause 14.1 of Article 14 supplemented by the fourth paragraph in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 786-IX of 07.14.2020 }
under comparable conditions, the person would not be willing to purchase (sell) such goods, works (services), intangible assets, other items of business transactions other than goods from unrelated persons.
{Subclause 14.1.231 of clause 14.1 of Article 14 supplemented by paragraph five in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 786-IX of 07.14.2020 }
This subparagraph shall apply for the purposes of Article 39 of this Code, including when proving circumstances indicating the absence of a business purpose, in cases specified in Clause 140.5 of Article 140 of this Code, which provide for the application of the relevant provisions of Article 39 of this Code;
{Subclause 14.1.231 of clause 14.1 of Article 14 is supplemented by the sixth paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
14.1.232. real estate fund certificate - a security certifying the right of its owner to receive income from investing in real estate transactions in accordance with the law;
14.1.234. agricultural products (agricultural goods) - products/goods falling under the definition of groups 1-24 of the UKT FEA , if such goods (products) are grown, fattened, caught, harvested, manufactured, produced, processed directly by the manufacturer of these goods (products), as well as products of processing and processing of these goods (products), if they were purchased or produced on own or leased facilities (areas) for sale, processing or internal consumption;
{Subclause 14.1.234 of clause 14.1 of Article 14 as amended by Laws No. 71-VIII of 12/28/2014 , No. 466-IX of 01/16/2020 }
14.1.235. agricultural producer - a legal entity, regardless of its organizational and legal form, or an individual entrepreneur, who is engaged in the production of agricultural products and/or breeding, growing and catching fish in inland waters (lakes, ponds and reservoirs) and its processing at its own or leased facilities, including self-produced raw materials on a tolling basis, and carries out operations for their supply.
{Paragraph two of subparagraph 14.1.235 of paragraph 14.1 of Article 14 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Subclause 14.1.235 of clause 14.1 of Article 14 as amended by Laws No. 71-VIII of 28.12.2014 , No. 2497-VIII dated 10.07.2018 , No. 1914-IX dated 30.11.2021 }
{Subclause 14.1.236 of clause 14.1 of Article 14 was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
14.1.237. ethyl alcohol - all types of rectified ethyl alcohol, bioethanol, other types of ethyl alcohol specified in commodity headings 2207 and 2208 according to the UKT Foreign Economic Activity;
{Subclause 14.1.237 of clause 14.1 of Article 14 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 3193-IX of 06/29/2023 }
14.1.237 - 1. alcohol distillate - alcohol obtained by distillation (distillation) after alcoholic fermentation of agricultural products, which does not have the characteristics of ethyl alcohol, retains the aroma and taste of the raw materials used and corresponds to commodity heading 2208 according to the UKT FEA;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.237 - 1 in accordance with Law No. 3193-IX of 29.06.2023 }
14.1.238. structures - land improvements that do not belong to buildings and are intended to perform special technical functions;
14.1.239. excluded;
14.1.240. land tax rate for the purposes of Section XII of this Code - the legally determined annual amount of payment per unit area of a taxable land plot;
{Subclause 14.1.240 of clause 14.1 of Article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.241. subject of government authority - within the meaning defined by the Code of Administrative Procedure of Ukraine ;
14.1.241 - 1. The term "ultimate beneficial owner" is used in the meaning given in the Law of Ukraine "On Prevention and Counteraction to the Legalization (Laundering) of Proceeds from Crime, Financing of Terrorism and Financing of the Proliferation of Weapons of Mass Destruction";
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.241 - 1 in accordance with Law No. 3813-IX of 18.06.2024 }
14.1.241 - 2. the term "illegitimate benefit" is used in the meaning given in the note to Article 364 - 1 of the Criminal Code of Ukraine;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.241 - 2 in accordance with Law No. 4112-IX of 04.12.2024 }
14.1.241 - 3. the term "official" for the purposes of applying the tax consequences provided for by this Code in connection with the provision of an unlawful benefit means any person from the list of persons specified in paragraph 1 of the note to Article 364 and/or the note to Article 369 - 2 of the Criminal Code of Ukraine, as well as any official of a foreign state;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.241 - 3 in accordance with Law No. 4112-IX of 04.12.2024 }
14.1.241 - 4. the term "official of a foreign state" means any person from the list of persons defined by Part Four of Article 18 of the Criminal Code of Ukraine and/or Point 2 of the Note to Article 364 of the Criminal Code of Ukraine;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.241 - 4 in accordance with Law No. 4112-IX of 04.12.2024 }
{Subclause 14.1.242 of clause 14.1 of Article 14 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
14.1.242. technical administrator of the electronic cabinet (hereinafter referred to as the technical administrator) - the central executive body implementing the state tax policy, carrying out measures to develop, create, implement and maintain the software of the electronic cabinet, is responsible for the implementation of all stages of the life cycle of such software, for its technical and technological support, implementation, functioning, updating, modification, elimination of errors, ensuring the integrity and authenticity of the source code; carries out technical and technological measures to provide, block and revoke access to the electronic cabinet, is responsible for the storage and protection of data of these electronic services;
{Sub-clause 14.1.242 is included in clause 14.1 of Article 14 in accordance with Law No. 1797-VIII of 21.12.2016 }
{Subclause 14.1.243 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.244. goods - tangible and intangible assets, including land plots, land shares (units), as well as securities and derivatives used in any transactions, except for transactions on their issue (emission) and redemption.
For the purposes of taxation of transactions involving the movement of property and energy across the customs border of Ukraine, the term "goods" is used in the meaning defined by the Customs Code of Ukraine ;
14.1.245. commodity credit - goods (works, services) transferred by a resident or non-resident to the ownership of legal entities or individuals under the terms of a contract that provides for the postponement of final payments for a specified period and at interest. A commodity credit provides for the transfer of ownership of goods (works, services) to the buyer (customer) at the time of signing the contract or at the time of physical receipt of goods (works, services) by such buyer (customer), regardless of the time of repayment of the debt;
{Subclause 14.1.246 of clause 14.1 of article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 14.1.247 of clause 14.1 of Article 14 was excluded on the basis of Law No. 2888-IX of 12.01.2023 }
{Subclause 14.1.248 of clause 14.1 of Article 14 was excluded on the basis of Law No. 2888-IX of 12.01.2023 }
14.1.249. Installment trade - a business transaction that involves the sale of goods by a resident or non-resident to individuals or legal entities on the terms of final payment in installments, for a specified period and at interest.
Installment trading involves the transfer of goods to the buyer at the time of making the first payment (deposit) with the transfer of ownership of such goods after the final settlement.
The rules for trading in installments for individuals are established by the Cabinet of Ministers of Ukraine;
{Subclause 14.1.250 of clause 14.1 of Article 14 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
14.1.251. used vehicles - vehicles for which authorized state bodies, including foreign ones, have issued registration documents granting the right to operate such vehicles;
{Subclause 14.1.251 - 1 of clause 14.1 of Article 14 was excluded on the basis of Law No. 72-VIII of 28.12.2014 }
14.1.252. tobacco products - cigarettes with or without a filter, cigarettes, cigars, cigarillos, as well as pipe, snuff, sucking, chewing tobacco, makhorka and other products made of tobacco or its substitutes, other than liquids used in electronic cigarettes, nicotine-containing products, their substitutes for smoking, sniffing, sucking, chewing or inhaling without burning by heating;
{Subclause 14.1.252 of clause 14.1 of Article 14 as amended by Law No. 3173-IX of 06/29/2023 ; as amended by Law No. 3553-IX of 01/16/2024 }
14.1.253. conditional exemption from customs duties - exemption from customs duties, the application of which provides for compliance with certain conditions and restrictions during the use of goods and means of transport for commercial purposes, their disposal after their release;
14.1.254. conditional exemption from value added tax and excise tax in the event of import of goods into the customs territory of Ukraine - exemption (conditional full or conditional partial) from payment of the accrued tax liability in the event of placing goods in customs regimes that provide for exemption from taxation subject to compliance with the requirements of the customs regime established by the Customs Code of Ukraine ;
{Subclause 14.1.254 of clause 14.1 of Article 14 as amended by Law No. 4915-VI of 07.06.2012 }
14.1.254 - 1. authorized participant (for the purposes of Article 39 of this Code) - a participant in an international group of companies authorized by such international group of companies to prepare and submit a report by country of the international group of companies on behalf of such international group of companies to the tax authority of the jurisdiction (state, territory) in which such participant is registered or in which its activities result in the establishment of a permanent establishment;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.254 - 1 in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 2970-IX of 03.20.2023 }
14.1.254 - 2. member of an international group of companies (for the purposes of Article 39 of this Code):
a) any separate business unit of an international group of companies (in particular, a Ukrainian or foreign legal entity or an entity without the status of a legal entity) that is included in the consolidated financial statements of such an international group of companies for the purposes of such reporting or that must have been included in the consolidated financial statements if the shares (corporate rights) of such a separate business unit of the international group of companies were traded on a national and/or foreign organized stock market (stock exchange);
b) any such business unit of an international group of companies that is excluded from the consolidated financial statements of such international group of companies in accordance with the criteria determined for the purposes of preparing the said statements (regarding ownership or control between legal entities or an unincorporated entity, the materiality of such business unit for the international group of companies, etc.);
c) any permanent establishment of any business entity of an international group of companies referred to in subparagraphs "a" and "b" of this subparagraph, provided that such business entity prepares separate financial statements in respect of such permanent establishment for financial, regulatory or tax purposes or for the purposes of internal management control;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.254 - 2 in accordance with Law No. 2970-IX of 20.03.2023 }
14.1.255. assignment of the right of claim - a transaction involving the assignment by a creditor of the right of claim for a third party's debt to a new creditor with prior or subsequent compensation of the value of such debt to the creditor or without such compensation;
{Sub-clause 14.1.256 of clause 14.1 of Article 14 is excluded on the basis of the Law No. 71-VIII dated 28.12.2014 }
14.1.257. financial assistance - financial assistance provided on a non-refundable or repayable basis.
Non-repayable financial assistance is:
the amount of funds transferred to the taxpayer under gift agreements, other similar agreements or without concluding such agreements;
the amount of bad debt reimbursed to the creditor by the borrower after such bad debt has been written off;
the amount of debt owed by one taxpayer to another taxpayer that has not been collected after the expiration of the statute of limitations;
the principal amount of a loan or deposit provided to a taxpayer without setting a repayment period for such principal amount, with the exception of loans provided under perpetual bonds and demand deposits in banking institutions, as well as the amount of interest accrued on such principal amount but not paid (written off).
{Paragraph seven of subparagraph 14.1.257 of paragraph 14.1 of Article 14 is excluded on the basis of the Law No. 71-VIII dated 28.12.2014 }
Reimbursable financial assistance - the amount of funds received by the taxpayer for use under an agreement that does not provide for the accrual of interest or the provision of other types of compensation in the form of a fee for the use of such funds, and is mandatory for return;
14.1.257 - 1. financial agent - any person (other than an individual) that meets the definition of a reporting financial institution of Ukraine, within the meaning of the FATCA Agreement , and/or a reporting financial institution in accordance with the CRS Multilateral Agreement and the CRS Common Reporting Standard, and which, in accordance with this Code and other legislative acts adopted to implement the provisions of the FATCA Agreement and the CRS Multilateral Agreement, is obliged to apply due diligence measures to financial accounts, submit a report on reporting accounts to the supervisory authority, perform other duties and be liable for violation of these duties in accordance with the procedure established by law.
Regulators of financial services markets, within the limits of their powers defined by legislative acts in the field of regulation of financial services activities, establish lists of non-bank financial institutions that are required to perform the duties of financial agents in accordance with the requirements of the FATCA Agreement .
Annex II to the FATCA Agreement are not financial agents .↑
For the purposes of the CRS Multilateral Agreement, persons who are required to perform the duties of financial agents (are accountable financial institutions) are determined in accordance with the rules of the said Agreement , the CRS Common Reporting Standard and regulatory legal acts of the central executive body that ensures the formation and implementation of state financial policy, for the implementation of the CRS Multilateral Agreement;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.257 - 1 in accordance with Law No. 323-IX of 03.12.2019 ; as amended by Law No. 2970-IX of 20.03.2023 }
14.1.258. financial credit - funds provided by a resident bank or a non-resident that qualifies as a banking institution in accordance with the legislation of the non-resident's country of residence, or by residents and non-residents that have the status of non-banking financial institutions in accordance with the relevant legislation, as well as by a foreign state or its official agencies, international financial organizations and other non-resident creditors to a legal entity or individual for a specified period for targeted use and at interest;
14.1.258 - 1. financial account - an account opened by a financial agent, or an agreement concluded by a financial agent.
For the purposes of this Code, financial accounts include bank accounts, payment accounts, securities accounts, other types of accounts, contracts that meet the criteria specified in the FATCA Agreement and/or the CRS Multilateral Agreement. For the purposes of the CRS Multilateral Agreement, the term "financial account" is used and interpreted in accordance with the provisions of the CRS Common Reporting Standard;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.258 - 1 in accordance with Law No. 323-IX of 03.12.2019 ; as amended by Law No. 2970-IX of 20.03.2023 }
14.1.259. banking management fund - funds of participants in banking management funds and other assets held in trust by an authorized bank in accordance with the law;
14.1.260. freight - remuneration (compensation) paid under contracts of carriage, hire or sublease of a vessel or vehicle (their parts) for:
transportation of goods and passengers by sea or aircraft;
transportation of goods by rail or road;
14.1.261. intended purpose of a land plot - use of a land plot for the purpose determined on the basis of land management documentation in accordance with the procedure established by law;
14.1.262. share of agricultural production for the purposes of Chapter 1, Section XIV of this Code - the share of the income of an agricultural producer received from the sale of agricultural products of its own production and products of its processing, in the total amount of its income, which is taken into account when determining the right of such a producer to register as a taxpayer;
{Subclause 14.1.262 of clause 14.1 of article 14 as amended by Law No. 71-VIII of 28.12.2014 }
14.1.263. Family members of an individual in the first degree of kinship for the purposes of Section IV of this Code are considered to be his or her parents, his or her husband or wife, and children of such individual, including adopted children.
Family members of an individual of the second degree of kinship for the purposes of Section IV of this Code are considered to be his or her brothers and sisters, his or her maternal and paternal grandparents, and grandchildren.
{Subclause 14.1.263 of clause 14.1 of Article 14 as amended by Law No. 1910-VIII of 23.02.2017 - applies to income received by a taxpayer as an inheritance/gift starting from January 1, 2017}
14.1.264. timing - the process of monitoring the conduct of a taxpayer's economic activity, which is carried out during actual inspections and is used by regulatory authorities in order to establish real indicators of the taxpayer's activity, which is carried out at the relevant place of its conduct;
14.1.265. penalty (financial sanction, fine) - a payment in the form of a fixed amount and/or interest, levied on persons who have committed a tax offense or violation of other legislation, control over compliance with which is entrusted to regulatory authorities, as well as penalties for violations in the field of foreign economic activity;
{Subclause 14.1.265 of clause 14.1 of Article 14 as amended by Law No. 466-IX of 16.01.2020 }
14.1.266. cash method for taxation purposes in accordance with Section V of this Code - a tax accounting method according to which the date of tax liability is determined as the date of crediting (receiving) funds to the taxpayer's accounts at a bank/non-bank payment service provider, to an electronic wallet at an electronic money issuer and/or to accounts at agencies providing treasury services for budget funds, to the taxpayer's cash desk or the date of receiving other types of compensation for the value of goods (services) supplied (or to be supplied) by him, and the date of assigning tax amounts to a tax credit is determined as the date of debiting funds from the taxpayer's accounts at a bank/non-bank payment service provider, from electronic wallets at an electronic money issuer and/or from accounts at agencies providing treasury services for budget funds, the date of issuance from the taxpayer's cash desk or the date of providing other types of compensation for the value of goods (services) supplied (or to be supplied) to him;
{Subclause 14.1.266 of clause 14.1 of Article 14 as amended by Laws No. 2245-VIII of 07.12.2017 , No. 466-IX of 16.01.2020 , No. 2888-IX of 12.01.2023 }
14.1.267. loan - funds provided by residents who are financial institutions, or non-residents, except for non-residents who have offshore status, to a borrower for a specified period with the obligation to repay them and pay interest for the use of the loan amount;
14.1.268. passive income - income received in the form of:
{Paragraph one of subparagraph 14.1.268 of paragraph 14.1 of Article 14 as amended by Law No. 466-IX of January 16, 2020 }
interest on a current or deposit bank account, on a deposit in credit unions, other interest (including discount income);
interest or discount income on a registered savings (deposit) certificate;
fees (interest), which are distributed according to the share membership fees of the credit union members;
income paid by the company managing the assets of a collective investment institution on the assets placed in accordance with the law, including income paid (accrued) by the issuer as a result of the redemption (redemption) of securities of a collective investment institution, which is defined as the difference between the amount received from the redemption and the amount of funds or the value of property paid by the taxpayer to the seller (including the issuer) in connection with the acquisition of such securities as compensation for their value;
income from mortgage securities (mortgage bonds and certificates) in accordance with the law;
interest (discount) received by the bond holder from their issuer in accordance with the law;
income from a real estate fund certificate and income received by the taxpayer as a result of the redemption (repayment) by the manager of real estate fund certificates in accordance with the procedure specified in the prospectus for the issue of the certificates;
investment income, including income from transactions with government securities and debt obligations of the National Bank of Ukraine, taking into account exchange rate differences;
royalties;
dividends;
insurance payments and reimbursements;
{Subclause 14.1.268 of clause 14.1 of Article 14 as amended by Law No. 1797-VIII of 21.12.2016 }
14.1.269. Platts - an international, global unified information monitoring system for market dynamics and pricing in the mining and fuel and energy industries;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.269 in accordance with Law No. 71-VIII of 28.12.2014 }
14.1.270. Platts indicators - indices officially defined by the global information agency Platts and are the basis for use by economic entities";
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.270 in accordance with Law No. 71-VIII of 28.12.2014 }
14.1.271. The income of entities that issue and conduct lotteries from operations on the issuance and conduct of lotteries consists of the income remaining after the formation of the prize (winning) fund and the amount of bad debts determined by subparagraph "e" of subparagraph 14.1.11 of this paragraph.
The income of entities that issue and conduct lotteries, remaining after the formation of the prize (winning) fund, is the part of the funds that constitutes the difference between the total amount of income received from accepting bets in the lottery and the amount of the formed prize (winning) fund of the lottery in accordance with the conditions of its conduct.
For the purposes of this subparagraph, the total amount of income received from accepting lottery bets means the amount of funds received in cash and/or non-cash form at the cash desk and/or on the accounts of the lottery operator;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.271 in accordance with Law No. 1797-VIII of 21.12.2016 }
14.1.272. "live" fermented kvass - a beverage with an ethyl alcohol content of not more than 1.2 percent by volume, obtained during the fermentation of kvass wort, which belongs to commodity headings 2202 and 2206 according to the UKT FEA ;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.272 in accordance with Law No. 2245-VIII of 07.12.2017 }
{Subclause 14.1.273 of clause 14.1 of Article 14 was excluded on the basis of Law No. 354-IX of 05.12.2019 }
{Subclause 14.1.274 of clause 14.1 of Article 14 was excluded on the basis of Law No. 354-IX of 05.12.2019 }
{Subclause 14.1.275 of clause 14.1 of Article 14 was excluded on the basis of Law No. 354-IX of 05.12.2019 }
{Subclause 14.1.276 of clause 14.1 of Article 14 was excluded on the basis of Law No. 354-IX of 05.12.2019 }
14.1.277. domestic tourism for the purposes of Section XII of this Code - movement within the territory of Ukraine of citizens of Ukraine and/or persons permanently residing in the territory of Ukraine for educational, professional, business or other purposes.
Inbound tourism for the purposes of Section XII of this Code - arrival to the territory of Ukraine and/or movement within the territory of Ukraine of persons who do not permanently reside in the territory of Ukraine, for educational, professional, business or other purposes;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.277 in accordance with Law No. 2628-VIII of 23.11.2018 }
14.1.277 - 1. budget grant - targeted assistance in the form of funds or property provided on a gratuitous and non-refundable basis at the expense of state and/or local budgets, international technical assistance for the implementation of a project or program in the fields of culture, tourism and the creative industries sector, sports and other humanitarian areas in accordance with the procedure established by law. The list of providers of budget grants is determined by the Cabinet of Ministers of Ukraine;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.277 - 1 in accordance with Law No. 962-IX of 04.11.2020 }
14.1.278. system for accounting of data of registrars of settlement operations (hereinafter referred to as the SOD RRO) - an information system intended for collection, storage, use of data of registrars of settlement operations and software registrars of settlement operations (including electronic copies of settlement documents and fiscal reporting checks created by registrars of settlement operations and software registrars of settlement operations), verification of authenticity and reliability of settlement documents.
Users-buyers (consumers) through the Electronic Cabinet, which operates in accordance with Article 42 - 1 of this Code, are provided with the opportunity to:
control of the authenticity and reliability of settlement documents stored in the RRO SOD.
The procedure for the functioning of the SOD RRO is determined by the central executive body, which ensures the formation and implementation of state financial policy;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.278 in accordance with Law No. 129-IX of 20.09.2019 , taking into account the amendments made by Law No. 1017-IX of 01.12.2020 }
14.1.279. investment gold for the purposes of Section V of this Code - gold in the form of:
a) bars or plates of a weight accepted in the bullion markets of 995 fineness or higher, regardless of whether it is represented in securities;
b) gold coins of 900 fineness or finer, minted after 1800, which are or were legal tender in the country of origin and are sold at a price that does not exceed the market value of the gold contained in the coins by more than 80 percent.
The market value of gold is the value of gold at the accounting price of banking metals, which is published by the National Bank of Ukraine on the page of the official Internet representative office of the National Bank of Ukraine;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.279 in accordance with Law No. 1914-IX of 30.11.2021 }
14.1.280. assets of an individual for the purposes of subsection 9 - 4 "Features of the application of one-time (special) voluntary declaration of assets of individuals" of section XX "Transitional provisions" of this Code - monetary assets of an individual, property, property rights;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.280 in accordance with Law No. 1539-IX of 15.06.2021 }
14.1.281. monetary assets of an individual for the purposes of subsection 9 - 4 "Features of the application of one-time (special) voluntary declaration of assets of individuals" of section XX "Transitional provisions" of this Code - funds in national and foreign currencies placed on accounts in Ukrainian and foreign banks, cash contributions to credit unions and other non-bank financial institutions, monetary claim rights (including funds lent to third parties under a loan agreement), drawn up in writing with a legal entity or notarized in the event of the declarant's right of claim to an individual, as well as assets in bank metals, commemorative banknotes and coins, electronic money;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.281 in accordance with Law No. 1539-IX of 15.06.2021 }
14.1.282. resident of Diya City - within the meaning of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine";
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.282 in accordance with Law No. 1946-IX of 14.12.2021 }
14.1.282 - 1. resident of Diya City - a taxpayer who pays corporate income tax under special conditions (hereinafter referred to as a resident of Diya City - a taxpayer under special conditions) - a resident of Diya City who, in accordance with the procedure provided for in Clause 141.10 of Article 141 of this Code, has chosen or switched to the appropriate taxation regime. Residents of Diya City who have not chosen (not switched) to the appropriate taxation regime shall pay corporate income tax on general grounds and shall be considered residents of Diya City who are not taxpayers under special conditions;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.282 - 1 in accordance with Law No. 1946-IX of 14.12.2021 }
14.1.283. specialists of a resident of Diya City - gig specialists who perform work (provide services) on order and for the benefit (in the interests) of a resident of Diya City on the basis of a gig contract concluded in accordance with the procedure provided for by the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", and/or persons who are in an employment relationship with a resident of Diya City;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.283 in accordance with Law No. 1946-IX of 14.12.2021 }
14.1.284. Diya City register - within the meaning of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine";
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.284 in accordance with Law No. 1946-IX of 14.12.2021 }
14.1.284 - 1. resident of Defense City - within the meaning given in the Law of Ukraine "On National Security of Ukraine" ;
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.284 - 1 in accordance with Law No. 4577-IX of 21.08.2025 }
14.1.284 - 2. Defense City register - within the meaning given in the Law of Ukraine " On National Security of Ukraine".
{Clause 14.1 of Article 14 is supplemented by subparagraph 14.1.284 - 2 in accordance with Law No. 4577-IX of 21.08.2025 }
14.2. For the purposes of this Code, debt obligations of the National Bank of Ukraine shall be considered securities.
{Article 14 is supplemented by paragraph 14.2 in accordance with Law No. 4238-VI of 22.12.2011 }
, the deposit (transfer, receipt, payment, crediting) of funds by a taxpayer to a single account in the cases provided for in Article 35-1 of this Code is considered the deposit (transfer, receipt, payment, crediting) of funds by such taxpayer to the budget.
{ Article 14 is supplemented by paragraph 14.3 in accordance with Law No. 190-IX of 04.10.2019 }
14.4. For the purposes of this Code, unless otherwise expressly provided herein, international treaties containing provisions on the exchange of information for tax purposes include the Convention on Mutual Administrative Assistance in Tax Matters , the International Treaty of Ukraine for the Avoidance of Double Taxation, and other international treaties on the exchange of information for tax purposes, the binding consent of which has been granted by the Verkhovna Rada of Ukraine, as well as interdepartmental treaties concluded on their basis.
{Article 14 is supplemented by paragraph 14.4 in accordance with Law No. 2970-IX of 20.03.2023 }
15.1. Taxpayers are individuals (residents and non-residents of Ukraine), legal entities (residents and non-residents of Ukraine) and their separate divisions that own, receive (transfer) taxable objects or conduct activities (transactions) that are subject to taxation in accordance with this Code or tax laws, and who are obligated to pay taxes and fees in accordance with this Code.
15.2. Each taxpayer may be a taxpayer for one or more taxes and fees.
16.1.1. register with regulatory authorities in accordance with the procedure established by the legislation of Ukraine;
16.1.2. keep records of income and expenses in accordance with the established procedure, prepare reports regarding the calculation and payment of taxes and fees;
16.1.3. submit to the regulatory authorities, in accordance with the procedure established by tax and customs legislation, declarations, reports and other documents related to the calculation and payment of taxes and fees;
16.1.4. pay taxes and fees within the deadlines and in the amounts established by this Code and laws on customs matters;
16.1.5. submit, upon a properly executed written request of the regulatory authorities (in cases specified by law), documents on accounting of income, expenses and other indicators related to the determination of objects of taxation (tax liabilities), primary documents, accounting registers, financial statements, other documents related to the calculation and payment of taxes and fees. The written request must specify a specific list of documents that the taxpayer must provide, and the grounds for their provision;
16.1.6. submit to the regulatory authorities information, data on the amounts of funds not paid to the budget in connection with the receipt of tax benefits (amounts of benefits received) and directions of their use (regarding conditional tax benefits - benefits provided on the condition of using funds released from the business entity as a result of the provision of the benefit, in accordance with the procedure determined by the state);
16.1.7. submit information to regulatory authorities in the manner, within the time limits and in the amounts established by tax legislation;
16.1.8. comply with the legal requirements of regulatory authorities to eliminate identified violations of laws on taxation and customs and sign acts (certificates) on the conduct of the inspection;
16.1.9. not to obstruct the lawful activities of an official of the regulatory body during the performance of his/her official duties and to comply with the lawful requirements of such official;
16.1.10. notify the regulatory authorities at the place of registration of such a payer about its liquidation or reorganization within three business days from the date of adoption of the relevant decision (except for cases when the obligation to provide such notification is imposed by law on the state registration authority);
16.1.11. notify regulatory authorities about the change of location of a legal entity and the change of place of residence of an individual entrepreneur;
16.1.12. ensure the preservation of documents related to the fulfillment of tax obligations within the time limits established by this Code;
16.1.13. allow officials of the regulatory body, during their inspections, to inspect premises and territories (except for citizens' homes) used to generate income or related to the maintenance of taxable objects, as well as to conduct inspections on the calculation and payment of taxes and fees in cases established by this Code;
{The provision of subparagraph 16.1.13 of paragraph 16.1 of Article 16, according to which the taxpayer is obliged to allow officials of the control body during their inspections to inspect premises, territories (except for citizens' housing) used for generating income or related to the maintenance of taxable objects, as well as to conduct inspections on the calculation and payment of taxes and fees in cases established by this Code, was recognized as constitutional in accordance with the Decision of the Constitutional Court No. 13-rp/2012 of 12.06.2012 }
16.1.14. use the electronic office for correspondence with regulatory authorities in electronic form in the event of submitting reports in electronic form, as well as after passing online electronic identification in the electronic office, except for taxpayers who have refused to use the electronic office in the manner established by this Code and taxpayers who have not determined the method of interaction with the regulatory authority;
{Clause 16.1 of Article 16 is supplemented by subparagraph 16.1.14 in accordance with Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
16.1.15. ensure that officials of the taxpayer provide written explanations upon written request of the regulatory authority on issues related to the subject of the inspection, and their documentary confirmation;
{Clause 16.1 of Article 16 is supplemented by subparagraph 16.1.15 in accordance with Law No. 466-IX of January 16, 2020 }
16.1.16. determine and change authorized persons of the taxpayer who have the right to use the electronic office, in particular regarding their signing, submission, and receipt of documents and information through the electronic office, and determine their powers.
{Clause 16.1 of Article 16 is supplemented by subparagraph 16.1.16 in accordance with Law No. 786-IX of 14.07.2020 }
17.1.1. to receive free of charge from regulatory authorities, including via the Internet, information on taxes and fees and regulatory legal acts that regulate them, the procedure for accounting and payment of taxes and fees, the rights and obligations of taxpayers, the powers of regulatory authorities and their officials regarding tax control;
{Subclause 17.1.1 of clause 17.1 of Article 17 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 }
17.1.2. represent their interests in regulatory authorities independently, through a tax agent or authorized representative;
17.1.3. to independently choose, unless otherwise established by this Code, the method of accounting for income and expenses;
17.1.4. to use tax benefits if there are grounds in accordance with the procedure established by this Code;
17.1.5. receive installments, deferral of monetary obligations or tax debt in accordance with the procedure and on the terms established by this Code;
{ Subparagraph 17.1.5 of paragraph 17.1 of Article 17 as amended by Law No. 3813-IX of 18.06.2024 }
17.1.6. be present during inspections and provide explanations on issues arising during such inspections, and on their own initiative provide explanations on issues not requested by the supervisory authority, familiarize themselves with and receive acts (certificates) of inspections conducted by the supervisory authorities before signing acts (certificates) on the inspection, in case of comments on the content (text) of the drawn up acts (certificates), sign them with a reservation and submit written objections to the supervisory authority in accordance with the procedure established by this Code;
{Subclause 17.1.6 of Clause 17.1 of Article 17 as amended by Laws No. 4834-VI of 05/24/2012 , No. 466-IX of 01/16/2020 }
17.1.7. to appeal, in accordance with the procedure established by this Code, decisions, actions (inaction) of regulatory bodies (officials), including individual tax advice provided to him in paper or electronic form, as well as general tax advice;
{Subclause 17.1.7 of Clause 17.1 of Article 17 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
17.1.8. require regulatory authorities to verify information and facts that may be in favor of the taxpayer;
17.1.9. for non-disclosure by the controlling body (officials) of information about such a payer without his written consent and information that constitutes confidential information, state, commercial or banking secret and became known to officials during the performance of their official duties, except for cases when this is expressly provided for by law;
17.1.10. for the offset or refund of overpaid, as well as overcollected amounts of taxes and fees, penalties, fines in accordance with the procedure established by this Code;
17.1.11. for full compensation for damage caused by illegal actions (inaction) of regulatory authorities (their officials), in accordance with the procedure established by law;
{Subclause 17.1.7 of Clause 17.1 of Article 17 as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 17.1.12 of clause 17.1 of Article 17 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
17.1.13. independently choose the method of interaction with the regulatory authority in electronic form through an electronic account, unless otherwise established by this Code;
{Clause 17.1 of Article 17 is supplemented by subparagraph 17.1.13 in accordance with Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
17.1.14. to exercise through the electronic office the rights and obligations provided for by this Code and which can be exercised in electronic form by means of electronic communication;
{Clause 17.1 of Article 17 is supplemented by subparagraph 17.1.14 in accordance with Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
17.1.15. submit a declaration and other documents in paper form in the event of technical and/or methodological errors or a technical failure in the operation of the electronic office (the presence of an error/failure must be confirmed by the technical administrator and/or methodologist of the electronic office, or according to a notification on the official website of the central executive body implementing state tax policy, or by a court decision), if the submission of such documents in electronic form is not mandatory in accordance with this Code;
{Clause 17.1 of Article 17 is supplemented by subparagraph 17.1.15 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 786-IX of 14.07.2020 }
17.1.16. provide, on his own initiative, written explanations and/or documents regarding the circumstances confirming his absence of guilt in the committed tax offense, in accordance with the procedure established by this Code;
{Clause 17.1 of Article 17 is supplemented by subparagraph 17.1.16 in accordance with Law No. 466-IX of January 16, 2020 }
17.1.17. openly use technical devices and technical means that have the functions of photo and film shooting, video recording, means of photo and film shooting, video recording; openly make sound recordings, photo and video fixation (video recording), accumulate and use such multimedia information (photo, video, sound recording) during inspections;
{Clause 17.1 of Article 17 is supplemented by subparagraph 17.1.17 in accordance with Law No. 1914-IX of 30.11.2021 }
17.1.18. interact with the regulatory authority via video conference in cases provided for by this Code, in order to provide oral explanations.
{Clause 17.1 of Article 17 is supplemented by subparagraph 17.1.18 in accordance with Law No. 3603-IX of 23.02.2024 }
17.2. The taxpayer also has other rights provided for by law.
17.3. The rights of a taxpayer provided for by this Code and other legislative acts, the control over compliance with which is entrusted to regulatory authorities, may be limited in the event of the application of special economic and other restrictive measures (sanctions) to the taxpayer in accordance with the procedure established by the Law of Ukraine "On Sanctions".
{Article 17 is supplemented by paragraph 17.3 in accordance with Law No. 3317-IX of 10.08.2023 }
18.1. A tax agent is a person who is obliged by this Code to calculate, withhold from income accrued (paid, provided) to the payer, and transfer taxes to the relevant budget on behalf of and at the expense of the taxpayer.
18.2. Tax agents are equated with taxpayers and have the rights and perform the duties established by this Code for taxpayers.
19.1. A taxpayer shall conduct tax-related matters personally or through his representative. The taxpayer's personal participation in tax relations does not deprive him of the right to have his own representative, just as the participation of a tax representative does not deprive the taxpayer of the right to personal participation in such relations.
19.2. Representatives of a taxpayer are recognized as persons who can represent his legitimate interests and conduct affairs related to the payment of taxes on the basis of law or a power of attorney. A power of attorney issued by a taxpayer - an individual to represent his interests and conduct affairs related to the payment of taxes must be certified in accordance with current legislation.
19.3. The representative of the taxpayer shall exercise the rights established by this Code for taxpayers.
19 - 1 .1. The supervisory authorities defined in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code shall perform the following functions, in addition to the features provided for state tax inspectorates by Article 19 - 3 of this Code:
{Clause 19 - 1 .1 of Article 19 - 1 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
19 - 1 .1.1. administer taxes, fees, payments, including conducting inspections and reconciliations of taxpayers in accordance with the legislation;
{Subclause 19 - 1 .1.1 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.2. monitor the timeliness of submission by taxpayers and single contribution payers of reporting provided for by law (declarations, calculations and other documents related to the calculation and payment of taxes, fees, payments), the timeliness, reliability, completeness of the calculation and payment of taxes, fees, payments;
19 - 1 .1.3. provide administrative services to payers of taxes, fees, and payments;
19 - 1 .1.4. exercise control over the deadlines established by law for making settlements in foreign currency, over compliance with the procedure for accepting cash for performing payment transactions (except for cash acceptance by banks), over compliance by business entities with the mandatory requirements established by law for ensuring the possibility of making settlements for goods (services) using electronic payment instruments, the procedure for making cash settlements for goods (services), carrying out settlement transactions, as well as over the availability of licenses for conducting types of economic activity subject to licensing in accordance with the law, and the availability of trade patents;
{Subclause 19 - 1 .1.4 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 2888-IX of 12.01.2023 }
19 - 1 .1.5. exercise control over compliance by the executive bodies of village and settlement councils with the procedure for accepting and accounting for taxes and fees from taxpayers, the timeliness and completeness of the transfer of the specified amounts to the budget;
{Subclause 19 - 1 .1.5 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
19 - 1 .1.6. exercise control over the legality of budget reimbursement of value added tax;
19 - 1 .1.7. register and keep records of taxpayers, single contribution payers, objects of taxation and objects related to taxation, carry out differentiation of taxpayers;
{Subclause 19 - 1 .1.7 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 466-IX of 16.01.2020 }
19 - 1 .1.8. ensure the reliability and completeness of accounting for taxpayers and single contribution payers, objects of taxation and objects related to taxation;
{Subclause 19 - 1 .1.8 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 466-IX of 16.01.2020 }
19 - 1 .1.9. form and maintain the State Register of Individual Taxpayers, the Unified Data Bank of Taxpayers - Legal Entities, registers, the maintenance of which is entrusted by law to regulatory authorities;
19 - 1 .1.9 - 1 . form and maintain the Register of recipients of budget subsidies for the development of agricultural producers and stimulation of agricultural production in accordance with the Law of Ukraine "On State Support for Agriculture of Ukraine;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.9 - 1 in accordance with Law No. 1791-VIII of 20.12.2016 }
19 - 1 .1.10. ensure the keeping of records of taxes, fees, payments and single contribution;
{Subclause 19 - 1 .1.10 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1914-IX of 11/30/2021 }
{Subclause 19 - 1 .1.10 - 1 of clause 19 - 1 .1 of article 19 - 1 was excluded on the basis of Law No. 3603-IX of 23.02.2024 }
19 - 1 .1.11. ensure the review of decisions of lower-level regulatory bodies in accordance with the procedure established by law;
{Subclause 19 - 1 .1.12 of clause 19 - 1 .1 of article 19 - 1 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
19 - 1 .1.13. carry out licensing of activities of business entities for the production of alcohol, alcoholic beverages, tobacco products and liquids used in electronic cigarettes, wholesale trade in alcohol, wholesale and retail trade in alcoholic beverages, tobacco products and liquids used in electronic cigarettes, and control over such production;
{Subclause 19 - 1 .1.13 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 466-IX of 16.01.2020 }
19 - 1 .1.14. exercise control over the production, circulation and sale of excisable goods, control over their intended use, ensure inter-sectoral coordination in this area;
19 - 1 .1.15. ensure control over the acceptance of declarations on maximum retail prices for excisable goods (products) established by the manufacturer or importer, and the generalization of information specified in such declarations for the organization of work and control over the completeness of the calculation and payment of excise tax;
19 - 1 .1.16. take measures to prevent and detect violations of legislation in the field of production and circulation of alcohol, alcoholic beverages, tobacco products, liquids used in electronic cigarettes, and fuel;
{Subclause 19 - 1 .1.16 of clause 19 - 1 .1 of article 19 - 1 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
19 - 1 .1.17. carry out work to combat the illegal production, movement, and circulation of alcohol, alcoholic beverages, tobacco products, liquids used in electronic cigarettes, and fuel;
{Subclause 19 - 1 .1.17 of clause 19 - 1 .1 of article 19 - 1 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
19 - 1 .1.18. organize work related to ordering excise tax stamps, their storage, sale, sampling, in order to conduct an examination of their authenticity and monitor the presence of such stamps on bottles (packaging) of alcoholic beverages, packs (packaging) of tobacco products, containers (packaging) of liquids used in electronic cigarettes, during their transportation, storage and sale;
{Subclause 19 - 1 .1.18 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 466-IX of 16.01.2020 }
19 - 1 .1.19. ensure control over compliance by business entities engaged in retail trade in tobacco products, liquids used in electronic cigarettes, with the legislation on maximum retail prices for such products set by their manufacturers or importers, and the retail selling prices of excisable goods for which maximum retail prices are set;
{Subclause 19 - 1 .1.19 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 4115-IX of 04.12.2024 - for the effect of the changes, see clause 2 of section II}
19 - 1 .1.20. ensure control over compliance by business entities engaged in wholesale or retail trade in alcoholic beverages with the requirements of the law regarding minimum wholesale or retail prices for such beverages;
19 - 1 .1.21. organize work and exercise control over the application of seizure of taxpayer property and/or suspension of expenditure transactions on his accounts/electronic wallets in a bank, other financial institution, non-bank payment service provider/electronic money issuer;
{Subclause 19 - 1 .1.21 of clause 19 - 1 .1 of article 19 - 1 as amended by Laws No. 2888-IX of 01/12/2023 , No. 3813-IX of 06/18/2024 }
19 - 1 .1.22. carry out the repayment of tax debt, collection of arrears from the payment of a single contribution and other payments, control over the collection of which is entrusted to the regulatory authorities;
{Subclause 19 - 1 .1.22 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 3813-IX of 18.06.2024 }
19 - 1 .1.23. organize work on identifying, accounting, storing, evaluating and disposing of ownerless property and other property that becomes state property, as well as on accounting, preliminary evaluation, and storing property seized and confiscated for violating customs and tax legislation;
19 - 1 .1.24. carry out installments, postponements and restructuring of monetary obligations and/or tax debt, arrears in the payment of a single contribution, as well as write-off of bad tax debt;
{Subclause 19 - 1 .1.24 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 3813-IX of 18.06.2024 }
19 - 1 .1.25. develop and submit proposals for regulatory legal acts on issues within the competence of regulatory authorities;
{Subclause 19 - 1 .1.25 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
{Subclause 19 - 1 .1.26 of clause 19 - 1 .1 of article 19 - 1 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.27. ensure the development, implementation and technical support of information and telecommunication systems and technologies, automation of procedures, in particular the organization of the implementation of electronic services for business entities by regulatory authorities;
{Subclause 19 - 1 .1.27 of clause 19 - 1 .1 of Article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
19 - 1 .1.28. provide individual tax consultations, information and reference services on tax and other legislation, the control over compliance with which is entrusted to regulatory authorities;
{Subclause 19 - 1 .1.28 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.29. ensure informing the public about the implementation of state tax policy;
{Subclause 19 - 1 .1.29 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 466-IX of 16.01.2020 }
19 - 1 .1.30. develop proposals for draft international treaties of Ukraine on taxation issues and ensure the implementation of concluded international treaties;
19 - 1 .1.31. provide the central executive body that ensures the formation and implementation of state financial policy, generalized practice of applying legislation on taxation, legislation on payment of a single contribution;
{Subclause 19 - 1 .1.31 of clause 19 - 1 .1 of article 19 - 1 as amended by Laws No. 657-VII of 10/24/2013 , No. 1797-VIII of 12/21/2016 }
19 - 1 .1.32. organize interaction and exchange of information with state bodies of other states in accordance with the legislation and international treaties of Ukraine, carry out international cooperation in the tax sphere;
{Subclause 19 - 1 .1.32 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 466-IX of 16.01.2020 }
19 - 1 .1.32 - 1 . organize interaction and exchange of information with regulators of financial services markets, defined by the laws of Ukraine in the field of regulation of activities for the provision of financial services, in order to monitor compliance by financial agents with the requirements of Article 39 - 3 of this Code and ensure the implementation of the FATCA Agreement and the CRS Multilateral Agreement;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.32 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
19 - 1 .1.33. submit to the central executive body that ensures the formation and implementation of state financial policy, and to the central executive body that implements state policy in the field of treasury services of budget funds, reports and information on the receipt of taxes, fees, payments, control over the collection of which is entrusted to the controlling bodies;
{Subclause 19 - 1 .1.33 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.34. ensure the determination, in cases established by this Code and other laws of Ukraine, of the amounts of tax and monetary obligations of taxpayers, the application and timely collection of amounts of punitive (financial) sanctions (fines) provided for by law for violations of tax, currency and other legislation, control over compliance with which is entrusted to regulatory authorities;
19 - 1 .1.34 - 1 . take measures to ensure the implementation of decisions on the application of special economic and other restrictive measures (sanctions) adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions";
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.34 - 1 in accordance with Law No. 3317-IX of 10.08.2023 }
19 - 1 .1.35. take measures to identify, analyze and verify financial transactions that may be related to the legalization (laundering) of proceeds from crime or the financing of terrorism, with regard to compliance with the legislation;
19 - 1 .1.36. provide other state bodies, in cases established by law, with access to information from the databases of the central executive body implementing state tax policy;
{Subclause 19 - 1 .1.36 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
19 - 1 .1.37. exercise control and ensure the provision of assistance in the collection of tax debt in international legal relations at the requests of competent authorities of foreign states;
19 - 1 .1.38. ensure the collection of overdue debts of business entities to the state (Autonomous Republic of Crimea, regional council or city territorial community) under credits (loans) attracted by the state (Autonomous Republic of Crimea, regional council or city territorial community) or under state (local) guarantees, as well as under credits from the budget (including fees for the use of such credits (loans) and interest) in accordance with the procedure established by this Code or other law, including the repayment of such debts at the expense of the property of this business entity;
{Subclause 19 - 1 .1.38 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 2719-IX of 03.11.2022 }
19 - 1 .1.39. carry out departmental control and internal audit over compliance with legislative requirements and performance of official duties in regulatory bodies, enterprises, institutions, and organizations within their sphere of management;
19 - 1 .1.40. organize the collection of tax information and enter it into the information databases of the central executive body that implements state tax policy;
{Subclause 19 - 1 .1.40 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
19 - 1 .1.41. organizes information and analytical support and organizes automation of administrative processes by supervisory bodies;
{Subclause 19 - 1 .1.41 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.41 - 1 . exercise compliance within the limits of the powers defined by this Code;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.41 - 1 in accordance with Law No. 3813-IX of 18.06.2024 }
19 - 1 .1.42. approve the decisions of the National Securities and Stock Market Commission on establishing signs of fictitiousness of a securities issuer, as well as on establishing the procedure for determining a securities issuer that meets the signs of fictitiousness;
19 - 1 .1.43. monitor the implementation of indicators of settlements with the budget and state trust funds, approved by the financial plans of state enterprises, economic organizations, in the authorized capital of which there are corporate rights belonging to the state, and their subsidiaries;
{Subclause 19 - 1 .1.43 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.44. provide qualified electronic trust services (as separate points of registration of a qualified provider of electronic trust services of the central executive body implementing state tax policy);
{Subclause 19 - 1 .1.44 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 2725-VIII of 05/16/2019 ; as amended by Law No. 466-IX of 01/16/2020 }
19 - 1 .1.45. apply to court in cases provided for by law;
19 - 1 .1.46. use, in the performance of their official (service) duties, tax information from information and telecommunication systems and other sources, obtained in the manner and manner specified by this Code;
{Subclause 19 - 1 .1.46 of clause 19 - 1 .1 of article 19 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.47. provide advice to taxpayers on the use of information and telecommunication systems when paying taxes and fees;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.47 in accordance with Law No. 1797-VIII of 21.12.2016 }
19 - 1 .1.48. prepare reports on the status of taxpayers' settlements with the budget and payment of a single contribution, as well as other performance indicators in the areas of activity of the central executive body that implements state tax policy;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.48 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
19 - 1 .1.49. inform state authorities about the status of taxpayers' settlements with budgets and payment of a single contribution;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.49 in accordance with Law No. 466-IX of January 16, 2020 }
19 - 1 .1.50. inform local self-government bodies about the status of settlements with local budgets;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.50 in accordance with Law No. 466-IX of January 16, 2020 }
19 - 1 .1.51. exercise control over the timeliness, reliability, completeness of the accrual and payment of part of the net profit (income) to the budget by state and municipal unitary enterprises and their associations, as well as business companies, the authorized capital of which includes state and/or municipal property;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.51 in accordance with Law No. 466-IX of January 16, 2020 }
19 - 1 .1.52. exercise control over the timeliness, reliability, completeness of accrual and payment to the budget of dividends on the state share by business companies, in the authorized capital of which there are corporate rights of the state, as well as business companies, 50 or more percent of the shares (shares, units) of which are in the authorized capitals of business companies, in which the state share is 100 percent;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.52 in accordance with Law No. 466-IX of January 16, 2020 }
19 - 1 .1.52 - 1 . exercise control over the timeliness and completeness of payment of advance payments for corporate income tax by taxpayers engaged in trading in foreign currency in cash, advance payments for corporate income tax and personal income tax by taxpayers engaged in retail fuel trade;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.52 - 1 in accordance with Law No. 2720-IX of 03.11.2022 ; as amended by Law No. 4015-IX of 10.10.2024 }
19 - 1 .1.53. submit to local self-government bodies the reporting specified in subparagraph 12.3.3 of paragraph 12.3 of Article 12 of this Code, including on taxpayers - legal entities;
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.53 in accordance with Law No. 466-IX of January 16, 2020 }
19 - 1 .1.53 - 1 . provide the central executive body that ensures the formation and implementation of state policy in the field of digital economy with the information necessary to determine the compliance of a legal entity with the requirements specified in paragraphs 2 , 3 of part one, paragraphs 3 , 10 of part two and paragraph 3 of part three of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine";
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.53 - 1 in accordance with Law No. 1946-IX of 14.12.2021 }
19 - 1 .1.53 - 2 . inform the National Anti-Corruption Bureau of Ukraine about:
facts of the taxpayer indicating in the corporate income tax return the difference defined by subparagraph 140.6.1 of paragraph 140.6 of Article 140 of this Code, or the object of taxation defined by subparagraph 141.9 - 1 .2.16 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of Article 141 of this Code;
circumstances (facts) that may indicate the implementation of transactions aimed at providing an illegal benefit to an official of a foreign state, identified during documentary checks of taxpayers;
cases of receiving information from the competent authorities of a foreign state indicating the implementation of transactions aimed at providing an illegal benefit to an official of a foreign state.
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.53 - 2 in accordance with Law No. 4112-IX of 04.12.2024 }
19 - 1 .1.53 - 3 . provide the Ministry of Defense of Ukraine with the information necessary to determine the compliance of the legal entity with the requirements established by paragraphs 2-4 of part seven of Article 37 of the Law of Ukraine "On National Security of Ukraine", and also inform the Ministry of Defense of Ukraine about the establishment of the fact of misuse by a resident of Defense City of tax-exempt income and/or the identified non-compliance of the resident of Defense City with the requirements established by the Law of Ukraine "On National Security of Ukraine".
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.53 - 3 in accordance with Law No. 4577-IX of 21.08.2025 }
19 - 1 .1.54. perform other functions defined by law.
{Clause 19 - 1 .1 of Article 19 - 1 is supplemented by subparagraph 19 - 1 .1.54 in accordance with Law No. 466-IX of January 16, 2020 }
19 - 1 .2. The supervisory authorities specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code shall perform the following functions:
19 - 1 .2.1. organize and carry out accounting and administration of customs duties, excise taxes, value added tax, other taxes, which, in accordance with tax, customs and other legislation, are collected in connection with the import (shipment) of goods into the customs territory of Ukraine or the territory of a free customs zone or the export (shipment) of goods from the customs territory of Ukraine or the territory of a free customs zone, ensure control over the timeliness, reliability, completeness of their calculation and payment in full by taxpayers to the relevant budget during the movement of goods across the customs border of Ukraine and after the completion of customs control and customs clearance operations;
19 - 1 .2.2. form and maintain the Unified State Register of Authorized Economic Operators;
19 - 1 .2.3. perform other functions defined by law.
{Article 19 - 1 is supplemented by paragraph 19 - 1 .2 in accordance with Law No. 466-IX of 16.01.2020 }
{The Code is supplemented by Article 19 - 1 in accordance with Law No. 5083-VI of 05.07.2012 ; as amended in accordance with Law No. 5519-VI of 06.12.2012 ; as amended by Law No. 404-VII of 04.07.2013 }
Article 19 - 2. Functions of the central executive body that ensures the formation and implementation of state financial policy, in terms of ensuring the formation and implementation of tax and customs policy↑
19 - 2 .1. The central executive body that ensures the formation and implementation of state financial policy, in terms of ensuring the formation and implementation of tax and customs policy, performs the following functions:
19 - 2 .1.1. coordinates the activities of regulatory bodies;
19 - 2 .1.2. approves regulatory legal acts on issues within the competence of regulatory authorities;
19 - 2 .1.3. forecasts, analyzes the receipts of taxes, fees, payments determined by the Tax and Customs Codes of Ukraine, the Law of Ukraine "On the Collection and Accounting of a Single Contribution for Compulsory State Social Insurance", sources of tax revenues, studies the impact of macroeconomic indicators, legislation, agreements on accession to international organizations, other international treaties of Ukraine on the receipts of taxes, fees, payments, provides proposals for increasing their volume and reducing budget losses;
19 - 2 .1.4. summarizes the practice of applying legislation on taxation, legislation on payment of a single contribution, develops draft regulatory legal acts;
19 - 2 .1.5. issues general tax advice in accordance with this Code;
19 - 2 .1.6. carries out mutual agreement procedures in accordance with international treaties of Ukraine on the avoidance of double taxation;
{Subclause 19 - 2 .1.6 of clause 19 - 2 .1 of article 19 - 2 as amended by Law No. 466-IX of 16.01.2020 }
19 - 2 .1.7. performs other functions provided for by law.
{Clause 19 - 2 .1 of Article 19 - 2 is supplemented by subparagraph 19 - 2 .1.7 in accordance with Law No. 466-IX of January 16, 2020 }
{ The Code is supplemented by Article 19 - 2 in accordance with the Law No. 1797-VIII dated 21.12.2016 }
Article 19 - 3. Functions of State Tax Inspectorates↑
19 - 3 .1. State tax inspectorates:
19 - 3 .1.1. provide services to taxpayers;
19 - 3 .1.2. carry out registration and record keeping of taxpayers and single contribution payers, objects of taxation and objects related to taxation;
19 - 3 .1.3. form and maintain the State Register of Individual Taxpayers, the Unified Data Bank of Taxpayers - Legal Entities, registers, the maintenance of which is entrusted by law to the controlling bodies specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code;
{Subclause 19 - 3 .1.3 of clause 19 - 3 .1 of article 19 - 3 as amended by the Law No. 466-IX dated 16.01.2020 }
19 - 3 .1.4. perform other taxpayer service functions defined by law.
{ The Code is supplemented by Article 19 - 3 in accordance with the Law No. 1797-VIII dated 21.12.2016 }
20.1. The supervisory authorities specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code have the right to:
{Paragraph one of clause 20.1 of Article 120 as amended by the Law No. 466-IX dated 16.01.2020 }
20.1.1. invite taxpayers, fees, payments or their representatives to verify the correctness of the calculation and timeliness of the payment of taxes, fees, payments, compliance with the requirements of the legislation on other issues, including legislation in the field of prevention and counteraction to the legalization (laundering) of proceeds from crime or the financing of terrorism, the control over which is entrusted to the regulatory authorities. Written notifications of such invitations shall be sent in accordance with the procedure established by Article 42 of this Code, no later than 10 calendar days before the date of the invitation, indicating the grounds for the invitation, the date and time to which the taxpayer (representative of the taxpayer) is invited;
{Sub-clause 20.1.1 of clause 20.1 of Article 20 as amended by the Law No. 1797-VIII dated 21.12.2016 }
20.1.1 - 1. analyze the financial condition of a taxpayer who has a tax debt and the status of securing such debt with a tax lien;
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.1 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
20.1.2. to perform the functions specified by law, receive free of charge from taxpayers, including charitable and other non-profit organizations, of all forms of ownership, in accordance with the procedure specified by law, certificates, copies of documents, certified by the signature of the taxpayer or his official and sealed (if any), on financial and economic activities, income received, expenses of taxpayers and other information related to the calculation and payment of taxes, fees, payments, on compliance with the requirements of the law, the control over which is entrusted to the controlling bodies, as well as financial and statistical reporting in accordance with the procedure and on the grounds specified by law;
20.1.3. receive free of charge from state bodies, local governments, enterprises, institutions and organizations of all forms of ownership and their officials, including from bodies that ensure the maintenance of relevant state registers (cadasters), information, documents and materials regarding taxpayers, and in cases specified by this Code - regarding heads of legal entities or permanent representative offices of non-resident debtors;
{Subclause 20.1.3 of Clause 20.1 of Article 20 as amended by Law No. 1914-IX of 11/30/2021 }
20.1.4. conduct inspections and reconciliations of taxpayers (except for the National Bank of Ukraine) in accordance with the legislation, including after customs control and/or customs clearance procedures;
20.1.5. receive free of charge from taxpayers, as well as from the National Bank of Ukraine, banks, other financial institutions, non-bank payment service providers, issuers of electronic money, certificates in accordance with the procedure and on the grounds specified in this Code, taking into account the laws determining the procedure for disclosure by the specified persons of information containing banking secrecy, the secrecy of the payment service provider, information on compliance with the deadlines for settlements for export and import of goods established by the National Bank of Ukraine in accordance with the procedure specified in the Law of Ukraine "On Banks and Banking Activities", and on the basis of a court decision - information on the volume and turnover of funds/electronic money in accounts with a bank/non-bank payment service provider, electronic wallets, information on the debtor's agreements on the storage of valuables or the provision to the debtor of an individual bank safe, protected by the bank;
{Subclause 20.1.5 of clause 20.1 of Article 20 as amended by the Law No. 1797-VIII dated 21.12.2016 ; as amended by Laws No. 2888-IX dated 12.01.2023 , No. 3706-IX dated 09.05.2024 }
20.1.5 - 1. receive information and documents free of charge from financial agents in the amounts, in the manner and on the grounds specified in this Code, taking into account the laws determining the procedure for disclosing restricted information.
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.5 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
20.1.6. to request and examine during inspections primary documents used in accounting, registers, financial, statistical and other reporting related to the calculation and payment of taxes, fees, payments, compliance with the requirements of the legislation, control over compliance with which is entrusted to regulatory authorities;
20.1.7. receive from taxpayers, single contribution payers and provide, within the limits provided by law, documents in electronic form;
20.1.8. during inspections of taxpayers - individuals, as well as officials of taxpayers - legal entities and single contribution payers, check identity documents, as well as documents confirming the position of officials and/or persons who actually carry out settlement operations;
20.1.9. to require, during inspections, taxpayers being inspected to conduct an inventory of fixed assets, inventory, funds, withdraw the balances of inventory, cash using information and documents regarding the results of such inventory as a result of such inspections or during subsequent tax control measures;
{Sub-clause 20.1.9 of clause 20.1 of Article 20 as amended by the Law No. 1797-VIII dated 21.12.2016 ; as amended by the Law No. 1914-IX dated 30.11.2021 }
20.1.10. to monitor compliance with legislation on the regulation of cash circulation (except for banks), the procedure for cash payments for goods (services), the availability of licenses for conducting types of economic activity subject to licensing in accordance with the law, trade patents, compliance with the procedure for accepting cash for further transfer (except for accepting cash by banks), compliance by business entities with mandatory requirements established by law to ensure the possibility of payments for goods (services) using electronic payment instruments;
20.1.11. conduct control settlement operations before the start of the audit of the taxpayer regarding his compliance with the procedure for cash settlements and the use of settlement transaction recorders and/or software recorders of settlement transactions. Goods received by officials of the regulatory authorities during the control settlement operation shall be returned to the taxpayer in an undamaged form. In the event that such goods cannot be returned, reimbursement of expenses shall be carried out in accordance with the legislation on consumer protection;
{Subclause 20.1.11 of clause 20.1 of Article 20 as amended by Law No. 129-IX of 20.09.2019 }
20.1.12. during inspections, require officials or employees of the taxpayer to involve authorized persons to jointly with employees of the supervisory authority take readings of internal and external meters equipped with technical devices used in the process of conducting the activity being inspected;
20.1.13. access during inspections to territories, premises (except for citizens' housing) and other property used for conducting economic activities and/or are objects of taxation, or are used to generate income (profit), or are related to other objects of taxation and/or may be a source of repayment of tax debt;
20.1.14. in case of detection of violations of the requirements of tax or other legislation of Ukraine, the control over compliance of which is entrusted to the regulatory authorities, to send written requests to taxpayers for the provision of duly certified copies of documents;
20.1.15. to require, during inspections, managers and other officials of enterprises, institutions and organizations, as well as individuals - entrepreneurs and individuals engaged in independent professional activities, to eliminate identified violations of the law;
20.1.16. use in official matters means of communication belonging to taxpayers, with their permission or with the permission of officials of such taxpayers;
20.1.17. to involve, if necessary, specialists, experts and translators, to use photography and video recording during the exercise by the tax manager of his powers specified in this Code;
{Sub-clause 20.1.17 of clause 20.1 of Article 20 as amended by the Law No. 1797-VIII dated 21.12.2016 }
20.1.18. determine, in accordance with the procedure established by this Code, the amounts of tax and monetary obligations of taxpayers;
20.1.19. apply to taxpayers financial (penal) sanctions (fines) provided for by law for violation of tax or other legislation, control over compliance with which is entrusted to regulatory authorities; collect from budgets and state trust funds the amounts of monetary obligations and/or tax debt in the cases, procedure and amount established by this Code and other laws of Ukraine; collect the amounts of arrears in the payment of a single contribution; collect the amounts of overdue debt of business entities to the state (Autonomous Republic of Crimea or territorial community of a city) for credits (loans) attracted by the state (Autonomous Republic of Crimea or territorial community of a city) or under state (local) guarantees, as well as for credits from the budget in the manner determined by this Code and other laws of Ukraine;
20.1.19 - 1. to implement decisions on the application of special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions", in the areas of relations regulated by this Code and other legislation, control over compliance with which is entrusted to regulatory authorities;
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.19 - 1 in accordance with Law No. 3317-IX of 10.08.2023 }
20.1.20. receive free of charge the necessary information for maintaining the Unified Register of Tax Invoices, the Unified Register of Excise Invoices, the formation of the information fund of the State Register of Individuals - Taxpayers from taxpayers, as well as the National Bank of Ukraine and its institutions - on the amounts of income paid to individuals and taxes, fees, payments withheld from them; from bodies authorized to conduct state registration of entities, issue licenses for the conduct of types of economic activity subject to licensing in accordance with the law - on state registration and issuance of licenses to entities of economic activity; from bodies carrying out registration of individuals - on citizens who arrived for residence in the relevant settlement or left it; from bodies of state registration of civil status acts - on individuals who died; information necessary to ensure registration and accounting of taxpayers, objects of taxation and objects related to taxation;
{Subclause 20.1.20 of clause 20.1 of Article 20 as amended by Law No. 909-VIII of 24.12.2015 }
20.1.21. to receive free of charge from statistical bodies the data necessary for use in analyzing the financial and economic activities of enterprises, institutions, and organizations of all forms of ownership;
20.1.22. receive from notaries upon written request information about the entry of an individual into the rights of heir with the mandatory indication of complete data about such person and data about property received by right of inheritance;
20.1.23. provide, in accordance with the law, information from the State Register of Individual Taxpayers and the Register of Insurers to state authorities, the Pension Fund of Ukraine and the funds of mandatory state social insurance;
{Sub-clause 20.1.23 of clause 20.1 of Article 20 as amended by the Law No. 466-IX dated 16.01.2020 }
20.1.24. receive free of charge from the bodies that ensure the maintenance of the relevant state registers (cadasters), information necessary for the exercise of the powers of the supervisory bodies to ensure the repayment of the taxpayer's tax debt. In cases provided for by law, the tax manager has the right to direct access to information about debtors contained in state databases and registers, including electronic ones. The term for providing information certificates by these bodies to written requests from the supervisory bodies cannot exceed five working days from the date of receipt of such requests;
{Subclause 20.1.24 of clause 20.1 of Article 20 as amended by the Law No. 1797-VIII dated 21.12.2016 }
20.1.25. make decisions on changing the main and secondary place of registration of large taxpayers, removing them from registration and transferring them to the territorial body of the central executive body implementing state tax policy, providing tax support to large taxpayers (its structural units), and other territorial bodies of the central executive body implementing state tax policy;
{Sub-clause 20.1.25 of clause 20.1 of Article 20 as amended by the Law No. 466-IX dated 16.01.2020 }
20.1.26. use information databases of state bodies, state, including government, communication systems, special communication networks and other technical means in accordance with the law;
20.1.27. apply financial (penalty) sanctions (fines) in the amount established by this Code to banks, other financial institutions, non-bank payment service providers, and electronic money issuers that have not submitted to the relevant regulatory authorities within the time period established by law a notification on the opening or closing of taxpayer accounts/electronic wallets or have begun to carry out expenditure transactions on the taxpayer's account/electronic wallet before receiving a notification from the relevant regulatory authority on the registration of the account/electronic wallet with such authority;
{Sub-clause 20.1.27 of clause 20.1 of Article 20 as amended by the Law No. 2888-IX dated 12.01.2023 }
20.1.28. to charge banks, other financial institutions, non-bank payment service providers, electronic money issuers, the body that provides treasury services for budget funds, a penalty for their untimely execution of court decisions, decisions of the head of the collection body (his deputy or authorized person) in cases provided for by this Code, and payment instructions of taxpayers on the payment of taxes, fees, and payments;
{Sub-clause 20.1.28 of clause 20.1 of Article 20 as amended by the Law No. 2888-IX dated 12.01.2023 }
20.1.29. make decisions on the installment and postponement of monetary obligations or tax debt, as well as on the write-off of bad tax debt in accordance with the procedure provided for by law;
20.1.30. to apply to court, including filing lawsuits against enterprises, institutions, organizations and individuals, to declare disputed transactions invalid and to apply measures specified by law related to declaring transactions invalid, as well as to recover funds received under invalid contracts from the state budget;
20.1.31. apply to the court to suspend the taxpayer's expenditure transactions on the accounts/electronic wallets of such taxpayer in banks, other financial institutions, non-bank payment service providers, issuers of electronic money (except for transactions on the issuance of wages and payment of taxes, fees, single contribution, as well as monetary obligations of the taxpayer determined by the regulatory authority, repayment of tax debt), including when preventing officials of regulatory authorities from inspecting territories and premises;
{Subclause 20.1.31 of clause 20.1 of Article 20 as amended by the Law No. 2888-IX dated 12.01.2023 }
20.1.32. to apply to court if the taxpayer impedes the tax administrator's exercise of the powers specified in this Code to suspend expenditure transactions on the taxpayer's accounts/electronic wallets by imposing an arrest on securities and/or funds and other valuables of such taxpayer located in a bank, other financial institution, non-bank payment service provider, electronic money issuer (except for transactions on the issuance of wages and payment of taxes, fees, single contribution, as well as monetary obligations of the taxpayer determined by the supervisory authority, repayment of tax debt), and the obligation of such taxpayer to fulfill the lawful requirements of the tax administrator provided for in this Code;
{Subclause 20.1.32 of clause 20.1 of Article 20 as amended by the Law No. 2888-IX dated 12.01.2023 }
20.1.33. apply to the court for the seizure of funds and other valuables located in a bank, other financial institution, non-bank payment service provider, electronic money issuer, taxpayer who has a tax debt, if such taxpayer has no property and/or its book value is less than the amount of the tax debt, and/or such property cannot be a source of repayment of the tax debt;
{Subclause 20.1.33 of clause 20.1 of Article 20 as amended by the Law No. 2888-IX dated 12.01.2023 }
20.1.34. apply to the court to collect funds of a taxpayer who has a tax debt from accounts in banks, other financial institutions, non-bank payment service providers, electronic wallets in electronic money issuers serving such taxpayer, in the amount of the tax debt or part thereof;
{Subclause 20.1.34 of clause 20.1 of Article 20 as amended by the Law No. 2888-IX dated 12.01.2023 }
20.1.34 - 1. apply to the court for permission to repay the entire amount of the tax debt or part of it at the expense of the taxpayer's property that is subject to tax lien;
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.34 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
20.1.35. apply to the court to recover from the debtors of a taxpayer who has a tax debt the amount of the receivable, the maturity date of which has come and the right to claim which has been transferred to the regulatory authority, against the repayment of the tax debt of such taxpayer;
20.1.35 - 1. apply to the court regarding the obligation of a taxpayer who has a tax debt to conclude an agreement on the transfer of the right to claim the receivables of this taxpayer to the regulatory authority;
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.35 - 1 in accordance with the Law No. 1797-VIII dated 21.12.2016 }
20.1.35 - 2. apply to the court to establish a temporary restriction on the right of heads of legal entities or permanent representative offices of non-resident debtors to travel outside Ukraine in the event of failure to fulfill the tax obligation to pay monetary obligations, which led to the emergence of a tax debt for such legal entity or permanent representative office of a non-resident;
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.35 - 2 in accordance with the Law No. 1914-IX dated 30.11.2021 }
20.1.36. apply to the court regarding the assessment and payment of tax liabilities, adjustment of the negative value of the taxable object or other tax reporting indicators as a result of the application of ordinary prices;
20.1.37. apply to the court regarding the termination of a legal entity and the termination of entrepreneurial activity by an individual entrepreneur and/or the invalidation of the constituent (founding) documents of business entities;
20.1.38. apply to the court with an application for the seizure of originals of primary financial, economic and accounting documents in cases provided for by this Code;
20.1.39. apply to the court with applications for the initiation of bankruptcy proceedings;
20.1.40. apply to the court regarding the application of sanctions related to the prohibition of organizing and conducting gambling on the territory of Ukraine;
20.1.40 - 1. apply to the court for recognition of persons as related based on facts and circumstances that one person exercised actual control over the business decisions of another legal entity and/or that the same individual or legal entity exercised actual control over the business decisions of each legal entity;
{Clause 20.1 of Article 20 is supplemented by clause 20.1.40 - 1 in accordance with Law No. 72-VIII of 28.12.2014 ; as amended by Law No. 2245-VIII of 07.12.2017 }
20.1.40 - 2. apply to the court for the seizure of fuel or ethyl alcohol, vehicles, containers and equipment to the state revenue (confiscation) in case of detection of facts specified in Article 228 of this Code;
{Clause 20.1 of Article 20 is supplemented by clause 20.1.40 - 2 in accordance with Law No. 2628-VIII of 23.11.2018 }
20.1.41. to draw up protocols on administrative offenses against individual taxpayers and officials of legal entities and to issue resolutions in cases of administrative offenses in accordance with the procedure established by law;
20.1.42. to manage tax risks within the limits of the powers defined by this Code;
{Subclause 20.1.42 of clause 20.1 of Article 20 as amended by Law No. 466-IX of 01/16/2020 ; as amended by Law No. 3813-IX of 06/18/2024 }
20.1.43. conduct, in accordance with the procedure established by law, a check of indicators related to the determination of objects of taxation and the timeliness, accuracy, completeness of the calculation and payment of all taxes and fees provided for by this Code, and the implementation of legislation on other issues, the control over compliance with which is entrusted to regulatory authorities;
{Clause 20.1 of Article 20 is supplemented by a new subparagraph 20.1.43 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by the Law No. 1797-VIII dated 21.12.2016 }
20.1.44. to verify the correctness and completeness of the determination of the financial result before taxation according to accounting in accordance with national accounting regulations (standards) or international financial reporting standards;
{Clause 20.1 of Article 20 is supplemented by a new subparagraph 20.1.44 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
20.1.45. carry out daily processing of data and information of the electronic office necessary for the performance of the functions assigned to them in the administration of tax legislation and legislation on other issues, control over compliance with which is entrusted to the regulatory authority, which includes, in particular, the acceptance, processing and analysis of documents and data of taxpayers, the exercise of powers provided for by law, which can be implemented in electronic form using electronic means of communication;
{Subclause 20.1.45 of clause 20.1 of Article 20 as amended by the Law No. 1797-VIII dated 21.12.2016 }
20.1.46. during the inspection and consideration of the inspection results, receive written explanations from officials (service personnel) on issues related to the subject of the inspection, and their documentary confirmation, including regarding the person's conduct of economic activities without state registration;
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.46 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
20.1.47. receive explanations from employers and/or their employees, and/or persons whose labor is used without documentation, during inspections on the employer's compliance with the legislation on concluding an employment contract, registration of employment relations with employees (employees), compliance by the tax agent with tax legislation on taxation of wages paid (accrued) to employees (including without documentation), including as a result of the taxpayer's failure to conclude employment contracts with employees in accordance with the law;
{Clause 20.1 of Article 20 is supplemented by a new subparagraph 20.1.47 in accordance with Law No. 466-IX of 16.01.2020 ; with amendments made in accordance with the Law No. 786-IX dated 14.07.2020 }
20.1.48. openly use technical devices and technical means that have the functions of photo and film shooting, video recording, means of photo and film shooting, video recording; openly make sound recordings, photo and video fixation (video recording), accumulate and use such multimedia information (photo, video, sound recording) during inspections;
{Clause 20.1 of Article 20 is supplemented with a new subparagraph in accordance with the Law No. 1914-IX dated 30.11.2021 }
20.1.49. exercise other powers provided for by law.
{Clause 20.1 of Article 20 is supplemented with a new subparagraph in accordance with Law No. 466-IX of January 16, 2020 }
20.1.50. receive free of charge from banks in accordance with the procedure established by the Law of Ukraine "On Banks and Banking" and this Code, information on transactions on accounts of electronic residents (e-residents), namely information on a specified date or for a specified period of time on transactions of crediting funds to accounts, purpose of payment, identification data and account number of the counterparty.
{Clause 20.1 of Article 20 is supplemented by subparagraph 20.1.50 in accordance with Law No. 2654-IX of 06.10.2022 }
20.1 - 1. The supervisory authorities specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code have the right:
20.1 - 1 .1. receive free of charge in accordance with the established procedure from state bodies and local self-government bodies, enterprises, institutions and organizations regardless of the form of ownership and their officials, taxpayers information, documents and materials relating to the accounting and administration of customs duties, excise tax, value added tax, other taxes, which, in accordance with tax, customs and other legislation, are collected in connection with the import (shipment) of goods into the customs territory of Ukraine or the territory of a free customs zone or the export (shipment) of goods from the customs territory of Ukraine or the territory of a free customs zone;
20.1 - 1 .2. conduct analysis and manage risks in order to determine the forms and scope of customs control;
20.1 - 1 .3. exercise other powers provided for by law.
{Article 20 supplemented with paragraph 20.1 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
20.2. The central executive body implementing the state tax policy shall make a decision on the registration/refusal to register tax invoices /adjustment calculations in the Unified Register of Tax Invoices in accordance with the procedure determined by the central executive body ensuring the formation and implementation of the state financial policy.
{Article 20 is supplemented by paragraph 20.2 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
20.3. Controlling authorities are prohibited from requiring a taxpayer to provide:
information previously received by the supervisory authority in accordance with the procedure established by law, including information contained and processed in databases maintained in accordance with Article 74 of this Code;
documents containing information entered into the relevant information databases maintained in accordance with Article 74 of this Code.
{Article 20 is supplemented by paragraph 20.3 in accordance with Law No. 1797-VIII of 21.12.2016 }
20.4. The head of a territorial body of a central executive body implementing state tax policy has the right to grant officials (service personnel) of such a body (its structural divisions) the authority to perform certain functions provided for by this Code, legislation on the payment of a single contribution, legislation on other issues, control over compliance with which is entrusted to controlling bodies, within the limits of the authority determined by the relevant provision on such territorial body.
The head of the central executive body implementing the state tax policy has the right to grant officials (service personnel) of the apparatus of such body, territorial bodies of the central executive body implementing the state tax policy, the authority to perform certain functions provided for by this Code, legislation on the payment of a single contribution, other legislation, control over compliance with which is entrusted to the central executive body implementing the state tax policy, legislation on civil service and other laws.
The list of delegated powers is determined by the regulation on the central executive body implementing state tax policy, which is approved by the Cabinet of Ministers of Ukraine, and by the regulations on the territorial body of the central executive body implementing state tax policy, which are approved by the central executive body implementing state tax policy, and are subject to coordination with the central executive body ensuring the formation and implementation of state financial policy.
Heads of territorial bodies of the central executive body implementing state tax policy are appointed to and dismissed from their positions by the head of the central executive body implementing state tax policy, in accordance with the legislation on civil service without the consent of the heads of local state administrations.
{Article 20 is supplemented by paragraph 20.4 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
{Article 20 as amended by Laws No. 3205-VI of 07.04.2011 , No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 , No. 5083-VI of 05.07.2012 , No. 5519-VI of 06.12.2012 ; as amended by Law No. 404-VII of 04.07.2013 }
Article 21. Duties and responsibilities of officials and employees of controlling bodies↑
{Title of Article 21 as amended by Law No. 2245-VIII of 07.12.2017 }
21.1. Officials and employees of regulatory bodies are obliged to:
{Paragraph one of clause 21.1 of Article 21 as amended by Law No. 2245-VIII of 07.12.2017 }
21.1.1. to comply with the Constitution of Ukraine and act exclusively in accordance with this Code and other laws of Ukraine, other regulatory acts;
21.1.2. ensure the conscientious performance of the functions assigned to the supervisory authorities;
21.1.3. ensure the effective work and performance of tasks of regulatory bodies in accordance with their powers;
21.1.4. prevent violations of the rights and legally protected interests of citizens, enterprises, institutions, and organizations;
21.1.5. to treat taxpayers, their representatives and other participants in relations arising during the implementation of the norms of this Code and other laws correctly and attentively, not to humiliate their honor and dignity;
21.1.6. prevent the disclosure of restricted information received, used, and stored during the implementation of the functions assigned to the regulatory authorities.
in paragraph seven of subparagraph 12.3.3 of clause 12.3 of Article 12 of this Code shall not be considered disclosure of information with limited access and/or dissemination of personal data without the consent of the personal data subject ;
{Sub-clause 21.1.6 of clause 21.1 of Article 21 is supplemented by the second paragraph in accordance with the Law No. 1914-IX dated 30.11.2021 }
21.1.7. provide public tax information to state authorities and local self-government bodies upon their written request in accordance with the procedure established by law;
21.1.7 - 1. based on the results of the inspection, notify the bank serving the taxpayer of the absence of a violation of the payment deadlines established by the National Bank of Ukraine for transactions on the export and import of goods, information about which was received from the National Bank of Ukraine and banks.
The form and procedure for notifying banks by the supervisory authority are established by the central executive authority that ensures the formation and implementation of state financial policy;
{Clause 21.1 of Article 21 is supplemented by subparagraph 21.1.7 - 1 in accordance with Law No. 3706-IX of 09.05.2024 }
21.1.8. publish on the official website of the central executive body implementing state tax policy a list of authorized persons of the controlling bodies, defined by subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, and the functions assigned to such persons in cases provided for by this Code;
{Clause 21.1 of Article 21 is supplemented by subparagraph 21.1.8 in accordance with Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
21.1.8 - 1. publish on the official website of the central executive body implementing the state customs policy a list of authorized persons of the control bodies specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code, and the functions assigned to such persons in cases provided for by this Code and the Customs Code of Ukraine ;
{Clause 21.1 of Article 21 is supplemented by subparagraph 21.1.8 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
21.1.9. use data and information received through the electronic account necessary to perform the functions assigned to them in the administration of taxes, fees, customs payments and the implementation of state tax and state customs policy within the limits of the powers granted to them;
{Clause 21.1 of Article 21 is supplemented by subparagraph 21.1.9 in accordance with Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016; as amended by Law No. 466-IX of 16.01.2020 }
21.1.10. enter into information databases information from documents received from taxpayers in paper form, as well as information on interaction with taxpayers received in another form;
{Clause 21.1 of Article 21 is supplemented by subparagraph 21.1.10 in accordance with Law No. 1797-VIII of 21.12.2016 }
21.1.11. immediately post on the official website of the central executive body implementing the state tax policy a notice of the detection of technical and/or methodological errors or a technical failure in the operation of the electronic office, indicating the date and time of their beginning, and immediately take all necessary measures to eliminate such technical and/or methodological errors or technical failure, as a result of which post on the official website of the central executive body implementing the state tax policy a notice of their elimination, indicating the date and time of their completion;
{Clause 21.1 of Article 21 is supplemented by subparagraph 21.1.11 in accordance with Law No. 786-IX of 14.07.2020 }
21.1.12. interact with taxpayers in cases provided for by this Code, via video conference.
{Clause 21.1 of Article 21 is supplemented by subparagraph 21.1.12 in accordance with Law No. 3603-IX of 23.02.2024 }
21.2. Officials of regulatory bodies shall be liable in accordance with the law for failure to perform or improper performance of their duties.
{Clause 21.2 of Article 21 as amended by Law No. 1797-VIII of 21.12.2016 }
21.2.1. for making an unlawful decision determining the tax (monetary) obligations of a taxpayer, the official (service) person of the controlling body who made such a decision, as well as the immediate supervisor of such official, shall be liable in accordance with the law.
Repeated adoption of an unlawful decision determining the tax (monetary) obligations of taxpayers by an official (service) of the controlling body who made such a decision within the last twelve months shall be grounds for the application of disciplinary action to such official (service) in accordance with the procedure prescribed by law.
{Clause 21.2 of Article 21 is supplemented by subparagraph 21.2.1 in accordance with Law No. 1797-VIII of 21.12.2016 }
21.2.2. Illegal refusal to provide individual tax advice is grounds for applying disciplinary action to the guilty official (service) of the supervisory body in accordance with the procedure provided for by law.
{Clause 21.2 of Article 21 is supplemented by subparagraph 21.2.2 in accordance with Law No. 466-IX of January 16, 2020 }
21.3. Damage caused to a taxpayer by unlawful decisions, actions or inaction of an official or employee of a regulatory body shall be compensated at the expense of the state budget funds allocated for financing this body, regardless of the fault of this person.
{Clause 21.3 of Article 21 as amended by Law No. 2245-VIII of 07.12.2017 }
21.4. An official or employee of a regulatory body shall be liable to the state in the form of recourse in the amount of compensation paid from the budget due to unlawful decisions, actions or inaction of this official (employee).
{Article 21 is supplemented by paragraph 21.4 in accordance with Law No. 2245-VIII of 07.12.2017 }
Article 21 - 1. Implementation of special economic and other restrictive measures (sanctions)↑
21 - 1 .1. Supervisory bodies shall implement decisions on the application of special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions", by implementing the following measures:
cancellation of licenses for the right to carry out activities in the field of production and circulation of alcohol, alcoholic beverages, tobacco products, liquids used in electronic cigarettes, and fuel - in the event of application of sanctions for the cancellation or suspension of licenses and other permits, the receipt (availability) of which is a condition for carrying out a certain type of activity;
refusal/suspension of the refund of erroneously and/or excessively paid amounts of taxes and fees, single contribution to mandatory state social insurance, penalties, fines - in the event of the application of a sanction to suspend the fulfillment of economic and financial obligations;
refusal to grant installments (deferrals) of monetary obligations (tax debt), as well as to make a decision to postpone the payment deadlines for installments (deferred) amounts - in the event of the application of a sanction to suspend the fulfillment of economic and financial obligations;
suspension/refusal to provide budget reimbursement of value added tax - in the event of application of a sanction to suspend the fulfillment of economic and financial obligations.
21 - 1 .2. The basis for the implementation by the supervisory authority of the measures specified in paragraph 21 - 1 .1 of this article is a decision on the application (amendment) of special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions".
{The Code is supplemented by Article 21 - 1 in accordance with Law No. 3317-IX of 10.08.2023 }
22.1. The object of taxation may be property, goods, income (profit) or part thereof, turnover from the sale of goods (works, services), transactions for the supply of goods (works, services) and other objects defined by tax legislation, the presence of which tax legislation associates with the emergence of a tax liability for the payer.
22.2. It is prohibited to reduce the object of taxation (income (profit), its part) by the amount of expenses in transactions:
committed with the aim of providing an improper benefit to an official (including an official of a foreign state), and/or
the totality of the conditions for the implementation of which gives rise to grounds to believe that the existing circumstances (facts) may indicate the implementation of such transactions with the aim of providing an unlawful benefit to an official (including an official of a foreign state).
It is prohibited to apply the provisions of this Code that may lead to a reduction in the object of taxation with respect to the results of transactions provided for in paragraphs two and three of this paragraph, including their taxation as part of the object of taxation at a tax rate lower than the base (basic) rate, as well as to use other tax benefits with respect to such transactions or their results.
The requirements of this paragraph do not limit the application of other provisions of this Code regarding the specifics of determining the object of taxation in the event that a taxpayer engages in activities prohibited by law or the performance of which is grounds for applying criminal measures or bringing the taxpayer and/or its officials to criminal liability in accordance with the law.
{Article 22 is supplemented by paragraph 22.2 in accordance with Law No. 4112-IX of 04.12.2024 }
23.1. The tax base is recognized as specific cost, physical or other characteristics of a certain taxable object.
The tax base is a physical, value or other characteristic expression of the object of taxation to which the tax rate is applied and which is used to determine the amount of the tax liability.
23.2. The tax base and the procedure for its determination are established by this Code for each tax separately.
23.3. In cases provided for by this Code, one taxable object may form several tax bases for different taxes.
23.4. In cases provided for by this Code, a specific value, physical or other characteristic of a certain taxable object may be the tax base for various taxes.
24.1. The unit of measurement of the tax base is a specific value, physical or other characteristic of the tax base or its part to which the tax rate is applied.
24.2. The unit of measurement of the tax base is the same for calculating and accounting for tax.
24.3. One unit of measurement of the tax base must correspond to one tax base.
28.1. An absolute (specific) tax rate is one in which the amount of tax assessments is set as a fixed value in relation to each unit of measurement of the tax base.
28.2. A relative (ad valorem) tax rate is a tax rate according to which the amount of tax assessments is set as a percentage or multiple of the unit of value of the tax base.
29.1. The tax amount is calculated by multiplying the tax base by the tax rate with/without applying the appropriate coefficients.
29.2. Specific rates, fixed rates and indicators established by this Code in value terms are subject to indexation in the manner specified by this Code.
30.1. Tax benefit - exemption of a taxpayer from the obligation to calculate and pay taxes and fees, provided for by tax and customs legislation, payment of taxes and fees in a lower amount if there are grounds specified in paragraph 30.2 of this article.
30.2. The grounds for granting tax benefits are the features that characterize a certain group of taxpayers, their type of activity, the object of taxation, or the nature and social significance of the expenses they incur.
30.3. A taxpayer has the right to use a tax benefit from the moment the relevant grounds for its application arise and throughout its entire term.
30.4. A taxpayer has the right to refuse to use a tax benefit (except for tax benefits on value added tax) or to suspend its use for one or more tax periods, unless otherwise provided for by this Code. Tax benefits not used by a taxpayer cannot be carried over to other tax periods, credited against future payments of taxes and fees, or reimbursed from the budget.
{Clause 30.4 of Article 30 as amended by Law No. 2628-VIII of 23.11.2018 }
30.5. Tax benefits, the procedure and grounds for their provision are established taking into account the requirements of the legislation of Ukraine on the protection of economic competition exclusively by this Code, decisions of the Verkhovna Rada of the Autonomous Republic of Crimea and local self-government bodies adopted in accordance with this Code.
30.6. Amounts of taxes and fees not paid by a business entity to the budget in connection with receiving tax benefits shall be accounted for by such entity - taxpayer. Accounting for the specified funds shall be conducted in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
30.7. Controlling bodies compile summarized information on the amounts of tax benefits for legal entities and individual entrepreneurs and determine the loss of budget revenues as a result of the provision of tax benefits.
30.8. Controlling bodies exercise control over the correctness of the provision and accounting of tax benefits, as well as their intended use, provided that there is a legislative definition of the areas of use (regarding conditional tax benefits) and the timely return of funds not paid to the budget as a result of the provision of the benefit, if it is provided on a repayable basis.
{Clause 30.8 of Article 30 as amended by Law No. 466-IX of January 16, 2020 }
30.9. Tax relief is granted by:
a) tax deduction (rebate), which reduces the tax base before tax and fee are charged;
b) reduction of tax liability after tax and fee are calculated;
31.1. The period for payment of a tax and fee is considered to be the period starting from the moment of the taxpayer's tax liability for paying a specific type of tax and ending on the last day of the period during which such tax or fee must be paid in accordance with the procedure established by tax legislation. A tax or fee that has not been paid within the specified period is considered not paid on time.
The moment of occurrence of the tax liability of a taxpayer, including a tax agent, is determined by a calendar date.
31.2. The term for payment of taxes and fees is calculated in years, quarters, months, decades, weeks, days, or by reference to an event that must occur or take place.
31.3. The deadline for payment of taxes and fees shall be established in accordance with tax legislation for each tax separately. A change by a taxpayer, tax agent or representative of a taxpayer or a supervisory authority of the established deadline for payment of taxes and fees shall be prohibited, except in cases provided for by this Code.
Article 32. Change of the deadline for payment of taxes and fees↑
32.1. A change in the deadline for payment of a tax and fee is carried out by postponing the deadline for payment of a tax and fee established by tax legislation or its part to a later date.
32.2. A change in the tax payment deadline is carried out in the form of installments or deferral of monetary obligations or tax debt.
{Clause 32.2 of Article 32 as amended by Law No. 657-VII of 24.10.2013 ; as amended by Law No. 3813-IX of 18.06.2024 }
32.3. Changing the tax payment deadline does not cancel the existing tax obligation or create a new tax obligation.
33.1. A tax period is a period of time established by this Code, taking into account which certain types of taxes and fees are calculated and paid.
33.2. A tax period may consist of several reporting periods.
33.3. Base tax (reporting) period - the period for which the taxpayer is obliged to make tax calculations, submit tax declarations (reports, calculations) and pay the amounts of taxes and fees to the budget, except for cases provided for by this Code, when the regulatory authority is obliged to independently determine the amount of the taxpayer's tax liability.
{Subclause 34.1.3 of Clause 34.1 of Article 34 as amended by Law No. 4834-VI of 24.05.2012 }
34.1.4. calendar quarter;
{Subclause 34.1.4 of Clause 34.1 of Article 34 as amended by Law No. 4834-VI of 24.05.2012 }
34.1.5. calendar month;
{Subclause 34.1.5 of Clause 34.1 of Article 34 as amended by Law No. 4834-VI of 24.05.2012 }
34.1.6. calendar day.
{Subclause 34.1.6 of Clause 34.1 of Article 34 as amended by Law No. 4834-VI of 24.05.2012 }
{Clause 34.1 of Article 34 as amended by Law No. 3609-VI of 07.07.2011 }
Article 35. Procedure for payment of taxes and fees↑
35.1. Payment of taxes and fees shall be made in cash in the national currency of Ukraine, except for cases provided for by this Code or laws on customs matters.
35.2. Payment of taxes and fees shall be made in cash or non-cash form (including using electronic money), except for cases provided for by this Code or laws on customs matters. For the purposes of this Code, the taxpayer's obligation to pay taxes and fees to the single account specified in Article 35-1 of this Code shall be deemed to have been fulfilled from the moment when the initiation of the transfer is completed for such taxpayer in accordance with the Law of Ukraine "On Payment Services".
{Clause 35.2 of Article 35 as amended by Law No. 190-IX of 04.10.2019 ; as amended by Law No. 2888-IX of 12.01.2023 }
35.3. The procedure for paying taxes and fees is established by this Code or laws on customs matters for each tax separately.
35.4. The following shall be published on the official web portal of the central executive body implementing state tax policy:
daily information on business entities that have tax debt, indicating the heads of such business entities and the amounts of tax debt broken down by payments and territorial bodies of the central executive body that implements state tax policy, indicating the heads of such territorial bodies;
monthly:
information on tax payments by natural monopolies and business entities that pay rent for the use of subsoil;
information about individuals who have tax debt, indicating the last name, first name, patronymic (if any), date of birth of the individual, amounts of tax debt broken down by payments and territorial bodies of the central executive body implementing state tax policy, indicating the heads of such territorial bodies;
information on the payment of taxes and fees by business entities that are registered as payers of excise tax on fuel sales and/or have received licenses for the right to produce or store fuel (except for the storage of fuel that is not sold to other persons and is used exclusively for the needs of own consumption or industrial processing), wholesale or retail trade in fuel.
The form of such information and the procedure for its publication are established by the central executive body that ensures the formation and implementation of state financial policy.
The supervisory authority shall not be liable for the publication of information provided for in this paragraph that is erroneous due to the taxpayer indicating incorrect details in documents on the payment of taxes and fees, failure to fulfill the obligation to provide supervisory authorities with information about changes in their data or data on objects of taxation, or for other reasons independent of the supervisory authorities.
{Article 35 is supplemented by paragraph 35.4 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Law No. 466-IX of 16.01.2020 ; as amended by the Law No. 1914-IX dated 30.11.2021 }
35 - 1 .1. A single account is an account opened in the central executive body implementing state policy in the field of treasury servicing of budget funds, for the central executive body implementing state tax policy, which can be used by a taxpayer to pay monetary obligations and/or tax debt on taxes and fees provided for by this Code, a single contribution and other payments, control over the collection of which is entrusted to the controlling bodies.
The single account cannot be used by a taxpayer to pay monetary obligations and/or tax debt on value added tax, excise tax on the sale of fuel and ethyl alcohol, as well as to pay part of the net profit (income) to the budget by state and municipal unitary enterprises and their associations.
Acceptance of electronic money into a single account is not allowed.
{Clause 35 - 1 .1 of Article 35 - 1 is supplemented by the third paragraph in accordance with Law No. 2888-IX of 12.01.2023 }
35 - 1 .2. Notification of use or refusal to use a single account shall be submitted by the taxpayer in electronic form through the electronic account in accordance with the procedure established by Article 42 - 1 of this Code.
A taxpayer has the right to report the use or refusal to use a single account once during a calendar year.
The taxpayer's use of a single account begins on the day following the day he submits a notification on the use of a single account.
If a taxpayer refuses to use a single account, such use shall cease starting from the first day of the month of the following calendar year.
35 - 1 .3. Upon the start of using a single account, the taxpayer is obliged to pay monetary obligations and/or tax debt on taxes and fees, a single contribution, other payments, control over the collection of which is entrusted to the regulatory authorities, through a single account, except for the cases provided for in the second paragraph of paragraph 35 - 1 .1 of this article.
In case of violation of the provisions specified in the first paragraph of this paragraph, funds paid by such a taxpayer to other accounts opened by the central executive body implementing state policy in the field of treasury servicing of budget funds, for the payment of monetary obligations and/or tax debt on taxes and fees, single contribution, other payments, control over the collection of which is entrusted to the controlling bodies, shall be considered erroneously paid monetary obligations.
35 - 1 .4. To transfer funds received to a single account, the central executive body implementing the state tax policy shall, every day, except weekends, holidays and non-working days, form, sign and send to the central executive body implementing the state policy in the field of treasury services of budget funds, a consolidated register of payments from the single account indicating the payment details of the recipients of funds and other information in accordance with the legislation.
The consolidated register of payments from a single account includes data from all registers of payments from a single account broken down by individual taxpayers.
The consolidated register of payments from a single account is the basis for the central executive body implementing state policy in the field of treasury services of budget funds to transfer payments to the recipients specified in it.
35 - 1 .5. To form a register of payments from a single account for each individual taxpayer, the central executive body implementing state tax policy is guided by:
tax information contained in the payment instructions submitted by the taxpayer for crediting funds to a single account;
{Paragraph two of clause 35 - 1 .5 of article 35 - 1 as amended by Law No. 2888-IX of 12.01.2023 }
tax information contained in tax declarations (calculations) submitted by the taxpayer, for which the deadline for payment of tax obligations has come in accordance with the provisions of this Code, taking into account the data of the submitted clarifying declarations (calculations);
information contained in the single contribution reports submitted by payers, after which the deadline for payment of obligations has come in accordance with the provisions of the Law of Ukraine "On the Collection and Accounting of the Single Contribution for Compulsory State Social Insurance";
other tax information in accordance with the provisions of this Code.
Payment instructions for crediting funds to a single account are used to make payments provided for in the first paragraph of clause 35 - 1.1 of this article.
{Paragraph six of clause 35 - 1 .5 of article 35 - 1 as amended by Law No. 2888-IX of 12.01.2023 }
Tax declarations (calculations, reports on a single contribution), according to which the deadline for payment of tax obligations (single contribution obligations) has come, are used to pay the relevant payments, if the obligation to make such a payment in accordance with this Code, the Law of Ukraine "On the Collection and Accounting of a Single Contribution for Compulsory State Social Insurance", other acts of legislation, the control over compliance with which is entrusted to regulatory authorities, arises after the taxpayer submits a tax declaration.
35 - 1 .6. The register of payments from a single account for each individual taxpayer is formed daily, except for weekends, holidays and non-working days, by the central executive body implementing state tax policy, within the limits of funds paid to the single account by such taxpayer, and taking into account the amounts of erroneously and/or excessively paid monetary obligations available to such taxpayer in accordance with clause 35 - 1 .8 of this Code, in compliance with the following payment order:
first of all - arrears on the single contribution;
secondly - tax debt within the limits of the relevant tax or fee, arrears on other payments, control over the collection of which is entrusted to the regulatory authorities, in accordance with the order of its occurrence, taking into account the provisions of paragraph 131.2 of Article 131 of this Code;
thirdly - monetary obligations determined on the basis of tax notices-decisions, in the chronological order of receipt of payment instructions for crediting funds to a single account, if such payment instructions contain information about the date and number of the relevant tax notice-decision;
fourthly - monetary obligations determined by the taxpayer (tax agent) for state taxes and fees, local taxes, single contribution in chronological order of receipt of payment instructions for crediting funds to a single account, if such payment instructions contain information about the purpose of the relevant payment and its recipient;
fifthly - monetary obligations from national taxes and fees in the chronological order of receipt of tax declarations (calculations) in the amount of tax obligations for the relevant tax period, taking into account payment deadlines;
sixthly - monetary obligations from local taxes in the chronological order of receipt of tax declarations (calculations) in the amount of tax obligations for the relevant tax period, taking into account payment deadlines;
in the seventh turn - other payments, the control over the collection of which is entrusted to the regulatory authorities, in chronological order of receipt of payment instructions for crediting funds to a single account, if such payment instructions contain information about the purpose of the relevant payment and its recipient.
{Clause 35 - 1 .6 of Article 35 - 1 as amended by Law No. 2888-IX of 12.01.2023 }
35 - 1 .7. When forming the Register of Payments from a Single Account by individual taxpayer in order to determine the recipients of payments from funds received on a single account, the central executive body implementing state tax policy uses:
information about the recipient of the payment specified by the taxpayer in the relevant payment instruction for crediting funds to a single account. If there are several recipients, information about the distribution of funds between them, if specified, is also taken into account;
information about the recipient of the payment specified by the taxpayer in the declaration (calculation, single contribution report) of the relevant payment from funds received into the single account, taking into account the data of the last clarifying declaration (calculation, single contribution report). If there are several recipients, the priority of distribution of funds specified by the taxpayer in such tax declaration (calculation, single contribution report) is taken into account.
In the event of errors or discrepancies in the information specified by the taxpayer in the payment instruction for crediting funds to a single account, as a result of which the central executive body implementing the state tax policy cannot determine the payment's belonging to the relevant recipient, the amount of such payment (part thereof) is not included in the Register of Payments from a Single Account for an individual taxpayer and is considered to be erroneously paid monetary obligations. In this case, on the day the Register of Payments from a Single Account for an individual taxpayer is formed, a notification is sent to the taxpayer's electronic account about the errors or discrepancies found.
{Clause 35 - 1 .7 of Article 35 - 1 as amended by Law No. 2888-IX of 12.01.2023 }
35 - 1 .8. The amounts of monetary obligations (single contribution obligations) and penalties paid by the taxpayer in error and/or in excess, according to the data of the supervisory authority, are considered funds received on the single account and are taken into account by the central executive body implementing the state tax policy when forming the Register of payments from the single account by individual taxpayer on the date of formation of such Register.
The taxpayer has the right to determine through the electronic account the direction of use of the amount of erroneously and/or excessively paid monetary obligations and penalties available on the date of formation of the Register of payments from a single account for an individual taxpayer, which must be taken into account when forming such a Register.
The provisions of this paragraph do not deprive the taxpayer of the right to a refund of erroneously and/or excessively paid monetary obligations and penalties in accordance with the procedure specified in Article 43 of this Code.
35 - 1 .9. The register of payments from a single account by individual taxpayer, which was sent to the central executive body implementing state policy in the field of treasury services of budget funds, as part of the consolidated register of payments from a single account, becomes available for viewing by such taxpayer through an electronic account in the manner provided for in Article 42 - 1 of this Code.
35 - 1 .10. The procedure for the functioning of the single account and the implementation of the norms of this article by the central executive authorities shall be established by the Cabinet of Ministers of Ukraine.
{The Code is supplemented with Article 35 - 1 in accordance with Law No. 190-IX of 04.10.2019 }
36.1. A tax obligation is the obligation of a taxpayer to calculate, declare and/or pay the amount of tax and fee in accordance with the procedure and terms specified by this Code and customs laws.
36.2. A tax liability arises for the payer for each tax and fee.
36.3. The tax obligation is unconditional and takes precedence over other non-tax obligations of the taxpayer, except in cases provided for by law.
36.4. The taxpayer may fulfill the tax obligation independently or with the help of his representative or tax agent.
36.5. Responsibility for failure to fulfill or improper fulfillment of a tax obligation shall be borne by the taxpayer, except for cases specified in this Code or laws on customs matters.
Article 37. Occurrence, change and termination of tax liability↑
37.1. The grounds for the emergence, change and termination of a tax obligation, the procedure and conditions for its fulfillment are established by this Code or laws on customs matters.
37.2. A tax liability arises for a taxpayer from the moment of occurrence of circumstances with which this Code and customs laws link the payment of tax by him.
37.3. The grounds for termination of a tax obligation, in addition to its fulfillment, are:
37.3.1. liquidation of a legal entity;
37.3.2. death of an individual, recognition of him as incapacitated or missing;
37.3.3. loss by a person of the characteristics of a taxpayer defined by this Code;
37.3.4. cancellation of tax liability in the manner prescribed by law.
38.1. The fulfillment of a tax obligation is recognized as the full payment by the payer of the relevant amounts of tax obligations within the period established by tax legislation.
38.2. Payment of taxes and fees shall be made by the taxpayer directly, and in cases provided for by tax legislation, by a tax agent or representative of the taxpayer.
{Clause 38.2 of Article 38 as amended by Law No. 3609-VI of 07.07.2011 }
38.3. The method, procedure and terms of fulfillment of tax obligations are established by this Code and laws on customs matters.
Article 38 - 1. Determination of the minimum tax liability↑
38 - 1 .1. Minimum tax liability (MTL).
38 - 1 .1.1. The minimum tax liability (MTL) for a land plot, the normative monetary valuation of which has been carried out, is calculated according to the formula:
MPZ = NGOd x K x M / 12,
where:
MTL - minimum tax liability;
NGOd - the normative monetary valuation of the relevant land plot taking into account the indexation coefficient determined in accordance with the procedure established by this Code for charging land fees;
K is a coefficient that is 0.05;
M - the number of calendar months during which the land plot is owned, leased, used on other terms (including emphyteusis terms) by the taxpayer.
38 - 1 .1.2. The minimum tax liability (MTL) for a land plot, the normative monetary valuation of which has not been carried out, is calculated according to the formula:
MPZ = NGO x S x K x M / 12,
where:
MTL - minimum tax liability;
NGO - the normative monetary value of 1 hectare of arable land in the Autonomous Republic of Crimea or in the region, taking into account the indexation coefficient determined in accordance with the procedure established by this Code for charging land fees;
S - area of land plot, hectares;
K is a coefficient of 0.05;
M - the number of calendar months during which the land plot is owned, leased, used on other terms (including emphyteusis terms) by the taxpayer.
38 - 1 .1.3. When calculating the minimum tax liability by single tax payers of the fourth group - individuals - entrepreneurs who carry out activities exclusively within the framework of a farm registered in accordance with the Law of Ukraine "On Farming", the coefficient "K" defined in subparagraphs 38 - 1 .1.1 and 38 - 1 .1.2 of this paragraph is applied at half the rate.
38 - 1 .1.4. The minimum tax liability is determined for the period of ownership (use) of the land plot, which falls on the relevant tax (reporting) year.
38 - 1 .2. The minimum tax liability is not determined for:
land plots used by summer cottage (summer cottage construction) and horticultural (gardening) cooperatives (companies), as well as acquired into ownership/use by members of these cooperatives (companies) as a result of privatization (purchase/sale, lease) within the boundaries of lands that belonged to these cooperatives (companies) under the right of collective ownership or were in their permanent use;
reserve lands;
unclaimed land plots (shares), managed by local self-government bodies, except for such land plots (shares) leased by local self-government bodies;
land plots in exclusion zones and unconditional (mandatory) resettlement zones that were subjected to radioactive contamination as a result of the Chernobyl disaster;
land plots classified as agricultural lands that belong to individuals on the right of ownership and/or on the right of use and as of January 1 of the reporting year were located within settlements;
{Paragraph six of clause 38 - 1 .2 of article 38 - 1 as amended by Law No. 4015-IX of 10.10.2024 }
land plots, land shares (shares) for which no land fee or single tax of the fourth group was accrued and paid, which are under conservation, or contaminated with explosive objects, or for which a decision has been made to provide tax benefits for the payment of local taxes and/or fees based on taxpayers' applications to recognize the land plots as unsuitable for use due to the potential threat of their contamination by explosive objects.
{Clause 38 - 1 .2 of Article 38 - 1 is supplemented by the seventh paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
The minimum tax liability for land plots, land shares (shares) provided for in paragraph seven of this paragraph is not determined for the period for which the land fee or the single tax of the fourth group is not determined.
{Clause 38 - 1 .2 of Article 38 - 1 is supplemented by the eighth paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
38 - 1.3 . In the event of transfer of land plots for lease (sublease), emphyteusis or other use, the minimum tax liability shall be determined for tenants, users on other terms of such land plots in the manner prescribed by this Code.
38 - 1 .4. In the event of the transfer of ownership or the right to use, including lease, emphyteusis, sublease, a land plot classified as agricultural land, from one owner, lessee, user on other terms (including on emphyteusis terms) to another owner, lessee, user on other terms (including on emphyteusis terms) during a calendar year and subject to state registration of such right in accordance with the legislation, the minimum tax liability for such land plot is determined for the previous owner, lessee, user on other terms (including on emphyteusis terms) for the period from January 1 of such calendar year to the beginning of the month in which the ownership right to such land plot terminated, or in which such land plot was transferred for use (lease, sublease, emphyteusis), and for the new owner, lessee or user on other terms (including on emphyteusis terms) - starting from the month in which he acquired the right of ownership or the right of use, including lease, emphyteusis, sublease for such land plot, and is taken into account as part of the total minimum tax liability of each of such owners or users.
In the absence of state registration of the transfer of ownership or right of use, including lease, emphyteusis, sublease, to a land plot classified as agricultural land, from one owner, lessee, user on other terms (including on emphyteusis terms) to another owner, lessee, user on other terms (including on emphyteusis terms) during the calendar year, the minimum tax liability for such land plot is determined for the previous owner, lessee, user on other terms (including on emphyteusis terms) on a general basis for the tax (reporting) year.
{The Code is supplemented with Article 38 - 1 in accordance with the Law No. 1914-IX dated 30.11.2021 }
39.1.1. A taxpayer participating in a controlled transaction must determine the amount of its taxable profit in accordance with the arm's length principle (the object of taxation - in cases where the application of the arm's length principle is provided for by this Code or international treaties).
{Subclause 39.1.1 of Clause 39.1 of Article 39 as amended by Law No. 1946-IX of 14.12.2021 }
39.1.2. The amount of taxable profit (taxable object) received by a taxpayer participating in one or more controlled transactions is considered to be in accordance with the "arm's length" principle if the terms of the specified transactions do not differ from the terms applicable between unrelated persons in comparable uncontrolled transactions.
{Subclause 39.1.2 of Clause 39.1 of Article 39 as amended by Law No. 1946-IX of 14.12.2021 }
39.1.3. If the conditions in one or more controlled transactions do not comply with the arm's length principle, the profit that would have accrued to the taxpayer under the conditions of a controlled transaction that complies with the specified principle is included in the taxable profit (object of taxation) of the taxpayer.
{Subclause 39.1.3 of Clause 39.1 of Article 39 as amended by Law No. 1946-IX of 14.12.2021 }
39.1.4. Establishing compliance of the conditions of a controlled transaction with the "arm's length" principle is carried out using the methods specified in paragraph 39.3 of this article, in order to verify the correctness and completeness of the calculation and payment of corporate income tax.
{Subclause 39.1.4 of Clause 39.1 of Article 39 as amended by Law No. 609-VIII of 15.07.2015 }
39.2. Controlled transactions
39.2.1. Principles for determining transactions as controlled:
{Paragraph one of subparagraph 39.2.1 of paragraph 39.2 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 }
39.2.1.1. Controlled transactions are business transactions of a taxpayer that may affect the object of taxation by the taxpayer's corporate income tax (for residents of Diya City - taxpayers under special conditions - on the financial result before tax, determined in the financial statements in accordance with national accounting regulations (standards) or international financial reporting standards), namely:
{Paragraph one of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 as amended by Law No. 1946-IX of 14.12.2021 }
a) business transactions carried out with related parties - non-residents, including in cases specified in subparagraph 39.2.1.5 of this subparagraph;
b) foreign economic transactions for the sale and/or purchase of goods and/or services through non-resident commission agents;
c) business transactions carried out with non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of this subparagraph, or who are residents of these states (territories);
{ Subparagraph "c" of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 as amended by Law No. 3813-IX of 18.06.2024 }
d) business transactions carried out with non-residents, the organizational and legal form of which is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of this subparagraph;
{Sub-clause "d" of sub-clause 39.2.1.1 of sub-clause 39.2.1 of clause 39.2 of Article 39 as amended by Laws No. 2245-VIII of 07.12.2017 , No. 2628-VIII of 23.11.2018 ; as amended by Law No. 3813-IX of 18.06.2024 }
e) business transactions (including intra-business settlements) carried out between a non-resident and its permanent establishment in Ukraine.
{Subclause 39.2.1.1 of subparagraph 39.2.1 of clause 39.2 of Article 39 is supplemented by subparagraph "e" in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 2628-VIII of 23.11.2018 }
{Subclause 39.2.1.1 of subparagraph 39.2.1 of clause 39.2 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 }
39.2.1.2. When determining the list of states (territories) for the purposes of subparagraph "c" of subparagraph 39.2.1.1 of this subparagraph, the Cabinet of Ministers of Ukraine shall take into account the following criteria:
states (territories) included in the list of offshore zones approved by the Cabinet of Ministers of Ukraine;
States (territories) included in the list of states (jurisdictions) that do not comply or improperly comply with the recommendations of international, intergovernmental organizations involved in the fight against the legalization (laundering) of proceeds from crime, or the financing of terrorism or the financing of the proliferation of weapons of mass destruction;
states (territories) whose competent authorities, based on the results of two consecutive reporting (tax) periods (years), do not ensure timely and complete exchange of tax and financial information (in particular, information on the ultimate beneficial owner) upon requests from the central executive body implementing state tax policy.
Proposals for the list of states (territories) that meet the criteria specified in this subparagraph, with appropriate justification, shall be submitted annually by October 1 by the central executive body implementing state tax policy to the central executive body ensuring the formation and implementation of state financial policy.
If changes to the specified list are approved by the Cabinet of Ministers of Ukraine before November 30, such changes shall apply from January 1 of the reporting year following the calendar year in which such changes are made. If changes to the specified list are approved after November 30, such changes shall apply from January 1 of the second reporting year following the calendar year in which such changes are made.
{Subclause 39.2.1.2 of subparagraph 39.2.1 of clause 39.2 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 , No. 2245-VIII of 12/07/2017 , No. 3813-IX of 06/18/2024 }
39.2.1.2 - 1. The list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine includes organizational and legal forms of non-residents that do not pay income tax (corporate tax), including on income received outside the state (territory) of registration of such non-residents, and/or are not tax residents of the state (territory) in which they are registered as legal entities.
Business transactions of a taxpayer with a non-resident, whose organizational and legal form is included by the Cabinet of Ministers of Ukraine in the list of organizational and legal forms of non-residents, in the absence of the criteria specified in subparagraphs "a" - "c" , "g" of subparagraph 39.2.1.1 of this subparagraph, are recognized as uncontrolled if at least one of the following conditions is present:
a non-resident is a resident of a state (territory) with which Ukraine has concluded an international agreement on the avoidance of double taxation, which is confirmed by submitting to the central executive body implementing state tax policy, by October 1 of the year following the reporting year, a certificate in paper or electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" , which confirms that the non-resident is a resident of a country with which Ukraine has concluded a relevant international agreement (except for a state (territory) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of this subparagraph), in accordance with paragraph 103.5 of Article 103 of this Code;
all participants (partners) of the non-resident are residents of states (territories) with which Ukraine has concluded international agreements on the avoidance of double taxation, which is confirmed by submitting to the central executive body implementing state tax policy, by October 1 of the year following the reporting year, a certificate in paper or electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" , which confirms that all participants (partners) of the non-resident are residents of the country with which Ukraine has concluded an international agreement (except for states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of this subparagraph), in accordance with subparagraph 103.5 of Article 103 of this Code.
In the event of changes to the list of organizational and legal forms, such changes shall apply from January 1 of the reporting year following the calendar year in which such changes were made.
{Sub -clause 39.2.1 of clause 39.2 of Article 39 is supplemented by sub-clause 39.2.1.2 - 1 in accordance with Law No. 3813-IX of 18.06.2024 }
{Subclause 39.2.1.3 of subparagraph 39.2.1 of clause 39.2 of Article 39 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
39.2.1.4. A business transaction for transfer pricing purposes is all types of transactions, contracts or arrangements, documented or unconfirmed, that may affect the object of taxation by the corporate income tax of the taxpayer (for residents of Diya City - taxpayers under special conditions - on the financial result before tax, determined in the financial statements in accordance with national accounting regulations (standards) or international financial reporting standards), in particular, but not exclusively:
{Paragraph one of subparagraph 39.2.1.4 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 as amended by Law No. 1946-IX of 14.12.2021 }
a) transactions with goods, such as raw materials, finished products, etc.;
b) transactions for the purchase (sale) of services;
c) transactions with intangible assets, such as royalties, licenses, fees for the use of patents, trademarks, know-how, etc., as well as with any other intellectual property objects;
d) financial transactions, including leasing, participation in investments, loans, guarantee fees, etc.;
e) transactions for the purchase or sale of corporate rights, shares or other investments, purchase or sale of long-term tangible and intangible assets;
e) transactions (including intra-company settlements) carried out between a non-resident and its permanent establishment in Ukraine;
e) transactions as a result of which the amount of income and/or financial result of the taxpayer decreases due to the full or partial, irrevocable or temporary transfer of functions together with tangible and/or intangible assets (or without them), benefits, risks and opportunities to another taxpayer (another person) in cases where in relations between unrelated persons such transfer would not be carried out without compensation, regardless of whether such transactions are reflected in accounting;
{Subclause 39.2.1.4 of subparagraph 39.2.1 of clause 39.2 of Article 39 is supplemented by subparagraph "e" in accordance with Law No. 466-IX of 16.01.2020 }
{Subclause 39.2.1.4 of subparagraph 39.2.1 of clause 39.2 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 , No. 2245-VIII of 12/07/2017 ; as amended by Law No. 2628-VIII of 11/23/2018 }
39.2.1.5. If in the chain of business transactions between a taxpayer and a non-resident, provided for in subparagraph 39.2.1.1 of this paragraph, the ownership of the object (result) of such a transaction, before passing from the taxpayer to such non-resident (in the case of export transactions) or before passing from such non-resident to the taxpayer (in the case of import transactions), is transferred to one or more persons and the transaction between the relevant resident and none of such persons was recognized by the taxpayer as a controlled transaction, such transaction shall be considered a controlled transaction between the taxpayer and such non-resident, if the persons to whom the ownership was transferred:
do not perform in such a set of operations essential functions related to the purchase (sale) of goods (works, services);
do not use significant assets in such a set of operations and/or do not assume significant risks to organize the purchase (sale) of goods (works, services).
For the purposes of this subparagraph:
essential functions are understood as functions that the taxpayer and the non-resident parties to the controlled transaction could not perform independently in their ordinary activities without involving other persons and using the assets of such persons;
significant assets are assets whose use is necessary during the implementation of such transactions and which are not available to the taxpayer and non-resident - parties to the controlled transaction;
significant risks are understood as risks the acceptance of which is mandatory for the business practice of such operations;
{Subclause 39.2.1.5 of subparagraph 39.2.1 of clause 39.2 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 ; as amended by Laws No. 2245-VIII of 12/07/2017 , No. 2628-VIII of 11/23/2018 }
39.2.1.6. Uncontrolled transactions - any business transactions not provided for in subparagraphs 39.2.1.1 and 39.2.1.5 of subparagraph 39.2.1 of this clause, carried out between unrelated persons.
{Subclause 39.2.1.6 of subparagraph 39.2.1 of clause 39.2 of Article 39 as amended by Law No. 609-VIII of 07/15/2015 ; as amended by Law No. 1797-VIII of 12/21/2016 }
39.2.1.7. Business transactions provided for in subparagraphs 39.2.1.1 (except for transactions carried out between a non-resident and its permanent establishment in Ukraine) and 39.2.1.5 of this subparagraph are recognized as controlled if the following conditions are simultaneously met:
the annual income of the taxpayer from any activity, determined according to accounting rules, exceeds 150 million hryvnias (net of indirect taxes) for the relevant tax (reporting) year;
the volume of such business transactions of the taxpayer with each counterparty, determined according to accounting rules, exceeds 10 million hryvnias (net of indirect taxes) for the relevant tax (reporting) year.
Business transactions carried out between a non-resident and its permanent establishment in Ukraine are recognized as controlled if the volume of such business transactions, determined according to accounting rules, exceeds 10 million hryvnias (net of indirect taxes) for the relevant tax (reporting) year.
{Subclause 39.2.1.7 of subparagraph 39.2.1 of clause 39.1 of Article 39 as amended by Law No. 609-VIII of 07.15.2015 ; as amended by Law No. 1797-VIII of 12.21.2016 ; as amended by Law No. 2245-VIII of 12.07.2017 }
39.2.1.8. Conditions under which business transactions are recognized as complying with the "arm's length" principle:
if prices (mark-ups) for goods (works, services) are subject to state regulation in accordance with the law, the price shall be deemed to comply with the "arm's length" principle if it is established in accordance with the rules of such regulation. This provision shall not apply to cases where a minimum (maximum) sale price (mark-up) or indicative price is established. In such a case, the price of a transaction that complies with the "arm's length" principle shall be determined in accordance with this Article, but may not be less than the minimum price (mark-up) or indicative price and greater than the maximum price (mark-up);
{Paragraph two of subparagraph 39.2.1.8 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
if an appraisal is required during the transaction, the value of the appraisal object is the basis for establishing compliance with the arm's length principle for taxation purposes;
in the event of an auction (public bidding), the mandatory nature of which is determined by law, the conditions resulting from such an auction (public bidding) shall be deemed to comply with the arm's length principle;
If the sale (alienation) of goods, including property pledged by the borrower to secure the creditor's claims, is carried out in a compulsory manner in accordance with the law, the conditions formed during such sale are recognized as complying with the "arm's length" principle.
{Subclause 39.2.1 of clause 39.2 of Article 39 is supplemented by subparagraph 39.2.1.8 in accordance with Law No. 609-VIII of 15.07.2015 }
39.2.1.9. The volume of a taxpayer's business transactions for the purposes of subparagraph 39.2.1.7 of this subparagraph shall be calculated at prices that comply with the "arm's length" principle.
{Subclause 39.2.1 of clause 39.2 of Article 39 is supplemented by subparagraph 39.2.1.9 in accordance with Law No. 2245-VIII of 07.12.2017 }
39.2.2. Comparison of commercial and financial terms of transactions
39.2.2.1. For the purposes of this Code, controlled transactions are considered comparable to uncontrolled transactions if:
there are no significant differences between them that could significantly affect the financial result when applying the appropriate transfer pricing method;
such differences can be eliminated by adjusting the terms and financial results of the controlled or uncontrolled transaction to avoid the impact of such differences on comparability.
{Paragraph three of subparagraph 39.2.2.1 of subparagraph 39.2.2 of paragraph 39.2 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.2.2.2. When determining the comparability of operations, the following elements of the controlled and comparable operations are analyzed:
characteristics of the goods (works, services) that are the subject of the transaction;
functions performed by the parties to the transaction, assets used by them, terms of distribution of risks and benefits between the parties to the transaction, distribution of responsibilities between the parties to the transaction and other terms of the transaction (hereinafter referred to as functional analysis);
established practice of relations and terms of contracts concluded between the parties to the transaction, which significantly affect the prices of goods (works, services);
economic conditions of the parties to the transaction, including an analysis of the relevant markets for goods (works, services), which significantly affect the prices of goods (works, services);
business strategies of the parties to the transaction (if any), which significantly affect the prices of goods (works, services).
In the absence or insufficiency of information on individual uncontrolled transactions, financial information of legal entities that carry out activities comparable to the controlled transaction may be used to determine profitability indicators, provided that there is information that these legal entities do not carry out transactions with related parties.
{Subclause 39.2.2.2 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph seven in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
The determination of the comparability of legal entities is carried out taking into account their industry specifics and the relevant types of activities carried out by them in economic (commercial) conditions comparable to the controlled transaction.
{Subclause 39.2.2.2 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph eight in accordance with Law No. 1797-VIII of 21.12.2016 }
39.2.2.3. The determination of the comparability of commercial and/or financial terms of transactions with the terms of the controlled transaction may be carried out, in particular, but not exclusively, based on the results of the analysis of:
quantity of goods, volume of work performed (services provided);
deadlines for fulfilling economic obligations;
payment terms during the transaction;
the official exchange rate of the hryvnia to a foreign currency established by the National Bank of Ukraine, in the event that such currency is used in calculations during the transaction, changes in such exchange rate;
the amount of usual surcharges or discounts to the price of goods (works, services), in particular discounts caused by seasonal and other fluctuations in consumer demand for goods (works, services), loss of consumer qualities of goods, expiration (approaching expiration date) of the storage (expiration, sale) period, sale of illiquid or low-liquid goods;
distribution of rights and obligations between the parties to the transaction, determined based on the results of the functional analysis.
39.2.2.4. Analysis of the functions performed by the parties to the transaction when determining the comparability of the commercial and/or financial terms of the transactions with the terms of controlled and uncontrolled transactions may be carried out taking into account the tangible and intangible assets held by the parties to the transaction and used for the purpose of generating income.
Such functions include, but are not limited to:
product design and technological development;
production of goods;
assembly of goods or their components;
assembly and/or installation of equipment;
conducting scientific research and development work;
acquisition of goods and materials;
wholesale or retail sales;
provision of repair and warranty services;
marketing, advertising of goods (works, services);
storage of goods;
transportation of goods;
insurance;
providing consultations, information services;
accounting;
legal services;
provision of personnel;
provision of agency, trust, commission and other similar intermediary services for the sale of goods (works, services);
quality control;
education and/or professional training, retraining or advanced training of personnel;
organization of sales of goods (works, services) with the involvement of third parties who have experience in relevant work;
implementation of strategic management, including determining pricing policy, strategy for production and sale of goods (works, services), sales volumes and assortment of goods (works, services), their consumer qualities, as well as implementation of operational management.
The definition and analysis of the functions performed by the parties to the transaction are carried out on the basis of concluded contracts, accounting data, actual actions of the parties to the transaction and the actual circumstances of its conduct in accordance with the essence of the transaction.
{Subclause 39.2.2.4 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph twenty-four in accordance with Law No. 2628-VIII of 23.11.2018 }
39.2.2.5. When determining the comparability of the commercial and/or financial terms of comparable transactions with the terms of the controlled transaction, the risks of the parties to the transaction associated with conducting business activities that affect the terms of the transaction may also be taken into account, including, but not limited to, the following:
production risks, including the risk of underutilization of production facilities;
the risk of changes in market prices for purchased materials and manufactured products due to changes in the economic situation and other market conditions;
risk of depreciation of production inventories, loss of consumer qualities of goods;
risks associated with the loss of property or property rights;
risks associated with changes in the official exchange rate of the hryvnia to foreign currency set by the National Bank of Ukraine, interest rates, credit risks;
risk associated with the lack of results from research and development work;
investment risks associated with possible financial losses due to errors made during investment, including the choice of investment object;
risk of harm to the environment;
{Paragraph ten of subparagraph 39.2.2.5 of subparagraph 39.2.2 of paragraph 39.2 of Article 39 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
risk of a decrease in consumer demand for goods (works, services);
The analysis of the risks assumed by the parties to a controlled transaction when determining the comparability of the commercial and/or financial terms of the transaction with the terms of uncontrolled transactions is carried out taking into account the following criteria:
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph twelfth in accordance with Law No. 466-IX of 16.01.2020 }
a) identification and characterization of significant economic risks assumed by the parties to the transaction on the basis of concluded contracts;
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph thirteen in accordance with Law No. 466-IX of 16.01.2020 }
b) whether the party taking the risk exercises control over the creation and management of the risk, and has the ability and authority to do so;
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph fourteen in accordance with Law No. 466-IX of 16.01.2020 }
c) whether the person taking the risk has the financial capacity to bear such risk and the resources necessary to cover such risk;
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph fifteen in accordance with Law No. 466-IX of 16.01.2020 }
d) determining the actual behavior of the parties to the transaction in connection with exercising control over significant economic risks, in particular, determining which party to the transaction exercises control or takes measures to minimize such risks, which party receives the negative consequences caused by accepting such risks, which party has the financial capacity to bear such risks;
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph sixteen in accordance with Law No. 466-IX of 16.01.2020 }
e) determining, taking into account the previous criteria, whether the actual behavior of the parties to the transaction complies with the risk-taking conditions stipulated by the contracts, in particular:
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph seventeen in accordance with Law No. 466-IX of 16.01.2020 }
whether the parties to the transaction fulfill the terms of the contracts;
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph eighteen in accordance with Law No. 466-IX of 16.01.2020 }
whether the party taking the risk exercises control over the risk and has the financial capacity to bear such risk and/or the capabilities and resources to cover it";
{Subclause 39.2.2.5 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by paragraph nineteen in accordance with Law No. 466-IX of 16.01.2020 }
39.2.2.6. When determining the comparability of the characteristics of goods (works, services) markets, the following factors may be taken into account, in particular, but not exclusively:
geographical location of markets and their volumes;
the presence of competition in the markets, the relative competitiveness of sellers and buyers in the market;
the presence of homogeneous (similar) goods (works, services) on the market;
market demand and supply, as well as consumer purchasing power;
the level of state regulation of market processes;
the level of development of production and transport infrastructure;
other market characteristics that affect the prices of goods (works, services).
39.2.2.7. When determining the comparability of commercial and/or financial terms of comparable transactions with the terms of the controlled transaction, an analysis of the commercial strategies of the parties to the transactions may be conducted, which, in particular, but not exclusively, include strategies aimed at updating and improving their own products, entering new markets for the sale of goods (works, services).
{Subclause 39.2.2.8 of subparagraph 39.2.2 of clause 39.2 of Article 39 was excluded on the basis of Law No. 609-VIII of 15.07.2015 }
39.2.2.9. When determining the comparability of the commercial and/or financial terms of comparable transactions with the terms of the controlled transaction, the characteristics of the assets used by the parties in the controlled transaction may also be taken into account, including, but not limited to:
type of asset (production equipment, intangible assets, financial assets, etc.);
the nature of the asset (age, market value, location, availability of protection rights, etc.).
The determination and analysis of the impact of intangible assets on the conditions of controlled and comparable transactions are carried out taking into account, in particular, but not exclusively:
legal ownership of intangible assets and contractual terms of their use;
categories and characteristics of intangible assets (exclusivity, degree and duration of legal protection, geographical scope, useful life, stage of development, etc.);
contractual and actual activities of the parties related to the development, improvement, maintenance, protection and operation of such assets.
{Subclause 39.2.2 of clause 39.2 of Article 39 is supplemented by subparagraph 39.2.2.9 in accordance with Law No. 2628-VIII of 23.11.2018 }
39.2.2.10. If the actual terms of the controlled transaction do not correspond to the terms of the concluded (written) contract and/or the actual actions of the parties to the controlled transaction and the actual circumstances of its conduct differ from the terms of such contract, the commercial and/or financial characteristics of the controlled transaction for transfer pricing purposes are determined in accordance with the actual actions of the parties to the transaction and the actual conditions of its conduct.
{Subclause 39.2.2 of clause 39.2 of Article 39 is supplemented by subparagraph 39.2.2.10 in accordance with Law No. 2628-VIII of 23.11.2018 }
39.2.2.11. If a controlled transaction is actually carried out, but not documented (not confirmed), for transfer pricing purposes it should be considered in accordance with the actual behavior of the parties to the transaction and the actual conditions of its conduct, in particular, the functions actually performed by the parties to the transaction, the assets actually used, and the risks actually assumed and controlled by each party are taken into account.
If the parties to a controlled transaction do not provide sufficient justification for the actual behavior of the parties to the transaction and the actual conditions of its conduct, the functions, risks, and assets are distributed in favor of the party to the controlled transaction that is a resident of Ukraine.
{Subclause 39.2.2.11 of subparagraph 39.2.2 of clause 39.2 of Article 39 is supplemented by the second paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
{Subclause 39.2.2 of clause 39.2 of Article 39 is supplemented by subparagraph 39.2.2.11 in accordance with Law No. 2628-VIII of 23.11.2018 }
39.2.2.12. If the commercial and/or financial characteristics of a controlled transaction for transfer pricing purposes, determined in accordance with the actual actions of the parties to the transaction and the actual conditions of its conduct, differ from the conditions applicable between unrelated persons, taking into account the presence of a reasonable economic reason (business purpose) in comparable circumstances, and it is established that unrelated persons acting in comparable conditions and behaving commercially rationally, taking into account the alternative options actually available to each of the parties to the transaction, would not enter into such a controlled transaction, the supervisory authority has the right, when calculating the financial result of the taxpayer before taxation, not to take into account (not to recognize) such a controlled transaction or the transaction may be replaced by an alternative option in order to determine the terms of the agreement (contract) that would have been agreed upon by unrelated persons acting commercially rationally in comparable conditions.
When determining the alternatives to the transaction that are realistically available to each party to the transaction, it is necessary to consider whether there were other realistic alternatives available to either party that would have resulted in a more beneficial economic effect if such party had entered into an agreement with unrelated parties instead of entering into an agreement with related parties.
If the financial result before taxation of the taxpayer increases due to non-recognition (non-recognition) of a controlled transaction in accordance with the requirements of paragraph one of this subparagraph, other adjustments provided for in Article 39 of this Code shall not be applied, and in the event of replacing the transaction with an alternative option, the compliance of the conditions of such an alternative transaction with the arm's length principle shall be determined taking into account the requirements of paragraph 39.3 of Article 39 of this Code.
The burden of proving the circumstances provided for in this subparagraph shall rest with the supervisory authority.
{Subclause 39.2.2 of clause 39.2 of Article 39 is supplemented by subparagraph 39.2.2.12 in accordance with Law No. 1117-IX of 17.12.2020 }
39.3. Methods for establishing compliance of the conditions of a controlled transaction with the arm's length principle
39.3.1. Establishing compliance of the conditions of a controlled transaction with the "arm's length" principle is carried out using one of the following methods:
39.3.1.1. comparative uncontrolled price;
39.3.1.2. resale prices;
39.3.1.3. "expenses plus";
39.3.1.4. net profit;
39.3.1.5. profit distribution.
39.3.2. Criteria for using methods to establish compliance of the conditions of a controlled transaction with the arm's length principle
39.3.2.1. Compliance of the terms of a controlled transaction with the arm's length principle is determined by applying the transfer pricing method that is most appropriate to the facts and circumstances of the controlled transaction, except in cases where this Code specifies requirements for the mandatory application of a specific method for establishing compliance of the terms of controlled transactions with the arm's length principle for controlled transactions of a certain type.
The most appropriate transfer pricing method is selected taking into account the following criteria:
the appropriateness of the selected method in accordance with the nature of the controlled transaction, which is determined, in particular, based on the results of the functional analysis of the controlled transaction (taking into account the functions performed, assets used and risks incurred);
availability of complete and reliable information necessary for the application of the selected transfer pricing method and/or methods;
the degree of comparability between controlled and uncontrolled transactions, including the reliability of comparability adjustments, if any, that may be used to eliminate discrepancies between such transactions.
Taking into account the specified criteria, the taxpayer uses any method that he considers most appropriate, however, if there is a possibility of using both the comparative uncontrolled price method and any other method, the comparative uncontrolled price method is applied.
If, taking into account such criteria, the resale price method or the "cost plus" method and the net profit or profit allocation method can be applied by the taxpayer with equal reliability, the resale price method or the "cost plus" method shall be applied.
A taxpayer may not apply more than one method to determine whether the terms of a controlled transaction meet the arm's length principle.
If the taxpayer has used a method that complies with the provisions of this Article, the establishment by the supervisory authority of the compliance of the conditions of the taxpayer's controlled transactions with the arm's length principle shall be based on the transfer pricing method used by the taxpayer, except in cases where the supervisory authority substantiates that the method used by the taxpayer is not the most appropriate.
The controlling authority shall not have the right to apply, when establishing the compliance of the conditions of the controlled transactions of the taxpayer with the arm's length principle, a transfer pricing method other than that specified in the agreement on preliminary pricing agreement.
{Subclause 39.3.2.1 of subparagraph 39.3.2 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Laws No. 466-IX of 01/16/2020 , No. 1117-IX of 12/17/2020 }
39.3.2.2. If, when applying transfer pricing methods, the price or profitability in a controlled transaction is compared with the prices or profitability indicators of several comparable uncontrolled transactions or legal entities that do not carry out transactions with related parties, a price (profitability) range must be used.
{Subclause 39.3.2.2 of subparagraph 39.3.2 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.2.3. If the price in a controlled transaction or the corresponding profitability indicator of a controlled transaction is:
within the range, the conditions of the controlled transaction are considered to be at arm's length;
{Paragraph two of subparagraph 39.3.2.3 of subparagraph 39.3.2 of paragraph 39.3 of Article 39 as amended by Law No. 609-VIII of 15.07.2015 }
outside the price (profitability) range, the calculation of the taxpayer's tax liabilities in the controlled transaction is carried out in accordance with the price (profitability indicator) that is equal to the median value of such range (except for cases where taxpayers make independent adjustments in accordance with subparagraph 39.5.4 of paragraph 39.5 of this article).
{Subclause 39.3.2.3 of subparagraph 39.3.2 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
The procedure for calculating the price range (profitability) and the median of the price range (profitability) is approved by the Cabinet of Ministers of Ukraine.
The application of the median of the price range (profitability) for taxation purposes is carried out provided that this does not lead to a reduction in the amount of tax payable to the budget.
39.3.2.4. The choice of profitability indicator may be made taking into account, in particular, but not exclusively, the following factors:
type of activity of the party to the controlled transaction;
distribution of functions, risks, and assets of the parties;
economic feasibility of the selected indicator;
independence of the indicator from income and/or expenses recognized in transactions between related parties and/or in controlled transactions.
{Paragraph five of subparagraph 39.3.2.4 of subparagraph 39.3.2 of paragraph 39.3 of Article 39 as amended by Law No. 2628-VIII of 23.11.2018 }
39.3.2.5. When determining the level of profitability of controlled transactions, financial indicators may be used that ensure compliance of the terms of the controlled transaction with the arm's length principle, in particular, but not exclusively:
a) gross profitability, defined as the ratio of gross profit to net income (revenue) from the sale of goods (works, services), calculated without taking into account excise tax, customs duty, value added tax, other taxes and fees;
b) gross profit margin, which is defined as the ratio of gross profit to the cost of goods sold (works, services);
c) net profitability, defined as the ratio of operating profit to net income (revenue) from the sale of goods (works, services), calculated without taking into account excise tax, customs duty, value added tax, other taxes and fees;
d) net cost profitability, which is defined as the ratio of profit from operating activities to the sum of the cost of goods (works, services) sold and operating expenses (administrative expenses, sales expenses, and others) related to the sale of goods (works, services);
e) profitability of operating expenses, which is defined as the ratio of gross profit to operating expenses (administrative expenses, sales expenses, and others) related to the sale of goods (works, services);
e) return on assets, which is defined as the ratio of operating income to the current market value of non-current and current assets (except for current financial investments and cash and cash equivalents) that are directly or indirectly used in the controlled transaction. In the absence of the necessary information on the current market value of assets, return on assets may be determined based on accounting data;
e) return on capital, defined as the ratio of operating profit to capital (the sum of non-current and current assets, excluding current financial investments and cash and cash equivalents, excluding current liabilities).
{Subclause 39.3.2.5 of subparagraph 39.3.2 of clause 39.3 of Article 39 as amended by Law No. 609-VIII of 15.07.2015 }
39.3.2.6. Profitability indicators for the purposes of this article are determined on the basis of accounting and financial reporting data reflected in accordance with national accounting regulations (standards) or international standards in accordance with accounting and financial reporting standards used in Ukraine, with appropriate adjustments to ensure comparability of indicators.
{Subclause 39.3.2.6 of subparagraph 39.3.2 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.2.7. In the case of applying the methods specified in subparagraphs 39.3.1.2-39.3.1.4 of subparagraph 39.3.1 of paragraph 39.3 of this article, the party for which the indicator is checked in accordance with the selected transfer pricing method (hereinafter referred to as the party under investigation) shall be selected.
The selection of the party under investigation should be made in accordance with the functions performed by each party to the controlled transaction, the assets used during the implementation of the controlled transactions, and the accepted economic (commercial) risks associated with the implementation of such a transaction.
When selecting the party under investigation, the applicability of the selected method (combination of methods) to each party of the controlled transaction is analyzed. The party under investigation is selected as the party:
for which the application of such a method (combination of methods) is most justified;
for which the most comparable transactions and/or comparable persons can be found;
for which there is the most complete and documented information on the financial indicators of the controlled transaction, which are used to calculate the profitability indicators provided for in subparagraph 39.3.2.5 of this subparagraph;
{Subclause 39.3.2.7 of subparagraph 39.3.2 of clause 39.2 of Article 39 is supplemented with a new paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
which:
performs the least complex functions in relation to the controlled operation;
accepts the lowest economic (commercial) risks in relation to the controlled transaction;
does not own intangible assets that have a significant impact on the level of profitability.
In the case of foreign economic transactions, the party for which the indicator is checked in accordance with the selected transfer pricing method does not necessarily have to be a resident.
{Subclause 39.3.2.7 of subparagraph 39.3.2 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.2.8. When determining the profitability range, the following is used:
information on comparable uncontrolled transactions in accordance with subparagraph "a" of subparagraph 39.5.3.1 of subparagraph 39.5.3 of paragraph 39.5 of this article, carried out during the reporting (tax) period (year) in which the controlled transaction was carried out; or
information on comparable legal entities based on accounting and financial reporting data reflected in accordance with national accounting regulations (standards) or international financial reporting standards, in accordance with subparagraph "b" of subparagraph 39.5.3.1 of subparagraph 39.5.3 of paragraph 39.5 of this article for the reporting (tax) period (year) in which the controlled transaction was carried out, or for several tax periods (years).
When using multiple tax periods (years), a weighted average value of the profitability indicator for the comparable entity is calculated.
The procedure for determining the weighted average value of the profitability indicator is determined by the Cabinet of Ministers of Ukraine.
{Subclause 39.3.2 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.2.8 in accordance with Law No. 1797-VIII of 21.12.2016 }
39.3.2.9. Information on comparable legal entities for calculating the financial indicators specified in subparagraph 39.3.2.5 of this subparagraph is used if the following conditions are simultaneously met:
{Paragraph one of subparagraph 39.3.2.9 subparagraph 39.3.2 of paragraph 39.3 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
1) if the comparable legal entity carries out activities comparable to the activities of the party to the controlled transaction under investigation and performs comparable functions related to such activities. The comparison of activities is determined, in particular, but not exclusively, taking into account the types of economic activities in accordance with KVED DK 009:2010 , as well as international classifiers;
{Paragraph two of subparagraph 39.3.2.9, subparagraph 39.3.2, paragraph 39.3 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
2) if the comparable legal entity does not have losses according to accounting (financial) reporting data in more than one reporting period in the periods used to calculate the relevant financial indicators;
3) if the comparable legal entity does not directly and/or indirectly own the corporate rights of another legal entity with a share of such participation of 25 percent or more and/or does not have as a participant (shareholder) a legal entity with a share of direct (indirect) participation of 25 percent or more.
{Paragraph four of subparagraph 39.3.2.9 subparagraph 39.3.2 of paragraph 39.3 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
{Subclause 39.3.2 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.2.9 in accordance with Law No. 1797-VIII of 21.12.2016 }
39.3.3. Comparative uncontrolled price method
39.3.3.1. The comparative uncontrolled price method consists in comparing the price applied in a controlled transaction with the price in the comparable uncontrolled transaction(s) actually carried out by the taxpayer (other persons) or on the basis of information obtained from sources specified in subparagraph 39.5.3 of paragraph 39.5 of this Article.
{Subclause 39.3.3.1 of subparagraph 39.3.3 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.3.3.2 of subparagraph 39.3.3 of clause 39.3 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
39.3.3.3. Comparison of the price of a controlled transaction with the price of comparable uncontrolled transactions is made on the basis of information on prices applied during the period being analyzed, in particular information on prices on the date closest to the date of the controlled transaction.
In the event of a controlled transaction based on a forward or futures contract, the price comparison is carried out on the basis of information on forward or futures prices on the date closest to the date of conclusion of the relevant forward or futures contract (provided that the taxpayer notifies the central executive body implementing tax policy about the conclusion of such a contract by electronic means in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" within 10 business days from the date of conclusion of the relevant forward or futures contract).
The form of such a notification and the procedure for its submission are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Subclause 39.3.3.3 Subclause 39.3.3 of clause 39.3 of Article 39 is supplemented by the third paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
{Subclause 39.3.3.3 of subparagraph 39.3.3 of clause 39.3 of Article 39 as amended by Law No. 609-VIII of 07/15/2015 ; as amended by Law No. 1797-VIII of 12/21/2016 }
39.3.3.4. For controlled transactions with raw materials, the determination of compliance of the conditions of controlled transactions with the "arm's length" principle is carried out using the comparative uncontrolled price method.
For the purposes of this subparagraph, raw materials are understood to mean goods for which unrelated persons use quoted prices as a reference (standard) for setting the price of uncontrolled transactions. The list of raw materials is determined by the Cabinet of Ministers of Ukraine.
When applying the comparative uncontrolled price method for controlled transactions with raw materials, the price of the controlled transaction may be compared with the price of comparable uncontrolled transactions actually carried out by the taxpayer or other persons with unrelated persons, and/or with quoted prices.
In the case of using the price of uncontrolled transactions as a comparator for a controlled transaction, such uncontrolled transactions must be regular, with multiple counterparties and in volumes comparable to those used in the controlled transaction.
Quoted prices used for comparison with prices of controlled transactions shall comply with the comparability conditions specified in subparagraph 39.2.2 of paragraph 39.2 of this Article. In the event of significant differences between the terms of a controlled transaction and the terms of uncontrolled transactions or the terms determining the quoted price of raw materials, which significantly affect the price of transactions with raw materials, appropriate adjustments shall be made.
The central executive body implementing state tax policy publishes a recommended (non-exclusive) list of information sources for obtaining quoted prices on its official web portal before the beginning of the reporting year.
The central executive body that ensures the formation and implementation of state financial policy may determine, in accordance with the requirements and methods provided for in Article 39 of this Code, separate procedures for establishing compliance of the conditions of a controlled transaction with raw materials with the arm's length principle. Such procedures and amendments thereto must be approved by July 1 of the current year and shall enter into force no earlier than January 1 of the year following the year of their approval. In the event of approval of such procedures, the establishment of compliance of the conditions of controlled transactions with the arm's length principle for controlled transactions with raw materials shall be carried out by taxpayers and control bodies, taking into account the requirements of the relevant procedure.
{Subclause 39.3.3 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.3.4 in accordance with Law No. 466-IX of 16.01.2020 }
39.3.3.5. A taxpayer carrying out controlled transactions with raw materials shall notify the central executive body implementing state tax policy of the conclusion of the relevant agreement (contract) in the form and in the manner provided for in subparagraph 39.3.3.3 of subparagraph 39.3.3 of this paragraph.
Sending such a notification by the payer is confirmation that the essential terms of the agreement (contract), in particular the characteristics and price of the goods, volume, terms of delivery, payment and liability, were agreed upon by the parties to the controlled transaction at the time of concluding such an agreement.
If the information specified in the notification is consistent with the actual behavior of the parties or with other facts of the controlled transaction, the comparison of the price of the controlled transaction with quoted prices is made on the date closest to the pricing date agreed upon by the parties to the controlled transaction.
{Subclause 39.3.3 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.3.5 in accordance with Law No. 466-IX of 16.01.2020 }
39.3.3.6. If the taxpayer fails to send a notification in accordance with subparagraph 39.3.3.5 of subparagraph 39.3.3 of this subparagraph or
the information specified in the message does not comply with the contractual terms, or
the parties to the transaction, after sending the notification, will make changes to the terms of the agreement (contract) regarding the characteristics, price, total cost, quantity and volume of goods, terms of delivery and payment, liability of the parties, or
the terms of such an agreement (contract) are inconsistent with the actual behavior of the parties to the transaction and the actual conditions of its implementation,
The regulatory authority compares the price of the controlled transaction with the quoted prices on the date of transfer of ownership of the subject of the controlled transaction or the date of shipment of the goods according to the cargo transport document (bill of lading or other document depending on the means of transport) in accordance with the conditions and actual circumstances of such controlled transaction.
{Subclause 39.3.3 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.3.6 in accordance with Law No. 466-IX of 16.01.2020 }
39.3.3.7. If a range of quoted prices specified in the information source was used to compare the price of a controlled transaction with raw materials, the minimum and maximum values of such a range shall correspond to the minimum and maximum values of the price range for the purposes of subparagraph 39.3.2.3 of subparagraph 39.3.2 of paragraph 39.3 and subparagraph 39.5.4 of paragraph 39.5 of this Article.
In the case of using several ranges of quoted prices, the price range shall be calculated in accordance with the procedure provided for in the fourth paragraph of subparagraph 39.3.2.3 of subparagraph 39.3.2 of this clause.
{Subclause 39.3.3 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.3.7 in accordance with Law No. 466-IX of 16.01.2020 }
39.3.3.8. In the event that a taxpayer applies the methods specified in subparagraphs 39.3.1.2-39.3.1.5 of subparagraph 39.3.1 of this paragraph to establish compliance with the conditions of controlled transactions with raw materials, the taxpayer must:
justify the impossibility of applying the comparative uncontrolled price method or the fact that the comparative uncontrolled price method is not the most appropriate in relation to the facts and circumstances of the controlled transaction;
indicate information about all persons who participated in the supply chain of such goods from the manufacturer (supplier) to the first unrelated person or non-resident person who does not meet the criteria specified in subparagraphs "c" - "d" of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of this article. The information must contain data on the level of profitability indicators of these persons, which are most appropriate, based on the facts and circumstances of their activities in the supply chain.
If the taxpayer fails to provide such information, the controlling authority has the right to independently determine the price level of the controlled transaction that corresponds to the "arm's length" principle, using the comparative uncontrolled price method, taking into account the requirements of subparagraph 39.3.3.4 of subparagraph 39.3.3 of this paragraph.
{Subclause 39.3.3 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.3.8 in accordance with Law No. 466-IX of 16.01.2020 }
39.3.4. Resale price method
39.3.4.1. The resale price method consists of comparing the gross profit from the resale of goods (works, services) purchased in a controlled transaction with the gross profit from the resale of goods (works, services) obtained in comparable uncontrolled transactions.
{Subclause 39.3.4.1 of subparagraph 39.3.4 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.4.2. The resale price method may be used, in particular, but not exclusively, if the following transactions are carried out during the resale of the goods:
{Paragraph one of subparagraph 39.3.4.2 of subparagraph 39.3.4 of paragraph 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
preparation of goods for resale and transportation (division of goods into batches, formation of deliveries, sorting, repackaging);
mixing of goods, if the characteristics of the final product (semi-finished products) do not significantly differ from the characteristics of the mixed goods.
39.3.5. Cost-plus method
39.3.5.1. The "cost plus" method consists in comparing the gross margin of the cost of sales of goods (works, services) in a controlled transaction with a similar profitability indicator in comparable uncontrolled transactions.
{Subclause 39.3.5.1 of subparagraph 39.3.5 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.5.2. The cost-plus method may be applied, in particular, but not exclusively, when:
performance of work (provision of services) by persons who are related to the recipients of the results of such work (services);
transactions for the sale of goods, raw materials or semi-finished products under contracts between related parties;
{Paragraph three of subparagraph 39.3.5.2 of subparagraph 39.3.5 of paragraph 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
transactions for the sale of goods (works, services) under long-term agreements (contracts) between related parties.
{Paragraph four of subparagraph 39.3.5.2 of subparagraph 39.3.5 of paragraph 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.6. Net profit method
39.3.6.1. The net profit method consists in comparing the relevant financial profitability indicator in a controlled operation (net profit based on the relevant base (expenses, sales, assets) or the profitability indicator of operating expenses) with the relevant profitability indicator in a comparable uncontrolled operation(s).
{Subclause 39.3.6.1 of subparagraph 39.3.6 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.6.2. The net profit method is used, in particular, in the absence or insufficiency of information on the basis of which it is possible to reasonably conclude that the conditions of a controlled transaction are sufficiently comparable with the conditions of a comparable uncontrolled transaction(s) when using the methods specified in subparagraphs 39.3.3-39.3.5 of paragraph 39.3 of this Article.
{Subclause 39.3.6 of clause 39.3 of Article 39 is supplemented by subparagraph 39.3.6.2 in accordance with Law No. 1797-VIII of 21.12.2016 }
39.3.7. Profit distribution method
39.3.7.1. The profit allocation method consists in allocating to each person participating in a controlled transaction(s) a portion of the total profit (or loss) resulting from such transaction that another unrelated person would receive from participation in a comparable uncontrolled transaction(s).
{Subclause 39.3.7.1 of subparagraph 39.3.7 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.7.2. If the parties to controlled transactions, the aggregate profit of which is subject to distribution taking into account the provisions of sub-clause 39.3.7 of this clause, maintain accounting and financial reporting based on different forms and methods of accounting, for the purposes of applying the profit distribution method, the accounting and financial reporting must be brought into line with the unified methodological principles of accounting.
39.3.7.3. The profit allocation method may be used, in particular, but not exclusively, in the presence of:
a significant relationship between the controlled transactions and other transactions carried out by the parties to the controlled transaction with their related parties;
the parties to a controlled transaction have rights to own (use) intangible assets that significantly affect the level of profitability received by the parties to a controlled transaction as a result of such a controlled transaction.
{Paragraph three of subparagraph 39.3.7.3 of subparagraph 39.3.7 of paragraph 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.7.4. The distribution of profit between the parties to controlled transactions is carried out on the basis of the results of assessing their contribution to the total profit in accordance with criteria based on objective data and confirmed by information in comparable transactions and/or internal data of the parties to controlled transactions, taking into account the functions performed by each of such parties, the assets used during the implementation of controlled transactions and the economic (commercial) risks assumed, associated with such implementation.
{Subclause 39.3.7.4 of subparagraph 39.3.7 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.7.5. For the purposes of sub-clause 39.3.7 of this clause, the aggregate profit of all parties to controlled transactions is the sum of the profit from such controlled transactions of all parties to controlled transactions for the period under analysis. In this case, the residual profit (loss) is defined as the difference between the aggregate profit (loss) obtained from the results of the controlled transactions and the sum of the estimated profit (loss) of all parties to controlled transactions.
39.3.7.6. The estimated profit (loss) is determined based on the methods provided for in subparagraphs 39.3.1.2-39.3.1.4 of subparagraph 39.3.1 of this paragraph, for each person who is a party to the controlled transactions, based on the range of prices of goods (works, services) or profitability indicators for each party, taking into account the functions performed by such party, assets used and commercial risks assumed, which are typical for comparable transactions.
{Subclause 39.3.7.6 of subparagraph 39.3.7 of clause 39.3 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.3.7.7. The determination of the final profit (loss) of each party to the controlled transactions is carried out by summing the corresponding estimated profit (loss) and residual profit (loss).
39.3.7.8. For the distribution between the parties to controlled transactions of the aggregate or residual profit (loss) of all parties to the said transactions, the following indicators may be taken into account, in particular, but not exclusively:
the amount of expenses incurred by each party to the controlled transactions in connection with the creation of intangible assets, the use of which affects the amount of actual profit (loss) from the controlled transactions;
characteristics of the personnel involved by each party to the controlled transactions, including their number and qualifications; time spent by the personnel; the amount of labor costs that have an impact on the amount of profit actually received (loss incurred) by each party to the controlled transactions;
the market value of assets that were used by each party to the controlled transactions and had an impact on the amount of profit (loss) actually received from the controlled transactions;
other indicators related to the performance of functions, use of assets, commercial risks assumed and the amount of profit (loss) actually received by each party to the controlled transactions.
39.3.8. The taxpayer has the right to determine the compliance of the conditions of a controlled transaction with the "arm's length" principle based on the totality of several controlled transactions with one person, combined according to the grouping principle.
The grouping principle provides for the possibility of combining operations for the purpose of applying the methods for establishing compliance of the conditions of a controlled operation with the arm's length principle specified in subparagraphs 39.3.4-39.3.7 of paragraph 39.3 of this Article, including for calculating the profitability indicators established by subparagraph 39.3.2.5 of subparagraph 39.3.2 of paragraph 39.3 of this Article, if such operations are closely interrelated or are a continuation of each other or are of a continuous or regular nature. Such operations may, in particular, include:
purchase (sale) of goods (works, services) under long-term contracts, in particular, transactions carried out throughout the entire reporting (tax) period;
transfer (receipt) of rights to use various intangible assets related to one product (service);
purchase (sale) of a series of closely related products (product group) and/or services;
purchase (sale) of various goods (works, services) provided that one good (work, service) or one group of goods (works, services) creates demand for another good (work, service) or group of goods (works, services).
{Clause 39.3 of Article 39 is supplemented by subparagraph 39.3.8 in accordance with Law No. 1797-VIII of 21.12.2016 }
39.3.9. When calculating the profitability ratio for a separate controlled transaction (a set of grouped controlled transactions in accordance with subparagraph 39.3.8 of this paragraph), the most reasonable allocation algorithm that corresponds to the economic essence of the controlled transaction and the nature of the expenses incurred or the income received shall be used to determine the operating expenses and income directly related to such transaction.
{Clause 39.3 of Article 39 is supplemented by subparagraph 39.3.9 in accordance with Law No. 1797-VIII of 21.12.2016 }
39.3.10. For controlled transactions provided for in subparagraphs "c" and "e" of subparagraph 39.2.1.4 of subparagraph 39.2.1 of clause 39.2 of this article, in the absence of reliable information on comparable uncontrolled transactions, and, as a result, the impossibility of establishing the compliance of the terms of the controlled transaction with the "arm's length" principle using the methods specified in subparagraph 39.3.1 of this clause, the determination of the value of intangible assets or the amount of the corresponding compensation may be carried out using the comparative valuation method, which is based on the calculation of the present value (discounted value) of future cash flows.
The calculation of the present value (discounted value) of future cash flows is carried out in accordance with National or International Valuation Standards.
{Clause 39.3 of Article 39 is supplemented by subparagraph 39.3.10 in accordance with Law No. 466-IX of January 16, 2020 }
39.4. Preparation and submission of reports for tax control
{Paragraph one of clause 39.4 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.4.1. For the purposes of tax control over transfer pricing, the reporting period is the calendar year.
39.4.2. Taxpayers who carried out controlled transactions in the reporting year are required to submit a report on controlled transactions by October 1 of the year following the reporting year.
{Paragraph one of subparagraph 39.4.2 of paragraph 39.4 of Article 39 as amended by Law No. 2970-IX of March 20, 2023 }
Taxpayers who are members of the relevant international group of companies and carried out controlled transactions in the reporting year are required to submit a notification of participation in the international group of companies by October 1 of the year following the reporting year.
{Subparagraph 39.4.2 of paragraph 39.4 of Article 39 is supplemented with a new paragraph in accordance with Law No. 2970-IX of March 20, 2023 }
The report on controlled transactions and notifications of participation in an international group of companies are submitted to the central executive body implementing state tax policy by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
39.4.2.1. The report on controlled transactions shall contain information on all controlled transactions carried out by the taxpayer in the reporting period.
If a taxpayer discovers that the previously submitted report on controlled transactions does not provide complete information, contains errors or shortcomings, such taxpayer has the right to submit:
a new report before the deadline for submitting a report on controlled transactions for the same reporting period;
a clarifying report if submitted after the deadline for the relevant reporting period.
Submission by the taxpayer of a clarifying report on controlled transactions does not exempt him from liability provided for in subparagraphs 120.4 and 120.6 of Article 120 of this Code.
During documentary audits, the taxpayer does not have the right to submit a report (clarification report) on controlled transactions for the reporting period being audited.
The form and procedure for compiling a report on controlled transactions are established by the central executive body that ensures the formation and implementation of state financial policy.
39.4.2.2. Notification of participation in an international group of companies must contain, in particular, the following information:
a) data on the parent company of the international group of companies to which the taxpayer belongs, in particular its name, data on the state (territory) of tax residence, the state (territory) of registration (if different from the state/territory of tax residence), the identification (registration) number (code) assigned to the parent company as a taxpayer in the state (territory) of its registration, any other identification (registration) numbers (codes) of the parent company and their type, information on the address(es) of the parent company (location address, address of place of business, etc.);
b) data on the participant of the international group of companies, which is an authorized participant of such an international group of companies to submit a report by country of the international group of companies to which the taxpayer belongs (if there is such an authorized participant), in particular its name, data on the state (territory) of tax residency, state (territory) of registration (if different from the state/territory of tax residency), identification (registration) number (code) assigned to the participant of the international group of companies as a taxpayer in the state (territory) of its registration, any other identification (registration) numbers (codes) of the participant of the international group of companies and their type, information on the address (addresses) of such a participant of the international group of companies (location address, address of place of business, etc.);
c) the date that is the last day of the financial year for which the consolidated financial statements of the international group of companies are prepared, and if such statements are not prepared - the date of the end of the financial year in accordance with the internal regulations of the parent company of the international group of companies;
d) information on the amount of the total consolidated income of the international group of companies for the financial year preceding the reporting year, calculated in accordance with the accounting standards applied by the parent company of the international group of companies.
If the legislation of the foreign jurisdiction of tax residence of the parent company does not provide for the requirement to submit reports by country of the international group of companies for the purposes of automatic exchange of tax and financial information, the notification of participation in the international group of companies shall also include information that the parent company of the international group of companies is not required to submit a report by country of the international group of companies.
The form and procedure for preparing a notification of participation in an international group of companies are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Subclause 39.4.2.2 of subparagraph 39.4.2 of clause 39.4 of Article 39 as amended by Law No. 2970-IX of 20.03.2023 }
{Subclause 39.4.2 of Clause 39.4 of Article 39 as amended by Law No. 609-VIII of 07/15/2015 ; as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 2245-VIII of 12/07/2017 ; as amended by Law No. 466-IX of 01/16/2020 }
39.4.3. Taxpayers carrying out controlled transactions must prepare and maintain transfer pricing documentation for each reporting period.
{Subclause 39.4.3 of clause 39.4 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.4.4. At the request of the central executive body implementing state tax policy, taxpayers shall, within 30 calendar days from the date of receipt of the request, submit transfer pricing documentation regarding controlled transactions specified in the request.
Transfer pricing documentation is submitted by the taxpayer to the regulatory authority specified in the request.
{Subclause 39.4.4 of Clause 39.4 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2628-VIII of 23.11.2018 }
39.4.5. The request shall be sent no earlier than October 1 of the year following the calendar year in which such controlled transaction(s) were carried out.
{Subclause 39.4.5 of clause 39.3 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
39.4.6. Transfer pricing documentation (a set of documents or a single document drawn up in any form) must contain the following information:
{Paragraph one of subparagraph 39.4.6 of paragraph 39.3 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
a) data on the person(s) who is a party to the controlled transaction and on the taxpayer's related parties (in the reporting period in which the controlled transaction was carried out and at the time of submission of the documentation), namely:
the counterparty(s) of the controlled transaction;
individuals who are the ultimate beneficial owners (controllers) of the taxpayer (if any);
{Subparagraph "a" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
persons who directly (indirectly) own corporate rights of the taxpayer in the amount of 25 percent or more;
{Paragraph four of subparagraph "a" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
persons whose corporate rights in the amount of 25 percent or more are directly (indirectly) owned by the taxpayer.
{Paragraph five of subparagraph "a" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
The data must be such as to allow identification of such related persons (including the names of the states (territories) of which such persons are tax residents, the person's code established in the state (country) of their registration) and disclose information on the criteria for recognizing such persons as related;
{Subparagraph "a" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
b) a general description of the activities of the group of companies (including the parent company and its subsidiaries), including the organizational structure of such group, a description of the economic activities of this group, transfer pricing policy, information about persons to whom the taxpayer provides local management reports (name of the state in whose territory such persons maintain their head offices);
{Subparagraph "b" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
c) a description of the taxpayer's management structure, a diagram of its organizational structure indicating the total number of employees and broken down by individual divisions of the taxpayer as of the date of the transaction or at the end of the reporting period;
{Subparagraph "c" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
d) a description of the activities and business strategy carried out by the taxpayer, in particular, the economic conditions of the activity, an analysis of the relevant markets for goods (works, services) in which the taxpayer operates, and the main competitors;
e) information about the taxpayer's participation in business restructuring or transfer of intangible assets in the reporting or previous year, with an explanation of the aspects of these transactions that affected or are affecting the taxpayer's activities;
e) a description of the controlled transaction indicating the supply chain (creation of value) of goods (works, services) in the controlled transaction.
The description of transactions for the acquisition (sale) of goods, works (services), intangible assets, and other items of business transactions other than goods must contain a justification of economic feasibility (economic benefit obtained as a result of the implementation of a controlled transaction in comparison with uncontrolled transactions that are realistically available alternatives to such a controlled transaction) and the presence of a business purpose for their acquisition (sale);
{Sub-clause "d" of subparagraph 39.4.6 of clause 39.3 of Article 39 is supplemented by the second paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
{Sub-clause "d" of sub-clause 39.4.6 of clause 39.3 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
e) description of the goods (works, services), including physical characteristics, quality and reputation in the market, country of origin and manufacturer, presence of a trademark and other information related to the qualitative characteristics of the goods (works, services).
{Paragraph two of subparagraph "e" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 was excluded on the basis of Law No. 1117-IX of 17.12.2020 }
h) information about the actually made payments in the controlled transaction (amount and currency of payments, date, payment documents);
g) factors that influenced the formation and setting of the price, in particular the business strategies of the parties to the transaction (if any), which significantly affect the prices of goods (works, services);
h) functional analysis of the controlled transaction: information about the functions of the persons who are parties (participating) in the controlled transaction, about the assets used by them related to such a controlled transaction, and the economic (commercial) risks that such persons took into account when carrying out the controlled transaction;
i) economic and comparative analysis:
the amount of income (profit) received and/or the amount of expenses (loss) incurred as a result of the controlled transaction, the level of profitability;
justification for the choice of the method used to determine the compliance of the terms of the controlled transaction with the arm's length principle, the financial indicator in accordance with subparagraph 39.3.2.5 of subparagraph 39.3.2 of paragraph 39.3 of this article and the party investigated in accordance with subparagraph 39.3.2.7 of subparagraph 39.3.2 of paragraph 39.3 of this article;
justification for the selection and information about comparable transactions (comparable entities) and sources of information used for the analysis;
justification for using information from several tax periods (years) when determining the profitability range in accordance with subparagraph 39.3.2.8 of subparagraph 39.3.2 of paragraph 39.3 of this article and calculating the weighted average value of the profitability indicator;
{Sub-paragraph "i" of subparagraph 39.4.6 of paragraph 39.4 of Article 39 is supplemented with a new paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
calculation of the price range (profitability);
description and calculation of the adjustments made in accordance with subparagraph 39.2.2.1, subparagraph 39.2.2, paragraph 39.2 of this article.
The financial indicators used in calculating the profitability indicators of the controlled transaction must be confirmed by the accounting and financial reporting data of the party to the controlled transaction that was investigated in accordance with subparagraph 39.3.2.7 of subparagraph 39.3.2 of paragraph 39.3 of this Article.
{Sub-paragraph "i" of subparagraph 39.4.6 of paragraph 39.3 of Article 39 is supplemented with a new paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
If a party to a controlled transaction supplies (sells) goods, works, services, other items under controlled transactions to several persons, and for the purposes of establishing compliance of the conditions of controlled transactions with the arm's length principle, a comparison of the profitability index of such a supplier is carried out, the documentation must contain a description of the algorithm for distributing the supplier's costs incurred for the implementation of such transactions, which are taken into account when calculating the profitability index. Such a description must contain information on the economic justification for the choice of the cost distribution algorithm, the methodology for its application, as well as the actual calculation carried out in accordance with the selected methodology;
i) information about the taxpayer's independent or proportional adjustment of the tax base and tax amounts in accordance with subparagraphs 39.5.4 and 39.5.5 of paragraph 39.5 of this article (if carried out);
{Subclause 39.4.6 of Clause 39.4 of Article 39 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
j) if the payer is part of an international group of companies:
copies of significant intra-group agreements affecting pricing in the controlled transaction;
copies of agreements on preliminary pricing coordination, tax clarifications of competent authorities of states (territories) used in agreements between members of an international group of companies regarding a controlled transaction and in the preparation of which the central executive body implementing state tax policy did not participate;
{Subclause 39.4.6 of clause 39.3 of Article 39 is supplemented by subparagraph "i" in accordance with Law No. 466-IX of 16.01.2020 }
j) a copy of the auditor's report on the taxpayer's accounting (financial) statements for the reporting period(s) for which transfer pricing documentation is submitted (if its presence is mandatory for the taxpayer);
{Subclause 39.4.6 of clause 39.3 of Article 39 is supplemented by subparagraph "y" in accordance with Law No. 466-IX of 16.01.2020 }
k) copies of agreements (contracts) and any amendments thereto, under which the controlled transaction was carried out.
{Subclause 39.4.6 of clause 39.3 of Article 39 is supplemented by subparagraph "k" in accordance with Law No. 466-IX of 16.01.2020 }
39.4.7. The central executive body implementing state tax policy has the right to send a request to provide global transfer pricing documentation (master file) to a taxpayer that is part of an international group of companies if the total consolidated income of the international group of companies for the financial year preceding the reporting year, calculated in accordance with the accounting standards applied by the parent company of the international group of companies, is equal to or exceeds the equivalent of 50 million euros.
A request for submission of global documentation (master file) may be sent no earlier than twelve months and no later than thirty-six months from the end of the fiscal year established by the international group of companies to which such taxpayer belongs, and in the absence of information about the fiscal year established by the international group of companies - no earlier than twelve months and no later than thirty-six months after the end of the reporting year.
Global transfer pricing documentation (master file) must be provided by the taxpayer to the central executive body implementing state tax policy within 90 calendar days from the date of receipt of the request.
If two or more taxpayers are registered in Ukraine and are part of the same international group of companies, the central executive body implementing state tax policy shall send a request for the provision of global transfer pricing documentation (master file) to only one of such taxpayers of its choice.
In the event of such a taxpayer's violation of the term specified in paragraph three of this subparagraph, the central executive body implementing the state tax policy shall have the right to send a request for the provision of global transfer pricing documentation (master file) for the same period to another taxpayer that is part of the same international group of companies. In this case, the first taxpayer shall not be exempted from the obligation to provide the central executive body implementing the state tax policy with global transfer pricing documentation (master file).
A request for the provision of global transfer pricing documentation (master file) to a taxpayer shall not be sent if such documentation has already been provided in accordance with this subparagraph to the central executive body implementing state tax policy by any other taxpayer belonging to the same international group of companies.
Global transfer pricing documentation (master file) - a set of documents or a single document drawn up in an arbitrary form, which must contain information about:
a) the organizational structure of the international group of companies (in the form of a graphic diagram) indicating the persons who are members of the international group of companies, their organizational and legal forms, the ownership structure (indicating ownership shares) and the states and territories in which the said persons carry out their activities;
b) a general description of the activities of the international group of companies, including:
description of key factors affecting the financial performance of an international group of companies;
a description of the supply chains and value creation of the five largest goods (works, services) by revenue of the international group of companies, as well as the supply chains of any other goods (works, services, other objects of civil rights), the share of which is more than 5 percent of the revenue of the international group of companies for the financial year, and the main geographical markets in which the specified goods (works, services) are sold (performed, provided);
a list and brief description of material contracts for the provision (receipt) of services and works concluded between members of the international group (except for contracts related to the conduct of scientific research and development work), including a description of the functional capabilities of the main members of the international group involved in the provision of such services and works, transfer pricing policy regarding the allocation of the cost of services and the determination of prices for payment for intra-group services;
a brief functional analysis of the activities of the participants in an international group of companies that have a significant impact on the financial results of this group, including a description of the main functions performed, assets used, and economic (commercial) risks taken;
information on major business restructuring, acquisition and disposal transactions that occurred during the financial year;
c) intangible assets used by an international group of companies in its activities, in particular:
a description of the development strategy of an international group of companies regarding the development, ownership and use of intangible assets, including the location of major research centers and their management bodies;
a list and description of intangible assets (groups of intangible assets) that have a significant impact on the pricing of companies in an international group, indicating the participants in such an international group of companies that own such assets by right of ownership or other right (use, possession and/or disposal);
a list of material agreements related to intangible assets concluded between members of an international group of companies, including licensing agreements, cost-coverage agreements, and major agreements for the provision of research and development services;
description of the transfer pricing policy of an international group of companies regarding research and development work and intangible assets;
a description of significant transactions for the transfer of intangible assets between members of an international group of companies during the relevant financial year, indicating the names of such members, the countries of registration and jurisdictions where they operate, the compensations made in the reporting (tax) period, and the level of remuneration (compensation payments) associated with such transfer;
d) financial activities of an international group of companies, in particular:
a general description of how such a group is financed, including information on financing raised from persons who are not members of the international group of companies;
indication of all participants in an international group of companies that carry out centralized intra-group financial activities for the participants of this group, with information on the states (territories) where such participants are registered and/or the location of their management body;
a general description of the transfer pricing policy regarding the financing of members of an international group of companies;
e) consolidated financial statements of the international group of companies for the last financial year, and in their absence - other consolidated statements prepared for management, tax or other purposes;
e) a list and brief description of existing unilateral agreements on preliminary pricing agreements, tax rulings of competent authorities of states (territories) that are applied in agreements between members of an international group of companies and related to the distribution of income between states (territories).
{Subclause 39.4.7 of clause 39.4 of Article 39 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
39.4.8. Transfer pricing documentation and global transfer pricing documentation (master file) shall be submitted by the taxpayer in the state language in paper form or in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
If documents in a foreign language are submitted together with the documentation, the taxpayer shall simultaneously submit a translation of such documents into the state language.
The translation of transfer pricing documentation and global transfer pricing documentation (master file) into the state language is not authenticated.
The values of the cost indicators of global documentation may be indicated in the currency in which the parent company of the international group of companies prepares its consolidated financial statements.
{Subclause 39.4.8 of Clause 39.4 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
39.4.9. The central executive body implementing the state tax policy has the right to send a request to the taxpayer with a requirement to additionally submit, within 30 calendar days from the date of its receipt, information in accordance with subparagraphs 39.4.6 and 39.4.7 of paragraph 39.4 of this article and/or justification of the compliance of the conditions of the controlled transaction with the "arm's length" principle in the event of one of the following circumstances being established:
the transfer pricing documentation submitted by the taxpayer does not contain information to the extent specified in subparagraph 39.4.6 of paragraph 39.4 of this article, and/or does not contain proper justification for the compliance of the terms of the controlled transaction with the arm's length principle;
the global transfer pricing documentation (master file) submitted by the taxpayer does not contain information to the extent specified in subparagraph 39.4.7 of paragraph 39.4 of this article.
The specified additional information is an integral part of the transfer pricing documentation and/or global documentation (master file).
{Subclause 39.4.9 of Clause 39.4 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
39.4.10. A taxpayer - a resident of Ukraine belonging to an international group of companies, in the cases specified in this subparagraph, is obliged to submit to the central executive body implementing state tax policy a report by country of the international group of companies in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" .
A report by country of an international group of companies is submitted if the total consolidated income of the international group of companies to which the taxpayer belongs, for the financial year preceding the reporting year, calculated in accordance with the accounting standards applied by the parent company of the international group of companies (in the absence of information - in accordance with international accounting standards), is equal to or exceeds the corresponding indicator of the minimum amount of total consolidated income, determined by subparagraph 39.4.10 - 2 of this paragraph, and in the presence of one of the following circumstances:
the taxpayer is the parent company of an international group of companies;
the parent company of an international group of companies authorizes a taxpayer resident in Ukraine to submit a report by country of the international group of companies to the regulatory authority;
In accordance with the requirements of the legislation of the jurisdiction of tax residency of the parent company of an international group of companies, such an international group of companies is not required to submit a report by country of the international group of companies;
there is a valid international treaty between Ukraine and the relevant foreign jurisdiction of tax residence of the parent company of an international group of companies containing provisions on the exchange of information for tax purposes, but the relevant QCAA agreement has not entered into force as of the end date of the financial year for which, in accordance with subparagraph 39.4.11 of this paragraph, a country-by-country report must be submitted for such international group of companies;
between Ukraine and the relevant foreign jurisdiction of tax residency of the parent company of the international group of companies there is a valid international agreement containing provisions on the exchange of information for tax purposes, but there are facts of systematic non-fulfillment of the relevant QCAA agreement. The central executive body implementing the state tax policy shall notify the taxpayer - resident of Ukraine, who belongs to the international group of companies, the parent company of which is a tax resident of such foreign jurisdiction, of the existence of such facts (including those identified on the basis of a notification of the foreign jurisdiction of tax residency of the authorized participant of the international group of companies about the systematic non-fulfillment of the relevant QCAA agreement, provided to the competent authority of Ukraine). The specified notification shall be sent within 10 business days from the date of establishment of the facts provided for in this paragraph in accordance with the procedure specified in Article 42 of this Code. If more than one member of such an international group of companies is a taxpayer resident of Ukraine, the specified notification shall be sent to one of them at the choice of the central executive body implementing state tax policy.
For the purposes of this subparagraph, a systematic failure to comply with a QCAA agreement with a foreign jurisdiction means that the foreign jurisdiction of tax residence of the relevant member of an international group of companies has a valid QCAA agreement with Ukraine, but has suspended the automatic exchange of reports by country of the international group of companies for reasons other than those consistent with the terms of such agreement, or has otherwise continuously and consistently failed to provide Ukraine with reports by country of the international group of companies at its disposal on international groups of companies that have members in Ukraine.
If more than one member of an international group of companies is a taxpayer resident of Ukraine and one or more circumstances specified in paragraphs five to seven of this subparagraph are present, the international group of companies may appoint one of such members as an authorized person to submit a report by country of the international group of companies. The authorized member of the international group of companies shall notify the central executive body implementing state tax policy of such appointment by submitting a notification on participation in the international group of companies specified in subparagraph 39.4.2 of this subparagraph. If, for the reasons provided for in this paragraph, an authorized participant in an international group of companies submits a revised notification of participation in an international group of companies and such submission is made no later than the 10th day of the month following the month in which this participant in an international group of companies received information about his appointment as an authorized participant in an international group of companies, the penalty for providing false information in the notification of participation in an international group of companies, provided for in Clause 120.5 of Article 120 of this Code, shall not apply.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.10 in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 2970-IX of 03.20.2023 }
39.4.10 - 1. In the presence of one or more circumstances provided for in paragraphs five to seven of subparagraph 39.4.10 of this paragraph, a taxpayer - a resident of Ukraine who belongs to an international group of companies is exempted from submitting a report by country of the international group of companies for the relevant financial year specified in subparagraph 39.4.11 of this paragraph, if the following conditions are simultaneously met:
1) the international group of companies, of which such taxpayer is a member, has submitted a report by country of the international group of companies for the relevant financial year through another authorized member of the international group of companies in the foreign jurisdiction of its tax residence for such financial year;
2) the report shall be submitted by country of the international group of companies no later than the deadline for submitting the report by country of the international group of companies, specified in subparagraph 39.4.11 of this paragraph;
3) the legislation of the foreign jurisdiction of tax residency of the authorized participant of the parent company provides for requirements for the submission of reports by country of the international group of companies for the purposes of automatic exchange of tax and financial information;
4) the foreign jurisdiction of tax residency of the authorized member of the international group of companies has a valid QCAA agreement with Ukraine as of the end date of the fiscal year for which, in accordance with subparagraph 39.4.11 of this paragraph, a report by country of the international group of companies must be submitted in respect of such international group of companies;
5) the foreign jurisdiction of tax residency of the authorized member of the international group of companies has not notified the competent authority of Ukraine of the systemic non-compliance with the relevant QCAA agreement;
6) a member of an international group of companies has notified the tax authorities of the jurisdiction of its tax residency that it is authorized to submit a report by country of the international group of companies for the relevant international group of companies (if such notification is provided for by the legislation of the jurisdiction of tax residency of this member of the international group of companies);
7) a taxpayer - a resident of Ukraine, belonging to the same international group of companies, has notified the central executive body implementing state tax policy about a participant in the international group of companies who is an authorized participant in such an international group of companies to submit a report by country of the international group of companies, by submitting a notification of participation in the international group of companies, specified in subparagraph 39.4.2 of this paragraph.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.10 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
39.4.10 - 2. For the purposes of submitting a report by country of an international group of companies, the following indicators of the minimum size of the total consolidated income of the international group of companies to which the taxpayer belongs shall be applied:
the equivalent of 750 million euros - for the circumstances specified in the third paragraph of sub-clause 39.4.10 of this clause;
the equivalent of 750 million euros - for the circumstances specified in paragraphs four to seven of subparagraph 39.4.10 of this clause, but if the legislation of the foreign jurisdiction of tax residence of the parent company of the international group of companies or the authorized participant of the parent company (in the event of its appointment by the parent company) determines a different amount of the total consolidated income of the international group of companies, denominated not in euros, which, according to the legislation of such foreign jurisdiction, is used for the purposes of submitting a report by country of the international group of companies (if such legislation exists), such other amount shall be considered the threshold amount for the circumstances of submitting a report by country of the international group of companies specified in paragraphs four to seven of subparagraph 39.4.10 of this clause.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.10 - 2 in accordance with Law No. 2970-IX of 20.03.2023 }
39.4.11. The report by country of an international group of companies contains information by each jurisdiction (state, territory) in which a member of the relevant international group of companies is registered or in which the international group of companies carries out its activities, and regarding each member of such international group of companies, in particular, but not exclusively:
{Paragraph one of subparagraph 39.4.11 of paragraph 39.4 of Article 39 as amended by Law No. 2970-IX of 20.03.2023 }
a) the name of the state (territory) under whose legislation the member of the international group of companies is established, and the state (territory) of which it is a resident;
b) the total amount of income (revenue) for the financial year for which the report is prepared by country, including a breakdown into the amount of income (revenue) under agreements concluded by members of this international group of companies and related parties, and the amount of income (revenue) under agreements with unrelated parties;
c) the amount of profit (loss) before tax for the financial year for which the report is prepared by country;
d) the amount of paid corporate income tax (corporate tax) or its equivalent in the financial year for which the report is prepared by country;
e) the amount of accrued corporate income tax (corporate tax) or its equivalent for the financial year for which the report is being prepared by country;
e) the amount of authorized capital (registered authorized capital) as of the end of the financial year for which the report is being prepared by country;
e) the amount of retained earnings (accumulated) as of the end of the financial year for which the report is prepared by country;
h) the number of employees for the financial year for which the report is being prepared, broken down by country;
g) the carrying amount of tangible assets (other than cash or cash equivalents, intangible assets, financial assets) as of the end of the financial year for which the report is prepared by country;
{Paragraph ten of subparagraph 39.4.11 of paragraph 39.4 of Article 39 as amended by Law No. 2970-IX of March 20, 2023 }
h) the main types of activities carried out by members of the international group of companies;
i) data on each participant of the international group of companies to which the taxpayer belongs, in particular its name, data on the state (territory) of tax residence, the state (territory) of registration (if different from the state/territory of tax residence), the identification (registration) number (code) assigned to the participant of the international group of companies as a taxpayer in the state (territory) of its registration, any other identification (registration) numbers (codes) of the participant of the international group of companies and their type, information on the address (addresses) of such participant of the international group of companies (location address, address of place of business, etc.).
{Subparagraph 39.4.11 of paragraph 39.4 of Article 39 is supplemented with a new paragraph in accordance with Law No. 2970-IX of March 20, 2023 }
The form of the report by country of an international group of companies and the procedure for filling it out are approved by the central executive body that ensures the formation and implementation of state financial policy.
The report by country of an international group of companies is prepared for the financial year established by the parent company of the international group of companies, which may not coincide with the calendar year, and is submitted no later than twelve months after the last day of such financial year (in the absence of information on the financial year established by the parent company of the international group of companies - within twelve months after the end of the calendar year).
{Paragraph fourteen of subparagraph 39.4.11 of paragraph 39.4 of Article 39 as amended by Law No. 2970-IX of March 20, 2023 }
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.11 in accordance with Law No. 466-IX of January 16, 2020 }
39.4.11 - 1. If the supervisory authority detects errors in the submitted report by country of the international group of companies or receives a notification of such errors from the competent authority of another jurisdiction on the basis of the QCAA agreement, it shall notify the taxpayer of the need to correct the errors or clarify the information in the submitted report by country of the international group of companies. The taxpayer shall be obliged to submit a clarified report by country of the international group of companies with the relevant corrections or provide explanations by electronic means in accordance with the procedure provided for in Article 42 of this Code, no later than 30 calendar days from the date of receipt of the notification by the supervisory authority.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.11 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
39.4.12. A report by country of an international group of companies submitted by a taxpayer in accordance with subparagraph 39.4.10 of this subparagraph is subject to automatic exchange of tax and financial information.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.12 in accordance with Law No. 466-IX of January 16, 2020 }
39.4.13. Information from the report by country of an international group of companies, received by the central executive body implementing state tax policy from the taxpayer in accordance with subparagraph 39.4.10 of this subparagraph and/or within the framework of international agreements on the automatic exchange of tax and financial information, is used for the purposes of assessing transfer pricing risks during the monitoring of controlled transactions and cannot be an independent basis for adjusting the amount of taxable profit of the taxpayer.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.13 in accordance with Law No. 466-IX of January 16, 2020 }
39.4.14. Information in the report by country of an international group of companies, received by the central executive body implementing state tax policy, within the framework of international agreements on the automatic exchange of tax and financial information, is information with limited access, taking into account the requirements of Article 22 of the Convention on Mutual Administrative Assistance in Tax Matters.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.14 in accordance with Law No. 466-IX of 16.01.2020 }
39.4.15. For the purposes of subparagraphs 39.4.7 and 39.4.10 of this subparagraph, the calculation of the total consolidated income of an international group of companies is carried out in accordance with the official exchange rate of the hryvnia against the euro (average for the period) for the calendar year preceding the reporting year.
{Clause 39.4 of Article 39 is supplemented by subparagraph 39.4.15 in accordance with Law No. 466-IX of January 16, 2020 }
39.5. Tax control over the establishment of compliance of controlled transactions with the arm's length principle
39.5.1. Tax control over the establishment of compliance of the conditions of controlled transactions with the "arm's length" principle is carried out by monitoring controlled transactions, conducting transfer pricing surveys and conducting inspections of taxpayer compliance with the "arm's length" principle.
{Paragraph one of subparagraph 39.5.1 of paragraph 39.5 of Article 39 as amended by Laws No. 609-VIII of 15.07.2015 , No. 1797-VIII of 21.12.2016 }
39.5.1.1. Monitoring of the conditions of controlled transactions is carried out by analyzing reports on controlled transactions, transfer pricing documentation, global transfer pricing documentation (master file) and a report by country of an international group of companies, any other information sources, and by obtaining tax information in accordance with Article 73 of this Code.
{Paragraph one of subparagraph 39.5.1.1 of subparagraph 39.5.1 of paragraph 39.5 of Article 39 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
In order to establish compliance of the conditions of controlled transactions with the arm's length principle, officials of the controlling body, when analyzing reports on controlled transactions and/or transfer pricing documentation and/or global transfer pricing documentation (master file) submitted by the taxpayer in accordance with clause 39.4 of this article, have the right to interview authorized persons and/or employees of the taxpayer.
{Paragraph two of subparagraph 39.5.1.1 of subparagraph 39.5.1 of paragraph 39.5 of Article 39 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
The procedure for monitoring controlled operations and conducting surveys is established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph three of subparagraph 39.5.1.1 of subparagraph 39.5.1 of paragraph 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.1.2. If the controlling body, while performing its tax control functions, has discovered facts of controlled transactions by a taxpayer, a report on which has not been submitted in accordance with subparagraph 39.4.2 of paragraph 39.4 of this Article, it shall send a notification of the detected controlled transactions to the central executive body implementing state tax policy. The notification shall be sent by electronic means no later than 5 business days from the date of discovery of such transactions.
The date of detection by the controlling authority of the facts of the taxpayer conducting controlled transactions, a report on which was not submitted in accordance with subparagraph 39.4.2 of paragraph 39.4 of this Article, is the date of drawing up the documentary audit report, in which such a fact is recorded.
{Paragraph two of subparagraph 39.5.1.2 of subparagraph 39.5.1 of paragraph 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.1.2 of subparagraph 39.5.1 of clause 39.5 of Article 39 as amended by Law No. 609-VIII of 15.07.2015 }
39.5.2. The audit of the taxpayer's compliance with the "arm's length" principle shall be conducted in accordance with the provisions of Chapter 8 , Section II of this Code, taking into account the features defined by this article.
{Paragraph one of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.1. An inspection of the taxpayer's compliance with the "arm's length" principle may be conducted by the supervisory authority in the following cases:
provision by the taxpayer of transfer pricing documentation in accordance with subparagraph 39.4.4 of paragraph 39.4 of this article;
failure by the taxpayer to submit or submission in violation of the requirements of paragraph 39.4 of this article of a report on controlled transactions, transfer pricing documentation, global transfer pricing documentation (master file), country-by-country report of an international group of companies;
submission by the taxpayer of a statement of intention to make a proportional adjustment.
{Subclause 39.5.2.1 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
39.5.2.2. The procedure for conducting an audit of taxpayer compliance with the "arm's length" principle is established by the central executive body that ensures the formation and implementation of state financial policy.
{Subclause 39.5.2.2 of Subclause 39.5.2 of Clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.3. The taxpayer shall provide documents in accordance with the requirements of paragraphs 85.2 and 85.3 of Article 85 of this Code within 10 business days from the date of commencement of the audit.
{Paragraph one of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
If it is necessary to obtain additional documents and/or information during the inspection regarding:
{Paragraph two of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
carrying out financial and economic operations related to the controlled operation;
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
business transactions with unrelated parties that may be considered comparable to a controlled transaction;
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
confirmation or refutation of the information provided by the payer in the submitted report on controlled transactions, transfer pricing documentation, global transfer pricing documentation (master file);
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
data specified in the report by country of the international group of companies to which the taxpayer belongs;
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
other documents and information necessary to establish compliance of the terms of the controlled transaction with the arm's length principle;
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
The specified documents and/or information shall be provided by the taxpayer within 15 business days from the date of receipt of the request from the officials (service personnel) of the controlling body conducting the inspection.
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
Officials (servicemen) of the controlling body conducting an inspection of the taxpayer's compliance with the "arm's length" principle shall have the right to receive from the taxpayer or his legal representatives copies of documents related to the subject of the inspection. Such copies shall be certified by the signature of the taxpayer or his official.
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
If the documents that are the subject of the audit were created by the taxpayer in electronic form, the taxpayer has the right to provide copies of such documents by electronic means in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Paragraph of subparagraph 39.5.2.3 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
39.5.2.4. The supervisory authority shall not have the right to conduct more than one inspection of the taxpayer's compliance with the arm's length principle of one taxpayer during a calendar year. The supervisory authority shall not have the right to re-conduct an inspection of the taxpayer's compliance with the arm's length principle of a taxpayer that has already been inspected (except for the cases specified in subparagraphs 78.1.5 , 78.1.12 of paragraph 78.1 of Article 78 of this Code).
{Subclause 39.5.2.4 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
{Subclause 39.5.2.5 of subparagraph 39.5.2 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
39.5.2.6. Conducting an audit of the taxpayer's compliance with the "arm's length" principle does not prevent the conduct of audits specified in Article 75 of this Code.
{Subclause 39.5.2.6 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
39.5.2.7. The term for conducting an audit of a taxpayer on compliance with the "arm's length" principle is calculated from the date of making a decision to conduct it until the date of drawing up a report (certificate) on conducting such an audit.
The term for conducting an audit of a taxpayer on issues of compliance with the "arm's length" principle is interrupted in the event that the court considers the taxpayer's claims on issues related to the appointment, conduct or subject of such an audit, until the completion of court proceedings.
{Subclause 39.5.2.7 of subparagraph 39.5.2 of clause 39.5 of Article 39 is supplemented by the second paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
{Subclause 39.5.2.7 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
39.5.2.8. The duration of the audit of the taxpayer's compliance with the "arm's length" principle shall not exceed 18 months.
Every six months of conducting an audit on the taxpayer's compliance with the "arm's length" principle, the regulatory authority provides the taxpayer with information on the current status of the audit.
{Subclause 39.5.2.8 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.9. If it is necessary to obtain information from foreign state bodies, conduct an examination and/or translate into Ukrainian documents necessary to examine the compliance of the conditions of a controlled transaction with the "arm's length" principle, the period for conducting the inspection may be extended by the decision of the head (deputy head) of the central executive body implementing state tax policy for a period not exceeding 12 months.
39.5.2.10. During an audit of the taxpayer's compliance with the "arm's length" principle, business transactions may be audited taking into account the period provided for in paragraph 102.1 of Article 102 of this Code.
{Subclause 39.5.2.10 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.11. If the taxpayer has used the most appropriate method of establishing compliance of the conditions of controlled transactions with the "arm's length" principle in accordance with the criteria provided for in paragraph 39.3 of this Article, such method shall be used during the inspection by the controlling body.
If the controlling body proves that the method (combination of methods) applied by the taxpayer does not allow for the most reasonable establishment of the compliance of the conditions of the controlled transaction with the arm's length principle, it has the right to apply other methods (combination of methods) to establish the compliance of the conditions of the controlled transaction with the arm's length principle.
39.5.2.12. The use of methods (combination of methods) to establish compliance of the conditions of a controlled transaction with the "arm's length" principle, not established by this article, is prohibited.
39.5.2.13. The supervisory authority conducting an inspection of the taxpayer's compliance with the "arm's length" principle has the right:
a) send requests for the provision of documents (information) regarding the controlled transaction to other taxpayers in accordance with subparagraph 73.3.1 of paragraph 73.3 of Article 73 of this Code, which:
{Paragraph one of subparagraph "a" of subparagraph 39.5.2.13 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 01.16.2020 ; as amended by Law No. 2970-IX of 03.20.2023 }
are parties to the controlled transaction being audited, or
{Paragraph of subparagraph "a" of subparagraph 39.5.2.13 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
were involved in the supply chain of goods (works, services, other objects of civil rights) that are the subject of the controlled transaction, or
{Paragraph of subparagraph "a" of subparagraph 39.5.2.13 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
taking into account the information received from the taxpayer and/or from other subjects of information relations, possess the information necessary to determine whether the conditions of the controlled transaction comply with the arm's length principle.
{Paragraph of subparagraph "a" of subparagraph 39.5.2.13 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
In the event that taxpayers specified in subparagraph "a" of this subparagraph fail to provide documents (information) at the request of the supervisory authority conducting an inspection of the taxpayer's compliance with the "arm's length" principle, and/or provide incomplete information, the supervisory authority has the right to conduct a counter-reconciliation of such taxpayers in accordance with the procedure provided for in paragraph 73.5 of Article 73 of this Code;
b) conduct interviews with officials and/or employees of taxpayers who are parties to the controlled transaction. Taxpayers are obliged to ensure that officials conducting an audit of the taxpayer's compliance with the arm's length principle have the opportunity to interview the relevant officials or employees;
c) send requests to competent authorities of foreign states regarding the subject and circumstances of the controlled transaction and/or regarding the business activities and financial reporting of a non-resident party to the controlled transaction;
d) hold meetings with the taxpayer (persons authorized by him) to discuss methods for determining the compliance of the conditions of controlled transactions with the "arm's length" principle applied by the controlling authority during the inspection;
{Sub-clause "d" of sub-clause 39.5.2.13 of sub-clause 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
e) visit and conduct, with the taxpayer's permission, an inspection of the premises, facilities and structures where the taxpayer's activities related to the conduct of a controlled transaction are carried out.
{Subclause 39.5.2.13 of subparagraph 39.5.2 of clause 39.5 of Article 39 is supplemented by subparagraph "e" in accordance with Law No. 466-IX of 16.01.2020 }
{Subclause 39.5.2.13 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 2628-VIII of 11/23/2018 }
39.5.2.14. The results of the audit on the taxpayer's compliance with the "arm's length" principle are drawn up in the form of a report (certificate), drawn up in two copies, signed by the officials who conducted the audit and the taxpayer or his representative.
{Subclause 39.5.2.14 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.15. If, based on the results of the inspection, it is found that the conditions of the controlled transaction differ from the conditions that comply with the "arm's length" principle, which led to an incorrect calculation of the amount of taxable profit of the taxpayer and/or an underestimation of the tax amount, an inspection report is drawn up. If there are no such violations, a certificate is drawn up.
{Subclause 39.5.2.15 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.16. If, based on the results of audits not related to transfer pricing, or the taxpayer independently has already accrued tax liabilities based on price adjustments and restrictions on the level of expenses and income for such transactions, the amounts of accrued tax liabilities based on the results of such audit and/or independent accrual shall be credited to the repayment of accrued taxes based on the results of the audit on the taxpayer's compliance with the "arm's length" principle.
{Subclause 39.5.2.16 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.17. The form of the act (certificate) on the results of the audit on the taxpayer's compliance with the "arm's length" principle and the requirements for its preparation are established by the central executive body that ensures the formation and implementation of state financial policy.
The report on the results of the audit on the taxpayer's compliance with the "arm's length" principle must contain documented facts of deviation of the conditions of the controlled transaction from the conditions that comply with the "arm's length" principle, justification that such deviation caused an incorrect calculation of the taxpayer's taxable profit and/or an underestimation of the tax amount, with a presentation of the relevant calculations.
{Subclause 39.5.2.17 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.18. In the event of a taxpayer or his representative refusing to sign an act (certificate) on the results of the audit on the taxpayer's compliance with the "arm's length" principle, officials of the controlling body shall draw up an appropriate act certifying the fact of such refusal.
{Subclause 39.5.2.18 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.19. The report (certificate) of the audit on the taxpayer's compliance with the "arm's length" principle must be delivered within two business days from the date of its preparation to the taxpayer in respect of whom the audit was conducted, or to his representative against receipt.
{Subclause 39.5.2.19 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.20. In case of disagreement of the taxpayer or his representative with the conclusions of the audit or the facts and data set out in the act on the results of the audit on the taxpayer's compliance with the "arm's length" principle, they have the right to submit their objections within 30 days from the date of receipt of the act. In this case, the taxpayer has the right to submit documents (certified copies thereof) confirming the validity of the objections together with the objections or within the agreed period.
Such objections shall be considered within 30 business days following the date of their receipt, and a response shall be sent to the taxpayer in accordance with the procedure specified in Article 58 of this Code for sending (delivering) tax notices-decisions.
{Subclause 39.5.2.20 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.5.2.21. Adoption of a tax notice-decision based on the results of an audit on compliance by the taxpayer with the "arm's length" principle shall be carried out in accordance with the procedure provided for in Article 86 of this Code, but not before the expiration of the deadline for the taxpayer to submit objections, specified in subparagraph 39.5.2.20 of this paragraph.
{Subclause 39.5.2.21 of subparagraph 39.5.2 of clause 39.5 of Article 39 as amended by Laws No. 609-VIII of 07/15/2015 , No. 1797-VIII of 12/21/2016 }
39.5.2.22. Appeals against tax notices-decisions adopted based on the results of an audit of compliance by the taxpayer with the "arm's length" principle shall be made in accordance with Article 56 of this Code.
{Subclause 39.5.2.22 of Subclause 39.5.2 of Clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.2.23 of subparagraph 39.5.2 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
39.5.3. Sources of information used to establish whether the terms of a controlled transaction comply with the arm's length principle
39.5.3.1. The taxpayer and the regulatory authority shall use information sources that contain information that allows for comparison of commercial and financial terms of transactions in accordance with subparagraph 39.2.2 of paragraph 39.2 of this article, in particular:
{Paragraph one of subparagraph 39.5.3.1 of subparagraph 39.5.3 of paragraph 39.5 of Article 39 as amended by Law No. 609-VIII of 15.07.2015 }
a) information on comparable uncontrolled transactions of the taxpayer, as well as information on comparable uncontrolled transactions of its counterparty - the party to the controlled transaction with unrelated persons;
{Paragraph two of subparagraph 39.5.3.1 of subparagraph 39.5.3 of paragraph 39.5 of Article 39 as amended by Law No. 609-VIII of 15.07.2015 }
b) any information sources containing open information and providing information on comparable transactions and persons;
{Subparagraph "b" of subparagraph 39.5.3.1 of subparagraph 39.5.3 of paragraph 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
c) other sources of information from which the information was obtained by the taxpayer in compliance with the requirements of the law and which provide information on comparable transactions and persons, provided that the taxpayer provides such information to the supervisory authority;
{Subclause 39.5.3.1 of subparagraph 39.5.3 of clause 39.5 of Article 39 is supplemented by subparagraph "d" in accordance with Law No. 1797-VIII of 21.12.2016 }
d) information received by the supervisory authority within the framework of international agreements concluded by Ukraine.
{Subclause 39.5.3.1 of subparagraph 39.5.3 of clause 39.5 of Article 39 is supplemented by subparagraph "d" in accordance with Law No. 1797-VIII of 21.12.2016 }
39.5.3.2. If the taxpayer, in order to establish the compliance of the terms of the controlled transaction with the "arm's length" principle using the methods specified in clause 39.3 of this Article, used the sources of information provided for in subclause 39.5.3.1 of subclause 39.5.3 of this clause, the controlling body shall use the same sources of information, unless it is proven that other sources of information provide a higher level of comparability of the commercial and financial terms of the transactions.
39.5.3.3. To compare the conditions of controlled transactions with the conditions of uncontrolled transactions for taxation purposes, the regulatory authority shall not have the right to use information that is not publicly available (in particular, information that is accessible only to state authorities).
The requirements of this subparagraph do not apply to tax information obtained by the supervisory authority during an inspection of the taxpayer's compliance with the arm's length principle in accordance with subparagraph 39.5.2.13 of subparagraph 39.5.2 of this subparagraph.
{Subclause 39.5.3.3 of subparagraph 39.5.3 of clause 39.5 of Article 39 is supplemented by the second paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
39.5.4. Self-adjustment
39.5.4.1. In the event that a taxpayer applies conditions during the implementation of controlled transactions that do not comply with the "arm's length" principle and/or do not meet a reasonable economic reason (business purpose), the taxpayer has the right to independently adjust the price of the controlled transaction and the amounts of tax liabilities, provided that this does not lead to a decrease in the amount of tax payable to the budget:
{Paragraph one of subparagraph 39.5.4.1, subparagraph 39.5.4, paragraph 39.5 of Article 39 as amended by Law No. 466-IX of 16.01.2020 }
having calculated your tax obligations according to:
{Subclause 39.5.4.1 of subparagraph 39.5.4 of clause 39.5 of Article 39 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
the maximum value of the price range (profitability), if the price/profitability indicator of the controlled transaction was above the maximum value of the price range (profitability); and/or
{Subclause 39.5.4.1 of subparagraph 39.5.4 of clause 39.5 of Article 39 is supplemented by the third paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
the minimum value of the price range (profitability), if the price/profitability indicator of the controlled transaction was below the minimum value of the price range (profitability).
{Subclause 39.5.4.1 of subparagraph 39.5.4 of clause 39.5 of Article 39 is supplemented by the fourth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
39.5.4.2. An independent adjustment is an adjustment by the taxpayer to the price of a controlled transaction, as a result of which the calculated price complies with the arm's length principle, even if such price differs from the actual price established during the performance of the controlled transaction.
The amount of tax liability calculated based on the results of self-adjustment shall be payable within the terms specified in Article 57 of this Code.
{Subclause 39.5.4.2 of subparagraph 39.5.4 of clause 39.5 of Article 39 is supplemented by the second paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
39.5.4.3. The taxpayer does not have the right to independently adjust the price of controlled transactions and/or the amounts of tax liabilities during the audit of the taxpayer on compliance with the "arm's length" principle of such controlled transactions.
{Subclause 39.5.4 of clause 39.5 of Article 39 is supplemented by subparagraph 39.5.4.3 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
39.5.5. Proportional adjustment
39.5.5.1. For the purposes of this Article, proportional adjustment means the right of one party to a controlled transaction to adjust its tax liabilities based on the results of the adjustment of the tax liabilities of the other party to the controlled transaction based on conditions that comply with the "arm's length" principle.
{Subclause 39.5.5.1 of subparagraph 39.5.5 of clause 39.5 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.2 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
39.5.5.2. The right to apply for a proportional adjustment arises for a taxpayer based on the current international treaty of Ukraine on the avoidance of double taxation after receiving from a related party - a party to a controlled transaction who is a resident of the state with which the relevant international treaty was concluded - a notification about the actual adjustment of tax liabilities by this person based on conditions that comply with the "arm's length" principle.
Based on the received notification, the taxpayer has the right to apply to the regulatory authority with a statement of intention to make a proportional adjustment in the reporting period or periods during which such controlled transactions were carried out. The statement shall be accompanied by a calculation of the amount of the proportional adjustment for each reporting period, other documents that served as the basis for the adjustment by the other party to the controlled transaction, and transfer pricing documentation.
The supervisory authority shall consider the taxpayer's application within 30 working days from the date of its receipt and, based on the results of the consideration, shall make one of the following decisions:
send a notification about the possibility of making a proportional adjustment;
to fully or partially refuse to make a proportional adjustment in the event that such adjustment is unfounded or the necessary documents are missing - with the obligatory justification of the reasons for such refusal to the taxpayer;
to appoint an inspection of the taxpayer's compliance with the "arm's length" principle to examine the grounds for making a proportional adjustment. The inspection shall be carried out in accordance with the procedure specified in subparagraph 39.5.2 of this Article. Based on the results of the inspection, the supervisory authority shall decide on the possibility of making a proportional adjustment or a full or partial refusal to make a proportional adjustment.
{Subclause 39.5.5.2 is included in subclause 39.5.5 of clause 39.5 of Article 39 in accordance with Law No. 466-IX of 16.01.2020 }
{Subclause 39.5.5.3 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
39.5.5.3. In the event of a full or partial refusal by the controlling body to make a proportional adjustment, the taxpayer has the right to apply to the central executive body that ensures the formation and implementation of state financial policy for consideration of the case under the mutual agreement procedure in accordance with international treaties of Ukraine on the elimination of double taxation.
{Subclause 39.5.5.3 is included in subclause 39.5.5 of clause 39.5 of article 39 in accordance with Law No. 466-IX of 16.01.2020 }
{Subclause 39.5.5.4 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.5 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.6 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.7 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.8 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.9 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.10 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Subclause 39.5.5.11 of subparagraph 39.5.5 of clause 39.5 of Article 39 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
39.6. Pre-agreement on pricing in controlled transactions
{Paragraph one of clause 39.6 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
39.6.1. A large taxpayer has the right to apply to the central executive body implementing state tax policy with a statement for preliminary coordination of pricing in controlled transactions.
{Paragraph one of subparagraph 39.6.1 of paragraph 39.6 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
Pre-agreement of pricing in controlled transactions is a procedure between a large taxpayer and the central executive body implementing state tax policy, during which criteria are agreed to determine whether the terms of controlled transactions carried out or to be carried out by a large taxpayer comply with the arm's length principle on the basis of a limited-term contract.
{Paragraph two of subparagraph 39.6.1 of paragraph 39.6 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
39.6.1.1. The subject of prior pricing agreement may include, in particular, but not exclusively:
{Paragraph one of subparagraph 39.6.1.1 of subparagraph 39.6.1 of paragraph 39.6 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 }
types and/or list of goods (works, services) that are the subject of controlled transactions;
methods or combination of methods for establishing compliance of the controlled transaction conditions with the arm's length principle;
a list of sources of information that are intended to be used to establish compliance of the conditions of controlled transactions with the arm's length principle;
the period for which prices in controlled transactions are agreed;
permissible deviation from the established level of economic conditions for the implementation of controlled operations;
procedure, deadlines for submission and a list of documents confirming compliance with agreed prices in controlled transactions.
39.6.1.2. Other terms of prior pricing agreement in controlled transactions shall be determined by agreement of the parties.
{Subclause 39.6.1.2 of subparagraph 39.6.1 of clause 39.6 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
39.6.2. Based on the results of preliminary pricing agreement in controlled transactions, an agreement is concluded, which is signed by the head of the large taxpayer or his authorized person and the head (deputy head) of the central executive body implementing state tax policy.
{Paragraph one of subparagraph 39.6.2 of paragraph 39.6 of Article 39 as amended by Law No. 2245-VIII of 07.12.2017 }
39.6.2.1. An agreement concluded based on the results of preliminary pricing agreement in controlled transactions between a large taxpayer and the central executive body implementing state tax policy is unilateral in nature.
{Subclause 39.6.2.1 of subparagraph 39.6.2 of clause 39.6 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
39.6.2.2. In the event of involvement in the procedure for preliminary pricing agreement in controlled transactions of a foreign state body authorized to administer taxes and fees in the state of which the party to the controlled transaction is a resident (provided that there is an international agreement (convention) on the avoidance of double taxation between Ukraine and such a state), the agreement concluded as a result of such agreement between the large taxpayer and the central executive body implementing state tax policy is bilateral in nature.
In the event that two or more state bodies authorized to administer taxes and fees in the state of which the party(ies) to the controlled transaction is a resident are involved in the procedure for preliminary pricing coordination (provided that there are international agreements (conventions) on the avoidance of double taxation between Ukraine and such states), the agreement concluded as a result of such coordination between the large taxpayer and the central executive body implementing state tax policy is multilateral in nature.
{Subclause 39.6.2.2 of subparagraph 39.6.2 of clause 39.6 of Article 39 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
{Subclause 39.6.2.3 of subparagraph 39.6.2 of clause 39.6 of Article 39 was excluded on the basis of Law No. 2245-VIII of 07.12.2017 }
39.6.2.4. The procedure for preliminary coordination of pricing in controlled transactions , the results of which lead to the conclusion of contracts of a unilateral, bilateral and multilateral nature, shall be approved by the Cabinet of Ministers of Ukraine.
The said procedure shall include, in particular, but not exclusively:
the procedure for submitting and considering an application for conducting a procedure for preliminary pricing coordination in controlled transactions;
a list of documents, the submission of which is necessary for the procedure of preliminary pricing agreement in controlled transactions;
grounds for amending the current contract concluded based on the results of preliminary pricing agreement in controlled transactions, extending its term or terminating it early;
grounds for terminating the procedure for preliminary pricing agreement;
grounds for terminating or extending the term of the agreement on preliminary pricing agreement.
{Subclause 39.6.2.4 of subparagraph 39.6.2 of clause 39.6 of Article 39 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 2245-VIII of 12/07/2017 }
39.6.2.5. In case of compliance with the terms of the agreement on preliminary pricing in controlled transactions, the regulatory authorities do not have the right to make decisions on additional tax liabilities, fines, penalties in relation to controlled transactions that are the subject of such an agreement.
In case of non-compliance with the terms of the agreement on pricing coordination by the taxpayer, such agreement shall cease to be valid from the date of its entry into force. Controlling authorities have the right to make decisions on additional tax liabilities, fines, penalties in respect of controlled transactions that are the subject of such agreement, the terms of which do not comply with the "arm's length" principle.
{Subclause 39.6.2 of clause 39.6 of Article 39 is supplemented by subparagraph 39.6.2.5 in accordance with Law No. 2245-VIII of 07.12.2017 }
39.6.2.6. An agreement concluded based on the results of preliminary pricing agreement in controlled transactions shall enter into force on the date agreed upon by the central executive body implementing state tax policy and the large taxpayer, depending on the circumstances and specifics of the controlled transactions that are the subject of such agreement.
By agreement of the parties, the validity of an agreement concluded based on the results of a preliminary agreement on pricing in controlled transactions may be extended to the entire reporting period in which such an agreement is concluded and/or to reporting periods preceding the entry into force of such an agreement.
{Subclause 39.6.2 of clause 39.6 of Article 39 is supplemented by subparagraph 39.6.2.6 in accordance with Law No. 2245-VIII of 07.12.2017 }
39.6.2.7. In the event that a large taxpayer complies with the terms of an agreement concluded based on the results of a preliminary agreement on pricing in controlled transactions, and provided that the agreed criteria for determining the compliance of the terms of controlled transactions that are the subject of the agreement with the arm's length principle remain unchanged, the validity of such an agreement may be extended for a period agreed upon by the parties.
{Subclause 39.6.2 of clause 39.6 of Article 39 is supplemented by subparagraph 39.6.2.7 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 2628-VIII of 23.11.2018 }
39.6.3. Stability of the terms of the contract concluded based on the results of preliminary pricing agreement in controlled transactions:
39.6.3.1. The terms of an agreement concluded based on the results of preliminary pricing agreement in controlled transactions shall remain unchanged in the event of a change in tax legislation in terms of regulating relations arising from the conclusion of such an agreement, amendments to it, termination of its validity, or loss by the taxpayer of the status of a large taxpayer.
39.6.3.2. In the event of amendments to tax legislation affecting the activities of a large taxpayer and/or the criteria for determining whether the terms of controlled transactions comply with the arm's length principle, the parties to the agreement concluded based on the results of preliminary pricing agreement in controlled transactions have the right to make appropriate amendments to its text.
In the event of disagreement between one of the parties with the proposed changes, the contract shall be terminated.
{Clause 39.6 of Article 39 is supplemented by subparagraph 39.6.3 in accordance with Law No. 2245-VIII of 07.12.2017 }
{Article 39 as amended by Laws No. 3610-VI of 07.07.2011 , No. 4915-VI of 07.06.2012 , No. 5083-VI of 05.07.2012 ; as amended by Law No. 408-VII of 04.07.2013 ; as amended by Laws No. 657-VII of 24.10.2013 , No. 1260-VII of 13.05.2014 ; as amended by Law No. 72-VIII of 28.12.2014 ; text of Article 39 as amended by Law No. 2725-VIII of 16.05.2019 }
Article 39 - 1. Peculiarities of applying exchange rates when calculating customs and tax payments↑
39 - 1 .1. For the purposes of determining tax liabilities for the payment of customs payments (except for the payment of excise tax on tobacco products, liquids used in electronic cigarettes, tobacco raw materials and tobacco waste), the official exchange rate of Ukraine to foreign currency established by the National Bank of Ukraine, valid at 0 o'clock on the day of submission of the customs declaration, and if the customs declaration is not submitted, on the day of determination of tax liabilities, shall be applied.
For the purposes of determining tax liabilities for the payment of taxes and fees, the official exchange rate of the Ukrainian currency to foreign currency established by the National Bank of Ukraine, valid for 0 hours, is applied:
the day of submission by a non-resident of a tax return for the supply of electronic services;
the date of occurrence (determination) of tax liabilities for other payers/transactions/tax liabilities, unless otherwise provided for by this Code.
For the purposes of determining tax liabilities for payment of excise tax on tobacco products, liquids used in electronic cigarettes, tobacco raw materials and tobacco waste, the official exchange rate of Ukraine's currency to foreign currency established by the National Bank of Ukraine, effective at 0:00 on the first day of the calendar half-year preceding the half-year in which:
purchase of excise tax stamps (until October 31, 2026 inclusive);
{Paragraph six of clause 39 - 1 .1 of article 39 - 1 as amended by Law No. 4698-IX of 03.12.2025 - shall apply from January 1, 2026 }
formation of a unique identifier and/or entry into the Electronic System for Circulation of Alcoholic Beverages, Tobacco Products and Liquids Used in Electronic Cigarettes of information about unique identifiers applied in accordance with European Union regulations to tobacco products manufactured in the Member States of the European Union (from November 1, 2026);
{Paragraph seven of clause 39 - 1 .1 of article 39 - 1 as amended by Law No. 4698-IX of 03.12.2025 - shall apply from January 1, 2026 }
sale of tobacco products, liquids used in electronic cigarettes produced in the customs territory of Ukraine, or submission of a customs declaration when importing tobacco products, liquids used in electronic cigarettes into the customs territory of Ukraine;
calculation of excise tax liabilities on tobacco raw materials and tobacco waste in accordance with the provisions of this Code.
When determining the minimum excise tax liability for payment of excise tax on tobacco products for the purposes of determining the retail price of excisable goods in accordance with subparagraph 14.1.106 of paragraph 14.1 of Article 14 of this Code, the official exchange rate of the currency of Ukraine to foreign currency established by the National Bank of Ukraine, which was in effect at 0 o'clock on the first day of the calendar half-year preceding the half-year in which the relevant tobacco products were produced, shall be applied.
{Chapter I supplemented by Article 39 - 1 in accordance with Law No. 1200-VII of 10.04.2014 ; as amended by Laws No. 1525-IX of 03.06.2021 , No. 4115-IX of 04.12.2024 }
39 - 2.1 . Definition of a controlled foreign company
39 - 2 .1.1. A controlled foreign company is any legal entity registered in a foreign state or territory that is recognized as being under the control of an individual resident of Ukraine or a legal entity resident of Ukraine in accordance with the rules specified in this Code.
A legal entity may be recognized as a corporate entity (association) or an organization authorized to own assets, have rights and obligations, and carry out activities in its own name and independently of the founders, participants, or form of ownership. The presence of the status of a legal entity in a controlled foreign company is recognized in accordance with the legislation of its registration.
In the cases provided for in this article, a foreign entity without the status of a legal entity may be equated to a controlled foreign company.
An entity without the status of a legal entity is an entity established on the basis of a transaction or registered in accordance with the legislation of a foreign state (territory) without the creation of a legal entity, which, in accordance with the legislation and/or documents regulating its activities (personal law), has the right to carry out activities aimed at generating income (profit) in the interests of its participants, partners, founders, trustees or other beneficiaries.
Entities without legal entity status may include, in particular, but not exclusively, partnerships, trusts, foundations, other institutions and organizations established on the basis of a transaction or law of a foreign state (territory). Entities without legal entity status shall be deemed to include non-resident persons whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraphs 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, which are not legal entities under personal law.
{Paragraph five of subparagraph 39 - 2 .1.1 of paragraph 39 - 2 .1 of Article 39 - 2 as amended by Law No. 3813-IX of 18.06.2024 }
39 - 2 .1.2. Taking into account the provisions of this article, a controlling person is an individual or legal entity - residents of Ukraine, who are direct or indirect owners (controllers) of a controlled foreign company.
In particular, a foreign company is recognized as a controlled foreign company if an individual resident of Ukraine or a legal entity resident of Ukraine (hereinafter referred to as the controlling entity):
a) owns a stake in a foreign legal entity of more than 50 percent, or
b) owns a stake in a foreign legal entity in the amount of more than 10 percent, provided that several individuals - residents of Ukraine and/or legal entities - residents of Ukraine own shares in a foreign legal entity, the size of which in aggregate is 50 percent or more, or
c) individually or together with other residents of Ukraine - related persons - exercises actual control over a foreign legal entity.
An individual resident of Ukraine or a legal entity resident of Ukraine shall not be recognized as a controlling entity if their ownership of a share in a controlled foreign company is realized through direct or indirect ownership in another legal entity resident of Ukraine, provided that the latter is recognized as a controlling entity in accordance with this paragraph and is subject to the obligation to tax the adjusted profit of the controlled foreign company.
39 - 2 .1.3. A share in a foreign legal entity means corporate rights, rights in an entity without the status of a legal entity, the assets of which include a share in a legal entity, or any other similar rights and/or powers that grant an individual or legal entity the right to:
a) influence on the relevant share of votes in the highest management body of a foreign legal entity (general meeting of shareholders, participants or other similar body), and/or
b) to receive the relevant part of the profit of a foreign legal entity, and/or
c) blocking the decision on the distribution of part of the profit of a foreign legal entity, and/or
d) to receive the relevant part of the assets of a foreign legal entity in the event of its liquidation or termination.
If, in accordance with the size of the share due to an individual, the amounts of rights provided for in subparagraphs "a" - "c" of this subparagraph are different, for the purposes of this Code, the largest value of such share shall be accepted.
39 - 2 .1.4. For the purposes of determining the ownership by an individual or legal entity of a relevant share in a foreign legal entity, all rights belonging to such individual or legal entity shall be considered the sum of shares that:
belong to such an individual or legal entity directly or indirectly through other persons, including through an entity without the status of a legal entity;
owned by any related persons of such individual or legal entity directly or indirectly through other persons.
The size of the share of indirect ownership is calculated:
in the case of ownership through one chain of persons who own shares in each other - by multiplying the shares;
in the case of ownership through several chains of persons who own shares in each other - by summing up the shares in each such chain.
However, for the purposes of calculating indirect ownership, if a person actually owns a stake of more than 50 percent (through one or more chains) in a legal entity in the chain, it is considered that the individual owns a stake in such legal entity of 100 percent.
If a person exercises actual control over the next legal entity in the chain, such person is deemed to own a 100 percent stake in the next legal entity.
A person is considered to own a share in another legal entity if:
possession based on ownership, or
if the ownership of the relevant share legally belongs to other persons acting in the interests of such person.
39 - 2 .1.5. A person is considered to own a share in another legal entity if such person is the founder of a trust, the owner of a share in the property of a fund, institution, other entity without the status of a legal entity, the assets of which include the specified share, or a participant (partner with full or limited liability) of a partnership, the assets of which include a share in a legal entity.
39 - 2 .1.5.1. The founder of a trust, institution, or other entity without the status of a legal entity, whose assets include the specified share in the legal entity, is not considered to own this share if the following conditions are simultaneously met:
a) such a person shall not have the right to directly or indirectly direct the payment in his favor of the profits or income of such an entity without the status of a legal entity;
b) such a person does not have the right to dispose directly or indirectly of the profit or income of such an entity without the status of a legal entity;
c) such a person does not have the right to return to him the property that is part of the assets of the formation without the status of a legal entity (the property was transferred on irrevocable terms). The condition established by this subparagraph is considered fulfilled if the founder of such a formation without the status of a legal entity does not have the right to return the property that is part of the assets of such a formation, both during the existence of such a formation and in the event of its liquidation (termination);
d) such person, acting alone or jointly with other beneficiaries or beneficiaries of such an unincorporated entity, shall not have the right to terminate such an unincorporated entity, in particular, but not exclusively, by liquidation, termination of the trust management agreement;
e) such person does not exercise actual control over an entity without the status of a legal entity, within the meaning of subparagraph 39 - 2 .1.6 of paragraph 39 - 2 .1 of this Article.
39 - 2 .1.5.2. A person who is not the founder of a trust, institution, or unincorporated entity, the assets of which include a person's share in a legal entity, is considered to own this share if at least one of the following conditions is met:
a) such a person has (legally or de facto) the right to demand the accrual and payment of income (profit) of such an entity without the status of a legal entity;
b) such a person has the right (directly or indirectly) to dispose of property that is part of the assets of such an entity without the status of a legal entity;
c) such a person has the right to receive property included in the assets of such an entity without the status of a legal entity in the event of its liquidation (termination), except for cases of receiving property in the event of liquidation (termination) of such an entity without the expression of the will of this person;
d) such person exercises actual control over an entity without the status of a legal entity within the meaning of subparagraph 39 - 2 .1.6 of paragraph 39 - 2 .1 of this Article.
39 - 2 .1.5.3. A person who is the founder of a trust, the owner of a share of the property of a fund, institution, or other entity without the status of a legal entity, together with the notification of the establishment of an entity without the status of a legal entity, has the right to provide confirmation of its compliance with the requirements of subparagraph 39 - 2 .1.5.1, subparagraph 39 - 2 .1.5, paragraph 39 - 2 .1 of this article.
To confirm the compliance of a person who is the founder of a trust, the owner of a share of the property of a fund, institution, or other entity without the status of a legal entity with the requirements of subparagraph 39 - 2 .1.5.1 of subparagraph 39 - 2 .1.5 of paragraph 39 - 2 .1 of this article, such person must provide the following documents:
1) a notification from a person managing and/or controlling a foreign entity without the status of a legal entity (including, but not limited to, a trust manager), which must contain:
a) a statement about the absence of the rights specified in subparagraph 39 - 2 .1.5.1 of subparagraph 39 - 2 .1.5 of paragraph 39 - 2 .1 of this article, of the founder in accordance with the contract and/or personal law, and/or constituent documents of such a foreign entity without the status of a legal entity;
b) a statement about the regulation and/or licensing of the person exercising management and/or control of a foreign entity without the status of a legal entity, regarding its management of such entity in accordance with the contract and/or personal law, and/or the constituent documents of such foreign entity or, in the event that such person exercising management and/or control of a foreign entity without the status of a legal entity is not regulated and/or licensed, a statement that it is administered by an administrator regulated and/or licensed in accordance with personal law;
c) a notarized signature of the person exercising management and/or control of a foreign entity without the status of a legal entity, and if such an entity is not regulated and/or licensed, then a notarized signature of the administrator of such an entity that is regulated and/or licensed in accordance with personal law. The document must be duly legalized in accordance with the requirements of the current legislation of Ukraine; or
2) an extract from the trust agreement in the form of information regarding the name of the trust founder, trust manager, protector (if appointed), beneficiary(ies) (if appointed) and the information specified in subparagraph 39 - 2 .1.5.1 of subparagraph 39 - 2 .1.5 of paragraph 39 - 2 .1 of this article, under the notarized signature of the person exercising management and/or control of the foreign entity without the status of a legal entity, and if such person is not regulated and/or licensed, then under the notarized signature of the administrator of such person, which is regulated and/or licensed in accordance with personal law. The extract must be duly legalized in accordance with the requirements of the legislation of Ukraine; or
3) a legal opinion addressed to the founder, under the legislation of the country of establishment of the discretionary irrevocable trust, confirming the information specified in subparagraph 39 - 2 .1.5.1 of subparagraph 39 - 2 .1.5 of paragraph 39 - 2 .1 of this Article, provided by a law firm or other person entitled to provide legal or advocacy services, the activities of which are subject to mandatory licensing or regulation in accordance with personal law. The signatures of the persons must be notarized and the document must be duly legalized in accordance with the requirements of the legislation of Ukraine.
A person who manages and/or controls a foreign entity without the status of a legal entity shall annually provide the founder with written confirmation of the founder's compliance with the conditions provided for in subparagraph 39 - 2 .1.5.1 of subparagraph 39 - 2 .1.5 of paragraph 39 - 2 .1 of this article.
In the future, such written confirmation is not sent to the regulatory authority, but must be provided by the person who is the founder of the trust, the owner of a share of the property of the fund, institution, or other entity without the status of a legal entity, to the regulatory authority at its request in accordance with the procedure established by the central executive authority that ensures the formation and implementation of state financial policy.
The responsibility to prove the founder's non-compliance with the conditions stipulated in this subparagraph lies with the regulatory authority.
39 - 2 .1.6. A person is considered to exercise actual control over a legal entity if such person has the ability to exercise significant or decisive influence on the decisions of such legal entity regarding the conclusion of agreements, disposal of assets and profits, and termination of activities, regardless of the legal form of such influence.
For the purposes of this Article, effective control shall be established on the basis of, in particular, but not exclusively, at least one of the following circumstances:
a) provision by a person of binding instructions to the management bodies of a legal entity;
b) conducting negotiations by a person regarding the conclusion of transactions by a legal entity and agreeing on the essential terms of such transactions, which are subsequently only formally approved by the management bodies of the legal entity or are executed by the management bodies of the legal entity without further additional approval;
c) the person has a power of attorney to carry out material transactions on behalf of a legal entity, issued for a period of more than one year and does not require prior approval of such transactions by the management bodies of the legal entity;
d) the person's performance of transactions on the bank accounts of a legal entity or the possibility of blocking transactions on such accounts;
e) designation of a person as the founder (beneficiary, actual beneficiary) of a legal entity when opening accounts by such a legal entity, except in cases where the assets of such a legal entity are part of the assets of a trust, fund, institution, or other entity without the status of a legal entity, the founder (beneficiary, actual beneficiary) of which is such a person.
For the purposes of applying this article, the exercise of actual control over a foreign entity without the status of a legal entity shall be deemed to be the exercise or possibility of exercising decisive influence on the decisions of the person or persons managing the assets of such entity, the adoption of decisions or the possibility of making decisions on the replacement of persons managing the assets of such entity, as well as the exercise or possibility of exercising decisive influence on decisions on the distribution of profits in accordance with the personal law and/or constituent documents of such entity.
The provisions of this subparagraph shall not apply to an individual who performs the duties of a director or other official of a legal entity in accordance with its statutory documents, and/or to specialists in the field of law, auditing, accounting, trust management of property, who act for the benefit and in the interests of such a legal entity in compliance with appropriate professional standards (in particular, but not exclusively, lawyers, auditors, trust managers, protectors, guarantors, enforcers, fund managers, insurers). If the persons specified in this paragraph act for the benefit and in the interests of an individual, while carrying out the mandatory instructions of such an individual, it is considered that such an individual exercises actual control over the legal entity.
In the event of the assessment of personal income tax liabilities and/or penalties based on the recognition by the regulatory authority of an individual as exercising actual control over a legal entity, the individual has the right to appeal such a decision in the administrative or judicial procedure provided for by this Code. In this case, the obligation to prove that the individual exercises actual control over the legal entity shall lie with the regulatory authority.
39 - 2 .2. Taxation of profits of a controlled foreign company
39 - 2 .2.1. The taxpayer of the profit of a controlled foreign company is the controlling entity.
If one individual or legal entity owns or controls a stake of 25 percent or more in a controlled foreign company together with other individuals and/or legal entities, and none of the individuals independently determines itself to be the controlling entity in respect of such stake in full, it is considered that all of the aforementioned individuals are controlling entities for the controlled foreign company in equal shares (regardless of whether the size of the stake of each of them reaches 25 percent).
39 - 2 .2.2. The object of taxation for the personal income tax (corporate income tax) of the controlling entity is a part of the adjusted profit of the controlled foreign company, proportional to the share owned or controlled by such individual (legal entity) on the last day of the relevant reporting period, in respect of which the adjusted profit of the controlled foreign company is calculated, which is calculated in accordance with the rules specified in this article. The specified part of the profit of the controlled foreign company:
is included in the total annual taxable income of the controlling entity in accordance with the procedure specified in Clause 170.13 of Article 170 of this Code, or
based on the results of the reporting tax year, increases the object of taxation by corporate income tax of the controlling entity in accordance with the procedure specified in Section III of this Code.
39 - 2 .2.3. The adjusted profit of a controlled foreign company, which was included in the object of taxation of one controlling entity in the manner prescribed by this Code, cannot be re-included in the object of taxation of another controlling entity or entities.
39 - 2 .3. Procedure for calculating the adjusted profit of a controlled foreign company taxable in Ukraine.
39 - 2 .3.1. For the purposes of this article, adjusted profit of a controlled foreign company shall be recognized as the profit of a controlled foreign company before taxation according to the data of its unconsolidated financial statements prepared for the reporting calendar year (if the reporting year does not correspond to the calendar year - for the periods ending in the relevant calendar year) in accordance with the accounting standards applied by the controlled foreign company and the deadlines for preparing such statements in the relevant foreign jurisdiction.
If the legislation of the foreign jurisdiction of tax residence of the controlled foreign company does not provide for the obligation to prepare financial statements, the controlling person must ensure that the controlled foreign company prepares financial statements in accordance with international financial reporting standards.
If the regulatory authority has doubts about the reliability of the submitted financial statements of a controlled foreign company, the regulatory authority has the right to require the provision of a written opinion of an audit company confirming the financial statements of the controlled foreign company, no earlier than 15 months after the end of the reporting period for which the adjusted profit of the controlled foreign company is calculated.
Such a written opinion must be provided by an audit firm that is authorized to conduct an audit of financial statements in the relevant foreign jurisdiction, and cannot contain an adverse opinion or a disclaimer of opinion.
39 - 2 .3.2. When calculating the adjusted profit of a controlled foreign company, the following features are taken into account:
39 - 2 .3.2.1. the financial result from transactions of a controlled foreign company with securities, other corporate rights, derivatives is calculated taking into account the features provided for in this subparagraph.
If, based on the results of the reporting period, a controlled foreign company has received a negative total financial result from sales or other disposal of securities and/or other corporate rights (the total amount of losses from sales or other disposal of securities and/or other corporate rights, taking into account the amount of the negative financial result from such transactions and/or the negative total result of the revaluation of securities and/or other corporate rights not taken into account in previous tax periods, exceeds the total amount of profits from such transactions), the amount of such negative value of the total financial result from sales or other disposal of securities and/or other corporate rights reduces the total financial result of the controlled foreign company from sales or other disposal of securities and/or other corporate rights of the subsequent tax (reporting) periods following the tax (reporting) period in which the specified negative value of the financial result occurred.
If, based on the results of the reporting period, a controlled foreign company has received a positive total financial result from sales or other disposal of securities and/or other corporate rights (the total amount of profits from sales or other disposal of securities and/or other corporate rights exceeds the total amount of losses from such operations, taking into account the amount of the negative financial result from such operations and/or the negative total result of the revaluation of securities and/or other corporate rights not taken into account in previous tax periods), the amount of the positive total financial result from sales or other disposal of securities and/or other corporate rights increases the financial result before taxation of the tax (reporting) period of the controlled foreign company.
When calculating the adjusted profit of a controlled foreign company, the following are not taken into account:
the amount of the write-down included in the financial result before tax in the current tax (reporting) period for equity instruments reclassified into financial liabilities in accordance with the financial reporting standards applied by the controlled foreign company;
losses from investments in associates, subsidiaries and joint ventures accounted for using the equity method or proportionate consolidation method;
the amount of the negative total result of the revaluation of securities and/or other corporate rights (the total amount of markdowns of securities and/or other corporate rights exceeds the total amount of their revaluations for the tax (reporting) period) (except for government securities or local loan bonds), reflected in the financial result before taxation of the reporting period in accordance with the financial reporting standards applied by the controlled foreign company;
39 - 2 .3.2.2. expenses of a controlled foreign company from the depreciation of non-current assets (fixed assets and intangible assets) are recognized exclusively at the time of sale (disposal) of such non-current assets or in the event of revaluation of such non-current assets within the amount of the revaluation;
39 - 2 .3.2.3. expenses of a controlled foreign company for accrual of interest on debt obligations are taken into account in an amount not exceeding 30 percent of the amount of financial result before taxation, financial expenses and the amount of depreciation deductions of the controlled foreign company according to the financial statements of the reporting (tax) period in which such interest is accrued.
The provisions of the first paragraph of this subparagraph shall not apply:
{Subclause 39 - 2 .3.2.3 of subparagraph 39 - 2 .3.2 of clause 39 - 2 .3 of article 39 - 2 is supplemented with a new paragraph in accordance with Law No. 3706-IX of 09.05.2024 }
a) to the part of the interest expenses of a controlled foreign company that are higher than the level of expenses calculated on an arm's length basis in accordance with the rules established by Article 39 of this Code. Such expenses shall be taken into account when calculating the adjusted profit of a controlled foreign company, taking into account subparagraph 39 - 2 .3.2.4 of this paragraph. In such a case, the provisions of the first paragraph of this subparagraph shall apply to the part of the interest expenses that comply with the arm's length principle;
{Subclause 39 - 2 .3.2.3 of subparagraph 39 - 2 .3.2 of clause 39 - 2 .3 of article 39 - 2 is supplemented with a new paragraph in accordance with Law No. 3706-IX of 09.05.2024 }
b) to the part of the interest expenses of a controlled foreign company on the amount of a credit (loan) obtained by placing foreign debt securities on a foreign organized stock market (stock exchange) included in the list approved by the Cabinet of Ministers of Ukraine, or from an unrelated person, for the purpose of providing a credit (loan) by a controlled foreign company to a related person - a resident of Ukraine, provided that the difference between the rate of providing a credit (loan) by a controlled foreign company to a related person - a resident of Ukraine and the lending (borrowing) rate at which the controlled foreign company received the relevant credit (loan) does not exceed 50 basis points.
{Subclause 39 - 2 .3.2.3 of subparagraph 39 - 2 .3.2 of clause 39 - 2 .3 of article 39 - 2 is supplemented with a new paragraph in accordance with Law No. 3706-IX of 09.05.2024 }
When calculating the adjusted profit of a controlled foreign company, expenses for the formation of reserves for doubtful debts, other receivables, as well as income from the liquidation of the aforementioned reserves are not taken into account.
The costs of writing off bad debts are taken into account only if such debts meet the criteria provided for in subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code;
39 - 2 .3.2.4. income and expenses of a controlled foreign company on transactions with non-residents - related persons, non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, as well as with non-residents whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, are determined in compliance with the "arm's length" principle.
{Paragraph one of subparagraph 39 - 2 .3.2.4 of subparagraph 39 - 2 .3.2 of paragraph 39 - 2 .3 of paragraph 39 - 2 .3 of Article 39 - 2 as amended by Law No. 3813-IX of 18.06.2024 }
If the income of a controlled foreign company from such transactions is lower than the income calculated on an arm's length basis in accordance with the rules established by Article 39 of this Code, the income of the controlled foreign company shall be increased by such difference. If the counterparty of the controlled foreign company in the performance of the said transactions was another controlled foreign company, such other controlled foreign company shall have the right to a proportional adjustment of the financial result from such transaction by such difference in the downward direction.
If the costs of a controlled foreign company for such transactions are higher than the costs calculated on an arm's length basis in accordance with the rules established by Article 39 of this Code, the adjusted profit of the controlled foreign company shall be increased by such difference. If the counterparty of the controlled foreign company in the performance of the said transactions was another controlled foreign company, such other controlled foreign company shall have the right to a proportional adjustment of the financial result for such transaction by such difference in the downward direction.
The supervisory authority may require the controlling entity to provide transfer pricing documentation regarding the transactions of a controlled foreign company with any person specified in this subparagraph, if the total volume of transactions of the controlled foreign company with such person exceeds UAH 10 million per calendar year, and the total revenue of such controlled foreign company exceeds UAH 150 million per calendar year. The controlling entity shall, within 60 calendar days from the date of receipt of such a request, be obliged to provide, at its own option, transfer pricing documentation prepared in accordance with the requirements of Article 39 of this Code, or transfer pricing documentation prepared in accordance with the requirements of the legislation of the foreign state (territory) in which the controlled foreign company is registered, with a translation of such documentation into Ukrainian.
{Paragraph four of subparagraph 39 - 2 .3.2.4 of subparagraph 39 - 2 .3.2 of paragraph 39 - 2 .3 of Article 39 - 2 as amended by Law No. 3706-IX of 09.05.2024 }
If the controlling entity does not submit transfer pricing documentation, the controlling authority increases the amount of the controlled foreign company's pre-tax profit by 30 percent of the value of income or expenses for which transfer pricing documentation and/or copies of primary documents were not submitted.
If the regulatory authority establishes that the submitted transfer pricing documentation does not comply with the requirements of Article 39 of this Code, the regulatory authority has the right to independently determine the amount of income and expenses of the controlled foreign company from such transactions in accordance with the requirements of Article 39 of this Code and accordingly increase the amount of profit of the controlled foreign company before taxation.
The report on controlled foreign companies shall reflect a list of transactions with non-residents - related persons, non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, as well as with non-residents whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code;
{Paragraph seven of subparagraph 39 - 2 .3.2.4 of subparagraph 39 - 2 .3.2 of paragraph 39 - 2 .3 of paragraph 39 - 2 .3 of Article 39 - 2 as amended by Law No. 3813-IX of 18.06.2024 }
39 - 2 .3.2.5. if a controlled foreign company owns a share in another foreign legal entity that is recognized as a controlled foreign company for the same controlling entity, the adjusted profit of the first controlled foreign company is reduced by the amount of accrued income from participation in the capital of the other controlled foreign company and by the amount of accrued income in the form of dividends paid or payable to the first company from the second company in which it owns a share.
For the purposes of this Article, the term "dividends" is used in the meaning defined by the financial reporting standards applied in the preparation of the financial statements of a controlled foreign company whose profit is subject to reduction under the rules of this subparagraph;
39 - 2 .3.2.6. if a controlled foreign company directly or indirectly receives income through a permanent establishment in the territory of Ukraine, the adjusted profit of the controlled foreign company is subject to adjustment by reduction by the amount of profit received through such permanent establishment;
39 - 2 .3.2.7. if a controlled foreign company directly or indirectly owns shares in legal entities registered in Ukraine, the adjusted profit of such controlled foreign company is reduced by the amount of accrued income from participation in the capital of such legal entities registered in Ukraine and by the amount of accrued income in the form of dividends paid or payable to the controlled foreign company from a legal entity registered in Ukraine.
39 - 2 .3.3. The adjusted profit of each controlled foreign company is determined separately. If the adjusted profit of a controlled foreign company for the reporting year is negative, such loss does not reduce the profit before tax of other controlled foreign companies for the reporting year, but may be taken into account in reducing the profit before tax of the same controlled foreign company in future reporting years.
39 - 2 .3.4. Adjusted profit of a controlled foreign company, determined in foreign currency, is subject to conversion into hryvnia at the weighted average official exchange rate of the National Bank of Ukraine for the reporting (tax) period.
39 - 2 .3.5. The controlling entity independently calculates the adjusted profit of each controlled foreign company based on the financial statements of the controlled foreign company using the features established by subparagraph 39 - 2 .3.2 of this paragraph, and determines the share of the adjusted profit subject to taxation in Ukraine in proportion to the share in this controlled foreign company that it owns.
39 - 2 .3.6. If the income (profit) of a controlled foreign company before taxation according to the financial statements is subsequently adjusted by the controlling authorities of the jurisdiction of the actual location (registration) of the controlled foreign company, the controlling person is obliged to recalculate the adjusted profit subject to taxation in Ukraine and submit a clarifying tax return without applying any financial sanctions provided for by this Code.
The controlling body has the right to send a request to the controlling person to provide documentary confirmation of the facts of adjustment by the controlling bodies of the jurisdiction of the actual location (registration) of a controlled foreign company to the income (profit) of such a controlled foreign company. The taxpayer is obliged to provide duly certified copies of the documents within 15 business days from the date of receipt of the request.
39 - 2 .3.7. If, during the inspection, the regulatory authority establishes that the controlling person has calculated the adjusted profit of the controlled foreign company in violation of the requirements of this article, the regulatory authority shall independently recalculate the adjusted profit of the controlled foreign company in accordance with the requirements of this article.
39 - 2 .4. Exemption from taxation of profits of a controlled foreign company
39 - 2 .4.1. The adjusted profit of a controlled foreign company is not subject to inclusion in the total taxable income, is not subject to corporate income tax of the controlling entity if the following conditions are met:
a) there is a valid agreement between Ukraine and the foreign jurisdiction of the location (registration) of the controlled foreign company on the avoidance of double taxation or on the exchange of tax information and
b) any of the following conditions is met:
the controlled foreign company actually pays income tax at an effective rate that is not less than the basic (basic) rate of corporate income tax in Ukraine, determined by clause 136.1 of Article 136 of this Code, or is less than such rate by no more than five percentage points, or
the share of passive income of a controlled foreign company does not exceed 50 percent of the total income of the controlled foreign company from all sources.
If the share of passive income of a controlled foreign company is more than 50 percent of the total amount of income of the controlled foreign company from all sources, for the purposes of applying this article, such income shall be recognized as active, provided that the controlled foreign company:
actually performs essential functions, bears risks and uses assets in transactions that result in the receipt of relevant active income;
has the necessary resources to perform the specified functions, manage risks and use assets (qualified personnel, fixed assets owned or used, sufficient equity, etc.).
For the purposes of this article, the effective corporate income tax rate is calculated by dividing the amount of corporate income tax expenses by the amount of profit before tax according to the financial statements for the relevant calendar year and multiplying by 100 percent.
39 - 2 .4.2. Regardless of the fulfillment of the conditions stipulated in subparagraph 39 - 2 .4.1 of paragraph 39 - 2 .4 of this article, the adjusted profit of a controlled foreign company shall not be included in the total taxable income and shall not be subject to corporate income tax of the controlling entity if any of the following conditions are met:
39 - 2 .4.2.1. the total aggregate income of all controlled foreign companies of one controlling person from all sources according to financial statements does not exceed the equivalent of 2 million euros at the end of the reporting period;
39 - 2 .4.2.2. a controlled foreign company is a public company, the shares (units) of which are traded on a recognized stock exchange. The list of exchanges and the requirements for recognizing shares (units) of public companies as being traded on the specified stock exchange shall be established by the Cabinet of Ministers of Ukraine.
Such exemption shall apply to all controlled foreign companies included in the consolidated financial statements of such public controlled foreign company, as well as to other foreign companies related to the public controlled foreign company in respect of dividends originating from such public controlled foreign company.
If a controlled foreign company to which such an exemption applies pays dividends to a controlled foreign company that is not a public company, such dividends shall be included in the calculation of the adjusted profit of such controlled foreign company on a general basis;
39 - 2 .4.2.3. a controlled foreign company is an organization that, in accordance with the legislation of the relevant foreign jurisdiction, carries out charitable activities and does not distribute income to the benefit of its founders (participants).
39 - 2 .4.3. If the profit of a controlled foreign company is exempt from taxation in accordance with the provisions of this clause, the controlling person is exempt from the obligation to calculate the adjusted profit of the controlled foreign company in accordance with the provisions of subclause 39 - 2 .3.2 of this Code.
39 - 2 .4.4. The controlling entity has the right to voluntarily waive the exemption from taxation of the profit of a controlled foreign company in accordance with the provisions of subparagraph 39 - 2 .4.1 or 39 - 2 .4.2 of this Code and to make a decision on taxation of the profit of a controlled foreign company by submitting a relevant application in any form simultaneously with the submission of a report on controlled foreign companies.
39 - 2 .5. Preparation and submission of a report on controlled foreign companies and notifications of acquisition or termination of participation in controlled foreign companies
39 - 2 .5.1. For the purposes of tax control over the taxation of the profit of a controlled foreign company, the reporting (tax) period is the calendar year or another reporting period of the controlled foreign company ending during the calendar year.
39 - 2 .5.2. Controlling persons are obliged to submit a report on controlled foreign companies to the controlling body simultaneously with the submission of the annual declaration on property status and income or tax declaration on corporate income tax for the relevant calendar year by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services ".
{Paragraph one of subparagraph 39 - 2 .5.2 of paragraph 39 - 2 .5 of Article 39 - 2 as amended by Law No. 2918-IX of 07.02.2023 }
The report on controlled foreign companies must be accompanied by duly certified copies of the financial statements of the controlled foreign company, confirming the amount of profit of the controlled foreign company for the reporting (tax) year. If the deadlines for preparing financial statements in the relevant foreign jurisdiction expire later than the deadlines for submitting the annual declaration of property status and income or the corporate income tax return , such copies of the financial statements of the controlled foreign company shall be submitted together with the annual declaration of property status and income or the corporate income tax return for the following reporting (tax) period.
39 - 2 .5.3. The report on controlled foreign companies shall indicate:
a) name of the controlled foreign company, its address, legal form, tax registration numbers (if any), state registration numbers;
b) the size of the share held by the controlling entity in the controlled foreign company;
c) the structure of ownership of a share in a controlled foreign company in the case of indirect ownership of such a share;
d) information on the amount of income (revenue) from the sale of goods (works, services) of a controlled foreign company, profit from operating activities and profit before tax in accordance with financial reporting data;
e) calculation of the adjusted profit of a controlled foreign company in accordance with the requirements of this article, the amount of such profit that is included in the total taxable income of the controlling entity;
e) information on the grounds for exemption from taxation of the profits of a controlled foreign company in accordance with the provisions of this article;
e) the amount of dividends received by a controlled foreign company directly or indirectly through a chain of controlled legal entities from Ukrainian legal entities;
h) the amounts of profits of a controlled foreign company that were actually paid to the controlling entity;
g) a list of transactions of a controlled foreign company with non-residents - related persons, non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, as well as with non-residents whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code;
{Sub -item "g" of sub -item 39 - 2 .5.3 of item 39 - 2 .5 of article 39 - 2 as amended by Law No. 3813-IX of 18.06.2024 }
h) the number of employees of the controlled foreign company as of the end of the reporting (tax) year;
i) information on the amount of profit of a controlled foreign company received from a permanent establishment in Ukraine.
39 - 2 .5.4. If the controlling person is unable to ensure the preparation of financial statements of a controlled foreign company and/or the calculation of the adjusted profit of a controlled foreign company by the deadline for submitting the annual declaration of property status and income or the corporate income tax return , such a controlling person shall submit a report on controlled foreign companies in an abbreviated form, which contains only the information provided for in subparagraphs "a" - "c" of subparagraph 39 - 2 .5.3 of this paragraph.
The controlling entity is obliged to submit a full report on controlled foreign companies by the end of the calendar year following the reporting (tax) year. If, according to such a report, the total taxable income, the object of taxation by corporate income tax of the controlling entity increases, such entity shall submit a clarifying annual declaration of property status and income or a corporate income tax declaration by the end of the calendar year following the reporting (tax) year . In this case, penalties and/or fines shall not apply.
39 - 2 .5.5. An individual resident of Ukraine or a legal entity resident of Ukraine is obliged to notify the regulatory authority of:
each direct or indirect acquisition of a share in a foreign legal entity or the beginning of the exercise of actual control over a foreign legal entity, which leads to the recognition of such an individual (legal entity) as a controlling entity in accordance with the requirements of this article;
establishment, creation or acquisition of property rights to a share in the assets, income or profits of an entity without the status of a legal entity;
each alienation of a share in a foreign legal entity or termination of actual control over a foreign legal entity, which results in the loss of recognition of such an individual (legal entity) as a controlling entity in accordance with the requirements of this article;
liquidation or alienation of property rights to a share in the assets, income or profits of an entity without the status of a legal entity.
The notification shall be sent to the regulatory authority within 60 days from the date of such acquisition (beginning of actual control) or alienation (termination of actual control). The form and procedure for sending such notification shall be established by the central executive authority responsible for the formation and implementation of state financial policy.
The requirements of this subparagraph shall not apply if the controlled foreign company is a public company, the requirements for which are established by subparagraph 39 - 2 .4.2.2 of subparagraph 39 - 2 .4.2 of paragraph 39 - 2 .4 of this Article.
39 - 2 .5.6. The form of the report on controlled foreign companies, the abbreviated form of the report on controlled foreign companies and the procedure for their completion and submission are established by the central executive body that ensures the formation and implementation of state financial policy.
39 - 2 .5.7. The controlling entity is obliged to ensure the preparation of separate financial statements in accordance with international standards for a partnership, trust or other unincorporated entity in which it owns a share, and to calculate the adjusted profit subject to taxation in accordance with the rules established for controlled foreign companies in relation to such an entity, except in the following cases:
a) the controlling person personally acquired property rights to a share in the assets, income or profits of a trust, fund or other entity without the status of a legal entity and reflects the income received through such an entity in its own declaration of property status and income ( corporate income tax return ), or
b) the direct owner of an interest in a partnership, trust, foundation, or other unincorporated entity is a controlled foreign company that includes the income earned through or from such an entity in its own financial statements.
If, in accordance with the provisions of this subparagraph, a controlling person is required to prepare financial statements for a partnership, trust or other unincorporated entity, the relevant entity shall be treated for tax purposes as a controlled foreign company.
The object of taxation for the personal income tax (corporate income tax) of the controlling entity is the part of the adjusted profit of the relevant entity without the status of a legal entity, proportional to the share owned or controlled by such individual (legal) entity, calculated in accordance with the rules specified in this article for controlled foreign companies.
39 - 2.6 . Tax control over controlled foreign companies
39 - 2 .6.1. The supervisory authority has the right to send a request to the taxpayer for additional explanations regarding a controlled foreign company if there is tax information that:
a) the taxpayer is a controlling entity and has not filed a report on controlled foreign companies, and/or
b) the information provided by the taxpayer in the report on controlled foreign companies is not true or contains errors.
39 - 2 .6.2. At the request of the regulatory authority, the taxpayer shall, within two months from the date of receipt of the request, provide a response with an explanation of the facts set forth in such request with duly certified copies of the relevant documents.
39 - 2 .6.3. If any regulatory body, other state authority, bank, other financial institution, non-bank payment service provider, electronic money issuer discovers facts indicating that an individual (legal entity) resident of Ukraine owns a share in a foreign legal entity, such body, bank, other financial institution, non-bank payment service provider, electronic money issuer shall send a notification thereof to the central executive body implementing state tax policy. The notification shall be sent by electronic means no later than five business days from the date of discovery of the specified facts.
{Subclause 39 - 2 .6.3 of clause 39 - 2 .6 of article 39 - 2 as amended by Law No. 2888-IX of 12.01.2023 }
39 - 2 .6.4. The inspection of the controlling person is carried out in accordance with the provisions of Chapter 8, Section II of this Code, taking into account the features defined by this article.
39 - 2 .6.4.1. The grounds for inspection of the controlling person are:
a) receipt by the controlling authority of tax information indicating that the taxpayer has failed to submit or submitted a report on controlled foreign companies in violation of the requirements of Article 39-2 of this Code;
b) failure to provide a response to the supervisory authority in accordance with subparagraph 39 - 2.6.2 of this paragraph.
39 - 2 .6.4.2. The procedure for conducting an inspection of a controlling entity is established by the central executive body that ensures the formation and implementation of state financial policy.
39 - 2 .6.4.3. During the inspection, the controlling person is obliged to ensure that the controlling body, upon its request, provides copies of primary documents regarding individual or all transactions of the controlled foreign company. The documents are submitted within one month from the date of receipt of the relevant request by the taxpayer in certified copies. In the case of submission of documents in English, translation into Ukrainian is not required.
If it is necessary to obtain additional documents confirming the financial and economic operations of a controlled foreign company during the audit, they shall be provided by the taxpayer within 30 calendar days from the date of receipt of the additional request from the controlling authority.
In case of doubts about the authenticity or completeness of the documents provided or failure to provide a complete set of documents, the regulatory authority may require the controlling entity to provide an audit opinion on the financial statements of the controlled foreign company, which may not contain a disclaimer of opinion or an adverse opinion.
When the controlling entity provides an audit report from an audit firm that is authorized to audit financial statements in the relevant foreign jurisdiction, confirming the financial results of the controlled foreign company, such audit report is a sufficient document on the basis of which the controlled foreign company's profit before tax is determined and the adjusted profit of the controlled foreign company is calculated. The submission of such an audit report by the controlling entity does not require it to provide additional documents to confirm the controlled foreign company's profit before tax.
39 - 2 .6.4.4. The supervisory authority shall not have the right to conduct more than one inspection of a controlling person within two calendar years.
39 - 2 .6.4.5. Conducting an inspection by a controlling person does not prevent the conduct of inspections specified in Article 75 of this Code.
39 - 2 .6.4.6. The term for conducting an inspection of a controlling person is calculated from the date of the decision to conduct it until the date of drawing up a certificate (act) on conducting such an inspection. The duration of an inspection of a controlling person must not exceed six months.
If it is necessary to obtain information from competent authorities of foreign states, conduct an examination and/or translate into Ukrainian documents necessary to investigate the compliance of the conditions of activity of a controlled foreign company and/or its controlling entity with the rules of this Code on controlled foreign companies, the period for conducting the inspection may be extended by the decision of the head (deputy head) of the central executive body implementing state tax policy for a period not exceeding six months.
39 - 2 .6.4.7. Officials of the regulatory body conducting an inspection of compliance with the rules on controlled foreign companies have the right to send to persons who are parties to the transactions of a foreign legal entity and/or other participants in a foreign legal entity a request for the provision of documents (information) and/or to conduct a counter-reconciliation in accordance with the procedure provided for in Article 73 of this Code, and/or to conduct an interview with officials or other employees of a foreign entity and/or legal entities related to it.
The taxpayer is obliged to assist the officials conducting the inspection of the controlling entity in ensuring the possibility of conducting an interview with the relevant officials or employees of the controlled foreign company. If it is not possible to conduct an interview on the territory of Ukraine, this interview may be conducted via video conferencing, which may be provided by the taxpayer.
39 - 2 .6.4.8. The results of the inspection of the controlling person are drawn up in the form of a report (certificate), drawn up in two copies, signed by the officials who conducted the inspection and the controlling person or his representative.
The form of the act (certificate) on the results of the inspection of the controlling entity and the requirements for its preparation are established by the central executive body that ensures the formation and implementation of state financial policy.
The act (certificate) on the results of the inspection of the controlling entity must be delivered within two working days from the date of its preparation to the controlling entity in respect of which the inspection was conducted, or to its representative, which is certified by the signature of the relevant person.
In the event of the refusal of the controlling entity or its representative to sign the act (certificate) on the results of the inspection of the controlling entity by officials of the controlling body, a corresponding act shall be drawn up certifying the fact of such refusal.
39 - 2 .6.4.9. In case of disagreement of the controlling person or its representative with the conclusions of the inspection or the facts and data set out in the act on the results of the inspection, they have the right to submit their objections within 30 calendar days from the date of receipt of the act. In this case, the controlling person has the right to submit, together with the objections or after submitting the objections within the period agreed with the controlling body, documents (their certified copies) confirming the validity of the objections.
Such objections shall be considered within 30 business days following the date of their receipt, and a response shall be sent to the taxpayer in accordance with the procedure specified in Article 58 of this Code for sending (delivering) tax notices-decisions.
39 - 2 .6.4.10. The adoption of a tax notice-decision based on the results of the inspection by the controlling entity shall be carried out in accordance with the procedure provided for in Article 86 of this Code, but not before the expiration of the period for the payer to submit objections, specified in subparagraph 39 - 2 .6.4.9 of this paragraph.
39 - 2 .6.4.11. Appeals against tax notices-decisions adopted based on the results of an inspection by the controlling entity shall be made in accordance with Article 56 of this Code.
{Chapter I is supplemented by Article 39 - 2 in accordance with Law No. 466-IX of 16.01.2020 , taking into account amendments made in accordance with Law No. 1117-IX of 17.12.2020 }
Article 39 - 3. International Automatic Exchange of Information and Reporting on Accounts↑
39 - 3.1 . General provisions
39 - 3 .1.1. This article defines the basic requirements for the establishment of reportable accounts by financial agents and the submission of reports on reportable accounts for the purposes of the FATCA Agreement and the CRS Multilateral Agreement. Issues not regulated by this Code shall be determined in accordance with the FATCA Agreement, the CRS Multilateral Agreement and the CRS Common Reporting Standard, as well as other legislative acts adopted to implement the provisions of the FATCA Agreement and the CRS Multilateral Agreement.
39 - 3 .1.2. For the purposes of the FATCA Agreement and the CRS Multilateral Agreement, the terms defined in this Code shall be applied and interpreted taking into account the FATCA Agreement, the CRS Multilateral Agreement and the CRS Common Reporting Standard, respectively, to the extent that they do not contradict the FATCA Agreement and the CRS Common Reporting Standard, depending on the purposes of which international agreement the relevant term is used.
39 - 3 .1.3. In this article, the term "due diligence measures" means:
a) for the purposes of the FATCA Agreement - the measures specified in Annex 1 to the FATCA Agreement;
b) for the purposes of the CRS Multilateral Agreement - the measures defined in sections II-VII of the CRS Common Reporting Standard.
39 - 3 .1.4. The central executive body that ensures the formation and implementation of state financial policy shall establish the procedure for applying the CRS Common Reporting Standard (hereinafter referred to as the CRS Application Procedure). The rules of the CRS Application Procedure include the provisions of sections I-VIII of the CRS Common Reporting Standard, taking into account the amendments and additions permitted or provided for by the said standard.
39 - 3 .1.5. In this article, the terms "account holder" and "controlling entity" (or "controlling entities") are used in the meaning given in the FATCA Agreement or the CRS Common Reporting Standard for the purposes of the CRS Multilateral Agreement, depending on the purpose of the implementation of which international agreement the term is used. To establish a controlling entity, a controlling interest in a legal entity is determined in accordance with the measure (level, degree, share) of the exercise of decisive influence (control) established by paragraph 30 of part one of Article 1 of the Law of Ukraine "On Prevention and Counteraction to the Legalization (Laundering) of Proceeds of Crime, Financing of Terrorism and Financing of the Proliferation of Weapons of Mass Destruction".
39 - 3 .2. Due diligence of financial accounts
39 - 3 .2.1. In order to identify reportable accounts, financial agents are required to take due diligence measures in accordance with the rules applicable in accordance with subparagraph 39 - 3 .1.3 of paragraph 39 - 3 .1 of this Article.
39 - 3 .2.2. In cases specified in the FATCA Agreement and/or the CRS Common Reporting Standard, financial agents must request, and account holders are obliged to provide to financial agents:
1) self-assessment documents regarding oneself and/or controlling persons in accordance with the requirements of Annex 1 to the FATCA Agreement to establish (verify) the status of the specified American person;
2) a document of self-assessment of tax residency status in relation to itself and/or in relation to controlling persons in accordance with the requirements of the CRS Common Reporting Standard to establish the state (territory) of which the account holder and/or the controlling person is a resident (hereinafter referred to as the CRS self-assessment document);
3) other information and/or documents necessary for the financial agent to take measures for proper due diligence of financial accounts, establish their accountability and prepare reports on accountable accounts to comply with the requirements of the FATCA Agreement and/or the CRS Common Reporting Standard in accordance with subparagraph 39 - 3 .1.3 of paragraph 39 - 3 .1 of this article.
39 - 3 .2.2.1. Account holders are required to notify the financial agent within 30 calendar days of any change in their tax residency status for the purposes of the Common Reporting Standard (CRS) and/or their status for the purposes of the FATCA Agreement and/or any change in the relevant controlling person status.
If, during the application of due diligence measures, a financial agent has reason to believe that a person is simultaneously a resident of Ukraine and at least one other jurisdiction, for the purposes of the CRS Multilateral Agreement and the CRS Common Reporting Standard, such person shall be considered a resident of the relevant other jurisdiction.
39 - 3 .2.2.2. In cases and to the extent specified by the FATCA Agreement and the CRS Common Reporting Standard, when verifying the tax residency status of the account holder and/or his/her controlling persons, financial agents have the right to use available information and documents obtained in accordance with the legislation on preventing and combating the legalization (laundering) of proceeds from crime, terrorist financing and financing of the proliferation of weapons of mass destruction.
39 - 3 .2.2.3. If, in cases specified by the FATCA Agreement and/or the CRS Common Reporting Standard, during or after the application of due diligence procedures, the financial agent learns or has reason to believe (suspects) that the account belongs to the reportable persons, but the account holder has submitted self-assessment documents regarding himself and/or the controlling persons and/or other information and/or documents indicating that the account is not reportable, the financial agent is obliged to send a request to the account holder with a request to provide explanations and information regarding the suspicion.
The account holder is obliged to provide the financial agent with explanations and information regarding the suspicion within 30 calendar days from the date of receipt of the request.
39 - 3 .2.2.4. Failure by the account holder to provide the documents specified in subparagraph 39 - 3 .2.2 of paragraph 39 - 3 .2 of this article, failure to notify the financial agent of a change in tax residency status, or failure to provide the requested information and/or documents within 30 calendar days from the date of receipt of the financial agent's request, or provision of information and/or documents that do not refute the financial agent's suspicion of the accountability of the account, shall be grounds for the financial agent's refusal to establish business relations, refusal to provide financial services, or refusal to provide further services, including termination of contractual relations with the account holder. In the event of termination of contractual relations with the account holder, the financial agent shall return the remaining funds to the account holder and shall not be liable for any losses incurred by the account holder related to the termination of contractual relations. If, after termination of the contractual relationship, the account holder is absent from the place of performance of the obligation or evades acceptance of performance, the financial agent transfers the remaining funds or deposits the securities belonging to such account holder into the deposit of the notary (notary office) in accordance with the procedure established by law. The financial agent transfers the funds or deposits the securities into the deposit of the notary (notary office) within 30 calendar days from the date of notification to the account holder of the termination of the contractual relationship. Regulators of financial services markets, within the limits of the powers determined by the legislation in the field of regulation of activities for the provision of financial services, may establish the features and procedure for the termination of business relations at the initiative of financial agents (depending on the specifics of their activities) to comply with the requirements of this article.
39 - 3 .2.2.5. If the financial agent becomes aware or has reason to believe (suspects) that the account holder has provided him with incomplete or inaccurate information, as a result of which the information about the account that should have been included in the report on accountable accounts was not included in the previously submitted report, the financial agent is obliged to contact the account holder with a request to provide explanations regarding the suspicion. If, within the period established by the financial agent (but not later than 90 calendar days from the date of receipt of the financial agent's request), the account holder does not provide the documents specified in subparagraph 39 - 3 .2.2 of paragraph 39 - 3 .2 of this Article and/or explanations refuting such suspicion, the financial agent must consider the fact of the account holder providing inaccurate or incomplete information to be established. The financial agent shall be obliged to immediately, but not later than 10 calendar days from the date of establishing the fact that the account holder provided incomplete or inaccurate information, provide the supervisory authority with complete information about the reporting account for which incomplete or inaccurate information was provided (submit a corrected report on reporting accounts). If the fact that the account holder provided incomplete or inaccurate information is established regarding a depositor-investor of a collective investment institution to which the rules of clause 39 - 3.11 of this article apply, the financial agent shall also notify the asset management company that manages the assets of this collective investment institution within the same period.
39 - 3 .2.3. A financial agent that meets the criteria for a reporting financial institution under the CRS Multilateral Agreement and the CRS Common Reporting Standard is required to apply due diligence procedures to identify reportable accounts from the date the financial institution becomes accountable, regardless of the date the financial agent is registered with a supervisory authority, in accordance with paragraph 39 - 3 .3 of this Article.
39 - 3 .3. Accounting for Financial Agents That Are Reporting Financial Institutions for the Purposes of the CRS Multilateral Agreement and the CRS Common Reporting Standard
39 - 3 .3.1. Financial agents that are reporting financial institutions for the purposes of the CRS Multilateral Agreement and in accordance with the CRS Common Reporting Standard are required to submit an application for registration with the supervisory authority within 60 calendar days after the financial agent is established as a reporting financial institution. The procedure for establishing the status of a reporting financial institution in accordance with the CRS Common Reporting Standard is determined by the central executive authority that ensures the formation and implementation of state financial policy.
39 - 3 .3.1.1. The supervisory authority shall register a financial agent within two business days from the date of receipt of the financial agent's application and shall be obliged to send a notification of the financial agent's registration or refusal to register, indicating the grounds in the manner determined in accordance with subparagraph 39 - 3 .3.3 of this paragraph. The grounds for refusal to register a financial agent shall be the submission of an application for registration in respect of a person already registered as a reporting financial institution.
On the day of registration, the regulatory authority sends the financial agent a notification (receipt) indicating the date of registration.
Legal entities - Reporting Financial Institutions (except corporate investment funds) are recorded under the tax identification numbers of such entities. The recording of a partnership, trust, collective investment institution or legal arrangement that is not a legal entity but meets the criteria for a Reporting Financial Institution for the purposes of the Common Reporting Standard CRS is carried out by additional recording of an asset management company or other legal entity that is authorized or required by law or contract to file reports on behalf of such legal arrangement.
39 - 3 .3.2. A financial agent that ceases to meet the criteria of a reporting financial institution under the Common Reporting Standard CRS shall be deregistered with the supervisory authority upon submission of a relevant application for deregistration.
39 - 3 .3.2.1. Together with the application, the financial agent submits documents and other information that substantiates the existence of grounds for deregistration.
39 - 3 .3.2.2. Within 30 calendar days after receiving the financial agent's application for deregistration, the regulatory authority shall notify such financial agent of its deregistration or of the need for the financial agent to provide additional information to substantiate the grounds for deregistration, indicating the deadline for its provision.
The decision to deregister a financial agent or to refuse to deregister is made by the supervisory authority no later than 90 calendar days after receiving the application.
39 - 3 .3.3. The procedure for registering and deregistering financial agents that are accountable financial institutions for the purposes of the CRS Multilateral Agreement and the CRS Common Reporting Standard is established by the central executive body that ensures the formation and implementation of state financial policy.
Submission of applications and other documents for registration of financial agents as accountable financial institutions and for their removal from registration is carried out in electronic form by means of electronic communication in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
39 - 3 .3.4. A financial agent, in respect of which the termination procedure has been initiated, shall, upon its application, be removed from the register with the supervisory authority after the financial agent has closed (terminated) all reporting accounts and submitted a report on reporting accounts for the period in which the last reporting account was closed. In the event of liquidation in accordance with the Law of Ukraine "On the Deposit Guarantee System of Individuals" of a bank in respect of which the National Bank of Ukraine has made a decision to revoke the banking license and liquidate, the bank shall be removed from the register with the supervisory authority as a reporting financial institution upon application by the authorized person of the Deposit Guarantee Fund for Individuals for the liquidation of the bank, submitted within 10 business days from the date of submission of the report on reporting accounts for the period in which the last reporting account was closed.
39 - 3 .3.5. Deregistration of a financial agent is carried out by an independent decision of the supervisory authority, if an entry on the termination of the legal entity has been made in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations in respect of the financial agent. The supervisory authority shall make the said decision within three working days after receipt of information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations.
39 - 3 .4. Submission of a report on accountable accounts
39 - 3 .4.1. Financial agents are obliged to submit a report on accountable accounts to the supervisory authority every year, by July 1.
39 - 3 .4.2. The reporting period is considered to be the previous calendar year, unless the FATCA Agreement or the CRS Multilateral Agreement, respectively, establishes other rules.
39 - 3 .4.3. In a report on Reportable Accounts submitted for the purposes of fulfilling the requirements of the FATCA Agreement or the CRS Multilateral Agreement, the financial agent provides information about all Reportable Accounts for the reporting period to the extent specified in the FATCA Agreement or Section I of the CRS Common Reporting Standard.
39 - 3 .4.4. The report on accountable accounts shall be submitted exclusively in electronic form. The form of the report on accountable accounts, the format (standard) of its completion and submission by financial agents to the supervisory authority shall be established by the central executive authority that ensures the formation and implementation of state financial policy.
39 - 3 .4.5. The supervisory authority collects information from financial agents, stores, protects such information and transfers information to the competent authority of a foreign jurisdiction or the financial agent from which it was received (in case of need to correct or clarify information on a financial account maintained by such financial agent). It is prohibited for the supervisory authority to provide information on accountable accounts (including information received from competent authorities of foreign states) to other persons, including law enforcement or other state bodies, local self-government bodies, legal entities and individuals (including those about whom information is provided in the report on accountable accounts), except for cases of providing such information in accordance with the requirements of the Criminal Procedure Code of Ukraine .
39 - 3 .5. Retention of documents confirming the implementation of due diligence measures by the financial agent
Financial agents (except asset management companies) are required to retain the documents specified in subparagraph 39 - 3 .2.2 of paragraph 39 - 3 .2 of this article (including electronic ones), their copies, records, data, information and documents regarding the measures taken by financial agents to comply with the requirements of this article, including all documents provided by persons with whom the financial agent has refused to establish business relations (including correspondence, questionnaires, certificates, reports, requests, results of any analysis during the conduct of customer due diligence), for at least 1825 days from the day following the deadline for submitting the report on accountable accounts for the preparation of which the specified documents are used or to which they relate.
The information and document retention requirements of this paragraph apply to all financial accounts, regardless of whether they have been designated as reportable accounts. The retention period for information and documents prepared or obtained during the audit of financial accounts that have not been designated as reportable accounts in a particular reporting period shall be calculated from the day following the deadline for submitting a report on reportable accounts for the same reporting period.
Asset management companies that, in accordance with the requirements of paragraph 39 - 3.11 of this article , fulfill the obligations to submit reports on accountable accounts for collective investment institutions, are obliged, within the period established by this paragraph, to store notifications received from depository institutions that maintain accounts in securities of depositors - investors of collective investment institutions, as well as any other information and documents confirming the implementation by asset management companies of measures to verify the correctness of determining the accountability of accounts in the relevant notifications from depository institutions.
39 - 3 .6. Prevention of acts and practices aimed at evading obligations under the CRS Common Reporting Standard and the identification of reportable accounts for the purposes of the CRS Multilateral Agreement
39 - 3 .6.1. If a financial agent, account holder or other person enters into a transaction or performs an act or operation and it follows from the terms of the transaction or the actual conduct of the parties to the transaction or act that the main purpose or one of the main purposes of such transaction, act or operation is to avoid establishing accountability of a financial account or to avoid fulfilling by the financial agent its obligations to establish accountable accounts, prepare and submit a report on accountable accounts in accordance with the requirements of this article, then for the purposes of verifying financial accounts and identifying accountable accounts, it is considered that the relevant transaction, act or operation was not concluded (performed) or did not take place.
39 - 3 .6.2. The supervisory authority shall, within five working days, notify the financial agent of any transaction, action or operation that may have led to the failure to establish a reporting account maintained by the financial agent.
Based on the notification of the regulatory authority, the financial agent is obliged to apply due diligence measures to the financial account to establish accountability and provide the regulatory authority with information about this financial account in full within 30 calendar days from the date of receipt of the relevant notification. The regulatory authority has the right in the notification to set a different (extended) deadline for the financial agent to provide information about the financial account. A financial agent who has timely provided the regulatory authority with complete information about the accountable account shall not be subject to the punitive (financial) sanctions provided for by this Code for submitting incomplete or inaccurate information in a previously submitted report on accountable accounts regarding this financial account.
39 - 3 .6.3. A financial agent who is himself a party to a transaction or a participant in a transaction aimed at evading his obligations to establish accountable accounts or to prepare and submit reports on accountable accounts shall be deemed to have failed to fulfill the obligations provided for in paragraphs 39 - 3 .2-39 - 3 .5 of this Article and shall bear the liability specified in this Code for committing an offense in respect of each financial account, information about which was not provided in the report on accountable accounts.
39 - 3 .6.4. The supervisory authority is obliged to provide information on the violation by a financial agent of the requirements of this article, which may also indicate the existence of a risk of non-compliance by such a financial agent with the requirements of the legislation in the field of prevention and counteraction to the legalization (laundering) of proceeds from crime, financing of terrorism and financing of the proliferation of weapons of mass destruction, to the National Bank of Ukraine and the National Securities and Stock Market Commission regarding financial agents, the state regulation and supervision of whose activities they carry out.
39 - 3.7 . Control over the submission of reports on accountable accounts
39 - 3 .7.1. The timeliness of submission by financial agents of reports on accountable accounts, corrected reports on accountable accounts and the provision by financial agents of responses to requests (notifications) of the supervisory authority sent in the cases specified in this article shall be subject to desk inspection. Desk inspection may be conducted within 30 calendar days following the last day of the deadline for submission of a report, corrected report on accountable accounts or response to a request of the supervisory authority, and if such documents were submitted later - on the day of their actual submission.
39 - 3 .7.2. If the supervisory authority receives a notification of errors in the submitted report on reportable accounts from the authorized body of the United States of America in accordance with the FATCA Agreement or from the competent authority of another jurisdiction on the basis of the CRS Multilateral Agreement, the supervisory authority shall, within five business days from the date of receipt of such notification, notify the financial agent of the need to correct the errors or clarify the information in the submitted report. The financial agent shall be obliged to submit a corrected report on reportable accounts or provide an explanation no later than 30 calendar days from the date of receipt of the notification from the supervisory authority.
39 - 3 .7.3. A financial agent who independently discovered errors in a previously submitted report on accountable accounts after July 1 of the year following the reporting year is obliged to submit a corrected report to the supervisory authority no later than 10 calendar days from the date of discovery of the error.
39 - 3 .7.4. In the event of timely correction by the financial agent of errors in the report on accountable accounts within the terms specified in this paragraph, the penalties provided for by this Code for failure to submit or untimely submission of the report on accountable accounts and for submitting a report with errors shall not apply (except for penalties for offenses committed intentionally or as a result of failure or violation by the financial agent of the rules of due diligence).
39 - 3 .7.5. If, based on the results of the desk inspection, the supervisory authority discovers that the financial agent has failed to submit a report on accountable accounts within the established period or has submitted the report untimely, or has failed to submit or submitted a corrected report or a response to a request (notification) sent by the supervisory authority under the rules of this article, the supervisory authority shall draw up a report describing the circumstances of the offense committed, established during the desk inspection. The results of the desk inspection shall be drawn up in accordance with the procedure established by Article 86 of this Code, taking into account the features specified in this article.
39 - 3 .7.6. If, during the application of due diligence measures, a financial agent has financial accounts that meet the conditions specified in paragraphs B(5), C(5)(c) and C(7) of Section III of the CRS Common Reporting Standard, the relevant accounts shall be considered undocumented accounts.
If the report on accountable accounts submitted by the financial agent contains information about undocumented accounts, the regulatory authority shall send a request to the financial agent to determine the reason for the existence of undocumented accounts. The financial agent shall be obliged to provide a response to the request regarding undocumented accounts no later than 30 calendar days from the date of receipt of the regulatory authority's request.
If the supervisory authority does not receive a response to the request from the financial agent or based on the results of the analysis of the response received, the supervisory authority has the right to appoint an unscheduled documentary audit of the financial agent regarding its compliance with the requirements for conducting a due diligence of financial accounts in accordance with the Common Reporting Standard (CRS).
39 - 3 .7.7. Verification of compliance by financial agents with the requirements of this article shall be carried out in accordance with the provisions of Chapter 8 , Section II of this Code, taking into account the features defined by this article.
39 - 3 .7.8. The supervisory authority shall send financial agents the notifications and requests provided for in this paragraph, and financial agents shall provide responses to them in electronic form by means of electronic communication in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
39 - 3 .8. Features of monitoring compliance by financial agents with the requirements of the Common Reporting Standard CRS
39 - 3 .8.1. Control over the implementation by financial agents and account holders of the requirements of this article regarding the CRS Common Reporting Standard is carried out by monitoring the activities of financial agents and conducting inspections.
39 - 3 .8.2. Monitoring of the activities of financial agents is carried out by analyzing reports on accountable accounts, tax reporting of financial agents, information received from competent authorities of foreign states, the National Bank of Ukraine, the National Securities and Stock Market Commission, any other information sources, by obtaining tax information in accordance with Article 73 of this Code. As part of monitoring and based on the results of information analysis, the regulatory authority may conduct surveys of financial agents.
39 - 3 .8.2.1. The survey is conducted by the supervisory authority by sending survey requests to the financial agent or group of financial agents, in whose activities a risk of non-compliance or violation of the requirements of this article, as well as other legislative acts adopted to implement the provisions of the CRS Common Reporting Standard, has been identified. The financial agent is obliged to provide information on the survey request within 30 calendar days from the date of receipt of the request. The supervisory authority has the right to establish a different (extended) deadline for providing a response, as indicated in the survey request.
A survey of one financial agent cannot be conducted more than once during a calendar year.
39 - 3 .8.2.2. If, based on the results of the survey of the financial agent, the supervisory authority identifies possible violations by the financial agent of the requirements of this article and other legislative acts adopted to implement the provisions of the CRS Common Reporting Standard, the supervisory authority has the right to appoint an unscheduled documentary audit of the financial agent on issues of its compliance with the requirements of the CRS Common Reporting Standard.
39 - 3 .8.2.3. The procedure for monitoring the activities of financial agents (including surveys) is established by the central executive body that ensures the formation and implementation of state financial policy.
39 - 3 .8.3. The provisions of subparagraphs 39 - 3 .8.2.1-39 - 3 .8.2.3 of subparagraph 39 - 3 .8.2 of paragraph 39 - 3 .8 of this article shall not apply when supervisory authorities exercise control over compliance by financial agents with the requirements of the FATCA Agreement .
39 - 3 .9. Features of control over non-resident account holders and their controlling persons
39 - 3 .9.1. If, during the audit of a financial agent or on the basis of a notification from a competent authority of another jurisdiction received in accordance with the CRS Multilateral Agreement, the supervisory authority discovers facts indicating a violation or a possible violation of the requirements of this article by the account holder or his controlling person, the supervisory authority, on the basis of the act (certificate) of the audit of the financial agent or the notification from the competent authority:
if the account holder is registered with the regulatory authority - appoints an unscheduled documentary audit in relation to him in accordance with the general procedure specified in this Code;
if the account holder is a non-resident who is not registered with the regulatory authority, - take measures provided for in subparagraph 39 - 3 .9.2 of paragraph 39 - 3 .9 of this article.
39 - 3 .9.2. If the account holder is a non-resident who is not registered with the supervisory authority, the supervisory authority shall send a tax notice to the non-resident for violation of the requirements of the Common Reporting Standard CRS in accordance with the procedure determined by the central executive body responsible for the formation and implementation of state financial policy. In this case, a copy of the order to conduct an unscheduled documentary audit shall not be sent to the account holder and an audit report shall not be drawn up.
39 - 3 .9.3. The tax notice to a non-resident person provided for by this article must contain:
a motivated basis for its preparation and/or accrual of a monetary obligation;
the amount of the monetary obligation that the non-resident person must pay (if determined);
the deadline and procedure for payment of such monetary obligation;
details of a current account in foreign currency opened for the central executive body implementing state policy in the field of treasury services of budget funds, in an authorized bank to which the monetary obligation is paid;
deadline and procedure for appealing a tax notice.
The form of a tax notice to a non-resident for violation of the requirements of the Common Reporting Standard CRS is established in the state and English languages and approved by the central executive body that ensures the formation and implementation of state financial policy.
39 - 3 .9.4. The amount of the monetary obligation specified in the tax notice to a non-resident person for violation of the requirements of the Common Reporting Standard CRS is subject to payment within 90 calendar days from the date of receipt of such tax notice or may be appealed in accordance with the procedure provided for in paragraph 56.25 of Article 56 of this Code.
39 - 3 .9.5. The rules for conducting and recording the results of inspections, provided for in Section II of this Code, shall apply when conducting inspections of account holders insofar as they do not contradict the requirements of this Article.
39 - 3 .10. The report on accountable accounts is not a tax return of a financial agent or a part thereof and is not equated with the tax reporting of a financial agent or an account holder and/or its controlling person. The provisions of this article are special in relation to other provisions of this Code in terms of determining the rules for the preparation, submission and verification of reports on accountable accounts. Penalty (financial) sanctions provided for by this Code for violation of the requirements for storing primary documents, maintaining and submitting tax reporting shall not be applied for violation of the requirements of this article.
39 - 3 .11. Compliance with the requirements of this article by collective investment institutions and other financial agents that are not legal entities
39 - 3 .11.1. If a mutual investment fund or any other legal arrangement without legal personality is a Reporting Financial Institution under the Common Reporting Standard CRS, the obligations set forth in this article shall be imposed on the person who, by law or contract, acts on behalf of or for the account of the assets of such legal arrangement and/or maintains the financial account.
39 - 3 .11.2. Compliance with the requirements of this article with respect to collective investment undertakings that are reporting financial institutions shall be entrusted to:
1) depository institutions that, in accordance with the legislation on depository activities, maintain accounts in the securities of depositors (hereinafter referred to as the depository institution), to which securities of collective investment institutions are credited/transferred, in terms of applying due diligence measures and establishing accountability for such accounts;
2) an asset management company in respect of each corporate and/or mutual investment fund whose assets it manages, in terms of verifying the correctness of establishing accountability of financial accounts and submitting reports on accountable accounts.
If an investor of a collective investment institution is a depositor of several securities accounts opened (maintained) by more than one depository institution and to which securities of this collective investment institution are credited/transferred, each depository institution shall fulfill the obligations stipulated by this clause and shall be obliged to provide the asset management company with information regarding the securities account in the manner specified in subclause 39 - 3 .11.3 of this clause.
39 - 3 .11.3. Each depository institution that opens (maintains) an account in the securities of a depositor - investor of a collective investment institution shall perform the duties of carrying out a due diligence check of this account and establish the accountability of the account. The depository institution shall be obliged, no later than 30 calendar days after the end of each calendar half-year, to provide the asset management company with a notification about depositors who have purchased securities of collective investment institutions, the assets of which are managed by such an asset management company, and to notify about changes in circumstances that affect the determination of the tax status of such depositors or their controlling persons. The format and form of such notification shall be established by the central executive body that ensures the formation and implementation of state financial policy, in agreement with the National Commission on Securities and Stock Market.
Based on the information received from the depository institution, the asset management company verifies the correctness of the determination of the accountability of accounts and includes information on the accountable accounts in the report on accountable accounts. In order to verify the information received, as well as to respond to the request of the regulatory authority regarding the submitted report on accountable accounts, the asset management company has the right to request, receive and use documents confirming the information provided by the depository institutions, and the depository institutions are obliged to provide copies of the confirming documents within 10 calendar days from the date of receipt of the request from the asset management company.
The depository institution shall be liable for violation of the requirements of this article in terms of conducting due diligence and determining the accountability of a securities account, as well as for the completeness and timeliness of the provision of information to the asset management company, but shall not be liable for including information about this account in the report on accountable accounts.
39 - 3 .11.4. In the event that a depository institution fails to provide a notice on depositors to an asset management company within the established period or provides incomplete information in the notice, or fails to provide the asset management company with a response to its request sent in accordance with the rules of this paragraph, the asset management company has the right to submit to the central executive body implementing state tax policy an application with a complaint against such depository institution. The application shall be accompanied by documents certifying the fact that the depository institution failed to provide a notice with information on depositors, provided incomplete information, or failed to provide a response to the asset management company's request.
Based on the received complaint, the regulatory authority shall send a request to the depository institution to establish the reason for the failure to provide information to the asset management company. The depository institution shall be obliged to provide the asset management company with complete information, the provision of which is provided for by this Article, and to notify the regulatory authority thereof or to provide a response to the regulatory authority's request justifying the reason for the impossibility of providing such information no later than five calendar days from the date of receipt of the regulatory authority's request.
If the supervisory authority does not receive a response to the request from the depository institution or based on the results of the analysis of the depository institution's response, the supervisory authority has the right to appoint an unscheduled documentary audit of the depository institution regarding its compliance with the requirements for conducting a due diligence of financial accounts in accordance with the Common Reporting Standard (CRS).
39 - 3 .11.5. The report on accountable accounts shall be submitted for each collective investment undertaking separately. The asset management company shall be responsible, as established by this Code, for submitting a report on accountable accounts for each corporate and/or mutual investment fund whose assets it manages.
39 - 3 .11.6. The procedure for interaction of financial agents to fulfill the requirements of this article regarding collective investment institutions, as well as the format and form of the statement of an asset management company with a complaint about the failure of the depository institution to provide the information provided for in this paragraph, shall be established by the central executive body that ensures the formation of state financial policy, in agreement with the National Securities and Stock Market Commission.
The other provisions of this Article shall apply to asset management companies and depository institutions, subject to the specifics set forth in this paragraph. A depository institution shall fulfill its obligations as a Reporting Financial Institution under the Common Reporting Standard (CRS), including reporting on Reportable Accounts in the general manner set forth in this Article.
{Chapter I supplemented by Article 39 - 3 in accordance with Law No. 2970-IX of 20.03.2023 }
CHAPTER II. ADMINISTRATION OF TAXES, FEES, PAYMENTS↑
40.1. This section determines the procedure for administering taxes and fees specified in Section I of this Code, as well as the procedure for monitoring compliance with the requirements of tax and other legislation in cases where such monitoring is entrusted to regulatory authorities.
If other sections of this Code or laws on customs issues determine a special procedure for the administration of individual taxes, fees, and payments, the rules specified in another section or law on customs issues shall be used.
41.1.1. tax authorities (the central executive body implementing the state tax policy, its territorial bodies) - regarding compliance with legislation on taxation (except for cases specified in subparagraph 41.1.2 of this paragraph), legislation on the payment of a single contribution, as well as regarding compliance with other legislation, control over the implementation of which is entrusted to the central executive body implementing the state tax policy, or its territorial bodies;
41.1.2. customs authorities (the central executive body implementing the state customs policy, its territorial bodies) - regarding compliance with the legislation on customs affairs and taxation with customs duties, excise tax, value added tax, other taxes and fees, which, in accordance with tax, customs and other legislation, are collected in connection with the import (shipment) of goods into the customs territory of Ukraine or the territory of a free customs zone or the export (shipment) of goods from the customs territory of Ukraine or the territory of a free customs zone.
41.2. The procedure for exchanging information between the central executive body implementing state tax policy, its territorial bodies and the central executive body implementing state customs policy, its territorial bodies for the purposes of performing the functions of controlling bodies is determined by the central executive body ensuring the formation and implementation of state financial policy.
41.3. State tax inspectorates are structural divisions of territorial bodies of the central executive body implementing state tax policy, and operate on the basis of regulations on such territorial bodies approved by the central executive body implementing state tax policy, within the functions defined in Article 19 - 3 of this Code.
41.4. The collection authorities are exclusively the supervisory authorities specified in subparagraph 41.1.1 of this paragraph, authorized to take measures to ensure the repayment of tax debt and arrears in the payment of a single contribution within the limits of their powers, as well as state bailiffs within the limits of their powers. The collection of tax debt and arrears in the payment of a single contribution by means of executive inscriptions of notaries is not permitted.
41.5. The powers and functions of regulatory authorities are determined by this Code, the Customs Code of Ukraine and the laws of Ukraine.
The division of powers and functional responsibilities of regulatory bodies is determined by the legislation of Ukraine.
41.6. Other state bodies do not have the right to conduct checks on the timeliness, accuracy, and completeness of the calculation and payment of taxes and fees, including at the request of law enforcement agencies.
{Article 41 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4915-VI of 07.06.2012 , No. 5083-VI of 05.07.2012 ; as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
Article 42. Correspondence between taxpayers and regulatory authorities↑
{Title of Article 42 as amended by Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
42.1. Tax notices - decisions, tax requirements or other documents on the administration of taxes, fees, payments, tax control, including on the conduct of inspections, reconciliations, addressed by the controlling authority to the taxpayer, must be drawn up in writing, duly signed and, in cases provided for by law, certified by the seal of such controlling authority and displayed in the electronic account.
{Clause 42.1 of Article 42 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 466-IX of 01.16.2020 , No. 786-IX of 07.14.2020 }
42.2. Documents are considered to be properly served if they are sent in the manner specified in paragraph 42.4 of this Article, sent to the address (location, tax address) of the taxpayer by registered letter with notification of delivery, or personally delivered to the taxpayer (his representative).
{Clause 42.2 of Article 42 as amended by Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
42.3. If a taxpayer, in accordance with the procedure and within the time limits specified in Article 66 of this Code, has notified the supervisory authority of a change in tax address, he shall be exempted from fulfilling the requirements of documents sent to him by the supervisory authority at the previous tax address and subsequently returned as undeliverable for the period from the date of state registration of the change in tax address to the date of making changes to the accounting data of such taxpayer.
{Clause 42.3 of Article 42 as amended by Law No. 3609-VI of 07.07.2011 }
42.4. Taxpayers who submit reports in electronic form and/or have undergone electronic identification online in an electronic office may correspond with regulatory authorities by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" . For persons who are financial agents, correspondence with the regulatory authority in electronic form is mandatory in cases specified by this Code.
Correspondence between regulatory authorities and taxpayers specified in paragraph one of this paragraph who have submitted an application for the receipt of documents via an electronic account, as well as with financial agents in cases specified by this Code, shall be carried out by electronic means in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" by sending a document to an electronic account while simultaneously sending information to the taxpayer's electronic address(es) about the type of document, date and time of its submission to the electronic account.
A document sent by a regulatory authority to the electronic account is considered to be delivered to the taxpayer or financial agent if it is formed in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" and is available in the electronic account.
The date of delivery of the document to the taxpayer or financial agent is the date indicated in the delivery receipt in text format, which is sent from the electronic account automatically and indicates the date and time of delivery of the document to the taxpayer/financial agent. If the delivery of the document occurred after 6 p.m., the date of delivery of the document to the taxpayer/financial agent is considered to be the next business day. If the delivery occurred on a weekend or holiday, the date of delivery of the document to the taxpayer/financial agent is considered to be the first business day following the weekend or holiday.
If the supervisory authority does not receive a receipt for the delivery of the document to the electronic account within two business days from the date of its sending, such a document in paper form shall be sent to the address (location, tax address) of the taxpayer/financial agent by registered letter with notification of delivery or shall be personally delivered to the taxpayer/financial agent (his representative) on the third business day from the date of sending from the electronic account.
In this case, the deadline for delivering a document to the electronic account, specified in paragraph five of this clause, is not included in the deadline for sending documents, specified in this Code.
A taxpayer (except for a financial agent in terms of correspondence with the supervisory authority on issues specified in Article 39-3 of this Code) may send to the supervisory authority via the electronic office once a year a statement of refusal to receive documents via the electronic office. The date of completion of the taxpayer's correspondence via the electronic office is the date indicated in the receipt of delivery to the supervisory authority of the statement of refusal to receive documents via the electronic office.
{Article 42 is supplemented by paragraph 42.4 in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 1797-VIII of 21.12.2016 - the change shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016; as amended by Law No. 2725-VIII of 16.05.2019 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 2654-IX of 06.10.2022 ; as amended by Law No. 2970-IX dated 20.03.2023 }
42.5. If the taxpayer has not submitted an application for the desire to receive documents via the electronic account, correspondence with the taxpayer shall be carried out by sending to the address (location, tax address) of the taxpayer by registered letter with notification of delivery or personally delivered to the taxpayer (his representative).
If the post office cannot deliver a document to the taxpayer due to the absence of the taxpayer's officials at the location, their refusal to accept the document, failure to find the taxpayer's actual location (location) or for other reasons, the document is considered delivered to the taxpayer on the day specified by the postal service in the notification of delivery, indicating the reason for non-delivery.
At the request of a taxpayer who received a document in electronic form, the regulatory authority shall provide such taxpayer with the relevant document in paper form within three business days from the date of receipt of the relevant request (in paper or electronic form) from the taxpayer.
{Article 42 is supplemented by paragraph 42.5 in accordance with Law No. 466-IX of 16.01.2020 }
42.6. Electronic document flow between a taxpayer and a supervisory authority is carried out in accordance with this Code, the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" without concluding a relevant agreement.
The head of the taxpayer determines and changes the list of authorized persons of the taxpayer who are authorized to sign, submit, and receive documents and information through the electronic account on behalf of the taxpayer, and determines their powers.
A taxpayer becomes a subject of electronic document flow after sending to the regulatory authority the first electronic document in the established format in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" .
Electronic document flow between the taxpayer and the supervisory authority is terminated exclusively in the following cases:
receiving information from a qualified electronic trust service provider about the expiration (or cancellation) of the qualified public key certificate of the taxpayer's manager;
obtaining information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations about the change of the head of the taxpayer;
obtaining information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations about the state registration of the termination of a legal entity;
the availability in the State Register of Individual Taxpayers of information about the termination of the entrepreneurial activity of an individual entrepreneur or the independent professional activity of an individual;
the availability in the State Register of Individual Taxpayers of information about the closure of the registration number of the taxpayer's registration card due to death.
The procedure for exchanging electronic documents between the taxpayer and the regulatory authority is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Article 42 is supplemented by paragraph 42.6 in accordance with Law No. 786-IX of 14.07.2020 }
42 - 1 .1. The electronic office is created and operates according to the following principles:
transparency - mandatory publication of the methodology for implementing the provisions of this Code in the work of the electronic office;
Controllability - ensuring the possibility of independent verification of the correctness of the operation of the electronic office through a test payer (payers) on an emulator created on the website of the electronic office methodologist for the absence of errors in the software, preventing unauthorized interference with the operation of the electronic office software, which means a violation of the integrity and authenticity of the source code;
integration with systems used by taxpayers - APIs of the software interface for electronic data interchange (EDI) are placed in open, free access;
timeliness of elimination of technical and/or methodological errors - ensuring the publication on the official website of the electronic office methodologist of a register of technical and/or methodological errors detected by taxpayers, the technical administrator and/or the electronic office methodologist, with a determination of the level of criticality of such errors and the establishment of deadlines for their elimination, informing all users of the electronic office about the fact of the detection of a technical and/or methodological error, as well as about the fact of its elimination and the restoration of the electronic office in full;
automation - maximum automation of the processes of creating, accepting, registering, processing, storing documents, processing and displaying data (indicators) of documents and other taxpayer accounting data;
{Paragraph six of clause 42 - 1 .1 of Article 42 - 1 as amended by Law No. 786-IX of 14.07.2020 }
completeness of functionality - the presence of such an electronic service interface that provides the possibility of exercising the rights and obligations of a taxpayer, obtaining documents stipulated by law and information related to such a taxpayer, online (via the Internet in real time) or through a program interface (API), by other means of information, telecommunications, information and telecommunications systems;
simplifying the procedure for interaction between taxpayers and the regulatory authority and accelerating electronic document flow between them;
performing automated logging of all actions (events) occurring in the electronic office, including, in particular, recording the date and time of sending, receiving documents through the electronic office and any change in data available in the electronic office, using a qualified electronic time stamp. Information on the date and time of sending and receiving documents, other correspondence with the identification of the sender and recipient is stored indefinitely and can be obtained through the electronic office in the form of an electronic document, including in the form of a receipt in text format;
{Paragraph nine of clause 42 - 1 .1 of article 42 - 1 as amended by Law No. 2725-VIII of 05/16/2019 }
prohibition of interference, creation of restrictions in the functioning and/or possibilities for taxpayers to use the electronic account, as provided for by this Code;
priority of documents received from state bodies, including regulatory bodies, starting work in the electronic office with automatic opening of messages received from state bodies, and/or blocking the possibility of sending documents by a taxpayer until such taxpayer receives documents received in his electronic office from state bodies.
42 - 1 .2. The electronic office ensures the possibility of taxpayers exercising the rights and obligations defined by this Code and other laws, the control over compliance of which is entrusted to the regulatory authorities, and by regulatory legal acts adopted on the basis of and in implementation of this Code and other laws, the control over compliance of which is entrusted to the regulatory authorities, including by:
{Paragraph one of clause 42 - 1 .2 of Article 42 - 1 as amended by Law No. 466-IX of January 16, 2020 }
viewing information about the taxpayer that is collected, used and formed by regulatory authorities in connection with the accounting of taxpayers and the administration of taxes, fees, customs payments, single contribution, and tax control, including data on operational accounting of taxes, fees, single contribution (including data on integrated taxpayer cards), data from the electronic administration system for value-added tax, data from the electronic administration system for the sale of fuel and ethyl alcohol, as well as obtaining such information in the form of a document that is automatically formed by uploading the relevant information from the electronic cabinet with a qualified electronic signature of an official of the regulatory authority in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services";
{Paragraph two of clause 42 - 1 .2 of article 42 - 1 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 2725-VIII of 05/16/2019 ; as amended by Law No. 466-IX of 01/16/2020 ; as amended by Laws No. 786-IX of 07/14/2020 , No. 2918-IX of 02/07/2023 }
submission by the taxpayer of a notification on the use and refusal to use a single account;
{Paragraph 42 - 1 .2 of Article 42 - 1 supplemented with a new paragraph in accordance with Law No. 190-IX of 04.10.2019 }
determining the direction of use of the amount of erroneously and/or excessively paid monetary obligations and penalties in accordance with Article 35 - 1 of this Code;
{Paragraph 42 - 1 .2 of Article 42 - 1 supplemented with a new paragraph in accordance with Law No. 190-IX of 04.10.2019 }
viewing information on the single account, including from the Register of payments from the single account for an individual taxpayer;
{Paragraph 42 - 1 .2 of Article 42 - 1 supplemented with a new paragraph in accordance with Law No. 190-IX of 04.10.2019 }
conducting reconciliation of taxpayers' settlements with the state and local budgets, as well as obtaining a document confirming the status of settlements, which is formed automatically by uploading relevant information from the electronic account with a qualified electronic signature of an official of the controlling body in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services";
{Paragraph of clause 42 - 1 .2 of article 42 - 1 as amended by Laws No. 2725-VIII of 05/16/2019 , No. 2918-IX of 02/07/2023 }
management of amounts of erroneously and/or excessively paid monetary obligations and penalties in accordance with the provisions of this Code, including by submitting an application for the return of erroneously and/or excessively paid monetary obligations and/or penalties;
{Paragraph of clause 42 - 1 .2 of article 42 - 1 as amended by Law No. 466-IX of 16.01.2020 }
automated determination of tax reporting forms and invoices required to be completed and submitted for the payment of taxes and fees for a specific taxpayer;
filling out, checking and submitting tax returns and reports to the regulatory authority;
registration, adjustment of tax invoices /calculations in the Unified Register of Tax Invoices and excise invoices in the Unified Register of Excise Invoices;
viewing information about tax invoices /adjustment calculations, the registration of which in the Unified Register of Tax Invoices has been suspended;
{Paragraph of clause 42 - 1 .2 of article 42 - 1 as amended by Law No. 786-IX of 14.07.2020 }
taxpayers' access to the electronic administration system for value-added tax in terms of the current values of all addends and subtractions provided for in paragraph 200 - 1.3 of Article 200 - 1 of this Code, in real-time viewing mode and access to data from the Unified Register of Tax Invoices, including the ability to form, verify and confirm tax invoices drawn up by the taxpayer or its counterparties for transactions concluded between them, for the purposes of forming a tax credit by the taxpayer, verifying and determining the date and time of registration of such invoices and/or adjustment calculations, as well as viewing information on unregistered tax invoices and/or adjustment calculations to them submitted for registration by the taxpayer, indicating the reason for refusing their registration;
receipt by taxpayers of copies of orders to conduct inspections, notices of inspections, inspection reports (certificates), relevant requests and other documents drawn up in connection with the conduct and results of inspections and reconciliations provided for by this Code, as well as in connection with the consideration of taxpayers' objections to the results of inspections and/or taxpayer explanations;
{Paragraph of clause 42 - 1 .2 of Article 42 - 1 as amended by Law No. 466-IX of 16.01.2020 }
receipt by the taxpayer of information (notification) about interaction via video conference with the supervisory authority specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, in cases provided for by this Code;
{Paragraph fourteen of clause 42 - 1 .2 of Article 42 - 1 as amended by Law No. 3603-IX of 02/23/2024 }
ensuring the possibility of administrative appeal of decisions of regulatory bodies, including filing objections to the act or certificate that formalizes the results of the inspection, filing a complaint against a tax notice-decision or other decision, action or inaction of the regulatory body or an official of the regulatory body, etc.;
{Paragraph fifteen of clause 42 - 1 .2 of Article 42 - 1 as amended by Law No. 3603-IX of 02/23/2024 }
informing about the status of counterparties based on publicly available data from information resources of the central executive body that ensures the formation and implementation of state financial policy, other registers and databases maintained in accordance with this Code, including providing information about counterparties of the taxpayer in respect of whom a decision has been made to liquidate a legal entity, to cancel the registration of a value-added tax payer, or who have been held liable for violating laws on taxation (exclusively after final agreement on sanctions and obligations);
{Paragraph of clause 42 - 1 .2 of article 42 - 1 as amended by Laws No. 2725-VIII of 05/16/2019 , No. 2918-IX of 02/07/2023 ; as amended by Law No. 3603-IX of 02/23/2024 }
registration, making changes to accounting information (including, but not limited to, entering or changing information about persons entitled to sign tax reports, and qualified certificates of public keys of qualified electronic signatures and/or seals (if available), deregistration, transition to special taxation regimes and other registration actions;
{Paragraph seventeen of clause 42 - 1 .2 of Article 42 - 1 as amended by Law No. 3603-IX of 02/23/2024 }
submission of applications and other documents for obtaining licenses;
{Paragraph eighteen of clause 42 - 1 .2 of Article 42 - 1 as amended by Law No. 3603-IX of 02/23/2024 }
registration by the regulatory authority of registrars of settlement transactions and/or software registrars of settlement transactions, if such registration is provided for by law, submission of reports related to the use of the registrar of settlement transactions, settlement transaction accounting books and settlement books, submission of electronic copies of settlement documents and fiscal reporting checks, submission of information on the volume of settlement transactions performed in cash and/or non-cash form, or on the volume of transactions for trading in currency values in cash, etc.;
{Paragraph of clause 42 - 1 .2 of article 42 - 1 as amended by Law No. 129-IX of 20.09.2019 }
submitting a report about a technical and/or methodological error detected in the operation of the electronic office;
obtaining any document relating to such a taxpayer and which must be issued to him by the controlling authority in accordance with the legislation of Ukraine, or information from databases about such a taxpayer by downloading the relevant information from the electronic account with the imposition of a qualified electronic signature of an official of the controlling authority in accordance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" ;
{Paragraph of clause 42 - 1 .2 of Article 42 - 1 as amended by Law No. 2725-VIII of 05/16/2019 ; as amended by Law No. 2918-IX of 02/07/2023 }
ensuring interaction of taxpayers with regulatory authorities on other issues provided for by this Code, which can be implemented in electronic form by means of electronic communication;
submitting an application for individual tax advice in electronic form. If necessary, taxpayers can attach copies of the necessary documents to the application;
{Clause 42 - 1 .2 of Article 42 - 1 is supplemented by a paragraph in accordance with Law No. 466-IX of January 16, 2020 }
determination and changes of authorized persons of the taxpayer who have the right to use the electronic office, in particular regarding their signing, submission, and receipt of documents and information through the electronic office and determination of their powers;
{Clause 42 - 1 .2 of Article 42 - 1 is supplemented with a new paragraph in accordance with Law No. 786-IX of 14.07.2020 }
receipt by a taxpayer of tax information about other taxpayers with the prior consent of such persons, as well as receipt of such information in the form of a document in the form established by the central executive body that ensures the formation and implementation of financial policy, in electronic form with the seal of the controlling body.
{Clause 42 - 1 .2 of Article 42 - 1 is supplemented by a paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
A taxpayer can, through an electronic account, provide the regulatory authority with consent to disclose tax information about him to another taxpayer in a self-determined amount.
{Clause 42 - 1 .2 of Article 42 - 1 is supplemented by a paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
42 - 1.3 . Property rights to the software of the electronic office are state property.
42 - 1 .4. The methodologist of the electronic office provides:
a) determination of methodological and methodological foundations for the creation and functioning of an electronic office;
b) preparation and approval of the technical specifications for the development, updating, modification, and troubleshooting of the electronic office software;
c) approval and verification of software algorithms for compliance with legal requirements;
d) integrity and authenticity of the source code of the electronic office;
e) storage of data contained in the electronic account;
e) monitoring the storage of data contained in the electronic account, ensuring that there is no technical interference with the data or substitution of data in the electronic account;
e) establishing a deadline for eliminating a technical and/or methodological error in the operation of the electronic office, taking into account the criticality of the detected error and the technical possibility of eliminating it;
h) performing other functions necessary to ensure the functioning of the electronic office;
g) establishing deadlines for updating information in the electronic account, specified in paragraphs two and eight of clause 42 - 1.2 of this article.
{Clause 42 - 1 .4 of Article 42 - 1 is supplemented by subparagraph "g" in accordance with Law No. 786-IX of 14.07.2020 }
42 - 1 .5. The taxpayer becomes a user of the electronic office and acquires the right to submit reports in electronic form and conduct correspondence by electronic means of communication in electronic form after passing online electronic identification in the electronic office using a qualified electronic signature or an advanced electronic signature based on a qualified electronic signature certificate, in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" , or those identification services, the use of which is permitted by the methodologist of the electronic office.
{Paragraph one of clause 42 - 1 .5 of Article 42 - 1 as amended by Laws No. 2725-VIII of 05/16/2019 , No. 2918-IX of 02/07/2023 }
It is prohibited to require the taxpayer to take additional actions not provided for in this paragraph in order to obtain the right to use the electronic account.
The only reason for refusing to undergo electronic identification of a taxpayer in the electronic office is the invalidity of his qualified electronic signature or advanced electronic signature based on a qualified electronic signature certificate, or other means of electronic identification with a similar level of trust in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services", including in connection with the expiration of the relevant qualified electronic signature certificate.
{Paragraph three of clause 42 - 1 .5 of Article 42 - 1 as amended by Laws No. 2725-VIII of 05/16/2019 , No. 2918-IX of 02/07/2023 }
A taxpayer (except for a taxpayer who has acquired the status of an electronic resident (e-resident) who has been identified in the electronic office) independently determines the method of interaction with the regulatory authority, namely in the general manner or in electronic form, about which he makes a corresponding mark in the electronic office with the simultaneous mandatory indication of his email address (addresses). In the event of a change in the email address, the taxpayer is obliged to make appropriate changes to his account data in the electronic office no later than the next business day.
{Paragraph four of clause 42 - 1 .5 of article 42 - 1 as amended by Law No. 2654-IX of 06.10.2022 }
Starting from the day following the day the taxpayer chooses an electronic form of interaction with the regulatory authority through an electronic office, except for weekends and holidays, interaction between them, which can be implemented in electronic form by means of electronic communication, is carried out through an electronic office.
By sending a corresponding notification via the electronic account with documentary confirmation of the facts set forth therein (in the form of an electronic document in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" or scanned copies of the relevant documents), the taxpayer has the right to correct inaccurate, incomplete or outdated information about himself, access to which is provided to him via the electronic account (except for information that regulatory authorities receive from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations in accordance with the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations").
{Paragraph six of clause 42 - 1 .5 of Article 42 - 1 as amended by Law No. 466-IX of January 16, 2020 }
The supervisory authority is obliged to make appropriate corrections to the information databases of the central executive body implementing the state tax policy, after establishing the reliability and/or verification of the data, within two working days from the moment of receiving the notification. The supervisory authority is exempted from such obligation in cases where the taxpayer has not provided confirmation of the facts set forth in the notification.
{Paragraph of clause 42 - 1 .5 of Article 42 - 1 as amended by Law No. 466-IX of 16.01.2020 }
{Clause 42 - 1 .5 of Article 42 - 1 shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016}
42 - 1 .6. The electronic office is open continuously (24 hours on the date of each calendar day), except for the time required for its technical maintenance. Conducting technical maintenance of the electronic office on the day on which the deadline for submitting tax returns falls , and from 8 a.m. to 8 p.m. on any other calendar day is prohibited. Technical maintenance of the electronic office is carried out in the manner determined by the methodologist of the electronic office.
{Clause 42 - 1 .6 of Article 42 - 1 shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016}
42 - 1 .7. In the event that a taxpayer discovers a technical and/or methodological error in the operation of the electronic office, he has the right to send a notification about the detected technical and/or methodological error via the electronic office or in another way. A notification about a methodological error is sent to the electronic office methodologist. A notification about a technical error is sent simultaneously to the electronic office methodologist and the technical administrator.
{Clause 42 - 1 .7 of Article 42 - 1 shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016}
42 - 1 .8. The methodologist of the electronic office is obliged to check the presence of a methodological error within 72 hours after receiving a notification from the taxpayer, except for weekends and holidays, and to notify the taxpayer of the results of the check within the same period. If the methodologist of the electronic office recognizes the presence of a methodological error, he is obliged to eliminate it within a period determined by him taking into account the criticality of the detected error and the technical possibility of its elimination. If the methodological error leads to a violation of the rights of taxpayers or involves holding taxpayers liable, the methodologist sends a document to the electronic office and to the taxpayer's email address (addresses) notifying him of the existence of a methodological error and the time required to eliminate it and restore the violated rights of taxpayers. The methodologist notifies taxpayers of the elimination of a methodological error by sending a corresponding document with a notification to the electronic office and to the taxpayer's email address (addresses).
{Clause 42 - 1 .8 of Article 42 - 1 shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016}
42 - 1 .9. The technical administrator is obliged to check the presence of a technical error within 72 hours after receiving a notification from the taxpayer, except for weekends and holidays, and to notify the methodologist of the electronic office and the taxpayer of the results of which within the same period. If the technical administrator recognizes the presence of a technical error, he is obliged to eliminate such a technical error within the period determined by the methodologist of the electronic office, taking into account the criticality of the detected error and the technical possibility of its elimination. If a technical error leads to a violation of the rights of taxpayers or involves holding taxpayers liable, the technical administrator sends a document to the electronic office and to the taxpayer's email address (addresses) informing all taxpayers of the existence of a technical error and the time required to eliminate it and restore the violated rights of taxpayers. The technical administrator notifies taxpayers of the elimination of a technical error by sending a corresponding document with a notification to the electronic office and to the taxpayer's email address (addresses).
{Clause 42 - 1 .9 of Article 42 - 1 shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016}
42 - 1 .10. If a technical and/or methodological error or technical malfunctions are detected in the operation of the electronic office and such error/malfunctions are recognized by the technical administrator and/or methodologist of the electronic office or according to a notification on the official web portal of the central executive body implementing state tax policy, or its existence is confirmed by a court decision, there are no grounds for holding the taxpayer and/or his officials to administrative or criminal liability for violations of tax legislation that were caused exclusively by a technical and/or methodological error or technical malfunction in the operation of the electronic office.
{Clause 42 - 1 .10 of Article 42 - 1 as amended by Law No. 466-IX of January 16, 2020 }
42 - 1 .11. If the technical administrator or methodologist does not send a response on the results of checking the notification of a technical and/or methodological error within the time period established by this Code or denies the presence of a technical and/or methodological error in the operation of the electronic office, the taxpayer has the right to apply to court for the protection of his rights and protected interests, about which he shall notify the regulatory body, technical administrator and methodologist of the electronic office through the electronic office. During the entire period of judicial consideration of such an application of the taxpayer, it is prohibited to determine a monetary obligation for the taxpayer, apply penalties and accrue a penalty, initiate bringing the taxpayer and/or its officials to administrative or criminal liability for violations of tax legislation that were caused by a technical and/or methodological error in the operation of the electronic office.
{Clause 42 - 1 .11 of Article 42 - 1 shall enter into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016}
{Clause 42 - 1 .11 of Article 42 - 1 as amended by Law No. 466-IX of January 16, 2020 }
{The Code is supplemented by Article 42 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
Article 43. Conditions for the return of erroneously and/or excessively paid monetary obligations and penalties↑
{Title of Article 43 as amended by Law No. 1797-VIII of 21.12.2016 }
43.1. Erroneously and/or excessively paid amounts of monetary obligation shall be refunded to the payer in accordance with this Article and Article 301 of the Customs Code of Ukraine , except in cases where such payer has a tax debt.
Erroneously and/or excessively paid amounts of monetary obligations and penalties shall not be subject to refund to taxpayers in respect of whom (and/or in respect of their founders (participants), ultimate beneficial owners) decisions have been made to apply special economic and other restrictive measures (sanctions) in accordance with the procedure established by the Law of Ukraine "On Sanctions" during the period of application of such sanctions.
{Clause 43.1 of Article 43 supplemented by the second paragraph in accordance with Law No. 3317-IX of 10.08.2023 ; with amendments made in accordance with Law No. 3813-IX of 18.06.2024 }
{Clause 43.1 of Article 43 as amended by Law No. 4915-VI of 07.06.2012 }
43.2. In the event that a taxpayer has a tax debt, the return of the erroneously and/or excessively paid amount of the monetary obligation to the account of such taxpayer in a bank or non-bank payment service provider, or to a single account, or by returning cash by check, in the event that the taxpayer does not have an account in a bank or non-bank payment service provider, shall be carried out only after the full repayment of such tax debt by the taxpayer.
{ Clause 43.2 of Article 43 as amended by Law No. 190-IX of 04.10.2019 ; as amended by Law No. 2888-IX of 12.01.2023 }
43.3. A mandatory condition for the refund of monetary obligations and penalties is the taxpayer's submission of an application for such refund (except for the refund of excess withheld (paid) amounts of personal income tax, which are returned by the regulatory authority on the basis of the taxpayer's tax return for the reporting calendar year based on the results of the recalculation of his total annual taxable income) within 1095 days from the date of the erroneous and/or excessive amount and/or penalty payment.
{Clause 43.3 of Article 43 as amended by Law No. 466-IX of January 16, 2020 }
43.4. The taxpayer submits an application for the return of erroneously and/or excessively paid monetary obligations and penalties in an arbitrary form, in which he indicates the direction of transferring funds: to the taxpayer's account in a bank, non-bank payment service provider; to a single account (if used); to repay a monetary obligation and/or tax debt from other payments, control over the collection of which is entrusted to regulatory authorities, regardless of the type of budget; return of funds in cash if the taxpayer does not have an account in a bank, non-bank payment service provider.
{Clause 43.4 of Article 43 as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 190-IX of 04.10.2019 ; as amended by Law No. 2888-IX of 12.01.2023 }
43.4 - 1. In the event of a refund of overpaid tax liabilities on value added tax credited to the budget from the taxpayer's account in the electronic administration system of value added tax in the manner specified in paragraph 200 - 1.5 of Article 200 - 1 of this Code, such funds shall be refunded exclusively to the payer 's account in the electronic administration system of value added tax, and in the absence thereof at the time of the taxpayer's application for the refund of overpaid tax liabilities on value added tax or at the time of the actual refund of funds - by transfer to the taxpayer's account in a bank or non-bank payment service provider.
{Paragraph one of clause 43.4 - 1 of Article 43 as amended by Law No. 2888-IX of 12.01.2023 }
Refund in cases specified by law of amounts of value added tax, control over the collection of which is entrusted to the controlling body specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code, upon import of goods into the customs territory of Ukraine shall be carried out in the part not exceeding the amount calculated in accordance with paragraph 200 - 1.3 of Article 200 - 1 of this Code at the time of registration of the customs declaration /adjustment sheet, on the basis of which such refund will be made.
{Clause 43.4 - 1 of Article 43 supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Article 43 is supplemented by paragraph 43.4 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
43.5. The supervisory authority shall, no later than five working days before the expiration of the twenty-day period from the date of submission of the application by the taxpayer, prepare a conclusion on the return of the due amounts of funds from the relevant budget or from the single account and submit it for execution to the body that carries out treasury services for budget funds.
{Paragraph one of clause 43.5 of Article 43 as amended by Law No. 466-IX of 16.01.2020 }
In the event of a refund of personal income tax amounts returned by the controlling authority on the basis of a tax return submitted by the taxpayer for the reporting calendar year based on the results of recalculating his total annual taxable income, the relevant notification shall be sent by the controlling authority to the body that carries out treasury services for budget funds no later than five working days before the end of the sixty-day period from the date of receipt of the relevant tax return.
{Clause 43.5 of Article 43 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Based on the conclusion received, the body that carries out treasury servicing of budget funds, within five working days, returns erroneously and/or excessively paid monetary obligations and penalties to taxpayers in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph of clause 43.5 of Article 43 as amended by Law No. 1797-VIII of 21.12.2016 }
The controlling body is liable under the law for the untimely transfer to the body carrying out treasury services of budget funds, for the execution of the conclusion on the return of the relevant amounts of funds from the relevant budget or from the single account.
{Clause 43.5 of Article 43 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by the Law No. 1914-IX dated 30.11.2021 }
43.6. Refund of erroneously and/or excessively paid monetary obligations to taxpayers shall be carried out from the budget to which such funds were credited, or from a single account.
{Article 43 is supplemented by paragraph 43.6 in accordance with Law No. 1166-VII of March 27, 2014 ; as amended by Law No. 190-IX of October 4, 2019 }
Article 44. Requirements for confirmation of data specified in tax reporting, as well as documentary confirmation of compliance with the requirements of tax and other legislation, control over the implementation of which is entrusted to regulatory authorities↑
{Title of Article 44 as amended by Law No. 466-IX of January 16, 2020 }
44.1. For taxation purposes, taxpayers are required to keep records of income, expenses and other indicators related to the determination of objects of taxation and/or tax liabilities, based on primary documents, accounting registers, financial statements, other documents, information related to the calculation and payment of taxes and fees, the maintenance of which is provided for by law.
{Paragraph one of clause 44.1 of Article 44 as amended by Law No. 2970-IX of 20.03.2023 }
Taxpayers are prohibited from forming tax reporting indicators and customs declarations based on data not confirmed by the documents specified in the first paragraph of this paragraph.
In cases provided for in Article 216 of the Civil Code of Ukraine , taxpayers have the right to make appropriate changes to tax reporting in accordance with the procedure specified in Article 50 of this Code.
{Paragraph three of clause 44.1 of Article 44 as amended by Law No. 3609-VI of 07.07.2011 }
The requirements of this article regarding the accounting of income, expenses and other indicators related to the determination of objects of taxation and/or tax liabilities, based on primary documents, accounting registers, financial statements, other documents related to the calculation and payment of taxes and fees, also apply to non-residents who carry out economic activities in the territory of Ukraine through a permanent representative office (regardless of whether the non-resident has a registered (accredited, legalized) separate subdivision), and to foreign legal entities defined in subparagraph 133.1.5 of paragraph 133.1 of Article 133 of this Code.
{Clause 44.1 of Article 44 is supplemented by the fourth paragraph in accordance with Law No. 2970-IX of 20.03.2023 }
44.2. To calculate the taxable amount, the income tax payer uses accounting and financial reporting data on income, expenses, and financial results before taxation.
{Paragraph one of clause 44.2 of Article 44 as amended by Law No. 71-VIII of 28.12.2014 }
Taxpayers who, in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine" , apply international financial reporting standards, keep records of income and expenses and determine the object of taxation of income tax according to such standards, taking into account the provisions of this Code. Such taxpayers, when applying the provisions of this Code, which contain a reference to accounting provisions (standards), apply the relevant international financial reporting standards.
{Clause 44.2 of Article 44 is supplemented with a new paragraph in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 71-VIII of 28.12.2014 }
Legal entities - payers of a single tax that meet the criteria specified in subparagraph 3 of paragraph 291.4 of Article 291 of this Code, maintain simplified accounting of income and expenses for the purpose of calculating the object of taxation according to the methodology approved by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph three of clause 44.2 of Article 44 as amended by Law No. 4014-VI of 04.11.2011 ; as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 466-IX of 16.01.2020 }
{Paragraph four of clause 44.2 of Article 44 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
Non-residents who carry out economic activities in the territory of Ukraine through a permanent establishment, to calculate the object of taxation by income tax, use accounting and financial reporting data on income, expenses and financial result before taxation, relating to activities (transactions) carried out by these non-residents through permanent establishments, including if such data is taken into account by non-residents when preparing financial statements on activities outside Ukraine or consolidated financial statements.
{Clause 44.2 of Article 44 is supplemented by the fifth paragraph in accordance with Law No. 2970-IX of 20.03.2023 }
Foreign companies defined in subparagraph 133.1.5 of paragraph 133.1 of Article 133 of this Code shall keep records of income and expenses and determine the object of taxation of corporate income tax in accordance with international financial reporting standards, taking into account the provisions of this Code. Such taxpayers, when applying the provisions of this Code that contain a reference to accounting provisions (standards), shall apply the relevant international financial reporting standards.
{Clause 44.2 of Article 44 is supplemented by the sixth paragraph in accordance with Law No. 2970-IX of 20.03.2023 }
44.3. Taxpayers are obliged to ensure the storage of documents and information specified in paragraph 44.1 of this Article, as well as documents related to the implementation of the requirements of the legislation, the control over compliance with which is entrusted to the regulatory authorities, within the periods specified by law, but not less than:
44.3.1. 2555 days - for documents and information necessary for tax control, in accordance with Articles 39 and 39-2 , Clause 141.4 of Article 141 of this Code;
{Subclause 44.3.1 of clause 44.3 of Article 44 as amended by Law No. 3721-IX of 21.05.2024 }
44.3.2. 1825 days - for primary documents, accounting registers, financial statements, other documents related to the calculation and payment of taxes and fees, the maintenance of which is provided for by law, compiled by persons specified in clause 133.1 of Article 133, subparagraph 133.2.2 of clause 133.2 and clause 133.4 of Article 133 of this Code, as well as legal entities that have chosen a simplified taxation system, with the exception of documents to which a longer storage period applies in accordance with subparagraph 44.3.1 of this clause;
44.3.3. 1095 days - for other documents that are not subject to the requirements of subparagraphs 44.3.1 and 44.3.2 of this paragraph;
44.3.4. 1095 days - for documents related to the implementation of the requirements of other legislation, the control over compliance with which is entrusted to regulatory authorities, including permits.
The periods for storing documents and information specified in this paragraph are calculated from the date of submission of tax reporting or other reporting provided for by this Code, for the preparation of which the specified documents and/or information are used, and in case of failure to submit them - from the deadline for submitting such reporting provided for by this Code, and for documents related to the fulfillment of the requirements of other legislation, the control over compliance with which is entrusted to the regulatory authorities - from the date of the relevant business transaction (for the relevant permits - from the date of their expiration).
In the event of liquidation of a taxpayer, the documents specified in clause 44.1 of this article, for the period of activity of the taxpayer of at least 1825 days (2555 days - for documents and information necessary for tax control in accordance with Articles 39 and 39-2 , clause 141.4 of Article 141 of this Code), which preceded the date of liquidation of the taxpayer, shall be transferred to the archive in accordance with the procedure established by law.
{Paragraph three of subparagraph 44.3.4 of paragraph 44.3 of Article 44 as amended by Law No. 3721-IX of 21.05.2024 }
The periods for storing documents and information provided for in this paragraph shall be extended for the period of suspension of the limitation period in cases provided for in paragraph 102.3 of Article 102 of this Code.
{Clause 44.3 of Article 44 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 ; as amended by Laws No. 2628-VIII of 23.11.2018 , No. 466-IX of 16.01.2020 ; as amended by Law No. 2970-IX of 20.03.2023 }
44.4. If the documents specified in clause 44.1 of this article are related to the subject of the inspection, the conduct of the procedure for administrative appeal of the tax notice-decision adopted as a result of the inspection, or judicial proceedings, such documents must be kept until the end of the inspection and the period prescribed by law for appealing the decisions adopted as a result of the inspection and/or the resolution of the case by the court, but not less than the periods prescribed in clause 44.3 of this article.
In the event that a taxpayer receives information from a regulatory authority about the identified circumstances (facts) in accordance with Clause 86.14 of Article 86 of this Code that may indicate the performance of transactions with the aim of providing an unlawful benefit to an official of a foreign state, the documents specified in Clause 44.1 of this Article, if they confirm the specified circumstances (facts) and/or are the basis for recording transactions related to the specified circumstances (facts), shall be stored for the periods specified in Clause 44.3 of this Article, increased by 1095 days.
{Clause 44.4 of Article 44 is supplemented by the second paragraph in accordance with Law No. 4112-IX of 04.12.2024 }
44.5. In the event of loss, damage or premature destruction of the documents specified in paragraphs 44.1 and 44.3 of this Article, the taxpayer shall be obliged, within five days from the date of such event, to notify in writing (with the provision of documents drawn up in accordance with the legislation, confirming the occurrence of the event that led to such loss, damage or premature destruction of the documents) the supervisory authority at the place of registration in accordance with the procedure established by this Code for the submission of tax reporting, and the supervisory authority to which the customs clearance of the relevant customs declaration was carried out, authorization was granted in accordance with the Customs Code of Ukraine or permission to apply special (including transit) simplifications.
{Paragraph one of clause 44.5 of Article 44 as amended by Law No. 466-IX of 16.01.2020 }
The taxpayer is obliged to restore lost documents within 90 calendar days from the day following the day the notification is received by the regulatory authority.
In the event that the taxpayer provides notification in the manner and within the time limits specified in the first paragraph of this subparagraph and that it is impossible to conduct an audit of the taxpayer due to the loss, damage or premature destruction of documents by the taxpayer, the terms for conducting such audits (except for audits specified in Article 200 of this Code) shall be postponed until the date of restoration and submission of documents for audit within the time limits specified in this subparagraph, but for a period not exceeding 120 days.
{Paragraph three of clause 44.5 of Article 44 as amended by Law No. 466-IX of 01.16.2020 ; as amended by Law No. 1914-IX of 11.30.2021 }
In the event of failure to restore the documents specified in paragraphs 44.1 and 44.3 of this Article, or their repeated loss, damage or premature destruction, which occurred after the taxpayer exercised the right to restore them in accordance with the procedure provided for in this paragraph, it shall be deemed that such documents were absent from such taxpayer at the time of preparation of such reporting or at the time of his fulfillment of the requirements of customs, currency and other legislation, the control over compliance with which is entrusted to the regulatory authorities.
{Clause 44.5 of Article 44 is supplemented by the fourth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
44.6. If, before the end of the audit or within the time limits specified in Clause 86.7 of Article 86 of this Code, the taxpayer does not provide the officials of the controlling body conducting the audit with documents (regardless of the reasons for such failure to provide, except in cases of seizure of documents or other seizure by law enforcement agencies) confirming the indicators reflected by such taxpayer in tax reporting, it is considered that such documents were not available to such taxpayer at the time of preparation of such reporting.
{ Paragraph one of clause 44.6 of Article 44 as amended by the Law No. 466-IX dated 16.01.2020 }
If, after the end of the audit and before the supervisory authority makes a decision based on the results of such audit, a taxpayer provides, in accordance with the procedure set forth in Clause 86.7 of Article 86 of this Code, documents confirming the indicators reflected by such taxpayer in tax reporting that were not provided during the audit, such documents must be taken into account by the supervisory authority when considering the issue of making a decision.
{Paragraph two of clause 44.6 of Article 44 as amended by Laws No. 3609-VI of 07.07.2011 , No. 466-IX of 16.01.2020 }
44.7. If the official of the controlling body conducting the inspection refuses for any reason to take into account the documents provided by the taxpayer during the inspection, the taxpayer has the right, before the end of the inspection, to send by letter with a notification of delivery and a description of the enclosed documents or to provide directly to the controlling body conducting the inspection, copies of such documents (certified by the taxpayer's seal (if there is a seal) and the signature of the taxpayer - an individual or an official of the taxpayer - a legal entity).
{Paragraph one of clause 44.7 of Article 44 as amended by Law No. 1797-VIII of 21.12.2016 }
{ Paragraph two of clause 44.7 of Article 44 was excluded on the basis of the Law No. 466-IX dated 16.01.2020 }
If, during the audit, the taxpayer provides documents less than three days before the date of its completion or when the documents sent in the manner provided for in the first paragraph of this paragraph are received by the regulatory authority less than three days before the date of completion of the audit, the audit shall be extended for the period specified in Article 82 of this Code.
If the documents sent in the manner provided for in the first paragraph of this paragraph are received by the regulatory authority after the completion of the audit, the regulatory authority has the right not to make a decision based on the results of the audit and to schedule an unscheduled documentary audit of such a taxpayer.
{ Paragraph four of clause 44.7 of Article 44 as amended by the Law No. 466-IX dated 16.01.2020 }
44.8. Separate subdivisions that are designated as payers of a separate tax must keep records of such tax in accordance with the rules established by this Code.
Article 44 - 1. Documents on the ownership structure and ultimate beneficial owners of non - residents conducting business activities or receiving income in Ukraine↑
44 - 1 .1. The requirements of this article apply to the following persons:
a) non-residents who carry out economic activities in the territory of Ukraine through a permanent representative office (regardless of the presence of a registered separate subdivision);
b) foreign legal entities defined in subparagraph 133.1.5 of paragraph 133.1 of Article 133 of this Code.
The requirements of this article do not apply to non-residents who meet the conditions of paragraph 44 - 1.4 of this article.
44 - 1 .2. The persons specified in paragraph 44 - 1 .1 of this article are obliged to establish their own ownership structure and all ultimate beneficial owners, regularly update and store the relevant information on the territory of Ukraine and provide it to the supervisory authority in the cases and to the extent provided for by this article. Information on the ownership structure and ultimate beneficial owners must be stored for at least 1825 days from the day following the end of the reporting year to which it relates.
The terms "ultimate beneficial owner" and "ownership structure" are used in this article in the meanings given in the Law of Ukraine "On Prevention and Counteraction to the Legalization (Laundering) of Proceeds of Crime, Financing of Terrorism and Financing of the Proliferation of Weapons of Mass Destruction".
The notification of the ownership structure and ultimate beneficial owners of the persons specified in clause 44 - 1.1 of this article shall be submitted to the regulatory authority for the first time in electronic form within the time limits established by this Code for submitting a quarterly corporate income tax return.
Requirements for the form and content of the ownership structure for non-residents are determined in accordance with the Regulation on the form and content of the ownership structure, approved by the central executive body that ensures the formation and implementation of state financial policy. The procedure for providing notification of the ownership structure and ultimate beneficial owners by the persons specified in this article is approved by the central executive body that ensures the formation and implementation of state financial policy.
Individuals are required to keep information about all their ultimate beneficial owners and their own ownership structure up to date, update it, and notify the regulatory authority of changes within 30 business days of their occurrence.
Reporting on the ownership structure and ultimate beneficial owners is not part of the corporate income tax return.
The obligations stipulated by this clause shall be fulfilled by the persons specified in clause 44 - 1.1 of this article, independently or by appointing an authorized bank in accordance with the procedure established by clause 44 - 1.3 of this article.
44 - 1 .3. The provisions of this paragraph shall apply to persons specified in paragraph 44 - 1 .1 of this Article who have at least one account in a bank operating in accordance with the legislation of Ukraine.
44 - 1 .3.1. The person specified in paragraph 44 - 1 .1 of this article has the right to decide not to apply the requirements of paragraph 44 - 1 .2 of this article regarding the independent submission of information on the ownership structure and ultimate beneficial owners to the regulatory authority and to delegate the obligation to provide the relevant information to the bank (or banks) in which such person has an account (accounts). The relevant person shall indicate the decision made in the notification on the ownership structure and ultimate beneficial owners.
The provisions of paragraph 44 - 1.3 of this article shall apply starting from the reporting quarter for which the relevant decision was notified.
44 - 1 .3.2. A person who meets the requirements of paragraph 44 - 1 .3 of this article shall notify each bank (hereinafter referred to as the authorized bank) of the relevant decision in writing in any form.
44 - 1 .3.3. An authorized bank, to which the authority to provide information specified in paragraph 44 - 1 .2 of this Article has been delegated, shall be obliged to provide such information at the request of the supervisory authority within 10 business days from the date of receipt of the request.
44 - 1 .3.4. A person who meets the requirements of paragraph 44 - 1 .3 of this article has the right to change the authorized bank or the decision to apply this paragraph and independently provide the supervisory authority with the information provided for in paragraph 44 - 1 .2 of this article, noting this in the notification of the ownership structure and ultimate beneficial owners.
44 - 1 .4. Non-residents who meet at least one of the following conditions are not required to disclose information on the ownership structure and ultimate beneficial owners in accordance with the requirements of this article:
a) the owner of a significant stake of more than 75 percent in such a person is international financial organizations that, in accordance with international treaties of Ukraine, are granted privileges and immunities;
b) the non-resident is a public company whose shares are admitted to trading on a foreign organized stock market (stock exchange) included in the list formed in accordance with the requirements of Part Eight , Article 5 - 1 of the Law of Ukraine "On Prevention and Counteraction to the Legalization (Laundering) of Proceeds of Crime, Financing of Terrorism and Financing of the Proliferation of Weapons of Mass Destruction".
{The Code is supplemented by Article 44 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 44 - 2. Financial statements and documents of trusts managed by residents of Ukraine↑
44 - 2 .1. Individuals and legal entities - residents of Ukraine, who, on a contractual basis, manage the activities, assets or property of a trust (are trustees) or perform the duties of an administrator of such a trust, are obliged to:
1) notify the regulatory authority about the conclusion and termination of the agreement on the management or administration of the trust;
2) store in the territory of Ukraine and provide upon request to the regulatory authority information about the founders, trustee, protectors (if any), beneficiary(ies) or group of beneficiary(ies), as well as any other individuals who are the ultimate beneficial owners of the trust (including through the chain of control/ownership);
3) store in the territory of Ukraine and provide, upon request, to the regulatory authority, separate financial reporting on the trust, as well as documents specified in Clause 44.1 of Article 44 of this Code, which confirm the data of such reporting.
44 - 2 .2. A notification of the conclusion of an agreement on the management or administration of a trust shall be sent to the supervisory authority within 30 calendar days from the date of its conclusion or termination. The form and procedure for sending such a notification shall be established by the central executive authority that ensures the formation and implementation of state financial policy.
44 - 2 .3. The terms "trust" , "ultimate beneficial owner" , "beneficiary (beneficiary) of the trust" are used in this article in the meanings given in the Law of Ukraine "On Prevention and Counteraction to the Legalization (Laundering) of Proceeds of Crime, Financing of Terrorism and Financing of the Proliferation of Weapons of Mass Destruction".
Requirements for the form and content of the information provided for in subparagraph 2 of paragraph 44 - 2.1 of this article are determined in accordance with the Regulation on the form and content of the ownership structure, approved by the central executive body that ensures the formation and implementation of state financial policy.
Trust managers and administrators are required to maintain up-to-date information on all ultimate beneficial owners and the ownership structure of trusts, update it, and ensure that the supervisory authority, upon its request, provides the information provided for in this article within 10 calendar days from the date of receipt of the relevant request.
44 - 2 .4. The financial statements of a trust must be prepared in accordance with the requirements established by the legislation regulating the activities of the trust (personal law). If the personal law does not require the preparation of financial statements for the trust, the persons specified in paragraph 44 - 2 .1 of this Article are obliged to ensure the preparation of separate financial statements in accordance with international standards.
The manager or administrator of the trust shall ensure that the supervisory authority, upon its request, provides copies of the documents provided for in this Article within 30 calendar days from the date of receipt of the relevant request. The documents shall be provided in certified copies and with a translation into Ukrainian. In the case of submission of documents in English, a translation into Ukrainian is not required.
Trust documents are retained for a period of at least 1,825 days from the end of the reporting period to which they relate and at least 1,825 days from the date of termination of the trust or termination of the agreement under which the trust is managed or administered, whichever comes first.
44 - 2 .5. The requirements of this article apply to persons who are trustees or administrators of trusts, regardless of whether the requirements of article 39 - 2 apply to the ultimate beneficial owners of the relevant trusts. of this Code.
{The Code is supplemented by Article 44 - 2 in accordance with Law No. 2970-IX of 20.03.2023 }
45.1. A taxpayer - an individual is obliged to determine his tax address.
The tax address of a taxpayer - an individual is recognized as the place of residence at which he is registered as a taxpayer with the regulatory authority.
A taxpayer - an individual may have no more than one tax address at a time.
The tax address of a taxpayer - electronic resident (e-resident) is the electronic address specified by such a person in the application for acquiring the status of electronic resident (e-resident).
{Clause 45.1 of Article 45 is supplemented by the fourth paragraph in accordance with Law No. 2654-IX of 06.10.2022 }
45.2. The tax address of a legal entity (separate subdivision of a legal entity) is the location of such a legal entity, information about which is contained in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations.
{Paragraph one of clause 45.2 of Article 45 as amended by Laws No. 4834-VI of 05/24/2012 , No. 466-IX of 01/16/2020 }
The tax address of an enterprise transferred to trust management is the location of the trust owner.
45.3. A taxpayer who chooses to interact with the regulatory authority via electronic means of communication in electronic form is obliged, when choosing the method of interaction, to notify the regulatory authority of his/her electronic address(es) by entering this information into his/her account data via his/her electronic account.
{Article 45 is supplemented by paragraph 45.3 in accordance with Law No. 1797-VIII of 21.12.2016 - the change comes into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of paragraph 1 of Section II of Law No. 1797-VIII of 21.12.2016}
46.1. Tax declaration , calculation, report (hereinafter referred to as tax declaration) - a document submitted by a taxpayer (including a separate subdivision in cases specified by this Code) to the regulatory authorities within the terms established by law, on the basis of which the accrual and/or payment of a monetary obligation, including a tax obligation, is carried out or the volumes of the transaction (transactions), income (profits) are reflected, in respect of which the tax and customs legislation provides for the exemption of the taxpayer from the obligation to accrual and payment of tax and fees, or a document indicating the amounts of income accrued (paid) in favor of taxpayers - individuals, the amount of tax withheld and/or paid, as well as the amount of the accrued single contribution.
{Paragraph one of clause 46.1 of Article 46 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Laws No. 466-IX of 01/16/2020 , No. 116-IX of 09/19/2019 }
Customs declarations are equated with tax declarations for the purposes of calculating and/or paying tax liabilities.
Calculations (including the calculation of a portion of net profit (income), dividends on the state share) submitted to regulatory authorities in accordance with other legislation, the control over compliance with which is entrusted to regulatory authorities, are equated with a tax return .
{Clause 46.1 of Article 46 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Annexes to the tax return are an integral part of it.
46.2. A taxpayer (except for taxpayers who, in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", are required to publish annual financial statements and annual consolidated financial statements together with an audit report) shall submit, together with the relevant tax return , quarterly or annual financial statements in the manner prescribed for filing a tax return, taking into account the requirements of Article 137 of this Code.
Income tax payers who, in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", are obliged to publish annual financial statements and annual consolidated financial statements together with an audit report, shall submit, together with the tax return for the relevant tax (reporting) period, a statement of financial position (balance sheet) and a statement of profit and loss and other comprehensive income (statement of financial results), drawn up prior to the audit of the financial statements by the auditor. The statement of financial position (balance sheet) and the statement of profit and loss and other comprehensive income (statement of financial results) shall be submitted by taxpayers in accordance with this paragraph in the form determined in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", in the manner prescribed for the submission of a tax return, taking into account the requirements of Article 137 of this Code.
The financial statements or statement of financial position (balance sheet) and the statement of profit and loss and other comprehensive income (statement of financial results), submitted in accordance with paragraphs one and two of this paragraph, are an appendix to the corporate income tax return (report on the use of income (profits) of a non-profit organization, calculation of the share of net income (income), dividends on the state share) and its integral part.
Income tax payers who, in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", are obliged to publish annual financial statements and annual consolidated financial statements together with an audit report, shall submit to the supervisory authority annual financial statements, which are subject to publication together with an audit report, no later than June 10 of the year following the reporting year. In the event of failure to submit (untimely submission) annual financial statements, which are subject to publication together with an audit report, the liability provided for in paragraph 120.1 of Article 120 of this Code shall apply for the submission of tax returns (calculations).
For part of the net profit (income), the tax (reporting) periods are calendar: quarter, half-year, three quarters, year. For business companies, the corporate rights of which are partially owned by the state, and business companies, 50 or more percent of the shares (shares, units) of which are owned by business companies, the state share in which is 100 percent, which have not made a decision on the accrual of dividends by May 1 of the year following the reporting, the tax (reporting) period is the calendar year.
In this case, the calculation of the part of net profit (income) and dividends on the state share is made up as a cumulative total and submitted to the regulatory authorities together with the financial statements within the terms provided for in Article 49 of this Code.
Income tax payers - producers of agricultural products who have chosen an annual tax (reporting) period in accordance with subparagraph 137.4.1 of paragraph 137.4 of Article 137 of this Code, shall prepare and submit with the relevant tax return financial statements for the first half of the previous reporting year, for the previous reporting year and for the first half of the current reporting year.
Payers of part of net profit (income) and/or dividends on the state share submit a calculation of the part of net profit (income), dividends on the state share in the form approved by the central executive body that ensures the formation and implementation of state financial policy, and financial reporting.
{Paragraph eight of clause 46.2 of Article 46 as amended by Law No. 3813-IX of 18.06.2024 }
Non-profit enterprises, institutions and organizations defined in paragraph 133.4 of Article 133 of this Code shall submit a report on the use of income (profits) of the non-profit organization in the form approved by the central executive body that ensures the formation and implementation of state financial policy, and annual financial statements.
{Clause 46.2 of Article 46 as amended by Laws No. 652-VIII of 17.07.2015 , No. 909-VIII of 24.12.2015 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 }
46.3. If, in accordance with the rules specified in this Code, tax reporting for a separate tax is compiled on a cumulative basis, the tax return based on the results of the last tax period of the year is equated to the annual tax return. In such a case, the annual tax return is not filed.
46.4. If a taxpayer believes that the form of a tax declaration determined by the central executive body that ensures the formation and implementation of state financial policy increases or decreases his tax obligations, contrary to the norms of this Code for such a tax or fee, he has the right to indicate this fact in a specially designated place in the tax declaration.
{Paragraph one of clause 46.4 of Article 46 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
If necessary, the taxpayer may submit, together with such tax return, supplements to such return, drawn up in any form, which shall be considered an integral part of the tax return. Such supplement shall be submitted with an explanation of the reasons for its submission. A taxpayer who submits reporting in electronic form shall submit such supplement in electronic form.
{Paragraph two of clause 46.4 of Article 46 as amended by Laws No. 655-VIII of 17.07.2015 , No. 1797-VIII of 21.12.2016 }
46.5. The form of the tax declaration is established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph one of clause 46.5 of Article 46 as amended by Laws No. 5083-VI of 05.07.2012 , No. 466-IX of 16.01.2020 }
In the same manner, forms of tax declarations for local taxes and fees are established, which are mandatory for use by their payers (tax agents).
The form of the declaration of property status and income (tax declaration) is established taking into account the features specified in paragraph 179.9 of Article 179 of this Code.
The form of the simplified tax declaration , provided for in the second paragraph of paragraph 49.2 of Article 49 of this Code, and the procedure for taxpayers to transition to submitting such a declaration shall be established by the Cabinet of Ministers of Ukraine.
{Paragraph four of clause 46.5 of Article 46 as amended by Law No. 1525-IX of 03.06.2021 }
The form of the simplified tax declaration, provided for in paragraph three of clause 49.2 of Article 49 of this Code, as well as the features of its preparation and submission, are established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 46.5 of Article 46 is supplemented with a new paragraph in accordance with Law No. 1525-IX of 03.06.2021 }
The form, procedure and terms of submission of a customs declaration, as well as the procedure for accepting a customs declaration by the controlling authority, are determined taking into account the requirements of the customs legislation of Ukraine.
State bodies that establish tax return forms in accordance with this paragraph shall be obliged to publish such forms for use by taxpayers.
46.6. If, as a result of the introduction of a new tax or changes in taxation rules, tax reporting forms change, the central executive body responsible for the formation and implementation of state financial policy, which approved such forms, is obliged to publish new reporting forms.
{Paragraph one of clause 46.6 of Article 46 as amended by Law No. 466-IX of 16.01.2020 }
Until the determination of new forms of declarations (calculations) that come into force for the preparation of reports for the tax period following the tax period in which they were published, the forms of declarations (calculations) in force prior to such determination shall be valid.
{Paragraph two of clause 46.6 of Article 46 as amended by Law No. 4834-VI of 24.05.2012 }
After amendments are made to regulatory legal acts on taxation, the central executive body that ensures the formation and implementation of state financial policy must take measures related to the publication and application of such changes.
{Paragraph three of clause 46.6 of Article 46 as amended by Laws No. 5083-VI of 05.07.2012 ; as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 466-IX of 16.01.2020 }
The requirements of Articles 46-50 of this Code do not apply to the declaration of goods (products) imported into the customs territory of Ukraine or exported from it in accordance with the customs legislation of Ukraine (except for the cases specified in these Articles), as well as to other information declarations containing economic information about taxable persons that do not relate to the calculation of taxes.
{Paragraph four of clause 46.6 of Article 46 as amended by Law No. 116-IX of September 19, 2019 }
Article 47. Persons responsible for preparing tax reports↑
47.1. Responsibility for failure to submit, violation of the procedure for filling out tax reporting documents, violation of the deadlines for their submission to regulatory authorities, unreliability of the information provided in the specified documents shall be borne by:
47.1.1. legal entities, residents or non-residents of Ukraine, which are determined as taxpayers in accordance with this Code, as well as their officials.
{Paragraph one of subparagraph 47.1.1 of paragraph 47.1 of Article 47 as amended by Law No. 466-IX of January 16, 2020 }
Responsibility for violation of tax legislation by a separate subdivision of a legal entity lies with the legal entity of which it is a part;
47.1.2. individuals - taxpayers and their legal or authorized representatives in cases provided for by law;
48.1. A tax declaration shall be prepared in a form approved in accordance with the procedure determined by the provisions of Clause 46.5 of Article 46 of this Code and in force at the time of its submission.
The tax return form must contain the necessary mandatory details and comply with the norms and content of the relevant tax and fee.
48.2. Mandatory details are information that must be contained in the tax declaration form and in the absence of which the document loses the status specified by this Code with the onset of legal consequences provided for by law.
48.3. The tax declaration must contain the following mandatory details:
document type (reporting, clarifying, new reporting);
reporting (tax) period for which the tax return is submitted;
reporting (tax) period being specified (for a clarifying calculation);
full name (surname, first name, patronymic) of the taxpayer according to registration documents;
taxpayer code according to the Unified State Register of Enterprises and Organizations of Ukraine or tax number;
taxpayer registration card registration number or series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the taxpayer registration card registration number and have notified the relevant regulatory authority and have a mark in their passport);
location (place of residence) of the taxpayer;
name of the supervisory authority to which the report is submitted;
date of report submission (or date of completion - depending on the form);
information about the annexes attached to the tax return and forming an integral part of it;
{Clause 48.3 of Article 48 is supplemented with a new paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
initials, surnames and registration numbers of registration cards or other information specified in paragraph seven of this paragraph, of officials of the taxpayer;
{Paragraph 48.3 of Article 48 as amended by Law No. 4834-VI of 24.05.2012 }
signatures of the taxpayer - an individual and/or officials of the taxpayer, defined by this Code, certified by the taxpayer's seal (if any).
48.4. In certain cases, when it corresponds to the essence of the tax or fee and is necessary for its administration, the tax declaration form may additionally contain the following mandatory details:
a note about reporting under a special regime;
code of type of economic activity (KVED);
local government body code according to KATOTTG ;
{Paragraph four of clause 48.4 of Article 48 as amended by Law No. 3813-IX of 18.06.2024 }
administrative-territorial unit code according to KATOTTG ;
{ Clause 48.4 of Article 48 is supplemented with a new paragraph in accordance with Law No. 3813-IX of 18.06.2024 }
individual tax number according to the data of the register of value added tax payers for the reporting (tax) period;
{Paragraph 48.4 of Article 48 as amended by Law No. 657-VII of October 24, 2013 }
date and number of the decision to include the non-profit organization in the Register of Non-Profit Institutions and Organizations;
{Clause 48.4 of Article 48 is supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
a sign of unprofitability of the organization;
{Clause 48.4 of Article 48 is supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
full name of the non-resident;
{Clause 48.4 of Article 48 is supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
location of the non-resident;
{Clause 48.4 of Article 48 is supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
name and code of the country of residence of the non-resident;
{Clause 48.4 of Article 48 is supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
non-resident code assigned by the state of which he is a resident.
{Clause 48.4 of Article 48 is supplemented by a paragraph in accordance with Law No. 466-IX of January 16, 2020 }
48.5. The tax return must be signed:
48.5.1. by the head of the taxpayer or an authorized person, as well as by the person responsible for keeping accounting records and submitting the tax return to the regulatory authority. In the case of keeping accounting records and submitting the tax return directly by the head of the taxpayer, such tax return shall be signed by such head;
{Paragraph one of subparagraph 48.5.1 of paragraph 48.5 of Article 48 as amended by Law No. 4834-VI of 24.05.2012 }
Sufficient confirmation of the authenticity of a tax reporting document is the presence of the original signature of an authorized person on the document in paper form or the presence of a qualified electronic signature or an advanced electronic signature based on a qualified electronic signature certificate superimposed on an electronic document, in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services".
{Subclause 48.5.1 of clause 48.5 of Article 48 is supplemented by the second paragraph in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 2725-VIII of 16.05.2019 , No. 2918-IX of 07.02.2023 }
48.5.2. an individual taxpayer or his representative;
{Subclause 48.5.2 of Clause 48.5 of Article 48 as amended by Law No. 655-VIII of 17.07.2015 }
48.5.3. the person responsible for maintaining accounting records and submitting tax returns in accordance with a joint venture agreement or a production sharing agreement.
48.6. If a tax return is submitted by tax agents - legal entities, it must be signed by the head of such agent and the person responsible for maintaining accounting records and submitting the tax return of such agent, and if the tax agent is a taxpayer - an individual - by such taxpayer.
48.7. Tax reporting prepared in violation of the provisions of this Article shall not be considered a tax return, except in cases established by Clause 46.4 of Article 46 of this Code.
{Clause 48.7 of Article 48 as amended by Law No. 3609-VI of 07.07.2011 }
Article 49. Submission of a tax return to regulatory authorities↑
49.1. A tax declaration shall be submitted for the reporting period within the time limits established by this Code to the supervisory authority with which the taxpayer is registered.
49.2. A taxpayer is obliged to submit tax returns for each reporting period established by this Code in which taxable items arise, or in the event of the presence of indicators subject to declaration, in accordance with the requirements of this Code, for each separate tax of which he is a payer. This paragraph applies to all taxpayers, including payers who are on a simplified system of taxation, accounting and reporting.
{Paragraph one of clause 49.2 of Article 44 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
Payers of corporate income tax who are taxed at a zero percent rate in accordance with Clause 44 of Subsection 4 of Section XX "Transitional Provisions" of this Code shall submit corporate income tax declarations (calculations) to the supervisory authorities in a simplified form in accordance with the procedure established by this Code.
{Paragraph two of clause 49.2 of Article 44 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
Value-added tax payers registered in accordance with Clause 208-1.2 of Article 208-1 of this Code shall submit to the central executive body implementing state tax policy a simplified tax return in accordance with Clause 208-1.8 of Article 208-1 of this Code.
{Clause 49.2 of Article 49 is supplemented by the third paragraph in accordance with Law No. 1525-IX of 03.06.2021 }
49.2 - 1. Payers defined by subparagraph 212.1.15 of paragraph 212.1 of Article 212 of this Code, as well as other excise tax payers who have valid licenses for the right to carry out activities with excisable products subject to licensing in accordance with the legislation, are obliged to submit tax returns for each reporting period established by this Code, regardless of whether such payers conducted economic activities in the reporting period.
{Article 49 is supplemented by paragraph 49.2 - 1 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 3813-IX of 18.06.2024 }
49.3. A tax return shall be filed at the taxpayer's choice, unless otherwise provided for by this Code, in one of the following ways:
a) personally by the taxpayer or a person authorized to do so;
b) sent by mail with a return receipt and a description of the attachment;
c) by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Subparagraph "c" of paragraph 49.3 of Article 49 as amended by Law No. 2725-VIII of 16.05.2019 }
The only reason for not accepting a tax return by electronic means in electronic form is the invalidity of a qualified electronic signature or an advanced electronic signature based on a qualified electronic signature certificate of such a taxpayer in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services", including in connection with the expiration of the relevant qualified electronic signature certificate, provided that such a tax return meets all the requirements of an electronic document, contains reliable mandatory details and is provided in a format accessible for its technical processing.
{Paragraph five of clause 49.3 of Article 49 as amended by Laws No. 2725-VIII of 05/16/2019 , No. 466-IX of 01/16/2020 ; as amended by Law No. 2918-IX of 02/07/2023 }
{Clause 49.3 of Article 49 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 1797-VIII of 21.12.2016 }
49.4. Taxpayers belonging to large and medium-sized enterprises shall submit tax returns to the regulatory authority in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Paragraph one of clause 49.4 of Article 49 as amended by Law No. 2725-VIII of 16.05.2019 }
Value-added tax tax reporting is submitted in electronic form to the regulatory authority by all payers of this tax in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Paragraph two of clause 49.4 of Article 49 as amended by Law No. 2725-VIII of 16.05.2019 }
Financial statements, statement of financial position (balance sheet) and statement of profit and loss and other comprehensive income (statement of financial results), submitted in accordance with the requirements of Clause 46.2 of Article 46 of this Code, shall be submitted in electronic form in compliance with the requirements of the Laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" to regulatory authorities by payers of corporate income tax, payers of part of net profit (income), payers of dividends on state shares and non-profit enterprises, institutions, organizations that submit tax reports in electronic form.
{Clause 49.4 of Article 49 is supplemented with a new paragraph in accordance with Law No. 466-IX of 01.16.2020 ; as amended in accordance with Law No. 3813-IX of 06.18.2024 }
{Paragraph four of clause 49.4 of Article 49 was excluded on the basis of Law No. 786-IX of 14.07.2020 }
{Paragraph five of clause 49.4 of Article 49 was excluded on the basis of Law No. 786-IX of 14.07.2020 }
{Clause 49.4 of Article 49 as amended by Laws No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
49.4 - 1. A qualified provider of electronic trust services of the central executive body implementing state tax policy shall provide qualified electronic trust services to taxpayers free of charge.
{Article 49 is supplemented by paragraph 49.4 - 1 in accordance with Law No. 404-VII of 04.07.2013 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2725-VIII of 16.05.2019 }
49.5. In the event of sending a tax return by mail, the taxpayer is obliged to send it to the address of the relevant regulatory authority no later than five days before the deadline for submitting a tax return specified in this article, and when submitting tax reporting in electronic form, no later than the end of the last hour of the day on which such deadline expires.
{Clause 49.5 of Article 49 as amended by Laws No. 3609-VI of 07.07.2011 , No. 655-VIII of 17.07.2015 }
49.6. In the event of loss or damage to a postal item or delay in its delivery to the regulatory authority due to the fault of the postal operator, such operator shall be liable in accordance with the law.
{Paragraph one of item 49.6 of Article 49 as amended by the Law No. 466-IX dated 16.01.2020 }
The taxpayer, within five business days from the date of receipt of the notification of the loss or damage of the postal item, is obliged to send by mail or provide in person (at his choice) to the supervisory authority a second copy of the tax return together with a copy of the notification of the loss or damage of the postal item.
49.7. Regardless of the fact of loss or damage of such postal item or delay in its delivery, the taxpayer is obliged to pay the amount of tax liability independently determined by him in such tax declaration within the terms established by this Code.
49.8. Acceptance of a tax return is the responsibility of the controlling authority. When accepting a tax return, an authorized official of the controlling authority with which the taxpayer is registered shall be obliged to verify the presence and accuracy of all mandatory details provided for in paragraphs 48.3 and 48.4 of Article 48 of this Code. Other indicators specified in the taxpayer's tax return shall not be subject to verification before its acceptance.
49.9. Provided that the taxpayer complies with the requirements of this article, an official of the regulatory body with which the taxpayer is registered shall be obliged to register the taxpayer's tax return on the date of its actual receipt by the regulatory body.
Provided that the requirements established by Articles 48 and 49 of this Code are met, the tax return submitted by the payer shall also be deemed accepted:
49.9.1. if there is a mark (stamp) on all sheets of the tax return and, at the request of the taxpayer, on its copies, of the controlling authority that received the tax return, indicating the date of its receipt, or a receipt of acceptance of the tax return in the case of its submission by electronic means, or a postal notification with a mark of delivery to the controlling authority, in the case of sending the tax return by mail;
{Sub-clause 49.9.1 of clause 49.9 of Article 49 as amended by the Law No. 466-IX dated 16.01.2020 }
49.9.2. if the supervisory authority, in compliance with the requirements of paragraph 49.11 of this Article, does not provide the taxpayer with a notice of refusal to accept the tax return or, in the cases specified in this paragraph, does not send it to the taxpayer within the period established by this Article.
49.10. Refusal by an official of a controlling body to accept a tax return for any reasons not specified in this article, including the putting forward of any preconditions for such acceptance not specified in this article (including changing the indicators of such a tax return, reducing or canceling the negative value of objects of taxation, amounts of budget compensation, illegal increase in tax liabilities, etc.) is prohibited.
49.11. In the event that a taxpayer submits to the supervisory authority a tax return filled out in violation of the requirements of paragraphs 48.3 and 48.4 of Article 48 , as well as failure to comply with the requirements of paragraphs one to three of paragraph 49.4 of Article 49 of this Code, the supervisory authority is obliged to provide such taxpayer with a written notice of refusal to accept his tax return, indicating the reasons for such refusal:
{Paragraph one of item 49.11 of Article 49 as amended by the Law No. 466-IX dated 16.01.2020 }
49.11.1. in case of receipt of such a tax return sent by mail or by electronic means - within five business days from the date of its receipt;
49.11.2. in case of receipt of such a tax return personally from the taxpayer or his representative - within three business days from the date of its receipt.
49.12. In the event of a refusal by the regulatory authority to accept a tax return, the taxpayer has the right to:
49.12.1. submit a tax return and pay a fine in case of violation of the deadline for its submission;
49.12.2. appeal the decision of the regulatory authority in accordance with the procedure provided for in Article 56 of this Code.
49.13. If, in accordance with the procedure established by law, it is established that the controlling body (official) unlawfully refused to accept a tax return, the latter shall be considered accepted on the day of its actual receipt by the controlling body.
49.14. For each application by a taxpayer regarding a violation of this article by an official of a regulatory body, an official investigation shall be conducted in accordance with the law.
Based on the results of such an investigation, the guilty official of the regulatory body shall be held liable in accordance with the law.
49.15. A tax return is considered not submitted if the norms of paragraphs 48.3 and 48.4 of Article 48, paragraphs one - three of paragraph 49.4 of Article 49 of this Code are violated and the controlling body provides or sends a notice to the taxpayer about the refusal to accept his tax return, in particular by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" for tax returns submitted in this manner.
{Clause 49.15 of Article 49 as amended by Laws No. 3609-VI of 07.07.2011 , No. 466-IX of 16.01.2020 }
49.16. Regardless of the refusal to accept a tax return, the taxpayer is obliged to repay the tax liability independently determined by him in such tax return within the terms established by this Code.
{Clause 49.17 of Article 49 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 - the change comes into force on the first day of the month following the month of implementation of the electronic office software, but no later than January 1, 2018, see paragraph two of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
49.18. Tax returns, except as otherwise provided for by this Code, shall be submitted for the basic reporting (tax) period equal to:
49.18.1. calendar month (including in the case of payment of monthly advance payments) - within 20 calendar days following the last calendar day of the reporting (tax) month;
49.18.2. calendar quarter or calendar half-year (including in the case of payment of quarterly or half-yearly advance payments) - within 40 calendar days following the last calendar day of the reporting (tax) quarter (half-year);
49.18.3. calendar year, except for cases provided for in subparagraph 49.18.4 of this paragraph - within 60 calendar days following the last calendar day of the reporting (tax) year;
{Subclause 49.18.3 of clause 49.18 of Article 49 as amended by Laws No. 3050-IX of 11.04.2023 }
49.18.4. calendar year for individual income tax payers, including self-employed persons, - by May 1 of the year following the reporting year, except for cases provided for in Section IV of this Code;
{Subclause 49.18.4 of clause 49.18 of Article 49 as amended by Laws No. 4661-VI of 04/24/2012 , No. 2520-IX of 08/15/2022 }
{Subclause 49.18.5 of clause 49.18 of Article 49 was excluded on the basis of Law No. 2520-IX of 15.08.2022 }
49.18.6. calendar year for payers of income tax (including payers of part of net profit (income)), for a tax return (including calculation of part of net profit (income), dividends on the state share), which is calculated on a cumulative basis for the year, - within 60 calendar days following the last calendar day of the reporting (tax) year;
{Clause 49.18 of Article 49 is supplemented by subparagraph 49.18.6 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 786-IX of 14.07.2020 }
49.18.7. calendar year for payers of dividends on the state share (including business companies, the corporate rights of which are partially owned by the state, and business companies, 50 or more percent of the shares (shares, units) of which are owned by business companies, the state share in which is 100 percent, which have not made a decision on the accrual of dividends by May 1 of the year following the reporting year) for calculating the part of net profit (income), dividends on the state share - by July 1 of the year following the reporting year;
{Clause 49.18 of Article 49 is supplemented by subparagraph 49.18.7 in accordance with Law No. 466-IX of January 16, 2020 }
49.18.8. if a taxpayer is liquidated or reorganized (including before the end of the tax (reporting) period), a declaration on rent , environmental tax, local taxes and fees may be submitted for the tax (reporting) period to which the date of liquidation or reorganization falls, before the end of such reporting period.
{Clause 49.18 of Article 49 is supplemented by subparagraph 49.18.8 in accordance with Law No. 466-IX of January 16, 2020 }
49.19. If a tax return for a quarter, half-year, three quarters or a year is calculated on a cumulative basis based on the indicators of the base tax periods that make up such quarter, half-year, three quarters or a year (excluding advance payments), in accordance with the relevant section of this Code, the specified tax return shall be submitted within the terms specified in paragraph 49.18 of this Article for such base reporting (tax) period, except for the tax return on income tax and calculation of the portion of net profit (income), dividends on the state share, which are calculated on a cumulative basis for the year.
{Paragraph one of clause 49.19 of Article 49 as amended by the Laws No. 2245-VIII dated 07.12.2017 , No. 466-IX dated 16.01.2020 }
For payers of a part of net profit (income), tax (reporting) periods are calendar: quarter, half-year, three quarters, year. In this case, the calculation of the part of net profit (income), dividends on the state share is made up as a cumulative total and submitted to the regulatory authorities together with the financial statements within the terms stipulated in clause 49.18.2 of Article 49 of this Code (except for payers specified in subparagraph 49.18.7 of clause 49.18 of Article 49 of this Code).
{Clause 49.19 of Article 49 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
For payers of dividends on state shares (business companies, the corporate rights of which are partly owned by the state, and business companies, 50 or more percent of the shares (shares, units) of which are owned by business companies, the state share in which is 100 percent), tax (reporting) periods are the calendar year. In this case, the calculation of the part of net profit (income), dividends on state shares is prepared and submitted to regulatory authorities together with financial statements by July 1 of the year following the reporting year.
{Clause 49.19 of Article 49 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Business companies whose authorized capital includes corporate rights of the state, and business companies whose 50 or more percent of shares (shares, units) are in the authorized capitals of business companies in which the state share is 100 percent, which have not made a decision on accrual of dividends by May 1 of the year following the reporting year, submit once a year by July 1 of the year following the reporting year, a calculation of the part of net profit (income), dividends for the state share, compiled based on the results of the reporting year.
{Clause 49.19 of Article 49 is supplemented with a new paragraph in accordance with Law No. 466-IX of 16.01.2020 ; with amendments made in accordance with the Law No. 786-IX dated 14.07.2020 }
For the purposes of this Code, the term "base reporting (tax) period" should be understood as the first reporting (tax) period of the year, determined by the relevant section of this Code.
49.20. If the last day of the deadline for filing a tax return falls on a weekend or holiday, the last day of the deadline is considered to be the business day following the weekend or holiday.
{Paragraph one of clause 49.20 of Article 49 as amended by Law No. 2888-IX of 12.01.2023 }
The deadlines for filing a tax return may be extended in accordance with the rules and on the grounds provided for by this Code.
49.21. If, in accordance with the relevant section of this Code on issues of a separate tax or levy, a reporting (tax) period is not established, the tax return shall be filed and the tax liability shall be paid within the terms provided for in this paragraph for the monthly basic reporting (tax) period, except for cases where the filing of a tax return is not provided for in such section of this Code.
50.1. If in future tax periods (taking into account the limitation periods specified in Article 102 of this Code) the taxpayer independently (including based on the results of electronic verification) detects errors contained in a previously submitted tax return (except for the restrictions specified in this Article), he is obliged to send a clarifying calculation to such tax return in the form valid at the time of submission of the clarifying calculation.
{Paragraph one of clause 50.1 of Article 50 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5503-VI of 20.11.2012 }
The taxpayer has the right not to submit such a calculation if the relevant revised figures are indicated by him in the tax return for any subsequent tax period during which such errors were independently (including as a result of electronic verification) detected.
{Paragraph two of clause 50.1 of Article 50 as amended by Law No. 5503-VI of 20.11.2012 }
If the indicators of the annual financial statements published together with the audit report have changed compared to the indicators of the statement of financial position (balance sheet) and the statement of profit and loss and other comprehensive income (financial results report) submitted together with the tax return in accordance with paragraph two of paragraph 46.2 of Article 46 of this Code, and such changes have affected the indicators of the previously submitted annual corporate income tax return for the relevant tax (reporting) period, income tax payers who, in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", are obliged to publish annual financial statements and annual consolidated financial statements together with the audit report, shall submit a clarifying calculation to the annual tax return no later than June 10 of the year following the reporting year.
{Clause 50.1 of Article 50 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
A taxpayer who independently (including based on the results of an electronic check) discovers the fact of understatement of tax liability for past tax periods is obliged, except for the cases established by paragraph 50.2 of this Article:
{Paragraph of Clause 50.1 of Article 50 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5503-VI of 20.11.2012 }
a) or send a clarifying calculation and pay the amount of the underpayment and a penalty in the amount of three percent of such amount before submitting such clarifying calculation. This penalty shall not apply in the case of submitting a clarifying calculation to the tax return on corporate income tax for the previous tax (reporting) year for the purpose of making an independent adjustment in accordance with Article 39 of this Code or when determining the tax base in accordance with subparagraph 141.9 - 1 .3 of paragraph 141.9 - 1 of Article 141 of this Code in the case of conducting controlled transactions, if their conditions do not comply with the "arm's length" principle, no later than October 1 of the year following the reporting year;
{Paragraph of clause 50.1 of Article 50 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended in accordance with the Laws No. 2245-VIII dated 07.12.2017 , No. 1946-IX dated 14.12.2021 }
b) or reflect the amount of the underpayment in the declaration for this tax submitted for the tax period following the period in which the fact of underpayment of the tax liability was discovered, increased by the amount of a fine in the amount of five percent of such amount, with a corresponding increase in the total amount of the monetary liability for this tax.
If, after submitting a declaration for the reporting period, the taxpayer submits a new declaration with corrected figures before the deadline for submitting a declaration for the same reporting period or submits a clarifying declaration in subsequent tax periods as a result of fulfilling the requirements of Clause 169.4 of Article 169 of this Code, the penalties specified in this Clause shall not apply.
{Paragraph of Clause 50.1 of Article 50 as amended by Law No. 657-VII of 24.10.2013 }
50.1 - 1. In the event that a taxpayer receives information from the regulatory authority, in accordance with paragraph 86.14 of Article 86 of this Code, about the identified circumstances (facts) that may indicate the implementation of transactions with the aim of providing an illegal benefit to an official of a foreign state, and when determining the object of taxation, expenses resulting from such transactions were taken into account (for residents of the City of Diya - taxpayers under special conditions - regarding transactions), which led to a decrease in the object of taxation and/or an underestimation of the tax liability, such taxpayer has the right to submit to the regulatory authority a clarifying calculation for the relevant tax (reporting) period in which the specified expenses led to a decrease in the object of taxation and/or an underestimation of the tax liability.
In the event of submitting a clarifying calculation in accordance with paragraph one of this clause, the taxpayer shall be obliged to calculate and pay the amount of underpayment and a penalty in the amount of 9 percent of such amount before submitting such clarifying calculation. The clarifying calculation shall be submitted within 90 calendar days from the date of receipt of the notification from the controlling body in accordance with clause 86.14 of Article 86 of this Code.
Submission of a clarifying calculation on the grounds and in accordance with the procedure specified in the first paragraph of this paragraph, after the expiration of the term specified in the second paragraph of this paragraph, and before the entry into force of a court verdict of conviction for committing a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, in relation to a taxpayer or any other persons who acted on behalf of and/or in the interests of such taxpayer, but no later than 1095 days after the end of the reporting (tax) period in which the reduction of the object of taxation and/or underestimation of the tax liability occurred, entails the taxpayer's obligation to pay the amount of the underpayment and a penalty in the amount of 18 percent of such amount before submitting such a clarifying calculation.
If transactions to provide an illegal benefit to an official of a foreign state had an impact on the object of taxation by corporate income tax in several tax (reporting) periods, such calculation is submitted for each such period, taking into account the indicators of clarifying calculations submitted for previous tax (reporting) periods.
{Article 50 is supplemented by paragraph 50.1 - 1 in accordance with Law No. 4112-IX of 04.12.2024 }
50.2. During scheduled and unscheduled documentary inspections (taking into account the terms of extension, suspension or postponement of the terms of its conduct), the taxpayer does not have the right to submit clarifying tax declarations (calculations) to the previously submitted tax declarations for the relevant tax and fee for the reporting (tax) period that is being inspected by the controlling authority.
This rule does not apply to the cases established by the third paragraph of clause 50.1 of Article 50 of this Code.
{Clause 50.2 of Article 50 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 5503-VI of 20.11.2012 ; as amended by Law No. 466-IX of 16.01.2020 }
50.3. If a taxpayer submits a clarification calculation to the tax return filed for the period under review, except for the case of submitting a clarification calculation in accordance with the requirements of clause 50.1 - 1 of this article, or fails to submit a clarification calculation within 20 business days after the date of drawing up a certificate of electronic audit, which established a violation of tax legislation, the relevant regulatory authority has the right to conduct an unscheduled audit of the taxpayer for the relevant period.
{Clause 50.3 of Article 50 as amended by Laws No. 5503-VI of 11/20/2012 , No. 4112-IX of 12/04/2024 }
50.4. If a payer of local taxes (in terms of real estate tax other than land, land payment and single tax of the fourth group) submits a declaration due to changes in the object and/or tax base (based on data entered in the relevant state registers) after the deadline for submitting the reporting declaration, then penalties are not applied.
{Article 50 is supplemented by paragraph 50.4 in accordance with Law No. 466-IX of 16.01.2020 }
Article 51. Submission of reports on the amounts of income accrued (paid) to individual taxpayers and the amounts of tax withheld from them, as well as the amounts of the accrued single contribution↑
{Title of Article 51 as amended by Law No. 116-IX of September 19, 2019 }
51.1. Taxpayers, including tax agents, single contribution payers (except for individual entrepreneurs and/or persons engaged in independent professional activities as tax agents and single contribution payers) are obliged to submit to the regulatory authorities, within the terms established by this Code for the tax month, a tax calculation of the amounts of income accrued (paid) in favor of individual taxpayers, and the amounts of tax withheld from them, as well as the amounts of the accrued single contribution.
Individual entrepreneurs and individuals engaged in independent professional activities as tax agents, single contribution payers are required to submit to the regulatory authorities, within the terms established by this Code for the tax quarter, a tax calculation of the amounts of income accrued (paid) in favor of individual taxpayers, and the amounts of tax withheld from them, as well as the amounts of the accrued single contribution, broken down by months of the reporting quarter.
{Clause 51.1 of Article 51 as amended by Laws No. 116-IX of 09/19/2019 , No. 4015-IX of 10/10/2024 - regarding the entry into force of certain provisions, see clause 1 of Section II; as amended by Law No. 4536-IX of 07/16/2025 }
51.2. In the cases specified in this Code, calculations shall be submitted electronically.
{Article 51 as amended by Law No. 71-VIII of 28.12.2014 }
52.1. Upon the application of taxpayers in paper or electronic form, the supervisory authority specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code shall provide them with free individual tax consultations on the practical application of certain norms of tax and other legislation, the control over compliance with which is entrusted to such supervisory authority, within 25 calendar days following the date of receipt of such an application by this supervisory authority.
{Paragraph one of clause 52.1 of Article 52 as amended by Law No. 466-IX of 16.01.2020 }
Taxpayers' requests for individual tax advice in paper or electronic form must contain:
{Paragraph two of clause 52.1 of Article 52 as amended by the Law No. 466-IX dated 16.01.2020 }
name for a legal entity or surname, first name, patronymic for an individual, tax address, as well as communication number and email address, if available;
code according to the Unified State Register of Taxpayers (for legal entities) or the registration number of the taxpayer's registration card (for individuals) or the series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have officially notified the relevant regulatory authority about this and have a mark in their passport);
indication of the practical necessity of obtaining tax advice (statement of the factual circumstances);
{Paragraph five of clause 52.1 of Article 52 as amended by Law No. 466-IX of 16.01.2020 }
handwritten signature or qualified electronic signature, or advanced electronic signature based on a qualified electronic signature certificate, of the taxpayer in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services";
{Paragraph six of clause 52.1 of Article 52 as amended by Laws No. 466-IX of 01/16/2020 , No. 2918-IX of 02/07/2023 }
date of application.
{Paragraph seven of clause 52.1 of Article 52 as amended by the Law No. 466-IX dated 16.01.2020 }
Individual tax advice shall not be provided to a taxpayer's application that does not meet the requirements specified in this paragraph, but a response shall be sent under the signature of the head (deputy head or authorized person) in paper or electronic form in accordance with the procedure and terms provided for by the Law of Ukraine "On Citizens' Applications".
{Paragraph eight of clause 52.1 of Article 52 as amended by the Law No. 466-IX dated 16.01.2020 }
An authorized person of the central executive body implementing state tax policy may decide to extend the period for consideration of an application for individual tax advice beyond the 25-day period, but not more than 15 calendar days, and notify the taxpayer in writing in paper or electronic form before the expiration of the period specified in paragraph one of this paragraph.
{Paragraph nine of clause 52.1 of Article 52 as amended by Law No. 466-IX of 16.01.2020 }
Individual tax advice or a response provided by the regulatory authority in electronic form shall be accompanied by a qualified electronic signature of an authorized official of the regulatory authority in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Clause 52.1 of Article 52 is supplemented by the tenth paragraph in accordance with the Law No. 466-IX dated January 16, 2020 ; as amended by the Law No. 2918-IX dated 07.02.2023 }
52.2. Individual tax advice is of an individual nature and may be used exclusively by the taxpayer to whom such advice is provided.
52.3. At the taxpayer's choice, individual tax advice is provided orally, in paper or electronic form. Individual tax advice provided in paper or electronic form must necessarily contain the title - individual tax advice, registration number in the unified register of individual tax advice, description of the issues raised by the taxpayer, taking into account the factual circumstances indicated in the taxpayer's application, justification for the application of the legislative norms and a conclusion on the practical use of such legislative norms.
{Clause 52.3 of Article 52 as amended by Law No. 466-IX of January 16, 2020 }
52.4. Individual tax consultations are provided by:
orally - by the supervisory authority specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, as well as by state tax inspectorates;
in paper and electronic forms - by the controlling body specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, except for state tax inspectorates.
Individual tax advice provided in paper or electronic form is subject to registration in the unified register of individual tax advice and posting on the official website of the central executive body implementing state tax policy, without indicating the name (surname, first name, patronymic) of the taxpayer, the code according to the Unified State Register of Individual Taxpayers (registration number of the account card) and his tax address.
Access to the specified data of the unified register of individual tax consultations and the official website is free of charge and open. The procedure for maintaining and the form of the unified register of individual tax consultations are determined by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 52.4 of Article 52 as amended by Law No. 466-IX of January 16, 2020 }
52.5. The territorial body of the central executive body implementing the state tax policy is obliged to send the central executive body implementing the state tax policy an individual tax consultation within 15 calendar days following the date of receipt of the taxpayer's application for individual tax consultation, for consideration of the issue of entering information about such consultation into the unified register of individual tax consultations, of which it shall notify the taxpayer in accordance with the procedure specified in Article 42 of this Code.
{Paragraph one of clause 52.5 of Article 52 as amended by Law No. 466-IX of 16.01.2020 }
The central executive body implementing the state tax policy, having received individual tax advice from the territorial body (separate subdivision) of the central executive body implementing the state tax policy, shall, within 15 calendar days following the day of receipt of such advice, but no more than 40 calendar days following the day of receipt by the supervisory body of the relevant application from taxpayers, take one of the following decisions:
{Paragraph two of clause 52.5 of Article 52 as amended by Law No. 466-IX of 16.01.2020 }
on entering information about individual tax advice into the unified register of individual tax advice, which is notified within one working day from the moment of making the decision by the supervisory authority subordinate to it;
on refusal to enter information into the unified register of individual tax consultations, with the simultaneous provision of individual tax consultations to the taxpayer on his behalf and entry of information about such consultations into the specified register, which shall be notified within one working day from the moment of making the decision by the territorial body (separate subdivision) of the central executive body implementing state tax policy, and the taxpayer in accordance with the procedure specified in Article 42 of this Code;
{Paragraph four of clause 52.5 of Article 52 as amended by Law No. 466-IX of 16.01.2020 }
on the refusal to enter information into the unified register of individual tax consultations if the unified register of individual tax consultations already contains a similar individual tax consultation provided to such a taxpayer on the same issues as those specified in the request of such a taxpayer, which is notified within one business day from the moment of making the decision by the supervisory authority subordinate to it and the taxpayer.
{Clause 52.5 of Article 52 is supplemented by the fifth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
52.6. The central executive body that ensures the formation and implementation of state financial policy conducts periodic generalization of individual tax consultations, and also analyzes circumstances indicating the ambiguity of individual norms of tax and other legislation, the control over compliance with which is entrusted to the regulatory authorities, by providing general tax consultations , which are approved by order of this body.
General tax consultations are subject to publication on the official website of the central executive body that ensures the formation and implementation of state financial policy, within five calendar days from the date of their provision.
{Article 52 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.05.2012 , No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 , No. 655-VIII of 17.07.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
Article 53. Consequences of the use of tax advice↑
53.1. { Paragraph one of clause 53.1 of Article 53 is excluded on the basis of the Law No. 466-IX dated 16.01.2020 }
{ Paragraph two of clause 53.1 of Article 53 was excluded on the basis of the Law No. 466-IX dated 16.01.2020 }
In the event that the provisions of an individual tax consultation contradict the provisions of a general tax consultation, the provisions of the general tax consultation shall apply.
A taxpayer and/or tax agent who acted in accordance with tax advice shall not be exempted from the obligation to pay the tax liability specified in this Code.
53.2. A taxpayer may appeal to the court an order approving a general tax consultation or an individual tax consultation provided to him in paper or electronic form as a legal act of individual action, which, in the opinion of such taxpayer, contradicts the norms or content of the relevant tax or fee.
{Paragraph one of clause 53.2 of Article 53 as amended by Law No. 466-IX of 16.01.2020 }
Cancellation by the court of an order approving a general tax consultation or individual tax consultation is grounds for providing a new tax consultation taking into account the court's conclusions.
Within 30 calendar days from the date of entry into force of the court decision to cancel the order approving the general tax consultation or individual tax consultation, the central executive body that ensures the formation and implementation of state financial policy, or the supervisory body, taking into account the court's conclusions, is obliged to publish the general tax consultation or provide the taxpayer with individual tax consultation.
{Article 52 as amended by Laws No. 3609-VI of 07.07.2011 , No. 655-VIII of 17.07.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
CHAPTER 4. DETERMINATION OF THE AMOUNT OF TAX AND/OR MONETARY LIABILITIES OF A TAXPAYER, THE PROCEDURE FOR THEIR PAYMENT AND APPEAL OF DECISIONS OF CONTROLLING BODIES↑
Article 54. Determination of the amounts of tax and monetary obligations↑
54.1. Except in cases provided for by tax legislation, the taxpayer shall independently calculate the amount of tax and/or monetary obligation and/or penalty, which he shall indicate in the tax (customs) declaration or clarifying calculation submitted to the supervisory authority within the terms established by this Code. Such amount of monetary obligation and/or penalty shall be deemed agreed.
{Clause 54.1 of Article 54 as amended by Law No. 3609-VI of 07.07.2011 }
54.2. A monetary obligation regarding the amount of tax liabilities subject to withholding and payment (transfer) to the budget in the event of accrual/payment of income in favor of a taxpayer - an individual, is considered to be agreed upon by a tax agent or a taxpayer who receives income not from a tax agent, at the time of the tax liability arising, which is determined by the calendar date established by Section IV of this Code for the deadline for paying tax to the relevant budget.
54.3. The supervisory authority is obliged to independently determine the amount of monetary obligations, reduce (increase) the amount of budget compensation and/or reduce (increase) the negative value of the object of taxation by income tax or the negative value of the amount of value added tax of the taxpayer, provided for by this Code or other legislation, or reduce the amount of personal income tax declared for refund from the budget in connection with the taxpayer's use of the right to a tax discount, if:
{Paragraph one of clause 54.3 of Article 54 as amended by Laws No. 3609-VI of 07.07.2011 , No. 466-IX of 16.01.2020 }
54.3.1. the taxpayer fails to submit a tax (customs) declaration within the established time limits, and during the implementation of tax control measures, the facts of the taxpayer's performance of activities that led to the emergence of taxable objects, the presence of indicators subject to declaration in accordance with the requirements of this Code and the presence of valid licenses for the right to carry out activities with excisable products subject to licensing in accordance with the legislation are established;
{Subclause 54.3.1 of Clause 54.3 of Article 54 as amended by Laws No. 71-VIII of 12/28/2014 , No. 3813-IX of 06/18/2024 }
54.3.2. data from audits of the taxpayer's performance, in addition to electronic audits, indicate an underestimation or overestimation of the amount of his tax liabilities and/or other liability, the payment control of which is entrusted to the regulatory authorities, the amount of budget compensation and/or the negative value of the object of taxation by income tax or the negative value of the amount of value added tax of the taxpayer, or an overestimation of the amount of personal income tax subject to refund from the budget in connection with the taxpayer's use of the right to a tax discount, declared in tax (customs) declarations, clarifying calculations;
{Subclause 54.3.2 of Clause 54.3 of Article 54 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5503-VI of 20.11.2012 , No. 466-IX of 16.01.2020 }
54.3.3. in accordance with tax and other legislation, the person responsible for calculating the amounts of tax liabilities from a separate tax or fee and/or other liability, control over the payment of which is entrusted to the regulatory authorities, the application of punitive (financial) sanctions and the calculation of fines, including for violations in the field of foreign economic activity, is the regulatory authority;
{ Subparagraph 54.3.3 of paragraph 54.3 of Article 54 as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 54.3.4 of clause 54.3 of Article 54 was excluded on the basis of Law No. 655-VIII of 17.07.2015 }
54.3.5. data from inspections regarding withholding taxes at the source of payment, including by a tax agent, indicate a violation of the rules for the accrual, withholding, and payment to the relevant budgets of taxes and fees provided for by this Code, including personal income tax, by such a tax agent;
54.3.6. the results of customs control obtained after the completion of the customs clearance procedure and the release of goods indicate an understatement or overstatement of tax liabilities specified by the taxpayer in customs declarations.
54.4. In the event of receipt from authorized bodies of foreign states of documented information regarding the country of origin, value, quantitative or qualitative characteristics that are important for the taxation of goods and items upon import (shipment) into the customs territory of Ukraine or the territory of a free customs zone or export (shipment) of goods and items from the customs territory of Ukraine or the territory of a free customs zone, which differ from those declared during customs clearance, the controlling body has the right to independently determine the tax base and tax obligations of the taxpayer by carrying out the actions specified in paragraph 54.3 of this Article, based on the information specified in such documents.
{Clause 54.4 of Article 54 as amended by Law No. 4915-VI of 07.06.2012 }
54.5. If, in accordance with the provisions of this Article, the amount of a monetary obligation is calculated by a controlling body, the taxpayer shall not be liable for the timeliness, accuracy and completeness of the calculation of such amount, but shall be liable for the timely and full repayment of the calculated agreed monetary obligation and shall have the right to appeal the specified amount in accordance with the procedure established by this Code.
Article 55. Cancellation of decisions of supervisory bodies↑
55.1. A tax notice-decision on determining the amount of a taxpayer's monetary obligation or any other decision of a supervisory authority may be canceled by a higher-level supervisory authority during the procedure for its administrative appeal and in other cases if it is established that such decisions are inconsistent with legislative acts.
{Paragraph two of clause 55.1 of Article 55 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
55.2. The higher-level supervisory authorities for the purposes of this Code are:
the central executive body implementing state tax policy - for territorial bodies of the central executive body implementing state tax policy, their structural divisions (including for state tax inspectorates);
the central executive body implementing the state customs policy - for territorial bodies of the central executive body implementing the state customs policy.
{Clause 55.2 of Article 55 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
Article 56. Appealing decisions of supervisory bodies↑
56.1. Decisions made by the supervisory authority may be appealed administratively or in court.
56.2. If a taxpayer believes that the regulatory authority has incorrectly determined the amount of the monetary obligation or has made any other decision that contradicts the legislation or goes beyond the powers of the regulatory authority established by this Code or other laws of Ukraine, such taxpayer has the right to file a complaint for review of this decision with a higher-level regulatory authority.
{ Clause 56.2 of Article 56 as amended by Law No. 466-IX of 16.01.2020 }
56.3. The complaint shall be submitted to the higher-level supervisory authority in writing or electronically by electronic means (if necessary - with duly certified copies of documents, calculations and evidence that the taxpayer considers necessary to provide, taking into account the requirements of paragraph 44.6 of Article 44 of this Code) within 10 business days following the date of receipt by the taxpayer of the tax notice-decision or other decision of the supervisory authority being appealed.
{Paragraph one of item 56.3 of Article 56 as amended by the Law No. 1525-IX dated 03.06.2021 }
Filing a complaint electronically by electronic means is carried out by taxpayers who submit reports in electronic form and/or have undergone electronic identification online in the electronic office, in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{ Item 56.3 of Article 56 is supplemented with a new paragraph in accordance with the Law No. 1525-IX dated 03.06.2021 }
Within six months from the date of expiry of the period established by paragraph one of this paragraph, the taxpayer has the right to file a complaint together with a petition for renewal of the missed deadline for filing a complaint in an administrative procedure and copies of documents confirming the validity of the reasons for its omission (if any). The complaint may contain a petition for renewal of the missed deadline for filing a complaint in an administrative procedure. The higher-level supervisory body, considering the taxpayer's petition, shall renew the missed deadline for filing a complaint in an administrative procedure if it recognizes the reasons for its omission as valid.
Complaints against decisions of territorial bodies of the central executive body implementing the state tax policy shall be submitted to the central executive body implementing the state tax policy. In the complaint, the taxpayer has the right to state his/her desire to be present in person or through his/her representative during the consideration of the complaint, including via video conference, and the supervisory body shall be obliged to notify such taxpayer of the date, time and place/method of consideration of the complaint no later than five calendar days before the date of consideration of such complaint. Information (notification) on the consideration of the complaint materials by the supervisory body via video conference shall be sent to the taxpayer in electronic form to the electronic account. The absence of the taxpayer (his/her representative) notified in accordance with the procedure provided for in this paragraph of the date, time and place/method of consideration of the complaint (including via video conference) shall not be an obstacle to consideration of the complaint.
{Paragraph four of clause 56.3 of Article 56 as amended by Law No. 3603-IX of 02/23/2024 }
Complaints against decisions of territorial bodies of the central executive body implementing the state customs policy, regarding the performance of the functions of the supervisory body in accordance with subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code, shall be submitted to the central executive body implementing the state customs policy.
{Clause 56.3 of Article 56 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 404-VII of 04.07.2013 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2628-VIII of 23.11.2018 ; as amended by Law No. 466-IX of 16.01.2020 }
56.3 - 1. Complaints against decisions of territorial bodies of the central executive body implementing state tax policy, adopted by the supervisory body regarding non-residents carrying out activities in Ukraine through separate divisions, including permanent representative offices, shall be submitted to the supervisory body of a higher level within the terms specified in paragraph 56.3 of this Article, regarding:
{Paragraph one of item 56.3 - 1 of Article 56 as amended by the Law No. 1525-IX dated 03.06.2021 }
a) decision on tax registration of a non-resident;
b) a tax notice-decision issued in connection with the determination of a monetary obligation in accordance with the procedure provided for in subparagraph 141.4.2 of paragraph 141.4 of Article 141 of this Code;
c) a tax notice-decision issued in connection with the determination of a monetary obligation in accordance with the procedure provided for in paragraphs 117.1 and 117.4 of Article 117 of this Code;
d) a tax notice-decision issued in connection with the determination of a monetary obligation provided for in paragraph 133.3 of Article 133 of this Code.
The complaints of non-residents operating in Ukraine through separate divisions, including permanent representative offices, specified in this paragraph shall be considered in accordance with the general procedure established for the higher-level supervisory authority.
{Paragraph six of item 56.3 - 1 of Article 56 as amended by the Law No. 1525-IX dated 03.06.2021 }
{Paragraph seven of item 56.3 - 1 of Article 56 is excluded on the basis of the Law No. 1525-IX dated 03.06.2021 }
{ Article 56 supplemented by item 56.3 - 1 in accordance with the Law No. 466-IX dated 16.01.2020 }
56.4. During the administrative appeal procedure, the burden of proving that any assessment made by the supervisory authority in the cases specified in this Code, or any other decision of the supervisory authority is lawful, shall lie with the supervisory authority.
The obligation to prove the legality of the assessment or adoption of any other decision by the supervisory authority in a judicial appeal is established by procedural law.
56.5. The taxpayer, simultaneously with submitting a complaint to a higher-level regulatory body, is obliged to notify the regulatory body, which determined the amount of the monetary obligation or made another decision, in writing or electronically by means of electronic communication (in compliance with the requirements specified in paragraph 42.4 of Article 42 of this Code), of the appeal against its tax notice-decision or any other decision.
{ Clause 56.5 of Article 56 as amended by the Law No. 1525-IX dated 03.06.2021 }
{Clause 56.6 of Article 56 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
56.7. In the event of a decision by a higher-level supervisory authority to refuse a taxpayer the renewal of the missed deadline for filing an administrative complaint or the taxpayer violates the requirements of paragraph 56.3 of this Article (except for cases where the taxpayer has filed a petition for renewal of the missed deadline for filing an administrative complaint), the complaints filed by the taxpayer shall not be considered and shall be returned to him with an indication of the reasons for the return.
{ Clause 56.7 of Article 56 as amended by Law No. 466-IX of 16.01.2020 }
56.8. The supervisory authority that considers a taxpayer's complaint is obliged to make a reasoned decision and send it within 20 calendar days following the date of receipt of the complaint to the taxpayer's address by postal means (with notification of delivery) or electronic means (in compliance with the requirements specified in paragraph 42.4 of Article 42 of this Code) or provide it to him against receipt.
{ Clause 56.8 of Article 56 as amended by the Law No. 1525-IX dated 03.06.2021 }
56.9. The head (his deputy or authorized person) of the regulatory authority may decide to extend the period for considering a taxpayer's complaint beyond the 20-day period specified in clause 56.8 of this article, but not more than 60 calendar days, and notify the taxpayer thereof in writing or electronically by means of electronic communication (in compliance with the requirements specified in clause 42.4 of Article 42 of this Code) before the expiration of the period specified in clause 56.8 of this article.
{Paragraph one of clause 56.9 of Article 56 as amended by Laws No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 , No. 1525-IX of 03.06.2021 }
If a reasoned decision on a taxpayer's complaint is not sent to the taxpayer within a 20-day period or within a period extended by decision of the head (his deputy or authorized person) of the regulatory authority, such complaint shall be deemed to be fully satisfied in favor of the taxpayer from the day following the last day of the specified periods.
{Paragraph two of clause 56.9 of Article 56 as amended by Laws No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 }
The complaint is also considered to be fully satisfied in favor of the taxpayer if the decision of the head (his deputy or authorized person) of the supervisory authority to extend the time limits for its consideration has not been sent to the taxpayer before the expiration of the 20-day period specified in the first paragraph of this paragraph.
{Paragraph three of clause 56.9 of Article 56 as amended by Laws No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 }
56.10. Decisions of the central executive body implementing state tax policy and decisions of the central executive body implementing state customs policy, adopted upon consideration of a taxpayer's complaint, are final and are not subject to further administrative appeal, but may be appealed in court.
{Clause 56.10 of Article 56 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
56.11. A monetary obligation independently determined by a taxpayer is not subject to appeal.
{Clause 56.11 of Article 56 as amended by Law No. 3609-VI of 07.07.2011 }
56.12. If, in accordance with this Code, the regulatory authority independently determines the taxpayer's monetary liability for reasons not related to a violation of tax legislation, such taxpayer has the right to administratively appeal the decisions of the regulatory authority within 30 calendar days following the date of receipt of the tax notification-decision (decision) of the regulatory authority.
56.13. In the event that the last day of the periods specified in this article falls on a weekend or holiday, the first business day following the weekend or holiday shall be considered the last day of such periods.
56.14. The time limits for filing a complaint against a tax notice-decision or any other decision of the supervisory authority may be extended according to the rules and on the grounds specified in paragraph 102.6 of Article 102 of this Code.
56.15. A complaint filed within the time limits specified in the first paragraph of clause 56.3 of this article suspends the taxpayer's fulfillment of monetary obligations specified in the tax notice-decision (decision) for the period from the date of filing such a complaint with the regulatory authority until the date of completion of the administrative appeal procedure.
During the specified period, tax claims for the disputed tax shall not be sent, and the amount of the disputed monetary obligation shall be considered as not agreed.
{ Clause 56.15 of Article 56 as amended by Law No. 466-IX of 16.01.2020 }
56.16. The date of filing a complaint is considered to be the day of actual receipt of the complaint by the relevant supervisory authority, and in the case of sending a complaint by mail - the date of receipt by the postal office from the taxpayer of the postal item with the complaint, which is indicated by the postal office in the notification of delivery of the postal item or on the envelope.
56.17. The administrative appeal procedure ends:
56.17.1. on the day following the last day of the period provided for filing a complaint against a tax notice-decision or any other decision of the relevant regulatory authority, if such a complaint was not filed within the period provided for in the first paragraph of clause 56.3 of this Article;
{Subclause 56.17.1 of clause 56.17 of Article 56 as amended by Law No. 466-IX of 16.01.2020 }
56.17.2. on the day the taxpayer receives the decision of the relevant regulatory authority on the full satisfaction of the complaint;
56.17.3. on the day the taxpayer receives the decision of the central executive body implementing state tax policy;
{Subclause 56.17.3 of clause 56.17 of Article 56 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
56.17.3 - 1. on the day the taxpayer receives the decision of the central executive body implementing the state customs policy;
{ Clause 56.17 of Article 56 is supplemented by subparagraph 56.17.3 - 1 in accordance with Law No. 466-IX of 16.01.2020 }
56.17.4. excluded;
56.17.5. on the day of the taxpayer's application to the regulatory body with an application for installments, postponement of disputed monetary obligations.
The day of completion of the administrative appeal procedure is considered the day of reconciliation of the taxpayer's monetary obligation, except for the case provided for in subparagraph 108 - 1 .2.2 of paragraph 108 - 1 .2 of Article 108 - 1 of this Code.
{Paragraph 56.17 of Article 56 as amended by the Law No. 466-IX dated 16.01.2020 }
{Subclause 56.17.5 of clause 56.17 of Article 56 as amended by Law No. 3609-VI of 07.07.2011 }
56.18. Taking into account the limitation periods specified in Article 102 of this Code, a taxpayer has the right to appeal in court a tax notice - decision or other decision of a regulatory authority at any time after receiving such a decision.
{Paragraph one of clause 56.18 of Article 56 as amended by Law No. 657-VII of 24.10.2013 }
A decision of a regulatory authority appealed in court is not subject to administrative appeal.
The administrative appeal procedure is considered a pre-trial dispute resolution procedure.
When a taxpayer files a lawsuit with a court to declare the decision of the regulatory authority unlawful and/or to cancel it, the monetary obligation is considered unresolved until the day the court decision enters into force.
{Paragraph four of clause 56.18 of Article 56 as amended by Law No. 1797-VIII of 21.12.2016 }
{Clause 56.18 of Article 56 as amended by Law No. 3609-VI of 07.07.2011 }
56.19. In the event that an administrative appeal procedure was conducted prior to the filing of the claim, the taxpayer has the right to appeal in court the tax notice-decision or other decision of the supervisory authority on the assessment of a monetary obligation within the month following the date of completion of the administrative appeal procedure in accordance with paragraph 56.17 of this Article.
56.20. Requirements for filing a complaint, the procedure for submitting and considering complaints shall be established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 56.20 of Article 56 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
56.21. In the event that a provision of this Code or another regulatory legal act issued on the basis of this Code, or when provisions of different laws or different regulatory legal acts, or when provisions of the same regulatory legal act contradict each other and imply an ambiguous (multiple) interpretation of the rights and obligations of taxpayers or regulatory authorities, as a result of which there is an opportunity to make a decision in favor of both the taxpayer and the regulatory authority, the decision shall be made in favor of the taxpayer.
{Clause 56.21 of Article 56 as amended by Law No. 3609-VI of 07.07.2011 }
56.22. If a taxpayer appeals a decision of a regulatory authority administratively and/or in court, notification to a person of suspicion of committing a criminal offense of tax evasion cannot be based solely on this decision until the administrative appeal procedure is completed or until the case is finally resolved by a court.
{Paragraph one of clause 56.22 of Article 56 as amended by Law No. 404-VII of 04.07.2013 ; as amended by the Law No. 466-IX dated 16.01.2020 }
The initiation of a pre-trial investigation into a taxpayer or a notification of suspicion of a criminal offense by his officials cannot be a basis for suspending the proceedings in the case or leaving without consideration a complaint (claim) of such a taxpayer filed with the court within the framework of the procedure for appealing decisions of regulatory bodies.
{Paragraph two of clause 56.22 of Article 56 as amended by Law No. 404-VII of 04.07.2013 }
{Clause 56.22 of Article 56 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 4652-VI of 13.04.2012 }
56.23. Appealing a decision to refuse to register a tax invoice/adjustment calculation in the Unified Register of Tax Invoices is carried out in accordance with the procedure determined by the Cabinet of Ministers of Ukraine, taking into account the following features:
56.23.1. a complaint against the decisions provided for in this paragraph shall be submitted in accordance with the procedure established by the Cabinet of Ministers of Ukraine to the central executive body implementing state tax policy within 10 working days following the date of adoption of the contested decision;
56.23.2. a taxpayer who has filed a complaint against the decisions provided for in this paragraph has the right to participate in the consideration of the complaint materials in person or through his representative in the videoconference mode. Information (notification) about the consideration of the complaint materials by the supervisory authority in the videoconference mode shall be sent to the taxpayer in electronic form in the electronic office no later than five calendar days before the date of consideration of such complaint. The absence of the taxpayer (his representative), notified in the manner provided for in this paragraph about the date, time and method of consideration of the complaint materials by the supervisory authority in the videoconference mode, shall not be an obstacle to consideration of the complaint;
56.23.3. a complaint against decisions provided for in this paragraph shall be considered in accordance with the procedure determined by the Cabinet of Ministers of Ukraine, by a commission of the central executive body implementing state tax policy, within:
10 calendar days following the date of receipt of such a complaint, if the taxpayer who filed the complaint did not express a desire to participate in the consideration of the complaint;
30 calendar days following the date of receipt of such a complaint, if the taxpayer who filed the complaint expressed a desire to participate in the consideration of the complaint.
The deadline for considering a complaint cannot be extended;
56.23.4. if a reasoned decision on a taxpayer's complaint against the decisions provided for in this paragraph is not sent to the taxpayer within the period specified in subparagraph 56.23. 3 of this paragraph, such complaint shall be deemed to be fully satisfied in favor of the taxpayer from the day following the expiration of the specified period;
56.23.5. filing a complaint against the decisions provided for in this paragraph, annexes to the complaint, statements on the withdrawal of the complaint, sending information (notifications) provided for in this paragraph, decisions based on the results of consideration of such a complaint shall be made in electronic form by means of electronic communication in compliance with the requirements of this Code, the laws of Ukraine "On Electronic Documents and Electronic Document Management" , "On Electronic Identification and Electronic Trust Services" .
{Article 56 was supplemented by paragraph 56.23 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 466-IX dated 01/16/2020 ; as amended by Law No. 3603-IX dated 02/23/2024 }
56.24. A non-resident person may file a complaint with the central executive body implementing state tax policy within 90 calendar days following the date of receipt by the non-resident person of a tax notice to a non-resident drawn up in accordance with Article 58 - 1 of this Code.
56.24.1. A complaint about a tax notice to a non-resident person registered as a value-added tax payer shall be submitted in electronic form through a special portal solution for non-resident users who provide electronic services, by means of electronic identification in the state or English language. In the complaint, a non-resident person registered as a value-added tax payer shall have the right to declare his/her desire to be present at the consideration of the complaint, including by videoconference, and the supervisory authority shall be obliged to notify such non-resident person of the date, time and place/method of consideration of the complaint no later than 10 calendar days before the date of consideration of such complaint by sending the relevant document in electronic form through a special portal solution for non-resident users who provide electronic services and to the email address(es) of the non-resident person. The absence of a non-resident person notified in accordance with the procedure provided for in this paragraph of the date, time and place/method of considering the complaint shall not be an obstacle to considering the complaint.
{Paragraph one of subparagraph 56.24.1 of paragraph 56.24 of Article 56 as amended by the Law No. 3603-IX dated 23.02.2024 }
A complaint about a tax notice to a non-resident person not registered as a value added tax payer is submitted in accordance with the procedure established by international treaties of Ukraine, and in the absence of an international treaty of Ukraine with the country of the non-resident person - in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
56.24.2. A complaint against a tax notice to a non-resident person shall be considered within 90 calendar days following the date of receipt of such a complaint by the central executive body implementing state tax policy. The term for consideration of the complaint may not be extended.
If a reasoned decision on the complaint is not sent within 90 calendar days:
to a non-resident person registered as a value added tax payer, through a special portal solution for non-resident users who provide electronic services,
to a non-resident person not registered as a value added tax payer, in accordance with the procedure established by international treaties of Ukraine, and in the absence of an international treaty of Ukraine with the country of the non-resident person - in accordance with the procedure established by the Cabinet of Ministers of Ukraine,
such a complaint shall be deemed to be fully satisfied in favor of the non-resident person from the day following the last day of the specified period.
The procedure for considering a complaint by a non-resident person against a tax notice to a non-resident person is established by the central executive body that ensures the formation and implementation of state financial policy.
56.24.3. A decision on a complaint against a tax notice to a non-resident person registered as a value-added tax payer shall be sent in electronic form through a special portal solution for non-resident users who provide electronic services, with a simultaneous notification of sending such a decision to the non-resident person's electronic address specified by him or her upon registration in accordance with Article 208-1 of this Code. A decision on a complaint against a tax notice to a non-resident person not registered as a value - added tax payer shall be sent in accordance with the procedure established by international treaties of Ukraine, and in the absence of an international treaty of Ukraine with the country of the non-resident person - in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The form of the decision on a complaint against a tax notice to a non-resident person is established in the state and English languages and approved by the central executive body that ensures the formation and implementation of state financial policy.
{Article 56 is supplemented by paragraph 56.24 in accordance with Law No. 1525-IX of 03.06.2021 }
56.25. A non-resident person who is the account holder in accordance with Article 39 - 3 of this Code may file a complaint with the supervisory authority within 90 calendar days from the date of receipt by the non-resident person of a tax notice to a non-resident person about a violation of the requirements of the Common Reporting Standard CRS, drawn up in accordance with Clause 39 - 3.9 of Article 39 - 3 of this Code. In the complaint, the non-resident person has the right to declare his desire to be present at the consideration of the complaint, including by videoconference, and the supervisory authority is obliged to notify such non-resident person of the date, time and place/method of consideration of the complaint no later than 10 calendar days before the date of consideration of such complaint by sending the relevant document in electronic form to the electronic address (addresses) of the non-resident person. The absence of a non-resident person notified in accordance with the procedure provided for in this paragraph of the date, time and place/method of considering the complaint shall not be an obstacle to considering the complaint.
{Paragraph one of clause 56.25 of Article 56 as amended by the Law No. 3603-IX dated 23.02.2024 }
A complaint filed within the time limit specified in the first paragraph of this paragraph suspends the taxpayer's fulfillment of monetary obligations specified in the tax notice for the period from the date of filing such a complaint with the regulatory authority until the date of completion of the administrative appeal procedure.
56.25.1. A complaint about a tax notice to a non-resident person for violation of the requirements of the Common Reporting Standard (CRS) shall be considered by the supervisory authority within 90 calendar days from the date of its receipt. The period for considering the complaint may not be extended.
If a reasoned decision on the complaint is not sent to the non-resident person within 90 calendar days, such complaint shall be deemed to be fully satisfied in favor of the non-resident person from the day following the last day of the specified period.
The procedure for considering a complaint about a tax notice to a non-resident person for violation of the requirements of the Common Reporting Standard (CRS) is established by the central executive body that ensures the formation and implementation of state financial policy.
56.25.2. The form of the decision on a complaint against a tax notice to a non-resident person for violation of the requirements of the Common Reporting Standard CRS is established in the state and English languages and is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Article 56 is supplemented by paragraph 56.25 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 57. Deadlines for payment of tax liability↑
57.1. The taxpayer is obliged to independently pay the amount of tax liability specified in the tax return submitted by him within 10 calendar days following the last day of the relevant deadline provided for by this Code for submitting a tax return, except for cases established by this Code.
A tax agent is obliged to pay the amount of tax liability (the amount of accrued (withheld) tax), independently determined by him from the income paid to the taxpayer - an individual and at the expense of such payment, within the terms provided for by this Code.
The taxpayer is obliged to pay the amount of tax liability specified in the customs declaration before/or on the day of submission of the customs declaration.
{Paragraph four of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph five of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph six of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph seven of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph eight of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph nine of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph ten of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph eleven of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph twelfth of clause 57.1 of Article 57 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
If the deadline for paying a tax liability falls on a weekend or holiday, the last day for paying the tax liability is the business day following the weekend or holiday.
{Clause 57.1 of Article 57 is supplemented by the thirteenth paragraph in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 2888-IX of 01.12.2023 }
{Clause 57.1 of Article 57 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 , No. 403-VII of 04.07.2013 ; as amended by Law No. 71-VIII of 28.12.2014 }
57.1 - 1. Procedure for payment of tax liability for income tax upon payment of dividends
57.1 - 1 .1. In the event of a decision to pay dividends, the payer of income tax - the issuer of corporate rights on which dividends are accrued, shall make the specified payments to the owner of such corporate rights regardless of whether there is taxable profit calculated according to the rules specified in Article 137 of this Code.
57.1 - 1 .2. Except for the cases provided for in subparagraph 57.1 - 1 .3 of this paragraph, the issuer of corporate rights, which makes a decision on the payment of dividends to its shareholders (owners), shall calculate and pay to the budget an advance payment of income tax.
The advance payment is calculated from the amount of the excess of dividends payable over the value of the taxable object for the relevant tax (reporting) year, based on the results of which dividends are paid, the monetary obligation in respect of which has been repaid. In the event of an outstanding monetary obligation, the advance payment is calculated from the entire amount of dividends payable. The advance payment is calculated at the base (basic) rate established by Article 136 of this Code. The amount of dividends payable is not reduced by the amount of the advance payment.
{Paragraph two of subparagraph 57.1 - 1 .2 of paragraph 57.1 - 1 of Article 57 as amended by Law No. 3474-IX of 21.11.2023 }
In this case, if dividends are paid for an incomplete calendar year, then the value of the taxable object, calculated in proportion to the number of months for which dividends are paid, is used to calculate the amount of the specified excess. The specified advance payment is paid to the budget before/or simultaneously with the payment of dividends.
The amount of advance income tax contributions paid during the tax (reporting) period upon payment of dividends shall be credited to reduce the accrued income tax liability declared in the tax return for such tax (reporting) period.
{Paragraph four of subparagraph 57.1 - 1 .2 of paragraph 57.1 - 1 of Article 57 as amended by Law No. 1797-VIII of 21.12.2016 }
If the amount of the advance payment previously paid during the reporting period exceeds the amount of the tax liability accrued by the enterprise - the issuer of corporate rights for such tax (reporting) period, the amount of such excess is carried over to reduce tax liabilities of subsequent tax (reporting) periods until its full repayment, and when the taxable object of such subsequent period becomes negative - to reduce tax liabilities of future tax (reporting) periods until its full repayment.
{Subclause 57.1 - 1 .2 of clause 57.1 - 1 of Article 57 is supplemented with a new paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
The amount of advance payments for income tax paid upon payment of dividends is not subject to refund to the taxpayer or to be credited towards repayment of monetary obligations for other taxes and fees (mandatory payments).
of dividends in a form other than cash (except for the cases provided for in subparagraphs 57.1 - 1.3 of this paragraph), the basis for calculating the advance payment in accordance with paragraphs one and two of this subparagraph is the value of such payment determined in the decision on the payment of dividends, or the value of such payment calculated in accordance with the "arm's length" principle in transactions recognized as controlled in accordance with Article 39 of this Code. The obligation to calculate and pay the advance payment of tax at the basic (basic) rate specified in Article 136 of this Code shall be imposed on any issuer of corporate rights (except for single tax payers) that is a resident, regardless of whether such issuer uses tax benefits provided for in this Code or in the form of applying a tax rate other than the basic (basic) rate established in Article 136 of this Code.
{Paragraph seven of subparagraph 57.1 - 1 .2 of paragraph 57.1 - 1 of Article 57 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2245-VIII of 12/07/2017 , No. 3474-IX of 11/21/2023 }
This provision also applies to state unincorporated, state-owned or municipal enterprises that count the amount of dividends in the amount established by the executive body to whose jurisdiction such enterprises belong, in accordance with the state or local budget.
However, if a payment is called a dividend by a person, such payment is taxable at the time of payment in accordance with the norms determined in accordance with the provisions of this paragraph, regardless of whether the person is a taxpayer.
57.1 - 1 .3. The advance payment provided for in subparagraph 57.1 - 1 .2 of this paragraph shall not be made in the event of payment of dividends:
in favor of the owners of corporate rights of the parent company, paid within the limits of the amounts of income of such company, received in the form of dividends from other persons. If the amount of dividend payments in favor of the owners of corporate rights of the parent company exceeds the amount of dividends received by such company, dividends paid within the limits of such excess are subject to taxation according to the rules established by subparagraph 57.1 - 1 .2 of this paragraph. For the purpose of taxation, the parent company keeps an accrual accounting of dividends received by it from other persons and dividends paid in favor of the owners of corporate rights of such company, and reflects dividends in tax reporting in the manner determined by the central executive body that ensures the formation and implementation of state financial policy;
{Paragraph two of subparagraph 57.1 - 1 .3 of paragraph 57.1 - 1 of Article 57 as amended by Law No. 1797-VIII of 21.12.2016 }
a payer of income tax whose income is exempt from taxation in accordance with the provisions of this Code, in the amount of income exempt from taxation in the period for which dividends are paid;
individuals.
57.1 - 1 .4. Payment of dividends in favor of individuals (including non-residents) on shares or corporate rights that have the status of preferred or other status that provides for the payment of a fixed amount of dividends or an amount that is greater than the amount of payments calculated on any other share (corporate right) issued by such taxpayer, is equated for taxation purposes to the payment of wages with appropriate taxation.
At the same time, such payment is not subject to taxation as dividends in accordance with the provisions of Section IV of this Code.
{Paragraph three of subparagraph 57.1 - 1 .4 of paragraph 57.1 - 1 of Article 57 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
57.1 - 1 .5. The advance payment of income tax paid in connection with the accrual/payment of dividends is an integral part of the income tax and cannot be considered as a tax levied upon the repatriation of dividends (their payment to non-residents) in accordance with Clause 141.4 of Article 141 of this Code or international treaties of Ukraine.
57.1 - 1 .6 Collective investment institutions are exempt from the obligation to pay advance income tax contributions in the event of dividend payments.
{Clause 57.1 - 1 of Article 57 is supplemented by subparagraph 57.1 - 1 .6 in accordance with Law No. 1797-VIII of 21.12.2016 }
57.1 - 1 .7. Advance payments are not collected/charged on the amounts of transactions that are equated to dividends for tax purposes in accordance with paragraphs four to seven of subparagraph 14.1.49 of paragraph 14.1 of Article 14 of this Code.
{Clause 57.1 - 1 of Article 57 is supplemented by subparagraph 57.1 - 1 .7 in accordance with Law No. 786-IX of 14.07.2020 }
57.1 - 1 .8. Residents of Diya City - taxpayers under special conditions are exempt from the obligation to pay advance income tax contributions in the event of dividend payments.
{Clause 57.1 - 1 of Article 57 is supplemented by subparagraph 57.1 - 1 .8 in accordance with Law No. 1946-IX of 14.12.2021 }
{Article 57 is supplemented by paragraph 57.1 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
57.2. In the event that, in accordance with this Code or other laws of Ukraine, the regulatory authority independently determines the tax liability of a taxpayer for reasons not related to a violation of tax legislation and sends (delivers) a tax notice/tax decision on the payment of the amount/amounts to the taxpayer, such taxpayer shall be obliged to pay the accrued amount of tax liability within the terms specified in this Code and in Article 297 of the Customs Code of Ukraine , and if such terms are not specified, within 30 calendar days following the date of receipt of the tax notice/decision on such assessment.
{Clause 57.2 of Article 57 as amended by Laws No. 4915-VI of 07.06.2012 , No. 2245-VIII of 07.12.2017 }
57.3. In the event of a monetary obligation being determined by the controlling body on the grounds specified in subparagraphs 54.3.1 - 54.3.6 of paragraph 54.3 of Article 54 of this Code, the taxpayer shall be obliged to pay the accrued amount of the monetary obligation within 10 business days following the date of receipt of the tax notice-decision, except for cases when, during such period, such taxpayer initiates the procedure for appealing the decision of the controlling body.
{Paragraph one of clause 57.3 of Article 57 as amended by Law No. 657-VII of 24.10.2013 }
In the event of an appeal against the decision of the supervisory authority on the accrued amount of the monetary obligation, the taxpayer is obliged to independently repay the agreed amount, as well as any fines and penalties, within 10 business days following the date of such approval.
{Clause 57.3 of Article 57 as amended by Laws No. 71-VIII of 12/28/2014 , No. 466-IX of 01/16/2020 }
57.4. Penalties and penalties accrued on the amount of a monetary obligation (its share) canceled as a result of an administrative or judicial appeal shall also be canceled, and if such penalties and penalties have been paid, they shall be credited against the repayment of tax debt, monetary obligations or refunded in accordance with the procedure established by Article 43 of this Code.
57.5. Individual taxpayers must pay taxes and fees established by this Code through banks (including using a single account in the manner specified in Article 35-1 of this Code) or non-bank payment service providers, electronic money issuers.
{Paragraph one of clause 57.3 of Article 57 as amended by Laws No. 190-IX of 04.10.2019 , No. 466-IX of 16.01.2020 ; as amended by Law No. 2888-IX of 12.01.2023 }
If the specified persons live in a rural (village) area, they may pay taxes and fees through the cash desks of village (village) councils using a receipt for the acceptance of taxes and fees, the form of which is established by the central executive body that ensures the formation of state financial policy.
{Paragraph two of clause 57.5 of Article 57 as amended by Law No. 909-VIII of 24.12.2015 }
58.1. The supervisory authority shall send (hand over) a tax notice-decision to the taxpayer if the amount of the taxpayer's monetary obligation, provided for by tax or other legislation, the control over compliance with which is entrusted to the supervisory authorities, is calculated by the supervisory authority in accordance with Article 54 of this Code (except for the declaration of goods, provided for by citizens) or if, based on the results of the inspection, the supervisory authority establishes the fact:
inconsistency of the amount of budget compensation with the amount declared in the tax return ;
overestimation of the declared negative value of the object of taxation by income tax or the negative value of the amount of value added tax calculated by the taxpayer in accordance with Section V of this Code;
understatement or overstatement of the amount of tax liabilities declared in the tax ( customs ) declaration, or the amount of tax credit declared in the value added tax declaration, except for cases where the specified understatement or overstatement was taken into account when issuing other tax notices-decisions based on the results of the audit;
overstatement of the amounts of personal income tax subject to refund from the budget, declared in tax returns , in particular when exercising the right to a tax discount in accordance with Section IV of this Code;
the presence of errors in determining the mandatory details of the tax invoice and/or the lack of registration of the tax invoice and/or calculation of adjustments to the tax invoice within the time limits provided for by this Code.
58.1.1. The tax notice-decision contains:
1) the amount and basis for determining (calculating/reducing) the monetary obligation and/or tax obligation that the taxpayer must pay, and/or the amount and basis for reducing the budget compensation and/or reducing the negative value of the object of taxation by profit tax or the negative value of the amount of value added tax, and/or reducing the personal income tax declared before the refund from the budget, in particular when exercising the right to a tax discount, and/or increasing/reducing the amount of tax obligations declared in the tax return , or the amount of tax credit declared in the tax return on value added tax, and a reference to the provisions of this Code and/or another law, control over the implementation of which is entrusted to the controlling bodies, in accordance with which their calculation was carried out;
invoice /calculate an adjustment to it in the Unified Register of Tax Invoices or about the need to correct errors made when specifying the details of the tax invoice (in cases provided for by this Code);
3) deadlines for payment of a monetary obligation and/or deadlines for the taxpayer to correct tax reporting indicators and/or register a tax invoice in the Unified Register of Tax Invoices / calculate adjustments to it or correct errors made when specifying the details of the tax invoice;
4) warning about the consequences of failure to comply with the tax notice-decision within the established time limit;
5) the time limits provided for by this Code for appealing a tax notice-decision.
The tax notice-decision shall state or be attached to it a detailed calculation of the tax liability (if any) and financial penalties.
58.1.2. If a tax notice-decision is adopted based on the results of a documentary audit and is a procedural basis for holding a person financially liable for committing a tax offense, it must, in addition to the information provided in paragraph 58.1.1 of this article, contain:
1) a substantiated basis for determining (calculating/reducing) a monetary obligation and/or a tax obligation that the taxpayer must pay, and/or reducing the amount of budget compensation and/or reducing the negative value of the object of taxation by income tax or the negative value of the amount of value added tax, and/or reducing the personal income tax declared before the refund from the budget, in particular when exercising the right to a tax discount, and/or understating or overstating the amount of tax obligations declared in the tax return , or the amount of tax credit declared in the tax return for value added tax in the form of a factual basis, namely, a concise summary of the violations of tax, currency and other legislation requirements identified by the inspection, with information on:
the circumstances of the committed offenses, which are reflected in the inspection report, as well as established during the consideration of the written explanations provided by the taxpayer in accordance with subparagraph 16.1.5 of paragraph 16.1 of Article 16 and paragraph 86.7 of Article 86 of Section I of this Code and their documentary confirmation (in particular, regarding the circumstances relating to the offense and the measures taken by the taxpayer to comply with the rules and regulations of the law, with reference to documents and other factual data confirming the specified circumstances);
the period (calendar day or month, quarter, half-year, three quarters, year) of the taxpayer's financial and economic activity during which these violations were committed;
calculation of the amount of tax liability that the taxpayer must pay, and/or reduction of budget compensation and/or reduction of the negative value of the object of taxation by income tax or the negative value of the amount of value added tax, and/or reduction of the amount of personal income tax declared before the refund from the budget when exercising the right to a tax discount, and/or underestimation or overestimation of the amount of tax liability declared in the tax return , or the amount of tax credit declared in the tax return on value added tax;
if the audit reveals facts of understatement (failure to charge and/or withhold) of tax liabilities by the taxpayer, including the tax agent, the deadline for payment of such tax liabilities is additionally indicated, including for the relevant tax (reporting) periods for which such understatement (failure to charge and/or withhold) was detected;
the taxpayer's submission or failure to submit objections, written explanations and additional documents, in particular regarding the circumstances of the identified violations, information provided by the taxpayer that refutes the existence of his guilt, the existence of mitigating circumstances or circumstances exempting him from financial liability in accordance with this Code;
regulatory basis - a reference to the norm of this Code and/or another law, the control over the implementation of which is entrusted to the regulatory authorities, in accordance with which the calculation or recalculation of the taxpayer's monetary obligations was made;
2) reference to the document verification report;
3) detailed calculation of penalties (financial sanctions, fines), including penalties or fines, for violation of other legislation, the control over the implementation of which is entrusted to regulatory authorities, as well as references to the provisions of this Code and/or other legislation in accordance with which such calculation was made;
4) information on the presence of circumstances that, in accordance with this Code, mitigate, aggravate or exempt from financial liability.
{Clause 58.1 of Article 58 as amended by Laws No. 5083-VI of 05.07.2012 , No. 655-VIII of 17.07.2015 , No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 466-IX dated 16.01.2020 }
58.2. The form and procedure for sending a tax notice-decision are determined by the central executive body that ensures the formation and implementation of state financial policy.
A tax notice-decision is sent (delivered) for each individual tax, fee and/or together with penalties provided for by this Code, as well as for each penalty (financial) sanction for violation of the norms of other legislation, control over compliance with which is entrusted to such a regulatory body, and/or a penalty for violation of payment deadlines in the field of foreign economic activity.
In the event of a reduction (increase) by the controlling body of the amount of budget compensation and/or a reduction in the negative value of the object of taxation by income tax or a negative value of the amount of value added tax, separate tax notices-decisions are sent (delivered) to the taxpayer.
The supervisory authority maintains a register of issued tax notices-decisions regarding taxpayers.
The Unified Register of Tax Notices-Decisions of Regulatory Bodies Sent (Delivered) to Taxpayers contains information about:
1) the dates of preparation, sending (delivery) and receipt by the taxpayer of the tax notice-decision;
2) the date of withdrawal or amendment of the tax notice-decision;
3) the specified amount (accrual/reduction) of the monetary obligation and/or tax obligation that the taxpayer must pay, and/or reduction of the amount of budget compensation and/or reduction of the negative value of the object of taxation by profit tax or the negative value of the amount of value added tax, and/or reduction of the personal income tax declared before the refund from the budget, in particular when exercising the right to a tax discount, and/or underestimation or overestimation of the amount of tax obligations declared in the tax return , or the amount of tax credit declared in the tax return on value added tax, and the date of the deadline for their payment;
4) the status of reconciliation of the amounts specified in paragraph 3 of this part;
5) the terms of payment of the amounts specified in paragraph 3 of this part;
6) the occurrence of the taxpayer's tax debt, the date and number of the tax claim;
7) appeal of a tax notice-decision in administrative or judicial proceedings.
The Unified Register of Tax Notices-Decisions of Regulatory Bodies Sent (Delivered) to Taxpayers may contain other information.
The central executive body implementing state tax policy is the technical administrator of the Unified Register of tax notifications-decisions of regulatory authorities sent (delivered) to taxpayers.
For the purposes of entering information into the Unified Register of Tax Notices-Decisions of Controlling Bodies Sent (Delivered) to Taxpayers, the technical administrator provides access to the central executive body implementing the state customs policy and its territorial bodies to the Unified Register of Tax Notices-Decisions of Controlling Bodies Sent (Delivered) to Taxpayers.
The procedure for information interaction between the central executive body implementing state tax policy, its territorial bodies and the central executive body implementing state customs policy, its territorial bodies regarding the provision of access to the Unified Register of tax notifications-decisions of controlling bodies sent (delivered) to taxpayers is established by the central executive body ensuring the formation and implementation of state financial policy.
{Paragraph 58.2 of Article 58 as amended by the Law No. 466-IX dated 16.01.2020 }
58.3. A tax notice-decision shall be sent (delivered) to the taxpayer in accordance with the procedure specified in Article 42 of this Code.
{Clause 58.3 of Article 58 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.24.2012 , No. 1797-VIII of 12.21.2016 ; as amended by Law No. 466-IX of 01.16.2020 }
{Clause 58.4 of Article 58 was excluded on the basis of Law No. 655-VIII of 17.07.2015 }
Article 58 - 1. Tax notice to a non-resident person↑
58 - 1 .1. A tax notice to a non-resident person not registered as a value-added tax payer shall be sent by the central executive body implementing state tax policy to the competent body of a foreign state for informing the non-resident person, if the non-resident person has not registered as a value-added tax payer in the cases and according to the procedure provided for in Article 208 - 1 of this Code.
58 - 1 .2. A tax notice to a non-resident person registered as a value added tax payer shall be sent by the central executive body implementing state tax policy if such non-resident person:
fails to submit a simplified tax return within the established deadline;
fails to pay the agreed amount of monetary obligations for value added tax within the established period;
commits another violation of the requirements of this Code, for which, in accordance with this Code, liability is provided for in the form of a penalty (financial) sanction.
Such a tax notice shall be sent in electronic form through a special portal solution for non-resident users who provide electronic services, with a simultaneous notification to the non-resident person's electronic address specified by him/her when registering as a value-added tax payer in accordance with Article 208-1 of this Code, within 30 calendar days after the expiration of the established deadlines for payment of the agreed amount of tax liabilities and/or submission of a simplified tax return and/or establishment of the fact of another violation of the requirements of this Code.
58 - 1 .3. The tax notice to a non-resident person specified in this article must contain:
the basis for its preparation and/or accrual of a monetary obligation;
the amount of the monetary obligation that the non-resident must pay;
deadlines and procedure for payment of such monetary obligation;
details of a foreign currency account opened for the central executive body implementing state policy in the field of treasury services of budget funds, in an authorized bank to which the monetary obligation is paid;
warning about the need to submit a simplified tax return;
deadlines and procedure for appealing such a tax notice.
A calculation of the monetary obligation is attached to the tax notice to a non-resident person.
The form of tax notification to a non-resident person and calculation of monetary liability are established in the state and English languages and approved by the central executive body that ensures the formation and implementation of state financial policy.
58 - 1 .4. The amount of the monetary obligation specified in the tax notice to a non-resident person shall be payable within 90 calendar days following the date of receipt of such tax notice, or shall be appealed in accordance with the procedure provided for in paragraph 56.24 of Article 56 of this Code.
58 - 1 .5. The unpaid agreed amount of the monetary obligation specified in the tax notice shall be collected in accordance with Article 104 - 1 of this Code. In this case, the provisions of Articles 59, 60, 87-101 of this Code shall not apply.
{The Code is supplemented by Article 58 - 1 in accordance with Law No. 1525-IX of 03.06.2021 }
59.1. In the event that a taxpayer has a tax debt, the regulatory authority shall send (deliver) to him a tax claim in accordance with the procedure established for sending (delivering) a tax notice-decision.
A tax claim may be sent (delivered) by the controlling authority at the place of registration of the taxpayer, where the taxpayer's tax debt is recorded.
A tax claim shall not be sent (not delivered), and measures aimed at the repayment (collection) of the tax debt shall not be applied if the total amount of the tax debt of the taxpayer does not exceed one hundred and eighty non-taxable minimum incomes of citizens. In the event of an increase in the total amount of the tax debt to an amount exceeding one hundred and eighty non-taxable minimum incomes of citizens, the supervisory authority shall send (deliver) a tax claim to such taxpayer. The limitation period specified in Clause 102.4 of Article 102 of this Code for the collection of the tax debt shall in such case begin no earlier than the date of the occurrence of the tax debt in the amount exceeding one hundred and eighty non-taxable minimum incomes of citizens.
{Paragraph three of clause 59.1 of Article 59 as amended by the Law No. 1072-IX dated 04.12.2020 }
{Clause 59.1 of Article 59 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 1797-VIII of 12/21/2016 }
{Clause 59.2 of Article 59 was excluded on the basis of Law No. 404-VII of 04.07.2013 }
59.3. A tax claim together with a detailed calculation of the amount of tax debt shall be sent no earlier than the first business day after the deadline for payment of the amount of the monetary obligation.
{Paragraph one of clause 59.3 of Article 59 as amended by Law No. 1914-IX of 30.11.2021 }
The tax claim must contain information about the fact of the occurrence of a tax debt and the right to a tax lien, the amount of the tax debt secured by the tax lien, the obligation to repay the tax debt and the possible consequences of its failure to repay within the established period, a warning about the description of assets that, in accordance with the legislation, may be the subject of a tax lien, as well as about the possible date and time of public auctions for their sale.
{Paragraph two of clause 59.3 of Article 59 as amended by Law No. 466-IX of 16.01.2020 }
59.4. A tax demand shall also be sent (delivered) to taxpayers who have independently filed tax returns but have not repaid the amount of tax liabilities within the time limits established by this Code, without prior sending (delivery) of a tax notice-decision.
{Clause 59.4 of Article 59 as amended by Law No. 4834-VI of 24.05.2012 }
59.5. If the amount of tax debt of a taxpayer to whom a tax demand has been sent (delivered) increases (decreases), the entire amount of tax debt of such taxpayer existing on the date of repayment shall be subject to repayment.
If, after sending (delivering) a tax claim, the amount of the tax debt has changed, but the tax debt has not been repaid in full, the tax claim is not sent (delivered) additionally.
{Clause 59.5 of Article 59 as amended by Law No. 4834-VI of 05/24/2012 }
Article 60. Withdrawal of tax notice-decision and tax claim↑
60.1. A tax notice or tax claim shall be deemed withdrawn if:
60.1.1. the amount of the tax debt is independently repaid by the taxpayer or the collection agency;
60.1.2. the supervisory authority cancels a previously adopted tax notice-decision on the assessment of the amount of a monetary obligation or tax claim;
60.1.3. the supervisory authority reduces the accrued amount of the monetary obligation of a previously adopted tax notice-decision or the amount of tax debt specified in the tax demand;
60.1.4. a court decision that has entered into legal force cancels the notification-decision of the regulatory authority or the amount of tax debt specified in the tax claim;
60.1.5. a court decision that has entered into legal force reduces the amount of the monetary obligation specified in the tax notice-decision of the regulatory authority, or the amount of the tax debt specified in the tax demand.
60.2. In cases specified in subparagraph 60.1.1 of paragraph 60.1 of this Article, the tax claim shall be deemed withdrawn on the day during which the tax debt was repaid in full.
60.3. In cases specified in subparagraph 60.1.2 of paragraph 60.1 of this Article, a tax notice-decision or tax claim shall be deemed withdrawn from the date of adoption by the supervisory authority of a decision to cancel such a tax notice-decision or tax claim.
60.4. In cases specified in subparagraphs 60.1.3 and 60.1.5 of paragraph 60.1 of this Article, a tax notice-decision or tax claim shall be deemed withdrawn from the date of receipt by the taxpayer of a tax notice-decision or tax claim containing a reduced amount of monetary liability or tax debt.
60.5. In cases specified in subparagraph 60.1.4 of paragraph 60.1 of this Article, a tax notice-decision or tax claim shall be deemed withdrawn on the day the relevant court decision enters into force.
60.6. If the accrued amount of a monetary obligation or tax debt increases as a result of their administrative appeal, a previously sent (served) tax notice-decision or tax claim shall not be withdrawn. A separate tax notice-decision shall be sent for the amount of the increased monetary obligation, and a separate tax claim shall not be sent (served) for the amount of the increased tax debt.
{Clause 60.6 of Article 60 as amended by Law No. 4834-VI of 24.05.2012 }
{Clause 60.7 of Article 60 was excluded on the basis of Law No. 404-VII of 04.07.2013 }
Article 61. Definition of tax control and powers of state authorities regarding its implementation↑
61.1. Tax control - a system of measures taken by regulatory authorities and coordinated by the central executive body that ensures the formation and implementation of state financial policy, in order to control the correctness of the calculation, completeness and timeliness of payment of taxes and fees, as well as compliance with legislation on the regulation of cash circulation, settlement and cash transactions, patenting, licensing and other legislation, control over compliance with which is entrusted to regulatory authorities.
{Paragraph one of clause 61.1 of Article 61 as amended by Law No. 3609-VI of 07.07.2011 }
{Paragraph two of clause 61.1 of Article 61 was excluded on the basis of Law No. 404-VII of 04.07.2013 }
{Clause 61.1 of Article 61 as amended by Law No. 1797-VIII of 21.12.2016 }
61.2. Tax control is carried out by the bodies specified in Article 41 of this Code, within the limits of their powers established by this Code.
61.3. Bodies of the Security Service of Ukraine, the National Police of Ukraine, the prosecutor's office, other law enforcement agencies and their officials (officials) may not directly participate in inspections conducted by regulatory authorities and conduct inspections of business entities on taxation issues.
{Clause 61.3 of Article 61 as amended by Law No. 1293-IX of March 2, 2021 ; as amended by Law No. 1797-VIII of December 21, 2016 - applicable from September 25, 2021 }
62.1.2. information and analytical support for the activities of regulatory bodies;
62.1.3. inspections and reconciliations in accordance with the requirements of this Code, as well as inspections of compliance with legislation, the control over compliance with which is entrusted to regulatory authorities, in accordance with the procedure established by the laws of Ukraine regulating the relevant sphere of legal relations;
62.1.4. monitoring of controlled operations and interviewing officials, authorized persons and/or employees of the taxpayer in accordance with Article 39 of this Code;
{Clause 62.1 of Article 62 is supplemented by subparagraph 62.1.4 in accordance with Law No. 1797-VIII of 21.12.2016 }
62.1.5. accounting and monitoring of the activities of financial agents in accordance with Article 39 - 3 of this Code.
{Clause 62.1 of Article 62 is supplemented by subparagraph 62.1.5 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 63. General provisions on the registration of taxpayers↑
63.1. Taxpayer registration is carried out in order to create conditions for the control of the regulatory authorities over the correctness of the calculation, timeliness and completeness of the payment of taxes, accrued financial sanctions, compliance with tax and other legislation, the control over compliance of which is entrusted to the regulatory authorities.
63.2. All taxpayers are subject to registration with regulatory authorities.
Registration with regulatory authorities of legal entities, their separate divisions, including non-residents specified in Clause 64.5 of Article 64 of this Code, as well as self-employed persons, is carried out regardless of the obligation to pay a particular tax and fee.
{Paragraph two of clause 63.2 of Article 63 as amended by Laws No. 466-IX of 01/16/2020 , No. 2888-IX of 01/12/2023 }
63.3. For the purpose of tax control, taxpayers are subject to registration or registration with regulatory authorities at the location of legal entities, separate divisions of legal entities, place of residence of a person (primary place of registration), as well as at the location (registration) of their divisions, movable and immovable property, objects of taxation or objects related to taxation or through which activities are carried out (non-primary place of registration).
The central executive body implementing state tax policy may decide to change the primary and secondary place of registration of a large taxpayer, including determining that the registration of such a taxpayer is carried out by the territorial body of the central executive body implementing state tax policy, which provides support to large taxpayers, and its structural divisions in the event of their creation.
{Paragraph two of clause 63.3 of Article 63 as amended by Laws No. 5083-VI of 05.07.2012 , No. 657-VII of 24.10.2013 , No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
Objects of taxation and objects related to taxation are property and actions in connection with which the taxpayer has obligations to pay taxes and fees. Such objects for each type of tax and fee are determined in accordance with the relevant section of this Code.
The taxpayer is obliged to register with the relevant regulatory authorities at the main and secondary place of registration, to report all objects of taxation and objects related to taxation to the regulatory authorities at the main place of registration in accordance with the procedure for registering taxpayers.
{Paragraph four of clause 63.3 of Article 63 as amended by Law No. 657-VII of 24.10.2013 }
An application for registration of a taxpayer at a non-primary place of registration is submitted to the relevant regulatory authority within 10 business days after the creation of a separate subdivision, registration of movable or immovable property, or opening of a facility or subdivision through which activities are conducted or which are subject to taxation.
63.4. Registration of taxpayers - legal entities and their separate subdivisions is carried out after their state registration or inclusion of information about them in the relevant state registers under the conditions determined by the legislative acts of Ukraine, except for cases specified by this Code, when the registration authorities are regulatory authorities or when the state registration of a taxpayer in the relevant status is not provided for by law.
63.5. All individuals - payers of taxes and fees are registered with regulatory authorities by including information about them in the State Register of Individuals - Taxpayers in the manner prescribed by this Code.
Individual entrepreneurs and persons who intend to engage in independent professional activities are subject to registration as self-employed persons with regulatory authorities in accordance with this Code.
63.6. Taxpayers are registered with regulatory authorities using tax numbers. The tax number is:
1) identification code of a legal entity (resident), a separate subdivision of a legal entity (resident and non-resident) in the Unified State Register of Enterprises and Organizations of Ukraine;
2) registration number assigned by regulatory authorities in the event of registration:
companies, organizations established in accordance with the legislation of other states;
foreign diplomatic missions and consular offices, representative offices of international organizations in Ukraine;
authorized persons under joint activity agreements, property managers under property management agreements, investors (operators) under production sharing agreements, implementers of international technical assistance projects (programs) and representative offices of donor institutions in Ukraine, other persons and payers in case of additional registration;
3) registration number of the taxpayer's registration card - an individual.
The procedure for determining a tax number is established by the central executive body that ensures the formation and implementation of state financial policy.
The registration of persons who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have notified the relevant regulatory authority thereof, is carried out by surname, first name, patronymic, series (if any) and number of a valid passport of a citizen of Ukraine in the form of a booklet or by the number of a valid passport of a citizen of Ukraine in the form of a card, which is issued using the means of the Unified State Demographic Register (hereinafter referred to as the series and passport number). A mark is made in the passports of a citizen of Ukraine from among the specified persons, indicating the right to make any payments by series and passport number. Such a mark is made:
by controlling bodies - to passports of citizens of Ukraine in the form of a booklet. The procedure for making such a mark is established by the central executive body that ensures the formation of state financial policy;
the body that issues a passport of a citizen of Ukraine in the form of a card, in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
Information interaction between the State Register of Individual Taxpayers and the Unified State Demographic Register regarding the exchange of information on the tax number (registration number of the taxpayer's registration card) or the right to make payments by series (if available) and passport number is carried out in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy, and the central executive body that ensures the formation of state policy in the field of migration (immigration and emigration), including countering illegal (illegal) migration, citizenship, registration of individuals, refugees and other categories of migrants defined by law.
{Clause 63.6 of Article 63 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2888-IX of 12.01.2023 }
63.7. The supervisory authority shall indicate the tax number or series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have notified the relevant supervisory authority about this and have a mark in their passport) in all certificates, references, other documents or notifications issued to or sent to the taxpayer.
{Paragraph one of clause 63.7 of Article 63 as amended by Laws No. 71-VIII of 28.12.2014 , No. 2888-IX of 12.01.2023 }
Each taxpayer indicates the tax number or series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have notified the relevant regulatory authority and have a mark in their passport) in all tax declarations (calculations, reports), payment instructions for taxes and fees, in financial documents, as well as in other cases provided for by law.
{Paragraph two of clause 63.7 of Article 63 as amended by Law No. 2888-IX of 12.01.2023 }
63.8. The specifics of accounting for taxpayers under certain taxes, as well as for certain categories of taxpayers, are established by the relevant sections of this Code.
63.9. Documents submitted by taxpayers for registration with regulatory authorities shall be checked in accordance with the procedure established by the central executive body responsible for the formation and implementation of state financial policy, and in case of errors or submission of inaccurate information, they shall be returned for correction. Taxpayers who have not submitted corrected documents for registration with regulatory authorities within 5 calendar days following the date of receipt of the returned documents or have resubmitted such documents with errors shall be liable in accordance with the law.
{Clause 63.9 of Article 63 as amended by Law No. 1797-VIII of 21.12.2016 }
63.10. The central executive body that ensures the formation and implementation of state financial policy is determined by:
{Clause 63.10 of Article 63 as amended by Law No. 1797-VIII of 21.12.2016 }
63.10.1. procedure for accounting of taxpayers and fees;
63.10.2. a list of documents submitted for registration of taxpayers, as well as the procedure for submitting such documents;
63.10.3. forms of applications, certificates and documents on issues of registration and accounting of taxpayers.
63.11. Supervisory authorities ensure the reliability of data on taxpayers in the Unified Data Bank on Taxpayers - Legal Entities and the State Register of Individual Taxpayers, the register of value-added tax payers, the register of non-profit organizations and other registers formed and maintained by supervisory authorities in accordance with this Code, their protection from unauthorized access, updating, archiving and restoration of data.
63.12. Information collected, used and formed by regulatory authorities in connection with taxpayer registration is entered into information databases.
{Clause 63.12 of Article 63 as amended by Law No. 1797-VIII of 12/21/2016 }
63.13. In order to constantly provide state authorities, local self-government bodies, legal entities and individuals with information, the central executive body implementing the state tax policy shall publish on the single state registration web portal of legal entities and individuals - entrepreneurs and public organizations and on its own official website data on the registration as taxpayers of legal entities, their separate divisions and self-employed persons no later than the next business day after registration.
{Paragraph one of clause 63.13 of Article 63 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
Access to the aforementioned web portal and website is free and open.
The specified data contains the following information about the taxpayer:
tax number (for a legal entity and its separate subdivision);
name for a legal entity or surname, first name, patronymic for an individual;
location;
date and number of the registration entry;
name and identification code of the controlling authority at the taxpayer's main place of registration;
information about the sending by the relevant regulatory authority to the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations of information in connection with the termination of a legal entity, as provided for by law.
{Paragraph nine of clause 63.13 of Article 63 as amended by Law No. 466-IX of January 16, 2020 }
{Article 63 is supplemented by paragraph 63.13 in accordance with Law No. 657-VII of 24.10.2013 }
63.14. For the purposes of this chapter, the date of receipt of documents (notifications, applications, requests and other documents) is:
for those submitted in paper form - the date of receipt by the relevant regulatory authority;
for those submitted electronically - the time and date of receipt of such an electronic document, as indicated in the electronic message (receipt) generated by the software of the central executive body implementing state tax policy, in the format approved in accordance with the procedure established by law.
If a document submitted electronically is received after 4 p.m. on a business (operational) day, the date of its receipt is considered to be the next business (operational) day.
{Article 63 is supplemented by paragraph 63.14 in accordance with Law No. 466-IX of January 16, 2020 }
Article 64. Registration of legal entities and separate divisions of legal entities↑
64.1. Registration at the main place of registration of legal entities and their separate divisions, separate divisions of legal entities established in accordance with the legislation of a foreign state, including permanent representative offices, as payers of taxes and fees in regulatory bodies is carried out on the basis of information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations, provided in accordance with the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations", on the day the regulatory bodies receive the specified information.
Data on the registration of legal entities and their separate divisions, separate divisions of legal entities established in accordance with the legislation of a foreign state, as payers of taxes and fees in regulatory bodies are transferred to the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations on the day of registration of such taxpayers in accordance with the procedure established by the Ministry of Justice of Ukraine and the central executive body that ensures the formation and implementation of state financial policy.
{Clause 64.1 of Article 64 as amended by Laws No. 4834-VI of 24.05.2012 , No. 404-VII of 04.07.2013 No. 1797-VIII dated 21.12.2016 ; as amended by Laws No. 466-IX dated 16.01.2020 , No. 3813-IX dated 18.06.2024 }
64.2. Registration at the main place of registration of taxpayers - legal entities and separate subdivisions of legal entities, for which the law establishes the peculiarities of their state registration and which are not included in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations, is carried out on the day of receipt of the relevant application, which the taxpayer is obliged to submit within ten days after state registration (legalization, accreditation or certification of the fact of creation in another way).
{Clause 64.2 of Article 64 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
64.3. Registration of legal entities and their separate divisions, separate divisions of legal entities established in accordance with the legislation of a foreign state, as payers of taxes and fees in regulatory authorities in accordance with paragraph 64.1 of this article is confirmed by information published on the electronic services portal in accordance with the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
{Paragraph one of clause 64.3 of Article 64 as amended by the Law No. 3813-IX dated 18.06.2024 }
In the event of registration of legal entities and their separate divisions as payers of taxes and fees with regulatory authorities in accordance with paragraph 64.2 of this article, a certificate of registration shall be sent (issued) to these legal entities and separate divisions of legal entities no later than the next business day from the date of registration at the main place of registration.
{Clause 64.3 of Article 64 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
64.4. Military units are obliged, within 10 calendar days after registration of the military unit as a business entity, to register with the regulatory body at the place of their deployment in accordance with paragraph 64.2 of this article.
{Clause 64.4 of Article 64 as amended by Law No. 3205-VI of 07.04.2011 }
64.5. Non-residents (foreign legal entities, organizations) that carry out activities in Ukraine through separate divisions, including permanent representative offices, or acquire real estate or obtain property rights to such property in Ukraine, or open accounts in Ukrainian banks (except for correspondent accounts opened with non-resident banks), in other financial institutions, in non-bank payment service providers, or open electronic wallets in electronic money issuers in accordance with Article 64 of the Law of Ukraine "On Payment Services", or acquire ownership of an investment asset defined in paragraphs three to six of subparagraph "e" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 of this Code, from another non-resident who does not have a permanent representative office in Ukraine, are required to register with regulatory authorities.
{Paragraph one of item 64.5 of Article 64 as amended by the Law No. 1117-IX of 17.12.2020 ; as amended by Law No. 2888-IX of 12.01.2023 }
Registration with the regulatory authority of a non-resident shall be carried out upon the occurrence of the first of the events specified in the first paragraph of this paragraph, no later than the next business day from the date of receipt of the relevant application from the non-resident, which he is obliged to submit:
within ten days after accreditation (registration, legalization) of a separate unit on the territory of Ukraine - to the supervisory authority at the location of the separate unit;
before purchasing real estate or obtaining property rights to such property in Ukraine - to the regulatory authority at the location of the real estate;
before opening an account/electronic wallet in Ukraine - to the regulatory authority at the location of the institution (branch) of the bank, other financial institution, non-bank payment service provider/electronic money issuer in which the account/electronic wallet is opened;
{Paragraph five of clause 64.5 of Article 64 as amended by Law No. 2888-IX of 12.01.2023 }
before the date of making the first payment for the investment asset being purchased - to the regulatory authority at the location of the Ukrainian legal entity, the shares of which, the corporate rights of which form the value of the investment asset that is the subject of such a transaction.
{ Item 64.5 of Article 64 is supplemented with a new paragraph in accordance with the Law No. 1117-IX dated 17.12.2020 }
Copies of the following documents are attached to the application (with presentation of the originals):
an extract from the relevant business register (trade, banking or other register, which records the fact of state registration of a company, organization), issued in the country of registration of a foreign company, organization and legalized in accordance with the established procedure, unless otherwise provided by international treaties, the binding consent of which has been granted by the Verkhovna Rada of Ukraine, accompanied by a notarized translation into Ukrainian;
a document confirming the assignment of an identification (registration, accounting) number (code) to a non-resident in the country of his registration, if the extract from the relevant business register does not contain information about such a number (code), accompanied by a notarized translation into Ukrainian;
a document confirming the powers of the non-resident's representative. If such a document is issued in the non-resident's country of registration, it must be legalized in accordance with the established procedure, unless otherwise provided for by international treaties, the binding nature of which has been approved by the Verkhovna Rada of Ukraine, and accompanied by a notarized translation into Ukrainian;
a document on accreditation (registration, legalization) of a separate division of a foreign company or organization on the territory of Ukraine, if a non-resident carries out activities in Ukraine through a separate division.
{Paragraph twelfth of clause 64.5 of Article 64 is excluded on the basis of the Law No. 3813-IX dated 18.06.2024 }
If the supervisory authority, based on the results of tax control, establishes signs of a non-resident conducting economic activities on the territory of Ukraine specified in paragraphs three to five of this paragraph, without the non-resident being registered for tax purposes, in particular, a resident conducting activities in the interests of a non-resident through separate subdivisions, including those that have the characteristics of a permanent establishment, the supervisory authority shall order an inspection of such activities. The procedure for conducting an inspection for the purposes of this paragraph shall be determined by the central executive authority that ensures the formation and implementation of state financial policy, taking into account the features specified by this Code.
If the inspection establishes that a non-resident is conducting business through separate divisions, including a permanent establishment in Ukraine without being registered for tax purposes, the supervisory authority shall draw up an inspection report, which shall be sent to the non-resident in accordance with the procedure specified in Clause 86.13 of Article 86 of this Code. On the basis of the inspection report, the supervisory authority may make a decision to register such a non-resident in Ukraine without the non-resident's application and without receiving an objection to the inspection report.
In the event of registration of a non-resident person as a value added tax payer in accordance with clause 208-1.2 of Article 208-1 of this Code , such non-resident person shall be automatically registered at the same time.
{ Item 64.5 of Article 64 is supplemented with a new paragraph in accordance with the Law No. 1525-IX dated 03.06.2021 }
The procedure for registering non-residents with regulatory authorities is established by the central executive body that ensures the formation and implementation of state financial policy.
The procedure for notifying non-residents of their registration as taxpayers is established by the Cabinet of Ministers of Ukraine.
{Clause 64.5 of Article 64 as amended by Laws No. 3609-VI of 07.07.2011 , No. 655-VIII of 17.07.2015 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
64.6. Production sharing agreements, property management agreements (except for agreements on transactions specified in the second sentence of the paragraph of the second subparagraph 5 of clause 180.1 of Article 180 of this Code) and agreements on joint activities in the territory of Ukraine without the creation of legal entities, which are subject to the peculiarities of tax accounting and taxation of activities under such agreements (agreements), specified in this Code, must be registered with the regulatory authorities.
{Paragraph one of clause 64.6 of Article 64 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 909-VIII of 12/24/2015 }
The regulatory authorities do not register agreements on joint activities that are not subject to the specifics of tax accounting and taxation of joint activities defined by this Code. Each participant in such agreements is registered with the regulatory authorities and fulfills the duties of a taxpayer independently.
{Paragraph three of clause 64.6 of Article 64 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
Registration of a contract or agreement is carried out by additional registration of the property manager, a participant in the contract on joint activities or a product sharing agreement as a taxpayer - responsible for withholding and paying taxes to the budget during the implementation of the contract or agreement.
{Paragraph four of clause 64.6 of Article 64 as amended by Law No. 4834-VI of 24.05.2012 }
{Paragraph five of clause 64.6 of Article 64 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
64.7. The central executive body that ensures the formation and implementation of state financial policy shall determine the procedure for recording taxpayers in regulatory bodies and the procedure for forming the Register of Large Taxpayers for the relevant year, taking into account the criteria defined by this Code for large taxpayers.
{Paragraph one of clause 64.7 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1797-VIII of 12/21/2016 }
If a taxpayer is included in the Register of Large Taxpayers, the features defined by this Code for large taxpayers apply to him.
After the taxpayer is included in the Register of Large Taxpayers and receiving a notification from the central executive body implementing the state tax policy about such inclusion, the taxpayer is obliged to register at the main place of registration in the territorial body of the central executive body implementing the state tax policy, which provides support for large taxpayers, from the beginning of the tax period (calendar year) for which the Register was formed, and at a non-main place of registration in such territorial body of the central executive body or its structural divisions for the objects of taxation or objects related to taxation available within the settlement at the location of the territorial body of the central executive body implementing the state tax policy, which provides support for large taxpayers, according to the list determined by the central executive body ensuring the formation and implementation of the state financial policy, or through which the activities of such a large taxpayer are carried out taxes.
{Paragraph three of clause 64.7 of Article 64 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 , No. 657-VII of 24.10.2013 ; as amended by Laws No. 2245-VIII of 07.12.2017 , No. 466-IX of 16.01.2020 }
Regarding large taxpayers who have not independently registered with the territorial body of the central executive body implementing state tax policy, which provides support for large taxpayers, or its structural units, the central executive body implementing state tax policy shall make a decision to change the main and secondary place of registration of such large taxpayers and transfer them to registration with the territorial body of the central executive body implementing state tax policy, which provides support for large taxpayers, or its structural units.
{Paragraph four of clause 64.7 of Article 64 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 ; as amended by Laws No. 2245-VIII of 07.12.2017 , No. 466-IX of 16.01.2020 }
In {Paragraph five of clause 64.7 of Article 64 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
In the event of a decision to transfer a large taxpayer to registration with a territorial body of the central executive body implementing state tax policy, which provides support to large taxpayers, or another regulatory body, the relevant regulatory bodies are obliged to register/deregister such taxpayer within 20 calendar days after making such a decision.
{Paragraph six of clause 64.7 of Article 64 as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 466-IX of 16.01.2020 }
A large taxpayer, for whom the central executive body implementing the state tax policy has made a decision to transfer it to a regulatory body that provides support for large taxpayers or another regulatory body, after registering it at a new place of registration, is obliged to pay taxes at the place of previous registration with regulatory bodies, and to submit tax reports and fulfill other obligations stipulated by this Code at the new place of registration.
{Paragraph seven of clause 64.7 of Article 64 as amended by Law No. 2856-VI of 12/23/2010 ; as amended by Laws No. 5083-VI of 07/05/2012 , No. 404-VII of 07/04/2013 , No. 2245-VIII of 12/07/2017 , No. 466-IX of 01/16/2020 }
65.1. Registration of individual entrepreneurs (except for those who have acquired the status of electronic resident (e-resident) in regulatory authorities is carried out at the tax address based on information from the Unified State Register of Legal Entities, Individual Entrepreneurs (except for those who have acquired the status of electronic resident (e-resident) and public organizations, provided by the state registrar in accordance with the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
{Clause 65.1 of Article 65 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 2654-IX dated 06.10.2022 }
65.2. Self-employed persons are registered by entering into the State Register of Individual Taxpayers (hereinafter referred to as the State Register) records on state registration or termination of entrepreneurial activity, independent professional activity, re-registration, registration, deregistration, making changes to a self-employed person, as well as performing other actions provided for by the Procedure for Registration of Taxpayers and Fees.
65.3. To register an individual who intends to conduct independent professional activities, such person must submit an application and documents in person (sent by registered letter with a description of the attachment) or through an authorized person to the regulatory authority at the place of permanent residence.
65.4. The supervisory authority shall refuse to consider documents submitted for registration of a person engaged in independent professional activity in the following cases:
65.4.1. the presence of restrictions on the conduct of independent professional activities established by law;
65.4.2. when documents are submitted to the wrong place of registration;
65.4.3. when the documents do not meet the established requirements, are not submitted in full, or when the information specified in different documents is mutually inconsistent;
65.4.4. when an individual is already registered as a self-employed person;
65.4.5. failure to submit for registration by a person intending to engage in independent professional activity a registration certificate or other document (permit, certificate, etc.) confirming the right of an individual to engage in independent professional activity.
After eliminating the reasons that were the basis for refusing to register a self-employed person, the individual may resubmit documents for registration.
65.5. Registration of a self-employed person is carried out by the supervisory authority on the day of receipt of relevant information from the state registrar (for individual entrepreneurs) or acceptance of the application (for persons engaged in independent professional activities).
Data on the registration of an individual entrepreneur is transferred to the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations on the day of registration in accordance with the procedure established by the Ministry of Justice of Ukraine and the central executive body that ensures the formation and implementation of state financial policy.
Registration of an individual entrepreneur is confirmed by information published on the electronic services portal, in accordance with the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
{Clause 65.5 of Article 65 as amended by Laws No. 4834-VI of 05/24/2012 , No. 404-VII of 07/04/2013 ; as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
65.6. Issuance and replacement of a certificate of taxpayer registration is free of charge.
65.7. A certificate of registration of a taxpayer shall be issued by the supervisory authority to an individual engaged in independent professional activity, indicating the term, if such term is specified in the registration certificate or other document (permit, certificate, etc.) confirming the right of the individual to engage in independent professional activity.
65.8. A certificate of registration of a self-employed person shall become invalid from the moment of any changes in the data about the individual specified in such certificate, and shall be subject to replacement by the supervisory authority.
65.9. If an individual is registered as an entrepreneur and at the same time such an individual conducts independent professional activities, such an individual is registered with the regulatory authorities as an individual entrepreneur with the sign of conducting independent professional activities.
{Clause 65.9 of Article 65 as amended by Law No. 466-IX of January 16, 2020 }
65.10. An entry in the State Register on the termination of the entrepreneurial activity of an individual - entrepreneur or independent professional activity of an individual is made in the case of:
65.10.1. entering into the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations a record of state registration of termination of entrepreneurial activity of an individual entrepreneur - from the date of state registration of termination of entrepreneurial activity of an individual entrepreneur;
65.10.2. termination or suspension of independent professional activity or change of organizational form of the relevant activity from independent (individual) to another - from the date of adoption of the relevant decision by the authorized body or another date specified by the law regulating the registration of the relevant independent professional activity, the date of termination, suspension or change of organizational form of the relevant activity from independent (individual) to another;
65.10.3. expiration of the registration certificate or other document (permit, certificate, etc.) - from the date of expiration of such period;
65.10.4. cancellation or revocation in accordance with the legislation of a registration certificate or other document (permit, certificate, etc.) confirming the right of an individual to conduct independent professional activities, or cancellation of a registration action regarding the state registration of an individual as an entrepreneur - from the date of such cancellation or revocation.
State registration (registration) of the termination of entrepreneurial or independent professional activity of an individual or entry in the State Register of the termination of such activity by an individual does not terminate his obligations that arose during the conduct of entrepreneurial or independent professional activity, and does not change the terms, procedures for the fulfillment of such obligations and the application of penalties and the accrual of fines for their failure to fulfill.
If, after entering an entry in the State Register on the termination of entrepreneurial or independent professional activity, an individual continues to conduct such activity, it is considered that he or she has started such activity without being registered as a self-employed person.
{Clause 65.10 of Article 65 as amended by the Law No. 1797-VIII dated 21.12.2016 ; as amended by the Law No. 466-IX dated 16.01.2020 }
Article 66. Making changes to the registration data of taxpayers, except for individuals who are not registered as entrepreneurs and do not conduct independent professional activities↑
{Title of Article 66 as amended by Law No. 4834-VI of 24.05.2012 }
66.1. The grounds for making changes to taxpayer registration data are:
66.1.1. information from state registration authorities;
66.1.2. information from banks, other financial institutions, non-bank payment service providers on the opening (closing) of taxpayer accounts and information from electronic money issuers on the opening (closing) of taxpayer electronic wallets;
{Subparagraph 66.1.2 of paragraph 66.1 of Article 66 as amended by Law No. 2888-IX of 12.01.2023 }
66.1.3. documented information provided by taxpayers;
66.1.4. information on information exchange entities authorized to perform any registration actions regarding the taxpayer;
66.1.5. court decision that has entered into legal force;
66.1.6. data from taxpayer audits.
66.2. Changes to taxpayer registration data shall be made in accordance with the procedure established by the central executive body responsible for the formation and implementation of state financial policy.
{Clause 66.2 of Article 66 as amended by Law No. 1797-VIII of 21.12.2016 }
66.3. In the event of state registration of a change in the location or place of residence of a taxpayer, as a result of which the controlling body with which the taxpayer is registered changes, as well as in the event of a change in the tax address of the taxpayer, the controlling bodies at the previous and new location (place of residence) of the taxpayer shall carry out procedures for deregistration/registration of such taxpayer, respectively.
{Paragraph one of clause 66.3 of Article 66 as amended by Law No. 2888-IX of 12.01.2023 }
The basis for removing a taxpayer from registration with one regulatory authority and registering with another is the receipt by at least one of these authorities of data indicating proper state registration of such changes by state registration authorities.
In such a case, the taxpayer specified in Clause 64.2 of Article 64 of this Code shall be obliged to submit to the supervisory authority at the new location a corresponding application within ten days from the date of registration of the change of location (place of residence) in accordance with the procedure for recording taxpayers. In the event of failure to submit such an application within 10 calendar days, the taxpayer or officials of the taxpayer shall be liable in accordance with the law.
{Paragraph three of clause 66.3 of Article 66 as amended by Law No. 657-VII of 24.10.2013 }
66.4. Taxpayers - legal entities and their separate divisions are obliged to submit to the supervisory authority information regarding the persons responsible for maintaining accounting and/or tax records of the legal entity, its separate divisions, within 10 days from the date of registration or changes in the taxpayers' accounting data, by submitting an application in accordance with the procedure determined by the central executive body that ensures the formation and implementation of state financial policy. Liability for failure to submit such information is determined by this Code.
{Clause 66.4 of Article 66 as amended by Law No. 1797-VIII of 21.12.2016 }
66.5. In the event of changes in data or amendments to documents submitted for registration in accordance with this chapter, except for changes made to the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations, and changes reported by the taxpayer to the main place of registration, the taxpayer is obliged to submit revised documents to the regulatory authority with which he is registered within 10 calendar days from the date of amendments to the specified documents.
{Clause 66.5 of Article 66 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 1797-VIII of 12/21/2016 }
Article 67. Grounds and procedure for deregistration of legal entities, their separate divisions and self-employed persons from the regulatory authorities↑
67.1. The grounds for deregistration from the regulatory authorities of a legal entity, its separate divisions, a separate division of a legal entity formed in accordance with the legislation of a foreign state, and self-employed persons are:
{Paragraph one of clause 67.1 of Article 67 as amended by the Law No. 3813-IX dated 18.06.2024 }
67.1.1. notification or documentary confirmation of the state registrar or other state registration authority on the state registration of the termination of a legal entity, a separate subdivision of a legal entity, a separate subdivision of a legal entity formed in accordance with the legislation of a foreign state;
{Paragraph two of subparagraph 67.1.1 of paragraph 67.1 of Article 67 was excluded on the basis of Law No. 657-VII of 24.10.2013 }
{Paragraph three of subparagraph 67.1.1 of paragraph 67.1 of Article 67 was excluded on the basis of Law No. 657-VII of 24.10.2013 }
{Subclause 67.1.1 of Clause 67.1 of Article 67 as amended by Laws No. 466-IX of 01/16/2020 , No. 3813-IX of 06/18/2024 }
67.1.2. the presence of at least one of the grounds specified in paragraph 65.10 of Article 65 of this Code for a self-employed person.
{Paragraph two of subparagraph 67.1.2 of paragraph 67.1 of Article 67 was excluded on the basis of Law No. 657-VII of 24.10.2013 }
{Paragraph three of subparagraph 67.1.2 of paragraph 67.1 of Article 67 was excluded on the basis of Law No. 657-VII of 24.10.2013 }
67.2. Supervisory authorities, in accordance with the procedure established by law, have the right to apply to the court for a court decision regarding:
termination of legal entities or entrepreneurial activities of individual entrepreneurs;
cancellation of state registration of termination of legal entities or entrepreneurial activities of individual entrepreneurs;
{Paragraph three of clause 67.2 of Article 67 as amended by Law No. 466-IX of January 16, 2020 }
cancellation of state registration of amendments to constituent documents.
67.3. In the event of termination of a legal entity, its separate divisions shall be deregistered from the regulatory authorities.
The procedure for deregistration from regulatory authorities of legal entities, their separate divisions, and self-employed persons is established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph two of clause 67.3 of Article 67 as amended by Law No. 1797-VIII of 21.12.2016 }
67.4. Joint activity agreements, property management agreements and product distribution agreements are removed from the register of regulatory authorities after their termination, termination, expiration or after the achievement of the purpose for which they were concluded, their recognition as invalid in court, as well as in the event of loss of the characteristics of a taxpayer specified in this Code.
{Clause 67.4 of Article 67 as amended by Laws No. 4834-VI of 05/24/2012 , No. 466-IX of 01/16/2020 }
67.5. Non-residents defined in paragraph 64.5 of Article 64 of this Code shall be deregistered with regulatory authorities after the alienation of real estate and/or the closure of all accounts/electronic wallets in banks, other financial institutions, non-bank payment service providers, electronic money issuers and/or the closure of separate divisions, including permanent representative offices, on the territory of Ukraine, provided that there are no other objects of taxation and objects related to taxation on the territory of Ukraine.
{Paragraph one of clause 67.5 of Article 67 as amended by Law No. 2888-IX of 12.01.2023 }
The procedure for removing non-residents from the register of regulatory authorities is established by the central executive body that ensures the formation and implementation of state financial policy.
In the event of cancellation of the registration of a non-resident person as a value added tax payer in accordance with clause 208-1.3 of Article 208-1 of this Code , such non-resident person shall simultaneously be automatically removed from the register.
{ Item 67.5 of Article 67 is supplemented by the third paragraph in accordance with the Law No. 1525-IX dated 03.06.2021 }
a value added tax payer in accordance with Clause 208-1.3 of Article 208-1 of this Code , has a tax debt or has not fulfilled tax obligations shall be automatically removed from the register after repayment of the debt and fulfillment of the obligations specified in this Code.
{ Item 67.5 of Article 67 is supplemented by the fourth paragraph in accordance with the Law No. 1525-IX dated 03.06.2021 }
{Article 67 is supplemented by paragraph 67.5 in accordance with Law No. 466-IX of January 16, 2020 }
Article 68. Information submitted for the registration of taxpayers by the state registration bodies of business entities and other bodies↑
68.1. The technical administrator of the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations on the day of the registration action must transfer to the information systems of the regulatory authorities the information, documents, and requests provided for by the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
68.2. The Central Securities Depository, which maintains the accounting system for shares of limited liability companies and additional liability companies (hereinafter referred to as the accounting system for shares of companies), on the day of the start of accounting for shares of such companies, making changes to the accounting system for shares of companies regarding the owners of shares of the company or the size of the shares of the owners of the company, is obliged to transmit, free of charge, in electronic form, to the information systems of the central executive body implementing state tax policy, data (information) about the limited liability company or additional liability company, all owners of shares of such company and the size of shares of the respective owners, and if the relevant share of the companies is an object of state or municipal property - about the entity managing objects of state or municipal property, which performs the functions of managing the relevant share of the company.
The procedure for electronic information interaction between the Central Securities Depository and the central executive body implementing state tax policy is established by the central executive body ensuring the formation and implementation of state financial policy, in agreement with the National Securities and Stock Market Commission.
68.3. Bodies that keep records or register movable property and other assets that are subject to taxation are obliged to report on the owners and/or users of such movable property and other assets located in the relevant territory, or on vehicles registered with these bodies, and their owners to the controlling bodies at their location every month, but no later than the 10th of the following month. The procedure for such reporting shall be established by the Cabinet of Ministers of Ukraine.
68.4. State bodies must submit other information to regulatory authorities in cases provided for by this Code and other regulatory legal acts of Ukraine.
{Article 68 as amended by Laws No. 4834-VI of 05/24/2012 , No. 657-VII of 10/24/2013 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 ; as amended by Law No. 3603-IX of 02/23/2024 }
Article 69. Requirements for opening and closing taxpayer accounts in banks, other financial institutions, non-bank payment service providers and electronic wallets in electronic money issuers↑
{Title of Article 69 as amended by Laws No. 323-IX of 03.12.2019 , No. 2888-IX of 12.01.2023 ; as amended by Law No. 2970-IX of 20.03.2023 ; as amended by Law No. 3603-IX of 23.02.2024 }
69.1. Banks, other financial institutions, non-bank payment service providers, electronic money issuers open the relevant accounts/electronic wallets provided for by the legislation of Ukraine, for taxpayers - legal entities (residents and non-residents) regardless of their organizational and legal form, separate divisions and representative offices of legal entities for which the law establishes the features of their state registration and which are not included in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations, individuals who carry out independent professional activities, if there are documents issued by regulatory authorities confirming their registration with such authorities, or extracts from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations (for persons whose registration with regulatory authorities is carried out on the basis of information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations provided by the state registrar in accordance with the Law of Ukraine "On state registration of legal entities, individual entrepreneurs and public organizations") or information from this register received by a bank, other financial institution, non-bank payment service provider, electronic money issuer in accordance with the law, indicating data on registration with regulatory authorities as a taxpayer.
{Clause 69.1 of Article 69 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 344-VIII of 04/21/2015 ; as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2888-IX of 01/12/2023 }
69.2. Banks, other financial institutions, non-bank payment service providers, and electronic money issuers are required to send a notification about the opening or closing of an account/electronic wallet of a taxpayer - a legal entity (resident and non-resident), including one opened through its separate divisions, or a self-employed individual, to the regulatory authority with which the taxpayer is registered, on the day of opening/closing the account/electronic wallet.
{Paragraph one of clause 69.2 of Article 69 as amended by Laws No. 657-VII of 10/24/2013 , No. 344-VIII of 04/21/2015 , No. 466-IX of 01/16/2020 ; as amended by Law No. 2888-IX of 01/12/2023 }
In the event of opening or closing a taxpayer's bank account, including one opened through its separate divisions, the notification shall be sent in the manner specified in this paragraph only in the event of opening or closing a correspondent account.
In the event of opening or closing their own correspondent account, banks are required to send a notification to the regulatory authority with which they are registered within the time limits specified in this paragraph.
69.2 - 1. The obligations stipulated by this article regarding sending to the regulatory body a notification about opening an account for the owner of the company's shares in the accounting system of the company's shares or closing such an account must be fulfilled by the depository institution or the Central Securities Depository with which (which) this owner has concluded an agreement on servicing the account(s) of the company's participant. The corresponding notification shall be sent on the day of conclusion/termination (termination) of such an agreement or closing of any of the accounts serviced in accordance with this agreement.
The obligations stipulated by this article regarding sending a notification to the regulatory authority about opening an escrow account for the company's shares or about closing such an account must be fulfilled by the Central Securities Depository with which the escrow account agreement for the company's shares was concluded:
on opening an escrow account for the company's shares, which are recorded in the share accounting system, - on the day the relevant account is opened;
on closing the escrow account of the company's shares, which are recorded in the share accounting system, - on the day of termination of recording of the company's share in the escrow account, including in connection with the termination of such an agreement.
The commencement of transactions in the accounting system for company shares on the account of the owner of the company's shares shall be carried out in accordance with the rules of paragraph 69.4 of this article, except for unconditional transactions.
{Article 69 is supplemented by paragraph 69.2 - 1 in accordance with Law No. 3603-IX of 23.02.2024 }
69.3. The supervisory authority shall, no later than the next business day from the date of receipt of a notification from a bank, other financial institution, non-bank payment service provider, or electronic money issuer about opening an account/electronic wallet, send a notification about registering the account/electronic wallet or about refusing to register the account/electronic wallet by the supervisory authority, indicating the reasons in accordance with the procedure specified by this Code.
If the regulatory authority, within the period established by the first paragraph of this paragraph, has not sent a notification of refusal to register an account/electronic wallet, such account/electronic wallet shall be deemed to have been registered with the regulatory authority by tacit consent - at the time and date of receipt by the relevant institution of a notification (receipt) from the regulatory authority confirming the fact of acceptance of the notification for processing in accordance with the procedure for submitting notifications established in accordance with paragraph 69.5 of this Article.
{Clause 69.3 of Article 69 as amended by Laws No. 657-VII of 10/24/2013 , No. 344-VIII of 04/21/2015 ; as amended by Law No. 2888-IX of 01/12/2023 }
69.4. The date of commencement of expenditure transactions on the account/electronic wallet of the taxpayer specified in clause 69.1 of this article (except for a bank) in banks, other financial institutions, non-bank payment service providers, and electronic money issuers is the date of receipt by the bank or other financial institution, non-bank payment service provider, or electronic money issuer of a notification from the regulatory authority about the registration of the account/electronic wallet with the regulatory authorities or the date determined as the date of registration with the regulatory authority by tacit consent in accordance with the second paragraph of clause 69.3 of this article.
{Clause 69.4 of Article 69 as amended by Law No. 344-VIII of 04/21/2015 ; as amended by Law No. 2888-IX of 01/12/2023 }
69.5. The procedure for submitting and the form and content of notifications on the opening/closing of accounts/electronic wallets of taxpayers in banks, other financial institutions, non-bank payment service providers, electronic money issuers, the list of grounds for refusal by regulatory authorities to register accounts/electronic wallets shall be determined by the central executive body that ensures the formation and implementation of state financial policy, in agreement with the relevant state bodies that regulate the activities of financial institutions.
{Clause 69.5 of Article 69 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 2888-IX of 12/12/2023 }
{Clause 69.6 of Article 69 was excluded pursuant to Law No. 466-IX of January 16, 2020 }
69.7. Individuals - entrepreneurs and persons engaged in independent professional activities are obliged to report their status to banks, other financial institutions, non-bank payment service providers, and electronic money issuers in which such persons open accounts/electronic wallets.
{Clause 69.7 of Article 69 as amended by Law No. 2888-IX of 12.01.2023 }
{Clause 69.8 of Article 69 was excluded on the basis of Law No. 2970-IX of 20.03.2023 }
Article 70. State Register of Individual Taxpayers↑
70.1. The central executive body implementing the state tax policy shall form and maintain the State Register of Individual Taxpayers (hereinafter referred to as the State Register).
{Paragraph one of clause 70.1 of Article 70 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 }
The State Register includes information about persons who are:
citizens of Ukraine;
foreigners and stateless persons permanently residing in Ukraine;
foreigners and stateless persons who do not have a permanent place of residence in Ukraine, but are obliged to pay taxes in Ukraine in accordance with the legislation or are founders of legal entities established on the territory of Ukraine, or have acquired the status of electronic resident (e-resident).
{ Paragraph five of clause 70.1 of Article 70 as amended by the Law No. 2654-IX dated 06.10.2022 }
Registration of individual taxpayers who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have notified the relevant regulatory authority thereof, is maintained in a separate register of the State Register by surname, first name, patronymic and series and number of the passport without using the registration number of the registration card.
{Paragraph seven of clause 70.1 of Article 70 is excluded on the basis of the Law No. 879-VII dated 13.03.2014 }
70.2. The following information shall be entered into the registration card of an individual taxpayer and the notification (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer registration card):
70.2.1. surname, first name and patronymic;
70.2.2. date of birth;
70.2.3. place of birth (country, region, district, settlement);
70.2.4. place of residence, and for foreign citizens - also citizenship;
70.2.5. series, number of birth certificate, passport (similar data of another identity document), by whom and when issued;
70.2.6. unique record number in the Unified State Demographic Register (in case of entering information about a person into the Unified State Demographic Register).
{Clause 70.2 of Article 70 is supplemented by subparagraph 70.2.6 in accordance with Law No. 786-IX of 14.07.2020 }
70.3. The following data on individuals shall be included in the information base of the State Register:
70.3.1. sources of income;
70.3.2. objects of taxation;
70.3.3. the amount of accrued and/or received income;
70.3.4. the amount of accrued and/or paid taxes;
70.3.5. information about the taxpayer's tax rebate and tax benefits;
70.3.6. a unique record number in the Unified State Demographic Register based on the data of the administrator of such register, provided in the procedure for information interaction in accordance with the legislation.
{Clause 70.3 of Article 70 is supplemented by subparagraph 70.3.6 in accordance with Law No. 786-IX of 14.07.2020 }
70.4. The State Register shall contain information on the state registration, registration and registration of individual entrepreneurs and persons engaged in independent professional activities. Such information shall include:
70.4.1. dates, numbers of records, certificates and other documents, as well as the grounds for state registration, registration and registration, termination of entrepreneurial or independent professional activity, other registration data;
70.4.2. information on state registration, registration and recording of changes in personal data, replacement or extension of registration certificates;
70.4.3. place of business, telephone numbers and other additional information for contacting an individual entrepreneur or a person carrying out independent professional activities;
70.4.4. types of activities;
70.4.5. citizenship and number used for taxation in the country of citizenship - for foreigners;
70.4.6. taxation system with indication of its validity periods.
70.5. An individual taxpayer, regardless of age (both resident and non-resident), for whom a taxpayer registration card has not previously been formed and who is not included in the State Register, is obliged to personally or through a legal representative or authorized person submit to the relevant regulatory authority a taxpayer registration card, which is also an application for registration in the State Register, and present an identity document.
The registration card of an individual taxpayer may be submitted in electronic form by means of electronic communications in compliance with the requirements of legislation in the field of electronic trust services, electronic document management, and the provision of public (electronic public) services.
{ Item 70.5 of Article 70 is supplemented with a new paragraph in accordance with the Law No. 2888-IX dated 12.01.2023 }
Submission by a foreigner of an application for obtaining the status of electronic resident (e-resident) is equivalent to the personal submission to the relevant regulatory authority of the registration card of an individual taxpayer and an application for registration in the State Register.
{ Item 70.5 of Article 70 is supplemented with a new paragraph in accordance with the Law No. 2654-IX dated 06.10.2022 }
An individual taxpayer who, due to his/her religious beliefs, refuses to accept the registration number of the taxpayer's registration card is obliged to personally submit a notification and documents to the relevant regulatory authority to ensure his/her registration by last name, first name, patronymic and passport series and number, as well as present his/her passport.
An individual submits a taxpayer registration card or a notification (for individuals who, due to their religious beliefs, refuse to accept the registration number of a taxpayer registration card) to the regulatory authority at their tax address, and an individual who does not have a permanent place of residence in Ukraine - to the regulatory authority at the place of income generation or at the location of another taxable object.
To fill out the registration card of an individual taxpayer, the data of the identity document is used. To fill out the notification (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer registration card), the passport data is used.
The form of the registration card of an individual taxpayer and the notification (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer registration card) and the procedure for their submission are established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph 70.5 of Article 70 as amended by Law No. 1797-VIII of 21.12.2016 }
An individual is responsible under the law for the accuracy of the information submitted for registration in the State Register.
70.6. State civil registration bodies, bodies that register individuals are obliged to submit to the relevant supervisory bodies information on changes in data included in the registration card of an individual taxpayer, every month, but no later than the 10th of the following month.
{Paragraph one of clause 70.6 of Article 70 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1293-IX of 02.03.2021 }
The procedure for submitting such information and interaction between subjects of information relations is determined by the Cabinet of Ministers of Ukraine.
{Clause 70.6 of Article 70 as amended by Law No. 3609-VI of 07.07.2011 }
70.7. Individual taxpayers are required to submit to the supervisory authorities information about changes in data entered in the registration card or notification (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer registration card and have a mark in their passport), within a month from the date of occurrence of such changes by submitting a relevant application in the form and in the manner determined by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 70.7 of Article 70 as amended by Law No. 1797-VIII of 21.12.2016 }
70.8. The central executive body implementing state tax policy shall inform the territorial body about the state registration of an individual taxpayer in the State Register and changes to the data contained in the State Register:
{Clause 70.8 of Article 70 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 404-VII of 04.07.2013 ; as amended by Laws No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
70.8.1. at the place of registration of an individual;
70.8.2. at the place of residence of the individual;
70.8.3. by the place of receipt of income or the location of another object of taxation of an individual.
70.9. Upon application by a taxpayer, his legal representative or authorized person, the regulatory authority shall issue a document certifying registration in the State Register, except for persons who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have notified the relevant regulatory authority about this and have a mark in their passport.
This document indicates the registration number of the taxpayer's registration card.
The procedure for generating the registration number of a taxpayer's registration card is determined and approved by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph three of paragraph 70.9 of Article 70 as amended by Law No. 1797-VIII of 21.12.2016 }
The form of the document and the procedure for its issuance are established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph four of clause 70.9 of Article 70 as amended by Law No. 1797-VIII of 21.12.2016 }
Confirmation of the authenticity of the registration number of the taxpayer's registration card is a document certifying the registration of the person in the State Register (taxpayer card), or data on the registration number of the taxpayer's registration card from the State Register, entered in the passport of a citizen of Ukraine or birth certificate.
{Clause 70.9 of Article 70 is supplemented by the fifth paragraph in accordance with Law No. 786-IX of 14.07.2020 }
The person, at his own choice, presents one of the specified documents to provide data on the registration number of the taxpayer's registration card.
{Clause 70.9 of Article 70 is supplemented by the sixth paragraph in accordance with Law No. 786-IX of 14.07.2020 }
A person may present a copy of a document certifying the registration of a person in the State Register, including in electronic form, provided that the recipient of the information has the technical ability to verify the compliance of the registration data of an individual with the data of the State Register in electronic form by information and telecommunication means using technical and cryptographic information protection means in accordance with the requirements of the legislation on information protection.
{Clause 70.9 of Article 70 is supplemented by paragraph seven in accordance with Law No. 786-IX of 14.07.2020 }
70.10. The controlling body at the place of residence of an individual taxpayer may, at the request of such person, enter into the passport (seventh, eighth or ninth page) data on the registration number of the taxpayer's registration card from the State Register.
70.11. If inaccurate data or errors are found in the submitted registration card or notification (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer registration card), the individual may be denied registration and/or a mark in the passport or the registration period may be extended.
70.12. The registration number of the taxpayer's registration card or series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have officially notified the relevant regulatory authority and have a mark in their passport) are used by state authorities and local self-government bodies, legal entities regardless of organizational and legal forms, including the National Bank of Ukraine, banks, other financial institutions, non-bank payment service providers, electronic money issuers, exchanges, individuals engaged in independent professional activities, individual entrepreneurs, as well as individuals in all documents containing information about the objects of taxation of individuals or about the payment of taxes, in particular in the case of:
{Paragraph one of item 70.12 of Article 70 as amended by the Law No. 2888-IX dated 12.01.2023 }
70.12.1. payments of income from which taxes are withheld in accordance with the legislation of Ukraine. Individuals are obliged to submit information about the registration number of the account card to legal entities and individuals that pay them income;
70.12.2. conclusion of civil law contracts, the subject of which are objects of taxation and in respect of which obligations arise to pay taxes and fees;
70.12.3. opening accounts in banks, other financial institutions, non-bank payment service providers, electronic wallets in electronic money issuers, as well as in payment instructions when making non-cash payments by individuals;
{Sub-clause 70.12.3 of clause 70.12 of Article 70 as amended by the Law No. 2888-IX dated 12.01.2023 }
70.12.4. filling out customs declarations by individuals specified in paragraph 70.1 of this article when crossing the customs border of Ukraine;
70.12.5. payment of taxes and fees by individuals;
70.12.6. conducting state registration of individual entrepreneurs or issuing special permits (licenses, etc.) to such persons to conduct certain types of economic activities, as well as registration of independent professional activities;
{Subclause 70.12.6 of clause 70.12 of Article 70 as amended by Law No. 71-VIII of 28.12.2014 }
70.12.7. registration of property and other assets of individuals that are subject to taxation, or rights to it;
70.12.8. submission of declarations of income, property and other assets to regulatory authorities;
70.12.9. registration of vehicles that are transferred to the ownership of individuals;
70.12.10. registration of benefits, subsidies and other social payments from state trust funds to individuals;
70.12.11. in other cases specified by the laws of Ukraine and other regulatory legal acts.
70.13. Documents related to the conduct of operations provided for in paragraph 70.12 of this article that do not have the registration number of the taxpayer's registration card or series (if any) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have officially notified the relevant regulatory authority about this and have a mark in their passport) are considered to have been issued in violation of the requirements of the legislation of Ukraine.
70.14. The supervisory authority shall indicate the registration number of the taxpayer's registration card or series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have officially notified the relevant supervisory authority about this and have a mark in their passport) in all messages sent to it.
Each taxpayer shall indicate the registration number of his/her taxpayer registration card or series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer registration card and have officially notified the relevant regulatory authority and have a mark in their passport) in all reporting or other documents, as well as in other cases provided for by the legislation of Ukraine.
70.15. Information from the State Register:
70.15.1. are used by regulatory authorities exclusively to monitor compliance with the tax legislation of Ukraine;
70.15.2. is information with limited access, except for information on the registration of individuals - entrepreneurs and persons engaged in independent professional activities;
70.15.3. are transferred to the Unified State Demographic Register for verification of data on individuals in accordance with parts four and seven of Article 34 of the Law of Ukraine "On Public Electronic Registers" in the volumes and procedure established by the Cabinet of Ministers of Ukraine.
{Clause 70.15 of Article 70 is supplemented by subparagraph 70.15.3 in accordance with Law No. 3050-IX of 11.04.2023 }
70.16. Executive bodies and local self-government bodies, legal entities, self-employed persons, tax agents shall submit free of charge, in accordance with the procedure established by the Cabinet of Ministers of Ukraine, to the controlling bodies at their location or centrally in electronic form (for executive bodies), information about individuals related to the registration of such persons as taxpayers, the accrual, payment of taxes and control over compliance with the tax legislation of Ukraine, indicating the registration numbers of the taxpayer's registration cards or series (if any) and passport number (for individuals who have a mark in their passport stating the right to make any payments by series and passport number), in particular:
{Paragraph one of clause 70.16 of Article 70 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Laws No. 1946-IX of 12/14/2021 , No. 3813-IX of 06/18/2024 }
70.16.1. in addition to the information provided for in Article 51 of this Code, also executive authorities and local self-government bodies, legal entities, tax agents (except for individuals - entrepreneurs and/or persons engaged in independent professional activities, as tax agents and payers of a single contribution) - on the date of hiring or dismissal from work of individuals within 20 calendar days following the last calendar day of the reporting (tax) month, individuals - entrepreneurs and persons engaged in independent professional activities - on the date of hiring or dismissal from work of individuals within 40 calendar days following the last calendar day of the reporting (tax) quarter;
{Subparagraph 70.16.1 of paragraph 70.16 of Article 70 as amended by Law No. 4015-IX of 10.10.2024 - regarding the entry into force of certain provisions, see paragraph 1 of Section II; as amended by Law No. 4536-IX of 16.07.2025 }
70.16.2. bodies carrying out state registration of vehicles - on vehicles for which the right of ownership arises or terminates for individuals, monthly, but no later than the 10th of the following month;
{Subclause 70.16.2 of clause 70.16 of Article 70 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 2611-VIII of 08.11.2018 }
70.16.3. state registration authorities for sea, river and aircraft vessels - on vessels for which individuals have ownership rights arising or terminating, monthly, but no later than the 10th of the following month;
70.16.4. state civil registration authorities - about individuals who have died (for closing registration cards), as well as about changes by individuals of their last name, first name, patronymic, date and place of birth every month, but no later than the 10th of the following month;
{Subclause 70.16.4 of clause 70.16 of Article 70 as amended by Law No. 5083-VI of 05.07.2012 }
70.16.5. bodies that register private notarial, legal, and other independent professional activities and issue certificates of the right to engage in such activities - on the issuance or cancellation of a registration certificate - within five days from the date of the relevant action;
70.16.6. state registration bodies of rights to real estate - on taxable real estate in respect of which the right of ownership arises or terminates for individuals and legal entities, within the terms and procedure established by subparagraph 266.7.4 of paragraph 266.7 of Article 266 of this Code;
{Subclause 70.16.6 of Clause 70.16 of Article 70 as amended by Laws No. 5503-VI of 11/20/2012 , No. 71-VIII of 12/28/2014 ; as amended by Law No. 1797-VIII of 12/21/2016 }
70.16.7. guardianship and trusteeship bodies, educational institutions, healthcare institutions, social protection institutions and other institutions that, in accordance with the legislation, exercise guardianship, custody or management of the property of a ward are obliged to report the establishment of guardianship over individuals recognized by the court as incompetent, guardianship, custody and management of the property of minors, other minor individuals, individuals limited in legal capacity by the court, capable individuals over whom guardianship has been established in the form of patronage, guardianship or management of the property of individuals recognized by the court as missing, as well as further changes related to the specified guardianship, custody or management of property, to the supervisory authorities at their place of residence no later than within five calendar days from the date of adoption of the relevant decision;
{ Subparagraph 70.16.7 of paragraph 70.16 of Article 70 as amended by Law No. 3813-IX of 18.06.2024 }
70.16.7 - 1. the central executive body implementing state policy in the field of migration (immigration and emigration), including countering illegal (illegal) migration, citizenship, registration of individuals, refugees and other categories of migrants defined by law, no later than the next working day after the day of entering, in accordance with the procedure established by law, information into the Unified State Demographic Register - on registration/deregistration of the place of residence/stay of an individual, as well as on series (if any) and numbers of invalid passports;
{Clause 70.16 of Article 70 is supplemented by clause 70.16.7 - 1 in accordance with Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 1946-IX of 14.12.2021 ; as amended by Law No. 3813-IX of 18.06.2024 }
70.16.8. other executive authorities and local self-government bodies - information on other objects of taxation.
70.17. The State Register of Individual Taxpayers is formed on the basis of the State Register of Individual Taxpayers and Other Mandatory Payments. Registration cards of individuals who, at the time of entry into force of this Code, are registered in the State Register of Individual Taxpayers and Other Mandatory Payments, shall be assigned numbers corresponding to the identification numbers of individual taxpayers. Documents on registration of individuals in the State Register of Individual Taxpayers and Other Mandatory Payments, issued by regulatory authorities in accordance with the procedure established by the legislation in force before the entry into force of this Code, shall be considered valid for all cases provided for the use of registration numbers of registration cards of individuals, shall not be subject to mandatory replacement and shall be such as to certify the registration of individuals in the State Register of Individual Taxpayers.
Article 70 - 1. Grounds and procedure for acquiring and losing the status of electronic resident (e-resident)↑
70 - 1 .1. A foreigner has the right to acquire the status of an electronic resident (e-resident) after submitting an application for the acquisition of the status of an electronic resident (e-resident) through the "E-resident" information system, his identification and the provision of qualified electronic trust services.
70 - 1 .2. The following cannot be electronic residents (e-residents):
a) citizens of Ukraine;
b) foreigners who have the right to permanent residence in Ukraine or are tax residents of Ukraine;
c) stateless persons;
d) persons who receive income with a source of origin from Ukraine for goods, works, services (except for passive income);
e) persons who are citizens (subjects), residents or persons whose permanent place of residence (stay, registration) is states (jurisdictions) not included in the List of states whose citizens or residents may acquire the status of electronic resident (e-resident).
The list of states whose citizens or residents may acquire the status of electronic resident (e-resident) is established by the central executive body that ensures the formation and implementation of state policy in the field of digital economy, in agreement with the central executive body that implements state policy in the field of prevention and counteraction to the legalization (laundering) of proceeds from crime, financing of terrorism and financing of the proliferation of weapons of mass destruction, in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
The List of countries whose citizens or residents may acquire the status of electronic resident (e-resident) may not include the following countries:
recognized as an aggressor state and/or an occupying state in relation to Ukraine;
included in the FATF list of high-risk countries (jurisdictions) to which enhanced due diligence measures and/or countermeasures are applied in order to protect the international financial system from persistent and significant risks of money laundering, terrorist financing and financing of the proliferation of weapons of mass destruction (FATF "blacklist");
included in the list of states (territories) that have strategic deficiencies in the field of preventing and combating the legalization (laundering) of proceeds from crime, the financing of terrorism and the financing of the proliferation of weapons of mass destruction in accordance with FATF statements (FATF "grey list");
identified by the European Commission as a country with weak regimes for preventing and combating the legalization (laundering) of proceeds from crime, the financing of terrorism, and the financing of the proliferation of weapons of mass destruction.
70 - 1 .3. The procedure for obtaining and revoking the status of an electronic resident (e-resident) , identifying persons who intend to obtain the status of an electronic resident (e-resident), and providing them with access to qualified electronic trust services is determined by the Cabinet of Ministers of Ukraine.
Registration of an electronic resident (e-resident) is carried out by the supervisory authority based on information received from the "E-resident" information system.
70 - 1 .4. The grounds for revoking the status of an electronic resident (e-resident) are:
a) submission by a foreigner of an application for cancellation of the status of electronic resident (e-resident) at his own request;
b) cancellation of the status of electronic resident (e-resident) based on the decision of the central executive body that ensures the formation and implementation of state policy in the field of the digital economy, in the event of receiving information about:
death of a person, recognition of him as missing;
restriction of a person's civil capacity or recognition of his or her incapacity;
the person with the requirements of paragraph 70 - 1.2 of this article;
c) expiration of the document on the conformity of the qualified electronic signature tool or a positive expert opinion based on the results of the state examination in the field of cryptographic information protection of the qualified electronic signature tool used by the electronic resident (e-resident), provided that the electronic resident (e-resident) does not, within one month from the date of expiration of the relevant document, obtain a qualified electronic signature tool with a valid document on conformity or with a positive expert opinion based on the results of the state examination in the field of cryptographic information protection.
A foreigner loses the status of electronic resident (e-resident) from the day following the day of entry of a record on the cancellation of the status of electronic resident (e-resident) in the "E-Resident" information system.
The procedure for forming and maintaining the "E-Resident" information system and access to it by regulatory authorities and tax agents of single tax payers is established by the Cabinet of Ministers of Ukraine.
70 - 1 .5. In the event of receiving information about the loss of the status of an electronic resident (e-resident) by a person, the regulatory authority automatically removes such a person from the register as an electronic resident (e-resident).
{Chapter 6 is supplemented by Article 70 - 1 in accordance with the Law No. 2654-IX dated 06.10.2022 }
CHAPTER 7. INFORMATION AND ANALYTICAL SUPPORT OF THE ACTIVITIES OF CONTROLLING BODIES↑
Article 71. Determination of information and analytical support for the activities of the supervisory authority↑
71.1. Information and analytical support for the activities of regulatory authorities - a set of measures coordinated by the central executive body that ensures the formation and implementation of state financial policy, regarding the collection, processing and use of information necessary for the performance of the functions assigned to regulatory authorities.
{Clause 71.1 of Article 71 as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 1797-VIII of 21.12.2016 }
72.1. For information and analytical support of the activities of the regulatory authority, information received from:
72.1.1. from taxpayers and tax agents, in particular information:
72.1.1.1. contained in tax returns, calculations, reports on the use of income (profits) of a non-profit organization defined in paragraph 133.4 of Article 133 of this Code, and other reporting documents;
{Subclause 72.1.1.1 of subparagraph 72.1.1 of clause 72.1 of Article 72 as amended by Law No. 652-VIII of 17.07.2015 }
72.1.1.2. contained in copies of documents provided by large taxpayers in electronic form on accounting of income, expenses and other indicators related to the determination of objects of taxation (tax liabilities), primary documents maintained in electronic form, accounting registers, financial statements, other documents related to the calculation and payment of taxes and fees;
{Subclause 72.1.1.2 of subparagraph 72.1.1 of clause 72.1 of Article 72 as amended by Law No. 3609-VI of 07.07.2011 }
72.1.1.3. on financial and economic transactions of taxpayers;
72.1.1.4. on the use of settlement transaction registrars, software settlement transaction registrars, including electronic copies of settlement documents and fiscal reporting checks submitted to regulatory authorities. For the purposes of this subparagraph, the terms are used in the meanings given in the Law of Ukraine "On the Use of Settlement Transaction Registrars in the Sphere of Trade, Public Catering and Services";
{ Subparagraph 72.1.1.4 of subparagraph 72.1.1 of paragraph 72.1 of Article 72 as amended by Law No. 129-IX of 20.09.2019 }
72.1.2. from executive authorities, local self-government bodies, the National Bank of Ukraine and the National Securities and Stock Market Commission, in particular information:
{Paragraph one of subparagraph 72.1.2 of paragraph 72.1 of Article 72 as amended by Law No. 2970-IX of March 20, 2023 }
72.1.2.1. on the objects of taxation provided and/or registered by such bodies. The specified information must contain, in particular, the type, characteristics, individual features of the object of taxation (if any), by which it can be identified;
72.1.2.2. on the results of state control over the taxpayer's economic activities;
72.1.2.3. contained in reporting documents (except for personalized statistical information) submitted by the taxpayer to executive authorities and/or local self-government bodies;
{Subclause 72.1.2.3 of subparagraph 72.1.2 of clause 72.1 of Article 72 as amended by Law No. 4834-VI of 24.05.2012 }
72.1.2.4. on the rates of local taxes and fees established by local self-government bodies and tax benefits granted by such bodies;
72.1.2.5. on permits, licenses, patents, certificates for the right to carry out certain types of activities, which must contain, in particular:
name of the taxpayer to whom such permits, licenses, patents have been issued;
tax number or registration number of the individual's registration card;
type of permit document;
type of activity for which a permit has been issued;
date of issue of the permit document;
the validity period of the permit document, information on the termination (suspension) of the permit document with an indication of the reasons for such termination (suspension);
payment of due fees for the issuance of a permit;
a list of places of activity for which a permit has been issued;
72.1.2.6. on export and import transactions of taxpayers;
72.1.2.7. lists of financial institutions, professional participants in capital markets, collective investment institutions and persons who are not financial institutions but have the right to provide certain types of financial services;
{Sub -clause 72.1.2 of clause 72.1 of Article 72 is supplemented by sub-clause 72.1.2.7 in accordance with the Law No. 2970-IX dated 20.03.2023 }
72.1.3. from banks, other financial institutions, non-bank payment service providers, electronic money issuers - information on the availability and movement of funds in the taxpayer's accounts/electronic wallets, reports on accountable accounts submitted by financial agents;
{Subclause 72.1.3 of clause 72.1 of Article 72 as amended by Laws No. 323-IX of 03.12.2019 , No. 2888-IX of 12.01.2023 }
72.1.3 - 1. from persons who are financial agents - reports on accountable accounts, other documents and information provided in accordance with the requirements of Article 39 - 3 of this Code;
{ Clause 72.1 of Article 72 is supplemented by subparagraph 72.1.3 - 1 in accordance with the Law No. 2970-IX dated 20.03.2023 }
72.1.4. from the authorities of other states, international organizations or non-residents;
72.1.5. as a result of tax control;
{Subclause 72.1.5 of clause 72.1 of Article 72 as amended by Laws No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 }
72.1.6. for information and analytical support of activities, other information published in accordance with the legislation and/or voluntarily or upon request provided to the regulatory authority in accordance with the procedure established by law, as well as information provided in the complaint of the buyer (consumer) regarding the taxpayer's violation of the established procedure for conducting settlement transactions using settlement transaction registrars and/or software settlement transaction registrars, is also used;
{Subclause 72.1.6 of Clause 72.1 of Article 72 as amended by Law No. 129-IX of 20.09.2019 }
72.1.7. from the central executive body that ensures the formation and implementation of state policy in the field of the digital economy, information on the compliance of Diya City residents with the requirements of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", in particular regarding the inclusion/exclusion of taxpayers in/from the Diya City register;
{Clause 72.1 of Article 72 is supplemented by subparagraph 72.1.7 in accordance with Law No. 1946-IX of 14.12.2021 }
72.1.8. from the Unified State Register of Court Decisions - final court convictions for committing criminal offenses provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, against taxpayers or any other persons who acted on behalf of and/or in the interests of such taxpayers, with an indication in the text of the verdict of information that cannot be disclosed in the texts of court decisions open to public access in the Unified State Register of Court Decisions;
{Clause 72.1 of Article 72 is supplemented by subparagraph 72.1.8 in accordance with Law No. 4112-IX of 04.12.2024 }
72.1.9. from the Ministry of Defense of Ukraine - information from the Defense City register, decisions on granting, terminating, losing the status of a Defense City resident and the period of non-compliance of a Defense City resident with the requirements established by the Law of Ukraine "On National Security of Ukraine".
{Clause 72.1 of Article 72 is supplemented by subparagraph 72.1.9 in accordance with Law No. 4577-IX of 21.08.2025 }
Article 73. Obtaining tax information by supervisory authorities↑
73.1. The information specified in Article 72 of this Code shall be provided free of charge to the regulatory authorities periodically or upon a separate written request of the regulatory authority within the terms specified in Clause 73.2 of this Code.
73.2. The information provided periodically includes the information specified in subparagraphs 72.1.1.1 , 72.1.1.2 , 72.1.1.3 (in relation to the taxpayer's obligation to provide a breakdown of tax credit and tax liabilities by counterparty, as provided for in Section V of this Code), 72.1.1.4 , 72.1.2.1 , 72.1.2.3 , 72.1.2.4 , 72.1.2.5 , 72.1.2.6 , 72.1.2.7 of subparagraph 72.1.2 , subparagraph 72.1.5 of Article 72 of this Code.
{ Clause 73.2 of Article 73 as amended by the Law No. 2970-IX dated 20.03.2023 }
Unless other sections of this Code specify other deadlines for providing such information:
73.2.1. the information specified in subparagraphs 72.1.2.1 and 72.1.2.5 of subparagraph 72.1.2 of paragraph 72.1 of Article 72 of this Code shall be provided by executive authorities and local self-government bodies monthly within 10 calendar days of the month following the reporting month;
73.2.2. the information specified in subparagraph 72.1.2.3 of subparagraph 72.1.2 of paragraph 72.1 of Article 72 of this Code shall be provided by executive authorities and local self-government bodies within 10 calendar days from the date of submission of such reporting to the relevant executive authority or local self-government body. State statistics bodies shall provide information in accordance with the plan of state statistical observations;
73.2.3. the information specified in subparagraph 72.1.2.4 of subparagraph 72.1.2 of paragraph 72.1 of Article 72 of this Code shall be provided to local self-government bodies no later than 10 calendar days from the date of entry into force of the relevant decision;
{Subclause 73.2.4 of clause 73.2 of Article 73 was excluded on the basis of Law No. 404-VII of 04.07.2013 }
The procedure for submitting information to regulatory authorities is determined by the Cabinet of Ministers of Ukraine.
73.3. Controlling bodies have the right to address taxpayers and other subjects of information relations with a written request for the provision of information (an exhaustive list and grounds for the provision of which are established by law) necessary for the performance of the functions and tasks assigned to the controlling bodies, and its documentary confirmation.
Such a request is signed by the head (his deputy or authorized person) of the regulatory body and must contain:
1) the grounds for sending a request in accordance with this paragraph, indicating the information confirming this;
2) a list of information requested and a list of documents to be provided;
3) the seal of the controlling body.
73.3.1. A written request for information shall be sent to a taxpayer or other subject of information relations if at least one of the following grounds exists:
1) based on the results of the analysis of tax information obtained in accordance with the procedure established by law, facts have been identified that may indicate a violation by the taxpayer of tax, currency legislation, legislation in the field of preventing and countering the legalization (laundering) of proceeds from crime, financing of terrorism and financing of the proliferation of weapons of mass destruction, and other legislation, control over compliance with which is entrusted to regulatory authorities, with the mandatory indication of such facts in the request;
2) to determine the compliance of the terms of a controlled transaction with the arm's length principle when exercising tax control over transfer pricing in accordance with Article 39 of this Code and/or to determine the level of normal prices in cases specified by this Code;
3) the data contained in the tax return submitted by the taxpayer is found to be inaccurate;
4) a complaint has been filed against a taxpayer regarding the failure of such taxpayer to provide:
tax invoice to the buyer or about the seller of goods/services making errors when indicating the mandatory details of the tax invoice, provided for in paragraph 201.1 of Article 201 of this Code, and/or the seller/buyer violating the deadlines for registering the tax invoice in the Unified Register of Tax Invoices and/or calculating the adjustment;
excise invoice to the buyer or about a violation of the procedure for filling out and/or registration of the excise invoice;
5) in the event of a counter-reconciliation;
6) an error or inaccuracy of the data contained in the report on reportable accounts submitted by the financial agent is detected, or in accordance with the Common Reporting Standard CRS, the financial agent has submitted a report on reportable accounts with information on undocumented accounts, or the submission of inaccurate information by the account holder to the financial agent is detected;
7) a notification has been received from the competent authority of a foreign jurisdiction with which Ukraine has concluded an international agreement containing provisions on the exchange of information for tax purposes, the binding consent of which has been granted by the Verkhovna Rada of Ukraine, or an interdepartmental agreement has been concluded on its basis, about the detection by such authority of an error, incomplete or unreliable data provided by the financial agent regarding the accountable account of a person who is a resident of the relevant foreign jurisdiction, or about another violation or failure by the financial agent to fulfill the obligations provided for by the FATCA Agreement or the Common Reporting Standard CRS, including about the participation of the financial agent or its client in transactions or operations provided for in paragraph 39 - 3.6 of Article 39 - 3 of this Code;
8) a request for information has been received from a competent authority of a foreign state on the basis of an international agreement containing provisions on the exchange of information for tax purposes, and the requested information is not available to the supervisory authority;
9) in other cases specified by this Code.
73.3.2. A request shall be deemed to have been duly served if it has been sent in accordance with the procedure specified in Article 42 of this Code.
73.3.3. Taxpayers and other subjects of information relations are obliged to provide the information specified in the request of the regulatory authority and its documentary confirmation (except for conducting a counter-reconciliation) within 15 business days from the day following the day of receipt of the request (unless otherwise provided by this Code), in accordance with the procedure specified in Article 42 of this Code.
In the event of a counter-reconciliation, taxpayers and other subjects of information relations are obliged to provide the information specified in the request of the regulatory authority within 10 business days from the day following the day of receipt of the request, and documentary confirmation of this information at the request of the regulatory authority in accordance with the procedure specified in Article 42 of this Code.
73.3.4. If the request is made in violation of the requirements specified in paragraphs one through five of paragraph 73.3 of Article 73 of this Code, the taxpayer is exempted from the obligation to provide a response to such a request.
In the event that a taxpayer receives a request for the provision of information and its documentary confirmation, which have already been provided by this taxpayer upon previous requests of this regulatory body, such taxpayer shall have the right to provide the regulatory body with information on the date and number of the letter by which the specified information and its documentary confirmation were provided to such regulatory body. In such case, the taxpayer shall be exempted from the obligation to provide information and its documentary confirmation in this regard.
Information at the request of the regulatory authority is provided by the National Bank of Ukraine, banks, other financial institutions, non-bank payment service providers, and electronic money issuers free of charge in the manner and to the extent established by the laws of Ukraine "On Banks and Banking Activities" and "On Payment Services" .
The procedure for obtaining information by regulatory authorities upon their written request is determined by the Cabinet of Ministers of Ukraine.
73.3.5. Information at the request of the regulatory authority shall be provided by banks, non-bank payment service providers, electronic money issuers, persons who are financial agents, and other entities that, in accordance with the legislation of Ukraine, are obliged to store the requested information free of charge and in the amounts necessary for the regulatory authorities to fulfill international obligations defined by the Convention on Mutual Administrative Assistance in Tax Matters , the international treaty of Ukraine on the avoidance of double taxation and another international treaty containing provisions on the exchange of information for tax purposes, the consent to which has been granted by the Verkhovna Rada of Ukraine, or by interdepartmental agreements concluded on their basis.
Disclosure of such information by providers of payment services for account maintenance, other financial institutions and persons who are not financial institutions but have the right to provide certain financial services, the state regulation and supervision of which is carried out by the National Bank of Ukraine, is carried out in accordance with the procedure established by the National Bank of Ukraine, by other financial agents - in accordance with the procedure established by the National Securities and Stock Market Commission, within the powers defined by the legislation in the field of regulation of activities for the provision of financial services.
73.3.6. If, on the basis of an international agreement containing provisions on the exchange of information, a competent authority of a foreign state addresses a supervisory authority with a request (hereinafter referred to as a foreign request) containing a request not to notify the taxpayer of the fact of the request of a foreign competent authority, the supervisory authority shall indicate in the request sent to the taxpayer or other person that the request is sent on the basis of subparagraph 8 of subparagraph 73.3.1 of paragraph 73.3 of this Article, without disclosing the content of the foreign request.
The supervisory authority has the right to send a request to the subject of primary financial monitoring on the basis of subparagraph 8 of subparagraph 73.3.1 of paragraph 73.3 of this Article, provided that all of the following requirements are met:
1) the information requested in the foreign request is not available to the supervisory authority;
2) the person to whom the request of the supervisory authority is sent is obliged to store the information that is the subject of the request or has access to it in accordance with the provisions of the law.
If a request is sent to a person on the basis of subparagraph 8 of subparagraph 73.3.1 of paragraph 73.3 of this Article (in connection with the collection of information for a competent authority of a foreign state), the provisions of this Article shall not be interpreted as allowing a bank or other account servicing payment service provider to refuse to provide information at the request of a supervisory authority solely on the grounds that the information requested is restricted information (including information constituting banking secrecy).
{ Clause 73.3 of Article 73 as amended by Laws No. 3609-VI of 07.07.2011 , No. 408-VII dated 04.07.2013 , No. 71-VIII dated 28.12.2014 , No. 909-VIII dated 24.12.2015 , No. 1797-VIII dated 12/21/2016 , No. 323-IX dated 12/03/2019 , No. 466-IX dated 01/16/2020 , No. 1914-IX dated 11/30/2021 , No. 2888-IX dated 01/12/2023 ; as amended by Law No. 2970-IX dated 03/20/2023 }
73.4. Information on the availability and movement of funds/electronic money in the accounts/electronic wallets of the taxpayer shall be provided in volumes greater than those provided for in paragraph 73.3 of this Article by banks, other financial institutions, non-bank payment service providers, and electronic money issuers to regulatory authorities by court decision. To obtain such information, the regulatory authority shall apply to the court.
The rules established by this paragraph do not apply to:
1) requests for financial agents to provide information on financial accounts in the amounts specified by the FATCA Agreement , the CRS Multilateral Agreement and the CRS Common Reporting Standard;
2) requests sent by the supervisory authority on the basis of subparagraph 8 of subparagraph 73.3.1 of paragraph 73.3 of this article for the purposes of collecting information for the competent authority of a foreign state in accordance with the Convention on Mutual Administrative Assistance in Tax Matters , an international treaty of Ukraine on the avoidance of double taxation or another international treaty containing provisions on the exchange of information for tax purposes.
{Clause 73.4 of Article 73 as amended by Laws No. 323-IX of 03.12.2019 , No. 2888-IX of 12.01.2023 ; as amended by Law No. 2970-IX of 20.03.2023 }
73.5. In order to obtain tax information necessary in connection with inspections, regulatory authorities have the right to cross-check data of business entities regarding the taxpayer.
During the counter-reconciliation:
data obtained from taxpayers and other subjects of information relations is compared in order to document economic relations with the taxpayer and fees, as well as to confirm the relationship, type, volume and quality of transactions and settlements carried out between them, in order to clarify the completeness of their reflection in the taxpayer's accounting;
It is ensured that tax information necessary to determine whether the conditions of a controlled transaction comply with the arm's length principle is obtained in cases provided for in subparagraph 39.5.2.13 of subparagraph 39.5.2 of paragraph 39.5 of Article 39 of this Code.
During the cross-check, only the issues specified in the written request of the regulatory authority for cross-checking are clarified.
The form of the request of the controlling body for a counter-reconciliation is established by the central executive body that ensures the formation and implementation of state financial policy.
Counter-reconciliations are not inspections and are carried out in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
Based on the results of the counter-reconciliations, a certificate is drawn up and provided to the business entity within ten days.
Repeated cross-checks by regulatory authorities on the same issue are prohibited.
{Clause 73.5 of Article 73 as amended by Law No. 652-VIII of 17.07.2015 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 }
73.6. Information received by the regulatory authorities from a competent authority of a foreign state in accordance with international treaties containing provisions on the exchange of information for tax purposes, the binding nature of which has been approved by the Verkhovna Rada of Ukraine, or interdepartmental agreements concluded on their basis, is information with restricted access.
{Article 73 is supplemented by paragraph 73.6 in accordance with Law No. 323-IX of 03.12.2019 }
Article 74. Processing and use of tax information↑
74.1. Tax information collected in accordance with this Code is stored in the databases of Information, telecommunications and information and telecommunications systems (hereinafter referred to as the Information Systems) of the central executive body implementing state tax policy.
Information systems and means of their support, developed, manufactured or purchased by the central executive body implementing state tax policy, are state property.
The system for protecting tax information stored in the databases of Information Systems is established by the central executive body implementing state tax policy.
The entry of information into the databases of Information Systems and its processing are carried out by the supervisory authority specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, as well as by the supervisory authority specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code, in accordance with the procedure for information interaction in accordance with paragraph 41.2 of Article 41 of this Code.
{Paragraph four of clause 74.1 of Article 74 as amended by Law No. 466-IX of 16.01.2020 }
The list of Information Systems is determined by the central executive body that implements state tax policy.
{Clause 74.2 of Article 74 was excluded on the basis of Law No. 2245-VIII of 07.12.2017 }
74.3. The collected tax information and the results of its processing are used to perform the functions and tasks assigned to the regulatory authorities, as well as by the central executive body that ensures the formation and implementation of state financial policy, to form and implement a unified state tax policy.
{Article 74 as amended by Law No. 5083-VI of 05.07.2012 ; text of Article 74 as amended by Law No. 1797-VIII of 21.12.2016 ; text of Article 74 as amended by Law No. 466-IX of 16.01.2020 }
75.1. Supervisory bodies have the right to conduct desk, documentary (scheduled or unscheduled; on-site or off-site) and actual inspections.
Desk and documentary inspections are conducted by supervisory authorities within the limits of their powers exclusively in cases and in accordance with the procedure established by this Code, and actual inspections - by this Code and other laws of Ukraine, control over compliance with which is entrusted to supervisory authorities.
Types of documentary checks, the procedure for planning, conducting and recording their results, carried out by the supervisory authority specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code, are established by the Customs Code of Ukraine .
{Clause 75.1 of Article 75 is supplemented by the third paragraph in accordance with Law No. 466-IX of January 16, 2020 }
75.1.1. An inspection carried out at the premises of the controlling body solely on the basis of data specified in the taxpayer's tax declarations (calculations) and data from the electronic administration system for value added tax (data from the central executive body implementing the state policy in the field of treasury services for budget funds, in which payers' accounts are opened in the electronic administration system for value added tax, data from the Unified Register of Tax Invoices and data from customs declarations), as well as data from the Unified Register of Excise Invoices and data from the electronic administration system for the sale of fuel and ethyl alcohol, data from the SOD of the RRO, data from the Unified Register of Licensees and Places of Fuel Circulation and the Unified Register of Licensees for the Production and Circulation of Ethyl Alcohol, Alcoholic Distillates, Alcoholic Beverages, Tobacco Products, Tobacco Raw Materials and Liquids Used in Electronic Cigarettes, is considered to be an in-house inspection.
{Paragraph one of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 129-IX of 09/20/2019 , No. 4015-IX of 10/10/2024 }
The subject of a desk inspection may also be:
{Subparagraph 75.1.1 of paragraph 75.1 of Article 75 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 1946-IX of 12/14/2021 ; as amended by Law No. 2720-IX of 11/03/2022 ; as amended by Law No. 2970-IX of 03/20/2023 }
1) timeliness of filing tax returns (calculations);
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
2) timeliness of registration of tax invoices and/or calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, excise invoices and/or calculations of adjustments to excise invoices in the Unified Register of Excise Invoices, correction of errors in tax invoices;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
3) timeliness of payment of the agreed amount of tax (monetary) liability solely on the basis of data stored (processed) in the relevant information databases;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
4) completeness of the calculation and timeliness of payment of personal income tax and a single contribution to mandatory state social insurance in case of non-compliance of the Dia City resident with the requirements specified in paragraphs 2 , 3 of part one and paragraph 10 of part two of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine";
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
5) timeliness of submission of an application for registration of financial agents in accordance with the requirements of Article 39-3 of this Code;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
6) timeliness of submission by financial agents of reports on accountable accounts and corrected reports on accountable accounts;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
7) timeliness of financial agents' responses to requests (notifications) from the regulatory authority sent in cases specified in Article 39-3 of this Code;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
the ownership structure and ultimate beneficial owners in accordance with the requirements of clause 44-1.2 of Article 44-1 of this Code;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
9) timeliness of submission by the person managing or administering the trust of a notification of the conclusion of an agreement on the management or administration of the trust or of the termination of such an agreement, financial statements, copies of primary documents and other information regarding the trust at the request of the supervisory authority in cases provided for in Article 44-2 of this Code;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
10) timeliness of providing information at the request of the regulatory authority in accordance with clause 44-1.3 of Article 44-1 , subparagraphs 6-8 of subparagraph 73.3.1 of clause 73.3 of Article 73 of this Code ;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
11) timeliness and completeness of payment of the agreed amount of monetary obligation in the form of an advance payment of corporate income tax, determined in accordance with Clause 141.13 of Article 141 of this Code, based on data from the Register of Foreign Currency Exchange Points;
{Paragraph of subparagraph 75.1.1 of paragraph 75.1 of Article 75 as amended by Law No. 2970-IX of 20.03.2023 }
12) timeliness and completeness of payment of the agreed amount of monetary obligation in the form of an advance payment for corporate income tax, determined in accordance with Clause 141.14 of Article 141 of this Code, as well as timeliness and completeness of payment of the agreed amount of monetary obligation in the form of an advance payment for personal income tax, determined in accordance with Subclause 177.5.1 - 1 of Clause 177.5 of Article 177 of this Code.
{Subparagraph 75.1.1 of paragraph 75.1 of Article 75 is supplemented by paragraph fourteen in accordance with Law No. 4015-IX of 10.10.2024 }
{Subclause 75.1.1 of Clause 75.1 of Article 75 as amended by Laws No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 , No. 1797-VIII of 21.12.2016 }
75.1.2. A documentary audit is considered an audit whose subject is the timeliness, reliability, completeness of the calculation and payment of all taxes and fees provided for by this Code, as well as compliance with currency and other legislation, control over which is entrusted to the regulatory authorities, compliance by the employer with the legislation on the conclusion of an employment contract, registration of employment relations with employees (employees) and which is carried out on the basis of tax declarations (calculations), financial, statistical and other reporting, tax and accounting registers, the maintenance of which is provided for by law, primary documents used in accounting and tax accounting and related to the calculation and payment of taxes and fees, compliance with the requirements of other legislation, control over which is entrusted to the regulatory authorities, as well as documents and tax information received by the regulatory authority in accordance with the procedure established by law, including the results of audits of other taxpayers.
A documentary scheduled inspection is carried out in accordance with the inspection plan-schedule.
During scheduled inspections of taxpayers who are financial agents, the subject of inspection shall also be compliance by financial agents with the requirements of Article 39-3 of this Code.
{Subparagraph 75.1.2 of paragraph 75.1 of Article 75 is supplemented with a new paragraph in accordance with Law No. 2970-IX of March 20, 2023 }
The issue of compliance by the taxpayer with the arm's length principle cannot be the subject of a scheduled documentary audit, except for cases of verification of compliance by the taxpayer with the requirements of subparagraphs 140.5.4 , 140.5.5-1 , 140.5.6 of paragraph 140.5 of Article 140 of this Code.
{Subclause 75.1.2 of clause 75.1 of Article 75 is supplemented with a new paragraph in accordance with Law No. 408-VII of 04.07.2013 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 ; with amendments made in accordance with Law No. 1117-IX dated 17.12.2020 }
An unscheduled documentary inspection is not provided for in the work plan of the regulatory body and is carried out if at least one of the grounds specified in this Code is present.
{Paragraph of subparagraph 75.1.2 of paragraph 75.1 of Article 75 as amended by Law No. 1797-VIII of 21.12.2016 }
A documentary on-site inspection is an inspection conducted at the taxpayer's location or at the location of the property subject to such inspection.
A documentary off-site inspection is an inspection that is carried out at the premises of the regulatory authority.
Documentary non-visit unscheduled electronic inspection at the taxpayer's request (hereinafter referred to as an electronic inspection) is an inspection conducted on the basis of an application submitted by a taxpayer with a low level of risk, determined in accordance with Clause 77.2 of Article 77 of this Code, to the supervisory authority in which he is registered for tax purposes. The application is submitted 10 calendar days before the expected start of the electronic inspection, but not earlier than the official notification of the central executive authority implementing state tax policy on the introduction of such an inspection for the relevant taxpayers: those applying the simplified system of taxation, accounting and reporting; micro, small and medium-sized business entities; other taxpayers. The form of the application , the procedure for its submission , and the decision to conduct an electronic inspection are established by the central executive authority ensuring the formation and implementation of state financial policy.
{Subclause 75.1.2 of clause 75.1 of Article 75 is supplemented by a paragraph in accordance with Law No. 5503-VI of 20.11.2012 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 , No. 1797-VIII of 21.12.2016 }
75.1.3. An inspection is considered to be actual if it is carried out at the place of actual conduct of activities by the taxpayer, the location of business or other objects of ownership of such a taxpayer. Such an inspection is carried out by the supervisory authority regarding compliance with the norms of legislation on the regulation of cash circulation, the procedure for taxpayers to perform settlement operations, conducting cash transactions, the availability of licenses, certificates, including on the production and circulation of excisable goods, compliance by the employer with the legislation on the conclusion of an employment contract, registration of employment relations with employees (employees).
{Paragraph one of subparagraph 75.1.3 of paragraph 75.1 of Article 75 as amended by Law No. 5083-VI of 05.07.2012 }
{Paragraph two of subparagraph 75.1.3 of paragraph 75.1 of Article 75 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
{Subclause 75.1.3 of Clause 75.1 of Article 75 as amended by Laws No. 3205-VI of 07.04.2011 , No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
Article 76. Procedure for conducting a desk inspection↑
76.1. A desk inspection is conducted by officials of the supervisory authority without any special decision of the head (his deputy or authorized person) of such authority or a referral for its conduct.
{Paragraph one of clause 76.1 of Article 76 as amended by Law No. 1797-VIII of 21.12.2016 }
All tax reporting is subject to a desk audit in a continuous manner.
The taxpayer's consent to the inspection and his presence during the desk inspection are not required.
76.2. The procedure for processing the results of a desk inspection shall be carried out in accordance with the requirements of Article 86 of this Code.
76.3. A desk audit of a tax return or a clarification calculation may be conducted only within 30 calendar days following the last day of the deadline for their submission, and if such documents were submitted later, - following the day of their actual submission, except for a desk audit of a tax return or clarification calculation (if submitted), which includes an application for the return of the amount of budget compensation, the term of which is determined by Article 200 of this Code.
{Paragraph one of clause 76.3 of Article 76 as amended by Law No. 3603-IX of 23.02.2024 }
A desk investigation on other issues shall be conducted taking into account the limitation periods specified in Article 102 of this Code.
{Article 76 is supplemented by paragraph 76.3 in accordance with Law No. 1797-VIII of 21.12.2016 }
76.4. Desk inspections on issues specified in Article 39 - 3 of this Code shall be conducted taking into account the requirements of Article 39 - 3 of this Code.
{Article 76 is supplemented by paragraph 76.4 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 77. Procedure for conducting documentary scheduled inspections↑
77.1. A planned documentary audit must be provided for in the schedule for conducting planned documentary audits.
The schedule of documentary scheduled inspections for the current year is published on the official website of the central executive body implementing state tax policy by December 25 of the year preceding the year in which such documentary scheduled inspections will be conducted.
{Clause 77.1 of Article 77 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
77.2. Taxpayers who are at risk of non-payment of taxes and fees, non-compliance with other legislation, control over which is entrusted to regulatory authorities, are selected for the schedule of documentary scheduled inspections.
The frequency of documentary scheduled audits of taxpayers is determined depending on the degree of risk in the activities of such taxpayers, which is divided into high, medium and low. Taxpayers with a low degree of risk are included in the schedule no more often than once every three calendar years, medium - no more often than once every two calendar years, high - no more often than once a calendar year.
The procedure for forming, approving the plan-schedule and making changes to it, as well as the list of risks and their division into levels, are established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph three of clause 77.2 of Article 77 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
Amendments to the schedule of documentary scheduled inspections for the current year are allowed no more than once in the first and once in the second quarter of such year, except for cases when the changes are related to changes in the name of a taxpayer that has already been included in the schedule and/or correction of technical errors.
{Clause 77.2 of Article 72 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
A documentary audit of a taxpayer who was included in the schedule of documentary scheduled audits for the current year as a result of changes made in such year (other than a change in the name of a taxpayer already included in the schedule and/or correction of technical errors) may be initiated no earlier than July 1 of the current year in the event of changes being made to the schedule of documentary audits for the current year in the first quarter of such year and no earlier than October 1 of the current year in the event of changes being made to the schedule of documentary audits for the current year in the second quarter of such year.
{Clause 77.2 of Article 72 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
The updated schedule is published on the official website of the central executive body implementing state tax policy by the 30th of the last month of the quarter (in cases of changes in the name of a taxpayer that has already been included in the schedule and/or correction of technical errors - by the 30th of the month preceding the month in which such documentary scheduled inspections will be conducted).
{Clause 77.2 of Article 72 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Taxpayers - legal entities that meet the criteria specified in paragraph 44 of subsection 4 of section XX "Transitional provisions" of this Code, and whose amount of value added tax paid to the budget is not less than five percent of the declared income for the reporting tax period, as well as self-employed persons whose amount of taxes paid is not less than five percent of the declared income for the reporting tax period, are included in the schedule no more often than once every three calendar years. The specified norm does not apply to such taxpayers in case of violation by them of articles 45 , 49 , 50 , 51 , 57 of this Code.
{Paragraph of Clause 77.2 of Article 77 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
77.3. It is prohibited to conduct a documentary scheduled audit of certain types of obligations to budgets, except for the correctness of the calculation, completeness and timeliness of payment of customs duties, taxes, fees and a single contribution when paying (accumulating) income to individuals, personal income tax and obligations under budget loans and credits guaranteed by budget funds.
{Clause 77.3 of Article 77 as amended by Law No. 1797-VIII of 21.12.2016 }
77.4. A decision to conduct a scheduled documentary inspection shall be made by the head (his deputy or authorized person) of the supervisory body, which shall be formalized by an order.
{Paragraph one of clause 77.4 of Article 77 as amended by Law No. 1797-VIII of 21.12.2016 }
The right to conduct a documentary scheduled audit of a taxpayer is granted only if he (his representative) is sent (handed over) a copy of the order to conduct a documentary scheduled audit and a written notification indicating the date of commencement of such audit, no later than 10 calendar days before the date of the said audit, in accordance with the procedure specified in Article 42 of this Code.
{Paragraph two of paragraph 77.4 of Article 77 as amended by Law No. 466-IX of January 16, 2020 }
77.5. In the event that inspections of the same taxpayer are planned by controlling bodies and state financial control bodies in the reporting period, such inspections shall be conducted by the said bodies simultaneously. The procedure for coordinating such inspections and involving other bodies provided for by law in the inspections shall be determined by the Cabinet of Ministers of Ukraine.
{Clause 77.5 of Article 77 as amended by Law No. 404-VII of 04.07.2013 }
77.6. Admission of officials of controlling bodies to conduct a documentary scheduled on-site inspection shall be carried out in accordance with Article 81 of this Code. A documentary scheduled non-on-site inspection shall be carried out in accordance with the procedure provided for in Article 79 of this Code.
77.7. The deadlines for conducting a scheduled documentary inspection are established by Article 82 of this Code.
77.8. The list of materials that may be the basis for conclusions during a documentary scheduled audit, and the procedure for taxpayers to provide documents for such an audit are established by Articles 83 and 85 of this Code.
77.9. The procedure for recording the results of a documentary scheduled inspection is established by Article 86 of this Code.
Article 78. Procedure for conducting unscheduled documentary inspections↑
78.1. An unscheduled documentary inspection is carried out if at least one of the following grounds exists:
{Paragraph one of clause 78.1 of Article 78 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1797-VIII of 12/21/2016 }
78.1.1. tax information has been received indicating a violation by the taxpayer of currency, tax legislation, legislation in the field of prevention and counteraction to the legalization (laundering) of proceeds from crime, financing of terrorism and financing of the proliferation of weapons of mass destruction and other legislation not regulated by this Code, the control over compliance with which is entrusted to the regulatory authorities, if the taxpayer does not provide explanations and their documentary confirmations upon a mandatory written request from the regulatory authority, which indicates violations by this taxpayer of currency, tax and other legislation not regulated by this Code, the control over compliance with which is entrusted to the regulatory authorities, within 15 business days from the day following the day of receipt of the request;
{Subclause 78.1.1 of Clause 78.1 of Article 78 as amended by Laws No. 657-VII of 10/24/2013 , No. 71-VIII of 12/28/2014 ; as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Laws No. 1797-VIII of 12/21/2016 , No. 1914-IX of 11/30/2021 }
78.1.2. the taxpayer has not submitted a tax return , calculations, or reporting for tax control over transfer pricing within the time period established by law in accordance with Clause 39.4 of Article 39 of this Code, if their submission is provided for by law;
{Subclause 78.1.2 of clause 78.1 of Article 78 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 72-VIII of 28.12.2014 , No. 466-IX of 16.01.2020 }
78.1.3. the taxpayer submitted to the supervisory authority a clarifying calculation of the relevant tax for the period that was audited by the supervisory authority;
78.1.4. the data contained in the tax returns submitted by the taxpayer are found to be inaccurate, if the taxpayer fails to provide explanations and documentary evidence thereof upon a written request from the regulatory authority, which indicates the identified inaccurate data and the relevant declaration, within 15 business days from the day following the date of receipt of the request;
{Subclause 78.1.4 of Clause 78.1 of Article 78 as amended by Laws No. 657-VII of 10/24/2013 , No. 1797-VIII of 12/21/2016 }
78.1.5. the taxpayer has submitted to the supervisory authority, in accordance with the established procedure, an objection to the audit report in accordance with the procedure specified in paragraph 86.7 of Article 86 of this Code, or a complaint against the tax notice-decision adopted based on its results, which requires a full or partial review of the results of the relevant audit or the cancellation of the tax notice-decision adopted based on its results, if the taxpayer in his complaint (objections) refers to circumstances that were not investigated during the audit, and their objective consideration is impossible without conducting an audit. Such an audit is conducted exclusively on issues that have become the subject of an appeal.
{ Paragraph one of subparagraph 78.1.5 of paragraph 78.1 of Article 78 as amended by the Law No. 466-IX dated 16.01.2020 }
An order to conduct an unscheduled documentary inspection on the grounds specified in this subparagraph is issued:
{Subclause 78.1.5 of clause 78.1 of Article 78 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
in the event of consideration of an objection to the inspection report, - by the supervisory authority that conducted the inspection;
{Subclause 78.1.5 of clause 78.1 of Article 78 is supplemented by the third paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; with amendments made in accordance with the Law No. 466-IX dated 16.01.2020 }
during the administrative appeal procedure - by a higher-level supervisory body that considers the taxpayer's complaint;
{Subclause 78.1.5 of clause 78.1 of Article 78 is supplemented by the fourth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
On the basis of the order specified in this paragraph, the supervisory authority entrusted with the inspection shall additionally issue an order in accordance with the procedure provided for in paragraph 81.1 of Article 81 of this Code.
{Subparagraph 78.1.5 of paragraph 78.1 of Article 78 is supplemented by the fifth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Subclause 78.1.5 of Clause 78.1 of Article 78 as amended by Law No. 1797-VIII of 21.12.2016 }
78.1.6. excluded;
78.1.7. the procedure for reorganization of a legal entity (except for transformation), termination of a legal entity or entrepreneurial activity of a natural person - entrepreneur, closure of a permanent representative office or separate subdivision of a legal entity, including a foreign company, organization, proceedings have been initiated in a case to declare a taxpayer bankrupt or an application has been filed for removal from the taxpayer's register;
{Subclause 78.1.7 of Clause 78.1 of Article 78 as amended by Law No. 657-VII of 24.10.2013 }
78.1.8. the payer has submitted a declaration in which he/she has applied for reimbursement of value added tax from the budget, if there are grounds for verification specified in Section V of this Code, and/or with a negative value of value added tax exceeding 100 thousand hryvnias.
Documentary unscheduled inspection on the grounds specified in this subparagraph is carried out exclusively with regard to the legality of declaring the value added tax claimed for reimbursement from the budget and/or the negative value of value added tax, which is more than 100 thousand hryvnias;
{Paragraph two of subparagraph 78.1.8 of paragraph 78.1 of Article 78 as amended by Law No. 4834-VI of 24.05.2012 }
78.1.9. a complaint has been filed against the taxpayer:
on the failure of such taxpayer to provide a tax invoice to the buyer or on the seller of goods/services making errors when indicating the mandatory details of the tax invoice, provided for in paragraph 201.1 of Article 201 of this Code, and/or violation by the seller/buyer of the deadlines for registering the tax invoice in the Unified Register of Tax Invoices and/or calculating the adjustment in the event of failure to provide such taxpayer within 15 business days from the day following the day of receipt of a written request from the regulatory authority, which indicates information from the complaint, explanations and documentary confirmation of this request;
{Paragraph two of subparagraph 78.1.9 of paragraph 78.1 of Article 78 as amended by Law No. 1797-VIII of 21.12.2016 }
or
on the failure of such taxpayer to provide an excise invoice to the buyer or on the violation of the procedure for filling out and/or registration of an excise invoice in the event of failure to provide such taxpayer with such invoice within 15 business days from the day following the day of receipt of a written request from the regulatory authority, which indicates information from the complaint, explanations and documentary confirmation of this request;
{Subclause 78.1.9 of Clause 78.1 of Article 78 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 1797-VIII of 12/21/2016 }
78.1.10. excluded;
{Subclause 78.1.11 of clause 78.1 of Article 78 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
78.1.12. a higher-level supervisory authority, in the course of monitoring the actions or inaction of officials of a lower-level supervisory authority, has inspected the taxpayer's mandatory reporting documents or the materials of a documentary audit conducted by a lower-level supervisory authority, and has revealed that the conclusions of the audit report do not comply with the requirements of the legislation or that issues that should be clarified during the audit were not fully clarified during the audit in order to draw an objective conclusion on the taxpayer's compliance with the requirements of the legislation, the control over which is entrusted to the supervisory authorities.
An order to conduct an unscheduled documentary audit in this case is accepted by a higher-level supervisory authority only if disciplinary proceedings have been initiated against officials of a lower-level supervisory authority who conducted a documentary audit of the specified taxpayer or if they have been notified of suspicion of committing a criminal offense;
{Paragraph two of subparagraph 78.1.12 of paragraph 78.1 of Article 78 as amended by Laws No. 4652-VI of 04/13/2012 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
On the basis of such an order, the supervisory authority entrusted with the inspection shall additionally issue an order in accordance with the procedure provided for in paragraph 81.1 of Article 81 of this Code.
{Subparagraph 78.1.12 of paragraph 78.1 of Article 78 is supplemented by the third paragraph in accordance with Law No. 466-IX of January 16, 2020 }
78.1.13. in case of receiving information about evasion by a tax agent of taxation of wages paid (accrued) to employees (including without documentary evidence), passive income, additional benefits, other payments and compensations subject to taxation, including as a result of the taxpayer's failure to conclude employment contracts with employees in accordance with the law, as well as the person's conduct of economic activity without state registration. Such an inspection is carried out exclusively on issues that became the basis for such an inspection;
78.1.14. in the event of receipt of documented information and data indicating non-compliance of the conditions of the controlled transaction with the arm's length principle and/or establishment of non-compliance of the conditions of the controlled transaction with the arm's length principle in accordance with the procedure provided for in subparagraph 39.5.1.1 of subparagraph 39.5.1 of paragraph 39.5 of Article 39 of this Code;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.14 in accordance with Law No. 408-VII of 04.07.2013 ; as amended by Law No. 72-VIII of 28.12.2014 }
78.1.15. failure by the taxpayer to submit or submission in violation of the requirements of paragraph 39.4 of Article 39 of this Code of a report on controlled transactions, a notification of participation in an international group of companies, a report by country of an international group of companies, global documentation (master file) and/or transfer pricing documentation;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.15 in accordance with Law No. 408-VII of 04.07.2013 ; as amended by Laws No. 72-VIII of 28.12.2014 , No. 2970-IX of 20.03.2023 }
78.1.16. a report on controlled transactions submitted by the taxpayer in accordance with clause 39.4 of Article 39 of this Code has been received. In such a case, the inspection shall be conducted exclusively on transfer pricing control issues;
{Sub-paragraph of paragraph 78.1 of Article 78 as amended by Law No. 72-VIII of 28.12.2014 }
78.1.17. the taxpayer has not submitted a clarifying calculation within the period established by clause 50.3 of Article 50 of this Code to correct errors identified based on the results of an electronic check conducted at the taxpayer's request;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.17 in accordance with Law No. 71-VIII of 28.12.2014 }
78.1.18. discrepancies were found between the data contained in the registered excise invoices/adjustment calculations in the Unified Register of Excise Invoices and excise tax declarations submitted by the excise tax payer selling fuel or ethyl alcohol;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.18 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 2628-VIII of 23.11.2018 }
78.1.19. the taxpayer has not provided the information specified in the request of the regulatory authority for cross-checking within 10 business days from the day following the day of receipt of the request. Such verification is carried out exclusively on the issues specified in the request of the regulatory authority.
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.19 in accordance with Law No. 1797-VIII of 21.12.2016 }
78.1.20. the taxpayer has submitted an application for an inspection of the submitted application for replenishment of the remaining fuel volume in accordance with paragraph 29 of subsection 5 of section XX "Transitional provisions" of this Code.
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.20 in accordance with Law No. 391-IX of 18.12.2019 }
78.1.21. the supervisory authority, after conducting a scheduled documentary inspection or an unscheduled documentary inspection, has received information and/or documents from foreign state authorities that relate to issues that were covered during previous inspections of the taxpayer and indicate a violation by the taxpayer of tax, currency and other legislation, control over which is entrusted to the supervisory authorities. Such an inspection is carried out exclusively on issues that became the basis for conducting such an inspection;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.21 in accordance with Law No. 466-IX of January 16, 2020 }
78.1.22. in case of receipt of information indicating that a non-resident is conducting economic activities through a permanent establishment on the territory of Ukraine, in accordance with the requirements of subparagraph 14.1.193 of paragraph 14.1 of Article 14 of this Code, without being included in tax registration.
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.22 in accordance with Law No. 466-IX of January 16, 2020 }
78.1.23. the financial agent has not submitted an application for registration in the cases and in accordance with the procedure provided for in paragraph 39 - 3 .3 of Article 39 - 3 of this Code, or has not provided a response or provided an incomplete response during the survey of the financial agent by the supervisory authority in accordance with paragraph 39 - 3 .8 of Article 39 - 3 of this Code, or has revealed a violation or possible violation by the financial agent of the requirements of Article 39 - 3 of this Code;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.23 in accordance with Law No. 2970-IX of 20.03.2023 }
78.1.24. failure by a financial agent to submit a report on accountable accounts, failure to submit or submit a corrected report on accountable accounts in violation of the deadlines specified in clause 39 - 3 .7 of Article 39 - 3 of this Code, or submission by a financial agent of a report on accountable accounts with information on undocumented accounts in accordance with the Common Reporting Standard CRS, or failure by a financial agent to respond to a request from a regulatory authority regarding undocumented accounts, failure by a depository institution to provide a notification about depositors - investors of collective investment institutions, provision of incomplete information in the notification, or failure by a depository institution to respond to a request from a regulatory authority in cases specified in clause 39 - 3 .11 of Article 39 - 3 of this Code;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.24 in accordance with Law No. 2970-IX of 20.03.2023 }
78.1.25. incompleteness or unreliability of the data contained in the report on accountable accounts submitted by the financial agent has been discovered, including as a result of a notification received from the competent authority of a foreign jurisdiction with which Ukraine has concluded an international agreement containing provisions on the exchange of information for tax purposes, on the detection by such authority of an error, incomplete or unreliable data provided by the financial agent regarding the accountable account of a person who is a resident of the relevant foreign jurisdiction, or on the failure or violation by the financial agent of the obligations provided for by such international agreement, including on the participation of the financial agent or its client in transactions or operations provided for in paragraph 39 - 3.6 of Article 39 - 3 of this Code;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.25 in accordance with Law No. 2970-IX of 20.03.2023 }
, within the established time limit , an explanation, documents or other information in response to a written request from the regulatory authority sent in accordance with clause 44-1.3 of Article 44-1 , subparagraph 8 of subparagraph 73.3.1 of clause 73.3 of Article 73 of this Code ;
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.26 in accordance with Law No. 2970-IX of 20.03.2023 }
78.1.27. a possible violation of the requirements of Article 39 - 3 of this Code by the account holder or its controlling person has been identified.
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.27 in accordance with Law No. 2970-IX of 20.03.2023 }
78.1.28. in relation to the taxpayer or any other persons who acted on behalf of and/or in the interests of the taxpayer, a court verdict of conviction for committing a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine has entered into legal force, and the consequence of such actions could be a reduction in the object of taxation and/or an underestimation of the tax liability determined in accordance with the requirements of this Code.
A documentary unscheduled audit on the grounds specified in this subparagraph shall be conducted without observing the limitation period specified in paragraphs one and two of paragraph 102.1 of Article 102 of this Code, and regardless of whether documentary audits of such a taxpayer were conducted for the relevant tax, in respect of which a reduction in the object of taxation and/or an underestimation of the tax liability could have been allowed, for all tax (reporting) periods in which the taxpayer's transactions, which can be identified on the basis of a court's conviction as having been carried out with the aim of providing an unlawful benefit to an official (including an official of a foreign state), affected the taxpayer's tax reporting indicators.
{Clause 78.1 of Article 78 is supplemented by subparagraph 78.1.28 in accordance with Law No. 4112-IX of 04.12.2024 }
78.2. Restrictions on the grounds for conducting audits of taxpayers, defined by this Code, do not apply to audits conducted at the request of such a taxpayer.
{Paragraph one of clause 78.2 of Article 78 as amended by the Law No. 466-IX dated 16.01.2020 }
Controlling bodies are prohibited from conducting unscheduled documentary inspections, which are provided for in subparagraphs 78.1.1 , 78.1.4 , 78.1.8 of paragraph 78.1 of Article 78 of this Code, if the issues that are the subject of such an inspection were covered during previous inspections of the taxpayer.
{Clause 78.2 of Article 78 supplemented by the second paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Law No. 1797-VIII of 21.12.2016 }
{Clause 78.2 of Article 78 as amended by Law No. 4652-VI of 13.04.2012 }
78.3. Law enforcement officers are prohibited from participating in scheduled and unscheduled on-site inspections of taxpayers conducted by regulatory authorities, unless such inspections are related to the conduct of operational-search cases or the conduct of criminal proceedings against such taxpayers (taxpayer officials) that are under their jurisdiction. Inspections of taxpayers by law enforcement authorities are conducted within the limits of their powers, as determined by law, and in accordance with the procedure provided for by the Law of Ukraine "On Operational-Search Activities" , the Criminal Procedure Code of Ukraine and other laws of Ukraine.
{Clause 78.3 of Article 78 as amended by Law No. 4652-VI of 13.04.2012 ; as amended by the Law No. 1797-VIII dated 21.12.2016 - applicable from September 25, 2021 }
78.4. The head (his deputy or authorized person) of the regulatory body shall make a decision to conduct an unscheduled documentary inspection, which shall be formalized by an order.
{Paragraph one of clause 78.4 of Article 78 as amended by Law No. 1797-VIII of 21.12.2016 }
The right to conduct an unscheduled documentary audit of a taxpayer (except for audits provided for in subparagraph 78.1.22 of paragraph 78.1 of this Article) is granted only if, prior to the commencement of the said audit, he is served with a copy of the order to conduct an unscheduled documentary audit in accordance with the procedure specified in Article 42 of this Code.
{Paragraph two of clause 78.4 of Article 78 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 , taking into account the amendments made by Law No. 1117-IX of 12/17/2020 }
78.5. Admission of officials of controlling bodies to conduct an unscheduled documentary on-site inspection shall be carried out in accordance with Article 81 of this Code. An unscheduled documentary on-site inspection shall be carried out in accordance with the procedure provided for in Article 79 of this Code.
78.6. The deadlines for conducting an unscheduled documentary inspection are established by Article 82 of this Code.
78.7. The list of materials that may be the basis for conclusions during an unscheduled documentary audit, and the procedure for taxpayers to provide documents for such an audit are established by Articles 83 and 85 of this Code.
78.8. The procedure for recording the results of a documentary unscheduled inspection is established by Article 86 of this Code.
78.9. Verification of a taxpayer regarding the completeness of the accrual and payment of taxes and fees during the implementation of controlled transactions is carried out taking into account the features specified in Article 39 of this Code.
{Article 78 is supplemented by paragraph 78.9 in accordance with Law No. 72-VIII of 28.12.2014 }
78.10. An unscheduled inspection of persons, appointed on the grounds specified in subparagraphs 78.1.23-78.1.25 of paragraph 78.1 of this Article, may be conducted on all issues related to the fulfillment of the requirements of Article 39 - 3 of this Code, and is not limited to the issues that served as the basis for appointing the inspection.
During an unscheduled inspection, the regulatory authority has the right to request from persons subject to the requirements of Article 39-3 of this Code all documents and information provided for in paragraph 39-3.5 of Article 39-3 of this Code, including, but not limited to , documents and information necessary for the inspection:
the completeness and accuracy of the information provided by the financial agent in the report on accountable accounts;
the existence and sufficiency of reasons for not including certain information in the report on accountable accounts;
's fulfillment and actual performance of all obligations stipulated in Article 39-3 of this Code.
{Article 78 is supplemented by paragraph 78.10 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 79. Peculiarities of conducting a documentary on-site inspection↑
79.1. A documentary non-visit inspection shall be carried out if the head (his deputy or an authorized person) of the supervisory authority decides to conduct it and if there are grounds for conducting a documentary inspection specified in Articles 77 and 78 of this Code. A documentary non-visit inspection shall be carried out on the basis of the documents and data specified in subparagraph 75.1.2 of paragraph 75.1 of Article 75 of this Code, provided by the taxpayer in the cases specified in this Code, or obtained in another manner provided for by law.
{Clause 79.1 of Article 79 as amended by Law No. 1797-VIII of 21.12.2016 }
79.2. An unscheduled documentary on-site inspection shall be conducted by officials of the controlling body solely on the basis of a decision of the head (his deputy or authorized person) of the controlling body, formalized by an order, and provided that the taxpayer (his representative) is served, in accordance with the procedure specified in Article 42 of this Code, with a copy of the order to conduct an unscheduled documentary on-site inspection and a written notification of the start date and place of such inspection.
{Paragraph one of clause 79.2 of Article 79 as amended by Law No. 1797-VIII of 21.12.2016 }
In the event of sending (delivering) to the taxpayer (his representative) a copy of the order to conduct an unscheduled documentary on-site inspection and a written notification of the start date and place of the unscheduled on-site inspection, by sending it to the address (location, tax address) of the taxpayer by registered letter with a notification of delivery, the unscheduled on-site inspection (except for the inspection specified in Article 200 of this Code) shall begin no earlier than 30 calendar days from the date of sending such notification and a copy of the order.
{Clause 79.2 of Article 79 is supplemented with a new paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
Fulfillment of the conditions of this article gives officials of the supervisory authority the right to begin conducting a documentary on-site inspection.
{Clause 79.2 of Article 79 is supplemented by a paragraph in accordance with Law No. 4834-VI of 24.05.2012 }
79.3. The presence of taxpayers during documentary off-site inspections is not mandatory.
{Clause 79.4 of Article 79 was excluded on the basis of Law No. 72-VIII of 28.12.2014 }
79.5. If there is a written request from the taxpayer, a documentary on-site inspection may be conducted instead of a documentary off-site inspection.
{Article 79 is supplemented by paragraph 79.5 in accordance with Law No. 655-VIII of 17.07.2015 }
Article 80. Procedure for conducting a factual inspection↑
80.1. The actual inspection is carried out without warning the taxpayer (person).
80.2. An actual inspection may be conducted on the basis of a decision of the head (his deputy or authorized person) of the supervisory authority, issued by an order, a copy of which is handed over to the taxpayer or his authorized representative, or to persons who actually carry out settlement transactions against receipt prior to the start of such an inspection, and if at least one of the following grounds exists:
{Paragraph one of clause 80.2 of Article 80 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1797-VIII of 12/21/2016 }
80.2.1. in the event that, based on the results of inspections of other taxpayers, facts are revealed that indicate possible violations by the taxpayer of legislation regarding the production and circulation of excisable goods, the taxpayer's performance of settlement transactions, cash transactions, the availability of patents, licenses and other documents, control over the availability of which is entrusted to the regulatory authorities, and there is a need to verify such facts;
{Subclause 80.2.1 of clause 80.2 of Article 80 as amended by Laws No. 3205-VI of 07.04.2011 , No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 }
80.2.2. in the event of the availability and/or receipt in accordance with the procedure established by law of information from state bodies or local self-government bodies indicating possible violations by the taxpayer of the legislation, control over which is entrusted to the regulatory authorities, in particular, regarding the implementation of settlement transactions by taxpayers, including ensuring the possibility of making payments for goods (services) using electronic payment instruments, conducting cash transactions, the availability of patents, licenses and other documents, control over the availability of which is entrusted to the regulatory authorities, production and circulation of excisable goods;
{Subclause 80.2.2 of Clause 80.2 of Article 80 as amended by Laws No. 3205-VI of 07.04.2011 , No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 , No. 2120-IX of 15.03.2022 }
80.2.3. a written application from a buyer (consumer), drawn up in accordance with the law, about the taxpayer's violation of the established procedure for conducting settlement transactions, including failure to ensure the possibility of making payments for goods (services) using electronic payment methods, cash transactions, patenting or licensing;
{ Subparagraph 80.2.3 of paragraph 80.2 of Article 80 as amended by Law No. 2120-IX of March 15, 2022 }
80.2.4. failure by a business entity to submit mandatory reporting on the use of settlement transaction registrars and/or software settlement transaction registrars, settlement books and settlement transaction accounting books within the time period established by law, submission of such reports with zero indicators;
{Subclause 80.2.4 of Clause 80.2 of Article 80 as amended by Law No. 129-IX of 20.09.2019 }
80.2.5. in the event of the presence and/or receipt in accordance with the procedure established by law of information on violations of the requirements of the law in terms of the production, accounting, storage and transportation of alcohol, alcoholic beverages, tobacco products and liquids used in electronic cigarettes and fuel, and the intended use of alcohol by taxpayers, the equipment of excise warehouses with flow meters and/or uniform meters and/or mass flow meters, as well as the performance of functions defined by law in the field of regulation of the production and circulation of alcohol, alcoholic beverages, tobacco products, liquids used in electronic cigarettes, fuel;
{Subclause 80.2.5 of Clause 80.2 of Article 80 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Laws No. 1914-IX of 30.11.2021 , No. 2284-IX of 31.05.2022 }
80.2.6. in the event of a violation of the legislation on the issues specified in clause 75.1.3 being detected as a result of the preliminary inspection ;
80.2.7. in the event of the availability and/or receipt in accordance with the procedure established by law of information about the use of labor of employees without proper registration of employment relations and payment by employers of income in the form of wages without paying taxes to the budget, as well as the implementation of entrepreneurial activity by an individual without state registration.
{Subclause 80.2.7 of Clause 80.2 of Article 80 as amended by Law No. 1797-VIII of 21.12.2016 }
80.3. An actual inspection, carried out if there is a reason specified in clause 80.2.6, may be conducted to control the cessation of violations of the legislation on the issues specified in clause 75.1.3 , once within 12 months from the date of drawing up the act based on the results of the preliminary inspection.
{Clause 80.3 of Article 80 as amended by the Law No. 466-IX dated 16.01.2020 }
80.4. Before the start of the actual inspection, on issues of compliance with the procedure for performing settlement operations and conducting cash transactions, officials of the controlling bodies may conduct a control settlement operation on the basis of subparagraph 20.1.10 of paragraph 20.1 of Article 20 of this Code.
{Clause 80.4 of Article 80 as amended by Law No. 2245-VIII of 07.12.2017 }
80.5. Admission of officials of controlling bodies to conduct an actual inspection is carried out in accordance with Article 81 of this Code.
80.6. During the actual inspection of the employer's compliance with the legislation on the conclusion of an employment contract, registration of employment relations with employees (employees), including those on probation, the presence of proper registration of employment relations is checked, issues regarding keeping records of work performed by the employee, accounting for labor costs, information on the employee's remuneration are clarified. To clarify the fact of proper registration of employment relations with an employee who performs labor activities, identity documents or other documents that allow for their identification (official ID, driver's license, health book, etc.) may be used.
80.7. The actual inspection is carried out by two or more officials of the supervisory authority in the presence of officials of the business entity or its representative and/or the person actually carrying out settlement operations.
80.8. During the inspection, the officials conducting such an inspection may record the timing of business transactions. Based on the results of the timekeeping, a certificate shall be drawn up, which shall be signed by the officials of the controlling body and the officials of the business entity or its representative and/or by the persons actually carrying out the business transactions.
80.9. The terms for conducting an actual inspection are established by Article 82 of this Code.
80.10. The procedure for recording the results of the actual inspection is established by Article 86 of this Code.
Article 81. Conditions and procedure for admission of officials of controlling bodies to conduct documentary on-site and actual inspections↑
81.1. Officials of the regulatory body have the right to proceed with a documentary on-site inspection, an actual inspection if there are grounds for their conduct, specified by this Code, and subject to the presentation or sending, in cases specified by this Code, of the following documents:
{Paragraph one of clause 81.1 of Article 81 as amended by Law No. 3609-VI of 07.07.2011 }
a referral to conduct such an inspection, which indicates the date of issue, the name of the controlling body, the details of the order to conduct the relevant inspection, the name and details of the subject (surname, first name, patronymic of the individual - taxpayer being inspected) or the object being inspected, the purpose, type (documentary, planned/unplanned or actual), grounds, start date and duration of the inspection, position and surname of the official (service) person who will conduct the inspection. In such a case, the referral to the inspection is valid if there is a signature of the head (his deputy or authorized person) of the controlling body, which is sealed with the seal of the controlling body;
{Paragraph two of clause 81.1 of Article 81 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 5519-VI of 06.12.2012 , No. 1797-VIII of 21.12.2016 }
copies of the order to conduct an inspection, which indicates the date of issue, the name of the controlling body, the name and details of the subject (surname, first name, patronymic of the individual - taxpayer being inspected) and, in the case of an inspection conducted in another place - the address of the facility being inspected, the purpose, type (documentary scheduled/unscheduled or actual inspection), the grounds for conducting the inspection, determined by this Code, the date of commencement and duration of the inspection, the period of activity to be inspected. The order to conduct an inspection is valid if it is signed by the head (his deputy or authorized person) of the controlling body and affixed with the seal of the controlling body;
{Paragraph of Clause 81.1 of Article 81 as amended by Laws No. 3609-VI of 07.07.2011 , No. 655-VIII of 17.07.2015 ; as amended by the Law No. 1797-VIII dated 21.12.2016 }
official identification card of the persons (a document duly issued by the relevant supervisory authority certifying the official (official) person) specified in the order for the inspection.
{Paragraph of clause 81.1 of Article 81 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by the Law No. 466-IX dated 16.01.2020 }
Failure to present or send, in cases specified by this Code, these documents to the taxpayer (his officials or his authorized representative, or persons who actually conduct settlement transactions) or presentation of the specified documents that are executed in violation of the requirements established by this paragraph, is grounds for denying officials of the controlling body access to conduct a documentary on-site or actual inspection.
{Paragraph of Clause 81.1 of Article 81 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 4834-VI of 24.05.2012 }
Refusal of a taxpayer and/or officials (service personnel) of the taxpayer (its representatives or persons who actually carry out settlement operations) from admission to an inspection on grounds other than those specified in paragraph five of this clause is not permitted.
{Paragraph six of clause 81.1 of Article 81 as amended by Law No. 3609-VI of 07.07.2011 }
When presenting the referral to the taxpayer and/or officials (service personnel) of the taxpayer (his representatives or persons who actually carry out settlement operations), such persons shall sign the referral, indicating their last name, first name, patronymic, position, date and time of review.
In the event of refusal of the taxpayer and/or officials (officials) of the taxpayer (his representatives or persons who actually carry out settlement operations) to sign the inspection referral, the officials (officials) of the controlling body shall draw up an act certifying the fact of refusal. In such a case, the act of refusal to sign the inspection referral shall be the basis for initiating such an inspection.
81.2. In the event of a refusal of the taxpayer and/or officials (officials) of the taxpayer (his representatives or persons who actually carry out settlement transactions) to allow officials (officials) of the controlling body to conduct an inspection by officials (officials) of the controlling body at the place of inspection, an act certifying the fact of refusal, indicating the stated reasons for the refusal, shall be immediately drawn up and registered with the controlling body in two copies no later than the next working day, one copy of which shall be handed over for signature, immediately after its drawing up, to the taxpayer and/or an authorized person of the taxpayer.
{Paragraph one of clause 81.2 of Article 81 as amended by the Law No. 466-IX dated 16.01.2020 }
An official (service) person of the taxpayer (his representative or the person who actually carries out settlement operations) has the right to provide his written explanations to the act drawn up by the supervisory authority.
In the event of refusal of the taxpayer and/or his officials (representatives or persons who actually carry out settlement operations) to sign an act certifying the fact of refusal of admission to the inspection, and/or in the event of refusal to receive a copy of this act or provide written explanations for it, the officials (officials) of the controlling body shall draw up an act certifying such fact and register it with the controlling body no later than the next business day.
{Paragraph three of clause 81.2 of Article 81 as amended by the Law No. 466-IX dated 16.01.2020 }
If, during the organization of a documentary scheduled and unscheduled on-site or actual inspection, it is established that it is impossible to conduct it, the officials (service personnel) of the controlling body shall immediately draw up and sign an act on the impossibility of conducting the inspection, which shall be registered with the controlling body no later than the next working day. Such act shall be accompanied by materials confirming the facts stated in such act. The said act and materials shall be sent by the controlling body to the taxpayer in accordance with the procedure specified in Article 42 of this Code.
{Clause 81.2 of Article 81 is supplemented by the fourth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
{Clause 81.2 of Article 81 as amended by Law No. 1797-VIII of 21.12.2016 }
81.3. During inspections, officials (service personnel) of civil service bodies must act within the limits of their powers defined by this Code.
Managers and relevant officials of legal entities and individual taxpayers, during an inspection conducted by regulatory authorities, are obliged to comply with the requirements of regulatory authorities to eliminate identified violations of taxation laws and sign an act (certificate) on the inspection and have the right to object to this act (certificate).
When conducting inspections, officials of the controlling body do not have the right to require a taxpayer to obtain an extract from the relevant register on the registration of such taxpayer in accordance with the requirements of this Code.
{Clause 81.3 of Article 81 is supplemented by the third paragraph in accordance with Law No. 657-VII of 24.10.2013 }
Article 82. Time limits for conducting on-site inspections↑
82.1. The duration of inspections specified in Article 77 of this Code shall not exceed 30 working days for large taxpayers, 10 working days for small businesses, and 20 working days for other taxpayers.
The extension of the terms for conducting inspections specified in Article 77 of this Code is possible by decision of the head (his deputy or authorized person) of the supervisory authority for no more than 15 working days for large taxpayers, for small business entities - for no more than 5 working days, and for other taxpayers - for no more than 10 working days.
{Paragraph two of clause 82.1 of Article 82 as amended by Law No. 1797-VIII of 21.12.2016 }
82.2. The duration of inspections specified in Article 78 of this Code shall not exceed 15 working days for large taxpayers, 5 working days for small business entities, 3 working days for individual entrepreneurs who do not have employees, subject to the conditions specified in paragraphs three to eight of this paragraph, and 10 working days for other taxpayers.
{Paragraph one of clause 82.2 of Article 82 as amended by Laws No. 5412-VI of 02.10.2012 , No. 909-VIII of 24.12.2015 }
The extension of the terms for conducting inspections specified in Article 78 of this Code is possible by decision of the head (his deputy or authorized person) of the supervisory authority for no more than 10 working days for large taxpayers, for small business entities - for no more than 2 working days, and for other taxpayers - for no more than 5 working days.
{Paragraph two of clause 82.2 of Article 82 as amended by Law No. 1797-VIII of 21.12.2016 }
An unscheduled documentary inspection on the grounds specified in subparagraph 78.1.7 of paragraph 78.1 of Article 78 of this Code, for individual entrepreneurs who do not have employees, is carried out within the period specified in the first paragraph of this paragraph, provided that the following conditions are simultaneously present for the last two calendar years:
{Clause 82.2 of Article 82 was supplemented with the third paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
the taxpayer has submitted a tax return stating that there is no income from conducting business activities;
{Clause 82.2 of Article 82 is supplemented by the fourth paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
the taxpayer is not registered as a value added tax payer;
{Clause 82.2 of Article 82 is supplemented by the fifth paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
The regulatory authorities lack tax information regarding:
{Clause 82.2 of Article 82 is supplemented by the sixth paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
use by the taxpayer of hired labor of individuals;
{Clause 82.2 of Article 82 was supplemented by the seventh paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
accounts opened by the taxpayer in banks and other financial institutions, non-bank payment service providers/electronic wallets in electronic money issuers.
{Clause 82.2 of Article 82 supplemented by paragraph eight in accordance with Law No. 5412-VI of 02.10.2012 ; as amended in accordance with Law No. 2888-IX of 12.01.2023 }
If, during the audit, the taxpayer provides documents less than three business days before the date of its completion or if the documents sent in accordance with the procedure provided for in paragraph one of paragraph 44.7 of Article 44 of Section I of this Code are received by the supervisory authority less than three business days before the date of completion of the audit, the audit may be additionally extended to the terms established by this paragraph for a period of three business days.
{Clause 82.2 of Article 82 is supplemented by paragraph nine in accordance with the Law No. 466-IX dated 16.01.2020 }
82.3. The duration of inspections specified in Article 80 of this Code shall not exceed 10 days.
The extension of the term of such inspections is carried out by decision of the head (his deputy or authorized person) of the supervisory body for no more than 5 days.
{Paragraph two of clause 82.3 of Article 82 as amended by Law No. 1797-VIII of 21.12.2016 }
The grounds for extending the inspection period are:
82.3.1. a statement from the business entity (if necessary to submit documents related to the inspection);
82.3.2. shift work or summarized accounting of working hours of a business entity and/or its business facilities.
82.4. Conducting a documentary scheduled and unscheduled audit of a taxpayer, except for a taxpayer who is a small business entity, may be suspended by decision of the head (his deputy or authorized person) of the regulatory body, which is drawn up by an order, a copy of which is handed over to the taxpayer or his authorized representative no later than the next business day against receipt or sent to the taxpayer in accordance with the procedure specified in Article 42 of this Code, with subsequent renewal of its conduct for the unused period.
{Paragraph one of clause 82.4 of Article 82 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 1117-IX dated 17.12.2020 }
The suspension of a scheduled or unscheduled documentary audit interrupts the period for conducting the audit if an order to suspend such an audit is served on the taxpayer or his authorized representative in accordance with the procedure specified in paragraph one of this paragraph.
{Paragraph two of clause 82.4 of Article 82 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 466-IX of 01/16/2020 }
In this case, the inspection may be suspended for a total period not exceeding 30 working days, and if it is necessary to conduct an examination, obtain information from foreign state bodies regarding the taxpayer's activities, complete the court's consideration of claims on issues related to the subject of the inspection, or restore lost documents by the taxpayer, the inspection may be suspended for the period necessary to complete such procedures.
The total period for conducting inspections specified in paragraphs 200.10 and 200.11 of Article 200 of this Code, taking into account the suspension periods established by this paragraph, may not exceed 40 calendar days.
{Paragraph four of clause 82.4 of Article 82 as amended by Law No. 3603-IX of 23.02.2024 }
{Clause 82.4 of Article 82 as amended by Law No. 1797-VIII of 21.12.2016 }
82.5. In the event of violation by officials (officials) of the regulatory body of the term specified in the second paragraph of paragraph 85.4 of Article 85 of this Code, upon the taxpayer's application, the conduct of a documentary on-site scheduled and unscheduled inspection shall be suspended for a period of not less than five working days.
{Article 82 is supplemented by paragraph 82.5 in accordance with the Law No. 466-IX dated 16.01.2020 }
Article 83. Materials that are the basis for conclusions during inspections↑
83.1. For officials of regulatory bodies during inspections, the grounds for conclusions are:
83.1.1. documents defined by this Code;
83.1.2. tax information;
83.1.3. expert opinions provided in accordance with Article 84 of this Code and other laws of Ukraine;
{Sub-clause 83.1.3 of clause 83.1 of Article 83 as amended by the Law No. 466-IX dated 16.01.2020 }
83.1.4. court decisions;
83.1.5. excluded;
83.1.6. tax consultations, other materials received in the manner and in the manner provided for by this Code or other laws, the control over compliance with which is entrusted to the regulatory authorities;
83.1.7. multimedia information (photo, video, sound recording) received (produced) by regulatory authorities.
{Clause 83.1 of Article 83 is supplemented by subparagraph 83.1.7 in accordance with Law No. 1914-IX of 30.11.2021 }
{Subclause 83.1.6 of Clause 83.1 of Article 83 as amended by Law No. 1797-VIII of 21.12.2016 }
Article 84. Conducting an examination during tax control by controlling bodies↑
84.1. An expert examination shall be conducted in cases where special knowledge in the field of science, art, technology, economics and other fields is required to resolve issues of importance for tax control. The engagement of an expert shall be carried out on a contractual basis and at the expense of the party initiating the engagement of the expert.
84.2. An examination is appointed upon the taxpayer's application or upon the decision of the head (his deputy or authorized person) of the supervisory authority, which shall specify:
{Clause 84.2 of Article 84 as amended by Law No. 1797-VIII of 21.12.2016 }
84.2.1. grounds for engaging an expert;
84.2.2. surname, first name and patronymic of the expert;
84.2.3. details of the taxpayer subject to tax control;
84.2.4. questions posed to the expert;
84.2.5. documents, objects and other materials submitted for review by the expert.
84.3. The controlling body, the head (his deputy or authorized person) of which controlling body has assigned the examination, is obliged to familiarize the taxpayer (his representative) with the decision to conduct the examination, and after the examination is completed - with the expert's conclusion.
{Clause 84.3 of Article 84 as amended by Law No. 1797-VIII of 21.12.2016 }
84.4. excluded.
84.5. The expert has the right to familiarize himself with the materials submitted to him that relate to the subject of the examination and to request the provision of additional materials.
An expert has the right to refuse to provide an opinion if the submitted materials are insufficient or such expert does not possess the necessary knowledge to conduct the specified examination.
84.6. An expert shall be liable in accordance with the law for providing a knowingly false opinion.
85.1. It is prohibited to request documents from a taxpayer by any officials (service personnel) of controlling bodies in cases not provided for by this Code.
85.2. The taxpayer is obliged to provide the officials (officials) of the controlling bodies with all documents belonging to or related to the subject of the inspection. Such obligation arises for the taxpayer after the start of the inspection.
At the same time, a large taxpayer, at the request of the regulatory authority, is also obliged to provide officials (service personnel) of regulatory authorities by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" with copies of such documents created by it in electronic form for accounting of income, expenses and other indicators related to the determination of objects of taxation (tax liabilities), primary documents, accounting registers, financial statements, other documents related to the calculation and payment of taxes and fees, no later than two business days following the date of receipt of the request.
{Paragraph two of clause 85.2 of Article 85 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Laws No. 2725-VIII of 05/16/2019 , No. 466-IX of 01/16/2020 }
For taxpayers who are required to provide information in electronic form in accordance with this paragraph, the general format and procedure for submitting such information shall be determined by the central executive body responsible for the formation and implementation of state financial policy. If an electronic format and procedure for providing such information are not established, the taxpayer shall be exempted from the obligation to submit it in electronic form.
{Clause 85.2 of Article 85 as amended by Law No. 3609-VI of 07.07.2011 - shall enter into force on January 1, 2012 in terms of the procedure for providing information in electronic form; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 }
To conduct an electronic audit, the taxpayer shall ensure the submission to the regulatory authority by electronic means in electronic form in compliance with the requirements of the Laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" of documents that, in accordance with this Code, are related to the calculation and payment of taxes and fees (if such documents are created by such taxpayer in electronic form and stored on machine data carriers). The general format and procedure for submitting such information shall be established by the central executive authority that ensures the formation and implementation of state financial policy.
{Clause 85.2 of Article 85 is supplemented by the fourth paragraph in accordance with Law No. 5503-VI of 20.11.2012 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2725-VIII of 16.05.2019 , No. 466-IX of 16.01.2020 }
85.3. Documents containing commercial secrets or being confidential shall be transferred separately, indicating the official (service) person who received them. The transfer of such documents for their review, study and their return shall be formalized by an act in any form, signed by the official (service) person of the controlling body and the taxpayer (his representative).
85.4. When conducting inspections, officials (service personnel) of the controlling body have the right to receive from taxpayers duly certified copies of primary financial, economic, accounting and other documents that indicate concealment (understatement) of objects of taxation, non-payment of taxes, fees, payments, violation of the requirements of other legislation, control over compliance with which is entrusted to the controlling bodies. Such copies must be certified by the signature of the taxpayer or his official and sealed (if any).
The corresponding request for copies of documents must be submitted by an official (service person) of the regulatory body no later than five working days before the end date of the inspection.
{Clause 85.4 of Article 85 is supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Clause 85.4 of Article 85 as amended by Laws No. 657-VII of 10/24/2013 , No. 1797-VIII of 12/21/2016 }
85.5. It is prohibited to seize originals of primary, financial, economic, accounting and other documents, except in cases provided for by criminal procedural legislation.
{Clause 85.5 of Article 85 as amended by Laws No. 4652-VI of 13.04.2012 , No. 657-VII of 24.10.2013 }
85.6. In case of refusal of the taxpayer or his legal representatives to provide copies of documents to the official (service) person of the controlling body, such person shall draw up an act in any form certifying the fact of refusal, indicating the position, surname, first name, patronymic of the taxpayer (his legal representative) and the list of documents that he is asked to submit. The said act shall be signed by the official (service) person of the controlling body and the taxpayer or his legal representative. In case of refusal of the taxpayer or his legal representative to sign the said act, a corresponding entry shall be made in it.
85.7. The receipt of copies of documents shall be formalized by a description. A copy of the description drawn up by officials (service personnel) of the controlling body shall be handed over to the taxpayer or his legal representative for signature. If the taxpayer or his legal representative refuses to certify the description or to sign for receipt of a copy of the description, the officials (service personnel) of the controlling body who receive the copies shall make a note of the refusal to sign.
85.8. An official (service) person of the controlling body conducting an inspection, in cases provided for by this Code, has the right to receive from the taxpayer or his legal representatives copies of documents related to the subject of the inspection. Such copies must be certified by the signature of the taxpayer or his official and sealed (if any).
85.9. In the event that, prior to or during the inspection, the originals of primary documents, accounting and other registers, financial and statistical reporting, other documents on the calculation and payment of taxes and fees, as well as the fulfillment of the requirements of other legislation, the control over compliance with which is entrusted to the regulatory authorities, were seized by law enforcement and other bodies, the said bodies are obliged to provide the regulatory authority with copies of the said documents for the inspection or to provide access to inspect such documents.
Such copies, certified by the seal and signatures of officials (service personnel) of law enforcement and other bodies who seized the original documents or who were provided with access to inspect the seized documents, must be provided within three business days from the date of receipt of a written request from the supervisory authority.
If the documents specified in the first paragraph of this paragraph have been seized by law enforcement and other authorities, the deadlines for conducting such an inspection, including the one that has already been initiated, shall be postponed until the date of receipt of the specified copies of the documents or provision of access to them.
86.1. The results of inspections (except for desk and electronic inspections) are drawn up in the form of an act or certificate, which are signed by officials of the controlling body and taxpayers or their legal representatives (if any). If violations are established during the inspection, an act is drawn up. If there are no such violations, a certificate is drawn up.
The act (certificate) drawn up based on the results of the inspection and signed by the officials who conducted the inspection or by persons authorized to do so in accordance with the established procedure, within the time limits specified by this Code, shall be provided to the taxpayer or his legal representative, who is obliged to sign it.
Inspection report - a document drawn up in the cases provided for by this Code, confirming the fact of conducting an inspection and reflecting its results.
The inspection report cannot be considered a statement or notification of the commission of a criminal offense related to tax evasion.
Inspection certificate - a document drawn up in cases provided for by this Code, confirming the fact of conducting an inspection and reflecting its results, and is a carrier of evidentiary information about the failure to establish facts of violations of the requirements of tax, currency and other legislation, the control over compliance with which is entrusted to regulatory authorities.
The period for drawing up a report (certificate) on the results of the inspection shall not be included in the period for conducting the inspection established by this Code (taking into account its extension).
In the event of a taxpayer's disagreement with the conclusions of the act (certificate), such taxpayer is obliged to sign such act (certificate) of inspection with objections, which he has the right to submit together with a signed copy of the act (certificate) or separately within the terms provided for by this Code.
The inspection materials are:
inspection report (certificate) with informative annexes that are an integral part of it;
objections submitted by the taxpayer to the audit report (certificate) (if any at the time of consideration);
explanations and their documentary confirmation provided by the taxpayer in accordance with subparagraph 16.1.15 of paragraph 16.1 of Article 16 and in accordance with the second paragraph of subparagraph 17.1.6 of paragraph 17.1 of Article 17 of Section I of this Code.
The procedure for registering the results of inspections conducted by the supervisory authorities specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code, and for submitting objections to them, is determined by the Customs Code of Ukraine .
{Clause 86.1 of Article 86 as amended by Laws No. 5503-VI of 11/20/2012 , No. 655-VIII of 07/17/2015 ; as amended by Law No. 466-IX of 01/16/2020 }
86.2. Based on the results of a desk audit, if violations are identified, an act is drawn up in two copies, which is signed by the officials of such body who conducted the audit, and after registration with the supervisory body, it is handed over or sent for signing within three business days to the taxpayer in accordance with the procedure specified in Article 42 of this Code.
86.3. The act (certificate) of the documentary on-site inspection, as defined in Articles 77 and 78 of this Code, shall be drawn up in two copies, signed by the officials of the supervisory authority who conducted the inspection, and registered with the supervisory authority within five working days from the day following the day of the expiration of the period established for conducting the inspection (for taxpayers who have branches and/or are on consolidated payment, within 10 working days).
In the event of the taxpayer or his legal representatives refusing to sign the act (certificate), the officials of the control body shall draw up a corresponding act certifying the fact of such refusal. One copy of the act or certificate on the results of the on-site scheduled or unscheduled documentary inspection on the day of its signing or refusal to sign shall be handed over or sent to the taxpayer or his legal representative in accordance with the procedure specified in Article 42 of this Code.
{Paragraph two of clause 86.3 of Article 86 as amended by Law No. 466-IX of 16.01.2020 }
The refusal of the taxpayer or his legal representatives to sign the inspection report or receive a copy thereof does not exempt the taxpayer from the obligation to pay the monetary obligations determined by the supervisory authority based on the results of the inspection.
In the event of the taxpayer or his legal representatives refusing to receive a copy of the act or certificate on the results of the inspection or the impossibility of its delivery and signing due to the absence of the taxpayer or his legal representatives at the location, such act or certificate shall be sent to the taxpayer in accordance with the procedure specified in Article 42 of this Code. In the cases specified in this paragraph, the controlling body shall draw up a corresponding act.
{Paragraph four of clause 86.3 of Article 86 as amended by Law No. 466-IX of 16.01.2020 }
86.4. The act (certificate) of a documentary on-site inspection shall be drawn up in two copies, signed by the officials of the supervisory authority who conducted the inspection, and registered with the supervisory authority within five working days from the day following the expiry of the period established for the inspection (for taxpayers who have branches and/or are on consolidated payment, within 10 working days).
The act (certificate) of a documentary on-site inspection shall be personally handed over to the taxpayer or his representatives no later than the next business day after its registration or shall be sent in accordance with the procedure specified in Article 42 of this Code. In the event of the taxpayer or his representatives refusing to sign the act (certificate) of inspection, officials of the controlling body shall draw up a corresponding act certifying the fact of such refusal. The refusal of the taxpayer or his representatives to sign the act of inspection shall not release such taxpayer from the obligation to pay the monetary obligations determined by the controlling body based on the results of the inspection. Objections to the act of inspection shall be considered in accordance with the procedure and within the time limits specified in Clause 86.7 of this Article. The tax notice-decision shall be adopted in accordance with the procedure and within the time limits specified in Clause 86.8 of this Article.
{Paragraph two of clause 86.4 of Article 86 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1797-VIII of 12/21/2016 }
86.5. The act (certificate) on the results of actual inspections specified in Article 80 of this Code shall be drawn up in two copies, signed by the officials of the supervisory authorities who conducted the inspection, and registered no later than the next business day after the end of the inspection. The act (certificate) on the results of the specified inspections shall be signed by the person who carried out the settlement operations, the taxpayer and his legal representatives (if any).
{Paragraph two of clause 86.5 of Article 86 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
The signing of the act (certificate) of such inspections by the person who carried out the settlement operations, the taxpayer and/or his representatives and officials of the supervisory authority who conducted the inspection is carried out at the place of inspection or at the premises of the supervisory authority.
{Paragraph three of clause 86.5 of Article 86 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1797-VIII of 12/21/2016 }
In case of refusal of the taxpayer, his legal representatives or the person who carried out the settlement operations to sign the act (certificate), the officials of the controlling body shall draw up an act certifying the fact of such refusal. One copy of the act or certificate on the results of the inspection shall be registered in the register of acts of the controlling body no later than the next working day after its drawing up and shall be handed over or sent to the taxpayer, his legal representative or the person who carried out the settlement operations no later than the next working day after its registration.
In the event of the taxpayer or his legal representatives refusing to receive a copy of the audit report (certificate) or the impossibility of delivering it to the taxpayer or his legal representatives or the person who carried out the settlement operations for any reason, such report or certificate shall be sent to the taxpayer in accordance with the procedure established by Article 58 of this Code for sending (delivering) tax notices-decisions. In the cases specified in this paragraph, the controlling body shall draw up a corresponding report or make a note in the report or certificate about the audit results.
86.6. Refusal of the taxpayer or his legal representatives or the person who carried out the settlement transactions to sign the inspection report or receive a copy thereof does not exempt the taxpayer from the obligation to pay the monetary obligations determined by the supervisory authority based on the results of the inspection.
86.7. In case of disagreement of the taxpayer or his representatives with the conclusions of the audit or the facts and data set out in the audit report (certificate) (except for a documentary unscheduled audit conducted in accordance with the procedure established by subparagraph 78.1.5 of paragraph 78.1 of Article 78 of this Code), they have the right to submit their objections and additional documents and explanations, in particular, but not exclusively, documents confirming the absence of guilt, the presence of mitigating circumstances or circumstances exempting from financial liability in accordance with this Code, to the supervisory authority that conducted the audit of the taxpayer, within 10 business days from the day following the day of receipt of the report (certificate).
Such objections, additional documents and explanations are an integral part of the inspection materials.
86.7.1. The inspection report, objections to the inspection report and/or additional documents and explanations, if submitted by the taxpayer in accordance with the procedure specified in this paragraph (hereinafter referred to as the inspection materials), shall be considered by the commission of such a supervisory authority for consideration of objections and explanations to inspection reports (hereinafter referred to as the commission for consideration of objections), which is a permanent collegial body of the supervisory authority. The composition of the commission and the procedure for its work shall be approved by order of the head of the supervisory authority.
The examination of the inspection materials shall be carried out by the commission for consideration of objections of the supervisory authority within 10 working days following the date of receipt of objections to the inspection report and/or additional documents and explanations in accordance with this paragraph (the date of completion of the inspection conducted in connection with the need to clarify circumstances that were not investigated during the inspection and specified in the objections, additional documents and explanations), and a response shall be sent to the taxpayer in accordance with the procedure specified in Article 42 of this Code.
86.7.2. In the event of receiving from the taxpayer, in accordance with the procedure specified in this paragraph, objections to the audit report and/or additional documents and explanations, the supervisory authority shall be obliged to notify the taxpayer of the date, time and place/method of consideration of the audit materials, including in the videoconference mode. Such notification shall be sent to the taxpayer within two working days from the date of receipt of objections and/or additional documents and explanations from him, but no later than four working days before the date of their consideration. Information (notification) on the consideration by the supervisory authority, specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, of the audit materials in the videoconference mode shall be sent to the taxpayer in electronic form in the electronic office.
{Sub-clause 86.7.2 of clause 86.7 of Article 86 as amended by the Law No. 3603-IX dated 23.02.2024 }
86.7.3. The taxpayer has the right to participate in the consideration of the audit materials in person or through his representative, including in the video conference mode, as noted in the submitted objections. Directly during the consideration of the audit materials, the taxpayer has the right to provide written (except for cases of consideration of the audit materials in the video conference mode) and/or oral explanations regarding the subject of consideration.
{Paragraph one of subparagraph 86.7.3 of paragraph 86.7 of Article 86 as amended by the Law No. 3603-IX dated 23.02.2024 }
The absence of the taxpayer or his representative, notified in the manner provided for by this Article of the time and place of consideration of the inspection materials, shall not be an obstacle to the consideration of the inspection materials.
86.7.4. During the review of the inspection materials, the objection review commission:
establishes whether the taxpayer, in respect of whom an inspection report was drawn up, has committed a violation of tax, currency and/or other legislation, the control over compliance with which is entrusted to the regulatory authorities;
considers the circumstances of the committed offenses, which are reflected in the inspection report, as well as established during the consideration of the written explanations provided by the taxpayer in accordance with this paragraph and their documentary confirmation (in particular, regarding the circumstances relating to the occurrence of the offense and the measures taken by the taxpayer to comply with the rules and regulations of the law, with reference to documents and other factual data confirming the specified circumstances);
investigates the issue of the presence or absence of circumstances that exclude guilt in committing an offense (except for offenses for which liability arises regardless of the presence of guilt), mitigate or exempt from liability;
investigates the issue of the need to conduct an inspection in accordance with the procedure established by subparagraph 78.1.5 of paragraph 78.1 of Article 78 of this Code;
determines the amount of monetary obligations and/or the amount of budget compensation reduction and/or reduction of the negative value of the object of taxation by income tax or the negative value of the amount of value added tax, and/or the amount of reduction of personal income tax declared before the refund from the budget, in particular when exercising the right to a tax discount, and/or understatement or overstatement of the amount of tax obligations declared in the tax return , or the amount of tax credit declared in the tax return on value added tax, as well as the need to send (deliver) to the taxpayer the relevant tax notice-decision in cases provided for by this Code.
When reviewing the inspection materials, the supervisory authority examines all available factual data related to the subject of consideration, including documents provided by the taxpayer or requested from him, written and oral explanations of the taxpayer, and other factual data available or accessible to the supervisory authority.
Based on the results of reviewing the inspection materials, the objection review commission adopts a conclusion that is an integral part of the inspection materials.
If it is established that it is necessary to conduct an unscheduled documentary inspection in accordance with the procedure established by subparagraph 78.1.5 of paragraph 78.1 of Article 78 of this Code, the conclusion based on the results of consideration of the inspection materials shall be adopted by the objection review commission after conducting such an inspection, taking into account its results.
In case of disagreement of the taxpayer or his representatives with the conclusions of the audit or the facts and data set out in the report (certificate) of the audit conducted on the basis of subparagraph 78.1.5 of paragraph 78.1 of Article 78 of this Code in connection with the consideration of objections to the report (certificate) of the audit submitted in accordance with the procedure specified in this paragraph, or the consideration of a complaint against a tax notice-decision adopted by the controlling body, they have the right to submit their objections to the controlling body that conducted such an audit within five working days from the day following the day of receipt of the report (certificate). Such objections shall not be considered separately. Such objections shall be attached to the inspection materials or materials regarding the consideration of the complaint, and the facts and data contained therein shall be taken into account by the supervisory authority when forming, in accordance with the procedure provided for in this subparagraph, a conclusion based on the results of the consideration of the inspection materials or during the consideration of a complaint against the adopted tax notice-decision in accordance with the procedure established by Article 56 of this Code.
86.7.5. A tax notification-decision shall be adopted by the head (his deputy or an authorized person) of the regulatory authority on the basis of the conclusion of the regulatory authority's commission on the consideration of objections within five working days following the date of adoption of such conclusion by the commission and provision (sending) of a written response to the taxpayer, in accordance with the procedure specified in subparagraph 86.7.1 of this paragraph.
Controlling and other state bodies are prohibited from using the inspection report as a basis for conclusions regarding the relationship between the taxpayer and its counterparties if, based on the results of drawing up the inspection report, the tax notice-decision has not been sent (not delivered) to the taxpayer or it is considered withdrawn in accordance with subparagraphs 60.1.2 and 60.1.4 of paragraph 60.1 of Article 60 of this Code.
{ Clause 86.7 of Article 86 as amended by Laws No. 4834-VI of 24.05.2012 , No. 655-VIII dated 17.07.2015 , No. 1797-VIII dated 21.12.2016 , No. 2628-VIII dated 23.11.2018 ; as amended by the Law No. 466-IX dated 16.01.2020 }
86.8. A tax notification-decision shall be adopted in accordance with the procedure provided for in Article 58 of this Code by the head (his deputy or an authorized person) of the supervisory authority within fifteen business days from the day following the day of delivery of the inspection report to the taxpayer, his representative or the person who carried out the settlement operations, and shall be sent (delivered) to the taxpayer in accordance with the procedure specified in Article 42 of this Code.
If there are objections from the taxpayer's officials to the inspection report and additional documents and explanations, in particular documents confirming the absence of guilt, the presence of mitigating circumstances or circumstances exempting from financial liability in accordance with this Code, submitted in accordance with the procedure established by this article, the tax notice-decision shall be adopted in accordance with the procedure and within the time limits specified in paragraph 86.7 of this article.
{Clause 86.8 of Article 86 as amended by Law No. 4834-VI of 24.05.2012 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 466-IX dated 16.01.2020 }
{Clause 86.9 of Article 86 was excluded on the basis of Law No. 655-VIII of 17.07.2015 }
86.10. The audit report shall indicate both the facts of understatement and the facts of overstatement of the payer's tax liabilities.
86.11. Based on the results of the electronic audit, a certificate is drawn up in two copies, signed by the officials of the supervisory authority who conducted the audit, and registered with the supervisory authority within three working days from the date of expiry of the period established for conducting the audit (for taxpayers who have branches and/or are on consolidated payment, within five working days).
After its registration, the electronic audit certificate is personally delivered to the taxpayer or his legal representatives for review and signing within five business days from the date of delivery.
In case of disagreement of the taxpayer or his legal representatives with the conclusions of the audit or the facts and data set out in the certificate drawn up based on the results of the electronic audit, they are obliged to sign such certificate and have the right to submit their objections, which are an integral part of such certificate, together with a signed copy of the certificate.
Such objections shall be considered by the supervisory authority within five working days from the date of their receipt and the taxpayer shall be sent a response in accordance with the procedure established by Article 58 of this Code for sending (delivering) tax notices-decisions. Such response shall be an integral part of the certificate of electronic inspection. The taxpayer (his authorized person and/or representative) shall have the right to participate in the consideration of objections, including by video conference, as he shall indicate in the submitted objections.
{Paragraph four of clause 86.11 of Article 86 as amended by the Law No. 3603-IX dated 23.02.2024 }
{Article 86 was supplemented by paragraph 86.11 in accordance with Law No. 5503-VI of 20.11.2012 }
86.12. The results of inspections on compliance by the taxpayer with the "arm's length" principle are drawn up taking into account the features specified in Article 39 of this Code.
{Article 86 is supplemented by paragraph 86.12 in accordance with Law No. 408-VII of 04.07.2013 ; as amended by Law No. 1797-VIII of 21.12.2016 }
86.13. An act (certificate) based on the results of an inspection of the activities of a non-resident through separate divisions, including a permanent representative office in Ukraine without registration with the regulatory authority, shall be sent to the non-resident in accordance with the procedure specified in Article 42 of this Code, or shall be provided to the authorized representative of the non-resident or shall be sent to the competent authority of the state of which the non-resident is a resident. In the event of written objections to the act (certificate) being received from the non-resident, such objections shall be considered in accordance with the procedure specified in this Code.
{Article 86 is supplemented by paragraph 86.13 in accordance with Law No. 466-IX of January 16, 2020 }
86.14. If the supervisory authority, based on the results of a documentary inspection, discovers circumstances (facts) that may indicate the implementation of transactions aimed at providing an illegal benefit to an official of a foreign state, regardless of the amount of such benefit, the supervisory authority shall send:
Notification to the National Anti-Corruption Bureau of Ukraine of the detection of such circumstances (facts) in the order of information interaction determined by the central executive body that ensures the formation and implementation of state financial policy, and the National Anti-Corruption Bureau of Ukraine - within 15 working days after the completion of the documentary check;
the taxpayer shall be informed of the fact of sending the notification in accordance with paragraph two of this paragraph and of the circumstances (facts) specified therein in the manner prescribed by Article 42 of this Code - on the next business day after sending the relevant notification to the National Anti-Corruption Bureau of Ukraine.
In order to identify the specified circumstances (facts), the regulatory authority is guided by the list published on the official website of the National Anti-Corruption Bureau of Ukraine in accordance with paragraph 12 of part one of Article 16 of the Law of Ukraine "On the National Anti-Corruption Bureau of Ukraine".
{Article 86 is supplemented by paragraph 86.14 in accordance with Law No. 4112-IX of 04.12.2024 }
Article 87. Sources of payment of monetary obligations or repayment of tax debt of a taxpayer↑
87.1. The sources of independent payment of monetary obligations or repayment of a taxpayer's tax debt are any own funds, including those received from the sale of goods (works, services), property, issuance of securities, in particular corporate rights, received as a loan (credit), and from other sources, taking into account the features defined by this article, as well as the amount of overpaid payments to the relevant budgets.
The source of self-payment of monetary obligations for value-added tax is the amounts of funds, the sources of which are specified in the first paragraph of this paragraph and are recorded in the electronic administration system for value-added tax. In the case of payment of tax obligations that arose before July 1, 2015, and/or repayment of tax debt for tax obligations that arose before July 1, 2015, the transfer of funds to the budget is carried out directly from the taxpayer's accounts opened in banks, non-bank payment service providers.
{Clause 87.1 of Article 87 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2888-IX of 12.01.2023 }
Payment of monetary obligations or repayment of a taxpayer's tax debt from the relevant payment can also be made:
{Paragraph three of clause 87.1 of Article 87 as amended by Law No. 909-VIII of 24.12.2015 }
a) due to the excess amounts paid for such payment (without the payer's application);
{Paragraph of clause 87.1 of Article 87 as amended by Law No. 909-VIII of 12/24/2015 }
b) at the expense of erroneously and/or excessively paid amounts from other payments (based on the relevant application of the payer) to the relevant budgets, taking into account the features specified in paragraph 43.4 - 1 of Article 43 of this Code;
{Paragraph 87.1 of Article 87 as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
c) at the expense of the amount of budget compensation for value added tax (based on the relevant application of the payer) to the State Budget of Ukraine."
{Paragraph of clause 87.1 of Article 87 as amended by Law No. 909-VIII of 12/24/2015 }
Funds on the payer's account in the electronic administration system for value-added tax cannot be a source of tax debt repayment, except for the repayment of tax debt on value-added tax (except for tax debt that arose before July 1, 2015). To repay such a tax debt from funds on the taxpayer's account in the electronic administration system for value-added tax, the central executive body implementing tax policy, provided that there are grounds provided for in Article 95 of this Code, shall send to the central executive body implementing state policy in the field of treasury services of budget funds, in which payers' accounts in the electronic administration system for value-added tax are opened, a register indicating the name of the taxpayer, the taxpayer's tax and individual tax number and the amount of tax debt subject to transfer to the budget (except for the amounts of tax debt under tax obligations on value-added tax that were subject to payment to the state budget and for which a register has been formed for the transfer of funds to the state budget from an account in the electronic administration system in accordance with Clause 200.2 of Article 200 of this Code). The procedure for forming and sending such a register to the central executive body implementing state policy in the field of treasury servicing of budget funds is determined by the central executive body ensuring the formation and implementation of state financial policy.
{Clause 87.1 of Article 87 supplemented by a paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 643-VIII of 16.07.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
87.2. The sources of repayment of a taxpayer's tax debt are any property of such taxpayer, taking into account the restrictions specified in this Code, as well as other legislative acts.
87.3. The following cannot be used as sources of repayment of a taxpayer's tax debt:
87.3.1. property of a taxpayer pledged by him to other persons (for the duration of such pledge), if such pledge is registered in accordance with the law in the relevant state registers before the right to tax pledge arises;
87.3.2. property owned by other persons and in the possession or use of the taxpayer, including (but not exclusively) property transferred to the taxpayer for leasing, rent, safekeeping (responsible storage), pawnshop custody, on commission (consignment); toll-based raw materials provided to the enterprise for processing, except for its part provided to the taxpayer as payment for such services, as well as property of other persons accepted by the taxpayer as a pledge or deposit, trust and any other types of agency management;
{Subclause 87.3.2 of Clause 87.3 of Article 87 as amended by Law No. 1605-IX of 01.07.2021 }
87.3.3. property rights of other persons granted to the taxpayer for use or possession, as well as non-property rights, including intellectual (industrial) property rights, transferred for use to such a taxpayer without the right to alienate them;
87.3.4. Amounts of credits or loans granted to a taxpayer by a credit and financial institution, recorded in loan accounts opened for such taxpayer, amounts of letters of credit issued in the name of the taxpayer but not opened, amounts of advance payments and prepayments under contracts of shipbuilding industry enterprises (class 35.11, group 35 of the KVED DK 009:2005 ), received from customers of sea and river vessels and other floating facilities;
{Subclause 87.3.4 of clause 87.3 of Article 87 as amended by Law No. 3609-VI of 07.07.2011 }
87.3.5. property included in the unified property complexes of state-owned enterprises that are not subject to privatization, including state-owned enterprises. The procedure for classifying property as included in the unified property complex of a state-owned enterprise is established by the State Property Fund of Ukraine;
87.3.6. property, the free circulation of which is prohibited under the legislation of Ukraine;
87.3.7. property that cannot be the subject of pledge in accordance with the Law of Ukraine "On Pledge" ;
87.3.8. funds of other persons provided to the taxpayer in a contribution (deposit) or trust management, as well as the legal entity's own funds used to pay arrears of basic wages for time actually worked to individuals who are in an employment relationship with such a legal entity.
87.4. Officials, including state executors, who have made a decision to use the property specified in paragraph 87.3 of this Article as a source of repayment of a monetary obligation or tax debt of a taxpayer shall be liable in accordance with the law.
87.5. If the implementation of measures to repay the taxpayer's tax debt by collecting funds in his possession has not led to the full repayment of the tax debt or if the taxpayer does not have sufficient funds to repay the tax debt, the regulatory authority shall determine the taxpayer's receivables, the maturity of which has come, as the source of repayment of the tax debt of such taxpayer.
The controlling authority shall enter into an agreement with the taxpayer to transfer the right to claim such receivables. Such receivables shall continue to be an asset of the taxpayer with a tax debt, as specified in the agreement between the taxpayer and the controlling authority, and shall be disclosed accordingly in the notes to the financial statements.
The tax debt continues to be recorded for the taxpayer who incurred it until funds are received into the budget through the collection of this receivable. The controlling body shall notify the taxpayer of such receipt within five days from the date of receipt of the relevant document.
In the event of a taxpayer with a tax debt refusing to conclude an agreement with a supervisory authority on the transfer of the right to claim receivables, such supervisory authority shall apply to the court regarding the taxpayer's obligation to conclude the specified agreement.
{Clause 87.5 of Article 87 as amended by Law No. 1797-VIII of 21.12.2016 }
87.6. In the event that a taxpayer that is a branch, a separate subdivision of a legal entity does not have property sufficient to repay its monetary obligation or tax debt, the source of repayment of the monetary obligation or tax debt of such taxpayer shall be the property of such legal entity, which may be subject to enforcement in accordance with this Code.
The procedure for applying paragraphs 87.5 and 87.6 of this article is determined by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph two of clause 87.6 of Article 87 as amended by Law No. 1797-VIII of 21.12.2016 }
87.7. Any assignment of a taxpayer's monetary obligation or tax debt to third parties is prohibited. The provisions of this paragraph do not apply to cases where other persons are guarantors of the full and timely repayment of the taxpayer's monetary obligations, if such a right is provided for by this Code.
87.8. In addition to the sources specified in clause 87.1 of this article, the source of repayment of tax debt of banks, non-bank financial institutions, including insurance organizations, may be funds, regardless of their sources of origin and without applying the restrictions specified in subclauses 87.3.4 and 87.3.8 of clause 87.3 of this article, in an amount not exceeding the amount of their equity capital (excluding insurance and equivalent mandatory reserves formed in accordance with the law). The amount of equity capital is determined in accordance with the legislation of Ukraine.
87.9. In the event that a taxpayer has a tax debt, the regulatory authorities are obliged to credit the funds paid by such taxpayer to the repayment of the tax debt in accordance with the order of its occurrence, regardless of the direction of payment specified by the taxpayer. The same procedure shall be used to credit funds received to the repayment of the taxpayer's tax debt in accordance with Article 95 of this Code or by court decision in cases provided for by law.
{Paragraph one of clause 87.9 of Article 87 as amended by Law No. 4834-VI of 24.05.2012 }
The allocation of funds by a taxpayer to repay a monetary obligation before the tax debt is repaid is prohibited, except in cases where these funds are allocated to pay wages and a single contribution to mandatory state social insurance.
87.10. From the moment the court issues a ruling to initiate proceedings in a taxpayer's bankruptcy case, the procedure for repaying monetary obligations that are included in the competitive creditor claims of the regulatory authorities against such a debtor is determined in accordance with the Code of Ukraine on Bankruptcy Procedures without applying the norms of this Code.
{Clause 87.10 of Article 87 as amended by Law No. 466-IX of January 16, 2020 }
87.11. The collection body shall file a claim with the court to collect the amount of tax debt of a taxpayer - an individual. The collection of tax debt by court decision shall be carried out by the state enforcement service in accordance with the law on enforcement proceedings.
87.12. If a tax debt arose from transactions carried out within the framework of joint activity agreements, the source of repayment of such tax debt is the property of taxpayers who are parties to such an agreement.
87.13. In the event of non-payment within 240 calendar days from the date of delivery of the tax claim to the taxpayer of the amount of tax debt exceeding 1 million hryvnias, the regulatory authority may apply to the court for a temporary restriction on the right of the head of the legal entity or permanent representative office of the non-resident debtor to travel outside Ukraine until such tax debt is repaid.
The requirements of the first paragraph of this paragraph shall not apply in the event of a state obligation to return to a legal entity or permanent establishment of a non-resident debtor monetary obligations paid by it in error and/or in excess, budget reimbursement of value added tax, if the total amount of the state's outstanding debt to the debtor is equal to or exceeds the amount of tax debt of such debtor.
A temporary restriction on the right of the head of a legal entity or permanent representative office of a non-resident debtor to travel outside Ukraine is established as a precautionary measure to enforce a court decision or a decision of the head of a regulatory authority to collect the amount of tax debt.
In the event of a temporary restriction on the right of the head of a legal entity or a permanent representative office of a non-resident debtor to travel outside Ukraine in accordance with a court decision that has entered into legal force, the supervisory authority shall, no later than the next business day from the date of receipt of the court decision:
informs the central executive body implementing state policy in the field of state border protection about this, in accordance with the procedure for information exchange approved by the central executive body ensuring the formation and implementation of state financial policy, jointly with the central executive body ensuring the formation of state policy in the field of state border protection;
places the relevant information in the Register of Heads of Taxpayers - Debtors.
No later than the next business day from the date of crediting funds to the relevant account of the body that carries out treasury services of budget funds, and/or in other cases of repayment of the tax debt in the amount specified in the court decision as of the date of adoption of such court decision, or in the event of receiving information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations about a change in the head of a legal entity or permanent representative office of a non-resident debtor, or in the event of the commencement of court proceedings in bankruptcy cases regarding such debtor, the supervisory authority:
informs the central executive body implementing state policy in the field of state border protection about the above, in accordance with the procedure for exchanging information approved by the central executive body ensuring the formation and implementation of state financial policy, jointly with the central executive body ensuring the formation of state policy in the field of state border protection, which is the basis for canceling the established temporary restriction on the right to travel of the head of a legal entity or permanent representative office of a non-resident debtor outside Ukraine;
places the relevant information in the Register of Heads of Taxpayers - Debtors.
{Article 87 is supplemented by paragraph 87.13 in accordance with Law No. 1914-IX of 30.11.2021 }
87.14. The temporary restriction on the right to leave the legal entity or permanent representative office of a non-resident debtor shall terminate upon repayment of the amount of tax debt specified in the court decision in connection with which such restriction was applied, or upon receipt of information from the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations about a change in the legal entity or permanent representative office of a non-resident debtor, or upon commencement of court proceedings in bankruptcy cases concerning such debtor.
{Article 87 is supplemented by paragraph 87.14 in accordance with Law No. 1914-IX of 30.11.2021 }
88.1. In order to ensure that the taxpayer fulfills his obligations specified in this Code, the property of the taxpayer who has a tax debt shall be transferred as a tax pledge.
88.2. The right to a tax lien arises in accordance with this Code and does not require written registration.
88.3. If the tax debt arose from transactions carried out within the framework of joint activity agreements, the property of the taxpayer who, according to the terms of the agreement, was responsible for transferring taxes to the budget and/or the property that is contributed to the joint activity and/or is the result of the joint activity of the taxpayers shall be transferred as a tax pledge. In the event of insufficiency of the property of such taxpayer, the property of other participants in the joint activity agreement shall be transferred as a tax pledge in the amounts proportional to their participation in such joint activity.
89.1.1. in case of failure to pay within the terms established by this Code the amount of the monetary obligation independently determined by the taxpayer in the tax return - from the day following the last day of the specified term;
89.1.2. in case of failure to pay within the terms established by this Code the amount of the monetary obligation independently determined by the controlling body - from the date of the tax debt;
89.1.3. in the case specified in paragraph 100.11 of Article 100 of this Code - from the date of conclusion of the agreement on installment payment, deferral of monetary obligations.
{Clause 89.1 of Article 89 as amended by Law No. 1797-VIII of 21.12.2016 }
89.2. Subject to the provisions of this Article, the right of tax lien shall apply to any property of the taxpayer that is in his ownership (economic management or operational management) on the date of the occurrence of such right and the book value of which corresponds to the amount of the taxpayer's tax debt, except for the cases provided for in paragraph 89.5 of this Article, as well as to other property to which the taxpayer will acquire ownership rights in the future.
If the book value of the property subject to a tax lien is less than the amount of the taxpayer's tax debt, the right to a tax lien applies to such property.
{Clause 89.2 of Article 89 is supplemented with a new paragraph in accordance with Law No. 3609-VI of 07.07.2011 }
If the book value of such property is not determined, its description is carried out based on the results of the appraisal, which is carried out in accordance with the Law of Ukraine "On the Appraisal of Property, Property Rights and Professional Appraisal Activities in Ukraine" .
In the event of an increase in the amount of tax debt, an inventory report shall be drawn up to the amount corresponding to the amount of the taxpayer's tax debt, in accordance with the procedure provided for in this article.
The right of tax lien does not apply to property defined in subparagraph 87.3.7 of paragraph 87.3 of Article 87 of this Code, to mortgage assets belonging to the issuer and serving as collateral for the relevant issue of fixed-income mortgage certificates, to cash income from these mortgage assets until the issuer has fully fulfilled its obligations under this issue of fixed-income mortgage certificates, as well as to the composition of the mortgage coverage and cash income from it until the issuer has fully fulfilled its obligations under the relevant issue of ordinary mortgage bonds.
The right to tax lien does not apply if the total amount of the taxpayer's tax debt does not exceed one hundred and eighty non-taxable minimum incomes of citizens.
{Clause 89.2 of Article 89 supplemented by the sixth paragraph in accordance with Law No. 4834-VI of 24.05.2012 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 1072-IX dated 04.12.2020 }
89.3. Property subject to tax lien shall be recorded in an inventory report.
The inventory report includes liquid assets that can be used as a source of tax debt repayment.
The description of property as a tax lien is carried out on the basis of a decision of the head (his deputy or authorized person) of the regulatory body, which is presented to the taxpayer who has a tax debt.
{Paragraph three of clause 89.3 of Article 89 as amended by Law No. 1797-VIII of 21.12.2016 }
The act of inventory of property subject to the right of tax lien is drawn up by the tax manager in accordance with the procedure and form approved by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph four of clause 89.3 of Article 89 as amended by Law No. 1797-VIII of 21.12.2016 }
The taxpayer's refusal to sign the inventory of property subject to tax lien does not exempt such taxpayer from the extension of tax lien to the described property. In such a case, the inventory shall be carried out in the presence of at least two witnesses.
89.4. If a taxpayer does not allow the tax administrator to carry out an inventory of the taxpayer's property under tax lien and/or does not submit the documents required for such inventory, the tax administrator shall draw up an act of the taxpayer's refusal to inventory the property under tax lien.
The supervisory authority applies to the court to suspend expenditure transactions on the taxpayer's accounts/electronic wallets, prohibit the alienation of property by such taxpayer, and oblige such taxpayer to allow the tax administrator to inventory the property in tax lien.
{ Paragraph two of clause 89.4 of Article 89 as amended by the Law No. 2888-IX dated 12.01.2023 }
The suspension of expenditure transactions on the taxpayer's accounts/electronic wallets and the prohibition on alienation of property by such a taxpayer shall be effective until the date of drawing up an act of inventory of the taxpayer's property as a tax lien by the tax administrator or an act on the absence of property that can be described as a tax lien, or the tax debt is fully repaid. The tax administrator shall, no later than the business day following the date of drawing up these acts, send to banks, other financial institutions, non-bank payment service providers, electronic money issuers, and the taxpayer a decision on drawing up acts, which is the basis for the resumption of expenditure transactions and the lifting of the prohibition on alienation of property.
{Paragraph three of clause 89.4 of Article 89 as amended by Law No. 4834-VI of 24.05.2012 ; as amended by the Law No. 2888-IX dated 12.01.2023 }
89.5. If at the time of drawing up the inventory report the property is missing or its book value is less than the amount of the tax debt, the right of tax lien shall apply to other property to which the taxpayer will acquire ownership in the future until the tax debt is fully repaid.
The taxpayer shall be obliged to notify the supervisory authority of the existence of such property no later than the business day following the day of acquisition of ownership of any property. The supervisory authority shall be obliged, within three business days from the date of receipt of the said notification, to make a decision on including such property in the inventory act of the property subject to the right of tax lien and the book value of which corresponds to the amount of the taxpayer's tax debt, or to refuse the taxpayer from including such property in the inventory act.
If the regulatory authority decides to include property in the inventory report, a corresponding inventory report is drawn up, one copy of which is sent to the taxpayer in accordance with the procedure specified in Article 42 of this Code.
{Paragraph three of clause 89.5 of Article 89 as amended by Law No. 1797-VIII of 21.12.2016 }
Until the relevant decision is made by the controlling body, the taxpayer does not have the right to alienate such property.
If a taxpayer violates the requirements of this paragraph, he shall be liable in accordance with the law.
89.6. If the taxpayer's property is indivisible and its book value is greater than the amount of the tax debt, such property shall be subject to description as a tax lien in full.
89.7. Replacement of the collateral may be carried out only with the consent of the supervisory authority.
89.8. The controlling authority is obliged to register the tax lien in the relevant state register free of charge.
91.1. In the event that a taxpayer has a tax debt, the head (his deputy or an authorized person) of the supervisory authority at the place of registration of the taxpayer who has a tax debt shall appoint a tax manager for such taxpayer. The tax manager must be an official (service) person of the supervisory authority. The tax manager has the rights and obligations specified in this Code.
{Clause 91.1 of Article 91 as amended by Law No. 1797-VIII of 21.12.2016 }
91.2. The procedure for appointment and dismissal, as well as the functions and powers of the tax administrator, shall be determined by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 91.2 of Article 91 as amended by Law No. 1797-VIII of 21.12.2016 }
91.3. The tax administrator shall describe the property of a taxpayer who has a tax debt in tax lien, shall check the state of preservation of the property that is in tax lien, shall make an inventory of the property to which the right of tax lien applies for its sale in cases provided for by this Code, shall receive from the debtor information about transactions with the pledged property, and in the event of its alienation without the consent of the supervisory authority (provided that the presence of such consent shall be mandatory in accordance with the requirements of this Code) shall demand an explanation from the taxpayer or his officials (officials), shall prepare documents for an application to the court with a motion to establish a temporary restriction on the right of the head of a legal entity or a permanent representative office of a non-resident debtor to travel outside Ukraine. In the event of the sale of property of a taxpayer subject to a tax lien to repay a tax debt, the tax administrator has the right to receive from such taxpayer documents certifying ownership of the said property.
{Paragraph one of clause 91.3 of Article 91 as amended by Law No. 1914-IX of 30.11.2021 }
In the event of a taxpayer's refusal to sign the act of inventory of property subject to the right of tax lien, the tax administrator has the right to involve at least two witnesses in the inventory of the taxpayer's property.
{Clause 91.3 of Article 91 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
91.4. If a taxpayer with a tax debt prevents a tax manager from exercising the powers specified in this Code, such tax manager shall draw up an act on the taxpayer's obstruction of the exercise of such powers in the manner and form established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph one of clause 91.4 of Article 91 as amended by Law No. 1797-VIII of 21.12.2016 }
The supervisory authority shall apply to the court to suspend expenditure transactions on the taxpayer's accounts/electronic wallets and oblige such taxpayer to comply with the tax administrator's lawful requirements provided for by this Code. The period for which expenditure transactions may be suspended shall be determined by the court, but not more than two months.
{Paragraph two of clause 91.4 of Article 91 as amended by Law No. 3813-IX of 18.06.2024 }
Suspension of expenditure transactions on the taxpayer's accounts/electronic wallets may be canceled early by decision of the tax administrator or court.
{Paragraph three of clause 91.4 of Article 91 as amended by Law No. 3813-IX of 18.06.2024 }
Article 92. Reconciliation of transactions with pledged property↑
92.1. The taxpayer retains the right to use property that is subject to tax lien, unless otherwise provided by law.
A taxpayer may alienate property subject to tax lien only with the consent of the regulatory authority, as well as if the regulatory authority has not provided such taxpayer with a response regarding the granting (non-granting) of consent within ten days of receiving the relevant application from the taxpayer.
If only finished products, goods and inventories are subject to tax lien, the taxpayer may alienate such property without the consent of the regulatory authority for funds at prices not lower than normal, and provided that the funds from such alienation will be used in full to pay wages, a single contribution to mandatory state social insurance and/or repay tax debt.
92.2. In the event of alienation or rental or leasing of property that is subject to tax lien, the taxpayer, with the consent of the controlling authority, is obliged to replace it with other property of the same or greater value. A reduction in the value of the replaced property is permitted only with the consent of the controlling authority, provided that the tax debt is partially repaid.
{Clause 92.2 of Article 92 as amended by Law No. 1605-IX of 01.07.2021 }
92.3. In the event of transactions with property that is subject to tax lien without the prior consent of the regulatory authority, the taxpayer shall be liable in accordance with the law.
92.4. The consent of the regulatory body is not required for the alienation in the process of privatization of state or municipal property as part of a single property complex of a state or municipal enterprise, if the purchase and sale agreement of the privatization object provides for the buyer's obligation to repay in full the amount of the tax debt, in connection with which the right of tax lien arose, no later than six calendar months from the date of transfer of ownership of the privatization object.
{Paragraph one of clause 92.4 of Article 92 as amended by Law No. 3813-IX of 18.06.2024 }
At the same time, such property is not released from tax lien until the tax debt is fully repaid by its buyer.
In the case provided for in the first paragraph of this paragraph, the provisions of paragraphs 92.1-92.3 of this Article shall not apply.
{Article 92 is supplemented by paragraph 92.4 in accordance with Law No. 2719-IX of 03.11.2022 }
93.1. The taxpayer's property is released from tax lien from the date of:
93.1.1. receipt by the controlling authority of confirmation of full repayment of the amount of tax debt and/or installment (deferred) monetary obligations and interest for the use of installment (deferral) payments in accordance with the procedure established by law;
{ Subparagraph 93.1.1 of paragraph 93.1 of Article 93 as amended by Law No. 466-IX of January 16, 2020 }
93.1.2. recognition of tax debt as hopeless;
93.1.3. entry into force of the relevant court decision on the termination of the tax lien within the procedures specified by the bankruptcy legislation;
{Subparagraph 93.1.3 of paragraph 93.1 of Article 93 as amended by Law No. 4834-VI of 24.05.2012 }
93.1.4. receipt by the taxpayer as a result of an administrative or judicial appeal procedure or in other cases provided for in Article 55 of this Code, of a decision of the relevant body on the recognition as unlawful and/or cancellation of previously adopted decisions on the calculation of the amount of the monetary obligation.
{ Subparagraph 93.1.4 of paragraph 93.1 of Article 93 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
{Sub-clause 93.1.5 of clause 93.1 of Article 93 was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
93.1.6. receipt by the taxpayer of the consent of the regulatory authority to alienate property subject to tax lien, in accordance with Article 92 of this Code.
{ Clause 93.1 of Article 93 is supplemented by subparagraph 93.1.6 in accordance with Law No. 466-IX of 16.01.2020 }
93.2. The basis for releasing a taxpayer's property from tax lien and its exclusion from the relevant state registers is a relevant document certifying the end of any of the events specified in paragraph 93.1 of this Article.
{Clause 93.2 of Article 93 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1117-IX of 12/17/2020 }
93.3. The procedure for applying tax liens is established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 93.3 of Article 93 as amended by Law No. 1797-VIII of 21.12.2016 }
93.4. In the event of the sale of property subject to tax lien, in accordance with Article 95 of this Code, such property shall be released from tax lien (with amendments to the relevant state registers) from the date of receipt by the controlling body of confirmation of receipt of funds to the budget from such sale.
{Article 93 was supplemented by paragraph 93.4 in accordance with Law No. 4834-VI of 24.05.2012 }
93.5. In the event of the sale of a single property complex of a state or municipal enterprise during the privatization process, such property shall be released from tax lien (with amendments to the relevant state registers) from the date the controlling body receives confirmation of full repayment of the tax debt by the buyer of the privatization object.
{Article 93 is supplemented by paragraph 93.5 in accordance with Law No. 2719-IX of 03.11.2022 ; as amended in accordance with Law No. 3813-IX of 18.06.2024 }
94.1. Administrative seizure of a taxpayer's property (hereinafter referred to as property seizure) is an exceptional method of ensuring that the taxpayer fulfills his obligations as defined by law.
94.2. Seizure of property may be applied if one of the following circumstances is found:
94.2.1. the taxpayer violates the rules for the alienation of property subject to tax lien;
94.2.2. an individual who has a tax debt travels abroad;
{The provision of subparagraph 94.2.2 of paragraph 94.2 of Article 94, according to which administrative seizure of a taxpayer's property may be applied if it is found that an individual who has a tax debt is traveling abroad, was recognized as constitutional in accordance with the Decision of the Constitutional Court No. 13-rp/2012 of 12.06.2012 }
94.2.3. the taxpayer refuses to conduct a documentary or actual inspection if there are legal grounds for conducting it or to allow officials of the controlling body to do so;
{Subclause 94.2.3, clause 94.2 of Article 94 as amended by Law No. 655-VIII of 17.07.2015 }
94.2.4. there are no permits (licenses) to carry out economic activities, as well as in the absence of registrars of settlement transactions and/or software registrars of settlement transactions registered in accordance with the procedure established by law, except for cases specified by law;
{Subclause 94.2.4 of Clause 94.2 of Article 94 as amended by Law No. 3205-VI of 07.04.2011 ; as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.05.2012 , No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 , No. 129-IX of 20.09.2019 }
94.2.5. there is no registration of a person as a taxpayer with a regulatory authority, if such registration is mandatory in accordance with this Code, or when a taxpayer who has received a tax notice or has a tax debt takes actions to transfer property outside Ukraine, conceal it or transfer it to other persons;
{The provision of subparagraph 94.2.5 of paragraph 94.2 of Article 94, according to which administrative seizure of a taxpayer's property may be applied if it is found that there is no registration of a person as a taxpayer with the state tax service body, if such registration is mandatory in accordance with this Code, or when a taxpayer who has received a tax notice or has a tax debt takes actions to transfer property outside Ukraine, conceal it or transfer it to other persons, has been recognized as constitutional in accordance with the Decision of the Constitutional Court No. 13-rp/2012 of 12.06.2012 }
94.2.6. the taxpayer refuses to conduct an inspection of the state of preservation of property that is subject to tax lien;
94.2.7. the taxpayer does not allow the tax administrator to draw up an inventory of the property transferred as a tax lien.
{Subclause 94.2.7 of Clause 94.2 of Article 94 as amended by Law No. 3609-VI of 07.07.2011 }
94.2.8. the taxpayer (its officials or persons who carry out cash settlements and/or conduct activities subject to licensing) refuses to conduct an inventory of fixed assets, tangible assets, funds (withdrawal of residual tangible assets, cash) in accordance with the requirements of this Code.
{Clause 94.2 of Article 94 is supplemented by subparagraph 94.2.8 in accordance with Law No. 1797-VIII of 21.12.2016 }
94.2.9. a non-resident commences and/or carries out economic activities through a permanent establishment in the territory of Ukraine without being registered for tax purposes, which is confirmed by an inspection report.
{ Clause 94.2 of Article 94 is supplemented by subparagraph 94.2.9 in accordance with Law No. 466-IX of 16.01.2020 }
94.3. Seizure of property consists in prohibiting the taxpayer from performing the actions specified in paragraph 94.5 of this article with respect to his property subject to seizure.
94.4. Arrest may be imposed by the controlling body on any property of a taxpayer, except for property that cannot be subject to seizure in accordance with the law and funds in the taxpayer's account.
94.5. The seizure of property may be complete or conditional.
A complete seizure of property is a prohibition on the taxpayer exercising the rights to dispose of or use his property. In this case, the risk associated with the loss of functional or consumer qualities of such property is borne by the body that made the decision on such a prohibition.
Conditional seizure of property is recognized as a restriction of the taxpayer on the exercise of property rights to such property, which consists in the mandatory prior receipt of permission from the head (his deputy or authorized person) of the regulatory body for the taxpayer to carry out any transaction with such property. The specified permission may be issued by the head (his deputy or authorized person) of the regulatory body if, according to the conclusion of the tax manager, the implementation of a separate transaction by the taxpayer will not lead to an increase in his tax debt or to a decrease in the probability of its repayment.
{Paragraph three of item 94.5 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
94.6. The head (his deputy or authorized person) of the supervisory authority, in the presence of one of the circumstances specified in paragraph 94.2 of this article, shall make a decision to seize the taxpayer's property, which shall be sent to:
{Paragraph one of item 94.6 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
94.6.1. to a taxpayer with a request to temporarily stop the alienation of his property;
94.6.2. to other persons in whose possession, disposal or use the property of such taxpayer is located, with a request to temporarily stop its alienation.
The seizure of funds in a taxpayer's account/electronic wallet is carried out exclusively on the basis of a court decision by means of an application by the regulatory authority to the court.
{ Paragraph two of subparagraph 94.6.2 of paragraph 94.6 of Article 94 as amended by the Law No. 2888-IX dated 12.01.2023 }
The release of funds from arrest by a bank, other financial institution, non-bank payment service provider, or electronic money issuer is carried out by a court decision.
{ Paragraph three of subparagraph 94.6.2 of paragraph 94.6 of Article 94 as amended by the Law No. 2888-IX dated 12.01.2023 }
94.7. Seizure of property may also be applied to goods that are manufactured, stored, transported or sold in violation of the rules established by the customs legislation of Ukraine or the legislation on excise taxation, and goods, including currency values, that are sold in violation of the procedure established by law, if their owner has not been identified.
In this case, officials of regulatory bodies or other law enforcement agencies, in accordance with their powers, temporarily detain such property with the preparation of a report, which must contain information about the reasons for such detention with reference to the violation of a specific legislative norm; a description of the property, its generic characteristics and quantity; information about the person(s) from whom such goods were seized (if any); a list of the rights and obligations of such persons arising in connection with such seizure. The form of the specified report is approved by the Cabinet of Ministers of Ukraine.
The head of the law enforcement agency unit under whose authority the official (official) who drew up a report on the temporary detention of property is is obliged to immediately inform the head (his deputy or authorized person) of the supervisory authority on whose territory such detention was carried out, with the obligatory delivery of a copy of the report.
{Paragraph three of item 94.7 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
Based on the information specified in the protocol, the head (his deputy or authorized person) of the regulatory body makes a decision to seize such property or refuse to do so by not making such a decision.
{Paragraph four of item 94.7 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
The decision to seize property must be made within 24 hours of the working day following the day of drawing up the protocol on the temporary detention of property, but if, in accordance with the legislation of Ukraine, the regulatory body ends its work earlier, such period expires at the time of such termination of work.
If a decision to seize property is not made within the specified period, the property is considered released from temporary detention, and officials or service personnel who impede such release are liable in accordance with the law.
94.8. When imposing an arrest on property in the cases specified in paragraph 94.7 of this article, the decision of the head (his deputy or authorized person) of the supervisory body shall be immediately served on the person (persons specified in paragraph 94.6 of this article) specified in the protocol on the temporary detention of property, without fulfilling the provisions of paragraph 94.6 of this article.
{ Clause 94.8 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
94.9. If the location of the persons specified in the protocol on temporary detention of property is not revealed or if the property has been detained and the persons to whom it belongs by right of ownership or other rights have not been established, the decision to arrest the property shall be made by the head (his deputy or an authorized person) of the supervisory body without serving it to the persons specified in paragraph 94.6 of this Article.
{ Clause 94.9 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
94.10. Property may be seized by decision of the head (his deputy or authorized person) of the regulatory body, the validity of which must be verified by a court within 96 hours.
{Paragraph one of item 94.10 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
The specified period may not be extended administratively, including by decision of other state bodies, except in cases where the owner of the property on which the seizure was imposed has not been established (not discovered). In these cases, such property shall be under administrative arrest for the period specified by law for recognizing it as ownerless, or in the case of property that is perishable, for the maximum period specified by law. The procedure for transactions with property whose owner has not been established shall be determined by the legislation on handling ownerless property.
The period specified in this paragraph does not include daily hours falling on weekends and holidays.
94.11. The decision of the head (his deputy or authorized person) of the regulatory body regarding the seizure of property may be appealed by the taxpayer in administrative or judicial proceedings.
{Paragraph one of item 94.11 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
In all cases where a higher-level supervisory body or a court cancels a decision to seize property, the higher-level supervisory body conducts an internal investigation into the motives for the decision to seize property by the head (his deputy or authorized person) of the supervisory body and makes a decision to hold the guilty parties accountable in accordance with the law.
{Paragraph two of item 94.11 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
94.12. When making a decision to seize the property of a bank, a non-bank payment service provider, or an electronic money issuer, the seizure may not be imposed on funds held in a bank's correspondent account, a settlement account of a non-bank payment service provider, or an electronic money issuer.
{ Item 94.12 of Article 94 as amended by the Law No. 2888-IX dated 12.01.2023 }
94.13. A taxpayer has the right to compensation for losses and non-pecuniary damage caused by a controlling body as a result of the unlawful seizure of the taxpayer's property, at the expense of state budget funds provided for controlling bodies in accordance with the law. The decision on such compensation shall be made by a court.
94.14. The functions of the executor of the decision to seize the taxpayer's property are assigned to the tax manager or another employee of the supervisory authority appointed by the head (his deputy or authorized person) of the supervisory authority. The executor of the decision to seize:
{Paragraph one of item 94.14 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
94.14.1. sends a decision on the seizure of property in accordance with paragraph 94.6 of this article;
94.14.2. organizes an inventory of the taxpayer's property.
94.15. The inventory of the taxpayer's property shall be conducted in the presence of its officials or their representatives, as well as attesting witnesses.
In the absence of the taxpayer's officials or their representatives, the inventory of his property shall be carried out in the presence of witnesses.
If necessary, an appraiser is involved to conduct a property inventory.
Representatives of a taxpayer whose property is subject to administrative arrest shall be informed of their rights and obligations.
by the Law of Ukraine "On Enforcement Proceedings" , cannot be witnesses .
94.16. During the inventory of a taxpayer's property, the persons conducting it shall be obliged to present to the officials of such taxpayer or their representatives the relevant decision on the imposition of administrative arrest, as well as documents certifying their authority to conduct such inventory. Based on the results of the inventory of the taxpayer's property, a protocol shall be drawn up containing a description and list of the property to be arrested, indicating the name, quantity, weight measures and individual characteristics and, if an appraiser is present, the value determined by such appraiser. All property subject to inventory shall be presented to the officials of the taxpayer or their representatives and witnesses, and in the absence of officials or their representatives - to witnesses, for inspection.
94.17. An official of the controlling body who executes a decision on administrative seizure of a taxpayer's property shall determine the procedure for its preservation and protection.
94.18. The implementation of measures provided for in paragraphs 94.15-94.17 of this article is not allowed between 8 p.m. and 9 a.m. the next day.
94.19. Termination of administrative seizure of taxpayer's property is carried out in connection with:
94.19.1. the absence, within the period specified in paragraph 94.10 , of a court decision recognizing the arrest as justified;
94.19.2. repayment of the taxpayer's tax debt;
94.19.3. elimination by the taxpayer of the reasons for the application of administrative arrest;
94.19.4. liquidation of the taxpayer, including as a result of bankruptcy proceedings;
94.19.5. provision by a third party to the relevant regulatory authority of appropriate evidence that the seized property belongs to the objects of ownership of this third party;
94.19.6. cancellation by a court or a supervisory authority of the decision of the head (his deputy or authorized person) of the supervisory authority on arrest;
{Subclause 94.19.6 of clause 94.19 of Article 94 as amended by Law No. 1797-VIII of 21.12.2016 }
94.19.7. by the court's decision to terminate administrative arrest;
94.19.8. presentation by the taxpayer of permits (licenses) for the conduct of activities, as well as a document confirming the registration of settlement transaction registrars and/or software settlement transaction registrars, carried out in accordance with the procedure established by law, except for cases specified by law;
{Subclause 94.19.8 of clause 94.19 of Article 94 as amended by Laws No. 3205-VI of 07.04.2011 , No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 , No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 , No. 129-IX of 20.09.2019 }
94.19.9. actual conduct by the taxpayer of an inventory of fixed assets, tangible assets, funds, including the withdrawal of residual tangible assets, cash;
{Subclause 94.19.9 of clause 94.19 of Article 94 as amended by Law No. 657-VII of 24.10.2013 }
94.19.10. by the controlling authority taking a non-resident into tax registration on the basis of an inspection report.
{ Item 94.19 of Article 94 is supplemented by sub-item 94.19.10 in accordance with the Law No. 1117-IX dated 17.12.2020 }
94.20. In cases specified in subparagraphs 94.19.2-94.19.4 , 94.19.8 , 94.19.9 , 94.19.10 of paragraph 94.19 of this article, the decision to release property from seizure shall be made by the supervisory authority within two working days following the day on which the supervisory authority became aware of the emergence of grounds for terminating administrative seizure.
{Paragraph one of clause 94.20 of Article 94 as amended by Laws No. 3609-VI of 07.07.2011 , No. 1117-IX of 17.12.2020 }
If a decision to release property from arrest is made in relation to an arrest that was found to be justified by the court, the supervisory authority shall notify the relevant court of its decision no later than the next business day.
94.21. If the taxpayer's property is released from administrative seizure in the cases specified in paragraphs 94.19.1 , 94.19.6 , 94.19.7 , 94.19.9 , repeated imposition of administrative seizure on the grounds for the imposition of the first seizure is not permitted.
95.1. The supervisory authority shall take measures on behalf of the taxpayer and in favor of the state to repay the tax debt of such taxpayer by collecting funds in his possession, and in case of their insufficiency - by selling the property of such taxpayer that is subject to tax lien.
95.2. The collection of funds and the sale of the taxpayer's property shall be carried out no earlier than 30 calendar days from the date of sending (delivering) a tax claim to such taxpayer.
{Clause 95.2 of Article 95 as amended by Laws No. 4834-VI of 05/24/2012 , No. 466-IX of 01/16/2020 }
95.3. The collection of funds from the taxpayer's accounts/electronic wallets in banks, non-bank payment service providers/electronic money issuers serving such a taxpayer, and from taxpayer accounts in the value-added tax electronic administration system opened in the central executive body implementing state policy in the field of treasury services of budget funds, is carried out by a court decision, which is sent for execution to the supervisory authorities, in the amount of the tax debt or part thereof.
{Paragraph one of clause 95.3 of Article 95 as amended by Laws No. 643-VIII of 16.07.2015 , No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 2888-IX dated 12.01.2023 }
The supervisory authority applies to the court for permission to repay the entire amount of the tax debt at the expense of the taxpayer's property that is under tax lien.
The court's decision to grant the specified permission is the basis for the supervisory authority to make a decision to repay the entire amount of the tax debt. The decision of the supervisory authority is signed by the head (his deputy or an authorized person) of the supervisory authority and is sealed with the official seal of the supervisory authority. The list of information specified in such a decision is established by the central executive authority that ensures the formation and implementation of state financial policy.
{Paragraph three of clause 95.3 of Article 95 as amended by Laws No. 1797-VIII of 21.12.2016 , No. 1797-VIII of 21.12.2016 }
95.4. The supervisory authority, on the basis of a court decision, shall collect funds to repay the tax debt from cash belonging to such taxpayer. Cash collection shall be carried out in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
95.5. Cash funds withdrawn in accordance with this Article shall be deposited by an official of the controlling body to the bank on the day of their collection for transfer to the relevant budget or to the state trust fund for the purpose of repaying the taxpayer's tax debt, and in the case of using a single account by the taxpayer - to such an account, and in the case of repaying the tax debt on value added tax for tax liabilities declared for payment for the periods starting from July 1, 2015, specified by the taxpayer in the value added tax return or clarifying calculation, such funds shall be deposited to the payer's account in the electronic administration system for value added tax. If it is impossible to deposit the specified funds during the same day, they shall be deposited in the bank on the next business day. The relevant controlling body shall ensure the safety of the specified funds until they are deposited in the bank.
{Paragraph one of clause 95.5 of Article 95 as amended by Law No. 466-IX of January 16, 2020 ; as amended by Law No. 190-IX of October 4, 2019 }
If the tax debt arose as a result of non-payment of monetary obligations and/or penalties specified by the taxpayer in tax returns or clarifying calculations submitted to the regulatory authority within the terms established by this Code, the collection of funds from cash belonging to such a taxpayer and/or funds from accounts/electronic wallets of such a taxpayer in banks, non-bank payment service providers/issuers of electronic money shall be carried out by decision of the head (his deputy or authorized person) of the regulatory authority without recourse to the court, provided that such tax debt is not paid within 90 calendar days following the last day of the deadline for its payment, and there is no/presence of an outstanding obligation of the state in a smaller amount to return to such a taxpayer monetary obligations paid by mistake and/or in excess, and/or budget reimbursement of value added tax. In the event of an outstanding state obligation to the taxpayer in an amount that is less than the amount of the tax debt, this rule is applied within the difference between the amount of the tax debt and the amount of the state obligation.
{ Item 95.5 of Article 95 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Laws No. 466-IX of 16.01.2020 , No. 1914-IX of 30.11.2021 , No. 2888-IX of 12.01.2023 }
In such cases:
{ Item 95.5 of Article 95 is supplemented by the third paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
a decision to collect funds from the accounts/electronic wallets of such a taxpayer in banks, non-bank payment service providers/electronic money issuers is a demand of the collector to the debtor, which is subject to immediate and mandatory execution by initiating a transfer in the payment system according to the rules of the relevant payment system;
{ Item 95.5 of Article 95 supplemented by the fourth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2888-IX of 12.01.2023 }
The decision to collect cash is served on such taxpayer and is the basis for collection.
{ Item 95.5 of Article 95 is supplemented by the fifth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
Cash collection is carried out in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
{ Item 95.5 of Article 95 is supplemented by the sixth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
95.6. If the amount of funds received as a result of the sale of a taxpayer's property exceeds the amount of his monetary obligation and tax debt, the difference shall be transferred to the accounts of such taxpayer or his successors.
95.7. The sale of a taxpayer's property is carried out at public auctions and/or through trading organizations.
The sale of a taxpayer's property at public auction is carried out in the following order:
95.7.1. property that can be grouped and standardized shall be subject to sale for money exclusively at stock exchanges conducted by exchanges established in accordance with the law.
The offer for each sale of collateral is sent to all exchanges that have a license to carry out activities to organize trade in products on commodity exchanges.
The supervisory authority concludes a corresponding agreement with the exchange that offered the lowest cost of services for the sale of collateral;
{Subparagraph 95.7.1 of paragraph 95.7 of Article 95 as amended by Law No. 3603-IX of 23.02.2024 }
95.7.2. securities - on organized capital markets in accordance with the procedure established by the Law of Ukraine "On Capital Markets and Organized Commodity Markets";
{Subparagraph 95.7.2 of paragraph 95.7 of Article 95 as amended by Law No. 3603-IX of 02/23/2024 }
95.7.3. other property, movable or immovable property, as well as single property complexes of enterprises are subject to sale for funds exclusively at targeted auctions, which are organized upon the submission of the relevant regulatory authority on the specified exchanges.
95.8. Perishable property, as well as other property, the volume of which is insufficient for organizing public auctions, shall be sold for money on commission terms through trade organizations determined by the regulatory authority on a competitive basis.
The debtor's property, the circulation of which is subject to restrictions by law, is sold at closed auctions, which are held on a competitive basis. Such closed auctions are attended by persons who, in accordance with the law, may own the said property or have other property rights.
95.9. If the sale is subject to a single property complex of an enterprise, the property of which is in state or municipal ownership, or if, according to the legislation on privatization, the alienation of the enterprise's property requires the prior consent of the privatization body or another state body authorized to manage corporate rights, the sale of the property of such an enterprise shall be organized by the state privatization body upon submission of the relevant supervisory body in compliance with the legislation on privatization. In this case, other methods of privatization, except for monetary, are not permitted.
The state privatization body is obliged to organize the sale of a single property complex within 60 calendar days from the date of receipt of the submission by the regulatory body.
95.10. In order to sell property that is subject to tax lien, an expert assessment of the value of such property shall be conducted to determine its initial sale price. Such assessment shall be conducted in accordance with the procedure established by the Law of Ukraine "On the Assessment of Property, Property Rights and Professional Appraisal Activities in Ukraine" .
95.11. Property that can be grouped or standardized or has a current exchange value and/or is listed on commodity exchanges is not assessed.
95.12. The taxpayer has the right to independently carry out the assessment by concluding a contract with an appraiser. If the taxpayer does not independently carry out the assessment within one month from the date of the decision to sell the property, the supervisory authority shall independently conclude a contract for the assessment of the property.
{ Clause 95.12 of Article 95 as amended by Law No. 466-IX of 16.01.2020 }
95.13. During the sale of property on commodity exchanges, the regulatory authority shall conclude a corresponding agreement with a member of the commodity exchange, who shall perform actions to sell such property on behalf of the regulatory authority on the terms of the best price offer.
{ Clause 95.13 of Article 95 as amended by Law No. 3603-IX of 23.02.2024 }
95.14. The buyer of property that is subject to tax lien acquires ownership of such property in accordance with the terms and conditions specified in the purchase and sale agreement concluded based on the results of the auction.
A property purchase and sale agreement concluded based on the results of the auction must be signed by the taxpayer - the debtor, whose property was sold at auction.
{ Item 95.5 of Article 95 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
In the event of the debtor's refusal to sign the purchase and sale agreement, such agreement shall be signed by the head (his deputy or authorized person) of the supervisory authority on whose behalf the sale of the property was carried out, in the presence of at least two witnesses.
{ Item 95.5 of Article 95 is supplemented by the third paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
{ Clause 95.14 of Article 95 as amended by Law No. 1797-VIII of 21.12.2016 }
95.15. The procedure for increasing or decreasing the initial sale price of a taxpayer's property shall be determined by the Cabinet of Ministers of Ukraine, except for the cases specified in paragraph 95.9 of this Article, which are regulated by the legislation on privatization.
95.16. Information on the composition of taxpayers' property intended for sale shall be published by the relevant stock exchange. Compensation for expenses related to the organization and conduct of auctions for the sale of taxpayers' property subject to tax lien and payment for banking services for transferring funds to the relevant budget shall be carried out in accordance with the procedure determined by the Cabinet of Ministers of Ukraine, at the expense of funds received from the sale of such property and at the expense of collected funds.
{Clause 95.16 of Article 95 as amended by Law No. 4834-VI of 24.05.2012 }
95.17. Information on the time and conditions for public auctions of taxpayers' property is published by the relevant exchange.
95.18. The information specified in paragraph 95.17 of this Article and the procedure for its publication shall be determined by the Cabinet of Ministers of Ukraine.
95.19. A taxpayer or any other person who manages the taxpayer's property or controls its use shall be obliged to ensure, upon first request, unhindered access of the tax administrator and participants in public auctions to inspect and evaluate the property offered for sale, as well as unhindered acquisition of ownership rights to such property by the person who purchased it at a public auction.
95.20. If the taxpayer at any time before the conclusion of the contract of sale of his property fully repays the amount of the tax debt, the regulatory authority shall cancel the decision to conduct its sale and take measures to suspend the auction.
95.21. Transactions for the sale of property specified in this article at stock exchanges and auctions are not subject to notarial certification.
{Clause 95.21 of Article 95 as amended by Law No. 3609-VI of 07.07.2011 }
95.22. The supervisory authority shall apply to the court to recover from the debtors of a taxpayer who has a tax debt the amount of the receivables, the maturity of which has come and the right to claim which has been transferred to the supervisory authorities, for the purpose of repaying the tax debt of such taxpayer. The amount of funds received as a result of the recovery of the receivables shall be credited in full (but within the amount of the tax debt) to the relevant budget or state trust fund for the purpose of repaying the taxpayer's tax debt. The amount of the receivables recovered in excess of the amount of the tax debt shall be transferred to the taxpayer's disposal.
{Clause 95.23 of Article 95 was excluded on the basis of Law No. 5083-VI of 05.07.2012 }
95.24. If the amount of funds received as a result of the sale of the taxpayer's property is insufficient to repay the taxpayer's tax debt, the tax administrator shall carry out an additional inventory of the property in the form of a tax lien in accordance with the procedure specified in Article 89 of this Code.
{Article 95 was supplemented by paragraph 95.24 in accordance with Law No. 4834-VI of 24.05.2012 }
Article 96. Repayment of tax debt of state-owned enterprises not subject to privatization and municipal enterprises↑
96.1. If the amount of funds received from the sale of property of a municipal enterprise deposited in a tax lien does not cover the amount of its tax debt and expenses related to the organization and conduct of public auctions, or if such a debtor does not have his own property that, in accordance with the legislation of Ukraine, can be deposited in a tax lien and alienated, the regulatory body is obliged to apply to the local government body or executive body, to whose sphere of management the property of such a taxpayer belongs, with a submission on making a decision on:
96.1.1. allocation of funds from the local budget to pay the tax debt of such a taxpayer. The decision on financing such expenses shall be considered at the nearest session of the relevant council;
96.1.2. approval of a pre-trial rehabilitation plan for such a taxpayer, which provides for the repayment of his tax debt;
96.1.3. liquidation of such taxpayer and appointment of a liquidation commission;
96.1.4. adoption by the session of the relevant council of a decision to initiate bankruptcy proceedings against the taxpayer.
96.2. If the amount of funds received from the sale of property deposited in a tax lien of a state enterprise that is not subject to privatization, including a state-owned enterprise, does not cover the amount of tax debt of such a taxpayer and expenses related to the organization and conduct of public auctions, or in the absence of property that, in accordance with the legislation of Ukraine, can be deposited in a tax lien and alienated, the regulatory body is obliged to apply to the executive body to whose jurisdiction such a taxpayer belongs, with a submission regarding the adoption of a decision on:
96.2.1. provision of appropriate compensation from the budget at the expense of funds allocated for the maintenance of such an executive body to whose sphere of management such a taxpayer belongs;
96.2.2. pre-trial rehabilitation of such taxpayer at the expense of the state budget;
96.2.3. liquidation of such taxpayer and appointment of a liquidation commission;
96.2.4. exclusion of a taxpayer from the list of state-owned objects that are not subject to privatization in accordance with the law, for the purpose of initiating bankruptcy proceedings, in accordance with the procedure established by the legislation of Ukraine.
96.3. The response regarding the adoption of one of the decisions specified in paragraphs 96.1 and 96.2 of this article shall be sent to the supervisory authority within 30 calendar days from the date of sending the application.
{Paragraph one of clause 96.3 of Article 96 as amended by Law No. 5503-VI of 20.11.2012 }
In the event of failure to receive the specified response within the period specified in this paragraph or receiving a response refusing to satisfy its requirements, the regulatory authority shall be obliged to apply to the court with a statement of claim for the collection of the tax debt from the funds of the state body or local government body under whose management such state (municipal) enterprise or its property is located.
{Paragraph two of clause 96.3 of Article 96 as amended by Law No. 5503-VI of 20.11.2012 }
96.4. The occurrence of a tax debt at a state or municipal enterprise is grounds for terminating an employment agreement (contract) with the head of such an enterprise.
96.5. Employment agreements (contracts) concluded with the head of a state or municipal enterprise must contain provisions on the specified liability, which is their essential condition.
The provisions of this paragraph do not apply to cases of tax debt arising as a result of force majeure circumstances or failure or improper fulfillment by state bodies of obligations to pay for goods (works, services) purchased from such a taxpayer at the expense of budget funds, to provide the taxpayer with subsidies or grants provided for by law, or to return to the taxpayer excessively paid taxes and fees or their budget reimbursement in accordance with this Code and the tax legislation of Ukraine.
96.6. Any agreements on the transfer of shares (other corporate rights) that are in state or municipal ownership to third parties for management must contain obligations of such third parties to prevent the occurrence of a tax debt after such transfer, as well as a condition on the termination of the agreement in the event of the occurrence of a tax debt, the right of the state or territorial community, respectively, to unilaterally (out of court) terminate such agreements in the event of the occurrence of such a tax debt.
{Clause 96.6 of Article 96 as amended by Law No. 5083-VI of 05.07.2012 }
Article 97. Repayment of monetary obligations or tax debt in the event of liquidation of a taxpayer not related to bankruptcy↑
97.1. In this article, the liquidation of a taxpayer means the liquidation of a taxpayer as a legal entity or the state registration of the termination of the entrepreneurial activity of an individual or the registration with the relevant authorized body of the termination of the independent professional activity of an individual (if such registration was a condition for conducting independent professional activity), as a result of which their accounts/electronic wallets are closed and/or their status as a taxpayer is lost in accordance with the legislation.
{Clause 97.1 of Article 97 as amended by Laws No. 657-VII of 10/24/2013 , No. 3813-IX of 06/18/2024 }
97.2. If the owner or a body authorized by him makes a decision on the liquidation of a taxpayer not related to bankruptcy, the property of the specified taxpayer shall be used in the order determined in accordance with the laws of Ukraine.
97.3. If, as a result of the liquidation of a taxpayer, a part of its monetary obligations or tax debt remains unpaid due to insufficient property, such part shall be repaid at the expense of the property of the founders or participants of such an enterprise, if they bear full or additional liability for the taxpayer's obligations in accordance with the law, within the limits of full or additional liability, and in the event of the liquidation of a branch, department or other separate subdivision of a legal entity - at the expense of the legal entity, regardless of whether it is the payer of the tax in respect of which the monetary obligation arose or the tax debt of such branch, department or other separate subdivision arose.
{Paragraph one of clause 97.3 of Article 97 as amended by Law No. 657-VII of 24.10.2013 }
In the event of state registration of the termination of an individual's entrepreneurial activity or registration with the relevant authorized body of the termination of an individual's independent professional activity (if such registration was a condition for conducting independent professional activity), repayment of monetary obligations and/or tax debt is carried out at the expense of the property of the specified individual.
{Clause 97.3 of Article 97 is supplemented with a new paragraph in accordance with Law No. 657-VII of 24.10.2013 }
In other cases, monetary obligations or tax debt that remain unpaid after the liquidation of the taxpayer are considered bad debt and are subject to write-off in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
{Paragraph three of clause 97.3 of Article 97 as amended by Law No. 657-VII of 24.10.2013 }
97.4. The person responsible for the repayment of monetary obligations or tax debt of a taxpayer is:
97.4.1. in relation to a taxpayer being liquidated - the liquidation commission or other body conducting the liquidation in accordance with the legislation of Ukraine;
97.4.2. with regard to branches, offices, other separate divisions of a taxpayer that are being liquidated - such taxpayer;
97.4.3. in relation to a natural person - an entrepreneur or a natural person who carries out independent professional activities - such a natural person;
{Subclause 97.4.3 of Clause 97.4 of Article 97 as amended by Law No. 657-VII of 24.10.2013 }
97.4.4. in relation to an individual who has died or been declared missing by a court or declared deceased or recognized as legally incompetent - persons who inherit or are authorized to dispose of the property of such person;
97.4.5. in relation to cooperatives, credit unions or other collective farms - their members (shareholders) jointly and severally;
{Subclause 97.4.5 of clause 97.4 of Article 97 as amended by Law No. 3609-VI of 07.07.2011 }
97.4.6. in relation to investment funds - an investment company that manages such an investment fund.
97.5. If a taxpayer being liquidated has amounts of overpaid monetary obligations or amounts of unreimbursed taxes from the relevant budget, such amounts shall be offset against its monetary obligations or tax debt to such budget.
97.6 If the amounts of overpaid monetary obligations or amounts of unreimbursed taxes from the relevant budget exceed the amounts of monetary obligations or tax debt to such budget, the excess amounts shall be used to repay monetary obligations or tax debt to other budgets, and in the absence of such obligations (debt) shall be transferred to the disposal of such taxpayer. The procedure for carrying out the offsets specified in this paragraph shall be established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 97.6 of Article 97 as amended by Law No. 1797-VIII of 21.12.2016 }
Article 98. Procedure for repayment of monetary obligations or tax debt in the event of reorganization of a taxpayer or transfer of a single property complex of a state or municipal enterprise for lease or concession, or sale of a single property complex of a state or municipal enterprise in the process of privatization
{Title of Article 98 as amended by Law No. 4057-VI of 11/17/2011 ; as amended by Law No. 2719-IX of 11/03/2022 ; as amended by Law No. 3813-IX of 06/18/2024 }
98.1. Reorganization of a taxpayer in this article means a change in its legal status, which involves any of the following actions or a combination thereof:
98.1.1. for business companies - a change in the organizational and legal status of the company, which entails a change in the code according to the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations;
{Subclause 98.1.1 of Clause 98.1 of Article 98 as amended by Laws No. 3609-VI of 07.07.2011 , No. 466-IX of 16.01.2020 }
98.1.2. merger of taxpayers, namely the transfer of the taxpayer's property to the authorized capitals of other taxpayers, resulting in the liquidation of the taxpayer merging with others;
98.1.3. division of a taxpayer into several persons, namely the division of its property between the authorized capitals of newly formed legal entities and/or individuals, as a result of which the legal status of the taxpayer being divided is liquidated;
98.1.4. separation of other taxpayers from the taxpayer, namely the transfer of part of the property of the taxpayer being reorganized to the authorized capitals of other taxpayers, which are created by the owners of the corporate rights of the taxpayer being reorganized, and as a result of which the taxpayer being reorganized does not liquidate;
{Subclause 98.1.4 of clause 98.1 of Article 98 as amended by Law No. 71-VIII of 28.12.2014 }
98.1.5. registration of an individual as a business entity without cancellation of its previous registration as another business entity or with such cancellation.
98.2. If the owner of a taxpayer or a body authorized by him makes a decision to reorganize such a taxpayer or the single property complex of a state or municipal enterprise is leased or concessioned, or the single property complex of a state or municipal enterprise is sold, monetary obligations or tax debt shall be settled in the following manner:
{Paragraph one of clause 98.2 of Article 98 as amended by Law No. 4057-VI of 17.11.2011 ; as amended by Law No. 2719-IX of 03.11.2022 }
98.2.1. if the reorganization is carried out by changing the name, organizational and legal status or place of registration of the taxpayer, after the reorganization it acquires all rights and obligations to repay monetary obligations or tax debt that arose before its reorganization;
98.2.2. if the reorganization is carried out by merging two or more taxpayers into one taxpayer with the liquidation of the merged taxpayers, the merged taxpayer acquires all rights and obligations to repay the monetary obligations or tax debt of all merged taxpayers;
98.2.3. if the reorganization is carried out by dividing a taxpayer into two or more persons with the liquidation of such a taxpayer being divided, all taxpayers that arise after such reorganization acquire all rights and obligations to repay monetary obligations or tax debt that arose before such reorganization.
The specified obligations or debt are distributed among the newly formed taxpayers in proportion to the shares of the book value of the property received by them in the reorganization process in accordance with the distribution balance sheet.
If one or more newly formed persons are not taxpayers in respect of whom monetary obligations or a debt of a taxpayer who has been reorganized arose, the said monetary obligations or tax debt shall be fully distributed among the persons who are payers of such taxes, in proportion to the shares of property received by them, without taking into account the property provided to persons who are not payers of such taxes.
98.2.4. in the event of the transfer of a single property complex of a state or municipal enterprise for lease or concession, the taxpayer - the lessee or concessionaire, after accepting the single property complex of the state or municipal enterprise for lease or concession, acquires all rights and obligations to repay monetary obligations or tax debt that arose in the state or municipal enterprise before the transfer of the single property complex for lease or concession;
{Clause 98.2 of Article 98 is supplemented by subparagraph 98.2.4 in accordance with Law No. 4057-VI of 17.11.2011 ; as amended by Law No. 2719-IX of 03.11.2022 }
98.2.5. in the event of the sale in the process of privatization of a single property complex of a state or municipal enterprise, the buyer acquires all rights and obligations to repay the tax debt of the state or municipal enterprise that remained outstanding at the time of transfer of ownership of the privatization object.
In the event that the buyer repays the tax debt in full and within the period specified in the purchase and sale agreement, but no later than six calendar months from the date of transfer of ownership of the privatization object, the penalties and interest provided for in Articles 124 and 129 of this Code shall not be applied (not accrued) to such paid amounts, and those applied (accrued) shall be subject to cancellation.
{Clause 98.2 of Article 98 is supplemented by subparagraph 98.2.5 in accordance with Law No. 2719-IX of 03.11.2022 }
98.3. Reorganization of a taxpayer by separating another taxpayer from its composition or contributing part of the taxpayer's property to the authorized capital of another taxpayer without liquidation of the taxpayer being reorganized shall not entail the distribution of monetary obligations or tax debt between such taxpayer and persons formed in the process of its reorganization, or the establishment of their joint and several liability for violation of tax legislation, except for cases when, according to the conclusions of the supervisory authority, such reorganization may lead to improper repayment of monetary obligations or tax debt by the taxpayer being reorganized. The decision to apply joint and several liability for violation of tax legislation may be made by the supervisory authority in the event that the property of the taxpayer being reorganized is under tax lien at the time of making the decision on such reorganization.
{Clause 98.3 of Article 98 as amended by Law No. 4057-VI of 17.11.2011 }
98.4. A taxpayer whose property is transferred as a tax pledge, or who has exercised the right to restructure a tax debt, is obliged to notify the supervisory authority in advance of the decision to carry out any types of reorganization and submit to the supervisory authority a plan for such reorganization. In the event that the supervisory authority establishes that the reorganization plan leads or may in the future lead to improper repayment of monetary obligations or tax debt, it has the right to make a decision on:
98.4.1. distribution of the amount of monetary obligations or tax debt between taxpayers arising as a result of the reorganization, taking into account the expected profitability (liquidity) of each such taxpayer without applying the principle of proportional distribution established by paragraphs 98.2 and 98.3 of this Article;
98.4.2. repayment of monetary obligations or tax debt secured by a tax lien prior to such reorganization;
98.4.3. establishing joint and several liability for payment of monetary obligations of the taxpayer undergoing reorganization in respect of all persons formed in the reorganization process, which entails the application of the tax lien regime in respect of all property of such persons;
98.4.4. extension of the right of tax lien to the property of a taxpayer created by merging other taxpayers, if one or more of them had monetary obligations or a tax debt secured by a tax lien.
98.5. Decisions of the supervisory authority adopted in accordance with paragraph 98.4 of this Article may be appealed in accordance with the procedure and within the time limits specified by this Code for appealing a monetary obligation assessed by the supervisory authority.
98.6. Conducting a reorganization in violation of the rules specified in paragraph 98.4 of this article shall entail liability established by law.
98.7. Reorganization of a taxpayer does not change the terms of repayment of monetary obligations or tax debt by taxpayers formed as a result of such reorganization.
98.8. If a taxpayer undergoing reorganization has overpaid monetary obligations, such amounts shall be offset against its outstanding monetary obligations or tax debt for other taxes. The specified amount shall be distributed between budgets and state special-purpose funds in proportion to the total amounts of monetary obligations or tax debt of such taxpayer.
98.9. If the amount of overpaid monetary obligations or unreimbursed taxes and fees of a taxpayer exceeds the amount of monetary obligations or tax debt from other taxes, the amount of the excess shall be transferred to the disposal of the legal successors of such taxpayer in proportion to his share in the property being distributed, in accordance with the distribution balance or transfer act, and in the case of receiving a single property complex of a state or municipal enterprise for lease or concession, the amount of the excess shall be transferred to the disposal of the taxpayer - the lessee or concessionaire in accordance with the transfer balance or act.
{Clause 98.9 of Article 98 as amended by Law No. 4057-VI of 17.11.2011 }
{Article 98 as amended by Law No. 3553-IX of 16.01.2024 ; text of Article 98 as amended by Law No. 3813-IX of 18.06.2024 }
Article 99. Procedure for fulfilling monetary obligations and/or repaying tax debt of an individual (including an individual entrepreneur, an individual engaged in independent professional activity) in the event of his/her death or recognition as missing or incapacitated, as well as of a minor/underage person
{Title of Article 99 as amended by Law No. 657-VII of 10/24/2013 }
99.1. Fulfillment of monetary obligations and/or repayment of tax debt of an individual (including an individual entrepreneur, an individual engaged in independent professional activity) in the event of his death or declaration of death by a court shall be carried out by his heirs who accepted the inheritance (except for the state), within the value of the property being inherited and in proportion to the share in the inheritance on the date of its opening.
{Paragraph one of clause 99.1 of Article 99 as amended by Law No. 657-VII of 24.10.2013 }
Claims against heirs are presented by the controlling bodies in the manner established by the civil legislation of Ukraine for the presentation of claims by the testator's creditors.
After the expiration of the term for accepting the inheritance, the testator's monetary obligations and/or tax debt become the monetary obligations and/or tax debt of the heirs.
During the term of acceptance of the inheritance, no penalty is charged on the testator's monetary obligations and/or tax debt.
In the event of the transfer of inheritance to the state, the monetary obligations of the deceased individual cease.
99.2. Monetary obligations of minors/underage persons shall be fulfilled by their parents (adoptive parents), guardians (trustees) until the minors/underage persons acquire full civil capacity.
Parents (adoptive parents) of minors/underage children and minors/underage children in the event of failure to fulfill the minors/underage children's financial obligations shall bear joint and several property liability for the repayment of financial obligations and/or tax debt.
99.3. The fulfillment of monetary obligations and/or repayment of tax debt of an individual (including an individual entrepreneur, an individual engaged in independent professional activity) who has been declared incompetent by a court shall be carried out by his guardian at the expense of the property of such individual in accordance with the procedure established by this Code.
{Paragraph one of clause 99.3 of Article 99 as amended by Law No. 657-VII of 24.10.2013 }
The guardian of an incapacitated person fulfills the monetary obligations that arose on the day of recognition of the incapacitated person and/or repays the tax debt at the expense of the property of such an individual that may be subject to seizure in accordance with the law.
{Paragraph two of clause 99.3 of Article 99 as amended by Law No. 657-VII of 24.10.2013 }
99.4. Fulfillment of monetary obligations and/or repayment of tax debt of an individual (including an individual entrepreneur, an individual engaged in independent professional activity) who is recognized by the court as missing, shall be carried out by the person who, in accordance with the established procedure, is entrusted with the custody of the property of the missing person.
{Paragraph one of clause 99.4 of Article 99 as amended by Law No. 657-VII of 24.10.2013 }
The person who exercises custody over the property of a missing person shall fulfill the monetary obligations that arose on the day of his/her recognition as missing and/or repay the tax debt at the expense of the property of such an individual, which may be subject to seizure in accordance with the law.
{Paragraph two of clause 99.4 of Article 99 as amended by Law No. 657-VII of 24.10.2013 }
99.5. Parents (adoptive parents) and guardians (trustees) of minors, guardians of incapacitated persons, persons entrusted with the custody of the property of missing persons (legal representatives of taxpayers - individuals), must, on behalf of the relevant individuals:
99.5.1. submit, if there are grounds, an application to the regulatory authority for registration of such individuals in the State Register of Individual Taxpayers and, in cases provided for by this Code, other information necessary for maintaining the specified State Register;
99.5.2. submit duly completed income and property declarations in a timely manner;
99.5.3. in cases provided for by this Code, keep records of income and expenses;
99.5.4. to perform other duties specified in this Code.
99.6. Legal representatives of taxpayers - individuals shall bear the liability provided for by this Code and other laws for taxpayers for failure to fulfill the obligations specified in paragraph 99.5 of this article.
99.7. If the property of an incapacitated or missing person is insufficient to ensure the fulfillment of monetary obligations and/or repayment of the tax debt of such an individual, as well as to pay the accrued fines (financial) sanctions, the amounts of the tax debt are written off in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 99.7 of Article 99 as amended by Laws No. 657-VII of 10/24/2013 , No. 1797-VIII of 12/21/2016 }
99.8. In the event of a court cancelling a decision to declare an individual missing or making a decision to restore the civil capacity of an individual who was declared incapacitated, the monetary obligation of such an individual shall be restored in the amount of taxes written off in accordance with clause 99.7 of this article. Penalty (financial) sanctions in such a case shall not be paid for the period from the date of entry into force of the court decision to declare an individual missing or incapacitated until the date of entry into force of the decisions to cancel the decision to declare an individual missing or to restore the civil capacity of an individual.
{Text of Article 99 as amended by Law No. 657-VII of 24.10.2013 }
Article 100. Installment and deferral of monetary obligations or tax debt of a taxpayer↑
100.1. Installment, deferral of monetary obligations or tax debt is the postponement of the payment terms by a taxpayer of his monetary obligations or tax debt with interest, the amount of which is equal to 120 percent of the annual discount rate of the National Bank of Ukraine, effective on the day the supervisory authority makes a decision on installment, deferral of monetary obligations or tax debt.
{Paragraph one of item 100.1 of Article 100 as amended by Law No. 1797-VIII of 21.12.2016 }
If the installment (deferred) amount includes a penalty, then the amount minus the penalty is taken to calculate interest.
100.2. A taxpayer has the right to apply to the supervisory authority with an application for installment and deferral of monetary obligations or tax debt. A taxpayer who applies to the supervisory authority with an application for installment or deferral of monetary obligations is considered to have agreed on the amount of such monetary obligation.
100.3. Installment and deferral of monetary obligations or tax debt within the framework of the procedure for restoring the debtor's solvency shall be carried out in accordance with the bankruptcy legislation.
100.4. The basis for the installment of monetary obligations or tax debt of a taxpayer is the provision by him of sufficient evidence of the existence of circumstances, the list of which is determined by the Cabinet of Ministers of Ukraine, indicating the presence of a threat of the emergence or accumulation of tax debt of such taxpayer, as well as economic justification indicating the possibility of repayment of monetary obligations and tax debt and/or an increase in tax revenues to the relevant budget as a result of the application of the installment regime, during which changes in the production or sales management policy of such taxpayer will occur.
100.5. The basis for deferring monetary obligations or tax debt of a taxpayer is the provision by him of evidence, the list of which is determined by the Cabinet of Ministers of Ukraine, indicating the presence of force majeure circumstances that led to the threat of the emergence or accumulation of tax debt of such taxpayer, as well as economic justification indicating the possibility of repayment of monetary obligations or tax debt and/or an increase in tax revenues to the relevant budget as a result of the application of the deferral regime, during which changes in the production or sales management policy of such taxpayer will occur.
100.6. Installment amounts of monetary obligations or tax debt (including separately - amounts of fines (financial) sanctions) shall be repaid in equal installments starting from the month following the month in which the decision to grant such an installment is made.
100.7. Deferred amounts of monetary obligations or tax debt shall be repaid in equal installments starting from any month determined by the relevant supervisory authority or relevant local government authority, which, in accordance with paragraph 100.8 of this Article, approves a decision on the installment or deferral of monetary obligations or tax debt, but no later than the end of 12 calendar months from the date of the occurrence of such monetary obligation or tax debt, or once in full.
100.8. A decision on the installment payment, deferral of monetary obligations or tax debt, as well as on the postponement of the payment terms of installment, deferred amounts or their portion, shall be made in the following order:
in relation to state taxes and fees - by the head (his deputy or authorized person) of the supervisory authority, taking into account the features specified in paragraph 100.9 of this article;
regarding local taxes and fees - by the head (his deputy or authorized person) of the controlling body and approved by the financial body of the local executive body, to the budget of which such local taxes and fees are included.
{ Clause 100.8 of Article 100 as amended by Law No. 1797-VIII of 21.12.2016 }
100.9. The decision to defer or postpone payment of monetary obligations or tax debt, as well as to postpone the payment deadlines for deferred or deferred amounts or their share in respect of state taxes and fees for a period exceeding one and/or more budget years, except for the cases provided for in this paragraph, shall be made by the head (his deputy or an authorized person) of the central executive body implementing state tax policy, which shall be notified to the central executive body ensuring the formation and implementation of state financial policy.
The decision to defer, postpone monetary obligations or tax debt, as well as to postpone the payment terms of deferred, deferred amounts or their share in respect of state taxes and fees for a period exceeding one and/or more budget years, if the amount declared for installment, postponement, or the amount of deferred, deferred monetary obligations or tax debt for which payment terms are postponed is 10 million hryvnias or more, is made by the head (his deputy or authorized person) of the central executive body implementing state tax policy, in agreement with the central executive body ensuring the formation and implementation of state financial policy.
{Paragraph two of item 100.9 of Article 100 as amended by Law No. 466-IX of 16.01.2020 }
The decision to defer or postpone payment of monetary obligations or tax debt, as well as to postpone the payment terms of deferred or deferred amounts, if the amount of the previously granted installment, deferment of monetary obligations or tax debt has not been repaid, is made by a motivated and substantiated decision of the head (deputy head) of the central executive body that ensures the formation and implementation of state financial policy.
{Clause 100.9 of Article 100 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Laws No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 }
100.10. The central executive body implementing state tax policy shall form and maintain a publicly accessible Register of applications for installments, deferral of monetary obligations or tax debt, which it shall publish daily on its official website.
The following data is entered into the specified register for each of the submitted applications:
taxpayer name and code according to the Unified State Register of Taxpayers (for legal entities) or the registration number of the taxpayer's registration card (for individuals) or the series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have officially notified the relevant regulatory authority about this and have a mark in their passport);
date of submission of an application for installment payment, deferral of monetary obligations or tax debt;
type of application (for installments, deferral of monetary obligations or tax debt);
the amount of the monetary obligation or tax debt declared for installments or deferral;
type of tax/fee, monetary obligation or tax debt for which installment or deferral is applied for;
the decision of the supervisory authority based on the results of consideration of the application, the number and date of such decision;
date and number of the agreement on installment payment, deferral of a monetary obligation or tax debt;
the term of the agreement on installment payments, deferral of a monetary obligation or tax debt;
the value of the property transferred as a tax lien.
Applications for installment payment, deferral of a monetary obligation or tax debt are entered into the Register of Applications for Installment Payment, Deferral of a Monetary Obligation or Tax Debt during the business day of their receipt in the chronological order of their receipt.
The procedure for maintaining and the form of the Register of applications for installments, deferral of monetary obligations or tax debt are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 100.10 of Article 100 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 1797-VIII of 21.12.2016 }
100.11. Installment, deferral of a monetary obligation or tax debt is provided separately for each tax and fee.
If the amount of the monetary obligation or tax debt declared for installment or deferral is 1 million hryvnia or more, installment or deferral is granted only on the condition that:
transfer of property of a taxpayer as a tax pledge, the book value of which is equal to or exceeds the amount of the monetary obligation declared before the installment or deferral, - in the case of installment or deferral of monetary obligations;
the taxpayer's property being subject to tax lien, the book value of which is equal to or exceeds the amount of tax debt declared before installment or deferral, - in the case of installment or deferral of tax debt.
The payment terms for installments, deferred amounts or their parts may be postponed by adopting a separate decision and making appropriate amendments to the installment, deferral agreements.
{ Clause 100.11 of Article 100 as amended by Law No. 1797-VIII of 21.12.2016 }
100.12. Installment agreements (deferrals) may be terminated early:
100.12.1. at the initiative of the taxpayer - upon early repayment of the installment amount of a monetary obligation and tax debt or the deferred amount of a monetary obligation or tax debt for which an agreement on installment or deferral was reached;
100.12.2. on the initiative of the supervisory authority in the event that:
it was found that the information provided by the taxpayer when concluding the specified contracts was unreliable, distorted or incomplete;
the taxpayer is recognized as having a tax debt from monetary obligations that arose after the conclusion of the specified agreements;
the taxpayer violates the terms of repayment of an installment payment obligation or tax debt or a deferred payment obligation or tax debt.
100.13. The procedure for installment and deferral of monetary obligations or tax debt of a taxpayer is established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 100.13 of Article 100 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
100.14. Installment or deferral of tax debt does not release the taxpayer's property from tax lien.
100.15. Taxpayers in respect of whom (and/or in respect of their founders (participants), ultimate beneficial owners) in accordance with the procedure established by the Law of Ukraine "On Sanctions", decisions have been made to apply special economic and other restrictive measures (sanctions), during the period of application of such sanctions, they do not have the right to receive installments (deferrals) of monetary obligations (tax debt), as well as to postpone the terms of payment of installments (deferred) amounts.
{Paragraph one of clause 100.15 of Article 100 as amended by Law No. 3813-IX of 18.06.2024 }
Installment (deferral) payments of monetary obligations (tax debt) of taxpayers in respect of whom (and/or in respect of founders (participants), ultimate beneficial owners of whom) as of the date of adoption of the decision to apply special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions", the term of the agreement on installment payment, deferral of monetary obligation or tax debt has not expired, shall remain in force in the absence of grounds for termination of the agreement on installment payment, deferral of monetary obligations (tax debt) specified in this article.
{Paragraph two of clause 100.15 of Article 100 as amended by Law No. 3813-IX of 18.06.2024 }
{ Article 100 supplemented by paragraph 100.15 in accordance with Law No. 3317-IX of 10.08.2023 }
101.1. Bad tax debt, including interest and penalties accrued on such tax debt, shall be subject to write-off.
101.2. The term "hopeless" means:
101.2.1. tax debt of a taxpayer recognized as bankrupt in accordance with the established procedure, the requirements for which were not satisfied due to the insufficiency of the bankrupt's property;
101.2.2. tax debt of an individual who:
is declared legally incompetent, missing or declared deceased, in the event of insufficient property that can be seized in accordance with the law;
died, in case of insufficient property, which can be seized in accordance with the law;
has been wanted for more than 720 days;
101.2.3. tax debt of a taxpayer, including a tax agent, in respect of which the limitation period established by paragraph 102.4 of Article 102 of this Code has expired;
{ Subparagraph 101.2.3 of paragraph 101.2 of Article 101 as amended by the Law No. 466-IX dated 16.01.2020 }
101.2.4. tax debt of a taxpayer that arose as a result of force majeure circumstances;
101.2.5. tax debt of a taxpayer for which a record of its termination has been entered in the State Register based on a court decision;
{Subclause 101.2.5 of clause 101.2 of Article 101 as amended by Laws No. 5519-VI of 06.12.2012 , No. 466-IX of 16.01.2020 }
101.2.6. tax debt of a bank for which there is a decision of the Deposit Guarantee Fund of Individuals on approval of the report on the completion of the bank's liquidation or a decision of the National Bank of Ukraine on approval of the liquidation balance sheet, adoption of the liquidator's final report and completion of the liquidation procedure.
{ Clause 101.2 of Article 101 is supplemented by subparagraph 101.2.6 in accordance with Law No. 466-IX of 16.01.2020 }
101.3. If an individual who is declared missing or declared deceased in court appears or if an individual who has been wanted for more than 720 days is found, the written-off debt of such individuals shall be restored and collected in the general procedure, subject to the statute of limitations starting from the date of restoration of such tax debt.
101.4. Collection authorities shall revoke payment instructions that provide for the collection of fines, penalties and bad tax debt written off in accordance with this Code.
{Clause 101.4 of Article 101 as amended by Law No. 2888-IX of 12.01.2023 }
101.5. Controlling bodies shall write off bad tax debts on a quarterly basis. The procedure for such write-off shall be established by the central executive body responsible for the formation and implementation of state financial policy.
{Clause 101.5 of Article 101 as amended by Law No. 1797-VIII of 21.12.2016 }
Article 102. Limitation periods and their application↑
102.1. The controlling body, except for the cases specified in clause 102.2 of this Article, has the right to conduct an inspection and independently determine the amount of the taxpayer's monetary obligations in the cases specified in this Code, no later than the expiration of 1095 days (2555 days - in the case of conducting an inspection in accordance with Articles 39 and 39 - 2 , applying the requirements of clause 141.4 of Article 141 of this Code), which follows the last day of the deadline for submitting a tax return , a report on the use of income (profits) of a non-profit organization specified in clause 133.4 of Article 133 of this Code, and/or the deadline for paying monetary obligations assessed by the controlling body, and if such a tax return was submitted later, - on the day of its actual submission. If, within the specified period, the regulatory authority does not determine the amount of monetary obligations, the taxpayer is considered free from such monetary obligation (including from the accrued penalty), and the dispute regarding such declaration and/or tax notice is not subject to administrative or judicial review.
{Paragraph one of clause 102.1 of Article 102 as amended by Law No. 3721-IX of 21.05.2024 }
In the event that a taxpayer submits a clarifying calculation to a tax return or a clarifying declaration, the controlling body has the right to determine the amount of tax liabilities, within the scope of the submitted clarifications, under such tax return within 1095 days (2555 days - in the event of an inspection in accordance with Articles 39 and 39-2 , applying the requirements of Clause 141.4 of Article 141 of this Code) from the date of submission of the clarifying calculation (declaration).
{Paragraph two of clause 102.1 of Article 102 as amended by Law No. 3721-IX of 21.05.2024 }
If, as a result of the inspection, violations of other tax legislation requirements not directly related to the declaration of tax obligations by the taxpayer, as well as violations of other legislation requirements, other than tax legislation, the control over compliance with which is entrusted to the regulatory authorities, are detected, the regulatory authority, except for the cases specified in paragraph 102.2 of this Article, has the right to independently determine the amount of penalties (financial sanctions, fines) for the taxpayer no later than 1095 days from the date of the relevant offense.
For local taxes and/or fees for which an annual tax return is required , the controlling body, except for the cases specified in clause 102.2 of this Article, has the right to independently determine the amount of monetary obligations based on the results of the audit, if it detects, based on the results of the audit, an underestimation of the amount of the tax liability determined by the taxpayer for these taxes, no later than the end of the 1095th day following the last day of the deadline for payment of these taxes, specified in the relevant sections of this Code.
{Clause 102.1 of Article 102 as amended by Laws No. 72-VIII of 28.12.2014 , No. 652-VIII of 17.07.2015 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 , taking into account the amendments made by Law No. 1117-IX of 17.12.2020 }
102.2. A monetary obligation may be assessed or proceedings in a case for the collection of such tax may be initiated without observing the limitation period specified in the first paragraph of paragraph 102.1 of this Article, if:
{Clause 102.2 of Article 102 as amended by Law No. 3609-VI of 07.07.2011 }
102.2.1. a tax return for the period during which the tax liability arose was not filed;
102.2.2. an official of the taxpayer (an individual taxpayer) has been convicted of evading payment of the specified monetary obligation or a decision has been made in criminal proceedings to close it on non-rehabilitative grounds, which has entered into legal force.
The supervisory authority has the right to conduct an inspection of compliance with the requirements of Article 39-3 of this Code by financial agents and account holders and to determine the amount of penalties (financial sanctions, fines) in the cases and amounts specified by this Code, no later than 1825 days following the last day of the deadline for submitting a report on accountable accounts, and if the relevant report was submitted later - on the day of its actual submission. The limitation period specified by this paragraph shall not apply to the inspection of a financial agent that has not submitted a report on accountable accounts for the reporting period in the manner specified by this Code.
{ Subparagraph 102.2.2 of paragraph 102.2 of Article 102 is supplemented by the second paragraph in accordance with Law No. 2970-IX of March 20, 2023 }
{Subclause 102.2.2 of Clause 102.2 of Article 102 as amended by Law No. 4652-VI of 13.04.2012 }
102.2 - 1. A monetary obligation may be assessed without observing the limitation period specified in paragraphs one and two of paragraph 102.1 of this Article, if a court verdict of conviction for committing a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine has entered into legal force in respect of the taxpayer or any person acting on his behalf and/or in his interests, and the consequence of such actions could be a reduction in the object of taxation and/or an underestimation of the tax liability determined in accordance with the requirements of this Code.
{Article 102 is supplemented by paragraph 102.2 - 1 in accordance with Law No. 4112-IX of 04.12.2024 }
102.3. The limitation period shall be suspended for any period during which:
102.3.1. the taxpayer is outside Ukraine if such stay is continuous and equal to or greater than 183 days;
102.3.2. the supervisory authority is prohibited by law and/or court decision from conducting an audit(s) of the taxpayer;
102.3.3. the supervisory authority has suspended, extended, or postponed the terms of the inspection in accordance with the procedure provided for in Articles 44 , 82 , and 85 of this Code or the Customs Code of Ukraine ;
102.3.4. the supervisory authority cannot conduct an inspection and independently determine the amount of the taxpayer's monetary obligations in connection with:
drawing up an act on the impossibility of conducting an inspection (except in the case of recognition of the actions for drawing up such an act as illegal);
by the taxpayer preventing officials of the controlling body from being inspected, provided that the controlling body complies with the following conditions:
a) specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, provided for in Article 81 of this Code;
b) specified in subparagraph 41.1.2 of paragraph 41.1 of Article 41 of this Code, provided for in Article 349 of the Customs Code of Ukraine;
by a taxpayer appealing in court the decision of the regulatory authority to conduct an inspection (except in cases where such a decision is declared unlawful and/or cancelled);
102.3.5. an administrative or judicial appeal is made by the taxpayer against the decision of the supervisory authority to assess a monetary obligation.
{Clause 102.3 of Article 102 as amended by Law No. 466-IX of January 16, 2020 }
102.4. If a monetary obligation is assessed by a controlling body before the expiration of the limitation period specified in clause 102.1 of this Article, the tax debt that arose in connection with the refusal to independently repay such monetary obligation may be collected within the next 1095 calendar days from the date of the tax debt, except for the cases provided for in paragraph three of clause 59.1 of Article 59 of this Code. If the payment is collected by a court decision, the collection terms shall be established until such payment is fully repaid or the debt is declared uncollectible.
{ Clause 102.4 of Article 102 as amended by the Law No. 1072-IX dated 04.12.2020 }
102.5. Applications for the return of overpaid monetary obligations or for their reimbursement in cases provided for by this Code may be submitted no later than the 1095th day following the date of occurrence of such overpayment or receipt of the right to such reimbursement.
{Clause 102.5 of Article 102 as amended by the Law No. 466-IX dated 16.01.2020 }
102.6. The deadlines for filing a tax return , a complaint for review of decisions of the regulatory authority, and an application for the return of overpaid monetary obligations shall be extended by the head (his deputy or authorized person) of the regulatory authority upon a written application by the taxpayer, if such taxpayer, within the specified periods:
{Paragraph one of clause 102.6 of Article 102 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
102.6.1. was outside Ukraine;
102.6.2. was sailing on sea vessels outside Ukraine as part of the team (crew) of such vessels;
102.6.3. was in prison pursuant to a court sentence;
102.6.4. had limited freedom of movement due to imprisonment or captivity in the territory of other states or due to other circumstances of force majeure, confirmed by documents;
102.6.5. was declared missing by a court decision or was wanted in cases provided for by law.
Penalties specified in this Code shall not apply during the extension of the deadlines for filing a tax return in accordance with this paragraph.
102.7. The effect of paragraph 102.6 of this article applies to:
102.7.1. taxpayers - individuals;
102.7.2. officials of a legal entity if, during the specified deadlines, such legal entity did not have other officials authorized in accordance with the legislation of Ukraine to calculate, collect and pay taxes to the budget, as well as to keep accounting records, prepare and submit tax reports.
102.8. The procedure for applying paragraphs 102.6-102.7 of this article shall be established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 102.8 of Article 102 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
{Clause 102.9 of Article 102 was excluded on the basis of Law No. 3219-IX of 06/30/2023 }
CHAPTER 10. APPLICATION OF INTERNATIONAL TREATIES AND REPAYMENT OF TAX DEBT AT THE REQUESTS OF COMPETENT AUTHORITIES OF FOREIGN STATES↑
Article 103. Procedure for applying the international treaty of Ukraine on the avoidance of double taxation regarding full or partial exemption from taxation of income of non-residents with a source of origin in Ukraine↑
103.1. The application of the rules of an international treaty of Ukraine is carried out by exempting from taxation income with a source of origin in Ukraine, reducing the tax rate, or by refunding the difference between the amount of tax paid and the amount that a non-resident must pay in accordance with an international treaty of Ukraine.
103.2. A person (tax agent) has the right to independently apply the exemption from taxation or the reduced tax rate provided for by the relevant international treaty of Ukraine at the time of payment of income to a non-resident, if such non-resident is the beneficial (actual) recipient (owner) of income (if the relevant condition is provided for by the international treaty) and is a resident of the country with which Ukraine has concluded an international treaty. In the case of receiving a syndicated financial loan, the person (tax agent) shall apply the tax rate provided for by the relevant international treaty of Ukraine on the date of payment of interest or other income received from sources in Ukraine to the members of the syndicate of creditors, taking into account the jurisdiction of which each member of the syndicated loan is a resident, and in proportion to his share within the credit agreement, provided that he is the beneficial (actual) recipient (owner) of income, regardless of whether the payment is made through an agent or directly.
{Paragraph one of clause 103.2 of Article 103 as amended by Laws No. 2245-VIII of 07.12.2017 , No. 466-IX of 16.01.2020 }
The application of an international treaty of Ukraine regarding exemption from taxation or the application of a reduced tax rate is permitted only if the non-resident provides the person (tax agent) with a document confirming the status of a tax resident in accordance with the requirements of paragraph 103.4 of this article.
Tax benefits in the form of exemption from taxation or application of a reduced tax rate, provided for by an international agreement, shall not be granted in respect of the relevant type of income or profit, if the main or predominant purpose of the relevant business transaction of a non-resident with a resident of Ukraine was the direct or indirect receipt of benefits provided by an international agreement in the form of exemption from taxation or application of a reduced tax rate. This rule shall not apply if it is established that receipt of such benefits corresponds to the object and purposes of the international agreement of Ukraine. If an international agreement, the consent to be bound by which has been granted by the Verkhovna Rada of Ukraine, establishes rules other than those provided for by this paragraph, the relevant rules of the international agreement shall apply.
{ Item 103.2 of Article 103 is supplemented by the third paragraph in accordance with Law No. 466-IX of January 16, 2020 }
If the recipient of income is a non-resident who is not the beneficial (actual) recipient (owner) of income, the application of an international treaty of Ukraine with the country of which the relevant beneficial (actual) recipient (owner) of such income is a resident is permitted, in terms of exemption from taxation or application of a reduced tax rate, provided that the person (tax agent) provides the following documents:
{ Item 103.2 of Article 103 is supplemented by the fourth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
a) from the recipient of income - a statement in any form stating that he does not have the status of a beneficial (actual) recipient (owner) of income, as well as the presence of such status in a non-resident who has provided the documents specified in subparagraph "b" of this paragraph;
{ Item 103.2 of Article 103 is supplemented by the fifth paragraph in accordance with Law No. 466-IX of 16.01.2020 }
b) from the beneficial (actual) recipient (owner) of income - a statement in any form about the presence of such a non-resident in the status of a beneficial (actual) recipient (owner) of income and documents confirming such status (in particular, but not exclusively, licenses, contracts, official letters from competent authorities), as well as a document confirming the status of a tax resident in accordance with the requirements of paragraph 103.4 of this article.
{ Item 103.2 of Article 103 is supplemented by the sixth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
103.3. The beneficial (actual) recipient (owner) of income for the purposes of applying a reduced tax rate in accordance with the rules of an international treaty of Ukraine to dividends, interest, royalties, fees, etc. of a non-resident received from sources in Ukraine (if the relevant condition is provided for by an international treaty) is considered to be a person who has the right to receive such income and is the beneficiary of it (has the right to actually dispose of such income).
In this case, the beneficial (actual) recipient (owner) of income is not a legal entity or individual, even if such a person has the right to receive income, but is an agent, a nominal holder (nominal owner) or performs only intermediary functions in relation to such income, which, in particular, may be evidenced by the following signs:
the specified person does not have sufficient authority or, in a case confirmed by facts and circumstances, does not have the right to use and dispose of such income, and/or
the specified person transfers the received income or a majority of it to another person, regardless of the method of registration of such transfer, and the specified person does not perform essential functions, does not use significant assets and does not bear significant risks in the transaction on such transfer, and/or the specified person does not have appropriate resources (qualified personnel, fixed assets in possession or use, sufficient equity, etc.) necessary for the actual performance of functions, use of assets and management of risks associated with obtaining the relevant type of income, which are only formally entrusted (used, accepted) to the specified person in connection with the transaction on such transfer.
If a non-resident - a direct recipient of income with a source of origin from Ukraine is not the beneficial (actual) recipient (owner) of such income, the provisions of the international treaty of Ukraine with the country whose resident is the relevant beneficial (actual) recipient (owner) of such income shall apply when paying such income. In the case provided for in this paragraph, the obligation to prove that a non-resident is the beneficial (actual) recipient (owner) of such income shall lie with such non-resident or with a non-resident who applies to the supervisory authority for a refund of the overwithheld tax.
For the purposes of applying this paragraph, in cases where resident cinematographers of Ukraine pay royalties to non-residents under sublicense agreements for the use or for granting the right to use audiovisual works (including films), as well as objects of copyright and/or related rights used in the production (creation) of audiovisual works (including films), such non-residents shall be considered beneficial (actual) recipients (owners) of such royalties.
{Clause 103.3 of Article 103 as amended by Law No. 2176-VIII of 07.11.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
103.4. The basis for exemption (reduction) from taxation of income with a source of origin in Ukraine is the submission by a non-resident, taking into account the features provided for in paragraphs 103.5 and 103.6 of this article, to the person (tax agent) who pays him income, of a certificate (or a notarized copy thereof) confirming that the non-resident is a resident of the country with which Ukraine has concluded an international treaty (hereinafter referred to as the certificate), as well as other documents, if this is provided for by an international treaty of Ukraine.
103.5. The certificate is issued by the competent (authorized) authority of the relevant country, determined by an international treaty of Ukraine, in a form approved in accordance with the legislation of the relevant country, and must be duly legalized and translated in accordance with the legislation of Ukraine.
103.6. If necessary, such a certificate may be requested from a non-resident by the person paying him income, or by the supervisory authority when considering the issue of returning the amounts of overpaid monetary obligations on another date preceding the date of payment of income.
If necessary, a person who pays income to a non-resident may contact the supervisory authority at his/her location (place of residence) regarding the central executive body implementing state tax policy's request to the competent authority of the country with which Ukraine has concluded an international agreement to confirm the information specified in the certificate.
{Paragraph two of clause 103.6 of Article 103 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
103.7. When legal entities - residents of Ukraine carry out transactions with foreign banks related to the payment of interest, confirmation of the fact that such a foreign bank is a resident of the country with which Ukraine has concluded an international agreement is not required if this is confirmed by an extract from the international catalog "International Bank Identifier Code" (SWIFT edition, Belgium International Organization for Standardization, Switzerland).
{Clause 103.7 of Article 103 as amended by Law No. 2245-VIII of 07.12.2017 }
103.8. A person who pays income to a non-resident in the reporting (tax) year, if the non-resident submits a certificate with information for the previous reporting tax period (year), may apply the rules of the international treaty of Ukraine, in particular regarding exemption (reduction) from taxation, in the reporting (tax) year with receipt of the certificate after the end of the reporting (tax) year.
103.9. A person who pays income to a non-resident is obliged, in the event of payments to non-residents of income originating from Ukraine in the reporting period (quarter), to submit to the regulatory body at its location (place of residence) a report on paid income, withheld and transferred to the budget taxes on non-resident income within the terms and in the form established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 103.9 of Article 103 as amended by Law No. 1797-VIII of 21.12.2016 }
103.10. If a non-resident fails to submit a certificate in accordance with paragraph 103.4 of this Article, the non-resident's income with a source of origin in Ukraine shall be subject to taxation in accordance with the legislation of Ukraine on taxation.
103.11. If a non-resident believes that an amount of tax has been withheld from his income that exceeds the amount due in accordance with the rules of an international treaty of Ukraine, consideration of the issue of reimbursement of the difference is carried out on the basis of submitting to the supervisory authority at the location (place of residence) of the person who paid the income to the non-resident and withheld tax from it, an application for a refund of the amount of tax on income with a source of origin in Ukraine.
The necessary documents are submitted by a non-resident or an official (authorized) person who must confirm their authority in accordance with the legislation of Ukraine.
103.12. The supervisory authority shall verify the compliance of the data specified in the application and supporting documents with the actual data and the relevant international treaty of Ukraine, as well as the fact of the transfer of the relevant tax amounts to the budget by the person who paid the income to the non-resident.
In case of confirmation of the fact of excessive withholding of tax amounts, the regulatory body shall make a decision on the return of the relevant amount to the non-resident, copies of which shall be provided to the person who withheld tax during the payment of income to the non-resident, and to the non-resident (authorized person). The conclusion on the return of the amounts of excessively paid tax shall be sent to the relevant body that carries out treasury services of budget funds.
In case of refusal to refund the tax amount, the regulatory authority is obliged to provide the non-resident (authorized person) with a reasoned response.
103.13. The body that carries out treasury services for budget funds, based on the conclusion of the controlling body, transfers funds in the amount specified in the conclusion to the account of the person who overwithheld tax from the non-resident's income.
103.14. A person who made a payment of income to a non-resident shall return to him the difference between the amount of tax that was withheld and the amount due for payment in accordance with an international treaty of Ukraine, after receiving a copy of the decision of the controlling body on the return of the amount of overpaid monetary obligations or after crediting the funds from the relevant body that carries out treasury services of budget funds.
The funds that, by decision of the supervisory authority, must be returned to the person who has withheld tax from the income of a non-resident in excess may be credited towards the payment of other tax obligations of such person upon his written application, which is submitted during the consideration of the non-resident's application for the return of the excess tax withheld. In this case, the conclusion on the return of the excess tax paid is not sent to the relevant authority that carries out treasury services of budget funds.
103.15. The central executive body that ensures the formation and implementation of state financial policy shall ensure the publication on its official website of the texts and/or translations of the texts of current international treaties of Ukraine containing provisions on the exchange of information for tax purposes, in the state language.
{ Article 103 supplemented by paragraph 103.15 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 104. Procedure for providing assistance in collecting tax debt in international legal relations↑
104.1. Assistance in collecting tax debt in international legal relations, under international treaties of Ukraine, shall be provided in accordance with the procedure provided for by this Code, taking into account the features specified in this article.
104.2. After receiving a document of a foreign state, according to which the amount of tax debt is collected in international legal relations, the supervisory authority shall, within thirty days, determine the compliance of such document with international treaties of Ukraine. In case of non-compliance of such document, it shall return it to the competent authority of the foreign state. If the specified document is recognized as compliant with international treaties of Ukraine, the supervisory authority shall send the taxpayer a tax notice in international legal relations in accordance with the procedure provided for in Article 42 of this Code.
104.3. Tax debt in international legal relations is transferred in hryvnia at the official exchange rate of hryvnia to foreign currency, determined by the National Bank of Ukraine on the day the tax notice is sent to such taxpayer.
Article 104 - 1. Procedure for providing assistance in collecting taxes in international legal relations at the request of a supervisory authority↑
104 - 1 .1. The provision by the competent authority of a foreign state, at the request of the supervisory authority, of assistance in collecting taxes on the basis of the relevant document specified in Articles 39 - 3 , 56 , 58 - 1 of this Code, shall be carried out in accordance with international treaties of Ukraine.
{Clause 104 - 1 .1 of Article 104 - 1 as amended by Law No. 2970-IX of 20.03.2023 }
104 - 1 .2. In order to collect the unpaid agreed amount of the taxpayer's monetary obligation, the supervisory authority, after the expiration of 90 calendar days from the date of sending the relevant document, shall apply to the competent authority of the foreign state of which such person is a resident, for the provision of administrative assistance in accordance with paragraph 104 - 1 .1 of this Article.
{The Code is supplemented by Article 104 - 1 in accordance with the Law No. 1525-IX dated 03.06.2021 }
Article 105. Reconciliation of the amount of tax debt in international legal relations↑
105.1. If a taxpayer believes that a tax debt in international legal relations, determined by a supervisory authority on the basis of a document of a foreign state, pursuant to which the amount of the tax debt is collected, is not true, such taxpayer has the right, within ten calendar days following the date of receipt of a tax notification in international legal relations on the determination of a tax debt in international legal relations, to submit a complaint to the competent authority of the foreign state through the supervisory authority for review of such decision.
105.2. During the period of appeal of the amount of a monetary obligation in international legal relations, such obligation cannot be a tax debt until the receipt of a final document on the assessment of a tax debt in international legal relations from the competent authority of a foreign state. Such a document shall be sent by the controlling authority to the taxpayer together with a tax notice in international legal relations in the manner prescribed by Article 58 of this Code. Such a tax notice in international legal relations shall not be subject to administrative appeal.
of Article 56 of this Code shall not apply to the consideration of taxpayers' applications for review of the decision of the competent authority of a foreign state .
Article 106. Withdrawal of tax notices in international legal relations or tax claims↑
106.1. A tax notice in international legal relations or tax claims shall be deemed withdrawn if the competent authority of a foreign state cancels or amends a document of a foreign state pursuant to which the amount of tax debt in international legal relations is collected. Such tax notices in international legal relations or tax claims shall be deemed withdrawn from the date of receipt by the controlling authority of a document of the competent authority of a foreign state of a decision to cancel or amend the previously accrued amount of tax debt in international legal relations that arose in a foreign state.
Article 107. Measures to collect the amount of tax debt in international legal relations↑
107.1. The supervisory authority shall independently transfer the amount of tax debt in international legal relations into hryvnia and take measures to collect the amount of tax debt of the taxpayer no later than the end of the 1095th day following the last day of the deadline for payment of taxes and fees in a foreign state specified in the document of the competent authority of the foreign state, according to which the amount of tax debt in international legal relations is collected. The deadline for collecting tax debt in international legal relations is determined in accordance with Clause 102.4 of Article 102 of this Code, unless otherwise provided for by an international treaty of Ukraine.
Article 108. Accrual of fines and penalties on the amount of tax debt in international legal relations↑
108.1. Penalty shall not be charged on the amount of tax debt in international legal relations upon execution of a document of a foreign state pursuant to which the amount of tax debt in international legal relations is collected.
108.2. Penalties for the amount of tax debt in international legal relations shall not be imposed upon the execution of a document of a foreign state pursuant to which the amount of tax debt in international legal relations is collected.
Article 108 - 1. Procedure for conducting the mutual agreement procedure↑
108 - 1 .1. Mutual agreement procedure.
108 - 1 .1.1. If a person considers that as a result of an action or decision of a supervisory authority of Ukraine or a relevant authority of another country, he is or will be subject to taxation that is not in accordance with the provisions of an international treaty of Ukraine for the avoidance of double taxation, he may, regardless of the remedies provided for by this Code, submit an application for consideration of the case under the mutual agreement procedure in accordance with the procedure specified in this Article.
108 - 1 .1.2. The right to submit an application for consideration of the case under the mutual agreement procedure provided for in this article shall be held by persons (residents or non-residents) if such right is provided for by the effective international treaty of Ukraine on the avoidance of double taxation.
108 - 1 .1.3. An application for consideration of the case under the mutual agreement procedure shall be submitted by the taxpayer to the competent authority of Ukraine.
For the purposes of this article, the competent authority of Ukraine is the central executive authority that ensures the formation and implementation of state financial policy, unless otherwise provided for by an international treaty of Ukraine on the avoidance of double taxation, or another authority authorized by it.
Unless otherwise provided for by an international treaty of Ukraine on the avoidance of double taxation, the decision to delegate powers to conduct the mutual agreement procedure to another body is made by the central executive body that ensures the formation and implementation of state financial policy.
If the competent authority of Ukraine has authorized another authority to conduct the mutual agreement procedure, the relevant authorized competent authority shall immediately notify the competent authority of another country with which an international agreement has been concluded of the receipt of the relevant authority.
108 - 1 .1.4. Requirements for an application for consideration of a case under the mutual agreement procedure and the procedure for considering the application (case) are established by the central executive body that ensures the formation and implementation of state financial policy.
108 - 1 .1.5. In order to ensure clarity or eliminate discrepancies in the interpretation and/or application of the provisions of the international treaty of Ukraine on the avoidance of double taxation or in order to conduct consultations on the avoidance of double taxation in cases not directly covered by the provisions of the international treaty of Ukraine on the avoidance of double taxation, a mutual agreement procedure may be initiated by the supervisory authority.
108 - 1 .2. Application for consideration of the case by mutual agreement procedure.
108 - 1 .2.1. An application for consideration of the case under the mutual agreement procedure shall be submitted by the taxpayer to the competent authority before the start or after the tax audit, including an audit of the taxpayer's compliance with the "arm's length" principle, with a description of the circumstances indicating the possibility of violation of the taxpayer's rights arising from the international treaty of Ukraine on the avoidance of double taxation.
An application for consideration of the case under the mutual agreement procedure is submitted by the taxpayer based on the results of a tax audit after receiving a decision on the results of an administrative appeal of the tax audit results within 10 business days.
Simultaneously with such an application, the taxpayer shall notify the supervisory authority in writing of the submission of an application for consideration of the case under the mutual agreement procedure regarding the circumstances set out in the inspection report on the basis of which the tax notice-decision was issued.
108 - 1 .2.2. In the event that the supervisory authority receives a notification from the taxpayer about the submitted application for consideration of the case under the mutual agreement procedure, the decision of the supervisory authority on determining monetary obligations on the issues raised in the application shall be considered non-agreed upon until the date of completion of consideration of the application (case) under the mutual agreement procedure or, if the application is refused, until the date of sending the notification of refusal.
108 - 1 .2.3. A taxpayer has the right to submit an application for consideration of the case under the mutual agreement procedure no later than 1095 calendar days from the date of agreement of the monetary obligation determined based on the results of a tax audit, including an audit of compliance by the taxpayer with the "arm's length" principle.
108 - 1 .2.4. A person who is a resident of Ukraine and believes that as a result of an action or decision of a state authority of a foreign state, he is or will be subject to taxation that does not comply with the provisions of an international treaty of Ukraine on the avoidance of double taxation, has the right to submit an application for consideration of the case under the mutual agreement procedure to the competent authority of Ukraine within 1095 calendar days from the date of receipt of notification of the action taken or decision taken by the relevant authority of the foreign state.
108 - 1 .3. Consideration of the application in the case by mutual agreement procedure.
108 - 1 .3.1. The competent authority of Ukraine shall consider the taxpayer's application and determine whether the case is subject to consideration under the mutual agreement procedure.
During the consideration of the application, the competent authority of Ukraine shall check the documents provided by the taxpayer for compliance with the requirements for the application for consideration of the case under the mutual agreement procedure established in accordance with subparagraph 108-1.1.4 of paragraph 108-1.1 of this Article , and shall check the presence of grounds for consideration or refusal to consider the case under the mutual agreement procedure in accordance with the international treaty of Ukraine for the avoidance of double taxation on the basis of which the application was submitted.
108 - 1 .3.2. During the consideration of the application, the competent authority of Ukraine has the right to request additional documents and explanations from the taxpayer regarding the circumstances set forth in the application, or to demand the elimination of violations committed by the taxpayer during the preparation of the documents.
108 - 1 .3.3. Based on the results of consideration of an application that meets the requirements established by subparagraph 108 - 1 .1.4 of paragraph 108 - 1 .1 of this Article, the competent authority of Ukraine shall, no later than 60 working days from the date of receipt of the application from the taxpayer, notify the taxpayer in writing of the commencement of consideration or refusal to consider the case under the mutual agreement procedure, indicating the reason for the refusal.
108 - 1 .4. The grounds for refusing to accept an application for consideration under the mutual agreement procedure are:
submission by the taxpayer of an application that does not meet the requirements of this article, or failure by the taxpayer to eliminate violations committed when preparing the application, upon written request of the competent authority of Ukraine within the time limits specified in the request;
failure by the taxpayer to provide documents or reasoned explanations upon a written request from the competent authority of Ukraine or failure to provide explanations as to the reason for the impossibility of providing such documents or information;
no violation of the taxpayer's rights provided for by the international treaty of Ukraine on the avoidance of double taxation;
the presence of an initiated but not completed administrative or judicial appeal on the same issues for which an application for consideration of the case under the mutual agreement procedure has been submitted;
a court decision on the same issues for which an application for consideration of the case under the mutual agreement procedure was submitted.
The taxpayer's refusal to participate in consultations with the competent authority of a foreign state during the consideration of the case in accordance with subparagraph 108 - 1 .5.2 of paragraph 108 - 1 .5 of this Article shall not be a basis for refusing to satisfy his application.
108 - 1 .5. Consideration of the case by mutual agreement procedure.
108 - 1 .5.1. The date of commencement of consideration of the case under the mutual agreement procedure shall be the date of the notification sent to the taxpayer in accordance with subparagraph 108 - 1 .3.3 of paragraph 108 - 1 .3 of this Article, unless otherwise established by the provisions of the current international treaty of Ukraine on the avoidance of double taxation.
108 - 1 .5.2. The competent authority of Ukraine shall address the competent authority of the state with which the international treaty was concluded, on the basis of which an application for consideration of the case under the mutual agreement procedure was submitted.
During the consideration of the case, if necessary, the competent authority of Ukraine has the right to involve representatives of the taxpayer in consultations with the competent authority of another country, including by videoconference. The participation of the taxpayer at the stage of consideration of the case under the mutual agreement procedure is not mandatory.
{Paragraph two of subparagraph 108 - 1 .5.2 of paragraph 108 - 1 .5 of Article 108 - 1 as amended by the Law No. 3603-IX dated 23.02.2024 }
108 - 1 .5.3. Following the results of consultations with the competent authority of another country under the mutual agreement procedure, the competent authority of Ukraine shall notify the taxpayer and the supervisory authority in writing of the results of the case consideration.
108 - 1 .5.4. The mutual agreement procedure may be terminated at any time based on the taxpayer's application for its termination.
108 - 1 .6. Peculiarities of conducting the mutual agreement procedure in the event of the assessment of tax liabilities by the controlling authorities of Ukraine.
108 - 1 .6.1. The competent authority shall notify the supervisory authority of the results of the consideration of the application (case) no later than five working days following the date of adoption of the relevant decision. Supervisory authorities shall not have the right to adopt any decisions that contradict the agreements reached within the framework of the mutual agreement procedure and shall ensure the implementation of such agreements reached, including by reviewing the agreed tax obligations in an administrative manner.
108 - 1 .6.2. If the competent authorities have reached agreements that recognize in full or in part that the taxpayer was or is subject to taxation that does not comply with the terms of the international treaty of Ukraine on the avoidance of double taxation, the supervisory authority, if tax notices-decisions were adopted based on the results of the audit, shall cancel these tax notices-decisions and send the taxpayer new tax notices-decisions within the amount, the validity of which was recognized within the framework of the agreements between the competent authorities.
108 - 1 .6.3. When conducting the mutual agreement procedure, the taxpayer is obliged to:
maintain the relevance of information, materials and documents provided to the competent authorities for the mutual agreement procedure;
to inform about any changes in the facts or circumstances that gave rise to the grounds for conducting the mutual agreement procedure.
108 - 1 .6.4. The mutual agreement procedure cannot be carried out simultaneously with an administrative or judicial appeal against the same decision of the supervisory authority.
The decision of the regulatory authority cannot be appealed administratively after reaching agreements based on the results of its consideration through the mutual agreement procedure.
If the taxpayer does not agree with the results of the agreements reached between the competent authorities under the mutual agreement procedure, he has the right to appeal the decision of the supervisory authority in court in accordance with paragraph 56.18 of Article 56 of this Code.
{Chapter 10 of Section II is supplemented by Article 108 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
109.1. A tax offense is an unlawful, culpable (in cases expressly provided for by this Code) act (action or inaction) of a taxpayer (including persons equated to him), regulatory authorities and/or their officials (service personnel), other entities in cases expressly provided for by this Code.
Actions are considered to have been committed intentionally if there are circumstances proven by the controlling body that indicate that the taxpayer has intentionally and purposefully created conditions that cannot have any other purpose than non-fulfillment or improper fulfillment of the requirements established by this Code and other legislation, control over compliance with which is entrusted to the controlling bodies.
{Clause 109.1 of Article 109 as amended by Law No. 466-IX of January 16, 2020 }
109.2. Violation of tax legislation and violations of requirements established by other legislation, the control over compliance with which is entrusted to regulatory authorities, entails liability provided for by this Code and other laws of Ukraine.
{Clause 109.2 of Article 109 as amended by Law No. 466-IX of January 16, 2020 }
109.3. In cases specified in paragraphs 123.2-123.5 of Article 123, paragraphs 124.2 , 124.3 of Article 124, paragraphs 125 - 1 .2-125 - 1 .4 of Article 125 - 1 of this Code, a necessary condition for holding a person financially liable for committing a tax offense is the establishment of the person's guilt by the supervisory authorities.
{Article 109 is supplemented by paragraph 109.3 in accordance with Law No. 466-IX of January 16, 2020 ; as amended by Law No. 1914-IX of November 30, 2021 }
109.4. Controlling bodies are liable for committing tax offenses regardless of guilt.
{ Article 109 supplemented by paragraph 109.4 in accordance with Law No. 466-IX of 16.01.2020 }
Article 110. Entities held liable for committing tax offenses↑
110.1. Taxpayers, tax agents, as well as other entities in cases expressly provided for by this Code, shall bear financial responsibility for committing tax offenses.
110.2. An individual taxpayer shall be financially liable provided that he or she has full civil capacity at the time of committing a tax offense.
110.3. Controlling bodies shall be liable in the form of compensation for damage to the person against whom a tax offense was committed, in accordance with the provisions of Article 114 of this Code. Controlling bodies shall be liable for the commission of tax offenses by officials (service personnel) of such controlling bodies.
110.4. Legal representatives of taxpayers - individuals, in accordance with Article 242 of the Civil Code of Ukraine, in case of failure to fulfill the obligations specified in this Code, shall bear the financial responsibility established for taxpayers.
110.5. A legal entity - a taxpayer shall be financially liable for the commission of tax offenses by its separate divisions.
{ Article 110 as amended by Law No. 466-IX of 16.01.2020 }
Article 111. Liability for Violation of Taxation Laws and Other Legislation, Control Over Compliance with Which Is Entrusted to Controlling Bodies↑
{Title of Article 111 as amended by Law No. 466-IX of January 16, 2020 }
111.1. The following types of legal liability apply for violations of laws on taxation and other legislation, the control over compliance of which is entrusted to regulatory authorities:
111.1.1. financial;
111.1.2. administrative;
111.1.3. criminal.
111.2. Financial liability for violations of laws on taxation and other legislation shall be established and applied in accordance with this Code and other laws. Financial liability established in accordance with this Code shall be applied in the form of punitive (financial) sanctions (fines).
{Paragraph one of clause 111.2 of Article 111 as amended by Law No. 466-IX of 16.01.2020 }
Financial liability established in accordance with other laws, the control over compliance of which is entrusted to regulatory authorities, may be applied in the form of punitive (financial) sanctions (fines) and/or penalties.
{Clause 111.2 of Article 111 is supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 }
111.3. Holding an individual or legal entity financially liable for a tax offense does not exempt the individual or officials (service personnel) of the legal entity from other types of legal liability in cases provided for by law.
Holding an individual or legal entity financially liable for a tax offense, which involves establishing the person's guilt by the regulatory authorities, does not imply a presumption of guilt of the individual or officials (service personnel) of the legal entity in cases where an individual or officials (service personnel) of the legal entity are held liable for other types of legal liability and does not exempt from the obligation to prove it in accordance with the procedure prescribed by law.
{Article 111 is supplemented by paragraph 111.3 in accordance with Law No. 466-IX of January 16, 2020, taking into account the amendments made by Law No. 1117-IX of December 17, 2020 }
111.4. A person is considered to have committed an offense repeatedly if he or she has been held liable in accordance with the procedure established by this Code.
{ Article 111 supplemented by paragraph 111.4 in accordance with Law No. 466-IX of 16.01.2020 }
111.5. Continuing offense - continuous failure to comply with the norms of this Code by a taxpayer who has committed certain actions or committed inaction and has not taken further actions to eliminate it until the moment such an offense is detected by the controlling body.
{ Article 111 supplemented by paragraph 111.5 in accordance with Law No. 466-IX of 16.01.2020 }
111.6. Notification to a taxpayer (or any other persons acting on his behalf and/or in his interests) of suspicion of committing a criminal offense regarding the provision of an unlawful benefit cannot be based solely on the fact that such taxpayer made changes to previously submitted tax reporting in accordance with clause 50.1 - 1 of Article 50 of this Code and/or on the fact that he made an adjustment (increase) in the financial result before taxation (profit or loss) in accordance with subparagraph 140.6.1 of clause 140.6 of Article 140 of this Code, or the determination of the object of taxation in accordance with subparagraph 141.9 - 1 .2.16 of subparagraph 141.9 - 1 .2 of clause 141.9 - 1 of Article 141 of this Code.
{Article 111 is supplemented by paragraph 111.6 in accordance with Law No. 4112-IX of 04.12.2024 }
Article 112. General conditions for holding financially liable for committing tax offenses and violations of other legislation, the control over compliance with which is entrusted to regulatory authorities↑
112.1. A person may be held financially liable for committing a tax offense provided that his/her act (action or inaction) was culpable, except for cases provided for by this Code.
112.2. A person is considered guilty of committing an offense if it is established that he had the opportunity to comply with the rules and regulations, the violation of which is punishable by this Code, but did not take sufficient measures to comply with them.
The measures taken by the taxpayer to comply with the rules and regulations of tax legislation are considered sufficient unless the regulatory authority proves that, by committing certain actions or allowing inaction for which liability is provided, the taxpayer acted unreasonably, in bad faith and without due care.
112.3. A person may not be held financially liable for committing a tax offense other than on the grounds and in accordance with the procedure provided for by this Code.
112.4. A person may not be held liable twice for the same type of tax offense.
112.5. The basis for holding a person financially liable for committing a tax offense and collecting a fine is a tax notice-decision that meets the requirements specified in paragraph 58.1 of Article 58 of this Code.
112.6. Holding or releasing a person from financial liability for committing a tax offense does not exempt him from fulfilling the tax obligation, as well as another obligation stipulated by this Code, the violation of which became the basis for holding him liable.
{Clause 112.6 of Article 112 as amended by Law No. 2970-IX of 20.03.2023 }
112.7. If the regulatory authority does not prove that the taxpayer had the opportunity to comply with the rules and regulations, the violation of which is subject to liability under this Code, but did not take sufficient measures to comply with them, the taxpayer may not be held liable for such a violation. The provisions of this paragraph apply only if the condition for holding the taxpayer financially liable for a tax offense is the taxpayer's fault.
The procedure for proving the circumstances under which a person may be held financially liable for a tax offense committed within the framework of judicial proceedings is determined by procedural legislation.
All doubts regarding the existence of circumstances under which a person may be held liable for violating tax legislation and other legislation, the control of which is entrusted to the regulatory authority, shall be interpreted in favor of such person.
112.8. Circumstances exempting from financial liability for committing tax offenses and violations of other legislation, the control over compliance with which is entrusted to regulatory authorities, are:
112.8.1. expiration of the statute of limitations for the application of fines for committing a tax offense;
112.8.2. commission of an act (action or inaction) by a person who acted in accordance with individual tax advice provided to such taxpayer in paper or electronic form, provided that such advice is registered in the unified register of individual tax advice, or to a general tax advice and/or to the conclusion of a joint chamber, the Grand Chamber of the Supreme Court on the application of a rule of law from which a later departure was made;
112.8.3. commission of an act (action or omission) by a person who acted in accordance with the legal conclusions of the Supreme Court set out in the decision based on the results of consideration of a model case, which were subsequently changed as a result of review by the Grand Chamber of the Supreme Court;
112.8.4. commission of an act (action or inaction) as a result of illegal decisions, actions or inaction of regulatory authorities;
112.8.5. commission of an act (action or inaction) due to the fault of a bank, a body providing treasury services for budget funds, a non-bank payment service provider, an acquirer, an issuer of electronic money (regarding tax offenses provided for in Articles 124 and 125 - 1 of this Code);
{Subparagraph 112.8.5 of paragraph 112.8 of Article 112 as amended by Law No. 2888-IX of 12.01.2023 }
112.8.6. commission of an act (action or inaction) due to the fault of a postal operator, information about which is contained in the Unified State Register of Postal Operators, subject to the fulfillment of the obligation specified in the second paragraph of paragraph 49.6 of Article 49 of this Code;
112.8.7. committing an act (action or inaction) as a result of detecting a technical and/or methodological error or technical failure in the operation of the electronic office and recognizing such an error/failure by the technical administrator and/or methodologist of the electronic office or according to a notification on the official website of the central executive body implementing state tax policy, or confirming its/its existence by a court decision, if the violations were caused exclusively by a technical and/or methodological error or technical failure in the operation of the electronic office.
Failure to accrue fines and/or penalties for violations that were caused solely by a technical and/or methodological error or technical failure in the operation of the electronic office is fixed (implemented) in the software used to automatically calculate fines and/or penalties for violations of tax legislation;
112.8.8. independent correction by the taxpayer, in compliance with the procedure, requirements and restrictions provided for in Article 50 of this Code, of errors contained in previously submitted tax returns and calculations (clarifying tax returns and calculations), subject to payment of independently accrued tax liabilities and penalty (financial) sanctions (fines) provided for in Clause 50.1 of Article 50 of this Code (regarding the offense provided for in Clause 123.1 of Article 123 of this Code).
Failure by a taxpayer to comply with the requirements provided for in paragraphs three to five of paragraph 50.1 of Article 50 of this Code, in terms of self-assessment and payment of the fine provided for in this paragraph, shall entail the imposition of a fine in accordance with paragraph 120.2 of Article 120 of this Code;
112.8.8 - 1. erroneous payment by a taxpayer, including a tax agent, of a monetary obligation to another budget account (without violating the legally established deadline for paying the tax or the agreed amount of the monetary obligation to the budget). The condition for confirming such circumstances is the taxpayer's taking the actions provided for in Article 43 of this Code regarding the return of erroneously paid monetary obligations;
{ Clause 112.8 of Article 112 is supplemented by subparagraph 112.8.8 - 1 in accordance with Law No. 3603-IX of 23.02.2024 }
112.8.9. commission of an act (action or inaction) as a result of circumstances of force majeure;
112.8.10. commission of an act (action or inaction) by a person who acted in accordance with advice on the practical application of certain norms of the legislation of Ukraine on customs matters, provided in written or electronic form, as well as general advice, in particular on the basis that such advice was subsequently amended or canceled;
112.8.11. commission of an act (action or inaction) by a person who acted in accordance with a previously issued decision of the customs authority on the application of certain provisions of the legislation of Ukraine on customs matters, including if such a decision was subsequently revoked for the reasons established by paragraphs 2 , 3 of part seven of Article 23 of the Customs Code of Ukraine;
112.8.12. other cases of exemption from financial liability provided for by this Code or the Customs Code of Ukraine .
{Article 112 as amended by Law No. 466-IX of 16.01.2020 }
Article 112 - 1. Circumstances mitigating the liability of a person↑
112 - 1 .1. Circumstances mitigating the liability of a person for committing offenses include:
112 - 1 .1.1. committing an act under the influence of threat, coercion or due to material, official or other dependence;
112 - 1 .1.2. committing an act in the event of difficult personal or family circumstances;
112 - 1 .1.3. independent notification by the taxpayer of the offense committed by him (except for the offenses provided for in Articles 123 and 125 - 1 of this Code).
112 - 1 .2. The supervisory authority may recognize as circumstances mitigating the liability of a person also other circumstances not provided for in paragraph 112 - 1 .1 of this Article.
{The Code is supplemented with Article 112 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
{Title of Article 113 as amended by Law No. 466-IX of January 16, 2020 }
113.1. The deadlines for applying punitive (financial) sanctions (fines) to taxpayers shall correspond to the statute of limitations for accruing monetary obligations specified in Article 102 of this Code.
{Clause 113.1 of Article 113 as amended by Law No. 466-IX of January 16, 2020 }
113.2. The limitation period for the application of punitive (financial) sanctions (fines) shall be suspended in the cases specified in paragraph 102.3 of Article 102 of this Code.
{Clause 113.2 of Article 113 as amended by Law No. 466-IX of 16.01.2020 }
113.3. In the event that a taxpayer commits two or more violations of other legislation, the control over compliance with which is entrusted to regulatory authorities, punitive (financial) sanctions (fines) are applied for each single and ongoing violation committed separately.
{Clause 113.3 of Article 113 as amended by Law No. 466-IX of January 16, 2020 }
113.5. The limitation period for the application of punitive (financial) sanctions (fines) shall be resumed from the day following the day of elimination of the circumstances provided for in paragraph 102.3 of Article 102 of this Code, which were the basis for stopping its calculation (run).
{ Article 113 supplemented by paragraph 113.5 in accordance with Law No. 466-IX of 16.01.2020 }
113.6. In the event of the presence of at least one circumstance mitigating liability, the amount of the fine shall be 50 percent of the amount established by the relevant article of this Code.
{ Article 113 supplemented by paragraph 113.6 in accordance with Law No. 466-IX of 16.01.2020 }
113.7. In the event that the regulatory authorities apply punitive (financial) sanctions (fines) to a taxpayer for violating laws on taxation and other legislation, the control over compliance with which is entrusted to the regulatory authorities, tax notices-decisions are sent (delivered) to such taxpayer.
{ Article 113 supplemented by paragraph 113.7 in accordance with Law No. 466-IX of 16.01.2020 }
113.8. For one tax offense, the regulatory authority may apply only one type of punitive (financial) sanction (fine) provided for by this Code and other laws of Ukraine.
{ Article 113 supplemented by paragraph 113.8 in accordance with Law No. 466-IX of 16.01.2020 }
Article 114. Compensation for damage caused by unlawful decisions, actions or inaction of regulatory bodies↑
114.1. A person whose rights and/or legitimate interests have been violated has the right to compensation for damage caused by unlawful decisions, actions or inaction of regulatory bodies and their officials.
Damage caused by unlawful decisions, actions or inaction of regulatory bodies and their officials shall be compensated by the state at the expense of the state budget, regardless of the fault of the regulatory body and its officials.
114.2. Damage caused by unlawful decisions, actions or inaction of regulatory authorities, their officials (service personnel), which are recognized as tax offenses in accordance with this Code, shall be compensated in full in accordance with the procedure provided for by the legislation on compensation for damage.
A person whose rights have been violated, in the presence of circumstances provided for in paragraph 128.2 of Article 128 of this Code, has the right to file claims for compensation for damage caused by unlawful decisions, actions or inaction of regulatory bodies, their officials (service personnel), in the amount of one minimum wage established as of the date of recognition of such decisions, actions or inaction as unlawful, in accordance with the procedure provided for by law. In such a case, only the unlawfulness of the decisions, actions or inaction in relation to the person shall be proven.
In the cases provided for in the second paragraph of this paragraph, damage exceeding the established amount shall not be subject to compensation.
114.3. Damage caused by unlawful decisions, actions or inaction of regulatory bodies and their officials may include:
114.3.1. the value of the taxpayer's lost, damaged or destroyed property, determined in accordance with the requirements of the law;
114.3.2. additional costs incurred by the taxpayer as a result of unlawful decisions, actions or inaction of regulatory authorities, their officials (fines paid to the taxpayer's counterparties, the cost of additional work, services, additional materials consumed, etc.);
114.3.3. documented expenses related to administrative and/or judicial appeal (except for amounts subject to reimbursement in accordance with the procedure for the distribution of court costs in accordance with procedural legislation) of illegal (unlawful) decisions, actions or inaction of regulatory authorities, their officials (officials) (legal support not related to the protection provided by a lawyer, travel of employees or representatives of the taxpayer, involvement of experts, obtaining necessary evidence, making copies of documents, etc.). The amount of such reimbursement shall not exceed 50 times the minimum wage established on January 1 of the calendar year in which the relevant court decision or decision of another body is made, in cases provided for by law.
114.4. Damage caused to a taxpayer as a result of a tax offense committed by a regulatory authority shall be compensated by a court decision.
114.5. The provisions of this article do not apply if the damage caused by the inaction of the controlling bodies or their officials is caused by the legal regime of martial law or a state of emergency.
{ Article 114 supplemented by paragraph 114.5 in accordance with Law No. 2120-IX of March 15, 2022 }
{Article 114 as amended by Law No. 466-IX of 16.01.2020 }
Article 115. { Article 115 was excluded on the basis of Law No. 466-IX of 16.01.2020 }↑
Article 116. Alienation of property subject to tax lien without the consent of the controlling body↑
116.1. Alienation by a taxpayer of property subject to tax lien without the prior consent of the controlling authority, if obtaining such consent is mandatory in accordance with this Code, -
entails the imposition of a fine in the amount of the value of the alienated property.
{Article 116 as amended by Law No. 466-IX of 16.01.2020 }
Article 117. Violation of the established procedure for registration with regulatory authorities↑
117.1. Failure to submit, within the time limits and in the cases provided for by this Code, applications or documents for registration with the relevant regulatory authority, registration of changes in location or making other changes to one's accounting data, failure to submit corrected documents for registration or making changes, submission with errors or in incomplete form, failure to submit information regarding persons responsible for maintaining accounting records and/or preparing tax reports, in accordance with the requirements established by this Code, -
entail a fine of 340 hryvnias for self-employed persons, and 1020 hryvnias for legal entities, separate divisions of a legal entity, or a legal entity responsible for the accrual and payment of taxes to the budget during the implementation of a joint activity agreement.
{Paragraph two of clause 117.1 of Article 117 as amended by Law No. 466-IX of January 16, 2020 }
In case of failure to eliminate such violations or for the same actions committed within a year by a person to whom fines were applied for such a violation, -
entail a fine of 680 hryvnias for self-employed persons, and 2040 hryvnias for legal entities, separate divisions of a legal entity, or a legal entity responsible for the accrual and payment of taxes to the budget during the implementation of a joint activity agreement.
{Paragraph four of clause 117.1 of Article 117 as amended by Law No. 466-IX of January 16, 2020 }
{Clause 117.2 of Article 117 was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
117.3. Carrying out transactions by business entities for the sale of fuel or ethyl alcohol without registering such entities as excise tax payers in accordance with the procedure provided for by this Code -
{Paragraph one of clause 117.3 of Article 117 as amended by Law No. 2628-VIII of 23.11.2018 }
entails the imposition of a fine on legal entities and individual entrepreneurs in the amount of 100 percent of the cost of fuel or ethyl alcohol sold.
{Paragraph two of clause 117.3 of Article 117 as amended by Law No. 2628-VIII of 23.11.2018 }
{Article 117 was supplemented by paragraph 117.3 in accordance with Law No. 909-VIII of 24.12.2015 }
117.4. Conducting activities by a non-resident (foreign legal company, organization) through a separate subdivision, including a permanent representative office, without being registered for tax purposes in accordance with the procedure provided for by this Code, -
entails a fine of 100,000 hryvnias for a non-resident.
{Article 117 is supplemented by paragraph 117.4 in accordance with Law No. 466-IX of 16.01.2020 }
117.5. Implementation by a non-resident person of transactions for the supply of electronic services in the customs territory of Ukraine to individuals, including individual entrepreneurs who are not registered as value added tax payers, without registering such non-resident person as a value added tax payer in accordance with Article 208 - 1 of this Code -
entails the imposition of a fine on such a non-resident person in the amount of 30 times the minimum wage established by law as of January 1 of the reporting (tax) year.
{Article 117 is supplemented by paragraph 117.5 in accordance with Law No. 1525-IX of 03.06.2021 }
117.6. Failure by a financial agent to submit an application for registration as a reporting financial institution in accordance with the requirements of paragraph 39 - 3.3 of Article 39 - 3 of this Code -
entails the imposition of a fine in the amount of 20 times the minimum wage established by law as of January 1 of the reporting (tax) year.
the financial agent from the obligation to register and fulfill other requirements of Article 39-3 of this Code.
{Article 117 is supplemented by paragraph 117.6 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 118. Violation of the deadline and procedure for submitting information on opening or closing accounts/electronic wallets, a report on accountable accounts↑
{Title of Article 118 as amended by Laws No. 323-IX of 03.12.2019 , No. 2888-IX of 12.01.2023 }
118.1. Failure by banks, other financial institutions, non-bank payment service providers, and electronic money issuers to notify the relevant regulatory authorities of the opening or closing of taxpayer accounts/electronic wallets within the period established by Article 69 of this Code -
{Paragraph one of clause 118.1 of Article 118 as amended by Law No. 2888-IX of 12.01.2023 }
entails a fine of 680 hryvnia for each case of failure to submit or delay.
{Paragraph two of clause 118.1 of Article 118 as amended by Law No. 466-IX of 16.01.2020 }
118.2. Carrying out expenditure transactions on the taxpayer's account/electronic wallet before receiving a notification from the relevant regulatory authority about registering the account with regulatory authorities -
entails the imposition of a fine on a bank, other financial institution, non-bank payment service provider, or electronic money issuer in the amount of 10 percent of the amount of all transactions for the entire period prior to receipt of such notification, carried out using such accounts (except for transactions to transfer funds to budgets or state trust funds), but not less than 1,700 hryvnias.
{ Clause 118.2 of Article 118 as amended by Law No. 466-IX of 01/16/2020 ; as amended by Law No. 2888-IX of 01/12/2023 }
118.3. Failure by individuals - entrepreneurs and persons engaged in independent professional activities - to notify a bank, other financial institution, non-bank payment service provider/electronic money issuer of their status when opening an account/electronic wallet -
{Paragraph one of clause 118.3 of Article 118 as amended by Law No. 2888-IX of 12.01.2023 }
entails a fine of 680 hryvnia for each case of failure to report.
{Paragraph two of clause 118.3 of Article 118 as amended by Law No. 466-IX of January 16, 2020 }
{Clause 118.4 of Article 118 was excluded on the basis of Law No. 2970-IX of 20.03.2023 }
Article 118 - 1. Violation of requirements for identifying reportable accounts and submitting reports for the automatic exchange of financial account information↑
118 - 1 .1. Failure by a financial agent to submit a report on accountable accounts in accordance with the requirements of Article 39 - 3 of this Code -
entails the imposition of a fine in the amount of 100 times the minimum wage established by law as of January 1 of the reporting (tax) year.
Payment of such a fine does not exempt the financial agent from the obligation to submit a report on accountable accounts.
118 - 1 .2. Failure by a depository institution to provide a notice on depositors - investors of collective investment institutions to an asset management company within the established period or providing incomplete information in the notice, or failure by an asset management company to provide a response to its request sent in accordance with clause 39 - 3 .11 of Article 39 - 3 of this Code, -
entails the imposition of a fine in the amount of 30 times the minimum wage established by law as of January 1 of the reporting (tax) year.
Payment of such a fine does not exempt the depository institution from the obligation to submit information and documents about depositors - investors of collective investment institutions to the asset management company.
118 - 1 .3. Untimely submission by a financial agent of a report on accountable accounts or untimely submission by a financial agent of a corrected report on accountable accounts at the request of the supervisory authority in violation of the established deadlines specified in Article 39 - 3 of this Code, -
entails the imposition of a fine of 0.5 times the minimum wage established by law as of January 1 of the reporting (tax) year for each calendar day of untimely submission of a report on accountable accounts, but not more than 100 times the minimum wage established by law as of January 1 of the reporting (tax) year.
Payment of such a fine does not exempt the financial agent from the obligation to submit a report on accountable accounts and correct errors in a previously submitted report.
118 - 1 .4. Submission by a financial agent of a report on accountable accounts with incomplete or inaccurate information or errors -
entails the imposition of a fine of 0.5 times the minimum wage established by law as of January 1 of the reporting (tax) year.
In the event of violations in one report regarding two or more financial accounts, the calculation of the fine amount is carried out by adding the amounts of fines for each financial account for which erroneous, incomplete or unreliable information was submitted.
The penalty provided for in this paragraph shall not apply if the inaccurate information or errors in the report on accountable accounts arose for reasons beyond the control of the financial agent and/or in connection with the submission of inaccurate information by the financial account holder, provided that the financial agent:
took the necessary due diligence measures to identify the Reportable Accounts and verify the tax residency status of the Account Holders and the Controlling Persons of such Account Holders;
timely, within the period established by Article 39-3 of this Code, notified the supervisory authority about the reporting account for which the financial account holder provided incomplete or inaccurate information.
The penalty provided for in this paragraph shall not apply if a financial agent has filed a report on reportable accounts with an error or errors, if the relevant errors did not affect the detection of the reportable account and the correct identification of the state or territory of which the account holder and/or its controlling persons are residents, as well as the correct identification of the persons to whom the relevant account is reportable.
, the financial agent submitted a corrected report independently or in response to a notification received from the supervisory authority within the time limits specified in Article 39-3 of this Code.
118 - 1 .5. Actions provided for in paragraph 118 - 1 .4 of this article committed by a financial agent as a result of failure to comply, improper compliance or violation of the rules of due diligence specified in subparagraph 39 - 3 .1.3 of paragraph 39 - 3 .1 of Article 39 - 3 of this Code, as well as intentional failure to include information about a reporting account in the report on reporting accounts -
entail the imposition of a fine in the amount of 5 percent of the balance or value of each financial account for which incomplete, erroneous or unreliable information was submitted or for which information was not submitted in the report on accountable accounts, but not less than one minimum wage and not more than 200 minimum wages established by law as of January 1 of the reporting (tax) year.
The penalty amount is calculated by adding the amounts of the penalties for each financial account for which false, incomplete or inaccurate information was provided, and for each financial account that was not included in the report on accountable accounts.
118 - 1 .6. Violation by financial agents of the requirements regarding the terms of storage of documents and information regarding financial accounts to the extent specified in Article 39 - 3 of this Code, -
entails the imposition of a fine in the amount of one minimum wage established by law as of January 1 of the reporting (tax) year.
The same violations that led to the non-inclusion of a reportable account in the report on reportable accounts or violation of the retention periods (or absence) of CRS self-assessment documents of the person for whom the account is reportable -
entail the imposition of a fine in the amount of 50 times the minimum wage established by law as of January 1 of the reporting (tax) year.
118 - 1 .7. Systematic intentional (more than twice during a continuous period of 24 calendar months) or other significant violation by a financial agent of the requirements of Article 39 - 3 of the Code in the part relating to the implementation of the CRS Multilateral Agreement and the CRS Common Reporting Standard, -
entails the imposition of a fine in the amount of 1 percent of the amount of income (revenue) of the financial agent according to its separate financial statements for the calendar year preceding the year in which the fine is applied.
The fine provided for in this paragraph shall be applied by the supervisory authority solely based on the results of a documentary audit of the financial agent.
For the purposes of applying the penalty (financial) sanction provided for in this paragraph, the existence of a material violation by a financial agent of the requirements of Article 39-3 of this Code is evidenced by at least one of the following conditions:
1) the financial agent has failed to provide a response or documents or other information to the supervisory authority's requests relating to the financial agent's compliance with the CRS Common Reporting Standard requirements three or more times during a continuous period of 24 calendar months;
2) the financial agent has not provided documents confirming its implementation of due diligence measures in accordance with the rules of sections II-VII of the CRS Common Reporting Standard, or documents of the CRS self-assessment regarding at least 25 percent of the total number of financial accounts of this financial agent;
3) at least three fines provided for in at least two paragraphs of this Article were applied to the financial agent within two consecutive calendar years, but the financial agent did not eliminate the violations that became the grounds for applying fines to it within three months from the date of application of the last fine (or the date of agreement on the relevant monetary obligation, if the decision to apply the fine was appealed by the financial agent).
If a financial agent has committed more than one offense for which liability is provided for under this Article, the penalty (financial) sanction provided for in this paragraph shall absorb other penalties provided for in this Article for violation of the requirements of Article 39-3 of this Code in terms of compliance with the requirements of the Common Reporting Standard CRS, which could have been applied for each separate offense that gave rise to the application of this paragraph.
118 - 1 .8. Intentional provision by the account holder of CRS self-assessment documents regarding himself and/or his controlling persons in cases provided for in Article 39 - 3 of this Code, with inaccurate information, which led to the failure to establish the accountability of the account for the account holder and/or his controlling persons, -
entails the imposition of a fine in the amount of 100 times the minimum wage established by law as of January 1 of the reporting (tax) year.
Payment of such a fine does not exempt the account holder from the obligation of the account holder to provide CRS self-assessment documents regarding himself and/or his controlling persons in the cases provided for in Article 39-3 of this Code, with reliable information.
{The Code is supplemented by Article 118 - 1 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 119. Violation by a taxpayer of the procedure for submitting information on individual taxpayers↑
119.1. Failure to submit, submission in violation of the established deadlines, submission of incomplete, inaccurate information or errors in tax reporting on the amounts of income accrued (paid) to the taxpayer, the amount of tax withheld from them, as well as amounts accrued (paid) to individuals for goods (works, services), if such inaccurate information or errors led to a decrease and/or increase in the taxpayer's tax liabilities and/or to a change in the taxpayer, -
entail a fine of 1020 hryvnias.
The same actions committed by a taxpayer who was fined for the same violation during the year -
entail a fine of 2040 hryvnias.
The fines provided for in this paragraph shall not be applied in cases where inaccurate information or errors in tax reporting on the amounts of income accrued (paid) to the taxpayer, the amounts of tax withheld from them, as well as the amounts accrued (paid) to individuals for goods (works, services) arose in connection with the tax agent's compliance with the requirements of paragraph 169.4 of Article 169 of this Code and were corrected in accordance with the requirements of Article 50 of this Code.
119.2. Preparation of documents containing information on the objects of taxation of individuals or on the payment of taxes without indicating the registration number of the taxpayer's registration card, in the event that the legislation requires a resident person to obtain such a number, or using an invalid registration number of the taxpayer's registration card, except for the cases specified in paragraph 119.1 of this Article, -
entails a fine of 340 hryvnias.
{For amendments to paragraph 119.2 of Article 119, see Law No. 116-IX of September 19, 2019 }
119.3. The fines provided for in paragraphs 119.1 and 119.2 of this Article shall not apply in cases where errors regarding the registration number of the taxpayer's account card in the tax reporting on the amounts of income accrued (paid) in favor of the taxpayer, the amounts of tax withheld from them were corrected by tax agents independently, including within 30 calendar days from the date of receipt of notifications of errors detected by the supervisory authority.
{ Article 119 as amended by Laws No. 657-VII of 24.10.2013 , No. 71-VIII of 28.12.2014 ; as amended by the Law No. 466-IX dated 16.01.2020 }
Article 119 - 1. Violation of the procedure for submitting information to regulatory authorities on real estate lease agreements↑
119 - 1 .1. Violation by a notary of the procedure and/or deadlines for submitting information regarding the certification of lease agreements for real estate objects in the event of the performance of such a notarial action -
entails a fine of 680 hryvnias for each such violation.
119 - 1 .2. Violation by a business entity conducting intermediary activities related to the provision of real estate rental services (realtor), of the procedure and/or deadlines for submitting information on civil law contracts (agreements) for real estate rental concluded through its mediation -
entails a fine of 680 hryvnias for each such violation.
119 - 1 .3. Actions provided for in paragraphs 119 - 1 .1 and 119 - 1 .2 of this article, committed by an entity to which a fine was imposed for such a violation within a year, -
entail a fine of 1,360 hryvnias for each such violation.
{The Code is supplemented by Article 119 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
Article 120. Failure to submit or untimely submission of tax reporting or failure to comply with requirements for making changes to tax reporting↑
120.1. Failure to submit (except in cases where a tax return is not submitted in accordance with Clause 49.2 of Article 49 of this Code) or untimely submission by a taxpayer or other persons obliged to calculate and pay taxes and fees, payments, control over the payment of which is entrusted to regulatory authorities, of tax returns (calculations), as well as other reporting, the obligation to submit which to regulatory authorities is provided for by this Code, -
{Paragraph one of item 120.1 of Article 120 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 16/01/2020 }
entail the imposition of a fine of 340 hryvnias for each such failure to submit or untimely submission.
{Paragraph two of clause 120.1 of Article 120 as amended by Law No. 466-IX of 16.01.2020 }
The same actions committed by a taxpayer who has been fined for such a violation during the year -
entail a fine of 1020 hryvnias for each such failure to submit or untimely submission.
{Subparagraph 120.1.1 of paragraph 120.1 of Article 120 was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
120.2. Failure by a taxpayer to comply with the requirements provided for in paragraphs three to five of paragraph 50.1 of Article 50 of this Code regarding the conditions for independently making changes to tax reporting in terms of independently calculating and paying the fine provided for in this paragraph -
{Paragraph one of clause 120.2 of Article 120 as amended by Law No. 657-VII of 24.10.2013 }
entails the imposition of a fine in the amount of 5 percent of the amount of the self-assessed understatement of tax liability (underpayment) and/or other liability, control over the payment of which is entrusted to the regulatory authorities.
If a taxpayer independently adds additional amounts of tax liabilities and/or other liabilities, the payment control of which is entrusted to the regulatory authorities, in compliance with the procedure, requirements and restrictions provided for in Article 50 of this Code, the fines provided for in this Chapter of the Code shall not apply.
{Paragraph three of clause 120.2 of Article 120 as amended by Law No. 786-IX of 14.07.2020 }
{ Clause 120.2 of Article 120 as amended by Law No. 466-IX of 16.01.2020 }
120.3. Failure by a taxpayer to submit a report on controlled transactions and/or transfer pricing documentation, and/or global transfer pricing documentation (master file), and/or a report by country of an international group of companies, and/or a notification of participation in an international group of companies in accordance with the requirements of Article 39 of this Code -
shall entail the imposition of a fine(s) in the amount of:
300 times the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, - in case of failure to submit a report on controlled transactions;
3 percent of the amount of controlled transactions for which documentation was not submitted, determined by subparagraphs 39.4.6 and 39.4.9 of paragraph 39.4 of Article 39 of this Code, but not more than 200 times the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year;
300 times the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year - in case of failure to submit global transfer pricing documentation (master file) specified in subparagraphs 39.4.7 and 39.4.9 of paragraph 39.4 of Article 39 of this Code;
1000 of the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, - in case of failure to submit a report by country of the international group of companies;
100 times the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, - in case of failure to submit a notification of participation in an international group of companies.
{Paragraph seven of clause 120.3 of Article 120 as amended by Law No. 4112-IX of 04.12.2024 }
Payment of such financial sanctions (fines) does not exempt the taxpayer from the obligation to submit a report on controlled transactions and/or transfer pricing documentation, and/or global transfer pricing documentation (master file), and/or a report by country of an international group of companies, and/or a notification of participation in an international group of companies.
Failure by a taxpayer to submit a report on controlled transactions and/or transfer pricing documentation, and/or global transfer pricing documentation (master file), and/or a report by country of an international group of companies, and/or a notification of participation in an international group of companies after the expiration of 30 calendar days following the last day of the deadline for payment of the fine(s) provided for in this paragraph, -
entails the imposition of a fine in the amount of 5 times the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year, for each calendar day of failure to submit a report on controlled transactions and/or transfer pricing documentation, and/or global transfer pricing documentation (master file), and/or a report by country of an international group of companies, and/or a notification of participation in an international group of companies, but not more than 300 times the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year.
{Article 120 is supplemented by paragraph 120.3 in accordance with Law No. 408-VII of 04.07.2013 ; as amended in accordance with Law No. 1260-VII of 13.05.2014 ; as amended by Laws No. 72-VIII of 28.12.2014 , No. 609-VIII of 15.07.2015 , No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 }
120.4. Failure to include in the submitted report on controlled transactions information on all controlled transactions carried out during the reporting period and/or failure to include in the submitted report by country of an international group of companies information in accordance with the requirements of Article 39 of this Code -
shall entail the imposition of a fine(s) in the amount of:
1 percent of the amount of controlled transactions not declared in the submitted report on controlled transactions, but not more than 300 times the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year, for all undeclared controlled transactions carried out in the relevant reporting year;
1 percent of the amount of income (revenue) of a participant in an international group of companies, information about which, in violation of the requirements of this Code, is not reflected in the report by country of the international group of companies, but not more than 1,000 times the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year.
Failure by a taxpayer to submit a clarifying report on controlled transactions after the expiration of 30 calendar days following the last day of the deadline for payment of the fine(s) provided for in this paragraph, -
entails the imposition of a fine in the amount of one subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, for each calendar day of failure to submit a clarifying report on controlled transactions, but not more than 300 subsistence minimums for an able-bodied person, established by law as of January 1 of the tax (reporting) year.
{Article 120 is supplemented by paragraph 120.4 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
120.5. Providing false information in a notification about participation in an international group of companies and/or in a report by country of an international group of companies -
shall entail the imposition of a fine(s) in the amount of:
50 times the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, - in case of providing inaccurate information in the notification of participation in an international group of companies;
200 times the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, - in case of providing inaccurate information in the report by country of an international group of companies regarding a participant in an international group of companies.
Payment of such fines does not exempt the taxpayer from the obligation to submit a clarifying notification on participation in an international group of companies and/or a clarifying report by country of the international group of companies (including on the basis of a notification to the supervisory authority about errors found in the report by country of the international group of companies).
{Clause 120.5 of Article 120 is supplemented by the fifth paragraph in accordance with Law No. 2970-IX of 20.03.2023 }
Failure to submit a clarifying report by country of the international group of companies within 30 calendar days from the date of receipt of the notification from the supervisory authority about the identified errors in the report by country of the international group of companies shall be considered as the taxpayer's untimely submission of the report by country of the international group of companies, for which the penalty specified in paragraph seven of clause 120.6 of this article shall be applied for each calendar day of untimely submission of the report by country of the international group of companies, starting from the 31st calendar day from the date of receipt of the notification from the supervisory authority about the identified errors in the report by country of the international group of companies.
{Clause 120.5 of Article 120 is supplemented by the sixth paragraph in accordance with Law No. 2970-IX of 20.03.2023 }
The penalty provided for in this paragraph shall not apply if the taxpayer submitted a notification of participation in an international group of companies and/or a report by country of the international group of companies with errors that did not affect the correct identification of the state or territory of which one or more participants in the international group of companies are residents, and/or the correct identification of each participant in the relevant international group of companies, and/or the correct identification of the jurisdiction for submitting the report by country of the international group of companies, and such taxpayer corrected the errors by submitting a clarifying notification of participation in an international group of companies and/or a report by country of the international group of companies independently or no later than 30 calendar days from the date of receipt of the notification from the supervisory authority about the errors identified in the report by country of the international group of companies.
{Clause 120.5 of Article 120 is supplemented by the seventh paragraph in accordance with Law No. 2970-IX of 20.03.2023 }
{Article 120 is supplemented by paragraph 120.5 in accordance with Law No. 466-IX of 16.01.2020 }
120.6. Untimely submission by a taxpayer of a report on controlled transactions and/or transfer pricing documentation, and/or global transfer pricing documentation (master file), and/or a report by country of an international group of companies, and/or a notification of participation in an international group of companies, including untimely submission of a revised report by country of an international group of companies at the request of the regulatory authority, or untimely declaration of controlled transactions in the submitted report in accordance with the requirements of Clause 39.4 of Article 39 of this Code -
{Paragraph one of clause 120.6 of Article 120 as amended by Law No. 2970-IX of 20.03.2023 }
shall entail the imposition of a fine(s) in the amount of:
one amount of the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, for each calendar day of untimely submission of a report on controlled transactions, but not more than 300 amounts of the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year;
one amount of the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, for each calendar day of untimely declaration of controlled transactions in the submitted report on controlled transactions in the case of submitting a clarifying report, but not more than an amount equal to one of the two values, whichever is smaller - either 300 amounts of the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, or 0.5 percent of the amount of controlled transactions not declared in the submitted report on controlled transactions;
{Paragraph four of clause 120.6 of Article 120 as amended by Law No. 4112-IX of 04.12.2024 }
two amounts of the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year, for each calendar day of untimely submission of transfer pricing documentation, specified in subparagraphs 39.4.6 and 39.4.9 of paragraph 39.4 of Article 39 of this Code, but not more than 200 amounts of the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year;
three amounts of the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year, for each calendar day of untimely submission of global transfer pricing documentation, defined by subparagraphs 39.4.7 and 39.4.9 of paragraph 39.4 of Article 39 of this Code, but not more than 300 amounts of the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year;
ten amounts of the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year, for each calendar day of untimely submission of a report by country of the international group of companies (including untimely submission of a revised report by country of the international group of companies at the request of the regulatory authority), but not more than 1,000 amounts of the subsistence minimum for an able-bodied person established by law as of January 1 of the tax (reporting) year;
{Paragraph seven of clause 120.6 of Article 120 as amended by Law No. 2970-IX of 20.03.2023 }
one amount of the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, for each calendar day of untimely submission of a notification of participation in an international group of companies, but not more than 50 amounts of the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year.
{Paragraph eight of clause 120.6 of Article 120 as amended by Law No. 4112-IX of 04.12.2024 }
{Article 120 is supplemented by paragraph 120.6 in accordance with Law No. 466-IX of January 16, 2020 }
120.7. Failure by a controlling entity to submit a report on controlled foreign companies -
entails the imposition of a fine in the amount of 100 subsistence minimums for an able-bodied person, established by law as of January 1 of the tax (reporting) year.
Untimely submission by the controlling entity of a report on controlled foreign companies -
entails the imposition of a fine in the amount of one subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, for each calendar day of failure to submit, but not more than 50 subsistence minimums for an able-bodied person, established by law as of January 1 of the tax (reporting) year.
Failure by a controlling entity to disclose information on existing controlled foreign companies in the report on controlled foreign companies and/or failure to disclose information specified in subparagraphs "d" - "z" of subparagraph 39 - 2 .5.3 of paragraph 39 - 2 .5 of Article 39 - 2 of this Code regarding existing controlled foreign companies -
shall entail the imposition of a fine in the amount of 3 percent of the amount of income of controlled foreign companies or 25 percent of the adjusted profit of the controlled foreign company for the relevant year not reflected in the report on controlled foreign companies, depending on which of these values is greater, but not more than 1,000 subsistence minimums for an able-bodied person established by law as of January 1 of the tax (reporting) year, for each fact of failure to reflect the controlled foreign company and/or for all unrecognized amounts.
Failure by a controlling entity to notify the controlling body of the acquisition of a share in a foreign legal entity, an entity without the status of a legal entity, or of the beginning of the exercise of actual control over a foreign legal entity, or of the alienation of a share in a foreign legal entity, or of the termination of the exercise of actual control over a foreign legal entity within the terms provided for in subparagraph 39 - 2 .5.5 of paragraph 39 - 2 .5 of Article 39 - 2 of this Code, -
entails the imposition of a fine in the amount of 300 subsistence minimums for an able-bodied person, established by law as of January 1 of the tax (reporting) year, for each such fact.
Failure or incomplete submission by a controlling entity of transfer pricing documentation and other copies of primary documents regarding a controlled foreign company at the request of the controlling body in cases provided for in Article 39-2 of this Code, -
entails the imposition of a fine in the amount of 3 percent of the amount of income of the controlled foreign company for which documentation and/or copies of primary documents were not submitted, but not more than 1,000 subsistence minimums for an able-bodied person established by law as of January 1 of the tax (reporting) year.
Payment of such financial sanctions (fines) does not exempt the taxpayer from the obligation to submit a report on controlled foreign companies and supporting documents provided for in Article 39-2 of this Code.
Failure to submit a report on controlled foreign companies within 30 calendar days following the last day of the deadline for payment of financial sanctions (fines) provided for in this paragraph -
entails the imposition of a fine in the amount of five subsistence minimums for an able-bodied person established by law as of January 1 of the tax (reporting) year for each calendar day of failure to submit a report on controlled foreign companies, but not more than 300 subsistence minimums for an able-bodied person established by law as of January 1 of the tax (reporting) year.
{Article 120 is supplemented by paragraph 120.7 in accordance with Law No. 466-IX of January 16, 2020 }
Article 120 - 1. Violation of the deadlines for registering a tax invoice and/or calculating adjustments in the Unified Register of Tax Invoices and making errors when specifying the mandatory details of a tax invoice↑
120 - 1 .1. Violation by value added tax payers of the deadline provided for in Article 201 of this Code for registering a tax invoice and/or calculating an adjustment to such a tax invoice in the Unified Register of Tax Invoices (except for a tax invoice/calculation of adjustment drawn up for transactions on the supply of goods/services that are exempt from taxation by value added tax; a tax invoice/calculation of adjustment drawn up for transactions that are taxed at a zero rate; a tax invoice drawn up in accordance with paragraph 198.5 of Article 198 of this Code in the case of transactions specified in subparagraphs "a" - "g" of this paragraph, and a calculation of adjustment drawn up for such a tax invoice; a tax invoice drawn up in accordance with Article 199 of this Code and a calculation of adjustment drawn up for such a tax invoice; a tax invoice drawn up in accordance with paragraph eleven of paragraph 201.4 of Article 201 of this Code, and the calculation of the adjustment made to such a tax invoice) shall entail the imposition on the value added tax payer, who, in accordance with the requirements of Articles 192 and 201 of this Code, is obliged to register, a fine in the amount of:
{Paragraph one of clause 120 - 1 .1 of Article 120 - 1 as amended by Law No. 466-IX of 01.16.2020 ; as amended by Law No. 786-IX of 07.14.2020 }
10 percent of the amount of value added tax indicated in such tax invoices /adjustment calculations - in case of violation of the registration deadline by up to 15 calendar days;
{Paragraph two of paragraph 120 - 1 .1 of Article 120 - 1 in connection with paragraph one of paragraph 120 - 1 .1 of Article 120 - 1 is recognized as complying with the Constitution of Ukraine (is constitutional), in accordance with the Decision of the Constitutional Court No. 5-r(II)/2025 of 26.11.2025 }
20 percent of the amount of value added tax indicated in such tax invoices /adjustment calculations - in case of violation of the registration deadline from 16 to 30 calendar days;
30 percent of the amount of value added tax indicated in such tax invoices /adjustment calculations - in case of violation of the registration deadline from 31 to 60 calendar days;
40 percent of the amount of value added tax indicated in such tax invoices /adjustment calculations - in case of violation of the registration deadline from 61 to 365 calendar days;
50 percent of the amount of value added tax indicated in such tax invoices /adjustment calculations - in case of violation of the registration deadline for 366 or more calendar days.
{Paragraph 120 - 1 .1 of Article 120 - 1 is supplemented with a new paragraph in accordance with Law No. 2198-VIII of 09.11.2017 }
In the event of violation by value added tax payers of the deadline provided for in Article 201 of this Code for registering a tax invoice and/or calculating adjustments to such a tax invoice in the Unified Register of Tax Invoices, this shall entail the imposition on the value added tax payer, who, in accordance with the requirements of Articles 192 and 201 of this Code, is obliged to register, a fine in the amount of 2 percent of the volume of supply (excluding value added tax), but not more than 1,020 hryvnias, upon registration in the Unified Register of Tax Invoices:
{Paragraph 120 - 1 .1 of Article 120 - 1 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
tax invoice /adjustment calculation drawn up for transactions for the supply of goods/services that are exempt from value added tax;
{Paragraph 120 - 1 .1 of Article 120 - 1 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
tax invoice /adjustment calculation drawn up for transactions taxed at a zero rate;
{Paragraph 120 - 1 .1 of Article 120 - 1 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
tax invoice drawn up in accordance with clause 198.5 of Article 198 of this Code in the event of the performance of operations specified in subparagraphs "a" - "d" of clause 198.5 of Article 198 of this Code, and the calculation of the adjustment drawn up for such tax invoice;
{Paragraph 120 - 1 .1 of Article 120 - 1 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
tax invoice drawn up in accordance with Article 199 of this Code, and the calculation of the adjustment drawn up for such tax invoice;
{Paragraph 120 - 1 .1 of Article 120 - 1 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
tax invoice prepared in accordance with paragraph eleven of paragraph 201.4 of Article 201 of this Code, and the calculation of the adjustment prepared for such tax invoice.
{Clause 120 - 1 .1 of Article 120 - 1 is supplemented with a new paragraph in accordance with Law No. 466-IX of 16.01.2020 ; with amendments made in accordance with Law No. 786-IX of 14.07.2020 }
In the event of suspension of registration of a tax invoice /adjustment calculation in the Unified Register of Tax Invoices in accordance with Clause 201.16 of Article 201 of this Code, the penalties provided for in this Clause shall not apply for the period of suspension of such registration until a decision is made to resume registration of such tax invoices/adjustment calculations.
{Paragraph thirteen of clause 120 - 1 .1 of article 120 - 1 as amended by Law No. 466-IX of 16.01.2020 }
In the event of registration of a tax invoice and/or calculation of adjustments to a tax invoice prior to the start of an inspection, the subject of which is compliance with the requirements of this Code regarding the timeliness of registration of such documents in the Unified Register of Tax Invoices, the penalties provided for in paragraph 120 - 1.2 of this Article shall not apply.
120 - 1 .2. Failure to register, within the time limit provided for in Article 201 of this Code, a tax invoice and/or an adjustment calculation to such a tax invoice in the Unified Register of Tax Invoices (except for a tax invoice/adjustment calculation drawn up for transactions on the supply of goods/services that are exempt from value added tax; a tax invoice/adjustment calculation drawn up for transactions that are taxed at a zero rate, a tax invoice drawn up in accordance with Clause 198.5 of Article 198 of this Code in the case of transactions specified in subparagraphs "a" - "d" of Clause 198.5 of Article 198 of this Code, and an adjustment calculation drawn up for such a tax invoice, a tax invoice drawn up in accordance with Article 199 of this Code, and an adjustment calculation drawn up for such a tax invoice, a tax invoice drawn up in accordance with paragraph eleven of Clause 201.4 of Article 201 of this Code), which is specified in the tax notice-decision drawn up based on the results of the inspection by the controlling body, - entails the imposition on the taxpayer of a fine in the amount of 50 percent of the amount of tax liabilities for value added tax indicated in such tax invoice and/or adjustment calculation to the tax invoice, or of the amount of value added tax charged for the transaction for the supply of goods/services, if a tax invoice for such transaction has not been drawn up. In the event of suspension of registration of a tax invoice/adjustment calculation in the Unified Register of Tax Invoices in accordance with Clause 201.16 of Article 201 of this Code, the penalties provided for in this Clause shall not apply for the period of suspension of such registration until the adoption of the relevant decision on the resumption of registration of such tax invoices/adjustment calculations.
{Paragraph one of clause 120 - 1 .2 of Article 120 - 1 as amended by Law No. 466-IX of January 16, 2020 }
a tax invoice and/or calculation of adjustments to such a tax invoice in the Unified Register of Tax Invoices , specified in the first paragraph of this paragraph, after the expiration of 10 calendar days following the date of receipt by the taxpayer of the tax notice-decision, shall entail the imposition on the taxpayer of a fine in the amount of 50 percent of the amount of tax liabilities for value added tax specified in such tax invoice and/or calculation of adjustments to the tax invoice or of the amount of value added tax charged for the transaction for the supply of goods/services, if a tax invoice for such a transaction has not been drawn up.
In the event of registration in the Unified Register of Tax Invoices of a tax invoice and/or calculation of adjustments to such a tax invoice, specified in the first paragraph of this paragraph, within 10 calendar days following the date of receipt by the taxpayer of the tax notice-decision, the penalties provided for in the second paragraph of this paragraph and in paragraph 120 - 1.1 of this article shall not apply.
In the absence of registration in the Unified Register of Tax Invoices of a tax invoice /adjustment calculation drawn up for transactions on the supply of goods/services exempt from VAT, and/or a tax invoice/adjustment calculation drawn up for transactions taxed at a zero rate, a tax invoice drawn up in accordance with Clause 198.5 of Article 198 of this Code in the event of transactions specified in subparagraphs "a" - "d" of Clause 198.5 of Article 198 of this Code, and an adjustment calculation drawn up for such a tax invoice, a tax invoice drawn up in accordance with Article 199 of this Code, and an adjustment calculation drawn up for such a tax invoice, a tax invoice drawn up in accordance with paragraph eleven of Clause 201.4 of Article 201 of this Code, within the deadline provided for by Article 201 of this Code for registration of a tax invoice invoice and/or calculation of adjustments to such a tax invoice in the Unified Register of Tax Invoices, which is indicated in the tax notice-decision drawn up based on the results of the inspection by the regulatory authority, - entails the imposition on the taxpayer of a fine in the amount of 5 percent of the supply volume (excluding value added tax), but not more than 3,400 hryvnias.
{Paragraph 120 - 1 .2 of Article 120 - 1 is supplemented by the fourth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
120 - 1 .3. The seller of goods/services making errors when indicating the mandatory details of the tax invoice , provided for in paragraph 201.1 of Article 201 of this Code, detected by the supervisory authority based on the results of the inspection conducted at the request of the buyer, entails the imposition of a fine of 170 hryvnias on the taxpayer - the seller and the obligation to correct such errors.
Failure to comply with the tax notice-decision of the regulatory authority with a warning about the need for the taxpayer - seller to correct the errors specified in the first paragraph of this paragraph within 10 calendar days following the date of its receipt - entails the imposition of a fine on such taxpayer in the amount of:
10 percent of the amount of value added tax indicated in such tax invoice - if errors are not corrected within 15 calendar days;
20 percent of the amount of value added tax indicated in such tax invoice - in case of failure to correct errors within 16 to 30 calendar days;
30 percent of the amount of value added tax indicated in such tax invoice - in case of failure to correct errors within a period of 31 to 60 calendar days;
40 percent of the amount of value added tax indicated in such tax invoice - in case of failure to correct errors within a period of 61 to 90 calendar days;
50 percent of the amount of value added tax indicated in such tax invoice - in case of failure to correct errors within a period of 91 to 120 calendar days;
60 percent of the amount of value added tax indicated in such tax invoice - in case of failure to correct errors within a period of 121 to 150 calendar days;
70 percent of the amount of value added tax indicated in such tax invoice - in case of failure to correct errors within a period of 151 to 180 calendar days;
100 percent of the amount of value added tax indicated in such tax invoice - if errors are not corrected after the expiration of 181 calendar days.
{The Code is supplemented by Article 120 - 1 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Laws No. 643-VIII of 16.07.2015 , No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
Article 120 - 2. Violation of the procedure for registering excise invoices and calculating adjustments to such excise invoices in the Unified Register of Excise Invoices↑
120 - 2 .1. Violation by excise tax payers of the deadlines for registering the first copies of excise invoices/first copies of adjustment calculations to excise invoices in the Unified Register of Excise Invoices, established by Article 231 of this Code, or failure to compile or register them in the Unified Register of Excise Invoices, established based on the results of a documentary check, -
entails the imposition of a fine in the amount of:
2 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol specified in such excise invoices/adjustment calculations, or 2 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol for which excise invoices have not been drawn up or registered - in case of violation of the registration deadline or lack of registration for up to 15 calendar days;
10 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol specified in such excise invoices/adjustment calculations, or 10 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol for which excise invoices have not been drawn up or registered - in case of violation of the registration deadline or lack of registration from 16 to 30 calendar days;
20 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol specified in such excise invoices/adjustment calculations, or 20 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol for which excise invoices have not been drawn up or registered - in case of violation of the registration deadline or lack of registration from 31 to 60 calendar days;
30 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol specified in such excise invoices/adjustment calculations, or 30 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol for which excise invoices have not been drawn up or registered - in case of violation of the registration deadline or lack of registration for 61 to 90 calendar days;
40 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol specified in such excise invoices/adjustment calculations, or 40 percent of the amount of excise tax on the corresponding volumes of fuel or ethyl alcohol for which excise invoices have not been drawn up or registered - in case of violation of the registration deadline or absence of registration for 91 or more calendar days.
{Clause 120 - 2 .1 of Article 120 - 2 as amended by Law No. 2628-VIII of 11/23/2018 ; as amended by Law No. 391-IX of 12/18/2019 }
120 - 2 .2. Failure, due to the fault of the excise tax payer, to register the first copy of the excise invoice/the first copy of the calculation of the adjustment to the excise invoice in the Unified Register of Excise Invoices after the expiration of 10 calendar days from the date of receipt by the taxpayer of the tax notice-decision on the application of a fine in accordance with clause 120 - 2 .1 of this article, -
{Paragraph one of clause 120 - 2 .2 of Article 120 - 2 as amended by Law No. 391-IX of 18.12.2019 }
entails the imposition of a fine in the amount of 50 percent of the amount of excise tax on the relevant volumes of fuel or ethyl alcohol for which the taxpayer is obliged to draw up such an excise invoice/adjustment calculation.
{Paragraph two of clause 120 - 2 .2 of article 120 - 2 as amended by Law No. 2628-VIII of 23.11.2018 }
When registering the first copy of excise invoices/the first copy of the adjustment calculation in the Unified Register of Excise Invoices, for the lack of registration of which the excise tax payer was subject to a fine provided for in this paragraph or in paragraph 120 - 2.1 of this Article, the fines for the excise tax payer's violation of the deadlines for registering the first copy of such excise invoice/such first copy of the adjustment calculations for the excise invoice in the Unified Register of Excise Invoices, provided for in paragraph 120 - 2.1 of this Article, shall not apply.
{Paragraph 120 - 2 .2 of Article 120 - 2 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
Failure, through the fault of the excise tax payer who received fuel or ethyl alcohol, to register the second copy of the excise invoice/second copy of the adjustment calculation in the Unified Register of Excise Invoices for more than 120 calendar days after the deadline for registering the second copy of the excise invoice/adjustment calculation -
{Clause 120 - 2 .2 of Article 120 - 2 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
shall entail the imposition of a fine in the amount of 2 percent of the amount of excise tax on the relevant volumes of fuel or ethyl alcohol specified in such excise invoice/adjustment calculation.
{Clause 120 - 2 .2 of Article 120 - 2 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
120 - 2 .3. The amount of excise tax for the purposes of paragraphs 120 - 2 .1 and 120 - 2 .2 of this article is determined at the rate established on the date of sale of fuel and the exchange rate of the National Bank of Ukraine in effect on the first day of the quarter in which the fuel is sold, and for ethyl alcohol - at the rate established on the date of sale of ethyl alcohol.
{Clause 120 - 2 .3 of Article 120 - 2 as amended by Law No. 2628-VIII of 23.11.2018 }
{The Code is supplemented by Article 120 - 2 in accordance with Law No. 909-VIII of 24.12.2015 }
Article 121. Violation of the statutory retention periods for documents on the calculation and payment of taxes and fees, as well as documents related to the fulfillment of the requirements of other legislation, control over compliance with which is entrusted to regulatory authorities
121.1. Failure by a taxpayer to store primary documents, accounting and other registers, accounting and statistical reporting, other documents on the calculation and payment of taxes and fees within the storage periods established by Article 44 of this Code and/or failure by a taxpayer to provide the controlling authorities with original documents (except for documents obtained from the Unified Register of Tax Invoices) or their copies when carrying out tax control in cases provided for by this Code, -
{Paragraph one of clause 121.1 of Article 121 as amended by Law No. 643-VIII of 16.07.2015 }
entail a fine of 1020 hryvnias.
{Paragraph two of clause 121.1 of Article 121 as amended by Law No. 466-IX of 16.01.2020 }
The same actions committed by a taxpayer who was fined for the same violation during the year -
entail a fine of 2040 hryvnias.
{Paragraph four of clause 121.1 of Article 121 as amended by Law No. 466-IX of January 16, 2020 }
{Clause 121.1 of Article 121 as amended by Law No. 657-VII of 24.10.2013 }
121.2. Failure to respond to a request, failure to submit or incomplete submission by a taxpayer, financial agent or other person of documents or other information at the request of a regulatory authority, sent in accordance with the grounds provided for in subparagraphs 6-8 of subparagraph 73.3.1 of paragraph 73.3 of Article 73 of the Code, -
entails the imposition of a fine in the amount of 5 times the minimum wage established by law as of January 1 of the tax (reporting) year for each such fact.
Failure to submit or incomplete submission by a taxpayer of documents or other information at the request of a regulatory authority in other cases provided for by Article 73 of the Code -
entails the imposition of a fine in the amount of one minimum wage established by law as of January 1 of the tax (reporting) year for each such fact.
Payment of such financial sanctions (fines) does not exempt a person from the obligation to submit information.
{ Article 121 supplemented by paragraph 121.2 in accordance with Law No. 2970-IX of 20.03.2023 }
121.3. Failure to submit or incomplete submission of information on the ownership structure or on the ultimate beneficial owner independently or at the request of the regulatory authority in cases provided for in Article 44 - 1 of this Code, -
entails the imposition of a fine in the amount of 5 times the minimum wage established by law as of January 1 of the tax (reporting) year for each such fact.
Payment of such financial sanctions (fines) does not exempt from the obligation to submit information provided for in Article 44-1 of this Code.
The fine shall be applied to taxpayers specified in Clause 44-1.1 of Article 44-1 of this Code who have notified the supervisory authority in accordance with the established procedure of their independent submission of information to the supervisory authority. In the event that the taxpayer appoints an authorized bank that is required to provide information at the request of the supervisory authority in accordance with Clause 44-1.3 of Article 44-1 of this Code, the fine shall be applied to the authorized bank.
{ Article 121 supplemented by paragraph 121.3 in accordance with Law No. 2970-IX of 20.03.2023 }
121.4. Failure by a resident of Ukraine to notify of the conclusion of an agreement on the management or administration of a trust, or of the termination of such an agreement within the terms provided for in Article 44-2 of this Code, -
entails the imposition of a fine in the amount of 5 times the minimum wage established by law as of January 1 of the tax (reporting) year for each such fact.
Payment of a fine does not exempt the responsible person from the obligation to submit a notice of the conclusion of an agreement on the management or administration of the trust, or of the termination of such an agreement.
{ Article 121 supplemented by paragraph 121.4 in accordance with Law No. 2970-IX of 20.03.2023 }
121.5. Failure to submit or incomplete submission by a person managing or administering a trust of financial statements, copies of primary documents and other information regarding the trust at the request of the supervisory authority in cases provided for in Article 44-2 of this Code, -
entails the imposition of a fine of 10 times the minimum wage established by law as of January 1 of the tax (reporting) year for each such fact.
the relevant person from the obligation to submit information and documents provided for in Article 44-2 of this Code.
{ Article 121 supplemented by paragraph 121.5 in accordance with Law No. 2970-IX of 20.03.2023 }
Article 122. Violation of the rules for applying the simplified taxation system by an individual entrepreneur↑
122.1. Failure to pay (fail to transfer) or payment (transfer) not in full by an individual - a single tax payer, defined by subparagraphs 1 and 2 of paragraph 291.4 of Article 291 of this Code, of advance payments of the single tax in the manner and within the terms specified by this Code, shall entail the imposition of a fine in the amount of 50 percent of the single tax rate selected by the single tax payer in accordance with this Code.
{Clause 122.1 of Article 122 as amended by Law No. 4014-VI of 04.11.2011 ; as amended by Law No. 466-IX of 16.01.2020 }
Article 123. Penalty (financial) sanctions (fines) in the event of the controlling body determining the amount of a tax liability and/or other liability, control over the payment of which is entrusted to the controlling bodies, a reduction in budget compensation, or the detection of facts of using tax benefits not for their intended purpose or contrary to the conditions or goals of their provision
123.1. The taxpayer commits acts that resulted in the determination by the controlling body of the amount of the tax liability and/or other liability, the control over the payment of which is entrusted to the controlling bodies, a reduction in the amount of budget compensation and/or a negative value of the amount of the taxpayer's value added tax on the grounds specified in subparagraphs 54.3.1 , 54.3.2 (except for cases of a reduction in the amount of personal income tax declared before the refund from the budget in connection with the exercise of the right to a tax discount), 54.3.6 , paragraph 54.3 of Article 54 of this Code, -
entails the imposition on the taxpayer of a fine in the amount of 10 percent of the amount of the specified tax liability and/or other liability, the payment control of which is entrusted to the regulatory authorities, of the overstated amount of budget compensation.
123.2. The acts provided for in paragraph 123.1 (except for the acts provided for in paragraph 123.2 - 1 ) of this article, committed intentionally, -
{Paragraph one of clause 123.2 of Article 123 as amended by Law No. 4112-IX of 04.12.2024 }
entail the imposition of a fine in the amount of 25 percent of the amount of the specified tax liability and/or other liability, the control over the payment of which is entrusted to the regulatory authorities, of the overstated amount of budget compensation.
123.2 - 1 . The taxpayer's actions that resulted in the supervisory authority determining the amount of the tax liability on the basis of subparagraph 54.3.2 of paragraph 54.3 of Article 54 of this Code with the adjustment of the financial result before taxation of the relevant tax (reporting) periods by the difference provided for in subparagraph 140.6.2 of paragraph 140.6 of Article 140 of this Code, or determining the objects of taxation of a resident of the City of Diya - a taxpayer under special conditions for transactions specified in subparagraph 141.9 - 1 .2.17 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of Article 141 of this Code, or as a result of the supervisory authority's failure to take into account (recognize) expenses on the grounds specified in paragraphs six and seven of subparagraph 177.4.5 of paragraph 177.4 of Article 177 or paragraphs six and seven of clause 178.3 of Article 178 of this Code, -
entails the imposition of a fine in the amount of 50 percent of the amount of the determined tax liability.
{ Article 123 supplemented by paragraph 123.2 - 1 according to Law No. 4112-IX of 04.12.2024 }
123.3. The acts provided for in paragraph 123.2 of this article, committed repeatedly within 1095 calendar days, -
entail the imposition of a fine in the amount of 50 percent of the amount of the specified tax liability and/or other liability, the payment control of which is entrusted to the regulatory authorities, of the overstated amount of budget compensation.
123.4. Use by a taxpayer (taxpayer's officials) of amounts not paid to the budget as a result of receiving (applying) a tax benefit, for purposes other than those for which it was granted and/or contrary to the conditions or goals of its provision in accordance with the law on the relevant tax, fee, payment, in addition to other liability specified in this Code, -
entail the imposition of a fine in the amount of the amounts that were used for purposes other than those intended and/or contrary to the conditions or purposes of providing such benefits.
123.5. The acts provided for in paragraph 123.4 of this article, committed intentionally, -
entail the imposition of a fine in the amount of double the amount of the amounts that were used for purposes other than those intended and/or contrary to the conditions or purposes of providing such benefits.
123.6. Payment of a fine does not exempt such persons from liability for intentional tax evasion.
{ Article 123 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 466-IX of 16.01.2020 }
Article 123 - 1. Violation of requirements for long-term life insurance contracts or insurance contracts within the framework of non-state pension provision, in particular, supplementary pension insurance↑
If a long-term life insurance contract or an insurance contract within the framework of non-state pension provision, in particular, a supplementary pension insurance contract, is terminated during the first five years of its validity for any reason, except for the case provided for in paragraph four of this article, before the expiration of its minimum term of validity or before the occurrence of a relevant insured event established by this Code and other legislation, as a result of which a partial insurance payment occurs, payment of the redemption amount or complete termination of the insurer's obligations under such a contract to such a taxpayer or other requirements established by this Code for such contracts, as well as requirements for voluntary health insurance contracts, are violated, except for the case provided for in paragraph four of this article, then the taxpayer-insured who recognized expenses in accounting is obliged to increase the financial result before taxation of the reporting period by the amount of such previously paid payments, contributions, premiums with the accrual of a penalty in the amount of 120 percent of the discount rate of the National Bank of Ukraine, which was in effect at the end of the reporting period in which the contract was terminated or such contract ceased to meet the requirements provided for by this Code.
Tax liabilities of the insurer in connection with the circumstances specified in the first paragraph of this sub-item, for the period until the end of the reporting period in which the long-term life insurance contract or the insurance contract within the framework of non-state pension provision, in particular, the supplementary pension insurance contract, was terminated, or such a contract or voluntary health insurance contract ceased to meet the requirements provided for by this Code, are not subject to adjustment.
Penalties for understating the object of taxation for income tax in the cases specified in this subparagraph shall not apply to either the insurer or the taxpayer.
A long-term life insurance contract, a health insurance contract, or an insurance contract within the framework of non-state pension provision, in particular, a supplementary pension insurance contract, in which the insured is the employer, may provide for:
change of the insured (employer) to a new insured, which may be either a new employer or the insured person, in the event of the insured person's dismissal;
changing the insurer to a new insurer.
In this case, such a change of the insured (insurer) must be confirmed by a tripartite agreement between the insured (insurer), the new insured (insurer) and the insurer (insured), subject to obtaining the appropriate consent from the insured person in accordance with the procedure specified by law and/or the insurance contract.
{Paragraph seven of Article 123 - 1 as amended by Law No. 2888-IX of 12.01.2023 }
{The Code is supplemented by Article 123 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
Article 124. Violation of the rules for payment (transfer) of a monetary obligation↑
124.1. If a taxpayer fails to pay the agreed amount of a monetary obligation (except for a monetary obligation in the form of punitive (financial) sanctions applied to him on the basis of this Code or other legislation, control over which is entrusted to regulatory authorities, as well as a penalty applied to him on the basis of this Code or other legislation, control over which is entrusted to regulatory authorities) within the terms specified by this Code, such taxpayer shall be held liable in the form of a fine in the following amounts:
in case of delay up to 30 calendar days inclusive, following the last day of the deadline for payment of the amount of the monetary obligation, - in the amount of 5 percent of the repaid amount of the tax debt;
if the delay is more than 30 calendar days following the last day of the deadline for payment of the amount of the monetary obligation - in the amount of 10 percent of the repaid amount of the tax debt.
If the crediting of funds from the electronic account in the electronic administration system of value added tax in payment of the agreed amount of the monetary obligation specified in the clarifying calculation to the tax return is carried out on the next operating day, the penalties specified in this paragraph shall not apply.
{Paragraph four of clause 124.1 of Article 124 as amended by Law No. 2888-IX of 12.01.2023 }
124.1 - 1. In the event of a taxpayer's failure to meet the deadline for paying the amount of excise tax to the budget, as provided for in paragraph two of subparagraph 222.1.2 of paragraph 222.1 of Article 222 of this Code, such taxpayer shall be held liable in the form of a fine in the amount of 10 percent of the amount of such excise tax.
{Article 124 is supplemented by paragraph 124.1 - 1 in accordance with Law No. 1914-IX of 30.11.2021 }
124.2. Actions provided for in paragraphs 124.1 , 124.1 - 1 of this article, committed intentionally, -
{Paragraph one of clause 124.2 of Article 124 as amended by Law No. 1914-IX of 30.11.2021 }
entail the imposition of a fine in the amount of 25 percent of the amount of the unpaid (untimely paid) monetary obligation.
124.3. Actions provided for in paragraph 124.2 of this article, committed repeatedly within 1095 calendar days or which resulted in a delay in payment of a monetary obligation for a period of more than 90 calendar days, -
entail the imposition of a fine in the amount of 50 percent of the amount of the unpaid (untimely paid) monetary obligation.
124.4. For violation of the deadline for crediting taxes to budgets or state trust funds established by the Law of Ukraine "On Payment Services", due to the fault of a bank, a body that provides treasury services for budget funds, a non-bank payment service provider, an acquirer, an issuer of electronic money, such a bank/body, a non-bank payment service provider, an issuer of electronic money shall pay fines in the amounts established by paragraph 124.1 of this Article.
{Clause 124.4 of Article 124 as amended by Law No. 2888-IX of 12.01.2023 }
124.5. If the regulatory authority has not sent (delivered) a tax notice/tax decision on property tax to an individual within the time limits established by the relevant provisions of this Code, individuals are exempt from liability provided for by this Code for untimely payment of a tax liability.
{Article 124 as amended by Law No. 466-IX of January 16, 2020, taking into account the amendments made by Law No. 1117-IX of December 17, 2020 }
Article 125. {Article 125 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }↑
Article 125 - 1. Violation of the rules for the calculation, withholding and payment (transfer) of taxes at the source of payment↑
125 - 1 .1. Failure to assess and/or withhold, and/or fail to pay (transfer), and/or assess, pay (transfer) taxes not in full by a taxpayer, including a tax agent, before or during the payment of income in favor of a non-resident or another taxpayer, as well as by a non-resident who is obligated to pay tax in accordance with the procedure established by Section III of this Code, -
entail the imposition of a fine in the amount of 10 percent of the amount of tax to be assessed and/or paid to the budget.
125 - 1 .2. The same actions, committed intentionally, -
entail the imposition of a fine in the amount of 25 percent of the amount of tax to be assessed and/or paid to the budget.
125 - 1 .3. The actions provided for in paragraph 125 - 1 .2 of this article, committed repeatedly within 1095 calendar days, -
entail the imposition of a fine in the amount of 50 percent of the amount of tax to be assessed and/or paid to the budget.
125 - 1 .4. The actions provided for in paragraph 125 - 1 .2 of this article, committed within 1095 days for the third time or more, -
entail the imposition of a fine in the amount of 75 percent of the amount of tax to be assessed and/or paid to the budget.
The responsibility for repayment of the amount of tax liability or tax debt arising from such actions and the obligation to repay such tax debt, including penalties, shall be borne by the tax agent. In this case, the taxpayer - recipient of such income shall be exempted from the obligation to repay such amount of tax liability or tax debt, except for the cases established by Section IV of this Code.
A tax agent is exempt from liability in accordance with this clause if the failure to assess, withhold and/or transfer personal income tax is independently detected by the tax agent when recalculating this tax, provided for in clause 169.4 of Article 169 of this Code, and is corrected in subsequent tax periods during the tax (reporting) year in accordance with the provisions of this Code.
{The Code is supplemented with Article 125 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
Article 126. Violation of the procedure for submitting tax information to regulatory authorities by banks, other financial institutions, non-bank payment service providers, and electronic money issuers↑
{Title of Article 126 as amended by Law No. 2888-IX of 12.01.2023 }
126.1. Failure to submit or submission of tax information by banks, other financial institutions, non-bank payment service providers, electronic money issuers in violation of the deadline specified by this Code to regulatory authorities -
{Paragraph one of clause 126.1 of Article 126 as amended by Law No. 2888-IX of 12.01.2023 }
entails a fine of 680 hryvnias.
The same acts committed within a year after the imposition of a fine -
entail a fine of 1,360 hryvnias.
{ Article 126 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 , No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of January 16, 2020 }
Article 126 - 1. Violation of the rules for withholding and payment (transfer) of taxes by tax agents of single tax payers↑
126 - 1 .1. Failure to withhold and/or fail to pay (fail to transfer), and/or fail to pay (transfer) the full amount of the single tax by the tax agent of the third group single tax payer -
entails the imposition of a fine in the amount of 10 percent of the amount of tax subject to withholding and/or payment to the budget.
126 - 1 .2. The same actions committed intentionally, -
entail the imposition of a fine in the amount of 25 percent of the amount of tax subject to withholding and/or payment to the budget.
126 - 1 .3. The actions provided for in paragraph 126 - 1 .2 of this article, committed repeatedly within 1095 calendar days, -
entail the imposition of a fine in the amount of 50 percent of the amount of tax subject to withholding and/or payment to the budget.
126 - 1 .4. The actions provided for in paragraph 126 - 1 .2 of this article, committed within 1095 days for the third or more times, -
entail the imposition of a fine in the amount of 75 percent of the amount of tax subject to withholding and/or payment to the budget.
{The Code is supplemented with Article 126 - 1 in accordance with Law No. 2654-IX of 06.10.2022 }
Article 127. {Article 127 was excluded on the basis of Law No. 466-IX of 16.01.2020 }↑
128.1. Tax offenses of regulatory authorities are unlawful decisions, actions or inactions of regulatory authorities, their officials (service personnel), the commission of which is a basis for compensation for damage to the person whose rights have been violated, in accordance with the law.
128.2. Tax violations, compensation for damage for which, in accordance with paragraph 114.2 of Article 114 of this Code, is allowed as a result of proving only the fact of its commission, are:
128.2.1. making an illegal decision, as well as committing illegal acts (actions or inactions) by the controlling body and/or its officials (service personnel), which led to an unjustified refusal to acquire, as well as to an unjustified loss by a person of the status of a taxpayer or a payer of one of the taxes, the acquisition and/or cancellation (loss) of which occurs by decision of the controlling body;
128.2.2. failure or untimely entry by the controlling body of data into the Register of applications for the return of the amount of budget compensation and/or violation of the deadlines for the start of the desk inspection provided for in paragraph 200.10 of Article 200 of this Code, and in the cases specified in paragraph 200.11 of Article 200 of this Code - the inspection specified in such paragraph, if as a result of such illegal actions the deadlines for the return of the amounts of budget compensation were violated;
128.2.3. adoption by officials (officials) of the controlling body of a decision on the use of property specified in paragraph 87.3 of Article 87 of this Code as a source of repayment of a monetary obligation or tax debt of a taxpayer;
128.2.4. obstruction by officials (service personnel) of the controlling body of the release of a person's property from temporary detention;
128.2.5. illegal use by officials (officials) of the supervisory body of seizure of property or funds in accounts;
128.2.6. unjustified entry by officials (service personnel) of the controlling body of data on the existence of a taxpayer's tax debt or untimely entry or failure to enter data on the absence of a taxpayer's tax debt.
{Article 128 as amended by Law No. 466-IX of 16.01.2020 }
Article 128 - 1. Violation of the rules for accounting, production and circulation of fuel or ethyl alcohol at excise warehouses and/or places of production of certain types of products↑
{Title of Article 128 - 1 as amended by Law No. 2628-VIII of 11/23/2018 ; as amended by Law No. 2284-IX of 05/31/2022 }
128 - 1 .1. Failure to equip and/or register in the Unified State Register of Flowmeters and Level Meters of Fuel Level in a Tank a level meter on a tank put into operation located in an excise warehouse, and/or a flow meter at the place of fuel release in bulk from an excise warehouse located in an excise warehouse, as well as failure to equip and/or register in the Unified State Register of Flowmeters of the Volume of Produced Ethyl Alcohol a flow meter of ethyl alcohol, and/or a mass flow meter at the place of receipt and release of ethyl alcohol located in an excise warehouse, and/or a place of receipt/release of ethyl alcohol for the production of products specified in subparagraphs "d"-"g" of subparagraph 229.1.1 of paragraph 229.1 of Article 229 of this Code, -
{Paragraph one of clause 128 - 1 .1 of Article 128 - 1 as amended by Law No. 2284-IX of 05/31/2022 }
entail a fine of 20,000 hryvnias for each unequipped tank and/or unregistered level meter, as well as for each unequipped place of fuel delivery in bulk from an excise warehouse or for each place of receipt and delivery of ethyl alcohol, and/or unregistered flow meter/flow meter of ethyl alcohol, and/or mass flow meter.
{Paragraph two of clause 128 - 1 .1 of article 128 - 1 as amended by Law No. 2284-IX of 05/31/2022 }
Repeated commission within a year of any of the violations provided for in the first paragraph of this paragraph at the same excise warehouse and/or place of receipt/distribution of ethyl alcohol for the production of products specified in subparagraphs "d"-"g" of subparagraph 229.1.1 of paragraph 229.1 of Article 229 of this Code, -
{Paragraph three of clause 128 - 1 .1 of Article 128 - 1 as amended by Law No. 2284-IX of 05/31/2022 }
entails the imposition of a fine of 50,000 hryvnias for each unequipped tank and/or unregistered level meter, as well as for each unequipped place of dispensing fuel in bulk from an excise warehouse or for each place of receipt and dispensing of ethyl alcohol, and/or unregistered flow meter/flow meter of ethyl alcohol, and/or mass flow meter.
{Paragraph four of clause 128 - 1 .1 of Article 128 - 1 as amended by Law No. 2284-IX of 05/31/2022 }
{Clause 128 - 1 .1 of Article 128 - 1 as amended by Law No. 2628-VIII of 23.11.2018 }
128 - 1 .2. Failure, due to the fault of the taxpayer, to register excise warehouses in the system of electronic administration of the sale of fuel and ethyl alcohol by the taxpayer - the manager of the excise warehouse -
entails the imposition of a fine of 1,000,000 hryvnias.
The same actions committed by a taxpayer who was fined for the same violation during the year -
entail a fine of 2,000,000 hryvnias.
{Article 128 - 1 is supplemented by paragraph 128 - 1 .2 in accordance with Law No. 2628-VIII of 23.11.2018 }
128 - 1 .3. Failure, due to the fault of the manager of an excise warehouse, to timely submit to the central executive body implementing state tax policy electronic documents containing data on actual fuel residues and the volume of fuel or ethyl alcohol turnover, -
entails a fine of 1,000 hryvnias for each unsubmitted electronic document.
{Article 128 - 1 is supplemented by paragraph 128 - 1 .3 in accordance with Law No. 2628-VIII of 23.11.2018 }
{Chapter 11 is supplemented by Article 128 - 1 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 2245-VIII of 07.12.2017 }
129.1.1. when the controlling authority assesses a tax liability in cases established by this Code that are not related to conducting an audit, or when the controlling authority assesses a monetary liability determined based on the results of an audit, - starting from the first business day following the last day of the deadline for payment by the taxpayer of such liability, determined in the tax notice-decision in accordance with this Code;
{Subclause 129.1.1 of Clause 129.1 of Article 129 as amended by Law No. 466-IX of 16.01.2020 }
129.1.2. when assessed by a controlling body based on the results of an audit of a tax liability and/or other liability, the control over the payment of which is entrusted to the controlling bodies, in the event of its understatement being detected - by the amount of such understatement, starting from the first business day following the last day of the deadline for payment by the taxpayer of this liability for the relevant tax (reporting) period for which the understatement was detected, and for the entire period of understatement (including the period of administrative and/or judicial appeal);
{Subclause 129.1.2 of clause 129.1 of Article 129 as amended by Law No. 466-IX of 16.01.2020 }
129.1.3. when calculating the amount of a monetary obligation determined by a taxpayer or tax agent, including in the event of amendments to tax reporting as a result of the taxpayer independently identifying errors in accordance with Article 50 of this Code, - after the expiration of 90 calendar days following the last day of the deadline for payment of the tax obligation.
{Subclause 129.1.3 of Clause 129.1 of Article 129 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
129.1.4. if the supervisory authority, based on the results of the inspection, detects an understatement of the tax liability by the tax agent when calculating (paying) taxable income in favor of non-residents or other taxpayers and/or untimely payment, non-payment (non-transfer) of withheld (accrued) taxes by the tax agent before or during the payment of taxable income in favor of a non-resident or other taxpayer - starting from the first business day following the last day of the deadline for payment by the tax agent of the amount of the tax liability determined by this Code;
{Clause 129.1 of Article 129 is supplemented by subparagraph 129.1.4 in accordance with Law No. 466-IX of 16.01.2020 }
129.1.5. in case of untimely return of overpaid/erroneously paid payments, as well as untimely reimbursement of value added tax amounts - starting from the first day following the last day of the deadline for the return of such funds;
{Clause 129.1 of Article 129 is supplemented by subparagraph 129.1.5 in accordance with Law No. 466-IX of 16.01.2020 }
{Clause 129.1 of Article 129 as amended by Law No. 655-VIII of July 17, 2015 ; as amended by Law No. 1797-VIII of December 21, 2016 }
129.2. In the event of cancellation of a monetary obligation (part thereof) assessed by the controlling authority through administrative and/or judicial appeal, the penalty assessed on such monetary obligation (part thereof) or on the identified underestimation of the tax obligation shall be canceled.
{Clause 129.2 of Article 129 as amended by Law No. 466-IX of January 16, 2020 }
129.3. The accrual of a penalty shall terminate (except for the penalty provided for in subparagraphs 129.1.2 , 129.1.4 of paragraph 129.1 of this Article):
{Paragraph one of clause 129.3 of Article 129 as amended by Law No. 466-IX of 16.01.2020 }
129.3.1. on the day of crediting funds to the relevant account of the body that provides treasury services for budget funds to the relevant account of the taxpayer and/or in other cases of repayment of tax debt and/or monetary obligations;
{Subclause 129.3.1 of Clause 129.3 of Article 129 as amended by Laws No. 5083-VI of 05.07.2012 , No. 466-IX of 16.01.2020 }
129.3.2. on the day of mutual settlements of outstanding counter-monetary obligations of the relevant budget to such taxpayer;
129.3.3. on the day of the introduction of a moratorium on the satisfaction of creditors' claims (upon the issuance of a relevant court ruling in a bankruptcy case or the adoption of a relevant decision by the National Bank of Ukraine);
129.3.4. when making a decision to cancel or write off the amount of tax debt (part thereof).
129.3.4 - 1. The accrual of the penalty provided for in subparagraph 129.1.2 of paragraph 129.1 of this Article shall end on the date of the maturity of the monetary obligation determined by the supervisory authority based on the results of the inspection. Such penalty shall be accrued on the date of the end of its accrual for the entire period of understatement of the tax obligation, starting from the date specified in subparagraph 129.1.2 of paragraph 129.1 of this Article, until the date of the end.
{Clause 129.3 of Article 129 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
The accrual of the penalty provided for in subparagraph 129.1.4 of paragraph 129.1 of this Article shall end:
{Clause 129.3 of Article 129 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
in the event that the controlling body discovers the fact of untimely payment, non-payment (non-transfer) of the amounts of tax liabilities determined by the tax agent - on the day of payment (repayment) of these amounts of tax liabilities by the tax agent;
{Clause 129.3 of Article 129 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
in the event that the controlling body discovers that a tax agent has understated tax liabilities when calculating (paying) taxable income in favor of non-residents or other taxpayers - on the day of the tax liability repayment deadline determined by the controlling body based on the results of the inspection. For tax agents who have understated tax liabilities when calculating (paying) taxable income in favor of non-residents, such a penalty shall be accrued on the day of the end of its accrual for the entire period of understating the tax liability, starting from the day specified in subparagraph 129.1.4 of paragraph 129.1 of this article, until the day of the end.
{Clause 129.3 of Article 129 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
For tax agents who pay taxable income to other taxpayers, such a penalty shall be charged for the entire period of understatement of the tax liability, starting from the day specified in subparagraph 129.1.4 of paragraph 129.1 of this Article, until the day of the maturity date of the tax liability determined by the controlling authority.
{Clause 129.3 of Article 129 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
In the event of partial repayment of the tax debt, the amount of such share is determined taking into account the penalty accrued on such share.
129.4. On the amount of the monetary obligation determined by subparagraph 129.1.1 of paragraph 129.1 of this Article (including the amount of penalties, if any, and excluding the amount of the penalty) and in other cases of determining the penalty in accordance with the requirements of this Code, if its amount is not established, a penalty shall be charged for each calendar day of delay in payment of the monetary obligation, including the repayment day, at the rate of 120 percent of the annual discount rate of the National Bank of Ukraine, effective for each such day.
on the amounts of understatement of the tax liability determined by subparagraphs 129.1.2 and 129.1.4 of paragraph 129.1 of this Article for each calendar day of understatement of the tax liability, including the day of the maturity date of the tax liability determined by the supervisory authority, at the rate of 120 percent of the annual discount rate of the National Bank of Ukraine, effective for each such day.
on the amount of the monetary obligation specified in subparagraph 129.1.3 of paragraph 129.1 of this Article (including the amount of penalties, if any, and excluding the amount of the penalty) for each calendar day of delay in its payment, starting from the 91st calendar day following the last day of the deadline for payment of the tax obligation, including the repayment day, at the rate of 100 percent of the annual discount rate of the National Bank of Ukraine, effective for each such day.
On the amounts of tax liabilities determined by the tax agent that are not paid on time and/or not paid (not transferred) in accordance with subparagraph 129.1.4 of paragraph 129.1 of this article, the supervisory authority shall charge a penalty for each calendar day of such non-payment (non-transfer), including the day of repayment of the tax liability, at the rate of 120 percent of the annual discount rate of the National Bank of Ukraine, effective for each such day.
{Clause 129.4 of Article 129 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 466-IX of 16.01.2020 }
129.5. The specified amount of the penalty applies to all payers and all types of taxes, fees and other monetary obligations, except for the penalty charged for violation of the payment deadline in the field of foreign economic activity, which is established by the relevant legislation.
{Clause 129.5 of Article 129 as amended by Law No. 466-IX of January 16, 2020 }
129.6. For violation of the deadline for crediting taxes to budgets or state trust funds established by the Law of Ukraine "On Payment Services", due to the fault of a bank, a body that provides treasury services for budget funds, a non-bank payment service provider, an acquirer, an issuer of electronic money, such bank/body, non-bank payment service provider, an issuer of electronic money shall pay a penalty for each day of delay, including the day of payment, and fines in the amounts established by this Code.
{Clause 129.6 of Article 129 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 466-IX of 16.01.2020 , No. 2888-IX of 12.01.2023 }
129.7. A violation committed as a result of the National Bank of Ukraine's regulation of the economic standards of such a bank, which leads to a lack of free balance of funds on such a correspondent account, is not considered a violation of the deadline for the transfer of taxes, fees, payments due to the fault of the bank, except for cases where the bank returned payment instructions without execution or the taxpayer contacted a bank classified as insolvent, and the initiation of payment of funds was not completed.
{Paragraph one of clause 129.7 of Article 129 as amended by Laws No. 466-IX of January 16, 2020 , No. 2888-IX of January 12, 2023 }
If in the future the bank or its successors restore solvency, the period for crediting taxes, fees and other payments begins from the moment of such restoration.
129.8. When collecting funds and property of taxpayers - bank clients, users of non-bank payment service providers, issuers of electronic money, policyholders of insurance organizations or members of other non-bank financial institutions established in accordance with the law, regulatory authorities or state enforcement officers do not have the right to collect on the balances of funds on correspondent accounts of banks, settlement accounts of non-bank payment service providers, issuers of electronic money, as well as on insurance and equivalent reserves of banks, insurance organizations or financial institutions formed in accordance with the legislation of Ukraine.
{Clause 129.8 of Article 129 as amended by Law No. 2888-IX of 12.01.2023 }
{Clause 129.9 of Article 129 was excluded on the basis of Law No. 2628-VIII of 23.11.2018 }
129.9. Penalty shall not be charged, and accrued penalty shall be subject to cancellation in the following cases:
129.9.1. the end of the 1095th day following the day on which the controlling body, in accordance with this Code, had the right to charge a penalty to the taxpayer;
129.9.2. commission of an act (action or inaction) by a person who acted in accordance with an individual or general tax consultation and/or an opinion on the application of a legal norm of the Supreme Court of Ukraine;
129.9.3. commission of an act (action or inaction) as a result of illegal decisions, actions or inaction of regulatory bodies, recognized as such in accordance with the procedure established by law;
129.9.4. commission of an act (action or inaction) due to the fault of a bank, a body providing treasury services for budget funds, a non-bank payment service provider, an acquirer, an issuer of electronic money;
{Subclause 129.9.4 of clause 129.9 of Article 129 as amended by Law No. 2888-IX of 12.01.2023 }
129.9.5. detection of a technical and/or methodological error or technical failure in the operation of the electronic office and recognition of such an error/failure by the technical administrator and/or methodologist of the electronic office or according to a notification on the official website of the central executive body implementing state tax policy, or confirmation of its existence by a court decision, if the violations were caused exclusively by a technical and/or methodological error or technical failure in the operation of the electronic office;
129.9.6. during the term of acceptance of the inheritance - for monetary obligations and/or tax debt of the testators;
129.9.7. commission of an act (action or inaction) by a person as a result of the introduction of a state of war or emergency;
{Subparagraph 129.9.7 of paragraph 129.9 of Article 129 as amended by Law No. 2120-IX of March 15, 2022 }
129.9.8. in the event of erroneous payment by a taxpayer, including a tax agent, of a monetary obligation to another budget account (without violating the legally established deadline for paying the tax or the agreed amount of the monetary obligation to the budget). The condition for confirming such circumstances is the taxpayer's taking the actions provided for in Article 43 of this Code regarding the return of erroneously paid monetary obligations;
{Clause 129.9 of Article 129 is supplemented by clause 129.9.8 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 3603-IX of February 23, 2024 }
129.9.9. in other cases provided for by this Code.
{Sub-paragraph of paragraph 129.9 of Article 129 as amended by the Law No. 3603-IX dated 23.02.2024 }
{Paragraph 129.9 is included in Article 129 in accordance with Law No. 466-IX of January 16, 2020 }
Article 130. Suspension of the terms for calculating penalties↑
130.1. If, within the framework of the administrative appeal procedure, a decision was made to extend the time limits for considering a taxpayer's complaint beyond the time limits specified in this Code, the penalty shall not be charged during such additional time limits, regardless of the results of the administrative appeal.
{Clause 130.1 of Article 130 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
{Title of Article 131 as amended by Law No. 466-IX of January 16, 2020 }
131.1. Penalties assessed by the regulatory authority shall be paid independently by the taxpayer.
131.2. When repaying the amount of tax debt (its part), the funds paid by such a taxpayer shall first be credited to the tax liability account. In the event of full repayment of the amount of tax debt, the funds paid by such a taxpayer shall next be credited to the repayment of fines, and lastly credited to the penalty account.
If the taxpayer does not comply with the payment order established by this clause or does not specify it in the payment instruction (or specifies it in violation of the specified procedure), the supervisory authority independently carries out such distribution of such amount in the manner specified by this clause.
{Paragraph two of clause 131.2 of Article 131 as amended by Law No. 2888-IX of 12.01.2023 }
131.3. The amounts of penalties shall be credited to the budgets to which the relevant taxes are credited in accordance with the law.
{Clause 131.3 of Article 131 as amended by Law No. 466-IX of January 16, 2020 }
131.4. The accrued amounts of penalties in favor of the taxpayer shall be paid to him in accordance with the procedure prescribed by the central executive body that ensures the formation and implementation of state financial policy.
{Article 131 is supplemented by paragraph 131.4 in accordance with Law No. 466-IX of January 16, 2020 }
Article 132. Procedure for calculating penalties in case of violation of the conditions under which exemption (conditional exemption) from taxation was granted upon import of goods into the customs territory of Ukraine↑
132.1. In case of violation of the conditions of customs regimes, upon placement of which conditional exemption from taxation was granted, as well as in case of violation of the conditions regarding the intended use of goods, upon import of which exemption from taxation was granted in accordance with this Code, the person responsible for compliance with the customs regime, as well as the person responsible for compliance with the conditions under which exemption from taxation is granted (regarding the intended use of goods), shall be obliged to pay the amount of the tax liability for which the exemption (conditional exemption) was granted, and the penalty accrued on the amount of such tax liability for the period from the date of granting the exemption (conditional exemption) from taxation to the date of payment.
In the event of claims for payment of tax obligations to the guarantor, the penalty shall be accrued for a period not exceeding 3 months from the day following the day of the expiration of the term for the performance of obligations secured by the guarantee.
When carrying out transportation under the terms of the Customs Convention on the International Carriage of Goods under Cover of the TIR Carnet of 1975, the accrual of penalties is suspended for a period of up to three months from the date of receipt of the claim by the guaranteeing association and is resumed if the claim remains unresolved after the expiration of this period.
{Clause 132.1 of Article 132 is supplemented by the third paragraph in accordance with Law No. 4915-VI of 07.06.2012 }
132.2. For the purposes of calculating penalties, the deadline for payment of customs payments is considered to be:
132.2.1. when using goods for purposes other than those for which exemption (conditional exemption) from customs duties was granted - the first day when the person violated the restrictions on the use and disposal of goods.
If it is impossible to establish such a day, the deadline for payment of customs payments shall be the day of acceptance of the customs declaration for such goods by the controlling authority;
132.2.2. in case of violation of the requirements and conditions of customs procedures, which in accordance with tax legislation entails the obligation to pay customs payments - the day of such violation. If such a day cannot be established - the date of commencement of the relevant customs procedure shall be considered the deadline for payment of customs payments;
132.2.3. in other cases - the day of the obligation to pay customs duties.
132.3. If the taxpayer independently discovers the fact of understatement of the tax liability and repays it before the start of its audit by the controlling body, a penalty is not charged.
This rule does not apply if:
a) the taxpayer fails to file a tax return for the period during which such understatement occurred;
b) the court has established the commission of a criminal offense by officials of the taxpayer or an individual taxpayer regarding intentional evasion of payment of the specified tax liability.
{Subparagraph "b" of paragraph 132.3 of Article 132 as amended by Law No. 786-IX of July 14, 2020 }
133.1.1. business entities - legal entities that carry out economic activities both in the territory of Ukraine and abroad, except for legal entities defined in paragraphs 133.4 and 133.5 of this article.
{Paragraph one of subparagraph 133.1.1 of paragraph 133.1 of Article 133 as amended by Law No. 1914-IX of 30.11.2021 }
Business entities - legal entities that have chosen a simplified taxation system are tax payers when paying income (profits) to a non-resident with a source of origin from Ukraine in the manner specified in Clause 141.4 of Article 141 of this Code. At the same time, single tax payers of the fourth group are not tax payers when paying income specified in paragraphs four to six of subparagraph 14.1.49 of clause 14.1 of Article 14 of this Code.
{Subparagraph 133.1.1 of paragraph 133.1 of Article 133 is supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Business entities - legal entities that have chosen a simplified taxation system are tax payers upon receipt of adjusted profit of a controlled foreign company, which is taxed in the manner specified in Article 39 - 2 and this section.
{Subparagraph 133.1.1 of paragraph 133.1 of Article 133 is supplemented by the third paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Legal entities - payers of the fourth group of the single tax are payers of tax on income (profits) received when carrying out transactions on the sale or other alienation of securities, and income received from the issuer of corporate rights, investment certificates or other securities certifying its ownership right to a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit, and calculated according to accounting rules.
{Subparagraph 133.1.1 of paragraph 133.1 of Article 133 is supplemented by the fourth paragraph in accordance with Law No. 4577-IX of 21.08.2025 }
{Subparagraph 133.1.1 of paragraph 133.1 of Article 133 as amended by Law No. 652-VIII of 17.07.2015 }
{Subclause 133.1.2 of clause 133.1 of Article 133 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
133.1.3. The manager of a real estate operations fund, which operates in accordance with the Law of Ukraine "On Financial and Credit Mechanisms and Property Management in Housing Construction and Real Estate Operations" regarding transactions and results of trust management activities carried out by such manager through the fund;
133.1.4. individual entrepreneurs, including those who have chosen a simplified taxation system, and individuals who carry out independent professional activities, in respect of income (profits) paid to a non-resident with a source of origin in Ukraine, which are taxed in accordance with the procedure specified in paragraph 141.4 of Article 141 of this Code.
{Clause 133.1 of Article 133 is supplemented by subparagraph 133.1.4 in accordance with Law No. 466-IX of January 16, 2020 }
133.1.5. legal entities established in accordance with the legislation of other countries (foreign companies) and having a place of effective management in the territory of Ukraine.
The place of effective management is considered to be Ukraine if one or more of the following conditions are met with respect to a foreign company or its activities:
a) holding meetings of the executive body of a foreign company more regularly in Ukraine than in any other country;
b) the making of management decisions and the implementation of other current (operational) activities of a foreign company by its officials are mainly carried out from Ukraine;
c) the actual management of the activities of a foreign company is mainly carried out from Ukraine, regardless of whether the persons exercising such management have formal (legal) powers for such management.
If a foreign company can be recognized as having a place of effective management in another foreign state, the place of management of such a foreign company is determined to be Ukraine if at least one of the following conditions is met in Ukraine:
management of bank accounts of a foreign company;
maintaining accounting or management records of a foreign company;
HR management of a foreign company.
A foreign company has the right to independently recognize itself as a tax resident of Ukraine from January 1 of the calendar year in which the relevant application in the form approved by the central executive body that ensures the formation and implementation of state financial policy is submitted to the central executive body that implements state tax policy.
If a foreign company submits an application for recognition as a tax resident of Ukraine between December 1 and December 31 of a calendar year, the first tax (reporting) period will be the year following the year in which the application was submitted.
A foreign company has the right to renounce the status of tax resident of Ukraine on the basis of a relevant application to the central executive body implementing the state tax policy, in the form approved by the central executive body ensuring the formation and implementation of the state financial policy, and based on the results of the relevant inspection by the supervisory body. Renunciation of tax residency by a foreign company is equivalent to the liquidation of a legal entity. Taxation of income paid in connection with the renunciation of tax residency by a foreign company is carried out at the level of shareholders or other persons entitled to receive such income.
The procedure for registering and deregistering a foreign company, as well as the procedure for conducting an inspection by the regulatory authority in connection with the refusal of a foreign company to apply for tax residency, is established by the central executive body that ensures the formation and implementation of state financial policy.
A foreign company that has received the status of a resident taxpayer is not recognized as a controlled foreign company.
A legal entity recognized as a non-resident of Ukraine in accordance with Ukraine's international treaty on the avoidance of double taxation is automatically recognized as a non-resident taxpayer.
{Clause 133.1 of Article 133 is supplemented by subparagraph 133.1.5 in accordance with Law No. 466-IX of January 16, 2020 }
133.2. Non-resident taxpayers are:
133.2.1. legal entities established in any organizational and legal form and receiving income with a source of origin from Ukraine, with the exception of institutions and organizations that have diplomatic privileges or immunity in accordance with international treaties of Ukraine;
133.2.2. non-residents who carry out economic activities in the territory of Ukraine through a permanent establishment and/or receive income with a source of origin in Ukraine, and other non-residents who are obliged to pay tax in accordance with the procedure established by this section.
{Subparagraph 133.2.2 of paragraph 133.2 of Article 133 as amended by Law No. 466-IX of January 16, 2020 }
133.3. A non-resident shall register with the regulatory body at the location of its permanent representative office prior to commencing its economic activity through such representative office in accordance with the procedure established by the central executive body responsible for formulating and implementing state financial policy. A non-resident who has commenced economic activity through its permanent representative office prior to registration with the regulatory body shall be deemed to be evading taxation, and the profits received by it shall be deemed to be concealed from taxation.
{Paragraph one of clause 133.3 of Article 133 as amended by Law No. 786-IX of 14.07.2020 }
Non-residents operating in accordance with the provisions of the Framework Agreement between Ukraine and the European Bank for Reconstruction and Development on the Activities of the Chernobyl Shelter Fund in Ukraine and the Grant Agreement (Chernobyl Nuclear Safety Project) between the European Bank for Reconstruction and Development as the Administrator of the Funds Provided under the Nuclear Safety Account Grant, the Government of Ukraine and the Chernobyl Nuclear Power Plant may conduct their economic activities without registering with the regulatory authority.
{Clause 133.3 of Article 133 is supplemented by the second paragraph in accordance with Law No. 364-VIII of 23.04.2015 }
{Clause 133.3 of Article 133 as amended by Law No. 1797-VIII of 21.12.2016 }
133.4. Non-profit enterprises, institutions and organizations are not tax payers in accordance with the procedure and under the conditions established by this paragraph.
133.4.1. A non-profit enterprise, institution and organization for the purposes of corporate income tax is an enterprise, institution and organization (hereinafter referred to as a non-profit organization) that simultaneously meets the following requirements:
{Paragraph one of subparagraph 133.4.1 of paragraph 133.4 of Article 133 as amended by Law No. 2628-VIII of 23.11.2018 - applies to tax periods starting from July 1, 2017, see paragraph 1 of Section II of Law No. 2628-VIII of 23.11.2018 }
established and registered in accordance with the procedure prescribed by the law regulating the activities of the relevant non-profit organization;
the constituent documents of which (or the constituent documents of a higher-level organization, on the basis of which the non-profit organization operates in accordance with the law) contain a prohibition on the distribution of received income (profits) or part thereof among the founders (participants within the meaning of the Civil Code of Ukraine ), members of such organization, employees (except for payment for their labor, calculation of a single social contribution), members of management bodies and other persons related to them. For the purposes of this paragraph, the distribution of received income (profits) is not considered to be the financing of expenses specified in subparagraph 133.4.2 of this paragraph;
{Paragraph three of subparagraph 133.4.1 of clause 133.4 of Article 133 as amended by Laws No. 1667-VIII of 06.10.2016 , No. 1797-VIII of 21.12.2016 , No. 2628-VIII of 23.11.2018 - applies to tax periods starting from July 1, 2017, see clause 1 of section II of Law No. 2628-VIII of 23.11.2018 }
whose constituent documents (or constituent documents of a higher-level organization on the basis of which the non-profit organization operates in accordance with the law) provide for the transfer of assets to one or more non-profit organizations of the appropriate type, to other legal entities that provide non-state pension provision in accordance with the law (for non-state pension funds), or for inclusion in budget income in the event of the termination of the legal entity (as a result of its liquidation, merger, division, accession or transformation). The provisions of this paragraph do not apply to associations and associations of associations of co-owners of apartment buildings, and housing and construction cooperatives;
{Paragraph four of subparagraph 133.4.1 of clause 133.4 of Article 133 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 , No. 2628-VIII of 11/23/2018 - applies to tax periods starting from July 1, 2017, see clause 1 of section II of Law No. 2628-VIII of 11/23/2018, No. 466-IX of 01/16/2020 }
entered by the regulatory authority into the Register of Non-Profit Institutions and Organizations.
The provisions of paragraphs three and four of this subparagraph regarding the requirements for the availability of constituent documents do not apply to budget institutions.
{Subclause 133.4.1 of clause 133.4 of Article 133 was supplemented by the sixth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
Registered institutions and organizations (newly established) that have submitted documents in accordance with the established procedure for inclusion in the Register of Non-profit Institutions and Organizations during or within 10 days from the date of state registration of the creation of a legal entity and which, based on the results of consideration of these documents, have been included in the Register of Non-profit Institutions and Organizations, are considered non-profit organizations for the purposes of taxation with corporate income tax from the date of state registration of the creation of a legal entity.
{Subparagraph 133.4.1 of paragraph 133.4 of Article 133 is supplemented by the seventh paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 3603-IX dated 23.02.2024 }
Institutions and organizations that, during or within 10 days from the date of state registration of changes to information about a legal entity, submitted documents for inclusion in the Register of Non-Profit Institutions and Organizations and, based on the results of consideration of these documents, were included in the Register of Non-Profit Institutions and Organizations, are considered non-profit organizations for the purposes of taxation with corporate income tax from the date of state registration of changes to information about a legal entity.
{Subclause 133.4.1 of clause 133.4 of Article 133 is supplemented by paragraph eight in accordance with Law No. 3603-IX of 23.02.2024 }
133.4.2. The income (profits) of a non-profit organization are used exclusively to finance expenses for the maintenance of such a non-profit organization, the implementation of the goals (objectives, tasks) and areas of activity defined by its constituent documents.
The income of non-profit religious organizations is also used to carry out non-profit (charitable) activities provided for by law for religious organizations, including providing humanitarian aid, carrying out charitable activities, and charity.
{Subclause 133.4.2 of clause 133.4 of Article 133 is supplemented by the second paragraph in accordance with Law No. 1667-VIII of 06.10.2016 }
133.4.3. In the event of non-compliance by a non-profit organization with the requirements specified in this clause, and for a religious organization - the requirements specified in the second paragraph of subparagraph 133.4.1 and subparagraph 133.4.2 of this clause, such non-profit organization is obliged to submit, within the period specified for the monthly tax (reporting) period, a report on the use of income (profits) of the non-profit organization for the period from the beginning of the year (or from the beginning of the recognition of the organization as non-profit in accordance with the established procedure, if such recognition occurred later) to the last day of the month in which such violation was committed, and to indicate and pay the amount of the independently assessed tax liability for income tax. The tax liability is calculated based on the amount of the transaction (transactions) of improper use of assets. Such a non-profit organization is excluded by the regulatory authority from the Register of Non-Profit Institutions and Organizations and is considered a payer of income tax for taxation purposes from the first day of the month following the month in which such a violation was committed.
{Paragraph one of subparagraph 133.4.3 of paragraph 133.4 of Article 133 as amended by Law No. 2245-VIII of 07.12.2017 }
For the period from the first day of the month following the month in which such a violation was committed until December 31 of the tax (reporting) year, such a non-profit organization is obliged to submit a quarterly income tax return (with a cumulative total) to the regulatory authority, pay the tax within the period specified for the quarterly period, and submit financial statements in accordance with the procedure established for income tax payers.
Starting from the next tax (reporting) year, such a non-profit organization shall submit a tax return for income tax and financial statements and pay income tax in accordance with the procedure established by this section for income tax payers.
{Subclause 133.4.3 of clause 133.4 of Article 133 as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
133.4.4. Establishment by the supervisory authority in accordance with the provisions of this Code of the fact of the use of income (profits) by a non-profit organization for purposes other than those provided for in subparagraph 133.4.2 of this paragraph, or the establishment of the fact of the use of income ( profits ) of a non-profit organization for the purpose of providing an unlawful benefit during the commission of a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, directly or indirectly (through third parties), regardless of the amount of the unlawful benefit, is the basis for the exclusion of such organization from the Register of Non-Profit Institutions and Organizations and the accrual of a tax liability for corporate income tax, penalties and fines in accordance with this Code. Tax liabilities, penalties and fines are accrued starting from the first day of the month in which such a violation was committed.
{Subclause 133.4.4 of Clause 133.4 of Article 133 as amended by Law No. 1667-VIII of 06.10.2016 ; as amended by Law No. 4112-IX of 04.12.2024 }
133.4.4 - 1. Payment of compensations and other payments (including those that are additional benefits) to employees of a charitable organization shall not be grounds for excluding such a charitable organization from the Register of Non-Profit Institutions and Organizations, provided that such compensations and other payments are related to the implementation of the goals and objectives of such a charitable organization and are provided for by its constituent documents and/or organizational and administrative documents and do not contradict the Law of Ukraine "On Charitable Activities and Charitable Organizations". The amount of such compensations and other payments in a tax (reporting) year shall not exceed 25 percent of the amount of administrative expenses incurred by such a charitable organization for the tax (reporting) year.
{Clause 133.4 of Article 133 is supplemented by subparagraph 133.4.4 - 1 in accordance with Law No. 4143-IX of 17.12.2024 }
133.4.5. The procedure for maintaining the Register of Non-Profit Institutions and Organizations, including non-profit enterprises, institutions and organizations in the Register and excluding them from the Register shall be established by the Cabinet of Ministers of Ukraine.
133.4.6. Non-profit organizations that meet the requirements of this paragraph and are not tax payers may include, in particular:
budgetary institutions;
public associations, political parties, creative unions, religious organizations, charitable organizations, pension funds;
unions, associations and other associations of legal entities;
housing and construction cooperatives (from the first day of the month following the month in which, in accordance with the law, a completed residential building was put into operation and such a residential building was constructed or purchased by a housing and construction (housing) cooperative), summer cottage (summer cottage construction), gardening and garage (garage construction) cooperatives (companies);
association of co-owners of an apartment building, association of owners of residential buildings;
trade unions, their associations and trade union organizations, as well as employers' organizations and their associations;
agricultural service cooperatives, cooperative associations of agricultural service cooperatives;
other legal entities whose activities meet the requirements of this paragraph.
133.4.7. For non-profit organizations that meet the requirements of this clause and are included in the Register of Non-profit Institutions and Organizations, an annual tax (reporting) period is established, except for cases provided for in subparagraph 133.4.3 of this clause.
{Clause 133.4 of Article 133 is supplemented by subparagraph 133.4.7 in accordance with Law No. 1797-VIII of 21.12.2016 }
{Article 133 was supplemented by paragraph 133.4 in accordance with Law No. 652-VIII of 17.07.2015 }
133.5. Business entities applying the simplified system of taxation, accounting and reporting, defined by Chapter 1 of Section XIV of this Code, are not tax payers, except for the cases provided for in the second , third and fourth paragraphs of subparagraph 133.1.1 and subparagraph 133.1.4 of paragraph 133.1 of this Article.
{Article 133 is supplemented by paragraph 133.5 in accordance with Law No. 652-VIII of 17.07.2015 ; as amended in accordance with Laws No. 466-IX of 16.01.2020 , No. 4577-IX dated 21.08.2025 }
133.6. The National Bank of Ukraine shall make settlements with the State Budget of Ukraine in accordance with the Law of Ukraine "On the National Bank of Ukraine".
{Article 133 was supplemented by paragraph 133.6 in accordance with Law No. 1797-VIII of 21.12.2016 }
134.1.1. profit with a source of origin in Ukraine and outside its borders, which is determined by adjusting (increasing or decreasing) the financial result before taxation (profit or loss) determined in the financial statements of the enterprise in accordance with national accounting regulations (standards) or international financial reporting standards, by the differences determined by the relevant provisions of this Code.
{Paragraph one of subparagraph 134.1.1 of paragraph 134.1 of Article 134 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 1914-IX of 11/30/2021 }
If, in accordance with this section, an adjustment is provided for by increasing the financial result before taxation, then in this case:
reduction of the negative value of the financial result before tax (loss);
increasing the positive value of the financial result before tax (profit).
If, in accordance with this section, an adjustment is provided for by reducing the financial result before taxation, then in this case:
increase in the negative value of the financial result before tax (loss);
reduction in the positive value of the financial result before tax (profit).
For taxpayers whose annual income from any activity (net of indirect taxes), determined according to accounting rules, for the last annual reporting period does not exceed 40 million hryvnias, the object of taxation may be determined without adjusting the financial result before taxation for all differences (except for the negative value of the object of taxation of previous tax (reporting) years and adjustments determined by subparagraph 140.4.8 of paragraph 140.4, subparagraph 140.5.16 of paragraph 140.5, paragraph 140.6 of Article 140 of this Code), determined in accordance with the provisions of this section. A taxpayer whose annual income (net of indirect taxes), determined according to accounting rules, for the last annual reporting period does not exceed 40 million hryvnias, has the right to make a decision not to apply the adjustment of the financial result to taxation for all differences (except for the negative value of the object of taxation of previous tax (reporting) years and adjustments specified in subparagraph 140.4.8 of paragraph 140.4, subparagraph 140.5.16 of paragraph 140.5, paragraph 140.6 of Article 140 of this Code), determined in accordance with the provisions of this section, no more than once during a continuous set of years, in each of which the specified criterion regarding the amount of income is met. The taxpayer shall indicate the decision made in the tax reporting for this tax, submitted for the first year of such continuous set of years. In subsequent years of such a set of years, adjustments to the financial result are also not applied, except for the negative value of the object of taxation of previous tax (reporting) years and adjustments specified in subparagraph 140.4.8 of paragraph 140.4, subparagraph 140.5.16 of paragraph 140.5, paragraph 140.6 of Article 140 of this Code.
{Paragraph eight of subparagraph 134.1.1 of paragraph 134.1 of Article 134 as amended by Law No. 962-IX of 04.11.2020 ; as amended by Law No. 4112-IX of 04.12.2024 }
If a taxpayer who has decided not to apply the adjustment of the financial result before taxation to all differences (except for the negative value of the object of taxation of previous tax (reporting) years and the adjustments specified in subparagraph 140.4.8 of paragraph 140.4, subparagraph 140.5.16 of paragraph 140.5, paragraph 140.6 of Article 140 of this Code) determined in accordance with the provisions of this section, in any subsequent year the annual income (net of indirect taxes), determined according to the accounting rules, for the last annual reporting period exceeds 40 million hryvnias, such taxpayer shall determine the object of taxation starting from such year by adjusting the financial result before taxation to all differences determined in accordance with the provisions of this section.
{Paragraph nine of subparagraph 134.1.1 of paragraph 134.1 of Article 134 as amended by Law No. 962-IX of 04.11.2020 ; as amended by Law No. 4112-IX of 04.12.2024 }
For the purposes of this subparagraph, annual income from any activity, determined according to accounting rules, includes income (revenue) from the sale of products (goods, works, services), other operating income, financial income and other income.
Payers of income tax - producers of agricultural products who have chosen an annual tax (reporting) period in accordance with subparagraph 137.4.1 of paragraph 137.4 of Article 137 of this Code, the financial result before taxation for the tax (reporting) period shall be calculated by reducing the financial result before taxation for the previous reporting year by the financial result before taxation for the first half of such year and increasing it by the financial result before taxation for the first half of the current reporting year, which are determined in accordance with national accounting regulations (standards) or international financial reporting standards;
{Subparagraph 134.1.1 of paragraph 134.1 of Article 134 is supplemented by the eleventh paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
For taxpayers defined in subparagraph 133.1.5 of paragraph 133.1 of Article 133 of this Code, income with a source of origin outside Ukraine is not subject to taxation.
{Subclause 134.1.1 of clause 134.1 of Article 134 is supplemented by a paragraph in accordance with Law No. 466-IX of 16.01.2020 }
When determining the object of taxation in accordance with this subparagraph, expenses resulting from transactions carried out by the taxpayer with the aim of providing an unlawful benefit to an official (including an official of a foreign state) shall not be taken into account. If such expenses are recognized by the taxpayer in the tax (reporting) period in accordance with national accounting regulations (standards) or international financial reporting standards, when determining the object of taxation, the financial result before taxation shall be adjusted taking into account the provisions of clause 140.6 of Article 140 of this Code.
{Subparagraph 134.1.1 of paragraph 134.1 of Article 134 is supplemented by the thirteenth paragraph in accordance with Law No. 4112-IX of 04.12.2024 }
{Subclause 134.1.1 of Clause 134.1 of Article 134 as amended by Law No. 466-IX of 16.01.2020 }
134.1.2. income from insurance contracts, determined in accordance with subparagraph 141.1.2 of paragraph 141.1 of Article 141 of this Code;
134.1.3. income (profit) of a non-resident, subject to taxation in accordance with paragraph 141.4 of Article 141 of this Code, with a source of origin in Ukraine;
134.1.4. the income of entities that issue and conduct lotteries is subject to taxation in accordance with paragraph 141.8 of Article 141 of this Code;
{Subclause 134.1.4 of Clause 134.1 of Article 134 as amended by Law No. 1797-VIII of 21.12.2016 }
134.1.5. income of gambling organizers received from activities in the field of organizing and conducting gambling, except for income received from organizing and conducting gambling in slot machine halls, reduced by the amount of payments paid to the player, which is subject to taxation in accordance with paragraph 141.5 of Article 141 of this Code.
{Subclause 134.1.5 of Clause 134.1 of Article 134 as amended by Law No. 3325-IX of 10.08.2023 }
134.1.6. income received from the organization and conduct of gambling in slot machine halls, which is subject to taxation in accordance with paragraph 141.5 of Article 141 of this Code.
{Clause 134.1 of Article 134 is supplemented by subparagraph 134.1.6 in accordance with Law No. 466-IX of 16.01.2020 ; as amended by Law No. 3325-IX of 10.08.2023 }
134.1.7. adjusted profit of a controlled foreign company determined in accordance with Article 39 - 2 of this Code.
Such a tax object is determined separately from the tax objects defined in subparagraphs 134.1.1-134.1.6 of this paragraph.
In the event of the presence of several controlled foreign companies, the object of taxation is determined separately for each such company;
{Clause 134.1 of Article 134 is supplemented by subparagraph 134.1.7 in accordance with Law No. 466-IX of January 16, 2020 }
134.1.8. transactions of residents of Diya City - taxpayers under special conditions, subject to taxation in accordance with clause 135.2 of Article 135, clause 137.10 of Article 137 and clause 141.9 - 1 of Article 141 of this Code.
{Clause 134.1 of Article 134 is supplemented by subparagraph 134.1.8 in accordance with Law No. 1946-IX of 14.12.2021 }
135.1. The tax base is the monetary expression of the object of taxation determined in accordance with Article 134 of this Code, taking into account the provisions of this Code.
135.2. The tax base for transactions of a resident of the City of Diya - a taxpayer under special conditions is the monetary expression of the object of taxation, calculated according to the rules specified in this paragraph and subparagraph 141.9 - 1 .3 of paragraph 141.9 - 1 of Article 141 of this Code. In the case of transactions that are the object of taxation in a form other than monetary, the tax base is the cost of such a transaction, determined at a level not lower than the usual price.
This tax base for transactions of a resident of the City of Action - a taxpayer under special conditions - is determined based on the value of the transaction without reduction by the amount of withheld tax on the non-resident's income.
135.2.1. The tax base is defined as the sum of:
135.2.1.1. dividends paid in favor of the owner of corporate rights (except for the owner of corporate rights who is a resident of Diya City - a tax payer under special conditions) in cash and/or non-cash form, with the exception of dividends accrued in favor of a shareholder/participant of a legal entity - the issuer in the form of shares (shares, units), provided that such accrual in no way changes the proportions (shares) of participation of all shareholders/participants in the authorized capital of the issuer and as a result of which the authorized capital of the issuer increases by the total nominal value of the accrued dividends.
The provisions of this subparagraph do not apply to amounts that are equated to dividends for tax purposes in accordance with paragraphs four to six of subparagraph 14.1.49 of paragraph 14.1 of Article 14 of this Code;
135.2.1.2. funds and/or the value of property that are returned (which is returned) or paid (transferred) (including the amount of dividends that were accrued but not paid) to the owner of corporate rights (shares, interests, units), who is not a resident of Diya City - a taxpayer on special terms, in connection with the withdrawal of such owner from the composition of participants/shareholders of the legal entity - the issuer of such corporate rights (shares, interests, units), liquidation of such legal entity - the issuer, repurchase by a resident of Diya City - a taxpayer on special terms of its own corporate rights (shares, interests, units) in an amount exceeding:
a) the value of the contribution made by the founder, shareholder or participant to the authorized capital of a legal entity that is a taxpayer. The value of the contribution to the authorized capital made at the expense of dividends accrued in favor of a shareholder/participant of a legal entity - the issuer in the form of shares (units, shares) without actual payment in favor of the shareholder/participant, provided that such accrual in no way changes the proportions (units) of participation of all shareholders/participants in the authorized capital of the issuer, for the purposes of applying this rule is considered (determined) to be equal to zero (except for cases where the amount of profit from which such dividends were accrued was taxed by income tax or an advance payment of income tax was paid from the amount of such dividends). If the contribution was made in a form other than cash (except for the case of accrual of dividends in favor of a shareholder/participant of a legal entity - the issuer in the form of shares (shares, units), provided that such accrual does not in any way change the proportions (shares) of participation of all shareholders/participants in the authorized capital of the issuer), the value of such contribution is determined on the basis of the constituent documents, and if such determination is not made, it is considered that the value of such contribution is zero;
and/or
b) the cost of acquiring shares (shares, units). The cost of acquiring shares (shares, units) is taken into account for calculating the amount of the excess if the settlements in cash between the parties to the purchase and sale, other alienation of such shares (shares, units) were carried out on the territory of Ukraine (including if the transfer of funds was initiated from an account opened in a Ukrainian bank and its completion took place abroad or if the transfer of funds was initiated abroad and its completion (crediting of funds) took place on an account opened in a Ukrainian bank). If the settlements in cash between the parties to the purchase and sale, other alienation of shares (shares, units) were not carried out on the territory of Ukraine or if the settlements were carried out in a form other than cash, it is considered that the cost of acquiring such shares (shares, units) is zero, except for cases where the cost of the relevant transaction was taken into account when determining the object of taxation by profit tax and/or the object of taxation by personal income tax. For the purposes of this subparagraph, the amounts of funds and/or the value of property (including the cost of the contribution, the cost of acquiring shares (shares, units)) expressed in foreign currency are converted into hryvnia at the official exchange rate of hryvnia to foreign currency determined by the National Bank of Ukraine on the day of return (payment, transfer) of funds and/or property to the owner of corporate rights.
The provisions of this subparagraph do not apply to transactions for the return (payment, transfer) of funds and/or property in favor of the owner of corporate rights - an individual, if the value of such transactions is taken into account when determining the object of taxation by personal income tax according to the rules of paragraph 170.2 of Article 170 of this Code;
135.2.1.2 - 1. funds and/or the value of property that are paid (transferred) to a person who is not a resident of Diia City - a taxpayer under special conditions, in connection with the redemption or repurchase by a resident of Diia City - a taxpayer under special conditions of securities of its own issue (except for shares specified in subparagraph 135.2.1.2 of this paragraph) in an amount exceeding the cost of acquiring such securities (including during their initial placement). The cost of purchasing securities is taken into account for calculating the amount of the excess if the settlements in cash between the parties to the purchase, sale, or other disposal of such securities were carried out on the territory of Ukraine (including if the transfer of funds was initiated from an account opened in a Ukrainian bank and completed abroad or if the transfer of funds was initiated abroad and completed (credited) to an account opened in a Ukrainian bank). If the settlements in cash between the parties to the purchase, sale, or other disposal of securities were carried out outside the territory of Ukraine or if the settlements were carried out in a form other than cash, it is considered that the cost of purchasing such securities is zero, except for cases where the cost of the relevant transaction was taken into account when determining the object of taxation by profit tax and/or the object of taxation by personal income tax.
For the purposes of this subparagraph, amounts of funds and/or the value of property expressed in foreign currency shall be converted into hryvnia at the official exchange rate of hryvnia to foreign currency determined by the National Bank of Ukraine on the day of payment (transfer) of funds and/or property to the person.
The provisions of this subparagraph do not apply to transactions involving the payment of funds and/or the transfer of property in favor of an individual, if the value of such transactions is taken into account when determining the object of taxation by personal income tax in accordance with the rules of paragraph 170.2 of Article 170 of this Code;
135.2.1.3. funds and/or the value of property paid (returned) within the framework of joint activities in an amount exceeding the amount of funds and/or the value of property provided (provided) for joint activities.
The provisions of this subparagraph do not apply to funds and/or the value of property paid (returned) to a resident of Diya City - a taxpayer under special conditions.
For the purposes of this subparagraph, the value of property provided for joint activities is its monetary value, determined by agreement between the participants in the joint activity and reflected in the primary documents and/or in the joint activity agreement;
135.2.1.4. funds paid during the tax (reporting) period to fulfill debt obligations (within the meaning of clause 140.1 of Article 140 of this Code) in the form of interest (including those that were included in the amount of the principal debt (loan body), commissions, other remuneration, compensation, fines, penalties related to the attraction and/or use of funds for the benefit of persons who are not residents of Diya City - taxpayers under special conditions.
The provisions of this clause do not apply to the amounts of interest (including those that were included in the amount of the principal debt (loan body), commissions, other fees, compensations, fines, penalties related to the attraction and/or use of funds paid in favor of:
a) non-residents (except for cases where the relevant transactions are carried out by a non-resident through his permanent establishment in Ukraine). Taxation of such transactions with non-residents is regulated by the norms of subparagraph 135.2.1.5 of this subparagraph;
b) resident banks;
135.2.1.5. funds paid during the tax (reporting) period to fulfill debt obligations (within the meaning of clause 140.1 of Article 140 of this Code) in the form of interest (including those that were included in the amount of the principal debt (loan body), commissions, other remuneration, compensation, fines, penalties related to the attraction and/or use of funds:
a) a related non-resident person; or
b) to a non-resident, if the total amount of debt obligations (within the meaning of Clause 140.1 of Article 140 of this Code, including accrued but unpaid interest, fines and penalties) of a resident of the City of Diya - a taxpayer on special terms to all non-residents exceeds the amount of his equity by more than 3.5 times.
Such excess is determined based on the results of the tax (reporting) year, based on the amount of debt obligations specified in the first paragraph of this subparagraph and the amount of equity, which for the purposes of this subparagraph is defined as the arithmetic mean of the ratio of such debt obligations to equity at the beginning and end of the tax (reporting) year.
When calculating such an excess, the following are not taken into account:
amounts received from an international financial organization of which Ukraine is a member or in respect of which Ukraine has undertaken to provide the legal regime granted to other international financial organizations or residents;
amounts of credits (loans) received under state guarantees by decision of the Cabinet of Ministers of Ukraine;
the amount of debt obligations arising from transactions with non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, or who are residents of these states (territories), as well as with non-residents whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code;
{Paragraph six of subparagraph "b" of subparagraph 135.2.1.5 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 as amended by Law No. 3813-IX of 18.06.2024 }
c) non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, or who are residents of these states (territories), as well as non-residents whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code.
{Paragraph one of subparagraph "c" of subparagraph 135.2.1.5 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 as amended by Law No. 3813-IX of 18.06.2024 }
The provisions of this subparagraph shall not apply to amounts of funds paid during the tax (reporting) period in favor of an international financial organization of which Ukraine is a member or in respect of which Ukraine has undertaken to provide the legal regime granted to other international financial organizations or residents, or in favor of a foreign bank that is not a non-resident defined in subparagraph "c" of this subparagraph;
135.2.1.6. the value of property (works, services) provided to a person who is not a resident of Diya City - a taxpayer under special conditions, without making claims for compensation for its (their) value (including goods (works, services) provided free of charge), with the exception of:
a) provided (provided) to non-profit organizations, the taxation of transactions with which is regulated by subparagraphs 135.2.1.8 and 135.2.1.8 - 1 of this subparagraph;
b) distributed (distributed) by a resident of Diya City - a taxpayer under special conditions (including with the involvement of third parties) during advertising (marketing) events, provided that the usual price of a unit of goods (works, services) used in an advertising (marketing) event as a separate unit of distribution does not exceed the amount of two subsistence minimums for an able-bodied person established by law as of January 1 of the tax (reporting) year;
c) if the value of such property (works, services) is subject to personal income tax in accordance with Section IV of this Code or is not included in the calculation of total monthly (annual) taxable income in accordance with Article 165 of this Code and/or is not taxed in accordance with Clause 170.7 of Article 170 of this Code;
d) additional benefits provided by a resident of Diya City - a taxpayer on special terms for the benefit of specialists of a resident of Diya City, if such additional benefits are not subject to personal income tax due to the lack of personalized accounting;
e) the amount of pension contributions within the framework of non-state pension provision and insurance payments provided for in subparagraphs "c" and "d" of subparagraph 164.2.16 of paragraph 164.2 of Article 164 of this Code.
{Subclause 135.2.1.6 of subparagraph 135.2.1 of clause 135.2 of Article 135 is supplemented by subparagraph "e" in accordance with Law No. 4113-IX of 04.12.2024 }
For the purposes of this subparagraph:
Property provided free of charge is also considered to be property, the shortage of which was discovered during the inventory, provided that the book value of such missing property as of the date of the inventory exceeds 5 percent of the total book value of the corresponding homogeneous group of property, in respect of which the inventory is being conducted (except for the write-off of the shortage within the limits of natural loss), and the taxpayer has not applied to the relevant authorities with a statement about committing a criminal offense or bringing the guilty persons to justice or has not taken measures to collect the amount of compensation from the custodian, insurance company, etc. in connection with such shortage;
A homogeneous group of property means a set of property that is combined based on the homogeneity of raw materials and materials, purpose, production method, etc. If the taxpayer has determined a homogeneous group of property in accordance with the accounting policy of the enterprise, the relevant provisions of the accounting policy of the enterprise are used;
135.2.1.7. financial assistance: provided to a person who is not a resident of Diya City - a taxpayer under special conditions, if such financial assistance is not subject to refund; provided to a related person (individual or legal entity) who is not a resident of Diya City - a taxpayer under special conditions, regardless of the presence of a refund condition; provided to an unrelated person (individual or legal entity) who is not a resident of Diya City - a taxpayer under special conditions, if the financial assistance was not returned within 12 calendar months, starting from the month following the calendar month in which the amount of financial assistance was issued, or if, before the expiration of the specified 12-month period, the debt for such financial assistance was recognized as hopeless in accordance with subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code or was terminated as a result of debt forgiveness, except for:
a) the amount of financial assistance provided to non-profit organizations, the taxation of transactions with which is regulated by subparagraphs 135.2.1.8 and 135.2.1.8 - 1 of this subparagraph;
b) the amount of financial assistance subject to refund, provided in accordance with the provisions of a collective agreement or by decision of the taxpayer's management body to an individual who is a specialist of a resident of Diia City - a taxpayer under special conditions and at the same time is not a person related to such a taxpayer, taking into account the norms of subparagraph 137.10.4.5, subparagraph 137.10.4, paragraph 137.10 of Article 137 of this Code;
c) the amount of financial assistance that is subject to personal income tax in accordance with Section IV of this Code or is not included in the calculation of total monthly (annual) taxable income in accordance with Article 165 of this Code and/or is not taxable in accordance with Clause 170.7 of Article 170 of this Code;
d) amounts of debt for goods (works, services) supplied by a resident of Diya City - a taxpayer under special conditions to an individual that was forgiven by such a resident of Diya City - a taxpayer under special conditions, which is subject to personal income tax in accordance with Section IV of this Code or is not included in the calculation of the total monthly (annual) taxable income in accordance with Article 165 of this Code and/or is not taxed in accordance with Clause 170.7 of Article 170 of this Code;
e) amounts defined as non-refundable financial assistance in accordance with paragraphs four to six of subparagraph 14.1.257 of paragraph 14.1 of Article 14 of this Code;
e) membership (entry) and/or target contributions to foreign (international) organizations and institutions in an amount not exceeding 300 times the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, per organization;
135.2.1.8. non-refundable financial assistance provided and/or the value of property (works, services) provided free of charge by the taxpayer during the tax (reporting) year to non-profit organizations defined in clause 133.4 of Article 133 of this Code, in an amount exceeding 0.5 percent of the amount of net income from the sale of products (goods, works, services) reflected in the taxpayer's financial statements for the previous reporting (tax) year, except for a non-profit organization to which the provisions of subparagraph 135.2.1.8 - 1 of this subparagraph apply;
135.2.1.8 - 1. non-refundable financial assistance provided and/or the value of property (works, services) provided free of charge by the taxpayer during the tax (reporting) year to a non-profit organization defined in Clause 133.4 of Article 133 of this Code and which is a national institution of higher education in accordance with the Law of Ukraine "On Higher Education", in an amount exceeding 1 percent of the amount of net income from the sale of products (goods, works, services) reflected in the taxpayer's financial statements for the previous reporting (tax) year;
135.2.1.9. funds and/or the value of property (including non-current assets) paid (transferred) and/or provided (provided) to a non-resident (except for cases where the relevant transactions are carried out by a non-resident through its permanent establishment in Ukraine), in connection with:
135.2.1.9.1. transfer of funds to accounts of non-residents to fulfill debt obligations under loans and credits (including interest, commissions, other fees, compensations, fines, penalties), if such loans were not credited to accounts in Ukrainian banks or were not used to pay for property located in the territory of Ukraine or imported into the customs territory of Ukraine;
135.2.1.9.2. repayment of obligations under recognized fines, penalties, penalties, compensation for losses, compensation for unearned income (lost profits) accrued in accordance with civil legislation and civil law contracts in favor of non-residents - related persons and/or non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, or who are residents of these states (territories), and/or non-residents whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code;
{Sub -clause 135.2.1.9.2 of sub -clause 135.2.1.9 of sub-clause 135.2.1 of clause 135.2 of Article 135 as amended by Law No. 3813-IX of 18.06.2024 }
135.2.1.9.3. investment in investment objects (including the creation of legal entities abroad; opening of branches, other separate divisions of the taxpayer abroad; creation and/or maintenance of a permanent place of business through which the taxpayer's economic activity is fully or partially carried out abroad; acquisition of property, including (but not exclusively) non-current assets, corporate rights and securities and their derivatives of foreign issuers, ownership rights to real estate located outside Ukraine), if such investment objects are located outside the territory of Ukraine, with the exception of:
a) payment of membership (entry) and/or target contributions to foreign (international) organizations and institutions in an amount not exceeding 300 times the subsistence minimum for an able-bodied person, established by law as of January 1 of the tax (reporting) year, per organization;
b) acquisition of property (including non-current assets) located abroad, if it is imported (imported) into the customs territory of Ukraine until the moment of payment or within 365 calendar days, or within other terms stipulated by the conclusion of the central executive body implementing the state policy of economic development, on exceeding the payment terms specified by law, from the date of transfer of funds (including those received under a commission agreement, mandate or on other similar grounds) abroad in payment for its acquisition;
c) acquisition of property for the purpose of further sale without its import into the customs territory of Ukraine, provided exclusively that the funds from such further sale are credited to accounts opened in Ukrainian banks within 365 calendar days from the date of transfer of funds to pay for the purchase of such property;
d) property located in the customs territory of Ukraine (including corporate rights and securities and their derivatives of issuers - residents of Ukraine), if a resident of the City of Action - a taxpayer under special conditions receives it before the moment of payment or within 365 calendar days from the date of transfer of funds to pay for its purchase;
e) investments in investment objects that are intangible assets;
135.2.1.9.4. purchase of works (services), with the exception of:
a) purchase of works (services), if a resident of the City of Diya - a taxpayer under special conditions receives the results of the works (services) by the time of payment or within 365 calendar days, or within other terms stipulated by the conclusion of the central executive body implementing the state policy of economic development, on exceeding the payment terms specified by law, from the date of transfer of funds (including those received under a commission agreement, mandate or on other similar grounds) abroad in payment for the purchase of works (services);
b) purchase of works (services) for the purpose of their further sale abroad, provided exclusively that the funds from such further sale are credited to accounts opened in Ukrainian banks within 365 calendar days from the date of transfer of funds abroad in payment for the purchase of works (services);
c) purchase of electronic services (including under the IaaS, PaaS, SaaS cloud service models), payment for which is made in the form of a fixed payment for the provision of such services on a subscription basis. If the purchase of works (services) involves their phased provision/performance, the terms are calculated for each stage separately.
When determining the tax base for transactions subject to taxation in accordance with subparagraph 135.2.1.9 of this subparagraph, the value of such transactions, expressed in foreign currency, is converted into hryvnia at the official exchange rate of hryvnia to foreign currency established by the National Bank of Ukraine on the date of payment (transfer) of funds and/or transfer (grant) of property to a non-resident;
135.2.1.10. the value of property (works, services) provided to a person who is not a resident of Diya City - a taxpayer on special terms, under a contract that provides for the payment of compensation for the value of such property (works, services), except for the sale (provision) of property (works, services) after receiving payment or provided that the funds from such sale (provision) are credited to the accounts of a resident of Diya City - a taxpayer on special terms, opened in Ukrainian banks, within 365 calendar days following the day:
a) customs clearance of products, if the subject of the transaction is the export (export from Ukraine) of property;
b) transfer of risks associated with the right of ownership of property, if the subject of the transaction is the sale of property in the territory of Ukraine or property located abroad, without its import and export;
c) execution in writing (in paper or electronic form) of an act, bill (invoice) or other document certifying their provision, if the subject of the transaction is the provision of works, services, intellectual property rights and/or other property or non-property rights;
d) receiving from a person who, on behalf of a resident of Diya City - a taxpayer on special terms, sells his property (works, services) by providing access through an electronic interface, providing technical, organizational, informational and other capabilities using information technologies and systems to establish contacts and conclude agreements between sellers and buyers, a report on the volumes and cost of property (works, services) sold on behalf of a resident of Diya City - a taxpayer on special terms, except for cases where the invoices (receipts) provided by such a person to buyers (customers) specify a list of property (works, services) and their actual supplier. For the purposes of this subparagraph, the tax base is determined based on the cost of selling property (works, services), but not lower than their usual price. If the value of the property (works, services) is determined in foreign currency, it shall be converted into hryvnia at the official hryvnia to foreign currency exchange rate established by the National Bank of Ukraine on the date of transfer of the property (provision of works, services). The provisions of this subparagraph shall not apply to transactions of a resident of the City of Diya - a taxpayer under special conditions with taxpayers of corporate income tax and non-profit organizations specified in paragraph 133.4 of Article 133 of this Code;
135.2.1.11. funds and/or the value of property (works, services) transferred (transferred) by a resident of Diya City - a taxpayer under special conditions, who carries out activities at the expense and on behalf of a non-resident, for the benefit of such non-resident (a person authorized by him) within the framework of the relevant commission agreement, mandate, agency agreement or similar agreements, with the exception of:
a) the amounts of funds and/or the value of property (works, services) that were provided (were provided) by a non-resident for the performance of the contract and are returned to the non-resident (or a person authorized by such non-resident);
b) the value of property, works, and services that were purchased on behalf of and at the expense of a non-resident for funds received directly for such purchase, except in cases where a resident of Diya City - a taxpayer under special conditions - has the characteristics of a permanent representative office of such non-resident;
c) amounts of funds from the sale of property (except for corporate rights and securities), works, services provided by a non-resident for sale, except in cases where a resident of the City of Diya - a taxpayer under special conditions has the characteristics of a permanent establishment of such a non-resident;
d) the amounts of funds paid by a non-resident (directly or through an attorney) for the purchase of securities or corporate rights in the territory of Ukraine (including the amounts of funds or the value of property at the expense of which the contribution was made), the proceeds from the sale of which are returned by the resident taxpayer in favor of the non-resident;
135.2.1.12. royalties paid to a non-resident of Diya City - a taxpayer under special conditions, during the tax (reporting) year in the amount exceeding the amount of royalty income increased by 4 percent of the net income from the sale of products (goods, works, services), according to financial statements (excluding royalty income) for the year preceding the reporting year. For taxpayers registered during the reporting (tax) year (newly created), which do not have financial statements for the previous reporting year, 4 percent of net income is calculated based on the financial statements for the current year. The provisions of this subparagraph do not apply to: royalty amounts that are taxable in accordance with subparagraph 135.2.1.13 of this subparagraph (except for cases where the relevant transactions are carried out by a non-resident through his permanent establishment in Ukraine); royalty amounts accrued (paid) to an individual, provided that personal income tax has been withheld (paid) from this amount;
135.2.1.13. royalties paid in favor of:
a) non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, or who are residents of these states (territories), as well as for the benefit of non-residents whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code;
{Sub -clause "a" of sub -clause 135.2.1.13 of sub-clause 135.2.1 of clause 135.2 of Article 135 as amended by Law No. 3813-IX of 18.06.2024 }
b) a non-resident regarding objects, intellectual property rights in respect of which were first created by a resident of Ukraine. In the event of disagreements regarding the determination by the controlling body and the taxpayer of the person who first created (acquired) intellectual property rights to an intellectual property object, such controlling body shall be obliged to apply to the central executive body implementing state policy in the field of intellectual property to obtain a relevant opinion;
c) a non-resident who is not subject to tax on royalties in the state of which he is a resident;
d) a non-resident who is not the beneficial (actual) recipient (owner) of the royalty, except in cases where the beneficiary (actual owner) has granted the right to receive the royalty to other persons;
e) collective investment institutions. The provisions of this subparagraph shall not apply if the relevant transactions are carried out by a non-resident through its permanent establishment in Ukraine;
135.2.1.14. funds and/or the value of property paid (transferred) as a contribution by a founder and/or participant to the authorized capital of a person who is not a resident of Diya City - a taxpayer under special conditions; as a contribution to joint activities to a person who is not a resident of Diya City - a taxpayer under special conditions, in trust management to a person who is not a resident of Diya City - a taxpayer under special conditions;
135.2.1.15. funds and/or the value of property (except for value-added tax, if applicable) paid (transferred) in connection with the acquisition of property, works, services (except for royalties) from single tax payers during the tax (reporting) year in an amount exceeding 20 percent of the amount of expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income) for the previous annual reporting (tax) period. At the same time, expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income) include expenses related to operating, financial and investment activities.
Residents of Diya City - taxpayers under special conditions who are registered during the reporting (tax) year (newly created), in the current calendar year, the calculation of the share of the cost of property (works, services) purchased (acquired) from single tax payers, provided for in the first paragraph of this subparagraph, is carried out based on the indicators of the Financial Results Report (Comprehensive Income Report) for the current annual reporting period.
If, on the date of payment of funds and/or transfer of property as an advance payment for property (works, services), the supplier was not a single tax payer, the provisions of this subparagraph shall apply to such transactions based on the results of the tax (reporting) period in which a resident of Diya City - a taxpayer under special conditions received property (works, services), provided that on the date of such receipt, the supplier is a single tax payer;
135.2.1.16. funds transferred from accounts of a resident of the City of Diya - a taxpayer under special conditions in Ukrainian banks to accounts of such a taxpayer opened abroad.
In the event that a resident of the City of Diya - a taxpayer under special conditions carries out transactions for the transfer (payment) of funds placed in accounts opened abroad, such transactions are not subject to taxation in accordance with clause 135.2 of Article 135, clause 137.10 of Article 137 and clause 141.9 - 1 (except for subparagraphs 141.9 - 1 .2.15 and 141.9 - 1 .3 ) of Article 141 of this Code, provided that such funds were taxed in accordance with the first paragraph of this subparagraph;
135.2.1.17. funds and/or the value of property paid (transferred) to a person who is not a resident of Diya City - a tax payer under special conditions and is a related person and/or a person - a payer of corporate income tax, whose profit is exempt from taxation due to the repayment of obligations under recognized fines, penalties, penalties, compensation for losses, compensation for unearned income (lost profit), accrued in accordance with civil legislation and civil law contracts.
The provisions of this subparagraph do not apply to transactions subject to taxation in accordance with subparagraph 135.2.1.9.2 of this subparagraph and transactions with individuals whose income is subject to personal income tax in accordance with Section IV of this Code.
{Article 135 is supplemented by paragraph 135.2 in accordance with Law No. 1946-IX of 14.12.2021 }
136.1 - 1. The basic (basic) tax rate is 25 percent for the purposes of:
a) taxation of the profit of a financial institution (except for an insurer), determined in accordance with subparagraph 134.1.1 of paragraph 134.1 of Article 134 of this Code;
b ) taxation of the adjusted profit of a controlled foreign company of a financial institution (except an insurer), determined in accordance with Article 39-2 of this Code;
c) application of the provisions of clause 57.1 - 1 of Article 57 of this Code for the payment of dividends by a financial institution (except for an insurer).
{Article 136 is supplemented by paragraph 136.1 - 1 in accordance with Law No. 3474-IX of 11/21/2023 - enters into force on January 1, 2024; as amended by Law No. 4015-IX of 10/10/2024 }
136.2. When conducting insurance activities of resident legal entities, simultaneously with the profit tax rate specified in clause 136.1 of this article, income tax rates are set at the following rates:
136.2.1. 3 percent under insurance contracts from the taxable object, which is defined in subparagraph 141.1.2 of paragraph 141.1 of Article 141 of this Code;
136.2.2. 0 percent under long-term life insurance contracts, voluntary health insurance contracts and insurance contracts within the framework of non-state pension provision, in particular supplementary pension insurance contracts, and specified in subparagraphs 14.1.52 , 14.1.52-1 , 14.1.52-2 and 14.1.116 of paragraph 14.1 of Article 14 of this Code .
136.3. Rates of 0, 4, 5, 6, 12, 15, 18 percent shall be applied to the income of non-residents and persons equated to them with their source of origin in Ukraine in the cases established by paragraph 141.4 of Article 141 of this Code.
{Clause 136.3 of Article 136 as amended by Law No. 466-IX of January 16, 2020 ; as amended by Law No. 3553-IX of January 16, 2024 }
136.4. When conducting activities in the field of organizing and conducting gambling games, simultaneously with the income tax rate specified in paragraph 136.1 of this article, the income tax rate is set at the amount of:
{Paragraph one of clause 136.4 of Article 136 as amended by Law No. 3325-IX of 10.08.2023 }
136.4.1. 10 percent of the income received from the organization and conduct of gambling in slot machine halls;
{Subclause 136.4.1 of Clause 136.4 of Article 136 as amended by Law No. 3325-IX of 10.08.2023 }
136.4.2. 18 percent of income received from activities in the field of organizing and conducting gambling, except for income received from organizing and conducting gambling in slot machine halls, reduced by the amount of payments paid to the player.
{Clause 136.4 of Article 136 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 3325-IX of 08/10/2023 }
136.5. Income tax, defined as an object of taxation in subparagraphs 134.1.2 , 134.1.4 , 134.1.5 of paragraph 134.1 of Article 134 of this Code, and on transactions of residents of the City of Diya - taxpayers under special conditions, defined as an object of taxation in subparagraph 134.1.8 of paragraph 134.1 of Article 134 of this Code, is part of the income tax.
{Clause 136.5 of Article 136 as amended by Law No. 1946-IX of 12/14/2021 }
136.6. When conducting activities related to the issuance and holding of lotteries, the income tax rate on the amount of income determined by subparagraph 134.1.4 of paragraph 134.1 of Article 134 of this Code shall be set at 30 percent, taking into account the provisions of paragraph 48 of subsection 4 of Section XX of this Code.
{Article 136 is supplemented by paragraph 136.6 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
136.7. The basic (basic) tax rate shall be applied to the object of taxation defined by subparagraph 134.1.7 of paragraph 134.1 of Article 134 of this Code.
{Article 136 is supplemented by paragraph 136.7 in accordance with Law No. 466-IX of 16.01.2020 }
136.8. When conducting activities by residents of Diya City - taxpayers under special conditions in accordance with the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", the tax rate is set at 9 percent of the tax base determined in accordance with the provisions of paragraph 135.2 of Article 135, paragraph 137.10 of Article 137 and paragraph 141.9 - 1 (except for subparagraphs 141.9 - 1 .2.16 , 141.9 - 1 .2.17 , 141.9 - 1 .3 , 141.9 - 1 .4 ) of Article 141 of this Code.
{Article 136 is supplemented by paragraph 136.8 in accordance with Law No. 1946-IX of 14.12.2021 ; as amended by Law No. 4112-IX of 04.12.2024 }
Article 137. Procedure for calculating and paying corporate income tax↑
{Title of Article 137 as amended by Law No. 909-VIII of 24.12.2015 }
137.1. The tax is calculated by the payer independently at the rate determined by Article 136 of this Code, from the tax base determined in accordance with Article 135 of this Code.
137.2. The tax payable to the budget by taxpayers engaged in insurance activities shall be determined in accordance with the procedure provided for in paragraph 141.1 of Article 141 of this Code.
137.3. Responsibility for the completeness of withholding and timely transfer to the budget of the tax specified in paragraphs 57.1 - 1 of Article 57 and 141.4 of Article 141 of this Code shall lie with taxpayers who make the relevant payments.
{Clause 137.3 of Article 137 as amended by Law No. 909-VIII of 24.12.2015 }
137.4. Tax (reporting) periods for corporate income tax, except for cases provided for in paragraph 137.5 of this article, are calendar periods: quarter, half-year, three quarters, year. In this case, the tax return is calculated on a cumulative basis. The tax (reporting) period begins on the first calendar day of the tax (reporting) period and ends on the last calendar day of the tax (reporting) period, except for:
137.4.1. agricultural producers who may choose an annual tax (reporting) period that begins on July 1 of the previous reporting year and ends on June 30 of the current reporting year.
{Paragraph one of subparagraph 137.4.1 of paragraph 137.4 of Article 137 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
For the purposes of income tax, enterprises whose main activity is the production of agricultural products include enterprises whose income from the sale of agricultural products of their own production for the previous tax (reporting) year exceeds 50 percent of the total income;
137.4.2. if a person is registered by a regulatory authority as a taxpayer during a tax (reporting) period, the first tax (reporting) period begins on the date on which such registration begins and ends on the last calendar day of such tax (reporting) period;
137.4.3. if the taxpayer is liquidated (including before the end of the first tax (reporting) period), the last tax (reporting) period is considered to be the period to which the date of liquidation falls.
{Clause 137.4 of Article 137 as amended by Law No. 909-VIII of 12/24/2015 }
137.5. The annual tax (reporting) period is established for the following taxpayers:
a) taxpayers registered during the reporting (tax) year (newly created), who pay income tax on the basis of the annual tax return for the period of activity in the reporting (tax) year;
b) agricultural producers;
c) taxpayers whose annual income from any activity (net of indirect taxes), determined by the indicators of the Financial Results Statement (Comprehensive Income Statement), for the previous annual reporting period, does not exceed 40 million hryvnias. At the same time, the annual income from any activity (net of indirect taxes), determined by the indicators of the Financial Results Statement (Comprehensive Income Statement), includes income (revenue) from the sale of products (goods, works, services), other operating income, financial income and other income;
{Subparagraph "c" of paragraph 137.5 of Article 137 as amended by Law No. 466-IX of January 16, 2020 }
d) individual entrepreneurs, including those who have chosen a simplified taxation system, and individuals who carry out independent professional activities, in respect of income (profits) paid to a non-resident with a source of origin in Ukraine, which are taxed in accordance with the procedure specified in paragraph 141.4 of Article 141 of this Code;
{Clause 137.5 of Article 137 is supplemented by subparagraph "d" in accordance with Law No. 466-IX of January 16, 2020 }
e) business entities - legal entities that have chosen a simplified taxation system, in respect of income (profits) paid to a non-resident with a source of origin from Ukraine, which are taxed in accordance with the procedure specified in paragraph 141.4 of Article 141 of this Code;
{Clause 137.5 of Article 137 is supplemented by subparagraph "g" in accordance with Law No. 466-IX of January 16, 2020 }
e) business entities - legal entities that have chosen a simplified taxation system, in relation to the received adjusted profit of a controlled foreign company, which is taxed in accordance with the procedure specified in Article 39 - 2 and this section;
{Clause 137.5 of Article 137 is supplemented by subparagraph "d" in accordance with Law No. 466-IX of January 16, 2020 }
f) legal entities - payers of the fourth group of the single tax on income (profits) received from the sale or other alienation of securities, and income received from the issuer of corporate rights, investment certificates or other securities certifying its ownership right to a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit, and calculated according to accounting rules.
{Clause 137.5 of Article 137 is supplemented by subparagraph "e" in accordance with Law No. 4577-IX of 21.08.2025 }
{Clause 137.5 of Article 137 as amended by Law No. 909-VIII of 12/24/2015 }
{Clause 137.6 of Article 137 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
137.7. A non-resident may annually receive from the controlling body confirmation in Ukrainian of tax payment in paper or electronic form in accordance with the procedure provided for by the central executive body that ensures the formation and implementation of state financial policy.
{Article 137 is supplemented by paragraph 137.7 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 1914-IX of 30.11.2021 }
137.8. Income tax payers: entities that issue and conduct lotteries pay income tax quarterly in the manner and within the deadlines established for the quarterly tax (reporting) period with the submission of a tax return on income tax .
{Article 137 was supplemented by paragraph 137.8 in accordance with Law No. 1797-VIII of 21.12.2016 }
137.9. The amount of corporate income tax payable to the budget by the controlling entity from the profit of a controlled foreign company shall be reduced by the amount of corporate tax or a similar tax levied in accordance with the legislation of foreign states actually paid by the controlled foreign company, including taxes withheld at the source of payment from the amount of income received by the controlled foreign company. The amount by which corporate income tax may be reduced shall be determined as the total amount of tax actually paid by the controlled foreign company based on the results of the relevant tax (reporting) period, proportional to the controlling entity's share in such a controlled foreign company, reflected in the report on controlled foreign companies.
The amount of corporate income tax reduction cannot exceed the amount of the legal entity's tax liability on the income of such controlled foreign company.
{Article 137 is supplemented by paragraph 137.9 in accordance with Law No. 466-IX of January 16, 2020 }
137.10. Features of calculation and payment of corporate income tax by residents of Diya City - taxpayers under special conditions
137.10.1. Residents of Diya City - taxpayers of tax under special conditions shall independently determine the amount of tax payable to the budget. The tax payable to the budget by residents of Diya City - taxpayers of tax under special conditions shall be determined taking into account the provisions stipulated in Clause 135.2 of Article 135, this Clause and Clause 141.9 - 1 of Article 141 of this Code. Residents of Diya City - taxpayers of tax under special conditions shall not separately determine the object of taxation stipulated in Subclause 134.1.1 of Clause 134.1 of Article 134 of this Code.
The amount of tax payable to the budget by a resident of Diya City - a taxpayer under special conditions for each separate transaction in accordance with Clause 135.2 of Article 135, this Clause and Clause 141.9 - 1 of Article 141 of this Code shall be reduced by the amount of tax on non-resident income accrued (paid) by a resident of Diya City - a taxpayer under special conditions for the relevant transaction in accordance with Clause 141.4 of Article 141 of this Code. In this case, the amount of the reduction may not exceed the amount of tax calculated in accordance with Clause 135.2 of Article 135, this Clause and Clause 141.9 - 1 of Article 141 of this Code.
137.10.2. In the event of a taxable transaction in a form other than cash, a resident of Diya City - a taxpayer under special conditions is obliged to independently verify the compliance of the contract price with the usual price and determine the tax base at a level not lower than the usual price. If a resident of Diya City - a taxpayer under special conditions has not determined the tax base at a level not lower than the usual price, the supervisory authority independently determines the difference between the usual price and the contractual (contractual) value of the taxable transaction, as well as the taxpayer's tax obligations.
137.10.3. The basic tax (reporting) period is equal to the calendar year. For a resident of Diya City registered in accordance with the procedure established by law - a taxpayer under special conditions, the first tax (reporting) period begins on the first day of the month following the tax (reporting) quarter in which:
137.10.3.1. such a taxpayer has acquired the status of a resident of Diya City, if an application for transition to taxation as a resident of Diya City - a taxpayer under special conditions was submitted to the authorized body during the application for acquisition of the status of a resident of Diya City in accordance with the first paragraph of subparagraph 141.10.2 of paragraph 141.10 of Article 141 of this Code;
137.10.3.2. such taxpayer has filed an application for transition to taxation as a resident of Diya City - a taxpayer under special conditions in accordance with paragraph two of subparagraph 141.10.2 of paragraph 141.10 of Article 141 of this Code;
137.10.3.3. an entry has been made in the Diya City register regarding such a taxpayer based on a court decision that has entered into legal force on the recognition as unlawful and the cancellation of the decision of the authorized body on the loss of the status of a Diya City resident in accordance with the procedure provided for by the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine" (if, prior to the adoption by the authorized body of a decision on the loss of the status of a Diya City resident that was recognized as unlawful and canceled by the court, such a resident was subject to taxation as a Diya City resident - a taxpayer under special conditions);
137.10.3.4. an entry has been made in the Diya City register regarding such a taxpayer based on a court decision that has entered into legal force, recognizing as unlawful and canceling the decision of the authorized body to return the application for acquiring the status of a Diya City resident or to refuse to acquire the status of a Diya City resident (if, together with the application for acquiring the status of a Diya City resident, an application for transition to taxation as a Diya City resident - a taxpayer under special conditions)
137.10.4. Tax liabilities are determined in the tax return submitted based on the results of the tax (reporting) year during which one of the following events occurred for transactions subject to taxation in accordance with subparagraph 141.9 - 1.2 of paragraph 141.9 - 1 of Article 141 of this Code:
137.10.4.1. funds were paid in cash or from accounts in Ukrainian banks, non-bank payment service providers/electronic wallets opened with electronic money issuers (including in connection with the provision of non-refundable financial assistance, transfer of funds to the taxpayer's accounts abroad) and/or property (including goods), works, services were provided (risks associated with ownership or results of work performed, services provided) were transferred;
{Subclause 137.10.4.1 of subparagraph 137.10.4 of clause 137.10 of Article 137 as amended by Law No. 2888-IX of 12.01.2023 }
137.10.4.2. set-off of counterclaims, assignment of the right of claim or transfer of debt, as a result of which the taxpayer's obligations for transactions that are subject to taxation in accordance with subparagraph 141.9 - 1.2 of paragraph 141.9 - 1 of Article 141 of this Code are terminated;
137.10.4.3. the 12-month period has expired starting from the month following the calendar month in which the refundable financial assistance was issued, which remained unpaid at the end of such 12-month period, or before the end of the 12-month period the debt for such financial assistance was recognized as uncollectible in accordance with subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code, or was terminated as a result of debt forgiveness;
137.10.4.4. the 365-day period has expired (or the period specified in the conclusion of the central executive body implementing the state policy of economic development, for exceeding the terms of settlements specified by law) from the date of payment of funds and/or transfer of property (including abroad), if such funds or property remain unreturned or the taxpayer has not received property or results of work performed (services rendered) in return for the paid funds, or funds in payment for property, work, services provided (has not offset counterclaims, as a result of which the taxpayer's obligation to pay funds or export property abroad is terminated);
137.10.4.5. the employment relationship is terminated or the gig contract is terminated with an individual who received financial assistance from the taxpayer in accordance with the provisions of the collective agreement or by decision of the taxpayer's highest management body, if on the date of termination of the employment relationship or termination of the gig contract the amount of funds received as financial assistance remains unpaid (in whole or in part);
137.10.4.6. an inventory was conducted, the results of which revealed a shortage of goods;
137.10.4.7. leasing payments have been paid under a financial leasing agreement with a non-resident (in the amount that reimburses the cost of the financial leasing object), if the leasing object located abroad has not been imported into Ukraine within 365 calendar days from the date of making the first leasing payment;
137.10.4.8. for transactions subject to taxation in accordance with subparagraph 141.9 - 1 .2.15 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of Article 141 of this Code, the transfer of ownership of property has been carried out or an act or other document has been drawn up in accordance with the requirements of the legislation, confirming the performance of work or the provision of services.
137.10.4 - 1. When determining tax liabilities for taxable transactions in accordance with subparagraph 135.2.1.7 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 and subparagraph 141.9 - 1 .2.6 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of Article 141 of this Code, the 12-month period shall be suspended if the debt for financial assistance issued by the taxpayer has not been repaid due to:
a) the debtor fails to fulfill his obligations and the resident of Diya City - a taxpayer under special conditions applies to the court with a request to collect such debt before the expiration of the 12-month period. In such a case, tax liabilities are determined based on the results of the tax (reporting) period during which the three-month period has expired from the date the court decision enters into force;
b) due to force majeure circumstances, natural disaster (force majeure circumstances), the existence of which is confirmed by documents issued by the competent authority of the relevant state. In such a case, the 12-month period shall be suspended for the period of such circumstances.
137.10.4 - 2 . When determining tax liabilities for taxable transactions in accordance with subparagraphs 135.2.1.9.3 , 135.2.1.9.4 and 135.2.1.10 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 and subparagraphs 141.9 - 1 .2.7 and 141.9 - 1 .2.8 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of Article 141 of this Code, the countdown of the 365-day period (the period specified in the conclusion of the central executive body implementing the state policy of economic development for exceeding the payment terms specified by law) is suspended if the debt that arose as a result of the payment by a resident of the City of Diya - a taxpayer on special terms of funds (provision of property, performance of work, provision of services) is not repaid in connection with:
a) failure of the debtor to fulfill his obligations and an appeal by a resident of Diya City - a taxpayer under special conditions to the court with a demand to collect such debt before the expiration of the 365-day period (the period specified in the conclusion of the central executive body implementing the state policy of economic development, for exceeding the payment terms specified by law). In such a case, tax liabilities are determined based on the results of the tax (reporting) period during which the three-month period expired from the date of entry into force of the court decision;
b) due to force majeure circumstances, natural disaster (force majeure circumstances), the existence of which is confirmed by documents issued by the competent authority of the relevant state. In such a case, the 365-day period (the period specified in the conclusion of the central executive body implementing the state economic development policy for exceeding the payment terms specified by law) is suspended for the period of such circumstances.
137.10.5. If a resident of Diya City - a taxpayer on special conditions is fully or partially refunded (including after the expiration of a 12-month period or a 365-day period (the period specified in the conclusion of the central executive body implementing the state policy of economic development, for exceeding the terms of settlements specified by law) funds or property previously provided by the taxpayer as a result of a transaction under which the resident of Diya City - a taxpayer on special conditions determined the amount of tax liabilities and paid the corresponding amount to the budget, the tax paid in the corresponding amount is reflected by the resident of Diya City - a taxpayer on special conditions as a reduction in tax liabilities in the tax declaration for the tax (reporting) period in which the resident of Diya City - a taxpayer on special conditions was refunded the funds or property.
For the purposes of this subparagraph, the return of funds or property to a resident of the City of Diya - a taxpayer under special conditions also includes:
a) repayment of debt arising from transactions involving the payment by a resident of Diya City - a taxpayer on special terms of funds (provision of property, performance of work, provision of services) to persons who are not residents of Diya City - taxpayers on special terms, under which the resident of Diya City - a taxpayer on special terms determined the amount of tax liabilities and paid the corresponding amount to the budget;
b) refund of funds (property) that were paid (transferred) in connection with investment in investment objects located outside the territory of Ukraine, as well as receipt of funds (property) from the sale (other alienation) of such investment objects or as compensation (reimbursement) of their value, provided that during the implementation of operations to invest funds (property) in such investment objects, the resident of Diya City - a taxpayer under special conditions determined the amount of tax liabilities and paid the corresponding amount to the budget.
Funds and/or property are considered returned to a Dia City resident if the funds are credited to the Dia City resident's accounts opened in Ukrainian banks, and the property is transferred to the Dia City resident in the customs territory of Ukraine or imported into the customs territory of Ukraine.
If the amounts of funds and/or the value of property returned to a resident of Diya City - a taxpayer under special conditions, are expressed in foreign currency, they are converted into hryvnia at the official exchange rate of hryvnia to foreign currency established by the National Bank of Ukraine, which was used to calculate the tax base when determining tax liabilities by a resident of Diya City - a taxpayer under special conditions.
137.10.6. If a financial leasing agreement with a non-resident does not provide for the import of the leasing object located abroad into the customs territory of Ukraine within 365 calendar days from the date of making the first leasing payment, the payment of leasing payments (in the amount that reimburses the cost of the financial leasing object) is equated to a transaction for making investments in investment objects located outside the territory of Ukraine.
, sets off counterclaims, assigns the right of claim or transfers debt, as a result of which his obligations are terminated, under transactions that are subject to taxation in accordance with subparagraph 141.9 - 1.2 of paragraph 141.9 - 1 of Article 141 of this Code, the implementation of such set-off of counterclaims, assignment of the right of claim or transfer of debt is equated to the object of taxation.
137.10.8. A taxpayer who was a resident of Diya City - a taxpayer under special conditions, is obliged to switch to paying corporate income tax on general grounds starting from:
a) on the first day of the year following the tax (reporting) year in which the Diya City resident did not meet the requirements of paragraph 4 of part one of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", regardless of the date of entry in the Diya City register of the loss of the status of a Diya City resident by the taxpayer;
b) on the first day of the month following the tax (reporting) quarter in which an entry was made in the Diya City register about the taxpayer losing the status of a Diya City resident for other reasons provided for by the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine". In this case, such a taxpayer submits an annual income tax return of a Diya City resident - a taxpayer under special conditions for the tax (reporting) period ending on the last day of the quarter in which an entry was made in the Diya City register about his loss of the status of a Diya City resident.
137.10.9. If the entry on the loss of the status of a Diya City resident by a taxpayer who was a Diya City resident - a taxpayer under special conditions - was made based on the results of a court appeal by the taxpayer against the decision on the loss of the status of a Diya City resident, which was not canceled, such a taxpayer is obliged to switch to paying corporate income tax on general grounds from the first day of the month following the tax (reporting) quarter in which the authorized body made a decision on the loss of the status of a Diya City resident.
In this case, such a taxpayer is obliged, within the period specified for the monthly tax (reporting) period, to submit a clarifying tax return(s) on corporate income tax for the relevant reporting periods, calculate the corporate income tax liability on a general basis without the application of penalties, and pay it within the terms specified in Article 57 of this Code.
{Article 137 is supplemented by paragraph 137.10 in accordance with Law No. 1946-IX of 14.12.2021 }
137.11. Taxpayers engaged in the activity of trading in currency values in cash shall be obliged to pay advance payments of corporate income tax for each foreign currency exchange point entered in the Register of Foreign Currency Exchange Points as of the first day of the current month. Advance payments and corporate income tax payable to the budget by taxpayers engaged in the activity of trading in currency values in cash shall be determined in accordance with the procedure provided for in Clause 141.13 of Article 141 of this Code.
{Article 137 is supplemented by paragraph 137.11 in accordance with Law No. 2720-IX of 03.11.2022 }
137.12. Taxpayers engaged in retail fuel trade shall be obliged to pay advance payments of corporate income tax for each place of retail fuel trade, information about which is entered in the Unified Register of Licensees and Places of Fuel Circulation as of the first day of the current month. Advance payments and corporate income tax payable to the budget by taxpayers engaged in retail fuel trade shall be determined in accordance with the procedure provided for in Clause 141.14 of Article 141 of this Code.
{Article 137 is supplemented by paragraph 137.12 in accordance with Law No. 4015-IX of 10.10.2024 }
Article 138. Differences arising when calculating depreciation of non-current assets↑
138.1. Financial result before tax increases:
for the amount of accrued depreciation of fixed assets and/or intangible assets in accordance with national accounting regulations (standards) or international financial reporting standards;
{Paragraph two of clause 138.1 of Article 138 as amended by Law No. 466-IX of 16.01.2020 }
for the amount of depreciation and impairment losses on fixed assets and/or intangible assets included in the expenses of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards;
{Paragraph two of clause 138.1 of Article 138 as amended by Law No. 466-IX of 16.01.2020 }
for the amount of the residual value of a separate item of fixed assets and/or intangible assets, determined in accordance with national accounting regulations (standards) or international financial reporting standards, in the event of liquidation or sale of such an item.
{Paragraph four of clause 138.1 of Article 138 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
for the amount of the residual value of a separate item of non-productive fixed assets and/or non-productive intangible assets, determined in accordance with national accounting regulations (standards) or international financial reporting standards, in the event of liquidation or sale of such an item;
{Clause 138.1 of Article 138 supplemented by paragraph five in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended in accordance with Law No. 466-IX of 16.01.2020 }
for the amount of expenses for repair, reconstruction, modernization or other improvements to non-productive fixed assets or non-productive intangible assets, classified as expenses in accordance with national accounting regulations (standards) or international financial reporting standards;
{Clause 138.1 of Article 138 was supplemented by the sixth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
138.2. The financial result before taxation is reduced:
for the amount of calculated depreciation of fixed assets and/or intangible assets in accordance with clause 138.3 of this article;
{Paragraph two of clause 138.2 of Article 138 as amended by Law No. 466-IX of 16.01.2020 }
for the amount of the residual value of a separate item of fixed assets and/or intangible assets, determined taking into account the provisions of this article of the Code, in the event of liquidation or sale of such an item;
{Paragraph three of clause 138.2 of Article 138 as amended by Law No. 466-IX of 16.01.2020 }
for the amount of the revaluation of fixed assets and/or intangible assets within the limits of previously allocated depreciation expenses in accordance with national accounting regulations (standards) or international financial reporting standards;
{Paragraph four of clause 138.2 of Article 138 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
to the amount of benefits from the restoration of the usefulness of fixed assets and/or intangible assets within the limits of previously allocated to expenses losses from the impairment of fixed assets or intangible assets in accordance with national accounting regulations (standards) or international financial reporting standards;
{Paragraph of Clause 138.2 of Article 138 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
for the amount of the original cost of acquiring or manufacturing a separate item of non-productive fixed assets and/or non-productive intangible assets and the costs of their repair, reconstruction, modernization or other improvements, including those attributed to expenses in accordance with national accounting regulations (standards) or international financial reporting standards, in the event of the sale of such an item of non-productive fixed assets or intangible assets, but not more than the amount of income (proceeds) received from such sale.
{Paragraph of Clause 138.2 of Article 138 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
138.3. Procedure for calculating depreciation of fixed assets or intangible assets to determine the object of taxation
138.3.1. The calculation of depreciation of fixed assets and intangible assets shall be carried out in accordance with national accounting regulations (standards) or international financial reporting standards, taking into account the restrictions established by subparagraph 14.1.138 of paragraph 14.1 of Article 14 of Section I of this Code, subparagraphs 138.3.2-138.3.4 of this paragraph. In such a calculation, the depreciation calculation methods provided for by national accounting regulations (standards) shall be applied.
{Paragraph one of subparagraph 138.3.1 of paragraph 138.3 of Article 138 as amended by Law No. 466-IX of January 16, 2020 }
To calculate depreciation in accordance with the provisions of this paragraph, the value of fixed assets and intangible assets is determined without taking into account their revaluation (mark-up, revaluation) carried out in accordance with accounting provisions.
{Subclause 138.3.1 of clause 138.3 of Article 138 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
Depreciation is not charged for the period of non-use (operation) of fixed assets in economic activities due to their conservation.
{Subparagraph 138.3.1 of paragraph 138.3 of Article 138 is supplemented by the third paragraph in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 786-IX of 07.14.2020 }
138.3.2. The following are not subject to depreciation and are carried out at the expense of appropriate sources:
the value of goodwill;
expenses for the acquisition/independent production of non-productive fixed assets, non-productive intangible assets;
for repair, reconstruction, modernization or other improvements of non-productive fixed assets, non-productive intangible assets.
The term "non-productive fixed assets", "non-productive intangible assets" means, respectively, fixed assets, intangible assets not intended for use in the taxpayer's business activities.
{Paragraph five of subparagraph 138.3.2 of paragraph 138.3 of Article 138 as amended by Law No. 1914-IX of 11/30/2021 }
For the purposes of calculating the difference by which the financial result before taxation is increased in accordance with Clause 140. 2 of Article 140 of this Code, the taxpayer is obliged to keep separate records of interest that was capitalized (subject to inclusion in the cost of a non-current asset) in accordance with national accounting regulations (standards) or international financial reporting standards.
{Subparagraph 138.3.2 of paragraph 138.3 of Article 138 is supplemented by the sixth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Subclause 138.3.2 of Clause 138.3 of Article 138 as amended by Law No. 1797-VIII of 21.12.2016 }
138.3.3. Minimum allowable depreciation periods for fixed assets and other non-current assets (except in the case of application of the production method of depreciation):
Groups
Minimum allowable useful life, years
group 1 - land plots
-
group 2 - capital expenditures for land improvements not related to construction
15
group 3 - buildings
20
buildings
15
transmitting devices
10
group 4 - machinery and equipment
5
Of these:
electronic computers, other machines for automatic data processing, related means of reading or printing information, related computer programs (except for programs, the acquisition costs of which are recognized as royalties, and/or programs that are recognized as intangible assets), other information systems, switches, routers, modules, modems, uninterruptible power supplies and means of connecting them to telecommunications networks, telephones (including cellular), microphones and walkie-talkies, the cost of which exceeds 20,000 hryvnias
2
group 5 - vehicles
5
group 6 - tools, appliances, inventory, furniture
4
group 7 - animals
6
group 8 - perennial plantings
10
group 9 - other fixed assets
12
group 10 - library funds, preservation of the National Archival Fund of Ukraine
-
group 11 - low-value non-current tangible assets
-
group 12 - temporary (non-title) structures
5
group 13 - natural resources
-
group 14 - inventory packaging
6
group 15 - rolled items
5
group 16 - long-term biological assets
7
The minimum allowable depreciation periods for fixed assets and other non-current assets are used taking into account the following.
If the useful life (operation) of a fixed asset in accounting is less than the minimum allowable depreciation periods for fixed assets and other non-current assets, the periods established by this subparagraph are used to calculate depreciation.
If the useful life (operation) of a fixed asset in accounting is equal to or greater than that established by this subparagraph, the useful life (operation) of the fixed asset established in accounting shall be used to calculate depreciation.
{Subclause 138.3.3 of Clause 138.3 of Article 138 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
138.3.4. Periods for calculating depreciation of intangible assets:
Groups
Term of validity of the right of use
group 1 - rights to use natural resources (right to use subsoil, other resources of the natural environment, geological and other information about the natural environment)
According to the title deed
group 2 - rights to use property (the right to use a land plot, except for the right to permanent use of a land plot in accordance with the law, the right to use a building, the right to rent premises, etc.)
According to the title deed
group 3 - rights to commercial designations (rights to trademarks (marks for goods and services), commercial (brand) names, etc.), except for those whose acquisition costs are recognized as royalties
According to the title deed
group 4 - rights to industrial property objects (rights to inventions, utility models, industrial designs, plant varieties, animal breeds, layouts (topographies) of integrated circuits, trade secrets, including know-how, protection against unfair competition, etc.), except for those whose acquisition costs are recognized as royalties
According to the title document, but not less than 5 years
group 5 - copyright and related rights (rights to literary, artistic, musical works, computer programs, programs for electronic computers, compilations of data (databases), phonograms, videograms, broadcasts (programs) of broadcasting organizations, etc.), except for those whose acquisition costs are recognized as royalties
According to the title document, but not less than 2 years
group 6 - other intangible assets (right to conduct business, use economic and other privileges, etc.)
According to the title deed
If, according to the title document, the term of the right to use an intangible asset is not established, such a useful life is determined by the taxpayer independently, but cannot be less than two and more than 10 years.
138.4. The requirements of paragraphs 138.1-138.3 of this article do not apply to transactions with assets under right-of-use lease agreements.
{Article 138 was supplemented by paragraph 138.4 in accordance with Law No. 2628-VIII of 23.11.2018 }
Article 139. Differences arising from the formation of reserves (provisions)↑
139.1. Provision for reimbursement of subsequent (future) expenses
139.1.1. The financial result before tax increases:
for the amount of expenses for creating provisions (reserves) to reimburse subsequent (future) expenses (except for provisions (reserves) for expenses for paying vacations to employees, other payments related to labor remuneration, and expenses for paying a single social contribution charged on such payments) in accordance with national accounting regulations (standards) or international financial reporting standards.
{Subparagraph 139.1.1 of paragraph 139.1 of Article 139 as amended by Law No. 1797-VIII of 21.12.2016 }
139.1.2. The financial result before taxation is reduced:
for the amount of use of created provisions (reserves) for expenses (except for provisions (reserves) for expenses for paying vacations to employees, other payments related to labor remuneration, and expenses for paying the single social contribution accrued on such payments), formed in accordance with national accounting regulations (standards) or international financial reporting standards;
by the amount of adjustment (reduction) of provisions (reserves) to compensate for subsequent (future) expenses (except for provisions (reserves) for employee vacations, other payments related to labor remuneration, and expenses for payment of a single social contribution accrued on such payments), by which the financial result before taxation increased in accordance with national accounting regulations (standards) or international financial reporting standards.
{Subclause 139.1.2 of Clause 139.1 of Article 139 as amended by Law No. 1797-VIII of 21.12.2016 }
139.2. Reserve for doubtful debts or reserve for expected credit losses (impairment of assets).
139.2.1. Financial result before tax increases:
for the amount of expenses for forming a reserve for doubtful debts or a reserve for expected credit losses (reduction in asset usefulness) in accordance with national accounting regulations (standards) or international financial reporting standards;
for the amount of expenses from the write-off of receivables in excess of the amount of the reserve for doubtful debts or in excess of the reserve for expected credit losses (impairment of assets).
139.2.2. The financial result before taxation is reduced:
by the amount of the adjustment (reduction) to the provision for doubtful debts or the provision for expected credit losses (reduction in asset usefulness) by which the financial result before tax increased in accordance with national accounting regulations (standards) or international financial reporting standards;
for the amount of written-off receivables (including at the expense of the created reserve for doubtful debts or reserve for expected credit losses (reduction in asset usefulness), which meets the criteria specified in subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code.
The provisions of paragraphs two and three of this subparagraph shall not be applied by state unitary enterprises and business companies in whose authorized capital more than 50 percent of the shares (shares) belong to the state, whose accounting policy in determining the methods for calculating the amount of the reserve for doubtful debts (reserve for expected credit losses) and the method of determining the doubtfulness coefficient has not been agreed with the owner (owners) or the body (official) authorized by him in accordance with the legislation.
{Subparagraph 139.2.2 of paragraph 139.2 of Article 139 is supplemented by the fourth paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
{Clause 139.2 of Article 139 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
139.3. Reserves of banks and non-bank financial institutions
139.3.1. Banks and non-bank financial institutions, except for insurance companies, non-state pension funds, corporate investment funds and administrators of non-state pension funds, shall recognize a reserve for assets for taxation in accordance with the requirements of international financial reporting standards, taking into account the requirements of subparagraphs 139.3.2-139.3.4 of this paragraph.
{Subclause 139.3.1 of clause 139.3 of Article 139 as amended by Law No. 2245-VIII of 07.12.2017 }
139.3.2. The use of a reserve in connection with the derecognition of an asset in accordance with the requirements of international financial reporting standards does not change the financial result before taxation, except for the cases specified in subparagraphs 139.3.3 and 139.3.4 of this paragraph.
139.3.3. Financial result before tax increases:
1) for the amount of the use of the reserve for the write-off (reimbursement) of an asset that does not meet the criteria specified in subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code;
2) for the amount of the use of the reserve in connection with the termination of recognition of an asset upon forgiveness of debt of individuals who are related to such a creditor or are in an employment relationship with such a creditor, or were in an employment relationship with such a creditor and the period between the date of termination of the employment relationship of such persons and the date of forgiveness of their debt does not exceed three years.
The amount of the use of the reserve in connection with the termination of recognition of an asset when the creditor forgives the debt of other persons not specified in subparagraph 2 of this subparagraph does not change the financial result before taxation.
{Subclause 139.3.3 of Clause 139.3 of Article 139 as amended by Law No. 1791-VIII of 20.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
139.3.4. The financial result before taxation is reduced:
{Subparagraph 1 of subparagraph 139.3.4 of paragraph 139.3 of Article 139 was excluded on the basis of Law No. 2245-VIII of 07.12.2017 }
2) for the amount of write-off in previous reporting periods of an asset that in the reporting period acquired the characteristics specified in subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code;
{Subparagraph 3 of subparagraph 139.3.4 of paragraph 139.3 of Article 139 was excluded on the basis of Law No. 2245-VIII of 07.12.2017 }
4) for the amount of income (reduction in expenses) from the repayment of debt previously written off against the reserve, which does not meet the criteria specified in subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code.
{Subclause 4 of subparagraph 139.2.4 of clause 139.2 of Article 139 as amended by Law No. 1797-VIII of 21.12.2016 }
139.3.5. Adjustment of the financial result before taxation in connection with the creation and use by banks and non-bank financial institutions of reserves (collateral), including under provided lending obligations, guarantees, sureties, letters of credit, acceptances, avals, in addition to the reserves specified in the previous subparagraphs of this paragraph, shall be carried out in accordance with the procedure established by paragraph 139.1 of this article.
Article 140. Differences arising from the implementation of financial transactions↑
140.1. Taxation of interest on debt obligations
For the purposes of this paragraph, debt obligations should be understood as obligations under any credits, loans, deposits, REPO transactions, obligations under financial leasing agreements and other borrowings, regardless of their legal form.
Capitalized interest that increased the cost of non-current assets in accordance with national accounting regulations (standards) or international financial reporting standards shall be taken into account when calculating the amount of the excess in accordance with paragraph 140.2 of this article in the depreciation period of the relevant fixed assets.
{Clause 140.1 of Article 140 is supplemented by the third paragraph in accordance with Law No. 466-IX of January 16, 2020 }
140.2. For a taxpayer whose amount of debt obligations specified in paragraph 140.1 of this Article, arising from transactions with non-residents, exceeds the amount of equity by more than 3.5 times, the financial result before taxation is increased by the amount of the excess of interest accrued in accounting on credits, loans and other debt obligations (except for interest subject to capitalization in accordance with national accounting regulations (standards) or international financial reporting standards until the relevant asset is put into operation) arising from transactions with non-residents over 30 percent of the amount of the calculated object of taxation by income tax of the reporting (tax) period in which such interest is accrued, increased by the amount of financial expenses according to the financial statements and the amount of depreciation deductions according to the tax statements of the same reporting (tax) period.
The amount of debt obligations arising from transactions with non-residents and the amount of equity for the purposes of this paragraph is determined as the arithmetic average of the values of such debt obligations and, accordingly, equity at the beginning and end of the reporting tax period, taking into account the interest specified in paragraph 140.3 of this Article.
For the purposes of this paragraph, the object of taxation is determined in accordance with Article 134 of this Code with the adjustment of the financial result before taxation for all differences determined in accordance with the provisions of this section, except for:
negative value of the object of taxation of previous tax (reporting) years;
the difference defined by this clause.
If in the reporting (tax) period the indicator calculated in accordance with the first paragraph of this paragraph has a negative value, the financial result before taxation is increased by the entire amount of interest arising from transactions with non-residents accrued in this reporting (tax) period.
For the purposes of this paragraph, the amount of interest expenses incurred on transactions with non-residents accrued during the reporting (tax) period shall be added to the amount of depreciation deductions attributable to the amount of such interest expenses capitalized as part of the cost of the non-current asset until its commissioning. The taxpayer shall determine in each separate reporting (tax) period the share of depreciation deductions from the cost of the relevant non-current asset attributable to the amount of such capitalized interest, based on the applicable depreciation method and the useful life of the relevant non-current asset.
In the event that the amount of interest expenses on controlled transactions exceeds the level determined in accordance with the "arm's length" principle, the provisions of this paragraph shall apply to the amount of interest expenses that comply with the "arm's length" principle. The provisions of this paragraph shall apply for the results of the reporting (tax) year.
The provisions of this paragraph do not apply and the financial result before taxation is not increased by the amount of interest that is subject to capitalization in accordance with national accounting regulations (standards) or international financial reporting standards and does not affect the financial result before taxation of the taxpayer in the reporting (tax) period, until the moment the relevant non-current asset is put into operation.
The adjustments provided for in this paragraph shall not be made in respect of:
a) the amounts of interest recognized as not complying with the "arm's length" principle in accordance with Article 39 of this Code;
b) the amount of interest accrued in favor of international financial organizations that, in accordance with international treaties of Ukraine, are granted privileges and immunity for credits (loans) received by business entities and the performance of which is secured by state or local guarantees;
c) the amount of interest accrued in favor of foreign banks.
The provisions of this paragraph do not apply to financial institutions and companies engaged exclusively in leasing activities.
{Clause 140.2 of Article 140 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020, taking into account the amendments made by Law No. 1117-IX of 17.12.2020 }
140.3. Interest exceeding the amount of the limitation specified in clause 140.2 of this article, which increased the financial result before taxation, shall reduce the financial result before taxation of future reporting tax periods in an amount reduced annually by 5 percent of the amount of interest that remained not taken into account in the reduction of the financial result before taxation, taking into account the limitations established in clause 140.2 of this article.
{Clause 140.3 of Article 140 as amended by Law No. 1797-VIII of 21.12.2016 }
140.4. Financial result before tax decreases:
140.4.1. on the amount of accrued income from participation in the capital of other payers of corporate income tax, payers of the single tax and on the amount of accrued income in the form of dividends payable in its favor from other payers of this tax (except for collective investment institutions and payers whose profit is exempt from taxation in accordance with the provisions of this Code, in the amount of profit exempt from taxation);
140.4.2. for the amount of accrued income in the form of dividends payable in his favor from a controlled foreign company within the limits not exceeding the amount by which the taxable amount was increased in accordance with subparagraph 134.1.7 of paragraph 134.1 of Article 134 of this Code.
The norms of this subparagraph are applied based on the results of the tax (reporting) year.
If the taxpayer is obliged to reduce the financial result before taxation by the amount of accrued income in the form of dividends specified in this subparagraph, as well as in accordance with the provisions of subparagraph 140.4.3 of this subparagraph, the adjustment in accordance with the provisions of this subparagraph shall not be made;
140.4.3. on the amount of accrued income from participation in the capital of non-residents (including controlled foreign companies) and on the amount of accrued income in the form of dividends payable in his favor from such a non-resident, provided that the share of participation in the capital of the non-resident is at least 10 percent during the calendar year and such a non-resident is not included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code (except for states (territories) with which Ukraine has international treaties on the avoidance of double taxation of income).
{Paragraph one of subparagraph 140.4.3 of paragraph 140.4 of Article 140 as amended by Law No. 3813-IX of 18.06.2024 }
If in previous tax (reporting) periods (taking into account the terms established by Article 102 of this Code) dividends were actually paid by a non-resident in favor of a resident in the period before such resident achieved a calendar year of continuous ownership of a share in the capital of a non-resident and such income was subject to taxation, the resident has the right to file a clarifying tax return for the relevant previous tax (reporting) periods and apply the provisions of this subparagraph after achieving one year of continuous ownership of a share in the capital of the relevant non-resident, if other conditions are met under which an adjustment is permitted by reducing the financial result before taxation by the amount of accrued income in the form of dividends;
140.4.4. for the amount of the negative value of the taxpayer's object of taxation (except for large taxpayers) in previous tax (reporting) years.
Large taxpayers reduce the financial result before taxation by a portion of the amount of the negative value of the object of taxation of previous tax (reporting) years until it is fully repaid in the following manner.
Large taxpayers have the right to reduce the financial result before taxation of the tax (reporting) period (profit, loss or zero value) by no more than 50 percent of the outstanding amount of the negative value of the object of taxation of previous tax (reporting) years.
The amount of the negative value of the taxable object of previous tax (reporting) years, not repaid by the positive value of the taxable object of the tax (reporting) year, reduces the financial result before taxation (profit, loss or zero value) of future tax (reporting) periods in the amount of no more than 50 percent of such outstanding amount until its full repayment.
If the outstanding amount of the negative value of the object of taxation of previous tax (reporting) years is no more than 10 percent of the positive value of the object of taxation of the tax (reporting) period, calculated in accordance with subparagraph 134.1.1 of paragraph 134.1 of Article 134 of this Code without taking into account the outstanding negative value of the object of taxation of previous tax (reporting) years, such amount of negative value reduces the financial result before taxation of this tax (reporting) period in full.
The provisions of this subparagraph shall apply taking into account paragraphs 3 and 4 - 2 of subsection 4 of section XX "Transitional provisions" of this Code.
For the purposes of this subparagraph, the amounts of the negative value of the object of taxation of previous tax (reporting) years for which two of the following conditions are simultaneously met are considered to be repaid:
a) these amounts were included in the calculation of the taxable amount for future tax (reporting) periods;
b) these amounts were used to reduce the positive value of the object of taxation (profit) of the relevant tax (reporting) years, calculated in accordance with subparagraph 134.1.1 of paragraph 134.1 of Article 134 of this Code, without taking into account the outstanding negative value of the object of taxation of previous tax (reporting) years;
{Subparagraph 140.4.4 of paragraph 140.4 of Article 140 as amended by Law No. 1914-IX of 11/30/2021 }
140.4.5. taxpayer - legal successor to the amount of the negative value of the taxable object of the taxpayer, which is reorganized by:
accession, merger, transformation - during the period of approval of the transfer act;
division, allocation - during the period of approval of the distribution balance in proportion to the received share of property according to the distribution balance.
When conducting a reorganization, the negative value of the object of taxation of the tax (reporting) period, which was recorded by the taxpayer being terminated, on the date of approval of the transfer act or distribution balance sheet, reduces the financial result before taxation of the taxpayer - legal successor in an amount that does not exceed the amount of the equity of the taxpayer being terminated, as of the end of the previous tax (reporting) year and provided that the taxpayer being terminated and the taxpayer - legal successor were related parties for more than eighteen consecutive months before the date of completion of the merger (merger);
140.4.6. for the amount of the write-down taken into account in the financial result before taxation in the current tax (reporting) period for equity instruments reclassified into financial liabilities in accordance with national accounting regulations (standards) or international financial reporting standards;
140.4.7. for the amount of subsidies received by a taxpayer - a subject of cinematography of Ukraine for the reimbursement of part of qualified expenses in accordance with the Law of Ukraine "On State Support of Cinematography in Ukraine", incurred during the production (creation) of a film and included in the income of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards.
140.4.8. for the amount of budget grants received by the taxpayer and included in the income of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards.
{Clause 140.4 of Article 140 is supplemented by subparagraph 140.4.8 in accordance with Law No. 962-IX of 04.11.2020 }
{Clause 140.4 of Article 140 as amended by Laws No. 903-VIII of 12/23/2015 , No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 , No. 2176-VIII of 11/07/2017 , No. 2245-VIII of 12/07/2017 ; as amended by Law No. 466-IX of 16/01/2020 }
140.5. The financial result of the tax (reporting) period increases:
140.5.1. for the amount of the excess of the price determined according to the "arm's length" principle over the contractual (contractual) value (the value at which the relevant transaction must be reflected when forming the financial result before taxation in accordance with the accounting rules) of the goods (works, services) sold when carrying out controlled transactions in the cases specified in Article 39 of this Code.
The norms of this subparagraph are applied based on the results of the tax (reporting) year;
{Subclause 140.5.1 of clause 140.5 of Article 140 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
140.5.2. for the amount of the excess of the contractual (contractual) value (the value at which the relevant transaction must be reflected when forming the financial result before taxation in accordance with the accounting rules) of the purchased goods (works, services) over the price determined according to the "arm's length" principle, when carrying out controlled transactions in cases specified in Article 39 of this Code.
The norms of this subparagraph are applied based on the results of the tax (reporting) year;
{Subclause 140.5.2 of Clause 140.5 of Article 140 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
140.5.2 - 1. for the amount of the transaction that the regulatory authority does not take into account (does not recognize) as a result of the application of subparagraph 39.2.2.12, subparagraph 39.2.2, paragraph 39.2 of Article 39 of this Code.
When the financial result before taxation of the taxpayer's tax (reporting) period increases in accordance with the requirements of this subparagraph, other adjustments provided for in subparagraphs 140.5.1 and 140.5.2 of this subparagraph with respect to such a transaction shall not be applied.
The obligation to make adjustments to the financial result before taxation provided for in this subparagraph shall be imposed on the controlling body, and the amount of this adjustment in respect of such a transaction shall be reduced by the amounts of the adjustments provided for in subparagraphs 140.5.1 and 140.5.2 of this subparagraph, if the taxpayer has already independently applied these adjustments in respect of such a transaction;
{ Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.2 - 1 in accordance with the Law No. 1117-IX dated 17.12.2020 }
140.5.3. for the amount of losses from investments in associates, subsidiaries and joint ventures, calculated using the equity method or the proportionate consolidation method;
140.5.4. in the amount of 30 percent of the cost of goods, including non-current assets (except for assets under lease agreements), works and services (except for transactions specified in clause 140.2 and subclause 140.5.6 of this clause, and transactions recognized as controlled in accordance with Article 39 of this Code), purchased from:
{Paragraph one of subparagraph 140.5.4 of paragraph 140.5 of Article 140 as amended by Law No. 2628-VIII of 23.11.2018 }
non-profit organizations entered in the Register of Non-profit Institutions and Organizations on the date of such acquisition, except for cases where the total value of goods, including non-current assets (except for assets under lease agreements), works and services purchased from such organizations, in aggregate during the reporting (tax) year does not exceed 25 times the minimum wage established by law as of January 1 of the reporting (tax) year, and except for budgetary institutions, the Accumulation Fund, non-state pension funds and a non-profit organization that is an association of insurers, if the participation of the insurer in such an association is a condition for the conduct of activities of such insurer in accordance with the law;
{Paragraph two of subparagraph 140.5.4 of paragraph 140.5 of Article 140 as amended by Law No. 2628-VIII of 23.11.2018 }
non-residents (including related persons - non-residents) registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code;
non-residents, whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, who do not pay income tax (corporate tax), including tax on income received outside the state (territory) of registration of such non-residents, and/or are not tax residents of the state (territory) in which they are registered as legal entities.
{Paragraph four of subparagraph 140.5.4 of paragraph 140.5 of Article 140 as amended by Law No. 3813-IX of 06/18/2024 }
The financial result before taxation is increased by the entire amount of the cost of goods, including non-current assets (except for assets from the right of use under lease agreements), works and services (except for transactions specified in clause 140.2 and subclause 140.5.6 of this clause, and transactions recognized as controlled in accordance with Article 39 of this Code), purchased from non-residents, defined in paragraphs three and four of this subclause, if such transactions do not have a business purpose. The obligation to prove the circumstances provided for in this paragraph shall be imposed on the controlling body with the application of the relevant provisions of Article 39 of this Code. In this case, other adjustments provided for in this subclause shall not be applied, and the amount of this adjustment in respect of such transaction shall be reduced by the amount of the adjustment provided for in paragraph one of this subclause, if the taxpayer has already independently applied this adjustment in respect of such transaction.
{Subparagraph 140.5.4 of paragraph 140.5 of Article 140 is supplemented with a new paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
The requirements of this subparagraph shall not be applied by the taxpayer if the transaction is not controlled and the amount of such expenses is confirmed by the taxpayer at prices determined at arm's length in accordance with the procedure established by Article 39 of this Code, but without submitting a report.
At the same time, if the purchase price of goods, including non-current assets (except for assets under lease agreements), works and services exceeds their price determined at arm's length in accordance with the procedure established by Article 39 of this Code, the financial result before taxation is adjusted by the amount of the difference between the purchase price and the price determined based on the price level determined at arm's length.
{Paragraph of subparagraph 140.5.4 of paragraph 140.5 of Article 140 as amended by Law No. 2628-VIII of 23.11.2018 }
In the event of non-application of the requirements of this subparagraph on the basis of paragraph six of this subparagraph, if the regulatory authority does not take into account (does not recognize) such a transaction based on the results of the analysis in accordance with Article 39 of this Code, the financial result before taxation shall be increased in the manner provided for in paragraph one of subparagraph 140.5.2 - 1 of paragraph 140.5 of Article 140 of this Code. In this case, other adjustments provided for in this subparagraph shall not be applied, and the amount of this adjustment in respect of such a transaction shall be reduced by the amount of the adjustment provided for in paragraph seven of this subparagraph, if the taxpayer has already independently applied this adjustment in respect of such a transaction.
{Subparagraph 140.5.4 of paragraph 140.5 of Article 140 is supplemented with a new paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
The norms of this subparagraph are applied based on the results of the tax (reporting) year.
{Subclause 140.5.4 of clause 140.5 of Article 140 is supplemented by a paragraph in accordance with Law No. 466-IX of 16.01.2020 }
{Subclause 140.5.4 of clause 140.5 of Article 140 as amended by Law No. 652-VIII of 17.07.2015 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 }
{Subclause 140.5.5 of clause 140.5 of Article 140 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
140.5.5 - 1. in the amount of 30 percent of the cost of goods, including non-current assets, works and services (except for transactions recognized as controlled in accordance with Article 39 of this Code), sold for the benefit of:
non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 Sub-clause 39.2.1 of clause 39.2 of Article 39 of this Code;
non-residents, whose organizational and legal form is included in the list of organizational and legal forms approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 - 1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, who do not pay income tax (corporate tax), including tax on income received outside the state (territory) of registration of such non-residents, and/or are not tax residents of the state (territory) in which they are registered as legal entities.
{Paragraph three of subparagraph 140.5.5 - 1 of paragraph 140.5 of Article 140 as amended by Law No. 3813-IX of 06/18/2024 }
The financial result before taxation is increased by the entire amount of the cost of goods, including non-current assets, works and services (except for transactions recognized as controlled in accordance with Article 39 of this Code), sold to non-residents, defined in paragraphs two and three of this sub-item, if such transactions do not have a business purpose. The obligation to prove the circumstances provided for in this paragraph shall be imposed on the controlling body with the application of the relevant provisions of Article 39 of this Code. In this case, other adjustments provided for in this sub-item shall not be applied, and the amount of this adjustment in respect of such transaction shall be reduced by the amount of the adjustment provided for in paragraph one of this sub-item, if the taxpayer has already independently applied this adjustment in respect of such transaction.
{Subclause 140.5.5 - 1 of clause 140.5 of Article 140 is supplemented with a new paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
The requirements of this subparagraph shall not be applied by the taxpayer if the transaction is not controlled and the amount of such income is confirmed by the taxpayer at prices determined at arm's length in accordance with the procedure established by Article 39 of this Code, but without submitting a report.
At the same time, if the sale price of goods, including non-current assets, works and services is lower than the price determined in accordance with the "arm's length" principle established by Article 39 of this Code, the adjustment of the financial result before taxation is carried out by the amount of the difference between the value determined based on the price level determined according to the "arm's length" principle and the sale price.
In the event of non-application of the requirements of this subparagraph on the basis of paragraph five of this subparagraph, if the regulatory authority does not take into account (does not recognize) such a transaction based on the results of the analysis in accordance with Article 39 of this Code, the financial result before taxation shall be increased in the manner provided for in paragraph one of subparagraph 140.5.2 - 1 of paragraph 140.5 of Article 140 of this Code. In this case, other adjustments provided for in this subparagraph shall not be applied, and the amount of this adjustment in respect of such a transaction shall be reduced by the amount of the adjustment provided for in paragraph six of this subparagraph, if the taxpayer has already independently applied this adjustment in respect of such a transaction.
{Subclause 140.5.5 - 1 of clause 140.5 of Article 140 is supplemented with a new paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
The norms of this subparagraph are applied based on the results of the tax (reporting) year.
{Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.5 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
140.5.6. for the amount of expenses for the calculation of royalties (except for transactions recognized as controlled in accordance with Article 39 of this Code) in favor of a non-resident (including a non-resident registered in the states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code), which exceeds the amount of income from royalties increased by 4 percent of the net income from the sale of products (goods, works, services) according to the financial statements for the year preceding the reporting year (except for business entities that carry out activities in the field of television and radio broadcasting in accordance with the Law of Ukraine "On Television and Radio Broadcasting", and after its lapse - except for entities in the field of audiovisual media that carry out activities as an entity in the field of linear audio media service or as an entity in the field of linear audiovisual media service in accordance with the Law of Ukraine "On Media"), and for banks - in an amount exceeding 4 percent of operating income (net of value added tax) for the year preceding the reporting year.
{Paragraph one of subparagraph 140.5.6 of paragraph 140.5 of Article 140 as amended by Laws No. 3813-IX of 06/18/2024 , No. 4113-IX of 12/04/2024 }
The financial result before taxation is increased by the entire amount of expenses for the calculation of royalties (except for transactions recognized as controlled in accordance with Article 39 of this Code) in favor of a non-resident (including a non-resident registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code), if such transactions do not have a business purpose. The obligation to prove the circumstances provided for in this paragraph shall be imposed on the controlling body with the application of the relevant provisions of Article 39 of this Code. In this case, other adjustments provided for in this subparagraph shall not be applied, and the amount of this adjustment in respect of such transaction shall be reduced by the amount of the adjustment provided for in the first paragraph of this subparagraph, if the taxpayer has already independently applied this adjustment in respect of such transaction.
{Subparagraph 140.5.6 of paragraph 140.5 of Article 140 is supplemented with a new paragraph in accordance with Law No. 1117-IX of December 17, 2020 ; as amended by Law No. 3813-IX of 18.06.2024 }
The requirements of this subparagraph shall not be applied by the taxpayer if:
the transaction is not controlled and the amount of such expenses is confirmed by the taxpayer at prices determined at arm's length, in accordance with the procedure established by Article 39 of this Code, but without submitting a report.
In the event that the requirements of this subparagraph are not applied on the basis of paragraphs three and four of this subparagraph, the financial result before taxation shall be increased in accordance with the procedure provided for in subparagraph 140.5.2 - 1 of paragraph 140.5 of Article 140 of this Code. In this case, other adjustments provided for in this subparagraph shall not be applied.
{Subparagraph 140.5.6 of paragraph 140.5 of Article 140 is supplemented with a new paragraph in accordance with Law No. 1117-IX of 17.12.2020 }
The norms of this subparagraph are applied based on the results of the tax (reporting) year;
{Subclause 140.5.6 of clause 140.5 of Article 140 is supplemented by a paragraph in accordance with Law No. 466-IX of 16.01.2020 }
{Subclause 140.5.6 of Clause 140.5 of Article 140 as amended by Law No. 1797-VIII of 21.12.2016 }
140.5.7. for the amount of expenses for accruing royalties in full, if royalties are accrued for the benefit of:
{Subparagraph 1 of subparagraph 140.5.7 of paragraph 140.5 of Article 140 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
2) a non-resident who is not the beneficial (actual) recipient (owner) of the royalty, except for cases where the beneficiary (actual owner) has granted the right to receive the royalty to other persons.
For the purposes of applying this subparagraph, in cases where resident cinematographers of Ukraine pay royalties to non-residents under sublicense agreements for the use or for granting the right to use audiovisual works (including films), as well as objects of copyright and/or related rights used in the production (creation) of audiovisual works (including films), such non-residents shall be considered beneficial (actual) recipients (owners) of such royalties;
{Subparagraph 2 of subparagraph 140.5.7 of paragraph 140.5 of Article 140 is supplemented by the second paragraph in accordance with Law No. 2176-VIII of 07.11.2017 }
3) a non-resident regarding objects, intellectual property rights to which first arose with a resident of Ukraine.
In the event of disagreements between the controlling body and the taxpayer regarding the determination of the person who first acquired (acquired) intellectual property rights to an intellectual property object, such controlling bodies are obliged to contact the central executive body implementing state policy in the field of intellectual property to obtain a relevant opinion.
The requirements of this subparagraph do not apply to cases of royalty accrual by a cinematographer for the use of intellectual property rights (films, literary works, musical works, works of fine art, photographic works, phonograms, videograms), except for cases where a resident of Ukraine is a cinematographer who has acquired copyright and related rights as a result of the creation (production) of the specified works, if he subsequently transferred or alienated copyright or related rights to a non-resident and charges royalties for the use of this object;
{Subclause 3 of subparagraph 140.5.7 of clause 140.5 of Article 140 is supplemented by the third paragraph in accordance with Law No. 2176-VIII of 07.11.2017 }
4) a non-resident who is not subject to tax in respect of royalties in the state of which he is a resident;
5) a person who pays tax as part of other taxes, except for individuals who are taxed in accordance with the procedure established by Section IV of this Code;
6) a legal entity that, in accordance with this Code, is exempt from paying this tax or pays this tax at a rate other than the base (basic) rate established by this Code.
{Paragraph one of subparagraph 6 of subparagraph 140.5.7 of paragraph 140.5 of Article 140 as amended by Law No. 3474-IX of 21.11.2023 }
The requirements of this subparagraph shall not be applied by the taxpayer in cases of accrual of royalties in favor of rightholders as remuneration for the use of copyright objects and (or) related rights or as deductions in favor of rightholders on the basis of agreements concluded by such taxpayer with collective management organizations in accordance with the Law of Ukraine "On Effective Management of Property Rights of Rightholders in the Sphere of Copyright and (or) Related Rights";
{Subclause 6 of subparagraph 140.5.7 of clause 140.5 of Article 140 is supplemented by the second paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
{Paragraph nine of subparagraph 140.5.7 of paragraph 140.5 of Article 140 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Paragraph ten of subparagraph 140.5.7 of paragraph 140.5 of Article 140 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Paragraph eleven of subparagraph 140.5.7 of paragraph 140.5 of Article 140 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Paragraph twelfth of subparagraph 140.5.7 of paragraph 140.5 of Article 140 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
140.5.8. for the amount of interest and revaluations included in the financial result before taxation in the current tax (reporting) period on equity instruments reclassified into financial liabilities in accordance with national accounting regulations (standards) or international financial reporting standards;
140.5.9. for the amount of funds or the cost of goods, work performed, services provided, transferred (transferred) free of charge during the reporting (tax) year to non-profit organizations entered in the Register of Non-profit Institutions and Organizations on the date of such transfer of funds, transfer of goods, work, services (except for a non-profit organization that is an association of insurers, if the participation of the insurer in such an association is a condition for conducting the activities of such insurer in accordance with the law, and non-profit organizations to which the provisions of subparagraph 140.5.14 of this paragraph apply), in an amount exceeding 4 percent of the taxable profit of the previous reporting year.
{Paragraph one of subparagraph 140.5.9 of paragraph 140.5 of Article 140 as amended by Law No. 466-IX of January 16, 2020 }
The requirements of this subparagraph do not apply to the payment by the bank of mandatory fees in accordance with the Law of Ukraine "On the Deposit Guarantee System of Individuals", as well as to the payment by taxpayers of other payments, the implementation of which is a mandatory condition for carrying out professional activities in accordance with the legislation of Ukraine.
{Subparagraph 140.5.9 of paragraph 140.5 of Article 140 is supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 }
The provisions of paragraph one of this subparagraph shall not apply to goods supplied (transferred) free of charge by a person authorized to carry out procurement in the healthcare sector, provided that:
{Subclause 140.5.9 of clause 140.5 of Article 140 is supplemented by a paragraph in accordance with Law No. 532-IX of March 17, 2020 }
1) such goods on the date of conclusion of the contract for their purchase were included in the List of medicines, medical devices and auxiliary means to them, which are purchased with the funds of the state budget for the implementation of programs and centralized measures in healthcare , and/or in the List of medicines, which are purchased under managed access contracts , approved by the Cabinet of Ministers of Ukraine, and
{Subclause 140.5.9 of clause 140.5 of Article 140 is supplemented by a paragraph in accordance with Law No. 532-IX of March 17, 2020 ; as amended by Law No. 4505-IX of June 18, 2025 }
2) such goods were purchased by a person authorized to make purchases in the healthcare sector, at the expense of state budget funds provided for the implementation of programs and centralized healthcare measures, and/or local budget funds, and/or at the expense of state or municipally owned business entities that have a license to conduct business activities in medical practice.
{Subclause 140.5.9 of clause 140.5 of Article 140 is supplemented by a paragraph in accordance with Law No. 532-IX of March 17, 2020 ; as amended by Law No. 4505-IX of June 18, 2025 }
The provisions of paragraph one of this subparagraph shall not apply to goods supplied (transferred) free of charge by a person authorized to make procurements in the healthcare sector, provided that such goods were purchased with funds from grants (sub-grants) for the implementation of programs of the Global Fund to Fight AIDS, Tuberculosis and Malaria in Ukraine in accordance with the law;
{Subclause 140.5.9 of clause 140.5 of Article 140 is supplemented by a paragraph in accordance with Law No. 532-IX of March 17, 2020 }
The provisions of paragraph one of this subparagraph shall not apply to intangible assets provided (transferred) free of charge by entities of the public sector of the economy to executive bodies, to the sphere of management of which such entities belong, which are created, modernized and/or purchased at the expense of the state budget within the framework of the implementation of informatization projects and/or e-government programs, and/or received as a result of the implementation of international technical assistance projects.
{Subparagraph 140.5.9 of paragraph 140.5 of Article 140 is supplemented with a new paragraph in accordance with Law No. 3603-IX of 23.02.2024 }
{Subclause 140.5.9 of Clause 140.5 of Article 140 as amended by Laws No. 652-VIII of 17.07.2015 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
140.5.10. for the amount of non-refundable financial assistance (goods, works, services provided free of charge) transferred to persons who are not tax payers (except for individuals who are payers of personal income tax), to taxpayers who are related persons (if the recipient of financial assistance (goods, works, services provided free of charge) declared a negative value of the object of taxation for the tax (reporting) year preceding the year in which such non-refundable financial assistance (goods, works, services provided free of charge) was received, provided that such assistance was taken into account as part of expenses when determining the financial result before taxation), and to taxpayers who are taxed at a rate of 0 percent in accordance with paragraph 44 of subsection 4 of section XX "Transitional provisions" of this Code, except for non-refundable financial assistance (goods, works, services provided free of charge) transferred to non-profit organizations entered in the Register of Non-profit Institutions and Organizations on the date of such transfer of funds, transfer of goods, works, services to which the provisions of subclause 140.5.9 of this clause apply;
{Paragraph one of subparagraph 140.5.10 of paragraph 140.5 of Article 140 as amended by Law No. 466-IX of January 16, 2020 ; as amended by Law No. 1914-IX of November 30, 2021 }
for the amount of full or partial compensation once per calendar year of the cost of vacation, health improvement and treatment trips in the territory of Ukraine of the taxpayer and/or his children under 18 years of age by an employer who is a payer of income tax, if such compensation, in accordance with this Code, is not included in the total monthly (annual) taxable income of an individual - a payer of income tax on individuals;
{Subclause 140.5.10 of clause 140.5 of Article 140 is supplemented by the second paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
{Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.10 in accordance with Law No. 1797-VIII of 21.12.2016 }
140.5.11. for the amount of expenses from recognized fines, penalties, penalties, compensation for losses, compensation for unearned income (lost profit), accrued in accordance with civil legislation and civil law contracts, including in the field of foreign economic activity, in favor of persons who are not tax payers (except for individuals who are payers of personal income tax), and in favor of taxpayers who are taxed at a rate of 0 percent in accordance with paragraph 44 of subsection 4 of section XX "Transitional provisions" of this Code, as well as for the amount of fines, penalties accrued by regulatory authorities and other state authorities for violation of the requirements of the law;
{Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.11 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
{Subparagraph 140.5.12 of paragraph 140.5 of Article 140 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
140.5.13. for the amount of expenses incurred by the taxpayer in the current reporting period at the expense of previously received subsidies to return part of qualified expenses in accordance with the Law of Ukraine "On State Support for Cinematography in Ukraine", but not more than the amount of such subsidy incurred during the production (creation) of the film and included in the expenses of the current reporting period in accordance with national accounting regulations (standards) or international financial reporting standards;
{Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.13 in accordance with Law No. 2176-VIII of 07.11.2017 }
140.5.14. for the amount of funds or the cost of goods, work performed, services provided, transferred (transferred) free of charge during the reporting (tax) year to entities in the field of physical culture and sports, namely children's and youth sports schools, Olympic training centers, schools of higher sports skills, centers of physical culture and sports for people with disabilities, sports federations in Olympic sports, which are non-profit organizations entered in the Register of Non-profit Institutions and Organizations, on the date of such transfer of funds, transfer of goods, work, services in an amount exceeding 8 percent of the taxable profit of the previous reporting year;
{Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.14 in accordance with Law No. 2245-VIII of 07.12.2017 }
{Subclause 140.5.15 of clause 140.5 of Article 140 was excluded on the basis of Law No. 1117-IX of 17.12.2020 }
140.5.16. for the amount of expenses related to the fulfillment of the terms of the budget grant agreement, incurred in the current reporting period at the expense of such grants (but not more than the amount of such grants) and included in the expenses of the current reporting period in accordance with national accounting regulations (standards) or international financial reporting standards;
{Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.16 in accordance with Law No. 962-IX of 04.11.2020 }
140.5.17. for the amount of the cost of property, works, services (except for royalties) purchased (acquired) by a resident of Diya City - a payer of corporate income tax on a general basis from payers of a single tax during the tax (reporting) year, in an amount exceeding 20 percent of the amount of expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income) for the previous annual reporting period. At the same time, expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income) include expenses related to operating, financial and investment activities.
Residents of Diya City - payers of corporate income tax on general grounds, registered during the reporting (tax) year (newly created), in the current calendar year, the calculation of the share of the cost of property (works, services) purchased (acquired) from payers of the single tax, provided for in the first paragraph of this subparagraph, is carried out based on the indicators of the Financial Results Report (Comprehensive Income Report) for the current annual reporting period.
If, on the date of receipt of property, works, or services, the supplier is not a single tax payer, such property, works, or services are considered to be purchased from a single tax payer, provided that, on the date of the advance payment, the supplier was a single tax payer.
{Clause 140.5 of Article 140 is supplemented by subparagraph 140.5.17 in accordance with Law No. 1946-IX of 14.12.2021 }
140.6. Prohibition of taking into account, when determining the object of taxation, expenses for transactions carried out with the aim of providing an unlawful benefit
140.6.1. The financial result before taxation is increased by the amount of expenses recognized by the taxpayer in accounting in accordance with national accounting regulations (standards) or international financial reporting standards, if the taxpayer, based on the totality of the conditions of the transaction, has reason to believe that the existing circumstances (facts) indicate the implementation of such a transaction for the purpose of providing an unlawful benefit to an official (including an official of a foreign state).
The financial result before tax increases for the tax (reporting) period in which the expenses were recognized by the taxpayer in accounting in accordance with national accounting regulations (standards) or international financial reporting standards.
For the purposes of applying this subparagraph, when considering the circumstances (facts) related to the relevant transaction that may indicate that it was carried out with the aim of providing an unlawful benefit to an official, the taxpayer shall take into account the actual actions of the parties to the transaction and the actual circumstances of the transaction in accordance with its essence, and for a transaction related to an official of a foreign state, he shall also be guided by the list published on the official website of the National Anti-Corruption Bureau of Ukraine in accordance with clause 12 of part one of Article 16 of the Law of Ukraine "On the National Anti-Corruption Bureau of Ukraine".
140.6.2. The financial result before taxation is increased by the amount of expenses recognized by the taxpayer in accounting in accordance with national accounting regulations (standards) or international financial reporting standards, if the regulatory authority does not take into account (does not recognize) such an amount of expenses due to the fact that, in accordance with the legislation, it is established that the transaction was carried out on behalf of and/or in the interests of the taxpayer for the purpose of providing unlawful benefit during the commission of a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, directly or indirectly (through third parties), regardless of the amount of unlawful benefit.
The responsibility for making adjustments to the financial result before taxation, as provided for in this subparagraph, lies with the regulatory authority. In this case:
when determining the total amount of expenses that the controlling authority does not take into account (does not recognize) when calculating the taxpayer's tax liability, the controlling authority takes into account the results of the taxpayer's adjustment of the financial result before taxation of the relevant tax (reporting) periods by the difference provided for in subparagraph 140.6.1 , as well as the requirements of subparagraph 140.6.3 of this paragraph regarding the relevant transaction;
The total amount of expenses that the regulatory authority does not take into account (does not recognize) when determining the taxpayer's tax liability is calculated for each tax (reporting) period in which such expenses had an impact on the object of taxation, for the entire period of time, starting from the tax (reporting) period in which the results of the transaction were reflected in the taxpayer's accounting, up to the tax (reporting) period (inclusive) in which, in accordance with the legislation, it is established that the relevant transaction was carried out on behalf of and/or in the interests of the taxpayer for the purpose of providing an unlawful benefit during the commission of a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, directly or indirectly (through third parties), regardless of the amount of the unlawful benefit .
140.6.3. When applying the provisions of subparagraphs 140.6.1 and 140.6.2 of this paragraph to transactions carried out with the involvement of fixed assets and/or intangible assets, the financial result before taxation of each of the tax (reporting) periods in which such involvement was carried out is increased by the amount of depreciation of fixed assets and/or intangible assets, calculated in accordance with the provisions of paragraph 138.3 of Article 138 of this Code. Such adjustment of the financial result before taxation is carried out exclusively if in the relevant tax (reporting) period the financial result before taxation is reduced by the specified amount of depreciation in accordance with the rules of paragraph 138.2 of Article 138 of this Code. In this case, the amount of accrued depreciation of fixed assets and/or intangible assets in accordance with national accounting regulations (standards) or international financial reporting standards, by which the financial result before taxation is increased in accordance with the second paragraph of paragraph 138.1 of Article 138 of this Code, is not taken into account when determining the amount of expenses for the purposes of subparagraphs 140.6.1 and 140.6.2 of this paragraph.
{Article 140 is supplemented by paragraph 140.6 in accordance with Law No. 4112-IX of 04.12.2024 }
Article 141. Peculiarities of taxation of certain types of activities and transactions↑
141.1. Features of taxation of the insurer
141.1.1. Insurers shall pay profit tax at the rate determined in accordance with Clause 136.1 of Article 136 of this Chapter, and income tax at the rate determined in accordance with Subclauses 136.2.1 and 136.2.2 of Clause 136.2 of Article 136 of this Code.
The income tax charged by the insurer at the rate specified in subparagraph 136.2.1 of paragraph 136.2 of Article 136 of this Code is the difference that reduces the financial result before taxation of such insurer.
141.1.2. The object of taxation of the insurer, to which the rate determined in accordance with subparagraphs 136.2.1 and 136.2.2 of paragraph 136.2 of Article 136 of this Code is applied, is calculated as the sum of insurance payments, insurance contributions, insurance premiums accrued under insurance and co-insurance contracts. In this case, insurance payments, insurance contributions, insurance premiums under co-insurance contracts are included in the object of taxation of the insurer only in the amount of its share of the insurance premium provided for by the co-insurance contract.
Insurance payments, insurance contributions, insurance premiums under reinsurance contracts are not included in the object of taxation to which the rate determined in accordance with subparagraphs 136.2.1 and 136.2.2 of paragraph 136.2 of Article 136 of this Code is applied.
{Subclause 141.1.2 of clause 141.1 of Article 141 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
141.1.3. The financial result before taxation of the insurer increases:
on the positive difference between the increase (loss) in insurance reserves formed in the relevant reporting period in accordance with international financial reporting standards, except for those that do not affect the formation of the financial result before taxation of the insurer (net of claims against reinsurers in insurance reserves), and the increase (loss) in the relevant reserves calculated according to the methodology determined by the National Bank of Ukraine (net of claims against reinsurers in insurance reserves);
{Paragraph two of subparagraph 141.1.3 of paragraph 141.1 of Article 141 as amended by Law No. 2888-IX of 12.01.2023 }
on the positive difference between the amount of any payments (remuneration) to insurance intermediaries and other persons for services provided in connection with the conclusion (prolongation) of insurance contracts and the amount of the standard cost of payments to insurance intermediaries, calculated according to the methodology determined by the authorized body carrying out state regulation in the field of financial services markets, in agreement with the central executive body that ensures the formation and implementation of state financial policy.
{Subclause 141.1.3 of clause 141.1 of Article 141 is supplemented by the third paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
{Subclause 141.1.3 of Clause 141.1 of Article 141 as amended by Law No. 1797-VIII of 21.12.2016 }
141.1.4. The financial result before taxation of the insurer is reduced:
on the negative difference between the increase (loss) in insurance reserves formed in the relevant reporting period in accordance with international financial reporting standards, except for those that do not affect the formation of the insurer's financial result before taxation (net of claims against reinsurers in insurance reserves), and the increase (loss) in the relevant reserves calculated according to the methodology determined by the National Bank of Ukraine (net of claims against reinsurers in insurance reserves).
{Paragraph two of subparagraph 141.1.4 of paragraph 141.1 of Article 141 as amended by Law No. 2888-IX of 12.01.2023 }
{Subclause 141.1.4 of clause 141.1 of Article 141 as amended by Law No. 1797-VIII of 21.12.2016 }
141.1.5. Adjustment of the financial result before taxation in connection with the creation and use by insurers of reserves (provisions) other than those specified in clause 141.1 of this Article shall be carried out in accordance with the procedure established by clause 139.1 of Article 139 of this Code.
{Subclause 141.1.5 of Clause 141.1 of Article 141 as amended by Law No. 1797-VIII of 21.12.2016 }
141.2. Differences regarding transactions for the sale or other disposal of securities
{Paragraph one of clause 141.2 of Article 141 as amended by Law No. 1797-VIII of 21.12.2016 }
141.2.1. The financial result before tax increases:
for the amount of negative financial result from the sale or other disposal of securities, reflected in the financial result before tax of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards;
{Paragraph two of subparagraph 141.2.1 of paragraph 141.2 of Article 141 as amended by Law No. 466-IX of January 16, 2020 }
for the amount of the negative total result of the revaluation of securities (the total amount of securities revaluations exceeds the total amount of their revaluations for the tax (reporting) period) (except for government securities or local loan bonds), reflected in the financial result before tax for the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards.
{Paragraph three of subparagraph 141.2.1 of paragraph 141.2 of Article 141 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
141.2.2. The financial result before taxation is reduced:
for the amount of positive financial result from the sale or other disposal of securities, reflected in the financial result before tax of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards.
{Paragraph two of subparagraph 141.2.1 of paragraph 141.2 of Article 141 as amended by Law No. 466-IX of January 16, 2020 }
141.2.3. Taxpayers shall separately determine the total financial result from transactions on the sale or other disposal of securities of the reporting period in accordance with national or international financial reporting standards.
141.2.4. If, based on the results of the reporting period, a negative total financial result is obtained from sales or other disposal of securities (the total amount of losses from sales or other disposal of securities, taking into account the amount of the negative financial result from such transactions and/or the negative total result of the revaluation of securities not taken into account in previous tax (reporting) periods, exceeds the total amount of profits from such transactions), the amount of such negative value of the total financial result from sales or other disposal of securities reduces the total financial result from sales or other disposal of securities of the following tax (reporting) periods that follow the tax (reporting) period in which the specified negative value of the financial result occurs.
{Subclause 141.2.4 of Clause 141.1 of Article 141 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
141.2.5. If, based on the results of the reporting period, the taxpayer received a positive total financial result from sales or other disposal of securities (the total amount of profits from sales or other disposal of securities exceeds the total amount of losses from such operations, taking into account the amount of the negative financial result from such operations and/or the negative total result of the revaluation of securities not taken into account in previous tax (reporting) periods), the amount of the positive total financial result from sales or other disposal of securities increases the financial result before taxation of the tax (reporting) period of the taxpayer.
{Subclause 141.2.5 of Clause 141.1 of Article 141 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
141.2.6. The provisions of this clause do not apply to:
1) transactions of taxpayers on placement, redemption, redemption and subsequent sale, conversion of securities of their own issue, as well as of promissory note issuers, pledgors and other persons who issued non-issued securities, during the issuance and redemption of such securities;
2) REPO transactions, transactions for the accounting of bills of exchange, other transactions with securities that, in accordance with accounting regulations (standards), are recognized as credit transactions;
3) derivatives transactions.
141.3. Taxation of profit received by a taxpayer under the terms of a production sharing agreement shall be carried out taking into account the features established by Section XVIII of this Code.
141.4. Peculiarities of taxation of non-residents
141.4.1. Income received by a non-resident with a source of origin in Ukraine shall be taxed in accordance with the procedure and at the rates specified in this Article. For the purposes of this paragraph, such income shall be:
a) interest, discount income paid to a non-resident, including interest on loans and debt obligations issued (issued) by a resident;
b) dividends paid by a resident;
c) royalties;
d) freight and engineering revenues;
e) leasing/rental fees paid by residents in favor of a non-resident - lessor/landlord under operating leasing/rental agreements;
{Subparagraph "g" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of January 16, 2020 }
e) income from the sale or other alienation of real estate or an indivisible object of unfinished construction/future real estate or a divisible object of unfinished construction, located or which, after the commissioning of the completed object, will be located in the territory of Ukraine, owned by a non-resident;
{Subparagraph "d" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of January 16, 2020 ; as amended by Law No. 2600-IX of September 20, 2022 }
e) profit from the sale or other disposal of the following investment assets:
securities, derivatives or other corporate rights in the authorized capital of resident legal entities, except for those traded on a stock exchange included in the list approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph "a" of subparagraph 141.4.11 of paragraph 141.4 of Article 141 of this Code;
shares, corporate rights, interests in foreign companies, organizations established in accordance with the legislation of other states (foreign legal entities), except for those traded on the stock exchange, included in the list approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph "a" of subparagraph 141.4.11 of paragraph 141.4 of Article 141 of this Code, which meet the following conditions:
a) at any time during the 365 days preceding the sale or other alienation, the value of shares, interests, corporate or other similar rights of a foreign legal entity is 50 percent or more formed at the expense of shares, interests in a Ukrainian legal entity that belong to the said foreign legal entity directly or indirectly, and
b) at any time during the 365 days preceding the sale or other disposal, the value of shares, interests in a Ukrainian legal entity is 50 percent or more formed at the expense of real estate located in Ukraine and owned by such Ukrainian legal entity or used by such Ukrainian legal entity on the basis of an operating or financial lease (leasing) agreement or a similar agreement, and such use must be reflected in the accounting of such legal entity as an asset, including an asset from the right of use, in accordance with the requirements of national accounting regulations (standards) or international financial reporting standards.
{Paragraph five of subparagraph "e" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 1117-IX of 17.12.2020 }
shares, corporate rights in the authorized capital of a legal entity - a resident of Ukraine, provided that at any time during the 365 days preceding the sale or other alienation, the value of such shares, corporate rights was formed by 50 percent or more at the expense of real estate located in Ukraine and owned by such legal entity - a resident of Ukraine or used by such legal entity - a resident of Ukraine on the basis of an operating or financial lease (leasing) agreement or a similar agreement, and such use must be reflected in the accounting of such legal entity as an asset, including an asset from the right of use, in accordance with the requirements of national accounting regulations (standards) or international financial reporting standards.
{Paragraph six of subparagraph "e" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 786-IX of July 14, 2020 ; as amended by Law No. 1117-IX of December 17, 2020 }
The value of shares, interests, corporate or other similar rights (for the purposes of paragraphs four and six subparagraphs "e" of this subparagraph) and real estate (for the purposes of paragraphs five and six subparagraphs "e" of this subparagraph) is determined on the basis of the book value (residual) according to accounting data as the highest amount at any time during the 365 days preceding the sale or other alienation, and is subject to comparison with the value of other property (assets) according to the book value (residual) according to accounting data of such legal entity;
{Paragraph of subparagraph "e" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 786-IX of 14.07.2020 }
{Subparagraph "e" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of 16.01.2020 }
g) income received from conducting joint activities in the territory of Ukraine, income from the implementation of long-term contracts in the territory of Ukraine;
g) remuneration for the conduct of cultural, educational, religious, sports, and entertainment activities on the territory of Ukraine by non-residents or persons authorized by them;
h) brokerage, commission or agency fees received from residents or permanent representations of other non-residents in respect of brokerage, commission or agency services provided by a non-resident in the territory of Ukraine for the benefit of residents;
{Subparagraph "c" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of 16.01.2020 }
i) contributions and premiums for insurance or reinsurance of risks in Ukraine (including life insurance) or insurance of residents against risks outside Ukraine;
i) income received from entertainment activities (except lottery activities);
j) income in the form of charitable contributions and donations for the benefit of non-residents;
j) income from the alienation of rights to extract and develop mineral deposits, mineral springs and other natural resources located on the territory of Ukraine, belonging to a non-resident;
{Subparagraph "y" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 as amended by Law No. 2176-VIII of 07.11.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
j) other income from conducting economic activities by a non-resident on the territory of Ukraine, except for income in the form of proceeds or other types of compensation for the cost of goods, work performed, services provided, transferred, performed, provided to a resident (permanent establishment of another non-resident) from such non-resident, including the cost of international communication services or international information support.
{Subclause 141.4.1 of clause 141.4 of Article 141 is supplemented by subparagraph "k" in accordance with Law No. 466-IX of 16.01.2020 }
by the Law of Ukraine "On State Support of Cinematography in Ukraine" are not considered income for the purposes of this paragraph .
{Subclause 141.4.1 of clause 141.4 of Article 141 is supplemented by a paragraph in accordance with Law No. 821-IX of 21.07.2020 }
141.4.2. A resident, including an individual entrepreneur, an individual engaged in independent professional activity, or a business entity (legal entity or individual entrepreneur) who has chosen a simplified taxation system, or another non-resident who conducts business through a permanent establishment in the territory of Ukraine, who makes any payment to a non-resident or a person authorized by him from income with a source of origin in Ukraine received by such non-resident (including to non-resident accounts maintained in the national currency), shall withhold tax on such income specified in subparagraph 141.4.1 of this paragraph at a rate of 15 percent (except for income specified in subparagraphs 141.4.4-141.4.5 and 141.4.11 of this paragraph) of their amount and at their expense, which is paid to the budget at the time of such payment, unless otherwise provided for by the provisions of international treaties of Ukraine with the countries of residence of the persons in whose favor the payments are made, which have entered into force. The requirements of this paragraph do not apply to income of non-residents received by them through their permanent establishments in the territory of Ukraine.
{Paragraph one of subparagraph 141.4.2 of paragraph 141.4 of Article 141 as amended by Law No. 1525-IX of 03.06.2021 }
If a resident (except for single tax payers of the fourth group) makes a payment to a non-resident of income specified in paragraphs four to six of subparagraph 14.1.49 of paragraph 14.1 of Article 14 of this Code in an amount exceeding the amount corresponding to the "arm's length" principle, or pays other income equated to dividends under this Code, such resident must withhold from the amount of such excess and from such other income a tax on non-resident income at a rate of 15 percent (unless another rate is established by an international treaty, the binding nature of which has been approved by the Verkhovna Rada of Ukraine). Such tax must be paid by the deadline for submitting a report on controlled transactions for the relevant reporting (tax) year.
If income is paid to a non-resident in any form other than cash, or if tax on the non-resident's income was not withheld from the relevant income at the time of payment (including during the payment of income equated to dividends under this Code), such tax shall be assessed and paid based on the following calculation:
Ps = SD*100/(100 - SP) - SD, where:
Ps - the amount of tax payable;
SD - the amount of income paid;
SP - the tax rate established by this subparagraph.
{Paragraph eight of subparagraph 141.4.2 of paragraph 141.4 of Article 141 was excluded on the basis of Law No. 786-IX of 14.07.2020 }
If a non-resident acquires ownership of an investment asset defined in paragraphs three to six of subparagraph "e" of subparagraph 141.4.1 of this paragraph from another non-resident who does not have a permanent establishment in Ukraine in accordance with the provisions of this paragraph, the non-resident who acquires ownership is obliged to withhold tax on the profit from the alienation of the investment asset paid in favor of another non-resident at a rate of 15 percent and at his expense, declare and transfer the tax to the budget of Ukraine at the time of such payment, unless otherwise provided for by the provisions of international treaties of Ukraine with the country of residence of the person in whose favor the payment is made, which have entered into force.
{Paragraph nine of subparagraph 141.4.2 of paragraph 141.4 of Article 141 as amended by Law No. 786-IX of July 14, 2020 }
Such a non-resident buyer shall be obliged, no later than the date of making the first payment for the investment asset being purchased, to register with the regulatory authority at the location of the Ukrainian legal entity, the shares of which corporate rights form the value of the investment asset that is the subject of such a transaction. Registration of such non-residents shall be carried out in accordance with the procedure established by Clause 64.5 of Article 64 of this Code.
Profit from the transactions specified in subparagraph "e" of subparagraph 141.4.1 of this paragraph is defined as the positive difference between the income received from the sale or other alienation of an investment asset and the documented costs of acquiring such an asset. If, at the request of the person who, in accordance with this subparagraph, is responsible for paying tax on profit from such a transaction, the non-resident alienating the investment asset does not provide documents confirming the costs of acquiring such an asset, the tax base for such profit shall be the cost of the transaction on the alienation of the investment asset.
{Subclause 141.4.2 of clause 141.4 of Article 141 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
141.4.3. Profits of non-residents received in the form of income from interest-free (discount) bonds or treasury bills are taxed at the rate established by paragraph 136.1 of Article 136 of this Code, taking into account the fact that:
the tax base is profit, which is calculated as the difference between the nominal value of interest-free (discount) securities, paid or accrued by their issuer, and their purchase price on the primary or secondary stock market;
for the purpose of tax control, the purchase or sale of securities specified in this subparagraph may be carried out on behalf of and at the expense of a non-resident exclusively by its permanent representative office or a resident acting on behalf of, at the expense of and on behalf of such non-resident;
the said resident or permanent representative office of a non-resident shall be responsible for the completeness and timeliness of the calculation and payment to the budget of taxes collected when paying a non-resident income from ownership of interest-bearing or interest-free (discount) securities. The central executive body that ensures the formation and implementation of state financial policy shall establish the procedure for residents or permanent representatives of a non-resident to submit calculations of non-resident tax liabilities and reports on the collection and payment to the relevant budget of taxes established by this paragraph.
{Paragraph four of subparagraph 141.4.3 of paragraph 141.4 of Article 141 as amended by Law No. 1797-VIII of 21.12.2016 }
Residents who work on behalf of, at the expense of and on behalf of a non-resident in the market of interest-bearing or interest-free (discount) bonds or treasury bills shall independently submit to the regulatory authority at their location a calculation (report) on the collection and payment to the relevant budget of the taxes established by this paragraph.
141.4.4. The amount of freight paid to a non-resident by a resident, including an individual entrepreneur, an individual engaged in independent professional activity, or a business entity (legal entity or individual entrepreneur) that has chosen a simplified taxation system, or another non-resident that conducts business through a permanent establishment under freight contracts, is taxed at a rate of 6 percent at the source of payment of such income at the expense of such income. In this case:
{Paragraph one of subparagraph 141.4.4 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of 16.01.2020 }
the basis for taxation is the basic rate of such freight;
The persons authorized to collect tax and pay it to the budget are the resident who pays such income, regardless of whether he is a taxpayer or a subject of simplified taxation.
141.4.5. Insurers or other residents, including individual entrepreneurs, individuals engaged in independent professional activities, or business entities (legal entities or individual entrepreneurs) who have chosen a simplified taxation system, another non-resident who conducts business through a permanent establishment, who make insurance payments (insurance contributions, insurance premiums) and insurance payments (insurance indemnities) within the framework of insurance or reinsurance contracts of risks, including life insurance for the benefit of non-residents, are obliged to tax the amounts transferred as follows:
{Paragraph one of subparagraph 141.4.5 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of January 16, 2020 }
within the framework of compulsory insurance contracts under which insurance payments (insurance indemnities) are made in favor of non-resident individuals, as well as under insurance contracts within the framework of the "Green Card" international agreement system, as well as under civil aviation passenger transportation insurance contracts - at a rate of 0 percent;
within the framework of insurance contracts for risks outside Ukraine, under which insurance payments (insurance indemnities) are made in favor of non-residents, except for the risks specified in the second paragraph of this subparagraph - at a rate of 4 percent of the amount transferred, at the insurer's own expense at the time of transfer of such amount;
{Paragraph three of subparagraph 141.4.5 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of January 16, 2020 }
when concluding insurance or reinsurance contracts directly with non-resident insurers and reinsurers who meet the requirements for reinsurance with non-resident insurers (reinsurers) established by the National Bank of Ukraine (including through or through insurance and/or reinsurance brokers), as well as when concluding reinsurance contracts for placing risks in foreign nuclear pools on behalf of members of the nuclear insurance pool - at a rate of 0 percent;
{Paragraph four of subparagraph 141.4.5 of paragraph 141.4 of Article 141 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2888-IX of 01/12/2023 }
in cases other than those specified in paragraphs two to four of this subparagraph - at a rate of 12 percent of the amount of such payments (disbursements) for one's own account at the time of transfer of such payments.
{Paragraph five of subparagraph 141.4.5 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 141.4.6 of clause 141.4 of Article 141 was excluded on the basis of Law No. 1525-IX of 03.06.2021 }
141.4.7. The amounts of income of non-residents who conduct their activities in the territory of Ukraine through a permanent establishment are taxed in the general manner. In this case, such a permanent establishment is equated for taxation purposes to a taxpayer who conducts his activities independently of such a non-resident.
A permanent establishment determines the amount of taxable profit received during the reporting (tax) period in accordance with the "arm's length" principle. The taxable profit of a permanent establishment must correspond to the profit of an independent enterprise carrying out the same or similar activities under the same or similar conditions and operating completely independently of the non-resident of which it is a permanent establishment.
{Paragraph two of subparagraph 141.4.7 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of 16.01.2020 }
The amount of taxable profit of a permanent establishment is calculated in accordance with the provisions of Article 39 of this Code.
{Paragraph three of subparagraph 141.4.7 of paragraph 141.4 of Article 141 as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 141.4.7 of clause 141.4 of Article 141 as amended by Law No. 2245-VIII of 07.12.2017 }
{Subparagraph 141.4.8 of paragraph 141.4 of Article 141 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
141.4.9. {Paragraph one of subparagraph 141.4.9 of paragraph 141.4 of Article 141 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
Amounts of tax on profits received from foreign sources paid by business entities abroad shall be credited when they pay tax in Ukraine. In this case, the amount of tax calculated according to the rules established by this section shall be subject to credit.
The amount of credited tax amounts from foreign sources during a tax (reporting) period cannot exceed the amount of tax payable in Ukraine by such taxpayer during such period.
The following taxes paid in other countries are not eligible for reduction of tax liabilities:
capital/property and capital gains tax;
postal taxes;
sales taxes;
other indirect taxes, regardless of whether they fall under the category of income taxes or are subject to other taxes under the laws of foreign countries.
The crediting of tax amounts paid across the customs border of Ukraine is carried out subject to the submission of written confirmation from the regulatory authority of another state regarding the fact of payment of such tax and the existence of a valid international treaty of Ukraine on the avoidance of double taxation of income.
{Paragraph ten of subparagraph 141.4.9 of paragraph 141.4 of Article 141 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
141.4.10. Income received by non-residents in the form of interest, or income (discount) or profit from the sale or other disposal of government securities or local loan bonds, or debt securities, the performance of obligations under which is secured by state or local guarantees (except for the profit of non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, from the sale or other disposal of government securities or local loan bonds, or debt securities, the performance of obligations under which is secured by state or local guarantees), or in the form of other income from government securities paid by the central executive body that ensures the formation of and implements state financial policy and/or implements state budget policy in the field of management of state debt and state-guaranteed debt, or in the form of interest paid to non-residents for loans (credits or external borrowings) received by the state or to the budget of the Autonomous Republic of Crimea or the city budget, which are reflected in the State Budget of Ukraine or local budgets or attributed to the expenses of the National Bank of Ukraine, or for credits (loans) received by business entities and the performance of which is secured by state or local guarantees.
{Clause 141.4 of Article 141 is supplemented by subparagraph 141.1.10 in accordance with Law No. 482-VIII of 22.05.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Laws No. 2146-VIII of 07.09.2017 , No. 466-IX of 16.01.2020 ; as amended by Law No. 1016-IX of 01.12.2020 }
141.4.11. Income of non-residents in the form of interest on loans or financial credits granted to residents is taxed at a rate of 5 percent at the source of payment of such income and at the expense of such income, while simultaneously complying with the following conditions:
a) funds provided by a non-resident under a loan or financial credit, attracted by him through the placement of foreign debt securities on a foreign stock exchange, included in the list approved by the Cabinet of Ministers of Ukraine;
b) funds provided by a non-resident under a loan or financial credit, attracted for the purpose of providing (directly or indirectly) a loan or financial credit to a resident;
c) the non-resident to whom interest is paid and/or the person authorized by him (if interest is paid through such person) are not residents of jurisdictions that, on the date of placement of foreign debt securities by the non-resident, are included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code.
{Clause 141.4 of Article 141 is supplemented by subparagraph 141.1.11 in accordance with Law No. 1797-VIII of 21.12.2016 }
141.4.12. Residents of Diya City - taxpayers under special conditions who make payments to non-residents of income specified in paragraphs four to six of subparagraph 14.1.49 of clause 14.1 of Article 14 of this Code shall not withhold tax from such income under the rules established by subparagraph 141.4.2 of this clause, if the amounts of such income are subject to taxation in accordance with subparagraph 141.9 - 1 .2.15 of subparagraph 141.9 - 1 .2 and subparagraph 141.9 - 1 .3 of clause 141.9 - 1 of this Article at the rate provided for in clause 136.1 of Article 136 of this Code.
{Clause 141.4 of Article 141 is supplemented by subparagraph 141.1.12 in accordance with Law No. 1946-IX of 14.12.2021 }
141.5. Peculiarities of taxation of activities in the field of organization and conduct of gambling
{Paragraph one of clause 141.5 of Article 141 as amended by Law No. 3325-IX of 10.08.2023 }
141.5.1. Entities engaged in the organization and conduct of gambling shall, in addition to paying income tax at the rate specified in Clause 136.1 of Article 136 of this Code, pay income tax at the rates specified in Subclauses 136.4.1 , 136.4.2 of Clause 136.4 of Article 136 of this Code.
{Paragraph one of subparagraph 141.5.1 of paragraph 141.5 of Article 141 as amended by Law No. 3325-IX of 10.08.2023 }
Income tax charged by an entity engaged in the organization and conduct of gambling at the rates specified in subparagraphs 136.4.1 , 136.4.2 of paragraph 136.4 of Article 136 of this Code is not a difference and does not reduce the financial result before taxation of such an entity.
{Paragraph two of subparagraph 141.5.1 of paragraph 141.5 of Article 141 as amended by Law No. 3325-IX of 10.08.2023 }
{Clause 141.5 of Article 141 as amended by Law No. 1797-VIII of 21.12.2016 }
141.6. Peculiarities of taxation of collective investment institutions and non-state pension entities
141.6.1. Collective investment funds are exempt from taxation, namely: funds contributed by the founders of a corporate fund, funds and other assets raised from participants in a collective investment institution, income from transactions with assets of a collective investment institution, income accrued on assets of a collective investment institution, and other income from the activities of a collective investment institution (interest on loans, rental (leasing) payments, royalties, etc.).
For the purposes of this subparagraph, the assets of a joint investment institution are understood to mean a set of property, corporate rights, real estate (including in the form of an indivisible object of unfinished construction/future real estate object and/or a divisible object of unfinished construction), property rights, claims and other assets provided for by laws and regulatory legal acts of the National Securities and Stock Market Commission, formed (paid for) at the expense of joint investment funds.
{Subparagraph 141.6.1 of paragraph 141.6 of Article 141 is supplemented by the second paragraph in accordance with Law No. 2600-IX of 20.09.2022 }
141.6.2. The amounts of funds in the form of contributions received by taxpayers who provide non-state pension provision in accordance with the law, from depositors of pension funds, depositors of pension deposit accounts and persons who have concluded insurance contracts in accordance with the Law of Ukraine "On Non-State Pension Provision", as well as persons who have concluded insurance contracts against the risk of disability or death of a participant in a non-state pension fund in accordance with the specified Law, are exempt from taxation.
{Clause 141.7 of Article 141 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
141.8. Peculiarities of taxation of entities that issue and conduct lotteries.
The income of entities that issue and conduct lotteries from operations on the issuance and conduct of lotteries is subject to taxation at the rate specified in Clause 136.6 of Article 136 of this Code.
The profit of entities issuing and conducting lotteries from other activities not related to issuing and conducting lotteries is calculated and paid according to the rules of this section at the basic (main) tax rate.
Income tax charged by entities issuing and conducting lotteries at the rate specified in Clause 136.6 of Article 136 of this Code is not a difference and does not reduce the financial result before taxation of such entity.
{Article 141 was supplemented by paragraph 141.8 in accordance with Law No. 1797-VIII of 21.12.2016 }
141.9. Features of determining the general minimum tax liability of taxpayers - owners, tenants, users on other terms (including emphyteusis terms) of land plots classified as agricultural land.
141.9.1. The taxpayer is obliged to submit an appendix with the calculation of the total minimum tax liability as part of the tax return for the tax (reporting) year.
Such an annex shall, in particular, specify:
cadastral numbers of land plots for which the minimum tax liability is determined, their normative monetary value and area;
the amount of the total minimum tax liability, the amount of the minimum tax liability for each land plot separately;
the total amount of taxes, fees, and payments paid by the taxpayer, the control over the collection of which is entrusted to the regulatory authorities, related to the production and sale of own agricultural products and/or to the ownership and/or use (lease, sublease, emphyteusis, permanent use) of land plots classified as agricultural land, and determined in accordance with subparagraph 141.9.2 or 141.9.3 of paragraph 141.9 of Article 141 of this Code, expenses for the lease of land plots (hereinafter in this paragraph - the total amount of taxes, fees, payments, and expenses for the lease of land plots) during the tax (reporting) year;
the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and land lease expenses paid.
141.9.2. For a taxpayer whose share of agricultural production for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code, is equal to or exceeds 75 percent, the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots shall be calculated by subtracting from the total minimum tax liability the total amount of taxes, fees, payments and expenses paid for the lease of land plots during the tax (reporting) year.
The amount of taxes, fees, payments and expenses paid for land leases includes:
corporate income tax;
personal income tax and military levy on the income of individuals who are in an employment or civil-law relationship with the taxpayer (except for income paid for the purchase of goods from individuals), on income under lease, sublease, and emphyteusis agreements for agricultural land plots;
single tax (in the event of a transition in the tax (reporting) year from a simplified taxation system to a general one);
land tax for land plots classified as agricultural land;
rental fee for special use of water;
20 percent of the costs of paying rent for land plots classified as agricultural land, the lessors of which are legal entities, and/or which are in state or municipal ownership.
The amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
141.9.3. For a taxpayer whose share of agricultural production for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code, is less than 75 percent, the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots shall be calculated by subtracting from the total minimum tax liability the total amount of taxes, fees, payments and expenses paid during the tax (reporting) year.
The amount of taxes, fees, payments and expenses paid for land leases includes:
corporate income tax in the amount proportional to the share of agricultural production of such payer for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
personal income tax and military levy on the income of individuals who are in an employment or civil-law relationship with the taxpayer (except for income paid for the purchase of goods from individuals), in an amount proportional to the share of agricultural production of such a taxpayer for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
personal income tax and military levy on income of individuals under lease, sublease, and emphyteusis agreements for land plots classified as agricultural land;
single tax of a single tax payer of the fourth group (in the event of a transition in the tax (reporting) year from a simplified taxation system to a general one);
single tax of a single tax payer of the third group (in the event of a transition in the tax (reporting) year from a simplified taxation system to a general one) in the amount proportional to the share of agricultural production of such payer for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
land tax for land plots classified as agricultural land;
rental fee for special use of water in an amount proportional to the share of agricultural production of such payer for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
20 percent of the costs of paying rent for land plots classified as agricultural land, the lessors of which are legal entities, and/or which are in state or municipal ownership.
The amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
141.9.4. In the case of using a land plot on the right of emphyteusis, the personal income tax and military duty paid when making payments under such an emphyteusis agreement are taken into account annually in a share calculated in proportion to the annual amount of accrued depreciation on an intangible asset in the form of the right to use the land plot under the emphyteusis agreement.
141.9.5. If the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is positive, the taxpayer is obliged to increase the amount of corporate income tax payable to the budget specified in the tax return by such positive value and pay such increased amount of tax to the budget in accordance with the procedure and terms specified by this Code for the payment of corporate income tax.
In the event that the taxpayer determines a negative value of the object of taxation in the tax (reporting) year, the positive value of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots shall be paid to the budget in accordance with the procedure and within the terms specified by this Code for the payment of corporate income tax.
The amount of corporate income tax in the positive part of such difference is not taken into account in the total amount of taxes, fees, payments and expenses paid for the lease of land plots in the next tax (reporting) year.
The positive value of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, charges, and land lease expenses paid is part of the corporate income tax liability.
{Article 141 is supplemented by paragraph 141.9 in accordance with Law No. 1914-IX of 30.11.2021 }
141.9 - 1. Features of taxation of residents of Diya City - taxpayers under special conditions
141.9 - 1 .1. A resident of Diya City - a taxpayer under special conditions shall pay corporate income tax at the rates determined in accordance with paragraphs 136.1 and 136.8 of Article 136 of this Code.
141.9 - 1 .2. The object of taxation of a resident of the City of Diya - a taxpayer under special conditions is transactions with:
141.9 - 1 .2.1. dividend payments to the owner of corporate rights (except for the owner of corporate rights who is a resident of Diya City - a tax payer under special conditions) in the amount determined according to the rules established by subparagraph 135.2.1.1 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.2. payments in cash and/or non-cash form for the return (payment, transfer) of contributions and/or other amounts to the owner of corporate rights (except for the owner of corporate rights who is a resident of Diya City - a tax payer on special conditions) in connection with the withdrawal of such owner from the composition of participants/shareholders of the legal entity - the issuer of such corporate rights, the liquidation of such legal entity - the issuer, the repurchase by a resident of Diya City - a tax payer on special conditions of its own shares (shares, units) in the amount determined by the rules established by subparagraph 135.2.1.2 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.2 - 1 . payments in cash and/or non-cash to a person who is not a resident of the City of Diya - a taxpayer under special conditions, in connection with the redemption or repurchase of securities of its own issue (except for shares specified in subparagraph 135.2.1.2 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code) in the amount determined according to the rules established by subparagraph 135.2.1.2 - 1 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.3. payments in cash and/or non-cash form for the return of contributions or an amount exceeding the amount of contributions to a person who is not a resident of Diya City - a taxpayer under special conditions and who provided property for joint activities, in the amount determined by the rules established by subparagraph 135.2.1.3 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.4. payments of interest (including those included in the amount of the principal debt (loan body), commissions, other remuneration, compensation, fines, penalties, which are associated with the attraction and/or use of funds for the benefit of persons who are not residents of Diia City - taxpayers under special conditions, in the amount and according to the rules established by subparagraphs 135.2.1.4 , 135.2.1.5 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code.
The provisions of this subparagraph shall not apply to:
a) rental (leasing) payments, except for interest and commissions under financial leasing agreements;
b) payments to repay the debt of a resident of Diya City - a taxpayer on special terms for property (works, services) received by him, including amounts recognized in accordance with national accounting regulations (standards) or international financial reporting standards as financial expenses, except for interest, commissions, other fees, reimbursements specified in the first paragraph of this subparagraph;
c) payments towards the repayment of the amount received for a loan, credit and/or other borrowing;
141.9 - 1 .2.5. transfer of property (provision of works, services) (transfer of risks associated with ownership, or transfer of results of works, services) to a person who is not a resident of the City of Diya - a taxpayer on special conditions, without making demands for compensation for its (their) value, including for the free transfer of property (works, services) in the amount determined according to the rules established by subparagraph 135.2.1.6 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.6. payment (provision) to a person who is not a resident of Diya City - a taxpayer under special conditions, of financial assistance in the amount determined according to the rules established by subparagraphs 135.2.1.7 , 135.2.1.8 , 135.2.1.8 - 1 subparagraph 135.2.1, paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.7. payments (transfers) made in cash and/or in a form other than cash in favor of a non-resident (except for cases of such transactions by a non-resident through its permanent establishment in Ukraine) in connection with:
a) repayment of debt obligations (including interest, commissions, other fees, compensations, fines, penalties) under credits (loans) that are not credited to accounts in Ukrainian banks or are not intended for payment for property located in the territory of Ukraine or imported into the customs territory of Ukraine;
b) repayment of obligations under recognized fines, penalties, forfeits, compensation for losses, compensation for unearned income (lost profits), accrued in accordance with the requirements of civil legislation and civil law contracts;
c) investing in investment objects (including the acquisition of property) located outside the territory of Ukraine;
d) purchase of works (services) in the amount determined according to the rules established by subparagraph 135.2.1.9 , subparagraph 135.2.1, paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.8. transfer of property (performance of work, provision of services) to a person who is not a resident of the City of Diya - a taxpayer under special conditions, under a contract providing for the payment of compensation for the cost of such property (work, services) in the amount determined according to the rules established by subparagraph 135.2.1.10 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.9. payments of funds and/or transfer of property (performance of work, provision of services) by a resident of the City of Diya - a taxpayer under special conditions, who carries out activities at the expense and on behalf of a non-resident, for the benefit of such non-resident (a person authorized by him) within the framework of the relevant commission agreement, mandate, agency agreement or similar agreements in the amount determined by the rules established by subparagraph 135.2.1.11 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.10. royalty payments to a person who is not a resident of the City of Diya - a taxpayer under special conditions, in the amount determined according to the rules established by subparagraphs 135.2.1.12 , 135.2.1.13 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.11. payments in cash and/or non-cash form in connection with a contribution to the authorized capital or to a joint activity, in trust management, if the recipient of such funds and/or property is a person who is not a resident of the City of Diya - a taxpayer under special conditions, in the amount determined according to the rules established by subparagraph 135.2.1.14 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.12. payments in cash and/or non-cash form in connection with the acquisition of property (works, services) from single tax payers in the amount determined according to the rules established by subparagraph 135.2.1.15 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.13. transfer of funds from accounts of a resident of the City of Diia - a taxpayer under special conditions in Ukrainian banks to accounts of such a taxpayer opened abroad, in the amount determined according to the rules established by subparagraph 135.2.1.16 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code;
141.9 - 1 .2.14. transfer (payment) of funds and/or transfer of property to a person who is not a resident of Diya City - a taxpayer under special conditions, in connection with the repayment of obligations under recognized fines, penalties, penalties, compensation for losses, compensation for unearned income (lost profit), accrued in accordance with the requirements of civil legislation and civil law contracts, in the amount determined according to the rules established by subparagraph 135.2.1.17 of subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code. The provisions of this subparagraph do not apply to transactions subject to taxation in accordance with subparagraph 141.9 - 1 .2.7 of this subparagraph;
141.9 - 1 .2.15. business transactions recognized as controlled in accordance with Article 39 of this Code, if their conditions do not comply with the "arm's length" principle, in the amount determined according to the rules established by subparagraph 141.9 - 1 .3 of this paragraph.
141.9 - 1 .2.16. transaction, if, based on the totality of the conditions of its implementation, the taxpayer has grounds to believe that the existing circumstances (facts) indicate the implementation of the transaction with the aim of providing an illegal benefit to an official (including an official of a foreign state).
The object of taxation by corporate income tax on such a transaction is taxed at the base (basic) rate determined by clause 136.1 of Article 136 of this Code.
For the purposes of applying this subparagraph, when considering the circumstances (facts) related to the relevant transaction that may indicate that it was carried out with the aim of providing an unlawful benefit to an official, the taxpayer shall take into account the actual actions of the parties to the transaction and the actual circumstances of the transaction in accordance with its essence, and for a transaction related to an official of a foreign state, he shall also be guided by the list published on the official website of the National Anti-Corruption Bureau of Ukraine in accordance with clause 12 of part one of Article 16 of the Law of Ukraine "On the National Anti-Corruption Bureau of Ukraine";
{Subclause 141.9 - 1 .2 of clause 141.9 - 1 of Article 141 is supplemented by subparagraph 141.9 - 1 .2.16 in accordance with Law No. 4112-IX of 04.12.2024 }
141.9 - 1 .2.17. transaction, if in accordance with the legislation it is established that such transaction was carried out on behalf of and/or in the interests of the taxpayer for the purpose of providing an unlawful benefit during the commission of a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, directly or indirectly (through third parties), regardless of the amount of the unlawful benefit.
The object of taxation by corporate income tax on such a transaction is taxed at the base (basic) rate determined by clause 136.1 of Article 136 of this Code.
{Subclause 141.9 - 1 .2 of clause 141.9 - 1 of Article 141 is supplemented by subparagraph 141.9 - 1 .2.17 in accordance with Law No. 4112-IX of 04.12.2024 }
141.9 - 1 .3. Procedure for determining the tax base when carrying out controlled transactions, the conditions of which do not comply with the "arm's length" principle
Regardless of the features defined by this paragraph, if a resident of the City of Diya - a taxpayer under special conditions carries out controlled transactions defined by Article 39 of this Code, the terms of which do not comply with the "arm's length" principle, the tax base for corporate income tax on such transactions, which is taxed at the rate determined in accordance with Clause 136.1 of Article 136 of this Code, is determined separately at the level of:
the excess of the price determined according to the "arm's length" principle over the contractual (contractual) value (the value at which the relevant transaction must be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of the sold property (works, services);
excess of the contractual value (the value at which the relevant transaction must be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of the purchased property (works, services) over the price determined according to the "arm's length" principle.
If the amount (part thereof) determined in accordance with paragraphs two to four of this subparagraph as the tax base for a separate controlled transaction:
a) was taxed with non-resident income tax in accordance with clause 141.4 of this article, the corresponding amount of accrued (paid) non-resident income tax shall be credited to reduce the amount of tax payable on such controlled transaction in accordance with subclause 141.9 - 1 .2.15 of subclause 141.9 - 1 .2 of this clause at the basic (basic) rate;
b) in previous tax (reporting) periods was included in the tax base determined in accordance with subparagraph 135.2.1 of subparagraph 135.2 of Article 135 of this Code, the amount of tax accrued (paid) in previous tax (reporting) periods on such amount (its part) at the rate determined in subparagraph 136.8 of Article 136 of this Code shall be included in the reduction of the amount of tax payable on such controlled transaction in accordance with subparagraph 141.9 - 1 .2.15 of subparagraph 141.9 - 1 .2 of this clause at the base (basic) rate.
The total amount by which the tax may be reduced in accordance with subparagraphs "a" and "b" of this subparagraph may not exceed the amount of such tax calculated at the basic (basic) rate from the tax base determined in accordance with paragraphs two to four of this subparagraph.
If the amount (part thereof) determined in accordance with paragraphs two to four of this subparagraph as the tax base for a controlled transaction, in subsequent reporting (tax) periods will be subject to inclusion in the tax base for transactions subject to taxation in accordance with subparagraph 141.9 - 1.2 (except for subparagraph 141.9 - 1.2.15 ) of this subparagraph at the rate determined in accordance with subparagraph 136.8 of Article 136 of this Code, such amount (part thereof) will be taken into account in reducing the tax base calculated in accordance with subparagraph 135.2.1 of paragraph 135.2 of Article 135 of this Code for such transactions.
141.9 - 1 .4. If a resident of the City of Diya - a taxpayer under special conditions is a controlling entity, a separate object of taxation of corporate income tax, which is taxed at the basic (basic) rate, is the adjusted profit of the controlled foreign company, determined in accordance with Article 39 - 2 of this Code.
{Article 141 is supplemented by paragraph 141.9 - 1 in accordance with Law No. 1946-IX of 14.12.2021 }
141.10. To transition to taxation as a resident of Diya City - a taxpayer under special conditions or to refuse such taxation, a legal entity submits a corresponding application to the regulatory authority at its tax address.
The form of the application, the procedure for its submission and consideration by the supervisory authority are established by the central executive authority that ensures the formation and implementation of state financial policy.
141.10.1. An application for transition to taxation as a resident of Diia City - a taxpayer under special conditions is submitted by electronic means in electronic form (including to the authorized body when applying for the status of a resident of Diia City in accordance with the procedure established by the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine") in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" .
141.10.2. Legal entities that have submitted an application for transition to taxation as a resident of Diya City - a taxpayer under special conditions to the authorized body when applying for the status of a resident of Diya City in accordance with subparagraph 141.10.1 of this paragraph are considered residents of Diya City - taxpayers under special conditions from the first day of the month following the quarter in which the legal entity was entered into the Diya City register.
A resident of Diya City who is a payer of corporate income tax on general grounds may decide to switch to taxation as a resident of Diya City - a payer of tax on special conditions by submitting a relevant application to the regulatory authority no later than 15 calendar days before the beginning of the next calendar quarter. Such a resident of Diya City is considered a payer of tax on special conditions from the first day of the month following the quarter in which the relevant application is submitted to the regulatory authority. A resident of Diya City who is a payer of corporate income tax on general grounds may switch to taxation as a resident of Diya City - a payer of tax on special conditions once during a calendar year.
141.10.3. A legal entity that is entered in the Diya City register but has not submitted an application for transition to taxation as a Diya City resident - a taxpayer under special conditions, is considered a Diya City resident - a taxpayer under general conditions.
141.10.4. To refuse taxation as a resident of Diya City - a taxpayer under special conditions, a resident of Diya City shall, no later than 10 calendar days before the beginning of the new calendar year, submit to the regulatory authority at his tax address by electronic means an application in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Article 141 is supplemented by paragraph 141.10 in accordance with Law No. 1946-IX of 14.12.2021 }
141.11. In the event that a resident of the City of Diya - a taxpayer under special conditions carries out a transaction that is subject to taxation simultaneously on two or more grounds provided for in subparagraphs 141.9 - 1 .2.1-141.9 - 1 .2.14 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of this article, taxation shall be carried out once according to the maximum tax base. If such a transaction is also subject to taxation in accordance with subparagraph 141.9 - 1 .2.15 of this article, the provisions of subparagraph 141.9 - 1 .3 of paragraph 141.9 - 1 of this article shall also apply .
{Article 141 is supplemented by paragraph 141.11 in accordance with Law No. 1946-IX of 14.12.2021 }
141.12. Peculiarities of taxation of transactions on the first sale under purchase and sale agreements of an indivisible residential property under construction/future residential property.
Payers of corporate income tax that carry out transactions on the first sale of an indivisible residential property under construction/future residential property, along with the norms established by this Code, have the right to determine the corporate income tax liability taking into account the features defined by this paragraph.
141.12.1. The financial result before taxation is reduced by the amount of income (revenue) that was taken into account by the construction customer, construction developer, in the financial result before taxation in the current tax (reporting) period for the transaction of the first sale (transfer to the buyer) of an indivisible residential property under construction/future residential property.
141.12.2. The financial result before tax is increased by the amount of expenses accrued in accounting that form the cost of an indivisible residential object under construction/future residential real estate object, which was taken into account by the construction customer, construction developer, in the financial result before tax for the transaction of the first sale (transfer to the buyer) of an indivisible residential object under construction/future residential real estate object.
141.12.3. The financial result before taxation is increased by the amount of income (revenue) from transactions from the first sale (transfer to the buyer) of an indivisible residential property under construction/future residential property, which in previous tax (reporting) periods reduced the financial result before taxation of the construction customer, construction developer, in the tax (reporting) period in which the relevant residential property completed by construction is put into operation.
141.12.4. The financial result before taxation is reduced by the amount of expenses accrued in accounting that form the cost of an indivisible residential property under construction/future residential property, which in previous tax (reporting) periods increased the financial result before taxation of the construction customer, construction developer, in the tax (reporting) period in which the relevant residential property completed by construction is put into operation.
{Article 141 is supplemented by paragraph 141.12 in accordance with Law No. 2600-IX of 20.09.2022 }
141.13. Features of taxation of activities related to trading in currency values in cash.
141.13.1. Taxpayers engaged in the trade of foreign currency in cash shall pay monthly, no later than the last operating (banking) day of the current month, an advance payment of corporate income tax for each foreign currency exchange point entered in the Register of Foreign Currency Exchange Points as of the first day of the current month, in the amount determined by subparagraph 141.13.2 of this paragraph.
For the purposes of taxation of activities related to the trade of foreign currency in cash, a foreign currency exchange point is understood as a structural/separate unit opened by a taxpayer who, in accordance with the Law of Ukraine "On Currency and Currency Transactions", has the right to trade in foreign currency in cash, for the purpose of trading foreign currency in cash.
141.13.2. Advance payment for corporate income tax shall be paid in the amount of:
a) equivalent to six hundred euros according to the official hryvnia exchange rate established by the National Bank of Ukraine on the first day of the first month of the calendar quarter in which the advance payment is made, for each foreign currency exchange point located in a settlement (except the city of Kyiv) with a population exceeding 50 thousand, according to statistical data on the current population of Ukraine posted on the website of the specially authorized central executive body in the field of statistics as of January 1 of the year preceding the current year;
b) equivalent to seven hundred euros according to the official hryvnia exchange rate established by the National Bank of Ukraine on the first day of the first month of the calendar quarter in which the advance payment is made, for each foreign currency exchange point located in the city of Kyiv;
c) equivalent to two hundred euros according to the official hryvnia exchange rate established by the National Bank of Ukraine on the first day of the first month of the calendar quarter in which the advance payment is made, for each foreign currency exchange point located in other settlements than those provided for in subparagraphs "a" and "b" of this subparagraph or outside settlements.
{Subclause 141.13.2 of clause 141.13 of Article 141 as amended by Law No. 4015-IX of 10.10.2024 }
141.13.3. Advance contributions from corporate income tax paid in accordance with this paragraph are an integral part of the income tax.
The amount of advance payments for corporate income tax paid during the reporting (tax) period reduces corporate income tax liabilities calculated based on the results of such reporting (tax) period at the base (basic) rate determined by Article 136 of this Code, in an amount not exceeding the amount of accrued tax liability for such tax (reporting) period.
{Paragraph two of subparagraph 141.13.3 of paragraph 141.13 of Article 141 as amended by Law No. 3474-IX of 21.11.2023 }
If the amount of the advance payment previously paid during the reporting (tax) year exceeds the amount of the accrued tax liability for such tax (reporting) year, the amount of such excess is not carried over to reduce tax liabilities in subsequent tax (reporting) periods.
The amount of paid advance income tax contributions is not subject to refund to the taxpayer as excessive and/or erroneously paid tax liabilities, cannot be credited against other taxes and fees (mandatory payments) and is not subject to the provisions of Article 43 of this Code.
141.13.4. A monetary obligation in the form of an advance payment of corporate income tax shall be deemed to have been agreed upon at the time of the occurrence of such obligation, which shall be determined by the calendar date established by subparagraph 141.13.1 of this paragraph for the deadline for payment of the advance payment of corporate income tax to the relevant budget.
If a taxpayer fails to pay the agreed amount of the advance payment for corporate income tax within the period specified in subparagraph 141.13.1 of this paragraph, such taxpayer shall be held liable in the form of a fine in the amounts specified in Article 124 of this Code.
141.13.5. The National Bank of Ukraine shall, by the 10th (inclusive) of the current month, submit to the central executive body implementing the state tax policy information on foreign currency exchange points entered in the Register of Foreign Currency Exchange Points as of the first day of the current month, indicating their location and the business entity on whose behalf the relevant foreign currency exchange point has the right to trade in foreign currency in cash. The information shall be submitted in accordance with the procedure determined by the National Bank of Ukraine in agreement with the central executive body implementing the state tax policy.
{Article 141 is supplemented by paragraph 141.13 in accordance with Law No. 2720-IX of 03.11.2022 }
141.14. Features of taxation of fuel retail trade activities
141.14.1. Taxpayers engaged in retail fuel trade shall pay a monthly advance payment of corporate income tax no later than the twentieth of the current month for each place of retail fuel trade, information about which is entered in the Unified Register of Licensees and Places of Fuel Circulation as of the first day of the current month, in the amount determined by subparagraph 141.14.2 of this paragraph.
The terms "retail fuel trade", "retail fuel trade location" are used in the meanings given in the Law of Ukraine "On State Regulation of the Production and Circulation of Ethyl Alcohol, Alcohol Distillates, Bioethanol, Alcoholic Beverages, Tobacco Products, Tobacco Raw Materials, Liquids Used in Electronic Cigarettes, and Fuel".
141.14.2. Advance payment of corporate income tax is paid for each place of retail sale of fuel, information about which is entered in the Unified Register of Licensees and Places of Fuel Circulation as of the first day of the current month:
a) in the amount of 60 thousand hryvnias for each place, except for the cases provided for in subparagraphs "b" and "c" of this subparagraph;
b) for a fuel retail outlet selling exclusively liquefied gas - in the amount of 30 thousand hryvnias for each location;
c) for a place of retail sale of fuel, where several types of fuel are sold and the share of sales of liquefied gas in liters brought to a temperature of 15 °C in the total volume of fuel sold during the previous month is 50 percent or more - in the amount of 45 thousand hryvnias for each place.
141.14.3. Advance contributions from corporate income tax paid in accordance with this paragraph are an integral part of the income tax.
The amount of advance payments for corporate income tax paid during the reporting (tax) period reduces corporate income tax liabilities calculated based on the results of such reporting (tax) period at the base (basic) rate determined by Article 136 of this Code, in an amount not exceeding the amount of accrued tax liability for such tax (reporting) period.
If the amount of the advance payment previously paid during the reporting (tax) year exceeds the amount of the accrued tax liability for such tax (reporting) year, the amount of such excess is not carried over to reduce tax liabilities in subsequent tax (reporting) periods.
The amount of paid advance income tax contributions is not subject to refund to the taxpayer as excessive and/or erroneously paid tax liabilities, cannot be credited against other taxes and fees (mandatory payments) and is not subject to the provisions of Article 43 of this Code.
141.14.4. A monetary obligation in the form of an advance payment of corporate income tax shall be deemed to have been agreed upon at the time of the occurrence of such obligation, which shall be determined by the calendar date established by subparagraph 141.14.1 of this paragraph for the deadline for payment of the advance payment of corporate income tax to the relevant budget.
If a taxpayer fails to pay the agreed amount of the advance payment for corporate income tax within the period specified in subparagraph 141.14.1 of this paragraph, such taxpayer shall be held liable in the form of a fine in the amounts specified in Article 124 of this Code.
141.14.5. For the purposes of this paragraph, liquefied gas shall be considered to be propane or a mixture of propane and butane, liquefied natural gas, other gases, according to the codes according to the UKT FEA 2711 11 00 00 , 2711 12 11 00, 2711 12 19 00, 2711 12 91 00, 2711 12 93 00, 2711 12 94 00, 2711 12 97 00, 2711 13 10 00, 2711 13 30 00, 2711 13 91 00, 2711 13 97 00, 2711 14 00 00, 2711 19 00 00 and/or are recorded in the electronic administration system for the sale of fuel and ethyl alcohol under the conditional code 2711 in liters, brought to a temperature of 15 °C.
{Article 141 is supplemented by paragraph 141.14 in accordance with Law No. 4015-IX of 10.10.2024 }
142.1. The profit of enterprises and organizations founded by public associations of persons with disabilities and fully owned by them, received from the sale (supply) of goods, performance of work and provision of services, except for excisable goods, services for the supply of excisable goods, received within the framework of commission (consignment) agreements, suretyship, mandate, trust management, other civil law agreements authorizing such a taxpayer to supply goods on behalf of and on behalf of another person without transferring ownership of such goods, where during the previous reporting (tax) period the number of persons with disabilities who have their main place of work there is not less than 50 percent of the average number of full-time employees of the accounting staff, provided that the payroll of such persons with disabilities is not less than 25 percent of the total labor costs during the reporting period.
The specified enterprises and organizations of public associations of persons with disabilities have the right to apply this benefit if they have a permit for the right to use such a benefit, which is issued by the authorized body in accordance with the Law of Ukraine "On the Fundamentals of Social Protection of Persons with Disabilities in Ukraine".
{Paragraph two of clause 142.1 of Article 142 as amended by Law No. 344-IX of 05.12.2019 }
In case of violation of the requirements for the targeted use of funds exempt from taxation, the taxpayer is obliged to increase tax liabilities for this tax based on the results of the tax period to which such violation applies, and also to pay a penalty accrued in accordance with this Code.
Enterprises and organizations subject to this clause shall be registered with the relevant regulatory authority in the manner prescribed for payers of this tax.
142.2. For the period of preparation for the decommissioning and decommissioning of the Chernobyl NPP power units and the transformation of the Shelter facility into an environmentally safe system, the profit of the Chernobyl NPP is exempt from taxation if such funds are used to finance the work on preparation for the decommissioning and decommissioning of the Chernobyl NPP and the transformation of the Shelter facility into an environmentally safe system.
In case of violation of the requirements for the targeted use of funds exempt from taxation, the taxpayer is obliged to increase tax liabilities for this tax based on the results of the tax (reporting) period to which such violation applies, and also to pay a penalty accrued in accordance with this Code.
{Paragraph two of clause 142.2 of Article 142 as amended by Law No. 466-IX of 16.01.2020 }
{Article 142 was supplemented by paragraph 142.2 in accordance with Law No. 364-VIII of 23.04.2015 }
142.3. The profit of enterprises received at the expense of international technical assistance or at the expense of funds provided for in the state budget as Ukraine's contribution to the Chernobyl Shelter Fund for the implementation of the international program - the Plan for the implementation of measures at the Shelter facility in accordance with the provisions of the Framework Agreement between Ukraine and the European Bank for Reconstruction and Development regarding the activities of the Chernobyl Shelter Fund in Ukraine , for further operation, preparation for decommissioning and decommissioning of the Chernobyl NPP power units, conversion of the Shelter facility into an environmentally safe system and ensuring social protection of the Chernobyl NPP personnel, is exempt from taxation.
In case of violation of the requirements for the targeted use of funds exempt from taxation, the taxpayer is obliged to increase tax liabilities for this tax based on the results of the tax (reporting) period to which such violation applies, and also to pay a penalty accrued in accordance with this Code.
{Paragraph two of clause 142.3 of Article 142 as amended by Law No. 466-IX of 16.01.2020 }
{Article 142 was supplemented by paragraph 142.3 in accordance with Law No. 364-VIII of 23.04.2015 }
142.4. The profit of a participant in an industrial park included in the Register of Industrial Parks from carrying out economic activities in the processing industry (section 10, class 11.07 of section 11, sections 13-17, 20-33 of the KVED 009:2010 , except for class 24.10 of section 24 of the KVED 009:2010 and except for the production of excisable goods, with the exception of the production of passenger cars, their bodies, trailers and semi-trailers, motorcycles, vehicles intended for the transportation of 10 or more people, vehicles for the transportation of goods) is exempt from taxation; in the field of waste collection, processing and disposal; recovery of materials (section 38 of the KVED 009:2010), except for waste disposal, or scientific and research activities (section 72 of the KVED 009:2010) exclusively on the territory (within) of the industrial park, for 10 consecutive years, starting from the first day of the first month of the calendar quarter specified by the taxpayer - participant of the industrial park in the application submitted by him to the regulatory authority at the place of registration of such taxpayer, drawn up in any form, on the exercise of the right to apply the exemption provided for in this paragraph, but not earlier than the date of submission of such application.
If the supervisory authority does not refuse to apply the exemption provided for in this paragraph within 10 working days from the date of receipt of the application, such application shall be deemed accepted. The application shall be submitted by the taxpayer in accordance with the procedure specified in paragraph 42.4 of Article 42 of this Code. The supervisory authority shall notify the taxpayer of the refusal to grant the exemption from taxation in accordance with the procedure specified in paragraph 42.4 of Article 42 of this Code.
The application of the taxation rules specified in this paragraph is permitted provided that the industrial park participant has the status of such a participant for at least 10 years and during these 10 years:
carries out economic activities exclusively on the territory and within the boundaries of the industrial park. To confirm the status of a participant in the industrial park, data from the Register of Industrial Parks is used;
does not accrue or pay dividends (payments equivalent to them) in favor of corporate rights holders.
Participants of the industrial park - legal entities, in the authorized capital of which there is a share that:
1) directly or indirectly owned by legal entities that are organizers of gambling, as well as legal entities that directly or indirectly own a share in the authorized capital of legal entities that are organizers of gambling;
2) directly or indirectly owned by legal entities registered in states (territories) classified by the Cabinet of Ministers of Ukraine as offshore zones;
3) directly or indirectly owned by legal entities registered in accordance with the legislation of states included by the Financial Action Task Force (FATF) in the list of states that do not cooperate in combating the laundering of proceeds of crime.
The amount of funds exempted from taxation (the amount of income tax not paid to the budget and remaining at the disposal of the taxpayer - participant of the industrial park) is directed to the development of the activities of the industrial park participant within such industrial park no later than December 31 of the following calendar year. The procedure for the use of funds exempted from taxation by the participant of the industrial park for the development of its activities within the industrial park is approved by the Cabinet of Ministers of Ukraine. The taxpayer shall indicate in the corporate income tax return for the tax (reporting) year information on the use or non-use of the amount of funds exempted from taxation in full.
In the event that a participant of an industrial park does not use the funds exempted from taxation for the development of its activities within the industrial park by December 31 of the calendar year following the tax (reporting) year, the taxpayer loses the right to apply the taxation rules specified in this paragraph from January 1 of the year following the year in which the specified funds were to be used. At the same time, for all other previous tax (reporting) periods of application of the tax exemption for which the taxpayer did not use the funds exempted from taxation within the established period and before the loss of such right, the taxpayer is obliged to submit a clarifying (clarifying) tax return on corporate income tax, calculate and pay the tax liability on corporate income tax, penalties and interest in accordance with the norms of this Code.
In the event of early termination of the application of the taxation rules specified in this paragraph at the initiative of the taxpayer, such taxpayer shall be obliged to determine the tax liability for corporate income tax in accordance with the general procedure based on the results of the tax (reporting) period in which he ceased to apply the specified taxation rules.
The central executive body implementing the state tax policy and the central executive body implementing the state policy on the creation and functioning of industrial parks in the territory of Ukraine shall automatically exchange information contained (to be contained) in the Register of Industrial Parks, including the list of participants in industrial parks, in the scope and manner determined by the central executive body ensuring the formation and implementation of the state financial policy, in agreement with the central executive body ensuring the formation and implementation of the state investment policy.
For taxpayers defined by this clause, tax (reporting) periods are calendar quarter, half-year, three quarters, year. In this case, the tax return is calculated on a cumulative basis. Taxpayers defined by this clause may not use exclusively annual tax (reporting) periods.
In the event of loss of the status of an industrial park participant, the taxpayer shall lose the right to apply the taxation rules established by this paragraph. Such taxpayer shall be obliged to determine the tax liability for corporate income tax in accordance with the general procedure based on the results of the tax (reporting) period in which the status of an industrial park participant was lost.
Regardless of the features defined by this paragraph, if a taxpayer - a participant in an industrial park carries out, within the framework of economic activity provided for in the first paragraph of this paragraph, controlled transactions defined by Article 39 of this Code, the object of taxation by corporate income tax, which is taxed at the basic (basic) rate, is determined separately at the level of:
the excess of the price determined according to the "arm's length" principle over the contractual (contract) value (the value at which the relevant transaction should be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of the goods (works, services) sold;
excess of the contractual value (the value at which the relevant transaction must be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of purchased goods (works, services) over the price determined according to the "arm's length" principle.
If the taxpayer - a participant in the industrial park is a controlling entity, a separate object of taxation of corporate income tax, which is taxed at the basic (basic) rate, is the adjusted profit of the controlled foreign company, determined in accordance with Article 39 - 2 of this Code.
The objects of taxation defined in paragraphs sixteen to nineteen of this clause are not exempt from taxation and are subject to taxation in the general manner.
{Article 142 is supplemented by paragraph 142.4 in accordance with Law No. 2330-IX of 06/21/2022 - for entry into force, see paragraph 1 of Section II of Law No. 2330-IX of 06/21/2022 }
{Chapter III as amended by Law No. 71-VIII of 28.12.2014 }
162.1.1. a resident individual who receives income from both sources of origin in Ukraine and foreign income;
162.1.1 - 1. a resident individual who owns and/or uses (rents (sublets), on emphyteusis terms, permanently uses) land plots classified as agricultural land, in terms of the minimum tax liability;
{Clause 162.1 of Article 162 is supplemented by subparagraph 162.1.1 - 1 in accordance with Law No. 1914-IX of 30.11.2021 }
162.1.2. a non-resident individual who receives income from a source of origin in Ukraine;
162.1.3. tax agent.
162.2. A non-resident who receives income from a source of origin in Ukraine and has diplomatic privileges and immunities established by a valid international treaty of Ukraine with respect to income that he receives directly from conducting diplomatic activities or activities equated to them by such an international treaty is not a taxpayer.
162.3. In the event of the death of a taxpayer or his declaration by a court as deceased or his recognition as missing or his loss of resident status (in the absence of tax obligations as a non-resident in accordance with this Code), the tax for the last tax period shall be levied on the income accrued in his favor. Accordingly, the last tax period shall be considered the period ending on the day on which the death of such taxpayer, the issuance of such a court decision or his loss of resident status, respectively, falls. In the absence of accrued income, the tax shall not be payable.
162.4. If an individual taxpayer receives taxable income for the first time within a tax period, the first tax period begins on the date of receipt of such income.
164.1. The tax base is the total taxable income, taking into account the features defined by this section.
Total taxable income - any taxable income accrued (paid, provided) to the taxpayer during the reporting tax period.
In the event of exercising the right to a tax deduction, the tax base is the net annual taxable income, which is determined by reducing the total taxable income, taking into account paragraph 164.6 of this article, by the amount of the tax deduction for such reporting year.
The tax base for income received from conducting business or independent professional activities is the net annual taxable income, which is determined in accordance with Clause 177.2 of Article 177 and Clause 178.3 of Article 178 of this Code.
{Clause 164.1 of Article 164 as amended by Law No. 3609-VI of 07.07.2011 }
164.1.1. Total taxable income consists of income that is finally taxed at the time of accrual (payment, provision), income that is taxed as part of the total annual taxable income, and income that is taxed under other rules specified in this Code.
164.1.2. Total monthly taxable income consists of the amount of taxable income accrued (paid, provided) during such reporting tax month.
164.1.3. Total annual taxable income is equal to the sum of total monthly taxable income, foreign income received during such reporting tax year, income received by an individual entrepreneur from conducting business activities in accordance with Article 177 of this Code, and income received by an individual engaged in independent professional activities in accordance with Article 178 of this Code.
164.2. The total monthly (annual) taxable income of a taxpayer includes:
164.2.1. income in the form of wages accrued (paid) to the taxpayer in accordance with the terms of an employment agreement (contract);
164.2.2. the amounts of remuneration and other payments accrued (paid) to the taxpayer in accordance with the terms of the civil law contract;
{Subclause 164.2.2 of Clause 164.2 of Article 164 and as amended by Laws No. 2497-VIII of 10.07.2018 , No. 466-IX of 16.01.2020 }
164.2.3. income from the sale of objects of property and non-property rights, in particular intellectual (industrial) property, and rights equated to them, income in the form of royalties, other payments for granting the right to use or dispose of an intangible asset (works of science, art, literature or other intangible assets) to other persons, objects of intellectual industrial property rights and rights equated to them (hereinafter - royalties), including those received by the heirs of the owner of such an intangible asset;
164.2.4. part of income from property transactions, the amount of which is determined in accordance with the provisions of Articles 172-173 of this Code;
164.2.5. income from leasing, renting or subleasing property (term ownership and/or use), determined in accordance with the procedure established by paragraph 170.1 of Article 170 of this Code;
164.2.6. taxable income (profit) not included in the calculation of total taxable income of previous tax periods and independently identified in the reporting period by the taxpayer or accrued by the controlling authority in accordance with this Code;
164.2.7. the amount of the taxpayer's debt under a civil law contract concluded by him, for which the statute of limitations has expired and which exceeds the amount constituting 50 percent of the monthly subsistence minimum valid for an able-bodied person as of January 1 of the reporting tax year, except for the amounts of tax debt for which the statute of limitations has expired in accordance with Section II of this Code, which establishes the procedure for collecting arrears of taxes, fees and repayment of tax debt. An individual independently pays tax on such income and indicates them in the annual tax return;
{Subclause 164.2.7 of Clause 164.2 of Article 164 as amended by Law No. 5519-VI of 06.12.2012 }
164.2.8. passive income (except for those specified in subparagraphs 165.1.2 and 165.1.41 of paragraph 165.1 of Article 165 of this Code), income in the form of winnings and prizes;
{Subclause 164.2.8 of Clause 164.2 of Article 164 as amended by Law No. 1166-VII of 03/27/2014 - regarding the entry into force of the amendments, see Clause 1 of Section IV of Law No. 1166-VII of 03/27/2014; Subclause 164.2.8 of Clause 164.2 of Article 164 as amended by Laws No. 1588-VII of 07/04/2014 , No. 71- VIII of 12/28/2014 ; as amended by Law No. 2628-VIII of 11/23/2018 }
164.2.9. investment income from transactions conducted by the taxpayer with securities, derivatives and corporate rights issued in forms other than securities, except for income from transactions specified in subparagraphs 165.1.40 and 165.1.52 of paragraph 165.1 of Article 165 of this Code;
{Subclause 164.2.9 of Clause 164.2 of Article 164 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 2628-VIII of 11/23/2018 }
164.2.10. income in the form of the value of inherited or gifted property within the limits taxable in accordance with this section;
164.2.11. the amount of excess funds/electronic money received by the taxpayer for business trips or for reporting purposes and not returned within the time limits established by law, the amount of which is calculated in accordance with paragraph 170.9 of Article 170 of this Code;
{Subclause 164.2.11 of Clause 164.2 of Article 164 as amended by Law No. 3813-IX of 18.06.2024 }
164.2.12. funds or property (intangible assets) received by the taxpayer as an unlawful benefit, stolen or found as treasure, not surrendered to the state in accordance with the law, in the amounts determined by the court's conviction, regardless of the punishment imposed by it;
{Subclause 164.2.12 of Clause 164.2 of Article 164 as amended by Law No. 4112-IX of 04.12.2024 }
164.2.13. income constituting a positive difference between:
the amount of funds received by the taxpayer as a result of his refusal to participate in the construction financing fund, and the amount of funds contributed by the taxpayer to such a fund, except for cases where the taxpayer simultaneously transfers the funds received from the construction financing fund to the management of the same manager in the same or another construction financing fund;
the amount of funds received by the taxpayer from other persons as a result of the assignment in their favor of the right of claim under the agreement on participation in the construction financing fund (including if such assignment is made on the basis of a purchase and sale agreement), and the amount of funds contributed by the taxpayer to such a fund under this agreement;
164.2.14. income in the form of penalties (fines, penalties), compensation for material or non-material (moral) damage, except for:
a) amounts that, by court decision, are directed to compensation for losses caused to the taxpayer as a result of causing him material damage, as well as damage to life and health, as well as compensation for moral damage in the amount determined by the court decision, but not higher than four times the minimum wage established by law as of January 1 of the reporting (tax) year, or in the amount determined by law;
{Subparagraph "a" of subparagraph 164.2.14 of paragraph 164.2 of Article 164 as amended by Law No. 466-IX of January 16, 2020 }
b) interest received from the debtor as a result of his delay in fulfilling a contractual obligation;
c) a penalty paid to the taxpayer at the expense of the budget (trust insurance fund) as a result of untimely return of excessively paid monetary obligations or other amounts of budget compensation;
d) the amount of losses caused to the taxpayer by acts recognized as unconstitutional, or by illegal decisions, actions or inaction of bodies carrying out operational and investigative activities, pre-trial investigation bodies, the prosecutor's office or the court, which are compensated by the state in accordance with the procedure established by law.
{Paragraph five of subparagraph 164.2.14 of paragraph 164.2 of Article 164 as amended by Law No. 4652-VI of 13.04.2012 }
e) payments from the state budget related to the implementation of decisions of foreign jurisdictional bodies, including the European Court of Human Rights, adopted as a result of the consideration of cases against Ukraine.
{Subparagraph 164.2.14 of paragraph 164.2 of Article 164 is supplemented with a new paragraph in accordance with Law No. 4834-VI of 24.05.2012 }
This subparagraph does not apply to the taxation of insurance payments, insurance indemnities and redemption amounts under insurance contracts;
164.2.15. the amount of insurance payments, insurance indemnities, redemption amounts or pension payments paid to the taxpayer under long-term life insurance contracts (including life pension insurance contracts) and non-state pension provision, under pension deposit contracts, trust management contracts concluded with participants in bank management funds, in the cases and amounts specified in subparagraph 170.8.2 of paragraph 170.8 of Article 170 of this Code;
164.2.16. the amount of pension contributions within the framework of non-state pension provision in accordance with the law, insurance payments (insurance contributions, insurance premiums), including under voluntary health insurance contracts and under a supplementary pension insurance contract, contributions to pension deposits, contributions to the bank management fund, paid by any resident person for or in favor of the taxpayer, except for amounts paid:
a) a resident person designated as the beneficiary under such agreements;
b) one of the first-degree family members of the taxpayer;
c) by a resident employer at his own expense under non-state pension insurance contracts of the taxpayer and/or under voluntary health insurance contracts within 30 percent of the accrued salary to such employee;
{Sub-clause "c" of sub-clause 164.2.16 of clause 164.2 of Article 164 as amended by Law No. 1791-VIII of 20.12.2016 ; as amended by Law No. 1946-IX of 14.12.2021 }
d) a resident of Diya City at his own expense under non-state pension insurance contracts and/or under voluntary health insurance contracts of a taxpayer - a gig specialist within 30 percent of the accrued remuneration to such a gig specialist;
{ Sub-clause 164.2.16 of clause 164.2 of Article 164 is supplemented by sub-clause "d" in accordance with the Law No. 1946-IX dated 14.12.2021 }
{Subclause 164.2.16 of Clause 164.2 of Article 164 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
164.2.17. income received by the taxpayer as an additional benefit (except for cases provided for in Article 165 of this Code) in the form of:
a) the cost of using housing, other tangible or intangible property belonging to the employer, provided to the taxpayer for free use, or compensation for the cost of such use, except for cases where such provision is conditioned by the taxpayer's performance of a labor function in accordance with an employment agreement (contract) or provided for by the norms of a collective agreement or in accordance with the law within the limits established by them;
{Subparagraph "a" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 as amended by Law No. 4834-VI of 24.05.2012 }
b) the value of property and food received free of charge by the taxpayer, except for cases specified by this Code for taxation of enterprise profits.
In addition to the exceptions provided for in subparagraph "a" of this subparagraph, income received in the form and amount subject to inclusion by the employer in the cost of goods sold, work performed, services provided, as well as funds, the cost of services, accommodation, travel, meals, sportswear, accessories, footwear and equipment, wheelchairs for persons with disabilities, including those intended for participation by persons with disabilities in physical education and rehabilitation and sports activities, medical and medical rehabilitation devices and other income provided (paid) to a taxpayer - a participant in sports (except for professional sports), physical education and health activities, activities for physical education and health activities and physical education and sports rehabilitation, financed from the budget and/or budget organizations, other non-profit organizations included in the Register of Non-profit Organizations and institutions on the date of provision of such funds.
{Paragraph two of subparagraph "b" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 as amended by Law No. 71-VIII of 28.12.2014 }
Also, the cost of goods and services paid by a cinematographic entity, namely travel, accommodation, meals, security, insurance, medical care, training, education, which are related to the participation of such a taxpayer in the production of audiovisual works produced (created) by cinematographic entities of Ukraine, if this is provided for by the terms of the contract with such taxpayers and/or the director's script of the audiovisual work, is not considered an additional benefit to the taxpayer.
{Subparagraph "b" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 is supplemented by the third paragraph in accordance with Law No. 2176-VIII of 07.11.2017 }
Also, the cost of goods and services paid by a cultural institution, namely travel, accommodation, meals, security, insurance, medical care, training, which are related to the participation of such a taxpayer in the creation and presentation (conducting) of cultural, including touring, events, is not considered an additional benefit of the taxpayer, if this is provided for in the terms of the contract with such taxpayers;
{Subparagraph "b" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 is supplemented by the fourth paragraph in accordance with Law No. 962-IX of 04.11.2020 }
c) the cost of services of domestic service personnel received free of charge by the taxpayer, including the work of subordinates, as well as persons in military service or who are arrested or imprisoned.
The term "domestic service personnel" means domestic service services provided to an individual, members of his or her family or on behalf of or on behalf of any third party, including the repair or construction of movable or immovable property owned or used by such individuals;
d) the amount of monetary or property compensation for any expenses or losses of the taxpayer, except for those that are necessarily reimbursed according to the law from the budget or are exempt from taxation according to this section;
e) the amount of non-refundable financial assistance (except for the amount of interest conditionally accrued on such assistance);
{Sub-paragraph "g" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 as amended by Law No. 3609-VI of 07.07.2011 }
e) the principal amount of the taxpayer's debt (loan) (except for the amount of the forgiven (cancelled) principal debt of the taxpayer under a mortgage loan in foreign currency secured by a mortgage on residential real estate), forgiven (cancelled) by the creditor by his independent decision, not related to the bankruptcy procedure, before the expiration of the limitation period, if its amount exceeds 25 percent of the amount of one minimum wage (per year) established as of January 1 of the reporting tax year, as well as the principal amount of the taxpayer's debt to the creditor - a financial institution upon execution by such creditor of a court decision on the discharge of the debtor - an individual from debts in an insolvency case, if its amount exceeds 25 percent of the amount of one minimum wage (per year) established as of January 1 of the reporting tax year. The creditor is obliged to notify the taxpayer - debtor by sending a registered letter with a return receipt or by concluding a relevant agreement, or by providing the debtor with a notice for signature in person about the forgiveness (cancellation) of the debt, the execution by the creditor - financial institution of the court decision on the release of the debtor - an individual from debts in an insolvency case. The creditor, including the creditor - financial institution, is obliged to include the amount of debt forgiven (cancelled) by its independent decision, not related to the bankruptcy procedure, the amount of debt in accordance with the court decision on the release of the debtor - an individual from debts in an insolvency case in the tax calculation of the amount of income accrued (paid) in favor of taxpayers, based on the results of the reporting period in which such debt was forgiven (cancelled), the court decision on the release of the debtor - an individual from debts in an insolvency case was executed. The debtor shall pay tax on such income independently and reflect it in the annual tax return. In the event of failure of the creditor to notify the debtor of the forgiveness (cancellation) of the debt, as well as failure of the creditor - financial institution to notify the execution of the court decision on the release of the debtor - individual from debts in the insolvency case in the manner specified in this subparagraph, such creditor shall be obliged to fulfill all the obligations of the tax agent in relation to the income specified in this subparagraph.
{Paragraph one of subparagraph "d" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 as amended by Laws No. 1383-IX of 04/13/2021 , No. 4698-IX of 12/03/2025 }
Under a loan received for the purchase of housing (mortgage loan), the taxpayer has the right to pay the amount of the tax liability accrued on the principal amount of the taxpayer's debt (loan) forgiven (cancelled) by the creditor by his independent decision, not related to the procedure of his bankruptcy, before the expiration of the limitation period, within three years starting from the year in which the amount of such tax liability was declared. To defer such amount of tax liability, the taxpayer, together with the declaration, submits to the regulatory authority an application in any form containing factual data on the amount of debt (loan and/or interest) forgiven (cancelled) by the creditor, confirmed by the relevant documents of the creditor, and a brief explanation of the circumstances that led to the need to defer the declared amount of tax liability.
{ Subparagraph "d" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
The amounts of deferred tax liabilities are calculated by the taxpayer independently according to the documents regarding the principal amount of the debt (loan) forgiven (cancelled) by the creditor and are repaid in equal installments of each calendar quarter by the 20th day of the month following each calendar quarter (by April 20, by July 20, by October 20 and by December 20) starting from the quarter following the quarter in which an application was submitted to the regulatory authority in an arbitrary form containing actual data on the principal amount of the debt (loan) forgiven (cancelled) by the creditor, confirmed by the relevant documents of the creditor, and a brief explanation of the circumstances that led to the need to defer the declared amount of the tax liability;
{ Subparagraph "d" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 is supplemented by the third paragraph in accordance with Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
{Sub-clause "d" of sub-clause 164.2.17 of clause 164.2 of Article 164 as amended by Laws No. 4834-VI of 24.05.2012 , No. 5519-VI of 06.12.2012 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1791-VIII of 20.12.2016 }
e) the value of goods (works, services) received free of charge, determined according to the rules of the usual price, as well as the amount of the discount on the usual price (value) of goods (works, services) individually assigned to such a taxpayer, except for the amounts specified in subparagraph 165.1.53 of paragraph 165.1 of Article 165 of this Code. The amount of the discount on the usual price (value) upon sale (alienation) in favor of the taxpayer of residential real estate acquired as a result of foreclosure on such property under mortgage agreements securing a loan granted in foreign currency is not an additional benefit.
{Subparagraph "e" of subparagraph 164.2.17 of paragraph 164.2 of Article 164 as amended by Laws No. 1275-VII of 05/20/2014 , No. 1383-IX of 04/13/2021 }
If additional benefits are provided in non-monetary form, the amount of tax on the taxable object is calculated according to the rules specified in paragraph 164.5 of this article;
164.2.18. income received by a taxpayer for scrap precious metals delivered (sold) by him, except for income received for scrap precious metals sold to the National Bank of Ukraine.
When paying income for scrap precious metals delivered (sold) by a taxpayer, the person purchasing it is considered a tax agent and is obliged to withhold tax from the amount of such payment at the rate established by this section;
{Clause 164.2 of Article 164 is supplemented by a new clause 164.2.18 in accordance with Law No. 4238-VI of 22.12.2011 ; as amended by Law No. 5083-VI of 05.07.2012 }
{Subparagraph 164.2.19 of paragraph 164.2 of Article 164 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
164.2.20. other income, except for those specified in Article 165 of this Code.
164.3. When determining the tax base, all income of the taxpayer, received by him in both monetary and non-monetary forms, shall be taken into account.
164.4. When accruing (receiving) income received in the form of currency values or other assets (the value of which is expressed in foreign currency or international units of account), such income is converted into hryvnia at the exchange rate of the National Bank of Ukraine in effect at the time of accruing (receiving) such income.
164.5. When calculating (providing) income in any non-monetary form, the tax base is the value of such income, calculated at ordinary prices, the rules for determining which are established in accordance with this Code, multiplied by a coefficient calculated according to the following formula:
K = 100 : (100 - Sp),
where K is the coefficient;
Sp - the tax rate established for such income at the time of its accrual.
The same procedure determines the object of taxation and the tax base for funds excessively spent by the taxpayer on business trips or for reporting and not returned within the time limits established by law.
164.6. When calculating income in the form of wages, the tax base is determined as the accrued wages, reduced by the amount of insurance contributions to the Accumulation Fund, and in cases provided for by law - mandatory insurance contributions to a non-state pension fund, which, in accordance with the law, are paid at the expense of the employee's wages, as well as by the amount of tax social benefits, if any.
{Paragraph one of clause 164.6 of Article 164 as amended by Law No. 466-IX of January 16, 2020 }
{Paragraph two of clause 164.6 of Article 164 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
Article 165. Income not included in the calculation of total monthly (annual) taxable income↑
165.1. The following income is not included in the total monthly (annual) taxable income of a taxpayer:
165.1.1 the amount of state and social material assistance, state assistance, compensations, the cost of social services and rehabilitation assistance (including monetary compensation for persons with disabilities, for children with disabilities when implementing individual rehabilitation programs for persons with disabilities, the amount of assistance for pregnancy and childbirth), remuneration and insurance payments received by the taxpayer from the budgets and funds of mandatory state social insurance and in the form of financial assistance to persons with disabilities from the Fund for Social Protection of Persons with Disabilities in accordance with the law, decrees of the President of Ukraine and acts of the Cabinet of Ministers of Ukraine, as well as the cost of social assistance in kind to low-income families received from providers of social services in accordance with the Law of Ukraine "On Social Services", including (but not limited to):
{Paragraph one of subparagraph 165.1.1 of paragraph 165.1 of Article 165 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 344-IX of 05.12.2019 ; as amended by Law No. 786-IX of 14.07.2020 ; as amended by Law No. 1914-IX of 11.30.2021 ; as amended by Law No. 2600-IX of 20.09.2022 }
a) the amount of monetary assistance provided in accordance with the law, decrees of the President of Ukraine and acts of the Cabinet of Ministers of Ukraine to family members of military personnel, police officers or command and rank-and-file personnel of internal affairs bodies, civil defense bodies and units, the State Penitentiary Service of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, who died (went missing) or died while performing their official duties and/or protecting the independence, sovereignty and territorial integrity of Ukraine;
{Sub-clause "a" of sub-clause 165.1.1 of clause 165.1 of Article 165 as amended by the Laws No. 1293-IX dated 02.03.2021 , No. 2600-IX dated 20.09.2022 }
b) the amount of state awards of Ukraine or scholarships of Ukraine, assigned by law, resolutions of the Verkhovna Rada of Ukraine, decrees of the President of Ukraine, awards to athletes - champions of Ukraine, prize-winners of international sports competitions, including athletes with disabilities, as well as the value of state awards or awards on behalf of Ukraine, except for those paid in cash or other property, the amount of the Nobel or Abel Prizes, as well as the amount of international awards in the field of scientific, scientific and technical activities, scholarships, grants paid (provided) within the framework of financing scientific (scientific and technical) projects, the implementation of which is carried out in accordance with international treaties of Ukraine, the consent to the binding nature of which has been provided by the Verkhovna Rada of Ukraine, and which are registered in accordance with Article 66 of the Law of Ukraine "On Scientific and Scientific and Technical Activities";
{Subparagraph "b" of subparagraph 165.1.1 of paragraph 165.1 of Article 165 as amended by Laws No. 344-IX of 05.12.2019 , No. 2836-XI of 13.12.2022 }
c) the amount of funds from the State Budget of Ukraine to full members (academicians) and corresponding members of the National Academy of Sciences of Ukraine, the Ukrainian Academy of Agrarian Sciences, the Academy of Medical Sciences of Ukraine, the Academy of Pedagogical Sciences of Ukraine, the Academy of Legal Sciences of Ukraine and the Academy of Arts of Ukraine as a monthly lifetime payment for the title of full member and corresponding member;
d) the amount of assistance paid (provided) to victims of Nazi persecution or their heirs from budgets or other sources specified by international treaties of Ukraine, the binding nature of which has been approved by the Verkhovna Rada of Ukraine, as well as to persons holding the title of "Righteous Among the Nations";
e) the amount of assistance paid (provided) to persons recognized as repressed and/or rehabilitated in accordance with the law, or to their heirs from budgets or other sources specified in international treaties of Ukraine, the binding nature of which has been approved by the Verkhovna Rada of Ukraine;
e) the amount of pensions (including the amount of their indexation, accrued in accordance with the law) or monthly lifetime cash support received by the taxpayer from the Pension Fund of Ukraine or the budget in accordance with the law, as well as pensions from foreign sources, if, according to international treaties, the binding consent of which has been granted by the Verkhovna Rada of Ukraine, such pensions are not subject to taxation or are taxable in the country of their payment;
{Subparagraph "e" of subparagraph 165.1.1 of paragraph 165.1 of Article 165 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 1166-VII of 03/27/2014 - for the entry into force of the amendments, see paragraph 1 of Section IV of Law No. 1166-VII of 03/27/2014; as amended by Law No. 466-IX of 01/16/2020 }
h) the amount of monetary compensation for time spent, the amount of which is established by the Cabinet of Ministers of Ukraine, received by individuals for keeping records and submitting information in accordance with the programs of state sample surveys conducted by state statistics bodies;
g) the amount of monetary compensation paid to military personnel for the housing they are entitled to receive;
h) the amount of annual one-time cash assistance provided in accordance with the Law of Ukraine "On the Status of War Veterans, Guarantees of Their Social Protection" ;
i) the amount of monetary assistance (including in kind) provided to individuals or members of their families (children, spouse, parents), military personnel called up for military service by conscription in connection with mobilization, in accordance with the Law of Ukraine "On Social and Legal Protection of Military Personnel and Members of Their Families" , and/or compensation payments from the budget within the average earnings of employees called up for military service by conscription during mobilization, for a special period;
{Subparagraph 165.1.1 of paragraph 165.1 of Article 165 is supplemented with a new paragraph in accordance with Law No. 1275-VII of 20.05.2014 }
i) the cost of social services provided in accordance with the Law of Ukraine "On Social Services" and the Classifier of Social Services by a social service provider included in the Register of Providers and Recipients of Social Services, at the expense of social service providers to a recipient of social services included in the Register of Providers and Recipients of Social Services.
{ Sub-clause 165.1.1 of clause 165.1 of Article 165 is supplemented by sub-clause "i" in accordance with the Law No. 1914-IX dated 30.11.2021 }
The exceptions provided for in this subparagraph do not apply to the payment of wages, cash (severance) benefits upon retirement (resignation) and payments related to temporary loss of working capacity;
165.1.2. the amount of income received by the taxpayer in the form of interest accrued on government securities issued by the central executive body that ensures the formation and implementation of state financial policy and/or implements state budget policy in the field of management of state debt and state-guaranteed debt, and on debt obligations of the National Bank of Ukraine, as well as the amount of income received by non-residents in the form of interest accrued on government securities or local loan bonds, or debt securities, the performance of obligations for which is secured by state or local guarantees, if such securities are purchased by non-residents outside the territory of Ukraine through authorized non-resident agents, or interest received by non-residents for loans (credits or external borrowings) provided to the state or the budget of the Autonomous Republic of Crimea or the city budget, which are reflected in the State Budget of Ukraine or local budgets or attributed to the expenses of the National Bank of Ukraine, or for credits (loans) provided to business entities, the performance of which is secured by state or local guarantees;
{Subclause 165.1.2 of Clause 165.1 of Article 165 as amended by Laws No. 4238-VI of 12/22/2011 , No. 5083-VI of 07/05/2012 , No. 482-VIII of 05/22/2015 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 , No. 1016-IX of 12/01/2020 }
165.1.3. the amount of compensation to the taxpayer for the amount of damage caused to him as a result of the Chernobyl disaster, in the manner and amounts determined by law;
165.1.4. the amount of payments or compensations (except for wages or other payments and compensations under civil law contracts) made taking into account paragraph 170.7 of Article 170 of this Code:
a) by creative unions to their members in cases provided for by law;
b) by the Ukrainian Red Cross Society for the benefit of recipients of charitable assistance in accordance with the law;
c) other non-profit organizations (except credit unions and other non-bank financial institutions) and charitable foundations of Ukraine, the status of which is determined in accordance with the law, for the benefit of the recipients of such payments, except for any payments or reimbursements to members of the governing bodies of such organizations or foundations and individuals related to them;
d) the amount paid annually to the winners of the Petro Jacyk International Ukrainian Language Competition;
165.1.5. the amount of contributions to the taxpayer's compulsory insurance in accordance with the law, other than a single contribution to the mandatory state social insurance;
165.1.6. the amount of the single contribution to the taxpayer's mandatory state social insurance, paid at the expense of his employer in the amounts determined by law;
165.1.7. the amount of insurance contributions to the Accumulation Fund, and in cases provided for by law - mandatory insurance contributions to the non-state pension fund and the banking management fund;
165.1.8. the amount of funds belonging to the taxpayer, which, in accordance with the law, are transferred from the Accumulation Fund to a non-state pension fund, a bank management fund or an insurance organization, from a non-state pension fund, a bank management fund to another non-state pension fund, a bank management fund, an insurance organization or to a pension deposit account in a bank;
165.1.9. the cost of free medical and preventive nutrition, milk or equivalent food products, carbonated salt water, detergents and disinfectants, as well as special clothing, special footwear and other personal protective equipment provided by the employer to the taxpayer in accordance with the Law of Ukraine "On Occupational Safety" , special (uniform) clothing and footwear provided by the employer for temporary use to the taxpayer who is in an employment relationship with him. The procedure for providing, the list and the deadlines for using special (including uniform) clothing, special footwear and other personal protective equipment are established by the Cabinet of Ministers of Ukraine and/or industry standards for the free provision of special (uniform) clothing, special footwear and other personal protective equipment to employees.
Standards for providing medical and preventive nutrition, milk or equivalent food products, carbonated salt water, detergents and disinfectants are developed by the central executive body that ensures the formation of state policy in the field of health care;
{Subclause 165.1.9 of Clause 165.1 of Article 165 as amended by Law No. 4834-VI of 24.05.2012 }
165.1.10. the amount of monetary or property maintenance or support for military personnel in conscription (including persons undergoing alternative service), provided for by law, which is paid from the budget or a budgetary institution;
165.1.11. funds received by the taxpayer for business trips or for reporting purposes and calculated in accordance with paragraph 170.9 of Article 170 of this Code, as well as the amounts of compensation payments in foreign currency paid in accordance with the law to diplomatic service employees sent on long-term business trips;
{Subclause 165.1.11 of Clause 165.1 of Article 165 as amended by Law No. 4834-VI of 24.05.2012 }
165.1.12. the cost of goods received by the taxpayer as a warranty replacement in accordance with the procedure established by law, as well as monetary compensation for the cost of goods provided to the taxpayer in the event of their return to the seller or a person authorized by such seller to provide warranty service (replacement) during the warranty period, but not higher than the purchase price of such goods;
165.1.13. funds or the value of property (intangible assets) that are received by the taxpayer by court decision as a result of the division of the spouses' joint property in connection with the dissolution of the marriage or its recognition as invalid or by voluntary decision of the parties, taking into account the norms of the Family Code of Ukraine ;
165.1.14. alimony paid to the taxpayer in accordance with a court decision or by voluntary decision of the parties in the amounts determined in accordance with the Family Code of Ukraine, including alimony paid by a non-resident;
{Subclause 165.1.14 of Clause 165.1 of Article 165 as amended by Law No. 2477-VIII of 03.07.2018 }
165.1.15. funds or property (property or non-property rights, cost of works, services) received by taxpayers as a gift, taking into account the provisions of this section;
165.1.16. funds received by the taxpayer as compensation (reimbursement) for the value of property (intangible assets) forcibly alienated by the state in cases provided for by law, or the value of such compensation received in non-monetary form;
income received from the sale of pledged property, property of the taxpayer when a financial institution levies a foreclosure on such property due to the taxpayer's failure to fulfill his obligations under a credit (loan) agreement, provided that such property was purchased at the expense of such credit (loan);
{Subclause 165.1.16 of clause 165.1 of Article 165 as amended by Law No. 5519-VI of 06.12.2012 ; as amended by Law No. 321-VIII of 09.04.2015 }
165.1.17. the amount of overpaid monetary obligations, insurance contributions from budgets or state special-purpose insurance funds in accordance with the law, as well as budget compensation when exercising the right to a tax discount, which is returned to the taxpayer;
165.1.18. dividends accrued to the taxpayer in the form of shares (units, shares) issued by a resident legal entity accruing such dividends, provided that such accrual in no way changes the proportions (shares) of participation of all shareholders (owners) in the authorized capital of the issuer, and as a result of which the authorized capital of the issuer increases by the total nominal value of the accrued dividends;
{Subclause 165.1.18 of clause 165.1 of Article 165 as amended by Law No. 3553-IX of 16.01.2024 }
165.1.19. funds or the value of property (services) provided as assistance for the treatment and medical care of a taxpayer or a family member of an individual in the first degree of kinship, a child who is under the guardianship or care of the taxpayer, subject to documentary confirmation of the expenses related to the provision of the specified assistance (in the case of the provision of funds), including, but not exclusively, for the purchase of medicines, donor components, prosthetic and orthopedic products, medical products for individual use by persons with disabilities, at the expense of a charitable organization or its employer, including in part the employer's expenses for a mandatory preventive examination of an employee in accordance with the Law of Ukraine "On Protection of the Population from Infectious Diseases" and for vaccination of an employee aimed at preventing diseases during the period of the threat of epidemics in accordance with the Law of Ukraine "On Ensuring the Sanitary and Epidemic Well-being of the Population" in the presence of relevant supporting documents, except for expenses compensated by payments from the Compulsory State Social Medical Insurance Fund;
{Subclause 165.1.19 of Clause 165.1 of Article 165 as amended by Laws No. 1668-VII of 02.09.2014 , No. 1797-VIII of 21.12.2016 }
165.1.20. the cost of coal and coal or peat briquettes provided free of charge in the amounts and according to the list of professions established by the Cabinet of Ministers of Ukraine, including compensation for the cost of such coal and coal or peat briquettes:
{Paragraph one of subparagraph 165.1.20 of paragraph 165.1 of Article 165 as amended by Law No. 427-VII of 03.09.2013 }
workers in coal mining (processing) and coal-mining enterprises;
pensioners who have worked at coal mining (processing) enterprises, coal-mining enterprises: in underground work - not less than 10 years for men and not less than 7 years 6 months for women; in work related to underground conditions - not less than 15 years for men and not less than 12 years 6 months for women; in work on the technological line on the surface of operating mines or mines under construction, cuttings, enrichment and briquette factories - not less than 20 years for men and not less than 15 years for women;
persons with disabilities and war and labor veterans, persons awarded the "Miner's Glory" or "Miner's Valor" badges of I, II, III degrees, persons whose disability occurred as a result of a general illness, if they exercised this right before the onset of disability;
to the families of workers who died (died) at coal mining (processing) enterprises, who receive pensions in connection with the loss of a breadwinner, as well as to the widows of deceased pensioners specified in this subparagraph, who had such a right during their lifetime.
{Paragraph five of subparagraph 165.1.20 of paragraph 165.1 of Article 165 as amended by Law No. 5019-VI of 21.06.2012 }
When paying monetary compensation for the cost of such coal and coal or peat briquettes, its amount is not included in the total taxable income of the taxpayer.
{Paragraph six of subparagraph 165.1.20 of paragraph 165.1 of Article 165 as amended by Law No. 427-VII of 03.09.2013 }
The procedure for implementing this subparagraph shall be determined by the Cabinet of Ministers of Ukraine;
165.1.21. the amount paid by any legal entity or individual to domestic higher and vocational educational institutions for the education, training or retraining of the taxpayer, but not exceeding three times the minimum wage established by law as of January 1 of the reporting (tax) year for each full or incomplete month of education, training or retraining of such individual;
{Subclause 165.1.21 of clause 165.1 of Article 165 as amended by Law No. 1797-VIII of 21.12.2016 }
165.1.22. funds or value of property (services) provided as assistance for the burial of a taxpayer:
a) any individual, charitable organization, Pension Fund of Ukraine, relevant structural unit of local state administration, mandatory state social insurance funds of Ukraine or professional union;
{Subparagraph "a" of subparagraph 165.1.22 of paragraph 165.1 of Article 165 as amended by Law No. 5083-VI of 05.07.2012 }
b) by the employer of such deceased taxpayer at his last place of work (including before retirement) in an amount not exceeding double the amount specified in paragraph one of subparagraph 169.4.1 of clause 169.4 of Article 169 of this Code. The amount of the excess, if any, is finally taxed at the time of its accrual (payment, provision);
165.1.23. the value of property, as well as the amount of financial assistance provided to orphans or children deprived of parental care (including graduates of vocational and technical educational institutions and higher educational institutions of I-IV levels of accreditation), in the manner and amounts determined by the Cabinet of Ministers of Ukraine;
{Subclause 165.1.23 of Clause 165.1 of Article 165 as amended by Law No. 3609-VI of 07.07.2011 }
165.1.24. income received from the sale of own agricultural products grown, fattened, caught, collected, manufactured, produced, processed and/or processed directly by an individual on land plots, for the purpose of maintaining:
{Paragraph one of subparagraph 165.1.24 of paragraph 165.1 of Article 165 as amended by Law No. 1914-IX of 30.11.2021 }
gardening and/or for the construction and maintenance of a residential building, outbuildings and structures (homestead plots) and/or for individual summer cottage construction;
{Paragraph two of subparagraph 165.1.24 of paragraph 165.1 of Article 165 as amended by Law No. 1914-IX of 30.11.2021 }
personal farm and/or land shares (shares) allocated in kind (on the ground).
{Paragraph three of subparagraph 165.1.24 of paragraph 165.1 of Article 165 as amended by Law No. 1914-IX of 30.11.2021 }
When selling one's own agricultural products (except livestock products), the income received from such sale is not taxable income if their total amount for the year does not exceed 12 minimum wages established by law as of January 1 of the reporting (tax) year. If the amount of income received exceeds the specified amount, the taxpayer is obliged to reflect the amount of such excess as part of the total monthly (annual) taxable income for the relevant reporting year and submit an annual declaration of property status and income (tax declaration) in accordance with this Code and independently pay tax on the amount of such excess.
{Paragraph four of subparagraph 165.1.24 of paragraph 165.1 of Article 165 as amended by Law No. 1914-IX of 30.11.2021 }
When selling agricultural products (except livestock products), its owner must submit to the tax agent a copy of the certificate of possession of the land plots specified in paragraphs two and three of this subparagraph. The original certificate is kept by the owner of agricultural products during the limitation period from the date of expiration of such certificate. The certificate is issued by the village, settlement, city council at the location of the taxpayer's tax address (place of residence) within five working days from the date of receipt by the relevant council of a written application for the issuance of such a certificate.
{Paragraph five of subparagraph 165.1.24 of paragraph 165.1 of Article 165 as amended by Law No. 1797-VIII of 21.12.2016 }
The form of the certificate shall be established in accordance with the procedure specified in Article 46 of this Code for tax returns.
When selling their own livestock products of groups 1-5, 15, 16 and 41 of the UKT FEA , the income received from such sales is not taxable income if their total amount for the year does not exceed 50 times the minimum wage established by law as of January 1 of the reporting (tax) year. Such individuals sell the specified products without obtaining a certificate of the availability of land plots.
{Paragraph seven of subparagraph 165.1.24 of paragraph 165.1 of Article 165 as amended by Law No. 1791-VIII of 20.12.2016 }
In the event that the amount of income received exceeds the amount established by this subparagraph, the individual is obliged to provide the regulatory body with a certificate of independent cultivation, breeding, fattening of livestock products, which is issued in any form by the village, settlement, city council at the place of tax address (place of residence) of the owner of the livestock products. If the certificate confirms the cultivation of the sold livestock products directly by the taxpayer, income exceeding 50 times the minimum wage established by law as of January 1 of the reporting (tax) year is subject to taxation.
{Paragraph eight of subparagraph 165.1.24 of paragraph 165.1 of Article 165 as amended by Laws No. 1791-VIII of 20.12.2016 , No. 1797-VIII of 21.12.2016 }
If such a taxpayer has not confirmed the independent cultivation, breeding, or fattening of livestock products, the income from the sale of which he received, such income is subject to taxation on a general basis;
{Subclause 165.1.24 of clause 165.1 of Article 165 as amended by Law No. 5412-VI of 02.10.2012 }
165.1.25. the amount of income received by the taxpayer for the secondary raw materials, household waste, scrap of ferrous metals (commodity position 7204 according to the UKT FEA ), scrap of non-ferrous metals, including used (exhausted) electric lead-acid batteries (code 8549 11 10 00 according to the UKT FEA ), residues and scrap of electric batteries containing lead (codes 8549 11 90 00, 8549 12 90 00 according to the UKT FEA), and scrap of precious metals sold to the National Bank of Ukraine;
{Subclause 165.1.25 of Clause 165.1 of Article 165 as amended by Laws No. 4238-VI of 12/22/2011 , No. 5083-VI of 07/05/2012 ; as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 3553-IX of 01/16/2024 }
165.1.26. the amount of the scholarship (including the amount of its indexation, accrued in accordance with the law), which is paid to a pupil, student, cadet of military educational institutions, resident, postgraduate or adjunct, but not higher than the amount specified in the first paragraph of subparagraph 169.4.1 of paragraph 169.4 of Article 169 of this Code. The amount of the excess, if any, is subject to taxation at the time of its accrual (payment) at the rate specified in paragraph 167.1 of Article 167 of this Code;
{Subclause 165.1.26 of Clause 165.1 of Article 165 as amended by Laws No. 3609-VI of 07.07.2011 , No. 909-VIII of 12.24.2015 , No. 2628-VIII of 11.23.2018 }
165.1.27. the amount of insurance payment, insurance indemnity or redemption amount received by the taxpayer under an insurance contract from a resident insurer or non-resident insurer, other than long-term life insurance (including life pension insurance) and non-state pension provision, and the amount of insurance (regular) payments, insurance indemnities made by the Motor (Transport) Insurance Bureau of Ukraine in accordance with the Law of Ukraine "On Compulsory Civil Liability Insurance of Owners of Land Vehicles", if the following conditions are met:
{Paragraph one of subparagraph 165.1.27 of paragraph 165.1 of Article 165 as amended by Law No. 466-IX of January 16, 2020 }
a) during life or health insurance of the taxpayer in the event of:
the insured person's survival to the date or event stipulated in the life insurance contract, or reaching the age stipulated in such contract;
the redemption amount in the part that does not exceed the amount of insurance premiums paid under a life insurance contract other than long-term life insurance;
in the event of an insured event - the fact of causing damage to the insured person must be duly confirmed. If the insured person dies, the amount of the insurance payment belonging to the beneficiaries or heirs is taxed according to the rules and rates established for inheritance taxation (the beneficiary is equated with the heir);
b) during property insurance, the amount of insurance compensation cannot exceed the value of the insured property, determined at normal prices on the date of conclusion of the insurance contract, increased by the amount of insurance payments paid (insurance premiums);
c) during civil liability insurance, the amount of insurance compensation, and during civil liability insurance of owners of land vehicles - the amount of insurance (regular) payments, insurance compensations made by the Motor (Transport) Insurance Bureau of Ukraine in accordance with the Law of Ukraine "On Compulsory Civil Liability Insurance of Owners of Land Vehicles", cannot exceed the amount of damage actually caused to the beneficiary, determined at normal prices on the date of such insurance payment;
{Subparagraph "c" of subparagraph 165.1.27 of paragraph 165.1 of Article 165 as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 165.1.27 of Clause 165.1 of Article 165 as amended by Law No. 2628-VIII of 23.11.2018 }
165.1.28. the amount of insurance payment, insurance indemnity, redemption amount or part thereof, or pension payment received by the taxpayer under a long-term life insurance contract, including life pension insurance, the amount of pension payment from the non-state pension system, the amount of payment under a pension deposit contract, a trust management contract concluded with a participant in a bank management fund, defined by subparagraph 170.8.3 of paragraph 170.8 of Article 170 of this Code.
The procedure for applying subparagraph 165.1.27 of this paragraph and this subparagraph shall be determined by the National Bank of Ukraine and the National Securities and Stock Market Commission in accordance with the distribution of powers determined by the legislation on the regulation of financial services markets.
{Paragraph two of subparagraph 165.1.28 of paragraph 165.1 of Article 165 as amended by Laws No. 5083-VI of 05.07.2012 , No. 2888-IX of 12.01.2023 }
165.1.29. the principal amount of the deposit (deposit) made by the taxpayer to a bank or non-bank financial institution, which is returned to him, the amount received by the taxpayer as a result of the sale of the right of claim on the deposit, as well as the principal amount of the loan received by the taxpayer (during the term of the agreement), including a financial loan secured by collateral, for a specified period and with interest. The total annual taxable income of the taxpayer who acquired the right of claim on such a deposit (deposit) includes the positive difference between the amount of funds received as a result of the exercise of the right of claim and the value determined from the amount of expenses for the acquisition of such a deposit (deposit). In the case of notarization of the contract of sale of the right of claim on the deposit, the notary shall notify the supervisory authority of such a contract in accordance with the procedure established by this section;
{Subclause 165.1.29 of clause 165.1 of Article 165 as amended by Law No. 5519-VI of 06.12.2012 ; as amended by Law No. 321-VIII of 09.04.2015 }
165.1.30. the amount of payments to citizens of Ukraine (their heirs) of monetary savings placed in the period before January 2, 1992 in institutions of the Savings Bank of the USSR and the State Insurance of the USSR operating in the territory of Ukraine, as well as in the following state securities: bonds of the State Targeted Interest-Free Loan of 1990, bonds of the State Internal Winning Loan of 1982, state treasury obligations of the USSR, certificates of the Savings Bank of the USSR and monetary savings of citizens of Ukraine placed in institutions of the Savings Bank of Ukraine and the former Ukrderzhstrakh during 1992-1994;
165.1.31. the principal amount of refundable financial assistance provided by the taxpayer to other persons, which is returned to him, the principal amount of refundable financial assistance received by the taxpayer;
165.1.32. profit from transactions with property or investment assets that is not subject to taxation in accordance with the relevant provisions of this section;
165.1.33. the amount received by the taxpayer for donating blood, breast milk, or other types of donation, which is paid from the budget or a budget institution;
165.1.34. the cost of housing that is transferred from state or municipal ownership to the property of the taxpayer free of charge or at a discount in accordance with the law, as well as the amount of state support for the construction or purchase of affordable housing provided to the taxpayer in accordance with the law.
If a taxpayer from among civil servants and persons equated to them has the right to receive a one-time monetary compensation for expenses for creating proper housing conditions in accordance with the legislation, the amount of such compensation is taxed as an additional benefit during its accrual (payment) at its expense;
165.1.35. the cost of vacation, health improvement and treatment trips, including rehabilitation of persons with disabilities, on the territory of Ukraine to the taxpayer and/or his children under the age of 18, which are provided to him free of charge or at a discount (in the amount of such discount) by a professional union to which the trade union contributions of the taxpayer - a member of such a professional union established in accordance with the legislation of Ukraine, or at the expense of the relevant mandatory state social insurance fund, are credited;
the cost of vacation, health improvement and treatment trips, including rehabilitation of persons with disabilities, in the territory of Ukraine to the taxpayer and/or members of his family of the first degree of kinship, which are provided by his employer - payer of corporate income tax free of charge or with a discount (in the amount of such discount) once per calendar year, provided that the cost of the trip (the amount of the discount) does not exceed 5 times the minimum wage established on January 1 of the tax (reporting) year;
{Subclause 165.1.35 of clause 165.1 of Article 165 is supplemented by the second paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
165.1.36. income of an individual entrepreneur on which a single tax is paid under the simplified taxation system in accordance with this Code;
165.1.37. the amount of the employer's expenses in connection with the taxpayer's advanced training (retraining) in accordance with the law;
165.1.38. the cost of orders, medals, badges, cups, diplomas, certificates and flowers awarded to employees, other categories of citizens and/or winners of competitions and contests;
165.1.39. the value of gifts (as well as prizes for winners and prize-winners of sports competitions) - in the part not exceeding 25 percent of one minimum wage (per month) established as of January 1 of the reporting tax year, excluding cash payments in any amount;
{Subclause 165.1.39 of clause 165.1 of Article 165 as amended by Law No. 1791-VIII of 20.12.2016 ; as amended by Law No. 2628-VIII of 23.11.2018 }
165.1.40. the amount of income received by a taxpayer as a result of the alienation of shares (other corporate rights) acquired by him in the privatization process in exchange for privatization compensation certificates directly received by him as compensation for the amount of his contribution to the institutions of the Savings Bank of the USSR or to the institutions of the USSR State Insurance, or in exchange for privatization certificates received by him in accordance with the law, as well as the amount of income received by such a taxpayer as a result of the alienation of agricultural land plots, land shares (shares) according to the norms of gratuitous transfer determined by Article 121 of the Land Code of Ukraine depending on their purpose, and property shares directly acquired by him in the privatization process;
165.1.41. income in the form of interest on current bank accounts, through which exclusively payments of wages, scholarships, pensions, social assistance and other social payments provided for by law are made in favor of individuals. The characteristics of such accounts are determined by the National Bank of Ukraine;
{Subclause 165.1.41 of Clause 165.1 of Article 165 as amended by Law No. 1166-VII of 27.03.2014 - for the entry into force of the amendments, see Clause 1 of Section IV of Law No. 1166-VII of 27.03.2014; as amended by Law No. 1588-VII of 04.07.2014 }
165.1.42. amounts of funds provided by charitable organizations, public associations included in the Register of Non-Profit Institutions and Organizations, all-Ukrainian public associations of persons with disabilities and their unions to taxpayers - participants in congresses, symposiums, meetings, conferences, plenums, conventions, festivals, exhibitions, concerts, rehabilitation events, physical culture and sports events, competitions, trainings and seminars held by such organizations, as compensation for accommodation, meals and travel to the venue of the events and back.
The expenses specified in the first paragraph of this subparagraph are not included in the total monthly (annual) taxable income of the taxpayer within the limits of the reimbursement rates for business trip expenses established for civil servants and employees of enterprises, institutions and organizations that are fully or partially maintained (financed) at the expense of budget funds;
{Subparagraph 165.1.42 of paragraph 165.1 of Article 165 as amended by Law No. 2520-IX of August 15, 2022 }
165.1.43. the amount of insurance payment under life insurance contracts in the event of the death of the insured person, if such payment is received by members of the insured person's family of the first degree of kinship, or by a person who is a person with a disability of group I or a child with a disability, or has the status of an orphan or a child deprived of parental care;
165.1.44. the amount of the taxpayer's property and non-property contribution to the authorized capital of a legal entity - the issuer of corporate rights, in exchange for such corporate rights;
{Subclause 165.1.44 of Clause 165.1 of Article 165 as amended by Law No. 3553-IX of 16.01.2024 }
165.1.45. the cost of secondary forest uses for own consumption (harvesting of medicinal plants, collection of forest litter, harvesting of reeds and other secondary forest uses provided for by the Forest Code of Ukraine );
{Subclause 165.1.46 of clause 165.1 of Article 165 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
165.1.47. the amount of payments or compensations (except for wages or other payments and compensations under civil law contracts) made by decision of a trade union, its association and/or trade union organization, adopted in accordance with the established procedure, in favor of a member of such trade union during the year in the aggregate amount not exceeding the amount of the income limit determined in accordance with paragraph one of subparagraph 169.4.1 of clause 169.4 of Article 169 of this Code;
{Subparagraph 165.1.47 of paragraph 165.1 of Article 165 as amended by Law No. 4834-VI of 24.05.2012 }
165.1.48. cooperative payments to a member of a production agricultural cooperative, a member of an agricultural service cooperative, as well as funds returned to a member of an agricultural service cooperative as a result of the cost of services provided by the cooperative being overpaid by him;
{Paragraph one of subparagraph 165.1.48 of paragraph 165.1 of Article 165 as amended by Law No. 2497-VIII of 10.07.2018 }
the size (amount, value) of the share returned to a member of an agricultural production cooperative, a member of an agricultural service cooperative in the event of his termination of membership in the cooperative. The excess of the size (amount, value) of the share over the size (amount, value) of the share contributions is subject to taxation in accordance with the procedure established by paragraph 170.2 of Article 170 of this section;
{Paragraph two of subparagraph 165.1.48 of paragraph 165.1 of Article 165 as amended by Law No. 2497-VIII of 10.07.2018 }
{Subparagraph 165.1.48 of paragraph 165.1 of Article 165 as amended by Law No. 5412-VI of 02.10.2012 }
165.1.49. other income that, in accordance with this Code, is not included in the total monthly (annual) taxable income.
165.1.50. transactions for the conversion of securities if their exchange is carried out at normal prices or at the value of net assets per security, which do not result in the alienation of investments and are carried out with securities of CII managed by one asset management company;
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.50 in accordance with Law No. 3609-VI of 07.07.2011 }
165.1.51. income from transactions with currency values (except for securities) related to the transfer of ownership of such currency values, with the exception of income, the taxation of which is expressly provided for by other provisions of this section;
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.51 in accordance with Law No. 4834-VI of 24.05.2012 }
165.1.52. investment income from transactions with debt obligations of the National Bank of Ukraine and with government securities issued by the central executive body that ensures the formation and implementation of state financial policy and/or implements state budget policy in the field of management of state debt and state-guaranteed debt, taking into account exchange rate differences;
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.52 in accordance with Law No. 4834-VI of 24.05.2012 ; as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 1016-IX dated 01.12.2020 }
165.1.53. the amount of unaccrued interest for using the loan in accordance with the Law of Ukraine "On Social and Legal Protection of Military Personnel and Members of Their Families" ;
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.53 in accordance with Law No. 1275-VII of 20.05.2014 }
165.1.54. amount (cost) of charitable assistance:
a) paid (provided) by benefactors, including benefactors - individuals who are included in the Register of volunteers of the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, in accordance with the procedure established by the Law of Ukraine "On Charitable Activities and Charitable Organizations", in favor of:
{Paragraph one of subparagraph "a" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 as amended by Law No. 2173-IX of 01.04.2022 }
participants in hostilities, servicemen (reservists, conscripts) and employees of the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, privates, commanding officers, servicemen, employees of the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations formed in accordance with the laws of Ukraine, police officers and employees of the National Police of Ukraine, who protect (protected) the independence, sovereignty and territorial integrity of Ukraine, take (took) direct part in the anti-terrorist operation, ensuring its conduct, being directly in the areas of the anti-terrorist operation, in the implementation of measures to ensure national security and defense, repel and deter the armed aggression of the Russian Federation in the Donetsk and Luhansk regions, being directly in the areas and during the implementation of the specified measures; employees of enterprises, institutions, organizations that are involved (were involved) and take (took) direct participation in the anti-terrorist operation in the areas of its implementation, in ensuring the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, while being directly in the areas and during the implementation of the specified measures, in the manner established by law, or for the benefit of family members of such combatants who, while participating in the anti-terrorist operation, participating in ensuring its implementation, in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, while being directly in the areas and during the implementation of the specified measures, suffered injuries, contusions or other damage to health, died, died as a result of injuries, contusions or mutilations received during participation in the anti-terrorist operation, ensuring its implementation, in the implementation measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, being directly in the areas and during the implementation of the specified measures, or recognized as missing in accordance with the established procedure;
{Paragraph two of subparagraph "a" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 as amended by Laws No. 1293-IX of 02.03.2021 , No. 3721-IX of 21.05.2024 }
participants in mass public protest actions in Ukraine who suffered injuries, contusions or other health damage while participating in these actions in the period from November 21, 2013 to February 28, 2014, as well as on May 2, 2014 in the city of Odessa, or in favor of family members of such participants who died or died as a result of injuries, contusions or other health damage received during this period or were recognized as missing in action in accordance with the established procedure;
individuals who live (residing) in the territories of settlements where an anti-terrorist operation is being (was being) conducted, and/or were forced to leave their place of residence in connection with the conduct of an anti-terrorist operation in such settlements;
individuals who lived in the territory of the Autonomous Republic of Crimea and were forced to leave their place of residence due to the temporary occupation of the territory of Ukraine, as defined by the Law of Ukraine "On Ensuring the Rights and Freedoms of Citizens and the Legal Regime on the Temporarily Occupied Territory of Ukraine";
b) received by benefactors - individuals who are included in the Register of Volunteers of the Anti-Terrorist Operation and/or implementing measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the manner prescribed by the Law of Ukraine "On Charitable Activities and Charitable Organizations" (hereinafter referred to as the Register of Volunteers), for the provision of charitable assistance in favor of persons specified in subparagraphs "a" and "c" of this subparagraph (directly to such persons or through the Ministry of Defense of Ukraine, the Main Directorate of the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the Administration of the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the National Police of Ukraine, the State Guard Directorate of Ukraine, the Administration of the State Service for Special Communications and Information Protection of Ukraine, through the management bodies of other military formations, their formations, military units, subdivisions, institutions or organizations established in accordance with the laws of Ukraine, maintained at the expense of the state budget), in the amount actually used for such purposes, and for reimbursement of documented expenses of such benefactors related to the provision of the specified charitable assistance;
{Paragraph one of subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 as amended by Law No. 3219-IX of 30.06.2023 }
The provisions of this subparagraph apply to charitable assistance received by the specified benefactors - individuals in the following reporting tax years:
{Subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 is supplemented by the second paragraph in accordance with Law No. 3219-IX of 06/30/2023 }
in the reporting tax year preceding the year of entry of the individual into the Volunteer Register;
{Subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 is supplemented by the third paragraph in accordance with Law No. 3219-IX of 30.06.2023 }
in the reporting tax year in which the individual was entered into the Volunteer Register;
{Subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 is supplemented by the fourth paragraph in accordance with Law No. 3219-IX of 30.06.2023 }
in the reporting tax years following the year of entry of the individual into the Register of Volunteers, but no later than December 31 of the year following the year in which the anti-terrorist operation was completed and/or the martial law, state of emergency in Ukraine was terminated or canceled, and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation was completed;
{Subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 is supplemented by the fifth paragraph in accordance with Law No. 3219-IX of 30.06.2023 }
{Subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 as amended by Laws No. 1293-IX of 02.03.2021 , No. 2173-IX of 01.04.2022 , No. 2520-IX of 15.08.2022 , No. 2747-IX of 16.11.2022 }
c) paid (provided) by benefactors, including benefactors - individuals, in accordance with the procedure specified by the Law of Ukraine "On Charitable Activities and Charitable Organizations", in favor of:
participants in hostilities, servicemen (reservists, conscripts) and employees of the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, privates, commanding officers, servicemen, employees of the Ministry of Internal Affairs of Ukraine, the State Security Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations formed in accordance with the laws of Ukraine, volunteer formations of territorial communities, police officers and employees of the National Police of Ukraine, including those who suffered injuries, contusions or other damage to health, died, died as a result of injuries, contusions or mutilations, who defend (defended) the independence, sovereignty and territorial integrity of Ukraine, take (took) direct part in repelling armed aggression and ensuring national security, eliminating the threat of danger to the state independence of Ukraine, its territorial integrity integrity during the period of martial law or a state of emergency in Ukraine, while being directly in the areas where the specified measures are being implemented, or for the benefit of family members of such participants in hostilities;
{Paragraph two of subparagraph "c" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 as amended by Law No. 3721-IX of 21.05.2024 }
employees of enterprises, institutions, organizations, and civil defense forces who are involved (were involved) and take (took) direct participation in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, being directly in the areas of hostilities and during the period of hostilities, in accordance with the procedure established by law, or for the benefit of their family members;
individuals who live (lived) in the territories of settlements where hostilities are (were) being conducted, and/or who were forced to leave their place of residence due to hostilities in such settlements;
military personnel (reservists) who suffered injuries, contusions or other damage to health while defending the independence, sovereignty and territorial integrity of Ukraine, while directly participating in repelling armed aggression and ensuring national security, eliminating the threat to the state independence of Ukraine, its territorial integrity during the period of martial law, a state of emergency in Ukraine, if such persons were directly in the areas where the specified measures were implemented, or for the benefit of family members of such military personnel (reservists) who died, died as a result of injuries, contusions or mutilation.
{Subparagraph 165.1.54 of paragraph 165.1 of Article 165 is supplemented with a new paragraph in accordance with Law No. 3603-IX of 23.02.2024 }
For the purposes of this subparagraph, family members of combatants, employees of enterprises, institutions, organizations, civil defense forces, military personnel (reservists) and/or participants in mass public protest actions in Ukraine include:
{Paragraph of subparagraph 165.1.54 of paragraph 165.1 of Article 165 as amended by Law No. 3603-IX of 02/23/2024 }
parents (if they were not deprived of parental rights before the person reached the age of majority);
grandparents (if parents are deceased);
the other spouse (if he (she) has not remarried);
young and/or minor children;
adult children who are studying full-time or dual education in institutions of vocational (vocational and technical), professional pre-higher and higher education, until they graduate from educational institutions, but no later than until they reach the age of 23;
adult children who do not have their own families;
adult children who have their own families but became disabled before reaching adulthood;
dependents of the deceased (deceased), who are paid a pension in this regard.
The income specified in this subparagraph shall not be included in the total monthly (annual) taxable income of taxpayers until December 31, inclusive, of the year following the year in which the anti-terrorist operation was completed and/or the martial law or state of emergency in Ukraine was terminated or abolished, and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation was completed.
{Subclause 165.1.54 of clause 165.1 of Article 165 is supplemented by subparagraph "c" in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 2516-IX of August 15, 2022 }
For the purposes of this subparagraph, family members of participants in hostilities and/or participants in mass public protest actions in Ukraine include: wife, husband who have not remarried, parents, grandparents (if parents are deceased), minor children, adult children with disabilities.
The income specified in this subparagraph shall not be included in the total monthly (annual) taxable income of taxpayers until December 31 (inclusive) of the year following the year in which the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation were completed;
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.54 in accordance with Law No. 1668-VII of 02.09.2014 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 2173-IX of 01.04.2022 }
165.1.55. the principal amount of the taxpayer's debt (credit), forgiven (cancelled) by the creditor by his independent decision, not related to the bankruptcy procedure, before the expiration of the limitation period in an amount not exceeding 25 percent of the amount of one minimum wage (per year) established as of January 1 of the reporting tax year, as well as the principal amount of the taxpayer's debt to the creditor - a financial institution upon execution by such creditor of a court decision on the release of the debtor - an individual from debts in an insolvency case in an amount not exceeding 25 percent of the amount of one minimum wage (per year) established as of January 1 of the reporting tax year;
{Subclause 165.1.55 of clause 165.1 of Article 165 as amended by Law No. 1791-VIII of 20.12.2016 ; first paragraph of subclause 165.1.55 of clause 165.1 of Article 165 as amended by Law No. 4698-IX of 03.12.2025 }
the amount of interest, commission and/or penalties (penalties) forgiven (cancelled) by the creditor by his independent decision, not related to his bankruptcy procedure, before the expiration of the limitation period, as well as the amount of interest, commission and/or penalties (penalties) upon execution by the creditor - a financial institution of a court decision on the release of the debtor - an individual from debts in an insolvency case;
{Subparagraph 165.1.55 of paragraph 165.1 of Article 165 is supplemented by the second paragraph in accordance with Law No. 321-VIII of 09.04.2015 ; as amended by Law No. 4698-IX of 03.12.2025 }
the principal amount of the taxpayer's debt (loan) under a mortgage loan in foreign currency secured by a mortgage on residential real estate, forgiven (cancelled) by the creditor by his independent decision, not related to the bankruptcy procedure, before the expiration of the limitation period, as well as the principal amount of the taxpayer's debt (loan) under a mortgage loan in foreign currency secured by a mortgage on residential real estate, upon execution by the creditor - a financial institution of a court decision on the release of the debtor - an individual from debts in an insolvency case;
{Subparagraph 165.1.55 of paragraph 165.1 of Article 165 is supplemented by the third paragraph in accordance with Law No. 1383-IX of April 13, 2021 ; as amended by Law No. 4698-IX of December 3, 2025 }
the amount of the taxpayer's debt under a consumer credit agreement or other agreement (including the amount of interest, commissions and other payments) canceled in accordance with paragraphs 12 and 16 of Section IV "Final and Transitional Provisions" of the Law of Ukraine "On Consumer Crediting", as well as the amount of interest, commissions and other payments under such an agreement that are not subject to payment by the taxpayer in accordance with paragraph 11 of Section IV "Final and Transitional Provisions" of the Law of Ukraine "On Consumer Crediting";
{Subparagraph 165.1.55 of paragraph 165.1 of Article 165 is supplemented by the fourth paragraph in accordance with Law No. 2823-IX of 01.12.2022 }
{ Clause 165.1 of Article 165 is supplemented by subclause 165.1.55 in accordance with the Law No. 71-VIII dated 28.12.2014 }
165.1.56. the amount (value) of charitable assistance paid (provided) by international charitable organizations (their branches, representative offices), the list of which is determined by the Cabinet of Ministers of Ukraine, in favor of:
individuals who live (reside) in the territories of settlements where an anti-terrorist operation is being (was being) conducted (except for territories in which state authorities temporarily do not exercise or do not exercise their powers to the full extent), and/or were forced to leave their place of residence in connection with the conduct of an anti-terrorist operation in such settlements and were registered in accordance with the procedure established by law in the structural units for social protection of the population of district, district in Kyiv state administrations, executive bodies of cities, district in cities (in case of formation) councils;
individuals who lived in the territory of the Autonomous Republic of Crimea and were forced to leave their place of residence due to the temporary occupation of the territory of Ukraine, defined by the Law of Ukraine "On Ensuring the Rights and Freedoms of Citizens and the Legal Regime on the Temporarily Occupied Territory of Ukraine", and registered in accordance with the procedure established by law in the structural units for social protection of the population of district, district in the city of Kyiv state administrations, executive bodies of city, district in cities (in case of formation) councils;
individuals who live (lived) in settlements on the territory of which combat operations are (were) conducted during the martial law or state of emergency, and/or were forced to leave their place of residence (temporarily displaced persons) due to force majeure circumstances (force majeure circumstances), including in connection with the introduction of martial law or state of emergency, confirmed in accordance with the procedure established by law;
{Sub -paragraph 165.1.56 of paragraph 165.1 of Article 165 is supplemented with a new paragraph in accordance with Law No. 2120-IX of March 15, 2022 }
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.56 in accordance with Law No. 211-VIII of 02.03.2015 }
165.1.57. the amount of funds provided to the taxpayer by an international financial organization within the framework of its official activities in Ukraine in connection with the implementation of energy efficiency and energy saving measures within the framework of the implementation of projects of the international financial organization in Ukraine (both directly and through authorized banks or in another manner provided for by the relevant project of such international financial organization);
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.57 in accordance with Law No. 909-VIII of 24.12.2015 }
165.1.58. the amount of funds provided in accordance with the procedure established by the Cabinet of Ministers of Ukraine to a taxpayer by a financial organization or fund other than that specified in subparagraph 165.1.57. of this paragraph, engaged in financing development programs, in connection with the implementation of energy efficiency and energy saving measures within the framework of the implementation of projects of such organization or fund in Ukraine (both directly and through authorized banks or in another manner provided for by the relevant project of such organization or fund);
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.58 in accordance with Law No. 909-VIII of 24.12.2015 }
165.1.59. amounts by which the debt of an individual was reduced (forgiven) by restructuring the obligations stipulated by the credit agreement, according to which the creditor provided the borrower - an individual with a loan in foreign currency, if such restructuring was carried out in accordance with the procedure and on the terms established by Section IV "Final and Transitional Provisions" of the Law of Ukraine "On Consumer Lending" or by Clause 5 of Section "Final and Transitional Provisions" of the Code of Ukraine on Bankruptcy Procedures;
amounts by which the debt of an individual has been reduced (forgiven) by restructuring the obligations stipulated by the credit agreement, if such restructuring was carried out in accordance with the procedure and on the terms established by paragraph 7 - 1 of Section IV "Final and Transitional Provisions" of the Law of Ukraine "On Consumer Lending".
{Sub-clause 165.1.59 of clause 165.1 of Article 165 is supplemented by the second paragraph in accordance with Law No. 3157-IX of 10.06.2023 }
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.59 in accordance with Law No. 909-VIII of 24.12.2015 ; as amended by the Law No. 1383-IX dated 13.04.2021 }
165.1.60. the cost of free of charge provided (transferred) by structural units on health care issues of regional, Kyiv and Sevastopol city state administrations and/or business entities that have a license to conduct business activities in medical practice, medicines, medical devices and auxiliary means for them, as well as services in the health care system for the benefit of the end consumer (patient), including for the purpose of providing necessary medical services and medicines provided for by the medical guarantees program.
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.60 in accordance with Law No. 532-IX of March 17, 2020 }
165.1.61. the value of medicines, medical devices and auxiliary means provided free of charge (transferred) by a person authorized to carry out procurement in the field of healthcare to business entities that have a license to conduct economic activity in medical practice, for the implementation of programs and implementation of centralized health care measures and/or as a result of the conclusion of managed access agreements financed from the state budget and/or local budgets, and/or funds of business entities of state or municipal ownership that have a license to conduct economic activity in medical practice, for the benefit of the end consumer (patient), provided that:
1) such goods on the date of conclusion of the contract for their purchase were included in the List of medicines, medical devices and auxiliary means to them, which are purchased with the funds of the state budget for the implementation of programs and centralized measures in healthcare , and/or in the List of medicines, which are purchased under managed access contracts , approved by the Cabinet of Ministers of Ukraine, and
2) such goods were purchased by a person authorized to make purchases in the healthcare sector, at the expense of the state budget funds provided for the implementation of programs and centralized healthcare measures, and/or local budget funds, and/or at the expense of state or municipal business entities that have a license to conduct business activities in medical practice, or at the expense of grants (sub-grants) for the implementation of programs of the Global Fund to Fight AIDS, Tuberculosis and Malaria in Ukraine in accordance with the law;
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.61 in accordance with Law No. 532-IX of March 17, 2020 ; as amended by Law No. 4505-IX of June 18, 2025 }
165.1.62. the amount of income received by the taxpayer in the form of support provided by the Fund of the President of Ukraine for the Support of Education, Science and Sports.
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.62 in accordance with Law No. 1914-IX of 30.11.2021 }
165.1.63. the amount of the reward for the combat equipment of the aggressor state voluntarily transferred to the Armed Forces of Ukraine, suitable for use, in accordance with the Law of Ukraine "On Establishing the Reward for the Combat Equipment of the aggressor state voluntarily transferred to the Armed Forces of Ukraine, suitable for use".
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.63 in accordance with Law No. 2214-IX of 21.04.2022 }
165.1.64. funds or the cost of property (services) provided to an individual - a volunteer, with whom an agreement on the implementation of volunteer activities has been concluded, in part of the expenses of a non-profit organization that involves volunteers in its activities, for conducting a medical examination and vaccination of the volunteer, other medical and preventive measures directly related to the provision of volunteer assistance by such a person in accordance with the Law of Ukraine "On Volunteer Activities";
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.64 in accordance with Law No. 2520-IX of August 15, 2022 }
165.1.65. reimbursement by a non-profit organization to a volunteer with whom an agreement on the implementation of volunteer activities has been concluded, of documented expenses related to the provision of volunteer assistance, in the amount and in accordance with the list provided for in Article 11 of the Law of Ukraine "On Volunteer Activities".
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.65 in accordance with Law No. 2520-IX of 15.08.2022 }
165.1.66. the amount of income received as compensation for damaged/destroyed real estate in accordance with the Law of Ukraine "On Compensation for Damage and Destruction of Certain Categories of Real Estate Objects as a Result of Hostilities, Terrorist Acts, and Sabotage Caused by Armed Aggression of the Russian Federation against Ukraine, and the State Register of Property Damaged and Destroyed as a Result of Hostilities, Terrorist Acts, and Sabotage Caused by Armed Aggression of the Russian Federation against Ukraine".
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.66 in accordance with Law No. 3219-IX of 30.06.2023 }
165.1.67. the cost of unregistered medicinal products provided (transferred) free of charge for the benefit of patients participating in clinical trials, programs of expanded patient access to unregistered medicinal products and/or programs of access of research subjects (patients) to the investigational medicinal product after the completion of the clinical trial, according to the list and in the amounts determined by the central executive body that ensures the formation of state policy in the field of healthcare, in accordance with the procedure and under the conditions specified by the Law of Ukraine "On Medicinal Products".
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.67 in accordance with Law No. 3603-IX of 23.02.2024 }
165.1.68. the amount (value) of a charitable donation received by individuals who carry out a public collection of charitable donations on behalf of a charitable organization or for the benefit of a charitable organization on their own behalf, on behalf of or for the benefit of other beneficiaries in accordance with the procedure specified by the Law of Ukraine "On Charitable Activities and Charitable Organizations", in the amount actually transferred (transferred) to such a charitable organization or beneficiary, on behalf of and/or for the benefit of which the public collection of charitable donations was carried out.
{Clause 165.1 of Article 165 is supplemented by subparagraph 165.1.68 in accordance with Law No. 4143-IX of 17.12.2024 ; as amended by Law No. 4254-IX of 25.02.2025 }
166.1.1. The taxpayer is entitled to a tax deduction based on the results of the reporting tax year;
166.1.2. The grounds for calculating a tax discount, indicating specific amounts, shall be reflected by the taxpayer in the annual tax return, which shall be submitted by December 31 of the tax year following the reporting year.
{Subclause 166.1.2 of Clause 166.1 of Article 166 as amended by Law No. 4661-VI of 24.04.2012 }
166.2. Documentary confirmation of expenses included in the tax deduction.
166.2.1. The tax rebate includes expenses actually incurred by the taxpayer during the reporting tax year, confirmed by relevant payment and settlement documents, in particular receipts, fiscal or commodity checks, cash receipts that identify the seller of goods (works, services) and the person applying for the tax rebate (their buyer (recipient), as well as copies of contracts, if any, which must necessarily reflect the cost of such goods (works, services) and the payment term for such goods (works, services);
{Subparagraph 166.2.1 of paragraph 166.2 of Article 166 as amended by Law No. 466-IX of January 16, 2020 }
166.2.2. Copies of the documents specified in subparagraph 166.2.1 of this paragraph (except for electronic settlement documents) shall be submitted together with the tax return , and the originals of these documents shall not be sent to the supervisory authority, but shall be kept by the taxpayer for the period of limitation established by this Code.
If the relevant expenses are confirmed by an electronic settlement document, the taxpayer indicates only the details of the electronic settlement document in the tax return .
{Subparagraph 166.2.2 of paragraph 166.2 of Article 166 is supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Subclause 166.2.2 of Clause 166.2 of Article 166 as amended by Law No. 466-IX of 16.01.2020 }
166.2.3. For documentary confirmation of expenses included in the tax discount, the controlling body does not have the right to require the taxpayer to provide documents and/or their copies contained in automated information and reference systems, registers, databases (databases) of state authorities and/or local self-government bodies, information from which is obtained free of charge by controlling bodies in accordance with this Code and contained in the information bases of the central executive body implementing state tax policy.
{Clause 166.2 of Article 166 is supplemented by subparagraph 166.2.3 in accordance with Law No. 1914-IX of 11/30/2021 ; as amended by Law No. 2520-IX of 08/15/2022 }
166.3. List of expenses allowed for inclusion in the tax deduction.
The taxpayer has the right to include in the tax deduction in the reduction of the taxpayer's taxable income as a result of the reporting tax year, accrued in the form of wages, reduced taking into account the provisions of Clause 164.6 of Article 164 of this Code, or in the form of dividends, except for the amounts of dividends that are not included in the calculation of the total monthly (annual) taxable income, the following expenses actually incurred by him during the reporting tax year:
{Paragraph two of item 166.3 of Article 166 as amended by Laws No. 1946-IX of 14.12.2021 , No. 2520-IX of 15.08.2022 }
166.3.1. part of the amount of interest paid by such taxpayer for the use of a mortgage housing loan, determined in accordance with Article 175 of this Code;
166.3.2. the amount of funds or the value of property transferred (transferred) by the taxpayer in the form of donations or charitable contributions to non-profit organizations that, on the date of transfer (transfer) of such funds and property, met the conditions specified in paragraph 133.4 of Article 133 of this Code, in an amount not exceeding 4 percent of the amount of his total taxable income for such reporting year;
{Subparagraph 166.3.2 of paragraph 166.3 of Article 166 as amended by Law No. 652-VIII of 17.07.2015 }
166.3.3. the amount of funds paid by the taxpayer to domestic institutions of preschool, extracurricular, general secondary, vocational (vocational and technical) and higher education to compensate for the cost of obtaining the relevant education by such taxpayer and/or a member of his family of the first degree of kinship and/or a person over whom guardianship or care has been established, or who has been placed in a foster family, a family-type orphanage, if such taxpayer has been appointed, respectively, as a guardian, trustee, adoptive father, adoptive mother, foster father, foster mother;
{Subclause 166.3.3 of Clause 166.3 of Article 166 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2477-VIII of 07/03/2018 , No. 1914-IX of 11/30/2021 }
166.3.4. the amount of funds paid by the taxpayer to healthcare institutions to compensate for the cost of paid services for the treatment of such a taxpayer or a member of his family of the first degree of kinship and/or a person over whom guardianship or care has been established, or who has been placed in a foster family, a family-type orphanage, if such a taxpayer has been appointed as a guardian, trustee, adoptive father, adoptive mother, foster father, foster mother, including for the purchase of medicines (donor components, prosthetic and orthopedic devices, medical products for individual use of persons with disabilities), as well as the amount of funds paid by a taxpayer recognized in accordance with the established procedure as a person with disabilities, to prosthetic and orthopedic enterprises, rehabilitation institutions to compensate for the cost of paid rehabilitation services, technical and other rehabilitation facilities provided to such a taxpayer or his child with disabilities in amounts that are not overlapped by payments from the funds of mandatory state social health insurance, except for:
{Paragraph one of subparagraph 166.3.4 of paragraph 166.3 of Article 166 as amended by Law No. 1914-IX of 11/30/2021 }
a) cosmetic treatment or cosmetic surgery, including cosmetic prosthetics, not related to medical indications, hydrotherapy and heliotherapy, not related to the treatment of chronic diseases;
b) dental prosthetics using precious metals, porcelain and electroplating;
c) abortions (except for abortions performed for medical reasons or when the pregnancy is the result of rape);
d) gender reassignment surgeries;
e) treatment of sexually transmitted diseases (except AIDS and sexually transmitted diseases caused by household infection or rape);
e) treatment of tobacco or alcohol addiction;
e) purchase of medicines, medical devices and appliances, payment of the cost of medical services that are not included in the list of vitally necessary goods approved by the Cabinet of Ministers of Ukraine;
166.3.5. the amount of the taxpayer's expenses for the payment of insurance payments (insurance contributions, insurance premiums) and pension contributions paid by the taxpayer to a resident insurer, a non-state pension fund, a banking institution under long-term life insurance contracts, non-state pension provision, under a pension contract with a non-state pension fund, as well as contributions to a bank pension deposit account, to pension deposits and accounts of participants in bank management funds of both such taxpayer and members of his family of the first degree of kinship, which do not exceed (calculated for each of the full or incomplete months of the reporting tax year during which the insurance contract was in force):
a) when insuring a taxpayer or under a pension contract with a non-state pension fund of the taxpayer, or to a bank pension deposit account, pension contribution, account of a participant in a bank management fund, or their totality - the amount specified in paragraph one of subparagraph 169.4.1 of clause 169.4 of Article 169 of this Code;
b) when insuring a family member of a first-degree relative of a taxpayer either under a pension contract with a non-state pension fund, or to a bank pension deposit account, pension contribution, account of a participant in a bank management fund in favor of such a family member or their totality - 50 percent of the amount specified in paragraph one of subparagraph 169.4.1 of clause 169.4 of Article 169 of this Code, calculated for each insured family member;
166.3.6. the amount of the taxpayer's expenses for:
payment for assisted reproductive technologies in accordance with the conditions established by law, but not more than an amount equal to one third of income in the form of wages for the reporting tax year;
payment of the cost of public services related to the adoption of a child, including payment of state duty;
166.3.7. the amount of funds paid by the taxpayer in connection with the conversion of a vehicle owned by the taxpayer using mixed motor fuel, bioethanol, biodiesel, compressed or liquefied gas, and other types of biofuel;
166.3.8. the amount of the taxpayer's expenses for the payment of expenses for the construction (purchase) of affordable housing, as determined by law, including the repayment of a preferential mortgage loan granted for such purposes, and interest thereon.
166.3.9. the amount of funds in the form of rent under a housing (apartment, house) rental agreement, drawn up in accordance with the requirements of current legislation, actually paid by a taxpayer who has the status of an internally displaced person, a participant in hostilities, or a person with a disability as a result of war.
{Paragraph one of subparagraph 166.3.9 of paragraph 166.3 of Article 166 and as amended by Law No. 4536-IX of 16.07.2025 }
The taxpayer has the right to use the tax discount specified in this subparagraph only on the condition that he and/or his first-degree family members:
do not own residential real estate suitable for habitation located outside the temporarily occupied territory of Ukraine;
do not receive budget payments to cover living expenses as provided for by the legislation of Ukraine.
The amount of such a discount cannot exceed (per calendar year) 30 times the minimum wage established on January 1 of the reporting (tax) year.
{Clause 166.3 of Article 166 is supplemented by subparagraph 166.3.9 in accordance with Law No. 2530-VIII of 06.09.2018 ; as amended by Law No. 2628-VIII of 23.11.2018 }
166.3.10. the amount of the taxpayer's expenses for the acquisition of shares (other corporate rights), the issuer of which is a legal entity that has acquired the status of a resident of the Diya City in accordance with Part Three of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", provided that such expenses were incurred by the taxpayer before the issuer acquired the status of a resident of the Diya City or during the period when such a resident of the Diya City met the requirement established by Clause 3 of Part Three of Article 5 of the said Law.
{Clause 166.3 of Article 166 is supplemented by subparagraph 166.3.10 in accordance with Law No. 1946-IX of 14.12.2021 }
166.4. Limitation of the right to tax deduction.
166.4.1. A tax discount may be granted exclusively to a resident who has a registration number of a taxpayer's registration card, as well as to a resident - an individual who, due to his religious beliefs, refused to accept a registration number of a taxpayer's registration card and officially notified the relevant regulatory authority about this and has a note about this in his passport;
166.4.2. The total amount of the tax credit accrued to the taxpayer in the reporting tax year may not exceed the amount of the taxpayer's annual total taxable income accrued as wages, reduced taking into account the provisions of Clause 164.6 of Article 164 of this Code, except for the case specified in Subclause 166.4.4 of this Clause.
If a taxpayer receives income in the form of wages during the reporting year that was taxed at different tax rates, the amount of tax by which tax liabilities are reduced in connection with the exercise of the taxpayer's right to a tax discount is determined in the following manner:
determination of the shares (in percentages) of income accrued in the form of wages, taxed at different tax rates, in the total amount of annual total taxable income specified in the first paragraph of this subparagraph;
determining the estimated tax base by reducing the total taxable income of the taxpayer, received in the form of wages, by the amount of expenses incurred by the taxpayer during the reporting tax year, provided for in subparagraphs 166.3.1-166.3.9 of paragraph 166.3 of this article;
determining the estimated tax amount separately for each rate by multiplying the estimated tax base by the tax rate and the share determined in accordance with paragraph three of this subparagraph for the relevant tax rate;
determining the amount of tax by which tax liabilities are reduced in connection with the taxpayer exercising his right to a tax deduction, as the difference between the amount of tax withheld during the reporting year from taxable income accrued in the form of wages and the estimated amount of tax determined in accordance with paragraph five of this subclause.
{Subclause 166.4.2 of clause 166.4 of Article 166 as amended by Laws No. 1946-IX of 12/14/2021 , No. 2520-IX of 08/15/2022 }
166.4.3. if the taxpayer has not exercised the right to accrue a tax discount based on the results of the reporting tax year by the end of the tax year following the reporting one, such right shall not be carried over to subsequent tax years.
{Subclause 166.4.3 of Clause 166.4 of Article 166 as amended by Law No. 3609-VI of 07.07.2011 }
166.4.4. the amount of the tax credit accrued to the taxpayer in the reporting tax year, in the event of including in the tax credit the expenses provided for in subparagraph 166.3.10 of paragraph 166.3 of this Article, shall be calculated separately from other expenses and may not exceed the amount of the taxpayer's annual total taxable income received in the form of dividends, except for the amounts of dividends that are not included in the calculation of the total monthly (annual) taxable income.
{Paragraph one of subparagraph 166.4.4 of paragraph 166.4 of Article 166 as amended by Law No. 2520-IX of August 15, 2022 }
In the event that a taxpayer receives income during the reporting year that was taxed at different tax rates, the amount of tax by which tax liabilities are reduced in connection with the exercise of the taxpayer's right to a tax discount specified in the first paragraph of this subparagraph shall be determined in the following manner:
determination of the shares (in percentages) of income taxed at different tax rates in the total annual total taxable income specified in the first paragraph of this subparagraph;
determining the estimated tax base by reducing the total taxable income of the taxpayer received in the form of dividends, except for the amounts of dividends that are not included in the calculation of the total monthly (annual) taxable income, by the amount of expenses incurred by the taxpayer during the reporting tax year, provided for in subparagraph 166.3.10 of paragraph 166.3 of this article;
determining the estimated tax amount separately for each rate by multiplying the estimated tax base by the tax rate and the share determined in accordance with paragraph three of this subparagraph for the relevant tax rate;
determining the amount of tax by which tax liabilities are reduced in connection with the taxpayer exercising the right to a tax deduction, as the difference between the amount of tax withheld during the reporting year from taxable income specified in the first paragraph of this subparagraph and the estimated amount of tax determined in accordance with the fifth paragraph of this subparagraph.
{Clause 166.4 of Article 166 is supplemented by subparagraph 166.4.4 in accordance with Law No. 1946-IX of 14.12.2021 }
166.5. The central executive body implementing the state tax policy shall provide free explanations of the procedure for documentary confirmation of rights to a tax discount and filing a tax return, including by conducting relevant training, seminars, etc., and shall ensure free provision of tax return forms for this tax and other calculations provided for in this section by the controlling bodies upon the first request of the payer of this tax.
{Clause 166.5 of Article 166 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
167.1. The tax rate is 18 percent of the tax base for income accrued (paid, provided) (except for the cases specified in paragraphs 167.2-167.5 of this article), including, but not exclusively, in the form of: wages, other incentive and compensation payments or other payments and rewards accrued (paid, provided) to the payer in connection with employment relations and under civil law contracts.
{Clause 167.1 of Article 167 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4661-VI of 24.04.2012 , No. 4834-VI of 24.05.2012 ; as amended by Law No. 1166-VII of 27.03.2014 - for the entry into force of the amendments, see Clause 1 of Section IV of Law No. 1166-VII of 27.03.2014; as amended by Law No. 1588-VII of 04.07.2014 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 }
167.2. The tax rate is 5 percent of the tax base in cases expressly defined by this section.
{Clause 167.2 of Article 167 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 , No. 1166-VII of 27.03.2014 ; as amended by Law No. 1588-VII of 04.07.2014 }
167.3. The tax rate may be 0 percent of the tax base in cases expressly defined by this section.
{Clause 167.3 of Article 167 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 }
{Paragraph 167.4 of Article 167 is excluded on the basis of Law No. 71-VIII of 28.12.2014 }
167.4. The tax rate is 18 percent of the tax base for exceeding the amount of the pension (including the amount of its indexation, accrued in accordance with the law), the monthly lifetime cash support, defined in subparagraph 164.2.19 of paragraph 164.2 of Article 164 of this section, which are received by the taxpayer from the Pension Fund of Ukraine or the budget in accordance with the law.
{Clause 167.4 of Article 167 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 1411-VIII of 06/02/2016 }
167.5. Tax rates on passive income to the tax base are set at the following rates:
167.5.1. 18 percent - for passive income, except for those specified in subparagraphs 167.5.2 and 167.5.4 of this paragraph;
{Subclause 167.5.1 of clause 167.5 of Article 167 as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
167.5.2. 5 percent - for income in the form of dividends on shares and corporate rights accrued by residents - payers of corporate income tax (except for income in the form of dividends on shares, investment certificates paid by collective investment institutions);
{Subclause 167.5.3 of clause 167.5 of Article 167 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
167.5.4. at half the rate established in paragraph 167.1 of this article - for income in the form of dividends on shares and/or investment certificates, corporate rights accrued by non-residents, collective investment institutions and business entities that are not payers of income tax.
{Clause 167.5 of Article 167 is supplemented by subparagraph 167.5.4 in accordance with Law No. 1797-VIII of 21.12.2016 , taking into account the amendments made by Law No. 1989-VIII of 23.03.2017 }
{Clause 167.5 of Article 167 as amended by Law No. 1166-VII of 03/27/2014 - regarding the entry into force of the amendments, see Clause 1 of Section IV of Law No. 1166-VII of 03/27/2014; as amended by Laws No. 1588-VII of 07/04/2014 , No. 71-VIII of 12/28/2014 }
{Clause 167.6 of Article 167 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
Article 168. Procedure for accrual, withholding and payment (transfer) of tax to the budget↑
168.1. Taxation of income accrued (paid, provided) to a taxpayer by a tax agent.
168.1.1. A tax agent who accrues (pays, provides) taxable income for the benefit of a taxpayer is obliged to withhold tax from the amount of such income at his expense, using the tax rate specified in Article 167 of this Code.
168.1.1 - 1. Tax agents (prisoner camps, penal institutions and pre-trial detention centers of the State Penitentiary Service of Ukraine) that calculate income in the form of remuneration for work to prisoners of war, in the tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code, reflect the total amount of income accrued in the reporting (tax) period and the total amount of tax withheld from them. At the same time, the tax calculation does not indicate information on the amounts of accrued income of individual individuals - taxpayers who are prisoners of war, as well as information about such individuals.
{Paragraph 168.1 of Article 168 is supplemented subparagraph 168.1.1 - 1 according to the Law No. 4536-IX dated 16.07.2025 }
168.1.2. The tax is paid (transferred) to the relevant budget when paying taxable income by a single payment document. Banks, non-bank payment service providers shall accept payment documents for the payment of income only if a payment instruction for the transfer of this tax to the relevant budget or a payment instruction for the crediting of funds in the amount of this tax to a single account specified in Article 35 - 1 of this Code is simultaneously submitted.
{Subclause 168.1.2 of Clause 168.1 of Article 168 as amended by Law No. 190-IX of 04.10.2019 ; as amended by Laws No. 1914-IX of 30.11.2021 , No. 2888-IX of 12.01.2023 }
168.1.3. If, in accordance with the provisions of this section, certain types of taxable income (profits) are not subject to taxation at the time of their accrual or payment, but are not exempt from taxation, the taxpayer is obliged to independently include the amount of such income in the total annual taxable income of the tax and submit an annual declaration for this tax.
168.1.4. If taxable income is provided in non-cash form or paid in cash from the cash desk of a tax agent, the tax shall be paid (transferred) to the budget within three business days from the day following the day of such accrual (payment, provision).
{Subclause 168.1.4 of Clause 168.1 of Article 168 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2888-IX of 01/12/2023 }
168.1.5. If taxable income is accrued by a tax agent, but is not paid (provided) to the taxpayer, then the tax subject to withholding from such accrued income shall be remitted to the budget by the tax agent within the terms established by this Code for the monthly tax period.
{Clause 168.1 of Article 168 is supplemented by subparagraph 168.1.5 in accordance with Law No. 3609-VI of 07.07.2011 }
168.1.6. For the purposes of this section and paragraph 54.2 of Article 54 of this Code, the term "deadline for payment of tax to the budget" means the tax payment deadlines specified in this paragraph.
{Paragraph of Clause 168.1 of Article 168 as amended by Law No. 3609-VI of 07.07.2011 }
168.2. Taxation of income accrued (paid, provided) to a taxpayer by a person who is not a tax agent, and foreign income.
168.2.1. A taxpayer who receives income from a person who is not a tax agent and foreign income is obliged to include the amount of such income in the total annual taxable income and file a tax return for the results of the reporting tax year, as well as pay tax on such income.
168.2.2. A person who is not a tax agent is considered a non-resident or an individual who does not have the status of a business entity or is not a person registered with regulatory authorities as a person engaged in independent professional activity.
168.3. The calculation of tax liabilities from the taxable income of the taxpayer, accrued at the source of its payment, is carried out by the tax agent (including the employer, bodies of the Pension Fund of Ukraine).
{Clause 168.3 of Article 168 as amended by Law No. 1166-VII of March 27, 2014 - for the entry into force of the amendments, see Clause 1 of Section IV of Law No. 1166-VII of March 27, 2014}
168.4. Procedure for payment (transfer) of tax to the budget.
168.4.1. Tax withheld from the income of residents and non-residents shall be credited to the relevant budgets in accordance with the Budget Code of Ukraine ;
{Subclause 168.4.1 of Clause 168.4 of Article 168 as amended by Law No. 1914-IX of 30.11.2021 }
168.4.2. this procedure is applied by all legal entities, including those that have branches, departments, other separate units located in the territory of a different territorial community than such legal entity, as well as separate units that are granted the authority to charge, withhold and pay (transfer) tax to the budget in accordance with the established procedure (hereinafter referred to as a separate unit).
In the event of a decision to create a separate unit, the legal entity shall notify the regulatory authorities at its location and the location of such newly created units in accordance with the established procedure;
168.4.3. the amounts of income tax accrued by a separate subdivision for the benefit of individuals for the reporting period shall be transferred to the relevant budget at the location of such separate subdivision.
If a separate unit is not authorized to charge (pay) personal income tax for such a separate unit, all duties of a tax agent shall be performed by a legal entity. Income tax charged to employees of a separate unit shall be transferred to the relevant budget at the location of such a separate unit;
{Subclause 168.4.3 of Clause 168.4 of Article 168 as amended by Law No. 4834-VI of 24.05.2012 }
168.4.4. a legal entity at its location and the location of separate subdivisions not authorized to pay tax, a separate subdivision authorized to calculate, withhold and pay (transfer) tax to the budget, at its location, simultaneously with the submission of documents for receiving funds for payment of income due to taxpayers, pays (transfers) the amounts of withheld tax to the relevant accounts opened in the bodies that carry out treasury services of budget funds at the location of separate subdivisions, and in cases provided for by this Code - at the location of land plots, land shares (shares), allocated or not allocated in kind (on the ground).
{Paragraph one of subparagraph 168.4.4 of paragraph 168.4 of Article 168 as amended by Law No. 2497-VIII of 10.07.2018 }
Bodies that carry out treasury servicing of budget funds in accordance with the procedure established by the Budget Code of Ukraine distribute the specified funds in accordance with the standards determined by the Budget Code of Ukraine and direct such distributed amounts to the relevant budgets.
Bodies that carry out treasury services for budget funds in accordance with the procedure established by the Budget Code of Ukraine distribute the specified funds in accordance with the standards determined by the Budget Code of Ukraine and direct such distributed amounts to the relevant budgets;
{Subclause 168.4.4 of Clause 168.4 of Article 168 as amended by Laws No. 4834-VI of 05.24.2012 , No. 5083-VI of 07.05.2012 }
168.4.5. an individual responsible in accordance with the requirements of this section for the assessment and withholding of tax shall pay (transfer) it to the relevant budget:
a) in the case when such an individual is a tax agent, - at the place of registration with the regulatory authorities, and in cases provided for by this Code, - at the location of land plots, land shares (shares), allocated or not allocated in kind (on the ground);
{Subparagraph "a" of subparagraph 168.4.5 of paragraph 168.4 of Article 168 as amended by Law No. 2497-VIII of 10.07.2018 }
b) in the case of notarization of property purchase and sale agreements by residents and non-residents, certification of gift agreements or issuance of certificates of inheritance rights to non-residents - at the place of notarization of such agreements (receipt of certificates);
{Subparagraph "b" of subparagraph 168.4.5 of paragraph 168.4 of Article 168 as amended by Law No. 3609-VI of 07.07.2011 }
c) in other cases - at its tax address, and in cases provided for by this Code - at the location of land plots, land shares (shares), allocated or not allocated in kind (on the ground);
{Subparagraph "c" of subparagraph 168.4.5 of paragraph 168.4 of Article 168 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 2497-VIII of 10.07.2018 }
{Subclause 168.4.6 of clause 168.4 of Article 168 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
168.4.7. Responsibility for the timely and full transfer of tax amounts to the relevant budget lies with the legal entity or its separate subdivision that calculates (pays) taxable income;
{Subclause 168.4.7 of Clause 168.4 of Article 168 as amended by Law No. 3609-VI of 07.07.2011 }
168.4.8. Responsibility for the timely and full transfer of tax amounts to the relevant budget lies with the individual in the cases specified in this section.
{Subclause 168.4.8 of Clause 168.4 of Article 168 as amended by Law No. 3609-VI of 07.07.2011 }
168.4.9. Tax amounts calculated by a tax agent or an individual who receives income from a person who is not a tax agent, from income from leasing (subleasing, emphyteusis) by individuals of land plots, land shares (shares), allocated or not allocated in kind (on the ground), shall be paid by such tax agent or such individual to the relevant budget at the location of such leased (subleasing, emphyteusis) objects.
{Clause 168.4 of Article 168 is supplemented by subparagraph 168.4.9 in accordance with the Law No. 2497-VIII dated 10.07.2018 ; as amended by Law No. 466-IX dated 16.01.2020 }
168.4.10. Tax amounts calculated by a tax agent from income from the sale of electricity generated from alternative energy sources by generating installations owned by individuals - taxpayers, shall be paid by such tax agent to the relevant budget at the location (location) of such generating installations.
{Clause 168.4 of Article 168 is supplemented by subparagraph 168.4.10 in accordance with Law No. 1914-IX of 30.11.2021 }
168.5. The amounts of personal income tax withheld from cash benefits, cash rewards and other payments received by military personnel, police officers, rank-and-file and command personnel of the State Penitentiary Service of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, the state fire service, civil defense bodies and units, the tax police, as well as family members, parents, and dependents of a deceased (deceased) military personnel determined by the Law of Ukraine "On Social and Legal Protection of Military Personnel and Members of Their Families" in connection with the performance of duties during service, shall be used exclusively to pay equivalent and full compensation for the loss of income of this category of citizens.
{Clause 168.5 of Article 168 as amended by Law No. 1797-VIII of 12/21/2016 , taking into account the amendments made by Law No. 1989-VIII of 03/23/2017 ; with amendments made in accordance with Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
Article 169. Tax recalculation and tax social benefits↑
169.1. List of tax and social benefits.
Taking into account the provisions of the first paragraph of subparagraph 169.4.1 of paragraph 169.4 of this article, the taxpayer has the right to reduce the amount of total monthly taxable income received from one employer in the form of wages by the amount of the tax social benefit:
169.1.1. in an amount equal to 50 percent of the subsistence minimum for an able-bodied person (per month), established by law as of January 1 of the reporting tax year, - for any taxpayer;
{Subclause 169.1.1 of Clause 169.1 of Article 169 as amended by Law No. 909-VIII of 24.12.2015 }
169.1.2. in an amount equal to 100 percent of the amount of the benefit determined by subparagraph 169.1.1 of this paragraph - for a taxpayer who supports two or more children under the age of 18 - calculated for each such child;
169.1.3. in the amount equal to 150 percent of the amount of the benefit determined by subparagraph 169.1.1 of this paragraph - for such a taxpayer who:
a) is a single mother (father), widow (widower) or guardian, custodian - for each child under the age of 18;
b) supports a child with a disability - calculated for each such child under the age of 18;
c) is a person classified by law as one of the first or second categories of persons affected by the Chernobyl disaster, including persons awarded certificates of the Presidium of the Supreme Soviet of the Ukrainian SSR in connection with their participation in the elimination of the consequences of the Chernobyl disaster;
d) is a student, graduate student, resident, adjunct;
e) is a person with a disability of group I or II, including since childhood, except for persons with disabilities whose benefit is determined by subparagraph "b" of subparagraph 169.1.4 of this paragraph;
e) is a person who has been awarded a lifetime scholarship as a citizen who has been persecuted for human rights activities, including journalists;
the Law of Ukraine "On the Status of War Veterans, Guarantees of Their Social Protection" applies , except for persons specified in subparagraph "b" of subparagraph 169.1.4 of this paragraph;
169.1.4. in the amount equal to 200 percent of the amount of the benefit determined by subparagraph 169.1.1 of this paragraph - for such a taxpayer who is:
a) Hero of Ukraine, Hero of the Soviet Union, Hero of Socialist Labor or full holder of the Order of Glory or the Order of Labor Glory, a person awarded four or more medals "For Courage";
b) a participant in hostilities during World War II or a person who worked in the rear at that time, and a person with disabilities of groups I and II, from among the participants in hostilities on the territory of other countries in the period after World War II, to whom the Law of Ukraine "On the Status of War Veterans, Guarantees of Their Social Protection" applies ;
c) a former prisoner of concentration camps, ghettos and other places of forced detention during World War II or a person recognized as repressed or rehabilitated;
d) a person who was forcibly deported from the territory of the former USSR during World War II to the territory of states that were at war with the former USSR or were occupied by fascist Germany and its allies;
e) a person who was in the blockaded territory of the former Leningrad (St. Petersburg, Russian Federation) between September 8, 1941 and January 27, 1944.
169.2. Choosing the place of receipt (application) of tax social benefits.
169.2.1. The tax social benefit is applied to the monthly income accrued to the taxpayer in the form of wages only at one place of its accrual (payment).
169.2.2. The taxpayer submits to the employer an application for independent selection of the place of application of the tax social benefit (hereinafter referred to as the application for the benefit).
The tax social benefit begins to be applied to accrued income in the form of wages from the date of receipt by the employer of the taxpayer's application for the benefit and documents confirming such right. The employer reflects in the tax reporting all cases of application or non-application of the tax social benefit in accordance with the applications for the benefit application received from taxpayers, as well as applications for refusal of such benefit.
The list of such documents and the procedure for their submission are determined by the Cabinet of Ministers of Ukraine.
169.2.3. The tax social benefit cannot be applied to:
the taxpayer's income other than wages;
salary that the taxpayer receives during the reporting tax month simultaneously with income in the form of a scholarship, monetary or property (material) support for pupils, students, postgraduate students, residents, adjuncts, and military personnel paid from the budget;
income of a self-employed person from conducting entrepreneurial activities, as well as other independent professional activities.
The tax social benefit to the salary of civil servants is applied during its accrual until the completion of accrual of such income without submitting the relevant applications specified in subparagraph 169.2.2 of this paragraph, but with the submission of supporting documents to establish the amount of the benefit.
169.2.4. If a taxpayer violates the provisions of this paragraph, as a result of which, in particular, the tax social benefit is also applied when receiving other income during any reporting tax month or for several places of income receipt, such taxpayer loses the right to receive the tax social benefit for all places of income receipt starting from the month in which such violation occurred and ending with the month in which the right to apply the tax social benefit is restored.
A taxpayer may restore the right to apply a tax social benefit if he submits an application for refusal of such benefit to all employers, indicating the month in which such violation occurred, on the basis of which each employer shall calculate and withhold the corresponding amount of tax underpayment and a penalty in the amount of 100 percent of the amount of this underpayment from the nearest payment of income to such taxpayer, and in the event that the amount of payment is insufficient, from the following payments. If the amount of underpayment and/or penalty was not withheld by the tax agent from the taxpayer's income, such amounts shall be included in the annual tax return of such taxpayer. In this case, the right to apply a tax social benefit shall be restored from the tax month following the month in which the amount of such underpayment and penalty are fully repaid.
The central executive body that ensures the formation and implementation of state financial policy shall also establish the procedure for informing the taxpayer's employers about the existence of violations by him of the norms of subparagraph 169.2.1 of this paragraph, identified on the basis of tax reporting data or documentary checks, as well as the procedure for informing the employer about the deprivation of the taxpayer or the restoration of his right to a tax social benefit.
{Paragraph three of subparagraph 169.2.4 of paragraph 169.2 of Article 169 as amended by Law No. 1797-VIII of 21.12.2016 }
169.3. Selection of the amount of tax social benefit and its validity period.
169.3.1. If a taxpayer is entitled to apply a tax social benefit on two or more grounds specified in clause 169.1 of this article, one tax social benefit shall be applied on the ground that provides for its largest amount, subject to compliance with the procedures specified in subparagraph 169.4.1 of clause 169.4 of this article, except for the case specified in subparagraph "b" of subparagraph 169.1.3 of clause 169.1 of this article, the tax social benefit under which is added to the benefit specified in subparagraph 169.1.2 of this clause if the person supports two or more children, including a disabled child (children with disabilities).
169.3.2. A taxpayer who has the right to apply a tax social benefit greater than that provided for in subparagraph 169.1.1 of paragraph 169.1 of this Article shall indicate such right in the application for the benefit, to which he shall attach the relevant supporting documents.
169.3.3. The tax social benefit provided for in subparagraph 169.1.2 and subparagraphs "a" , "b" of subparagraph 169.1.3 of clause 169.1 of this article shall be granted until the end of the year in which the child reaches the age of 18, and in the event of his death before reaching the specified age - until the end of the year in which the death occurs. The right to receive such a tax social benefit shall be lost in the event of the deprivation of the taxpayer of parental rights or if he abandons the child or transfers the child to state maintenance, including in institutions for orphans and children deprived of parental care, regardless of whether a fee is charged for such maintenance or not, and also if the child becomes a cadet on the terms of its full maintenance, starting from the tax month in which such an event occurred.
The provision of the tax social benefit provided for in subparagraphs "c" - "e" of subparagraph 169.1.3 and subparagraph 169.1.4 of subparagraph 169.1 of this Article shall be suspended from the tax month following the month in which the taxpayer lost or was deprived of the status specified in these subparagraphs.
{Paragraph two of subparagraph 169.3.3 of paragraph 169.3 of Article 169 as amended by Law No. 4108-IX of 03.12.2024 }
169.3.4. The tax social benefit is granted taking into account the last monthly tax period in which the taxpayer died or was declared dead by a court or was recognized as missing by a court, or lost resident status, or was dismissed from his place of employment.
169.4. Tax recalculation, recalculation and limitation of tax social benefits.
169.4.1. The tax social benefit applies to income accrued to the taxpayer during the reporting tax month as wages (other payments, compensations and rewards equated to it in accordance with the legislation), if its amount does not exceed the amount equal to the monthly subsistence minimum in force for an able-bodied person on January 1 of the reporting tax year, multiplied by 1.4 and rounded to the nearest 10 hryvnias.
At the same time, the maximum amount of income that entitles one of the parents to receive a tax social benefit in the case and in the amount provided for in subparagraph 169.1.2 and subparagraphs "a" and "b" of subparagraph 169.1.3 of paragraph 169.1 of this article is determined as the product of the amount specified in the first paragraph of this subparagraph and the corresponding number of children.
{Paragraph two of subparagraph 169.4.1 of paragraph 169.4 of Article 169 as amended by Law No. 3609-VI of 07.07.2011 }
If a taxpayer receives income in the form of wages for the period of its retention in accordance with the legislation, including during vacation or sick leave, then for the purpose of determining the maximum amount of income that gives the right to receive a tax social benefit, and in other cases of their taxation, such income (part thereof) is attributed to the relevant tax periods of their accrual.
169.4.2. The employer of a taxpayer is obliged to recalculate, including at the place of application of the tax social benefit, the amount of income accrued to such taxpayer in the form of wages, as well as the amount of the tax social benefit provided:
{Paragraph one of subparagraph 169.4.2 of paragraph 169.4 of Article 169 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.24.2012 , No. 466-IX of 01.16.2020 }
a) following the results of each reporting tax year during the calculation of wages for the last month of the reporting year;
b) during the calculation for the last month of application of the tax social benefit in the event of a change in the place of its application by the taxpayer's independent decision or in the cases specified in subparagraph 169.2.3 of paragraph 169.2 of this article;
c) during the final settlement with the taxpayer who terminates employment relations with such employer.
169.4.3. The employer and/or tax agent has the right to recalculate the amounts of accrued income and withheld tax for any period and in any cases to determine the correctness of taxation, regardless of whether the taxpayer is entitled to apply a tax social benefit.
169.4.4. If as a result of the recalculation, an underpayment of withheld tax occurs, the amount of such underpayment shall be collected by the employer at the expense of any taxable income (after taxation) for the relevant month, and in the event of insufficient amount of such income - at the expense of taxable income of the following months, until the amount of such underpayment is fully repaid.
If, as a result of the final settlement with a taxpayer who terminates employment with the employer, an underpayment arises that exceeds the amount of the taxpayer's taxable income for the last reporting period, the outstanding portion of such underpayment is included in the taxpayer's tax liability for the reporting tax year and is paid by the taxpayer himself.
Article 170. Peculiarities of accrual (payment) and taxation of certain types of income↑
170.1. Taxation of income from leasing real estate (sublease, emphyteusis), residential rental (sublease).
{Title of Clause 170.1 of Article 170 as amended by the Law No. 2497-VIII dated 10.07.2018 }
170.1.1. The tax agent of the taxpayer - lessor with respect to his income from the lease (emphyteusis) of a land plot for agricultural purposes, a land share (share), or a property share is the lessee.
{Paragraph one of subparagraph 170.1.1 of paragraph 170.1 of Article 170 as amended by the Law No. 2497-VIII dated 10.07.2018 }
In this case, the object of taxation is determined based on the amount of rent specified in the lease agreement, but not less than the minimum amount of rent established by the legislation on land lease.
170.1.2. The tax agent of the taxpayer - lessor when calculating income from the lease of real estate objects other than those specified in subparagraph 170.1.1 of this paragraph (including the land plot located under such real estate or a personal plot) is the lessee.
In this case, the object of taxation is determined based on the amount of rent specified in the lease agreement, but not less than the minimum amount of rent for a full or incomplete month of rent. The minimum amount of rent is determined according to the methodology approved by the Cabinet of Ministers of Ukraine, based on the minimum cost of monthly rent of one square meter of total area of real estate, taking into account its location, other functional and qualitative indicators established by the local government body of the village, town, city on the territory of which it is located, and published in the manner most accessible to residents of such territorial community. If the minimum cost is not established or not published before the beginning of the reporting (tax) year, the object of taxation is determined based on the amount of rent specified in the lease agreement.
{Paragraph two of subparagraph 170.1.2 of paragraph 170.1 of Article 170 as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2330-IX dated 06/21/2022 }
170.1.3. Real estate owned by a non-resident individual shall be leased exclusively through a resident individual entrepreneur or legal entity (authorized persons) who perform representative functions of such non-resident on the basis of a written agreement and act as his tax agent with respect to such income. A non-resident who violates the provisions of this paragraph shall be considered to be evading tax.
170.1.4. Income specified in subparagraphs 170.1.1-170.1.3 of this paragraph shall be taxed by the tax agent at the time of their accrual (payment) at the rate determined by subparagraph 167.1 of Article 167 of this Code.
{Subclause 170.1.4 of Clause 170.1 of Article 170 as amended by Laws No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 }
170.1.5. If the tenant is an individual who is not a self-employed person, the person responsible for the calculation and payment (transfer) of tax to the budget is the tax payer - the landlord.
{Paragraph one of subparagraph 170.1.5 of paragraph 170.1 of Article 170 as amended by Law No. 466-IX of 16.01.2020 }
At the same time:
a) such a lessor independently calculates and pays tax to the budget within the terms established by this Code for the quarterly reporting (tax) period, namely: within 40 calendar days after the last day of such reporting (tax) quarter, the amount of income received, the amount of tax paid during the reporting tax year and the tax liability based on the results of such year are reflected in the annual tax return;
b) in the event of a notarial action to certify a lease agreement for real estate, the notary is obliged to send information about such an agreement to the supervisory authority at the tax address of the taxpayer - lessor in the form and manner established by the Cabinet of Ministers of Ukraine. For violation of the procedure and/or deadlines for submitting the specified information, the notary shall bear the responsibility provided for in Article 119 - 1 of this Code;
{Subparagraph "b" of subparagraph 170.1.5 of paragraph 170.1 of Article 170 as amended by Law No. 466-IX of January 16, 2020 }
170.1.6. business entities that carry out intermediary activities related to the provision of real estate rental services (realtors) are obliged to send information about civil law contracts (agreements) for real estate rental concluded through their mediation to the regulatory authority at the place of their registration within the deadlines provided for submitting a tax calculation, in the form established by the central executive authority that ensures the formation and implementation of state financial policy.
{Paragraph one of subparagraph 170.1.6 of paragraph 170.1 of Article 170 as amended by Law No. 1797-VIII of 21.12.2016 }
, the realtor shall be liable as provided for in Article 119-1 of this Code.
{Paragraph two of subparagraph 170.1.6 of paragraph 170.1 of Article 170 as amended by Law No. 466-IX of January 16, 2020 }
170.2. Taxation of investment income.
170.2.1. The total financial result of operations with investment assets shall be kept by the taxpayer independently, separately from other income and expenses. For the purposes of taxation of investment income, the reporting period shall be the calendar year, based on the results of which the taxpayer is obliged to submit an annual tax return , in which the total financial result (investment profit or investment loss) obtained during such reporting year shall be reflected.
{Subclause 170.2.1 of Clause 170.2 of Article 170 as amended by Law No. 1797-VIII of 21.12.2016 }
170.2.2. Investment profit is calculated as the positive difference between the income received by the taxpayer from the sale of a separate investment asset, taking into account the exchange rate difference (if any), and its value, which is determined from the amount of documented expenses for the acquisition of such an asset or the value of the investment asset that was declared by the person as an object of declaration under the procedure of one-time (special) voluntary declaration in accordance with Subsection 9 - 4 of Section XX of this Code, taking into account the norms of Subsections 170.2.4-170.2.6 of this paragraph (except for transactions with derivatives).
{Paragraph one of subparagraph 170.2.2 of paragraph 170.2 of Article 170 as amended by Laws No. 3609-VI of 07.07.2011 , No. 1797-VIII of 21.12.2016 , No. 1914-IX of 30.11.2021 }
When a taxpayer applies the provisions of subparagraph 170.2.9 of this paragraph, a tax agent - a professional securities trader, including a bank, in order to determine the object of taxation when paying the taxpayer income tax for investment assets purchased from him, takes into account the documented expenses of such taxpayer for the purchase of these assets.
{Paragraph three of subparagraph 170.2.2 of paragraph 170.2 of Article 170 was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
The introduction of the tax agent obligation for a professional securities trader, including a bank, does not exempt the taxpayer from the obligation to declare the results of all transactions on the purchase and sale of investment assets carried out during the reporting (tax) year both in the territory of Ukraine and abroad, except for the cases specified in subparagraph 170.2.8 of this paragraph.
The following transactions are also considered to be the sale of an investment asset:
exchange of an investment asset for another investment asset;
repurchase or redemption of an investment asset by its issuer that belonged to the taxpayer;
{Paragraph seven of subparagraph 170.2.2 of paragraph 170.2 of Article 170 as amended by Law No. 4834-VI of 24.05.2012 }
return to the taxpayer of funds or property (property rights) previously contributed by him (or by the person from whom the investment asset was purchased directly or indirectly) to the authorized capital of the issuer of corporate rights, in the event of such taxpayer's withdrawal from the number of founders (participants) of such issuer, reduction of the authorized capital of such issuer or liquidation of such issuer.
{Paragraph eight of subparagraph 170.2.2 of paragraph 170.2 of Article 170 as amended by Law No. 466-IX of January 16, 2020 }
Transactions involving the taxpayer's contribution of funds or property to the authorized capital of a resident legal entity in exchange for corporate rights issued by it are also considered to be the acquisition of an investment asset.
An investment asset gifted to a taxpayer or inherited by a taxpayer is considered to be acquired at a cost equal to the amount of state duty and personal income tax paid in connection with such gift or inheritance.
Investment profit on derivatives transactions is calculated as the positive difference between the income received by the taxpayer on derivatives transactions (derivatives), including the amounts received for periodic or one-time payments provided for in the terms of contracts (agreements), and the documented amount paid by the taxpayer to the other party to such a contract (agreement) with derivatives (derivatives), including the amounts paid for periodic or one-time payments provided for in the terms of the contract (agreement).
{Subclause 170.2.2 of clause 170.2 of Article 170 is supplemented by a paragraph in accordance with Law No. 3609-VI of 07.07.2011 }
Documentary confirmation (primary document) of income and expenses on transactions with investment assets concluded in electronic form on the stock exchange for clients - participants of the stock exchange is recognized as a report of a securities trader (broker), which is formed on the basis of an exchange report and a brokerage service agreement.
{Subclause 170.2.2 of clause 170.2 of Article 170 is supplemented by a paragraph in accordance with Law No. 3609-VI of 07.07.2011 }
In the event of a taxpayer selling or purchasing investment assets to/from non-residents - related persons or non-residents registered in states (territories) included in the list of states (territories) approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph 39.2.1.2 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code, income and expenses for such transactions are determined:
{ Subparagraph 170.2.2 of paragraph 170.2 of Article 170 is supplemented by the thirteenth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
in an amount not lower than the normal price in the event of the sale of an investment asset by the taxpayer;
{ Subparagraph 170.2.2 of paragraph 170.2 of Article 170 is supplemented by the fourteenth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
in an amount not exceeding the normal price in the event of the taxpayer's purchase of an investment asset.
{ Subparagraph 170.2.2 of paragraph 170.2 of Article 170 is supplemented by the fifteenth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
The provisions of paragraphs thirteen to fifteen of this subparagraph shall not apply if the buyer of the investment asset is a directly or indirectly controlled foreign company in which the seller of the investment asset is the controlling entity and which remains the owner of the specified investment asset as of the end of the reporting period in which the alienation of the investment asset occurred.
{ Subparagraph 170.2.2 of paragraph 170.2 of Article 170 is supplemented by the sixteenth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
170.2.3. If the calculation of investment profit according to the rules established by this article results in a negative value, it shall be considered an investment loss.
170.2.4. If, within 30 calendar days prior to the date of sale of a package of securities (corporate rights) or derivatives, as well as within the next 30 calendar days from the date of such sale, the taxpayer acquires a package of identical securities (corporate rights) or derivatives, then:
a) the investment loss arising from such sale shall not be taken into account when determining the overall financial result of operations with investment assets;
b) the value of the purchased package for tax purposes is determined by its purchase price, but not lower than the price of the sold package.
170.2.5. If a taxpayer sells an investment asset during the reporting (tax) year under a contract that stipulates the right to repurchase it in the following year, or purchases an option for such repurchase, the investment loss arising from such sale shall not be taken into account when determining the overall financial result of transactions with investment assets.
If a taxpayer who sells an investment asset during a reporting (tax) year, resulting in an investment loss, acquires such an investment asset or an identical package in the following reporting (tax) year, then for tax purposes the value of such purchased package is determined at the price of the sold package, increased or decreased by the difference between the purchase prices of such two packages.
If a taxpayer sells a package of securities (corporate rights) or derivatives to persons related to him, the investment loss arising from such sale is not taken into account when determining the overall financial result of transactions with investment assets.
If a taxpayer donates or bequeaths an investment asset, the investment loss resulting from such donation or bequest is not taken into account when determining the overall financial result of transactions with investment assets.
170.2.6. The total annual taxable income of a taxpayer shall include the positive value of the total financial result of transactions with investment assets as a result of such a reporting (tax) year.
The total financial result of transactions with investment assets is defined as the amount of investment profits received by the taxpayer during the reporting (tax) year, reduced by the amount of investment losses incurred by the taxpayer during such year.
If the total financial result of operations with investment assets is negative, its amount is carried forward to reduce the total financial result of operations with investment assets in subsequent years until it is fully repaid.
{Paragraph three of subparagraph 170.2.6 of paragraph 170.2 of Article 170 as amended by Law No. 5519-VI of 06.12.2012 }
The financial result from transactions with securities or derivatives is determined by the taxpayer. In this case, the taxpayer determines the financial result from transactions with securities or derivatives traded on the stock exchange separately from the financial result from transactions with securities or derivatives not traded on the stock exchange.
{Paragraph four of subparagraph 170.2.6 of paragraph 170.2 of Article 170 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 5519-VI of 06.12.2012 }
{ Paragraph five of subparagraph 170.2.6 of paragraph 170.2 of Article 170 is excluded on the basis of the Law No. 1797-VIII dated 21.12.2016 }
{Paragraph six of subparagraph 170.2.6 of paragraph 170.2 of Article 170 was excluded on the basis of Law No. 5519-VI of 06.12.2012 }
{Paragraph seven of subparagraph 170.2.6 of paragraph 170.2 of Article 170 was excluded on the basis of Law No. 5519-VI of 06.12.2012 }
{Paragraph eight of subparagraph 170.2.6 of paragraph 170.2 of Article 170 was excluded on the basis of Law No. 5519-VI of 06.12.2012 }
For the purposes of this paragraph, national legislation means the legislation of the state on whose territory securities or derivatives are traded (conclusion of civil law agreements entailing the transfer of ownership of securities or derivatives).
The effect of subparagraphs 170.2.4 and 170.2.5 does not apply to the purchase or sale of securities and derivatives traded on a stock exchange, as well as in the case of:
acquisition or sale of a block of shares exceeding 25 percent of the issuer's authorized capital;
redemption of shares by the issuer, including at the request of the shareholder;
acquisition of securities in the process of their private placement;
purchase or sale of securities that, according to legal requirements, cannot be traded on the stock exchange.
If during the reporting period the taxpayer incurred (accrued) expenses related to the acquisition of securities and derivatives, the issuers of which at the time of conclusion of the relevant contract were included by the National Securities and Stock Market Commission in the list of issuers that have signs of fictitiousness, such expenses are not taken into account when determining the financial result of transactions with securities or derivatives.
{Paragraph fifteen of subparagraph 170.2.6 of paragraph 170.2 of Article 170 as amended by Law No. 3610-VI of 07.07.2011 ; as amended by the Law No. 466-IX dated 16.01.2020 }
170.2.7. For the purposes of this clause:
a) the term "investment asset" means a package of securities, derivatives or corporate rights expressed in forms other than securities, issued by a single issuer;
{Subparagraph "a" of subparagraph 170.2.7 of paragraph 170.2 of Article 170 as amended by Law No. 3609-VI of 07.07.2011 }
b) the term "package of securities" means a separate security, a stock and commodity derivative, as well as a collection of identical securities or stock and commodity derivatives;
c) the term "identical security or derivative" means securities or derivatives issued by the same issuer under identical terms of issue, payment of income, redemption or repayment.
170.2.8. The following are not subject to taxation and are not included in the total annual taxable income:
a) income received by the taxpayer during the reporting tax year from the sale of investment assets, if the amount of such income does not exceed the amount specified in paragraph one of subparagraph 169.4.1 of clause 169.4 of Article 169 of this Code;
b) income received by the taxpayer from the sale of investment assets in the case specified in subparagraphs 165.1.40 and 165.1.52 of paragraph 165.1 of Article 165 of this Code.
{Subparagraph "b" of subparagraph 170.2.8 of paragraph 170.2 of Article 170 as amended by Law No. 4834-VI of 24.05.2012 }
In the cases specified in subparagraphs "a" and "b" of this subparagraph, the taxpayer shall not include in the calculation of the total financial result of transactions with investment assets the amount of income and expenses for the acquisition of such investment assets.
170.2.9. The tax agent of a taxpayer who carries out transactions with investment assets using the services of a professional securities trader, including a bank, is such a professional trader. The tax agent, during each accrual of investment income to the taxpayer, shall calculate (withhold) tax at the rate determined by subparagraph 167.5.1 of paragraph 167.5 of Article 167 of this Code, and shall pay (transfer) the withheld tax to the budget during each accrual of such income, which does not exempt the taxpayer from filing an annual tax return upon receipt of the income specified in this paragraph.
{Paragraph one of subparagraph 170.2.9 of paragraph 170.2 of Article 170 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1588-VII of 04.07.2014 }
The methodology for determining investment income by a professional securities trader when performing the functions of a tax agent is established by the central executive body that ensures the formation and implementation of state financial policy together with the National Securities and Stock Market Commission.
{Paragraph two of subparagraph 170.2.9 of paragraph 170.2 of Article 170 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 }
{Subclause 170.2.9 of Clause 170.2 of Article 170 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 2628-VIII of 23.11.2018 }
170.3. Taxation of royalties.
170.3.1. Royalties are taxed according to the rules established for the taxation of dividends, at the rate determined by subparagraph 167.5.1 of paragraph 167.5 of Article 167 of this Code.
{Subclause 170.3.1 of Clause 170.3 of Article 170 as amended by Law No. 71-VIII of 28.12.2014 }
170.4. Taxation of interest.
170.4.1. The tax agent of the taxpayer during the accrual of income in the form of interest in his favor is the person who carries out such accrual.
The tax agent shall pay (transfer) to the budget, within the terms specified by this Code for the monthly tax period, the total amount of tax accrued at the rate specified in Clause 167.1 of Article 167 of this Code, from the total amount of interest accrued for the tax (reporting) month on the amounts of bank deposit (deposit) or current accounts, savings (deposit) certificates, and deposits (deposits) of members of a credit union in a credit union.
{Paragraph two of subparagraph 170.4.1 of paragraph 170.4 of Article 170 as amended by Law No. 909-VIII of 24.12.2015 }
The income specified in this subparagraph is finally taxed by the tax agent at the time of its accrual.
170.4.2. Tax agents (banks, credit unions) that accrue income in the form of interest specified in subparagraph 170.4.1 of this paragraph shall, in the tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code, reflect the total amount of income accrued in the reporting tax period and the total amount of tax withheld from it. In this case, the tax calculation shall not indicate information about the amounts of a separate bank deposit (deposit) or current account, savings (deposit) certificate, deposit (deposit) of a credit union member in a credit union, the amount of accrued interest, as well as information about the individual taxpayer to whom such income was accrued.
170.4.3. Taxation of interest and discount income accrued to individuals from any income other than that specified in subparagraph 170.4.1 of this paragraph shall be carried out in accordance with the general procedure established by this Code for income that is finally taxed at the time of its accrual, at the rate determined by subparagraph 167.1 of Article 167 of this Code.
{Subclause 170.4.3 of Clause 170.4 of Article 170 as amended by Laws No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 }
170.4.4. In the event of early termination of a deposit agreement and the recalculation of income in the form of interest at the interest rate provided for in the terms of the agreement for such cases, the tax agent shall recalculate the amounts of tax withheld from such income.
Refund of excess withheld tax amounts resulting from the recalculation carried out in accordance with the first paragraph of this subparagraph shall be carried out by reducing the tax amounts subject to recalculation by the tax agent for the current and/or next tax (reporting) month.
{Clause 170.4 of Article 170 as amended by Law No. 1166-VII of March 27, 2014 ; as amended by Law No. 1588-VII of July 4, 2014 }
170.5. Taxation of dividends.
170.5.1. The tax agent of the taxpayer during the accrual of dividends in his favor, except for the cases specified in subparagraph 165.1.18 of paragraph 165.1 of Article 165 of this Code, is the issuer of corporate rights or, on his behalf, another person who carries out such accrual.
170.5.2. Any resident who accrues dividends, including one who pays corporate income tax in a manner other than the general one (is subject to a simplified taxation system), or is exempt from paying such tax for any reason, is a tax agent when accruing dividends.
170.5.3. Dividends accrued to a taxpayer on shares or other corporate rights that have the status of preferred shares or another status that provides for the payment of a fixed amount of dividends or an amount exceeding the amount of payments calculated on any other share (corporate right) issued by such taxpayer in accordance with subparagraph 57.1 - 1.4 of paragraph 57.1 - 1 of Article 57 of this Code, for taxation purposes, are equated to the payment of wages with appropriate taxation.
{Subclause 170.5.3 of Clause 170.5 of Article 170 as amended by Law No. 466-IX of 01/16/2020 ; as amended by Law No. 786-IX of 07/14/2020 }
170.5.4. The income specified in this paragraph shall be finally taxed by the tax agent when it is credited to the taxpayer at the rate determined by subparagraphs 167.5.1 , 167.5.2 and 167.5.4 of paragraph 167.5 of Article 167 of this Code.
{Subclause 170.5.4 of clause 170.5 of Article 170 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 466-IX of 01/16/2020 }
170.5.5. Dividends accrued in his favor by an issuer of corporate rights who is a resident of Diya City - a taxpayer under special conditions shall not be included in the calculation of the total monthly (annual) taxable income of a taxpayer, provided that such resident of Diya City - a taxpayer under special conditions has not paid dividends on shares or other corporate rights for two consecutive calendar years.
{Clause 170.5 of Article 170 is supplemented by subparagraph 170.5.5 in accordance with Law No. 1946-IX of 14.12.2021 }
{Clause 170.5 of Article 170 as amended by Law No. 1166-VII of March 27, 2014 ; as amended by Law No. 1588-VII of July 4, 2014 }
170.6. Taxation of winnings and prizes
170.6.1. The tax agent of the taxpayer during the accrual (payment, provision) in his favor of income in the form of winnings (prizes) in the lottery or other draws, in bookmaker bets, in totalizer bets, prizes and winnings in cash received for winning and/or participating in amateur sports competitions, including billiard sports, is the person who carries out such accrual (payment).
170.6.2. The tax agent - lottery operator, within the terms specified by this Code for the monthly tax period, shall pay (transfer) to the budget the total amount of tax charged at the rate specified in Clause 167.1 of Article 167 of this Code, from the total amount of winnings (prizes) paid to lottery players for the tax (reporting) month.
Tax agents - lottery operators in the tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code, reflect the total amount of income accrued (paid) in the reporting tax period in the form of winnings (prizes) and the total amount of tax withheld from them. At the same time, the tax calculation does not indicate information about the amounts of individual winnings, the amount of tax accrued on them, as well as information about the individual taxpayer who received income in the form of winnings (prizes).
{Subclause 170.6.2 of Clause 170.6 of Article 170 as amended by Law No. 909-VIII of 24.12.2015 }
170.6.3. Taxation of income in the form of winnings and prizes, other than winnings (prizes) in a lottery, shall be carried out in accordance with the general procedure established by this Code for income that is finally taxed at the time of its accrual, at the rate specified in the first paragraph of paragraph 167.1 of Article 167 of this Code.
170.6.4. When calculating (paying) income in the form of winnings in a lottery or other draws that require the taxpayer to previously purchase the right to participate in such lotteries or draws, the taxpayer's expenses in connection with obtaining such income are not taken into account.
170.6.5. The income specified in this paragraph shall be finally taxed at the time of its payment at their expense.
{Clause 170.6 of Article 170 as amended by Law No. 71-VIII of 28.12.2014 }
170.7. Taxation of charitable assistance.
170.7.1. Charitable, including humanitarian, aid (hereinafter referred to as charitable aid) received in the form of funds or property (free work performed, services provided) and meeting the requirements specified in this paragraph shall not be taxed and shall not be included in the total monthly or annual taxable income of a taxpayer.
For tax purposes, charitable assistance is divided into targeted and non-targeted.
Targeted is charitable assistance provided under certain conditions and directions of its spending, and non-targeted is assistance provided without establishing such conditions or directions;
170.7.2. Targeted or non-targeted charitable assistance provided to a taxpayer who has suffered as a result of:
a) ecological, man-made and other disasters in areas declared in accordance with the Constitution of Ukraine as zones of ecological emergency - within the limits determined by the Cabinet of Ministers of Ukraine;
b) natural disasters, accidents, epidemics and epizootics of a national or local nature that have caused harm or pose a threat to the health of citizens, the natural environment, caused or may cause human casualties or loss of property of citizens, in connection with which the decision to attract (provide) charitable assistance was made by the Cabinet of Ministers of Ukraine or a local self-government body, respectively, in the maximum amounts determined by the Cabinet of Ministers of Ukraine or a local self-government body, respectively;
c) armed aggression of the Russian Federation during the period of the legal regime of martial law or a state of emergency;
{Sub -clause 170.7.2 of clause 170.7 of Article 170 is supplemented by subparagraph "c" in accordance with Law No. 2120-IX of March 15, 2022 }
Charitable assistance provided for the above purposes must be distributed through the state or local budget or through charitable organizations, the Ukrainian Red Cross Society, included in the Register of Non-Profit Organizations and Institutions.
{Paragraph five of subparagraph 170.7.2 of paragraph 170.7 of Article 170 as amended by the Law No. 4254-IX dated 25.02.2025 }
This subparagraph applies to charitable assistance provided in a form other than cash, for the restoration of lost property, for housing, social and household needs and for other needs according to the list determined by the Cabinet of Ministers of Ukraine in accordance with subparagraph "b" of subparagraph 170.7.8 of paragraph 170.8 of Article 170 of this Code.
{Paragraph of subparagraph 170.7.2 of paragraph 170.7 of Article 170 as amended by the Law No. 4254-IX dated 25.02.2025 }
For the purposes of this subparagraph, a trade union payment made pursuant to a trade union decision adopted in accordance with the established procedure in favor of a member of such trade union who has the status of a victim as a result of the circumstances specified in this subparagraph shall be considered targeted charitable assistance and shall not be subject to taxation.
The procedure for confirming the status of persons who suffered as a result of the armed aggression of the Russian Federation against Ukraine during the period of the legal regime of martial law or a state of emergency, for the purpose of excluding from the taxable income of individuals - taxpayers income received in the form of targeted or non-targeted charitable assistance, is determined by the Cabinet of Ministers of Ukraine.
{Sub -clause 170.7.2 of clause 170.7 of Article 170 is supplemented by a paragraph in accordance with the Law No. 2520-IX dated 15.08.2022 }
170.7.3. The amount of non-targeted charitable assistance, including material assistance, provided by residents - legal entities or individuals in favor of the taxpayer during the reporting tax year in the aggregate amount not exceeding the amount of the income limit determined in accordance with paragraph one of subparagraph 169.4.1 of paragraph 169.4 of Article 169 of this Code, established as of January 1 of such year, is not included in taxable income.
The provisions of this subparagraph do not apply to trade union payments to their members, the conditions for exemption from taxation of which are provided for in subparagraph 165.1.47 of paragraph 165.1 of Article 165 of this Code.
A philanthropist - a legal entity - records information about the amounts of non-targeted charitable assistance provided in tax reporting.
In the event of receiving non-targeted charitable assistance from a benefactor - an individual or legal entity, the taxpayer is obliged to submit an annual tax return indicating its amount, if the total amount of non-targeted charitable assistance received during the reporting tax year exceeds its limit established by the first paragraph of subparagraph 169.4.1 of paragraph 169.4 of Article 169 of this Code.
170.7.4. Targeted charitable assistance provided by residents - legal entities or individuals - in any amount (value) is not included in taxable income:
a) a healthcare institution to compensate for the cost of paid services for the treatment of a taxpayer or a member of his or her first-degree relative, a person with a disability, a child with a disability or a child in which at least one parent is a person with a disability; an orphan, a half-orphan; a child from a large or low-income family; a child whose parents are deprived of parental rights, including for the purchase of medicines (donor components, prosthetic and orthopedic products, medical products for individual use by persons with disabilities) in amounts not covered by payments from the compulsory state social health insurance fund, except for expenses for cosmetic treatment or cosmetic surgery (including cosmetic prosthetics not related to medical indications), hydrotherapy and heliotherapy not related to chronic diseases, treatment and prosthetics of teeth using precious metals, electroplating and porcelain, abortions (except for abortions performed for medical indications or if the pregnancy was the result of rape), sex reassignment surgery; treatment of sexually transmitted diseases (except for AIDS and sexually transmitted diseases caused by non-sexual infection or rape), treatment of tobacco or alcohol addiction; purchase of medicines, medical devices and appliances that are not included in the list of essential goods approved by the Cabinet of Ministers of Ukraine;
prosthetic and orthopedic enterprises, rehabilitation institutions to compensate for the cost of paid rehabilitation services, technical and other rehabilitation facilities provided to a taxpayer recognized in accordance with the established procedure as a person with a disability, or his child with a disability, in amounts that do not overlap with payments from budgets and the compulsory state social medical insurance fund;
b) a children's home, an orphanage, a general education boarding school, a specialized boarding school, a special boarding school, an educational and rehabilitation center, a school of social rehabilitation and a vocational school of social rehabilitation of educational institutions, a center for medical and social rehabilitation of children of health care institutions, a reception and distribution center for children of the National Police of Ukraine, a special educational institution of the State Penitentiary Service of Ukraine, a shelter for children of the Children's Service, a center for social and psychological rehabilitation of children, a social rehabilitation center (children's town), a small group home for the distribution of charitable assistance among children or the use of such charitable assistance in another way in the interests of children staying in these institutions.
{Subparagraph "b" of subparagraph 170.7.4 of paragraph 170.7 of Article 170 as amended by Law No. 1293-IX of March 2, 2021 ; as amended by Law No. 3325-IX of August 10, 2023 }
Adoptive families, family-type orphanages, foster families, guardians (custodians) of children, single-parent families, large families for the distribution of charitable assistance between children or the use of such charitable assistance in another way in the interests of children living in these families;
{Paragraph of subparagraph 170.7.4 of paragraph 170.7 of Article 170 as amended by Law No. 3325-IX of 10.08.2023 }
c) a state or municipal institution or charitable organization, including the Ukrainian Red Cross Society, that provides services to homeless persons, including food and accommodation for the night;
d) a penitentiary institution to improve the conditions of detention, nutrition or medical care of persons held in remand prisons or places of deprivation of liberty, or directly to such persons;
e) a boarding house for elderly citizens and persons with disabilities and their department, a boarding house for war and labor veterans, a geriatric boarding house to improve the conditions of their maintenance, nutrition, medical care, social rehabilitation, a rehabilitation center, a territorial center for social services (provision of social services), registration centers and social protection institutions for homeless persons, centers for social adaptation of persons released from places of deprivation of liberty, sanatoriums for veterans and persons with disabilities, which are maintained at the expense of state and local budgets, for the distribution of charitable assistance among persons staying in such institutions;
{Sub-paragraph "g" of subparagraph 170.7.4 of paragraph 170.7 of Article 170 as amended by Law No. 4834-VI of 24.05.2012 }
e) to a taxpayer conducting scientific research or development, to reimburse the cost of equipment, materials, and other expenses (except for wages, fringe benefits, and other expenses for personal needs), provided that the results of such research or development are made public and cannot be subject to patenting or other restrictions on the publication or free distribution of intellectual (industrial) property rights obtained as a result of such research or development, and also if receiving such assistance will not be a prerequisite for the emergence of any contractual obligations between the benefactor or a third party and the recipient of charitable assistance in the future, except for obligations for the targeted use of such charitable assistance;
e) to an amateur sports organization or club to compensate for the costs of purchasing or renting sports equipment and supplies, using sports grounds, premises or structures for training, ensuring the participation of an amateur athlete in sports competitions, purchasing sports uniforms and meals during such competitions.
The term "amateur sports organization, club" means a public organization whose activities are not aimed at generating income.
The term "amateur athlete" means a person whose sports activities are not aimed at generating income, with the exception of receiving awards or rewards on behalf of the state, local governments or public organizations of both Ukraine and other states in the form of medals, diplomas, commemorative prizes in non-monetary form, as well as the amount of reimbursement of expenses related to the travel of such an amateur athlete to the venue of the competition, within the limits established by law for the travel of an employee;
g) to an educational institution in the form of tuition fees or for the provision of additional educational services for a person with a disability, a child with a disability or a child with at least one parent who is a person with a disability; an orphan, half-orphan; a child from a large or low-income family; a child whose parents are deprived of parental rights;
g) a taxpayer recognized in accordance with the established procedure as a person with a disability, a legal representative of a child with a disability to fulfill the obligations of the state in accordance with the legislation of Ukraine to provide technical and other means of rehabilitation, medical products, a car at the expense of budget funds (provided that the person with a disability, a child with a disability is removed from the register for provision with such means, products, a car at the expense of budget funds). The categories of persons with disabilities and children with disabilities, the list of technical and other means of rehabilitation, medical products, and car brands specified in this subparagraph are approved by law.
Prior to the introduction of the system of mandatory state social health insurance, the provisions of subparagraph "a" of this subparagraph shall apply to the total amount (value) of charitable assistance received by the recipient for such purposes (taking into account the restrictions specified in this subparagraph).
Charitable assistance received by an adoptive family, a family-type orphanage, a foster family, a guardian (trustee) of a child, a single-parent family, a large family is exempt from taxation if its total amount (value) during the reporting tax year does not exceed three hundred thousand hryvnias.
{Paragraph sixteen of subparagraph 170.7.4 of paragraph 170.7 of Article 170 as amended by Law No. 3325-IX of 10.08.2023 }
170.7.5. The recipient of targeted charitable assistance in the form of funds has the right to use it within the period established by the terms of such assistance, but not more than 12 calendar months following the month of receipt of such assistance, except for assistance provided for treatment, the right to use which is no more than 24 calendar months following the month of receipt of such assistance, with the exception of receiving charitable assistance in the form of an endowment. If targeted charitable assistance in the form of funds is not used by its recipient within such period and is not returned to the benefactor before its expiration, such recipient is obliged to include the unused amount of such assistance in the total annual taxable income and pay the appropriate tax.
{Paragraph one of subparagraph 170.7.5 of paragraph 170.7 of Article 170 as amended by Law No. 1797-VIII of 21.12.2016 }
The term "endowment" means an amount of funds or securities deposited by a benefactor in a bank or non-bank financial institution, whereby the recipient of the charitable assistance receives the right to use the interest or dividends accrued on the amount of such endowment. In this case, such recipient does not have the right to spend or alienate the principal amount of such endowment without the consent of the benefactor.
170.7.6. The recipient of targeted charitable assistance has the right to apply to the regulatory body with a request to extend the period of use of such targeted charitable assistance, stating the circumstances that indicate the impossibility of its full use within the terms specified in this paragraph, and the head (his deputy or an authorized person) of such regulatory body has the right to make a decision on such an extension. If the regulatory body refuses such an extension, its decision may be appealed in accordance with the procedure established for appealing the decision of the regulatory body in accordance with this Code.
{Subclause 170.7.6 of Clause 170.7 of Article 170 as amended by Law No. 1797-VIII of 21.12.2016 }
170.7.7. It is prohibited to provide charitable assistance to state authorities and local self-government bodies or to non-profit organizations created by them or, on their behalf, to third parties, if the provision of such charitable assistance is a prior or subsequent condition for the issuance to the taxpayer of any permit, license, approval, provision of a state service or adoption of another decision in his favor or the acceleration of such issuance, provision, adoption (simplification of the procedure).
Actions of officials (service personnel) of state authorities and local self-government bodies to impose such conditions are considered actions to extort funds or property in the amount of charitable or sponsorship assistance.
170.7.8. Charitable assistance provided in accordance with subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code shall not be included in taxable income:
a) in any amount (value) provided:
taxpayers defined by the second paragraph of subparagraph "a" , subparagraph "b" and the second and fifth paragraphs of subparagraph "c" of subparagraph 165.1.54 of clause 165.1 of Article 165 of this Code - for the purchase or in the form of special personal protective equipment (helmets, bulletproof vests manufactured in accordance with military standards), technical means of surveillance, medicines, personal hygiene products, food products, items of material provision or other goods (works, services) according to the list determined by the Cabinet of Ministers of Ukraine, or for payment (compensation) of the cost of medicines, donor components, medical products, technical and other rehabilitation means, paid treatment (examination, diagnostics) services, provision of medical products, technical and other rehabilitation means, medical rehabilitation services, sanatorium and resort health improvement;
{Paragraph two of subparagraph "a" of subparagraph 170.7.8 of paragraph 170.7 of Article 170 as amended by Law No. 2120-IX of March 15, 2022 , No. 3603-IX of February 23, 2024 }
taxpayers defined in paragraphs three to five of subparagraph "a" , paragraphs three and four of subparagraph "c" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code, as assistance for treatment and medical care (examination, diagnostics), including for payment (compensation) of the cost of medicines, donor components, medical products, technical and other rehabilitation equipment, paid treatment services, provision of medical products, technical and other rehabilitation equipment, medical rehabilitation services, sanatorium and resort health improvement;
{Paragraph three of subparagraph "a" of subparagraph 170.7.8 of paragraph 170.7 of Article 170 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2120-IX of 03/15/2022 }
b) the amount (value) that in total during the reporting (tax) year does not exceed 500 times the minimum wage established by law as of January 1 of the reporting (tax) year - for the restoration of lost property, for housing, social and household needs and for other needs according to the list determined by the Cabinet of Ministers of Ukraine, which arose for taxpayers specified in subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code. If the total amount (value) of charitable assistance received during the reporting (tax) year exceeds the specified limit, the amount exceeding such amount is taxed at the rate established by paragraph 167.1 of Article 167 of this Code, and the taxpayer is obliged to submit an annual tax return indicating the amounts of charitable assistance.
{Subparagraph "b" of subparagraph 170.7.8 of paragraph 170.7 of Article 170 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2516-IX of 08/15/2022 ; as amended by Law No. 4254-IX of 02/25/2025 }
{Clause 170.7 of Article 170 is supplemented by subparagraph 170.7.8 in accordance with Law No. 1668-VII of 02.09.2014 }
170.7.9. In the event of payment (provision) of charitable assistance to taxpayers, the amount (value) of such charitable assistance shall be indicated by the tax agent in the tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code.
{Clause 170.7 of Article 170 is supplemented by subparagraph 170.7.9 in accordance with Law No. 4254-IX of 25.02.2025 }
170.7 - 1. Taxation of budget grant.
170.7 - 1 .1. Income in the form of a budget grant at the time of its accrual (payment, provision) in favor of the taxpayer is not taxable and is not included in the total monthly or annual taxable income of the taxpayer.
170.7 - 1 .2. The tax agent of the taxpayer during the accrual (payment, provision) of income in the form of a budget grant in his favor is the provider of such grant.
Tax agents - providers of budget grants in the tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code, reflect (for the reporting month) the amount of income accrued (paid) in the reporting tax period in the form of budget grants. At the same time, the tax calculation shall indicate information about the concluded contracts for the provision of budget grants and their terms, including the term of performance of the contract, the registration number of the registration card of the individual taxpayer who received the budget grant, or the series and number of the passport (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have notified the relevant regulatory authority about this and have a mark in their passport). Information is also provided on the fact of the taxpayer's use of the budget grant or part of it for its intended purpose or the taxpayer's violation of the terms of the agreement on the intended use of the budget grant, on the full or partial return of the budget grant by the taxpayer to the tax agent - the provider of the budget grant (in the event of such return).
{Paragraph two of subparagraph 170.7 - 1 .2 of paragraph 170.7 - 1 of Article 170 as amended by Law No. 4015-IX of 10.10.2024 - regarding the entry into force of certain provisions, see paragraph 1 of Section II }
170.7 - 1.3 . In the event that a tax agent - a provider of budget grants - does not include in the tax calculation information about the taxpayer's violation of the terms of the agreement on the targeted use of the budget grant, such a provider of budget grant is obliged to fulfill all the obligations of a tax agent regarding the income specified in this paragraph.
170.7 - 1 .4. If a taxpayer has committed a violation of the intended use of a targeted grant, the taxpayer is obliged to reflect the amount of income received in the form of a budget grant (its part), in respect of which a violation of the relevant terms of the agreement on the intended use of the grant was committed, as part of the annual taxable income for the relevant reporting year and submit an annual tax return in accordance with this Code and independently pay tax on such income.
170.7 - 1 .5. If a taxpayer has fully or partially returned a budget grant to the grantor (tax agent) in the reporting (tax) year of its payment (grant), such taxpayer has the right, in accordance with the procedure established by Article 42 of this Code, to notify the regulatory authority thereof with copies of documents confirming the fact of such return. In this case, the taxpayer is exempted from the obligation to reflect such part of the paid (granted) and returned grant as part of income in the annual tax declaration and to pay tax on the relevant income.
If a taxpayer has returned a budget grant in favor of the grantor (tax agent) in full or in part in the calendar year following the reporting (tax) year in which the relevant grant amount was included in the annual taxable income, the taxpayer has the right to file a clarifying tax return and reduce the amount of annual taxable income for the relevant reporting year by the returned grant amount, provided that copies of documents are provided confirming the fact of the return of the relevant grant or part of it in favor of the grantor (tax agent).
{Article 170 is supplemented by paragraph 170.7 - 1 in accordance with Law No. 962-IX of 04.11.2020 }
170.8. Taxation of income received under long-term life insurance contracts (including life pension insurance), non-state pension provision, pension contributions, and under trust management contracts.
170.8.1. The tax agent of the taxpayer - recipient of the payment, life pension or redemption amount is the resident insurer that calculates the insurance payment or redemption amount under a non-state pension provision or long-term life insurance contract.
The tax agent of a taxpayer - a participant in non-state pension funds is the administrator of non-state pension funds, who accrues the payment under the contract with the non-state pension fund.
The tax agent of a taxpayer - a depositor under a pension deposit agreement or a participant in a bank management fund is the bank that makes payments under the pension deposit agreement or the account of the participant in the bank management fund.
The tax agent of a taxpayer who is a recipient of a lump-sum payment from the funds of a Savings Fund or a non-state pension fund is the administrator of such a fund.
170.8.2. The tax agent shall withhold and pay (transfer) to the budget the tax at the rate established by paragraph 167.1 of Article 167 of this Code, from:
{Paragraph one of subparagraph 170.8.2 of paragraph 170.8 of Article 170 as amended by Law No. 909-VIII of 24.12.2015 }
a) 60 percent of the amount:
a lump-sum insurance payment under a long-term life insurance contract in the event that the insured person reaches a certain age specified in such insurance contract or survives until the expiration of such contract.
If the beneficiary is an insured under the contract, the amount of the excess of the insurance payment over the amount of insurance payments made is subject to taxation according to the rules for taxation of income from placing funds in deposit accounts;
a lump-sum insurance payment under a life annuity insurance contract, with the exception of a lump-sum payment provided for in subparagraph "c" of subparagraph 170.8.3 of this paragraph;
pension payments for a specified period made from a non-state pension fund to a fund participant in the manner and within the terms specified by law;
regular and consecutive payments (annuities) under a long-term life insurance contract, pension payments under a pension deposit contract, pension and target payments of a participant in a banking management fund, life pension payments (life annuities), except for the cases specified in subparagraph "a" of subparagraph 170.8.3 of this paragraph;
b) the surrender amount in the event of early termination of the long-term life insurance contract by the insured;
c) the amount of funds from which tax was not withheld (paid) and which is paid to the depositor from his pension deposit or account of a participant in a bank management fund in connection with the early termination of a pension deposit agreement, trust management agreement, or non-state pension provision agreement.
170.8.3. The following are not taxable when they are accrued (paid) by a tax agent:
a) the amount of regular and consecutive payments (annuities) under a long-term life insurance contract or pension payments under a pension deposit contract, pension and target payments of a participant in a bank management fund, pension payments for a specified period, lump-sum pension payments or life pensions accrued and/or paid to a resident taxpayer who has not reached the age of majority or is at least 70 years old;
{Subparagraph "a" of subparagraph 170.8.3 of paragraph 170.8 of Article 170 as amended by Law No. 3609-VI of 07.07.2011 }
b) the amount of insurance payment under a long-term life insurance contract, if as a result of an insured event the insured person received a group I disability;
c) the amount of payment under a pension deposit agreement, payments from the account of a participant in a banking management fund, payment of a pension for a specified period, a lifetime pension or a lump sum payment, if the depositor, participant in a banking management fund, participant in a non-state pension fund or insured person has received a group I disability;
{Subparagraph "c" of subparagraph 170.8.3 of paragraph 170.8 of Article 170 as amended by Law No. 3609-VI of 07.07.2011 }
d) the amount of a one-time pension payment to a participant of a non-state pension fund or Accumulation Fund at the expense of the Accumulation Fund.
Income in the form of an insurance payment or payment under a pension deposit agreement, a trust management agreement, or a non-state pension provision agreement, which in the event of the death of the insured person is paid to the beneficiary or heir of the taxpayer, is taxed according to the rules established by this Code for inheritance taxation.
The amount of income received under long-term life insurance contracts, pension deposits, trust management contracts concluded with participants in bank management funds, and non-state pension provision that are subject to taxation is reduced by the amount of contributions paid under such contracts before January 1, 2004.
{Paragraph seven of subparagraph 170.8.3 of paragraph 170.8 of Article 170 as amended by Law No. 3609-VI of 07.07.2011 }
170.9. Taxation of the amount of excess funds/electronic money received by the taxpayer for business trips or for reporting purposes, not returned within the established period.
170.9.1. The tax agent of the taxpayer during the taxation of the amount issued to the taxpayer for reporting and not returned by him within the period established by subparagraph 170.9.3 of this paragraph is the person who issued such amount, namely:
a) for a business trip - in an amount exceeding the amount of the taxpayer's expenses for such a business trip, calculated in accordance with this subparagraph.
The amount of travel expenses reimbursed to him in accordance with the procedure established by law within the limits of actual expenses, namely: travel (including luggage transportation, booking of transport tickets) both to the place of business trip and back, and at the place of business trip (including on rented transport), payment of the cost of accommodation in hotels (motels), as well as expenses included in such accounts for food or household services (laundry, cleaning, mending and ironing of clothes, shoes or linen), for renting other living quarters, payment for telephone calls, registration of foreign passports, entry permits (visas), compulsory insurance, other documented expenses related to the rules of entry and stay at the place of business trip, including any fees and taxes payable in connection with the implementation of such expenses.
The actual number of days spent on a business trip is determined in accordance with the business trip order if there is one or more documentary evidence of the person's stay on a business trip (border service records on border crossing, travel documents, accommodation bills and/or any other documents confirming the person's actual stay on a business trip).
specified in the second paragraph of this subparagraph are not subject to taxation by this tax only if there are supporting documents certifying the cost of such expenses.
Supporting documents include:
transport tickets or transport invoices and baggage receipts (including electronic tickets);
documents received from persons providing accommodation and residence services to an individual, insurance policies;
documents (statements and/or account information) containing information specified by law about payment transactions performed on the account to which payment instruments are issued;
documents confirming the execution of a transaction using payment instruments;
other documents certifying the cost of expenses.
Included in taxable income are the cost of alcoholic beverages and tobacco products, the amount of "tips", except for cases where the amount of such "tips" is included in the bill in accordance with the laws of the host country, as well as fees for entertainment events.
Taxable income also does not include expenses for business trips that are not confirmed by documents, for food and financing other personal needs of an individual (daily expenses), incurred in connection with such a business trip within the territory of Ukraine, but not more than 0.1 of the minimum wage established by law as of January 1 of the tax (reporting) year, calculated for each calendar day of such a business trip, and for business trips abroad - not more than 80 euros for each calendar day of such a business trip at the official exchange rate of the hryvnia to the euro, established by the National Bank of Ukraine, calculated for each such day.
The Cabinet of Ministers of Ukraine separately determines the maximum daily allowances for the travel of crew members of vessels/other vehicles or the amounts allocated for the meals of such crew members instead of daily allowances, if such vessels (other vehicles):
carry out commercial, industrial, scientific research or fishing activities outside the territorial waters of Ukraine;
perform international flights for the purpose of conducting navigation activities or transporting passengers or cargo for a fee outside the air or customs border of Ukraine;
are used to conduct emergency rescue and search and rescue operations outside the customs border or territorial waters of Ukraine.
The amounts and composition of travel expenses, the procedure for reporting on the use of funds allocated for travel of civil servants, as well as other persons sent on business trips by enterprises, institutions and organizations that are fully or partially maintained (financed) at the expense of budget funds, shall be determined by the Cabinet of Ministers of Ukraine. The amount of daily allowances for such categories of individuals may not exceed the amount established by this subparagraph.
{Paragraph seventeen of subparagraph "a" of subparagraph 170.9.1 of paragraph 170.9 of Article 170 as amended by Law No. 3219-IX of 06/30/2023 }
The amount of daily allowance is determined in the case of a business trip:
within Ukraine and countries whose citizens of Ukraine do not require a visa (entry permit) to enter the territory - in accordance with the order on business trip and relevant primary documents;
to countries, the entry of citizens of Ukraine into the territory of which is carried out with a visa (entry permit), - in accordance with the order on business trip with documentary evidence of the person's stay on business trip (border service notes on crossing the border, travel documents, accommodation bills and/or any other documents confirming the person's actual stay on business trip).
In the absence of the specified relevant supporting documents, the amount of daily allowances is included in the taxable income of the taxpayer.
Any travel expenses are not included in the taxable income of the taxpayer if there are documents confirming the connection of such a trip with the business activities of the employer/sending party, including (but not limited to) the following: invitations from the receiving party, whose activities coincide with those of the employer/sending party; a concluded agreement or contract; other documents establishing or certifying the desire to establish civil-law relations; documents certifying the participation of the seconded person in negotiations, conferences or symposiums, other events held on topics that coincide with the business activities of the employer/sending party.
If, according to the laws of the country of business trip or countries through whose territory transit traffic to the country of business trip is carried out, it is mandatory to insure the life or health of the business tripped person or his civil liability (in the case of using vehicles), the costs of such insurance are not included in the taxable income of the taxpayer.
At the request of a representative of the supervisory authority, the employer/sending party shall provide, at its own expense, the translation of supporting documents issued in a foreign language;
b) under the report for the performance of certain civil legal actions on behalf of and at the expense of the person who issued them - in an amount exceeding the amount of the taxpayer's actual expenses for the performance of such actions.
For the purposes of this paragraph, the excess amount does not include and is not subject to tax documented expenses incurred using cash or non-cash funds/electronic money provided to the taxpayer for reporting by the employer for the organization and holding of receptions, presentations, holidays, entertainment and recreation, purchase and distribution of gifts, within the established limits, incurred by such taxpayer and/or other persons for advertising purposes.
The amount of tax accrued on the amount of such excess shall be withheld by the person who issued such funds/electronic money from any taxable income (after taxation) of the taxpayer for the relevant month, and in the event of insufficient income, from the taxable income of the following reporting months until the full payment of such tax.
In the event that the taxpayer terminates employment or civil-law relations with the person who issued such funds/electronic money, the amount of tax is withheld from the last payment of taxable income during the final settlement. In the event that the amount of such income is insufficient, the unpaid part of the tax is included in the taxpayer's tax liability for the results of the reporting (tax) year.
If the full withholding of such tax amount is impossible due to the death of the taxpayer or his recognition by the court as missing or his declaration by the court as deceased, such amount shall be withheld when calculating income for the last tax period for such taxpayer, and the unpaid portion shall be recognized as uncollectible.
170.9.2. If, during a business trip or the performance of certain civil legal actions, the taxpayer used a payment instrument, including a corporate (business) payment instrument or a personal payment instrument, or its details, to make payments, the cost of expenses is certified by a document (statement and/or account information) in electronic or paper form, containing information specified by law about the payment transactions performed on the account to which such payment instrument was issued.
170.9.3. Documentary confirmation of the amount of actual expenses for business trips or the performance of individual civil legal actions by providing supporting documents certifying the amount of such expenses, in the case of non-cash payments using payment instruments, including corporate (business) payment instruments or personal payment instruments, or their details, and the return to the person who issued the funds/electronic money for the report, of the amount of excess funds/electronic money spent, the amount of which is calculated in accordance with subparagraph 170.9.1 of this paragraph, shall be carried out by the taxpayer before the end of the month following the month in which the taxpayer:
a) completes such a business trip;
b) completes the execution of a separate civil legal action on behalf of and at the expense of the person who issued the funds/electronic money for the report.
If, during a business trip or the performance of individual civil legal actions, the taxpayer used a payment instrument, including a corporate (business) payment instrument or a personal payment instrument, or its details, to make payments and the debiting of funds/electronic money for the expenses incurred is carried out by the payment service provider later than the date when the taxpayer completes such a business trip or completes the performance of an individual civil legal action, the terms established by this subparagraph shall be extended by one calendar month.
170.9.4. A report on the use of funds/electronic money issued for business trips or for reporting purposes shall be prepared and submitted within the terms specified in subparagraph 170.9.3 of this paragraph by the taxpayer (in paper or electronic form (in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" ) in the form established by the central executive body that ensures the formation and implementation of state financial policy, in the case of:
a) the presence of taxable income, determined in accordance with subparagraph 170.9.1 of this paragraph, for the purpose of calculating the amount of tax;
b) the taxpayer's use of cash in excess of the amount of daily expenses (including that obtained using payment instruments).
If, during a business trip or the performance of certain civil legal actions, the taxpayer used payment instruments, including corporate (business) payment instruments or personal payment instruments, or their details, to make non-cash payments and/or to receive cash within the amount of daily expenses and in the absence of taxable income, a report on the use of funds/electronic money issued for a business trip or for reporting purposes is not prepared and submitted.
{Clause 170.9 of Article 170 as amended by Laws No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2888-IX of 12.01.2023 }
170.10. Taxation of income received by non-residents.
170.10.1. Income with a source of origin in Ukraine, accrued (paid, provided) to non-residents, is taxed according to the rules and rates determined for residents (taking into account the features determined by some norms of this section for non-residents).
170.10.2. If income with a source of origin in Ukraine is paid to a non-resident by another non-resident, it must be credited to an account opened by such non-resident in a resident bank, the regime of which is established by the National Bank of Ukraine. In this case, such resident bank is considered a tax agent when carrying out any expenditure transactions from such account.
In the event that a non-resident pays such income to another non-resident in cash or in non-cash form, the non-resident recipient of such income is obliged to independently calculate and pay (transfer) tax to the budget within 20 calendar days after receiving such income, but no later than the end of his stay in Ukraine.
The procedure for implementing the norms of this subparagraph shall be determined by the Cabinet of Ministers of Ukraine in agreement with the National Bank of Ukraine.
170.10.3. If income with a source of origin in Ukraine is paid to a non-resident by a resident - a legal entity or a self-employed individual, such resident is considered a tax agent of the non-resident with respect to such income. When concluding an agreement with a non-resident, the terms of which provide for the receipt by such non-resident of income with a source of origin in Ukraine, the resident is obliged to specify in the agreement the tax rate that will be applied to such income.
170.10.4. Based on the results of the reporting tax year in which a foreigner acquired the status of a resident of Ukraine, he must submit an annual tax return, in which he indicates income with a source of origin in Ukraine and foreign income.
170.10.5. Taxation of income of non-residents from participation in touring events.
For the purposes of this section, touring events are defined as entertainment events (concerts, performances, circus, lecture-concert, entertainment programs, creative evenings, performances by mobile circus groups, mobile mechanized attractions of the Luna Park type, etc.) with the participation of cultural institutions (enterprises, institutions or organizations), including independent professional groups and solo concert performers.
This subparagraph does not apply to charitable touring events held in accordance with the legislation of Ukraine.
Taxation of non-residents' income from participation in touring events is carried out by tax agents on the general grounds specified in this section.
Business entities - concert venues, with which lease agreements for the conduct of a touring event are directly concluded, are equated to tax agents of participants in touring events. Business entities - concert venues perform the functions of tax agents in terms of checking the completeness and timeliness of tax payment by foreign participants in touring events (their representative) or independently pay tax under the relevant agreement with such participant (his representative) to the budget at the location of such concert venues.
170.11. Taxation of foreign income.
170.11.1. If the source of payments of any taxable income is foreign, the amount of such income is included in the total annual taxable income of the taxpayer - recipient, who is obliged to file an annual tax return, and is taxed at the rate determined by paragraph 167.1 of Article 167 of this Code, except for:
a) income specified in subparagraph 167.5.4 of paragraph 167.5 of Article 167 of this Code, which is taxable at the rate specified in subparagraph 167.5.4 of paragraph 167.5 of Article 167 of this Code;
b) profit from transactions with investment assets, which is taxed in accordance with the procedure specified in paragraph 170.2 of this article;
c) profits of controlled foreign companies, which are taxed in accordance with the procedure specified in paragraph 170.13 of this article;
d) payments in cash or non-cash form in connection with the distribution of profit, or part thereof, the source of which is an entity without the status of a legal entity, created on the basis of a transaction or registered in accordance with the legislation of a foreign state (territory) without the creation of a legal entity, which are taxable in the manner specified in paragraph 170.11 - 1 of this article";
{Subclause 170.11.1 of Clause 170.11 of Article 170 as amended by Laws No. 657-VII of 10/24/2013 , No. 71-VIII of 12/28/2014 , No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 , No. 2628-VIII of 11/23/2018 ; as amended by Laws No. 466-IX of 01/16/2020 , No. 1914-IX of 11/30/2021 }
170.11.2. If, in accordance with the provisions of international treaties, the consent to the binding nature of which has been granted by the Verkhovna Rada of Ukraine, a taxpayer may reduce the amount of the annual tax liability by the amount of taxes paid abroad, he shall determine the amount of such reduction on the specified grounds in the annual tax return.
If a taxpayer does not have supporting documents regarding the amount of income received by him from foreign sources and the amount of tax paid by him in a foreign jurisdiction, issued in accordance with Article 13 of this Code, such taxpayer shall be obliged to submit to the supervisory authority at his tax address an application for postponement of the deadline for filing a tax return until December 31 of the year following the reporting year. In case of failure to file a tax return within the established deadline, the taxpayer shall bear the liability established by this Code and other laws.
170.11.3. The following shall not be included in the reduction of the amount of the taxpayer's annual tax liability:
a) taxes on capital (capital gains), property taxes;
b) postal taxes;
c) sales taxes;
d) other indirect taxes, regardless of whether they belong to the category of income taxes or are considered separate taxes under the legislation of foreign states.
170.11.4. The amount of tax on foreign income of a resident taxpayer paid outside Ukraine may not exceed the amount of tax calculated on the basis of the total annual taxable income of such taxpayer in accordance with the legislation of Ukraine.
170.11 - 1. Taxation of payments from an organization without the status of a legal entity
170.11 - 1 .1. If the source of payments in cash or non-cash form in connection with the distribution of profit, or part thereof, of the current period and/or accumulated (undistributed) for previous periods is an entity without the status of a legal entity, created on the basis of a transaction or registered in accordance with the legislation of a foreign state (territory) without the creation of a legal entity, namely a partnership, trust, fund, which:
a) in accordance with the legislation and/or documents regulating its activities (personal law), has the right to carry out activities aimed at generating income (profit) in the interests of its participants, partners, founders, trustees, beneficiaries, beneficiaries (beneficiaries) or a group of beneficiaries (beneficiaries) in accordance with a trust agreement or other document regulating the activities of such an entity, and
b) makes such payments in favor of such participants, partners, founders, trustees, beneficiaries, beneficiaries (beneficiaries) or group of beneficiaries (beneficiaries) in accordance with the trust agreement or other document regulating the activities of such entity, and
c) is not a controlled foreign company,
The amount of such payments is included in the total annual taxable income of the taxpayer-recipient and is taxed at the rate determined by subparagraph 167.5.4 of paragraph 167.5 of Article 167 of this Code.
170.11 - 1 .2. In this case, the taxpayer - recipient of such payments is obliged to submit an annual tax return for the relevant reporting (tax) period, in which such payments are reflected.
The taxpayer submits copies of the following documents along with the tax return:
a) a decision of a person exercising management and/or control of a foreign entity without the status of a legal entity (in particular, but not exclusively, a trust manager), which must contain information that the payment in cash or non-cash form is made in connection with the distribution of profit, or part thereof, of the current period and/or accumulated (undistributed) for previous periods;
b) written confirmation that the taxpayer has the right to receive such payments in accordance with the contract and/or personal law, and/or constituent documents of such a foreign entity without the status of a legal entity, signed by its manager (authorized person), trust manager, administrator or authorized custodian of the relevant documents of such a foreign entity without the status of a legal entity, including a banking institution.
Copies of the specified documents shall be submitted in accordance with the form and rules applicable to such foreign entity without legal entity status, trust manager, administrator, authorized custodian of relevant documents of such foreign entity without legal entity status, including a banking institution, in the relevant foreign state (territory).
At the request of the regulatory authority, the taxpayer is obliged to provide the originals of the specified documents and their translation into Ukrainian. In the case of submission of documents in English, translation into Ukrainian is not required.
{Article 170 is supplemented by paragraph 170.11 - 1 in accordance with Law No. 1914-IX of 11/30/2021 }
170.12. Taxation of income received by individuals in the form of fees (interest) distributed among the share membership fees of members of a credit union.
170.12.1. The tax agent of the taxpayer when calculating (paying) in his favor a fee (interest) distributed among the share membership fees of the members of the credit union is the credit union, which taxes such income at the rate determined by paragraph 167.1 of Article 167 of this Code.
{Subclause 170.12.1 of clause 170.12 of Article 170 as amended by Laws No. 1588-VII of 04.07.2014 , No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 }
170.12.2. A credit union that pays a fee (interest) distributed among the share membership fees of the credit union members to the payers of this tax shall submit to the supervisory authority, within the terms established by this Code for the tax month, a tax calculation of the accrued fee (interest) and the tax withheld thereon.
{Subclause 170.12.2 of Clause 170.12 of Article 170 as amended by Law No. 4015-IX of 10.10.2024 - for the entry into force of certain provisions, see Clause 1 of Section II }
170.13. Taxation of profits of controlled foreign companies.
170.13.1. A resident taxpayer recognized as a controlling entity in relation to a controlled foreign company shall be obliged to determine a portion of the profit of the controlled foreign company in accordance with the provisions of Article 39-2 of this Code and include it in the total taxable income reflected in the annual tax return and taxed at the rate determined by Clause 167.1 of Article 167 of this Code.
170.13.2. In the event that a controlled foreign company distributes profits or a portion thereof to the benefit of the controlling person, and such person actually receives the distributed funds (either directly or through a chain of indirect ownership), the following rules apply:
170.13.2.1. in the event of a distribution by the controlling entity of the profit of a controlled foreign company (part thereof) before the submission of the report on controlled foreign companies and the inclusion of the specified part of the profit of the controlled foreign company in the total taxable income reflected in the annual tax return , the tax rate determined by subparagraph 167.5.4 of paragraph 167.5 of Article 167 of this Code shall be applied to such actually received (distributed) income .
In this case, the relevant part of the profit of the controlled foreign company is not subject to re-inclusion in the total taxable income after filing the report on controlled foreign companies;
170.13.2.2. in the event of a distribution by a controlling person of the profit of a controlled foreign company (part thereof) after the submission of a report on controlled foreign companies and the inclusion of the specified part of the profit of a controlled foreign company in the total taxable income reflected in the annual tax return , but before the end of the second calendar year following the reporting year, the tax on the profit of a controlled foreign company reflected in the tax return shall be recalculated using the tax rate determined by subparagraph 167.5.4 of paragraph 167.5 of Article 167 of this Code. The controlling person - a resident of Ukraine has the right to submit a clarifying annual tax return reflecting the results of such recalculation. In this case, the received part of the profit of a controlled foreign company shall not be subject to re-inclusion in the total taxable income in the calendar year in which it is actually received (distributed);
170.13.2.3. in the event of the distribution by the controlling entity of the profit of the controlling foreign company (part thereof) after the date of submission of the report on controlled foreign companies and the inclusion of the specified part of the profit of the controlled foreign company in the total taxable income reflected in the annual tax return , after the end of the second calendar year following the reporting year, the tax recalculation shall not be carried out. In this case, the received part of the profit of the controlled foreign company shall not be subject to re-inclusion in the total taxable income in the calendar year in which it is actually received (distributed);
170.13.2.4. the amount of personal income tax payable on the profit of a controlled foreign company (both distributed and undistributed) shall be reduced by the amount of corporate tax or other similar tax levied in accordance with the legislation of foreign states and actually paid by the controlled foreign company, including taxes withheld at source from the amount of income received by the controlled foreign company.
The amount of such tax is determined as the total amount of tax actually paid by a controlled foreign company based on the results of the relevant reporting (tax) period (corporate tax or other similar tax levied in accordance with the legislation of foreign states - paid during the reporting period) proportional to the controlling entity's share in such a controlled foreign company, reflected in the report on controlled foreign companies.
The taxpayer is entitled to such a reduction subject to documentary confirmation of the actual payment. Copies of documents confirming the fact of such payment are submitted by the taxpayer together with the tax return .
In this case, the amount of the reduction in personal income tax, determined by the first paragraph of this subclause, cannot exceed the amount of the tax liability of the individual in respect of the profit of such a controlled foreign company.
170.13.3. The amount of profit of a controlled foreign company received in the form of dividends from legal entities of Ukraine (both directly and indirectly through a chain of controlled legal entities) in accordance with subparagraph 39 - 2 .3.2.7 of subparagraph 39 - 2 .3.2 of paragraph 39 - 2 .3 of Article 39 - 2 of this Code is considered the amount of dividends received from Ukrainian legal entities directly by the controlling entity.
Such amount is included in the total taxable income of the controlling entity for the reporting period during which the controlled foreign company received dividends, and is subject to taxation:
received from legal entities of Ukraine - payers of income tax (except for collective investment institutions) at the rate determined by Clause 167.2 of Article 167 of this Code;
received from collective investment institutions, business entities that are not payers of income tax, at the rate determined by subparagraph 167.5.4 of paragraph 167.5 of Article 167 of this Code.
At the same time, such amount is not taken into account by the taxpayer when determining the part of the profit of a controlled foreign company in accordance with subparagraph 39 - 2 .3.2.7 of subparagraph 39 - 2 .3.2 of paragraph 39 - 2 .3 of Article 39 - 2 of this Code, is not subject to taxation in accordance with subparagraph 170.13.1 of paragraph 170.13 of Article 170 of this Code, and is also not subject to further taxation upon its actual payment to the controlling entity in accordance with subparagraph 170.13.2 of paragraph 170.13 of Article 170 of this Code.
{Paragraph five of subparagraph 170.13.3 of paragraph 170.13 of Article 170 as amended by Law No. 4505-IX of 06/18/2025 }
{Article 170 is supplemented by paragraph 170.13 in accordance with Law No. 466-IX of January 16, 2020 }
170.13 - 1. Taxation of income of controlled foreign companies.
The following are not included in the total monthly (annual) taxable income of the taxpayer:
1) dividends that are considered to be received by the taxpayer in accordance with the first paragraph of subparagraph 170.13.3 of paragraph 170.13 of Article 170 of this Code were previously taxed at the level of a legal entity of Ukraine in accordance with the procedure specified in subparagraph 141.4.2 of paragraph 141.2 of Article 141 of this Code;
{Subparagraph 1 of paragraph 170.13 - 1 of Article 170 as amended by Law No. 4505-IX of 06/18/2025 }
2) income in cash and/or other property form, which is not a distribution of profit in accordance with international financial reporting standards, received by a taxpayer - shareholder (participant, partner, shareholder, founder, controlling person) from a foreign legal entity or a foreign entity without the status of a legal entity, including upon liquidation (termination) of such a foreign legal entity or a foreign entity without the status of a legal entity, within the value of funds and/or property previously contributed by such a taxpayer (members of his family of the first and second degrees of kinship) and accounted for as the capital of a foreign legal entity or a foreign entity without the status of a legal entity in accordance with international financial accounting standards;
3) income in cash and/or other property form received upon liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity by a taxpayer - shareholder (participant, partner, shareholder, founder, controlling person) of a foreign legal entity or a foreign entity without the status of a legal entity, if all of the following conditions are met:
a) the procedure for liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity was initiated no earlier than January 1, 2020 and completed no later than December 31, 2021.
If the decision of shareholders or other authorized persons on the liquidation (termination) of a foreign legal entity or foreign entity without the status of a legal entity is made after January 1, 2020, but no later than December 31, 2021, however, the liquidation (termination) procedure cannot be completed by December 31, 2021 due to restrictions and/or requirements established by the personal law of the foreign legal entity or foreign entity without the status of a legal entity, or due to the participation of the foreign legal entity or foreign entity without the status of a legal entity in a court dispute, the condition regarding the terms for completing the liquidation (termination) procedure of the foreign legal entity or foreign entity without the status of a legal entity is considered fulfilled if the liquidation (termination) procedure is completed within 365 consecutive calendar days after the date of termination of such restrictions and/or completion of the court dispute.
If the personal law of a foreign legal entity or a foreign entity without the status of a legal entity provides for requirements regarding the minimum period of ownership by the taxpayer of shares (units, shares) of this foreign legal entity and/or its subsidiary organization, and/or a foreign entity without the status of a legal entity, failure to comply with which will result in such a taxpayer being obliged to pay the relevant amount of foreign tax, and the beginning of such period falls on the period before January 1, 2021, and the end of such period falls on a date after December 31, 2021, the condition regarding the terms of completion of the procedure for liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity is met if the procedure for liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity is completed within 365 consecutive calendar days from the date of completion of the period of minimum ownership of shares (units, shares);
b) the taxpayer submitted to the regulatory authority, simultaneously with the tax return, an application drawn up in an arbitrary form for the exemption of such income from taxation, indicating the characteristics of the received property and the liquidated (terminated) foreign legal entity or foreign entity without the status of a legal entity, as well as documents containing information on the value of the received property, in accordance with the financial statements of the foreign legal entity or foreign entity without the status of a legal entity, drawn up in accordance with international financial accounting standards, as of the date of the decision to distribute property as income payment in connection with the liquidation (termination) of the foreign legal entity or foreign entity without the status of a legal entity;
c) a foreign legal entity or a foreign entity without the status of a legal entity was established on the basis of a transaction or law of a foreign state (territory) no later than May 23, 2020, or was registered no later than May 23, 2020 in accordance with the legislation of a foreign state (territory) if, in accordance with the legislation of such foreign state (territory), regulatory requirements and/or documents regulating the activities (personal law) of such a foreign legal entity or a foreign entity without the status of a legal entity, such a person (entity) is subject to registration in the relevant state (territory);
4) income provided for in clause 3 of clause 170.13 - 1 of Article 170 of this Code, received by the ultimate beneficial owner (controller) from the nominal holder (nominal owner), within the meaning of clause 103.3 of Article 103 of this Code, in connection with the liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity, provided that the requirements of subparagraphs "a" - "c" of clause 3 of clause 170.13 - 1 of Article 170 of this Code are met. In this case, the taxpayer, in addition to the information and documents provided for in subparagraph "b" of paragraph 3 of paragraph 170.13 - 1 of Article 170 of this Code, is obliged to provide documents confirming the receipt of such income from the nominal holder (nominal owner) in connection with the liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity.
Regarding income in cash received upon liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity by a taxpayer - shareholder (participant, partner, shareholder, founder, controlling person) of a foreign legal entity or a foreign entity without the status of a legal entity, all necessary measures are taken to establish the sources of origin of such income in accordance with the legislation in the field of financial monitoring.
{Article 170 is supplemented by paragraph 170.13 - 1 in accordance with Law No. 466-IX of 01.16.2020, taking into account the amendments made by Laws No. 1117-IX of 12.17.2020 , No. 1539-IX of 06.15.2021 }
170.14. Features of determining the general minimum tax liability of taxpayers - owners, tenants, users on other terms (including emphyteusis terms) of land plots classified as agricultural land.
170.14.1. For taxpayers - owners, tenants, users on other terms (including on emphyteusis terms) of land plots classified as agricultural lands, not transferred by such persons for lease (sublease), emphyteusis or other use on the basis of agreements concluded and registered in accordance with the legislation, the general minimum tax liability is determined by the controlling body.
170.14.2. In the event of transfer of such land plots for lease (sublease), emphyteusis or other use on the basis of agreements concluded and registered in accordance with the legislation, their size shall be taken into account when determining the total minimum tax liability of tenants, users on other terms (including on emphyteusis terms) of such land plots in accordance with the procedure established by this Code.
170.14.3. The determination of the general minimum tax liability for individuals is carried out by the supervisory authorities at the tax address of such individuals.
The minimum tax liability is calculated by the controlling authority based on data from the State Register of Real Property Rights to Real Estate, the State Land Cadastre and/or based on originals or duly certified copies of relevant documents of the taxpayer, in particular documents confirming the right of ownership/use.
When calculating the minimum tax liability, the regulatory monetary valuation of land plots is applied by the regulatory authorities, taking into account the requirements established by paragraph 271.2 of Article 271 of this Code.
In the event of state registration of a taxpayer as an individual entrepreneur, the general minimum tax liability for land plots classified as agricultural lands used by such entrepreneur to conduct economic activities shall be calculated by such taxpayer in accordance with the procedure specified in Clause 177.14 of Article 177 and Article 297-1 of this Code, from the first day of the month following the month in which the state registration of the individual entrepreneur took place.
A tax notice-decision together with a detailed calculation of the amount of tax on payment of the annual tax liability on personal income tax, for the amount of the positive difference between the amount of the total minimum tax liability and the amount of taxes, fees, and payments paid during the tax (reporting) year, the control over the collection of which is entrusted to the regulatory authorities, related to the production and sale of one's own agricultural products and/or to the ownership and/or use (lease, sublease, emphyteusis, permanent use) of land plots classified as agricultural land (hereinafter in this paragraph - the total amount of taxes, fees, and payments paid), shall be sent (delivered) to the taxpayer in accordance with the procedure specified in Article 42 of this Code, by July 1 of the year following the reporting year.
If the regulatory authority has not sent (delivered) such a tax notice-decision together with a detailed calculation of the tax amount within the specified period, the individual is exempted from liability provided for by this Code for untimely payment of the annual tax liability by the amount of the positive difference between the amount of the total minimum tax liability and the total amount of taxes, fees, and payments paid.
Such annual tax liability may be accrued for tax (reporting) periods (years) within the time limits specified in Clause 102.1 of Article 102 of this Code.
The positive value of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, and payments paid is part of the personal income tax liability.
The amount of personal income tax in the positive part of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, and payments paid is distributed by the controlling body in proportion to the specific weight of the area of each of the land plots classified as agricultural land, and is paid (transferred) to local budgets at the location of such land plots.
170.14.4. The amount of personal income tax in the positive part of such difference shall not be taken into account in the total amount of taxes, fees, and payments paid in the next tax (reporting) year.
170.14.5. The total amount of taxes, fees, and payments paid by a taxpayer during the tax (reporting) year includes:
personal income tax and military levy on income from the sale of one's own agricultural products;
land tax for land plots classified as agricultural land.
The amount of taxes, fees, and payments paid does not include amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
170.14.6. In the event of a taxpayer's agreement with the general minimum tax liability and/or the calculated amount of the annual personal income tax liability determined by the supervisory authority, such taxpayer shall be obliged to pay the tax amount specified in the relevant tax notice-decision within 60 days from the date of delivery of the tax notice-decision.
In the event of a taxpayer's disagreement with the general minimum tax liability determined by the supervisory authority and/or the amount of the annual personal income tax liability calculated in the relevant tax notice-decision, such taxpayer has the right, in accordance with the procedure established by Article 42 of this Code, to contact the supervisory authority at his tax address to conduct a reconciliation of the data used to calculate the amount of personal income tax, with the provision of supporting documents, in particular regarding:
{Paragraph two of subparagraph 170.14.6 of paragraph 170.14 of Article 170 as amended by Law No. 3603-IX of 23.02.2024 }
land plots owned and/or permanently used by the taxpayer or leased (sublease, emphyteusis), their normative monetary value and area;
the amount of income received from the sale of one's own agricultural products;
amounts of taxes, fees, and payments paid.
In the event that a taxpayer submits to the supervisory authority title documents for land plots or contracts for the transfer of lease, emphyteusis or other use of land plots, concluded and registered in accordance with the legislation, information about which is missing from the databases of information systems of the central executive body implementing state tax policy, the calculation of the minimum tax liability is carried out on the basis of the information submitted by the taxpayer until the supervisory authority receives information from the relevant authorities about the ownership/use or transfer of ownership/use rights to such land plots.
If, as a result of the reconciliation, discrepancies are found between the data of the controlling authority and the data confirmed by the taxpayer on the basis of the originals of the relevant documents, the controlling authority, within 10 days following the date of completion of the reconciliation, is obliged to cancel (withdraw) such a tax notice-decision and, if necessary, send (deliver) to the taxpayer a new tax notice-decision together with a detailed calculation of the tax amount, drawn up taking into account the results of the reconciliation.
170.14.7. The supervisory authorities at the location of the taxpayer's tax address shall, within 10 days, inform the supervisory authorities at the location of the relevant land plots about the tax notices-decisions on tax payment sent (delivered) to the taxpayer in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy.
{Article 170 is supplemented by paragraph 170.14 in accordance with Law No. 1914-IX of 30.11.2021 }
170.14 - 1. Features of taxation of income of resident specialists of the City of Diya
170.14 - 1 .1. The tax agent of the taxpayer - a resident specialist of Diya City during the accrual (payment) in his favor of income in the form of wages, other incentive and compensation payments or other payments and rewards that are accrued (paid, provided) to the taxpayer in connection with employment relations or in connection with the performance of a gig contract concluded in accordance with the procedure provided for by the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine" are residents of Diya City.
170.14 - 1 .2. At the rate determined by paragraph 167.2 of Article 167 of this Code, the income of a taxpayer - a specialist resident of Diya City, accrued (paid) in his favor by a resident of Diya City (except for a resident of Diya City who simultaneously has the status of a resident of Defense City) starting from the calendar month following the calendar month in which the status of a resident of Diya City was acquired, shall be taxed in the form of:
{Paragraph one of clause 170.14 - 1 .2 of clause 170.14 - 1 Article 170 as amended by the Law No. 4577-IX dated 21.08.2025 }
a) salary;
b) remuneration under a gig contract concluded in accordance with the procedure provided for by the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", including remuneration for the creation and transfer of rights to works created on order;
c) royalties for the creation of a service work and the transfer of rights to service works.
The income of specialists resident in Diya City, provided for in subparagraphs "a" - "c" of this subparagraph, which was accrued (paid) in the calendar month in which the status of a resident of Diya City was acquired, is taxed at the rate determined by paragraph 167.1 of Article 167 of this Code.
{Subclause 170.14 - 1 .2 of clause 170.14 - 1 of Article 170 as amended by Law No. 4113-IX of 04.12.2024 }
170.14 - 1 .3. The provisions of subparagraph 170.14 - 1 .2 of this paragraph apply to the total (annual) taxable income in the form of wages or remuneration accrued (paid, provided) to the taxpayer in connection with employment relations or in connection with the performance of a gig contract, the amount of which does not exceed the equivalent of 240 thousand euros per calendar year at the official exchange rate of the hryvnia against the euro, established by the National Bank of Ukraine as of January 1 of the reporting tax year. At the same time, for the purposes of calculating this amount, it does not include the income of a resident specialist of Diya City, taxed by a tax agent - resident of Diya City in the manner provided for in subparagraphs 170.14 - 1 .4-170.14 - 1 .6 of this paragraph, at the rate established by paragraph 167.1 of Article 167 of this Code. If the amount of income received exceeds the specified amount, the rate established by paragraph 167.1 of Article 167 of this Code shall be applied to the amount of such excess, and the taxpayer shall be obliged to reflect the amount of such excess as part of the total monthly (annual) taxable income for the relevant reporting year and submit an annual declaration of property status and income (tax declaration) in accordance with this Code and independently pay tax on the amount of such excess.
{Subclause 170.14 - 1 .3 of clause 170.14 - 1 of Article 170 as amended by Law No. 4113-IX of 04.12.2024 }
170.14 - 1 .4. If the entry on the loss of the status of a resident of Diya City by a tax agent was made as a result of a court appeal of the decision on the loss of the status of a resident of Diya City, which was not canceled, such a tax agent is obliged, within the period specified for the monthly tax (reporting) period, to independently calculate and pay (transfer) to the budget at its own expense the tax at the rate established by clause 167.1 of Article 167 of this Code, in respect of the income of specialists of a resident of Diya City, provided for in subparagraphs "a"-"c" of subparagraph 170.14 - 1 .2 of this clause, which were paid during the period from the date of adoption by the authorized body of the decision on the loss of the status of a resident of Diya City until the date of entry of the entry on the loss of the status of a resident of Diya City by the tax agent. At the same time, the amount of such tax paid by the tax agent is not included in the total monthly (annual) taxable income of resident specialists of Diya City.
170.14 - 1 .5. If a tax agent - resident of Diya City in the relevant calendar month did not meet the requirements specified in paragraphs 2 and 3 of part one of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine" (except for the cases specified in the first paragraph of subparagraph 170.14 - 1.6 of this paragraph), such a tax agent is obliged, within the framework of the tax calculation of the amounts of income accrued (paid) in favor of taxpayers - individuals, and the amounts of tax withheld from them, as well as the amounts of the accrued single contribution, to independently calculate the tax at the rate established by subparagraph 167.1 of Article 167 of this Code, in relation to the income of specialists of a resident of Diya City, provided for by subparagraphs "a" and "b" of subparagraph 170.14 - 1.2 of this paragraph, which were accrued (paid) during such calendar month, and to pay (transfer) at its own expense the tax to budget minus the tax that was paid (transferred) to the budget from such income.
At the same time, the amount of such tax paid (transferred) by the tax agent is not included in the total monthly (annual) taxable income of resident specialists of Diya City.
{Subclause 170.14 - 1 .5 of clause 170.14 - 1 of Article 170 as amended by Law No. 4113-IX of 04.12.2024 }
170.14 - 1 .6. Until December 31 of the calendar year following the calendar year in which the tax agent acquired the status of a resident of the City of Action in accordance with Part Three of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", the provisions of Sub-Clause 170.14 - 1 .5 of this clause regarding the tax consequences of non-compliance with the requirement specified in Clause 3 of Part One of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine" shall not apply. Taxation of such income of specialists resident of the City of Action shall be carried out in accordance with the provisions of Sub-Clause 170.14 - 1 .2 of this clause.
If, after the deadline specified in the first paragraph of this subparagraph, such a tax agent - resident of Diya City continues to fail to meet the requirement specified in paragraph 3 of part one of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", such a tax agent - resident of Diya City shall, within the period specified for the monthly tax (reporting) period, independently calculate and pay (transfer) to the budget at its own expense the tax at the rate established by paragraph 167.1 of Article 167 of this Code, in respect of the income of specialists of a resident of Diya City, provided for in subparagraphs "a"-"c" of subparagraph 170.14 - 1 .2 of this subparagraph, paid during the tax periods when the tax agent did not meet the requirement specified in paragraph 3 of part one of Article 5 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine", within the last three months of the calendar year following the calendar year in which the tax agent acquired the status of a resident of Diya City, minus the tax that was paid (transferred) to the budget from such income. In this case, the amount of such tax paid (transferred) by the tax agent is not included in the total monthly (annual) taxable income of Diya City resident specialists.
{Regarding the application of the provisions of the second subparagraph of paragraph 170.14 - 1 .6 of paragraph 170.14 - 1 of Article 170, see paragraph 2 of Section II of Law No. 4113-IX of 04.12.2024 }
{Clause 170.14 - 1 of Article 170 is supplemented by subparagraph 170.14 - 1 .6 in accordance with Law No. 4113-IX of 04.12.2024 }
{Article 170 is supplemented by paragraph 170.14 - 1 in accordance with Law No. 1946-IX of 14.12.2021 }
Article 171. Persons responsible for withholding (calculation) and payment (transfer) of tax to the budget↑
171.1. The person responsible for the accrual, withholding and payment (transfer) to the budget of tax on income in the form of wages is the employer who pays such income to the taxpayer.
171.2. The person responsible for the calculation, withholding and payment (transfer) to the budget of tax on other income is:
a) tax agent - for taxable income from its source of origin in Ukraine;
b) taxpayer - for foreign income and income, the source of payment of which belongs to persons exempt from the obligations of accrual, withholding or payment (transfer) of tax to the budget.
Article 172. Procedure for taxation of transactions on the sale (exchange) of real estate objects, an indivisible object of unfinished construction/future real estate object, a divisible object of unfinished construction and the assignment of rights under a contract of sale of an indivisible object of unfinished construction/future real estate object for which the price has been partially paid and an encumbrance of real rights in favor of the buyer has been registered
172.1. Income received by the taxpayer from the sale (exchange) of:
a residential building, apartment or part thereof, room, garden (summer) house (including an object of unfinished construction of such objects, a land plot on which such objects are located, as well as household structures and buildings located on such a land plot);
a land plot that does not exceed the norms of free transfer determined by Article 121 of the Land Code of Ukraine, depending on its purpose;
agricultural land plot directly acquired by the taxpayer in the process of privatization of land of state and municipal agricultural enterprises, institutions and organizations or privatization of land plots that were in use by such taxpayer, or allocated in kind (on the ground) to the owner of a land share (share), as well as such land plots received by the taxpayer as an inheritance.
The condition that such property must remain in the taxpayer's ownership for more than three years does not apply to property received by the taxpayer as an inheritance.
Income from the alienation of household and household structures located on the same plot as a residential or garden (summer) house and sold together with it for taxation purposes is not determined separately.
172.2. Income received by a taxpayer from the sale during the reporting (tax) year of a second real estate object (except for transactions on the alienation of residential real estate by banks in the procedure for foreclosure under mortgage agreements securing a loan granted in foreign currency), from those specified in paragraph 172.1 of this Article, or from the sale of a real estate object not specified in paragraph 172.1 of this Article, is subject to taxation at the rate determined by paragraph 167.2 of Article 167 of this Code.
Income received by a taxpayer from the sale during the reporting (tax) year of the third and subsequent real estate objects (except for transactions on the alienation of residential real estate by banks in the procedure for foreclosure under mortgage agreements securing a loan granted in foreign currency), from those specified in paragraph 172.1 of this article, or from the sale of the second and subsequent real estate objects not specified in paragraph 172.1 of this article, is subject to taxation at the rate determined by paragraph 167.1 of Article 167 of this Code, except for cases where the property specified in this paragraph was received by the taxpayer as an inheritance.
Income received by a taxpayer from the sale during the reporting (tax) year of an indivisible object of unfinished construction/future real estate, a divisible object of unfinished construction and from the assignment of rights under a contract of sale of an indivisible object of unfinished construction/future real estate, for which the price has been partially paid and an encumbrance of real rights in favor of the buyer has been registered, is subject to taxation at the rate determined by paragraph 167.1 of Article 167 of this Code, except for cases where the property and property rights specified in this paragraph were received by the taxpayer as an inheritance.
Income received by a taxpayer from the sale during the reporting (tax) year of the third and subsequent real estate objects in the form of inherited real estate objects, as well as income from the sale during the reporting (tax) year of an indivisible object of unfinished construction/future real estate object, a divisible object of unfinished construction and/or from the assignment of rights under a purchase and sale agreement of an indivisible object of unfinished construction/future real estate object, for which the price has been partially paid and an encumbrance of real rights in favor of the buyer has been registered, provided that such property, property rights were received by the taxpayer as an inheritance, is subject to taxation at the rate determined by Clause 167.2 of Article 167 of this Code.
Income from the sale of real estate specified in paragraph two of clause 172.2 of this article may be reduced by documented expenses for the acquisition of real estate located in the territory of Ukraine.
Income from the sale during the reporting (tax) year of an indivisible object of unfinished construction/future real estate, a divisible object of unfinished construction, and from the assignment of rights under a contract of sale of an indivisible object of unfinished construction/future real estate, for which the price has been partially paid and an encumbrance of real rights in favor of the buyer has been registered, may be reduced by the documented costs of acquiring such an object, property rights.
The costs of purchasing a real estate object are understood to mean:
a) funds paid by the taxpayer as the value of securities, derivatives (derivative contracts) and property rights, the repayment of which occurred through the transfer of a real estate object (or part thereof);
b) funds transferred to the management of the construction financing fund manager;
c) expenses incurred for the acquisition of real estate at the stage of incomplete construction;
d) the value of a real estate object, an indivisible object of unfinished construction/future real estate object, transferred to the taxpayer as payment for his share in the authorized capital of a business company upon the withdrawal of such a taxpayer from the composition of the participants of the legal entity;
e) the value of the mortgaged property at which the mortgagee acquired ownership of the mortgaged property;
e) expenses for the acquisition of real estate on the basis of a purchase and sale agreement, exchange, including the value of property transferred as compensation under such agreements;
f) registration fees, state duty and similar payments made in connection with the acquisition (receipt) of rights to real estate;
h) the value of the real estate object that was declared by the person as an object of declaration under the procedure of one-time (special) voluntary declaration, in accordance with Subsection 9 - 4 of Section XX of this Code;
g) the value of a real estate object, an indivisible object of unfinished construction/future real estate object that was obtained upon liquidation (termination) of a legal entity (including a foreign one) or an establishment without the status of a legal entity (including a foreign one) by a taxpayer - shareholder (participant, partner, shareholder, founder, controlling person);
h) expenses incurred for the construction of the real estate object;
i) expenses incurred for the acquisition of an indivisible object of construction in progress/future real estate;
i) the amount of money specified in the housing certificate for the purchase of a residential real estate object, which was received by the taxpayer as compensation for a damaged/destroyed real estate object in accordance with the Law of Ukraine "On Compensation for Damage and Destruction of Certain Categories of Real Estate Objects as a Result of Hostilities, Terrorist Acts, and Sabotage Caused by Armed Aggression of the Russian Federation against Ukraine, and the State Register of Property Damaged and Destroyed as a Result of Hostilities, Terrorist Acts, and Sabotage Caused by Armed Aggression of the Russian Federation against Ukraine".
{Clause 172.2 of Article 172 is supplemented with a new paragraph in accordance with Law No. 3219-IX of 06/30/2023 }
A real estate object, an indivisible object of unfinished construction/future real estate object donated to a taxpayer is considered to be acquired at a cost equal to the amount of state duty, registration fee or other similar payments, taxes and fees paid in connection with such donation.
The calculation of the reduction of income from the sale of real estate, an indivisible object of unfinished construction/future real estate, a divisible object of unfinished construction and from the assignment of rights under a contract of sale of an indivisible object of unfinished construction/future real estate, for which the price has been partially paid and an encumbrance of real rights in favor of the buyer has been registered, by the amount of allowed expenses is carried out by the taxpayer independently, and if the party to the relevant contract is a legal entity or a self-employed person, by such a person.
At the same time, if the taxpayer has exercised the right to deduct expenses, he is obliged to declare income from all transactions on the sale, exchange or other alienation of the relevant objects carried out during the reporting (tax) year, including if the party to the relevant contract is a legal entity or a self-employed person.
Copies of documents confirming the specified expenses are provided together with the tax return.
172.3. Income from the sale of a real estate object, an indivisible object of unfinished construction/future real estate object is determined based on the price specified in the purchase and sale agreement, but not lower than the estimated value of such an object, calculated by the module for electronic determination of the estimated value of the Unified Database of Evaluation Reports, or not lower than the market value of such an object, determined by the subject of evaluation activity (evaluator) in accordance with the legislation and specified in the evaluation report registered in the Unified Database of Evaluation Reports.
Unified database of appraisal reports (hereinafter referred to as the Unified Database) is a state automated information and telecommunications system, which includes a database, software, a module for electronic determination of the estimated value, a service for electronic determination of the estimated value and automatic generation of electronic certificates on the estimated value of a real estate object, an indivisible object of unfinished construction/future real estate object.
A single database provides:
1) entering, updating, creating, storing, transmitting and automatically publishing relevant information about a real estate object, an indivisible object of unfinished construction/future real estate object and its value (except for information about the normative monetary valuation of a land plot);
2) registration, authorization (identification) of valuation entities (valuators) and notaries;
3) entry of assessment reports and information from them by assessment entities (appraisers) directly and directly into the Unified Database;
4) registration and storage of assessment reports in the Unified Database with automatic assignment of a unique registration number to each report;
5) electronic determination of the estimated value of real estate objects, an indivisible object of unfinished construction/future real estate object and automatic generation of electronic certificates of the estimated value of real estate objects at the request of individuals and legal entities with automatic assignment of a unique registration number to each certificate;
6) automatic exchange of information and documents, accessed via the Internet.
The owner of the Unified Database, intellectual property rights to the Unified Database and its software is the state represented by the State Property Fund of Ukraine.
The State Property Fund of Ukraine is the holder, manager and administrator of the Unified Database, as well as the owner of all information contained in it.
The single database should ensure the preservation and proper protection of all information regarding real estate objects, an indivisible object of unfinished construction/future real estate object, the estimated value of which is determined and verified, and the possibility of access to information by entities engaged in valuation activities (appraisers), notaries and regulatory authorities within the limits of their powers.
Information from the Unified Database about a real estate object, an indivisible object of unfinished construction/future real estate object and its value, including valuation reports, is automatically published on the official website of the State Property Fund of Ukraine in real time (except for information with restricted access). Such information is provided with open, direct unauthorized access with the possibility of downloading in open data format.
For the purposes of this paragraph, information with restricted access does not include information about valuation entities (valuators).
The procedure for maintaining the Unified Database is approved by the State Property Fund of Ukraine in agreement with the central executive body that ensures the formation of state financial policy.
In order to form an information basis for determining the estimated value of a real estate object, an indivisible object of unfinished construction/future real estate object, the State Property Fund of Ukraine uses open access information sources and data on prices specified in purchase and sale contracts for real estate objects, an indivisible object of unfinished construction/future real estate object, entered by notaries into the Unified Database, as well as data on the market value of real estate objects, an indivisible object of unfinished construction/future real estate object, entered into the Unified Database on the basis of appraisal reports.
The determination of the estimated value of a real estate object, an indivisible object of unfinished construction/future real estate object is carried out automatically, based on data about the real estate object, an indivisible object of unfinished construction/future real estate object entered into the Unified Database by any person via the Internet, which are confirmed by official documents for such an object. The list of data entered by a person into the Unified Database for the purpose of determining the estimated value of a real estate object is approved by the State Property Fund of Ukraine.
Based on the result of determining the estimated value of a real estate object, an indivisible object of unfinished construction/future real estate object, a certificate of its estimated value is formed using a single database, with each certificate automatically assigned a unique registration number.
If a person disagrees with the results of the automatic determination of the assessed value of a real estate object, an indivisible object of unfinished construction/future real estate object, he or she has the right to contact the subject of appraisal activity (appraiser) in order to determine the market value of such an object.
The entry of information from appraisal reports into the Unified Database is carried out by the subject of appraisal activity (appraiser) on the basis of the appraisal report, the electronic version of which is stored in the Unified Database. The list of data on the real estate object, indivisible object of unfinished construction/future real estate object from the appraisal report, which are entered by the subject of appraisal activity (appraiser) into the Unified Database for the purpose of registering the report in the Unified Database, is approved by the State Property Fund of Ukraine. Appraiser reports are registered in the Unified Database by the subjects of appraisal activity (appraisers) exclusively using a qualified electronic signature or an advanced electronic signature based on a qualified electronic signature certificate of the appraiser who directly conducted the appraisal, in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services".
{Paragraph twenty of clause 172.3 of Article 172 as amended by Law No. 2918-IX of 07.02.2023 }
Registration of the valuation report with assignment of a unique registration number is carried out by the Unified Database provided that the market value of the real estate object, indivisible object of unfinished construction/future real estate object determined in the valuation report is within the permissible 25 percent price range of market prices for comparable real estate objects, indivisible objects of unfinished construction/future real estate objects, information about which is contained in the Unified Database. Algorithms for establishing comparable real estate objects, indivisible objects of unfinished construction/future real estate objects by the Unified Database are determined by the State Property Fund of Ukraine.
If the market value of a real estate object, an indivisible object of unfinished construction/future real estate object specified in the appraisal report exceeds the permissible 25 percent price range, the Unified Database automatically refuses to register such a report. In such a case, the person using the appraisal report or the subject of appraisal activity (appraiser) has the right, within five working days from the date of refusal to register the appraisal report, to apply through the Unified Database or in writing to the State Property Fund of Ukraine with an application for review of the appraisal report in accordance with the Law of Ukraine "On Appraisal of Property, Property Rights and Professional Appraisal Activities". The State Property Fund of Ukraine considers such an application no more than five working days from the date of receipt and makes an appropriate decision. The specified decision is registered by the State Property Fund of Ukraine in the Unified Database no later than the next working day after its adoption, no later than the next working day after its adoption. The evaluation report based on the review results is subject to registration in the Unified Database with assignment of a unique registration number, subject to such a decision.
Access, entry, and verification of information to/from the Unified Database are free of charge. Generation of electronic certificates on the estimated value of a real estate object, an indivisible object of unfinished construction/future real estate object is free of charge.
An appraisal report that is not registered in the Unified Database, without a unique registration number assigned in accordance with the requirements of this Article, or more than six months have passed since the date of registration, shall not be used for taxation purposes. The Unified Database shall not assign a unique registration number to an appraisal report if more than five business days have passed since the date of the appraisal report (or, in the case of a review of the appraisal report, since the date of completion of such review).
When certifying transactions for the sale (exchange) or other alienation of real estate, an indivisible object of unfinished construction/future real estate, the notary checks the contents of the electronic certificate of the estimated value of the real estate, an indivisible object of unfinished construction/future real estate for the reliability of the data on the real estate, the unique registration number and the date of formation of this certificate or registration of the appraisal report in the Unified Database and the presence of a unique registration number assigned to it, and also verifies information about the subject of appraisal activity (appraiser) and the market value of the real estate, an indivisible object of unfinished construction/future real estate, contained in the appraisal report, with the data of the Unified Database.
A certificate of the estimated value of a real estate object, an indivisible object of unfinished construction/future real estate object based on the results of electronic determination of the estimated value is valid for 30 calendar days from the date of its formation by the Unified Database.
Access by a notary to the Unified Database to verify the fact of the formation by the Unified Database of a certificate on the estimated value of a real estate object, an indivisible object of unfinished construction/future real estate object or registration of an appraisal report in the Unified Database and assignment of a unique registration number to it, as well as to enter into the Unified Database information on the price of a real estate object, an indivisible object of unfinished construction/future real estate object, specified in the purchase and sale agreement certified by it, is free of charge.
In the event of an exchange of real estate, the taxpayer's income in the form of monetary compensation received by him from the alienation of the real estate, determined by:
a) paragraph one of clause 172.1 of this article - is not taxable;
b) clause 172.2 of this article, - is taxed at the rate determined by clause 167.2 of Article 167 of this Code.
172.4. When conducting transactions for the sale (exchange) of real estate, an indivisible object of unfinished construction/future real estate between individuals, a notary shall certify the relevant contract in the presence of an electronic certificate of the estimated value of such real estate, an indivisible object of unfinished construction/future real estate or an appraisal report registered in accordance with paragraph 172.3 of this article, and a document on the payment of tax to the budget by the party (parties) to the contract and enter information on the price of the purchase and sale contract into the Unified Database.
A public notary (public notary office) shall submit monthly, and a private notary quarterly, in accordance with the procedure established by this section for tax calculation, to the regulatory authority at the location of the public notary office or the workplace of a private notary, information in the form of such tax calculation, which shall indicate, respectively, information on purchase and sale contracts (mines) between individuals certified by public notaries during the reporting month and by private notaries during the reporting quarter (with a breakdown by months of the reporting quarter), including information provided for in the tax calculation, the submission of which is provided for in subparagraph "b" of paragraph 176.2 of Article 176 of this Code, including the price (value) of contracts and the amount of tax paid for each contract.
{Paragraph two of paragraph 172.4 of Article 172 as amended by Law No. 4015-IX of 10.10.2024 - regarding the entry into force of certain provisions, see paragraph 1 of Section II ; as amended by Law No. 4536-IX of 16.07.2025 }
172.5. The amount of tax is determined and paid independently through banks, non-bank payment service providers, and electronic money issuers:
{Paragraph one of clause 172.5 of Article 172 as amended by Law No. 2888-IX of 12.01.2023 }
a) a person who sells or exchanges real estate, an indivisible object of unfinished construction/future real estate with another individual - until the notarial certification of the purchase and sale agreement, exchange;
b) a person who owned a real estate object, an indivisible object of unfinished construction/future real estate object, alienated by a court decision on a change of owner and transfer of ownership of such property. An individual is obliged to reflect the income from such alienation in the annual tax return.
172.6. In the event of failure to perform a notarial act to certify a purchase and sale agreement, exchange of a real estate object, an indivisible object of unfinished construction/future real estate object for which tax has been paid, the taxpayer has the right to a refund of the overpaid amount of tax based on a tax return filed in accordance with the established procedure and supporting documents on the actual payment of the tax.
172.7. Simultaneously with the effect of clause 172.4 of this article, if a party to a contract of sale, exchange or other disposition of an object of real estate, an indivisible object of unfinished construction/future object of real estate, a divisible object of unfinished construction and from the assignment of rights under a contract of sale of an indivisible object of unfinished construction/future object of real estate, for which the price has been partially paid and an encumbrance of real rights in favor of the buyer has been registered, is a legal entity or a self-employed person, such a person is a tax agent of the taxpayer with respect to the accrual, withholding and payment (transfer) to the budget of tax on income received by the taxpayer from such sale (exchange).
172.8. For the purposes of this article, sale means any transfer of ownership or any other similar rights to real estate, an indivisible object of unfinished construction/future real estate, a divisible object of unfinished construction, except for their inheritance and donation.
172.9. Income from transactions on the sale (exchange) of real estate objects carried out by individuals - non-residents, is taxed in accordance with this article in the manner established for residents, at the rate determined by paragraph 167.1 of Article 167 of this Code.
172.10. The sale by residents and non-residents of inherited (received as a gift) real estate, an indivisible object of unfinished construction/future real estate is subject to taxation in accordance with the provisions of this article.
172.11. The procedure for determining the estimated value of real estate and objects of unfinished construction, an indivisible object of unfinished construction/future real estate object that are sold (exchanged) is determined by the State Property Fund of Ukraine.
Article 173. Procedure for taxation of transactions on the sale or exchange of movable property↑
173.1. The taxpayer's income from the sale (exchange) of a movable property object during the reporting tax year is taxed at the rate specified in Clause 167.2 of Article 167 of this Code.
Income from the sale (exchange) of an object of movable property (except for passenger cars, motorcycles, mopeds) is determined based on the price specified in the purchase and sale agreement (mine), but not lower than the estimated value of this object, determined in accordance with the law.
{Paragraph two of clause 173.1 of Article 173 as amended by Law No. 5413-VI of 02.10.2012 }
Income from the sale (exchange) of a passenger car, motorcycle, moped is determined based on the price specified in the purchase and sale agreement (mine), but not lower than the average market value of the relevant vehicle or not lower than its estimated, market value determined in accordance with the law (at the taxpayer's choice).
{Paragraph of Clause 173.1 of Article 173 as amended by Law No. 5413-VI of 02.10.2012 ; as amended by Law No. 354-IX of 05.12.2019 - for the entry into force of the amendments, see Clause 1 of Section II}
The average market value of passenger cars, motorcycles, mopeds is determined quarterly by the central executive body that ensures the formation of state policy in the field of economic development, in accordance with the procedure established by the Cabinet of Ministers of Ukraine (for each brand, model of such vehicles, taking into account the year of manufacture and mileage, based on an analysis of the actual sales prices of the relevant vehicles), and is published on the official website of this body in free access mode by the 10th of the month following the reporting quarter.
{Paragraph of clause 173.1 of Article 173 as amended by Law No. 5413-VI of 02.10.2012 }
173.2. As an exception to the provisions of paragraph 173.1 of this article, income received by a taxpayer from the sale (exchange) during the reporting (tax) year of one of the movable property objects in the form of a passenger car and/or motorcycle and/or moped is not subject to taxation.
Income received by a taxpayer from the sale (exchange) during the reporting (tax) year of a second movable property object in the form of a passenger car and/or motorcycle and/or moped is subject to taxation at the rate determined by Clause 167.2 of Article 167 of this Code.
{Paragraph two of item 173.2 of Article 173 as amended by Law No. 466-IX of 16.01.2020 }
Income received by a taxpayer from the sale (exchange) during the reporting (tax) year of the third and subsequent movable property in the form of a passenger car and/or motorcycle, and/or moped or other vehicle is subject to taxation at the rate determined by paragraph 167.1 of Article 167 of this Code.
{ Item 173.2 of Article 173 is supplemented by a paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Income received by a taxpayer from the sale (exchange) during the reporting (tax) year of the third and subsequent movable property objects in the form of a passenger car and/or motorcycle, and/or moped or other vehicle may be reduced by the value of such movable property object that was declared by the person as an object of declaration under the procedure of one-time (special) voluntary declaration), in accordance with Subsection 9 - 4 of Section XX of this Code.
{ Item 173.2 of Article 173 is supplemented by the fourth paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
{Clause 173.2 of Article 173 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 5413-VI of 02.10.2012 }
173.3. If a party to a contract of sale of movable property is a legal entity or a self-employed person, such a person shall be considered a tax agent of the taxpayer and shall be obliged to perform all the functions of a tax agent specified in this section. In this case, the tax agent shall withhold tax at the rates determined in accordance with paragraphs 173.1 or 173.2 of this Article, taking into account information on the priority of sale of movable property specified by the taxpayer in the contract of sale or in a separate application.
{Paragraph one of clause 173.3 of Article 173 as amended by Laws No. 3609-VI of 07.07.2011 , No. 466-IX of 16.01.2020 }
In the event of the sale (exchange) of a movable property object through the intermediary of a legal entity (its branch, department, other separate subdivision) or a representative office of a non-resident or an individual entrepreneur, or the conclusion and execution of contracts for the alienation of vehicles in the presence of officials of the bodies that carry out the registration (re-registration) of vehicles, such intermediary or the relevant body performs the functions of a tax agent in relation to the submission to the supervisory body of information on the amount of income and the amount of tax paid to the budget in the manner and within the terms established for tax calculation, and the taxpayer, when concluding the contract, is obliged to independently pay tax to the budget on income from transactions on the sale (exchange) of movable property objects.
{Paragraph two of clause 173.3 of Article 173 as amended by Law No. 1797-VIII of 21.12.2016 }
173.4. During the conduct of transactions for the alienation of movable property in accordance with the procedure provided for in this article:
a notary certifies the relevant contract of sale (barter) of movable property (except for passenger cars, motorcycles, mopeds) if there is a document on the valuation of the property and a document on the payment to the budget by the seller (parties to the barter contract) of the tax calculated based on the price specified in the contract;
{Paragraph two of clause 173.4 of Article 173 as amended by Law No. 5413-VI of 02.10.2012 }
when selling (exchange) passenger cars, motorcycles, mopeds, the relevant contracts are certified by a notary if there is a document confirming the payment to the budget by the seller (parties to the exchange contract) of the tax calculated based on the purchase price (exchange) specified in the purchase and sale contract, but not lower than the average market value of such vehicles;
{Paragraph of clause 173.4 of Article 173 as amended by Law No. 5413-VI of 02.10.2012 }
If, upon sale (exchange) of passenger cars, motorcycles, mopeds, their evaluation is carried out in accordance with the law, the notary shall certify the relevant contracts upon the presence of a document on payment to the budget by the seller (parties to the exchange agreement) of the tax calculated based on such estimated value of such vehicles, and a document on the evaluation of the vehicles.
{Paragraph of clause 173.4 of Article 173 as amended by Law No. 5413-VI of 02.10.2012 }
A public notary (public notary office) shall submit monthly, and a private notary quarterly, in accordance with the procedure established by this section for tax calculation, to the regulatory authority at the location of the public notary office or the workplace of a private notary, information in the form of such tax calculation, which shall indicate, respectively, information on purchase and sale contracts (mines) between individuals certified by public notaries during the reporting month and by private notaries during the reporting quarter (with a breakdown by months of the reporting quarter), including information provided for in the tax calculation, the submission of which is provided for in subparagraph "b" of paragraph 176.2 of Article 176 of this Code, including the price (value) of such contracts and the amount of tax paid for each contract;
{Paragraph of Clause 173.4 of Article 173 as amended by Laws No. 5413-VI dated 02.10.2012 , No. 4015-IX dated 10.10.2024 - regarding the entry into force of certain provisions, see Clause 1 of Section II ; as amended by Law No. 4536-IX dated 16.07.2025 }
Business entities that provide services for concluding stock market transactions or participate in their conclusion, provided that the estimated value of such movable property and a document on tax payment by the parties to the contract are available (a legal entity - monthly, and an individual entrepreneur - quarterly), in accordance with the procedure established by this section, shall submit to the regulatory authority a tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code, in which they indicate information about such transactions, including information about the amount of income and the amount of tax paid to the budget.
{Paragraph six of paragraph 173.4 of Article 173 as amended by Law No. 4015-IX of 10.10.2024 - regarding the entry into force of certain provisions, see paragraph 1 of Section II ; as amended by Law No. 4536-IX of 16.07.2025 }
Bodies, in the presence of whose officials, contracts of sale (purchase, supply) and other contracts are concluded and executed between individuals, shall, in accordance with the procedure established by law, register such vehicles if there is an estimated or average market value of such movable property and a document on the payment of tax by the parties to the contract, calculated in accordance with the procedure established by this Code, and shall, on a monthly basis, in accordance with the procedure established by this section, submit to the supervisory authority a tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code, in which information about such contracts (agreements) is indicated, including information about the amount of income and the amount of tax paid to the budget.
{Clause 173.4 of Article 173 is supplemented with a new paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 4015-IX of 10.10.2024 - regarding the entry into force of certain provisions, see clause 1 of section II }
For the purposes of this paragraph, the taxpayer independently determines the amount of tax and pays it to the budget through banks, non-bank payment service providers/electronic money issuers.
{ Paragraph eight of clause 173.4 of Article 173 as amended by Law No. 2888-IX of 12.01.2023 }
In the event of a court or arbitration court making a decision on the change of owner and transfer of ownership of movable property, the amount of tax is determined and paid independently through banks, non-bank payment service providers/electronic money issuers by the person who owned the movable property alienated under such a decision, based on the income from such alienation being reflected by him as part of the total annual taxable income.
{ Paragraph nine of clause 173.4 of Article 173 as amended by Law No. 2888-IX of 12.01.2023 }
{Clause 173.5 of Article 173 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
173.6. Income from transactions on the sale (exchange) of movable property carried out by individuals - non-residents, is taxed in accordance with this article in the manner established for residents, at the rate specified in paragraph 167.1 of Article 167 of this Code.
{Clause 173.6 of Article 173 as amended by Law No. 909-VIII of 24.12.2015 }
173.7. The sale by residents and non-residents of an inherited (received as a gift) movable property is subject to taxation in accordance with the provisions of this article.
173.8. For the purposes of this Article, sale shall mean any transfer of ownership of movable property, except for inheritance and gift. The provisions of this Article shall not apply to transactions with currency values that are taxable in accordance with subparagraph 165.1.51 of paragraph 165.1 of Article 165 of this Code.
{Clause 173.8 of Article 173 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 }
Article 174. Taxation of income received by a taxpayer as a result of his acceptance of funds, property, property or non-property rights as an inheritance or gift↑
174.1. The assets of a taxpayer's inheritance are divided for taxation purposes into:
a) real estate, indivisible object of unfinished construction/future real estate, divisible object of unfinished construction;
{Subparagraph "a" of paragraph 174.1 of Article 174 as amended by Law No. 2600-IX of September 20, 2022 }
b) movable property, in particular:
an antique or work of art;
natural precious stones or precious metal, jewelry using precious metals and/or natural precious stones;
any vehicle and its accessories;
other types of movable property;
c) an object of commercial property, namely: securities (except for deposit (savings) and mortgage certificates), corporate law, ownership of a business object as such, i.e. ownership of a single property complex, intellectual (industrial) property or the right to receive income from it, property and non-property rights;
d) the amount of insurance compensation (insurance payments) under insurance contracts, as well as the amount stored, respectively, in the pension deposit account, accumulative pension account, individual pension account of the testator - a participant in the accumulative pension system;
e) cash or funds stored in the testator's accounts/electronic wallets opened in banks, other financial institutions, non-bank payment service providers/electronic money issuers, deposit, savings, mortgage certificates, real estate fund certificates.
{Subparagraph "g" of paragraph 174.1 of Article 174 as amended by Law No. 2888-IX of 12.01.2023 }
174.2. Inheritance objects are taxed:
174.2.1. at zero rate:
a) objects of inheritance inherited by members of the testator's family of the first and second degrees of kinship;
{Subparagraph "a" of subparagraph 174.2.1 of paragraph 174.2 of Article 174 as amended by Law No. 1910-VIII of February 23, 2017 - applies to income received by a taxpayer as an inheritance/gift starting from January 1, 2017}
b) the value of the property specified in subparagraphs "a" , "b" , "g" of paragraph 174.1 of this article, which is inherited by a person who is a person with a disability of group I or has the status of an orphan or a child deprived of parental care, and the value of the property specified in subparagraphs "a", "b" of paragraph 174.1, which is inherited by a child with a disability;
c) monetary savings placed before January 2, 1992 in institutions of the Savings Bank of the USSR and the State Insurance of the USSR operating in the territory of Ukraine, as well as in state securities (bonds of the State Target Interest-Free Loan of 1990, bonds of the State Internal Winning Loan of 1982, state treasury obligations of the USSR, certificates of the Savings Bank of the USSR) and monetary savings of citizens of Ukraine placed in institutions of the Savings Bank of Ukraine and the former Ukrderzhstrakh during 1992-1994, the repayment of which did not occur, which are inherited by any heir;
174.2.2. at the rate determined by clause 167.2 of Article 167 of this Code, the value of any object of inheritance inherited by heirs not specified in subparagraph 174.2.1 of this clause;
{Subclause 174.2.2 of Clause 174.2 of Article 174 as amended by Law No. 1910-VIII of 23.02.2017 - applies to income received by a taxpayer as an inheritance/gift starting from January 1, 2017}
174.2.3. at the rate specified in paragraph 167.1 of Article 167 of this Code, for any object of inheritance inherited by an heir from a non-resident testator, and for any object of inheritance inherited by a non-resident heir from a resident testator.
{Subclause 174.2.3 of Clause 174.2 of Article 174 as amended by Law No. 909-VIII of 24.12.2015 }
174.3. The persons responsible for paying (transferring) tax to the budget are the heirs who received the inheritance.
Income in the form of the value of inherited property (funds, property, property or non-property rights) within the taxable limits is indicated in the annual tax return, except for non-resident heirs who are obliged to pay tax before notarization of inheritance objects or, in rural settlements, before registration by an authorized official of the relevant local government body at the place of opening the inheritance, and heirs who received objects as an inheritance that are taxed at a zero rate of personal income tax, as well as other resident heirs who paid tax before notarization of inheritance objects.
{Paragraph two of clause 174.3 of Article 174 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4661-VI of 04.24.2012 , No. 1910-VIII of 02.23.2017 - applies to income received by a taxpayer as an inheritance/gift starting from January 1, 2017 }
174.4. The state notary (state notary office) at the location of the state notary office and/or in rural settlements, an authorized official of the relevant local government body at the location of the inheritance, shall submit information to the controlling body on the form of such tax calculation, in which information on the issuance of certificates of the right to inheritance, as well as other information provided for by the tax calculation, the submission of which is provided for by subparagraph "b" of paragraph 176.2 of Article 176 of this Code, shall be indicated. In the same manner, notaries shall submit information on the certification of gift agreements.
{Paragraph one of clause 174.4 of Article 174 as amended by Law No. 4015-IX of 10.10.2024 - regarding the entry into force of certain provisions, see clause 1 of Section II ; as amended by Law No. 4536-IX of 16.07.2025 }
At the same time, such a tax calculation must necessarily indicate the amount of income in the form of the value of inherited property received by the taxpayer specified in subparagraph 174.2.2 of this paragraph.
A notary or, in rural settlements, an authorized official of the relevant local government body issues a certificate of inheritance to a non-resident heir if there is a document confirming that such heir has paid the tax on the value of the inheritance object.
{Clause 174.4 of Article 174 as amended by Law No. 1910-VIII of 23.02.2017 - applies to income received by a taxpayer as an inheritance/gift starting from January 1, 2017}
174.5. {Paragraph one of clause 174.5 of Article 174 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
In the event of transfer of the right to receive insurance benefits in accordance with Article 1229 of the Civil Code of Ukraine, the tax agent is the insurer - a financial institution.
174.6. Objects of donation specified in paragraph 174.1 of this article, donated to the taxpayer by another individual, are taxed in accordance with the rules established by this section for inheritance taxation.
Income in the form of a gift, accrued (paid, provided) to a taxpayer by a legal entity or self-employed person, is taxed on the general grounds provided for in this section for the taxation of additional benefits.
{Paragraph two of item 174.6 of Article 174 as amended by Law No. 466-IX of 16.01.2020 }
{Clause 174.6 of Article 174 as amended by Law No. 1910-VIII of 23.02.2017 - applies to income received by a taxpayer as an inheritance/gift starting from January 1, 2017}
174.7. The value of passenger cars, motorcycles, mopeds received as an inheritance or gift, which are subject to taxation in accordance with this article, is determined in accordance with the procedure established by paragraph three of clause 173.1 of Article 173 of this Code.
{Article 174 was supplemented by paragraph 174.7 in accordance with Law No. 5413-VI of 02.10.2012 }
174.8. In the event of inheritance of any inheritance objects that are taxed at a zero rate, the market value of such objects for taxation purposes is not determined.
{Paragraph one of clause 174.8 of Article 174 as amended by Law No. 354-IX of 05.12.2019 - for the entry into force of the amendments, see clause 1 of section II}
If objects donated to a taxpayer are taxed at a zero rate, the market value of such objects is not determined for tax purposes.
{Paragraph two of paragraph 174.8 of Article 174 as amended by Law No. 354-IX of 05.12.2019 - for the entry into force of the amendments, see paragraph 1 of Section II}
In other cases of receiving income in the form of inheritance/gifts, the object of taxation is the estimated value or market value of such inheritance/gifts, determined in accordance with Clause 172.3 of Article 172 of this Code.
{Paragraph three of paragraph 174.8 of Article 174 as amended by Law No. 354-IX of 05.12.2019 - for the entry into force of the amendments, see paragraph 1 of Section II}
{ Article 174 is supplemented by paragraph 174.8 in accordance with the Law No. 1910-VIII dated 02/23/2017 - applies to income received starting from January 1, 2017 by a taxpayer in the form of an inheritance/gift}
Article 175. Determination of the amount of interest paid by a taxpayer for the use of a mortgage loan for the purpose of calculating a tax deduction↑
175.1. A resident taxpayer has the right to include in the tax deduction a portion of the amount of interest for the use of a mortgage loan granted to the borrower in national or foreign currencies, actually paid during the reporting tax year.
When paying interest on a mortgage loan in foreign currency, the amount of payments on such interest made in foreign currency is converted into hryvnia at the official currency (exchange) rate of the National Bank of Ukraine, effective on the day of payment of such interest.
Such a right arises if a residential building (apartment, room) is built or purchased using a mortgage loan, determined by the taxpayer as his main place of residence, in particular according to the mark in the passport on registration at the location of such housing.
175.2. If a house (apartment, room) is purchased at the expense of a mortgage loan, the part of the amount of interest included in the tax deduction of the taxpayer - borrower of the mortgage loan is equal to the product of the amount of interest actually paid by the taxpayer during the reporting tax year on its repayment and the coefficient that takes into account the minimum area of the dwelling for determining the tax deduction, calculated in accordance with paragraph 175.3 of this article.
If a house (apartment, room) was built at the expense of a mortgage housing loan, part of the amount of interest included in the tax deduction of the taxpayer - borrower of a mortgage housing loan, accrued in the first year of repayment of such loan, may be included in the tax deduction based on the results of the reporting tax year in which the constructed residential mortgage object passes into the ownership of the taxpayer and begins to be used as a primary residence, with a sequential transfer of the right to include in the tax deduction the subsequent annual amounts of interest actually paid by the taxpayer during the validity period of the right to include part of such interest in the tax deduction, as provided for in paragraph 175.4 of this Article. In this case, the total amount of the portion of the interest amount allowed for inclusion in the tax deduction is equal to the product of the amount of interest actually paid by the taxpayer-borrower during the relevant reporting tax year, which is taken into account in the repayment, and the coefficient that takes into account the minimum area of the dwelling for determining the tax deduction, calculated in accordance with paragraph 175.3 of this article.
175.3. The coefficient that takes into account the minimum area of housing for determining the tax deduction for the amount of interest on a mortgage loan is calculated using the following formula:
K = MP/FP,
where K is the coefficient;
MP - minimum total area of housing, equal to 100 square meters;
FP - the actual total area of housing built (purchased) by the taxpayer at the expense of a mortgage loan.
If this coefficient is greater than one, the amount of interest actually paid on the mortgage loan without applying such a coefficient is included in the tax deduction.
175.4. The right to include in the tax deduction the amount calculated in accordance with this article is granted to the taxpayer for one mortgage loan for 10 consecutive calendar years starting from the year in which:
the residential mortgage object is purchased;
The constructed residential mortgage object becomes the property of the taxpayer and begins to be used as a primary residence.
If the mortgage loan has a repayment term of more than 10 calendar years, the taxpayer has the right to include part of the interest amount in the tax deduction for the new mortgage loan after the full repayment of the principal amount and interest of the previous mortgage loan.
The taxpayer may restore the right to include part of the amount of interest actually paid on a new mortgage loan in the tax deduction without complying with the deadlines specified in this article in the case of:
a) forced sale or confiscation of the mortgaged property in cases provided for by law;
b) liquidation of a residential mortgage object by decision of a local executive body or local government body in cases provided for by law;
c) destruction of the residential mortgage object or its recognition as unfit for use due to force majeure;
d) sale of the mortgaged property due to the insolvency (bankruptcy) of the taxpayer in accordance with the law.
175.5. If the amount of a mortgage loan received by an individual exceeds the amount spent on the purchase (construction) of the mortgaged property, the amount of interest paid for the use of the mortgage loan in the part spent for the intended purpose is included in the expenses.
Article 176. Ensuring the fulfillment of tax obligations and single contribution obligations↑
{Title of Article 176 as amended by Law No. 116-IX of September 19, 2019 }
176.1. Taxpayers are obliged to:
a) keep records of income and expenses in the amounts necessary to determine the amount of total annual taxable income, if such a taxpayer is obliged to file a declaration in accordance with this Code or has the right to such filing for the purpose of refunding overpaid taxes, including when applying the right to a tax deduction.
{Paragraph one of subparagraph "a" of paragraph 176.1 of Article 176 as amended by Law No. 3050-IX of 11.04.2023 }
The forms of such accounting and the procedure for its maintenance are determined by the central executive body that ensures the formation and implementation of state financial policy;
b) receive and store, within the limitation period established by this Code, primary accounting documents, including those on the basis of which expenses are determined when calculating investment profit and the taxpayer's tax discount is formed;
c) submit a tax return in the prescribed form within the specified time limits in cases where, according to the provisions of this Code, such submission is mandatory.
At the request of the regulatory authority and within the limits of its powers determined by law, taxpayers are obliged to present documents and information related to the occurrence of income or the right to receive a tax discount, the calculation and payment of tax, and confirm with the necessary documents the accuracy of the information specified in the tax return for this tax;
{Subparagraph "c" of paragraph 176.1 of Article 176 as amended by Law No. 3050-IX of 11.04.2023 }
d) submit to persons who, in accordance with this Code, are determined to be responsible for withholding (calculation) and paying tax to the budget, documents confirming the right of the taxpayer who receives such income to apply social tax benefits;
e) in accordance with the procedure established by law, allow officials (service personnel) of the controlling body to enter the territory or premises used by the taxpayer to receive income from conducting economic activities;
e) take measures provided for by this Code in the event of a change in the grounds for receiving a tax social benefit;
e) timely pay the agreed amount of tax liabilities, as well as the amount of punitive (financial) sanctions assessed by the regulatory authority, and penalties, with the exception of the amount that is contested in administrative or judicial proceedings.
{Sub-paragraph "e" of paragraph 176.1 of Article 176 is excluded on the basis of the Law No. 909-VIII dated 24.12.2015 }
{Sub-paragraph "g" of paragraph 176.1 of Article 176 was excluded on the basis of Law No. 1588-VII of 04.07.2014 }
{Clause 176.1 of Article 176 as amended by Law No. 1797-VIII of 21.12.2016 }
176.2. Persons who, in accordance with this Code, have the status of tax agents and payers of a single contribution are obliged to:
{Paragraph one of clause 176.2 of Article 176 as amended by Law No. 116-IX of September 19, 2019 }
a) timely and fully calculate, withhold and pay (transfer) to the budget the income tax paid in favor of the taxpayer and taxed before or at the time of such payment at its expense;
b) submit a tax calculation of the amounts of income accrued (paid) in favor of taxpayers - individuals, and the amounts of tax withheld from them, as well as the amounts of the accrued single contribution to the controlling body at the main place of registration:
{Paragraph one of subparagraph "b" of paragraph 176.2 of Article 176 as amended by Law No. 4015-IX of 10.10.2024 - regarding the entry into force of individual provisions, see paragraph 1 of Section II ; as amended by Law No. 4536-IX of 16.07.2025 }
for tax agents who are individuals - entrepreneurs and persons engaged in independent professional activities - within the terms established by this Code for the tax quarter (with a breakdown by months of the reporting quarter);
{Paragraph of subparagraph "b" of paragraph 176.2 of Article 176 as amended by Law No. 4536-IX of 16.07.2025 }
for other tax agents, except for individuals - entrepreneurs and/or persons engaged in independent professional activities - within the terms established by this Code for the tax month.
{Paragraph of subparagraph "b" of paragraph 176.2 of Article 176 as amended by Law No. 4536-IX of 16.07.2025 }
Such a tax calculation is submitted only if the amounts of the specified income are accrued to the taxpayer - an individual tax agent, a single contribution payer during the reporting period.
{Paragraph of subparagraph "b" of paragraph 176.2 of Article 176 as amended by Law No. 4536-IX of 16.07.2025 }
If a separate subdivision of a legal entity is not authorized to calculate, withhold and pay (transfer) tax to the budget, the tax calculation for such subdivision shall be submitted by the legal entity to the controlling authority at the main place of registration;
{Subparagraph "b" of paragraph 176.2 of Article 176 as amended by Law No. 3221-VI of 07.04.2011 ; as amended by Law No. 116-IX of 19.09.2019 }
c) submit, at the request of the taxpayer, information on the amount of income paid to him, the amount of social tax benefits applied, and the amount of tax withheld;
d) submit to the regulatory authority other information on the taxation of income of an individual taxpayer in the amounts and in accordance with the procedure specified in this section and section II of this Code;
e) bear responsibility in cases specified in this Code.
{Subparagraph "g" of paragraph 176.2 of Article 176 as amended by Law No. 3609-VI of 07.07.2011 }
{Subparagraph "d" of paragraph 176.2 of Article 176 was excluded on the basis of Law No. 3221-VI of 07.04.2011 }
Article 177. Taxation of income received by an individual entrepreneur from conducting economic activities, except for persons who have chosen a simplified taxation system↑
177.1. Income of individual entrepreneurs received during a calendar year from conducting business activities is taxed at the rate determined by paragraph 167.1 of Article 167 of this Code.
{Clause 177.1 of Article 177 as amended by Law No. 909-VIII of 24.12.2015 }
177.2. The object of taxation is net taxable income, i.e. the difference between total taxable income (revenue in monetary and non-monetary form) and documented expenses related to the economic activities of such an individual entrepreneur.
177.3. For an individual entrepreneur registered as a value-added tax payer, the amounts of value-added tax included in the price of purchased or sold goods (works, services) are not included in expenses and income.
177.3.1. The amounts of excise tax on excisable goods sold by retail business entities are not included in the income of an individual entrepreneur.
{Clause 177.3 of Article 177 is supplemented by subparagraph 177.3.1 in accordance with Law No. 1797-VIII of 21.12.2016 }
177.3.2. The income of an individual entrepreneur shall not include amounts of income in the form of a budget grant.
Taxation of income received by an individual entrepreneur in the form of such a grant is carried out in accordance with the procedure specified in paragraph 170.7 - 1 of Article 170 of this Code.
{Clause 177.3 of Article 177 is supplemented by subparagraph 177.3.2 in accordance with Law No. 962-IX of 04.11.2020 }
177.4. The list of expenses directly related to generating income includes:
177.4.1. expenses, which include the cost of raw materials, materials, goods that form the basis for the manufacture (sale) of products or goods (provision of works, services), purchased semi-finished products and components, fuel and energy, building materials, spare parts, containers and packaging materials, auxiliary and other materials that can be directly attributed to a specific cost object;
177.4.2. expenses for the payment of labor of individuals who are in an employment relationship with such a taxpayer (hereinafter referred to as employees), which include expenses for the payment of basic and additional wages and other types of incentives and payments based on tariff rates, in the form of bonuses, incentives, reimbursement of the cost of goods (works, services), expenses for payment for the performance of works, services under civil law contracts, any other payment in cash or in kind established by agreement of the parties (except for amounts of material assistance that are exempt from taxation in accordance with the provisions of this section);
mandatory payments, as well as compensation for the cost of services provided to employees in cases provided for by law, taxpayer contributions for mandatory life or health insurance of employees in cases provided for by law;
177.4.3. the amount of taxes and fees related to the conduct of economic activities of such an individual entrepreneur (except for value added tax for an individual entrepreneur registered as a value added tax payer, and excise tax, personal income tax on income from economic activities, tax on real estate other than land plots, on residential real estate); the amount of a single contribution to mandatory state social insurance in the amounts and in the manner established by law; payments paid for obtaining licenses for conducting certain types of economic activity by an individual entrepreneur, royalties in favor of rightholders, as remuneration for the use of copyright objects and (or) related rights or as deductions in favor of rightholders on the basis of agreements concluded by such a taxpayer with collective management organizations in accordance with the Law of Ukraine "On Effective Management of Property Rights of Rightholders in the Field of Copyright and (or) Related Rights", obtaining a permit, other document of a permissive nature, related to the economic activity of an individual entrepreneur;
{Subclause 177.4.3 of clause 177.4 of Article 177 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 ; as amended by Law No. 1914-IX of 11/30/2021 }
177.4.4. other expenses, which include expenses related to conducting business activities that are not specified in subparagraphs 177.4.1-177.4.3 of this paragraph, which include expenses for sending employees on business trips, for communication services, advertising, payments for settlement and cash services, for paying rent, repairs and maintenance of property used in business activities, for transportation of finished products (goods), freight forwarding and other services related to the transportation of products (goods), the cost of purchased services directly related to the production of goods, performance of work, provision of services.
177.4.5. The following are not included in the entrepreneur's expenses:
expenses not related to the conduct of business activities by such an individual entrepreneur;
costs of acquisition, independent production of fixed assets and costs of acquisition of intangible assets subject to amortization;
expenses for the acquisition and maintenance of fixed assets specified in paragraphs eight to ten of subparagraph 177.4.6 of this paragraph;
{Paragraph four of subparagraph 177.4.5 of clause 177.4 of Article 177 as amended by Law No. 466-IX of 16.01.2020 }
undocumented expenses;
expenses for which, based on the totality of the conditions of the transaction, there are grounds to believe that the existing circumstances (facts) indicate that it was carried out with the aim of providing an improper benefit to an official (including an official of a foreign state);
{Subparagraph 177.4.5 of paragraph 177.4 of Article 177 is supplemented by the sixth paragraph in accordance with Law No. 4112-IX of 04.12.2024 }
expenses that the regulatory authority does not take into account (does not recognize) due to the fact that, in accordance with the legislation, it has been established that the transaction was carried out on behalf of and/or in the interests of the taxpayer with the aim of providing an unlawful benefit during the commission of a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, directly or indirectly (through third parties), regardless of the amount of the unlawful benefit.
{Subparagraph 177.4.5 of paragraph 177.4 of Article 177 is supplemented by paragraph seven in accordance with Law No. 4112-IX of 04.12.2024 }
For the purposes of applying paragraph six of this subparagraph, when considering the circumstances (facts) related to the relevant transaction that may indicate that it was carried out with the aim of providing an illegal benefit to an official, the actual actions of the parties to the transaction and the actual circumstances of the transaction in accordance with its essence shall be taken into account, and for a transaction related to an official of a foreign state, the list published on the official website of the National Anti-Corruption Bureau of Ukraine in accordance with paragraph 12 of part one of Article 16 of the Law of Ukraine "On the National Anti-Corruption Bureau of Ukraine" shall also be used.
{Subparagraph 177.4.5 of paragraph 177.4 of Article 177 is supplemented by paragraph eight in accordance with Law No. 4112-IX of 04.12.2024 }
{Clause 177.4 of Article 177 is supplemented by subparagraph 177.4.5 in accordance with Law No. 1797-VIII of 21.12.2016 }
177.4.6. The entrepreneurs specified in this article have the right (at their own discretion) to include depreciation deductions in the costs associated with the conduct of their business activities, with appropriate separate accounting of such costs. In this case, depreciation is subject to:
expenses for the acquisition of fixed assets and intangible assets;
costs for independent production of fixed assets, reconstruction, modernization and other types of improvements to fixed assets (except for current repairs).
{Paragraph three of subparagraph 177.4.6 of clause 177.4 of Article 177 as amended by Law No. 466-IX of 16.01.2020 }
The following expenses are not subject to depreciation and are fully included in the expenses of the reporting period:
carrying out current repairs;
{Paragraph five of subparagraph 177.4.6 of clause 177.4 of Article 177 as amended by Law No. 466-IX of 16.01.2020 }
liquidation of fixed assets (in terms of residual value).
The following fixed assets are not subject to depreciation:
{Paragraph seven of subparagraph 177.4.6 of clause 177.4 of Article 177 as amended by Law No. 466-IX of 16.01.2020 }
land plots;
residential real estate objects;
passenger cars.
{Paragraph ten of subparagraph 177.4.6 of clause 177.4 of Article 177 as amended by Law No. 466-IX of 16.01.2020 }
{Clause 177.4 of Article 177 is supplemented by subparagraph 177.4.6 in accordance with Law No. 1797-VIII of 21.12.2016 }
177.4.7. The calculation of depreciation of fixed assets and intangible assets is carried out using the straight-line depreciation method, according to which the annual depreciation amount is determined by dividing the original cost of the fixed assets and intangible assets being depreciated by the useful life of the fixed assets and intangible assets.
{Clause 177.4 of Article 177 is supplemented by subparagraph 177.4.7 in accordance with Law No. 1797-VIII of 21.12.2016 }
177.4.8. Accounting for the depreciable value is kept for each object.
{Clause 177.4 of Article 177 is supplemented by subparagraph 177.4.8 in accordance with Law No. 1797-VIII of 21.12.2016 }
177.4.9. Depreciation is accrued over the useful life (operation) of the fixed assets and intangible assets, independently established by the individual, but not less than the minimum allowable useful life of the fixed assets and intangible assets:
Groups
Minimum allowable useful life, years
1 - Capital expenditures for land improvements not related to construction
15
2 - Buildings, structures, transmitting devices
10
3 - Machinery, equipment, animals, perennial plantings, etc.
5
4 - Intangible assets
according to the title document, but not less than two years
This subparagraph applies exclusively to fixed assets and intangible assets, the costs of acquisition or independent production of which are documented.
{Clause 177.4 of Article 177 is supplemented by subparagraph 177.4.9 in accordance with Law No. 1797-VIII of 21.12.2016 }
{Clause 177.4 of Article 177 as amended by Laws No. 3609-VI of 07.07.2011 , No. 71-VIII of 28.12.2014 }
177.5. Individual entrepreneurs shall submit a tax declaration to the regulatory authority at the location of their tax address based on the results of the calendar year within the terms established by this Code for the annual reporting tax period, which shall also indicate advance payments of income tax.
177.5.1. Advance payments for personal income tax shall be calculated by the taxpayer independently, except for the case specified in subparagraph 177.5.1 - 1 of this paragraph, according to the actual data of accounting for income and expenses, which is maintained in accordance with paragraph 177.10 of this article, without taking into account the income and expenses specified in the third paragraph of paragraph 177.10 of this article, for each calendar quarter and shall be paid to the budget by the 20th day of the month following each calendar quarter (by April 20, by July 20 and by October 20). The advance payment for the fourth calendar quarter shall not be calculated and paid.
{Paragraph one of subparagraph 177.5.1 of paragraph 177.5 of Article 177 as amended by Law No. 786-IX of July 14, 2020 ; as amended by Law No. 4015-IX of October 10, 2024 }
If the result of the calculation of the advance payment for the relevant calendar quarter is a negative value, then the advance payment for such period is not paid.
{ Subparagraph 177.5.1 of paragraph 177.5 of Article 177 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 909-VIII of 24.12.2015 }
177.5.1 - 1. Taxpayers - individuals - entrepreneurs who engage in retail fuel trade are obliged to pay an advance payment of personal income tax every month, no later than the 20th of the current month, for each place of retail fuel trade, information about which is entered in the Unified Register of Licensees and Places of Fuel Circulation as of the first day of the current month, in the amount determined by this subparagraph.
The terms "retail fuel trade", "retail fuel trade location" are used in the meanings given in the Law of Ukraine "On State Regulation of the Production and Circulation of Ethyl Alcohol, Alcohol Distillates, Bioethanol, Alcoholic Beverages, Tobacco Products, Tobacco Raw Materials, Liquids Used in Electronic Cigarettes, and Fuel".
The advance payment for personal income tax is paid for each place of retail sale of fuel, information about which is entered in the Unified Register of Licensees and Places of Fuel Circulation as of the first day of the current month:
a) in the amount of 60 thousand hryvnias for each place, except for the cases provided for in subparagraphs "b" and "c" of this subparagraph;
b) for a fuel retail outlet selling exclusively liquefied gas - in the amount of 30 thousand hryvnias for each location;
c) for a place of retail sale of fuel, where several types of fuel are sold and the share of sales of liquefied gas in liters, brought to a temperature of 15 °C, in the total volume of fuel sold during the previous month is 50 percent or more - in the amount of 45 thousand hryvnias for each place.
Advance payments for personal income tax paid in accordance with this subparagraph shall be an integral part of the personal income tax.
A monetary obligation in the form of an advance payment of personal income tax, defined by this subparagraph, is considered agreed upon from the moment such obligation arises, which is determined by the calendar date established by the first paragraph of this subparagraph for the deadline for payment of the advance payment of personal income tax to the relevant budget.
If a taxpayer fails to pay the agreed amount of the advance payment for personal income tax, determined in accordance with this subparagraph, within the period established by the first paragraph of this subparagraph, such taxpayer shall be held liable in the form of a fine in the amounts determined by Article 124 of this Code.
For the purposes of this sub-item, liquefied gas shall be considered to be propane or a mixture of propane and butane, liquefied natural gas, other gases, according to the codes according to the UKT FEA 2711 11 00 00 , 2711 12 11 00, 2711 12 19 00, 2711 12 91 00, 2711 12 93 00, 2711 12 94 00, 2711 12 97 00, 2711 13 10 00, 2711 13 30 00, 2711 13 91 00, 2711 13 97 00, 2711 14 00 00, 2711 19 00 00 and/or are recorded in the electronic administration system for the sale of fuel and ethyl alcohol under the conditional code 2711 in liters, brought to a temperature of 15 °C.
{Clause 177.5 of Article 177 is supplemented by subparagraph 177.5.1 - 1 in accordance with Law No. 4015-IX of 10.10.2024 }
177.5.2. Individual entrepreneurs who are registered during the year in accordance with the procedure established by law, or who are switching to a simplified system of taxation, accounting and reporting, or who have switched from a simplified system of taxation, accounting and reporting, shall submit a tax return based on the results of the reporting year in which such activity was started or the transition to (transition from) a simplified system of taxation, accounting and reporting took place. Taxpayers shall calculate and pay advance payments within the terms specified in subparagraph 177.5.1 of paragraph 177.5 of this Article, which shall occur in the reporting tax year.
{Subparagraph 177.5.2 of paragraph 177.5 of Article 177 as amended by Law No. 466-IX of 16.01.2020 }
177.5.3. The final calculation of personal income tax for the reporting tax year is carried out by the payer independently according to the data specified in the annual tax return, taking into account the personal income tax paid by him during the year on the basis of documentary confirmation of the fact of its payment.
For taxpayers - individuals - entrepreneurs engaged in retail trade in fuel, the tax liability for personal income tax calculated based on the results of such final calculation for the reporting tax year is reduced by the amount of advance payments paid in accordance with subparagraph 177.5.1 - 1 of this paragraph, while the amount of such reduction must not exceed the amount of the calculated tax liability for this tax.
Overpaid tax amounts (except for the cases specified in paragraphs four and five of this sub-item) shall be credited against future payments of this tax or refunded to the taxpayer in accordance with the procedure provided for by this Code.
If the amount of the advance tax payment previously paid during the reporting tax year in accordance with subparagraph 177.5.1 - 1 of this paragraph exceeds the amount of the accrued tax liability for personal income tax for such reporting tax year, the amount of such excess shall not be credited against future payments of this tax.
The amount of advance tax payments paid in accordance with subparagraph 177.5.1 - 1 of this paragraph shall not be refunded to the taxpayer as excessively and/or erroneously paid tax liabilities, may not be credited against other taxes and fees (mandatory payments) and shall not be subject to the provisions of Article 43 of this Code.
{Subclause 177.5.3 of clause 177.5 of Article 177 as amended by Laws No. 3609-VI of 07.07.2011 , No. 71-VIII of 28.12.2014 ; as amended by Law No. 4015-IX of 10.10.2024 }
177.6. If an individual entrepreneur receives income other than from conducting entrepreneurial activities, within the scope of the types of such activities chosen by him, such income is taxed according to the general rules established by this Code for individual taxpayers.
177.7. An individual entrepreneur is considered a tax agent of an employee - an individual with whom he or she has an employment or civil-law relationship, or of any other individual with respect to any taxable income accrued (paid, provided) in favor of such individual.
177.8. When accruing (paying) income from entrepreneurial activity to an individual entrepreneur, the business entity and/or self-employed person who accrues (pays) such income shall not withhold income tax at the source of payment if the individual entrepreneur who receives such income has provided a copy of a document confirming his state registration in accordance with the law as a business entity. This rule shall not apply in the case of accruing (paying) income for the performance of certain work and/or the provision of a service under a civil law contract, when it is established that the relationship under such a contract is actually labor, and the parties to the contract may be equated to an employee or employer in accordance with subparagraphs 14.1.195 and 14.1.222 of paragraph 14.1 of Article 14 of this Code.
{Clause 177.8 of Article 177 as amended by Law No. 3205-VI of 07.04.2011 ; as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 4834-VI of 24.05.2012 }
177.9. Taxation of income received by an individual entrepreneur who has chosen a different system of taxation of income from conducting economic activities shall be carried out in accordance with the rules established by this Code.
177.10. Individual entrepreneurs are required to keep records of income and expenses and have supporting documents regarding the origin of goods. Records of income and expenses may be kept in paper and/or electronic form, including through an electronic account.
Accounting for income and expenses from the production and sale of own agricultural products is kept separately from accounting for income and expenses from other types of economic activity.
{ Item 177.10 of Article 177 is supplemented with a new paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
Accounting for income and expenses from the retail sale of fuel, retail sale of alcoholic beverages and/or tobacco products, which is carried out at the address of the place of retail sale of fuel, is kept separately from accounting for income and expenses from other types of economic activity.
{Paragraph 177.10 of Article 177 is supplemented with a new paragraph in accordance with Law No. 4015-IX of 10.10.2024 }
The standard form in which income and expenses are recorded and the procedure for maintaining such records are determined by the central executive body that ensures the formation and implementation of state financial policy.
Individual entrepreneurs use payment transaction registrars in accordance with the Law of Ukraine "On the Use of Payment Transaction Registrars in the Sphere of Trade, Public Catering and Services".
{ Clause 177.10 of Article 177 as amended by Laws No. 71-VIII of 12/28/2014 , No. 129-IX of 09/20/2019 , No. 466-IX of 01/16/2020 ; as amended by Law No. 786-IX of 07/14/2020 }
177.11. Individual entrepreneurs shall submit an annual tax return within the period specified in subparagraph 49.18.4 of paragraph 49.18 of Article 49 of this Code, which, along with income from entrepreneurial activity, shall indicate other income from sources originating in Ukraine and foreign income, as well as information on the amounts of the single contribution charged on income from entrepreneurial activity in the amounts determined in accordance with the law.
{Paragraph one of clause 177.11 of Article 177 as amended by Laws No. 116-IX of September 19, 2019 , No. 3050-IX of April 11, 2023 }
Individuals in respect of whom state registration of termination of entrepreneurial activity of an individual entrepreneur has been carried out by his/her decision shall submit a tax return for the last basic tax (reporting) period, which reflects exclusively income from entrepreneurial activity, within the terms established by this Code for the monthly tax period.
{Paragraph 177.11 of Article 177 is supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; with amendments made in accordance with the Law No. 466-IX dated 16.01.2020 }
In the event of state registration of the termination of entrepreneurial activity of an individual entrepreneur by his/her decision, the last basic tax (reporting) period is the period from the day following the end of the previous basic tax (reporting) period to the last day of the calendar month in which state registration of the termination of entrepreneurial activity was carried out.
{Paragraph 177.11 of Article 177 was supplemented with a third paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
177.12. Foreigners and stateless persons who are registered as entrepreneurs in accordance with the legislation of Ukraine are residents, and they are subject to the provisions of paragraph 177.11 of this Article.
177.13. An individual entrepreneur who makes any payments from income originating in Ukraine to a non-resident legal entity or a person authorized by him (except for a permanent representative office in Ukraine) shall calculate and pay corporate income tax on the income (profits) of non-residents in the manner, amount and terms established by Section III of this Code.
{ Article 177 supplemented by paragraph 177.13 in accordance with the Law No. 466-IX dated 16.01.2020 }
177.14. Registered entrepreneurs, individuals - owners, tenants, users on other terms (including emphyteusis terms) of land plots classified as agricultural lands, who produce their own agricultural products, as well as heads of family farms, including land plots owned by members of such a family farm and used by such a family farm, are required to submit an appendix with the calculation of the total minimum tax liability as part of the annual tax return.
Such an annex shall, in particular, specify:
cadastral numbers of land plots used by such an entrepreneur to carry out entrepreneurial activities and for which the minimum tax liability is determined, their normative monetary value and area;
the amount of the total minimum tax liability, the amount of the minimum tax liability for each land plot separately;
the total amount of taxes, fees, and payments paid by the taxpayer, the control over the collection of which is entrusted to the regulatory authorities, related to the production and sale of own agricultural products and/or to the ownership and/or use (lease, sublease, emphyteusis, permanent use) of land plots classified as agricultural land, and the costs of renting land plots determined in accordance with paragraph 177.15 of this article (hereinafter in this paragraph - the total amount of taxes, fees, payments, and costs of renting land plots) during the tax (reporting) year;
the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and land lease expenses paid.
{ Article 177 supplemented by paragraph 177.14 in accordance with the Law No. 1914-IX dated 30.11.2021 }
177.15. The difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is calculated by subtracting from the total minimum tax liability the total amount of taxes, fees, payments and expenses paid during the tax (reporting) year for the lease of land plots.
The amount of taxes, fees, payments and expenses paid for land leases includes:
personal income tax and military levy on net taxable income from the sale of one's own agricultural products;
personal income tax and military levy on the income of individuals who are in an employment or civil-law relationship with the taxpayer (except for income paid for the purchase of goods from individuals), on income under lease, sublease, and emphyteusis agreements for agricultural land plots;
single tax (in the event of a transition in the tax (reporting) year from a simplified taxation system to a general one);
land tax for land plots classified as agricultural land used in business activities;
rental fee for special use of water;
20 percent of the costs of paying rent for land plots classified as agricultural land, the lessors of which are legal entities and/or which are in state or municipal ownership.
The amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
{ Article 177 supplemented by paragraph 177.15 in accordance with the Law No. 1914-IX dated 30.11.2021 }
177.16. In the case of using a land plot on the right of emphyteusis, the personal income tax and military levy paid when making payments under such an emphyteusis agreement are taken into account annually in a share calculated in proportion to the annual amount of accrued depreciation on an intangible asset in the form of the right to use the land plot under the emphyteusis agreement.
{ Article 177 supplemented by paragraph 177.16 in accordance with the Law No. 1914-IX dated 30.11.2021 }
177.17. If the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is positive, the taxpayer is obliged to increase the amount of personal income tax payable to the budget specified in the annual tax return by such positive value and pay such increased amount of tax to the budget in the manner and within the terms specified by this Code for the payment of personal income tax. The positive value of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is part of the personal income tax liabilities.
{ Article 177 is supplemented by paragraph 177.17 in accordance with the Law No. 1914-IX dated 30.11.2021 }
177.18. The positive value of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots shall be paid to the budget in accordance with the procedure and within the terms specified by this Code for the payment of personal income tax.
{ Article 177 supplemented by paragraph 177.18 in accordance with the Law No. 1914-IX dated 30.11.2021 }
177.19. The amount of personal income tax in the positive part of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is paid (transferred) to local budgets at the location of the land plots in proportion to the specific weight of the area of each of the land plots classified as agricultural land.
{ Article 177 supplemented by paragraph 177.19 in accordance with the Law No. 1914-IX dated 30.11.2021 }
177.20. The amount of personal income tax in the positive part of such difference is not taken into account in the total amount of taxes, fees, payments and expenses paid for the lease of land plots in the next tax (reporting) year.
{ Article 177 is supplemented by paragraph 177.20 in accordance with the Law No. 1914-IX dated 30.11.2021 }
Article 178. Taxation of income received by an individual engaged in independent professional activity↑
178.1. Persons who intend to engage in independent professional activities are required to register with the regulatory authorities at their place of permanent residence as self-employed persons and obtain a certificate of registration in accordance with Article 65 of this Code.
{Clause 178.1 of Article 178 as amended by Law No. 3609-VI of 07.07.2011 }
178.2. Income of citizens received during a calendar year from independent professional activities shall be taxed at the rate determined by paragraph 167.1 of Article 167 of this Code.
{Clause 178.2 of Article 178 as amended by Law No. 909-VIII of 24.12.2015 }
178.3. Taxable income is considered to be the total net income, i.e. the difference between income and documented expenses necessary for carrying out a certain type of independent professional activity.
In the event that a person engaged in independent professional activity does not receive a certificate of registration, the object of taxation is the income received from such activity without taking into account expenses.
{Paragraph two of clause 178.3 of Article 178 as amended by Law No. 3609-VI of 07.07.2011 }
For private executors, taxable income is considered to be the total net income, i.e. the difference between the income consisting of the amounts of remuneration received in accordance with the Law of Ukraine "On Bodies and Persons Enforcing Court Decisions and Decisions of Other Bodies" and the documented expenses necessary for conducting independent professional activities.
{Item 178.3 of Article 178 is supplemented by the third paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
The income of a person engaged in independent professional activity shall not include amounts of income in the form of a budget grant. Taxation of income received by a person engaged in independent professional activity in the form of such a grant shall be carried out in accordance with the procedure specified in Clause 170.7 - 1 of Article 170 of this Code.
{Item 178.3 of Article 178 is supplemented by the fourth paragraph in accordance with the Law No. 962-IX dated 04.11.2020 }
The following are not included in the expenses of a person engaged in independent professional activity:
{Subparagraph 178.3 of Article 178 is supplemented by paragraph five in accordance with Law No. 4112-IX of 04.12.2024 }
expenses for which, based on the totality of the conditions of the transaction, there are grounds to believe that the existing circumstances (facts) indicate that it was carried out with the aim of providing an improper benefit to an official (including an official of a foreign state);
{Subparagraph 178.3 of Article 178 is supplemented by the sixth paragraph in accordance with Law No. 4112-IX of 04.12.2024 }
expenses that the regulatory authority does not take into account (does not recognize) due to the fact that, in accordance with the legislation, it has been established that the transaction was carried out on behalf of and/or in the interests of the taxpayer with the aim of providing an unlawful benefit during the commission of a criminal offense provided for in Articles 369 , 369-2 of the Criminal Code of Ukraine, directly or indirectly (through third parties), regardless of the amount of the unlawful benefit.
{Subparagraph 178.3 of Article 178 is supplemented by paragraph seven in accordance with Law No. 4112-IX of 04.12.2024 }
For the purposes of applying paragraph six of this paragraph, when considering the circumstances (facts) related to the relevant transaction that may indicate that it was carried out with the aim of providing an illegal benefit to an official, the actual actions of the parties to the transaction and the actual circumstances of the transaction in accordance with its essence shall be taken into account, and for a transaction related to an official of a foreign state, the list published on the official website of the National Anti-Corruption Bureau of Ukraine in accordance with paragraph 12 of part one of Article 16 of the Law of Ukraine "On the National Anti-Corruption Bureau of Ukraine" shall also be used.
{Subparagraph 178.3 of Article 178 is supplemented by paragraph eight in accordance with Law No. 4112-IX of 04.12.2024 }
178.4. Individuals who conduct independent professional activities, as well as foreigners and stateless persons who have registered with regulatory authorities as self-employed persons and are residents, shall submit a tax declaration based on the results of the reporting year in accordance with this section within the deadlines provided for payers of personal income tax, in which, along with income from independent professional activities, other income from sources originating in Ukraine and foreign income must be indicated.
{Paragraph 178.4 of Article 178 as amended by the Law No. 466-IX dated 16.01.2020 }
178.5. When paying income directly related to such activity by business entities - tax agents, individuals engaged in independent professional activities, income tax at the source of payment is not withheld if such individual provides a copy of the certificate of his/her tax registration as an individual engaged in independent professional activities. This rule does not apply in the case of accrual (payment) of income for the performance of certain work and/or provision of services under a civil law contract, the relations under which are established by employment relations, and the parties to the contract may be equated to an employee or employer in accordance with paragraphs 14.1.195 and 14.1.222 of paragraph 14.1 of Article 14 of this Code.
{Clause 178.5 of Article 178 as amended by Law No. 3609-VI of 07.07.2011 }
178.6. Individuals engaged in independent professional activities are required to keep records of income and expenses from such activities. Income and expense records may be kept in paper and/or electronic form, including through an electronic account.
The typical form of such accounting and the procedure for its maintenance are determined by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 178.6 of Article 178 as amended by Laws No. 71-VIII of 12/28/2014 , No. 466-IX of 01/16/2020 ; as amended by Law No. 786-IX of 07/14/2020 }
178.7. The final calculation of personal income tax for the reporting tax year is carried out by the payer independently according to the data specified in the tax declaration, which, along with income from independent professional activities, must indicate other income from sources originating in Ukraine and foreign income, as well as information on the amounts of the single contribution charged on income from independent professional activities in the amounts determined in accordance with the law.
{Clause 178.7 of Article 178 as amended by Law No. 116-IX of September 19, 2019 }
178.8. An individual who carries out independent professional activities and makes any payments from income originating in Ukraine to a non-resident legal entity or a person authorized by it (except for a permanent representative office in Ukraine) shall calculate and pay corporate income tax on the income (profits) of non-residents in the manner, amount and within the terms established by Section III of this Code.
{ Article 178 supplemented by paragraph 178.8 in accordance with the Law No. 466-IX dated 16.01.2020 }
Article 179. Procedure for submitting an annual declaration of assets and income (tax declaration)↑
179.1. A taxpayer is obliged to submit an annual declaration of assets and income (tax declaration) in accordance with this Code.
{Clause 179.1 of Article 179 as amended by Law No. 4661-VI of 24.04.2012 }
179.2. In accordance with this Code, the taxpayer's obligation to file a tax return is deemed to be fulfilled and the tax return is not filed, except in cases where filing a tax return is expressly provided for by this Code, if such taxpayer received:
income, including foreign income, which, in accordance with this Code, is not included in the total monthly (annual) taxable income;
income exclusively from tax agents, regardless of the type and amount of accrued (paid, provided) income;
income from transactions of sale (exchange) of property, donations, income from which in accordance with this Code is not taxed, is taxed at a zero rate and/or from which upon notarization of contracts under which tax was paid in accordance with this section;
income in the form of inheritance objects, which in accordance with this section are taxed at a zero tax rate and/or on which tax has been paid in accordance with paragraph 174.3 of Article 174 of this Code.
Also, a tax return is not filed in cases expressly provided for by this Code.
If a taxpayer is required to submit a tax return in accordance with other provisions of this Code, the return shall indicate, along with other income, the income provided for in this paragraph.
{Clause 179.2 of Article 179 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4661-VI of 24.04.2012 , No. 4834-VI of 24.05.2012 , No. 909-VIII of 24.12.2015 , No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 ; as amended by Law No. 3050-IX of 11.04.2023 }
179.3. Resident taxpayers who travel abroad for permanent residence are required to submit a tax return to the regulatory authority no later than 60 calendar days prior to departure.
The controlling authority, within 30 calendar days after receipt of the tax declaration, is obliged to verify the specified tax liability, payment of the due amount of tax and issue a certificate of such payment and the absence of tax liabilities for this tax, which is submitted to the customs control authorities when crossing the customs border and serves as the basis for carrying out customs procedures.
The form of such a certificate is established by the central executive body that ensures the formation and implementation of state financial policy.
The procedure for applying this paragraph shall be determined by the Cabinet of Ministers of Ukraine.
{Clause 179.3 of Article 179 as amended by Law No. 1797-VIII of 21.12.2016 }
179.4. Taxpayers are exempt from the obligation to submit a tax return in the following cases:
a) regardless of the type and amount of income received by taxpayers who:
are minors/underage or incapacitated persons and are fully dependent on other persons (including parents) and/or the state as of the end of the reporting tax year;
{Paragraph three of clause 179.4 of Article 179 as amended by Law No. 657-VII of 24.10.2013 }
are under arrest or are detained or sentenced to imprisonment, are in captivity or imprisonment in the territory of other states as of the end of the deadline for submitting the declaration;
are wanted as of the end of the reporting tax year;
are on compulsory military service as of the end of the reporting tax year;
b) in other cases specified in this section.
179.5. The tax return shall be filled out by the taxpayer himself or by another person notarized by the taxpayer to complete such a return, in accordance with the procedure provided for in Chapter 2 of Section II of this Code.
179.6. The obligation to complete and submit a tax return on behalf of the taxpayer shall be imposed on the following persons:
parents, guardian or custodian - regarding income received by a minor/underage person or a person recognized by a court as incompetent;
{Paragraph two of clause 179.6 of Article 179 as amended by Laws No. 657-VII of 10/24/2013 , No. 1797-VIII of 12/21/2016 }
heirs (property administrators, state executors) - regarding income received during the reporting tax year by a deceased taxpayer;
a state bailiff authorized to take measures to secure the property claims of creditors of a taxpayer determined in accordance with the established procedure to be bankrupt.
179.7. An individual is obliged to independently pay the amount of tax liability indicated in the tax return submitted by him or her by August 1 of the year following the reporting year.
The amount of tax liabilities additionally assessed by the controlling body shall be paid to the relevant budget within the terms established by this Code.
179.8. The amount to be refunded to the taxpayer shall be credited to his account opened with a bank or non-bank payment service provider within 60 calendar days after receipt of such tax return.
{Item 179.8 of Article 179 as amended by the Law No. 2520-IX dated 15.08.2022 ; as amended by the Law No. 2888-IX dated 12.01.2023 }
179.9. The form of the tax declaration is established by the central executive body that ensures the formation and implementation of state financial policy, based on the following conditions:
the general part of the tax return should have a simplified form and not contain information about income (expenses) received (carried) by a small number of taxpayers;
the tax return is unified and single for all cases of its submission established by this section;
{Paragraph three of clause 179.9 of Article 179 as amended by Law No. 4661-VI of 24.04.2012 }
{Paragraph four of clause 179.9 of Article 179 was excluded on the basis of Law No. 4661-VI of 24.04.2012 }
Calculations of individual types of income (expenses) and the total minimum tax liability must be contained in annexes to the tax return, which are filled out exclusively by taxpayers if such income (expenses) are available or if it is necessary to calculate such a total minimum tax liability;
{ Paragraph five of clause 179.9 of Article 179 as amended by the Law No. 1914-IX dated 30.11.2021 }
the tax return and its annexes must be drawn up using commonly used terminology, and also contain detailed instructions for their completion;
The tax return and its annexes must identify the taxpayer and contain information necessary to determine the amount of his tax liabilities or the amount of tax refundable in the event that the taxpayer exercises his right to a tax deduction.
Tax return forms should be provided free of charge by regulatory authorities to taxpayers upon their request, and should also be publicly available to the public.
{Clause 179.9 of Article 179 as amended by Law No. 1797-VIII of 21.12.2016 }
179.10. A taxpayer has the right to apply to the relevant regulatory authority with a request to provide advisory assistance on issues related to filling out his annual tax return , and the regulatory authority is obliged to provide free services upon such an application.
{ Paragraph 179.10 of Article 179 as amended by the Law No. 1797-VIII dated 21.12.2016 }
179.11. Individuals who submit a declaration of a person authorized to perform state or local government functions, in accordance with the Law of Ukraine "On Prevention of Corruption", submit a tax declaration exclusively in cases provided for by this Code.
{Clause 179.11 of Article 179 as amended by Law No. 4661-VI of 04/24/2012 ; as amended by Law No. 466-IX of 01/16/2020 ; as amended by Law No. 3603-IX of 02/23/2024 }
179.12. Upon the taxpayer's request, the supervisory authority to which the tax return was submitted shall issue a certificate of the submitted declaration of property status and income (tax return) in the form established by the central executive authority that ensures the formation and implementation of state financial policy.
{Clause 179.12 of Article 179 as amended by Law No. 1797-VIII of 21.12.2016 }
1) any person who conducts or plans to conduct economic activity and registers by his/her voluntary decision as a taxpayer in accordance with the procedure specified in Article 183 of this section;
{Subparagraph 1 of paragraph 180.1 of Article 180 as amended by Law No. 443-VII of 05.09.2013 }
2) any person who is registered or subject to registration as a taxpayer;
3) any person who imports goods into the customs territory of Ukraine in taxable quantities and who is responsible for paying taxes in the event of the movement of goods across the customs border of Ukraine in accordance with the Customs Code of Ukraine , as well as:
a person who is responsible for complying with the requirements of customs regimes that provide for full or partial conditional exemption from taxation, in the event of violation of such customs regimes established by customs legislation;
a person who uses, including when importing goods into the customs territory of Ukraine, a tax benefit for purposes other than its intended purpose and/or contrary to the conditions or purposes of its provision in accordance with this Code, as well as any other persons who use a tax benefit that is not intended for them.
The provisions of this paragraph do not apply to operations involving the import into the customs territory of Ukraine by individuals (citizens) or business entities who are not tax payers of cultural values specified in paragraph 197.7 of Article 197 of this Code;
4) a person who keeps records of the results of activities under a joint activity agreement without the formation of a legal entity;
5) a person - a property manager who maintains separate tax records for value added tax regarding business transactions related to the use of property received for management under property management agreements.
For taxation purposes, the economic relations between a property manager in his own economic activity and his property management activities are equated to relations based on separate civil law contracts. The provisions of this subparagraph do not apply to property managers who manage the assets of collective investment institutions, bank management funds, construction financing funds and real estate transaction funds established in accordance with the law;
{Paragraph two of subparagraph 5 of clause 180.1 of Article 180 as amended by Law No. 3609-VI of 07.07.2011 }
6) a person who carries out operations to supply confiscated property, finds, treasures, property recognized as ownerless, property that the owner has not applied for by the end of the storage period, and property that, by right of inheritance or on other legal grounds, passes into the ownership of the state (including property defined in Article 243 of the Customs Code of Ukraine ), regardless of whether it reaches the total amount from the implementation of operations to supply goods/services defined in paragraph 181.1 of Article 181 of this Code, as well as regardless of what taxation regime such a person uses in accordance with the legislation;
{Subparagraph 6 of paragraph 180.1 of Article 180 as amended by Laws No. 4915-VI of 07.06.2012 , No. 1914-IX of 30.11.2021 }
7) a person authorized to pay tax on taxable items arising from the supply of services by railway transport enterprises as part of their main activity, which are subordinate to the taxpayer in accordance with the procedure established by the Cabinet of Ministers of Ukraine;
8) a person - an investor (operator) who maintains separate tax records related to the implementation of a production sharing agreement;
{Clause 180.1 of Article 180 was supplemented by subparagraph 8 in accordance with Law No. 5412-VI of 02.10.2012 }
9) a person defined in subparagraph "d" of subparagraph 14.1.139 of paragraph 14.1 of Article 14 of this Code.
{ Clause 180.1 of Article 180 is supplemented by subparagraph 9 in accordance with the Law No. 1525-IX dated 03.06.2021 }
{Text of paragraph 180.1 of Article 180 as amended by the Law No. 1914-IX dated 30.11.2021 }
180.2. The person responsible for the calculation and payment of tax to the budget in the case of the supply of services by non-residents, including their permanent representative offices not registered as taxpayers, if the place of supply of services is located in the customs territory of Ukraine, is the recipient of services, except for the cases established by Article 208 - 1 of this Code.
{Clause 180.2 of Article 180 as amended by Law No. 1525-IX of 03.06.2021 }
180.2 - 1. The person responsible for the calculation and payment to the budget of tax in the event of import of goods into the customs territory of Ukraine in international postal and express shipments is the postal operator, express carrier, if he declares such goods by submitting registers (temporary and/or additional) of international postal and express shipments.
{Article 180 is supplemented by paragraph 180.2 - 1 in accordance with Law No. 2628-VIII of 11/23/2018 ; as amended by Law No. 1998-IX of 01/25/2022 }
180.2 - 2. The person responsible for paying tax to the budget as part of customs payments in the manner established by Article 295 - 1 of the Customs Code of Ukraine is the person who sells goods specified in Part Seven of Article 293 of the Customs Code of Ukraine.
{Article 180 is supplemented by paragraph 180.2 - 2 in accordance with the Law No. 3474-IX dated 21.11.2023 }
The persons specified in paragraphs 180.2 , 180.2-1 and 180.2-2 of this article shall have the rights, perform the duties and bear the responsibility provided for by law as tax payers .
{Clause 180.3 of Article 180 as amended by the Laws No. 2628-VIII dated 23.11.2018 , No. 3474-IX dated 21.11.2023 }
180.4. The provisions of this article do not apply to non-resident persons who provide services for the preparation for the decommissioning and decommissioning of the Chernobyl NPP power units and the conversion of the Shelter facility into an environmentally safe system, the financing of which is carried out at the expense of international technical assistance funds provided on a gratuitous and non-refundable basis, in accordance with the provisions of the Framework Agreement between Ukraine and the European Bank for Reconstruction and Development on the activities of the Chernobyl Shelter Fund in Ukraine and the Grant Agreement (Chernobyl NPP Nuclear Safety Project) between the European Bank for Reconstruction and Development as the Administrator of funds provided under the Nuclear Safety Account Grant, the Government of Ukraine and the Chernobyl Nuclear Power Plant .
{Article 180 was supplemented by paragraph 180.4 in accordance with Law No. 3609-VI of 07.07.2011 }
Article 181. Requirements for registration of persons as tax payers↑
181.1. If the total amount from the performance of transactions for the supply of goods/services subject to taxation in accordance with this section, including transactions for the supply of goods/services using a local or global computer network (in particular, but not exclusively by installing a special application or supplement on smartphones, tablets or other digital devices), accrued (paid) to such a person during the last 12 calendar months, in total exceeds 1,000,000 hryvnias (excluding value added tax), such a person is obliged to register as a taxpayer with the regulatory authority at his location (place of residence) in compliance with the requirements provided for in Article 183 of this Code, except for a person who is a single tax payer of the first - third groups.
{Clause 181.1 of Article 181 as amended by Law No. 1621-VII of 31.07.2014, taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; clause 181.1 of Article 181 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by the Law No. 1914-IX dated 30.11.2021 }
181.2. If persons not registered as taxpayers import goods into the customs territory of Ukraine in amounts subject to taxation in accordance with the law, such persons shall pay tax during customs clearance of the goods without registration as taxpayers of such tax.
182.1. If a person who, in accordance with paragraph 181.1 of Article 181 of this Code, is not a taxpayer due to the fact that the volumes of taxable transactions are absent or are less than the amount established by the specified article, considers it appropriate to voluntarily register as a taxpayer, such registration shall be carried out upon his application.
{Paragraph one of clause 182.1 of Article 182 as amended by Law No. 4834-VI of 24.05.2012 }
{Paragraph two of clause 182.1 of Article 182 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
{Clause 182.1 of Article 182 as amended by Laws No. 3609-VI of 07.07.2011 , No. 443-VII of 05.09.2013 }
183.1. Any person subject to mandatory registration as a taxpayer shall submit a registration application to the regulatory authority at his/her location (place of residence) .
{Clause 183.1 of Article 183 as amended by Laws No. 443-VII of 05.09.2013 , No. 1914-IX of 30.11.2021 }
183.2. In the case of mandatory registration of a person as a taxpayer, the registration application shall be submitted to the regulatory authority no later than the 10th day of the calendar month following the month in which the volume of taxable transactions specified in Article 181 of this Code was first reached.
183.3. In the case of voluntary registration of a person as a taxpayer or a person who meets the requirements specified in subparagraph 6 of paragraph 180.1 of Article 180 of this Code, a registration application shall be submitted in accordance with paragraph 183.7 of this Article no later than 10 calendar days before the beginning of the tax period from which such persons will be considered taxpayers and will have the right to a tax credit and the preparation of tax invoices.
{Clause 183.3 of Article 183 as amended by Laws No. 3609-VI of 07.07.2011 , No. 443-VII of 05.09.2013 , No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 }
183.4. In the event of persons switching from a simplified taxation system that does not provide for the payment of a tax to the payment of other taxes and fees established by this Code, in the cases specified in Chapter 1 of Section XIV of this Code, provided that such persons meet the requirements specified in Clause 181.1 of Article 181 of this Code, the registration application shall be submitted no later than the 10th day of the first calendar month in which the switch to the payment of other taxes and fees established by this Code was made. If such persons meet the requirements specified in Clause 182.1 of Article 182 of this Code, the registration application shall be submitted within the period specified in Clause 183.3 of this Article.
In the event of a change in the single tax rate in accordance with subparagraph "b" of subparagraph 4 of paragraph 293.8 of Article 293 of this Code, the registration application shall be submitted no later than 10 calendar days before the beginning of the calendar month in which the single tax rate, which provides for the payment of value added tax, will be applied.
{Paragraph two of clause 183.4 of Article 183 as amended by Law No. 4834-VI of 05.24.2012 , as amended by Laws No. 5083-VI of 07.05.2012 , No. 466-IX of 01.16.2020 }
{Clause 183.4 of Article 183 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4014-VI of 04.11.2011 ; as amended by Law No. 5503-VI of 20.11.2012 }
183.5. Persons specified in paragraph 183.3 of this Article may indicate in the application the desired (planned) day of registration as a taxpayer, which corresponds to the date of the beginning of the tax period (calendar month), from which such persons will be considered taxpayers and will have the right to prepare tax invoices.
{Paragraph one of clause 183.5 of Article 183 as amended by Law No. 4834-VI of 24.05.2012 }
The registration of persons specified in paragraph two of clause 183.4 of this article shall be effective from the first day of the calendar month in which the single tax rate, which provides for the payment of value added tax, will be applied.
{Paragraph two of clause 183.5 of Article 183 as amended by Law No. 4834-VI of 05.24.2012 , as amended by Laws No. 5083-VI of 07.05.2012 , No. 466-IX of 01.16.2020 }
{Clause 183.5 of Article 183 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 5503-VI of 20.11.2012 , No. 1797-VIII of 21.12.2016 }
183.6. If the last day of the application submission period falls on a weekend, holiday or non-working day, the last day of the period shall be the working day following the weekend, holiday or non-working day.
183.7. An application for registration of a person as a taxpayer shall be submitted to the supervisory authority by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Paragraph one of clause 183.7 of Article 183 as amended by Law No. 466-IX of January 16, 2020 }
{Paragraph two of clause 183.7 of Article 183 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
Business entities (including newly established ones) may declare their desire to voluntarily register as a taxpayer during the state registration of the creation of a legal entity or state registration of an individual entrepreneur, state registration of changes to information about a legal entity or about an individual entrepreneur contained in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations. The relevant application or information is transmitted to the regulatory authorities in accordance with the procedure established by the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
{Clause 183.7 of Article 183 is supplemented by a paragraph in accordance with Law No. 443-VII of 05.09.2013 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 , No. 3603-IX of 23.02.2024 }
The registration application states the grounds for registering the person as a taxpayer.
{Clause 183.7 of Article 183 was supplemented with a paragraph in accordance with Law No. 443-VII of 05.09.2013 }
With regard to such applications or information, the three-day period for their consideration by the regulatory authorities begins on the day following the day of their receipt by the regulatory authority; the rules, procedure and terms of consideration are the same as for registration applications submitted in accordance with the first paragraph of this paragraph.
{Clause 183.7 of Article 183 is supplemented by the fifth paragraph in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 3603-IX of 02.23.2024 }
{Clause 183.7 of Article 183 as amended by Laws No. 3609-VI of 07.07.2011 , No. 443-VII of 05.09.2013 }
183.8. The supervisory authority shall refuse to register a person as a taxpayer if, based on the results of consideration of the registration application and/or submitted documents, it is established that the person does not meet the requirements specified in Article 180 , Clause 181.1 of Article 181, Clause 182.1 of Article 182 and Clause 183.7 of Article 183 of this Code, or if there are circumstances that constitute grounds for cancellation of registration in accordance with Article 184 of this Code, as well as if, when submitting a registration application or determining the desired (planned) date of registration, the procedure and terms (deadlines) established by Clauses 183.1, 183.3-183.7 of this Article were not followed.
{Clause 183.8 of Article 183 as amended by Laws No. 657-VII of 10/24/2013 , No. 71-VIII of 12/28/2014 }
183.9. In the absence of grounds for refusal to register a person as a taxpayer, the regulatory authority is obliged, within three working days after the receipt of the registration application by the regulatory authority, to enter an entry in the register of taxpayers on the registration of such a person as a taxpayer:
from the desired (planned) date of registration specified in the registration application, which corresponds to the date of the beginning of the tax period (calendar month), from which such persons will be considered taxpayers and will have the right to draw up tax invoices, in the case of voluntary registration of a person as a taxpayer;
{Paragraph two of clause 183.9 of Article 183 as amended by Law No. 1797-VIII of 21.12.2016 }
from the first day of the month following the day of expiration of 10 calendar days after submitting the registration application to the regulatory authority or state registrar, in the case of voluntary registration of a person as a value added tax payer, if the desired (planned) date of registration is not indicated in the application;
{Paragraph three of paragraph 183.9 of Article 183 as amended by Law No. 466-IX of January 16, 2020 }
from the desired (planned) day corresponding to the first number of the calendar quarter in which the single tax rate will be applied, which provides for the payment of value added tax, in the event of individuals switching to the simplified taxation system;
{Paragraph four of clause 183.9 of Article 183 as amended by Law No. 466-IX of 16.01.2020 }
from the desired (planned) day corresponding to the first day of the calendar month in which the single tax rate will be applied, which provides for the payment of value added tax, in the event of a change in the single tax rate of the third group;
{Clause 183.9 of Article 183 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
from the first day of the calendar month in which the transition to payment of other taxes and fees is made, in the case of registration of persons specified in the first paragraph of paragraph 183.4 who meet the requirements specified in paragraph 181.1 of Article 181 of this Code, if the first day of the calendar month from which the transition to payment of other taxes and fees is made has not yet come on the day of submission of the registration application;
from the date of entry in the register of taxpayers in the case of mandatory registration of a person as a taxpayer or in the case of registration of persons specified in the first paragraph of paragraph 183.4 who meet the requirements specified in paragraph 181.1 of Article 181 of this Code, if the first day of the calendar month in which the transition to payment of other taxes and fees was made has come on the day of submission of the registration application.
{Clause 183.9 of Article 183 as amended by Laws No. 4834-VI of 24.05.2012 , No. 657-VII of 24.10.2013 ; as amended by Law No. 71-VIII of 28.12.2014 }
183.10. Any person who is subject to mandatory registration as a taxpayer and, in the cases and in the manner provided for by this article, has not submitted a registration application to the regulatory authority shall be liable for failure to assess or pay this tax at the level of a registered taxpayer without the right to accrue a tax credit and receive budget reimbursement.
{Clause 183.10 of Article 183 as amended by Law No. 3609-VI of 07.07.2011 }
183.11. At the request of a taxpayer, the regulatory authority shall provide, free of charge and unconditionally, within two business days following the date of receipt of such a request, an extract from the register of taxpayers. The extract shall be valid until changes are made to the register.
The form of a request for an extract and an extract from the register of taxpayers is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 183.11 of Article 183 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 1797-VIII of 12/21/2016 }
183.12. The central executive body implementing state tax policy shall maintain a register of taxpayers, which contains information on persons registered as taxpayers.
{Clause 183.12 of Article 183 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
183.13. In order to constantly provide state authorities, local self-government bodies, legal entities and individuals with information, the central executive body implementing state tax policy shall publish daily on the single state registration web portal of legal entities and individuals - entrepreneurs and public organizations and on its own official website:
{Paragraph one of clause 183.13 of Article 183 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
183.13.1. data from the register of taxpayers indicating the name or surname, first and middle name of the taxpayer, date of tax registration, individual tax number and validity period of the taxpayer's registration;
183.13.2. information about persons whose registration as taxpayers has been canceled, indicating individual tax numbers, date of cancellation, reasons and grounds for cancellation of registration.
Upon request in electronic form of taxpayers who submit tax returns by electronic means in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" , the regulatory authorities shall provide free of charge, within five business days from the date of receipt of such a request, the information published in accordance with this paragraph.
{Paragraph two of subparagraph 183.13.2 of paragraph 183.13 of Article 183 as amended by Law No. 2725-VIII of May 16, 2019 ; as amended by Law No. 466-IX of January 16, 2020 }
The forms of requests for information and certificates from the register and the procedure for their formation are established by the central executive body that ensures the formation and implementation of state financial policy.
{Subclause 183.13.2 of clause 183.13 of Article 183 as amended by Law No. 1797-VIII of 21.12.2016 }
{Clause 183.13 of Article 183 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 657-VII of 24.10.2013 }
183.14. Forms of registration applications, applications for cancellation of registration, as well as regulations on the registration of taxpayers are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 183.14 of Article 183 as amended by Laws No. 657-VII of 10/24/2013 , No. 1797-VIII of 12/21/2016 }
183.15. In the event of a taxpayer changing his/her location (place of residence) or transferring him/her for service to another regulatory body, the removal of such taxpayer from registration with one regulatory body and registration with another shall be carried out in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy.
In the event of the transformation of a legal entity - a taxpayer or changes in data about the taxpayer that relate to the tax number and/or name (surname, first name and patronymic) of the taxpayer and are not related to the liquidation or reorganization of the taxpayer, as well as the establishment of discrepancies or errors in the entries in the taxpayer register, the taxpayer is re-registered.
{Clause 183.15 of Article 183 is supplemented by the second paragraph in accordance with Law No. 4834-VI of 05/24/2012 ; as amended by Laws No. 657-VII of 10/24/2013 , No. 466-IX of 01/16/2020 }
Re-registration of a taxpayer shall be carried out in compliance with the rules and within the time limits specified in this article for the registration of taxpayers, by making a corresponding entry in the register of taxpayers.
{Clause 183.15 of Article 183 is supplemented by the third paragraph in accordance with Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 657-VII of 10/24/2013 }
For re-registration, the taxpayer shall submit an application in accordance with paragraph 183.7 of this article within 10 business days following the day on which the taxpayer's data changed or other grounds for re-registration arose.
{Paragraph 183.15 of Article 183 is supplemented by the fourth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Re-registration in connection with a change in the name (except for transformation) (surname, first name and patronymic) of a taxpayer included in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations is carried out by the supervisory authority without the submission of an application by the taxpayer based on information from this Unified State Register.
{Paragraph 183.15 of Article 183 is supplemented by the fifth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
If a person formed through transformation fails to submit an application for re-registration within the established period, its registration as a taxpayer shall be canceled in accordance with Article 184 of this Code.
{Paragraph 183.15 of Article 183 is supplemented by the sixth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Clause 183.15 of Article 183 as amended by Law No. 1797-VIII of 21.12.2016 }
183.16. If, in accordance with the legislation, a period for which a person is established or a period after which the taxpayer's registration data changes is determined, the taxpayer's registration is valid until the expiration of such period.
{Clause 183.16 of Article 183 as amended by Law No. 657-VII of October 24, 2013 }
183.17. A person formed as a result of the reorganization of a taxpayer (except for a person formed through transformation) shall be registered by the taxpayer as another newly formed person in the manner prescribed by this Code, including in cases where such person has been assigned tax payment obligations in connection with the distribution of tax liabilities or tax debt.
183.18. A person registering as a taxpayer is assigned an individual tax number, which is used to pay tax.
Article 184. Cancellation of Taxpayer Registration↑
184.1. Registration is valid until the date of cancellation of the taxpayer's registration, which is carried out by exclusion from the register of taxpayers and occurs if:
a) any person registered as a taxpayer during the previous 12 months has filed an application for cancellation of registration if the total value of taxable goods/services provided by such person during the previous 12 calendar months was less than the amount specified in Article 181 of this Code, subject to payment of the amount of tax liabilities in the cases specified in this section;
b) any person registered as a taxpayer has made a decision to terminate and approved a liquidation balance sheet, transfer deed or distribution balance sheet in accordance with the legislation, subject to payment of the amount of tax liabilities in the cases specified in this section;
{Subparagraph "b" of paragraph 184.1 of Article 184 as amended by Law No. 4834-VI of 24.05.2012 }
c) any person registered as a taxpayer shall be registered as a payer of a single tax, the condition for payment of which does not provide for the payment of value added tax;
d) a person registered as a taxpayer does not submit a value added tax declaration to the supervisory authority for 12 consecutive tax months and/or submits such a declaration (tax calculation) that indicates the absence of supply/purchase of goods/services made for the purpose of forming a tax liability or tax credit;
{Subparagraph "d" of paragraph 184.1 of Article 184 as amended by Law No. 1797-VIII of 21.12.2016 }
e) the constituent documents of any person registered as a taxpayer are declared invalid by a court decision;
e) the commercial court has issued a ruling on the liquidation of a bankrupt legal entity;
f) the taxpayer is liquidated by a court decision (an individual loses the status of a business entity) or the person is exempted from paying tax or his tax registration is annulled (cancelled, declared invalid) by a court decision;
h) an individual registered as a taxpayer has died, been declared deceased, recognized as legally incompetent or missing, or has had his civil legal capacity restricted;
{Sub-paragraph "g" of paragraph 184.1 of Article 184 was excluded on the basis of the Law No. 909-VIII dated 24.12.2015 }
h) the joint activity agreement, property management agreement, product distribution agreement (for taxpayers specified in subparagraphs 4 , 5 and 8 of paragraph 180.1 of Article 180 of this Code) has been terminated or the term for which the person registered as a taxpayer was established has expired.
{Subparagraph "c" of paragraph 184.1 of Article 184 as amended by Law No. 657-VII of October 24, 2013 }
{Sub-paragraph "i" of paragraph 184.1 of Article 184 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
184.2. Cancellation of registration on the grounds specified in subparagraph "a" of paragraph 184.1 of this Article shall be carried out upon the application of the taxpayer, and on the grounds specified in subparagraphs "b"-"c" of paragraph 184.1 of this Article, may be carried out upon the application of the taxpayer or by an independent decision of the relevant supervisory authority.
If, for a person registered as a taxpayer in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations, an entry is made about the state registration of the termination of a legal entity (except for transformation) or entrepreneurial activity of an individual entrepreneur, or if an entry is made in the register of single tax payers about the application of a simplified taxation system that does not provide for the payment of value added tax, the cancellation of registration is carried out by the controlling body automatically on the basis of relevant information obtained in accordance with the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations" or according to the data of the register of single tax payers.
{Clause 184.2 of Article 184 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
Cancellation of registration is carried out on the date:
{Clause 184.2 of Article 184 was supplemented with a paragraph in accordance with Law No. 4834-VI of 24.05.2012 }
submission of an application by the taxpayer or adoption of a decision by the supervisory authority to cancel the registration;
{Clause 184.2 of Article 184 is supplemented by a paragraph in accordance with Law No. 4834-VI of 24.05.2012 ; as amended by Law No. 657-VII of 24.10.2013 }
specified in the court decision;
{Clause 184.2 of Article 184 is supplemented by a paragraph in accordance with Law No. 4834-VI of 24.05.2012 }
termination of a joint activity agreement, property management agreement, production sharing agreement or expiration of the term for which a person registered as a taxpayer was established;
{Clause 184.2 of Article 184 is supplemented by a paragraph in accordance with Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 657-VII of 10/24/2013 }
preceding the day on which the person loses the status of a value added tax payer;
{Clause 184.2 of Article 184 was supplemented with a paragraph in accordance with Law No. 4834-VI of 24.05.2012 }
state registration of the termination of a legal entity or entrepreneurial activity of an individual entrepreneur.
{Clause 184.2 of Article 184 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
In this case, the date of cancellation of the taxpayer's registration is determined by the date that occurred earlier.
{ Clause 184.2 of Article 184 is supplemented with a paragraph in accordance with the Law No. 657-VII dated 24.10.2013 }
{Clause 184.2 of Article 184 as amended by Law No. 4834-VI of 24.05.2012 }
184.3. The supervisory authority shall cancel the registration of a person as a taxpayer who has submitted an application for cancellation of registration if it establishes that he meets the requirements of paragraph 184.1 of this Article.
{Clause 184.3 of Article 184 as amended by Law No. 1914-IX of 30.11.2021 }
184.4. In the absence of legal grounds for cancellation of registration, the regulatory authority, within 10 calendar days after receipt of the taxpayer's application for cancellation of registration, shall submit to such taxpayer a reasoned written refusal to cancel the registration with explanations on the specified issue.
184.5. From the moment of cancellation of a person's registration as a taxpayer, such person loses the right to attribute tax amounts to a tax credit and to prepare tax invoices.
{Clause 184.5 of Article 184 as amended by Law No. 1797-VIII of 21.12.2016 }
184.6. In the event of cancellation of a person's registration as a taxpayer, the last reporting (tax) period is the period that begins on the day following the last day of the previous tax period and ends on the day of cancellation of registration.
184.7. If goods/services, non-current assets, the tax amounts for which were included in the tax credit, were not used in taxable transactions within the framework of economic activity, such a taxpayer in the last reporting (tax) period no later than the date of cancellation of his registration as a taxpayer is obliged to determine tax liabilities for such goods/services, non-current assets based on the usual price of the relevant goods/services or non-current assets, except for cases of cancellation of registration as a taxpayer as a result of reorganization of the taxpayer by means of accession, merger, transformation, division and separation in accordance with the law.
{Clause 184.7 of Article 184 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 4834-VI of 24.05.2012 }
184.8. If a taxpayer whose registration is canceled has tax liabilities based on the results of the last tax period, such tax amount shall be taken into account in the amount of the reduction in budget compensation, and in the event of its absence within the terms specified by this Code, the taxpayer shall be obliged to repay the amount of tax liabilities or tax debt on this tax that arose before such cancellation, if any, regardless of whether such person remains registered as a taxpayer on the day of payment of such tax amount or not.
{Clause 184.8 of Article 184 as amended by Law No. 4834-VI of 05/24/2012 }
184.9. If, based on the results of the last tax period, a person is entitled to receive a budget refund, such refund shall be provided within the time limits specified in this section, regardless of whether such person remains registered as a payer of this tax on the date of receipt of such budget refund or not.
184.10. The supervisory authority that has made an independent decision to cancel the registration of a taxpayer is obliged to notify the person in writing within three business days after the day of cancellation of such registration.
{Clause 184.10 of Article 184 as amended by Law No. 466-IX of January 16, 2020 }
Article 185. Determination of the object of taxation↑
185.1. The object of taxation is the transactions of taxpayers with:
a) supply of goods, the place of supply of which is located in the customs territory of Ukraine, in accordance with Article 186 of this Code, including transactions on the gratuitous transfer and transfer of ownership of collateral to the borrower (creditor), on goods transferred under the terms of a commodity loan, as well as on the transfer of a financial leasing object into the possession and use of the lessee/lessee;
{Subparagraph "a" of paragraph 185.1 of Article 185 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 1605-IX of 07/01/2021 }
b) supply of services, the place of supply of which is located in the customs territory of Ukraine, in accordance with Article 186 of this Code;
c) import of goods into the customs territory of Ukraine;
{Subparagraph "c" of paragraph 185.1 of Article 185 as amended by Law No. 4915-VI of 07.06.2012 }
d) export of goods outside the customs territory of Ukraine;
{Subparagraph "d" of paragraph 185.1 of Article 185 as amended by Law No. 4915-VI of 07.06.2012 }
{Subparagraph "g" of paragraph 185.1 of Article 185 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
{Subparagraph "d" of paragraph 185.1 of Article 185 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
e) provision of services for international transportation of passengers and luggage and cargo by rail, road, sea and river and air transport.
For the purpose of taxation by this tax, placing goods under any customs regime defined by the Customs Code of Ukraine is equated to operations on the import of goods into the customs territory of Ukraine and the export of goods out of the customs territory of Ukraine .
{Clause 185.1 of Article 185 is supplemented by a paragraph in accordance with Law No. 4915-VI of 07.06.2012 }
Article 186. Place of supply of goods and services↑
186.1. The place of supply of goods is:
a) the actual location of the goods at the time of their delivery (except for the cases provided for in subparagraphs "b" and "c" of this paragraph);
b) the place where the goods are located at the time of the commencement of their transport or shipment, if the goods are transported or shipped by the seller, the buyer or a third party;
c) the place where the assembly, installation or installation is carried out, if the goods are assembled, installed or installed (with or without testing) by the seller or on his behalf.
186.1.1. If the supply of goods is carried out for consumption on board sea and aircraft vessels or in trains during the passenger transportation section carried out within the customs territory of Ukraine, the place of supply is considered to be the point of departure of the passenger vehicle.
A section of passenger transportation carried out within the customs territory of Ukraine is considered to be a section where such transportation takes place without stops outside the customs territory of Ukraine between the point of departure and the point of arrival of the passenger vehicle.
The point of departure of a passenger vehicle is the first point of boarding of passengers within the customs territory of Ukraine, if necessary - after a stop outside the customs territory of Ukraine.
The point of arrival of a vehicle in the customs territory of Ukraine is the last point in the customs territory of Ukraine for boarding/disembarking passengers in the customs territory of Ukraine.
186.2. The place of supply of services is:
186.2.1. the place of actual supply of services related to movable property, namely:
a) services that are auxiliary to transport activities: loading, unloading, reloading, warehouse processing of goods and other similar types of services;
b) services for conducting expertise and evaluation of movable property;
c) services related to the transportation of passengers and cargo, including the supply of food and beverages intended for consumption;
d) repair services and raw material processing services, as well as other works and services related to movable property;
186.2.2. actual location of real estate, including that under construction, for those services related to real estate:
a) real estate agency services;
b) services for the preparation and implementation of construction works;
c) other services at the location of real estate, including property under construction;
186.2.3. the place of actual provision of services in the field of culture, art, education, science, sports, entertainment or other similar services, including services of organizers of activities in the specified fields and services provided for the organization of paid exhibitions, conferences, training seminars and other similar events.
186.3. The place of supply of the services specified in this clause shall be the place where the recipient of the services is registered as a business entity or - in the absence of such a place - the place of his permanent or primary residence. Such services include:
a) granting of intellectual property rights, creation on order and use of intellectual property rights, including under license agreements, as well as granting (transfer) of the right to reduce greenhouse gas emissions (carbon units);
b) advertising services;
c) consulting, engineering, engineering, legal (including legal), accounting, auditing, actuarial, as well as services for the development and testing of software, data processing and provision of consultations on issues of informatization, provision of information and other services in the field of informatization, including using computer systems;
{Subparagraph "c" of paragraph 186.3 of Article 186 as amended by Laws No. 3609-VI of 07.07.2011 , No. 1914-IX of 30.11.2021 }
d) provision of personnel, including if the personnel work at the buyer's place of business;
e) rental, leasing of movable property, except for vehicles and bank safes;
{Subparagraph "g" of paragraph 186.3 of Article 186 as amended by Law No. 1605-IX of 01.07.2021 }
e) telecommunications services, namely: services related to the transmission, dissemination or reception of signals, words, images and sounds or information of any nature by means of wire, satellite, cellular, radio, optical or other electromagnetic communication systems, including the relevant provision or transfer of the right to use the capabilities of such transmission, dissemination or reception, including the provision of access to global information networks;
f) radio and television broadcasting services;
g) provision of intermediary services on behalf of and at the expense of another person or on one's own behalf but at the expense of another person, if the provision of the services listed in this paragraph to the buyer is ensured;
{Subparagraph "e" of paragraph 186.3 of Article 186 as amended by Law No. 466-IX of January 16, 2020 }
g) provision of freight forwarding services;
h) provision of services for the production and layout of video films, motion pictures, animated (cartoon) films, television programs, advertising films, photo advertising materials and computer graphics;
{Clause 186.3 of Article 186 is supplemented by subparagraph "z" in accordance with Law No. 821-IX of 21.07.2020 }
i) services for access to the capacity of interstate intersections (physical rights to transmission) and ancillary services defined by the Law of Ukraine "On the Electricity Market".
{Clause 186.3 of Article 186 is supplemented by subparagraph "i" in accordance with Law No. 3219-IX of 30.06.2023 }
186.3 - 1. The place of supply of electronic services is considered to be the location of the recipient of services. For the purpose of applying the specified paragraph, the location of the recipient of electronic services is determined by:
for a recipient of services - an individual registered as a business entity - at the place of registration of such recipient as a business entity;
for a recipient of services - an individual who is not registered as a business entity - at the place of actual location of such individual - recipient of services. In order to establish the actual location of an individual - recipient of services, the following information is taken into account:
a) if electronic services are provided by means of fixed communication - the actual location of the individual - recipient of services is considered to be the country of installation of the fixed communication line (location of the telecommunications provider whose services were used by the recipient in the process of receiving the electronic service);
b) if electronic services are provided by means of mobile communication - the actual location of the individual - recipient of services is considered to be the country identified by the mobile country code of the SIM card used when receiving such services;
c) if electronic services are provided by means of communication other than those specified in this paragraph, including using an access card, the actual location of the individual - recipient of the services is considered to be the country in which such other means of communication are located or to which the access card was sent for its use (including the location of the device, which is determined by its IP address, used by the recipient of the electronic service).
Additional evidence for determining the location of an individual - recipient of services, one of which is used simultaneously with one of the information specified in subparagraphs "a" - "c" of this paragraph, is:
billing address of the individual - recipient of services;
bank details, including the location of the bank account used to pay for electronic services;
other commercially important information.
An individual recipient of electronic services can confirm that he is registered as a taxable business entity by reporting his individual VAT number.
If the contract, including one concluded in electronic form, does not contain information that the recipient of electronic services is a business entity, it is considered that such a service was received by an individual, including an individual entrepreneur, not registered as a taxpayer.
{ Article 186 is supplemented by paragraph 186.3 - 1 in accordance with the Law No. 1525-IX dated 03.06.2021 }
186.4. The place of supply of services is the place of registration of the supplier, except for the transactions specified in paragraphs 186.2 , 186.3 and 186.3-1 of this article.
{ Paragraph 186.4 of Article 186 as amended by the Law No. 1525-IX dated 03.06.2021 }
Article 187. Date of occurrence of tax liabilities↑
187.1. The date of occurrence of tax liabilities for the supply of goods/services is considered to be the date falling within the tax period during which any of the following events occurs, whichever occurred earlier:
a) the date of crediting funds from the buyer/customer to the taxpayer's account at a bank/non-bank payment service provider as payment for goods/services to be supplied, and in the case of the supply of goods/services paid for in electronic money, the date of crediting electronic money to the taxpayer as payment for goods/services to be supplied to an electronic wallet, and in the case of the supply of goods/services for cash, the date of posting funds to the taxpayer's cash desk, and in the absence of such a cash desk, the date of cash collection at the banking institution serving the taxpayer;
{Subparagraph "a" of paragraph 187.1 of Article 187 as amended by Law No. 2888-IX of 12.01.2023 }
b) the date of shipment of goods, and in the case of export of goods - the date of registration of the customs declaration certifying the fact of crossing the customs border of Ukraine, issued in accordance with the requirements of customs legislation, and for services - the date of registration of the document certifying the fact of supply of services by the taxpayer. For documents drawn up in electronic form, the date of registration of the document certifying the fact of supply of services by the taxpayer is the date indicated in the document itself as the date of its preparation in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", regardless of the date of affixing the electronic signature.
{Paragraph three of item 187.1 of Article 187 as amended by the Law No. 1525-IX dated 03.06.2021 }
For transactions involving the performance of contract construction work, business entities (contractors and subcontractors) may apply the cash method of tax accounting in accordance with subparagraph 14.1.266 of paragraph 14.1 of Article 14 of this Code.
{Clause 187.1 of Article 187 is supplemented by the fourth paragraph in accordance with Law No. 4220-VI of 12/22/2011 ; as amended by Law No. 466-IX of 01/16/2020 }
For transactions on the first supply of housing (residential real estate), an indivisible residential property under construction/future residential property, the cash method of tax accounting is applied in accordance with subparagraph 14.1.266 of paragraph 14.1 of Article 14 of this Code.
{Clause 187.1 of Article 187 is supplemented by the fifth paragraph in accordance with Law No. 2600-IX of 20.09.2022 }
187.2. In the case of supply of goods or services using vending machines or other similar equipment that does not require the presence of a cash register controlled by an authorized individual, the date of occurrence of tax liabilities shall be the date of withdrawal of cash proceeds from such vending machines or similar equipment. The rules for collection of the said proceeds shall be established by the National Bank of Ukraine.
187.3. In the case of supply of goods under commodity credit agreements (commodity loan, installment agreements), the terms of which provide for the payment (accrual) of interest, the date of increase in tax liabilities in respect of such interest shall be the date of its accrual in accordance with the terms of the relevant agreement.
187.4. If the supply of goods/services through vending machines is carried out using tokens, cards or other substitutes for national currency, the date of increase in tax liabilities shall be the date of supply of such tokens, cards or other substitutes for national currency.
187.5. If the supply of goods/services is carried out using credit or debit cards, traveler's, commercial, registered or other checks, the date of increase in tax liabilities is considered to be the date certifying the fact of the supply of goods/services by the taxpayer to the buyer, issued by a tax invoice, or the date of issuing the relevant invoice (goods receipt), depending on which event occurred earlier.
187.6. The date of occurrence of the tax obligations of the lessor (landlord) for financial leasing (financial lease) transactions is the date of actual transfer of the financial leasing (financial lease) object into the possession and use of the lessee (lessee).
{Clause 187.6 of Article 187 as amended by Law No. 1605-IX of 01.07.2021 }
187.7. The date of occurrence of tax liabilities in the case of supply of goods/services with payment from budget funds is the date of crediting such funds to the taxpayer's account with a bank/non-bank payment service provider or the date of receipt of appropriate compensation in any other form, including the reduction of such taxpayer's debt under his obligations to the budget.
{Paragraph 187.7 of Article 187 as amended by the Law No. 2888-IX dated 12.01.2023 }
187.8. The date of occurrence of tax liabilities in the event of import of goods into the customs territory of Ukraine is the date of submission of the customs declaration for customs clearance.
In cases provided for in Article 191 of this Code, the date of occurrence of tax liabilities shall be determined taking into account the provisions of Article 191 of this Code.
{Clause 187.8 of Article 187 is supplemented with a new paragraph in accordance with Law No. 4915-VI of 07.06.2012 }
The date of occurrence of tax liabilities for transactions on the supply of services by non-residents to business entities, the place of supply of which is located in the customs territory of Ukraine, is the date of debiting funds from the taxpayer's account with a bank/non-bank payment service provider in payment for services or the date of execution of a document certifying the fact of the supply of services by a non-resident, depending on which of the events occurred earlier.
{Paragraph three of item 187.8 of Article 187 as amended by the Laws No. 1525-IX dated 03.06.2021 , No. 2888-IX dated 12.01.2023 }
187.9. The date of occurrence of tax liabilities of the executor of long-term agreements (contracts), except for agreements (contracts) for the construction of housing (residential real estate objects), purchase and sale agreements of an indivisible residential object under construction/future residential real estate object, in respect of which their first delivery takes place, is the date of actual transfer by the executor of the results of work under such agreements (contracts).
{Paragraph one of item 187.9 of Article 187 as amended by the Law No. 2600-IX dated 20.09.2022 }
For the purposes of this paragraph, a long-term agreement (contract) is any agreement for the manufacture of goods, performance of work, provision of services with a long-term (more than one year) technological production cycle and if the agreements concluded for the manufacture of such goods, performance of work, provision of services do not provide for their phased delivery.
187.10. Taxpayers who supply thermal energy, natural gas (except liquefied), provide services for the transportation and/or distribution of natural gas, other housing and communal services, the list of which is determined by law, charge a fee for subscriber service, services (works), the cost of which is included in the fee for the service for the maintenance of buildings and structures and adjacent territories or the service for the management of an apartment building, to individuals, budgetary institutions not registered as taxpayers, as well as housing and operational offices, managers of apartment buildings, apartment and operational parts, associations of co-owners of apartment buildings, other taxpayers who collect funds from the specified buyers for the purpose of their subsequent transfer to sellers of such goods (service providers) to compensate for their cost, determine the date of occurrence of tax liabilities and tax credit using the cash method.
{Paragraph one of clause 187.10 of Article 187 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.24.2012 , No. 812-VIII of 11.24.2015 , No. 2628-VIII of 11.23.2018 ; as amended by Law No. 1914-IX of 11.30.2021 }
The specified rule for determining the date of occurrence of tax liabilities also applies to transactions for the supply of the specified goods/services to housing and operational offices, managers of apartment buildings, and budgetary institutions that receive such goods/services, if they are registered as taxpayers.
{Paragraph two of clause 187.10 of Article 187 as amended by Law No. 2628-VIII of 23.11.2018 }
For the purposes of this clause, services (works), the cost of which is included in the fee for the service of maintaining buildings and structures and adjacent territories or the service of managing an apartment building, are considered to be services for the technical maintenance of elevators and dispatching systems, fire-fighting automation and smoke removal systems, maintenance of smoke and ventilation ducts, intra-building systems, cleaning of the building and adjacent territories, purchase of electricity to ensure the functioning of the common property of an apartment building, as well as other services provided by housing and operational offices or managers of apartment buildings specified in this clause to buyers at their expense.
{Paragraph three of clause 187.10 of Article 187 as amended by Law No. 2628-VIII of 11/23/2018 }
187.11. Preliminary (advance) payment of the value of goods exported outside the customs territory of Ukraine or imported into the customs territory of Ukraine does not change the value of the tax amounts that relate to the tax credit or tax liabilities of the taxpayer, such exporter or importer.
{Clause 187.11 of Article 187 as amended by Law No. 657-VII of 24.10.2013 }
Article 188. Procedure for determining the tax base in the case of supply of goods/services↑
188.1. The tax base for transactions on the supply of goods/services is determined based on their contractual value, taking into account state taxes and fees (except for excise tax, which is charged in accordance with subparagraphs 213.1.9 and 213.1.14 of paragraph 213.1 of Article 213 of this Code, the levy on mandatory state pension insurance, which is levied on the cost of cellular mobile communication services, value added tax and excise tax on ethyl alcohol used by manufacturers - business entities for the production of medicines, including blood components and preparations made from them (except for medicines in the form of balms and elixirs).
{Paragraph one of clause 188.1 of Article 188 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 609-VIII of 07/15/2015 ; as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 1914-IX of 11/30/2021 }
At the same time, the tax base for transactions on the supply of goods/services cannot be lower than the purchase price of such goods/services, the tax base for transactions on the supply of self-manufactured goods/services cannot be lower than normal prices, and the tax base for transactions on the supply of non-current assets cannot be lower than the book value (residual) according to accounting data as of the beginning of the reporting (tax) period during which such transactions are carried out (in the absence of accounting for non-current assets - based on the normal price), with the exception of:
{Clause 188.1 of Article 188 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; with amendments made in accordance with Law No. 909-VIII of 24.12.2015 }
goods (services), prices for which are subject to state regulation;
{Clause 188.1 of Article 188 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 }
gas supplied for the needs of the population;
{Clause 188.1 of Article 188 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 }
electrical energy, the price for which has developed on the electrical energy market.
{ Paragraph 188.1 of Article 188 is supplemented with a new paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
The contractual (contractual) value includes any amounts of money, the value of tangible and intangible assets transferred to the taxpayer directly by the buyer or through any third party in connection with the compensation of the cost of goods/services. The contractual (contractual) value does not include the amounts of penalties (fines and/or penalties), three percent per annum of the overdue amount and inflation costs, compensation for damage, including compensation for lost profits under decisions of international commercial and investment arbitrations or foreign courts, received by the taxpayer as a result of non-fulfillment or improper fulfillment of contractual obligations.
{Paragraph of clause 188.1 of Article 188 as amended by Law No. 657-VII of 24.10.2013 ; as amended by the Law No. 466-IX dated 16.01.2020 }
The tax base includes the cost of goods/services supplied (excluding the amount of compensation to cover the difference between actual costs and regulated prices (tariffs) in the form of a production subsidy from the budget and/or the amount of reimbursement to the lessor - a budgetary institution for the costs of maintaining leased real estate, utilities and energy), and the cost of tangible and intangible assets transferred to the taxpayer directly by the recipient of goods/services supplied by such taxpayer.
In cases provided for in Article 189 of this Code, the tax base shall be determined taking into account the provisions of Article 189 of this Code.
{Clause 188.1 of Article 188 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4014-VI of 04.11.2011 , No. 4834-VI dated 24.05.2012 ; as amended by Law No. 408-VII dated 04.07.2013 }
Article 189. Peculiarities of determining the tax base in the event of the supply of goods/services in certain cases↑
189.1. In the case of transactions in accordance with Clause 198.5 of Article 198 of this Code, the tax base for non-current assets is determined based on the book value (residual value) as of the beginning of the reporting (tax) period during which such transactions are carried out (in the absence of accounting for non-current assets - based on the usual price), and for goods/services - based on the cost of their acquisition.
{Clause 189.1 of Article 189 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 }
189.2. The cost of packaging that is defined as returnable (pledgeable) under the terms of the agreement (contract) is not included in the tax base. If the returnable packaging is not returned to the sender within a period of more than 12 calendar months from the date of receipt, the cost of such packaging is included in the tax base of the recipient.
189.3. If a taxpayer carries out entrepreneurial activity in the supply of used goods (commission trade) accepted under a commission agreement from persons not registered as taxpayers, the tax base is the commission fee of such taxpayer.
{Paragraph one of clause 189.3 of Article 189 as amended by Law No. 1084-VIII of 12.04.2016 }
In cases where a taxpayer carries out activities related to the supply of used goods purchased from persons not registered as taxpayers under contracts providing for the transfer of ownership of such goods, the tax base is the positive difference between the selling price and the purchase price of such goods, determined in accordance with the procedure established by this section.
{Paragraph two of clause 189.3 of Article 189 as amended by Laws No. 1084-VIII of 12.04.2016 , No. 1797-VIII of 21.12.2016 }
The date of increase in the taxpayer's tax liabilities is the date determined according to the rules established by Clause 187.1 of Article 187 of this Code.
In this case, the selling price of a used vehicle is determined by:
for persons not registered as taxpayers, based on the price specified in the purchase and sale agreement, but not lower than the average market value of the relevant vehicle or not lower than the market value of such vehicle calculated by the subject of valuation activities authorized to carry out valuation in accordance with the law (at the taxpayer's choice). In this case, the average market value of the vehicle is determined in accordance with paragraph 173.1 of Article 173 of this Code;
{Paragraph five of clause 189.3 of Article 189 as amended by Laws No. 1084-VIII dated 12.04.2016 , No. 354-IX dated 05.12.2019 - regarding the entry into force of the changes, see paragraph 1 of section II; as amended by Law No. 4143-IX dated 17.12.2024 }
for taxpayers based on the agreed (contract) value, but not lower than regular prices.
For the purposes of this section:
Used goods are goods that have been in use for at least a year and are suitable for further use in their original condition or after repair, as well as vehicles that do not fall under the definition of a new vehicle.
{Paragraph eight of clause 189.3 of Article 189 as amended by Law No. 1084-VIII of 12.04.2016 }
New vehicles are considered to be:
a) land vehicle - one that is registered in Ukraine for the first time in accordance with the legislation, has not been registered in other states and has a total land mileage of up to 6,000 kilometers;
{Paragraph ten of clause 189.3 of Article 189 as amended by Law No. 1084-VIII of 12.04.2016 }
b) a vessel - one that is registered for the first time in Ukraine in accordance with the legislation, has not been registered in other states and no more than 100 hours have passed since its first commissioning;
{Paragraph eleven of clause 189.3 of Article 189 as amended by Law No. 1084-VIII of 12.04.2016 }
c) aircraft - one that is registered in Ukraine for the first time in accordance with the legislation, has not been registered in other states and its flight time before such registration does not exceed 40 hours after the first commissioning. The flight time is considered to be the time calculated from the block time of the aircraft's take-off to the block time of its landing;
{Paragraph twelfth of clause 189.3 of Article 189 as amended by Law No. 1084-VIII of 12.04.2016 }
{Paragraph thirteen of clause 189.3 of Article 189 is excluded on the grounds Law No. 1084-VIII of 12.04.2016 }
189.4. The tax base for goods/services transferred/received under commission (consignment), surety, or trust management agreements is the cost of supplying these goods/services, determined in accordance with the procedure established by Article 188 of this Code.
{Paragraph one of item 189.4 of Article 188 as amended by Law No. 466-IX of January 16, 2020 }
The date of increase in tax liabilities and tax credit of taxpayers supplying/receiving goods/services under commission (consignment) agreements, suretyship, mandate, trust management, other civil law agreements and without ownership of such goods/services is determined according to the rules established by Articles 187 and 198 of this Code.
The specified procedure for the date of occurrence of tax liabilities and tax credit also applies to transactions involving the forced sale of seized property by judicial authorities.
189.5. In the case of the supply of goods that were returned by the lessee to the lessor under a financial leasing agreement due to its non-performance or improper performance (including those returned on the basis of a notary's executive inscription), and the lessor did not include tax amounts in the tax credit for the transaction to return such goods, the tax base is the positive difference between the supply price and the purchase price of such goods.
The purchase price is determined as the cost of goods at which such goods were returned to the lessor, namely as the original cost of goods (financial leasing object) minus the lease payments paid in part to compensate for the cost of the financial leasing object. In the case of purchasing goods from a taxpayer, the purchase price is determined taking into account value added tax.
If, for goods, the tax base upon supply of which was determined as the positive difference between the supply price and the purchase price, in future tax periods the amounts of tax on the transaction for the return of such goods were included in the lessor's tax credit, the provisions of paragraph 198.5 of Article 198 of this Code shall apply.
{Clause 189.5 of Article 189 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 425-IX of 20.12.2019 }
189.6. The provisions of paragraphs 189.3-189.5 of this article do not apply to operations on the export of goods outside the customs territory of Ukraine or on the import of goods into the customs territory of Ukraine within the framework of the specified agreements.
189.7. If a taxpayer carries out transactions for the supply of goods/services that are subject to taxation in accordance with Article 185 of this Code, secured by the buyer's debt obligations provided to such taxpayer in the form of a simple or transferable bill of exchange, or other debt instruments (hereinafter referred to as the bill of exchange) issued by such buyer or a third party, the tax base is the contractual value determined in accordance with the procedure established by Clause 188.1 of Article 188 of this Code, excluding discounts or other reductions from the nominal value of such bill, and for interest-bearing bills - such contractual value increased by the amount of interest accrued or to be accrued on the nominal value of such bill.
189.8. Tax liabilities are not accrued on the face value of the bill, including without taking into account discounts or including interest.
189.9. If fixed production or non-production assets are liquidated by the taxpayer's independent decision, such liquidation shall be considered for tax purposes as the supply of such fixed production or non-production assets at normal prices, but not lower than the book value at the time of liquidation.
The norm of this paragraph does not apply to cases when fixed production or non-production assets are liquidated due to their destruction or destruction due to force majeure circumstances, in other cases when such liquidation is carried out without the consent of the taxpayer, including in the case of theft of fixed production or non-production assets, which is confirmed in accordance with the legislation or when the taxpayer submits to the regulatory authority a relevant document on the destruction, dismantling or transformation of fixed production or non-production assets in another way, as a result of which they cannot be used for their original purpose.
{Clause 189.9 of Article 189 as amended by Law No. 3609-VI of 07.07.2011 }
189.10. If, as a result of the liquidation of non-current assets, components, parts, or other waste are obtained, which are recorded in material accounts for the purpose of their use in the payer's business activities, no tax liabilities are accrued for such transactions.
{Clause 189.11 of Article 189 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
189.12. In cases where a taxpayer carries out operations to supply to persons who are not registered as taxpayers, agricultural products and products of their processing, previously purchased (procured) by such taxpayer from individuals who are not taxpayers of this tax, the object of taxation is the trade mark-up (surcharge) established by such taxpayer.
189.13. In the case of the supply of tickets for travel on buses and for the transportation of luggage in accordance with the Law of Ukraine "On Road Transport", the tax base is the remuneration, which includes the bus station fee. The tax base does not include the cost of transportation, which is transferred to the carrier, and the amount of expenses for passenger insurance, which is transferred to the insurance company.
{Article 189 was supplemented by paragraph 189.13 in accordance with Law No. 4834-VI of 24.05.2012 }
189.14. In the case of supply in the customs territory of Ukraine of goods that are products of processing of goods placed under the customs regime of processing in the customs territory, including those received as payment for the supply of processing services, the tax base is determined in accordance with Article 188 of this Code.
{Article 189 was supplemented by paragraph 189.14 in accordance with Law No. 4915-VI of 07.06.2012 }
189.15. In the case of supply (sale, alienation in another way) by banks and other financial institutions of property acquired by them as a result of foreclosure on such property, the tax base is the positive difference between the supply price and the purchase price of such property. The purchase price is determined as the value of the property at which such property was acquired. In the case of acquisition of property from a taxpayer, the purchase price is determined taking into account value added tax.
If tax amounts for such property were included in the tax credit by a bank or other financial institution, the provisions of Clause 198.5 of Article 198 of this Code shall apply.
{Article 189 was supplemented by paragraph 189.15 in accordance with Law No. 909-VIII of 24.12.2015 }
189.16. The tax base for transactions on the supply of services for the transportation (movement, transportation) of natural gas through cross-border gas pipelines (transportation of natural gas through the territory of Ukraine under the customs transit regime), performed (provided) by the public joint-stock company "National Joint-Stock Company "Naftogaz of Ukraine", is determined based on the contractual (contractual) value, taking into account national taxes and fees.
{Article 189 was supplemented by paragraph 189.16 in accordance with Law No. 909-VIII of 24.12.2015 }
189.17. The tax base for operations involving the export of goods outside the customs territory of Ukraine is the contractual value of such goods, indicated in the customs declaration , drawn up in accordance with the requirements of the Customs Code of Ukraine .
{Article 189 is supplemented by clause 189.17 in accordance with Law No. 466-IX of January 16, 2020 }
189.18. In the case of the supply of tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes for which maximum retail prices are established, when they are supplied within the customs territory of Ukraine, the tax base is the maximum retail price of such goods excluding value added tax.
{ Article 189 is supplemented by item 189.18 in accordance with By law No. 1914-IX dated 30.11.2021 }
Article 190. Procedure for determining the tax base for goods imported into the customs territory of Ukraine, services supplied by non-residents in the customs territory of Ukraine↑
190.1. The tax base for goods imported into the customs territory of Ukraine is the contractual value, but not lower than the customs value of these goods, determined in accordance with Section III of the Customs Code of Ukraine , taking into account the customs duty and excise tax payable and included in the price of the goods.
The tax base for tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes for which maximum retail prices are established, imported into the customs territory of Ukraine, is the maximum retail price of such goods excluding value added tax.
{Paragraph 190.1 of Article 190 is supplemented with a new paragraph in accordance with By law No. 1914-IX dated 30.11.2021 }
When determining the tax base for goods imported into the customs territory of Ukraine, the conversion of foreign currency into the currency of Ukraine shall be carried out at the exchange rate determined in accordance with Article 39-1 of this Code.
{Paragraph of Clause 190.1 of Article 190 as amended by Law No. 1200-VII of 10.04.2014 }
{Clause 190.1 of Article 190 as amended by Law No. 4915-VI of 07.06.2012 }
190.2. For services supplied by non-residents in the customs territory of Ukraine, the tax base is the contractual (contractual) value of such services, taking into account taxes and fees, except for value added tax, which are included in the supply price in accordance with the legislation. The determined value is converted into national currency at the exchange rate of the National Bank of Ukraine on the date of the occurrence of tax liabilities. In the case of receiving services from non-residents without paying for them, the tax base is determined based on the usual prices for such services excluding tax.
190.3. In cases provided for in Article 191 of this Code, the tax base shall be determined taking into account the provisions of Article 191 of this Code.
{Article 190 is supplemented by paragraph 190.3 in accordance with Law No. 4915-VI of 07.06.2012 }
Article 191. Peculiarities of taxation of operations on the import into the customs territory of Ukraine of goods in international postal and express shipments, in unaccompanied baggage and goods imported into the customs territory of Ukraine by individuals in hand luggage and/or in accompanied baggage
{Title of Article 191 as amended by Law No. 2628-VIII of 11/23/2018 }
191.1. Peculiarities of taxation of operations on the import of goods into the customs territory of Ukraine in international postal and express shipments, and in unaccompanied baggage.
191.1.1. In the case of importation into the customs territory of Ukraine of goods in international postal and express shipments, in unaccompanied baggage, the tax base is their customs value (for legal entities or individual entrepreneurs) or part of the total invoice value (for individuals), determined in accordance with the Customs Code of Ukraine , taking into account the duty and excise tax payable.
{Subclause 191.1.1 of Clause 191.1 of Article 191 as amended by Law No. 1998-IX of 01/25/2022 }
191.1.2. The date of occurrence of tax liabilities in the case of importation into the customs territory of Ukraine of goods in international postal and express shipments, in unaccompanied baggage is the date of submission to the controlling authority of a customs declaration or a document that, in accordance with the legislation, replaces a customs declaration.
191.1.3. Payment of tax accrued in the registers (temporary and/or additional) of international postal and express shipments submitted by a postal operator or express carrier shall be made taking into account the features established by Articles 236 and 374 of the Customs Code of Ukraine.
{Subparagraph 191.1.3 of paragraph 191.1 of Article 191 as amended by Law No. 1998-IX of 01/25/2022 }
191.1.4. Payment of tax calculated in customs declarations submitted by individuals, legal entities, individual entrepreneurs or persons authorized by them shall be carried out in accordance with the general procedure determined by the Customs Code of Ukraine .
{Subparagraph 191.1.4 of paragraph 191.1 of Article 191 as amended by Law No. 1998-IX of 01/25/2022 }
191.1.5. When determining the tax base for goods imported into the customs territory of Ukraine in international postal and express shipments, in unaccompanied baggage, the conversion of foreign currency into the currency of Ukraine is carried out at the exchange rate determined in accordance with Article 39 - 1 of this Code.
{Clause 191.1 of Article 191 as amended by Law No. 1200-VII of 10.04.2014 ; as amended by Law No. 2628-VIII of 23.11.2018 }
191.2. Peculiarities of determining the tax base for goods imported into the customs territory of Ukraine by individuals in hand luggage and/or in accompanied luggage.
{Sub-clause 191.2.1 of clause 191.2 of Article 191 is excluded on the basis of the Law No. 2245-VIII dated 07.12.2017 }
191.2.2. In the case of import into the customs territory of Ukraine by individuals in hand luggage and/or in accompanied baggage of goods (except for excisable goods and personal effects), the total invoice value of which exceeds the equivalent of 1,000 euros, through checkpoints across the state border of Ukraine open to air traffic, the tax base is the part of their total invoice value exceeding the equivalent of 1,000 euros, taking into account the duty payable.
{Subclause 191.2.2 of Clause 191.2 of Article 191 as amended by Law No. 1200-VII of 10.04.2014 }
191.2.3. In the case of import into the customs territory of Ukraine by individuals in hand luggage and/or in accompanied baggage of goods (except for excisable goods and personal effects), the total invoice value of which exceeds the equivalent of 500 euros, through checkpoints across the state border of Ukraine other than those open to air traffic, the tax base is the part of their total invoice value exceeding the equivalent of 500 euros, taking into account the duty payable.
In the case of import into the customs territory of Ukraine in hand luggage and/or in accompanied baggage of goods (except for excisable goods and personal effects), the total invoice value of which does not exceed the equivalent of 500 euros and the total weight of which does not exceed 50 kg, through checkpoints across the state border of Ukraine other than those open to air traffic by an individual who has been absent from Ukraine for less than 24 hours or who enters Ukraine more than once within 72 hours, the tax base is the part of the total invoice value of such goods that exceeds the equivalent of 50 euros, taking into account the duty payable.
{Subparagraph 191.2.3 of paragraph 191.2 of Article 191 is supplemented by the second paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
{Subclause 191.2.3 of Clause 191.2 of Article 191 as amended by Law No. 1200-VII of 10.04.2014 }
191.2.4. In the case of import into the customs territory of Ukraine by individuals in hand luggage and/or in accompanied baggage of goods (except for excisable goods and personal effects) through checkpoints across the state border of Ukraine other than those open to air traffic, the total weight of which exceeds 50 kg, the tax base is the total invoice value of the goods, calculated in proportion to the weight exceeding 50 kg, taking into account the duty payable.
{Subclause 191.2.4 of Clause 191.2 of Article 191 as amended by Law No. 1200-VII of 10.04.2014 }
191.3. The invoice value of goods imported into the customs territory of Ukraine in international postal and express shipments, in unaccompanied baggage, by individuals in hand luggage and/or in accompanied baggage, is determined in accordance with the procedure provided for by the Customs Code of Ukraine .
{Clause 191.3 of Article 191 as amended by Law No. 1914-IX of 30.11.2021 }
{Article 191 as amended by Law No. 4915-VI of 07.06.2012 }
Article 192. Peculiarities of determining the tax base in certain cases (procedure for adjusting tax liabilities and tax credit)↑
192.1. If, after the supply of goods/services, any change is made to the amount of compensation for their value, including a subsequent price revision after the supply, recalculation in cases of return of goods/services to the person who provided them, or when the supplier returns the amount of prepayment for goods/services, the amounts of tax liabilities and tax credit of the supplier and recipient are subject to appropriate adjustment based on the calculation of the adjustment to the tax invoice, drawn up in accordance with the procedure established for tax invoices, and registered in the Unified Register of Tax Invoices.
{Paragraph one of clause 192.1 of Article 192 as amended by Law No. 71-VIII of 28.12.2014 }
A calculation of an adjustment to a tax invoice cannot be registered in the Unified Register of Tax Invoices later than 1095 calendar days from the date of preparation of the tax invoice to which such an adjustment calculation is prepared.
{Clause 192.1 of Article 192 is supplemented with a new paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
The adjustment calculation made by the supplier of goods/services to the tax invoice, which is drawn up for the recipient - the taxpayer, is subject to registration in the Unified Register of Tax Invoices:
{Clause 192.1 of Article 192 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 ; with amendments made in accordance with Law No. 1797-VIII of 21.12.2016 }
by the supplier (seller) of goods/services, if it is intended to increase the amount of compensation for their cost in favor of such supplier or if the adjustment of quantitative and cost indicators does not ultimately change the amount of compensation;
{Clause 192.1 of Article 192 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 }
by the recipient (buyer) of goods/services, if it is intended to reduce the amount of compensation for the cost of goods/services to their supplier, for which the supplier sends a prepared adjustment calculation to the recipient.
{Clause 192.1 of Article 192 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 ; with amendments made in accordance with Law No. 909-VIII of 24.12.2015 }
Adjustment calculations made by the taxpayer to tax invoices drawn up before February 1, 2015, adjustment calculations to tax invoices that were not subject to provision to the recipient (buyer) - the taxpayer, are subject to registration in the Unified Register of Tax Invoices by the supplier (seller). The above does not apply to adjustment calculations that provide for a reduction in the amount of compensation for the cost of goods/services to their supplier (reduction of the supplier's tax liability and the recipient's tax credit), drawn up after July 1, 2015 to tax invoices drawn up before July 1, 2015 for the recipient (buyer) - the taxpayer, which are subject to registration in the Unified Register of Tax Invoices by the recipient (buyer) of goods/services.
{Clause 192.1 of Article 192 is supplemented with a new paragraph in accordance with Law No. 643-VIII of July 16, 2015 ; as amended by Law No. 1797-VIII of December 21, 2016 }
The calculation of adjustments to the tax invoice is also made in the event of correction of errors made when drawing up the tax invoice, including those not related to a change in the amount of compensation for the cost of goods/services.
{Clause 192.1 of Article 192 is supplemented by a paragraph in accordance with Law No. 71-VIII of 28.12.2014 }
{Clause 192.1 of Article 192 as amended by Laws No. 3609-VI of 07.07.2011 , No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 }
192.1.1. If, as a result of such recalculation, the amount of compensation is reduced in favor of the taxpayer - supplier, then:
a) the supplier shall accordingly reduce the amount of tax liabilities based on the results of the tax period during which such recalculation was carried out;
{Paragraph two of subparagraph 192.1.1 of paragraph 192.1 of Article 192 as amended by Law No. 643-VIII of 16.07.2015 }
b) the recipient shall accordingly reduce the amount of the tax credit based on the results of such tax period if he is registered as a taxpayer on the date of the adjustment, and also increase the tax credit in connection with the receipt of such goods/services.
The supplier has the right to reduce the amount of tax liabilities only after registering the adjustment to the tax invoice in the Unified Register of Tax Invoices.
{Subclause 192.1.1 of clause 192.1 of Article 192 is supplemented by a paragraph in accordance with Law No. 643-VIII of 16.07.2015 }
192.1.2. If, as a result of such recalculation, the amount of compensation increases in favor of the taxpayer - supplier, then:
a) the supplier shall accordingly increase the amount of tax liabilities based on the results of the tax period during which such recalculation was carried out;
{Paragraph two of subparagraph 192.1.2 of paragraph 192.1 of Article 192 as amended by Law No. 643-VIII of July 16, 2015 }
b) the recipient shall accordingly increase the amount of the tax credit based on the results of such tax period if he is registered as a taxpayer on the date of the recalculation.
The recipient has the right to increase the amount of the tax credit only after the supplier registers the adjustment calculation to the tax invoice in the Unified Register of Tax Invoices.
{Subparagraph 192.1.2 of paragraph 192.1 of Article 192 is supplemented by a paragraph in accordance with Law No. 643-VIII of July 16, 2015 }
192.2. The provision of paragraph 192.1 of this article does not apply to cases where the supplier of goods/services is not a tax payer at the end of the reporting (tax) period in which such recalculation was made.
A reduction in the amount of tax liabilities of a taxpayer - supplier in the event of a change in the amount of compensation for the cost of goods/services provided to persons who were not payers of this tax on the date of such supply is permitted only upon return of previously delivered goods to the property of the supplier with provision of full monetary compensation for their cost to the recipient, including when revising prices related to warranty replacement of goods or low-quality goods in accordance with the law or contract.
A reduction in the amount of tax liabilities of a taxpayer - supplier - telecommunications operator in the event of a subscriber's refusal of prepaid but not received telecommunications services is permitted when transferring part of the amount of the prepaid telecommunications services as a charitable donation when performing a charitable telecommunications message on behalf of the subscriber.
{Clause 192.2 of Article 192 was supplemented by the third paragraph in accordance with Law No. 1665-VIII of 06.10.2016 }
192.3. The result of the recalculation of tax liabilities and tax credit of the supplier and recipient is reflected in the tax return for the reporting tax period in the manner determined by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 192.3 of Article 192 as amended by Law No. 1797-VIII of 21.12.2016 }
193.1. Tax rates are set on the tax base in the following amounts:
a) 20 percent;
{Subparagraph "a" of paragraph 193.1 of Article 193 as amended by Law No. 1166-VII of March 27, 2014 }
b) 0 percent;
c) 7 percent on transactions with:
supply to the customs territory of Ukraine and import into the customs territory of Ukraine of medicinal products permitted for production and use in Ukraine and included in the State Register of Medicinal Products, as well as medical devices that are included in the State Register of Medical Equipment and Medical Devices or meet the requirements of relevant technical regulations, as confirmed by a document of conformity, and permitted for placing on the market and/or putting into operation and use in Ukraine;
{Paragraph two of subparagraph "c" of paragraph 193.1 of Article 193 as amended by Law No. 2245-VIII of 07.12.2017 }
supply to the customs territory of Ukraine and import into the customs territory of Ukraine of medicinal products, medical devices and/or medical equipment permitted for use within the framework of clinical trials, the permission for which has been granted by the central executive body responsible for the formation of state policy in the field of healthcare;
{Paragraph three of subparagraph "c" of paragraph 193.1 of Article 193 as amended by Law No. 1914-IX of 30.11.2021 }
importation into the customs territory of Ukraine of unregistered medicinal products within the framework of programs of expanded access of patients to unregistered medicinal products and/or programs of access of research subjects (patients) to the investigational medicinal product after the completion of the clinical trial (hereinafter referred to as the access programs) according to the list and in the volumes determined by the central executive body that ensures the formation of state policy in the field of healthcare, in the manner and under the conditions determined by the Law of Ukraine "On Medicinal Products", as well as further free supply of medicinal products imported on the basis of this paragraph in the customs territory of Ukraine for the benefit of medical service providers involved in conducting access programs and patients participating in access programs, within the limits and volumes of the specified access programs;
{Subparagraph "c" of paragraph 193.1 of Article 193 is supplemented with a new paragraph in accordance with Law No. 3603-IX of 23.02.2024 }
provision of services for the presentation (conducting) of theatrical, operatic, ballet, musical, concert, choreographic, puppet, circus, sound, light and other performances, productions, performances by professional artistic collectives, artistic groups, actors and artists (performers), film premieres, cultural and artistic events;
{Subparagraph "c" of paragraph 193.1 of Article 193 is supplemented by a paragraph in accordance with Law No. 962-IX of 04.11.2020 }
provision of services for showing original musical works, demonstrating exhibition projects, conducting excursions for groups and individual visitors to museums, zoos and reserves, and visiting their territories and objects by visitors;
{Subparagraph "c" of paragraph 193.1 of Article 193 is supplemented by a paragraph in accordance with Law No. 962-IX of 04.11.2020 }
provision of services for the distribution, demonstration, public notification and public screening of films adapted in accordance with the legislation in Ukrainian-language versions for persons with visual impairments and persons with hearing impairments;
{Subparagraph "c" of paragraph 193.1 of Article 193 is supplemented by a paragraph in accordance with Law No. 962-IX of 04.11.2020 }
supply of temporary accommodation (accommodation) services provided by hotels and similar temporary accommodation facilities (class 55.10, group 55 of the KVED DK 009:2010 );
{Subparagraph "c" of paragraph 193.1 of Article 193 is supplemented by a paragraph in accordance with Law No. 962-IX of 04.11.2020 }
sale of tickets for sporting events at the national and international levels;
{Subparagraph "c" of paragraph 193.1 of Article 193 is supplemented with a new paragraph in accordance with Law No. 1984-IX of 17.12.2021 }
{Clause 193.1 of Article 193 is supplemented by subparagraph "c" in accordance with Law No. 1166-VII of March 27, 2014 ; as amended by Law No. 1200-VII of April 10, 2014 }
d) 14 percent on transactions for the supply in the customs territory of Ukraine and the import into the customs territory of Ukraine of agricultural products classified under the following codes according to the UKT FEA : 1001, 1003, 1005, 1201, 1205, 1206 00.
{Clause 193.1 of Article 193 is supplemented by subparagraph "d" in accordance with Law No. 1115-IX of 17.12.2020 ; as amended by Law No. 1600-IX of 01.07.2021 }
Article 194. Transactions subject to tax at the basic rate↑
194.1. The transactions specified in Article 185 of this Code, except for transactions that are not subject to taxation, exempt from taxation, and transactions to which a zero rate and 7 and 14 percent are applied, are taxed at the rate specified in subparagraph "a" of paragraph 193.1 of Article 193 of this Code, which is the main one.
{Clause 194.1 of Article 194 as amended by Laws No. 1166-VII of March 27, 2014 , No. 1115-IX of December 17, 2020 }
194.1.1. The tax is 20 percent, 7 percent and 14 percent of the tax base and is added to the price of goods/services.
{Subclause 194.1.1 of Clause 194.1 of Article 194 as amended by Laws No. 1166-VII of March 27, 2014 , No. 1115-IX of December 17, 2020 }
Article 195. Transactions subject to zero tax rate↑
195.1. Transactions with:
195.1.1. export of goods outside the customs territory of Ukraine:
a) under the export customs regime;
b) under the customs regime of re-export, if the goods are placed under such regime in accordance with paragraphs 3 (regarding goods in the form of products of their processing) and 5 of part one of Article 86 of the Customs Code of Ukraine;
{Sub-clause "b" of sub-clause 195.1.1 of clause 195.1 of Article 195 as amended by the Law No. 2497-VIII dated 10.07.2018 }
c) under the customs regime of duty-free trade;
d) in the customs regime of a free customs zone.
Goods are considered to be exported outside the customs territory of Ukraine if such export is confirmed in the manner determined by the Cabinet of Ministers of Ukraine by a customs declaration drawn up in accordance with the requirements of the Customs Code of Ukraine .
{Subparagraph 195.1.1 of paragraph 195.1 of Article 195 as amended by Law No. 4915-VI of 07.06.2012 }
195.1.2. supply of goods:
a) for refueling or provisioning seagoing vessels that:
are used for navigation activities, transportation of passengers or cargo for a fee, industrial, fishing or other economic activities carried out outside the territorial waters of Ukraine;
used for rescue or assistance in neutral or territorial waters of other countries;
are part of the Naval Forces of Ukraine and are sent outside the territorial waters of Ukraine, including to anchorages;
b) for refueling or supplying aircraft that:
perform international flights for navigational purposes or for the carriage of passengers or cargo for remuneration;
are part of the Air Force of Ukraine and are sent beyond the air border of Ukraine, including to temporary bases;
c) for refueling (refueling) and providing spaceships, space launch vehicles or Earth satellites;
d) for refueling (refueling) or providing ground military transport or other special contingent of the Armed Forces of Ukraine participating in peacekeeping operations abroad of Ukraine, or in other cases provided for by law;
e) duty-free shops, in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The supply of goods by duty-free shops may be carried out exclusively:
individuals traveling outside the customs territory of Ukraine;
individuals entering the customs territory of Ukraine at checkpoints across the state border of Ukraine open to international air traffic;
individuals who travel by vehicles owned by residents and located outside the customs border of Ukraine.
Violation of the norms of this subparagraph shall entail liability established by law. The procedure for monitoring compliance with the norms of this subparagraph shall be established by the Cabinet of Ministers of Ukraine.
{Sub-paragraph "g" of subparagraph 195.1.2 of paragraph 195.1 of Article 195 as amended by Law No. 4915-VI of 07.06.2012 ; as amended by Law No. 1797-VIII of 21.12.2016 }
195.1.3. provision of the following services:
a) international transportation of passengers and luggage and cargo by rail, road, sea and river and air transport.
For the purposes of this subparagraph, carriage shall be considered international if such carriage is carried out under a single international transport document;
b) services that involve work with movable property previously imported into the customs territory of Ukraine for the performance of such work and exported outside the customs territory of Ukraine by the payer who performed such work, or by a non-resident recipient.
Works with movable property include works on the processing of goods, which may include the actual processing (processing) of goods - assembly, assembly, mounting and adjustment, as a result of which other goods are created, including the supply of services for the processing of toll raw materials, as well as the modernization and repair of goods, which involves carrying out a set of operations with partial or complete restoration of the production resource of an object (or its components), determined by regulatory and technical documentation, as a result of which an improvement in the condition of such an object is expected;
c) services for servicing aircraft operating international flights.
Services for servicing aircraft operating international flights include services that are comprehensively necessary and directly related to the operation of an international flight, namely:
servicing aircraft and passengers at the airport (landing and takeoff of aircraft, servicing passengers in the airport terminal, ensuring aviation security, over-parking of aircraft);
ground handling services for aircraft and passengers at airports;
rental of airport premises for use in servicing international flights (offices, check-in counters and other office premises rented by air carriers operating international flights);
aircraft maintenance personnel services.
{Sub-clause "d" of subparagraph 195.1.3 of clause 195.1 of Article 195 was excluded on the basis of Law No. 1621-VII of 31.07.2014 }
195.2. If transactions for the supply of goods are exempt from taxation in the customs territory of Ukraine in accordance with the provisions of this section, a zero rate shall be applied to transactions for the export of such goods.
{Clause 195.2 of Article 195 as amended by Law No. 4915-VI of 07.06.2012 }
Article 196. Operations that are not subject to taxation↑
196.1. The following transactions are not subject to taxation:
196.1.1. issue (issue), placement in any form of management and sale (redemption, redemption) for funds of securities issued (issued) by business entities, the National Bank of Ukraine, the central executive body that ensures the formation and implementation of state financial policy and/or implements state budget policy in the field of management of state debt and state-guaranteed debt, local governments in accordance with the law, including investment and mortgage certificates, certificates of a real estate fund, derivatives, as well as corporate rights expressed in forms other than securities; exchange of the specified securities and corporate rights expressed in forms other than securities for other securities, corporate rights expressed in forms other than securities; settlement and clearing, registrar and depository activities in the securities market, as well as asset management activities (including pension assets, bank management funds), in accordance with the law and other types of professional activities in the stock market, which are subject to licensing in accordance with the law.
{Paragraph one of subparagraph 196.1.1 of paragraph 196.1 of Article 196 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.05.2012 , No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 , No. 1016-IX of 01.12.2020 }
The norms of this sub-item do not apply to transactions for the sale of blank traveler's, bank and registered checks, securities, settlement and payment documents, plastic (settlement) cards, as well as anniversary and commemorative coins sold for numismatic purposes and other goods/services for which a separate fee is charged in the form of a fixed amount or percentage;
196.1.2. transfer of property into safekeeping (responsible storage), into concession, as well as into leasing (rent), except for transfer into financial leasing;
{Paragraph one of subparagraph 196.1.2 of paragraph 196.1 of Article 196 as amended by Law No. 3609-VI of 07.07.2011 }
return of property from storage (responsible custody) to its owner, as well as property previously transferred for concession or lease (rent) to the concessionaire or lessor (lessor), except for property transferred for financial leasing;
{Paragraph two of subparagraph 196.1.2 of paragraph 196.1 of Article 196 as amended by Law No. 3609-VI of 07.07.2011 }
accrual and payment of interest or commissions as part of the rental (leasing) payment within the framework of a financial leasing agreement;
{Paragraph three of subparagraph 196.1.2 of paragraph 196.1 of Article 196 as amended by Law No. 3609-VI of 07.07.2011 }
transfer of property as collateral (mortgage) to the lender (creditor) and/or as security for another valid claim of the creditor, return of such property from collateral (mortgage) to its owner after the expiration of the relevant agreement, if the place of such transfer (return) is located in the customs territory of Ukraine;
cash payments of the principal amount of the consolidated mortgage debt and interest accrued thereon, consolidation and/or purchase (sale) of the consolidated mortgage debt, replacement of one share of the consolidated mortgage debt with another, or return (repurchase) of such consolidated mortgage debt in accordance with the law by or in favor of the resident;
196.1.3. provision of insurance, co-insurance or reinsurance services by persons licensed to carry out insurance activities in accordance with the law, as well as services related to such activities by insurance (reinsurance) brokers and insurance agents;
provision of services for mandatory state social insurance (including pension insurance), non-state pension provision, attraction and servicing of pension deposits and accounts of participants in banking management funds, administration of non-state pension funds;
196.1.4. circulation of currency values (except for bank metals, banknotes and coins used for numismatic purposes, as well as foreign coins made of precious metals, the tax base of which is the sales value); issue, circulation and redemption of lottery tickets, other documents certifying the right to participate in lotteries; purchase of chips, tokens, payment in another way for the right to participate in a gambling game, payment (transfer) of winnings by the organizer of gambling games; placing a bet for the purpose of placing a bet and payment of winnings by a business entity conducting a bet (bookmaker's bet, totalizator bet); payment of cash winnings (prizes) and cash rewards;
{Subclause 196.1.4 of Clause 196.1 of Article 196 as amended by Law No. 4238-VI of 12/22/2011 ; as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Laws No. 1914-IX of 11/30/2021 , No. 3325-IX of 08/10/2023 , No. 3706-IX of 05/09/2024 }
196.1.5. assignment of the right of claim, transfer of debt, trading in debt obligations (claims) for cash or securities, with the exception of operations for the collection of debt claims and factoring (factoring) operations, except for factoring operations, if the object of the debt is currency values, securities, including compensation papers (certificates), investment certificates, fixed-income mortgage certificates, operations for the assignment of the right of claim under mortgage-secured credits (loans), housing checks, land bonds and derivatives;
transfer of ownership of the financial leasing object to the lessor (new creditor) from the lessor (primary creditor) with preservation of the rights and obligations of the parties under the financial leasing agreement in the event that the lessor (primary creditor) during the transfer of such financial leasing object to the lessee accrued and reflected in the tax reporting for the relevant reporting (tax) period tax liabilities;
provision of services with:
execution of payment transactions provided by payment service providers and payment system operators;
settlement and cash services;
collections;
attraction, placement and return of funds under loan, deposit, and contribution agreements (including pension);
management of funds and securities (corporate rights and derivatives);
assignment, granting, management and assignment of claims under financial loans of financial institutions;
providing guarantees, bank guarantees;
issuance, redemption of electronic money;
issuance, exchange, redemption of digital money of the National Bank of Ukraine.
The list of services for the execution of payment transactions, settlement and cash services is determined by the National Bank of Ukraine in agreement with the central executive body that ensures the formation and implementation of state financial policy;
{Subclause 196.1.5 of Clause 196.1 of Article 196 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 , No. 5519-VI of 06.12.2012 , No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 4; as amended by Law No. 2888-IX of 12.01.2023 }
196.1.6. payments in cash of wages (other payments equivalent to them), as well as pensions, scholarships, subsidies, grants from budgets or the Pension Fund of Ukraine or other mandatory social insurance funds (except for those provided in the form of property);
payments of dividends, royalties in cash or in the form of securities made by the issuer;
provision of commission (brokerage, dealer) services for trading and/or managing securities (corporate rights), derivatives and currency values, including any monetary payments (including commissions) to stock or currency exchanges or over-the-counter stock systems or their members in connection with the organization and trading of securities by licensed securities dealers, as well as derivatives and currency values;
196.1.7. reorganization (merger, acquisition, division, separation and transformation) of legal entities.
When carrying out joint (joint) activities, the transfer of goods (works, services) to a separate balance sheet of the taxpayer authorized by the contract to keep records of the results of such joint activities is considered a supply of such goods (works, services);
196.1.8. provision by an out-of-school educational institution to pupils, students and trainees of paid services in the field of out-of-school education;
196.1.9. provision by banks (financial institutions) of services within the framework of management of bank management funds, real estate transaction funds, construction financing funds (including for transferring funds for construction financing from the construction financing fund), for making payments on mortgage certificates in accordance with the legislation;
196.1.10. payment of the arbitration fee and reimbursement of other expenses related to the resolution of the dispute by the arbitration court in accordance with the law;
196.1.11. provision of agency and chartering services for the merchant marine fleet by ship agents for the benefit of non-residents who provide services for the international transportation of passengers, their baggage, cargo or international shipments;
{Subparagraph 196.1.12 of paragraph 196.1 of Article 196 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
{Subparagraph 196.1.13 of paragraph 196.1 of Article 196 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
{Subparagraph 196.1.14 of paragraph 196.1 of Article 196 was excluded on the basis of Law No. 3387-VI of 19.05.2011 }
196.1.15. payment of rent or concession payment under contracts for the lease or concession of a single property complex of a state or municipal enterprise (its structural unit), if the lessors or concessionaires under the contracts are state authorities or local self-government bodies, and the payments are credited to the State Budget of Ukraine or the local budget in accordance with the law.
{Clause 196.1 of Article 196 is supplemented by subparagraph 196.1.15 in accordance with Law No. 4057-VI of 17.11.2011 }
196.1.16. import into the customs territory of Ukraine, export outside the customs territory of Ukraine, regardless of the selected customs regime, of goods whose customs value does not exceed the equivalent of 150 euros;
{Clause 196.1 of Article 196 is supplemented by subparagraph 196.1.16 in accordance with Law No. 4915-VI of 07.06.2012 ; as amended by Law No. 1166-VII of 27.03.2014 }
196.1.17. import into the customs territory of Ukraine of goods, the total invoice value of which does not exceed the equivalent of 150 euros, in unaccompanied baggage;
import into the customs territory of Ukraine of goods, the total customs value of which does not exceed the equivalent of 150 euros, to the address of one recipient - a legal entity or an individual entrepreneur in one dispatch from one sender in international postal shipments or in one express carrier shipment from one sender in international express shipments;
import into the customs territory of Ukraine of goods, the total invoice value of which does not exceed the equivalent of 150 euros, for one recipient - an individual in one dispatch from one sender in international postal shipments or in one express carrier's cargo from one sender in international express shipments;
{Clause 196.1 of Article 196 is supplemented by subparagraph 196.1.17 in accordance with Law No. 4915-VI of 07.06.2012 ; as amended by Law No. 1166-VII of 27.03.2014 ; as amended by Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 1998-IX dated 01/25/2022 }
196.1.18. import into the customs territory of Ukraine by individuals in hand luggage and/or in accompanied baggage of goods (except for excisable goods and personal effects), the total invoice value of which does not exceed the equivalent of 1,000 euros, through checkpoints across the state border of Ukraine open to air traffic;
import into the customs territory of Ukraine in hand luggage and/or in accompanied baggage of goods (except for excisable goods and personal effects), the total invoice value of which does not exceed the equivalent of 500 euros and the total weight of which does not exceed 50 kg, through checkpoints across the state border of Ukraine other than those open to air traffic by an individual who has been absent from Ukraine for more than 24 hours and who enters Ukraine no more than once within 72 hours;
import into the customs territory of Ukraine in hand luggage and/or in accompanied baggage of goods (except for excisable goods and personal effects), the total invoice value of which does not exceed the equivalent of 50 euros and the total weight of which does not exceed 50 kg, through checkpoints across the state border of Ukraine other than those open to air traffic by an individual who has been absent from Ukraine for less than 24 hours or who enters Ukraine more than once within 72 hours;
{Clause 196.1 of Article 196 is supplemented by subparagraph 196.1.18 in accordance with Law No. 4915-VI of 07.06.2012 ; as amended by Law No. 2245-VIII of 07.12.2017 }
196.1.19. conversion of the radio frequency spectrum (radio frequency resource) of Ukraine.
{Clause 196.1 of Article 196 is supplemented by subparagraph 196.1.19 in accordance with Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 3721-IX of 21.05.2024 }
196.1.20. transfer of property (confiscated property, finds, property recognized as ownerless, treasures, property that the owner has not applied for by the end of the storage period (including property defined in Article 184 of the Customs Code of Ukraine), which by right of inheritance or on other legal grounds passes into the ownership of the state, to the disposal of state institutions or organizations authorized to carry out their preservation or supply in accordance with the law, as well as transactions for the free transfer of the property specified in this paragraph in cases specified by the law, to the possession and use of state bodies, institutions (organizations) maintained at the expense of budget funds, as well as institutions in which orphans and children deprived of parental care are raised, family-type orphanages, and foster families.
{ Clause 196.1 of Article 196 is supplemented by subclause 196.1.20 in accordance with the Law No. 466-IX dated 16.01.2020 }
197.1. The following transactions are exempt from taxation:
197.1.1. supply of baby food products and baby products for infants according to the list approved by the Cabinet of Ministers of Ukraine;
197.1.2. provision of services for obtaining higher, secondary, vocational and pre-school education by educational institutions, including training of postgraduate and doctoral students, by educational institutions licensed to provide such services, including the provision of distance learning services on the Internet, if the Internet is used exclusively as a means of communication between a teacher and a student, as well as services for raising and teaching children in cultural centers, children's music, art, sports schools and clubs, art schools and services for accommodation of pupils or students in dormitories. Such services include services for:
{Paragraph one of subparagraph 197.1.2 of paragraph 197.1 of Article 197 as amended by Law No. 1525-IX of 03.06.2021 }
a) education and training of children provided by children's music and art schools, art schools, and cultural centers (playing musical instruments, choreography, fine arts, foreign language clubs (electives), and computer training);
b) maintenance, upbringing and education of children in preschool educational institutions both within the scope established by curricula and programs, and beyond the specified scope;
{Sub-clause "b" of sub-clause 197.1.2 of clause 197.1 of Article 197 as amended by the Law No. 466-IX dated 16.01.2020 }
c) all types of educational activities provided by general secondary education institutions of levels I-III;
{Sub-clause "c" of subparagraph 197.1.2 of clause 197.1 of Article 197 as amended by the Law No. 466-IX dated 16.01.2020 }
d) all types of educational activities provided by vocational (vocational and technical) education institutions;
{Sub-clause "d" of sub-clause 197.1.2 of clause 197.1 of Article 197 as amended by the Law No. 466-IX dated 16.01.2020 }
e) all types of educational activities provided by higher education institutions, including for obtaining other higher and postgraduate education;
{Paragraph six of subparagraph 197.1.2 of paragraph 197.1 of Article 197 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
e) training of students of preparatory departments of higher educational institutions;
f) re-study of individual disciplines and courses by expelled students (cadets) with subsequent passing of exams;
h) training of postgraduate and doctoral students;
g) taking candidate exams;
h) providing scientific consultations for individuals who are improving their qualifications independently;
i) pre-university training;
i) conducting lectures on science and technology, culture and art, physical education and sports, legal knowledge, tourism and local history;
j) providing consultations for pupils, students, cadets beyond the scope established by curricula and programs, for postgraduates, doctoral students;
j) organization of summer language courses, schools, seminars; group and individual physical education and sports classes at stadiums, in gyms and swimming pools, on tennis courts for children, pupils and students;
197.1.3. supply:
a) technical and other rehabilitation equipment (except for cars), services for their repair and delivery; special-purpose goods, including medical products for individual use, for persons with disabilities and other privileged categories of the population, defined by the legislation of Ukraine according to the list approved by the Cabinet of Ministers of Ukraine;
b) components and semi-finished products for the manufacture of technical and other rehabilitation equipment (except for automobiles), special-purpose goods, including medical products for individual use, for persons with disabilities and other privileged categories of the population according to the list approved by the Cabinet of Ministers of Ukraine;
c) passenger cars for persons with disabilities to the authorized executive body with their payment from state or local budgets and funds of mandatory state insurance funds, as well as transactions for their free transfer to persons with disabilities;
197.1.4. provision of services for the delivery of pensions, insurance payments and cash assistance to the population (regardless of the delivery method) at all stages of delivery to the end consumer;
197.1.5. provision of medical care services to the population (medical service) by healthcare institutions licensed to provide such services, as well as provision of services for persons with disabilities and children with disabilities by rehabilitation institutions licensed to provide such services in accordance with the legislation, except for the following services:
{Paragraph one of subparagraph 197.1.5 of paragraph 197.1 of Article 197 as amended by Law No. 3553-IX of 16.01.2024 }
a) provision of cosmetic care, other than that provided for medical indications;
b) massage to improve the health of the adult population, correct posture, etc.;
c) conducting preventive medical examinations with the preparation of a health report at the request of citizens;
d) conducting a hygienic examination of design materials and preliminary design proposals, including those regarding the location of the facility, as well as regulatory documentation for new production technologies and new types of products at the request of the customer, hygienic assessment of samples of new types of products;
e) providing consulting assistance on issues related to conducting state sanitary and hygienic expertise;
e) inspection at the request of the customer of facilities being built, reconstructed or operated, for the purpose of their compliance with sanitary legislation;
f) conducting, at the request of the customer, toxicological and hygienic, medical and biological, sanitary and hygienic, physiological and other examinations in order to determine the safety of products for human health;
g) issuance of permits to business entities for the production, use, transportation, storage, sale, disposal, destruction, and utilization of domestic and imported products and substances that are potentially hazardous to human health;
g) providing legal entities and individuals with consulting assistance on the application of health protection legislation, including on ensuring the sanitary and epidemiological well-being of the population;
h) conducting a medical examination of persons for the issuance of:
permits for the right to obtain and carry weapons for citizens, except for military personnel and officials whose carrying of weapons is provided for by law;
relevant documents for citizens to travel abroad at the call of relatives living in foreign countries, for recovery in foreign medical or sanatorium facilities at their own request, as well as for business trips (except for civil servants whose work is related to such trips and who have relevant medical documents);
vehicle driver's license;
i) medical services for congresses, conferences, symposiums, festivals, meetings, competitions, etc.;
i) medical care for citizens at their request in medical institutions with improved service;
j) organization of medical control of persons engaged in physical education and sports in health facilities;
j) conducting preventive vaccinations for citizens who travel abroad on call, for recovery in foreign medical or sanatorium institutions at their own request, as well as on tourist trips (except for those traveling for treatment and on business trips);
j) drawing up, at the request of customers, sanitary passports for radio engineering facilities and conducting research to confirm them;
k) conducting, at the request of customers, state sanitary and hygienic expertise for accreditation and certification of enterprises, institutions, and organizations for the right to conduct toxicological and hygienic, medical and biological, sanitary and hygienic and other research;
m) determination, at the request of the customer, of harmful and dangerous factors of the production environment, technological and labor processes, conducting research to develop means and measures to eliminate or reduce their dangerous effects;
n) training at the request of customers at the workplaces of specialists of enterprises, institutions, organizations in institutions of the sanitary and epidemiological service, state research institutes of a hygienic and epidemiological profile, as well as specialists of enterprises, institutions, organizations conducting sanitary and hygienic and bacteriological research;
o) provision, upon request from customers, of services for organizing the work of departmental sanitary laboratories, equipping them with medical equipment (equipment, apparatus, devices); on-site training of specialists of such laboratories in the methods of conducting sanitary and hygienic research;
197.1.6. provision of rehabilitation services to persons with disabilities, children with disabilities, as well as provision of vouchers for sanatorium and resort treatment, rehabilitation and recreation in the territory of Ukraine to individuals under the age of 18, persons with disabilities, and children with disabilities;
197.1.7. supply of services from:
a) keeping children in preschool educational institutions, boarding schools;
b) detention of persons in rehabilitation institutions;
{Subparagraph "b" of subparagraph 197.1.7 of paragraph 197.1 of Article 197 as amended by Law No. 4505-IX of 18.06.2025 }
c) provision of social services in accordance with the Law of Ukraine "On Social Services" by social service providers included in the Register of Providers and Recipients of Social Services;
{Subparagraph "c" of subparagraph 197.1.7 of paragraph 197.1 of Article 197 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 4505-IX of 06/18/2025 }
d) nutrition of children in preschool, general education and vocational and technical educational institutions and citizens in healthcare institutions . The procedure for providing such services is approved by the Cabinet of Ministers of Ukraine;
{Sub-clause "d" of subparagraph 197.1.7 of clause 197.1 of Article 197 as amended by Law No. 3609-VI of 07.07.2011 }
e) food, provision of property, utilities and other services provided to persons held in penitentiary institutions, namely:
nutrition, including cooking;
provision of clothing, linen, shoes and bedding;
use of long-term dating rooms;
postal and telephone and telegraph services;
supply of food and essential items;
shoe and clothing repair;
additional medical care;
bath and laundry services;
film and video film rental, cultural and educational events;
{Sub-clause "d" of subparagraph 197.1.7 of clause 197.1 of Article 197 was excluded on the basis of Law No. 4505-IX of 18.06.2025 }
197.1.8. provision of passenger transportation services by urban passenger transport (except taxis), the tariffs for which are regulated in accordance with the procedure established by law.
This rule does not apply to transactions involving the provision of passenger transport for rent (hire);
197.1.9. supply by religious organizations of religious services and objects of religious purpose according to the list, namely:
a) religious services: baptism, church marriage, funeral, prayer service, memorial service, consecration (of premises, cars, etc.), circumcision, first communion, bar mitzvah (coming of age);
b) objects of religious purpose: candles, icons (images), crosses (body, funeral, altar, treble, water blessing, priestly, with decorations, etc.), rosaries, veils (altar, funeral, etc.), medallions with religious symbols, incense coals, incense, lamp oil, myrrh, lamps, censers, candlesticks (seven-candlesticks, three-candlesticks Easter, etc.), shrouds, vestments of clergy (cassocks, under-vestments, airs, eagles, stychares, skufias, mitres, kamilavki, etc.), wreaths, certificates, baptismal accessories (baptismal box), gift carriers, gift boxes (reliquaries), fonts, seals for prosphora, sprinkling, copy, styuchtsi, bowls (chalices), saucers, stars, spoons, ladles, discuses, floats, bells, organs, harmoniums, prayers of passage, a "living in help" belt, mezuzahs, thales, tefillin (phylacteries), sculptural images of saints, banners, fans, matzah, prosphora, wafers, liturgical literature;
197.1.10. provision of burial services and supply of ritual goods by state and municipal services, namely:
a) calling a funeral service agent to place an order for the organization and conduct of the funeral;
b) issuing a medical certificate on the cause of death;
c) delivery to the customer of ritual attributes for organizing a funeral;
d) loading, unloading and carrying ritual attributes;
e) transport services provided in the process of organizing a funeral;
e) sale of a standard coffin;
f) sale of a container for transporting a galvanized coffin; sealing of a galvanized coffin;
h) keeping the bodies of the deceased in refrigerated chambers beyond the normal stay (after death in a medical institution, as well as those who died at home or in other places);
g) services for preparing the body of the deceased for burial or cremation (hairdresser and beautician services, washing, embalming, placing in a coffin);
h) digging a grave;
i) moving the coffin with the body of the deceased (to the house, to the apartment in a multi-storey building, to the morgue; from the house, apartment, morgue, etc. to the burial place);
i) musical accompaniment of the funeral ceremony;
j) holding a civil memorial service;
j) services of a funeral organizer;
j) manufacture and installation of a metal gravestone, cross, headstone or temporary memorial sign;
l) sale of standard funeral wreaths and mourning ribbons for them;
m) organizing the shipment of a coffin with the body of the deceased or an urn with the ashes of the deceased abroad;
n) in the case of burial in a grave, services for dismantling the elements of the existing tombstone (monument) and their installation;
o) writing text on a mourning ribbon;
n) cremation;
r) sale of ballot boxes;
c) sale of a cup for an urn;
t) burial of an urn with ashes in a grave, in a columbarium, scattering of ashes;
197.1.11. the exemptions specified in subparagraph 197.1.10 of this paragraph do not apply to operations for the supply of services for the burial and cremation of animal corpses and related activities;
197.1.12. free transfer of rolling stock by one railway or public railway transport enterprise to other railways or public railway transport enterprises of state ownership.
Free transfer of rolling stock between enterprises within the railway is carried out upon the submission of the railway manager based on the decision of Ukrzaliznytsia, and within Ukrzaliznytsia - according to the order of its General Director. Free transfer of rolling stock is formalized by an acceptance and transfer act in accordance with the legislation.
Free transfer is carried out in the following cases:
production needs in connection with a single technological process;
distribution of rolling stock in connection with the restructuring of the industry and the liquidation of individual divisions.
If, on the date of the transaction for the free transfer of rolling stock by one railway or public railway transport enterprise to other railways or public railway transport enterprises of state ownership, no tax liabilities arise. In this case, railways or railway transport enterprises that transfer rolling stock free of charge shall not adjust the amounts of the tax credit;
{Paragraph six of subparagraph 197.1.12 of paragraph 197.1 of Article 197 as amended by Law No. 3609-VI of 07.07.2011 }
197.1.13. free privatization of housing stock, including common areas in apartment buildings and adjacent areas, homestead land plots in accordance with the legislation, as well as the provision of services, the receipt of which, according to the legislation, is a mandatory prerequisite for the privatization of housing, adjacent areas of apartment buildings, and homestead land plots;
free transfer of shares of state property (shares) to employees of state farms and other agricultural enterprises being privatized and persons equated to them in accordance with the Law of Ukraine "On the Features of the Privatization of Property in the Agro-Industrial Complex" . The list of enterprises subject to privatization is determined by the Cabinet of Ministers of Ukraine;
197.1.14. supply of housing (residential real estate), an indivisible residential property under construction/future residential property, except for the first supply of such properties.
In this subparagraph, the first supply of housing (residential real estate) means:
a) the first transfer of finished newly built housing (residential real estate) into the ownership of the buyer or the supply of services (including the cost of materials purchased at the expense of the contractor) for the construction of such housing at the expense of the customer;
b) the first sale of reconstructed or overhauled housing (residential real estate object) to a buyer who is a person other than the owner of such object at the time of its decommissioning (use) in connection with such reconstruction or overhaul, or the supply of services (including the cost of materials purchased at the expense of the contractor) for such reconstruction or overhaul at the expense of the customer.
In this subparagraph, the first delivery of an indivisible residential object under construction/future residential real estate object means the first transfer of a special property right to the relevant object to the buyer under a contract of sale of an indivisible residential object under construction/future residential real estate object (first sale) from the construction customer/construction developer, under which the special property right to the relevant object is registered.
The provisions of this subparagraph also apply to the first sale of summer or garden houses, as well as any other property registered in accordance with the law as housing (residential real estate).
Transactions for the first supply of affordable housing and housing built with public funds are exempt from taxation.
{Sub -clause 197.1.14 of clause 197.1 of Article 197 as amended by Law No. 4220-VI of 22.12.2011 ; as amended by the Law No. 2600-IX dated 20.09.2022 }
197.1.15. provision of charitable assistance, in particular free supply of goods/services to charitable organizations established and registered in accordance with the legislation, as well as provision of such assistance by charitable organizations to recipients (entities) of charitable assistance in accordance with the legislation on charitable activities and charitable organizations.
{Paragraph one of subparagraph 197.1.15 of paragraph 197.1 of Article 197 as amended by Law No. 5073-VI of 05.07.2012 }
Free supply should be understood as the supply of goods/services to charitable organizations and recipients of charitable assistance without any monetary, material or other types of compensation. In case of non-compliance with the conditions specified in this subparagraph, such transactions are taxed on a general basis.
to goods received as charitable assistance from domestic benefactors for the purposes specified in Article 3 of the Law of Ukraine "On Charitable Activities and Charitable Organizations".
{Paragraph three of subparagraph 197.1.15 of paragraph 197.1 of Article 197 as amended by Law No. 5073-VI of 05.07.2012 }
Marking is carried out by applying the inscription "Charity. Sale prohibited" on the label, tag or directly on the outer or inner packaging of the product. When marking charitable goods, the symbols of the charitable organization and the benefactor may be used.
Goods are labeled in such a way that the inscription is fully and clearly visible when inspecting the packaging or the goods themselves.
Charitable aid goods are labeled by the benefactors who provide such aid.
Monitoring of compliance with labeling rules is carried out by local executive authorities and regulatory authorities.
Charitable assistance may be provided in the form of goods, works, and services intended for use by legal entities - its purchasers - for the purpose of carrying out activities for the purposes stipulated in Article 3 of the Law of Ukraine "On Charitable Activities and Charitable Organizations".
{Paragraph eight of subparagraph 197.1.15 of paragraph 197.1 of Article 197 as amended by Law No. 5073-VI of 05.07.2012 }
After receiving a proposal from the benefactor to provide charitable assistance in the form of goods, its types, sizes, etc., the legal entity - the recipient of charitable assistance:
determines, taking into account the recommendations of the relevant executive authorities and local self-government bodies, the circle of persons to whom it will be provided;
informs the benefactor of his intention to accept the proposed charitable assistance.
Legal entities - recipients of charitable assistance keep accounting and operational records of the receipt, storage, distribution and use of charitable assistance in the form of goods, works, services, as well as reporting in the form established by the central executive body that ensures the formation of state policy in the field of statistics, which is sent to regulatory authorities.
{Paragraph twelve of subparagraph 197.1.15 of paragraph 197.1 of Article 197 as amended by Law No. 5083-VI of 05.07.2012 }
For accounting of transactions related to charitable assistance, legal entities - recipients of charitable assistance use the chart of accounts and instructions in force in Ukraine.
Legal entities - recipients of charitable assistance independently determine the procedure for analytical accounting of transactions related to charitable assistance and open appropriate accounts.
Legal entities that receive charitable assistance shall reflect in their annual financial statements:
in the balance sheet - separately funds (goods, works, services) received as charitable assistance;
in the income statement - separately the value of the charitable assistance received.
The appendix (comments) to the annual report provides the necessary explanations regarding the specified indicators of activities related to charitable assistance.
Control over the receipt, storage, and distribution of charitable assistance in the form of goods, works, and services is exercised by local executive authorities, and over their intended use - by local executive authorities and regulatory authorities.
Labeled goods received for the purpose of providing charitable assistance, which are supplied for money or other types of compensation, and/or the proceeds received for such supply, are subject to seizure from the unscrupulous seller and are confiscated to the state revenue in accordance with the established procedure.
Section VI of this Code, securities (except for endowments provided specified in Section IV of this Code), intangible assets and goods/services intended for use in economic activities are not subject to tax exemption;↑
197.1.16. free transfer to state ownership or communal ownership of territorial communities of villages, towns, cities or to their joint ownership of objects of all forms of ownership that are on the balance sheet of one taxpayer and are transferred to the balance sheet of another taxpayer, if such operations are carried out by decision of the Cabinet of Ministers of Ukraine, central and local executive authorities, local self-government bodies, adopted within the limits of their powers.
The norms of this subparagraph also apply to transactions for the free transfer of objects from the balance sheet of a legal entity of any form of ownership to the balance sheet of another legal entity that is in state or municipal ownership, carried out by decision of a state authority of Ukraine or a local self-government body adopted within the limits of their powers and by decision of legal entities, in the case of the transfer of fixed assets of railway transport infrastructure, regardless of whether the subjects of the transaction are taxpayers;
{Paragraph two of subparagraph 197.1.16 of paragraph 197.1 of Article 197 as amended by Law No. 3609-VI of 07.07.2011 }
197.1.17. free supply of goods/services of own production by subsidiary farms and medical and production workshops (workshops, sites) of boarding houses, territorial social service centers (provision of social services), reintegration centers for homeless people, social adaptation centers for persons released from places of deprivation of liberty, specialized hospitals, special-type medical and preventive institutions and dispensaries, provided that such transfer is carried out to meet the own needs of the specified institutions;
{Subclause 197.1.17 of Clause 197.1 of Article 197 as amended by Law No. 4834-VI of 24.05.2012 }
197.1.18. provision of state paid services to individuals or legal entities by executive authorities and local self-government bodies, as well as other persons authorized by such authorities or by law to provide the specified services, the obligation to receive (provide) which is established by law, including fees for registration, issuance of licenses, certificates in the form of fees, state duty, etc.;
197.1.19. provision of services for registration of civil status acts by state bodies authorized to carry out such registration in accordance with the legislation;
{Subparagraph 197.1.19 of paragraph 197.1 of Article 197 as amended by Law No. 4834-VI of 24.05.2012 }
197.1.20. provision by libraries that are state-owned or municipally-owned or owned by all-Ukrainian public associations of persons with disabilities of paid services for completing registration and accounting documents (tickets, forms), using rare, valuable reference books, books (including night subscriptions), thematic selection of literature at the request of the consumer and providing thematic, address-bibliographic and factual references;
197.1.21. supply (sale, transfer) of land plots, land shares (shares), except for those located under real estate objects and included in their value in accordance with the legislation (taking into account the provisions of the first paragraph of subparagraph 197.1.13 of paragraph 197.1 of Article 197 of this Code);
provision of services for the lease (sublease) of land plots owned by the state or a territorial community, if the funds for such services are paid in full directly to the relevant accounts of the bodies that carry out treasury servicing of budget funds;
{Paragraph two of subparagraph 197.1.21 of paragraph 197.1 of Article 197 as amended by the Law No. 2628-VIII dated 23.11.2018 }
197.1.22. provision of services for fundamental research, scientific research and development works, if such services and/or works are provided by a person who directly receives payment for their cost from the account of the body that carries out treasury services of budget funds;
{Subparagraph 197.1.22 of paragraph 197.1 of Article 197 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by the Law No. 466-IX dated 16.01.2020 }
197.1.23. free transfer of devices, equipment, materials, except for excisable ones, to scientific institutions and scientific organizations, higher educational institutions included in the State Register of Scientific Institutions, which are provided with state support;
{Sub-clause 197.1.22 of clause 197.1 of Article 197 as amended by the Law No. 466-IX dated 16.01.2020 }
197.1.24. supply in rural areas by agricultural producers of services for the repair of schools, preschool institutions, boarding schools, healthcare institutions and provision of material assistance (within the limits of one non-taxable minimum income of citizens per month per person) with food products of their own production and services for land cultivation to large families, labor and war veterans, rehabilitated citizens, persons with disabilities, single elderly persons, persons affected by the Chernobyl disaster, and to schools, preschool institutions, boarding schools, healthcare institutions;
197.1.25. supply (subscription) and delivery of periodicals of printed media (except erotic publications) of domestic production, preparation (literary, scientific and technical editing, correction, design and layout), production (printing on paper or recording on an electronic medium), distribution of books, including electronic content (except erotic publications) and children's book publications, domestic production, student notebooks, textbooks and teaching aids, Ukrainian-foreign or foreign-Ukrainian language dictionaries of domestic production on the customs territory of Ukraine;
{Subclause 197.1.25 of Clause 197.1 of Article 197 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 206-VIII of 13.02.2015 , No. 2245-VIII of 07.12.2017 }
197.1.25 - 1. supply, preparation (literary, scientific and technical editing, proofreading, etc.), production, distribution of audiobooks dubbed in Ukrainian, except for publications of an erotic nature.
The norms of this sub-item also apply to electronic services for the supply of electronic copies (electronic digital information) and/or providing access to audiobooks voiced in Ukrainian, except for publications of an erotic nature.
{Clause 197.1 of Article 197 is supplemented by subparagraph 197.1.25 - 1 in accordance with Law No. 2273-IX of 05/22/2022 }
{Sub-clause 197.1.26 of clause 197.1 of Article 197 is excluded on the basis of the Law No. 466-IX dated 16.01.2020 }
{Subparagraph 197.1.27 of paragraph 197.1 of Article 197 was excluded on the basis of Law No. 1166-VII of March 27, 2014 }
197.1.28. supply of goods/services in the amount of compensation to cover the difference between actual costs and regulated prices (tariffs) in the form of a production subsidy from the budget;
197.1.29. free transfer to the state or municipal property of the relevant territorial communities of tram cars (commodity subcategory according to UKT FEA 8603 10 00 10), trolleybuses (commodity subcategory according to UKT FEA 8702 40 00 10), buses (commodity position according to UKT FEA 8702) for the transportation of citizens on routes (lines) in accordance with the requirements of the life support of settlements. In case of improper use of the specified goods, the taxpayer is obliged to increase tax liabilities for the consequences of the tax period to which such a violation falls, by the amount of value added tax that should have been paid at the time of import (supply) of such goods, and also to pay a penalty in accordance with the law;
{Clause 197.1 of Article 197 is supplemented by subparagraph 197.1.29 in accordance with Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 1914-IX of 11/30/2021 }
197.1.30. free transfer of property by the State Concern "Ukroboronprom" and state enterprises, including state-owned ones, included in its composition, if such transfer is carried out to enterprises, institutions or organizations for the purpose of demonstrating military or dual-use goods (with the subsequent return of this property), conducting joint or independent tests of military products (with or without the subsequent return of this property), supporting scientific research and development activities of state enterprises, institutions and organizations (with or without the subsequent return of this property), ensuring the activities of representative offices of the State Concern "Ukroboronprom" and enterprises of the defense-industrial complex included in its composition (with or without the subsequent return of this property);
{Clause 197.1 of Article 197 is supplemented by subparagraph 197.1.30 in accordance with Law No. 5414-VI of 02.10.2012 }
197.1.31. creation, supply, promotion, restoration and distribution of a national cultural product in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
{Clause 197.1 of Article 197 is supplemented by subparagraph 197.1.31 in accordance with Law No. 5412-VI of 02.10.2012 }
197.1.32. provision of educational services through access to public educational, scientific and information resources on the Internet in areas of knowledge and specialties in which higher education applicants are trained, the conduct and provision of which does not require human participation, including by providing access to virtual classrooms, educational resources in which students (students) complete tasks online, and grades are given automatically, without human participation;
{ Clause 197.1 of Article 197 is supplemented by subclause 197.1.32 in accordance with the Law No. 1525-IX dated 03.06.2021 }
197.1.33. provision by residents of Diya City through access to public educational, scientific and information resources on the Internet, including by providing access to virtual classrooms, educational resources, educational services in the field of information technologies, including services for providing higher, professional pre-higher and vocational education in such specialties as computer science, information systems and technologies, computer engineering, cybersecurity, data science, as well as services for providing other types of education, namely: computer literacy training (digital literacy), which includes services for training in digital literacy, development, modification, testing and technical support of software, including computer games, business analysis training (for the purposes of developing, modifying, testing and technical support of software), building graphical interfaces, organizing quality control processes, system administration, project management, documentation development (for the purposes of developing, modifying, testing and software technical support).
{ Clause 197.1 of Article 197 is supplemented by subparagraph 197.1.33 in accordance with Law No. 2330-IX of 21.06.2022 }
197.2. Transactions for the supply and import into the customs territory of Ukraine of goods/services intended for the own needs of diplomatic missions, consular offices of foreign states and representative offices of international organizations in Ukraine, as well as for use by persons from among the diplomatic staff of these diplomatic missions and members of their families living with such persons, are exempt from taxation. The procedure for exemption from taxation and the list of transactions subject to exemption from taxation are established by the Cabinet of Ministers of Ukraine based on the principle of reciprocity in relation to each individual state and/or the rules of international treaties of Ukraine, the consent to be bound by which has been provided in accordance with the procedure established by law.
{Paragraph one of clause 197.2 of Article 197 as amended by the Law No. 466-IX dated 16.01.2020 }
In the event of further supply (sale) on the customs territory of Ukraine of vehicles imported with exemption from taxation in accordance with the provisions of this subparagraph, the tax shall be paid by the person specified in the third paragraph of subparagraph 3 of clause 180.1 of Article 180 of this Code no later than the day of such supply.
In accordance with the procedure established by paragraph one of this paragraph, transactions for the supply of goods/services on the customs territory of Ukraine intended for the provision of humanitarian aid in Ukraine by diplomatic missions, consular offices of foreign states and representative offices of international organizations in Ukraine in accordance with the provisions of the Law of Ukraine "On Humanitarian Aid" are also exempt from taxation with value added tax.
{Paragraph 197.2 of Article 197 is supplemented by a third paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
197.3. Operations on the import into the customs territory of Ukraine of marine fishery products (fish, mammals, shells, crustaceans, aquatic plants, etc. in chilled, salted, frozen, canned form, processed into flour or other products), extracted (caught, produced) by vessels registered in the State Ship Register of Ukraine or the Ship Book of Ukraine , are exempt from taxation. Operations on the subsequent supply of the specified goods by legal entities - shipowners or charterers are taxed in accordance with the general procedure established by this Code.
197.4. Exemption from taxation of goods, provided for in paragraph 197.1 of this Article, applies to operations of import into the customs territory of Ukraine.
197.5. The exemption from taxation provided for in paragraph 197.1 of this Article shall not apply to transactions with excisable goods specified in Section VI of this Code.
197.6. Transactions for the supply of goods (except for excisable goods) and services (except for services provided during lotteries and entertainment games and services for the supply of goods received under commission (consignment) agreements, suretyship, mandate, trust management, other civil law agreements authorizing such a taxpayer to supply goods on behalf of and on behalf of another person without transferring ownership of such goods) that are directly produced by enterprises and organizations founded by public associations of persons with disabilities, where the number of persons with disabilities who have their main place of work in such organizations during the previous reporting period is not less than 50 percent of the average number of full-time employees, and provided that the payroll of such persons with disabilities during the reporting period is not less than 25 percent of the total amount of labor costs that are included in the costs according to the rules for taxation by corporate income tax.
{Paragraph one of clause 197.6 of Article 197 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 }
Direct production is considered to be the production of goods/services, as a result of which the amount of costs for processing (processing, other types of transformation) of raw materials, components, components, other purchased goods/services used in the production of such goods/services is at least 8 percent of the supply price of such manufactured goods/services.
The specified enterprises and organizations of public associations of persons with disabilities have the right to apply the specified benefit upon registration with the relevant regulatory body, which is carried out on the basis of the relevant application of the taxpayer about the desire to receive such a benefit and the decision of the authorized body in accordance with the Law of Ukraine "On the Fundamentals of Social Protection of Persons with Disabilities in Ukraine".
{Paragraph three of clause 197.6 of Article 197 as amended by Laws No. 5083-VI of 05.07.2012 , No. 344-IX of 05.12.2019 }
In the event of a taxpayer violating the requirements of this subparagraph, the regulatory authority shall cancel his registration as a person entitled to a tax benefit, and the tax liabilities of such taxpayer shall be recalculated from the tax period in which such violations were detected, in accordance with the general taxation rules established by this Code, and with the simultaneous application of appropriate financial sanctions.
Tax reporting of such enterprises and organizations is submitted in accordance with the procedure established by law.
197.7. The following transactions are exempt from taxation: import into the customs territory of Ukraine of cultural values manufactured 50 or more years ago, classified by codes according to the Ukrainian Classification of Foreign Economic Activities : 9701 21 00 00; 9701 91 00 00; 9701 29 00 00; 9701 22 00 00; 9701 92 00 00; 9701 99 00 00; 9702 10 00 00; 9702 90 00 00; 9703 10 00 00; 9703 90 00 00; 9704 00 00 00; 9705 10 00 00; 9705 21 00 00; 9705 22 00 00; 9705 29 00 00; 9705 31 00 00; 9705 39 00 00; 9706 10 00 00; 9706 90 00 00.
{Clause 197.7 of Article 197 as amended by Law No. 3553-IX of 16.01.2024 }
197.8. Transactions for the supply of services for the transportation (movement) of passengers and cargo in transit through the customs territory of Ukraine, as well as the supply of services related to such transportation (movement), are exempt from taxation.
The exemption from taxation provided for in the first paragraph of this paragraph does not apply to transactions for the supply of services performed (provided) to ensure the movement (transportation) of natural gas through cross-border gas pipelines (transportation of natural gas through the territory of Ukraine under the customs transit regime).
{Paragraph 197.8 of Article 197 is supplemented by the second paragraph in accordance with Law No. 909-VIII of 24.12.2015 }
{Clause 197.9 of Article 197 was excluded on the basis of Law No. 3387-VI of 19.05.2011 }
197.9. Transactions for the supply of services provided to foreign and domestic vessels that carry out international transportation of passengers, their baggage and cargo and are paid by them in accordance with the legislation of Ukraine in the form of port dues are exempt from taxation.
{Article 197 includes paragraph 197.9 in accordance with Law No. 3609-VI of 07.07.2011 - applies from the first day of the reporting (tax) month in which Law No. 3609-VI of 07.07.2011 enters into force }
197.10. Transactions for the supply of air navigation services to aircraft performing domestic, international and transit flights in the flight information areas of the zone of responsibility of Ukraine are exempt from taxation. The procedure for documenting, preparing tax invoices and reflecting these transactions in tax reporting is determined by the Cabinet of Ministers of Ukraine.
{Clause 197.10 of Article 197 as amended by Law No. 1797-VIII of 21.12.2016 }
197.11. The following transactions are exempt from taxation:
supply of goods and services in the customs territory of Ukraine and import into the customs territory of Ukraine of goods as international technical assistance, which is provided in accordance with international treaties of Ukraine, the consent to which is binding has been provided in accordance with the procedure established by law;
supply of goods and services in the customs territory of Ukraine and import into the customs territory of Ukraine of goods financed by international technical assistance provided in accordance with international treaties of Ukraine, the consent to which is binding has been provided in accordance with the procedure established by law;
importation into the customs territory of Ukraine of property as humanitarian aid provided in accordance with the provisions of the Law of Ukraine "On Humanitarian Aid".
{Clause 197.11 of Article 197 as amended by Law No. 909-VIII of 12/24/2015 }
197.12. Transactions of banks and other financial institutions on the supply (sale, alienation in another way) of property transferred by individuals, as well as business entities - private entrepreneurs and other persons who are not tax payers, as collateral, including mortgages, and on which foreclosure has been filed, are exempt from taxation.
Transactions of banks and other financial institutions for the supply of property acquired by them as a result of foreclosure on such property are exempt from taxation. The exemption applies to that part of the value of the property at which it was acquired as a result of repayment of obligations under a credit agreement (loan).
{Paragraph 197.12 of Article 197 is supplemented by the second paragraph in accordance with Law No. 909-VIII of 24.12.2015 }
197.13. Bank transactions for the sale (transfer) or purchase of deposit liabilities are exempt from taxation.
{Clause 197.14 of Article 197 was excluded on the basis of Law No. 713-VII of 19.12.2013 }
197.15. Transactions for the supply of construction and installation works for the construction of affordable housing and housing built with state funds are exempt from taxation.
197.16. The following transactions for import into the customs territory of Ukraine are exempt from taxation:
197.16.1. equipment that operates on renewable energy sources, energy-saving equipment and materials, means of measuring, controlling and managing the consumption of fuel and energy resources, equipment and materials for the production of alternative fuels or for the production of energy from renewable energy sources;
197.16.2. materials, equipment, components used for production:
197.16.2.1. equipment that operates on renewable energy sources;
197.16.2.2. materials, raw materials, equipment and components that will be used in the production of alternative fuels or the production of energy from renewable energy sources;
197.16.2.3. energy-saving equipment and materials, products, the operation of which ensures economy and rational use of fuel and energy resources;
197.16.2.4. means of measuring, controlling and managing the consumption of fuel and energy resources.
Operations involving the import into the customs territory of Ukraine of the goods specified in this paragraph are exempt from taxation if these goods are used by the taxpayer for his own production and if identical goods with similar quality indicators are not produced in Ukraine.
The list of such goods, indicating the UKT FEA codes, is established by the Cabinet of Ministers of Ukraine.
In case of violation of the requirements for the intended use of such goods, the taxpayer is obliged to increase the tax liability based on the results of the tax period to which such violation applies by the amount of value added tax that should have been paid from the specified transactions at the time of import of such goods, and also to pay a penalty accrued on such tax amount, based on 120 percent of the discount rate of the National Bank of Ukraine, which was in effect on the day of payment of the tax liability, and for the period from the day of import of such goods to the day of increase in the tax liability.
197.17. For the period of military exercises on the territory of Ukraine, which are held within the framework of the "Partnership for Peace" program , transactions for the supply of fuels and lubricants on the customs territory of Ukraine, purchased by non-residents for transfer to participants in joint military exercises with units of the Armed Forces of Ukraine, are exempt from taxation.
The procedure , list of enterprises and volumes of supply of fuels and lubricants are established by the Cabinet of Ministers of Ukraine.
197.18. Operations on the import into the customs territory of Ukraine of purebred breeding animals, breeding (genetic) resources under the codes according to the UKT ZEA 0101 21 00 00, 0102 21 10 00, 0102 21 30 00, 0103 10 00 00, 0104 10 10 00, 0511 10 00 00, 0511 99 85 10, carried out by agricultural producers, are exempt from taxation. Operations on the subsequent supply of the specified purebred breeding animals or breeding (genetic) resources are taxed in the general procedure established by this Code.
{Article 197 is supplemented by paragraph 197.18 in accordance with Law No. 4014-VI of 04.11.2011 ; as amended in accordance with the Laws No. 466-IX dated 16.01.2020 , No. 1914-IX dated 30.11.2021 }
197.19. The following transactions for supplies to the National Bank of Ukraine are exempt from taxation:
precious metals, including their import into the customs territory of Ukraine;
services related to the production and use of precious metals for the purpose of replenishing gold and foreign exchange reserves and manufacturing banking metals.
{Paragraph three of paragraph 197.19 of Article 197 as amended by Law No. 1914-IX of 30.11.2021 }
{Article 197 was supplemented by paragraph 197.19 in accordance with Law No. 4238-VI of 22.12.2011 }
197.20. Transactions involving the import into the customs territory of Ukraine by individuals of goods specified in Part Ten of Article 374 of the Customs Code of Ukraine are exempt from taxation .
{Article 197 was supplemented by paragraph 197.20 in accordance with Law No. 4915-VI of 07.06.2012 }
{ Paragraph 197.21 of Article 197 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Clause 197.22 of Article 197 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
197.23. The operations of import into the customs territory of Ukraine under the customs regime of import of goods specified in Part Eight of Article 287 of the Customs Code of Ukraine, and the first supply of these goods in the customs territory of Ukraine for their use in the production of defense goods specified in accordance with the law, and if the customer of such goods is a state customer in the field of defense specified by the Cabinet of Ministers of Ukraine, are exempt from taxation.
{Paragraph one of clause 197.23 of Article 197 as amended by Law No. 2120-IX of March 15, 2022 }
The operations of import into the customs territory of Ukraine under the customs regime of import of goods specified in Part Eight of Article 287 of the Customs Code of Ukraine, imported by taxpayers for use in their own production activities for the production of weapons, military and special equipment (in particular, unmanned systems, electronic warfare and reconnaissance means, active means of countering technical intelligence, multi-channel opto-electronic systems, opto-electronic devices), weapons and ammunition (hereinafter referred to as defense goods) are exempt from taxation, provided that the final recipient of such defense goods, in accordance with the end-user certificate or in accordance with the terms of the contract, is determined to be law enforcement agencies, the Ministry of Defense of Ukraine, the Armed Forces of Ukraine and other military formations, voluntary formations of territorial communities formed in accordance with the laws of Ukraine, other entities that combat terrorism in accordance with the law and/or participate in the implementation of measures to ensure national security and defense, counter and deterrence of armed aggression of the Russian Federation against Ukraine, and if such defense goods are received without prior or subsequent reimbursement of their cost by the final recipient.
{Paragraph 197.23 of Article 197 is supplemented with a new paragraph in accordance with Law No. 4967-IX of 03.09.2026 }
In the event of misuse of goods specified in Part Eight of Article 287 of the Customs Code of Ukraine, the taxpayer shall increase the tax liabilities based on the results of the tax period to which the violation applies by the amount of tax that should have been paid at the time of import of such goods or accrued for transactions on the supply of such goods, pay the penalty accrued in accordance with this Code, and bear the financial, administrative and criminal liability established by this Code and the legislation of Ukraine.
The procedure for the import, supply and intended use of goods specified in Part Eight of Article 287 of the Customs Code of Ukraine, imported into the customs territory of Ukraine under the customs import regime and supplied on the customs territory of Ukraine, is determined by the Cabinet of Ministers of Ukraine.
The exemption from taxation established by this paragraph does not apply to operations for import into the customs territory of Ukraine under the customs import regime and for the supply to the customs territory of Ukraine of goods originating from a country recognized as an occupying state in accordance with the law of Ukraine and/or recognized as an aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of such an occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law of Ukraine.
{Article 197 was supplemented by paragraph 197.23 in accordance with Law No. 366-VIII of 23.04.2015 }
197.24. The operations of a telecommunications operator providing telecommunications services in the part of carrying out charitable telecommunications messages for charitable purposes are exempt from taxation.
{Article 197 was supplemented by paragraph 197.24 in accordance with Law No. 1665-VIII of 06.10.2016 }
197.25. Transactions for the import into the customs territory of Ukraine under the customs regime of import of goods that are part of the national cinematographic heritage are exempt from taxation.
{Article 197 is supplemented by paragraph 197.25 in accordance with Law No. 962-IX of 04.11.2020 }
197.26. The following transactions of taxpayers are exempt from taxation:
a) supply to the customs territory of Ukraine and/or import into the customs territory of Ukraine of investment gold, including investment gold in the form of certificates of distributed or undistributed gold, or gold traded on gold accounts, in particular, gold loans and swaps that provide for ownership or a right of claim in respect of investment gold, as well as transactions with investment gold that provide for futures and forward agreements that result in the transfer of ownership or a right of claim in respect of investment gold;
b) the supply of services by agents acting on behalf of and on behalf of another person in cases where they are involved in the supply of investment gold to their principal/principal;
c) supply of services related to the production of investment gold and/or services for the conversion of gold into investment gold.
{Article 197 is supplemented by paragraph 197.26 in accordance with Law No. 1914-IX of 30.11.2021 }
197.27. Transactions for the supply within the customs territory of Ukraine of tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes for which maximum retail prices are established are exempt from taxation, except for transactions:
a) from the first supply of such goods by their manufacturers;
b) from the first supply of such goods by economic entities that are connected by control relations with producers within the meaning of the Law of Ukraine "On Protection of Economic Competition". The list of economic entities connected by control relations with producers is approved by the Cabinet of Ministers of Ukraine upon submission of the central executive body that ensures the formation and implementation of the state policy of economic, social development and trade;
c) from the import of such goods into the customs territory of Ukraine and their first supply by the importer in the customs territory of Ukraine.
{Article 197 is supplemented by paragraph 197.27 in accordance with Law No. 1914-IX of 11/30/2021 }
197.28. Transactions for the import into the customs territory of Ukraine under the customs regime of import of goods specified in paragraph 21 of part one of Article 282 of the Customs Code of Ukraine, imported by state scientific institutions, state institutions of higher education to ensure their own educational, scientific and scientific and technical activities, are exempt from taxation.
The volumes, procedure for import and intended use of such goods are determined by the Cabinet of Ministers of Ukraine.
In case of violation of the requirements for the intended use of goods specified in paragraph 21 of part one of Article 282 of the Customs Code of Ukraine, the taxpayer shall increase the tax liabilities based on the results of the tax period to which the violation applies by the amount of tax that should have been paid at the time of import of such goods, pay the penalty accrued in accordance with this Code, and bear the financial, administrative and other liability established by this Code and the legislation of Ukraine.
The exemption from taxation established by this paragraph does not apply to operations for the import into the customs territory of Ukraine under the customs regime of import of goods originating from a country recognized as an occupying state in accordance with the law of Ukraine and/or recognized as an aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of such an occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law of Ukraine.
{Article 197 is supplemented by paragraph 197.28 in accordance with Law No. 2082-IX of February 17, 2022 }
197.28 - 1. The following transactions for the import into the customs territory of Ukraine under the customs regime of import of new equipment (equipment) and components for it, defined by part six of Article 287 of the Customs Code of Ukraine, imported by participants of industrial parks included in the Register of Industrial Parks, exclusively for their own use for the purpose of carrying out their activities in the processing industry (section 10, class 11.07 of section 11, sections 13-17, 20-33 of the KVED 009:2010 , except for class 24.10 of section 24 of the KVED 009:2010 and except for the production of excisable goods, with the exception of the production of passenger cars, their bodies, trailers and semi-trailers, motorcycles, vehicles intended for the transportation of 10 or more people, vehicles for the transportation of goods) are exempt from taxation by value added tax; in the field of waste collection, processing and disposal; recovery of materials (section 38 of the KVED 009:2010), except for waste disposal, or scientific and research activities (section 72 of the KVED 009:2010) on the territory (within) of the industrial park (without the right to rent, lease or transfer for use to third parties on any other terms), provided that no more than three years have passed from the date of manufacture of the equipment (equipment) and its components to the date of their import into the customs territory of Ukraine and they have not been in use.
The procedure for the import and intended use of goods specified in the first paragraph of this paragraph shall be established by the Cabinet of Ministers of Ukraine.
Alienation of equipment (equipment) and its components imported into the customs territory of Ukraine in accordance with the procedure specified in this paragraph, earlier than five years from the date of their import into the customs territory of Ukraine or in the event of their misuse, including transfer for use to other persons, earlier than five years from the date of their import into the customs territory of Ukraine or loss of the status of a participant in an industrial park shall entail the emergence of an obligation for the taxpayer to pay tax liabilities based on the results of the tax period to which such alienation, misuse or loss of the status of a participant in an industrial park falls, for the amount of value added tax that should have been paid upon import into the customs territory of Ukraine of such goods, as well as obligations to pay a penalty in accordance with this Code, calculated from the date of import into the customs territory of Ukraine until the date of increase in the tax liability. In this case, the limitation periods established by Article 102 of this Code shall not apply.
The provisions of this paragraph do not apply to equipment (equipment) and components for it originating from a country recognized by the occupying state in accordance with the law and/or by the aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of the occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law.
{Article 197 is supplemented by paragraph 197.28 - 1 in accordance with Law No. 2330-IX of 06/21/2022 - regarding the entry into force, see paragraph 1 of Section II of Law No. 2330-IX of 06/21/2022 }
198.1. Tax credit includes tax amounts paid/accrued in the event of transactions with:
{Paragraph one of clause 198.1 of Article 198 as amended by Law No. 643-VIII of 16.07.2015 }
a) purchase or production of goods and services;
{Paragraph two of clause 198.1 of Article 198 as amended by Law No. 1797-VIII of 21.12.2016 }
b) acquisition (construction, erection, creation) of non-current assets (including in connection with the acquisition and/or import of such assets as a contribution to the authorized capital and/or upon transfer of such assets to the balance sheet of the taxpayer authorized to keep records of the results of joint activities);
{Paragraph three of clause 198.1 of Article 198 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 3553-IX of 01/16/2024 }
c) receipt of services provided by a non-resident in the customs territory of Ukraine, and in the case of receipt of services, the place of supply of which is the customs territory of Ukraine;
d) import of non-current assets into the customs territory of Ukraine under operating or financial leasing agreements;
e) import of goods and/or non-current assets into the customs territory of Ukraine.
{Clause 198.1 of Article 198 was supplemented by the sixth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
198.2. The date of assignment of tax amounts to a tax credit is considered to be the date of the event that occurred earlier:
{Paragraphs one and two of clause 198.2 of Article 198 were replaced by one paragraph in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 643-VIII of 16.07.2015 }
the date of debiting funds from the taxpayer's account with a bank/non-bank payment service provider to pay for goods/services, and in the case of the supply of goods/services paid for with electronic money, the date of debiting the taxpayer's electronic money as payment for the goods/services to be supplied to the supplier's electronic wallet;
{Paragraph two of clause 198.2 of Article 198 as amended by Law No. 2888-IX of 12.01.2023 }
date of receipt of goods/services by the taxpayer.
{Paragraph three of clause 198.2 of Article 198 as amended by Law No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 71-VIII of 28.12.2014 }
For transactions involving the import of goods into the customs territory of Ukraine, the date of assignment of tax amounts to the tax credit is the date of payment of tax on tax liabilities in accordance with Clause 187.8 of Article 187 of this Code, and for transactions involving the supply of services by a non-resident in the customs territory of Ukraine, the date of preparation by the payer of a tax invoice for such transactions, provided that such a tax invoice is registered in the Unified Register of Tax Invoices.
{Paragraph four of clause 198.2 of Article 198 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 4834-VI of 24.05.2012 , No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; with amendments made in accordance with Laws No. 71-VIII of 28.12.2014 , No. 643-VIII of 16.07.2015 }
The date of increase in the lessee's (lessee's) tax credit for financial leasing (financial lease) transactions is the date of actual receipt of the financial leasing (financial lease) object by such lessee (lessee).
{Paragraph five of clause 198.2 of Article 198 as amended by Laws No. 643-VIII of 07/16/2015 , No. 1605-IX of 07/01/2021 }
The date of allocation of amounts to the customer's tax credit from agreements (contracts) determined to be long-term in accordance with Clause 187.9 of Article 187 of this Code is the date of actual receipt by the customer of the results of work (executed by acts of work performed) under such agreements (contracts).
{Paragraph six of clause 198.2 of Article 198 as amended by Law No. 643-VIII of 16.07.2015 }
For goods/services, the supply (purchase) of which is controlled by metering devices, the fact of supply (purchase) of such goods/services is certified by metering data.
198.3. The tax credit for the reporting period is determined based on the contractual (contractual) value of goods/services and consists of the amounts of taxes accrued (paid) by the taxpayer at the rate established by paragraph 193.1 of Article 193 of this Code during such reporting period in connection with:
the purchase or manufacture of goods and the provision of services;
acquisition (construction, erection) of fixed assets, including other non-current tangible assets and unfinished capital investments in non-current capital assets;
{Paragraph three of clause 198.3 of Article 198 as amended by Law No. 3553-IX of 16.01.2024 }
import of goods and/or non-current assets into the customs territory of Ukraine.
The tax credit is calculated regardless of whether such goods/services and fixed assets began to be used in taxable transactions within the taxpayer's business activities during the reporting tax period, as well as whether the taxpayer carried out taxable transactions during such reporting tax period.
{Paragraph five of clause 198.3 of Article 198 as amended by Law No. 3553-IX of 16.01.2024 }
{Clause 198.3 of Article 198 as amended by Laws No. 408-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 , No. 609-VIII of 15.07.2015 , No. 643-VIII of 16.07.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
{Paragraph 198.4 of Article 198 is excluded on the basis of the Law No. 71-VIII dated 28.12.2014 }
198.5. The taxpayer is obliged to calculate tax liabilities based on the tax base determined in accordance with clause 189.1 of Article 189 of this Code, and to draw up no later than the last day of the reporting (tax) period and register in the Unified Register of Tax Invoices within the terms established by this Code for such registration, a consolidated tax invoice for goods/services, non-current assets purchased/manufactured with value added tax (for goods/services, non-current assets purchased or manufactured before July 1, 2015, - if during such purchase or manufacture the tax amounts were included in the tax credit), if such goods/services, non-current assets are intended for their use or begin to be used:
{Paragraph one of clause 198.5 of Article 198 as amended by Law No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; with amendments made in accordance with Law No. 71-VIII of 28.12.2014 ; with amendments made in accordance with Law No. 643-VIII of 16.07.2015 }
a) in transactions that are not subject to taxation in accordance with Article 196 of this Code (except for transactions provided for in subparagraph 196.1.7 of paragraph 196.1 of Article 196 of this Code) or the place of supply of which is located outside the customs territory of Ukraine;
{Subparagraph "a" of paragraph 198.5 of Article 198 as amended by Laws No. 657-VII of 10/24/2013 , No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 }
b) in transactions exempt from taxation in accordance with Article 197, Subsection 2 of Section XX of this Code, international treaties (agreements) (except for transactions provided for in Subsection 197.1.28 of Clause 197.1 of Article 197 of this Code and transactions provided for in Clause 197.11 of Article 197 of this Code);
{Subparagraph "b" of paragraph 198.5 of Article 198 as amended by Laws No. 657-VII of 10/24/2013 , No. 909-VIII of 12/24/2015 }
c) in transactions carried out by the taxpayer within the taxpayer's balance sheet, including transfer for non-productive use, transfer of production non-current assets to non-production non-current assets;
d) in transactions that are not economic activities of the taxpayer (except for cases provided for in paragraph 189.9 of Article 189 of this Code).
{Paragraph five of clause 198.5 of Article 198 as amended by Law No. 1797-VIII of 21.12.2016 }
If such goods/services, non-current assets subsequently begin to be used in taxable transactions within the framework of economic activity, including the transfer of non-productive non-current assets to productive non-current assets, the taxpayer may reduce the amount of tax liabilities accrued in accordance with this paragraph, based on the calculation of the adjustment to the tax invoice specified in the first paragraph of this paragraph, registered in the Unified Register of Tax Invoices.
{Paragraph six of clause 198.5 of Article 198 as amended by Law No. 71-VIII of 28.12.2014 }
For the purpose of applying this paragraph, tax liabilities are determined by goods/services, non-current assets:
{Paragraph seven of clause 198.5 of Article 198 as amended by Law No. 71-VIII of 28.12.2014 }
purchased for use in non-taxable transactions - on the date of their acquisition;
{Paragraph of clause 198.5 of Article 198 as amended by Law No. 71-VIII of 28.12.2014 }
purchased for use in taxable transactions that begin to be used in non-taxable transactions - on the date of the start of their actual use, determined in the primary documents drawn up in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine.
{Paragraph of clause 198.5 of Article 198 as amended by Law No. 71-VIII of 28.12.2014 }
If, at the time of the taxpayer's inspection by the controlling body, a shortage of goods purchased by such taxpayer is detected in the act of a selective (partial) inventory conducted by the taxpayer at the request of such body (except for the case where such shortage is due to destruction due to force majeure circumstances, which is confirmed in accordance with the legislation), for the purposes of Section V of this Code, such goods are considered to have been used by the taxpayer in transactions that are not the taxpayer's economic activity.
{Paragraph 198.5 of Article 198 is supplemented by paragraph ten in accordance with Law No. 909-VIII of 24.12.2015 }
{Clause 198.5 of Article 198 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.24.2012 ; as amended by Law No. 2245-VIII of 07.12.2017 }
198.6. The tax credit does not include the amounts of tax paid (accrued) in connection with the purchase of goods/services that are not confirmed by tax invoices registered in the Unified Register of Tax Invoices / calculations of adjustments to such tax invoices or are not confirmed by customs declarations (temporary, additional and other types of customs declarations under which tax amounts are paid to the budget upon import of goods into the customs territory of Ukraine), other documents provided for in paragraph 201.11 of Article 201 of this Code.
{Paragraph one of clause 198.6 of Article 198 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; with the amendments made in accordance with Laws No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 ; as amended by the Law No. 466-IX dated 16.01.2020 }
If, at the time of the taxpayer's inspection by the controlling authority, the tax amounts previously included in the tax credit remain unconfirmed by the documents specified in the first paragraph of this paragraph, the taxpayer shall be liable in accordance with this Code.
{Paragraph two of clause 198.6 of Article 198 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 71-VIII of 28.12.2014 }
Tax invoices received from the Unified Register of Tax Invoices are the basis for the recipient of goods/services to calculate tax amounts related to the tax credit.
{Paragraph 198.6 of Article 198 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 }
If the taxpayer did not include in the relevant reporting period the amount of value added tax in the tax credit based on the received tax invoices /adjustment calculations to such tax invoices registered in the Unified Register of Tax Invoices, such right is retained by him for 365 calendar days from the date of preparation of the tax invoice/adjustment calculation.
{Clause 198.6 of Article 198 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 07/16/2015 ; as amended by Law No. 1797-VIII of 12/21/2016 ; with amendments made in accordance with Laws No. 2198-VIII of 11/09/2017 , No. 1914-IX of 11/30/2021 }
The amounts of tax paid (accrued) in connection with the purchase of goods/services indicated in tax invoices /calculations of adjustments to such tax invoices registered in the Unified Register of Tax Invoices in violation of the registration deadline are included in the tax credit for the reporting tax period in which the tax invoices/calculations of adjustments to such tax invoices were registered in the Unified Register of Tax Invoices, but no later than 365 calendar days from the date of preparation of the tax invoices/calculations of adjustments to such tax invoices.
{Paragraphs five - seven of clause 198.6 of Article 198 were replaced by one paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2198-VIII of 09.11.2017 ; as amended by the Law No. 466-IX dated 16.01.2020 ; as amended by Law No. 1914-IX dated 30.11.2021 }
Taxpayers who apply the cash method of tax accounting, the tax amounts specified in tax invoices / adjustment calculations to such tax invoices, registered in the Unified Register of Tax Invoices, and not included in the tax credit within a period of 365 calendar days from the date of preparation of such tax invoices / adjustment calculations to such tax invoices due to the absence of facts of debiting funds from the taxpayer's account with a bank / non-bank payment service provider (withdrawal from the cash register) or providing other types of compensation for the cost of goods / services delivered (or to be delivered) to him, have the right to include such amounts in the tax credit in the reporting tax period in which the debiting of funds from the taxpayer's account with a bank / non-bank payment service provider (withdrawal from the cash register) or providing other types of compensation for the cost of goods / services delivered (or to be delivered) to him took place, but no later than 60 calendar days from the date of such write-off, provision of other types of compensation.
{Paragraph 198.6 of Article 198 is supplemented with a new paragraph in accordance with the Law No. 466-IX dated 01/16/2020 ; as amended by Laws No. 1914-IX dated 11/30/2021 , No. 2888-IX dated 01/12/2023 }
In the event of suspension of registration of a tax invoice / adjustment calculation in the Unified Register of Tax Invoices in accordance with Clause 201.16 of Article 201 of this Code, the running of the terms specified in this clause shall be interrupted for the period of suspension of registration of such tax invoices / adjustment calculations in the Unified Register of Tax Invoices.
{ Paragraph 198.6 of Article 198 is supplemented with a new paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
{Paragraph 198.6 of Article 198 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
The tax credit does not include the amounts of tax paid (accrued) in accordance with subparagraph 191.1.2 of paragraph 191.1 of Article 191 of this Code by a postal operator or express carrier.
{Clause 198.6 of Article 198 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
198.7. The amount of the negative value to be included in the tax credit of the next reporting (tax) period of the payer that is reorganized by:
accession, merger, transformation, - is subject to transfer to the tax credit of the legal successor in the next period after signing the transfer deed in accordance with the legislation;
division, allocation, - is subject to transfer to the tax credit of the legal successor in proportion to the received share of the property according to the distribution balance in the next period after the signing of the distribution balance in accordance with the legislation.
Such a transfer is carried out if the amount of the negative value to be included in the tax credit of the next reporting (tax) period of the reorganized payer is confirmed by a documentary check by the regulatory authority.
{Article 198 was supplemented by paragraph 198.7 in accordance with Law No. 1797-VIII of 21.12.2016 }
Article 199. Proportional allocation of tax amounts to tax credit↑
199.1. If purchased and/or manufactured goods/services, non-current assets are partially used in taxable transactions, and partially not, the taxpayer is obliged to calculate tax liabilities based on the tax base determined in accordance with Clause 189.1 of Article 189 of this Code, and draw up no later than the last day of the reporting (tax) period and register a consolidated tax invoice in the Unified Register of Tax Invoices for the total amount of the share of tax paid (accrued) during their purchase or manufacture, which corresponds to the share of use of such goods/services, non-current assets in non-taxable transactions.
{Clause 199.1 of Article 199 as amended by Law No. 4834-VI of 24.05.2012 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 643-VIII dated 16.07.2015 }
199.2. The share of use of goods/services, non-current assets in taxable transactions is determined in percentage as the ratio of the volumes of supplies of taxable transactions (excluding tax amounts) for the previous calendar year to the total volumes of supplies of taxable and non-taxable transactions (excluding tax amounts) for the same previous calendar year. The value determined in percentage is applied during the current calendar year.
{Clause 199.2 of Article 199 as amended by Law No. 4834-VI of 24.05.2012 }
199.3. Taxpayers who did not have any non-taxable transactions during the previous calendar year, and such non-taxable transactions began to be carried out in the reporting period, as well as newly established taxpayers, shall calculate in the current calendar year the share of use of goods/services, non-current assets in taxable transactions based on the calculation determined based on actual data on the volumes of supplies of taxable and non-taxable transactions of the first reporting tax period in which such transactions are declared.
{Paragraph one of clause 199.3 of Article 199 as amended by Law No. 4834-VI of 24.05.2012 }
The calculation of the share of use of goods/services, non-current assets in taxable transactions is submitted to the regulatory authority simultaneously with the tax return for the reporting tax period in which such taxable and non-taxable transactions are declared.
{Paragraph two of clause 199.3 of Article 199 as amended by Law No. 4834-VI of 24.05.2012 }
199.4. The taxpayer shall, at the end of the calendar year, recalculate the share of the use of goods/services and non-current assets in taxable transactions based on the actual volumes of taxable and non-taxable transactions carried out during the year. In the event of the taxpayer's deregistration, including by court decision, the share shall be recalculated based on the actual volumes of taxable and non-taxable transactions carried out from the beginning of the current year until the date of deregistration.
{Paragraph one of clause 199.4 of Article 199 as amended by Law No. 4834-VI of 24.05.2012 }
{Paragraph two of clause 199.4 of Article 199 was excluded on the basis of Law No. 643-VIII of 16.07.2015 }
199.5. The share of use of goods/services, non-current assets in taxable transactions, determined taking into account the norms of paragraphs 199.2-199.4 of Article 199 of this Code, is used to adjust the amounts of tax liabilities specified in paragraph 199.1 of Article 199 of this Code. The results of recalculation of the amounts of tax liabilities are reflected in the tax return for the last tax period of the year. In the event of deregistration of a taxpayer, including by court decision, the adjustment is reflected by the taxpayer in the tax return for the last tax period when the deregistration occurred.
{Clause 199.5 of Article 199 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.24.2012 , No. 1797-VIII of 12.21.2016 }
199.6. The rules of this article do not apply in the case of:
{Paragraph one of clause 199.6 of Article 199 as amended by the Law No. 71-VIII dated 28.12.2014 }
carrying out operations provided for in subparagraph 196.1.7 of paragraph 196.1 of Article 196 of this Code;
{Paragraph three of clause 199.6 of Article 199 was excluded on the basis of Law No. 1914-IX of 30.11.2021 }
carrying out operations provided for in subparagraph 197.1.28 of paragraph 197.1, paragraphs 197.11 and 197.24 of Article 197 of this Code.
{Clause 199.6 of Article 199 supplemented by the fourth paragraph in accordance with Law No. 4834-VI of 24.05.2012 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 1665-VIII of 06.10.2016 }
Article 200. Procedure for determining the amount of tax subject to payment (transfer) to the State Budget of Ukraine or reimbursement from the State Budget of Ukraine (budgetary reimbursement), and the terms of calculations↑
200.1. The amount of tax payable (transferred) to the State Budget of Ukraine or budget reimbursement is determined as the difference between the amount of tax liability for the reporting (tax) period and the amount of tax credit for such reporting (tax) period.
paragraph 200.1 of this Article is positive , such amount shall be paid (transferred) to the budget within the terms established by this section.
To transfer tax to the budget, the central executive body implementing the state tax policy shall send to the central executive body implementing the state policy in the field of treasury services of budget funds, in which payers' accounts are opened in the system of electronic administration of value added tax, a register of payers, which shall indicate the name of the payer, tax number and individual tax number of the payer, the reporting period and the amount of tax to be transferred to the budget. Based on such a register, the central executive body implementing the state policy in the field of treasury services of budget funds, in which payers' accounts are opened in the system of electronic administration of value added tax, shall transfer the tax amounts to the budget no later than the last day of the period established by this Code for independent payment of tax obligations.
{Clause 200.2 of Article 200 supplemented by the second paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Law No. 1797-VIII of 21.12.2016 }
{Paragraph 200.3 of Article 200 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
200.4. If the amount calculated in accordance with paragraph 200.1 of this Article is negative, such amount:
a) is taken into account in reducing the amount of tax debt from tax that arose for previous reporting (tax) periods (including installments or deferred in accordance with this Code) in the part that does not exceed the amount calculated in accordance with clause 200 - 1.3 of Article 200 - 1 of this Code at the time of receipt of the tax return by the controlling authority, and in the absence of tax debt -
b) or is subject to budget reimbursement at the payer's request in the amount of tax actually paid by the recipient of goods/services in the previous and reporting tax periods to the suppliers of such goods/services or to the State Budget of Ukraine, in the part that does not exceed the amount calculated in accordance with Clause 200 - 1.3 of Article 200 - 1 of this Code at the time of receipt of the tax declaration by the controlling body, to the relevant account of the taxpayer in a bank/non-bank payment service provider and/or to pay monetary obligations or repay tax debt of such taxpayer from other payments paid to the state budget;
{Subparagraph "b" of paragraph 200.4 of Article 200 as amended by Laws No. 909-VIII of 12/24/2015 , No. 2600-IX of 09/20/2022 ; as amended by Law No. 2888-IX of 01/12/2023 }
c) and/or is included in the tax credit of the next reporting (tax) period.
{Clause 200.4 of Article 200 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 , No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 71-VIII of 28.12.2014 }
200.4 - 1. Taxpayers in respect of whom (and/or in respect of their founders (participants), ultimate beneficial owners) in accordance with the procedure established by the Law of Ukraine "On Sanctions", decisions have been made to apply special economic and other restrictive measures (sanctions), during the period of application of such sanctions, they are not entitled to receive budget compensation for the amount of negative value.
{Paragraph one of clause 200.4 - 1 of Article 200 as amended by Law No. 3813-IX of 18.06.2024 }
Amounts of such negative value are included in the reduction of the amount of tax debt from the tax that arose for previous reporting (tax) periods (including installments or deferred in accordance with this Code), and in the absence of tax debt - in the tax credit of the next reporting (tax) period.
{ Article 200 is supplemented by paragraph 200.4 - 1 in accordance with Law No. 3317-IX of 10.08.2023 }
200.4 - 2. The amount of a negative value, the calculation of which includes the amounts of tax paid by the recipient of goods/services in previous and reporting tax periods to suppliers of goods/services that are used or will be used in transactions for the first supply of housing (residential real estate), an indivisible residential property under construction/future residential property, is not subject to budget reimbursement.
Amounts of such negative value are included in the tax credit of the next reporting (tax) period until they are fully repaid by tax liabilities.
{ Article 200 is supplemented by paragraph 200.4 - 2 in accordance with Law No. 3317-IX of 10.08.2023 }
{Clause 200.5 of Article 200 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Paragraph 200.6 of Article 200 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
200.7. A taxpayer who is entitled to receive a budget refund and has made a decision to return the amount of budget refund shall submit to the relevant supervisory authority a tax return and an application for the return of the amount of budget refund, which is reflected in the tax return.
{Paragraph one of clause 200.7 of Article 200 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 }
200.7.1. The Register of applications for the return of the amount of budget compensation is formed on the basis of the databases of the central executive body implementing tax policy and the central executive body implementing state policy in the field of treasury servicing of budget funds.
The following data shall be entered into such a Register:
1) the name of the taxpayer and his individual tax number;
2) date of submission of the application for the return of the budget compensation amount to the payer's account with a bank/non-bank payment service provider, submitted as part of the tax return or clarifying calculation (if submitted);
{Paragraph four of subparagraph 200.7.1 of paragraph 200.7 of Article 200 as amended by Law No. 2888-IX of 12.01.2023 }
3) the amount of tax declared for budget reimbursement is indicated in each application submitted as part of the tax return or clarification calculation (if submitted), including separately, which is subject to transfer to the taxpayer's account at a bank/non-bank payment service provider and/or to the payment of monetary obligations, and/or to the repayment of the tax debt of such taxpayer from other payments paid to the state budget;
{Paragraph five of subparagraph 200.7.1 of paragraph 200.7 of Article 200 as amended by Law No. 2888-IX of 12.01.2023 }
4) the amount of tax declared for budget reimbursement is reduced by the amount of tax debt;
5) details of the taxpayer's account with a bank/non-bank payment service provider for transferring budget reimbursement;
{Paragraph seven of subparagraph 200.7.1 of paragraph 200.7 of Article 200 as amended by Law No. 2888-IX of 12.01.2023 }
6) details of budget accounts for transfer to the account of payment of monetary obligations or repayment of tax debt of such taxpayer from other payments paid to the state budget;
7) details of the budget account from which the budget tax refund is made;
8) the date of the start and end of the verification of the data specified in the tax return or clarification calculation (if submitted), which includes an application for the return of the amount of budget compensation, with a mandatory note on the type of verification (in-office, documentary);
9) the amount of tax declared for budget reimbursement and the date of the application submitted to the regulatory authority in the event that the taxpayer needs to change the direction of the agreed budget reimbursement;
10) date of preparation and delivery of the audit report to the taxpayer;
11) date and number of the tax notice-decision and the amount of budget compensation for each application, taking into account (if submitted) a clarifying calculation, not approved by the supervisory authority;
12) the date of commencement of the appeal of the tax notice-decision and the amount of budget compensation being appealed;
13) the end date of the appeal of the tax notice-decision and the amount of budget compensation agreed upon based on the results of the appeal;
14) the amount of budget compensation agreed by the controlling body for each application and the date of its agreement;
15) date and amount of the budget reimbursement to the payer's account at the bank/non-bank payment service provider;
{Paragraph seventeen of subparagraph 200.7.1 of paragraph 200.7 of Article 200 as amended by Law No. 2888-IX of 12.01.2023 }
16) date and amount of credit (transfer) for payment of monetary obligations or repayment of tax debt of such taxpayer from other payments paid to the state budget;
17) date of adoption of the decision on the application of special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions";
{Subparagraph 200.7.1 of paragraph 200.7 of Article 200 is supplemented with a new paragraph in accordance with Law No. 3317-IX of 10.08.2023 }
18) date of adoption of the decision on the abolition of special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions".
{Subparagraph 200.7.1 of paragraph 200.7 of Article 200 is supplemented with a new paragraph in accordance with Law No. 3317-IX of 10.08.2023 }
Data entry into the Register of applications for the return of the amount of budget compensation by officials of the relevant bodies is carried out in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Paragraph of subparagraph 200.7.1 of paragraph 200.7 of Article 200 as amended by Law No. 2725-VIII of 16.05.2019 }
The procedure for maintaining and the form of the Register of applications for the return of the amount of budget compensation are approved by the Cabinet of Ministers of Ukraine.
{Clause 200.7 of Article 200 is supplemented by subparagraph 200.7.1 in accordance with Laws No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
200.7.2. Applications for the return of budget compensation amounts are automatically entered into the Register of Applications for the Return of Budget Compensation Amounts during the operating day of their receipt in the chronological order of their receipt.
The refund of the agreed amounts of budget compensation is carried out in chronological order in accordance with the order of entry of applications for the refund of the amount of budget compensation into the Register.
{Clause 200.7 of Article 200 is supplemented by subparagraph 200.7.2 in accordance with Laws No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
200.7.3. Data from the Register of applications for the return of the amount of budget compensation, provided for in subparagraph 200.7.1 of this paragraph, except for subparagraph 5 of subparagraph 200.7.1 of this paragraph regarding the details of the taxpayer's account with a bank/non-bank payment service provider for the transfer of budget compensation, are not information with restricted access and are subject to daily publication, except for weekends, holidays and non-working days, on the official website of the central executive body that ensures the formation of state financial policy.
{Paragraph one of subparagraph 200.7.3 of paragraph 200.7 of Article 200 as amended by Law No. 2888-IX of 12.01.2023 }
The procedure for providing relevant information by the central executive body implementing tax policy and the central executive body implementing state policy in the field of treasury servicing of budget funds, for its publication on the official website of the central executive body ensuring the formation of state financial policy, is established by the central executive body ensuring the formation of state financial policy.
{Clause 200.7 of Article 200 is supplemented by subparagraph 200.7.3 in accordance with Laws No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
200.8. The taxpayer shall attach to the tax return or clarifying calculations (if submitted) the calculation of the amount of budget compensation and the originals of customs declarations. If customs clearance of goods exported outside the customs territory of Ukraine was carried out using an electronic customs declaration, such electronic customs declaration shall be provided by the controlling body at the place of customs clearance to the controlling body at the place of registration of such taxpayer in accordance with the procedure approved by the central executive body that ensures the formation and implementation of state financial policy, in electronic form using a qualified electronic signature in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services".
{Clause 200.8 of Article 200 as amended by Law No. 4915-VI of 07.06.2012 ; as amended by Laws No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 , No. 2725-VIII of 16.05.2019 , No. 2918-IX of 07.02.2023 }
200.9. The form of the application for reimbursement and the form of calculation of the amount of budget reimbursement are determined by the central executive body that ensures the formation of state financial policy.
{Clause 200.9 of Article 200 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 }
200.10. Within the period provided for in the first paragraph of paragraph 76.3 of Article 76 of this Code, the supervisory authority shall conduct an in-house verification of the data of the tax declaration or clarifying calculations (if they are submitted).
Taxpayers who are entitled to budget compensation in accordance with this Article and have submitted an application for the return of the amount of budget compensation shall receive such budget compensation if the controlling body approves the declared amount of budget compensation based on the results of a desk audit conducted within 20 calendar days following the deadline for submitting a tax return or clarifying calculation (if submitted), and if such documents were submitted later - on the day of their actual submission, and in accordance with the requirements specified in Article 76 of this Code, and in cases specified in paragraph 200.11 of this Article - based on the results of the audit specified in such paragraph, in accordance with this Code.
{Paragraph two of clause 200.10 of Article 200 as amended by Law No. 3603-IX of 02/23/2024 }
{Clause 200.10 of Article 200 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 1797-VIII of 12/21/2016 } {Regarding the suspension of the effect of clause 200.10 of Article 200 until 07/21/2022, see subparagraph 69.11 of clause 69, subsection 10 of section XX}
200.11. {Regarding the suspension of clause 200.11 of Article 200, see subparagraph 69.11 of clause 69, subsection 10, section XX} The supervisory authority has the right, within 40 calendar days following the deadline for filing a tax return , and if such a tax return is filed after the deadline - following the day of its actual filing, to conduct a documentary audit of the taxpayer in accordance with subparagraph 78.1.8 of clause 78.1 of Article 78 of this Code.
{Paragraph one of clause 200.11 of Article 200 as amended by Law No. 3603-IX of 02/23/2024 }
The decision to conduct a documentary audit must be made no later than the expiration of the deadline for conducting a desk audit.
{Clause 200.11 of Article 200 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Laws No. 1791-VIII of 12/20/2016 , No. 466-IX of 01/16/2020 ; as amended by Law No. 1914-IX of 11/30/2021 } {Regarding the suspension of clause 200.11 of Article 200 until 07/21/2022, see subparagraph 69.11 of clause 69, subsection 10, section XX}
200.12. The amount of budget compensation specified in the application is considered to be agreed in the Register of applications for the return of the amount of budget compensation from one of the following dates:
{Paragraph one of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 }
a) from the day following the day of the end of the deadline for conducting the inspection, if the controlling body has entered information about the absence of violations during such inspection into the Register of applications for the return of the amount of budget compensation;
{Paragraph two of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 21.12.2016 }
b) from the day following the end of the deadline for conducting an in-house audit, if the controlling body has not entered into the Register of applications for the return of the amount of budget compensation information on the date of the start and end of the audit of the data specified in the tax declaration or clarifying calculation, with a mandatory note on the type of audit (in-house, documentary);
{Paragraph three of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 }
c) from the day following the day of expiry of the deadline provided for by this Code for drawing up an inspection report, if the controlling body has not entered information on the date of drawing up the inspection report into the Register of applications for the return of the amount of budget compensation;
{Paragraph of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 }
d) from the day following the day of expiry of the deadline provided for by this Code for sending (delivering) a tax notice-decision, if the controlling body has not entered information about the date and number of the tax notice-decision into the Register of applications for the return of the amount of budget compensation;
{Paragraph of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 }
e) from the date of recognition of the tax notice as unlawful and/or cancellation.
{Paragraph of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 }
In the cases provided for in subparagraphs "b" and "c" of this paragraph, information on the consistency of the budget compensation and its amount is displayed in the Register of applications for the return of the amount of budget compensation automatically on the next business day after the occurrence of such an event.
{Paragraph of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 }
In cases provided for in subparagraphs "a", "d" and "e" of this paragraph, information on the consistency of budget compensation and its amount is reflected in the Register of applications for the return of the amount of budget compensation by the controlling body on the next business day after the occurrence of such an event.
{Paragraph of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 }
The agreed amount of budget compensation becomes available to the body performing treasury servicing of budget funds for execution on the next business day after the day of its reflection in the Register of applications for the return of the amount of budget compensation and is transferred by the body performing treasury servicing of budget funds, within the terms provided for in paragraph 200.13 of this Article, to the taxpayer's account in the servicing bank/non-bank payment service provider and/or to budget accounts for transfer to pay monetary obligations or repay tax debt of such taxpayer from other payments paid to the State Budget of Ukraine.
{Paragraph of Clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 2888-IX of 12/12/2023 }
If a taxpayer has a tax debt, the declared tax amount, reduced by the amount of such tax debt, is subject to budget reimbursement.
If a taxpayer needs to change the direction of the agreed budget reimbursement, such taxpayer has the right to submit a corresponding application to the regulatory authority, which is obliged to enter the relevant data into the Register of applications for the refund of the amount of budget reimbursement no later than the next business day from the date of receipt of such application.
{Paragraph eleven of clause 200.12 of Article 200 as amended by Law No. 1797-VIII of 21.12.2016 }
{Clause 200.12 of Article 200 as amended by Law No. 909-VIII of 12/24/2015 } {Regarding the suspension of clause 200.12 of Article 200 until 07/21/2022, see subparagraph 69.11 of clause 69, subsection 10, section XX}
200.12 - 1. From the date of the decision to apply special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions", the budget compensation of the agreed amount of budget compensation and the running of the terms for the implementation of such budget compensation, determined by this article, shall be suspended.
The amount of budget compensation specified in the first paragraph of this paragraph remains available to the body that carries out treasury servicing of budget funds, and is transferred by this body to the taxpayer's account in the servicing bank/non-bank payment service provider and/or to budget accounts for transfer to the account of payment of monetary obligations or repayment of tax debt of such taxpayer from other payments paid to the State Budget of Ukraine, within five business days from the date of the decision to cancel special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions".
{ Article 200 is supplemented by paragraph 200.12 - 1 in accordance with Law No. 3317-IX of 10.08.2023 }
200.13. Based on the data of the Register of applications for the return of the amount of budget compensation, the body that carries out treasury servicing of budget funds, after the day of acquiring the status of the agreed amount of budget compensation, transfers such amount from the budget account to the taxpayer's account in the servicing bank/non-bank payment service provider and/or to budget accounts for transfer to pay monetary obligations or repay the tax debt of such taxpayer from other payments paid to the state budget, within five business days.
{Clause 200.13 of Article 200 as amended by Laws No. 5519-VI of 06.12.2012 , No. 407-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2888-IX of 12.01.2023 }
200.14. If, based on the results of a desk or documentary inspection, the controlling body detects a discrepancy between the amount of budget compensation and the amount declared in the tax return, such body:
{Paragraph one of clause 200.14 of Article 200 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 }
{Paragraph two of clause 200.14 of Article 200 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
b) in the event that the amount of budget compensation declared by the taxpayer exceeds the amount determined by the supervisory authority based on the results of inspections, sends the taxpayer a tax notification-decision, which indicates the amount of such excess and the grounds for its deduction;
c) in the event of clarification based on the results of inspections of a fact according to which the taxpayer is not entitled to receive budget compensation, sends the taxpayer a tax notification-decision, which indicates the grounds for refusing to provide budget compensation.
{Clause 200.14 of Article 200 as amended by Laws No. 71-VIII of 12/28/2014 , No. 3317-IX of 08/10/2023 }
200.14 - 1. If during the period of conducting a desk or documentary inspection by the controlling body a decision is made to apply special economic and other restrictive measures (sanctions) in accordance with the procedure established by the Law of Ukraine "On Sanctions", such controlling body shall send the taxpayer a tax notification-decision, which shall state the refusal to provide budget compensation.
Such a tax notice-decision is not subject to appeal.
{ Article 200 is supplemented by paragraph 200.14 - 1 in accordance with Law No. 3317-IX of 10.08.2023 }
200.15. In the event that, based on the results of the audit of the tax amounts declared for reimbursement, the taxpayer initiates an administrative or judicial appeal procedure, the supervisory authority shall, no later than the next business day after receiving the relevant notification from the taxpayer or the court ruling on the initiation of proceedings in the case, enter the relevant data into the Register of applications for the refund of the amount of budget reimbursement.
{Paragraph one of clause 200.15 of Article 200 as amended by Law No. 1797-VIII of 21.12.2016 }
After the administrative appeal procedure is completed or the court decision enters into force, the supervisory authority is obliged to enter data on the agreed amount of the payer's budget compensation into the Register of applications for the return of the budget compensation amount on the next business day after receiving the relevant decision.
{Paragraph two of clause 200.15 of Article 200 as amended by Law No. 1797-VIII of 21.12.2016 }
In the event of disagreement by the controlling authority of the amount of tax declared for reimbursement, or its part, the obligation for budgetary tax reimbursement in the part of the disagreement arises from the date of completion of the administrative or judicial appeal procedure, based on the results of which a decision was made in favor of the taxpayer.
{Paragraph 200.15 of Article 200 is supplemented by the third paragraph in accordance with Law No. 909-VIII of 24.12.2015 }
200.16. If a taxpayer exports goods outside the customs territory of Ukraine, received from another taxpayer under the terms of a commission, consignment, mandate or other types of agreements that do not provide for the transfer of ownership of such goods from such other taxpayer to the exporter, such other taxpayer shall have the right to receive budget compensation. In this case, the commission fee received by the taxpayer - exporter from such other taxpayer shall be included in the tax base at the rate determined by subparagraph "a" of paragraph 193.1 of Article 193 of this Code, and shall not be included in the customs value of the goods being exported.
{Clause 200.16 of Article 200 as amended by Law No. 4915-VI of 07.06.2012 }
200.17. The source of payment of budget compensation (including budget arrears) is the revenues of the budget to which the tax is paid.
{Paragraph one of clause 200.17 of Article 200 as amended by Law No. 1166-VII of March 27, 2014 }
It is prohibited to condition or limit the payment of budget compensation on the presence or absence of revenues received from this tax in certain regions of Ukraine.
{Clause 200.18 of Article 200 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Clause 200.19 of Article 200 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Clause 200.20 of Article 200 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Clause 200.21 of Article 200 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Clause 200.22 of Article 200 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
200.23. Tax amounts not reimbursed to payers within the period specified in this article shall be considered a debt to the budget for the reimbursement of value-added tax. A penalty of 120 percent of the discount rate of the National Bank of Ukraine established at the time of the penalty arising shall be charged on the amount of such debt, for the duration of its validity, including the day of repayment.
Penalty charges shall not be levied in accordance with the first paragraph of this clause if such debt is due to:
{ Item 200.23 of Article 200 is supplemented by the second paragraph in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 3317-IX of August 10, 2023 }
the occurrence of force majeure circumstances (force majeure circumstances) in connection with the introduction of martial law or a state of emergency;
{Paragraph of item 200.23 of Article 200 as amended by Law No. 3317-IX of 10.08.2023 }
suspension/refusal of providing budget compensation under a decision to apply special economic and other restrictive measures (sanctions) adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions".
{Paragraph of item 200.23 of Article 200 as amended by Law No. 3317-IX of 10.08.2023 }
Article 200 - 1. Electronic administration of value added tax↑
200 - 1 .1. The electronic administration system for value added tax provides automatic accounting by taxpayer:
tax amounts contained in prepared and received tax invoices and adjustment calculations registered in the Unified Register of Tax Invoices;
{Paragraph two of clause 200 - 1 .1 of Article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
tax amounts paid by taxpayers upon importation of goods into the customs territory of Ukraine;
the amount of replenishment and the balance of funds on accounts in the electronic administration system of value added tax;
the amount of tax for which payers have the right to register tax invoices and calculations of adjustments to tax invoices in the Unified Register of Tax Invoices;
other indicators that, in accordance with the requirements of Clause 34, Subsection 2, Section XX "Transitional Provisions" of this Code, are taken into account when calculating the tax amount calculated according to the formula specified in Clause 200 - 1.3 of Article 200 - 1 of this Code.
{Paragraph 200 - 1 .1 of Article 200 - 1 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 }
The procedure for electronic administration of value added tax is established by the Cabinet of Ministers of Ukraine.
200 - 1 .2. Taxpayers are automatically opened accounts in the electronic administration system for value added tax.
Settlements with the budget in the electronic administration system of value added tax are made from these accounts, except for the case provided for in paragraph two of clause 87.1 of Article 87 of this Code.
{Paragraph 200 - 1 .2 of Article 200 - 1 is supplemented with a new paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
to taxpayers - agricultural enterprises that have chosen a special taxation regime in accordance with Article 209 of this Code:
{Paragraph 200 - 1 .2 of Article 200 - 1 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 ; as amended by Law No. 909-VIII of 24.12.2015 }
a) accounts in the electronic tax administration system intended for transferring funds to the State Budget of Ukraine and to their special accounts opened in banking institutions and/or bodies providing treasury services for budget funds, for carrying out operations for the supply of agricultural goods/services (except for grain and industrial crops and livestock products specified in Clause 209.19 of Article 209 of this Code);
{Paragraph of clause 200 - 1 .2 of Article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
b) accounts in the electronic tax administration system intended for transferring funds to the State Budget of Ukraine and to their special accounts opened in banking institutions and/or bodies providing treasury services for budget funds, for carrying out operations for the supply of grain and industrial crops specified in Clause 209.19 of Article 209 of this Code;
{Paragraph of clause 200 - 1 .2 of Article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
c) accounts in the electronic tax administration system intended for transferring funds to the State Budget of Ukraine and to their special accounts opened in banking institutions and/or bodies providing treasury services for budget funds, for carrying out operations for the supply of livestock products specified in Clause 209.19 of Article 209 of this Code.
{Paragraph of clause 200 - 1 .2 of Article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
To open accounts in the electronic administration system for value-added tax, the central executive body that ensures the implementation of tax and customs policy sends to the central executive body that implements state policy in the field of treasury services of budget funds, in which payer accounts are opened in the electronic administration system for value-added tax, a register of payers, which indicates the name of the payer, tax number and individual tax number of the payer.
{Paragraph seven of clause 200 - 1 .2 of article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
200 - 1 .3. The taxpayer has the right to register tax invoices and/or adjustment calculations in the Unified Register of Tax Invoices for the tax amount ( Σ Invoice), calculated according to the following formula:
{Paragraph two of clause 200 - 1 .3 of Article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
where:
Σ NaklOtr - the total amount of tax on tax invoices received by the payer, registered in the Unified Register of Tax Invoices, tax invoices drawn up by the payer in accordance with Clause 208.2 of Article 208 of this Code and registered in the Unified Register of Tax Invoices, and adjustment calculations to such tax invoices, registered in the Unified Register of Tax Invoices;
SCustoms - the total amount of tax paid by the payer upon import of goods into the customs territory of Ukraine, except for the amounts of tax paid (accumulated) in accordance with subparagraph 191.1.2 of paragraph 191.1 of Article 191 of this Code by the postal operator, express carrier;
{Paragraph five of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 2628-VIII of 23.11.2018 }
Σ PopRah - the total amount of replenishment from the account with the bank/non-bank payment service provider of the taxpayer's account in the electronic tax administration system, including accounts in the electronic tax administration system of the taxpayer - an agricultural enterprise that has chosen a special taxation regime in accordance with Article 209 of this Code, specified in subparagraphs "a" - "c" of paragraph 200 - 1.2 of this article.
{Paragraph six of clause 200 - 1 .3 of Article 200 - 1 as amended by Law No. 643-VIII of 07/16/2015 ; as amended by Law No. 909-VIII of 12/24/2015 }
When calculating the Σ PopRah indicator, the amount of funds is taken into account:
{Paragraph 200 - 1 .3 of Article 200 - 1 is supplemented with a new paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 466-IX dated 16.01.2020 }
a) withdrawn and credited by the controlling authority to the taxpayer's account in the electronic tax administration system in accordance with Clause 95.5 of Article 95 of this Code for the purpose of repaying the tax debt on value added tax on tax liabilities declared for payment for periods starting from July 1, 2015, specified by the taxpayer in the value added tax return or clarifying calculation;
{Paragraph of item 200 - 1 .3 of Article 200 - 1 as amended by the Law No. 466-IX dated 16.01.2020 ; as amended by Law No. 3553-IX dated 16.01.2024 }
b) in the case of the body carrying out treasury services of budget funds, the taxpayer's calculations for the repayment of debt from the difference in tariffs for thermal energy, heating and hot water supply, centralized water supply, and water disposal services produced, transported and supplied to the population and/or other centralized drinking water supply and water disposal enterprises that provide centralized water supply and water disposal services to the population, which arose due to the discrepancy between the actual cost of thermal energy and centralized water supply, water disposal, heating and hot water supply services and the tariffs approved and/or agreed upon by state authorities or local self-government bodies, at the expense of a subvention from the state budget to local budgets with the subsequent allocation of funds in accordance with the Law of Ukraine on the State Budget of Ukraine for the repayment of tax debt. At the same time, to replenish the account in the electronic tax administration system, the amount of the reduction in the balance of the agreed tax obligations of such a taxpayer, not paid to the budget, the payment deadline for which has arrived, which is recorded by the body that carries out treasury services of budget funds, until full execution according to the adjusting registers, is taken into account within the limits of the tax calculations made.
{Paragraph of item 200 - 1 .3 of Article 200 - 1 as amended by the Law No. 466-IX dated 16.01.2020 }
The procedure and terms for taking such amounts into account in the electronic tax administration system are established by the Cabinet of Ministers of Ukraine.
{Paragraph 200 - 1 .3 of Article 200 - 1 is supplemented with a new paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
The following amounts credited to payers' accounts in the electronic tax administration system are not taken into account in the calculation of the indicator ∑ PopRah:
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
a) accounts in the electronic tax administration system opened for transferring funds to the State Budget of Ukraine and to special accounts opened in banking institutions and/or in bodies providing treasury services for budget funds, for carrying out operations for the supply of agricultural goods/services (except for grain and industrial crops and livestock products specified in Clause 209.19 of Article 209 of this Code);
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
b) accounts in the electronic tax administration system opened for transferring funds to the State Budget of Ukraine and to special accounts opened in banking institutions and/or in bodies providing treasury services for budget funds, for carrying out operations for the supply of grain and industrial crops specified in Clause 209.19 of Article 209 of this Code;
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
c) accounts in the electronic tax administration system opened for transferring funds to the State Budget of Ukraine and to special accounts opened in banking institutions and/or in bodies providing treasury services for budget funds, for carrying out operations for the supply of livestock products specified in Clause 209.19 of Article 209 of this Code.
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
{Paragraph 200 - 1 .3 of Article 200 - 1 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Paragraph 200 - 1 .3 of Article 200 - 1 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
∑ Overdraft - the sum of the average monthly amount of tax amounts that were declared by the payer for payment to the budget and repaid or paid in installments or deferred, as well as declared by the payer - an agricultural enterprise that has chosen a special taxation regime in accordance with Article 209 of this Code, over the last 12 reporting (tax) months.
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
Indicator ∑ Overdraft every quarter (during the first six business days of such quarter) is subject to automatic recalculation taking into account the indicator of the average monthly amount of tax amounts that, for the last 12 reporting (tax) months as of the date of such recalculation, were declared by the payer for payment to the budget and repaid or paid in installments or deferred, as well as declared by the payer - an agricultural enterprise that has chosen a special taxation regime in accordance with Article 209 of this Code. Such recalculation is carried out by subtracting the amount of the previous increase and adding the amount of the increase in accordance with the current recalculation.
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
For taxpayers who, as of January 1, 2016, have been registered as value-added tax payers for less than 12 reporting (tax) months, as well as for taxpayers registered as value-added tax payers after January 1, 2016, such an increase shall be made within the first six business days of the quarter following the quarter in which the term of such registration reaches 12 reporting (tax) months.
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
Σ InvoiceType - the total amount of tax on tax invoices drawn up by the payer, registered in the Unified Register of Tax Invoices and adjustment calculations to such tax invoices, registered in the Unified Register of Tax Invoices;
{Paragraph eighteen of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
Σ Refund - the total amount of tax declared by the payer for budget refund, taking into account the amounts of adjustments and the results of inspections carried out in accordance with this Code;
{Paragraph of clause 200 - 1 .3 of article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
Σ Excess - the total amount of the excess of tax liabilities indicated by the payer in the submitted tax returns, taking into account the submitted clarifying calculations to them, over the amount of tax contained in the tax invoices drawn up by such payer and the adjustment calculations to such tax invoices registered in the Unified Register of Tax Invoices.
The indicators of the formula defined by this paragraph are calculated from July 1, 2015. When calculating the indicators Σ NaklOtr and Σ NaklVyd, adjustment calculations drawn up starting from July 1, 2015 and registered in the Unified Register of Tax Invoices are also used for tax invoices drawn up before July 1, 2015, which were subject to provision to buyers - taxpayers. For calculating the indicators Σ NaklOtr , Σ NaklVyd and Σ Mytn, documents (tax invoices, adjustment calculations, customs declarations, adjustment sheets and additional declarations) drawn up starting from July 1, 2015 are used.
{Clause 200 - 1 .3 of Article 200 - 1 is supplemented by a paragraph in accordance with Law No. 643-VIII of 16.07.2015 }
When calculating the amount Σ Nakl , the indicators defined in paragraphs 34 , 34-1 of subsection 2 of section XX "Transitional provisions" of this Code are also used .
{Clause 200 - 1 .3 of Article 200 - 1 supplemented by a paragraph in accordance with Law No. 643-VIII of 16.07.2015 ; as amended by Law No. 909-VIII of 24.12.2015 }
The amount of ∑ Taxpayer's tax liability of a taxpayer reorganized through a merger, acquisition, or transformation, formed at the time of state registration of the termination of a legal entity, is used when calculating the amount of ∑ Taxpayer's tax liability of the successor of such taxpayer.
{Clause 200 - 1 .3 of Article 200 - 1 is supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
The amount of ∑ Taxpayer's tax liability, reorganized by division (from which the separation is made), formed at the time of state registration of the termination of the legal entity of such payer (state registration of the creation of the legal entity of the successor), is used when calculating the amount of ∑ Taxpayer's tax liability of the successor of such taxpayer in proportion to the received share of property according to the distribution balance.
{Clause 200 - 1 .3 of Article 200 - 1 is supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
In the event of changes to the register of value added tax payers, by decision of a regulatory body or a court decision that has entered into legal force, regarding the cancellation (cancellation) of the cancellation of the registration of a value added tax payer, the amount of Σ Nakl of such a payer shall be recalculated for the reporting (tax) period in which the cancellation of the registration of the taxpayer, which is canceled (cancelled), took place.
{ Paragraph 200 - 1 .3 of Article 200 - 1 is supplemented by paragraph twenty-seven in accordance with the Law No. 466-IX dated 16.01.2020 }
Such recalculation shall be carried out by the supervisory authority within three working days following the day on which the supervisory authority makes changes to the register of value added tax payers regarding the cancellation of the registration of such payer, except in cases where, at the time of cancellation of the decision to cancel the registration, the person applies a simplified taxation system that does not provide for the payment of value added tax, or the re-registration (following the canceled one) of the taxpayer of such person is canceled on the grounds provided for in paragraph 184.1 of Article 184 of this Code.
{ Paragraph 200 - 1 .3 of Article 200 - 1 is supplemented by paragraph twenty-eight in accordance with the Law No. 466-IX dated 16.01.2020 }
200 - 1 .4. The following funds are credited to the payer's account in the electronic administration system of value added tax:
a) from the account with the bank/non-bank payment service provider of such payer in the amounts necessary to increase the amount calculated in accordance with clause 200 - 1.3 of Article 200 - 1 of this Code;
{Subparagraph "a" of paragraph 200 - 1 .4 of Article 200 - 1 as amended by Law No. 2245-VIII of 07.12.2017 }
b) from the account with a bank/non-bank payment service provider of such payer in amounts insufficient to pay the agreed tax liabilities for this tax to the budget;
{Subparagraph "b" of paragraph 200 - 1 .4 of Article 200 - 1 as amended by Law No. 2245-VIII of 07.12.2017 }
c) from payer accounts opened in the relevant treasury bodies for settlements to repay debts from the difference in tariffs for thermal energy, heating and hot water supply, centralized water supply, and wastewater services produced, transported, and supplied to the population and/or other centralized drinking water supply and wastewater enterprises that provide centralized water supply and wastewater services to the population, which arose due to the discrepancy between the actual cost of thermal energy and centralized water supply, wastewater, heating, and hot water supply services and the tariffs approved and/or agreed upon by state authorities or local self-government bodies, and the account of subventions from the state budget to local budgets with further allocation of funds in accordance with the Law of Ukraine on the State Budget of Ukraine;
{Clause 200 - 1 .4 of Article 200 - 1 is supplemented by subparagraph "c" in accordance with Law No. 643-VIII of 16.07.2015 }
d) from the budget in the amounts of overpaid monetary obligations for value added tax, returned to the taxpayer in accordance with the procedure established by Clause 43.4 - 1 of Article 43 of this Code;
{Clause 200 - 1 .4 of Article 200 - 1 is supplemented by subparagraph "d" in accordance with Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
e) withdrawn by the controlling authority in accordance with Clause 95.5 of Article 95 of this Code to repay the tax debt on value added tax on tax liabilities declared for payment for periods starting from July 1, 2015, specified by the taxpayer in the value added tax tax return or clarifying calculation.
{ Paragraph 200 - 1 .4 of Article 200 - 1 is supplemented by subparagraph "e" in accordance with the Law No. 466-IX dated 16.01.2020 ; as amended by Law No. 3553-IX dated 16.01.2024 }
200 - 1 .5. From the account in the electronic administration system of the payer's value added tax, funds are transferred to the state budget in the amount of tax liabilities on value added tax, payable as a result of the reporting tax period, and to the account in the bank/non-bank payment service provider of the taxpayer upon his application, which is submitted to the regulatory authority as part of the tax reporting on value added tax, in the amount of funds exceeding the amount of tax liabilities declared for payment to the budget and the amount of tax debt on the tax. At the same time, the transfer of funds to the account with the payer's bank/non-bank payment service provider may be carried out if the amount of tax indicated in the tax invoices drawn up in the reporting period and registered in the Unified Register of Tax Invoices does not exceed the amount of tax liabilities for transactions on the supply of goods/services declared in the tax reporting on value added tax in this reporting period.
{Paragraph one of clause 200 - 1 .5 of Article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
The funds received on the accounts specified in subparagraphs "a" - "c" of paragraph 200 - 1 .2 of this article shall be automatically transferred by the body carrying out treasury services of budget funds to the account of such payer in the electronic administration system of value added tax and to the special account of such payer during the next business day. The payer - an agricultural enterprise that has chosen a special taxation regime in accordance with Article 209 of this Code, is obliged to indicate the details of such a special account in the tax reporting on value added tax.
{Paragraph two of clause 200 - 1 .5 of Article 200 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
At the request of the taxpayer, he is provided with information about the movement of funds in his accounts in the electronic tax administration system by sending an electronic message.
{Clause 200 - 1 .5 of Article 200 - 1 as amended by Law No. 643-VIII of 16.07.2015 }
200 - 1 .6. Based on the results of the reporting tax period, in accordance with the results declared in the tax return, as well as in the case of submitting clarifying calculations to the tax return , the payer shall make a settlement with the budget in the manner specified in Articles 200 and 209 of this Code.
{Paragraph one of clause 200 - 1 .6 of Article 200 - 1 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 }
If, on the date of submission of the tax return, the amount of funds in the account in the electronic administration system of the value-added tax of the taxpayer exceeds the amount subject to transfer to the budget in accordance with the submitted reporting, the taxpayer has the right to submit to the regulatory authority, as part of such tax reporting, an application, according to which such funds are subject to transfer to the account in the bank/non-bank payment service provider of such taxpayer, the details of which the payer indicates in the application, in the amount of the balance of funds exceeding the amount of the tax debt and the amount of agreed tax liabilities.
{Paragraphs two - four of clause 200 - 1 .6 of Article 200 - 1 were replaced by one paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
The amount of tax that, according to the submitted application, is subject to transfer to the account with the payer's bank/non-bank payment service provider, at the time of submission of the application, the value of the tax amount determined by clause 200 - 1.3 of Article 200 - 1 of this Code is reduced by reducing by such amount the indicator of the total amount of account replenishment in the electronic tax administration system from the account with the payer's bank/non-bank payment service provider ( Σ PopRakh).
{Paragraph three of clause 200 - 1 .6 of Article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
The transfer of funds to the payer's bank/non-bank payment service provider account may be carried out if such a reduction in the total amount of electronic account replenishment ( ∑ PopRakh) does not result in a negative value of the tax amount determined in accordance with clause 200 - 1.3 of Article 200 - 1 of this Code ( ∑ Nakl).
{Paragraph 200 - 1 .6 of Article 200 - 1 is supplemented with a new paragraph in accordance with Law No. 909-VIII of 24.12.2015 }
For the appropriate transfer of such funds, the central executive body that ensures the implementation of tax and customs policy shall send to the central executive body that implements state policy in the field of treasury services of budget funds, in which payer accounts are opened in the system of electronic administration of value-added tax, a register indicating the name of the payer, tax number and individual tax number of the payer, the amount of tax to be transferred to the budget/to an account in a bank/non-bank payment service provider and the details of the account in the bank/non-bank payment service provider of the payer (in the case of submitting an application by the payer for a refund of funds to such an account).
{Paragraph five of clause 200 - 1 .6 of Article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
Based on such a register, the central executive body implementing state policy in the field of treasury services of budget funds, within five working days after the deadline established by this Code for the taxpayer to independently pay the amounts of tax liabilities, makes such a transfer to the budget/to the taxpayer's bank account/non-bank payment service provider.
{Paragraph six of clause 200 - 1 .6 of Article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
The central executive body implementing tax policy has the right to send to the central executive body implementing state policy in the field of treasury servicing of budget funds, in which payer accounts are opened in the electronic administration system of value added tax:
{Clause 200 - 1 .6 of Article 200 - 1 is supplemented by a paragraph in accordance with Law No. 643-VIII of 16.07.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
registers - for transferring tax to the budget in the event that the taxpayer submits clarifying calculations to tax returns ;
{Paragraph of clause 200 - 1 .6 of article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
corrective registers - to clarify information specified in previously sent registers.
{Paragraph of clause 200 - 1 .6 of article 200 - 1 as amended by Law No. 1797-VIII of 21.12.2016 }
200 - 1 .7. Funds credited to the payer's account in the electronic administration system for value added tax are funds used exclusively for the purposes specified in paragraph 200 - 1 .5 of Article 200 - 1 of this Code, and for the repayment of tax debt for value added tax.
{Clause 200 - 1 .7 of Article 200 - 1 as amended by Law No. 643-VIII of 16.07.2015 }
200 - 1 .8. After the cancellation of the taxpayer's registration, the balance of funds on his account in the electronic administration system of value-added tax is transferred to the budget, and such account is closed. The transfer of funds to the budget is carried out on the basis of the register, which the central executive body ensuring the implementation of tax and customs policy sends to the body carrying out treasury services of budget funds, in which the payers' accounts in the electronic administration system of value-added tax are opened, which indicates the name of the payer, tax number and individual tax number of the payer and the amount of tax to be transferred to the budget. On the basis of such a register, such body transfers the tax amounts to the budget.
200 - 1 .9. If the total amount of tax liabilities of a taxpayer, indicated by him in the submitted tax returns, taking into account the clarifying calculations to them, exceeds the amount of tax contained in the tax invoices drawn up by such taxpayer and the adjustment calculations to such tax invoices, registered in the Unified Register of Tax Invoices ( ∑ Excess), and the amount determined by paragraph 200 - 1.3 of Article 200 - 1 of this Code ( ∑ Incl . ), is insufficient for registration by such taxpayer of a tax invoice or calculation of an adjustment to such tax invoice for the reporting periods in which such excess occurs, the taxpayer has the right to register a tax invoice or calculation of an adjustment in the Unified Register of Tax Invoices for the amount of tax equal to the value of the indicator ∑ Excess, reduced by the amount of tax liabilities declared for payment for the periods starting from July 1, 2015 (including tax liabilities, which were paid by the taxpayer, and tax liabilities which were not paid by the taxpayer) and increased by the value of the indicator ∑ PopRah, regardless of the value of the indicator ∑ Nakl, determined in accordance with paragraph 200 - 1 .3 of this article.
The taxpayer has the right to register, in accordance with the procedure specified in the first paragraph of this paragraph, only tax invoices /calculations of adjustments to such tax invoices for reporting periods in which the tax liabilities indicated by the taxpayer in the submitted tax returns, taking into account the clarifying calculations to them, exceeded the amount of tax contained in the tax invoices drawn up by such taxpayer and the calculations of adjustments to such tax invoices registered in the Unified Register of Tax Invoices ( ∑ Excess).
{Paragraph two of item 200 - 1 .9 of Article 200 - 1 as amended by the Law No. 466-IX dated 16.01.2020 }
{Article 200 - 1 is supplemented by paragraph 200 - 1 .9 in accordance with Law No. 1797-VIII of 21.12.2016 }
{The Code is supplemented by Article 200 - 1 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 2888-IX of 12.01.2023 }
201.1. On the date of occurrence of tax liabilities, the taxpayer is obliged to draw up a tax invoice in electronic form using a qualified electronic signature or an advanced electronic signature based on a qualified electronic signature certificate of a person authorized by the payer in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services" and register it in the Unified Register of Tax Invoices within the period established by this Code.
{Paragraphs one - three of clause 201.1 of Article 201 are replaced by one paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 643-VIII of 16.07.2015 ; as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Laws No. 2725-VIII dated 05/16/2019 , No. 2918-IX dated 02/07/2023 }
The tax invoice contains the following mandatory details in separate lines:
{Paragraph of Clause 201.1 of Article 201 as amended by Law No. 4834-VI of 05/24/2012 }
a) serial number of the tax invoice;
{Paragraph of Clause 201.1 of Article 201 as amended by Law No. 4834-VI of 05/24/2012 }
b) date of preparation of the tax invoice;
{Paragraph four of clause 201.1 of Article 201 as amended by Law No. 1797-VIII of 21.12.2016 }
c) full or abbreviated name specified in the statutory documents of a legal entity or the surname, first name and patronymic of an individual registered as a value added tax payer - the seller of goods/services;
d) tax number of the taxpayer (seller and buyer). In the case of supply/purchase of goods/services by a branch (structural unit), which is actually a party to the contract on behalf of the main enterprise - the taxpayer, the tax invoice, in addition to the tax number of the taxpayer, additionally indicates the numerical number of such branch (structural unit);
{Subparagraph "d" of paragraph 201.1 of Article 201 as amended by Law No. 643-VIII of July 16, 2015 }
{Subparagraph "g" of paragraph 201.1 of Article 201 was excluded on the basis of Law No. 643-VIII of July 16, 2015 }
e) full or abbreviated name specified in the statutory documents of a legal entity or the surname, first name and patronymic of an individual registered as a value added tax payer - the buyer (recipient) of goods/services;
f) description (nomenclature) of goods/services and their quantity, volume. The tax invoice drawn up for operations on the export of goods outside the customs territory of Ukraine shall indicate the units of measurement of goods that are used when drawing up a customs declaration for such goods;
{Subparagraph "e" of paragraph 201.1 of Article 201 as amended by the Law No. 3706-IX dated 09.05.2024 }
h) supply price excluding tax;
g) tax rate and corresponding tax amount in numerical value;
h) the total amount of funds payable, including tax;
{Sub-paragraph "i" of paragraph 201.1 of Article 201 was excluded on the basis of Law No. 643-VIII of 16.07.2015 }
i) the product code according to the UKT FEA , for services - the service code according to the State Classifier of Products and Services ; taxpayers, except for the supply of excisable goods and goods imported into the customs territory of Ukraine, have the right to indicate the product code according to the UKT FEA or the service code according to the State Classifier of Products and Services in full, but not less than the first four digits of the corresponding code;
{Clause 201.1 of Article 201 is supplemented by subparagraph "i" in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 1797-VIII of 21.12.2016 }
{Sub -paragraph "i" of paragraph 201.1 of Article 201 was excluded on the basis of Law No. 657-VII of 24.10.2013 }
j) individual tax number;
{ Paragraph 201.1 of Article 201 is supplemented by subparagraph "y" in accordance with the Law No. 2628-VIII dated 23.11.2018 }
k) the date and number of the customs declaration are indicated in the event that the payer draws up a tax invoice for operations involving the export of goods outside the customs territory of Ukraine;
{ Paragraph 201.1 of Article 201 is supplemented with subparagraph "k" in accordance with the Law No. 3706-IX dated 09.05.2024 }
l) the date and number of the agreement (contract) shall be indicated in the event that the payer draws up a tax invoice for operations on the export of goods outside the customs territory of Ukraine. The tax invoice drawn up for operations on the export of goods outside the customs territory of Ukraine on the basis of a forward contract shall contain a corresponding note on the forward contract.
{ Paragraph 201.1 of Article 201 is supplemented with subparagraph "l" in accordance with the Law No. 3706-IX dated 09.05.2024 }
{Clause 201.1 of Article 201 as amended by Law No. 1621-VII of July 31, 2014, taking into account the amendments made by Law No. 71-VIII of December 28, 2014 }
201.2. The form and procedure for filling out a tax invoice are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 201.2 of Article 201 as amended by Law No. 1797-VIII of 21.12.2016 }
201.3. In the case of exemption from taxation, the entry "Without VAT" shall be made in the tax invoice with reference to the relevant paragraphs (subparagraphs), articles, subsections, sections of this Code and/or international agreement that provide for exemption from taxation.
{Clause 201.3 of Article 201 as amended by Law No. 1797-VIII of 21.12.2016 }
201.4. {Paragraph one of item 201.4 of Article 201 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
Taxpayers in the event of the supply of goods/services during the period for which such a tax invoice is drawn up, the supply of which is continuous or rhythmic in nature:
{Paragraph two of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 ; as amended by Law No. 909-VIII dated 24.12.2015 }
Buyers - taxpayers - may prepare, no later than the last day of the month in which such supplies were made, consolidated tax invoices for each taxpayer with whom supplies are of such nature during the period for which such tax invoice is prepared, taking into account the entire volume of supplies of goods/services to the relevant taxpayer during such month;
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 ; as amended by Law No. 909-VIII dated 24.12.2015 }
buyers - persons not registered as taxpayers - may draw up, no later than the last day of the month in which such supplies were made, a consolidated tax invoice taking into account the entire volume of supplies of goods/services to such buyers with whom the supplies are of such nature, during such month.
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 }
If, as of the date of preparation of the specified tax invoices, the amount of funds received on the account with the seller's bank/non-bank payment service provider as payment (prepayment) for goods/services exceeds the cost of goods/services delivered during the month, such excess is considered a preliminary payment (advance payment), for the amount of which a tax invoice is prepared in the general manner no later than the last day of such month.
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 }
For the purposes of this paragraph, the rhythmic nature of supply is considered to be the supply of goods/services to one buyer two or more times a month.
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 }
A tax invoice may be drawn up based on daily transaction summaries (if a tax invoice was not drawn up for these transactions) in the following cases:
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 }
the supply of goods/services for cash to the final consumer (who is not a taxpayer), payments for which are made through a cash register/registers of settlement transactions and/or software registers of settlement transactions, or through a bank, non-bank payment service provider or payment device (directly to the supplier's account);
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 ; paragraph eight of clause 201.4 of article 201 as amended by Law No. 129-IX dated 20.09.2019 ; as amended by Law No. 2888-IX dated 12.01.2023 }
statements of transport tickets, hotel bills or bills issued to the taxpayer for communication services, other services, the cost of which is determined by the indicators of metering devices, containing the total amount of payment, the amount of tax and the tax number of the supplier (seller), except for those whose form is established by international standards;
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 }
providing the taxpayer with cash receipts containing the amount of goods/services supplied and the total amount of tax charged (with the identification of the supplier's fiscal and tax numbers).
{Paragraph of item 201.4 of Article 201 as amended by the Law No. 643-VIII dated 16.07.2015 }
Taxpayers, in the event of the supply of goods/services, the tax base of which, determined in accordance with Articles 188 and 189 of this Code, exceeds the actual price of the supply of such goods/services, may draw up, no later than the last day of the month in which such supplies were made, a consolidated tax invoice taking into account the tax amounts calculated based on the excess of the tax base over the actual price, determined separately for each transaction for the supply of goods/services.
{Clause 201.4 of Article 201 is supplemented by paragraph eleven in accordance with Law No. 1797-VIII of 21.12.2016 }
{Clause 201.4 of Article 201 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1621-VII of 07/31/2014, taking into account the amendments made by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 71-VIII of 12/28/2014 }
201.5. Separate tax invoices shall be prepared for taxable transactions and transactions exempt from taxation.
{Clause 201.6 of Article 201 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
201.7. A tax invoice is drawn up for each full or partial supply of goods/services, as well as for the amount of funds received on an account with a bank/non-bank payment service provider as a prepayment (advance payment).
{Paragraph one of clause 201.7 of Article 201 as amended by Law No. 4834-VI of 24.05.2012 }
If the share of goods/services does not contain a separate value, the list (nomenclature) of partially delivered goods/services is indicated in the appendix to the tax invoice in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy, and is taken into account when determining general tax liabilities.
{Clause 201.7 of Article 201 as amended by Law No. 1797-VIII of 21.12.2016 }
201.8. The right to charge tax and prepare tax invoices is granted exclusively to persons registered as tax payers in accordance with the procedure provided for in Article 183 of this Code.
201.9. A tax invoice drawn up by a payer exempted from paying tax by a court decision after such a court decision enters into force does not give the right to attribute tax amounts to a tax credit.
{Clause 201.9 of Article 201 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 }
201.10. {Amendments to paragraph 201.10 of Article 201 by Law No. 1797-VIII of 21.12.2016 in terms of suspension of registration of tax invoices/calculations, adjustments in the Unified Register of Tax Invoices shall enter into force on 01.04.2017, see paragraph five of clause 1 of section II of Law No. 1797-VIII of 21.12.2016} When carrying out transactions for the supply of goods/services, the taxpayer - the seller of goods/services is obliged to draw up a tax invoice within the established time limits, register it in the Unified Register of Tax Invoices and provide it to the buyer upon his request.
{Paragraph one of clause 201.10 of Article 201 as amended by Law No. 71-VIII of 28.12.2014 }
A tax invoice drawn up and registered in the Unified Register of Tax Invoices by a taxpayer who carries out transactions for the supply of goods/services is, for the buyer of such goods/services, the basis for calculating the tax amounts related to the tax credit.
{Paragraph two of clause 201.10 of Article 201 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 71-VIII of 12/28/2014 }
A tax invoice and/or calculation of adjustments to it, drawn up and registered after July 1, 2017 in the Unified Register of Tax Invoices by a taxpayer carrying out transactions for the supply of goods/services, is a sufficient basis for the purchaser of such goods/services to calculate the tax amounts related to the tax credit and does not require any other additional confirmation.
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
Tax invoices that are not provided to the buyer, as well as tax invoices drawn up for transactions for the supply of goods/services that are exempt from taxation, are subject to registration in the Unified Register of Tax Invoices.
{Paragraph of clause 201.10 of Article 201 as amended by Law No. 71-VIII of 12/28/2014 }
Confirmation to the seller of the acceptance of his tax invoice and/or adjustment calculation to the Unified Register of Tax Invoices is an electronic receipt in text format, which is sent during the operating day.
In order to receive a tax invoice/adjustment calculation registered in the Unified Register of Tax Invoices, the buyer sends an electronic request to the Unified Register of Tax Invoices, after which he receives an electronic notification of the registration of the tax invoice/adjustment calculation in the Unified Register of Tax Invoices and the tax invoice/adjustment calculation in electronic form. Such a tax invoice/adjustment calculation is considered registered in the Unified Register of Tax Invoices and received by the buyer.
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 }
The buyer of goods/services may be provided with a tax invoice/adjustment calculation by the seller of such goods/services in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 ; as amended by Law No. 2725-VIII of 16.05.2019 }
In order for the seller to receive the adjustment calculation registered in the Unified Register of Tax Invoices, which is subject to registration in the Unified Register of Tax Invoices by the buyer, such seller sends an electronic request to the Unified Register of Tax Invoices, after which he receives an electronic notification about the registration of the adjustment calculation in the Unified Register of Tax Invoices and the adjustment calculation in electronic form. Such an adjustment calculation is considered registered in the Unified Register of Tax Invoices and received by the seller.
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 }
The date and time of submission of the tax invoice and/or adjustment calculation in electronic form to the central executive body implementing state tax policy is the date and time recorded on the receipt.
{Paragraph of Clause 201.10 of Article 201 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
If the sent tax invoices /adjustment calculations were generated in violation of the requirements stipulated in paragraph 201.1 of this Article and/or paragraph 192.1 of Article 192 of this Code, as well as in the event of suspension of registration of the tax invoice/adjustment calculation in accordance with paragraph 201.16 of this Article, during the business day the seller/buyer shall be sent an electronic receipt in text format stating their non-acceptance in electronic form or suspension of their registration, indicating the reasons.
{Paragraph 201.10 of Article 201 as amended by the Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
Errors in the details specified in paragraph 201.1 of this article (except for the product code in accordance with the Ukrainian Code of Foreign Economic Activities ), which do not prevent the identification of the transaction performed, its content (goods/services supplied), period, parties and amount of tax liabilities, cannot be the reason for non-acceptance of tax invoices in electronic form.
{Paragraph of clause 201.10 of Article 201 as amended by Law No. 1797-VIII of 21.12.2016 }
The receipt for stopping the registration of the tax invoice /adjustment calculation is sent simultaneously to the seller and the buyer who is a taxpayer.
{Paragraph of clause 201.10 of Article 201 as amended by Law No. 1797-VIII of 12/21/2016 }
If no receipt is sent during the business day regarding acceptance or rejection, or suspension of registration of a tax invoice /adjustment calculation, such tax invoice is considered registered in the Unified Register of Tax Invoices.
{Paragraph thirteen of clause 201.10 of Article 201 as amended by the Law No. 1797-VIII dated 21.12.2016 }
Registration of tax invoices and/or adjustment calculations to tax invoices in the Unified Register of Tax Invoices must be carried out taking into account the following deadlines:
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 3609-VI of 07.07.2011 ; as amended in accordance with Laws No. 4834-VI of 05.24.2012 ; as amended by Laws No. 909-VIII of 12.24.2015 , No. 1797-VIII of 12.21.2016 }
for tax invoices /calculations of adjustments to tax invoices drawn up from the 1st to the 15th calendar day (inclusive) of a calendar month - until the last day (inclusive) of the calendar month in which they were drawn up;
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
for tax invoices /calculations of adjustments to tax invoices drawn up from the 16th to the last calendar day (inclusive) of a calendar month - by the 15th calendar day (inclusive) of the calendar month following the month in which they were drawn up;
{Paragraph of clause 201.10 of Article 201 as amended by Law No. 1797-VIII of 21.12.2016 }
for consolidated tax invoices and/or adjustment calculations to such consolidated tax invoices drawn up for transactions specified in Clause 198.5 of Article 198 and Clause 199.1 of Article 199 of this Code - within 20 calendar days following the last calendar day of the month in which they were drawn up;
{ Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
for adjustment calculations made by the supplier of goods/services to the tax invoice drawn up for the recipient - the taxpayer, which provide for a reduction in the amount of compensation for the cost of goods/services to their supplier - within 15 calendar days from the date of receipt of such adjustment calculation to the tax invoice by the recipient (buyer).
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
In case of violation of such deadlines, penalties shall be applied in accordance with this Code.
{Paragraph of clause 201.10 of Article 201 as amended by Law No. 1797-VIII of 12/21/2016 }
The taxpayer has the right to register in the Unified Register of Tax Invoices a tax invoice and/or adjustment calculation drawn up starting from July 1, 2015, in which the total amount of tax does not exceed the amount calculated in accordance with clause 200 - 1.3 of Article 200 - 1 of this Code.
{Paragraph of clause 201.10 of Article 201 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2198-VIII of 11/09/2017 }
If the amount determined in accordance with paragraph 200 - 1.3 of Article 200 - 1 of this Code is less than the amount of tax in the tax invoice and/or the calculation of adjustments that the payer must register in the Unified Register of Tax Invoices, the payer is obliged to transfer the required amount of funds from his account with a bank/non-bank payment service provider to his account in the electronic administration system of value added tax.
{Clause 201.10 of Article 201 is supplemented with a new paragraph in accordance with Law No. 71-VIII of 28.12.2014 }
The procedure for maintaining the Unified Register of Tax Invoices is established by the Cabinet of Ministers of Ukraine. The buyer has the right to verify the data of the received tax invoice for compliance with the data of the Unified Register of Tax Invoices.
The absence of registration by the taxpayer - seller of goods/services of tax invoices in the Unified Register of Tax Invoices does not entitle the buyer to include the amounts of value added tax in the tax credit and does not exempt the seller from the obligation to include the amount of value added tax indicated in the tax invoice in the amount of tax liabilities for the relevant reporting period.
{Paragraph of Clause 201.10 of Article 201 as amended by Laws No. 4834-VI of 05/24/2012 , No. 643-VIII of 07/16/2015 , No. 909-VIII of 12/24/2015 }
The detection of discrepancies between the data of the tax declaration and the data of the Unified Register of Tax Invoices is the basis for the regulatory authorities to conduct an unscheduled documentary on-site inspection of the seller and, in appropriate cases, the buyer of goods/services.
{Paragraph of clause 201.10 of Article 201 as amended by Law No. 1621-VII of 31.07.2014 , taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 71-VIII of 28.12.2014 }
In the event that the seller of goods/services makes errors when indicating the mandatory details of the tax invoice , provided for in paragraph 201.1 of Article 201 of this Code, and/or the seller/buyer violates the deadlines for registering the tax invoice and/or adjustment calculation in the Unified Register of Tax Invoices (except for tax invoices/adjustment calculations, the registration of which is suspended in accordance with paragraph 201.16 of this Article), the buyer/seller of such goods/services has the right to add a statement with a complaint against such seller/buyer to the tax return for the reporting tax period. This right is retained by him for 365 calendar days following the deadline for submitting a tax return for the reporting (tax) period in which a tax invoice was not submitted or an error was made when specifying the mandatory details of the tax invoice and/or the deadlines for registration in the Unified Register of Tax Invoices were violated. The application shall be accompanied by copies of documents certifying the fact of payment of tax in connection with the purchase of such goods/services, or copies of primary documents drawn up in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", confirming the fact of receipt of such goods/services.
{Paragraph of Clause 201.10 of Article 201 as amended by Laws No. 3609-VI dated 07.07.2011 , No. 657-VII dated 10.24.2013 , No. 1621-VII dated 07.07.2014, taking into account the amendments made by Law No. 71-VIII dated 12.28.2014 ; as amended by Laws No. 71-VIII dated 12.28.2014 , No. 643-VIII dated 07.16.2015 ; as amended by Law No. 909-VIII dated 12.24.2015 ; as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2888-IX of 01/12/2023 }
Within 90 calendar days from the date of receipt of such a statement with a complaint, taking into account the requirements established by subparagraph 78.1.9 of paragraph 78.1 of Article 78 of this Code, the regulatory authority is obliged to conduct a documentary audit of the specified seller to determine the accuracy and completeness of his calculation of tax liabilities for such a transaction.
{Paragraph of clause 201.10 of Article 201 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 }
{Paragraph 201.10 of Article 201 is excluded on the grounds Law No. 1797-VIII of 21.12.2016 }
{Amendments to paragraph 201.10 of Article 201 by Law No. 1797-VIII of 21.12.2016 regarding the suspension of registration of tax invoices/calculations, adjustments in the Unified Register of Tax Invoices shall enter into force on 01.04.2017, see paragraph five of clause 1 of section II of Law No. 1797-VIII of 21.12.2016}
201.11. The basis for calculating tax amounts related to a tax credit without receiving a tax invoice is also:
a) a transport ticket, hotel bill or bill issued to a taxpayer for communication services, other services, the cost of which is determined by the indicators of metering devices, containing the total amount of payment, the amount of tax and the seller's tax number, except for those whose form is established by international standards;
b) cash receipts containing the amount of goods/services received, the total amount of tax charged (with the identification of the fiscal number and tax number of the supplier). However, for the purpose of such charging, the total amount of goods/services received cannot exceed 200 hryvnias per day (excluding tax).
In the case of using payment transaction registrars and/or software payment transaction registrars by payers for settlements with consumers, the cash receipt must contain data on the total amount of funds payable by the buyer, including tax, and the amount of this tax paid as part of the total amount.
{ Paragraph two of subparagraph "b" of paragraph 201.11 of Article 201 as amended by the Law No. 129-IX dated 20.09.2019 }
The procedure for calculating and accumulating tax amounts by the registrars of settlement transactions and the fiscal server of the controlling body is established by the Cabinet of Ministers of Ukraine;
{Paragraph three of subparagraph "b" of paragraph 201.11 of Article 201 as amended by Laws No. 3609-VI of 07.07.2011 , No. 129-IX of 20.09.2019 }
c) accounting certificate drawn up in accordance with clause 36 of subsection 2 of section XX of this Code;
{Clause 201.11 of Article 201 is supplemented by subparagraph "c" in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Law No. 71-VIII dated 28.12.2014 }
d) a tax invoice drawn up by the taxpayer in accordance with Clause 208.2 of Article 208 of this Code and registered in the Unified Register of Tax Invoices.
{Clause 201.11 of Article 201 is supplemented by subparagraph "d" in accordance with Law No. 71-VIII of 28.12.2014 }
201.11 - 1. The taxpayer shall keep a register of documents specified in subparagraphs "a" - "c" of paragraph 201.11 of this article.
{Article 201 is supplemented by paragraph 201.11 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
201.12. In the case of import of goods into the customs territory of Ukraine, a document certifying the right to attribute tax amounts to a tax credit is a customs declaration, drawn up in accordance with the requirements of the legislation, confirming the payment of tax.
For transactions involving the supply of services by a non-resident in the customs territory of Ukraine, a document certifying the right to attribute tax amounts to a tax credit is a tax invoice drawn up by the payer for such transactions and registered in the Unified Register of Tax Invoices, the tax obligations for which are included in the tax declaration for the relevant reporting period.
{Paragraph 201.12 of Article 201 as amended by the Law No. 71-VIII dated 28.12.2014 }
201.13. For individuals not registered as business entities importing goods (items) into the customs territory of Ukraine in amounts subject to taxation in accordance with the legislation, the completion of a customs declaration is equivalent to the submission of a tax invoice .
201.14. Taxpayers are required to keep separate records of transactions for the supply and purchase of goods/services that are subject to taxation, as well as those that are not subject to taxation and are exempt from taxation in accordance with this section.
201.15. The summarized results of such accounting shall be reflected in tax declarations , the form of which shall be established in accordance with the procedure provided for in Article 46 of this Code.
{Clause 201.15 of Article 201 as amended by Law No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; as amended by the Law No. 71-VIII dated 28.12.2014 }
201.16. Registration of a tax invoice /adjustment calculation in the Unified Register of Tax Invoices may be suspended in accordance with the procedure and on the grounds determined by the Cabinet of Ministers of Ukraine.
{Article 201 is supplemented by paragraph 201.16 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
{Text of Article 201 as amended by Law No. 2888-IX of 12.01.2023 }
202.1. The reporting (tax) period is one calendar month, taking into account the following features:
{Paragraph one of clause 202.1 of Article 202 as amended by Law No. 466-IX of January 16, 2020 }
a) if a person is registered as a taxpayer on a day other than the first day of a calendar month, the first reporting (tax) period is the period that begins on the day of such registration and ends on the last day of the first full calendar month;
b) if the tax registration of a person is canceled on a day other than the last day of a calendar month, then the last reporting (tax) period is the period that begins on the first day of such month and ends on the day of such cancellation.
{Clause 202.2 of Article 202 was excluded pursuant to Law No. 466-IX of January 16, 2020 }
Article 203. Procedure for submitting a tax return and deadlines for payments to the budget↑
203.1. A tax return is submitted for the basic reporting (tax) period, which is equal to a calendar month, within 20 calendar days following the last calendar day of the reporting (tax) month.
203.2. The amount of tax liability indicated by the taxpayer in the tax return submitted by him shall be payable within 10 calendar days following the last day of the relevant deadline provided for in paragraph 203.1 of this Article for submitting a tax return.
{Clause 203.2 of Article 203 as amended by Law No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; with the amendments made in accordance with the Law No. 71-VIII dated 28.12.2014 }
{Article 204 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
{Article 205 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
Article 206. Peculiarities of taxation of transactions during the movement of goods across the customs border of Ukraine depending on the chosen customs regime↑
206.1. When importing goods into the customs territory of Ukraine, tax amounts are subject to payment to the state budget by taxpayers before/or on the day of submission of the customs declaration directly to the single treasury account, except for transactions for which exemption (conditional exemption) from taxation is granted.
206.2. Operations involving the import of goods into the customs territory of Ukraine under the customs regime of import shall be taxed at the rate determined by subparagraph 194.1.1 of paragraph 194.1 of Article 194 of this Code, except for operations:
206.2.1. on the import of goods exempt from taxation in accordance with Article 197 and Subsection 2 of Section XX of this Code, as well as in accordance with international treaties ratified by the Verkhovna Rada of Ukraine;
206.2.2. from the import with exemption from taxation of goods that were placed under the customs regime of processing outside the customs territory of Ukraine and are returned to the customs territory of Ukraine within the period specified by the Customs Code of Ukraine :
in the same condition in which they were exported outside the customs territory of Ukraine, in compliance with the conditions established by the Customs Code of Ukraine;
in a repaired form, if the repair was carried out within the framework of warranty obligations;
206.2.3. from the import with partial exemption from taxation of goods that were placed:
under the customs regime of processing outside the customs territory of Ukraine (except for those specified in clause 206.2.2 of this Article) and within the period specified by the Customs Code of Ukraine are returned to the customs territory of Ukraine. The positive difference between the amounts of tax calculated based on the tax base of processed products and the tax base of goods exported outside the customs territory of Ukraine for processing, determined in accordance with the rules established by clause 190.1 of Article 190 of this Code, shall be payable;
under the customs regime of processing in the customs territory of Ukraine and within the period specified by the Customs Code of Ukraine are not exported outside the customs territory of Ukraine. The amount of tax calculated based on the tax base determined in accordance with the rules established by Clause 190.1 of Article 190 of this Code, goods imported into the customs territory of Ukraine for processing, shall be subject to payment.
206.3. Operations on the import of goods under the customs regime of re-import are exempt from taxation, except for import operations in accordance with clause 3 of part two of Article 78 of the Customs Code of Ukraine , which are subject to tax at the rate determined by subparagraph 194.1.1 of clause 194.1 of Article 194 of this Code.
206.4. Operations for the export of goods under the customs regime of export are taxed at the rate determined by subparagraph 195.1.1 of paragraph 195.1 of Article 195 of this Code.
206.5. Operations for the export of goods under the customs regime of re-export are exempt from taxation, except for operations for export in accordance with paragraphs 3 (regarding goods in the form of products of their processing) and 5 of part one of Article 86 of the Customs Code of Ukraine, which are subject to tax at the rate determined by subparagraph 195.1.1 of paragraph 195.1 of Article 195 of this Code.
{Paragraph 206.5 of Article 206 as amended by the Law No. 2497-VIII dated 10.07.2018 }
206.6. Conditional full exemption from taxation shall apply to operations involving the import of goods under the customs transit regime, provided that the requirements and restrictions established by Chapter 17 of the Customs Code of Ukraine are met .
206.7. Conditional full exemption from taxation or conditional partial exemption from taxation shall apply to operations involving the import of goods into the customs territory of Ukraine under the customs regime of temporary importation, provided that the requirements and restrictions established by Chapter 18 of the Customs Code of Ukraine are met :
206.7.1. conditional full exemption from taxation shall apply to goods and in the manner specified in Article 105 of the Customs Code of Ukraine ;
206.7.2. conditional partial exemption from taxation shall be applied to goods and in the manner specified in Article 106 of the Customs Code of Ukraine . The tax amounts paid shall be included by the payer in the tax credit in the reporting (tax) period in which the tax was paid.
206.8. Conditional full exemption from taxation shall apply to operations for the export of goods outside the customs territory of Ukraine under the customs regime of temporary export, provided that the requirements and restrictions established by Chapter 19 of the Customs Code of Ukraine are met .
206.9. Conditional full exemption from taxation shall apply to operations on the export of goods from the customs territory of Ukraine to a customs warehouse and operations on the import of goods from outside the customs territory of Ukraine to a customs warehouse, provided that the requirements and restrictions established by Chapter 20 of the Customs Code of Ukraine are met .
206.10. Transactions with goods placed under the customs regime of a free customs zone are taxed in the following order:
206.10.1. operations on the export of goods from the customs territory of Ukraine to a free customs zone are taxed at the rate determined by subparagraph 195.1.1 of paragraph 195.1 of Article 195 of this Code;
206.10.2. Conditional full exemption from taxation shall apply to operations involving the import of goods from outside the customs territory of Ukraine to a free customs zone, provided that the requirements and restrictions established by Chapter 21 of the Customs Code of Ukraine are met ;
206.10.3. operations on the import into the customs territory of Ukraine of products of processing of goods placed under the customs regime of a free customs zone shall be taxed at the rate determined by subparagraph 194.1.1 of paragraph 194.1 of Article 194 of this Code, and by the payment of interest that would be payable in the event of installments or deferral of tax payment in accordance with Article 100 of this Code.
206.11. Transactions with goods placed under the customs regime of duty-free trade are taxed in the following order:
206.11.1. Conditional full exemption from taxation shall apply to operations involving the import of goods from outside the customs territory of Ukraine into a duty-free shop, provided that the requirements and restrictions established by Chapter 22 of the Customs Code of Ukraine are met ;
206.11.2. operations for the export of goods from the customs territory of Ukraine to a duty-free shop are taxed in accordance with subparagraph 195.1.1 of paragraph 195.1 of Article 195 of this Code.
206.12. Conditional full exemption from taxation shall apply to operations involving the import of goods into the customs territory of Ukraine under the customs regime of inward processing, provided that the requirements and restrictions established by Chapter 23 of the Customs Code of Ukraine are met .
206.13. Conditional full exemption from taxation shall apply to operations for the export of goods from the customs territory of Ukraine under the customs regime of processing outside the customs territory, provided that the requirements and restrictions established by Chapter 24 of the Customs Code of Ukraine are met .
206.14. Conditional full exemption from taxation shall apply to operations for the import of goods under the customs regime of destruction or destruction, provided that the requirements and restrictions established by Chapter 25 of the Customs Code of Ukraine are met .
206.15. Operations on the import of goods under the customs regime of refusal in favor of the state in accordance with the procedure specified in Chapter 26 of the Customs Code of Ukraine are exempt from tax.
206.16. In the event of loss of goods under customs control in customs regimes in which exemption or conditional exemption from taxation has been granted, misuse of these goods, or failure to take measures to terminate such customs regimes within the time limits established by the Customs Code of Ukraine , the person responsible for compliance with the customs regime shall be obliged to pay the amount of the tax liability for which such exemption or conditional exemption was granted, and the penalty accrued in accordance with Article 129 of this Code, calculated from the date of granting the exemption or conditional exemption from taxation.
{Article 206 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 4915-VI of 07.06.2012 }
Article 207. Procedure for taxation of tour operator and travel agent activities↑
207.1. This article establishes the features of taxation of a tourist product (tourist service) provided by a tourist operator and a travel agent in accordance with the legislation. A tourist product, as a complex of tourist services, is considered as a single service for taxation purposes.
207.2. The tax base in the case of transactions for the supply by a tourist operator of a tourist product (tourist service) intended for its consumption (receipt) on the territory of Ukraine is the remuneration, which is defined as the difference between the cost of the tourist product (tourist service) supplied by it and the cost of expenses incurred by such a tourist operator as a result of the acquisition (creation) of such a tourist product (tourist service).
207.3. The tax base in the case of operations for the supply in the territory of Ukraine by a tourist operator of a tourist product (tourist service) intended for its consumption (receipt) outside the territory of Ukraine is the remuneration, which is defined as the difference between the cost of the tourist product (tourist service) supplied by him and the cost of expenses incurred by such a tourist operator as a result of the acquisition (creation) of such a tourist product (tourist service).
207.4. The tax base of a tour operator that carries out intermediary activities in the territory of Ukraine for concluding tourist service contracts with foreign entities of tourist activity is the remuneration that is accrued (paid) to it by such foreign entity of tourist activity, including by granting the right to independently withhold the amount of remuneration due to such tour operator from the funds paid by the customer (consumer) of tourist services.
207.5. The tax base for transactions carried out by a travel agent is the remuneration accrued (paid) by the travel operator and other service providers in favor of such travel agent, including at the expense of funds received by the latter from the consumer of the travel product (travel service).
{Clause 207.5 of Article 207 as amended by Law No. 4834-VI of 24.05.2012 }
207.6. Tax amounts paid (accrued) upon purchase of goods/services that are included in the cost of a tourist product (tourist service) do not apply to a tax credit and are not included in the tax base of the tour operator.
Tax amounts paid (accrued) upon purchase of goods/services that are not included in the cost of a tourist product (tourist service) are included in the tax credit in accordance with the procedure specified by this Code.
The date of occurrence of tax liabilities for a tour operator upon supply of a tourist product (tourist service) is the date of execution of the document certifying the fact of supply of the tourist product (tourist service).
The date of the right to attribute tax amounts to the tour operator's tax credit when purchasing goods/services that are not included in the cost of the tour product (tourist service) is the date of receipt of the goods/services, confirmed by the tax invoice.
{Clause 207.6 of Article 207 as amended by Law No. 4834-VI of 05/24/2012 }
207.7. The tax rate specified in subparagraph "a" of paragraph 193.1 of Article 193 of this section shall be applied to the tax base determined in accordance with paragraphs 207.2-207.5 of this Article.
{Article 207 as amended by Law No. 3609-VI of 07.07.2011 }
Article 208. Taxation of services supplied by non-residents, the place of supply of which is located in the customs territory of Ukraine↑
208.1. This article establishes the rules for taxation in the event of the supply by a non-resident of services, including electronic services, the place of provision of which is located in the customs territory of Ukraine, to a person registered as a taxpayer, or to any other resident person - a business entity, or a permanent establishment of a non-resident in Ukraine.
The rules of this article do not apply in the case of the supply of electronic services by a non-resident person registered as a taxpayer in accordance with clause 208-1.2 of Article 208-1 of this Code to an individual entrepreneur who is not registered as a taxpayer.
{Clause 208.1 of Article 208 as amended by Laws No. 466-IX of 01/16/2020 , No. 1525-IX of 06/03/2021 }
208.2. The recipient of services supplied by non-residents, the place of supply of which is located in the customs territory of Ukraine, shall charge tax at the basic tax rate or at the rate of 7 percent for services specified in paragraphs four to six of subparagraph "c" of paragraph 193.1 of Article 193 of this Code, on the tax base determined in accordance with paragraph 190.2 of Article 190 of this Code.
{Paragraph one of clause 208.2 of Article 208 as amended by Law No. 962-IX of 04.11.2020 }
In this case, the recipient of services - the taxpayer, in accordance with the procedure specified in Article 201 of this Code, shall draw up a tax invoice indicating the amount of tax charged by him, which is the basis for attributing the tax amounts to the tax credit in accordance with the established procedure.
Such a tax invoice is subject to mandatory registration in the Unified Register of Tax Invoices.
{Paragraph three of clause 208.2 of Article 208 as amended by Law No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; as amended by the Law No. 71-VIII dated 28.12.2014 }
208.3. If the recipient of services is registered as a taxpayer, the amount of tax charged is included in the tax liabilities of the declaration for the relevant reporting period.
208.4. If the recipient of services is not registered as a taxpayer, then a tax invoice is not drawn up. The form for calculating the tax obligations of such a recipient of services is approved by the central executive body that ensures the formation and implementation of state financial policy."
{Clause 208.4 of Article 208 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
208.5. The recipient of services is equated with the taxpayer for the purposes of applying the rules of this section regarding the payment of tax, collection of tax debt and prosecution for tax offenses.
208.5 - 1. A document confirming the fact of the provision of electronic services by a non-resident is any document confirming the fact of payment for the cost of such services, including one sent in electronic form by means of electronic communication.
{ Article 208 is supplemented by paragraph 208.5 - 1 in accordance with the Law No. 1525-IX dated 03.06.2021 }
208.6. The provisions of this article do not apply to the supply by a non-resident person who is not registered as a taxpayer of services for the preparation for the removal and removal of the power units of the Chernobyl NPP from operation and the transformation of the "Shelter" facility into an environmentally safe system, the financing of which is carried out at the expense of international technical assistance funds provided on a gratuitous and non-refundable basis, in accordance with the provisions of the Framework Agreement between Ukraine and the European Bank for Reconstruction and Development on the activities of the Chernobyl Shelter Fund in Ukraine and the Grant Agreement (Chernobyl NPP Nuclear Safety Project) between the European Bank for Reconstruction and Development as the Administrator of funds provided under the Grant from the Nuclear Safety Account, the Government of Ukraine and the Chernobyl Nuclear Power Plant .
{Article 208 was supplemented by paragraph 208.6 in accordance with Law No. 3609-VI of 07.07.2011 }
208.7. The provisions of this article do not apply to the supply by a non-resident person who is not registered as a taxpayer of services under the terms of a gig contract concluded in accordance with Article 17 of the Law of Ukraine "On Stimulating the Development of the Digital Economy in Ukraine".
{ Article 208 is supplemented by paragraph 208.7 in accordance with the Law No. 4113-IX dated 04.12.2024 }
Article 208 - 1. Taxation of electronic services supplied by non-residents to individuals, the place of supply of which is located in the customs territory of Ukraine↑
208 - 1 .1. This article establishes the rules for taxation of electronic services, the place of supply of which is located in the customs territory of Ukraine, in the case of supply of such services to an individual, including an individual entrepreneur who is not registered as a taxpayer (hereinafter referred to in this article as an individual), by a non-resident person who is defined by subparagraph "d" of subparagraph 14.1.139 of paragraph 14.1 of Article 14 of this Code and who is registered as a taxpayer in accordance with paragraph 208 - 1 .2 of this article.
If electronic services in the customs territory of Ukraine are supplied to an individual through an intermediary, then for the purposes of taxation by this tax, the intermediary shall be considered to be the supplier of such electronic services. Such an intermediary, if he is a non-resident, shall be subject to the taxation rules established by this article. The provisions of this paragraph shall not apply to non-residents who supply electronic services under intermediary agreements if the invoices (receipts) provided to customers of electronic services specify a list of such electronic services and their actual supplier.
208 - 1 .2. Registration as a taxpayer of a non-resident person who supplies electronic services to individuals whose place of supply is located in the customs territory of Ukraine is carried out on the basis of an application for registration as a taxpayer of such a non-resident person.
A non-resident person is obliged to submit an application for registration as a taxpayer if, according to the results of the previous calendar year, the total amount from the performance of transactions by him for the supply of electronic services to individuals, the place of supply of which is located in the customs territory of Ukraine, collectively exceeds the amount equivalent to 1,000,000 hryvnias, which is calculated at the official exchange rate of the currency of Ukraine to foreign currency established by the National Bank of Ukraine, effective at 0 hours on January 1 of the relevant year. Such an application shall be submitted by March 31 inclusive of the relevant calendar year following the year in which such non-resident person reached the volume provided for in this paragraph.
A non-resident person who has not reached the amount specified in this paragraph and considers it appropriate to voluntarily register as a taxpayer may submit an application for registration as a taxpayer no later than 10 calendar days before the beginning of the reporting (tax) period from which such non-resident person will be considered a taxpayer.
An application for registration as a taxpayer, together with copies of an extract from the relevant business register (trade, banking or other register recording the fact of state registration of a company or organization), issued in the country of registration of such a non-resident person, and a document confirming the assignment of an identification (registration, accounting) number (code) of a non-resident in the country of his registration, if the extract from the relevant business register does not contain information about such a number (code), shall be submitted to the central executive body implementing state tax policy in electronic form through a special portal solution for non-resident users who provide electronic services, by means of electronic identification.
The application for registration as a taxpayer shall contain information on the registration of a non-resident in the country of the non-resident, identification data of the non-resident, the non-resident who will be subject to electronic identification, data on his representative, electronic address, reason for registration, information on confirmation of the fact and period of reaching the amount of transactions for the supply of electronic services to individuals, determined for mandatory registration by the taxpayer in accordance with paragraph two of this paragraph, as well as the foreign currency (euro or US dollar) in which the non-resident will pay the tax.
The central executive body implementing the state tax policy shall refuse to register a person as a taxpayer if, based on the results of consideration of the application for registration as a taxpayer and/or the submitted documents, it is established that the person does not meet the requirements specified in Article 180 , paragraph two of paragraph 208-1.2 of Article 208-1 of this Code, or there are circumstances that constitute grounds for cancellation of registration in accordance with Article 208-1.3 of this Code, and also if the procedure established by this paragraph was not followed when submitting the application.
In the absence of grounds for refusing to register a person as a taxpayer, the central executive body implementing state tax policy, within three working days after receiving the application, must register the non-resident person as a taxpayer and within the same period send such a non-resident person through a special portal solution for non-resident users who provide electronic services, with a simultaneous notification to the email address specified in the application for registration as a taxpayer, information about:
a) registration as a taxpayer;
b) individual tax number of a non-resident person registered as a taxpayer;
c) reporting (tax) period, deadlines for submitting tax reports and deadlines and procedure for paying tax liabilities.
A non-resident person specified in this paragraph shall be considered registered as a taxpayer from the date of entry in the register of taxpayers in the case of mandatory registration of the person as a taxpayer or from the first day of the reporting (tax) period following the day of expiration of 10 calendar days after submission to the central executive body implementing state tax policy of an application for registration as a taxpayer, in the case of voluntary registration.
Within 180 calendar days from the date of registration of a non-resident person as a taxpayer, such non-resident person shall send to the central executive body implementing state tax policy an official letter confirming the information provided upon registration as a taxpayer, including his/her identification (registration, accounting) number (code) and the representative of the non-resident who has been electronically remotely identified.
If a non-resident person registered as a taxpayer experiences any changes in their accounting information, such non-resident person shall notify the changes electronically through a special portal solution for non-resident users who provide electronic services by submitting an application for re-registration within 10 business days following the day the taxpayer's data changed.
The form of the application for registration of a non-resident person as a taxpayer, specified in the first paragraph of this paragraph, and the form of making changes to accounting information shall be established in the state and English languages and approved by the central executive body that ensures the formation and implementation of state financial policy.
Registration of a non-resident as a taxpayer and interaction of such a non-resident with the supervisory authority shall be carried out by means of electronic identification using the non-resident's domain name and/or, at the request of the non-resident, using other permitted technologies of electronic identification of the taxpayer, defined for the purposes of this Code. The procedure for electronic identification shall be approved by the central executive body that ensures the formation and implementation of state financial policy, its official translation into English shall be posted on a special portal solution for non-resident users who provide electronic services.
208 - 1 .3. Cancellation of registration as a non-resident taxpayer is carried out on the basis of:
1) an application for cancellation of registration as a taxpayer (hereinafter referred to as the application for cancellation of registration), which is submitted in electronic form through a special portal solution for non-resident users who provide electronic services, by means of electronic identification;
2) decision of the supervisory authority, if:
a non-resident person registered as a taxpayer in accordance with clause 208 - 1.2 of this article, for four consecutive reporting (tax) periods does not submit simplified tax returns to the regulatory authority and / or submits such returns that indicate the absence of provision of electronic services;
the activities of a non-resident person in the country of registration of the non-resident have been terminated (liquidated).
The central executive body implementing the state tax policy, within three working days after receiving an application for cancellation of registration or making a decision to cancel registration as a taxpayer of a non-resident person, must send such a non-resident person in electronic form through a special portal solution for non-resident users who provide electronic services, with a simultaneous notification to the email address specified in the application for cancellation of registration, information about:
the date from which the registration as a non-resident taxpayer will be canceled;
consequences of cancellation of registration as a taxpayer;
deadlines for submitting tax reports for the last reporting (tax) period and deadlines and procedure for paying tax liabilities for the last reporting (tax) period.
An application for cancellation of registration shall be submitted by a non-resident person in the relevant reporting (tax) period no later than three business days before its end. In case of violation of the deadline specified in this paragraph, such an application shall be deemed to have been submitted on the first day of the following reporting (tax) period.
Cancellation of registration as a non-resident taxpayer shall occur on the last day of the reporting period in which the application for cancellation of registration was submitted, the decision provided for in this paragraph was made, or from the date of termination of the non-resident's activities in the non-resident's country. In this case, the amount of tax paid in excess by the non-resident is not subject to refund from the state budget.
Submission of a simplified tax return for the last reporting (tax) period and payment of the tax liability specified in such a return shall be carried out in accordance with the procedure and within the terms specified in this article.
The rule specified in this paragraph regarding the cancellation of registration as a non-resident taxpayer shall not apply if, based on the results of the previous calendar year, the total amount from the performance of transactions by him for the supply of electronic services to individuals, the place of supply of which is located in the customs territory of Ukraine, collectively exceeds the amount equivalent to 1,000,000 hryvnias, which is calculated at the official exchange rate of the Ukrainian currency to foreign currency established by the National Bank of Ukraine, effective at 0:00 on January 1 of the relevant year, except in the case of termination of the non-resident's activity in the country of the non-resident.
The central executive body implementing the state tax policy, within three working days after receiving an application for cancellation of registration as a taxpayer from a non-resident person whose registration as a taxpayer is not subject to cancellation, must send such a non-resident person in electronic form through a special portal solution for non-resident users who provide electronic services, with a simultaneous notification to the email address specified in the application for cancellation of registration, information about:
refusal to cancel registration as a taxpayer;
reasons for such refusal.
The form of the application for cancellation of registration, specified in the second paragraph of this paragraph, the forms of the decision on cancellation of registration as a non-resident taxpayer and the decision on refusal to cancel registration as a taxpayer shall be approved by the central executive body that ensures the formation and implementation of state financial policy. The procedure for making a decision on cancellation of registration as a non-resident taxpayer and the decision on refusal to cancel registration as a taxpayer shall be approved by the central executive body that ensures the formation and implementation of state financial policy, its official translation into English shall be posted on a special portal solution for non-resident users who provide electronic services.
208 - 1 .4. The basic reporting (tax) period for a non-resident person registered as a taxpayer in accordance with clause 208 - 1 .2 of this article is a quarter.
The last reporting (tax) period is the period that begins on the first day of the quarter in which the registration as a non-resident taxpayer was canceled and ends on the day the registration as a non-resident taxpayer was canceled.
208 - 1 .5. The date of occurrence of tax liabilities for transactions on the supply of electronic services by a non-resident person registered as a taxpayer in accordance with paragraph 208 - 1 .2 of this Article is the last day of the reporting (tax) period in which payment for electronic services was made.
208 - 1 .6. The tax base for transactions on the supply of electronic services by a non-resident person registered as a taxpayer in accordance with paragraph 208 - 1 .2 of this Article is determined based on the cost of such services.
The tax is 20 percent of the tax base and is added to the cost of electronic services, except for transactions exempt from VAT.
The tax base and tax amount are determined in foreign currency (euro or US dollar).
208 - 1 .7. A non-resident person registered as a taxpayer in accordance with paragraph 208 - 1 .2 of this article shall not generate a tax credit from the tax and shall not issue tax invoices for transactions for the supply of electronic services, the place of supply of which is located in the customs territory of Ukraine.
208 - 1 .8. A non-resident person registered as a taxpayer in accordance with clause 208 - 1 .2 of this article shall prepare a simplified tax return and submit it in electronic form through a special portal solution for non-resident users who provide electronic services, by means of electronic identification within 40 calendar days following the last calendar day of the reporting (tax) period, regardless of whether the non-resident provided electronic services to individuals during the reporting (tax) period, the place of supply of which is located in the customs territory of Ukraine.
208 - 1 .8.1. The simplified tax return shall indicate:
a) the name of the non-resident person registered as a taxpayer;
b) individual tax number of a non-resident person registered as a taxpayer;
c) the reporting (tax) period for which the simplified tax return is submitted;
d) the contractual cost of the supply of electronic services, excluding tax;
e) the amount of tax.
If in future tax periods a non-resident person registered as a taxpayer independently discovers errors contained in a previously submitted simplified tax return, he is obliged to send a clarifying calculation to such simplified tax return and pay the amount of the underpayment.
208 - 1 .8.2. The clarifying calculation to the simplified tax return shall indicate:
a) the name of the non-resident person registered as a taxpayer;
b) individual tax number of a non-resident person registered as a taxpayer;
c) the date of preparation of the clarifying calculation for the simplified tax return;
d) the reporting (tax) period for which the simplified tax return was submitted;
e) the contractual value of the supply of electronic services that was not declared in the simplified tax return, excluding tax, or was over-declared in the simplified tax return;
e) the amount of tax that was not declared in the simplified tax return, or the amount of tax that was over-declared in the simplified tax return.
The amount of tax liability indicated by a non-resident person in the clarifying calculation to the simplified tax return is subject to payment within 30 calendar days following the date of submission of such clarifying calculation to the simplified tax return, and the amount of overpaid tax indicated by a non-resident person in the clarifying calculation to the simplified tax return is automatically credited against the payment of tax liabilities on value added tax for subsequent reporting (tax) periods and cannot be refunded to the account of a non-resident person.
The forms of the simplified tax declaration and the clarifying calculation to it are approved by the central executive body that ensures the formation and implementation of the state financial policy. The features of the preparation and submission of the simplified tax declaration and the clarifying calculation are approved by the central executive body that ensures the formation and implementation of the state financial policy, its official translation into English is posted on a special portal solution for non-resident users who provide electronic services.
The forms of the simplified tax return and the clarifying calculation to it, other forms specified in this article, are posted on a special portal solution for non-resident users who provide electronic services.
The simplified tax return and the clarifying calculation to it are filled out in the state language or English.
208 - 1 .9. The amount of tax liability specified by a non-resident person registered as a taxpayer in accordance with clause 208 - 1 .2 of this article shall be payable in foreign currency (euro or US dollar) within 30 calendar days following the last day of the deadline provided for in clause 208 - 1 .8 of this article for submitting a simplified tax return, to a foreign currency account opened with the central executive body implementing state policy in the field of treasury servicing of budget funds, in an authorized bank.
The details of such a foreign currency account are posted on a special portal solution for non-resident users who provide electronic services.
208 - 1 .10. If a non-resident person registered as a taxpayer in accordance with clause 208 - 1 .2 of this article fails to submit a simplified tax return within the established period or fails to pay tax within the established period, the central executive body implementing the state tax policy shall, within 30 calendar days after the expiration of the established periods, send such non-resident a notification in the manner provided for in Article 58 - 1 of this Code about the need to submit a simplified tax return and/or pay tax, as well as about the amount of penalties for such violations.
Penalties for violation of the deadlines for submitting a simplified tax return and/or paying tax are applied in accordance with Chapter 11, Section II of this Code.
208 - 1 .11. A simplified tax return is subject exclusively to a special in-house audit.
A special office inspection is an inspection conducted at the premises of a regulatory authority based on the data specified in a simplified tax return submitted by a non-resident person registered as a taxpayer in accordance with paragraph 208 - 1.2 of this Article of this Code, as well as information received in accordance with this paragraph.
The term for conducting a special desk audit cannot exceed 90 calendar days following the date of submission of the simplified tax return.
Based on the results of a special desk audit, if violations are identified, only a tax notice is drawn up, containing a detailed calculation of the tax liability (if any) and financial penalties, as well as the circumstances of the offense committed, established during the special desk audit, and the deadlines for paying the monetary obligation.
of a simplified tax return submitted by a non-resident person registered as a taxpayer in accordance with paragraph 208 - 1.2 of this Article, the central executive body implementing state tax policy may, by decision of the head, request from the non-resident person generalized information on the supply of electronic services to individuals in the customs territory of Ukraine, on the cost of the services provided and the terms of their payment.
The central executive body implementing the state tax policy may send requests to a non-resident person registered as a taxpayer for obtaining generalized information (hereinafter referred to as an electronic request) in electronic form through a special portal solution for non-resident users who provide electronic services, with a simultaneous notification to the email address specified by the non-resident when registering as a taxpayer.
The electronic request shall specify:
a list of information requested;
list of documents to be submitted;
the time limit and method of providing such information;
consequences of failure to provide or untimely response to a request received.
The response to the electronic request shall be provided by the non-resident person within 30 calendar days from the day following the day of receipt of such a request in electronic form through a special portal solution for non-resident users who provide electronic services.
The form of the electronic request specified in this paragraph shall be approved by the central executive body responsible for the formation and implementation of state financial policy.
208 - 1 .12. The provisions of this article are special in relation to other provisions of this Code in terms of determining the rules for taxation of a non-resident person registered as a taxpayer in accordance with paragraph 208 - 1 .2 of this article.
The provisions of this Code regarding registration as a taxpayer, cancellation of registration as a taxpayer and inspections of non-residents specified in subparagraph "d" of subparagraph 14.1.139 of paragraph 14.1 of Article 14 of this Code shall apply to the extent specified in this Article.
208 - 1 .13. The accounting of a non-resident person registered as a taxpayer in accordance with clause 208 - 1 .2 of this article, as well as control over the timeliness and completeness of the calculation and payment of tax by such a non-resident person - taxpayer, shall be carried out by the supervisory authority.
{The Code is supplemented by Article 208 - 1 in accordance with the Law No. 1525-IX dated 03.06.2021 }
Article 209. {Article 209 has become invalid since January 1, 2017 - see subparagraph 4 of paragraph 2 of section XIX of this Code}↑
Article 210. Special taxation regime for activities related to works of art, collectibles or antiques↑
210.1. In the cases specified in this article, transactions for the supply of works of art, collectibles or antiques shall be subject to taxation in accordance with the provisions of this article and shall not be subject to taxation in accordance with the general procedure established by this section.
210.2. In this article, the following terms are used in the following meaning:
cultural values - works of art, collectibles or antiques - goods belonging to commodity headings under codes 9701-9706 according to the UKT Foreign Economic Activity ;
dealer - a taxpayer who purchases (acquires under other civil law contracts), including by importing into the customs territory of Ukraine, cultural values, regardless of the purpose and objectives of their import, for the purpose of their further resale, regardless of whether such a person acts on his own behalf or on behalf of another person for remuneration;
Marginal profit (excluding tax) is the amount received as the difference between the selling price of goods and their purchase price, calculated at regular prices.
In the case of the sale of cultural property at public auctions (auctions), its organizer is equated for tax purposes to a dealer in accordance with this subparagraph.
210.3. In the case of the supply of cultural values, a special scheme for taxation of the marginal profit received by the dealer shall be applied, in accordance with the provisions of this article.
210.4. The margin scheme applies to the supply by a dealer of cultural values if such values were supplied to him by one of the following persons:
a) a person who is not registered as a taxpayer;
b) by a taxpayer if the transaction for the supply of such cultural property by him is exempt from taxation or not subject to taxation in accordance with this section;
c) by the taxpayer, if this taxpayer was charged tax under the marginal scheme when supplying cultural values;
d) authors of cultural values or their successors in title.
The margin scheme may be applied by a dealer to operations for the supply of cultural values to the customs territory of Ukraine that were imported by the dealer under the customs import regime.
210.5. The tax base for transactions involving the supply of cultural property by a dealer is his marginal profit (excluding tax), to which the rate determined by subparagraph "a" of paragraph 193.1 of Article 193 of this Code is applied.
A tax invoice shall not be issued for supply operations within the customs territory of Ukraine by a dealer who applies the rules established by this article.
{Paragraph two of clause 210.5 of Article 210 as amended by Law No. 1797-VIII of 21.12.2016 }
{Clause 206.5 of Article 208 as amended by Law No. 1797-VIII of 21.12.2016 }
210.6. A dealer who purchases cultural property from persons specified in paragraph 210.4 of this Article is not entitled to a tax credit.
210.7. The zero tax rate does not apply to operations for the export of cultural property under the customs export regime.
210.8. A taxpayer purchasing cultural property from a dealer using a margin scheme does not have the right to request a tax invoice and attribute the amount of tax paid on the margin profit to a tax credit.
The dealer is obliged to keep separate tax records for transactions on the acquisition and supply of cultural values and separate records for transactions on the acquisition and supply of other goods/services to which the general taxation regime applies.
Article 211. Features of taxation of transactions related to the performance of work on preparation for decommissioning and decommissioning of the Chernobyl NPP power units and the transformation of the Shelter facility into an environmentally safe system↑
211.1. For the period of preparation for decommissioning and decommissioning of the Chernobyl NPP power units and conversion of the Shelter facility into an environmentally safe system, which are carried out at the expense of international technical assistance funds provided on a gratuitous and non-refundable basis, or at the expense of funds provided in the State Budget of Ukraine as Ukraine's contribution to the Chernobyl Shelter Fund for the implementation of the international program - the Plan for the implementation of measures at the Shelter facility in accordance with the provisions of the Framework Agreement between Ukraine and the European Bank for Reconstruction and Development on the activities of the Chernobyl Shelter Fund in Ukraine and the Grant Agreement (Chernobyl NPP nuclear safety project) between the European Bank for Reconstruction and Development, the Government of Ukraine and the Chernobyl Nuclear Power Plant :
exempt from taxation transactions for the import of goods (raw materials, equipment and machinery);
Transactions for the supply of goods (raw materials, equipment and facilities), performance of work and provision of services on the customs territory of Ukraine carried out within the framework of international technical assistance are taxed at a zero rate. The amounts of tax paid by the taxpayer - the performer of work, services under a contract concluded with a non-resident person who concluded a contract with the recipient are reimbursed from the budget during the month following the month in which the tax declaration is submitted, provided that properly executed documents are available and confirmed by documentary verification materials.
{Paragraph three of clause 211.1 of Article 211 as amended by Law No. 3609-VI of 07.07.2011 }
211.2. The benefits specified in this article do not apply to transactions involving excisable goods and goods of groups 1-24 of the UKT FEA .
211.3. In case of violation of the requirements for the intended use of the specified goods or performance of work and provision of services, the taxpayer is obliged to increase the tax liabilities based on the results of the tax period to which such violation applies, by the amount of tax that must be paid at the time of importation into the customs territory of Ukraine of such goods or performance of work and provision of services in the customs territory of Ukraine, as well as to pay a penalty accrued on such amount of tax, based on 120 percent of the discount rate of the National Bank of Ukraine, which was in effect on the date of the increase in the tax liability, and for the period from the date of importation into the customs territory of Ukraine of such goods or performance of work and provision of services to the date of the increase in the tax liabilities.
212.1.1. A person, permanent establishment, that produces excisable goods (products) in the customs territory of Ukraine, including from toll-based raw materials.
{Subclause 212.1.1 of Clause 212.1 of Article 212 as amended by Law No. 391-IX of 18.12.2019 }
212.1.2. A person - a business entity, a permanent establishment, which imports excisable goods (products) into the customs territory of Ukraine.
{Subclause 212.1.2 of Clause 212.1 of Article 212 as amended by Law No. 391-IX of 18.12.2019 }
212.1.3. An individual - resident or non-resident, who imports excisable goods (products) into the customs territory of Ukraine in taxable quantities in accordance with customs legislation.
212.1.4. A person who sells confiscated excisable goods (products), excisable goods (products) recognized as ownerless, excisable goods (products) for which the owner has not applied by the end of the storage period, and excisable goods (products) that, by right of inheritance or on other legal grounds, become the property of the state, if these goods (products) are subject to sale in accordance with the procedure established by law.
212.1.5. A person who sells or transfers into possession, use or disposal excisable goods (products) that were imported into the customs territory of Ukraine with exemption from taxation before the expiration of the period determined by law in accordance with Clause 213.3 of Article 213 of this Code.
212.1.6. A person who is responsible for complying with the requirements of customs regimes that provide for exemption from taxation, in the event of a violation of such requirements.
212.1.7. A person who is responsible for fulfilling the conditions for the intended use of excisable goods (products) for which the tax rate is set at 0 hryvnias per 1 liter of 100 percent alcohol, 0 euros per 1,000 kg of petroleum products in case of violation of such conditions.
212.1.8. A person who, when carrying out transactions with excisable goods (products) that are not subject to taxation or are exempt from taxation, is required to fulfill the conditions regarding the intended use of excisable goods (products) in the event of violation of such conditions.
{Subclause 212.1.9 of clause 212.1 of Article 212 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 212.1.10 of clause 212.1 of Article 212 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
212.1.11. A person is a retail business entity that sells excisable goods (except for tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes).
{Clause 212.1 of Article 212 is supplemented by subparagraph 212.1.11 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1914-IX of 30.11.2021 }
{Sub- paragraph 212.1.12 of paragraph 212.1 of Article 212 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
212.1.13. Electricity producers who have a license to carry out entrepreneurial activities in the production of electricity and sell it on the electricity market.
{Clause 212.1 of Article 212 is supplemented by subparagraph 212.1.13 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 466-IX of 16.01.2020 }
212.1.14. A person is the owner of a freight vehicle imported into the customs territory of Ukraine that is converted into a passenger car, on which excise tax is levied.
{Clause 212.1 of Article 212 is supplemented by subparagraph 212.1.14 in accordance with Law No. 71-VIII of 28.12.2014 }
212.1.15. A person (including a legal entity that keeps records of the results of activities under a joint activity agreement without creating a legal entity), a permanent representative office, which sells fuel or ethyl alcohol.
{Clause 212.1 of Article 212 is supplemented by subparagraph 212.1.15 in accordance with Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 391-IX of 18.12.2019 }
212.1.16. A person - a business entity, a permanent establishment that uses goods (products), the codes of which according to the UKT FEA are not specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKT FEA ), as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, with spark-ignition internal combustion engines, with crank-and-rod internal combustion engines.
{Clause 212.1 of Article 212 is supplemented by subparagraph 212.1.16 in accordance with Law No. 391-IX of 18.12.2019 }
212.1.17. A person is a manufacturer and/or importer of tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes, who sells them for the purposes of taxation with excise tax on the sale of excisable goods by retail business entities at the rate determined by subparagraph 215.3.10 of paragraph 215.3 of Article 215 of this Code.
{Clause 212.1 of Article 212 is supplemented by subparagraph 212.1.17 in accordance with Law No. 1914-IX of 30.11.2021 }
212.2. Customers, on whose behalf excisable goods (products) are produced from toll raw materials, pay tax to the manufacturer.
212.2 - 1. The person responsible for paying tax to the budget as part of customs payments in the manner established by Article 295 - 1 of the Customs Code of Ukraine is the person who sells excisable goods defined in Part Seven of Article 293 of the Customs Code of Ukraine. Such a person has the rights, performs the duties and bears the responsibility provided for by law as a tax payer.
{Article 212 is supplemented by paragraph 212.2 - 1 in accordance with the Law No. 3474-IX dated 21.11.2023 }
212.3. Registration of persons as tax payers.
212.3.1. Registration with regulatory authorities as a tax payer of a business entity, permanent representative office, engaged in the production of excisable goods (products) subject to licensing, is carried out on the basis of information on the issuance of the relevant license to such an entity.
{ Paragraph one of subparagraph 212.3.1 of paragraph 212.3 of Article 212 as amended by the Law No. 391-IX dated 18.12.2019 }
Licensing authorities authorized to issue licenses for the specified types of activities are obliged to provide the regulatory authority at the location of legal entities, permanent representative offices, and place of residence of individual entrepreneurs with information on issued, reissued, suspended, or canceled licenses within five days from the date of such actions.
{Paragraph two of subparagraph 212.3.1 of paragraph 212.3 of Article 212 as amended by Laws No. 3609-VI of 07.07.2011 , No. 391-IX of 18.12.2019 }
212.3.1 - 1. Retail business entities that sell excisable goods are subject to mandatory registration as tax payers by the regulatory authorities at the location of the point of sale of goods no later than the deadline for submitting an excise tax declaration for the month in which the business activity is carried out.
{Clause 212.3 of Article 212 is supplemented by subparagraph 212.3.1 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
212.3.2. Other payers are subject to mandatory registration as tax payers by the regulatory authorities at the location of legal entities, place of residence of individual entrepreneurs, no later than the deadline for submitting an excise tax declaration for the month in which economic activity was started.
{Subclause 212.3.2 of Clause 212.3 of Article 212 as amended by Law No. 3609-VI of 07.07.2011 }
{Subclause 212.3.3 of clause 212.3 of Article 212 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
212.3.4. Persons who will sell fuel or ethyl alcohol are subject to mandatory registration as tax payers by the regulatory authorities at the location of legal entities, permanent representative offices, and place of residence of individual entrepreneurs before the start of the sale of fuel or ethyl alcohol.
{ Paragraph one of subparagraph 212.3.4 of paragraph 212.3 of Article 212 as amended by the Law No. 391-IX dated 18.12.2019 }
Registration of a taxpayer is carried out on the basis of a person submitting a declaration no later than three working days before the start of the sale of fuel or ethyl alcohol, the form of which is approved by the central executive body that ensures the formation of state financial policy.
The central executive body implementing state tax policy maintains a register of excise tax payers on the sale of fuel or ethyl alcohol, which contains information about persons registered as excise tax payers.
{ Paragraph three of subparagraph 212.3.4 of paragraph 212.3 of Article 212 as amended by the Law No. 391-IX dated 18.12.2019 }
{Clause 212.3 of Article 212 is supplemented by subparagraph 212.3.4 in accordance with Law No. 909-VIII of 24.12.2015 ; as amended in accordance with Law No. 2628-VIII dated 23.11.2018 }
213.1. The objects of taxation are transactions with:
213.1.1. sales of excisable goods (products) produced in Ukraine;
213.1.2. sale and/or transfer within one enterprise of excisable goods (products) for the purpose of own consumption, industrial processing, to its employees, as well as making contributions with excisable goods (products) to the authorized capital. This norm does not apply to transactions for the transfer within one enterprise of electricity (code 2716 00 00 00 according to the UKT FEA ), produced at power generation facilities;
{Subclause 213.1.2 of Clause 213.1 of Article 213 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 466-IX of 01/16/2020 }
213.1.3. import of excisable goods (products) into the customs territory of Ukraine;
213.1.4. sale of confiscated excisable goods (products), excisable goods (products) recognized as ownerless, excisable goods (products) for which the owner has not applied by the end of the storage period, and excisable goods (products) that, by right of inheritance or on other legal grounds, become the property of the state;
213.1.5. sale or transfer into possession, use or disposal of excisable goods (products) that were imported into the customs territory of Ukraine with exemption from taxation before the expiration of the period specified by law, in accordance with paragraph 213.3 of Article 213 of this Code;
213.1.6. volumes and value of lost excisable goods (products), except for cases provided for in paragraph 216.3 of Article 216 of this Code;
{Subclause 213.1.6 of Clause 213.1 of Article 213 as amended by Law No. 1914-IX of 30.11.2021 }
{Subclause 213.1.7 of clause 213.1 of Article 213 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 213.1.8 of clause 213.1 of Article 213 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
213.1.9. sales by retail business entities of excisable goods (except for tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes);
{Clause 213.1 of Article 213 is supplemented by subparagraph 213.1.9 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1914-IX of 30.11.2021 }
{Sub- paragraph 213.1.10 of paragraph 213.1 of Article 213 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
213.1.11. conversion of a vehicle imported into the customs territory of Ukraine into an excisable passenger car.
{Clause 213.1 of Article 213 is supplemented by subparagraph 213.1.11 in accordance with Law No. 71-VIII of 28.12.2014 }
213.1.12. sales from an excise warehouse/mobile excise warehouse of any volumes of fuel or ethyl alcohol in excess of the volumes that:
{Paragraph one of subparagraph 213.1.12 of paragraph 213.1 of Article 213 as amended by Law No. 2628-VIII of 23.11.2018 }
received from other excise warehouses/mobile excise warehouses, confirmed by registered excise invoices in the Unified Register of Excise Invoices;
{Paragraph two of subparagraph 213.1.12 of paragraph 213.1 of Article 213 as amended by Law No. 2628-VIII of 23.11.2018 }
imported into the customs territory of Ukraine, certified by a properly executed customs declaration;
produced in Ukraine, the sale of which is subject to taxation in accordance with subparagraph 213.1.1 of this paragraph, is either not subject to taxation, or is exempt from taxation, or is taxed under the conditions established by Article 229 of this Code, which are confirmed by registered excise invoices in the Unified Register of Excise Invoices.
{Paragraph four of subparagraph 213.1.12 of paragraph 213.1 of Article 213 as amended by Law No. 2628-VIII of 23.11.2018 }
{Clause 213.1 of Article 213 is supplemented by subparagraph 213.1.12 in accordance with Law No. 909-VIII of 24.12.2015 }
213.1.13. use of goods (products), the codes of which according to the UKT FEA are not specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKT FEA ), as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, with spark-ignition internal combustion engines, with crank-and-connecting internal combustion engines.
{Clause 213.1 of Article 213 is supplemented by subparagraph 213.1.13 in accordance with Law No. 391-IX of 18.12.2019 }
213.1.14. sales by manufacturers and/or importers, including in retail trade, of tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes, for the purposes of taxation with excise tax on the sale of excisable goods by retail business entities.
{Clause 213.1 of Article 213 is supplemented by subparagraph 213.1.14 in accordance with Law No. 1914-IX of 30.11.2021 }
213.2. Transactions with excisable goods that are not subject to taxation:
213.2.1. export of excisable goods (products) by the taxpayer outside the customs territory of Ukraine.
Goods (products) are considered to be exported (exported) by the taxpayer outside the customs territory of Ukraine if their export (export) is certified by a properly executed customs declaration, including if the shipment took place in the reporting period, and the export (export) took place in the next reporting period and such a customs declaration is available on the date of submission of the excise tax declaration for the reporting month;
{Paragraph two of subparagraph 213.2.1 of paragraph 213.2 of Article 213 as amended by Law No. 3609-VI of 07.07.2011 }
213.2.2. import into the customs territory of Ukraine of previously exported excisable goods (products) in which defects have been identified that prevent the sale of these goods in the customs territory of the importing country, for their return to the exporter.
Such excisable goods (products) are imported by their seller (exporter) without further sale in the customs territory of Ukraine;
{Subclause 213.2.3 of clause 213.2 of Article 213 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 213.2.4 of clause 213.2 of Article 213 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 213.2.5 of clause 213.2 of Article 213 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 213.2.6 of clause 213.2 of Article 213 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subclause 213.2.7 of clause 213.2 of Article 213 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
213.2.8. sale of electricity generated by qualified cogeneration plants and/or from renewable energy sources;
{Clause 213.2 of Article 213 is supplemented by subparagraph 213.2.8 in accordance with Law No. 71-VIII of 28.12.2014 }
213.2.9. transfer for own consumption within one enterprise of electrical energy (code 2716 00 00 00 according to the UKT FEA ) produced at this enterprise.
{Clause 213.2 of Article 213 is supplemented by subparagraph 213.2.9 in accordance with Law No. 466-IX of January 16, 2020 }
213.3. Transactions with excisable goods that are exempt from taxation:
213.3.1. sales of passenger cars for persons with disabilities, including children with disabilities, the cost of which is paid for from state or local budgets, funds from compulsory state insurance funds, as well as special-purpose passenger cars (ambulance and for the needs of central executive bodies implementing state policy in the areas of civil protection, rescue, fire and technogenic safety), the cost of which is paid for from state and local budgets;
{Subclause 213.3.1 of Clause 213.3 of Article 213 as amended by Law No. 5083-VI of 05.07.2012 }
213.3.2. import of excisable goods (products) into the customs territory of Ukraine intended for official (service) use by diplomatic missions of foreign states, consular institutions of foreign states and for personal use by members of diplomatic missions of foreign states, consular institutions of foreign states based on the principle of reciprocity in relation to each individual state.
In the event of the sale of excisable goods (products) on the customs territory of Ukraine that were imported with exemption from taxation in accordance with the norms of this subparagraph, the tax shall be paid by persons who sell or transfer such excisable goods (products) into possession, use or disposal, no later than the date of such sale, simultaneously with the payment of value added tax at the rates in effect at the time of submission of the customs declaration upon importation of excisable goods (products) into the customs territory of Ukraine;
213.3.3. import of excisable goods (products) from outside the customs territory of Ukraine into the customs territory of Ukraine, if in accordance with the law, value added tax is not levied in connection with the placement of goods (products) in customs regimes: reimport, transit, temporary import, customs warehouse, free customs zone, duty-free trade, processing in the customs territory, destruction or destruction, refusal in favor of the state. In case of violation of the conditions of customs regimes that provide for full or partial exemption from taxation, the person responsible for compliance with the regime is obliged to calculate and pay the amount of the tax liability. In the event that in the specified cases the customs legislation of Ukraine provides for a requirement to implement guarantee measures, such a requirement is also established for excise tax purposes. The tax is levied if in the future obligations to pay value added tax arise in relation to such goods (products);
{Subclause 213.3.3 of Clause 213.3 of Article 213 as amended by Law No. 4915-VI of 07.06.2012 }
213.3.4. free transfer for destruction of excisable goods (products) confiscated by court decision and those that have become the property of the state due to the owner's refusal, if they are not subject to sale (realization) in accordance with the procedure established by law;
free transfer into possession and use to the Armed Forces of Ukraine and other military formations established in accordance with the laws of Ukraine, bodies of the Security Service of Ukraine, the National Police of Ukraine, the State Border Service of Ukraine, the State Emergency Service of Ukraine, the National Guard of Ukraine of confiscated excisable goods specified in subparagraphs 215.3.5-215.3.5 - 2 of paragraph 215.3 of Article 215 of this Code (hereinafter referred to as vehicles for this paragraph); vehicles recognized as ownerless; vehicles for which the owner has not applied by the end of the storage period; vehicles that have become the property of the state by right of inheritance or on other legal grounds.
{ Subparagraph 213.3.4 of paragraph 213.3 of Article 213 is supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 ; with amendments made in accordance with the Law No. 1293-IX dated 02.03.2021 }
In the case of the sale on the customs territory of Ukraine of vehicles, the free transfer of which is exempt from taxation in accordance with this subparagraph, the tax shall be paid by the persons who sell or transfer such vehicles into possession, use or disposal, no later than the date of such sale, simultaneously with the payment of value added tax at the rates in effect at the time of the free transfer of such excisable vehicles;
{ Subparagraph 213.3.4 of paragraph 213.3 of Article 213 is supplemented by the third paragraph in accordance with Law No. 466-IX of January 16, 2020 }
213.3.5. sales and/or transfer within one enterprise of excisable goods (products) produced in the customs territory of Ukraine, used as raw materials for the production of excisable goods (products) and benzene (under code 2902 20 00 00 according to the UKT FEA). This norm does not apply to transactions for the sale and/or transfer within one enterprise of petroleum products (except for goods (products) under codes 2707 10 00 00, 2707 50 00 90, 2710 12 90 00 and 2711 19 00 00 according to the UKT FEA );
{Subclause 213.3.5 of clause 213.3 of Article 213 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by the Laws No. 2245-VIII dated 07.12.2017 , No. 1914-IX dated 30.11.2021 }
213.3.6. import into the customs territory of Ukraine of excisable goods (products) used as raw materials for the production of excisable goods (products, including raw materials), provided that such raw materials are subsequently manufactured into other excisable goods (products, including raw materials) that are sold in the customs territory of Ukraine or for export, or export outside the customs territory of Ukraine of raw materials not used in production, and presentation to the regulatory authority of a license for the right to produce alcoholic beverages or tobacco products. This norm does not apply to fuel import operations;
{Subclause 213.3.6 of clause 213.3 of Article 213 as amended by Law No. 5503-VI of 20.11.2012 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII dated 24.12.2015 ; as amended by Law No. 1914-IX dated 30.11.2021 }
213.3.7. import by individuals into the customs territory of Ukraine of excisable goods (products) in quantities not exceeding the norms of duty-free import established by the Customs Code of Ukraine ;
{Subclause 213.3.7 of Clause 213.3 of Article 213 as amended by Law No. 4915-VI of 07.06.2012 }
213.3.8. sales directly by domestic producers of alcoholic beverages and tobacco products to duty-free shops. The basis for exemption from tax on products intended for sale by duty-free shops is a properly executed customs declaration, which is issued during the shipment of products from such a producer;
213.3.9. import into the customs territory of Ukraine of excisable goods (products) (except for alcoholic beverages and tobacco products) as international technical assistance provided in accordance with international treaties of Ukraine, the binding consent of which has been granted by the Verkhovna Rada of Ukraine, or as humanitarian assistance provided in accordance with the provisions of the Law of Ukraine "On Humanitarian Aid" ;
213.3.10. import by accredited state testing laboratories and/or business entities that have licenses for the production of tobacco products, reference (monitoring) or test samples of tobacco products (not intended for retail sale) for conducting research or testing (calibration of laboratory equipment, conducting tastings, studying physicochemical indicators, design);
213.3.11. sale of liquefied gas at specialized auctions for the needs of the population in accordance with the procedure established by the Cabinet of Ministers of Ukraine;
213.3.12. sale of tobacco waste subject to documentary confirmation of its generation and subsequent destruction or disposal;
{Clause 213.3 of Article 213 is supplemented by subparagraph 213.3.12 in accordance with Law No. 909-VIII of 24.12.2015 }
213.3.13. import into the customs territory of Ukraine of unfermented (unprocessed) tobacco raw materials by tobacco fermentation plants, subject to the subsequent manufacture of fermented (processed) tobacco raw materials from such raw materials and their sale to tobacco product manufacturers or their export; sale of tobacco raw materials to tobacco fermentation plants by persons who produce tobacco raw materials on the customs territory of Ukraine; sale of fermented (processed) tobacco raw materials by tobacco fermentation plants to tobacco product manufacturers.
{Paragraph one of subparagraph 213.3.13 of paragraph 213.3 of Article 213 as amended by Law No. 1914-IX of 30.11.2021 }
Tobacco fermentation plants, within the period provided for by this Code for submitting a tax declaration for a monthly tax period, shall submit to the regulatory authorities at the main place of registration a report on the volumes of imports of unfermented (unprocessed) tobacco raw materials, volumes of purchased tobacco raw materials from persons producing tobacco raw materials in the customs territory of Ukraine, volumes of production, sales to tobacco product manufacturers and exports of fermented (processed) tobacco raw materials in the form approved by the central executive body that ensures the formation and implementation of state financial policy. Such a report shall be equated to a tax declaration for the purposes of applying the provisions of this Code regarding inspections and bringing to justice for tax offenses;
{Subclause 213.3.13 of clause 213.3 of Article 213 is supplemented by the second paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
{Clause 213.3 of Article 213 is supplemented by subparagraph 213.3.13 in accordance with Law No. 1797-VIII of 21.12.2016 }
213.3.14. import into the customs territory of Ukraine and sale in the customs territory of Ukraine of bodies for passenger cars, provided that they are subsequently manufactured into cars specified in commodity heading 8703 in accordance with the UKT Foreign Economic Activity .
{Clause 213.3 of Article 213 is supplemented by subparagraph 213.3.14 in accordance with Law No. 2611-VIII of 08.11.2018 }
214.1. In the case of calculating tax using ad valorem rates, the tax base is:
214.1.1. the cost of sold goods (products) produced in the customs territory of Ukraine, at the maximum retail prices set by the manufacturer, taking into account value added tax and excise tax;
{Subclause 214.1.1 of Clause 214.1 of Article 214 as amended by Law No. 909-VIII of 24.12.2015 }
214.1.2. the cost of goods (products) imported into the customs territory of Ukraine, at the maximum retail prices set by the importer for the goods (products) he imports, taking into account value added tax and excise tax;
{Subclause 214.1.2 of Clause 214.1 of Article 214 as amended by Law No. 909-VIII of 24.12.2015 }
214.1.3. the cost of the electricity sold by the producer, calculated on the basis of prices prevailing on the electricity market in the reporting (tax) period, excluding value added tax and excise tax, determined at the rate established by subparagraph 215.3.9 of paragraph 215.3 of Article 215 of this Code.
The cost of electricity sold by a producer is equal to the share of the volume of electricity sold by the producer in the total volume of electricity sold by the producer in the total cost of electricity sold by the producer in such reporting period;
{Clause 214.1 of Article 214 is supplemented by subparagraph 214.1.3 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 466-IX of 16.01.2020 }
214.1.4. the value (including value added tax and excluding excise tax on the sale of excisable goods by retail business entities) of excisable goods sold in accordance with subparagraph 213.1.9 of paragraph 213.1 of Article 213 of this Code.
{Clause 214.1 of Article 214 is supplemented by subparagraph 214.1.4 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII of 24.12.2015 }
214.1.5. the value at maximum retail prices of tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes, including value added tax and excise tax, sold in accordance with subparagraph 213.1.14 of paragraph 213.1 of Article 213 of this Code.
{Clause 214.1 of Article 214 is supplemented by subparagraph 214.1.5 in accordance with Law No. 1914-IX of 30.11.2021 }
214.2. When determining the tax base, the conversion of foreign currency into the currency of Ukraine shall be carried out at the exchange rate determined in accordance with Article 39 - 1 of this Code.
{Clause 214.2 of Article 214 as amended by Law No. 1200-VII of 10.04.2014 }
214.3. The customs value of goods imported into the customs territory of Ukraine is determined in accordance with the Customs Code of Ukraine .
214.4. In the case of calculating tax using specific rates on excisable goods (products), the tax base is their value, determined in units of weight, volume, quantity of goods (products), volume of vehicle engine cylinders, or other physical indicators.
{Clause 214.4 of Article 214 as amended by Law No. 909-VIII of 24.12.2015 }
214.5. In the case of calculating tax using both ad valorem and specific tax rates, the tax base shall be the base determined in accordance with paragraphs 214.1 and 214.4 of this Article.
214.6. Norms of production losses and yield of ethyl alcohol, alcohol distillates, bioethanol, norms of losses of alcohol, wine materials, juices during the production of alcoholic beverages, norms of production losses of alcoholic beverages are approved by the Cabinet of Ministers of Ukraine.
{ Resolutions of the Cabinet of Ministers No. 1218 of 10/28/2022 , No. 1310 of 11/22/2022 }
The total losses and waste of fermented tobacco raw materials during their storage, transportation and use in the production of tobacco products during a calendar (reporting) month may not exceed 5 percent of the total volume of such tobacco raw materials used for the production of tobacco products during such calendar (reporting) month.
During the calendar (reporting) month, the average costs of fermented tobacco raw materials for the production of all tobacco products, recorded in:
pieces, cannot exceed 600 grams per 1000 pieces of such tobacco products (excluding losses);
kilograms, cannot exceed 1000 grams per 1000 grams of such tobacco products (excluding losses).
Total losses and waste of unfermented tobacco raw materials during storage, transportation, and production of fermented tobacco raw materials during a calendar (reporting) month may not exceed 5 percent of the total volume (weight) of unfermented tobacco raw materials used for the production of fermented tobacco raw materials during the calendar (reporting) month.
{Paragraph six of clause 214.6 of Article 214 as amended by Law No. 4115-IX of 04.12.2024 }
The loss rates of liquids used in electronic cigarettes during their storage, transportation and use in production, including electronic cigarettes, during a calendar (reporting) month may not exceed 5 percent of the total volume of such liquids used in production, including electronic cigarettes, during such calendar (reporting) month.
The norms for losses of petroleum products during their reception, storage, release, reloading and transportation are approved by the Cabinet of Ministers of Ukraine.
In the event of failure to ensure the regulatory yield of ethyl alcohol, including bioethanol, and alcoholic distillates, due to the fault of the manufacturer during the production of ethyl alcohol, including bioethanol, and alcoholic distillates, the tax base is the amount of ethyl alcohol, including bioethanol, and alcoholic distillates, which is defined as the difference between the amount of ethyl alcohol, including bioethanol, and alcoholic distillates that could be produced in compliance with the yield standards approved by the Cabinet of Ministers of Ukraine, and the amount of ethyl alcohol, including bioethanol, and alcoholic distillates actually produced.
In the event of excessive losses of ethyl alcohol, including bioethanol, and alcohol distillates, the tax base is the excess quantity lost.
In the event of excessive losses of alcohol, wine materials, juices during the production of alcoholic beverages or excessive production losses of alcoholic beverages, the tax base is the number of such excessive lost goods (products).
In the presence of excess aggregate losses and waste of fermented tobacco raw materials during their storage, transportation and use in the production of tobacco products or unfermented tobacco raw materials during their storage, transportation, production of fermented tobacco raw materials, the tax base is the lost volume of tobacco raw materials that exceeds the aggregate loss and waste standards defined by this Code for the relevant calendar (reporting) month.
If there are excess costs of fermented tobacco raw materials during the production of tobacco products for the relevant calendar (reporting) month, the tax base is:
for tobacco products, the accounting of which is kept in kilograms, - the volume of fermented tobacco raw materials consumed in excess in the production of tobacco products;
for tobacco products, the accounting of which is kept in pieces, the number of such tobacco products that could be produced from the volumes of overused tobacco raw materials at the rate of 600 grams per 1,000 pieces.
The payer must ensure that separate accounting is maintained for the costs of fermented tobacco raw materials for the production of tobacco products, which are recorded in pieces and kilograms. In the absence of such accounting, compliance with the norms of average costs of fermented tobacco raw materials for the production of tobacco products is carried out based on the calculation of the costs of fermented tobacco raw materials for the production of tobacco products, which are recorded in pieces.
In the event of excessive losses of liquids used in electronic cigarettes during their storage, transportation and use in production, including electronic cigarettes, the tax base is the volume of liquids used in electronic cigarettes lost during storage, transportation and use in production, including electronic cigarettes, which exceeds the loss norms specified in this Code.
If there are excessive losses of petroleum products during their acceptance, storage, release, reloading and transportation, and if excise tax was not paid on such volumes or was paid at a preferential rate, the tax base is the volume of petroleum products lost during their acceptance, storage, release, reloading and transportation, which exceeds the loss norms approved by the Cabinet of Ministers of Ukraine.
{Clause 214.6 of Article 214 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Laws No. 2284-IX of 05/31/2022 , No. 3603-IX of 02/23/2024 }
214.7. In the event of spoilage, destruction, or loss of excisable goods (products), except for the cases provided for in Clause 216.3 of Article 216 of this Code, the tax base shall be the value and volume of lost goods (products) exceeding the established loss norms in accordance with Clause 214.6 of Article 214 of this Code.
{Clause 214.8 of Article 214 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Paragraph two of clause 215.1 of Article 215 as amended by the Law No. 2245-VIII dated 07.12.2017 ; as amended by Law No. 3193-IX dated 29.06.2023 }
tobacco products, tobacco and industrial tobacco substitutes;
tobacco raw materials, tobacco waste;
{Clause 215.1 of Article 215 is supplemented with a new paragraph in accordance with Law No. 3173-IX of 29.06.2023 }
liquids used in electronic cigarettes;
{Clause 215.1 of Article 215 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
fuel, including goods (products) used as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, spark-ignition internal combustion engines, crank-type internal combustion engines and the codes of which according to the UKT FEA are not specified in subparagraph 215.3.4 of paragraph 215.3 of this article (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKT FEA );
{Paragraph of Clause 215.1 of Article 215 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 391-IX of 18.12.2019 }
passenger cars, bodies for them, trailers and semi-trailers, motorcycles, vehicles designed to transport 10 or more people, vehicles for transporting goods;
{Paragraph of Clause 215.1 of Article 215 as amended by Law No. 71-VIII of 28.12.2014 }
electrical energy.
{Clause 215.1 of Article 215 is supplemented by a paragraph in accordance with Law No. 71-VIII of 28.12.2014 }
215.2. Tax rates and list of goods subject to tax:
215.2.1. tax rates are established by this article and are uniform throughout the territory of Ukraine;
215.2.2. tax rates are established in accordance with the definitions of Section I of this Code:
ad valorem,
specific,
ad valorem and specific at the same time;
215.2.3. excise tax rates on motor gasoline under codes according to the Ukrainian Classification of Foreign Economic Activities 2710 12 50 10, 2710 12 50 90, containing tetraethyl lead, are increased by 1.5 times.
{Subclause 215.2.3 of clause 215.2 of Article 215 as amended by Law No. 1914-IX of 11/30/2021 ; as amended by Law No. 3553-IX of 01/16/2024 }
215.3. The tax is levied on the following goods and is calculated at the following rates:
215.3.1. ethyl alcohol and other alcoholic distillates, alcoholic beverages, beer:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Ordinary (still) wines, grape must, fermented beverages, the actual strength of which is higher than 1.2 percent volume units of ethyl alcohol, but not higher than 15 percent volume units of ethyl alcohol, provided that the ethyl alcohol contained in the finished product is of entirely enzymatic (endogenous) origin
Sparkling wines and aerated wines, fermented beverages, aromatized sparkling (aerated) wines (beverages) with an actual strength of more than 1.2 percent by volume of ethyl alcohol but not more than 15 percent by volume of ethyl alcohol, provided that the ethyl alcohol contained in the finished product is of entirely enzymatic (endogenous) origin, which are bottled with special corks for such beverages of the "mushroom" type, held in place by means of ties or clasps, and/or have an excess pressure caused by the presence of carbon dioxide in solution of not less than 1 bar at a temperature of 20° C
hryvnias per 1 liter
12.23
2204, 2205, 2206 00 (wines and other fermented beverages not containing added ethyl alcohol, not elsewhere specified or included; wines and other fermented beverages containing added ethyl alcohol)
Wines and other fermented beverages (including mixtures of fermented beverages and mixtures based on fermented beverages) of an actual strength exceeding 1.2% vol. but not exceeding 22% vol. (intermediate products)
hryvnias per 1 liter
12.23
2204, 2205, 2206 00 (alcoholic beverages, whether or not containing added ethyl alcohol, not elsewhere specified or included)
Alcoholic beverages of an actual strength exceeding 22 percent by volume of ethyl alcohol, other mixtures of fermented beverages and mixtures based on fermented beverages
hryvnias for 1 liter of 100 percent alcohol
133.31
2206 00 31 00, 2206 00 51 00, 2206 00 81 00
Cider and perry (without added alcohol)
hryvnias per 1 liter
1.11
2207
Undenatured ethyl alcohol of an alcoholic strength by volume of 80 per cent or higher; ethyl alcohol and other spirituous distillates, denatured, of any strength
hryvnias for 1 liter of 100 percent alcohol
133.31
2208
Ethyl alcohol, undenatured, of an alcoholic strength by volume of less than 80 per cent, spirituous distillates and spirituous beverages obtained by distillation, liqueurs and other spirituous beverages
hryvnias for 1 liter of 100 percent alcohol
133.31
2103 90 30 00, 2106 90
Only products with an ethyl alcohol content of 8.5 percent by volume and above
hryvnias for 1 liter of 100 percent alcohol
177.73;
{Subclause 215.3.1 of clause 215.3 of Article 215 as amended by Laws No. 5503-VI of 20.11.2012 , No. 713-VII of 19.12.2013 ; as amended by Laws No. 1166-VII of 27.03.2014 , No. 1621-VII of 31.07.2014 ; as amended by Law No. 909-VIII of 24.12.2015 - the change in excise tax rates on alcoholic beverages subject to excise tax stamps shall enter into force on the first day of the third month from the date of entry into force of Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1791-VIII of 12/20/2016 ; as amended by Law No. 2245-VIII of 12/07/2017 , No. 2628-VIII of 11/23/2018 ; as amended by Law No. 1914-IX of 11/30/2021 - changes to excise tax rates on alcoholic beverages come into force from 03/01/2022 , as amended by Law No. 3553-IX of 01/16/2024 ; as amended by Law No. 3878-IX of 07/18/2024 }
215.3.2. tobacco products, tobacco and industrial tobacco substitutes:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rate
2401
Tobacco raw materials; tobacco waste
euro per 1 kilogram (net)*
85
2402 10 00 10
Cigars, including cut-end cigars, containing tobacco
euro per 1 kilogram (net)*
85
2402 10 00 90
Cigarillos, including cigarillos with cut ends, containing tobacco
euros per 1000 pieces
67
2402 20 90 10
Cigarettes without a filter, cigarettes
euros per 1000 pieces
67
2402 20 90 20
Filter cigarettes
euros per 1000 pieces
67
2403
Other manufactured tobacco and manufactured tobacco substitutes; "homogenized" or "reconstituted" tobacco; tobacco extracts and essences
euro per 1 kilogram (net)*
85
2404 11 00 10
Tobacco-containing products for electrical heating (TVEN) using an electronically controlled heater
euros per 1000 pieces
72
2404 11 00 90 2404 19 10 00
Other products containing tobacco, reconstituted tobacco and tobacco substitutes intended for inhalation without burning
euro per 1 kilogram (net)*
85
2404 91 90 00
Other nicotine-containing products for oral use
euro per 1 kilogram (net)*
85**
2404 99 00 00
Other nicotine-containing products and their substitutes
euro per 1 kilogram (net)*
85
__________ * Net weight is the weight of the goods (products) without taking into account the weight of any container or packaging. ** Excise tax on transactions with goods under code 2404 91 90 00 according to the UKT FEA is carried out starting from September 1, 2024;
{Subclause 215.3.2 of clause 215.3 of Article 215 as amended by Laws No. 5503-VI of 20.11.2012 , No. 1166-VII of 27.03.2014 , No. 1621-VII of 31.07.2014 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 , No. 2245-VIII of 07.12.2017 , No. 2628-VIII of 23.11.2018 ; as amended by Law No. 466-IX dated 01/16/2020 ; as amended by Laws No. 3553-IX dated 01/16/2024 , No. 4115-IX dated 04.12.2024 }
215.3.2 - 1. cigarettes and cigarillos:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rates
2402 20 90 10
Cigarettes without a filter, cigarettes
percent
12
2402 20 90 20
Filter cigarettes
percent
12
2402 10 00 90
Cigarillos, including cigarillos with cut ends, containing tobacco
percent
12";
{Clause 215.3 of Article 215 is supplemented by subparagraph 215.3.2 - 1 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by the Law No. 466-IX dated 16.01.2020 }
215.3.3. minimum excise tax liability for payment of excise tax on tobacco products:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rate
2402 20 90 10
Cigarettes without a filter, cigarettes
euros per 1000 pieces
90
2402 20 90 20
Filter cigarettes
euros per 1000 pieces
90
2402 10 00 90
Cigarillos, including cigarillos with cut ends, containing tobacco
euros per 1000 pieces
90, but not less than 85 euros per 1 kilogram (net);
{Subclause 215.3.3 of Clause 215.3 of Article 215 as amended by Laws No. 5503-VI of 20.11.2012 , No. 1166-VII of 27.03.2014 , No. 1621-VII of 31.07.2014 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 , No. 2245-VIII of 07.12.2017 , No. 2628-VIII of 23.11.2018 , No. 466-IX of 16.01.2020 , No. 4115-IX dated 04.12.2024 }
215.3.3 - 1. liquids used in electronic cigarettes:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Liquids used in electronic cigarettes, contained in particular in cartridges, refill containers and other containers
euro per 1 liter
300;
{Clause 215.3 of Article 215 is supplemented by subparagraph 215.3.3 - 1 in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 1914-IX of 11.30.2021 ; as amended by Law No. 2139-IX of 03.15.2022 - the change is valid during the state of war and/or emergency , as amended by Laws No. 3553-IX of 16.01.2024 , No. 4115-IX dated 04.12.2024 }
215.3.4. fuel:
Product code according to the UKTZED
Description of goods (products) according to the UKTZED
Excise tax rate in fixed amounts per unit of sold goods (products)
unit of measurement (volume in liters, reduced to t 15° C)
rate
2707 50 00 10 2707 50 00 90
Mixtures of aromatic hydrocarbons of which 65 vol. % or more (including losses) distil at temperatures up to 250 °C by the ISO 3405 method (equivalent to the ASTM D 86 method)
Other ethers, ether alcohols, ether phenols, ether alcohol phenols, alcohol peroxides, ether peroxides, ketone peroxides (whether or not chemically defined) and their halogenated, sulphonated, nitrated or nitrosated derivatives, except diethyl ether (code 2909 11 00 00 according to the UKTZED) Anti-knock preparations, antioxidants, pitch inhibitors, thickeners, anti-corrosion preparations and other prepared additives, additives for petroleum products (including gasoline) or for other liquids used for the same purposes as petroleum products:
euros per 1000 liters
359
3811 11 10 00 3811 11 90 00 3811 19 00 00
anti-knock agents
euros per 1000 liters
359
3811 90 00 00
Others
euros per 1000 liters
359
3826 00 10 00 3826 00 90 00
Biodiesel and its blends (not containing or containing less than 70% by weight of petroleum or petroleum products obtained from bituminous rocks) based on monoalkyl esters of fatty acids
Liquid fuels based on gas oils (diesel fuel), less than 85 vol. % of which, including the costs, distils at a temperature of 350° C (according to the ISO 3405 method, equivalent to the ASTM D 86 method), except for household heating fuels, base oils and other lubricants, and other distillates, which during fractional distillation according to the ISO 3405 method (or an equivalent ASTM D 86 method) at a temperature of 350° C and atmospheric pressure distil no more than 35 vol. %
euros per 1000 liters
359
3814 00 90 90
Only solvents or thinners based on methanol; other methanol-based ready-mixtures
euros per 1000 liters
359
__________
* A 10% increase is applied to the tax rate in the following cases:
import of fuel into the customs territory of Ukraine;
sales by the manufacturer of fuel produced in Ukraine.
The increasing coefficient of 10 is not applied by business entities that, in accordance with Clause 229.8 of Article 229 of this Code, have issued a tax bill.
Goods (products) used as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, spark-ignition internal combustion engines, crank-type internal combustion engines, the codes of which according to the UKTZED are not specified in this sub-item (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKTZED), are taxed at an excise tax rate of EUR 359 per 1,000 liters.
{Subclause 215.3.4 of Clause 215.3 of Article 215 as amended by Law No. 5471-VI of 06.11.2012 ; as amended by Laws No. 5503-VI of 20.11.2012 , No. 5519-VI of 06.12.2012 ; as amended by Laws No. 1166-VII of 27.03.2014 , No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 ; as amended by Laws No. 2628-VIII of 11/23/2018 , No. 391-IX of 12/18/2019 , No. 466-IX of 01/16/2020 , No. 786-IX of 07/14/2020 , No. 1914-IX of 11/30/2021 ; as amended by Laws No. 3553-IX of 01/16/2024 , No. 3878-IX of 07/18/2024 }
215.3.5. Motor vehicles designed for the transport of 10 or more persons, including the driver (except for motor vehicles specified in commodity subcategories 8702 40 00 10, 8702 40 00 90, 8702 90 90 00 according to the UKT FEA ):
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Tax rate in a fixed amount per unit of sold goods (products) (specific)
8702
Motor vehicles designed to carry 10 or more persons, including the driver:
8702 10
- only with compression-ignition internal combustion piston engine (diesel or semi-diesel):
- - with an engine cylinder capacity exceeding 2500 cc:
8702 10 11
- - - new:
8702 10 11 10
- - - - with an engine cylinder capacity not exceeding 5000 cc
0.003 euros per 1 cubic cm of engine cylinder capacity
8702 10 11 30
- - - - with an engine cylinder capacity exceeding 5000 cc
0.003 euros per 1 cubic cm of engine cylinder capacity
8702 10 19
- - - used:
8702 10 19 10
- - - - with an engine cylinder capacity not exceeding 5000 cc
0.003 euros per 1 cubic cm of engine cylinder capacity
8702 10 19 90
- - - - with an engine cylinder capacity exceeding 5000 cc
0.007 euros per 1 cubic cm of engine cylinder capacity
- - with an engine cylinder capacity not exceeding 2500 cc:
8702 10 91 00
- - - new
0.003 euros per 1 cubic cm of engine cylinder capacity
8702 10 99 00
- - - used
0.007 euros per 1 cubic cm of engine cylinder capacity
8702 20
- with compression-ignition internal combustion piston engine (diesel or semi-diesel) and electric motor as propulsion engines:
8702 20 10
- - with an engine cylinder capacity exceeding 2500 cc:
8702 20 10 10
- - - with an engine cylinder capacity not exceeding 5000 cc
new 0.003 euros per 1 cubic cm of engine cylinder capacity, used 0.007 euros per 1 cubic cm of engine cylinder capacity
8702 20 10 90
- - - with an engine cylinder capacity exceeding 5000 cc
new 0.003 euros per 1 cubic cm of engine cylinder capacity, used 0.007 euros per 1 cubic cm of engine cylinder capacity
8702 20 90 00
- - with an engine cylinder capacity not exceeding 2500 cc
new 0.003 euros per 1 cubic cm of engine cylinder capacity, used 0.007 euros per 1 cubic cm of engine cylinder capacity
8702 30
- with a spark-ignition internal combustion piston engine and an electric motor as propulsion engines:
8702 30 10 00
- - with an engine cylinder capacity exceeding 2800 cc
new 0.003 euros per 1 cubic cm of engine cylinder capacity, used 0.007 euros per 1 cubic cm of engine cylinder capacity
8702 30 90 00
- - with an engine cylinder capacity not exceeding 2800 cc
new 0.003 euros per 1 cubic cm of engine cylinder capacity, used 0.007 euros per 1 cubic cm of engine cylinder capacity
8702 90
- others:
- - with spark-ignition internal combustion piston engine:
- - - with an engine cylinder capacity exceeding 2800 cc:
8702 90 11 00
- - - - new
0.003 euros per 1 cubic cm of engine cylinder capacity
8702 90 19 00
- - - - used
0.007 euros per 1 cubic cm of engine cylinder capacity
- - - with an engine cylinder capacity not exceeding 2800 cc:
8702 90 31 00
- - - - new
0.003 euros per 1 cubic cm of engine cylinder capacity
8702 90 39 00
- - - - used
0.007 euros per 1 cubic cm of engine cylinder capacity.
Tax rates for vehicles used for more than 8 years and corresponding to code 8702 according to the UKT Foreign Economic Activity Code are applied with a coefficient of 50;
{Subclause 215.3.5 of Clause 215.3 of Article 215 as amended by Laws No. 713-VII of 19.12.2013 , No. 1166-VII of 27.03.2014 , No. 1191-VII of 08.04.2014 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 1914-IX of 30.11.2021 ; as amended by Law No. 3553-IX of 16.01.2024 }
215.3.5 - 1. passenger cars and other motor vehicles intended primarily for the transport of people, corresponding to commodity heading 8703 according to the UKT FEA (except for motor vehicles specified in commodity heading 8702 according to the UKT FEA), including cargo-passenger vans, racing cars, including cars that are submitted in accordance with the procedure established by law to the bodies carrying out state registration of vehicles for registration or re-registration in connection with a change in the model of a vehicle that, before conversion during import, corresponded to commodity heading 8704 according to the UKT FEA, and after conversion, corresponds to commodity heading 8703 according to the UKT FEA:
The tax rate (Rate) for the relevant vehicle is determined by the formula:
Rate = Base rate x K engine x K age ,
Base rate - tax rate in euros for 1 vehicle:
with a spark-ignition internal combustion engine and a crank mechanism with a cylinder capacity of up to 3,000 cubic centimeters (inclusive) - 50.0;
with a spark-ignition internal combustion engine and a crank mechanism with a cylinder capacity of over 3,000 cubic centimeters - 100.0;
with a compression-ignition internal combustion engine (diesel or semi-diesel) with a cylinder capacity of up to 3,500 cubic centimeters (inclusive) - 75.0;
with a compression-ignition internal combustion engine (diesel or semi-diesel) with a cylinder capacity of over 3,500 cubic centimeters - 150.0;
K engine - a coefficient determined by dividing the cylinder capacity of the internal combustion engine of the corresponding vehicle in cubic centimeters by 1000 cubic centimeters;
K age - a coefficient equal to the number of full calendar years from the year following the year of manufacture of the relevant vehicle to the year of determining the tax rate (for new vehicles and vehicles used for up to one full calendar year, the coefficient is 1, and for vehicles used for more than fifteen full calendar years, the coefficient is 15).
The tax rate for vehicles specified in commodity subcategories 8703 80 10 10, 8703 80 90 10 according to the UKT ZEA , equipped exclusively with electric motors (one or more), is set at 1 euro per 1 kilowatt-hour of electric battery capacity of such vehicles.
{Paragraph eleven of subparagraph 215.3.5 - 1 of paragraph 215.3 of Article 215 as amended by Law No. 1914-IX of 30.11.2021 }
The tax rate for vehicles specified in commodity subcategories 8703 10 18 00 (for vehicles propelled only by an electric motor, one or more), 8703 80 10 90, 8703 80 90 90, 8703 90 00 00 according to the UKT ZEA is set at 100 euros per 1 piece.
{Paragraph twelve of subparagraph 215.3.5 - 1 of paragraph 215.3 of Article 215 as amended by Law No. 1914-IX of 11/30/2021 }
{Clause 215.3 of Article 215 is supplemented by subparagraph 215.3.5 - 1 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2611-VIII of 08.11.2018 }
215.3.5 - 2. motor vehicles for the transport of goods:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Tax rate in a fixed amount per unit of sold goods (products) (specific)
8704
Motor vehicles for the transport of goods:
8704 10
- dump trucks designed for off-road use:
8704 10 10
- - with compression-ignition internal combustion engine (diesel or semi-diesel) or with spark-ignition internal combustion engine:
8704 10 10 10
- - - with a lifting capacity exceeding 75 t
0.016 euros per 1 cubic cm of engine cylinder capacity
8704 10 10 90
- - - others
0.016 euros per 1 cubic cm of engine cylinder capacity
8704 10 90
- - other:
8704 10 90 10
- - - dump trucks weighing up to 5 tons
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 10 90 90
- - - others
0.01 euros per 1 cubic cm of engine cylinder capacity
- Other, with compression-ignition internal combustion piston engine only (diesel or semi-diesel):
8704 21
- - with a gross vehicle weight not exceeding 5 tonnes:
- - - - with an engine cylinder capacity exceeding 2500 cc:
8704 21 31 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 21 39 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
- - - - with an engine cylinder capacity not exceeding 2500 cc:
8704 21 91 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 21 99 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
8704 22
- - with a gross vehicle weight exceeding 5 tonnes but not exceeding 20 tonnes:
8704 22 91 00
- - - - new
0.013 euros per 1 cubic cm of engine cylinder capacity
8704 22 99 00
- - - - used
0.026 euros per 1 cubic cm of engine cylinder capacity
8704 23
- - with a gross vehicle weight exceeding 20 tonnes:
8704 23 91 00
- - - - new
0.016 euros per 1 cubic cm of engine cylinder capacity
8704 23 99 00
- - - - used
0.033 euros per 1 cubic cm of engine cylinder capacity
- Other, with spark-ignition internal combustion piston engine only:
8704 31
- - with a gross vehicle weight not exceeding 5 tonnes:
- - - - with an engine cylinder capacity exceeding 2800 cc:
8704 31 31 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 31 39 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
- - - - with an engine cylinder capacity not exceeding 2800 cc:
8704 31 91 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 31 99 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
8704 32
- - with a gross vehicle weight exceeding 5 tonnes:
8704 32 91 00
- - - - new
0.013 euros per 1 cubic cm of engine cylinder capacity
8704 32 99 00
- - - - used
0.026 euros per 1 cubic cm of engine cylinder capacity
- Other, with compression-ignition internal combustion piston engine (diesel or semi-diesel) and electric motor as propulsion engines:
8704 41
- - with a gross vehicle weight not exceeding 5 tonnes:
- - - - with an engine cylinder capacity exceeding 2500 cc:
8704 41 31 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 41 39 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
- - - - with an engine cylinder capacity not exceeding 2500 cc:
8704 41 91 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 41 99 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
8704 42
- - with a gross vehicle weight exceeding 5 tonnes but not exceeding 20 tonnes:
8704 42 91 00
- - - - new
0.013 euros per 1 cubic cm of engine cylinder capacity
8704 42 99 00
- - - - used
0.026 euros per 1 cubic cm of engine cylinder capacity
8704 43
- - with a gross vehicle weight exceeding 20 tonnes:
8704 43 91 00
- - - - new
0.016 euros per 1 cubic cm of engine cylinder capacity
8704 43 99 00
- - - - used
0.033 euros per 1 cubic cm of engine cylinder capacity
- Other, with spark-ignition reciprocating internal combustion piston engine and electric motor as propulsion engines:
8704 51
- - with a gross vehicle weight not exceeding 5 tonnes:
- - - - with an engine cylinder capacity exceeding 2800 cc:
8704 51 31 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 51 39 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
- - - - with an engine cylinder capacity not exceeding 2800 cc:
8704 51 91 00
- - - - - new
0.01 euros per 1 cubic cm of engine cylinder capacity
8704 51 99 00
- - - - - used
0.02 euros per 1 cubic cm of engine cylinder capacity
8704 52
- - with a gross vehicle weight exceeding 5 tonnes:
8704 52 91 00
- - - - new
0.013 euros per 1 cubic cm of engine cylinder capacity
8704 52 99 00
- - - - used
0.026 euros per 1 cubic cm of engine cylinder capacity.
Tax rates for vehicles corresponding to commodity heading 8704 according to the UKT Foreign Economic Activity are applied for cars used from 5 to 8 years, with a coefficient of 40, for cars used for more than 8 years - with a coefficient of 50.
{Clause 215.3 of Article 215 is supplemented by subparagraph 215.3.5 - 2 in accordance with Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 3553-IX of 01/16/2024 }
215.3.6. bodies for motor vehicles specified in the commodity heading according to the UKT FEA 8703:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Tax rate in a fixed amount per unit of sold goods (products) (specific)
8707
Bodies (including cabs) for motor vehicles of headings 8701 to 8705:
8707 10
- bodies for motor vehicles of heading 8703:
8707 10 10
- - for industrial assembly:
8707 10 10 10
- - - complete
218 euros for 1 piece
8707 10 10 20
- - - not complete
218 euros for 1 piece
8707 10 90
- - other:
8707 10 90 10
- - - used for five years or less
872 euros for 1 piece
8707 10 90 20
- - - used for more than five years
872 euros for 1 piece
8707 10 90 90
- - - others
872 euros for 1 piece
{Subclause 215.3.6 of Clause 215.3 of Article 215 as amended by Law No. 1166-VII of March 27, 2014 }
215.3.7. motorcycles (including mopeds) and bicycles with an auxiliary engine, with or without sidecars:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Tax rate in a fixed amount per unit of sold goods (products) (specific)
8711 10 00 00
Motorcycles (including mopeds) and cycles fitted with an auxiliary motor, with or without side-cars, with internal combustion piston engine of a cylinder capacity not exceeding 50 cc
0.062 euros per 1 cubic cm of engine cylinder capacity
8711 20
Motorcycles (including mopeds) and cycles fitted with an auxiliary motor, with or without side-cars, with internal combustion piston engine of a cylinder capacity exceeding 50 cc but not exceeding 250 cc:
0.062 euros per 1 cubic cm of engine cylinder capacity
8711 30
Motorcycles (including mopeds) and cycles fitted with an auxiliary motor, with or without side-cars, with internal combustion piston engine of a cylinder capacity exceeding 250 cc but not exceeding 500 cc:
0.062 euros per 1 cubic cm of engine cylinder capacity
8711 40 00 00
Motorcycles (including mopeds) and cycles fitted with an auxiliary motor, with or without side-cars, with internal combustion piston engine of a cylinder capacity exceeding 500 cc but not exceeding 800 cc
0.443 euros per 1 cubic cm of engine cylinder capacity
8711 50 00 00
Motorcycles (including mopeds) and cycles fitted with an auxiliary motor, with or without side-cars, with internal combustion piston engine of a cylinder capacity exceeding 800 cc
0.447 euros per 1 cubic cm of engine cylinder capacity
8711 60
Motorcycles (including mopeds) and cycles with or without side-cars, with an electric motor for propulsion
22 euros for 1 piece
8711 90 00 00
Other motorcycles (including mopeds) and cycles fitted with an auxiliary motor, with or without side-cars; side-cars
22 euros for 1 piece
{Subclause 215.3.7 of Clause 215.3 of Article 215 as amended by Laws No. 1166-VII of 03/27/2014 , No. 71-VIII of 12/28/2014 , No. 1797-VIII of 12/21/2016 , No. 1914-IX of 11/30/2021 ; as amended by Law No. 3553-IX of 01/16/2024 }
215.3.8. trailers and semi-trailers for temporary accommodation in campsites, such as mobile homes:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Tax rate in a fixed amount per unit of sold goods (products) (specific)
8716 10 98 00
trailers and semi-trailers for temporary accommodation in camping sites, such as mobile homes, with a mass exceeding 3,500 kg, except those that are foldable
109 euros for 1 piece
{Subclause 215.3.8 of Clause 215.3 of Article 215 as amended by Law No. 1914-IX of 30.11.2021 }
215.3.9. electrical energy:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rates (ad valorem)
2716 00 00 00
Electricity
percent
3.2;
{Clause 215.3 of Article 215 is supplemented by subparagraph 215.3.9 in accordance with Law No. 71-VIII of 28.12.2014 }
215.3.10. For beer, alcoholic beverages, tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes, sold in accordance with subparagraphs 213.1.9 and 213.1.14 of paragraph 213.1 of Article 213 of this Code, the tax rate is 5 percent.
{Clause 215.3 of Article 215 is supplemented by subparagraph 215.3.10 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 1791-VIII of 20.12.2016 ; as amended by Law No. 1914-IX dated 30.11.2021 }
{Clause 215.3 of Article 215 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 4235-VI of 22.12.2011 }
{Article 215 - 1 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
Article 216. Date of occurrence of tax liabilities↑
216.1. The date of occurrence of tax liabilities for excisable goods (products) produced in the customs territory of Ukraine is the date of their sale by the person producing them, regardless of the purposes and directions of further use of such goods (products), except for the cases specified in Articles 225 and 229 of this Code.
216.2. The date of occurrence of the tax liability for spoiled, destroyed, lost excisable goods (products) is the date of drawing up the relevant act. In this paragraph, lost goods (products) are goods (products) whose location the taxpayer cannot establish.
216.3. A tax liability for lost excisable goods (products) does not arise if:
a) the taxpayer documented these losses and provided the regulatory authorities with the necessary evidence that the relevant excisable goods (products) were lost as a result of an accident, fire, flood or other force majeure circumstances and their use in the customs territory of Ukraine is impossible;
b) the excisable goods (products) were lost due to evaporation during the production, processing, processing, storage or transportation of such goods (products) or for another reason related to a natural result. This requirement applies in the case of loss of excisable goods (products) within the limits of the loss standards approved in accordance with the procedure determined by the Cabinet of Ministers of Ukraine;
{Subparagraph "b" of paragraph 216.3 of Article 216 as amended by Law No. 4834-VI of 24.05.2012 ; for further information on the amendments, see No. 5083-VI of 05.07.2012 ; as amended by Law No. 5412-VI of 02.10.2012 }
c) excisable goods (products):
forcibly alienated or seized for state needs in accordance with the Law of Ukraine "On the Transfer, Forcible Alienation or Seizure of Property under the Legal Regime of Martial Law or a State of Emergency", provided that in the future its previous owner or a person authorized by him will not take measures to obtain compensation for the forcibly alienated excisable goods (products);
transferred to the Armed Forces of Ukraine and volunteer formations of territorial communities, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their formations, military units, subdivisions, institutions or organizations formed in accordance with the laws of Ukraine, maintained at the expense of the state budget, for the needs of ensuring the defense of the state, local self-government bodies, as well as in favor of the central executive body that ensures the formation and implementation of state policy in the field of civil defense, civil defense forces and/or health care institutions of state, municipal property, and/or structural units on health care issues of regional, Kyiv and Sevastopol city state administrations without prior or subsequent reimbursement of their value;
provided as humanitarian aid.
{ Clause 216.3 of Article 216 is supplemented by subparagraph "c" in accordance with Law No. 2120-IX of March 15, 2022 }
216.4. The date of occurrence of tax liabilities in the event of import of excisable goods (products) into the customs territory of Ukraine is the date of submission of a customs declaration to the controlling authority for customs clearance or the date of accrual of such tax liability by the controlling authority in cases specified by law.
216.5. When transferring excisable goods (products) manufactured from toll raw materials, the date of occurrence of tax liabilities is the date of their shipment by the manufacturer to the customer or, on his behalf, to another person.
216.6. When using excisable goods (products) for one's own production needs, the date of occurrence of tax liabilities is the date of their transfer for such use, except for use for the production of excisable goods (products).
{Clause 216.7 of Article 216 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Clause 216.8 of Article 216 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
216.9. The date of occurrence of tax obligations for the sale of excisable goods by retail business entities is the date of the settlement transaction in accordance with the Law of Ukraine "On the Use of Registrars of Settlement Transactions in the Sphere of Trade, Public Catering and Services", for non-cash settlements - the date of execution of a settlement document for the amount of the transaction, which confirms the fact of sale, and in the case of sale of goods by individuals - entrepreneurs who pay a single tax, - the date of receipt of payment for the sold goods, and for excisable goods, the presence or location of which is not confirmed by such business entity, including such goods, the shortage of which was detected according to the results of an inventory conducted by a retail business entity at the request of a regulatory authority during an inspection by such authority, - the date of drawing up the relevant document certifying the specified facts.
{Article 216 is supplemented by paragraph 216.9 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Laws No. 1791-VIII of 20.12.2016 , No. 1914-IX of 30.11.2021 }
216.10. The date of occurrence of tax obligations for the supply of electricity is the date of preparation of the document certifying the fact of the supply of electricity. For documents drawn up in electronic form, the date of preparation of the document is the date indicated in the document itself as the date of its preparation in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", regardless of the date of affixing the electronic signature.
{Article 216 is supplemented by paragraph 216.10 in accordance with Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 2173-IX of 04/01/2022 }
216.11. The date of occurrence of tax liabilities in the event of conversion of a freight vehicle, which corresponds to commodity heading 8704 according to the UKT FEA , into a passenger car, which corresponds to commodity heading 8703 according to the UKT FEA, is the date of issuance of a document on the compliance of the converted vehicle with road safety requirements. In this case, the excise tax is paid by the owner of such a vehicle no later than the date of submission of documents to the body carrying out state registration of vehicles for registration or re-registration of such a vehicle.
{Article 216 is supplemented by paragraph 216.11 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 2611-VIII of 08.11.2018 }
216.12. The date of occurrence of tax liabilities for transactions specified in subparagraph 213.1.12 of paragraph 213.1 of Article 213 of this Code is the date of sale of such volumes of fuel or ethyl alcohol.
{Article 216 is supplemented by paragraph 216.12 in accordance with Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 2628-VIII of 23.11.2018 }
216.13. The date of occurrence of tax liabilities for transactions specified in subparagraph 213.1.13 of paragraph 213.1 of Article 213 of this Code is the date of use of goods (products) as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, with spark-ignition internal combustion engines, with crank-rod internal combustion engines, the codes of which according to the UKT FEA are not specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKT FEA ).
{Article 216 is supplemented by paragraph 216.13 in accordance with Law No. 391-IX of 18.12.2019 }
216.14. The date of occurrence of tax liabilities for the sale of tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes, in accordance with subparagraph 213.1.14 of paragraph 213.1 of Article 213 of this Code is the date of sale by manufacturers and/or importers of tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes in retail trade or to business entities engaged in wholesale and/or retail trade in such products.
{Article 216 is supplemented by paragraph 216.14 in accordance with Law No. 1914-IX of 30.11.2021 }
Article 217. Procedure for calculating tax on excisable goods (products) produced in the customs territory of Ukraine, as well as on excisable goods (products) sold by retail business entities, and on goods (products) used as fuel↑
{Title of Article 217 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 391-IX of 12/18/2019 }
217.1. The amounts of tax payable on excisable goods (products) produced in the customs territory of Ukraine, on excisable goods (products) sold by retail business entities, and on goods (products) whose codes according to the UKT FEA are not specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKT FEA ), which are used as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, with spark-ignition internal combustion engines, with crank-and-rod internal combustion engines, are determined by the taxpayer independently based on the objects of taxation, the tax base and the rates of this tax in force on the date of the occurrence of tax liabilities. obligations.
{Clause 217.1 of Article 217 as amended by Law No. 909-VIII of 24.12.2015 ; as amended by Law No. 391-IX of 18.12.2019 }
217.2. The amounts of tax on excisable goods (products) produced from toll raw materials are determined by the manufacturer (processor), based on the objects of taxation, the tax base and the rates of this tax, which are in effect on the date of shipment of the finished product to its customer or, on his behalf, to another person.
217.3. Tax on excisable goods (products) produced in the customs territory of Ukraine, and goods (products) whose codes according to the UKT FEA are not specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKT FEA), which are used as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, with spark-ignition internal combustion engines, with crank-and-connecting internal combustion engines, for which tax rates are set in foreign currency, is paid in national currency and calculated at the official exchange rate of hryvnia to foreign currency established by the National Bank of Ukraine, effective on the first day of the quarter in which the goods (products) are sold, and remains unchanged during the quarter. The tax on tobacco products, liquids used in electronic cigarettes produced in the customs territory of Ukraine, tobacco raw materials and tobacco waste is calculated in the national currency at the official exchange rate of Ukraine to foreign currency, determined in accordance with Article 39-1 of this Code , taking into account the features determined by Article 222 of this Code.
{Clause 217.3 of Article 217 as amended by Laws No. 1791-VIII of 20.12.2016 , No. 391-IX of 18.12.2019 ; as amended by Law No. 4115-IX of 04.12.2024 }
217.4. It is prohibited to pay tax amounts by means of mutual offsets, counter-obligations, bills of exchange and in other forms that do not provide for the payment of such tax amounts in cash.
217.5. In the event of a full or partial return by the buyer of excisable goods (products) manufactured (produced) in the customs territory of Ukraine to the seller to eliminate the defects of the goods (products) or its destruction (processing) due to the impossibility of eliminating such defects, the taxpayer - the seller shall adjust tax liabilities for payment of excise tax in the reporting period in which such return occurred.
The adjustment amount is calculated by the taxpayer using the maximum retail prices, excise tax rates, taking into account the minimum tax liability for payment of excise tax, which were in effect on the date of the tax liability for such goods (products).
The amount of the adjustment is indicated in the excise tax declaration for the reporting period in which such a refund occurred.
In the event of further sale of these goods (products), excise tax obligations are calculated in the general manner.
217.6. For fuel, in the production of which other taxable excisable goods were used as raw materials, the amount of tax payable is reduced by the amount of tax calculated for such raw materials.
The amount of tax on raw materials subject to deduction is calculated using the tax rates for such raw materials in effect on the date of sale of the fuel. If such amount exceeds the amount of tax on fuel produced from such raw materials, the difference is not reimbursed to the payer.
The norms of this paragraph shall apply during the operation of the electronic administration system for the sale of fuel and ethyl alcohol, defined by Article 232 of this Code.
{Paragraph three of clause 217.6 of Article 217 as amended by Law No. 2628-VIII of 23.11.2018 }
{Article 217 was supplemented by paragraph 217.6 in accordance with Law No. 909-VIII of 24.12.2015 }
Article 218. Procedure for calculating tax on goods imported into the customs territory of Ukraine↑
218.1. The amounts of tax on goods (products) imported into the customs territory of Ukraine that are subject to payment are determined by taxpayers independently, based on the objects of taxation, the tax base and the rates of this tax.
218.2. Tax on excisable goods (products) imported into the customs territory of Ukraine shall be calculated in the national currency at the exchange rate determined in accordance with Article 39 - 1 of this Code.
{Clause 218.2 of Article 218 as amended by Law No. 1200-VII of 10.04.2014 }
218.3. In the event of loss of goods under customs control in customs regimes in which exemption or conditional exemption from taxation has been granted, misuse of these goods, or failure to take measures to terminate such customs regimes within the time limits established by the Customs Code of Ukraine , the amounts of tax payable shall be determined based on the objects of taxation, the tax base and the rates of this tax in force on the date of submission of the customs declaration upon placement in the relevant customs regime. In this case, the person responsible for compliance with the customs regime shall be obliged to pay such amount and a penalty accrued in accordance with Article 129 of this Code, calculated from the date of granting exemption or conditional exemption from taxation.
{Clause 218.3 of Article 218 as amended by Law No. 4915-VI of 07.06.2012 }
218.4. In the event of a full or partial return by the importer of excisable goods (products) imported into the customs territory of Ukraine to the seller due to their unsuitability for sale in the customs territory of Ukraine, the taxpayer - importer shall adjust tax obligations for payment of excise tax in the reporting period in which the unused and damaged stamps were returned, or the relevant documents confirming the loss of the stamps are provided to the regulatory authority that issued the stamps.
The adjustment amount is calculated by the taxpayer using the maximum retail prices, excise tax rates, taking into account the minimum tax liability for payment of excise tax, which were in effect on the date of the tax liability for such goods (products).
The amount of the adjustment is indicated in the excise tax declaration for the relevant reporting period. At the same time, the amount of excise tax, at the request of the importer, is returned to his account at the bank/non-bank payment service provider at the bank or is credited when purchasing subsequent batches of excise tax stamps.
{Paragraph three of clause 218.4 of Article 218 as amended by Law No. 2888-IX of 12.01.2023 }
{Article 219 was excluded on the basis of Law No. 4915-VI of 07.06.2012 }
{Article 219 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
Article 220. Peculiarities of calculating the tax on tobacco products at ad valorem rates↑
{Title of Article 220 as amended by Law No. 71-VIII of 28.12.2014 }
{For a partial change in the provisions of Article 220, manufacturers or importers of tobacco products may submit a new declaration on the established maximum retail prices in the month in which Law No. 4235-VI of 22.12.2011 was published, including the last working day of this calendar month - see paragraph 2 of Section II of Law No. 4235-VI of 22.12.2011 }
220.1. The establishment of maximum retail prices for excisable goods (products) is carried out by the manufacturer or importer of goods (products) by declaring such prices.
220.2. The declaration on maximum retail prices for excisable goods (products) (hereinafter referred to as the declaration), established by the manufacturer or importer of goods (products), shall be submitted to the central executive body implementing state tax policy by means of electronic communication in an electronic form determined by the central executive body ensuring the formation and implementation of state financial policy, using a qualified electronic signature or an advanced electronic signature based on a qualified electronic signature certificate, of the accountable person in the manner prescribed by the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Clause 220.2 of Article 220 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2725-VIII of 16.05.2019 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 2918-IX of 07.02.2023 }
220.3. The declaration must contain information about the maximum retail prices established by the manufacturer or importer for all excisable goods (products) produced by him in Ukraine, or for all excisable goods (products) imported by him into Ukraine, and the date from which the maximum retail prices are established.
220.4. The declaration shall be submitted by the manufacturer or importer of excisable goods (products) to the central executive body implementing state tax policy no later than the 10th and 25th of the month.
{Clause 220.4 of Article 220 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 71-VIII of 28.12.2014 }
220.5. The declaration shall not be accepted in the following cases:
submission later than five calendar days before the date of establishment of maximum retail prices therein;
setting in the declaration the maximum retail price for excisable goods in an amount lower than the amount established by subparagraph 14.1.106 of paragraph 14.1 of Article 14 of this Code;
inconsistency of its form with the form determined by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 220.5 of Article 220 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 4115-IX of 04.12.2024 - for the effect of the amendments, see clause 2 of section II}
220.6. The declaration is submitted electronically in electronic form by an authorized person of the manufacturer or importer of excisable goods (products) and is considered accepted upon receipt of a receipt for receipt of the tax declaration by electronic means, containing the date of acceptance and the registration number of the accepted declaration.
{Clause 220.6 of Article 220 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 ; as amended by Law No. 71-VIII of 28.12.2014 }
220.7. Maximum retail prices for goods (products) listed in the declaration, established by the manufacturer or importer no later than the 10th, shall be implemented from the 15th of the month in which the declaration is submitted, and those established no later than the 25th - from the 1st of the month following the month in which the declaration is submitted to the central executive body implementing state tax policy, and shall be effective until they are changed in accordance with the procedure established by this Code.
{Clause 220.7 of Article 220 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 ; as amended by Law No. 71-VIII of 28.12.2014 }
220.8. If it is necessary to change any information contained in the declaration on maximum retail prices for excisable goods (products) submitted by their manufacturer or importer to the central executive body implementing state tax policy, the manufacturer or importer must submit a new declaration to such bodies.
{Clause 220.8 of Article 220 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 , No. 1797-VIII of 21.12.2016 , No. 1797-VIII of 21.12.2016 }
220.9. Any changes to information contained in the declaration on maximum retail prices for excisable goods (products) submitted by their manufacturer or importer to the central executive body implementing state tax policy may be made no more than twice a month.
{Clause 220.9 of Article 220 as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 }
{Clause 220.10 of Article 220 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
220.11. The maximum retail prices for excisable goods (products) established by the manufacturer or importer must be marked on the consumer packaging of such goods together with the date of their production.
Article 221. Peculiarities of calculating the tax on tobacco products↑
221.1. The calculation of tax amounts on tobacco products is carried out simultaneously at ad valorem and specific rates.
221.2. When determining the tax liability for cigarettes, cigarillos, and cigarillos of the same name, the amount of excise tax calculated simultaneously at the established ad valorem and specific excise tax rates must not be less than the established minimum excise tax liability.
{Clause 221.2 of Article 221 as amended by Law No. 466-IX of January 16, 2020 }
221.3. If there are such products of the same name at a place of sale of tobacco products, the packs, boxes and souvenir boxes of which have different maximum retail prices, the sale of such tobacco products shall be carried out at prices not higher than those indicated on the relevant packs, boxes and souvenir boxes, increased by the amount of excise tax on tobacco products, tobacco and industrial tobacco substitutes sold by retail business entities.
{Clause 221.3 of Article 221 as amended by Law No. 71-VIII of 28.12.2014 }
221.4. Control over compliance by business entities engaged in retail trade in tobacco products, liquids used in electronic cigarettes, with the requirements for maximum retail prices for tobacco products, liquids used in electronic cigarettes established by manufacturers or importers of such products, the amount of retail sales prices of excisable goods for which maximum retail prices are established, and the correctness of the calculation of excise tax on tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes sold by business entities in retail trade, is carried out by regulatory authorities.
{Clause 221.4 of Article 221 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 4115-IX of 04.12.2024 }
221.5. In the event of the sale of tobacco raw materials to business entities that are not producers of tobacco products and/or tobacco fermentation plants, a fine of 200 percent of the value of the sold tobacco raw materials shall be imposed on the entities that carried out such sale. The raw materials sold in this way shall be subject to confiscation and destruction.
{Article 221 was supplemented by paragraph 221.5 in accordance with Law No. 1797-VIII of 21.12.2016 }
221.6. The share of the total amount of tax liabilities from the excise tax on cigarettes must be at least 60 percent of the weighted average retail selling price of cigarettes.
If the share of the total amount of tax liabilities from excise tax on cigarettes for the previous year is less than 60 percent of the weighted average retail selling price of cigarettes for the same year, when determining the tax liability for cigarettes under the UKT FEA codes 2402 20 90 10, 2402 20 90 20 from April 1 to December 31 of the current year, the amount of excise tax shall not be less than the established minimum excise tax liability multiplied by a coefficient of 1.1.
{Article 221 is supplemented by paragraph 221.6 in accordance with Law No. 2245-VIII of 07.12.2017 - enters into force on January 1, 2025, see paragraph 1 of Part II of Law No. 2245-VIII of 07.12.2017}
221.7. Excise tax on sold tobacco products, tobacco and industrial tobacco substitutes, liquids used in electronic cigarettes, in accordance with subparagraph 213.1.14 of paragraph 213.1 of Article 213 of this Code, is calculated and paid by taxpayers independently in the event of their sale of tobacco products, tobacco and/or industrial tobacco substitutes, liquids used in electronic cigarettes, in retail trade or to business entities engaged in wholesale and/or retail trade in such products.
{Article 221 is supplemented by paragraph 221.7 in accordance with Law No. 1914-IX of 30.11.2021 }
Article 222. Procedure and deadlines for tax payment↑
222.1. Deadlines for payment of tax on excisable goods (products) produced in the customs territory of Ukraine, on excisable goods (products) sold by retail business entities, and goods (products) whose codes according to the UKT FEA are not specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKT FEA ), which are used as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, with spark-ignition internal combustion engines, with crank-and-rod internal combustion engines
{Paragraph one of clause 222.1 of Article 222 as amended by Law No. 909-VIII of 24.12.2015 ; clause 222.1 of Article 222 as amended by Law No. 391-IX of 18.12.2019 }
222.1.1. Tax amounts shall be transferred to the budget by excise tax payers within 10 calendar days following the last day of the relevant deadline provided for by this Code for submitting a tax return for a monthly tax period.
{Subclause 222.1.1 of Clause 222.1 of Article 222 as amended by Law No. 71-VIII of 28.12.2014 }
222.1.2. Tax amounts on alcoholic beverages, for the production of which undenatured ethyl alcohol is used, are paid upon purchase of excise tax stamps.
The amounts of tax, taking into account the minimum excise tax liability for the payment of excise tax on tobacco products, tax rates in force in accordance with the norms of this Code, and the official exchange rate of the Ukrainian currency to foreign currency established by the National Bank of Ukraine, which was in force at 0 o'clock on the first day of the calendar half-year preceding the half-year in which the excise tax stamps were purchased, shall be paid by tobacco product manufacturers to the budget within 15 working days after receiving the excise tax stamps with a surcharge (if necessary) within 10 calendar days following the last day of the deadline provided for by this Code for submitting a tax declaration for the monthly tax period, which shall be determined taking into account the official exchange rate of the Ukrainian currency to foreign currency established by the National Bank of Ukraine, which was in force at 0 o'clock on the first day of the calendar half-year preceding the half-year in which such tobacco products are sold. If the specified period falls on a day of the next fiscal year, the amount of excise tax shall be paid by tobacco product manufacturers before the end of the fiscal year in which the stamps were received.
The amounts of tax on liquids used in electronic cigarettes, taking into account the official exchange rate of the Ukrainian currency to foreign currency established by the National Bank of Ukraine, which was in effect at 0:00 on the first day of the calendar half-year preceding the half-year in which the excise tax stamps were purchased, shall be paid by the producers of such liquids to the budget within 15 working days after receiving the excise tax stamps with a surcharge (if necessary) within 10 calendar days following the last day of the deadline provided for by this Code for submitting a tax return for the monthly tax period, which is determined taking into account the official exchange rate of the Ukrainian currency to foreign currency established by the National Bank of Ukraine, which was in effect at 0:00 on the first day of the calendar half-year preceding the half-year in which the sale of such liquids used in electronic cigarettes is carried out. If the specified period falls on a day of the following fiscal year, the amount of excise tax shall be paid by manufacturers of liquids used in electronic cigarettes before the end of the fiscal year in which the stamps were received.
In case of failure to meet the conditions specified in paragraphs two and three of this sub-clause, stamps for subsequent applications-calculations of manufacturers of tobacco products and manufacturers of liquids used in electronic cigarettes shall not be issued until the day on which the excise tax and penalties calculated in accordance with clause 124.1 - 1 of Article 124 of this Code are paid in full.
{Subclause 222.1.2 of Clause 222.1 of Article 222 as amended by Laws No. 5503-VI of 20.11.2012 No. 1797-VIII dated 12/21/2016 , No. 2245-VIII dated 12/07/2017 , No. 466-IX dated 01/16/2020 , No. 1914-IX dated 11/30/2021 ; as amended by Law No. 4115-IX dated 12/04/2024 }
222.1.3. Enterprises that produce grape wines with added alcohol and fortified wines, vermouths, other fermented beverages with added alcohol, mixtures of fermented beverages with added alcohol, mixtures of fermented beverages with non-alcoholic beverages with added alcohol, pay tax upon purchase of excise tax stamps in the amount calculated from the tax rates for finished products made from wine materials or must, in the production of which ethyl alcohol is used.
222.1.4. The owner of finished products manufactured from toll raw materials shall pay the tax to the manufacturer (processor) no later than the date of shipment of the finished products to such owner or, on his behalf, to another person.
222.1.5. The condition for the shipment by the manufacturer of finished products manufactured from toll raw materials to his customer or, on his behalf, to another person is documentary confirmation from the bank/non-bank payment service provider of the transfer of the relevant tax amount to the account with the manufacturer's bank/non-bank payment service provider.
{Subclause 222.1.5 of clause 222.1 of Article 222 as amended by Law No. 2888-IX of 12.01.2023 }
222.2. Payment of tax in case of import of excisable goods into the customs territory of Ukraine
222.2.1. Tax on excisable goods (products) imported into the customs territory of Ukraine shall be paid by taxpayers before or on the day of submission of the customs declaration.
222.2.2. In the case of import of marked excisable products (except for tobacco products and liquids used in electronic cigarettes) into the customs territory of Ukraine, the tax is paid upon purchase of excise tax stamps with a surcharge (if necessary) on the day of submission of the customs declaration.
In the case of import of marked tobacco products, liquids used in electronic cigarettes, into the customs territory of Ukraine, the tax is paid upon purchase of excise tax stamps, taking into account the official exchange rate of the Ukrainian currency to foreign currency, established by the National Bank of Ukraine, in effect at 0:00 on the first day of the calendar half-year preceding the half-year in which the excise tax stamps are purchased, with a surcharge (if necessary) on the day of submission of the customs declaration, which is determined taking into account the official exchange rate of the Ukrainian currency to foreign currency, established by the National Bank of Ukraine, in effect at 0:00 on the first day of the calendar half-year preceding the half-year in which the customs declaration for the import of such tobacco products, liquids used in electronic cigarettes into the customs territory of Ukraine is submitted.
{Subparagraph 222.2.2 of paragraph 222.2 of Article 222 as amended by Law No. 4115-IX of 04.12.2024 }
{Subclause 222.2.3 of clause 222.2 of Article 222 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
222.2.4. Excise tax payers, when applying to the bodies carrying out state registration of vehicles for registration or re-registration of a converted freight vehicle into a passenger car, are required to present receipts or payment instructions for tax payment with a note from the bank/non-bank payment service provider on the date of its execution.
{Clause 222.2 of Article 222 is supplemented by subparagraph 222.2.4 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 2611-VIII of 08.11.2018 , No. 2888-IX of 12.01.2023 }
222.3. Payment of tax upon sale of excisable goods by a retail business entity.
222.3.1. Tax amounts shall be transferred to the budget by a retail business entity that sells excisable goods within 10 calendar days following the last day of the relevant deadline provided for by this Code for submitting a tax return for a monthly tax period.
222.3.2. A person - a retail business entity that sells excisable goods shall pay tax at the place of sale of such goods.
{Article 222 was supplemented by paragraph 222.3 in accordance with Law No. 71-VIII of 28.12.2014 }
Article 223. Preparation and submission of excise tax declaration↑
223.1. The base tax period for tax payment corresponds to a calendar month.
223.2. Taxpayers specified in clause 212.1 of Article 212 of this Code (except for importers of excisable goods specified in subparagraphs 215.3.4 , 215.3.5 , 215.3.5 - 1 , 215.3.5 - 2 , 215.3.6 , 215.3.7 , 215.3.8 of clause 215.3 of Article 215 of this Code) shall submit a monthly excise tax declaration to the controlling authority at the place of registration no later than the 20th day of the following reporting (tax) period in the form approved in accordance with the procedure established by Article 46 of this Code.
{Clause 223.2 of Article 223 as amended by Laws No. 71-VIII of 12/28/2014 , No. 1797-VIII of 12/21/2016 }
224.1. Control over the correctness of the calculation and timeliness of payment to the budget of tax on excisable goods (products) produced in the territory of Ukraine is carried out by the controlling bodies.
224.2. Control over the correctness of the calculation, completeness and timeliness of payment to the budget of tax on excisable goods (products) imported into the customs territory of Ukraine during customs clearance is carried out by the controlling authorities.
{Clause 224.2 of Article 224 as amended by Law No. 404-VII of 04.07.2013 }
Article 225. Peculiarities of taxation of alcoholic beverages↑
225.1. A business entity is obliged to pay tax or submit to the regulatory authority at its location, prior to receiving undenatured ethyl alcohol from an excise warehouse intended for processing into alcoholic beverages (except wine materials and vermouths), a tax bill, which is a security for the fulfillment of the obligation of such a payer within a period of up to 90 calendar days, starting from the date of issue of the tax bill, to pay the amount of tax calculated at the rates for this product.
{Clause 225.1 of Article 225 as amended by Law No. 5074-VI of 05.07.2012 }
225.2. When receiving undenatured ethyl alcohol, the issuing enterprise, with the participation of a representative of the controlling body at the excise warehouse, draws up an act on the actually received quantity of alcohol and the calculation of excise tax based on the actually received quantity of alcohol. This act is an adjustment to the already paid amount of tax or the provided tax bill, indicating the final amount of tax payable.
225.3. The adjusted amount of tax in a tax bill is paid in part in the event of the purchase of excise tax stamps during the validity period of such bill.
225.4. A tax bill is considered to be paid by the drawer if the tax amount is paid in full and within the period specified in the tax bill.
225.5. The amount of tax for which the bill is repaid is determined based on the actually received quantity of alcohol (in accordance with the act) and the tax rates for finished products, reduced by the amount of tax calculated based on the actually lost quantity of ethyl alcohol during transportation and storage, in the process of production of finished products within the limits of the norms approved in the established procedure, as well as the actually returned irreparable defect. The calculation of the amount of tax reduction is carried out in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
225.5 - 1. For the import into the customs territory of Ukraine by a producer of alcoholic beverages in containers that are not consumer containers, for their bottling into consumer containers, such producer shall, prior to import, submit to the regulatory authority at its location a tax bill drawn up in triplicate, which shall be a security for the fulfillment of the obligation of such payer within a period of up to 90 calendar days, starting from the date of issue of the tax bill, to pay the amount of tax calculated at the rates for these products.
One copy is submitted to the regulatory authority at the location of the manufacturer, the second to the regulatory authority at the place of customs clearance of the specified goods, and the third remains with the taxpayer.
The bill holder is the regulatory authority at the place of registration of the drawer.
A tax bill is issued for the amount of excise tax levied upon the import of goods in accordance with the legislation.
The basis for customs clearance of alcoholic beverages in containers that are not consumer containers, imported into the customs territory of Ukraine for the purpose of bottling them into consumer containers, is the submission by such a manufacturer to the regulatory authority that carries out customs clearance, in accordance with the procedure provided for by the Customs Code of Ukraine , by electronic means of communication, of a copy of a tax bill endorsed by a bank and registered by the regulatory authority at the location of the manufacturer.
Obligations to repay a tax bill cannot be transferred to other persons, regardless of their relationship with the drawer.
No interest or other fees provided by law for other types of bills are charged for the use of a tax bill.
The amount of tax for which the bill is repaid is determined based on the actual quantity of alcoholic beverages imported (according to the customs declaration) and the tax rates on finished products, reduced by the amount of tax calculated based on the actual quantity of alcoholic beverages lost during transportation and storage, in the process of production (bottling) of finished products within the limits of the norms approved in the prescribed manner. The adjusted amount of tax in the tax bill is paid in part when purchasing excise tax stamps or in the case of forming unique identifiers during the validity period of such a bill.
{Article 225 is supplemented by paragraph 225.5 - 1 in accordance with Law No. 3173-IX of 29.06.2023 }
225.6. In the case of export (export) of excisable goods (products) outside the customs territory of Ukraine, the amount of tax for repayment of the tax bill is determined taking into account the volumes of products shipped for export in accordance with a properly executed customs declaration.
225.7. If the tax bill provided for in this Article is not repaid within the specified period, the bill holder shall protest such bill in default in accordance with the law and, within one business day from the date of the protest, shall apply to the bank that has avalized this bill with the protested bill. The avalizing bank shall be obliged to transfer the amount specified in this bill to the bill holder no later than the business day following the date of the bill holder's application with the protested bill. Partial repayment of a tax bill after the expiration of the term for which it was issued is prohibited.
225.8. If a tax bill, the payment term of which has come, has not been repaid, the next bill may not be issued by such entity.
225.9. Wine materials sold to secondary winemaking enterprises that use these wine materials for the production of finished products, grape wine materials (codes according to the UKT FEA 2204 29-2204 30), produced at primary winemaking enterprises that are exported by these enterprises, are not taxed. In other cases, the sale of wine materials is taxed at the tax rates for winemaking products established by subparagraph 215.3.1 of paragraph 215.3 of Article 215 of this Code.
{Clause 225.9 of Article 225 as amended by Law No. 2836-XI of 13.12.2022 }
225.10. The procedure for the issuance, circulation and repayment of tax bills in accordance with this article shall be established by the Cabinet of Ministers of Ukraine.
{Article 225 is supplemented by paragraph 225.10 in accordance with Law No. 3173-IX of 29.06.2023 }
Article 226. Production, storage, sale of excise tax stamps and labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes↑
{Title of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
226.1. In the case of production in the customs territory of Ukraine of alcoholic beverages, tobacco products and liquids used in electronic cigarettes, or import of such goods into the customs territory of Ukraine, taxpayers are obliged to ensure that they are marked with stamps of the established sample in such a way that the excise tax stamp is torn during uncorking (opening) of the goods.
{Clause 226.1 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
226.2. The presence of an excise tax stamp of the established sample, affixed in accordance with the established procedure, on a bottle (packaging) of an alcoholic beverage, a pack (packaging) of a tobacco product or a container (packaging) with liquid used in electronic cigarettes is one of the conditions for importing such goods into the customs territory of Ukraine and selling them to consumers, as well as confirmation of payment of tax and legality of the import of goods.
{Clause 226.2 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
226.3. The production, storage, sale of excise tax stamps and labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes shall be carried out in accordance with the regulations approved by the Cabinet of Ministers of Ukraine.
{Clause 226.3 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
226.4. Excise tax stamps for alcoholic beverages and tobacco products produced in Ukraine differ in design and color from stamps for alcoholic beverages and tobacco products imported into the customs territory of Ukraine.
Excise tax stamps for tobacco products manufactured in Ukraine under the UKT ZED code 2402 20 90 20 and 2402 20 90 10 differ from excise tax stamps for other tobacco products manufactured in Ukraine in design and color. Excise tax stamps for tobacco products imported into Ukraine under the UKT ZED code 2402 20 90 20 and 2402 20 90 10 differ from excise tax stamps for other tobacco products imported into Ukraine in design and color.
{Clause 226.4 of Article 226 is supplemented by the second paragraph in accordance with Law No. 2245-VIII of 07.12.2017 - enters into force on July 1, 2018, see clause 1 of Part II of Law No. 2245-VIII of 07.12.2017 }
226.5. Labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes shall be carried out with excise tax stamps, samples of which shall be approved by the Cabinet of Ministers of Ukraine.
{Clause 226.5 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
226.6. All alcoholic beverages (except those specified in paragraph 226.10 of this Article) with an ethyl alcohol content of more than 8.5 percent by volume shall be subject to labeling. Alcoholic beverages produced in Ukraine with an ethyl alcohol content of up to 8.5 percent by volume shall not be labeled.
{Clause 226.6 of Article 226 as amended by Laws No. 71-VIII of 12/28/2014 , No. 1914-IX of 11/30/2021 }
226.7. Each excise tax stamp on alcoholic beverages must have a separate number, month and year of issue of the stamp and an indication of the amount of excise tax paid per unit of labeled products, in addition to the amount of excise tax on the sale of alcoholic beverages by retail business entities.
{Clause 226.7 of Article 226 as amended by Law No. 71-VIII of 28.12.2014 }
226.8. Each excise tax stamp on tobacco products must have a separate number and an indication of the quarter and year of issue of the stamp.
The number of pieces in a pack (packaging) is additionally marked on the excise tax stamp for cigarettes, cigarillos, and cigarillos.
{ Paragraph 226.8 of Article 226 is supplemented with a new paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
Manufacturers and importers of tobacco products keep records and report on the use of excise tax stamps by type of stamp (TI - "imported tobacco", TV - "domestic tobacco") in quantitative terms.
{Clause 226.8 of Article 226 is supplemented by a paragraph in accordance with Law No. 3609-VI of 07.07.2011 }
Each excise tax stamp on liquids used in electronic cigarettes must have a separate number and a designation of the quarter and year of issue of the stamp.
{ Paragraph 226.8 of Article 226 is supplemented with a fourth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
Manufacturers and importers of liquids used in electronic cigarettes keep records and report on the use of excise tax stamps by type of stamp (PI - "imported liquid", RP - "domestic liquid") in quantitative terms.
{ Paragraph 226.8 of Article 226 is supplemented with a fifth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
226.9. The following are considered unmarked:
alcoholic beverages, tobacco products and liquids used in electronic cigarettes with counterfeit excise tax stamps;
{Paragraph two of clause 226.9 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
alcoholic beverages, tobacco products and liquids used in electronic cigarettes, labeled in deviation from the requirements of the regulation approved by the Cabinet of Ministers of Ukraine, in accordance with which the manufacture, storage, sale of excise tax stamps and labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes are carried out, and/or with stamps that were not issued directly to the manufacturer or importer of the specified products;
{Paragraph three of paragraph 226.9 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
alcoholic beverages produced in Ukraine with excise tax stamps, on which the indication of the amount of excise tax paid per unit of labeled product does not correspond to the amount determined taking into account the excise tax rates in effect on the date of bottling of the product, the strength of the product and the capacity of the container;
{Paragraph four of clause 226.9 of Article 226 as amended by Law No. 1797-VIII of 21.12.2016 }
Foreign-produced alcoholic beverages with excise tax stamps indicating the amount of excise tax paid per unit of labeled product does not correspond to the amount determined taking into account the strength of the product, the capacity of the container, and the excise tax rates in effect at the time of production of the stamp.
{ Paragraph 226.9 of Article 226 is supplemented with a fifth paragraph in accordance with the Law No. 1797-VIII dated 21.12.2016 }
cigarettes, cigarillos and cigarillos manufactured after January 1, 2021, in which the number of units in the pack (packaging) does not correspond to the number of units indicated on the excise tax stamps;
{ Paragraph 226.8 of Article 226 is supplemented with a sixth paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
liquids used in electronic cigarettes manufactured before January 1, 2021.
{ Paragraph 226.8 of Article 226 is supplemented by the seventh paragraph in accordance with the Law No. 466-IX dated 16.01.2020 }
226.10. The following are not subject to marking:
alcoholic beverages and tobacco products supplied for sale to duty-free shops directly by domestic producers of such products under direct contracts concluded between domestic producers of alcoholic beverages and tobacco products and owners of duty-free shops. In this case, the movement of alcoholic beverages and tobacco products sent by producers to duty-free shops is carried out under customs control with the application of delivery guarantee measures;
alcoholic beverages and tobacco products imported into Ukraine and placed under the customs regime of a duty-free shop;
reference (monitoring) or test samples of tobacco products that are not intended for retail sale and are imported into the customs territory of Ukraine by accredited state testing laboratories and/or business entities that have licenses for the right to produce the relevant products, for conducting research or testing (calibration of laboratory equipment, conducting tastings, studying physicochemical indicators, design);
test samples of alcoholic beverages that are not intended for retail sale and are imported into the customs territory of Ukraine by business entities that have licenses for the right to wholesale the relevant products, for conducting research or testing (calibration of laboratory equipment, conducting tastings, studying physicochemical indicators, design), but not more than 3 liters of each product;
{Clause 226.10 of Article 226 is supplemented by the fifth paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
ordinary (still) wines and fermented beverages classified in commodity heading 2204 (except 2204 10, 2204 21 06 00, 2204 21 07 00, 2204 21 08 00, 2204 21 09 00, 2204 22 10 00, 2204 29 10 00) and in commodity subcategories 2205 10 10 00, 2205 90 10 00, 2206 00 59 00, 2206 00 89 00 according to the UKT ZEA , the actual strength of which is higher than 1.2 percent by volume of ethyl alcohol, but not higher than 15 percent volumetric units of ethyl alcohol, provided that the ethyl alcohol contained in the finished product is of completely enzymatic (endogenous) origin.
{Clause 226.10 of Article 226 is supplemented by the sixth paragraph in accordance with Law No. 1914-IX of 11/30/2021 }
226.11. Import into the customs territory of Ukraine, storage, transportation, acceptance for commission for the purpose of sale and sale in the customs territory of Ukraine of alcoholic beverages, tobacco products and liquids used in electronic cigarettes that are not labeled in accordance with the established procedure are prohibited.
{Clause 226.11 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
226.12. The sale of excise tax stamps to domestic producers of alcoholic beverages, tobacco products, and liquids used in electronic cigarettes is carried out on the basis of:
{Paragraph one of clause 226.12 of Article 226 as amended by Law No. 466-IX of January 16, 2020 }
certificates of payment of the tax amount calculated at the rates for finished products (for alcoholic beverages, for the production of which undenatured ethyl alcohol is used);
application for calculation of the number of excise tax stamps (hereinafter referred to as the application for calculation);
a report on the use of stamps purchased in the previous month, in the form approved by the central executive body responsible for the formation and implementation of state financial policy, in two copies, one of which remains with the seller of the stamps, the second (with the seller's mark) - with the manufacturer;
{Paragraph four of clause 226.12 of Article 226 as amended by Law No. 5083-VI of 05.07.2012 }
payment instruction for the transfer of the fee for stamps with a note from the bank/non-bank payment service provider on the date of its execution.
{Paragraph five of clause 226.12 of Article 226 as amended by Law No. 2888-IX of 12.01.2023 }
Forms of certificates and calculation applications are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 226.12 of Article 226 as amended by Law No. 1797-VIII of 21.12.2016 }
226.13. The number of excise tax stamps that can be obtained by producers of alcoholic beverages, for the production of which undenatured ethyl alcohol is used, is determined in accordance with the amount of tax paid. Producers of tobacco products and alcoholic beverages, for the production of which undenatured ethyl alcohol is not used, determine the need for excise tax stamps taking into account the planned monthly sales volumes of products.
226.14. To obtain excise tax stamps, the importer must submit to the seller of such stamps an application-calculation in the form approved by the central executive body that ensures the formation and implementation of state financial policy, documents confirming the payment of the stamp fee and the payment of the tax to the relevant budget.
{Paragraph one of clause 226.14 of Article 226 as amended by Law No. 1797-VIII of 12.21.2016 ; as amended by Law No. 2888-IX of 12.01.2023 }
The controlling authority is prohibited from requiring additional documents from importers for the issuance of excise tax stamps, unless they are provided for by this article.
226.15. The sale (transfer) of purchased excise tax stamps by the purchaser of the stamps to other persons is prohibited, except for the cases provided for in Clause 227.4 of Article 227 of this Code.
226.16. Excise tax stamps not used for marking goods due to their damage shall be accepted from stamp buyers for disposal with reimbursement of the actually paid tax amounts in accordance with the Regulations on the Production, Storage, and Sale of Excise Tax Stamps, Marking of Alcoholic Beverages and Tobacco Products . The fee for the stamps shall not be refundable.
Article 227. Importation into the customs territory of Ukraine of imported alcoholic beverages, tobacco products and liquids used in electronic cigarettes↑
{Title of Article 227 as amended by Law No. 466-IX of January 16, 2020 }
227.1. Business entities - legal entities and individuals who have concluded a contract (agreement) with foreign manufacturers or other non-residents for the supply of alcoholic beverages, tobacco products and liquids used in electronic cigarettes to Ukraine have the right to import imported alcoholic beverages, tobacco products and liquids used in electronic cigarettes into the customs territory of Ukraine if:
{Paragraph one of clause 227.1 of Article 227 as amended by Law No. 71-VIII of 28.12.2014 }
a) their import into the customs territory of Ukraine is carried out exclusively through the state border checkpoints designated by the Cabinet of Ministers of Ukraine, which are indicated by the stamp buyers (importers) in the settlement application;
b) labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes is carried out in accordance with the established procedure with excise tax stamps of the established sample;
c) alcoholic beverages in automobile and railway tanks, as well as in tanks, vats and other containers with a capacity of more than 5 liters are imported into Ukraine for the purpose of sale or exchange on the customs territory of Ukraine and are not subject to labeling. In this case, the tax is paid before or during customs clearance. Control over its payment is carried out by regulatory authorities;
d) the buyer of the stamps (importer) submitted to the regulatory authority a customs declaration, a copy of the declaration on maximum retail prices (for tobacco products) and a copy of the application-calculation with a mark from the seller of the excise tax stamps on the payment of the tax amounts to the relevant budget in full.
{Clause 227.1 of Article 227 as amended by Law No. 466-IX of January 16, 2020 }
227.2. In the event of importation by the buyer (importer) of stamps into the territory of Ukraine under a contract (agreement) for the supply of alcoholic beverages, tobacco products and liquids used in electronic cigarettes in several batches, the central executive body implementing the state tax policy shall make notes in such contract (agreement) on the number of issued excise tax stamps, indicating the date of their issue.
{Clause 227.2 of Article 227 as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 }
227.3. The term for obtaining excise tax stamps for each contract is determined by the stamp buyers (importers) in agreement with the stamp seller, depending on the volume of imported goods, but is no more than three business days from the date of submission of documents for obtaining excise tax stamps specified in paragraph 226.14 of Article 226 of this Code.
{Clause 227.3 of Article 227 as amended by Law No. 1914-IX of 30.11.2021 }
227.4. Purchased excise tax stamps are transferred by stamp buyers (importers) to foreign business entities for labeling alcoholic beverages, tobacco products, and liquids used in electronic cigarettes, which are subject to further import into the customs territory of Ukraine.
{Clause 227.4 of Article 227 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 466-IX of 01/16/2020 }
227.5. Transit transportation of alcoholic beverages, tobacco products and liquids used in electronic cigarettes through the customs territory of Ukraine shall be carried out in compliance with the requirements established by customs legislation.
{Clause 227.5 of Article 227 as amended by Laws No. 2245-VIII of 07.12.2017 , No. 466-IX of 16.01.2020 }
227.6. In case of violation of the labeling procedure for imported alcoholic beverages, tobacco products and liquids used in electronic cigarettes and/or incomplete payment of tax, the goods are not allowed for customs clearance and their import into the customs territory of Ukraine is prohibited.
{Clause 227.6 of Article 227 as amended by Law No. 466-IX of January 16, 2020 }
Article 228. Control over the collection of tax on alcoholic beverages, tobacco products, liquids used in electronic cigarettes, fuel and ethyl alcohol↑
{Title of Article 228 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
228.1. Control over the payment of tax on the customs territory of Ukraine on alcoholic beverages, tobacco products, liquids used in electronic cigarettes, fuel and ethyl alcohol is carried out by regulatory authorities.
{Clause 228.1 of Article 228 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
228.2. Control over the presence of excise tax stamps on packs (packaging) of tobacco products and on containers (packaging) with liquids used in electronic cigarettes, during their transportation, storage and sale, as well as in the case of import of such goods into the customs territory of Ukraine, control over the movement, storage and sale of fuel and ethyl alcohol is carried out by the relevant regulatory authorities.
{Clause 228.2 of Article 228 as amended by Law No. 404-VII of 04.07.2013 ; as amended by Laws No. 2628-VIII of 23.11.2018 , No. 466-IX of 16.01.2020 }
228.3. In the event of detection of facts of import into the customs territory of Ukraine, storage, transportation and sale in the customs territory of Ukraine of alcoholic beverages, tobacco products, liquids used in electronic cigarettes, without the presence of excise tax stamps of the established sample, the regulatory authorities specified in paragraph 228.2 of this Article shall remove such goods from free circulation and submit relevant materials to the court for a ruling on their seizure to the state revenue (confiscation).
{Paragraph one of clause 228.3 of Article 228 as amended by Law No. 466-IX of January 16, 2020 }
In the event of detection of facts of movement and/or storage of fuel or ethyl alcohol using vehicles not specified in excise invoices registered in the Unified Register of Excise Invoices drawn up for transactions in which fuel or ethyl alcohol is moved and/or stored in such vehicles, or in applications for the movement of fuel or ethyl alcohol by vehicles that are not mobile excise warehouses, or in customs declarations when moving fuel or ethyl alcohol through the customs territory of Ukraine by transit or internal transit, defined by subparagraph "a" of paragraph 2 of part two of Article 91 of the Customs Code of Ukraine, as well as facts of sale of fuel or ethyl alcohol from such vehicles, the relevant regulatory authorities shall temporarily (until a court decision is rendered) remove such fuel or ethyl alcohol and vehicles from free circulation and submit relevant materials to the court for a ruling on their withdrawal to the state revenue (confiscation).
{Clause 228.3 of Article 228 is supplemented by the second paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
In the event of detection of facts of storage or sale in the customs territory of Ukraine of fuel or ethyl alcohol in an excise warehouse not registered in the system of electronic administration of the sale of fuel and ethyl alcohol, the relevant regulatory authorities shall temporarily (until a court decision is made) remove from free circulation such fuel or ethyl alcohol, containers and equipment used for storage or sale of such fuel or ethyl alcohol, and submit relevant materials to the court for a ruling on their seizure to the state revenue (confiscation).
{Clause 228.3 of Article 228 was supplemented by the third paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
228.4. The execution of a court decision on the seizure of alcoholic beverages, tobacco products, liquids used in electronic cigarettes, and fuel or ethyl alcohol, as well as containers, equipment and vehicles in which such fuel or ethyl alcohol was transported and/or stored or from which it was sold, shall be carried out in accordance with the law.
{Clause 228.4 of Article 228 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 }
228.5. Excise goods (except for ethyl alcohol, alcoholic beverages and tobacco products) seized as state revenue (confiscated) shall, in the event of their sale (sale) in accordance with the procedure established by law, be subject to excise tax and other taxes in accordance with the laws of Ukraine.
{Clause 228.5 of Article 228 as amended by Law No. 404-VII of 04.07.2013 }
228.6. Ethyl alcohol and alcoholic beverages confiscated as state revenue (confiscated) shall be destroyed in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Clause 228.6 of Article 228 as amended by Law No. 466-IX of January 16, 2020 }
228.7. Tobacco products and liquids used in electronic cigarettes that have been confiscated as state revenue shall be destroyed in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Clause 228.7 of Article 228 as amended by Law No. 466-IX of January 16, 2020 }
228.8. In the event of a shortage of excise tax stamps at the buyer (due to their theft, destruction, labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes intended for sale for export, etc.), the buyers of the stamps shall bear full property liability in the amount of the estimated tax amount that must be paid to the budget in the event of the sale of excisable goods for the labeling of which excise tax stamps were purchased. The specified amounts shall be calculated in the form established by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 228.8 of Article 228 as amended by Laws No. 71-VIII of 12/28/2014 , No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
228.9. Responsibility for non-compliance with the labeling procedure, sale of alcoholic beverages, tobacco products and liquids used in electronic cigarettes, non-payment or untimely payment of tax shall be borne by manufacturers (customers), importers, sellers of such goods and their officials in accordance with the law.
{Clause 228.9 of Article 228 as amended by Law No. 466-IX of January 16, 2020 }
Article 229. Peculiarities of taxation of certain excisable goods depending on their use↑
229.1. Peculiarities of taxation of ethyl alcohol
229.1.1. The tax is levied at a rate of 0 hryvnias per 1 liter of 100 percent alcohol from:
a) ethyl alcohol, which is used by primary and mixed winemaking enterprises for the production of grape, fruit and berry, other wine materials and must and vermouth;
{Subparagraph "a" of subparagraph 229.1.1 of paragraph 229.1 of Article 229 as amended by Law No. 5074-VI of 05.07.2012 }
b) ethyl alcohol used for the production of medicinal products (including blood components and preparations made from them), except for medicinal products in the form of balms and elixirs;
c) denatured ethyl alcohol (technical alcohol), which is sold to business entities for the purpose of using it as a raw material for the production of organic synthesis products that do not contain more than 0.1 percent of residual ethanol;
d) bioethanol used by enterprises for the production of blended motor gasolines containing bioethanol, ethyl tert-butyl ether (ETBE), and other bioethanol-based additives;
e) bioethanol, which is used for the production of biofuel;
e) denatured ethyl alcohol, which is used for the production of chemical and technical products included in the list approved by the Cabinet of Ministers of Ukraine;
{Subclause 229.1.1 of clause 229.1 of Article 229 is supplemented by subparagraph "d" in accordance with Law No. 2628-VIII of 23.11.2018 }
e) undenatured ethyl alcohol, which is used for the production of vinegar from food raw materials;
{Subclause 229.1.1 of clause 229.1 of Article 229 is supplemented by subparagraph "e" in accordance with Law No. 2628-VIII of 23.11.2018 }
h) denatured ethyl alcohol, which is used for the production of perfume and cosmetic products;
{Subclause 229.1.1 of clause 229.1 of Article 229 is supplemented by subparagraph "is" in accordance with Law No. 2628-VIII of 23.11.2018 }
g) raw ethyl alcohol used for the production of bioethanol;
{Subclause 229.1.1 of clause 229.1 of Article 229 is supplemented by subparagraph "g" in accordance with Law No. 2628-VIII of 11/23/2018 ; as amended by Law No. 3193-IX of 06/29/2023 }
h) ethyl alcohol moving between excise warehouses within the same business entity.
{Subclause 229.1.1 of clause 229.1 of Article 229 is supplemented by subparagraph "z" in accordance with Law No. 2628-VIII of 23.11.2018 }
Ethyl alcohol at a rate of 0 hryvnia per 1 liter of 100 percent alcohol for the production of products specified in subparagraphs "d", "e", "e" of this subparagraph is allowed to be obtained only by business entities (including foreign business entities operating through their registered permanent representative offices) entered in the Electronic Register of Business Entities Using Ethyl Alcohol for the Production of Chemical and Technical Products, Perfumery and Cosmetic Products, and Vinegar from Food Raw Materials (hereinafter referred to as the Electronic Register), which is maintained by the central executive body implementing state tax policy.
{Subparagraph 229.1.1 of paragraph 229.1 of Article 229 is supplemented by paragraph twelfth in accordance with Law No. 2284-IX of 05/31/2022 }
229.1.2. Before receiving from the excise warehouse undenatured ethyl alcohol, denatured ethyl alcohol (technical alcohol), bioethanol, which are used for the production of certain types of products and for which a tax rate of 0 hryvnias per 1 liter of 100 percent alcohol is established by subparagraph 229.1.1 of this Article, a tax bill shall be issued for the amount of tax charged on the volume of alcohol received based on the rate specified in paragraph 215.3 of Article 215 of this Code.
229.1.3. The period for which a tax bill is issued by manufacturing enterprises for the production of certain types of products cannot exceed 90 calendar days, and by primary winemaking enterprises, vermouth producers and pharmaceutical manufacturers - 180 calendar days.
{Subclause 229.1.3 of Clause 229.1 of Article 229 as amended by Law No. 5074-VI of 05.07.2012 }
229.1.4. The tax bill is issued before the ethyl alcohol is received from the excise warehouse.
229.1.5. A tax bill may be issued:
a) a primary winemaking enterprise that is a producer of grape, fruit and berry, other wine materials and must and vermouth;
{Subparagraph "a" of subparagraph 229.1.5 of paragraph 229.1 of Article 229 as amended by Law No. 5074-VI of 05.07.2012 }
b) a manufacturer of medicinal products;
c) a manufacturer of organic synthesis products;
d) oil refineries (or other business entities) that use bioethanol for the production of blended motor gasolines containing bioethanol, ethyl tert-butyl ether (ETBE), and other bioethanol-based additives;
e) biofuel producers;
e) a manufacturer of chemical and technical products included in the list approved by the Cabinet of Ministers of Ukraine;
{Subclause 229.1.5 of clause 229.1 of Article 229 is supplemented by subparagraph "d" in accordance with Law No. 2628-VIII of 23.11.2018 }
f) a producer of vinegar from food raw materials;
{Subclause 229.1.5 of clause 229.1 of Article 229 is supplemented by subparagraph "e" in accordance with Law No. 2628-VIII of 23.11.2018 }
h) a manufacturer of perfume and cosmetic products;
{Subclause 229.1.5 of clause 229.1 of Article 229 is supplemented by subparagraph "is" in accordance with Law No. 2628-VIII of 23.11.2018 }
g) a bioethanol producer who uses raw ethyl alcohol for the production of bioethanol.
{Subclause 229.1.5 of clause 229.1 of Article 229 is supplemented by subparagraph "g" in accordance with Law No. 3193-IX of 29.06.2023 }
229.1.6. Obligations to repay a tax bill may not be transferred to other persons regardless of their relationship with the drawer.
229.1.7. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.1.8. A tax bill is considered to be redeemed if documentary confirmation of the fact of the intended use of ethyl alcohol for the production of products specified in subparagraph 229.1.1 of paragraph 229.1 of this article is submitted to the bill holder in the form of an electronic document in accordance with the legislation.
Business entities that use ethyl alcohol for the production of products specified in subparagraphs "d"-"g" of subparagraph 229.1.1 of paragraph 229.1 of this Article are obliged to:
a) equip each place of receipt and place of release for the production of undenatured ethyl alcohol with flow meters-counters of the volume of ethyl alcohol produced, registered in the Unified State Register of flow meters-counters of the volume of ethyl alcohol produced;
b) equip each place of receipt and place of release for the production of denatured ethyl alcohol with mass flow meters registered in the Unified State Register of flow meters-counters of the volume of ethyl alcohol produced;
c) equip each point of sale of products for the production of which the obtained ethyl alcohol is used, with mass flow meters registered in the Unified State Register of flow meters-counters of the volume of ethyl alcohol produced, or with means of accounting for the products produced;
d) send to the central executive body implementing state tax policy a technological scheme for installing ethyl alcohol flow meters and/or mass flow meters in the places specified in subparagraphs "a", "b", "c" of this subparagraph, by electronic means no later than 10 working days before the date of installation of ethyl alcohol flow meters and/or mass flow meters;
e) submit a certificate of the intended use of ethyl alcohol in terms of 100 percent ethyl alcohol when repaying the tax bill;
e) daily generate and submit to the central executive body implementing state tax policy data on the daily actual volume of ethyl alcohol received and released for production.
Data on the daily actual volume of ethyl alcohol received and released for production are submitted by sending electronic documents by electronic means of communication, drawn up in a form approved by the central executive body that ensures the formation and implementation of state financial policy.
Electronic documents are filled in by transferring data to them on the volume of undenatured ethyl alcohol received and released for production from ethyl alcohol flow meters and/or the volume of denatured ethyl alcohol received and released for production from mass flow meters, converted into decaliters of 100 percent alcohol, brought to a temperature of 20°C, using methods determined in accordance with the Law of Ukraine "On Metrology and Metrological Activities".
Data on the daily actual volume of ethyl alcohol received and released for production are formed after the last operation to obtain ethyl alcohol on the reporting day, but no later than 23:59 of this day, before the start of operations to obtain ethyl alcohol on the day following the reporting day, and are submitted to the central executive body implementing state tax policy no later than 23:59 of the day following the reporting day.
It is prohibited to receive and release ethyl alcohol for the production of products using it without the presence of registered ethyl alcohol flow meters and/or registered mass flow meters without a technological scheme for installing ethyl alcohol flow meters and/or mass flow meters sent to the central executive body implementing state tax policy, as well as through each place of receipt and release of ethyl alcohol where the ethyl alcohol flow meter or mass flow meter is out of order or missing.
Ethyl alcohol flow meters, mass flow meters must comply with the requirements of the legislation and have a positive result of verification or conformity assessment carried out in accordance with the legislation. In the absence of a technological scheme for the installation of ethyl alcohol flow meters and/or mass flow meters sent to the central executive body implementing state tax policy, and a positive result of verification or conformity assessment of ethyl alcohol flow meters, mass flow meters, for the purposes of this Code, ethyl alcohol flow meters, mass flow meters are considered not installed.
{Subclause 229.1.8 of clause 229.1 of Article 229 as amended by the Law No. 2628-VIII dated 23.11.2018 ; as amended by Law No. 2284-IX dated 31.05.2022 }
229.1.9. If the tax bill provided for in this Article is not repaid within the established period, the bill holder shall protest such tax bill for non-payment in accordance with the law and within one business day from the date of the protest shall apply to the bank that has made the aval of this tax bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the bill holder's application with the protested tax bill.
229.1.10. The procedure for issuing, circulating and repaying tax bills issued for receipt from the excise warehouse of ethyl alcohol used by business entities for the production of certain types of products is established by the Cabinet of Ministers of Ukraine.
229.1.11. Lists of producers of denatured ethyl alcohol (technical alcohol) for the needs of enterprises producing organic synthesis products are approved by the Cabinet of Ministers of Ukraine.
{Subclause 229.1.11 of Clause 229.1 of Article 229 as amended by Law No. 1638-VII of 12.08.2014 }
229.1.12. Shipment of denatured ethyl alcohol (technical alcohol) for the needs of enterprises producing organic synthesis products is carried out within the quotas established by the Cabinet of Ministers of Ukraine.
229.1.13. Shipment of ethyl alcohol for the production of medicinal products shall be carried out within the quotas established by the Cabinet of Ministers of Ukraine. The list of medicinal products for the production of which ethyl alcohol is used shall be approved by the Cabinet of Ministers of Ukraine.
229.1.14. At enterprises where alcohol is used at a zero rate, tax posts are established, the procedure for which is determined by the central executive body that ensures the formation and implementation of state financial policy.
Tax posts at enterprises that use ethyl alcohol for the production of products specified in subparagraphs "d" - "g" of subparagraph 229.1.1 of paragraph 229.1 of this article shall not be established.
{Subclause 229.1.14 of clause 229.1 of Article 229 is supplemented by the second paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
{Subclause 229.1.14 of Clause 229.1 of Article 229 as amended by Law No. 1797-VIII of 21.12.2016 }
229.1.15. In excise warehouses where bioethanol is produced, it is prohibited to:
a) production and storage of other types of ethyl alcohol (except for the storage of raw ethyl alcohol used for the production of bioethanol);
b) storage and/or sale of bioethanol without denaturing it with gasoline (1-10 percent) or ethyl tert-butyl ether, the content of which meets the requirements of technical regulations, with the exception of bioethanol produced for export outside the customs territory of Ukraine, the requirements for denaturing which are determined by the terms of concluded foreign economic agreements.
{Subparagraph "b" of subparagraph 229.1.15 of paragraph 229.1 of Article 229 as amended by Law No. 2284-IX of 05/31/2022 }
{Subclause 229.1.15 of clause 229.1 of Article 229 as amended by Laws No. 1638-VII of 12.08.2014 , No. 2628-VIII of 23.11.2018 }
229.1.16. A tax bill shall not be issued by business entities that are simultaneously:
a) producers of bioethanol and biofuels;
b) manufacturers of denatured ethyl alcohol and products of chemical and technical purpose included in the list approved by the Cabinet of Ministers of Ukraine;
c) producers of undenatured ethyl alcohol and vinegar from food raw materials;
d) manufacturers of denatured ethyl alcohol and perfume and cosmetic products;
e) producers of raw ethyl alcohol and bioethanol.
Confirmation of the fact of the intended use of ethyl alcohol for the production of products specified in this subparagraph is a certificate attached to the excise tax declaration.
{Subclause 229.1.16 of clause 229.1 of Article 229 as amended by Law No. 2628-VIII of 23.11.2018 }
229.1.17. In the event of misuse by business entities of ethyl alcohol and bioethanol obtained as raw materials for the production of products specified in paragraph 229.1.1 of this Article, such entities shall be fined in the amount calculated based on the volumes of ethyl alcohol and bioethanol used for purposes other than their intended purpose and the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code, increased by 1.5 times.
229.2. Features of taxation of petroleum products produced in Ukraine and used as raw materials for the petrochemical industry.
229.2.1. Light distillates (code 2710 12 11 10, 2710 12 11 20, 2710 12 11 90 according to the UKT FEA ) and heavy distillates (code 2710 19 31 30 according to the UKT FEA) can be sold as raw materials for the production of ethylene at a zero excise tax rate.
{Subclause 229.2.1 of Clause 229.2 of Article 229 as amended by Law No. 71-VIII of 28.12.2014 }
229.2.2. In the case of using these petroleum products as raw materials for the production of ethylene at a zero excise tax rate, the regulatory authorities shall monitor their intended use.
229.2.3. Before receiving light distillates (code 2710 12 11 10, 2710 12 11 20, 2710 12 11 90 according to the UKT FEA) and heavy distillates (code 2710 19 31 30 according to the UKT FEA), which are used by business entities as raw materials for the production of ethylene, producers shall issue a tax bill for the amount of excise tax charged on the volume of petroleum products received based on the rate determined as the difference between the excise tax rate provided for in paragraph 215.3 of Article 215 of this section and the rate of 0 euros per 1000 kg.
{Subclause 229.2.3 of Clause 229.2 of Article 229 as amended by Law No. 71-VIII of 28.12.2014 }
229.2.4. A tax bill may be issued only by a business entity - an ethylene producer.
229.2.5. The term for which a tax bill is issued may not exceed 90 calendar days.
229.2.6. Obligations to repay a tax bill may not be transferred to other persons, regardless of their relationship with the drawer.
229.2.7. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.2.8. The bill holder is the regulatory authority at the place of registration of the drawer.
229.2.9. Tax posts shall be established at enterprises that use light and heavy distillates as raw materials in the production of ethylene. At the tax post, representatives of the controlling authority at its location shall exercise constant direct control over the intended use of petroleum products as raw materials for the production of ethylene.
229.2.10. A tax bill is considered to be repaid in the event of documentary confirmation of the fact of the intended use of light and heavy distillates exclusively as raw materials in the production of ethylene.
229.2.11. To repay a tax bill, the bill holder shall be provided with a certificate from the drawer on the intended use of light and heavy distillates as raw materials in the production of ethylene, approved by a representative of the tax office established at the enterprise.
229.2.12. If the tax bill provided for in this Article is not repaid within the established period, the bill holder shall protest such tax bill for non-payment in accordance with the law and within one business day from the date of the protest shall apply to the bank that has avalized this tax bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the day of the bill holder's application with the protested tax bill.
229.2.13. The procedure for the issuance, circulation and repayment of tax bills issued prior to the receipt of light and heavy distillates for use as raw materials for the production of ethylene shall be established by the Cabinet of Ministers of Ukraine.
229.2.14. The list of enterprises that receive light and heavy distillates for use as raw materials for ethylene production is approved by the Cabinet of Ministers of Ukraine.
229.2.15. Shipment of light and heavy distillates used as raw materials for ethylene production is carried out within the quotas established by the Cabinet of Ministers of Ukraine.
229.2.16. In the event of misuse by business entities of light and heavy distillates obtained as raw materials for the production of ethylene, such entities shall be fined in the amount calculated based on the volumes of light and heavy distillates used for purposes other than their intended purpose and the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code, increased by 1.5 times.
229.3. Features of taxation of petroleum products imported into Ukraine and used as raw materials for the petrochemical industry
229.3.1. Light distillates (code 2710 12 11 10, 2710 12 11 20, 2710 12 11 90 according to the UKT FEA ) and heavy distillates (codes 2710 19 31 01, 2710 19 31 10, 2710 19 31 20, 2710 19 31 30 according to the UKT FEA ), as well as liquefied gas (codes 2711 12 11 00, 2711 12 19 00, 2711 12 91 00, 2711 12 93 00, 2711 12 94 00, 2711 12 97 00, 2711 13 10 00, 2711 13 30 00, 2711 13 91 00, 2711 13 97 00, 2711 14 00 00, 2711 19 00 00 according to the UKT FEA) and butane, isobutane (code 2901 10 00 10 according to the UKT FEA ) can be imported into Ukraine as raw materials for the production of ethylene without paying excise tax.
{Subclause 229.3.1 of Clause 229.3 of Article 229 as amended by Laws No. 71-VIII of 28.12.2014 , No. 1791-VIII of 20.12.2016 }
229.3.2. In the case of using these petroleum products as raw materials for the production of ethylene without paying excise tax, the regulatory authorities shall monitor their intended use.
229.3.3. For the import into the customs territory of Ukraine of light distillates (code 2710 12 11 10, 2710 12 11 20, 2710 12 11 90 according to the UKT FEA) and heavy distillates (codes 2710 19 31 01, 2710 19 31 10, 2710 19 31 20, 2710 19 31 30 according to the UKT FEA ), as well as liquefied gas (codes 2711 12 11 00, 2711 12 19 00, 2711 12 91 00, 2711 12 93 00, 2711 12 94 00, 2711 12 97 00, 2711 13 10 00, 2711 13 30 00, 2711 13 91 00, 2711 13 97 00, 2711 14 00 00, 2711 19 00 00 according to the UKT FEA) and butane, isobutane (code 2901 10 00 10 according to the UKT FEA ) for the purpose of using them as raw materials in the production of ethylene, the ethylene producer draws up a tax bill in three copies. One copy is submitted to the regulatory authority at the location of the producer, the second - to the regulatory authority at the place of customs clearance of the specified goods, the third remains with the taxpayer.
{Subclause 229.3.3 of Clause 229.3 of Article 229 as amended by Laws No. 404-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 , No. 1791-VIII of 20.12.2016 }
229.3.4. A tax bill is issued for the amount of excise tax levied upon the import of goods in accordance with the legislation.
229.3.5. A tax bill may be issued only by a business entity - an ethylene producer.
229.3.6. The term for which an avalized tax bill is issued cannot exceed 90 calendar days from the date of registration of the customs declaration.
229.3.7. The basis for customs clearance of light distillates (code 2710 12 11 10, 2710 12 11 20, 2710 12 11 90 according to the UKT FEA ) and heavy distillates (codes 2710 19 31 01, 2710 19 31 10, 2710 19 31 20, 2710 19 31 30 according to the UKT FEA), as well as liquefied gas (codes 2711 12 11 00, 2711 12 19 00, 2711 12 91 00, 2711 12 93 00, 2711 12 94 00, 2711 12 97 00, 2711 13 10 00, 2711 13 30 00, 2711 13 91 00, 2711 13 97 00, 2711 14 00 00, 2711 19 00 00 according to the UKT FEA) and butane, isobutane (code 2901 10 00 10 according to the UKT FEA ), imported into the customs territory of Ukraine for the purpose of use in the production of ethylene, is the submission by the ethylene producer to the controlling authority that carries out customs clearance, in accordance with the procedure provided for by the Customs Code of Ukraine , by means of electronic communication of a copy of the tax bill, endorsed by the bank and registered by the controlling authority.
{Subclause 229.3.7 of Clause 229.3 of Article 229 as amended by Laws No. 404-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 , No. 1791-VIII of 20.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
229.3.8. Obligations to repay a tax bill may not be transferred to other persons, regardless of their relationship with the drawer.
229.3.9. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.3.10. The bill holder is the regulatory authority at the place of registration of the drawer.
229.3.11. Tax posts shall be established at enterprises that use light and heavy distillates, as well as liquefied gas and butane, isobutane as raw materials in the production of ethylene. At the tax post, representatives of the controlling body at its location shall exercise constant direct control over the intended use of petroleum products as raw materials for the production of ethylene.
{Subclause 229.3.11 of Clause 229.3 of Article 229 as amended by Law No. 1791-VIII of 20.12.2016 }
229.3.12. A tax bill without payment of the amount of excise tax in cash is considered to be repaid in the event of documentary confirmation of the fact of the intended use of light and heavy distillates, as well as liquefied gas and butane, isobutane exclusively as raw materials in the production of ethylene.
{Subclause 229.3.12 of Clause 229.3 of Article 229 as amended by Law No. 1791-VIII of 20.12.2016 }
229.3.13. To repay a tax bill, the bill holder shall be provided with a certificate from the drawer on the intended use of light and heavy distillates, as well as liquefied gas and butane, isobutane as raw materials in the production of ethylene, approved by a representative of the tax post established at the enterprise. A copy of the certificate on intended use shall be provided to the supervisory authority.
{Subclause 229.3.13 of Clause 229.3 of Article 229 as amended by Law No. 1791-VIII of 20.12.2016 }
229.3.14. If the tax bill provided for in this Article is not repaid within the established period, the bill holder shall protest such tax bill for non-payment in accordance with the law and within one business day from the date of the protest shall apply to the bank that has avalized this tax bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the bill holder's application with the protested tax bill.
229.3.15. The procedure for issuing, circulating and repaying tax bills issued prior to the import of light and heavy distillates, as well as liquefied gas and butane, isobutane for use as raw materials for the production of ethylene, is established by the Cabinet of Ministers of Ukraine.
{Subclause 229.3.15 of clause 229.3 of Article 229 as amended by Law No. 1791-VIII of 20.12.2016 }
229.3.16. The list of enterprises importing light and heavy distillates, as well as liquefied gas and butane, isobutane for use as raw materials for the production of ethylene is approved by the Cabinet of Ministers of Ukraine.
{Subclause 229.3.16 of Clause 229.3 of Article 229 as amended by Law No. 1791-VIII of 20.12.2016 }
229.3.17. Import of light and heavy distillates, as well as liquefied gas and butane, isobutane, used as raw materials for the production of ethylene, is carried out within the quotas established by the Cabinet of Ministers of Ukraine.
{Subclause 229.3.17 of Clause 229.3 of Article 229 as amended by Law No. 1791-VIII of 20.12.2016 }
229.3.18. In the event of misuse by business entities of light and heavy distillates, as well as liquefied gas and butane, isobutane, imported as raw materials for the production of ethylene, such entities shall be fined in the amount calculated based on the volumes of light and heavy distillates used for purposes other than their intended purpose and the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code, increased by 1.5 times.
as well as liquefied gas and butane, isobutane
{Subclause 229.3.18 of Clause 229.3 of Article 229 as amended by Law No. 1791-VIII of 20.12.2016 }
229.4. Peculiarities of taxation of petroleum products produced in Ukraine and used as raw materials for the chemical industry
229.4.1. Petroleum products (codes 2710 12 11 10, 2710 12 11 20, 2710 12 11 90; 2710 12 15 10, 2710 12 15 20, 2710 12 15 90; 2710 12 21 10, 2710 12 21 90; 2710 19 11 10, 2710 19 11 20, 2710 19 11 90; 2710 19 15 10, 2710 19 15 20, 2710 19 15 90, 2710 19 25 00, 2710 19 29 00 according to the UKT Foreign Economic Activity ) can be sold as raw materials for production in the chemical industry at a zero excise tax rate.
{Subclause 229.4.1 of Clause 229.4 of Article 229 as amended by Laws No. 71-VIII of 12/28/2014 , No. 1914-IX of 11/30/2021 }
229.4.2. In the case of using these petroleum products as raw materials for production in the chemical industry at a zero excise tax rate, the regulatory authorities shall monitor their intended use.
229.4.3. Before receiving petroleum products used by business entities as raw materials for production in the chemical industry, producers shall issue a tax bill for the amount of excise tax charged on the volume of petroleum products received based on the rate determined as the difference between the excise tax rate provided for in paragraph 215.3 of Article 215 of this section and the rate of 0 euros per 1000 kg.
229.4.4. A tax bill may be issued only by a business entity - a producer that uses these petroleum products as raw materials in the chemical industry.
229.4.5. The term for which a tax bill is issued may not exceed 90 calendar days.
229.4.6. Obligations to repay a tax bill may not be transferred to other persons, regardless of their relationship with the drawer.
229.4.7. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.4.8. The bill holder is the regulatory authority at the place of registration of the drawer.
229.4.9. Tax posts shall be established at enterprises that use petroleum products as raw materials for production in the chemical industry. At the tax post, representatives of the controlling body at its location shall exercise constant direct control over the intended use of petroleum products as raw materials for the chemical industry.
229.4.10. A tax bill is considered to be repaid in the event of documentary confirmation of the fact of the intended use of petroleum products exclusively as raw materials for production in the chemical industry.
229.4.11. To repay a tax bill, the bill holder shall be provided with a certificate from the drawer on the intended use of petroleum products as raw materials for production in the chemical industry, approved by a representative of the tax office established at the enterprise.
229.4.12. If the tax bill provided for in this Article is not repaid within the established period, the bill holder shall protest such tax bill for non-payment in accordance with the law and within one business day from the date of the protest shall apply to the bank that has avalized this tax bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the day of the bill holder's application with the protested tax bill.
229.4.13. The procedure for the issuance, circulation and repayment of tax bills issued prior to the receipt of petroleum products for use as raw materials for production in the chemical industry shall be established by the Cabinet of Ministers of Ukraine.
229.4.14. The list of enterprises that receive petroleum products for use as raw materials for production in the chemical industry is approved by the Cabinet of Ministers of Ukraine.
229.4.15. Shipment of petroleum products used as raw materials for production in the chemical industry is carried out within the quotas established by the Cabinet of Ministers of Ukraine.
229.4.16. In the event of misuse by business entities of petroleum products obtained as raw materials for production in the chemical industry, such entities shall be fined in the amount calculated based on the volumes of petroleum products used for purposes other than their intended purpose and the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code, increased by 1.5 times.
{Article 229 was supplemented by paragraph 229.4 in accordance with Law No. 3609-VI of 07.07.2011 }
229.5. Features of taxation of petroleum products imported into Ukraine and used as raw materials for the chemical industry
229.5.1. Petroleum products (codes 2710 12 11 10, 2710 12 11 20, 2710 12 11 90; 2710 12 15 10, 2710 12 15 20, 2710 12 15 90; 2710 12 21 10, 2710 12 21 90; 2710 19 11 10, 2710 19 11 20, 2710 19 11 90; 2710 19 15 10, 2710 19 15 20, 2710 19 15 90, 2710 19 25 00, 2710 19 29 00 according to the UKT Foreign Economic Activity ) can be imported into Ukraine as raw materials for production in the chemical industry without paying excise tax.
{Subclause 229.5.1 of Clause 229.5 of Article 229 as amended by Laws No. 71-VIII of 12/28/2014 , No. 1914-IX of 11/30/2021 }
229.5.2. In the case of using these petroleum products as raw materials for production in the chemical industry without paying excise tax, the regulatory authorities shall monitor their intended use.
229.5.3. For the import into the customs territory of Ukraine of petroleum products (codes 2710 12 11 10, 2710 12 11 20, 2710 12 11 90; 2710 12 15 10, 2710 12 15 20, 2710 12 15 90; 2710 12 21 10, 2710 12 21 90; 2710 19 11 10, 2710 19 11 20, 2710 19 11 90; 2710 19 15 10, 2710 19 15 20, 2710 19 15 90, 2710 19 25 00, 2710 19 29 00 according to the UKT Foreign Economic Activity) for the purpose of using them as raw materials in the chemical industry, the manufacturer draws up a tax bill in triplicate. One copy is submitted to the regulatory authority at the location of the manufacturer, the second to the regulatory authority at the place of customs clearance of the specified goods, the third remains with the taxpayer.
{Subclause 229.5.3 of Clause 229.5 of Article 229 as amended by Laws No. 404-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 , No. 1914-IX of 30.11.2021 }
229.5.4. A tax bill is issued for the amount of excise tax levied upon the import of goods in accordance with the legislation.
229.5.5. A tax bill may be issued only by a business entity - a producer that uses these petroleum products as raw materials in the chemical industry.
229.5.6. The term for which an avalized tax bill is issued cannot exceed 90 calendar days from the date of registration of the customs declaration.
229.5.7. The basis for customs clearance of petroleum products (codes 2710 12 11 10, 2710 12 11 20, 2710 12 11 90; 2710 12 15 10, 2710 12 15 20, 2710 12 15 90; 2710 12 21 10, 2710 12 21 90; 2710 19 11 10, 2710 19 11 20, 2710 19 11 90; 2710 19 15 10, 2710 19 15 20, 2710 19 15 90, 2710 19 25 00, 2710 19 29 00 according to the UKT Foreign Economic Activity Code), imported into the customs territory of Ukraine for use in the chemical industry, is the submission by the manufacturer to the controlling authority that carries out customs clearance, of a second copy of the tax bill, endorsed by the bank and registered by the controlling authority at the location of the manufacturer.
{Subclause 229.5.7 of Clause 229.5 of Article 229 as amended by Laws No. 404-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 , No. 1914-IX of 30.11.2021 }
229.5.8. Obligations to repay a tax bill may not be transferred to other persons, regardless of their relationship with the drawer.
229.5.9. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.5.10. The bill holder is the regulatory authority at the place of registration of the drawer.
229.5.11. Tax posts shall be established at enterprises that use petroleum products as raw materials for production in the chemical industry. At the tax post, representatives of the controlling authority at its location shall exercise constant direct control over the intended use of petroleum products as raw materials for the chemical industry.
229.5.12. A tax bill without payment of the amount of excise tax in cash is considered to be repaid in the event of documentary confirmation of the fact of the intended use of petroleum products exclusively as raw materials for production in the chemical industry.
229.5.13. To repay a tax bill, the bill holder shall be provided with a certificate from the drawer on the intended use of petroleum products as raw materials for production in the chemical industry , approved by a representative of the tax office established at the enterprise. A copy of the certificate on intended use shall be submitted to the supervisory authority.
229.5.14. If the tax bill provided for in this Article is not repaid within the established period, the bill holder shall protest such tax bill for non-payment in accordance with the law and within one business day from the date of the protest shall apply to the bank that has avalized this tax bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the bill holder's application with the protested tax bill.
229.5.15. The procedure for issuing, circulating and repaying tax bills issued prior to the import of petroleum products for use as raw materials for production in the chemical industry shall be established by the Cabinet of Ministers of Ukraine.
229.5.16. The list of enterprises importing petroleum products for use as raw materials for production in the chemical industry is approved by the Cabinet of Ministers of Ukraine.
229.5.17. Import of petroleum products used as raw materials for production in the chemical industry is carried out within the quotas established by the Cabinet of Ministers of Ukraine.
229.5.18. In the event of misuse by business entities of petroleum products imported as raw materials for production in the chemical industry, such entities shall be fined in the amount calculated based on the volumes of petroleum products used for purposes other than their intended purpose and the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code, increased by 1.5 times.
{Article 229 was supplemented by paragraph 229.5 in accordance with Law No. 3609-VI of 07.07.2011 }
229.6. Features of taxation of substances used as components of motor fuels produced in Ukraine and used as raw materials for the chemical industry
229.6.1. Substances used as components of motor fuels (codes 2707 10 00 00, 2707 20 00 90, 2707 30 00 90, 2707 50 00 90, 2905 11 00 00, 2909 19 10 00, 2909 19 90 10, 2909 19 90 20, 2909 19 90 90 according to the Ukrainian Customs Union of Foreign Economic Activities ) may be sold as raw materials for production in the chemical industry at a zero excise tax rate.
{Paragraph one of subparagraph 229.6.1 of paragraph 229.6 of Article 229 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1914-IX of 11/30/2021 }
In this case, regulatory authorities exercise control over their intended use.
Operations on the transfer of substances used as components of motor fuels (codes 2707 10 00 00, 2707 20 00 90, 2707 30 00 90, 2707 50 00 90, 2905 11 00 00, 2909 19 10 00, 2909 19 90 10, 2909 19 90 20, 2909 19 90 90 according to the UKT Foreign Economic Activity ) within one legal entity are carried out without the registration of a tax bill with mandatory confirmation of the intended use of such substances in the manner provided for by this paragraph of this article for operations on the registration of a tax bill.
{Subparagraph 229.6.1 of paragraph 229.6 of Article 229 is supplemented by the third paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Laws No. 909-VIII of 24.12.2015 , No. 2245-VIII of 07.12.2017 , No. 1914-IX of 30.11.2021 }
229.6.2. Prior to receipt of substances used as components of motor fuels used by business entities as raw materials for production in the chemical industry, the manufacturer shall issue a tax bill for the amount of excise tax charged on the volume of such substances based on the rate determined as the difference between the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code and the rate of 0 euros per 1,000 kilograms.
229.6.3. A tax bill may be issued only by a business entity - a manufacturer that uses as raw materials in the chemical industry substances that are used as components of motor fuels.
229.6.4. The term for which a tax bill is issued may not exceed 90 calendar days.
229.6.5. Obligations to repay a tax bill cannot be transferred to other persons.
229.6.6. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.6.7. The bill holder is the regulatory authority at the place of registration of the drawer.
229.6.8. Tax posts shall be established at enterprises that use substances used as components of motor fuels as raw materials for the production in the chemical industry. Representatives of the supervisory authority at the location of the tax post shall exercise constant direct control over the intended use of such substances.
229.6.9. A tax bill is considered to be repaid in the event of documentary confirmation of the fact of intended use exclusively as raw materials for the production in the chemical industry of substances used as components of motor fuels.
229.6.10. To repay a tax bill, the bill holder shall be provided with a certificate from the drawer on the intended use as raw materials for the production in the chemical industry of substances used as components of motor fuels , approved by a representative of the tax office established at the enterprise.
229.6.11. If the tax bill provided for in this paragraph is not repaid within the established period, the bill holder shall protest such bill for non-payment in accordance with the law and within one business day from the date of the protest shall apply to the bank that has avalized the bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the bill holder's application with the protested tax bill.
229.6.12. The procedure for issuing, circulating and repaying tax bills issued for the receipt of substances used as components of motor fuels for use as raw materials for production in the chemical industry, as well as the list of enterprises receiving such substances, shall be approved by the Cabinet of Ministers of Ukraine.
229.6.13. The shipment of substances used as components of motor fuels, which are obtained as raw materials for production in the chemical industry, is carried out within the quotas established by the Cabinet of Ministers of Ukraine.
229.6.14. In the event of misuse by business entities of substances used as components of motor fuels, which are obtained as raw materials for production in the chemical industry, such entities shall be fined in the amount calculated based on the volumes of the specified substances used for purposes other than their intended purpose and the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code, increased by 1.5 times.
{Article 229 was supplemented by paragraph 229.6 in accordance with Law No. 5471-VI of 06.11.2012 }
229.7. Features of taxation of substances used as components of motor fuels imported into Ukraine and used as raw materials for the chemical industry
229.7.1. Substances used as components of motor fuels (codes 2707 10 00 00, 2707 20 00 90, 2707 30 00 90, 2707 50 00 90, 2905 11 00 00, 2909 19 10 00, 2909 19 90 10, 2909 19 90 20, 2909 19 90 90 according to the Ukrainian Customs Union of Foreign Economic Activities ) may be imported into Ukraine as raw materials for production in the chemical industry without paying excise tax.
{Paragraph one of subparagraph 229.7.1 of paragraph 229.7 of Article 229 as amended by Laws No. 909-VIII of 24.12.2015 , No. 1914-IX dated 30.11.2021 }
In this case, regulatory authorities exercise control over their intended use.
229.7.2. For the import into the customs territory of Ukraine of substances used as components of motor fuels for the purpose of their use as raw materials in the chemical industry, the manufacturer shall issue a tax bill in triplicate. One copy shall be submitted to the regulatory authority at the location of the manufacturer, the second copy shall be submitted to the regulatory authority at the place of customs clearance of the specified goods, and the third copy shall remain with the taxpayer.
{Subclause 229.7.2 of Clause 229.7 of Article 229 as amended by Law No. 404-VII of 04.07.2013 }
229.7.3. A tax bill is issued for the amount of excise tax levied upon the import of goods in accordance with the legislation.
229.7.4. A tax bill may be issued only by a business entity - a manufacturer that uses as raw materials in the chemical industry substances used as components of motor fuels.
229.7.5. The term for which an avalized tax bill is issued cannot exceed 90 calendar days from the date of registration of the customs declaration.
229.7.6. The basis for customs clearance of substances used as components of motor fuels imported into the customs territory of Ukraine for use in the chemical industry is the submission by the manufacturer to the regulatory authority carrying out customs clearance, in accordance with the procedure provided for by the Customs Code of Ukraine, by electronic means of communication, of a copy of a tax bill endorsed by a bank and registered by the regulatory authority.
{Subclause 229.7.6 of Clause 229.7 of Article 229 as amended by Law No. 404-VII of 04.07.2013 ; as amended by Law No. 2245-VIII of 07.12.2017 }
229.7.7. Obligations to repay a tax bill cannot be transferred to other persons.
229.7.8. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.7.9. The bill holder is the regulatory authority at the place of registration of the drawer.
229.7.10. Tax posts shall be established at enterprises that use substances used as components of motor fuels as raw materials for the production in the chemical industry. Representatives of the supervisory authority at the location of the tax post shall exercise constant direct control over the intended use of such substances.
229.7.11. A tax bill is considered to be repaid without payment of the amount of excise tax in cash if there is documentary confirmation of the fact of the intended use of substances used as components of motor fuels, exclusively as raw materials for production in the chemical industry.
229.7.12. To repay a tax bill, the bill holder shall be provided with a certificate from the drawer on the intended use as raw materials for the production in the chemical industry of substances used as components of motor fuels , approved by a representative of the tax post established at the enterprise. A copy of the certificate shall be submitted to the supervisory authority.
229.7.13. If the tax bill provided for in this paragraph is not repaid within the established period, the bill holder shall protest such bill for non-payment in accordance with the law and within one business day from the date of the protest shall apply to the bank that has avalized the bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the bill holder's application with the protested tax bill.
229.7.14. The procedure for issuing, circulating and repaying tax bills issued for the import into the customs territory of Ukraine of substances used as components of motor fuels for use as raw materials for production in the chemical industry, as well as the list of enterprises importing such substances, shall be approved by the Cabinet of Ministers of Ukraine.
229.7.15. Import of substances used as components of motor fuels, which are used as raw materials for production in the chemical industry, is carried out within the quotas established by the Cabinet of Ministers of Ukraine.
229.7.16. In the event of misuse by business entities of substances used as components of motor fuels imported as raw materials for production in the chemical industry, such entities shall be fined in the amount calculated based on the volumes of the specified substances used for purposes other than their intended purpose and the excise tax rate provided for in paragraph 215.3 of Article 215 of this Code, increased by 1.5 times.
{Article 229 was supplemented by paragraph 229.7 in accordance with Law No. 5471-VI of 06.11.2012 }
229.8. Peculiarities of taxation of aviation gasoline and jet fuel
229.8.1. Import into the customs territory of Ukraine or sale of aviation gasoline (code 2710 12 31 00 according to the UKT FEA ) and jet engine fuel (code 2710 12 70 00, 2710 19 21 00 according to the UKT FEA ) produced in Ukraine may be carried out with the payment of excise tax at the rates determined by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code without the application of the increasing coefficient of 10.
229.8.2. For the import into the customs territory of Ukraine or the sale of aviation gasoline or jet fuel produced in Ukraine, the importer of aviation gasoline or jet fuel (hereinafter referred to as the importer) shall draw up a tax bill in triplicate, and the manufacturer of aviation gasoline or jet fuel (hereinafter referred to as the manufacturer) shall draw up two copies. The first copy shall be submitted to the regulatory authority (bill holder) at the location of the importer or manufacturer, the second copy shall remain with the importer or manufacturer, and the third copy shall be submitted to the regulatory authority at the place of customs clearance of such aviation gasoline or jet fuel.
229.8.3. A tax bill is issued for the amount of excise tax charged on the volume of aviation gasoline or jet fuel imported into the customs territory of Ukraine or produced in Ukraine, based on the rate determined as the difference between the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code with the application of an increasing coefficient of 10, and the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code without the application of an increasing coefficient of 10. The tax bill shall be accompanied by a calculation of the amount of excise tax.
The sale of volumes of aviation gasoline or jet fuel by business entities that have received excise invoices registered in the Unified Register of Excise Invoices, indicating the details of the tax bill issued for the amount of excise tax charged on such volumes, is carried out without paying excise tax.
229.8.4. The period for which a tax bill is issued cannot exceed 90 calendar days for jet fuel (code 2710 12 70 00, 2710 19 21 00 according to the UKT FEA ) and 270 calendar days for aviation gasoline (code 2710 12 31 00 according to the UKT FEA ).
{Subclause 229.8.4 of Clause 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
229.8.5. A tax bill may be issued only by an importer or a manufacturer - a tax payer.
229.8.6. A tax bill issued by the manufacturer is the basis for the sale of aviation gasoline or jet fuel with payment of excise tax at the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code without applying the increasing coefficient of 10.
229.8.7. The basis for customs clearance of aviation gasoline or jet fuel imported into the customs territory of Ukraine by an importer with payment of excise tax at the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code without applying the increasing coefficient of 10 is the submission by such importer to the controlling authority carrying out customs clearance, in accordance with the procedure provided for by the Customs Code of Ukraine , by means of electronic communication of a copy of the tax bill registered by the controlling authority.
229.8.8. Obligations to repay a tax bill may not be transferred to other persons, regardless of their relationship with the drawer.
229.8.9. No interest or other types of fees provided for by law for other types of bills of exchange shall be charged for the use of a tax bill.
229.8.10. A tax bill without payment of the amount of excise tax specified therein shall be repaid in the event of confirmation of the fact of the intended use of aviation gasoline or jet fuel during the period for which such a bill was issued, by registering excise invoices in the Unified Register of Excise Invoices for transactions with:
1) refueling of aircraft with aviation gasoline or jet fuel prepared by business entities that provide aviation fuel in accordance with the current certificate of compliance with the requirements of the aviation rules of Ukraine for ground handling, issued by the authorized body for civil aviation, or by business entities that have a certificate of admission to the operation of a permanent take-off and landing site, issued by the authorized body for civil aviation in accordance with the requirements of the aviation rules of Ukraine;
{Paragraph two of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
2) sales of aviation gasoline or jet engine fuel to aircraft manufacturing entities subject to the provisions of Article 2 of the Law of Ukraine "On the Development of the Aircraft Manufacturing Industry", drawn up by the taxpayer carrying out such sales;
3) sales of aviation gasoline or jet fuel to customers who have made a purchase to meet the needs of the state or a territorial community in accordance with the Law of Ukraine "On Public Procurement", drawn up by the taxpayer carrying out such sales;
4) sales of aviation gasoline or jet fuel to the central executive body implementing state policy in the field of state material reserves, compiled by the taxpayer carrying out such sales.
{Paragraph five of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
Excise invoices for such transactions are drawn up on the basis of primary documents.
Tax bill without payment of the amount of excise tax specified in it for transactions defined as:
{Paragraph seven of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
in subparagraph 1 of this subparagraph, - is repaid on the basis of excise invoices registered in the Unified Register of Excise Invoices by the business entities specified in subparagraph 1 of this subparagraph, based on the volumes of fuel specified in such excise invoices;
{Paragraph eight of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
in subparagraphs 2-4 of this subparagraph, - shall be repaid on the basis of copies of primary documents and contracts for the sale of fuel, confirming the sale of fuel throughout the entire fuel sales chain from the manufacturer/importer to the entities specified in subparagraphs 2-4 of this subparagraph, submitted to the regulatory authority, and excise invoices drawn up for such transactions and registered in the Unified Register of Excise Invoices.
{Paragraph of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
A tax bill without payment of the amount of excise tax specified therein on the volumes of lost aviation gasoline or jet fuel that do not exceed the loss standards approved by the Cabinet of Ministers of Ukraine shall be repaid on the basis of copies of primary documents on the loss of such volumes of fuel and excise invoices registered in the Unified Register of Excise Invoices.
{Paragraph of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
The amount of excise tax paid by the manufacturer/importer before the expiration of the term for which the tax bill was issued, based on the volumes of aviation gasoline or jet fuel, the intended use of which has not been confirmed, shall be taken into account by the bill holder upon repayment of the tax bill. Such amount of tax is calculated based on the volume of aviation gasoline or jet fuel, the intended use of which has not been confirmed, and the tax rate, which is determined as the difference between the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code with the application of an increasing coefficient of 10, and the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code without the application of an increasing coefficient of 10.
{Paragraph of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
The bill holder shall verify the documents provided by the manufacturer/importer for the repayment of the tax bill within five business days from the date of their receipt. Based on the results of the verification, the bill holder shall make a decision to repay the tax bill or to carry out the procedures provided for in subparagraph 229.8.11 of this paragraph.
{Paragraph of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
Information on business entities that provide aviation fuel supply in accordance with the current certificate of compliance with the requirements of the aviation rules of Ukraine for the provision of ground handling services, and business entities that have a certificate of admission to the operation of a permanent airfield, issued by the authorized body for civil aviation in accordance with the requirements of the aviation rules of Ukraine, is published by the central executive body that implements state policy in the field of civil aviation and the use of airspace of Ukraine, on its official website.
{Paragraph thirteen of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
Business entities that provide aviation fuel in accordance with the current certificate of compliance with the requirements of the aviation rules of Ukraine for the provision of ground services, and business entities that have a certificate of admission to the operation of a permanent airfield issued by the authorized body for civil aviation in accordance with the requirements of the aviation rules of Ukraine, shall provide information on the aircraft that were refueled and on the volumes of aviation gasoline or jet fuel used to refuel such aircraft as part of the excise tax declaration.
{Paragraph fourteen of subparagraph 229.8.10 of paragraph 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
229.8.11. If the tax bill provided for in this paragraph is not repaid within the established period, the bill holder shall, within five business days following the last day of the period for which the tax bill was issued, protest such bill for non-payment in accordance with the law and, within one business day from the date of the protest, apply to the bank that avalized the bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the application of the bill holder with the protested tax bill.
{Subclause 229.8.11 of Clause 229.8 of Article 229 as amended by Law No. 391-IX of 18.12.2019 }
229.8.12. In the event of the absence of confirmation within the established period of the intended use of aviation gasoline or jet fuel by the importer or manufacturer who issued the tax bill, such importer or manufacturer shall be charged a fine in the amount of 50 percent of the amount of excise tax, which is calculated based on the volumes of aviation gasoline or jet fuel for which there is no confirmation of intended use, and the excise tax rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code, with the application of an increasing coefficient of 10.
229.8.13. Business entities specified in subparagraphs 2-3 of subparagraph 229.8.10 of this paragraph have the right to sell aviation gasoline and/or jet fuel to other persons upon payment of excise tax charged on the volumes of such fuel, based on the rate determined as the difference between the rate established by subparagraph 215.3.4 of subparagraph 215.3 of Article 215 of this Code with the application of an increasing coefficient of 10, and the rate established by subparagraph 215.3.4 of subparagraph 215.3 of Article 215 of this Code without the application of an increasing coefficient of 10.
{Clause 229.8 of Article 229 is supplemented by subparagraph 229.8.13 in accordance with Law No. 391-IX of 18.12.2019 }
{Article 229 was supplemented by paragraph 229.8 in accordance with Law No. 2628-VIII of 23.11.2018 }
230.1. Excise warehouses and mobile excise warehouses are established to increase the efficiency of work to prevent and combat the illegal production and circulation of ethyl alcohol, vodka and alcoholic beverages, fuel, and to strengthen control over the completeness and timeliness of excise tax receipts to the budget.
230.1.1. Excise warehouses on the territory of which ethyl alcohol, including bioethanol, is produced, must be equipped with:
at each place of receipt and release of undenatured ethyl alcohol located in an excise warehouse, with flow meters-counters of ethyl alcohol, which are designed for continuous measurement, storage, recording and display in electronic form of data on the volume of receipt or release of ethyl alcohol in decalitres of 100 percent alcohol brought to a temperature of 20°C (hereinafter referred to as the flow meter-counter of ethyl alcohol), registered in the Unified State Register of flow meters-counters of the volume of ethyl alcohol produced;
at each place of receipt and release of denatured ethyl alcohol, including bioethanol, located in an excise warehouse, with mass flow meters designed to continuously measure, store, record and display in electronic form data on the volume of receipt and/or release of denatured ethyl alcohol, including bioethanol, in kilograms (hereinafter referred to as the mass flow meter), registered in the Unified State Register of Flow Meters-Counters of the Volume of Produced Ethyl Alcohol.
Taxpayers - managers of excise warehouses are obliged to:
a) register all ethyl alcohol flow meters and mass flow meters located in excise warehouses in the Unified State Register of Flow Meters and Meters of the Volume of Ethyl Alcohol Produced;
b) register all excise warehouses in the electronic administration system for the sale of fuel and ethyl alcohol;
c) send to the central executive body implementing state tax policy a technological scheme for installing ethyl alcohol flow meters and/or mass flow meters by electronic means no later than 10 working days before the date of installation of ethyl alcohol flow meters and/or mass flow meters.
One excise warehouse may be registered exclusively by one excise warehouse manager. One excise warehouse manager may register one or more excise warehouses.
It is prohibited to obtain and sell ethyl alcohol, including bioethanol, without registered ethyl alcohol flow meters and/or registered mass flow meters, without registration of an excise warehouse, without a technological scheme for installing ethyl alcohol flow meters and/or mass flow meters sent to the central executive body implementing state tax policy, as well as through each place of receipt and sale of ethyl alcohol, including bioethanol, where the ethyl alcohol flow meter and/or mass flow meter is out of order or missing.
Ethyl alcohol flow meters, mass flow meters must meet the requirements of the legislation and have a positive result of verification or conformity assessment carried out in accordance with the legislation. In the absence of a technological scheme for installing ethyl alcohol flow meters and/or mass flow meters sent to the central executive body implementing state tax policy, and a positive result of verification or conformity assessment of ethyl alcohol flow meters, mass flow meters, for the purposes of this Code, the excise warehouses in which they are located are considered not equipped with ethyl alcohol flow meters, mass flow meters, respectively.
Excise warehouse managers are required to generate data on the daily actual volumes of ethyl alcohol received and sold, including bioethanol (hereinafter in this section - the volume of ethyl alcohol turnover), broken down by commodity subcategories codes according to the UKT Foreign Economic Activity in decaliters of 100 percent alcohol, brought to a temperature of 20°C, at each excise warehouse every day (except for days when the excise warehouse is closed).
Data on the volume of ethyl alcohol turnover, including bioethanol, are generated after the last transaction on the turnover of ethyl alcohol on the reporting day, but no later than 23:59 of this day, before the start of transactions on the turnover of ethyl alcohol on the day following the reporting day, and are submitted to the central executive body implementing state tax policy no later than 23:59 of the day following the reporting day.
Data on the volume of turnover of ethyl alcohol, including bioethanol, are submitted by sending electronic documents by electronic means of communication, drawn up in a form approved by the central executive body that ensures the formation and implementation of state financial policy.
Electronic documents are filled in by transferring to them data on the volume of circulation of undenatured ethyl alcohol from ethyl alcohol flow meters and/or the volume of circulation of denatured ethyl alcohol, including bioethanol, from mass flow meters, converted into decaliters of 100 percent alcohol brought to a temperature of 20°C, using methods determined in accordance with the Law of Ukraine "On Metrology and Metrological Activities". The responsible person of the excise warehouse manager also indicates in electronic documents data on the volume of ethyl alcohol residues, including bioethanol, located in the excise warehouse in containers, packaging, on the daily volume of sold ethyl alcohol, including bioethanol, in containers, packaging, as well as information on days when the excise warehouse is closed.
The procedure for maintaining the Unified State Register of flow meters for the volume of ethyl alcohol produced and for transmitting accounting data from them by electronic means of communication to regulatory authorities is established by the Cabinet of Ministers of Ukraine.
This register contains tax information about excise warehouse managers, the excise warehouses they have, ethyl alcohol flow meters, mass flow meters located in excise warehouses, their serial (identification) numbers, as well as data on the actual volume of ethyl alcohol turnover, including bioethanol, broken down by commodity subcategory codes according to the UKT FEA , excise warehouses, and excise warehouse managers.
Data on the actual volume of turnover of ethyl alcohol, including bioethanol, broken down by commodity subcategory codes according to the UKT FEA , excise warehouses and excise warehouse managers are compared by the central executive body implementing state tax policy with the indicators of the electronic administration system for the sale of fuel and ethyl alcohol.
Sealing of places of possible access to alcohol in excise warehouses, on the territory of which ethyl alcohol, including bioethanol, is produced, and on the territory of enterprises that are manufacturers of products specified in paragraph 229.1 of Article 229 of this Code, is carried out in accordance with the procedure approved by the central executive body that ensures the formation and implementation of state financial policy, which establishes requirements for sealing equipment, facilities, alcohol communications and alcohol metering devices, including ethyl alcohol flow meters, mass flow meters.
The scheme for installing 24-hour video surveillance systems for the production and release of ethyl alcohol in excise warehouses on the territory of which ethyl alcohol, including bioethanol, is produced, shall be sent to the central executive body implementing state tax policy by electronic means no later than 10 business days following the day of putting such a system into operation.
{Subclause 230.1.1 of Clause 230.1 of Article 230 as amended by Law No. 1914-IX of 11/30/2021 ; as amended by Law No. 2284-IX of 05/31/2022 }
230.1.2. Excise warehouses, on the territory of which production, processing (refining), mixing, bottling, loading-unloading, storage, and sale of fuel are carried out, must be equipped with flow meters at each point of fuel delivery in bulk from the excise warehouse located at the excise warehouse, and level meters for the level of such goods (products) in the tank, and for liquefied gas (propane or a mixture of propane and butane), other gases, butane, isobutane according to the codes according to the UKT ZEA 2711 12 11 00, 2711 12 19 00, 2711 12 91 00, 2711 12 93 00, 2711 12 94 00, 2711 12 97 00, 2711 13 10 00, 2711 13 30 00, 2711 13 91 00, 2711 13 97 00, 2711 14 00 00, 2711 19 00 00, 2901 10 00 10 - may also be equipped with devices for measuring the level or percentage of fuel in the tank (hereinafter referred to as the level gauge) on each commissioned stationary tank located in the excise warehouse.
{Paragraph one of subparagraph 230.1.2 of paragraph 230.1 of Article 230 as amended by Law No. 391-IX of 18.12.2019 }
Excise warehouses where activities are carried out for the processing of oil, gas condensate, natural gas and their mixtures, for the purification of coke oven gas, in order to extract target components (raw materials), which involves a full technological cycle of their processing into finished products (fuel), must be equipped only with flow meters at each point of release of finished excisable products (fuel) in bulk from such an excise warehouse.
{Paragraph two of subparagraph 230.1.2 of paragraph 230.1 of Article 230 as amended by Law No. 391-IX of 18.12.2019 }
Excise warehouses that exclusively store and sell fuel that is obtained and sold exclusively in consumer containers without changing the packaging, as well as liquefied natural gas, benzene, and methanol, are not equipped with flow meters and level meters.
{Paragraph three of subparagraph 230.1.2 of paragraph 230.1 of Article 230 as amended by Law No. 391-IX of 18.12.2019 }
Flow meters and tanks must meet the requirements of the legislation and have a positive result of verification or conformity assessment carried out in accordance with the legislation, and level meters must meet the requirements of the legislation and have a positive result of verification or conformity assessment, or calibration carried out in accordance with the legislation. In the absence of a positive result of verification or conformity assessment, or calibration of flow meters and level meters, for the purposes of this Code, the excise warehouses in which they are located are considered to be unequipped flow meters and level meters.
Fuel dispensers and/or oil dispensers installed in excise warehouses, for which there are positive results of verification or conformity assessment carried out in accordance with the legislation, perform the functions of flow meters.
Taxpayers - managers of excise warehouses are required to register:
a) all tanks located in excise warehouses, put into operation, flow meters and level meters by excise warehouses - in the Unified State Register of Flow Meters and Level Meters of Fuel Level in the Tank;
b) all excise warehouses - in the system of electronic administration of fuel and ethyl alcohol sales.
One excise warehouse may be registered exclusively by one excise warehouse manager. One excise warehouse manager may register one or more excise warehouses.
It is prohibited to sell fuel without registered flow meters, level meters and tanks, or without registering an excise warehouse.
230.1.3. Excise warehouse managers are obliged to generate data on actual fuel balances at each excise warehouse daily (except for days when the excise warehouse is not operating) and on actual daily volumes of fuel received and sold (hereinafter in this section - fuel turnover) in terms of commodity subcategory codes according to the UKT Foreign Economic Activity in liters, brought to a temperature of 15°C.
Managers of excise warehouses, in whose excise warehouses activities are carried out for the processing of oil, gas condensate, natural gas and their mixtures, for the purification of coke oven gas, in order to extract target components (raw materials), which involves a full technological cycle of their processing into finished products (fuel), are obliged to generate data on a daily basis at each excise warehouse only on the daily actual volume of fuel sold in terms of commodity subcategory codes according to the UKT FEA in liters, brought to a temperature of 15° C.
{Paragraph two of subparagraph 230.1.3 of paragraph 230.1 of Article 230 as amended by Law No. 391-IX of 18.12.2019 }
Managers of excise warehouses that use fuel exclusively for their own consumption or industrial processing and do not carry out operations to sell and store fuel to other persons are obliged to generate data on the volumes of fuel turnover for the reporting calendar month and actual fuel balances as of the first and last days of such month in the breakdown of commodity subcategories codes according to the UKT FEA in liters, brought to a temperature of 15°C.
{Subparagraph 230.1.3 of paragraph 230.1 of Article 230 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
For the purposes of Articles 230-233 of this Code, liquefied gas (propane or a mixture of propane with butane), other gases, butane, isobutane according to the codes according to the UKT FEA 2711 12 11 00, 2711 12 19 00, 2711 12 91 00, 2711 12 93 00, 2711 12 94 00, 2711 12 97 00, 2711 13 10 00, 2711 13 30 00, 2711 13 91 00, 2711 13 97 00, 2711 14 00 00, 2711 19 00 00, 2901 10 00 10 are recorded under the conditional code 2711 in liters, brought to a temperature of 15°C.
{Subclause 230.1.3 of clause 230.1 of Article 230 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
Data on actual fuel balances and the volume of fuel turnover are generated after the last fuel turnover operation on the reporting day, but no later than 23:59 of that day, before the start of fuel turnover operations on the day following the reporting day, and are submitted to the central executive body implementing state tax policy no later than 23:59 of the day following the reporting day.
{Paragraph five of subparagraph 230.1.3 of paragraph 230.1 of Article 230 as amended by Law No. 391-IX of 18.12.2019 }
Data on actual fuel balances on the first and last days of the calendar month and on the volume of fuel turnover for the reporting calendar month are generated by managers of excise warehouses that use fuel exclusively for their own consumption or industrial processing and do not carry out operations on the sale and storage of fuel to other persons, after the last fuel turnover operation in the reporting calendar month, but no later than 23:59 on the last day of the reporting calendar month, before the start of fuel turnover operations on the day following such last day of the reporting calendar month, and are submitted to the central executive body implementing state tax policy no later than 15 calendar days following the last day of the reporting calendar month.
{Subparagraph 230.1.3 of paragraph 230.1 of Article 230 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
At each excise warehouse, for each commodity subcategory code according to the UKT Foreign Economic Activity, indicators are generated on:
the volumes of fuel residues at the beginning and end of the reporting day, determined by summing the volumes of fuel residues in each tank based on the readings of level meters installed on such tanks located at such excise warehouse;
daily volume of fuel sold, determined by summing the volumes of fuel sold during the reporting day through each point of sale of fuel in bulk from an excise warehouse based on the readings of flow meters installed at each point of sale of fuel in bulk from an excise warehouse located at such an excise warehouse;
the daily volume of fuel received, which is determined by subtracting the volume of fuel remaining at the end of the reporting day from the volume of fuel remaining at the beginning of the reporting day and adding the daily volume of fuel sold from such excise warehouse with the addition of the volume of lost fuel indicated in the excise invoices registered in the Unified Register of Excise Invoices, and with the subtraction of the additional volume of fuel indicated in the applications for replenishment of the volume of fuel remaining or ethyl alcohol registered in the electronic administration system for the sale of fuel and ethyl alcohol.
The actual indicators of flow meters and level meters regarding the volume of fuel residues and the daily volume of fuel sold are converted into liters, brought to a temperature of 15° C, except for the indicators of fuel dispensers and/or oil dispensers that perform the functions of flow meters.
During the failure, verification or calibration of a level meter or flow meter, the determination of data on the volume of fuel residues and the volume of fuel circulation is carried out in full-capacity measures that have a positive result of the verification carried out in accordance with the legislation, and/or using a tape measure and a meter rod or a portable (portable) level meter-analyzer that have a positive result of the verification carried out in accordance with the legislation. The use of this measurement method may be carried out for no more than 20 calendar days in a row (for excise warehouses that are places of retail sale of fuel for which licenses for the right to retail sale of fuel have been obtained - no more than 15 calendar days in a row) and no more than four times during a calendar year.
Data on fuel balances and fuel turnover are submitted by electronic means of communication in the form of electronic documents, which is approved by the central executive body that ensures the formation and implementation of state financial policy.
Electronic documents are filled in automatically by transferring data from flow meters and level meters to them (during a failure, verification or calibration of a level meter or flow meter - they are filled in by the responsible person of the excise warehouse manager).
The electronic documents also contain data on the volume of fuel residues in the excise warehouse in containers, cylinders, and packaging, on the daily volume of fuel sold in containers, cylinders, and packaging, as well as information on days when the excise warehouse is closed, by the responsible person of the excise warehouse manager.
230.1.4. The procedure for maintaining the Unified State Register of flow meters and fuel level meters in the tank, and for transmitting accounting data from them by electronic means of communication to regulatory authorities shall be established by the Cabinet of Ministers of Ukraine.
This register contains tax information about excise warehouse managers, the excise warehouses they have, tanks located in excise warehouses, flow meters and level meters, their serial (identification) numbers, as well as data on the actual fuel balances at the beginning and end of the reporting day and on the actual volume of fuel turnover broken down by commodity subcategory codes according to the UKT FEA , excise warehouses and excise warehouse managers.
Data on actual fuel balances at the beginning and end of the day and on the actual volume of fuel turnover by commodity subcategory codes according to the UKT FEA , excise warehouses and excise warehouse managers are compared by the central executive body implementing state tax policy with the indicators of the electronic administration system for the sale of fuel and ethyl alcohol.
230.1.5. Vehicles that have acquired the status of mobile excise warehouses, as well as vehicles used by a business entity that is not the manager of an excise warehouse, to move its own fuel or ethyl alcohol within the customs territory of Ukraine for its own consumption or industrial processing, must be recorded in the List of Vehicles Moving Fuel or Ethyl Alcohol, the creation and maintenance of which is ensured by the central executive body implementing state tax policy, in accordance with the procedure approved by the central executive body ensuring the formation and implementation of state financial policy. The list of vehicles moving fuel or ethyl alcohol is posted on the official website of the central executive body implementing state tax policy.
Inclusion/exclusion of vehicles to/from the List of vehicles transporting fuel or ethyl alcohol is carried out automatically based on excise invoices registered in the Unified Register of Excise Invoices, or on the basis of applications for the movement of fuel or ethyl alcohol by vehicles that are not mobile excise warehouses, indicating the period of movement of such fuel or ethyl alcohol, or on the basis of customs declarations when moving fuel or ethyl alcohol through the customs territory of Ukraine by transit or internal transit, defined by subparagraph "a" of paragraph 2 of part two of Article 91 of the Customs Code of Ukraine. Such applications are submitted by business entities that are not managers of excise warehouses, before moving their own fuel or ethyl alcohol through the customs territory of Ukraine in vehicles that are not mobile excise warehouses for the needs of their own consumption or industrial processing. The application form for the movement of fuel or ethyl alcohol by means of transport that are not mobile excise warehouses shall be approved by the central executive body that ensures the formation and implementation of state financial policy. Such applications in the form of electronic documents shall be sent to the central executive body that implements state tax policy.
The movement of fuel or ethyl alcohol by means of transport that are not specified in excise invoices registered in the Unified Register of Excise Invoices drawn up for transactions in which fuel or ethyl alcohol is moved in such means of transport, as well as those not specified in applications for the movement of fuel or ethyl alcohol by means of transport that are not mobile excise warehouses, which are sent to the central executive body implementing state tax policy, is prohibited.
Vehicles used for the movement of fuel or ethyl alcohol within the customs territory of Ukraine are not equipped with flow meters and level meters.
{Clause 230.1 of Article 230 as amended by Laws No. 5503-VI of 11/20/2012 , No. 71-VIII of 12/28/2014 , No. 909-VIII of 12/24/2015 ; as amended by Law No. 2628-VIII of 11/23/2018 }
230.2. Representatives of the controlling authority at the location of the excise warehouse (except for fuel) are permanently present at excise warehouses.
{Clause 230.2 of Article 230 as amended by Law No. 909-VIII of 24.12.2015 }
230.3. The controlling authority at the location of the excise warehouse shall appoint its permanent representative(s) at such warehouse.
230.4. A copy of the order appointing a representative(s) of the controlling authority shall be sent to the excise warehouse manager on the day such decision is made.
230.5. The representative(s) of the controlling body shall exercise constant direct control over the availability of ethyl alcohol flow meters, mass flow meters and other measuring devices; compliance with the established procedure for the release of ethyl alcohol, including bioethanol, vodka and alcoholic beverages and payment of tax on them.
{Clause 230.5 of Article 230 as amended by Law No. 5503-VI of 20.11.2012 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 909-VIII of 24.12.2015 , No. 2628-VIII of 23.11.2018 ; as amended by Law No. 2284-IX of 31.05.2022 }
230.6. The work schedule of representatives of the controlling authority must comply with the work schedule of the excise warehouse established by its manager.
230.7. Officials appointed as representatives of the control body at the excise warehouse must undergo special training or instruction on the specifics of control over the production and circulation of ethyl alcohol, including bioethanol, vodka and alcoholic beverages, as well as the methods of using measuring devices.
{Clause 230.7 of Article 230 as amended by Laws No. 404-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 , No. 909-VIII of 24.12.2015 , No. 2284-IX of 31.05.2022 }
230.8. The procedure for conducting special training or instruction shall be approved by the central executive body responsible for the formation and implementation of state financial policy.
{Clause 230.8 of Article 230 as amended by Law No. 1797-VIII of 21.12.2016 }
230.9. In orders on appointment, the head (his deputy or authorized person) of the controlling body determines the working regime of the representative of the controlling body, taking into account the working regime of the excise warehouse, the procedure for monitoring the work of the representative of the controlling body, develops measures for the material and technical support of the representative of the controlling body, transport services, and other conditions necessary to ensure the effectiveness of control.
{Clause 230.9 of Article 230 as amended by Law No. 1797-VIII of 21.12.2016 }
230.10. A copy of the order shall be sent to the manager of the excise warehouse, who shall be obliged to issue a corresponding order within three days, providing for the creation of appropriate conditions for the effective work of the representative of the regulatory authority.
230.11. The main task of the representative of the controlling authority at excise warehouses is to exercise constant direct control over compliance with the established procedure for the production, storage, release of ethyl alcohol, including bioethanol, vodka and alcoholic beverages, and payment of tax, and to take measures to prevent violations of the legislation of Ukraine.
{Clause 230.11 of Article 230 as amended by Laws No. 71-VIII of 12/28/2014 , No. 909-VIII of 12/24/2015 , No. 2284-IX of 05/31/2022 }
230.12. The representative of the controlling authority at the excise warehouse, in accordance with the tasks assigned to him:
a) exercises control over the production, storage, release, if there is an ethyl alcohol flow meter, mass flow meter and other measuring devices, and accounting for ethyl alcohol, including bioethanol, vodka and alcoholic beverages according to the accounting data of the excise warehouse;
{Subparagraph "a" of paragraph 230.12 of Article 230 as amended by Laws No. 5503-VI of 11/20/2012 , No. 71-VIII of 12/28/2014 , No. 2628-VIII of 11/23/2018 ; as amended by Law No. 2284-IX of 05/31/2022 }
b) exercises control over the registration, storage and use of excise tax stamps and product labeling;
c) controls the accounting of the receipt and consumption of raw materials used for the production of ethyl alcohol, including bioethanol, vodka and alcoholic beverages, and the quantity of products produced;
{ Subparagraph "c" of paragraph 230.12 of Article 230 as amended by Laws No. 71-VIII of 12/28/2014 , No. 2284-IX of 05/31/2022 }
d) monitors compliance with the established procedure for calculating and paying tax;
e) participates in conducting an inventory of raw materials, ethyl alcohol, including bioethanol, vodka and alcoholic beverages, and excise tax stamps;
{ Subparagraph "g" of paragraph 230.12 of Article 230 as amended by Laws No. 71-VIII of 12/28/2014 , No. 2284-IX of 05/31/2022 }
e) in the event of violations of the procedure established by law for keeping records, storing and releasing ethyl alcohol, including bioethanol, vodka and alcoholic beverages, excise tax stamps, and raw materials, provide the manager of the excise warehouse with proposals to eliminate the identified violations and monitor their implementation;
{ Subparagraph "d" of paragraph 230.12 of Article 230 as amended by Laws No. 71-VIII of 12/28/2014 , No. 2284-IX of 05/31/2022 }
e) makes proposals to improve the control system for the accounting, storage, release and transportation of vodka and alcoholic beverages;
{ Subparagraph "e" of paragraph 230.12 of Article 230 as amended by Law No. 71-VIII of 28.12.2014 }
h) is present when sealing places of possible access to alcohol (including ethyl alcohol flow meters and mass flow meters), alcohol storage, bottling shop and finished product warehouse after the end of the working day.
{Subparagraph "e" of paragraph 230.12 of Article 230 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 2284-IX of 05/31/2022 }
{Clause 230.12 of Article 230 as amended by Law No. 909-VIII of 24.12.2015 }
230.13. During the import of alcohol, a representative of the regulatory authority at the excise warehouse of the enterprise where vodka and alcoholic beverages are produced:
a) participates in the work of the commission for accepting ethyl alcohol and makes a record in the ethyl alcohol receipt registration log about the amount of alcohol received, the time of entry and the vehicle's mileage;
{Subparagraph "a" of paragraph 230.13 of Article 230 as amended by Law No. 5503-VI of 11/20/2012 ; as amended by Law No. 1638-VII of 08/12/2014 ; as amended by Law No. 391-IX of 12/18/2019 ; as amended by Law No. 466-IX of 01/16/2020 }
b) sends a certificate of receipt of ethyl alcohol within three days to the representative of the regulatory authority at the excise warehouse of the enterprise that released the alcohol, which is noted in the specified journal.
{Clause 230.13 - 1 of Article 230 was excluded on the basis of Law No. 2628-VIII of 23.11.2018 }
230.14. In the event of detection of facts of non-registration or incomplete registration of ethyl alcohol, the regulatory authorities shall take appropriate measures in accordance with the law.
The inventory of ethyl alcohol in the excise warehouse, including the inventory conducted on the first day of each month, is conducted in the presence of a representative of the controlling authority at the excise warehouse.
{Paragraph 230.14 of Article 230 is supplemented by the second paragraph in accordance with Law No. 1638-VII of 12.08.2014 }
If the inventory results reveal losses of ethyl alcohol exceeding the loss norms established in accordance with Clause 214.6 of Article 214 of this Code, or if these losses did not arise for reasons specified in Clause 216.3 of Article 216 of this Code, the payer shall pay excise tax based on the amount of such losses and the excise tax rate in effect on the date of drawing up the inventory report.
{Clause 230.14 of Article 230 was supplemented with the third paragraph in accordance with Law No. 1638-VII of 12.08.2014 }
In the event of detection of excess ethyl alcohol, the regulatory authority shall take appropriate measures in accordance with the law.
{Clause 230.14 of Article 230 was supplemented with a fourth paragraph in accordance with Law No. 1638-VII of 12.08.2014 }
230.15. During the shipment of vodka and alcoholic beverages, a consignment note is filled out, registered in the Unified Register of Consignment Notes for the Movement of Alcoholic Beverages, in which the representative of the controlling authority at the excise warehouse makes a note of approval of the release by affixing the stamp "Exit permitted" and a personal signature, indicating the time of departure from the excise warehouse and the vehicle's mileage, and also makes an entry in the logbook of registration of the shipment of vodka and alcoholic beverages.
{Clause 230.15 of Article 230 as amended by Laws No. 5503-VI of 20.11.2012 , No. 1638-VII dated 12.08.2014 , No. 391-IX dated 18.12.2019 }
230.16. All documents that are the basis for the release of ethyl alcohol, vodka, and alcoholic beverages are necessarily checked by a representative of the regulatory authority at the excise warehouse.
{Clause 230.16 of Article 230 as amended by Law No. 1638-VII of 12.08.2014 }
230.17. When importing vodka and alcoholic beverages into an excise warehouse, a representative of the regulatory authority makes a note on the consignment note registered in the Unified Register of Consignment Notes for the Movement of Alcoholic Beverages, approving their import by affixing the stamp "Entry permitted" and a personal signature, indicating the time of entry into the excise warehouse and the vehicle's mileage, and also makes an entry in the logbook of receipt of vodka and alcoholic beverages.
{Clause 230.17 of Article 230 as amended by Laws No. 5503-VI of 20.11.2012 , No. 1638-VII dated 12.08.2014 , No. 391-IX dated 18.12.2019 }
230.18. Transportation of vodka and alcoholic beverages shipped from the excise warehouse of an enterprise where vodka and alcoholic beverages are produced, without consignment notes registered in the Unified Register of Consignment Notes for the Movement of Alcoholic Beverages, with a mark from a representative of the controlling authority at the excise warehouse, is prohibited.
{Paragraph one of clause 230.18 of Article 230 as amended by Law No. 1638-VII of 12.08.2014 }
The procedure for maintaining the Unified Register of Consignment Notes for the Movement of Alcoholic Beverages is established by the Cabinet of Ministers of Ukraine.
{Paragraph 230.18 of Article 230 supplemented by the second paragraph in accordance with Law No. 5503-VI of 20.11.2012 }
{Clause 230.18 of Article 230 as amended by Laws No. 5503-VI of 11/20/2012 , No. 2628-VIII of 11/23/2018 }
230.19. The manager of an excise warehouse is obliged to:
a) provide the permanent representative of the regulatory authority with a separate room that meets sanitary and hygienic standards, equipped with a telephone, and take measures to prevent unauthorized interference in the work of the representative of the regulatory authority and the use of official and other information stored by the representative of the regulatory authority at the excise warehouse;
b) install and maintain in proper condition the necessary locks, seals, meters or other measuring devices that may be required by the permanent representative of the controlling authority at the excise warehouse in order to ensure the full payment of the due amount of tax on alcohol, vodka and alcoholic beverages, and fuel produced at the excise warehouse;
{ Subparagraph "b" of paragraph 230.19 of Article 230 as amended by Law No. 71-VIII of 28.12.2014 }
c) ensure accounting of the availability and movement of raw materials, ethyl alcohol and water-alcohol solutions in the unfinished production of vodka and alcoholic beverages and finished products placed in the excise warehouse;
d) submit reliable information on this issue to the permanent representative of the regulatory authority, as well as relevant primary accounting and reporting documents for review.
{Clause 230.19 of Article 230 as amended by Law No. 909-VIII of 24.12.2015 }
{Clause 230.20 of Article 230 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Clause 230.21 of Article 230 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Clause 230.22 of Article 230 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Clause 230.23 of Article 230 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
231.1. The taxpayer, upon import into the customs territory of Ukraine of fuel or ethyl alcohol on which excise tax has been paid, or under the conditions specified in Article 229 of this Code, or upon sale of fuel or ethyl alcohol, shall be obliged to draw up an excise invoice in electronic form for each commodity subcategory code in accordance with the Ukrainian Classification of Foreign Economic Activities of the sold fuel or ethyl alcohol using a qualified electronic signature or an advanced electronic signature based on a qualified electronic signature certificate of a person authorized by the payer in accordance with the requirements of the Law of Ukraine "On Electronic Identification and Electronic Trust Services" and to register such an excise invoice in the Unified Register of Excise Invoices.
{Paragraph one of clause 231.1 of Article 231 as amended by Law No. 2918-IX of 07.02.2023 }
The taxpayer is obliged to issue an excise invoice for the volumes of fuel or ethyl alcohol used for his own consumption; sold and/or used for the production of non-excise products under the conditions established by Article 229 of this Code; lost within and/or exceeding the established loss norms; spoiled, destroyed, including as a result of an accident, fire, flood, other force majeure circumstances or for another reason related to a natural result, as well as as a result of evaporation in the process of production, processing, processing, storage or transportation of such fuel or ethyl alcohol, as well as when carrying out operations that are not subject to taxation or are exempt from taxation.
The fuel producer, as well as the person who fills fuel into consumer containers with a capacity of up to 5 liters (inclusive), are required to draw up an excise invoice for the volumes of such fuel.
A manufacturer of ethyl alcohol that bottles ethyl alcohol used as a medicine into medical glass bottles with a volume of no more than 100 cubic centimeters is required to prepare an excise invoice for the volume of such ethyl alcohol.
The excise invoice contains the following mandatory details in separate fields:
a) serial number of the excise invoice with copy number;
b) date of preparation of the excise invoice;
c) full or abbreviated name of a legal entity or surname, first name and patronymic of an individual registered as an excise tax payer - a person who sells fuel or ethyl alcohol;
d) EDRPOU code (for legal entities) or registration number of the taxpayer's registration card (for individuals) of the person selling fuel or ethyl alcohol, and of the business entity - recipient of fuel or ethyl alcohol;
e) full or abbreviated name of the legal entity or surname, first name and patronymic of the individual - business entity - recipient of fuel or ethyl alcohol;
e) commodity subcategory code according to the UKT FEA or the conditional code defined in subparagraph 230.1.3 of paragraph 230.1 of this article;
{Paragraph eleven of clause 231.1 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
e) description of fuel or ethyl alcohol;
h) the volume of fuel in liters, brought to a temperature of 15° C, or the volume of ethyl alcohol in decaliters of 100 percent alcohol, brought to a temperature of 20° C;
g) the unified number of the excise warehouse in the electronic administration system for the sale of fuel and ethyl alcohol, from which the fuel or ethyl alcohol was sold;
h) the unified excise warehouse number in the electronic administration system for the sale of fuel and ethyl alcohol, for which the fuel was received;
i) the vehicle registration number in the authorized bodies of the relevant state and the type and capacity of the vehicle - mobile excise warehouse, and for pipeline transport - the name of the pipeline. When indicating the state registration number (Ukrainian, international or foreign) of the vehicle, it is allowed to use letters (Latin, Cyrillic) and numbers without spaces and punctuation marks. If the letter part of the number coincides in the Cyrillic and Latin alphabets, it is indicated in Latin, and if a specific Cyrillic letter is found, the letter part is indicated in Cyrillic;
{Paragraph sixteen of clause 231.1 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
i) an indication of the direction of use and conditions of taxation of fuel or ethyl alcohol;
j) a sign regarding the sale of fuel into the fuel tank of a vehicle or into a consumer container through a fuel or oil dispenser from an excise warehouse, which is a place of retail sale of fuel for which a license for the right to retail sale of fuel has been obtained;
{Paragraph eighteen of clause 231.1 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
j) indication of the import/export of fuel or ethyl alcohol into the customs territory of Ukraine/outside the customs territory of Ukraine;
{Paragraph nineteen of clause 231.1 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
k) an indication of the sale of fuel or ethyl alcohol from an excise warehouse to another excise warehouse using a mobile excise warehouse, if such another excise warehouse is already known before the sale of fuel or ethyl alcohol;
l) a sign regarding the sale of fuel under the conditions specified in paragraph 229.8 of Article 229 of this Code, indicating the details of the tax bill, business entities that provide aviation fuel in accordance with the current certificate of compliance with the requirements of the aviation rules of Ukraine for the provision of ground handling services, or aircraft manufacturing entities, or customers who have made a purchase to meet the needs of the state or a territorial community in accordance with the Law of Ukraine "On Public Procurement", or enterprises, institutions and organizations of the state reserve system;
m) address of the place of storage of fuel, which is not an excise warehouse, where a business entity that is not a taxpayer stores fuel exclusively for the needs of its own consumption or industrial processing;
n) sign for consolidated excise invoices;
{Clause 231.1 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
o) a sign of the sale of fuel into the fuel tank of the taxpayer's vehicle through a fuel or oil dispenser from an excise warehouse that is not a place of retail sale of fuel;
{Clause 231.1 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
p) a sign regarding the sale of fuel from an excise warehouse transferred to the fuel tank of a mobile vehicle, equipment or device.
{Clause 231.1 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
When selling fuel through a fuel or oil dispenser from an excise warehouse, which is a place of retail sale of fuel for which a license for the right to retail sale of fuel has been obtained, the details of the excise invoice identifying the recipient of the fuel, specified in subparagraphs "d" and "e" of this paragraph, are mandatory:
may not be filled in exclusively when selling fuel to a non-business entity;
are mandatory to be filled in when selling fuel to a business entity, indicating the data identifying such business entity.
When selling fuel or ethyl alcohol from an excise warehouse to another excise warehouse using a mobile excise warehouse, if such another excise warehouse is already known before the sale of fuel or ethyl alcohol, one excise invoice is drawn up for the sale of fuel from the excise warehouse to such another excise warehouse, indicating in such excise invoice the identification data of such mobile excise warehouse.
When refueling aircraft with aviation gasoline or jet fuel by business entities defined in subparagraph 1 of subparagraph 229.8.10 of Article 229 of this Code, excise invoices for such operations shall be drawn up and registered in the Unified Register of Excise Invoices by such business entities, regardless of who owns such aviation gasoline or jet fuel.
{Clause 231.1 of Article 231 is supplemented by paragraph thirty in accordance with Law No. 391-IX of 18.12.2019 }
When ownership of fuel in a vehicle is transferred from one business entity to another, the manager of the mobile excise warehouse changes, and the vehicle becomes another mobile excise warehouse, and an excise invoice is drawn up for such a transaction.
{Clause 231.1 of Article 231 is supplemented by paragraph thirty-one in accordance with Law No. 391-IX of 18.12.2019 }
{Clause 231.1 of Article 231 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2725-VIII of 05/16/2019 ; as amended by Law No. 2628-VIII of 11/23/2018 }
231.2. The form and procedure for filling out the excise invoice shall be approved by the central executive body responsible for the formation of state financial policy.
231.3. An excise invoice shall be drawn up by the taxpayer on the day of importation of fuel or ethyl alcohol into the customs territory of Ukraine or on the day of sale of fuel or ethyl alcohol for each full or partial transaction for the sale of fuel or ethyl alcohol.
{Paragraph one of clause 231.3 of Article 231 as amended by Law No. 2628-VIII of 23.11.2018 }
{Paragraph two of clause 231.3 of Article 231 was excluded on the basis of Law No. 2628-VIII of 23.11.2018 }
An excise invoice may be drawn up based on daily transaction results (if excise invoices were not drawn up for these transactions) for each commodity subcategory code in accordance with the UKT FEA in the case of fuel sales for cash to an end consumer (who is not a business entity), settlements for which are made through a cash register/registrars of settlement transactions and/or software registrars of settlement transactions, taking into account the requirements determined by the Cabinet of Ministers of Ukraine, or through a bank, non-bank payment service provider or payment device (directly to the account of the person selling fuel). In this case, certain mandatory details of the excise invoice identifying the recipient of fuel, determined by subparagraphs "d" and "e" of paragraph 231.1 of this article, are not filled in.
{Paragraph three of clause 231.3 of Article 231 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 129-IX of 09/20/2019 ; as amended by Law No. 2888-IX of 01/12/2023 }
In the event of ensuring a continuous supply of fuel, the person selling fuel may prepare consolidated excise invoices for each recipient of fuel for each commodity subcategory code in accordance with the UKT FEA no later than the last day of such month for the entire volume of fuel sold during such month.
{Paragraph four of clause 231.3 of Article 231 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 391-IX of 12/18/2019 }
For the purposes of this paragraph, continuous supply is considered to be the provision by the person selling fuel of the opportunity for fuel recipients to receive fuel at any hour of the day and on any day of the relevant month.
{Paragraph five of clause 231.3 of Article 231 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 391-IX of 12/18/2019 }
A consolidated excise invoice may also be drawn up for each commodity subcategory code in accordance with the UKT FEA and separately for each excise warehouse/mobile excise warehouse by a person selling fuel, no later than the last day of the reporting month for the total volume of fuel sold into the fuel tank of a vehicle or into a consumer's container through fuel or oil dispensers from an excise warehouse that is a place of retail trade for which an appropriate license has been obtained, if excise invoices were not drawn up for these operations, or used for own consumption or industrial processing during the reporting month, or lost within and/or in excess of the established loss norms, damaged, destroyed, including as a result of an accident, fire, flood, other force majeure circumstances or for other reasons related to a natural result, as well as as a result of evaporation in the process of production, processing, processing, storage or transportation during the reporting month. In the case of the sale of fuel through a fuel or oil dispenser into the fuel tank of a vehicle or into a consumer container for cash to the end consumer, settlements for which are made through settlement transaction registrars or through a bank, non-bank payment service provider or payment device, the payer has the right to independently choose the method of drawing up excise invoices for such transactions (summarized or based on daily transaction results).
{Paragraph six of clause 231.3 of Article 231 as amended by Law No. 2628-VIII of 11/23/2018 ; as amended by Law No. 391-IX of 12/18/2019 ; as amended by Law No. 2888-IX of 01/12/2023 }
A person who sells fuel or ethyl alcohol is obliged to prepare an excise invoice in one copy in the event of the sale of fuel or ethyl alcohol:
{Clause 231.3 of Article 231 was supplemented by the seventh paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
a) from an excise warehouse:
{Clause 231.3 of Article 231 is supplemented by paragraph eight in accordance with Law No. 2628-VIII of 23.11.2018 }
for own consumption or industrial processing or for volumes lost within and/or exceeding established loss norms, spoiled, destroyed, including as a result of an accident, fire, flood, other force majeure circumstances or for another reason related to a natural result, as well as as a result of evaporation in the process of production, processing, processing, storage or transportation of fuel or ethyl alcohol;
{Clause 231.3 of Article 231 supplemented by paragraph nine in accordance with Law No. 2628-VIII of 23.11.2018 ; as amended in accordance with Law No. 391-IX of 18.12.2019 }
to any other persons - not taxpayers;
{Clause 231.3 of Article 231 is supplemented by the tenth paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
to a taxpayer, a business entity that is not a taxpayer, a person who is not a business entity, into the fuel tank of a vehicle through a fuel or oil dispenser from an excise warehouse that is a place of retail fuel trade for which a license for the right to retail fuel trade has been obtained;
{Clause 231.3 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
to the taxpayer into the fuel tank of a vehicle through a fuel or oil dispenser from an excise warehouse that is not a place of retail sale of fuel;
{Clause 231.3 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
fuel in consumer containers with a capacity of up to 5 liters (inclusive);
{Clause 231.3 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
into the fuel tank of a vehicle, equipment or device;
{Clause 231.3 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
when refueling aircraft with aviation gasoline or jet fuel;
{Clause 231.3 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
b) from a mobile excise warehouse:
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
for own consumption or industrial processing or for the volume of lost/spoiled/destroyed fuel or ethyl alcohol;
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
to any other persons - not taxpayers.
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
A person who imports/exports fuel or ethyl alcohol into the customs territory of Ukraine/outside the customs territory of Ukraine is obliged to draw up an excise invoice in one copy based on the data of the relevant customs declaration.
{Clause 231.3 of Article 231 supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 391-IX of 18.12.2019 }
A person who has drawn up an excise invoice in one copy is obliged to register such excise invoice in the Unified Register of Excise Invoices.
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
A person who sells fuel or ethyl alcohol is obliged to prepare an excise invoice in duplicate in the event of the sale of fuel or ethyl alcohol:
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
a) from an excise warehouse to another excise warehouse, including through a pipeline or using a mobile excise warehouse, if such another excise warehouse is already known before the sale of fuel or ethyl alcohol;
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
b) from an excise warehouse to a mobile excise warehouse;
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
c) from a mobile excise warehouse to another mobile excise warehouse;
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
d) from a mobile excise warehouse to an excise warehouse.
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
A person who has drawn up an excise invoice in duplicate is obliged to register the first copy of such excise invoice in the Unified Register of Excise Invoices, and send the second copy of such excise invoice to the manager of the excise warehouse - the recipient of fuel or ethyl alcohol on the day of its drawing up.
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
The manager of the excise warehouse/manager of the mobile excise warehouse - the recipient of fuel or ethyl alcohol is obliged to register the second copy of such excise invoice in the Unified Register of Excise Invoices after registering the first copy of such excise invoice in the Unified Register of Excise Invoices and receiving fuel or ethyl alcohol at the excise warehouse/mobile excise warehouse.
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
If the taxpayer is simultaneously a person who sells and receives fuel or ethyl alcohol, the preparation and registration of excise invoices in duplicate shall be carried out in accordance with the procedure established by this paragraph for the preparation and registration of excise invoices in duplicate.
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
The taxpayer - the manager of a mobile excise warehouse, whose mobile excise warehouse was used to import fuel or ethyl alcohol into the customs territory of Ukraine, always draws up excise invoices when selling such fuel or ethyl alcohol from such mobile excise warehouse to another mobile excise warehouse or excise warehouse.
{Clause 231.3 of Article 231 is supplemented by a paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
The transfer of ownership of fuel or ethyl alcohol transported and/or stored in a vehicle from one business entity to another is considered the sale of fuel or ethyl alcohol from one mobile excise warehouse to another. In this case, the business entity from which the ownership of such fuel or ethyl alcohol is transferred is considered the person selling the fuel, and the business entity to which the ownership of such fuel or ethyl alcohol is transferred is considered the recipient of the fuel or ethyl alcohol.
{Clause 231.3 of Article 231 was supplemented by paragraph thirty in accordance with Law No. 391-IX of 18.12.2019 }
231.4. The right to prepare excise invoices is granted exclusively to persons registered as excise tax payers in accordance with the procedure provided for in Article 212 of this Code.
231.5. When selling fuel or ethyl alcohol, the person selling fuel or ethyl alcohol is obliged to draw up an excise invoice within the established time limits and register it in the Unified Register of Excise Invoices; such registration shall be considered as the provision of an excise invoice to the recipient of fuel or ethyl alcohol. Excise invoices that are not provided to the recipient of fuel or ethyl alcohol, and excise invoices/adjustment calculations drawn up for transactions on the sale of fuel or ethyl alcohol to business entities and individuals who are not excise tax payers, shall also be subject to registration in the Unified Register of Excise Invoices.
{Clause 231.5 of Article 231 as amended by Law No. 2628-VIII of 23.11.2018 }
231.6. Registration in the Unified Register of Excise Invoices is carried out:
excise invoices drawn up when selling fuel through a fuel or oil dispenser into the fuel tank of a vehicle from an excise warehouse that is a place of retail fuel trade for which a license for the right to retail fuel trade has been obtained - no later than fifteen calendar days following the date of their drawing up;
{Paragraph two of clause 231.6 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
the first copy of the excise invoice when selling fuel or ethyl alcohol from an excise warehouse - on the day of drawing up such an excise invoice, but no later than the date of the transaction for the sale of fuel or ethyl alcohol from an excise warehouse;
the first copy of the excise invoice when selling fuel or ethyl alcohol from a mobile excise warehouse to another mobile excise warehouse - on the day of drawing up such excise invoice, but no later than the transaction for selling fuel or ethyl alcohol from a mobile excise warehouse;
the first copy of the excise invoice when selling fuel or ethyl alcohol from a mobile excise warehouse to an excise warehouse - after the actual receipt of fuel or ethyl alcohol at the excise warehouse, but no later than three calendar days following the date of preparation of the excise invoice;
the first copy of the excise invoice when selling fuel from an excise warehouse to the fuel tank of a mobile vehicle, equipment or device, to a place of storage of fuel that is not an excise warehouse - within three calendar days from the date of actual receipt of fuel;
{Clause 231.6 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
the first copy of the consolidated excise invoice and the excise invoice drawn up for the transactions specified in subparagraph 1 of subparagraph 229.8.10 of paragraph 229.8 of Article 229 of this Code - no later than 15 calendar days from the date of their drawing up;
{Clause 231.6 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
excise invoice when importing fuel or ethyl alcohol into the customs territory of Ukraine - no later than the day following the day of proper registration of the customs declaration;
{Paragraph eight of clause 231.6 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
the first copy of the excise invoice drawn up when exporting fuel outside the customs territory of Ukraine - within three calendar days from the date of actual export of fuel outside the customs territory of Ukraine, which is confirmed by a properly executed customs declaration;
{Clause 231.6 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
the second copy of the excise invoice - after the actual receipt of fuel or ethyl alcohol at the excise warehouse/mobile excise warehouse, but no later than three calendar days following the day of receipt of fuel or ethyl alcohol at the excise warehouse/mobile excise warehouse by the manager of the excise warehouse/mobile excise warehouse - the recipient of fuel or ethyl alcohol;
calculation of the adjustment - no later than three calendar days following the date of its preparation.
Confirmation to the person selling fuel or ethyl alcohol of the acceptance of their excise invoice and/or calculation of the adjustment to the Unified Register of Excise Invoices is an electronic receipt in text format, which is sent during the operating day.
In order to receive an excise invoice/adjustment calculation registered in the Unified Register of Excise Invoices, the recipient of fuel or ethyl alcohol sends an electronic request to the Unified Register of Excise Invoices, after which he receives an electronic notification of the registration of the excise invoice/adjustment calculation in the Unified Register of Excise Invoices and the excise invoice/adjustment calculation in electronic form. Such excise invoice/adjustment calculation are considered registered in the Unified Register of Excise Invoices and received by the recipient of fuel or ethyl alcohol.
In order for a person who sells fuel or ethyl alcohol to receive an adjustment calculation registered in the Unified Register of Excise Invoices, which is subject to registration in the Unified Register of Excise Invoices by the recipient of the fuel or ethyl alcohol, such a person who sells fuel or ethyl alcohol shall send an electronic request to the Unified Register of Excise Invoices, after which he shall receive an electronic notification of registration of the adjustment calculation in the Unified Register of Excise Invoices and the adjustment calculation in electronic form. Such an adjustment calculation shall be considered registered in the Unified Register of Excise Invoices and received by the person who sells fuel or ethyl alcohol.
A person who issued a tax bill in accordance with subparagraph 229.8.10 of paragraph 229.8 of Article 229 of this Code has the right to receive notifications in electronic form with information on all excise invoices registered in the Unified Register of Excise Invoices, in which the tax bill issued by him is indicated, upon request to the Unified Register of Excise Invoices.
{Clause 231.6 of Article 231 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
The date and time of submission of the excise invoice and/or adjustment calculation in electronic form to the central executive body implementing state tax policy is the date and time recorded on the receipt.
{Paragraph sixteen of clause 231.6 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
If the sent excise invoices and/or adjustment calculations were generated in violation of the requirements stipulated in paragraph 231.1 of this article, during the operating day, the recipient of fuel or ethyl alcohol/person selling fuel or ethyl alcohol shall be sent an electronic receipt in text format stating their non-acceptance in electronic form, indicating the reasons.
If no receipt of acceptance or non-acceptance is sent during the operating day, such excise invoice/adjustment calculation is considered registered in the Unified Register of Excise Invoices.
Confirmation of the provision of a second copy of the excise invoice to the recipient of fuel or ethyl alcohol, registration in the Unified Register of Excise Invoices and receipt of the second copy of the excise invoice from the Unified Register of Excise Invoices shall be carried out in accordance with the rules provided for in this section for confirmation of the provision, registration and receipt from the Unified Register of Excise Invoices of adjustment calculations registered by recipients of fuel or ethyl alcohol.
The recipient of fuel or ethyl alcohol has the right to verify the data on the received excise invoice for compliance with the data in the Unified Register of Excise Invoices.
The taxpayer has the right to register an excise invoice and/or adjustment calculation in the Unified Register of Excise Invoices, in which the total volume of fuel or ethyl alcohol sold does not exceed the volume calculated in accordance with Clause 232.3 of Article 232 of this Code.
If the volume determined in accordance with Clause 232.3 of Article 232 of this Code is less than the volume of fuel or ethyl alcohol in the excise invoice and/or the adjustment calculation, which the taxpayer must register in the Unified Register of Excise Invoices, the taxpayer is obliged to transfer to the budget the amount of funds in the amount of excise tax for the corresponding volume of sold fuel or ethyl alcohol, independently calculated at the rates provided for in Subclauses 215.3.1 or 215.3.4 of Clause 215.3 of Article 215 of this Code, and register an application for replenishment of the remaining volume of fuel or ethyl alcohol in the system of electronic administration of the sale of fuel and ethyl alcohol.
In the event of a technical error in the software or software components, software and hardware, communication channels, the functioning of an electronic signature or other means of electronic identification (hereinafter referred to as technical maintenance), which makes it impossible to register excise invoices/adjustment calculations in the Unified Register of Excise Invoices, the central executive body implementing the state tax policy is obliged to immediately post on its official website a notice of the detection of such a technical error, indicating the date and time of its beginning, take all necessary measures to restore the registration of excise invoices/adjustment calculations in the Unified Register of Excise Invoices, and based on the results, post on its official website a notice of the elimination of the technical error, indicating the date and time of its completion.
{Paragraph twenty-three of paragraph 231.6 of Article 231 as amended by Laws No. 391-IX of December 18, 2019 , No. 2918-IX of February 7, 2023 }
During the period of technical maintenance, if it is impossible to register an excise invoice in the Unified Register of Excise Invoices, the movement of fuel or ethyl alcohol by means of transport is allowed if there is a freight bill, which must contain information from the relevant excise invoice, and a paper copy of the excise invoice signed by the person authorized to draw it up.
{Paragraph twenty-four of clause 231.6 of Article 231 as amended by Law No. 391-IX of 18.12.2019 }
The taxpayer is obliged, within three calendar days from the date of resumption of registration of excise invoices/adjustment calculations in the Unified Register of Excise Invoices, to register all excise invoices/adjustment calculations, the registration deadline for which falls within the period of existence of the technical error.
Penalties for untimely registration of excise invoices/adjustment calculations in the Unified Register of Excise Invoices, the registration deadline for which falls within the period of existence of a technical error, do not apply.
{Clause 231.6 of Article 231 as amended by Law No. 2628-VIII of 11/23/2018 }
231.7. If, after the sale of fuel or ethyl alcohol, part or all of the fuel or ethyl alcohol is returned to the person selling the fuel or ethyl alcohol, or there is a need to correct errors made when drawing up an excise invoice, the indicators of such an excise invoice shall be adjusted by drawing up an adjustment calculation and registering it in the Unified Register of Excise Invoices:
a person who sells fuel or ethyl alcohol, if an increase in the volume of fuel or ethyl alcohol sold is expected or if the adjustment of indicators does not ultimately change the volume of fuel or ethyl alcohol sold;
by the recipient of fuel or ethyl alcohol, if a reduction in the volumes of sold fuel or ethyl alcohol is envisaged, for which purpose the person selling fuel or ethyl alcohol shall send a prepared adjustment calculation to the recipient of fuel or ethyl alcohol. In this case, the person selling fuel or ethyl alcohol shall have the right to reduce the volume of sold fuel or ethyl alcohol according to such adjustment calculation after its registration in the Unified Register of Excise Invoices by the recipient of fuel or ethyl alcohol.
An adjustment calculation made by a taxpayer to excise invoices for the sale of fuel or ethyl alcohol to non-excise tax payers, or an adjustment calculation made for transactions other than the sale of fuel or ethyl alcohol to recipients of fuel or ethyl alcohol, shall be subject to registration in the Unified Register of Excise Invoices by such taxpayer.
Adjustment calculations shall be prepared in the same number of copies as the number of copies of the excise invoice to which they are prepared, except for adjustment calculations prepared for an excise invoice in which incorrect details of the person receiving the fuel are indicated, or errors are made in the details of the excise warehouse or mobile excise warehouse for which the fuel was received, as specified in subparagraphs "z" and "y" of paragraph 231.1 of this Article, or an excise invoice for a transaction for the sale of fuel or ethyl alcohol that did not take place.
{Clause 231.7 of Article 231 is supplemented by the fifth paragraph in accordance with Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 391-IX of 18.12.2019 }
In the event that the taxpayer indicates incorrect details of the person receiving the fuel in the excise invoice, or makes an error in the details of the excise warehouse or mobile excise warehouse for which the fuel was received, as specified in subparagraphs "z" and "y" of paragraph 231.1 of this article, or draws up an excise invoice for a transaction for the sale of fuel or ethyl alcohol that did not take place, and registers such excise invoice (the first copy of such excise invoice) in the Unified Register of Excise Invoices, the taxpayer shall draw up a calculation of the adjustment to such excise invoice:
{Clause 231.7 of Article 231 was supplemented by the sixth paragraph in accordance with Law No. 391-IX of 18.12.2019 }
in one copy - for correction of an excise invoice drawn up in one copy;
{Clause 231.7 of Article 231 was supplemented by the seventh paragraph in accordance with Law No. 391-IX of 18.12.2019 }
in one copy - for correction of an excise invoice drawn up in two copies, the second copy of which is not registered by the recipient in the Unified Register of Excise Invoices;
{Clause 231.7 of Article 231 is supplemented by paragraph eight in accordance with Law No. 391-IX of 18.12.2019 }
in duplicate - for correction of an excise invoice drawn up in duplicate, the second copy of which is registered by the recipient in the Unified Register of Excise Invoices.
{Clause 231.7 of Article 231 is supplemented by paragraph nine in accordance with Law No. 391-IX of 18.12.2019 }
The calculation of the adjustment to the excise invoice, which contains incorrect details of the person receiving the fuel, or errors in the details of the excise warehouse or mobile excise warehouse, specified in subparagraphs "z" and "y" of paragraph 231.1 of this article, for which the fuel was received, or the excise invoice for the operation of selling fuel or ethyl alcohol that did not take place, shall be registered in the Unified Register of Excise Invoices:
{Clause 231.7 of Article 231 is supplemented by paragraph ten in accordance with Law No. 391-IX of 18.12.2019 }
by a person who sells fuel or ethyl alcohol - a calculation of the adjustment, drawn up in one copy;
{Clause 231.7 of Article 231 is supplemented by the eleventh paragraph in accordance with Law No. 391-IX of 18.12.2019 }
the recipient of fuel or ethyl alcohol - an adjustment calculation, drawn up in duplicate.
{Clause 231.7 of Article 231 is supplemented by the twelfth paragraph in accordance with Law No. 391-IX of 18.12.2019 }
{Clause 231.7 of Article 231 as amended by Law No. 2628-VIII of 23.11.2018 }
231.8. The Unified Register of Excise Invoices operates continuously (24 hours a day), except for the time required for its technical maintenance.
Maintenance of the Unified Register of Excise Invoices is carried out at intervals with a small number of excise invoice registrations/adjustment calculations.
Information about the scheduled maintenance time of the Unified Register of Excise Invoices is posted on the official website of the central executive body implementing state tax policy no later than 24 hours before the start of maintenance.
The procedure for maintaining the Unified Register of Excise Invoices is established by the Cabinet of Ministers of Ukraine.
{Clause 231.8 of Article 231 as amended by Law No. 2628-VIII of 11/23/2018 }
231.9. The detection of discrepancies between the data of the taxpayer's excise tax declarations and the data of the Unified Register of Excise Invoices is the basis for the regulatory authorities to conduct an unscheduled documentary on-site inspection of the person selling fuel or ethyl alcohol, and in appropriate cases, the recipient of the fuel or ethyl alcohol.
{Clause 231.9 of Article 231 as amended by Law No. 2628-VIII of 23.11.2018 }
231.10. In the event of a violation by a person who sells fuel or ethyl alcohol of the procedure for filling out and/or the procedure for registering an excise invoice in the Unified Register of Excise Invoices, the recipient of fuel or ethyl alcohol has the right, within 60 calendar days following the day of sale of fuel or ethyl alcohol, to submit an application to the regulatory authority with a complaint against such a person who sells fuel or ethyl alcohol. The application shall be accompanied by copies of primary documents drawn up in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", confirming the fact of receipt of such fuel or ethyl alcohol, or additional written explanations from a business entity that did not actually receive fuel or ethyl alcohol, but is indicated in the excise invoice registered in the Unified Register of Excise Invoices as the recipient of fuel or ethyl alcohol.
{Paragraph one of clause 231.10 of Article 231 as amended by Law No. 2628-VIII of 23.11.2018 }
The receipt of such a statement with a complaint is grounds for conducting a documentary unscheduled on-site inspection of the specified person who sells fuel or ethyl alcohol.
{Paragraph two of clause 231.10 of Article 231 as amended by Law No. 2628-VIII of 23.11.2018 }
{The Code is supplemented by Article 231 in accordance with Law No. 909-VIII of 24.12.2015 - the amendment regarding the introduction of excise invoices for the sale of fuel, the Unified Register of Excise Invoices and the system of electronic administration of fuel sales comes into force on March 1, 2016 - see paragraph 1 of Section II of Law No. 909-VIII of 24.12.2015}
Article 232. Electronic administration of fuel and ethyl alcohol sales↑
{Title of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
232.1. In the system of electronic administration of the sale of fuel and ethyl alcohol, in the context of taxpayers - managers of excise warehouses/mobile excise warehouses and excise warehouses/mobile excise warehouses, for each commodity subcategory code in accordance with the UKT FEA and the conditional code, separate accounting is maintained of the volumes of fuel or ethyl alcohol that:
{Paragraph one of clause 232.1 of Article 232 as amended by Law No. 391-IX of 18.12.2019 }
are subject to excise tax, including separately at each different tax rate;
are taxed under the conditions established by Article 229 of this Code;
are not subject to taxation;
are exempt from taxation.
The volumes of fuel or ethyl alcohol imported into the customs territory of Ukraine are recorded in the electronic administration system for the sale of fuel and ethyl alcohol in the following sequence:
1) are credited automatically based on properly completed customs declarations by taxpayers and the conditions for taxation of fuel or ethyl alcohol for each commodity subcategory code in accordance with the Ukrainian Code of Foreign Economic Activities ;
2) are distributed between mobile excise warehouses used during such importation, or excise warehouses that are licensed customs warehouses where customs clearance is carried out, on the basis of excise invoices registered in the Unified Register of Excise Invoices, drawn up by the taxpayer - the manager of such mobile excise warehouses/excise warehouses.
{Paragraph eight of clause 232.1 of Article 232 as amended by Law No. 391-IX of 18.12.2019 }
The central executive body implementing state tax policy keeps records of fuel or ethyl alcohol volumes in the electronic administration system for the sale of fuel and ethyl alcohol.
{Paragraph nine of clause 232.1 of Article 232 as amended by Law No. 391-IX of 18.12.2019 }
The central executive body implementing state tax policy posts on its official website information on excise warehouses registered in the electronic administration system for the sale of fuel and ethyl alcohol with unified numbers and addresses of their location.
{Clause 232.1 of Article 232 is supplemented with a new paragraph in accordance with Law No. 391-IX of 18.12.2019 }
The unit of accounting for fuel volumes in the electronic administration system for the sale of fuel and ethyl alcohol is liters brought to a temperature of 15° C - for fuel and decaliters of 100 percent alcohol brought to a temperature of 20° C - for ethyl alcohol. In this case, liters released at fuel retail outlets for which a license for the right to retail fuel has been obtained are considered, for the purposes of this section, as liters brought to a temperature of 15° C. Such units of accounting for fuel and ethyl alcohol must be used in primary accounting documents, excise invoices/calculations of adjustments to excise invoices, and excise tax declarations.
The electronic administration system for the sale of fuel and ethyl alcohol provides automatic accounting by taxpayers - managers of excise warehouses/mobile excise warehouses for each commodity subcategory code in accordance with the UKT Foreign Economic Activity :
volumes of fuel or ethyl alcohol by excise warehouses/mobile excise warehouses, contained in issued and received excise invoices and adjustment calculations registered in the Unified Register of Excise Invoices;
volumes of fuel or ethyl alcohol produced in the customs territory of Ukraine or imported into the customs territory of Ukraine, on which excise tax has been paid, which are taxable under the conditions established by Article 229 of this Code, are not subject to taxation or are exempt from taxation in the context of excise warehouses/mobile excise warehouses;
volumes of fuel or ethyl alcohol for which taxpayers registered applications for replenishment of the remaining volumes of fuel or ethyl alcohol at the expense of funds paid to the budget, in the system of electronic administration of fuel and ethyl alcohol sales by excise warehouses/mobile excise warehouses;
amounts of excise tax paid, at the expense of which taxpayers can register applications for replenishment of the remaining volumes of fuel and ethyl alcohol;
volumes of fuel or ethyl alcohol residues by excise warehouses/mobile excise warehouses for which taxpayers have the right to register excise invoices and adjustment calculations in the Unified Register of Excise Invoices.
The electronic administration system for the sale of fuel and ethyl alcohol operates continuously (24 hours a day), except for the time required for its technical maintenance.
Maintenance of the electronic administration system for the sale of fuel and ethyl alcohol is carried out at intervals with a small number of requests from excise tax payers.
Information about the scheduled maintenance time of the electronic administration system for the sale of fuel and ethyl alcohol is posted on the official website of the central executive body implementing state tax policy no later than 24 hours before the start of maintenance.
{Paragraph 232.1 of Article 232 as amended by Law No. 391-IX of 18.12.2019 }
The procedure for electronic administration of the sale of fuel and ethyl alcohol and registration of taxpayers - managers of excise warehouses/mobile excise warehouses, excise warehouses/mobile excise warehouses in the system of electronic administration of the sale of fuel and ethyl alcohol is established by the Cabinet of Ministers of Ukraine.
{Clause 232.1 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
232.2. Excise tax payers are automatically issued with accounting cards in the electronic administration system for the sale of fuel and ethyl alcohol for each commodity subcategory code in accordance with the UKT Foreign Economic Activity .
{Clause 232.2 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
232.3. The taxpayer has the right to register excise invoices and/or adjustment calculations, as well as adjustments to applications for replenishment of the remaining volume of fuel or ethyl alcohol in the Unified Register of Excise Invoices for the volume of fuel or ethyl alcohol sold for each commodity subcategory code in accordance with the UKT FEA ( ∑ АНакл), calculated by the following formula:
{Paragraph one of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
{Paragraph two of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
where:
∑ ANaklotr - the total volume of fuel or ethyl alcohol according to the excise invoices received by the taxpayer, registered in the Unified Register of Excise Invoices, which is confirmed by the second copy of the excise invoice, registered in the Unified Register of Excise Invoices, and by the calculations of adjustments to such excise invoices, registered in the Unified Register of Excise Invoices;
{Paragraph four of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 11/23/2018 }
∑ AMytn - the total volume of fuel or ethyl alcohol imported into the customs territory of Ukraine, duly declared by customs, on which excise tax has been paid;
{Paragraph five of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
∑ RequestsReplenishment - the total volume of fuel or ethyl alcohol according to applications for replenishment of the remaining volume of fuel or ethyl alcohol, issued and registered in the electronic administration system for the sale of fuel and ethyl alcohol, with the debiting from the accounting cards of the funds of excise tax paid to the budget, equal to the amount of excise tax for the corresponding volume of fuel or ethyl alcohol;
{Paragraph six of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
∑ KorigZayavkiPopovn - the total volume of fuel or ethyl alcohol according to the adjustments to applications for replenishment of the remaining volume of fuel or ethyl alcohol, which are issued and registered in the electronic administration system for the sale of fuel and ethyl alcohol, which reduce the previously increased volume of the remaining fuel or ethyl alcohol;
{Paragraph seven of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
∑ ANaklVid - the total volume of fuel or ethyl alcohol according to excise invoices issued by the taxpayer, registered in the Unified Register of Excise Invoices, and adjustment calculations to such excise invoices, registered in the Unified Register of Excise Invoices;
{Paragraph eight of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
∑ Losses - the total volume of fuel or ethyl alcohol lost, both within and above the established loss norms, spoiled, destroyed, including cases due to an accident, fire, flood, other force majeure circumstances or for another reason related to a natural result, as well as due to evaporation in the process of production, processing, processing, storage or transportation of such fuel or ethyl alcohol, which is certified by the relevant act of loss, spoilage or destruction of fuel or ethyl alcohol, indicated in the excise invoice/adjustment calculation registered in the Unified Register of Excise Invoices;
{Paragraph nine of clause 232.3 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
∑ AMytnExport - the total volume of fuel or ethyl alcohol exported outside the customs territory of Ukraine, duly completed with customs declarations, for which excise invoices have been drawn up and registered in the Unified Register of Excise Invoices.
{Clause 232.3 of Article 232 is supplemented with a new paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
Excise invoices that provide for the shipment of fuel or ethyl alcohol under the conditions established by Article 229 of this Code may be issued within the quota limit established by the Cabinet of Ministers of Ukraine for recipients of such fuel or ethyl alcohol.
{Clause 232.3 of Article 232 supplemented by a paragraph in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2628-VIII of 23.11.2018 }
Change in the indicator ∑ ANaklVid occurs on the day of registration of the excise invoice in the Unified Register of Excise Invoices, and the change in the indicator ∑ ANaklOtr - on the day of registration of the second copy of the excise invoice (when importing fuel or ethyl alcohol into the customs territory of Ukraine - on the day of registration of the first copy of the excise invoice) in the Unified Register of Excise Invoices.
{Clause 232.3 of Article 232 is supplemented by paragraph twelfth in accordance with Law No. 2628-VIII of 23.11.2018 }
When selling fuel or ethyl alcohol from an excise warehouse to another excise warehouse using a mobile excise warehouse, if such another excise warehouse is already known before the sale of fuel or ethyl alcohol:
{Clause 232.3 of Article 232 is supplemented by the thirteenth paragraph in accordance with Law No. 2628-VIII of 23.11.2018 }
∑ ANaklVid is changed by excise warehouse;
{Clause 232.3 of Article 232 was supplemented by paragraph fourteen in accordance with Law No. 2628-VIII of 23.11.2018 }
∑ ANaklOtr is changed for such other excise warehouse;
{Clause 232.3 of Article 232 is supplemented by paragraph fifteen in accordance with Law No. 2628-VIII of 23.11.2018 }
The indicators ∑ ANaklOtr and ∑ ANaklVid for mobile excise warehouses do not change.
{Clause 232.3 of Article 232 was supplemented by paragraph sixteen in accordance with Law No. 2628-VIII of 23.11.2018 }
For the taxpayer - recipient of fuel, the change in the indicator ∑ АНаклОтр does not occur for the volumes of fuel sold:
{Clause 232.3 of Article 232 is supplemented by paragraph seventeen in accordance with Law No. 2628-VIII of 11/23/2018 ; as amended by Law No. 391-IX of 12/18/2019 }
from an excise warehouse, which is a place of retail sale of fuel for which a license for the right to retail sale of fuel has been obtained, through fuel or oil dispensers into the fuel tank of a vehicle or into the consumer's container;
{Paragraph of clause 232.3 of Article 232 as amended by Law No. 391-IX of 18.12.2019 }
from an excise warehouse that is not a place of retail sale of fuel, through fuel or oil dispensers into the fuel tank of a vehicle;
{Paragraph of clause 232.3 of Article 232 as amended by Law No. 391-IX of 18.12.2019 }
from the excise warehouse to the fuel tank of a mobile vehicle, equipment or device.
{Paragraph of clause 232.3 of Article 232 as amended by Law No. 391-IX of 18.12.2019 }
232.4. Procedure for registering applications for replenishment of the remaining volume of fuel or ethyl alcohol in the system of electronic administration of fuel and ethyl alcohol sales";
{Paragraph one of clause 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
232.4.1. Applications for replenishment of the remaining volume of fuel or ethyl alcohol in the electronic administration system for the sale of fuel and ethyl alcohol must contain the following mandatory fields (details):
{Paragraph one of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
a) application serial number;
b) date of application;
c) full or abbreviated name of a legal entity or surname, first name and patronymic of an individual registered as an excise tax payer - the person registering an application for replenishment of the remaining volume of fuel or ethyl alcohol;
{Subparagraph "c" of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
d) EDRPOU code (for legal entities) or registration number of the taxpayer's registration card (for individuals) of the taxpayer registering an application for replenishment of the remaining volume of fuel or ethyl alcohol;
{Subparagraph "d" of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
e) commodity subcategory code according to the UKT FEA ;
e) description of fuel or ethyl alcohol;
{Subparagraph "d" of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
e) the volume of fuel in liters, brought to a temperature of 15° C, or ethyl alcohol in decaliters of 100 percent alcohol, brought to a temperature of 20° C before being recorded in the System for Electronic Administration of Sales of Fuel and Ethyl Alcohol for each commodity subcategory code in accordance with the UKT Foreign Economic Activity ;
{Subparagraph "e" of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
g) the excise tax rate on the relevant fuel or ethyl alcohol, established on the date of sale of the fuel or ethyl alcohol;
{Sub-clause "e" of subparagraph 232.4.1 of clause 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
g) the exchange rate of the National Bank of Ukraine, valid on the first day of the quarter in which fuel is sold;
h) the amount of excise tax for each commodity subcategory code in accordance with the UKT Foreign Economic Activity , calculated at the excise tax rate provided for in subparagraphs 215.3.1 or 215.3.4 of paragraph 215.3 of Article 215 of this Code, and the volumes of fuel or ethyl alcohol contained in such applications (except for applications for replenishment of the remaining volume of fuel or ethyl alcohol, which is shipped under the conditions established by Article 229 of this Code, is not subject to taxation or is exempt from taxation);
{Subparagraph "c" of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2628-VIII of 11/23/2018 }
i) number and date of the application for replenishment of the remaining volume of fuel or ethyl alcohol in the case of making adjustments to applications for replenishment of the remaining volume of fuel or ethyl alcohol in the Unified Register of Excise Invoices;
{Subparagraph "i" of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
i) an indication of the conditions for taxation of fuel or ethyl alcohol;
{Subclause 232.4.1 of clause 232.4 of Article 232 is supplemented by subparagraph "i" in accordance with Law No. 2628-VIII of 23.11.2018 }
j) the unified excise warehouse number in the electronic administration system for the sale of fuel and ethyl alcohol or the registration number of the vehicle in the authorized bodies of the relevant state, which is a mobile excise warehouse, where there is a need to replenish the remaining volumes of fuel or ethyl alcohol.
{Subclause 232.4.1 of clause 232.4 of Article 232 is supplemented by subparagraph "i" in accordance with Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 391-IX of 18.12.2019 }
232.4.2. If an excise tax payer needs to replenish the remaining volumes of fuel or ethyl alcohol in the electronic administration system for the sale of fuel and ethyl alcohol, he may register an application for replenishment of the remaining volumes of fuel or ethyl alcohol provided that:
{Paragraph one of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
the presence on the accounting card of the amounts of excise tax paid, not less than the amount of excise tax calculated from the volume of fuel or ethyl alcohol in such an application, - for the volumes of fuel or ethyl alcohol subject to excise tax;
{Paragraph of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
without the presence on the accounting card of the amounts of excise tax paid - for volumes of fuel or ethyl alcohol that are taxable under the conditions established by Article 229 of this Code, or are not subject to taxation, or are exempt from taxation.
{Paragraph of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
The funds from the excise tax paid, which are recorded in the electronic administration system for the sale of fuel and ethyl alcohol, are credited to separate accounts opened for the excise tax payer in the central executive body that carries out treasury services for budget funds.
{Paragraph four of subparagraph 232.4.1 of paragraph 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
232.4.3. If, as a result of changes in the physical and chemical parameters of fuel or ethyl alcohol, the excise tax payer needs to increase the volume of fuel or ethyl alcohol under a certain commodity subcategory code according to the UKT FEA and at the same time reduce the volume of fuel or ethyl alcohol under another commodity subcategory code according to the UKT FEA, such a taxpayer may file an application for replenishment of the remaining volume of fuel or ethyl alcohol, which indicates the volumes of fuel or ethyl alcohol that are increasing and decreasing.
At the same time, if the amounts of excise tax on such fuel or ethyl alcohol are equal, then such an application is made with a zero amount of excise tax and is registered without writing off the paid excise tax from the cash register card.
If the amount of excise tax on fuel or ethyl alcohol, the volume of the remaining fuel or ethyl alcohol, the volume of the remaining fuel or ethyl alcohol, is greater than the amount of excise tax on fuel or ethyl alcohol, the volume of the remaining fuel or ethyl alcohol, the volume of the remaining fuel or ethyl alcohol, the amount
If the amount of excise tax on fuel or ethyl alcohol, the volume of the residues of which increases, is less than the amount of excise tax on fuel or ethyl alcohol, the volume of the residues of which decreases due to a change in their physical and chemical indicators, the application for replenishment of the volume of the residue of fuel or ethyl alcohol is drawn up with a zero amount of excise tax and is registered without returning the paid excise tax to the accounting card.
{Subclause 232.4.3 of Clause 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
232.4.4. In case of detection of errors in registered applications for replenishment of the volume of remaining fuel or ethyl alcohol, the taxpayer has the right, within 365 days, to register an adjustment to such an application for replenishment of the volume of remaining fuel or ethyl alcohol within the positive value of the indicator ∑ АНакл, determined in accordance with clause 232.3 of this article. In this case, such an adjustment to the application for replenishment of the volume of remaining fuel or ethyl alcohol must be reflected in the excise tax declaration for the period in which such an adjustment occurred.
{Subclause 232.4.4 of Clause 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
232.4.5. The form and procedure for filling out an application for replenishing the remaining volume of fuel or ethyl alcohol and making adjustments to applications for replenishing the remaining volume of fuel or ethyl alcohol in the electronic administration system for the sale of fuel and ethyl alcohol are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Subclause 232.4.5 of clause 232.4 of Article 232 as amended by Law No. 2628-VIII of 23.11.2018 }
{The Code is supplemented by Article 232 in accordance with Law No. 909-VIII of 24.12.2015 - the amendment regarding the introduction of excise invoices for the sale of fuel, the Unified Register of Excise Invoices and the system of electronic administration of fuel sales comes into force on March 1, 2016 - see paragraph 1 of Section II of Law No. 909-VIII of 24.12.2015}
Article 233. Comparison of indicators of turnover and fuel residues, indicators of turnover of ethyl alcohol↑
233.1. To verify the completeness of the declaration and payment of excise tax by taxpayers on the volumes of fuel or ethyl alcohol imported into the customs territory of Ukraine, produced and sold in the customs territory of Ukraine, an automatic comparison of the indicators of the volumes of circulation and fuel residues, indicators of the volumes of circulation of ethyl alcohol (hereinafter referred to as the comparison) is carried out.
233.2. The comparison is carried out by the central executive body implementing the state tax policy, in accordance with the procedure approved by the Cabinet of Ministers of Ukraine.
233.3. When comparing, indicators from the electronic administration system for the sale of fuel and ethyl alcohol are compared with indicators from the Unified State Register of Flowmeters and Level Meters for Fuel Level in the Tank regarding the volumes of circulation and fuel residues broken down by codes in accordance with the UKT Foreign Economic Activity (except for liquefied gas (propane or a mixture of propane and butane), other gases, butane, isobutane, for which the same excise tax rates are established, for which the volumes of circulation and fuel residues are summed up and compared with the general total), excise warehouses and excise warehouse managers.
When comparing, discrepancies of no more than 5 percent of the volume of circulation or fuel residues are allowed (for liquefied gas (propane or a mixture of propane and butane), other gases, butane, isobutane, for which the same excise tax rates are established, - no more than 15 percent) or no more than 2 percent of the volume of the corresponding tank.
233.4. When comparing, indicators from the electronic administration system for the sale of fuel and ethyl alcohol are compared with indicators from the Unified State Register of Flowmeters-Counters of the Volume of Produced Ethyl Alcohol in relation to the volume of ethyl alcohol turnover, including bioethanol, broken down by codes according to the UKT Foreign Economic Activity , excise warehouses and excise warehouse managers.
{Clause 233.4 of Article 233 as amended by Law No. 2284-IX of 05/31/2022 }
{Chapter VI supplemented by Article 233 in accordance with Law No. 2628-VIII of 11/23/2018 - enters into force on July 1, 2020, taking into account the amendments made by Law No. 540-IX of 03/30/2020 }
{Chapter VII "Fees for the first registration of a vehicle" excluded pursuant to Law No. 71-VIII of 28.12.2014 }
240.1. Taxpayers are business entities, legal entities that do not conduct economic (entrepreneurial) activities, budgetary institutions, public and other enterprises, institutions and organizations, permanent representative offices of non-residents, including those that perform agency (representative) functions in relation to such non-residents or their founders, during the conduct of whose activities on the territory of Ukraine and within its continental shelf and exclusive (maritime) economic zone, the following are carried out:
240.1.1. emissions of pollutants into the atmospheric air by stationary sources of pollution;
240.1.2. discharges of pollutants directly into water bodies;
240.1.3. waste disposal (except for the disposal of certain types (classes) of waste as secondary raw materials, which are placed on the own territories (facilities) of business entities);
{Subclause 240.1.3 of Clause 240.1 of Article 240 as amended by Law No. 4834-VI of 24.05.2012 }
240.1.4. generation of radioactive waste (including already accumulated waste);
240.1.5. temporary storage of radioactive waste by its producers beyond the period established by the special conditions of the license.
{Subclause 240.1.6 of clause 240.1 of Article 240 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Paragraph 240.2 of Article 240 is excluded on the basis of the Law No. 71-VIII dated 28.12.2014 }
{Clause 240.2 - 1 of Article 240 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
240.3. Entities operating in the field of nuclear energy use are not tax payers for the generation of radioactive waste (including already accumulated waste) if:
240.3.1. by the last calendar day (inclusive) of the reporting quarter in which the ionizing radiation source was purchased, an agreement was concluded on the return of the spent sealed ionizing radiation source outside Ukraine to the enterprise that produced such a source;
240.3.2. carry out management of radioactive waste resulting from the Chernobyl disaster, in terms of activities related to such waste.
240.4. State specialized enterprises for radioactive waste management, the main activity of which is the storage, processing and disposal of radioactive waste owned by the state, as well as the decontamination of radiation-contaminated facilities, are not payers of the tax levied for the generation of radioactive waste (including already accumulated waste) and/or temporary storage of radioactive waste by their producers beyond the period established by the special conditions of the license.
240.5. Business entities that place waste exclusively as secondary raw materials on their own territories (facilities) are not tax payers for waste disposal.
{Clause 240.5 of Article 240 as amended by Law No. 4834-VI of 05/24/2012 }
{Clause 240.6 of Article 240 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
240.7. Entities specified in clause 240.1 of this article that emit such emissions in an amount not exceeding 500 tons per year are not tax payers for carbon dioxide emissions.
If the annual volume of carbon dioxide emissions exceeds 500 tons per year, entities are required to register as taxpayers in the tax (reporting) period in which such excess occurred. Such taxpayers are required to prepare and submit tax reports, calculate and pay tax for the tax (reporting) period in which such excess occurred, in accordance with the procedure provided for by this Code.
{Article 240 was supplemented by paragraph 240.7 in accordance with Law No. 2628-VIII of 23.11.2018 }
{Article 241 was excluded based on the Law No. 71-VIII dated 28.12.2014 }
242.1.1. volumes and types of pollutants emitted into the atmosphere by stationary sources;
242.1.2. volumes and types of pollutants discharged directly into water bodies;
242.1.3. volumes and types (classes) of disposed waste, except for volumes and types (classes) of waste as secondary raw materials disposed on the own territories (facilities) of business entities;
{Subclause 242.1.3 of Clause 242.1 of Article 242 as amended by Law No. 4834-VI of 24.05.2012 }
{ Sub-clause 242.1.4 of clause 242.1 of Article 242 is excluded on the basis of the Law No. 71-VIII dated 28.12.2014 }
242.1.5. volumes and categories of radioactive waste generated as a result of the activities of business entities and/or temporarily stored by their producers beyond the period established by the special conditions of the license;
242.1.6. volumes of electrical energy generated by operating organizations of nuclear installations (nuclear power plants).
{Clause 242.2 of Article 242 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 242.3 of Article 242 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
242.4. The tax base for carbon dioxide emissions based on the results of the tax (reporting) year is reduced by the volume of such emissions in the amount of 500 tons per year.
{Article 242 was supplemented by paragraph 242.4 in accordance with Law No. 2628-VIII of 23.11.2018 }
Article 243. Tax rates for emissions of pollutants into the atmospheric air by stationary sources of pollution↑
243.1. Tax rates for emissions into the atmospheric air of certain pollutants by stationary sources of pollution:
Name of the pollutant
Tax rate, UAH per 1 ton
Nitrogen oxides
2574.43
Ammonia
482.84
Sulfur dioxide
2574.43
Acetone
965.67
Benzo(o)pyrene
3277278.63
Butyl acetate
579.84
Vanadium pentoxide
9656.78
Hydrogen chloride
96.99
Carbon monoxide
96.99
Hydrocarbons
145.50
Gaseous fluorine compounds
6373.91
Solids
96.99
Cadmium compounds
20376.22
Manganese and its compounds
20376.22
Nickel and its compounds
103816.62
Ozone
2574.43
Mercury and its compounds
109127.84
Lead and its compounds
109127.84
Hydrogen sulfide
8273.63
Carbon disulfide
5376.59
n-Butyl alcohol
2574.43
Styrene
18799.08
Phenol
11685.10
Formaldehyde
6373.91
Chromium and its compounds
69113.38.
{Clause 243.1 of Article 243 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , No. 1166-VII of 03/27/2014 , No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
243.2. Tax rates for emissions into the atmospheric air by stationary sources of pollution of pollutants (compounds) that are not included in clause 243.1 of this article and for which a hazard class has been established:
Hazard class
Tax rate, UAH per 1 ton
I
18413.24
II
4216.92
III
628.32
IV
145.50.
{Clause 243.2 of Article 243 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , No. 1166-VII of 03/27/2014 , No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
243.3. For pollutants (compounds) that are not included in clause 243.1 of this article and for which a hazard class has not been established (except for carbon dioxide), tax rates are applied depending on the established approximate safe levels of exposure to such substances (compounds) in the atmospheric air of populated areas:
Approximate safe exposure level of substances (compounds), milligrams per 1 cubic meter
Tax rate, UAH per 1 ton
Less than 0.0001
775097.25
0.0001 - 0.001 (inclusive)
66410.35
Over 0.001 - 0.01 (inclusive)
9173.92
Over 0.01 - 0.1 (inclusive)
2574.43
Over 0.1
96.99.
{Clause 243.3 of Article 243 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , No. 1166-VII of 03/27/2014 , No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
243.4. The tax rate for carbon dioxide emissions is 30 hryvnias per 1 ton.
{Clause 243.4 of Article 243 as amended by Laws No. 4235-VI of 22.12.2011 , No. 5503-VI of 20.11.2012 , No. 1166-VII of 27.03.2014 , No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 , No. 2245-VIII of 07.12.2017 ; as amended by the Law No. 2628-VIII dated 23.11.2018 ; as amended by Law No. 1914-IX dated 30.11.2021 }
243.5. For pollutants (compounds) for which a hazard class and an estimated safe exposure level have not been established (except for carbon dioxide), tax rates are set as for emissions of pollutants of hazard class I in accordance with paragraph 243.2 of this article.
{Article 244 was excluded based on the Law No. 71-VIII dated 28.12.2014 }
Article 245. Tax rates for discharges of pollutants into water bodies↑
245.1. Tax rates for discharges of certain pollutants into water bodies:
Name of the pollutant
Tax rate, UAH per 1 ton
Ammonium nitrogen
12883.84
Organic matter (based on biochemical oxygen demand (BOD 5))
5156.8
Suspended matter
369.52
Petroleum products
75792.4
Nitrates
1108.56
Nitrites
63278.16
Sulfates
369.52
Phosphates
10297.44
Chlorides
369.52.
{Clause 245.1 of Article 245 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , 1166-VII of 03/27/2014 , No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
245.2. Tax rates for discharges into water bodies of pollutants that are not included in clause 245.1 of this article and for which a maximum permissible concentration or an estimated safe level of exposure has been established:
Maximum permissible concentration of pollutants or approximate safe exposure level, milligrams per 1 liter
Tax rate, UAH per 1 ton
Up to 0.001 (inclusive)
1349948.0
Over 0.001 - 0.1 (inclusive)
978777.84
Over 0.1 - 1 (inclusive)
168741.52
Over 1 - 10 (inclusive)
17173.04
Over 10
3437.76.
{Clause 245.2 of Article 245 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , 1166-VII of 03/27/2014 , No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
245.3. For discharges of pollutants for which no maximum permissible concentration or estimated safe exposure level has been established, tax rates shall be applied at the lowest maximum permissible concentration specified in paragraph 245.2 of this Article.
245.4. For discharges of pollutants into ponds and lakes, the tax rates specified in paragraphs 245.1 and 245.2 of this article shall be increased by 1.5 times.
Article 246. Tax rates for waste disposal in specially designated places or facilities↑
246.1. Tax rates for the disposal of certain types of extremely hazardous waste:
246.1.1. equipment and devices containing mercury, elements with ionizing radiation - 952.02 hryvnias per unit;
246.1.2. fluorescent lamps - 16.57 hryvnia per unit.
{Clause 246.1 of Article 246 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , 1166-VII of 03/27/2014 ; as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
246.2. Tax rates for waste disposal, which are set depending on the hazard class and level of hazard of the waste:
Waste hazard class
Waste hazard level
Tax rate, UAH per 1 ton
I
extremely dangerous
1546.22
II
highly dangerous
56.32
III
moderately dangerous
14.12
IV
low-risk
5.50
low-hazard non-toxic waste from the mining industry
0.54".
{Clause 246.2 of Article 246 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , 1166-VII of 03/27/2014 , No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
246.3. For the disposal of waste for which no hazard class has been established, the tax rate established for the disposal of waste of hazard class I shall apply.
246.4. For the placement of waste in landfills that do not ensure the complete elimination of pollution of atmospheric air or water bodies, the tax rates specified in paragraphs 246.1-246.3 of this article shall be increased by 3 times.
246.5. Coefficient to tax rates, which is set depending on the location (zone) of waste placement in the surrounding natural environment:
Waste disposal site (zone)
Coefficient
Within the boundaries of a settlement or at a distance of less than 3 km from such boundaries
3
At a distance of 3 km or more from the boundaries of the settlement
1
{Article 246 - 1 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
Article 247. Tax rates for the generation of radioactive waste (including already accumulated)↑
247.1. The tax rate for the generation of radioactive waste by electricity producers - operating organizations of nuclear installations (nuclear power plants), including already accumulated waste, is 0.0133 hryvnia per 1 kWh of electricity produced.
{Clause 247.1 of Article 247 as amended by Laws No. 4235-VI of 12/22/2011 , No. 5503-VI of 11/20/2012 , 1166-VII of 03/27/2014 , No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
247.2. The correction factor established for operating organizations of nuclear installations (nuclear power plants) depending on the activity of radioactive waste:
Waste category
Coefficient
Highly active
50
Medium and low activity
2
Article 248. Tax rates for temporary storage of radioactive waste by its producers beyond the period established by the special conditions of the license↑
248.1. Tax rates for temporary storage of radioactive waste by its producers beyond the period established by the special conditions of the license:
Waste category
Tax rate for temporary storage of radioactive waste (except for waste presented as sources of ionizing radiation), hryvnias per 1 cubic meter
Tax rate for temporary storage of radioactive waste presented as sources of ionizing radiation, hryvnias per 1 cubic centimeter
Highly active
632539.66
21084.66
Medium and low activity
11807.40
4216.92.
{Clause 248.1 of Article 248 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
{Article 248 as amended by Law No. 4235-VI of 22.12.2011 ; as amended by Laws No. 5503-VI of 20.11.2012 , 1166-VII of 27.03.2014 }
249.1. Tax amounts are calculated for the tax (reporting) quarter by taxpayers.
{Clause 249.1 of Article 249 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Laws No. 422-VII of 04.07.2013 , No. 1191-VII of 08.04.2014 , No. 71-VIII of 28.12.2014 }
249.2. If, during the conduct of economic activities, a taxpayer carries out various types of environmental pollution and/or pollution with various types of pollutants, such taxpayer is obliged to determine the amount of tax separately for each type of pollution and/or for each type of pollutant.
249.3. The amounts of tax levied for emissions of pollutants into the atmosphere by stationary sources of pollution (PSP) are calculated by taxpayers independently every quarter based on the actual volumes of emissions and tax rates according to the formula:
where Mi is the actual emission volume of the i-th pollutant in tons (t);
Npi - tax rates in the current year for a ton of the i-th pollutant in hryvnias with kopecks.
{Clause 249.4 of Article 249 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
249.5. The amounts of tax levied for discharges of pollutants into water bodies (Ps) are calculated by payers independently every quarter based on the actual volumes of discharges, tax rates and correction coefficients according to the formula:
where Mli is the volume of discharge of the i-th pollutant in tons (t);
Npi - tax rates in the current year per ton of the i-th type of pollutant in hryvnias with kopecks;
Kos is a coefficient equal to 1.5 and is used in the case of discharge of pollutants into ponds and lakes (otherwise the coefficient is equal to 1).
249.6. The amounts of tax levied for waste disposal (Prv) are calculated by payers independently every quarter based on the actual volumes of waste disposal, tax rates and adjustment coefficients according to the formula:
where Npi - tax rates in the current year for a ton of the i-th type of waste in hryvnias with kopecks;
Mli - the volume of waste of the i-th type in tons (t);
Kt - correction coefficient that takes into account the location of the waste disposal site and which is given in paragraph 246.5 of Article 246 of this Code;
Ko - correction coefficient equal to 3 and applied in the case of waste placement in landfills that do not ensure complete elimination of pollution of atmospheric air or water bodies.
249.7. The amounts of tax levied for the generation of radioactive waste (including already accumulated) are calculated by taxpayers - operating organizations (operators) of nuclear power plants, including operating organizations (operators) of research reactors, independently every quarter based on the indicators of electricity production, the tax rate, as well as in proportion to the volume and activity of radioactive waste based on the actual volume of radioactive waste generated during the base tax (reporting) period, and the actual volume of radioactive waste accumulated until April 1, 2009, and the adjustment coefficient according to the formula:
AES = On x H + (rns x C1ns x V1ns + rv x C1v x V1v) + 1/32 (rns x C2ns x V2ns + rv x C2v x V2v),
where NPP - the amount of tax levied for the generation of radioactive waste (including already accumulated) by operating organizations (operators) of nuclear power plants, calculated for the base tax (reporting) period, in hryvnias with kopecks;
On - the actual volume of electrical energy generated during the base tax (reporting) period by operating organizations (operators) of nuclear power plants, kWh (for research reactors it is equal to 0);
H - the tax rate levied on electrical energy generated by operating organizations (operators) of nuclear power plants, which is reviewed if necessary once a year, is determined in paragraph 247.1 of Article 247 of this Code, in hryvnias per 1 kWh;
1/32 - tax restructuring coefficient for radioactive waste accumulated before April 1, 2009 (the coefficient is valid from April 1, 2011 to April 1, 2019, during the other period it is equal to 0);
rv - correction factor for high-level waste, specified in paragraph 247.2 of Article 247 of this Code;
rns - correction factor for intermediate and low-level waste, specified in paragraph 247.2 of Article 247 of this Code;
С1нс - cost of storage of 1 cubic meter (1 cubic centimeter of radioactive waste, presented in the form of ionizing radiation sources) of low-level and medium-level radioactive waste generated by their producers during the base tax (reporting) period, in hryvnias with kopecks;
С1в - cost of storage of 1 cubic meter (1 cubic centimeter of radioactive waste, presented in the form of ionizing radiation sources) of high-level radioactive waste generated by their producers during the base tax (reporting) period, in hryvnias with kopecks;
С2нс - cost of storage of 1 cubic meter (1 cubic centimeter of radioactive waste, presented in the form of ionizing radiation sources) of low-level and intermediate-level radioactive waste accumulated by their producers until April 1, 2009, in hryvnias with kopecks;
С2в - cost of storage of 1 cubic meter (1 cubic centimeter of radioactive waste, presented in the form of ionizing radiation sources) of high-level radioactive waste accumulated by their producers until April 1, 2009, in hryvnias with kopecks;
V1нс - actual volume of low-level and intermediate-level radioactive waste accepted into the storage of operating organizations (operators) of nuclear power plants for the base tax (reporting) period, cubic meters (cubic centimeters - for radioactive waste presented in the form of ionizing radiation sources);
V1в - actual volume of high-level radioactive waste accepted into the storage of operating organizations (operators) of nuclear power plants for the base tax (reporting) period, cubic meters (cubic centimeters - for radioactive waste presented in the form of ionizing radiation sources);
V2нс - actual volume of low-level and intermediate-level radioactive waste accumulated in storage facilities of operating organizations (operators) of nuclear power plants until April 1, 2009, cubic meters (cubic centimeters - for radioactive waste presented in the form of ionizing radiation sources);
V2v - actual volume of high-level radioactive waste accumulated in storage facilities of operating organizations (operators) of nuclear power plants until April 1, 2009, cubic meters (cubic centimeters - for radioactive waste presented in the form of ionizing radiation sources).
Other taxpayers - entities operating in the field of nuclear energy use calculate the amount of tax levied for the generation of radioactive waste by their producers, in proportion to the volume and activity of radioactive materials each quarter, which is paid in the total amount of 10 percent of the cost (excluding value added tax) of each source of ionizing radiation, which is determined from the date of acquisition (purchase and sale) of this source. The cost of handing over radioactive waste accumulated until April 1, 2009 for such entities is determined by agreements between producers of radioactive waste and specialized enterprises for handling radioactive waste.
249.8. The amounts of tax collected for temporary storage of radioactive waste by its producers beyond the period established by the special conditions of the license shall be calculated by taxpayers - producers of radioactive waste independently every quarter based on the tax rates specified in paragraph 248.1 of Article 248 of this Code, and in proportion to the period of storage of such waste beyond the established period according to the formula:
S storage = N x V x T storage,
where S storage - the amount of tax collected for temporary storage of radioactive waste by its producers beyond the period established by the special conditions of the license, calculated for the base tax (reporting) period, calendar quarter, in hryvnias with kopecks;
N - the tax rate charged for temporary storage of radioactive waste by its producers beyond the period established by the special conditions of the license, specified in paragraph 248.1 of Article 248 of this Code;
V - the actual volume of radioactive waste stored by the producer of such waste beyond the period established by the special conditions of the license, cubic meters (cubic centimeters - for radioactive waste presented in the form of ionizing radiation sources);
T storage - the number of full calendar quarters during which radioactive waste is stored beyond the period established by the special conditions of the license.
{Clause 249.9 of Article 249 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 249.10 of Article 249 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 249.11 of Article 249 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
Article 250. Procedure for submitting tax reports and paying tax↑
250.1. The basic tax (reporting) period is equal to a calendar quarter.
250.2. Taxpayers shall prepare tax returns in the form established in accordance with the procedure provided for in Article 46 of this Code, submit them within 40 calendar days following the last calendar day of the tax (reporting) quarter to the regulatory authorities and pay the tax within 10 calendar days following the last day of the deadline for submitting the tax return:
{Clause 250.2 of Article 250 as amended by Laws No. 422-VII of 04.07.2013 , No. 1191-VII of 08.04.2014 , No. 71-VIII of 28.12.2014 }
250.2.1. for emissions of pollutants into the atmosphere by stationary sources of pollution, discharges of pollutants into water bodies, placement of waste during the reporting quarter in specially designated places or facilities - at the location of stationary sources, specially designated places or facilities;
{Sub-clause 250.2.2 of clause 250.2 of Article 250 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
250.2.3. for the generation of radioactive waste and temporary storage of radioactive waste beyond the period established by the special conditions of the license - at the place of residence of the payer on tax registration with the regulatory authorities.
{Subclause 250.2.4 of clause 250.2 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.2 of Article 250 as amended by Law No. 3609-VI of 07.07.2011 }
250.3. The central executive body implementing the state policy in the field of environmental protection, the executive body of the Autonomous Republic of Crimea for environmental protection, regional, Kyiv and Sevastopol city state administrations, by December 1 of the year preceding the reporting year, shall submit to the regulatory bodies lists of enterprises, institutions, organizations, individual entrepreneurs who have been issued permits for emissions, special water use, waste treatment operations and/or an integrated environmental permit in accordance with the established procedure, and shall also send information on changes to the list no later than the 10th of the month following the quarter in which such changes occurred.
{Clause 250.3 of Article 250 as amended by Laws No. 5083-VI of 05.07.2012 , No. 4536-IX of 16.07.2025 }
250.4. The state regulatory body for nuclear and radiation safety shall, by December 1 of the year preceding the reporting year, submit to the regulatory bodies lists of enterprises, institutions, organizations, individuals - entities operating in the field of nuclear energy use, as a result of whose activities radioactive waste has been, is being or may be generated and which temporarily store such waste beyond the period established by the special conditions of the license, and shall also send information on changes to the list by the 30th day of the month following the quarter in which such changes occurred.
{Clause 250.4 of Article 250 as amended by Law No. 5083-VI of 05.07.2012 }
250.5. Taxpayers shall transfer the amounts of tax collected for emissions, discharges of pollutants and waste disposal in one payment instruction to accounts opened in bodies that provide treasury services for budget funds, which ensure the distribution of these funds in the ratio determined by law.
{Paragraph one of clause 250.5 of Article 250 as amended by Laws No. 1191-VII of 08.04.2014 , No. 2888-IX of 12.01.2023 }
{Paragraph two of clause 250.5 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Paragraph three of clause 250.5 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.5 of Article 250 as amended by Laws No. 5083-VI of 05.07.2012 , No. 422-VII of 04.07.2013 , No. 71-VIII of 28.12.2014 }
250.6. Payers of the tax levied for the generation of radioactive waste (including already accumulated) and/or temporary storage of radioactive waste by their producers beyond the period established by the special conditions of the license shall transfer the tax amounts to the state budget, which are used in accordance with the Law of Ukraine "On Radioactive Waste Management" and the Law of Ukraine on the State Budget of Ukraine for the relevant year. By decision of the taxpayer, the tax amount may be paid monthly in the amount of one third of the planned amount for the quarter with recalculation based on the results of the base tax (reporting) period.
250.7. Reporting on the actual volumes of radioactive waste generated during the base tax (reporting) period, calendar quarter (including those already accumulated before April 1, 2009), and the actual volumes of radioactive waste stored by the producer of such waste beyond the period established by the special conditions of the license, shall be agreed upon by the state sanitary and epidemiological service body and the state regulatory body for nuclear and radiation safety. Requirements for the deadlines for submission and content of the specified reporting shall be established by the special conditions of the license. Copies of the reporting shall be submitted by taxpayers together with the tax return.
{Clause 250.7 of Article 250 as amended by Law No. 5083-VI of 05.07.2012 }
250.8. If the place of filing tax returns does not coincide with the place of residence on the tax register of an enterprise, institution, organization, citizen - a business entity, which has been issued a permit for emissions of pollutants into the atmospheric air by stationary sources, special water use, waste treatment operations and/or an integrated environmental permit in accordance with the established procedure, copies of the relevant tax returns shall be submitted to the regulatory body in which such enterprise, institution, organization or citizen - a business entity is registered within 40 calendar days following the last calendar day of the tax (reporting) period.
{Clause 250.8 of Article 250 as amended by Law No. 4536-IX of 16.07.2025 }
250.9. If a taxpayer does not plan to make emissions, discharges of pollutants, dispose of waste, or generate radioactive waste during the reporting year from the beginning of the reporting year, such taxpayer must notify the relevant regulatory authority at the location of the pollution sources and file a statement stating that he does not have an object for calculating the environmental tax in the reporting year. Otherwise, the taxpayer is obliged to submit tax returns in accordance with this Article of the Code.
250.10. In the event that:
250.10.1. a taxpayer has several stationary sources of pollution or places or facilities specially designated for waste disposal within several settlements (villages, towns or cities) or outside them (the codes according to the Codifier of Administrative-Territorial Units and Territories of Territorial Communities (KATOTTG) are different), then such a taxpayer is obliged to submit to the relevant regulatory body at the location of the stationary source of pollution or places or facilities specially designated for waste disposal a tax declaration for each stationary source of pollution or place or facility specially designated for waste disposal separately;
250.10.2. a taxpayer has several stationary sources of pollution or places or facilities specifically designated for waste disposal within the boundaries of one settlement (village, town or city) or outside it (the code according to the Codifier of Administrative-Territorial Units and Territories of Territorial Communities (KATOTTG) is the same), then such a taxpayer may submit to the relevant regulatory authority one tax return for such sources of pollution;
250.10.3. a taxpayer is registered in a city with district divisions, then such a taxpayer may submit one tax return for emissions, discharges from all its sources of pollution and/or waste disposal, if these sources and/or specially designated places for waste disposal are located on the territory of such a city (the code is indicated in accordance with the Codifier of Administrative-Territorial Units and Territories of Territorial Communities (KATOTTG), at the place of residence of the taxpayer on tax registration (city council).
{ Clause 250.10 of Article 250 as amended by the Law No. 3813-IX dated 18.06.2024 }
250.11. Control over the temporary storage of radioactive waste by its producers beyond the period established by the special conditions of the license is carried out by the state regulatory body for nuclear and radiation safety and the body of the state sanitary and epidemiological service.
{Clause 250.11 of Article 250 as amended by Law No. 5083-VI of 05.07.2012 }
250.12. Controlling bodies shall, with prior approval, involve employees of the executive body of the Autonomous Republic of Crimea for environmental protection and the central executive body implementing the state policy on state supervision (control) in the field of environmental protection to verify the correctness of taxpayers' determination of the actual volumes of emissions from stationary sources of pollution, discharges and waste disposal.
{Paragraph one of clause 250.12 of Article 250 as amended by Law No. 5083-VI of 05.07.2012 }
The supervisory authorities, with prior approval, involve employees of the state sanitary and epidemiological service and the state regulatory body for nuclear and radiation safety to verify the correctness of the determination by payers of the actual volumes of radioactive waste.
{Paragraph two of clause 250.12 of Article 250 as amended by Law No. 5083-VI of 05.07.2012 }
{Clause 250.13 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.14 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.15 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.16 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.17 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.18 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
{Clause 250.19 of Article 250 was excluded on the basis of Law No. 1191-VII of 08.04.2014 }
251.1.1. rent for the use of subsoil for the extraction of minerals;
251.1.2. rent for the use of subsoil for purposes not related to the extraction of minerals;
251.1.3. rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine;
{Subclause 251.1.3 of Clause 251.1 of Article 251 as amended by Law No. 3721-IX of 21.05.2024 }
251.1.4. rental fee for special use of water;
251.1.5. rental payments for the special use of forest resources;
251.1.6. rental fees for the transportation of oil and oil products through main oil pipelines and oil product pipelines, transit transportation of ammonia through pipelines across the territory of Ukraine.
{Subclause 251.1.6 of Clause 251.1 of Article 251 as amended by Law No. 909-VIII of 24.12.2015 }
Article 252. Rent for the use of subsoil for the extraction of minerals↑
252.1. Payers of rent for the use of subsoil for the extraction of minerals in the form of marketable products of a mining enterprise - extracted minerals (mineral raw materials), the types of which are established by the conditions for mineral raw materials of the subsoil object (site) (hereinafter referred to as rent payers)
{Paragraph one of clause 252.1 of Article 252 as amended by Law No. 1914-IX of 11/30/2021 }
252.1.1. Payers of the rental fee for the use of subsoil for the extraction of minerals are business entities, including citizens of Ukraine, foreigners and stateless persons, registered in accordance with the law as entrepreneurs who have acquired the right to use a subsoil object (site) on the basis of special permits for the use of subsoil (hereinafter referred to as the special permit) within specific subsoil areas for the purpose of conducting economic activity in the extraction of minerals, including during geological exploration (or geological exploration with subsequent experimental and industrial development) within the subsoil objects (sites) specified in such special permits.
252.1.2. In the event that holders of special permits conclude contracts with third parties for the performance of works (services) related to the use of subsoil, including (but not exclusively) transactions with toll-based raw materials, the payers of the rental fee for the use of subsoil for the extraction of minerals are the holders of such special permits.
252.1.3. The payer of the rent for the use of subsoil for the extraction of minerals during the execution of agreements on joint activities without the formation of a legal entity is an authorized person - one of the participants in such an agreement, who, according to its terms, is obliged to calculate, withhold and pay taxes and fees to the budget from the single current account of joint activities (hereinafter referred to as the authorized person), provided that one of the participants in the specified agreement has the appropriate special permit. Accounting for the results of joint activities is maintained by such a participant separately from accounting for his economic activities. Such a participant is additionally registered as a payer of the rent for the use of subsoil for the extraction of minerals in accordance with the procedure specified by this Code.
252.1.4. Payers of the rent for the use of subsoil for the extraction of minerals are landowners and land users, except for business entities that, in accordance with the legislation, belong to farms that conduct economic activities for the extraction of groundwater on the basis of permits for special water use and/or an integrated environmental permit.
{Clause 252.1.4 of Clause 252.1 of Article 252 as amended by Law No. 4536-IX of 16.07.2025 }
252.1.5. Payers of the rent for the use of subsoil for the extraction of minerals are landowners and land users, except for business entities that, in accordance with the legislation, are classified as farms - citizens of Ukraine, foreigners and stateless persons who, within the boundaries of the land plots provided to them, the size of which exceeds the norms provided for in Article 121 of the Land Code of Ukraine, extract fresh groundwater using electrical devices in an amount of more than 13 cubic meters per person per month (according to meter readings).
252.1.6. Payers of the rent for the use of subsoil for the extraction of minerals are business entities that perform work that requires approval from the central executive body that implements state policy in the field of geological study and rational use of subsoil.
{Clause 252.1 of Article 252 is supplemented by subparagraph 252.1.6 in accordance with Law No. 1797-VIII of 21.12.2016 }
252.2. Payers of rent for the use of subsoil for the extraction of minerals shall, for taxation purposes, maintain separate (from other types of operating activities) accounting and tax records of expenses and income for each type of mineral raw material for each subsoil object for which a special permit has been granted.
252.3. The object of taxation of the rent for the use of subsoil for the extraction of minerals for each subsoil area provided for use, as determined in the relevant special permit, is the volume of the mining enterprise's commodity products - extracted minerals (mineral raw materials), which are the result of economic activity for the extraction of minerals in the tax (reporting) period, the types of which are established by the conditions for mineral raw materials of the subsoil object (area), which include:
{Paragraph one of clause 252.3 of Article 252 as amended by Law No. 1914-IX of 11/30/2021 }
252.3.1. the volume of commodity products of a mining enterprise - extracted minerals (mineral raw materials), which are the result of economic activity in the extraction of minerals from the subsoil on the territory of Ukraine, its continental shelf and exclusive (marine) economic zone, including the volume of mineral raw materials formed as a result of primary processing carried out by business entities other than the rent payer under the terms of economic contracts for services with toll raw materials;
252.3.2. the volume of commodity products of a mining enterprise - extracted minerals (mineral raw materials), which are the result of economic activity on the extraction of minerals from waste (losses, tailings, etc.) of mining production, including the volume of mineral raw materials formed as a result of primary processing carried out by entities other than the rent payer under the terms of economic contracts for services with toll raw materials, if a special permit is required for its extraction in accordance with the legislation.
252.3.3. volume of marketable products - extracted minerals (mineral raw materials), which are the result of economic activity in the extraction of minerals from the subsoil on the territory of Ukraine, its continental shelf and exclusive (marine) economic zone, including the volume of mineral raw materials formed during the performance of work, for the conduct of which it is necessary to obtain approval from the central executive body that implements state policy in the field of geological study and rational use of subsoil, including during the performance of work in the water areas of water bodies.
{Clause 252.3 of Article 252 is supplemented by subparagraph 252.3.3 in accordance with Law No. 1797-VIII of 21.12.2016 }
252.4. The following are not subject to taxation of rent for the use of subsoil for the extraction of minerals:
252.4.1. minerals of local importance and peat extracted by landowners or land users within their land plots to meet their own household needs are not included in the state balance of mineral reserves;
{Subclause 252.4.1 of clause 252.4 of Article 252 as amended by Law No. 466-IX of 16.01.2020 }
252.4.2. mined (collected) mineralogical, paleontological and other geological collection samples, if their use does not involve obtaining economic benefit with or without transfer of ownership of them;
252.4.3. minerals extracted from the subsoil during the creation, use, or reconstruction of geological objects of the nature reserve fund, if the use of these minerals does not involve obtaining economic benefits with or without the transfer of ownership rights to them;
252.4.4. drainage and associated-layer groundwater that are not included in the state balance of mineral reserves, extracted during the development of mineral deposits or during the construction and operation of underground structures, and the use of which does not provide for obtaining economic benefits with or without the transfer of ownership of them, including from use for own technological needs, with the exception of volumes used for own technological needs related to the extraction of minerals;
252.4.5. extracted minerals, which, without the payer acquiring and/or retaining ownership of such minerals in accordance with the technological project for the development of mineral reserves of the relevant subsoil area approved in accordance with the procedure established by law, are used to form mineral reserves of a technogenic deposit;
252.4.6. the volume of natural gas recognized as recirculating in accordance with the requirements of this Code, which is determined by the rent payer based on the indicators of measuring devices indicated in the record of extracted minerals in compliance with the schemes of movement of extracted hydrocarbon raw materials at production sites and storage locations independently approved by him in accordance with the requirements of the license conditions, taking into account the composition of the source raw materials, specific production conditions, and features of the technological process;
252.4.7. volumes of mineral waters extracted by state children's specialized sanatoriums and resorts, in part of the volumes used for treatment on their territory;
252.4.8. the volume of gas (methane) from degassing of coal deposits, which is determined by the approved conditions for the mineral raw materials of the subsoil area as not meeting or cannot be brought into line with the requirements of standardization documents regarding the quality of natural gas intended for transportation, industrial or municipal consumption;
{Clause 252.4 of Article 252 is supplemented by subparagraph 252.4.8 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
252.4.9. uranium-containing minerals extracted at the geological exploration stage on the basis of special permits obtained after January 1, 2018.
{Clause 252.4 of Article 252 is supplemented by subparagraph 252.4.9 in accordance with Law No. 2628-VIII of 23.11.2018 }
252.5. Types of commodity products of a mining enterprise - extracted minerals (mineral raw materials) are determined by the rent payer in accordance with the types of products established by the conditions for mineral raw materials of the subsoil object (site), including the conditions of goods and services, taking into account the schemes approved by the payer for the movement of commodity products of a mining enterprise - extracted minerals (mineral raw materials) at production sites and storage locations, taking into account the composition of the raw materials, specific production conditions, features of the technological process and requirements for the final product.
{Clause 252.5 of Article 252 as amended by Law No. 1914-IX of 11/30/2021 }
252.6. The tax base for the rental fee for the use of subsoil for the extraction of minerals is the cost of the volumes of minerals (mineral raw materials) extracted in the tax (reporting) period, which is calculated separately for each type of mineral (mineral raw material) for each subsoil area on the basic terms of delivery (the composition of the finished products of the mining enterprise).
252.7. The cost of the relevant type of commodity product of a mining enterprise - extracted minerals (mineral raw materials) in the tax (reporting) period is calculated by the payer for each subsoil area on the basic terms of delivery (composition of the finished product of the mining enterprise) at the greater of the following values:
252.7.1. at the actual sales prices of the relevant type of commodity products of the mining enterprise - extracted minerals (mineral raw materials);
252.7.2. at the estimated cost of the relevant type of commodity products of the mining enterprise - extracted minerals (mineral raw materials), except for hydrocarbon raw materials, as well as iron ores.
{Subclause 252.7.2 of Clause 252.7 of Article 252 as amended by Law No. 1914-IX of 30.11.2021 }
252.8. In the case of calculating the cost of the commodity products of a mining enterprise - extracted minerals (mineral raw materials) at actual sales prices, the cost of a unit of the corresponding type of commodity products of a mining enterprise - extracted minerals (mineral raw materials) is established by the rent payer based on the amount of income received (accrued) from the economic obligations fulfilled in the tax (reporting) period from the sale of the corresponding volume (quantity) of such type of commodity products of a mining enterprise - extracted minerals (mineral raw materials).
The actual selling price for oil and condensate is determined by the central executive body implementing the state policy of economic development for the tax (reporting) period as the average price of one barrel of Urals oil (excluding VAT), converted into hryvnia per ton at the rate of the National Bank of Ukraine as of the 1st day of the month following the tax (reporting) period, determined according to information from an international agency (UralsMediterranean and UralsRotterdam quotes). When determining the actual selling price for oil and condensate, the average capacity of barrels in 1 ton of Urals oil is used in the amount of 7.28.
{Paragraph two of clause 252.8 of Article 252 as amended by Law No. 4015-IX of 10.10.2024 }
{Paragraph three of clause 252.8 of Article 252 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
{Paragraph four of clause 252.8 of Article 252 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
The actual selling price for natural gas is considered to be:
{Paragraph five of clause 252.8 of Article 252 as amended by Law No. 812-VIII of 24.11.2015 }
for natural gas that meets the condition specified in clause 252.24 of this article - the price specified in the relevant contracts for the purchase and sale of natural gas between the rent payer and the natural gas market entity, on which the Cabinet of Ministers of Ukraine has imposed special obligations regarding the formation of a natural gas resource for household consumers and heat energy producers in accordance with the Law of Ukraine "On the Natural Gas Market", in the tax (reporting) period excluding VAT, in hryvnias per 1000 cubic meters. For the purposes of applying clause 252.20 of this article, the actual sales price of such natural gas is converted into US dollars at the arithmetic average official exchange rate of the National Bank of Ukraine for the tax (reporting) period;
{Paragraph six of clause 252.8 of Article 252 as amended by Law No. 812-VIII of 11/24/2015 ; as amended by Law No. 4015-IX of 10/10/2024 }
for other natural gas - the price determined as the arithmetic mean of the following values:
{Paragraph seven of paragraph 252.8 of Article 252 as amended by Laws No. 812-VIII of 11/24/2015 , No. 2139-IX of 03/15/2022 - regarding the entry into force and operation of the Law, see paragraph 1 of Section II}
the average customs value of imported natural gas, established in the process of its customs clearance during import into the territory of Ukraine for the tax (reporting) period. The average customs value of imported natural gas, established in the process of its customs clearance during import into the territory of Ukraine for the tax (reporting) period, is calculated by the central executive body implementing the state customs policy and is provided by the 5th day of the month following the tax (reporting) period to the central executive body implementing the state policy of economic development;
{Paragraph of Clause 252.8 of Article 252 as amended by Law No. 2139-IX of March 15, 2022 - regarding the entry into force and operation of the Law, see Clause 1 of Section II}
the arithmetic mean of natural gas price quotations for the reporting month (Front Month Settlement Prices) on the Dutch gas hub (TTF), according to information from the EEX (The European Energy Exchange), formed for the calendar month preceding the tax (reporting) period, which is calculated by the central executive body implementing the state policy of economic development, per 1000 cubic meters in US dollars and in the national currency of Ukraine (excluding VAT) at the arithmetic mean official exchange rate of the National Bank of Ukraine for the tax (reporting) period.
{Paragraph of Clause 252.8 of Article 252 as amended by Law No. 2139-IX of March 15, 2022 - regarding the entry into force and operation of the Law, see Clause 1 of Section II}
The central executive body implementing the state policy of economic development shall, by the 10th day of the month following the tax (reporting) period, post on its official website in a special section the actual sales price of natural gas, determined per 1,000 cubic meters in the national currency of Ukraine and in US dollars, and provides information about such actual price to the central executive body that implements state tax policy.
{Paragraph of Clause 252.8 of Article 252 as amended by Law No. 2139-IX of March 15, 2022 - regarding the entry into force and operation of the Law, see Clause 1 of Section II}
When carrying out controlled operations in cases specified in Article 39 of this Code, the actual selling price of the relevant type of commodity product of a mining enterprise - extracted minerals (mineral raw materials) cannot be less than the price determined according to the "arm's length" principle.
{Clause 252.8 of Article 252 is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
The central executive body implementing the state economic development policy shall, by the 10th day of the month following the tax (reporting) period, place the determined sales price of the corresponding type of commodity product of the mining enterprise - extracted minerals (mineral raw materials) on its official website in a special section and notify the central executive body implementing the state tax policy.
{Paragraph of Clause 252.8 of Article 252 as amended by Law No. 1797-VIII of 21.12.2016 }
The amount of income received (accrued) from the sale of the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials) for the tax (reporting) period is reduced by the amount of the payer's expenses related to pre-sale preparation operations, including packaging, packaging (bottling), as well as delivery (transportation, transportation) of the volume (quantity) of the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials) to the consumer in the amounts established in the purchase and sale agreement in accordance with the terms of supply.
{Paragraph of Clause 252.8 of Article 252 as amended by Law No. 1797-VIII of 21.12.2016 }
The amounts of advance payment for the cost of the volume (quantity) of the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials), received before the actual fulfillment of economic obligations (actual delivery) or before the deadline for the fulfillment of economic obligations (delivery) under the relevant contract, are included in the amount of income for calculating the cost of a unit of the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials) in the tax (reporting) period, if such economic obligations (deliveries) have been fulfilled or should have been fulfilled under the specified contract.
The amount of income received from the sale of the volume (quantity) of the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials) in foreign currency is calculated in the national currency at the official exchange rate of the hryvnia to foreign currencies established by the National Bank of Ukraine on the date of sale of such minerals.
The actual sales price for iron ore is determined by the central executive body implementing the state policy of economic development for the tax (reporting) period as the average cost of iron ore according to the IODEX 62% FE CFR China index (excluding VAT), converted into hryvnia per ton at the exchange rate of the National Bank of Ukraine as of the 1st of the month following the tax (reporting) period, according to information officially indicated by the global information agency Platts.
{Clause 252.8 of Article 252 supplemented by a paragraph in accordance with Law No. 1914-IX of 11/30/2021 ; as amended by Law No. 4015-IX of 10/10/2024 }
The central executive body implementing the state economic development policy shall, by the 10th day of the month following the tax (reporting) period, post the determined actual sale price of iron ore on its official website in a special section and notify the central executive body implementing the state tax policy.
{Clause 252.8 of Article 252 is supplemented by a paragraph in accordance with Law No. 1914-IX of 11/30/2021 }
{Paragraph eighteen of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph nineteen of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty-one of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty-two of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty-three of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty-four of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty-five of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty-six of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
{Paragraph twenty-seven of clause 252.8 of Article 252 was excluded on the basis of Law No. 4113-IX of 04.12.2024 }
The actual sales price of extracted minerals (mineral raw materials) of commodity products of a mining enterprise from rocks, classified by code according to the UKT FEA 2517 , is determined by the weighted average (by sales volume) in the reporting period of the sales price of the corresponding type of commodity products of a mining enterprise - extracted minerals (mineral raw materials) under supply contracts, but not less than 6.5 US dollars per 1 ton.
{Clause 252.8 of Article 252 is supplemented by a paragraph in accordance with Law No. 4113-IX of 04.12.2024 }
The actual sales price of extracted minerals (mineral raw materials) of commodity products of a mining enterprise from rocks, classified by code according to the UKT FEA 2505 , is determined by the weighted average (by sales volume) in the reporting period of the sales price of the corresponding type of commodity products of a mining enterprise - extracted minerals (mineral raw materials) under supply contracts, but not less than 5 US dollars per 1 ton.
{Clause 252.8 of Article 252 is supplemented by a paragraph in accordance with Law No. 4113-IX of 04.12.2024 }
The actual sales price of extracted minerals (mineral raw materials) of commodity products of a mining enterprise from rocks, classified by code according to the UKT FEA 2507 00 , is determined by the weighted average (by sales volume) in the reporting period of the sales price of the corresponding type of commodity products of a mining enterprise under supply contracts, but not less than:
{Clause 252.8 of Article 252 is supplemented by a paragraph in accordance with Law No. 4113-IX of 04.12.2024 }
120 US dollars per 1 ton of commodity products of a mining enterprise extracted within the subsoil facility (site) from mineral raw materials, which, in accordance with the approved conditions for mineral raw materials of the subsoil facility (site), is recognized as suitable for primary processing (enrichment) by its properties;
{Clause 252.8 of Article 252 is supplemented by a paragraph in accordance with Law No. 4113-IX of 04.12.2024 }
40 US dollars per 1 ton of commodity products of a mining enterprise extracted within the subsoil facility (site) from mineral raw materials, which, in accordance with the approved conditions for mineral raw materials of the subsoil facility (site), is recognized as unsuitable for primary processing (enrichment) by its properties.
{Clause 252.8 of Article 252 is supplemented by a paragraph in accordance with Law No. 4113-IX of 04.12.2024 }
The actual price per ton of commodity products of a mining enterprise, classified by codes according to the UKT FEA 2505 , 2507 00, 2517, is calculated in hryvnias at the exchange rate of the National Bank of Ukraine as of the first day of the month following the tax (reporting) period.
{Clause 252.8 of Article 252 is supplemented by a paragraph in accordance with Law No. 4113-IX of 04.12.2024 }
252.9. The expenses of the rent payer related to pre-sale preparation operations, including packaging, packing (bottling), as well as delivery (transportation, transportation) of the commodity products of the mining enterprise - extracted minerals (mineral raw materials) to the consumer, include:
{Paragraph one of clause 252.9 of Article 252 as amended by Law No. 1797-VIII of 21.12.2016 }
252.9.1. expenses related to pre-sale preparation operations, including packaging, packaging (bottling), as well as delivery (transportation, transportation) of the commodity products of the mining enterprise - extracted minerals (mineral raw materials) from the warehouse of the finished products of the rent payer (metering point, entrance to the main pipeline, point of shipment to the consumer or for processing, the boundary of the networks with the consumer) to the consumer, namely:
{Paragraph one of subparagraph 252.9.1 of paragraph 252.9 of Article 252 as amended by Law No. 1797-VIII of 21.12.2016 }
with delivery (transportation, transportation) by main pipelines, railway, water and other modes of transport;
with draining, pouring, loading, unloading and reloading;
with payment for port services, in particular port dues;
with payment for freight forwarding services;
252.9.2. costs of compulsory cargo insurance, calculated in accordance with the legislation;
252.9.3. customs payments in the event of sale outside the customs territory of Ukraine.
252.10. The unit cost of each type of commodity product of a mining enterprise - extracted minerals (mineral raw materials) is calculated as the ratio of the amount of income received by the rent payer from the sale of the corresponding type of commodity product of a mining enterprise - extracted minerals (mineral raw materials), determined in accordance with paragraph 252.8 of this Article, and the volume (quantity) of the corresponding type of commodity product sold by a mining enterprise - extracted minerals (mineral raw materials), which is determined according to the accounting data of the finished product inventories of such payer.
252.11. In the case of calculating the cost of the relevant type of commodity product of a mining enterprise - extracted minerals (mineral raw materials) at the estimated cost, the expenses of the rent payer for the tax (reporting) period include:
252.11.1. material costs, including costs associated with the implementation of business contracts with toll-based raw materials, with the exception of material costs associated with:
storage;
transportation;
packaging, including bottling;
{Paragraph four of subparagraph 252.11.1 of paragraph 252.11 of Article 252 as amended by Law No. 1797-VIII of 21.12.2016 }
carrying out another type of preparation (including pre-sale preparation), except for operations classified as primary processing (enrichment) operations within the meaning given in Section I of this Code, for the sale of the corresponding type of commodity products of a mining enterprise - extracted minerals (mineral raw materials);
production and sale of other types of products, goods (works, services);
252.11.2. labor costs, except for the costs of labor costs of employees who are not engaged in economic activities for the extraction of the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials);
252.11.3. expenses for the repair of fixed assets, except for expenses for the repair of fixed assets not technically and technologically related to the economic activity of extracting the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials);
252.11.4. other expenses included in the expenses, including expenses distributed in accordance with the accounting policy principles of the rent payer, incurred by him during periods when economic activity in the extraction of minerals was not carried out due to seasonal conditions for mining operations, except for expenses not related to economic activity in the extraction of the relevant type of commodity product of the mining enterprise - extracted minerals (mineral raw materials), including:
which arise as a result of the formation of financial reserves;
for the payment of interest on the rent payer's debt obligations;
for the payment of rent for the use of subsoil for the extraction of minerals;
for the payment of fines and/or penalties or penalties by decision of the parties to the contract or by decision of the relevant state bodies or court.
252.12. When calculating the estimated cost of the relevant type of commodity product of a mining enterprise - extracted minerals (mineral raw materials), the following are also taken into account:
252.12.1. the amount of accrued depreciation, except for the amount of accrued depreciation on fixed assets and intangible assets subject to depreciation, but not technically and technologically related to the economic activity of extracting the relevant type of commodity product of a mining enterprise - extracted minerals (mineral raw materials);
252.12.2. the amount of depreciation of expenses related to economic activities related to the extraction of the relevant type of commodity products of a mining enterprise - extracted minerals (mineral raw materials).
252.13. In the event that there are state subventions for mining enterprises, the value of the extracted mineral raw materials (minerals) is determined without taking into account the subvention, the amount of which for each subsoil plot is calculated based on the calculation of the cost of the extracted mineral according to the accounting materials of the conduct of economic activities within such subsoil plot.
252.14. The amount of expenses incurred for conducting economic activities for the extraction of minerals, for which a set of technological operations (processes) for extraction was completed in the tax (reporting) period, is fully included in the estimated cost of extracted minerals for the relevant tax (reporting) period.
If, after the occurrence of tax obligations on the rent for the use of subsoil for the extraction of minerals for the volume (quantity) of the relevant type of commodity product of the mining enterprise - extracted mineral (mineral raw material), the rent payer in any subsequent tax (reporting) period made a decision to apply to it (the relevant type of commodity product of the mining enterprise - extracted mineral (mineral raw material) or its part) other primary processing operations, as a result of which a new type of commodity product of the mining enterprise arose, which differs from the product for which the relevant obligations on the rent for the use of subsoil for the extraction of minerals were recognized and fulfilled by the rent payer, the rent payer in such tax (reporting) period determines the amount of tax obligations on the rent for the new relevant type of commodity product of the mining enterprise - extracted mineral. (mineral raw materials) taking into account the fulfilled tax obligations for the volume (quantity) of the corresponding type of commodity products of the mining enterprise - the extracted mineral (mineral raw materials) that was used to create new commodity products of the mining enterprise, minus the amounts of tax obligations that arose from previous transactions with this type of mineral.
252.15. The amount of expenses incurred for conducting economic activities for the extraction of minerals, for which the set of technological operations (processes) for extraction has not been completed in the tax (reporting) period, shall be included in the estimated cost of the corresponding type of commodity product of the mining enterprise - extracted minerals (mineral raw materials) in the tax (reporting) period in which such a set of technological operations (processes) is completed.
252.16. The estimated cost of a unit of the relevant type of commodity product of a mining enterprise - extracted minerals (mineral raw materials) (Cr) is calculated using the following formula:
where Vmp - costs calculated in accordance with paragraphs 252.11 - 252.15 of this article (in hryvnias);
Krmpe - profitability coefficient of a mining enterprise in the amount of 0.20, except for cases when a higher value of such coefficient is approved in the technical and economic calculations of the materials of the geological and economic assessment of mineral reserves of a subsoil area, approved by the central executive body that implements state policy in the field of geological study and rational use of subsoil (decimal fraction) when establishing conditions for mineral raw materials of a subsoil object (site);
{Paragraph four of clause 252.16 of Article 252 as amended by Law No. 1914-IX of 11/30/2021 }
Vmp - the volume (quantity) of the commodity products of a mining enterprise - extracted minerals (mineral raw materials) extracted during the tax (reporting) period.
252.17. The cost of uranium and gold ores extracted from primary deposits is calculated taking into account the sales price for the tax (reporting) period (in the absence of sales in this period - for the nearest previous tax periods) of chemically pure metal, excluding value added tax, reduced by the amount of the rent payer's expenses for enrichment (refining) and delivery (transportation, transportation) to the consumer. The cost of a unit of commodity products of a mining enterprise - extracted minerals (mineral raw materials) is determined taking into account the share (in natural terms) of the content of chemically pure metal in a unit of extracted minerals.
252.18. Tax liabilities on rent for the use of subsoil for the relevant type of commodity product of a mining enterprise - extracted minerals (mineral raw materials) within one subsoil plot for the tax (reporting) period are calculated using the following formula:
Pzn = Vf x Vkk x Svnz x Kpp,
where Vf is the volume (quantity) of the corresponding type of commodity products of the mining enterprise - extracted minerals (mineral raw materials) in the tax (reporting) period (in units of mass or volume);
Vkk - the cost of a unit of the corresponding type of commodity product of a mining enterprise - extracted minerals (mineral raw materials), calculated in accordance with paragraphs 252.7 - 252.17 of this article;
Svnz - the value of the rental rate for the use of subsoil for the extraction of minerals (in percent), established in paragraph 252.20 of this article;
Kpp - a correction coefficient, the value of which corresponds to that established in paragraph 252.22 of this article or the value of the product of several coefficients established in paragraph 252.22 of this article, if there are grounds for their simultaneous application according to the relevant criteria.
{Paragraph six of clause 252.18 of Article 252 as amended by Law No. 1914-IX of 11/30/2021 }
252.19. The volume (quantity) of the corresponding type of commodity products of a mining enterprise - extracted minerals (mineral raw materials), in accordance with the types of products established by the approved conditions for mineral raw materials of the subsoil object (site), is determined by the rent payer independently in the journal of accounting for extracted minerals in accordance with the requirements of the schemes of movement of extracted minerals (mineral raw materials) at production sites and storage locations approved by him, taking into account the composition of the starting materials, the conditions of specific production, the features of the technological process and the requirements for the final product and regulatory acts regulating the requirements for determining the quality of raw materials and the final product, determining the content of the main and associated minerals in laboratories certified in accordance with the rules of authorization and certification in the state metrological system.
{Paragraph one of clause 252.19 of Article 252 as amended by Law No. 1914-IX of 11/30/2021 }
Depending on the type of extracted mineral (raw material), its quantity is determined in units of mass or volume.
252.20. The rates of rent for the use of subsoil for the extraction of minerals for extracted minerals (mineral raw materials), the types of commodity products of the mining enterprise of which are approved by the conditions for mineral raw materials of the subsoil object (site), are established as a percentage of the cost of commodity products of the mining enterprise in the following amounts:
{Paragraph one of clause 252.20 of Article 252 as amended by Law No. 1914-IX of 11/30/2021 }
The name of the groups of minerals provided for the use of subsoil to a mining enterprise for the extraction of minerals in the form of a commodity product of the mining enterprise - extracted minerals (mineral raw materials)
Rate, percentage of the value of the commodity products of a mining enterprise - extracted minerals (mineral raw materials)
Ore (metal-bearing (metallic), including ores) minerals:
ferrous metals (except iron ores), non-ferrous and alloy metals
6.25
iron ore
3.50, if the average cost of iron ore according to the IODEX 62% FE CFR China index, officially determined by the global information agency Platts, for the tax (reporting) period is 100 US dollars or less; 5.00, if the average cost of iron ore according to the IODEX 62% FE CFR China index, officially determined by the global information agency Platts, for the tax (reporting) period is more than 100 and does not exceed 200 US dollars inclusive;
10.00, if the average cost of iron ore according to the IODEX 62% FE CFR China index, officially determined by the global information agency Platts, for the tax (reporting) period is more than 200 US dollars;
uranium-containing (in technological solution)
5.00
other than uranium-containing, ferrous, non-ferrous and alloy metals
5.00
energy minerals:
coal:
coking coal
1.50
energy
0.75
anthracite
1.00
brown
1.00
peat
1.00
hydrocarbons:
oil:
from deposits that lie completely or partially at a depth of up to 5,000 meters
31.00
from deposits that lie entirely at a depth of more than 5,000 meters
16.00
condensate:
from deposits that lie completely or partially at a depth of up to 5,000 meters
31.00
from deposits that lie entirely at a depth of more than 5,000 meters
16.00
natural gas (of any origin):
from deposits that lie completely or partially at a depth of up to 5,000 meters
if the actual selling price of natural gas for the tax (reporting) period is 400 USD or less per 1000 cubic meters: 29.00 of the actual selling price of natural gas for the tax (reporting) period;
if the actual selling price of natural gas for the tax (reporting) period exceeds 400 US dollars per 1000 cubic meters: 29.00 from the part of the actual cost of natural gas for the tax (reporting) period in the amount of 400 US dollars per 1000 cubic meters and 65.00 from the part of the actual selling price of natural gas for the tax (reporting) period exceeding 400 US dollars per 1000 cubic meters;
from deposits that lie wholly or partly at a depth of more than 5,000 meters
if the actual selling price of natural gas for the tax (reporting) period is 400 USD or less per 1000 cubic meters: 14.00 of the actual selling price of natural gas for the tax (reporting) period;
if the actual selling price of natural gas for the tax (reporting) period exceeds 400 US dollars per 1000 cubic meters: 14.00 from the part of the actual cost of natural gas for the tax (reporting) period in the amount of 400 US dollars per 1000 cubic meters and 31.00 from the part of the actual selling price of natural gas for the tax (reporting) period exceeding 400 US dollars per 1000 cubic meters;
natural gas extracted from new wells from deposits that lie wholly or partially at a depth of up to 5,000 meters
if the actual selling price of natural gas for the tax (reporting) period is 400 USD or less per 1000 cubic meters: 12.00 of the actual selling price of natural gas for the tax (reporting) period;
if the actual selling price of natural gas for the tax (reporting) period exceeds 400 US dollars per 1000 cubic meters: 12.00 of the part of the actual cost of natural gas for the tax (reporting) period in the amount of 400 US dollars per 1000 cubic meters and 36.00 of the part of the actual selling price of natural gas for the tax (reporting) period exceeding 400 US dollars per 1000 cubic meters;
natural gas produced from new wells from deposits that lie wholly or partially at a depth of more than 5,000 meters
if the actual selling price of natural gas for the tax (reporting) period is 400 USD or less per 1000 cubic meters: 6.00 of the actual selling price of natural gas for the tax (reporting) period;
if the actual selling price of natural gas for the tax (reporting) period exceeds 400 US dollars per 1000 cubic meters: 6.00 of the part of the actual cost of natural gas for the tax (reporting) period in the amount of 400 US dollars per 1000 cubic meters and 18.00 of the part of the actual selling price of natural gas for the tax (reporting) period exceeding 400 US dollars per 1000 cubic meters;
from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine, regardless of the depth of the deposits and the date of commencement of well drilling
11.00
natural gas produced during the execution of joint activity agreements, regardless of the depth of the deposits and the date of commencement of well drilling
{Note - 1) to clause 252.20 Article 252 was excluded on the basis of Law No. 211-VIII of 02.03.2015 }
- 1) From January 1, 2019 to December 31, 2019 (inclusive), a coefficient of 1.1 is applied to the rent rate for the use of subsoil for the extraction of iron ore.
{A note has been added to paragraph 252.20 of Article 252 - 1) in accordance with Law No. 2628-VIII of 23.11.2018 }
- 2) The rent for the use of subsoil for the extraction of fresh groundwater, which is extracted by the payers specified in subparagraph 252.1.5 of paragraph 252.1 of this Article, is applied at the rates specified in subparagraph 255.5.2 of paragraph 255.5 of Article 255 of this Code.
- 3) Under the terms of the production sharing agreement for oil and condensate extracted within the territory of Ukraine, the continental shelf, and the exclusive (maritime) economic zone of Ukraine, the rent for the use of subsoil for the extraction of minerals is calculated at a rate of 2 percent of the value of the mining enterprise's marketable products, and for natural gas, including gas dissolved in oil (oil (associated) gas), ethane, propane, butane, coal gas (methane), shale gas, central-basin type gas, gas from tight rock reservoirs, extracted within the territory of Ukraine, the continental shelf, and the exclusive (maritime) economic zone of Ukraine, the rent for the use of subsoil for the extraction of minerals is calculated at a rate of 1.25 percent of the value of the mining enterprise's marketable products.
{Clause 252.20 of Article 252 supplemented by Note 3 in accordance with Law No. 2245-VIII of 07.12.2017 }
{Note 4 to paragraph 252.20 of Article 252 was excluded on the basis of Law No. 1914-IX of 11/30/2021 }
{Clause 252.20 of Article 252 as amended by Laws No. 211-VIII of 02.03.2015 , No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 , No. 2245-VIII of 07.12.2017 , No. 2628-VIII of 23.11.2018 , No. 466-IX of 16.01.2020 , No. 490-IX of 04.02.2020 , No. 1914-IX of 30.11.2021 , No. 2139-IX of 15.03.2022 - regarding the entry into force and operation of the Law, see clause 1 of section II, No. 4015-IX dated 10.10.2024 }
252.21. Additional volumes of hydrocarbon raw materials extracted as a result of the implementation of existing or new investment projects (programs, agreements) that provide for the increase in the production of hydrocarbon raw materials, in subsoil areas (fields, deposits) characterized by deteriorated mining and geological conditions (difficult to extract) or depletion during development in previous periods, in individual operating wells after major repairs, wells restored from among the liquidated, new wells or groups of wells located in such subsoil areas, are taxed at a rate of 2 percent of the cost of additional production of the relevant hydrocarbon raw materials.
The procedure for selecting and approving new investment projects (programs, agreements) that provide for the increase in hydrocarbon production, the procedure for determining additional volumes of hydrocarbon raw materials, as well as the procedure for monitoring the implementation of such investment projects (programs) are determined by the Cabinet of Ministers of Ukraine upon submission by the central executive body that ensures the formation and implementation of the state policy of economic development.
The list of subsoil areas and/or subsoil area objects on which new investment projects (programs, contracts) are implemented is determined by the central executive body that ensures the formation and implementation of state policy in the oil and gas complex.
The provisions of this paragraph apply to:
enterprises, the share of the state in the authorized capital of which is 25 percent or more;
business companies, 25 percent or more of whose shares (shares, units) are in the authorized capitals of other business companies, the controlling stake of which is owned by the state;
subsidiaries, representative offices and branches of such enterprises and companies;
participants in joint activity agreements, according to which the value of the contribution of enterprises, the share of the state in the authorized capital of which is 25 percent or more, business companies, 25 percent or more of the shares (shares, units) of which are in the authorized capital of other business companies, the controlling stake of which is owned by the state, as well as subsidiaries, representative offices and branches of such enterprises and companies, is 25 percent or more of the total value of the contributions of the participants in joint activity agreements.
252.22. The rates of rent for the use of subsoil for the extraction of minerals shall be subject to correction coefficients determined depending on the type of mineral (mineral raw material) and the conditions of its extraction:
Criteria for applying the coefficient
Coefficient value
Extraction of mineral reserves (resources) from man-made deposits
0.50
Extraction of sand and gravel raw materials within the water area of seas, reservoirs, in rivers and their floodplains (except for extraction related to planned works on cleaning river fairways)
2.00
Extraction of carbonated mineral groundwater (hydrocarbonate) from wells not equipped with stationary gas separators
0.85
Extraction of reserves from deposits that are recognized as subsidized reserves in accordance with the procedure established by law
0.01
Extraction of mineral reserves of a subsoil area in compliance with the conditions of mineral raw materials of the subsoil area, approved by the state examination on the basis of geological study reports, which are carried out by the rent payer at his own expense no earlier than 5 years before the reporting tax period, except for hydrocarbon raw materials
0.95
Extraction of off-balance sheet natural gas reserves that meets the condition specified in paragraph 252.24 of this article*
0.79
Extraction of off-balance reserves of natural gas from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine, which meets the condition specified in paragraph 252.24 of this article*
0.61
Extraction of off-balance sheet natural gas reserves that does not meet the condition specified in paragraph 252.24 of this article*
0.96
Extraction of natural gas reserves that meet the condition specified in paragraph 252.24 of this article, subsoil areas approved by the state expert examination on the basis of geological study reports, which are carried out by the rent payer at the expense of his own funds
0.88
Extraction of natural gas reserves from deposits in subsoil areas (fields) within the continental shelf and/or exclusive (maritime) economic zone of Ukraine, which meets the condition specified in paragraph 252.24 of this article, subsoil areas approved by the state expertise on the basis of geological study reports, which are carried out by the rent payer at the expense of his own funds
0.77
Extraction of natural gas reserves that does not meet the condition specified in paragraph 252.24 of this article, subsoil areas approved by the state examination on the basis of geological study reports, which were carried out by the rent payer at his own expense
0.97
Extraction by underground mining from a depth of more than 300 meters of iron ore for enrichment with a magnetite iron content of less than 35 percent
0.25
Iron ore mining
0.90
* Provided that mineral reserves are classified as such based on the results of a geological and economic assessment conducted no earlier than 10 years before the tax liabilities arise.
{Clause 252.22 of Article 252 as amended by Laws No. 211-VIII of 02.03.2015 , No. 909-VIII of 24.12.2015 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 ; as amended by Law No. 1914-IX of 30.11.2021 }
252.23. Tax returns on rent for the use of subsoil for the extraction of minerals shall be filed by the payer starting from the calendar quarter following the quarter in which such payer received or renewed a special permit.
{Paragraph one of clause 252.23 of Article 252 as amended by Law No. 1797-VIII of 21.12.2016 }
Tax returns on rent during the execution of agreements on joint activities without the formation of a legal entity shall be submitted by the authorized person determined in accordance with paragraph 252.1 of this article starting from the calendar quarter following the quarter in which such an agreement is registered with the regulatory authorities.
252.24. The rent payer or an authorized person who, in the tax (reporting) period, extracted natural gas (including petroleum (associated) gas) and sold it to a natural gas market entity, which the Cabinet of Ministers of Ukraine, on the basis of the Law of Ukraine "On the Natural Gas Market", has assigned special responsibilities to form a natural gas resource for household consumers and thermal energy producers, shall determine tax liabilities in the tax return, taking into account the volumes specified in the acceptance and transfer acts and the volumes of production and technological costs of natural gas for technical operations on extraction and preparation for transportation. Acceptance and transfer certificates are drawn up in the tax (reporting) period in which such gas was produced, and no later than the 8th day of the month following the tax (reporting) period, they are signed by the rent payer or an authorized person and the above-mentioned natural gas market entity on the basis of the natural gas purchase and sale contracts concluded by them.
The volumes of production and technological costs of natural gas for the implementation of technical operations for extraction and preparation for transportation (including oil (associated) gas), specified in the first paragraph of this paragraph, are determined in proportion to the specific weight of the volumes of such natural gas sold to the specified natural gas market entity in the total volume of natural gas (including oil (associated) gas) subject to taxation, reduced by the volume of production and technological costs of such natural gas, which cannot exceed the regulatory volumes of production and technological costs.
{Paragraph two of clause 252.24 of Article 252 as amended by Law No. 466-IX of 16.01.2020 }
The list and procedure for determining the size of the standard production and technological costs of natural gas for technical operations on extraction and preparation for transportation are established by the central executive body that ensures the formation and implementation of state policy in the oil and gas and oil and gas processing complexes.
{Paragraph 252.24 of Article 252 supplemented by the third paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Clause 252.24 of Article 252 as amended by Law No. 812-VIII of 11/24/2015 }
252.25. The rent payer and the authorized person shall pay tax liabilities:
252.25.1. by the location of the subsoil area from which the minerals were extracted, if such subsoil area is located within the territory of Ukraine;
252.25.2. at the place of registration of the rent payer in the event that the subsoil area from which minerals were extracted is located within the continental shelf and/or exclusive (maritime) economic zone of Ukraine.
252.26. Submission of the declaration, payment deadlines, liability of payers and control over the collection of rent payments are determined by Articles 257 and 258 of this Code.
Article 253. Rent for the use of subsoil for purposes not related to the extraction of minerals↑
253.1. Payers of rent for the use of subsoil for purposes not related to the extraction of minerals are legal entities and individuals - business entities that use subsoil plots within the territory of Ukraine for:
253.1.1. storage of natural gas, oil, gaseous and other liquid petroleum products;
253.1.2. aging of wine materials, production and storage of wine products;
253.1.3. growing mushrooms, vegetables, flowers and other plants;
253.1.4. storage of food products, industrial and other goods, substances and materials;
253.1.5. conducting other types of economic activities.
253.2. Military units, institutions, establishments and organizations of the Armed Forces of Ukraine and other military formations established in accordance with the law and financed from the state budget are not payers of rent for the use of subsoil for purposes not related to the extraction of minerals.
253.3. The object of taxation of rent for the use of subsoil for purposes not related to the extraction of minerals is the volume of underground space (area) of subsoil:
253.3.1. for the storage of natural gas and gaseous products - the active volume of gas storage in porous or fractured geological formations (reservoirs);
253.3.2. for the storage of oil and other liquid petroleum products - the volume of specially created and existing mining operations (worked out and adapted), as well as natural cavities (caves);
253.3.3. for aging wine materials, production and storage of wine products, growing mushrooms, vegetables, flowers and other plants, storage of food products, industrial and other goods, substances and materials, conducting other types of economic activities - the area of underground space provided for use in specially created and existing mining operations (worked out and adapted), as well as natural cavities (caves).
253.4. Rent for the use of subsoil for purposes not related to the extraction of minerals is not collected:
253.4.1. for the use of transport tunnels and other underground communications, collector and drainage systems and municipal utilities;
253.4.2. for the use of underground structures at a depth of no more than 20 meters, constructed in an open way without backfilling or with subsequent backfilling with soil.
253.5. The rates of rent for the use of subsoil for purposes not related to the extraction of minerals are set depending on the useful properties of the subsoil and the degree of environmental safety during their use in the following amounts:
Nature of subsoil use
Type of subsoil use
Unit of measurement
Rent rate for the use of subsoil for purposes not related to mineral extraction, per unit of subsoil use, hryvnias per year
Use of underground space - porous or fractured geological formations (reservoir layers)
storage of natural gas and gaseous products
thousand cubic meters of active volume
0.56
Use of underground space - specially created and existing mining operations (worked out and adapted), as well as natural cavities (caves)
storage of oil and other liquid petroleum products
cubic meters
0.56
aging of wine materials, production and storage of wine products
sq. meters
1.59
growing mushrooms, vegetables, flowers and other plants
-"-
0.90
storage of food products, industrial and other goods, substances and materials
-"-
0.69
conducting other economic activities
-"-
2.23.
{Clause 253.5 of Article 253 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 1914-IX of 11/30/2021 }
253.6. Submission of the declaration, payment deadlines, liability of payers and control over the collection of rent payments are determined by Articles 257 and 258 of this Code.
Article 254. Rent for the use of the radio frequency spectrum (radio frequency resource) of Ukraine↑
{Title of Article 254 as amended by Law No. 3721-IX of 05/21/2024 }
254.1. Payers of the rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine are general users of the radio frequency spectrum of Ukraine, defined by the legislation on electronic communications and the radio frequency spectrum, who are granted the right to use the radio frequency spectrum of Ukraine within the allocated part of the radio frequency bands for general use on the basis of:
254.1.1. licenses for the use of the radio frequency spectrum (radio frequency resource) of Ukraine;
254.1.2. broadcasting licenses with assignment of radio frequencies to general users in radio frequency bands allocated for broadcasting needs;
254.1.3. licenses for the provision of services for broadcasting needs with the assignment of radio frequencies to general users in radio frequency bands allocated for broadcasting needs;
254.1.4. temporary broadcasting permits with assignment of radio frequencies to general users in radio frequency bands allocated for broadcasting needs;
254.1.5. assignment of radio frequencies (according to extracts from the register of assignments) for broadcasting purposes, received by a provider of electronic communications networks and/or services for the provision of services to the holder of a broadcasting license;
254.1.6. radio frequency assignment (according to extracts from the assignment register) for general users.
{Clause 254.1 of Article 254 as amended by Law No. 3721-IX of 05/21/2024 }
by the Law of Ukraine "On Electronic Communications", radio amateurs and users of ship stations installed on board a ship are not renters .
{Clause 254.2 of Article 254 as amended by Law No. 3721-IX of 05/21/2024 }
254.2 - 1. Diplomatic missions, consular offices of foreign states, missions of international organizations in Ukraine and military formations of foreign states temporarily located on the territory of Ukraine, which meet the requirements established by paragraph 254.1 of this Article, are not payers of the rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine if this type of payment is not applied to a similar mission of Ukraine in the relevant state, which is confirmed by information from the central executive body that ensures the formation and implementation of state policy in the field of foreign relations.
Such information is provided by the central executive body that ensures the formation and implementation of state policy in the field of foreign relations, at the request of the supervisory body.
{Article 254 is supplemented by paragraph 254.2 - 1 in accordance with Law No. 3721-IX of 21.05.2024 }
254.3. The object of taxation of the rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine is the width of the radio frequency band, which is defined as a part of the radio frequency band for public use in the relevant region and specified in the relevant licenses, permits and assignments specified in paragraph 254.1 of this article.
{Clause 254.3 of Article 254 as amended by Law No. 3721-IX of 05/21/2024 }
254.4. The rental rates for the use of the radio frequency spectrum (radio frequency resource) of Ukraine are set at the following rates:
Type of radio communication
Radio frequency range
Rental fee rate for 1 MHz of radio frequency band per month, hryvnias
1.
Radio relay communication of the fixed radio service
0.03-300 GHz
1.30
2.
Radio communication:
fixed, mobile land radio services
0.03-470 MHz
1274.57
maritime radio service
0.03-470 MHz
637.29
3.
Radio communication in the security and fire alarm system
30-470 MHz
1274.57
4.
Radio communication using radio extenders
30-470 MHz
639.28
5.
Radio communication in a data transmission system using noise-like signals
1427-2400 MHz 2400-2483.5 MHz 5150-5850 MHz
32.20
6.
Radio communication in a system with fixed subscriber radio access of the DECT standard
30-3000 MHz
64.33
7.
Trunked radio communication
30-470 MHz
3952.32
8.
Search radio communication
30-960 MHz
50982.39
9.
Radar and radio navigation radio services
30-3000 MHz 3-30 GHz
128.64
10.
Radiocommunication of satellite mobile and fixed radio services
Radio communication in multi-channel distribution systems for transmission and retransmission of television images, sound transmission, digital information
Transmission and retransmission of television images depending on power:
30-300 MHz
from 1 to 10 W inclusive
64.33
from 10.1 to 100 W inclusive
193.01
from 101 W to 1 kW inclusive
317.63
from 1.1 to 5 kW inclusive
510.65
from 5.1 to 20 kW inclusive
956.94
from 20.1 kW and above
1274.57
15.
Sound transmission depending on power:
66-74 MHz 87.5-108 MHz
up to 100 W inclusive
478.46
from 101 W to 1 kW inclusive
956.94
from 1.1 to 10 kW inclusive
1527.84
from 10.1 kW and above
1913.82
16.
Transmission and retransmission of television images depending on power:
300-880 MHz
up to 10 W inclusive
44.24
from 10.1 to 100 W inclusive
88.45
from 101 W to 1 kW inclusive
193.01
from 1.1 to 5 kW inclusive
382.02
from 5.1 to 20 kW inclusive
763.93
from 20.1 kW and above
956.94
16 - 1 .
Types of radio communication (regardless of service, system, radio technology, radio electronic means, radiating devices)
2300-2400 MHz 2575-2610 MHz 3400-3800 MHz
3685.50
17.
Types of radio communication (services, systems, radio technologies, radio electronic means, radiating devices) not specified in paragraphs 1-16 - 1 paragraph 254.4 of this article
9 kHz-400 GHz
1913.82
{Clause 254.4 of Article 254 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 ; as amended by Law No. 466-IX of 01/16/2020 ; as amended by Laws No. 1914-IX of 11/30/2021 , No. 3721-IX of 05/21/2024 }
254.5. Procedure for calculating tax liabilities from rent for the use of the radio frequency spectrum (radio frequency resource) of Ukraine
{Clause 254.5 of Article 254 as amended by Law No. 3721-IX of 21.05.2024 }
254.5.1. The National Commission, which carries out state regulation in the areas of electronic communications, radio frequency spectrum and provision of postal services, shall submit, in the procedure for information exchange, to the central executive body implementing state tax policy:
monthly, by the 10th day of the month following the reporting month, information on issued licenses for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, indicating the radio frequency bands for each rent payer, who calculates the amount of the rent in accordance with item 11, paragraph 254.4 , Article 254 of this Code;
twice a year by March 1 and September 1 of the current year as of January 1 and July 1, a list of users of the radio frequency spectrum (radio frequency resource) of Ukraine - payers of the rental fee and/or changes to it, indicating the type of communication, radio frequency band and regions of use of the radio frequency spectrum (radio frequency resource) of Ukraine.
{Subclause 254.5.1 of clause 254.5 of Article 254 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 3721-IX of 05/21/2024 }
254.5.2. Rent payers calculate the amount of rent based on the type of radio communication, the amount of established rates and the width of the radio frequency bandwidth for each region separately, in terms of the actual duration (calendar days) of the validity of the permit in the reporting period.
{Subclause 254.5.2 of Clause 254.5 of Article 254 as amended by Law No. 3721-IX of 05/21/2024 }
254.5.3. Rent payers who are granted the right to use the radio frequency spectrum (radio frequency resource) of Ukraine on the basis of a license to use the radio frequency spectrum (radio frequency resource) of Ukraine shall pay rent starting from the date of issuance of the license.
In the event of an extension of the term of validity of a license for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, the rental fee is paid from the beginning of the term of validity of the extended license.
Other rent payers shall pay rent starting from the date of entry of the radio frequency assignment into the register of radio frequency assignments of general users with the status "involved". Rent payers shall pay rent from the date of receipt of the first radio frequency assignment for radio equipment in a given radio frequency band in the relevant region, regardless of the total number of assignments made to the rent payer in such a radio frequency band in a particular region, except for cases when subsequent radio frequency assignments are made for radio equipment, the power of which provides for the application of a different rent rate than for previous assignments.
{Subclause 254.5.3 of Clause 254.5 of Article 254 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 3721-IX of 05/21/2024 }
254.5.4. Rent payers shall submit to the regulatory authorities copies of the relevant licenses and permits specified in clause 254.1 of this Article within one month after their issuance and extracts from the register of assignments of radio frequencies to general users within one month after assignment.
{Subclause 254.5.4 of clause 254.5 of Article 254 as amended by Law No. 3721-IX of 05/21/2024 }
254.6. The procedure for submitting a declaration, payment deadlines, liability of rent payers and control over its collection are determined by Articles 257 and 258 of this Code.
255.1. The payers of rent for special water use are:
primary water users - business entities regardless of the form of ownership: legal entities, their branches, departments, representative offices, other separate divisions without the formation of a legal entity, permanent representative offices of non-residents, as well as individual entrepreneurs who use and/or transfer to secondary water users water obtained by taking water from water bodies;
business entities regardless of the form of ownership: legal entities, their branches, departments, representative offices, other separate units without the formation of a legal entity, permanent representative offices of non-residents, as well as individual entrepreneurs who use water for the needs of hydropower, water transport and fish farming.
{Clause 255.1 of Article 255 as amended by Law No. 1797-VIII of 21.12.2016 }
255.2. Water users who use water exclusively to meet the drinking and sanitary and hygienic needs of the population (the aggregate of people who are in a given territory at a given time period, regardless of the nature and duration of residence, within their housing stock and household plots), including to meet exclusively their own drinking and sanitary and hygienic needs of legal entities, individual entrepreneurs and single tax payers, are not payers of rent for special water use.
For the purposes of this article, the term "sanitary and hygienic needs" should be understood as the use of water in toilets, showers, bathrooms and washbasins and the use to maintain premises in proper sanitary and hygienic condition.
255.3. The object of taxation by the rental fee for special use of water is the actual volume of water used by water users.
{Paragraph one of clause 255.3 of Article 255 as amended by Law No. 1797-VIII of 21.12.2016 }
255.3.1. The object of taxation of rental payments for the special use of water without its withdrawal from water bodies is:
for hydropower needs - the actual volume of water passed through the turbines of hydroelectric power plants to generate electricity;
for water transport needs - the time of use of surface waters by the operated self-propelled and non-self-propelled cargo fleet (depending on tonnage), and the operated passenger fleet (depending on the number of seats).
255.3.2. The object of taxation by the rental fee for the special use of water for the needs of fish farming is the actual volume of water necessary for replenishing water bodies during the breeding of fish and other aquatic living resources (including for replenishment associated with water losses due to filtration and evaporation).
255.4. The rent for the special use of water is not collected:
255.4.1. for water used to meet the drinking and sanitary and hygienic needs of the population (the totality of people who are in a given territory at a given time period, regardless of the nature and duration of residence, within their housing stock and household plots), including to meet exclusively their own drinking and sanitary and hygienic needs of legal entities, individual entrepreneurs and single tax payers;
255.4.2. for water used for fire-fighting purposes;
255.4.3. for water used for the needs of external improvement of the territories of cities and other settlements;
255.4.4. for water used for dust suppression in mines and quarries;
255.4.5. for water withdrawn by scientific research institutions, the list of which is approved by the Cabinet of Ministers of Ukraine, for conducting scientific research in the field of rice sowing and for the production of elite rice seeds;
{Subclause 255.4.6 of clause 255.4 of Article 255 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
255.4.7. for groundwater extracted from the subsoil to eliminate the harmful effects of water (flooding, salinization, waterlogging, landslides, pollution, etc.), except for quarry, mine and drainage water used in economic activities after extraction and/or obtained for use by other users;
255.4.8. for water withdrawn to ensure the release of juveniles of valuable commercial fish species and other aquatic living resources into water bodies;
255.4.9. for sea water, except for water from estuaries;
255.4.10. for water used by horticultural and garden societies (cooperatives);
255.4.11. for water withdrawn for rehabilitation, treatment and improvement by rehabilitation institutions for persons with disabilities and children with disabilities, enterprises, institutions and organizations of physical education and sports for persons with disabilities and children with disabilities, which are founded by all-Ukrainian public associations of persons with disabilities in accordance with the law;
255.4.12. for the needs of hydropower - from pumped storage power plants that operate in a complex with hydroelectric power plants;
255.4.13. for the needs of water transport:
from sea water transport, which uses a river waterway exclusively for entering from the sea into a seaport located downstream, without using special measures to ensure navigation (water releases from reservoirs and sluice gates);
during the operation of waterways by stationary (oil pumping stations, floating oil depots, landing stages, floating docks, vessels with mechanical equipment and other stationary vessels) and service and auxiliary vessels and the operation of the waterways of the Danube River.
255.5. Rental rates for special water use are set at the following rates:
255.5.1. for special use of surface waters:
River basin area
Rental rate, hryvnias per 100 cubic meters
Dnipro River Basin Area
75.53
Dniester River Basin Area
39.90
Danube River Basin District
29.96
Southern Bug River Basin Area
89.87
Don River Basin Area
129.90
Vistula River Basin District
39.90
Crimean river basin area
133.19
Black Sea River Basin Area
159.91
Azov River Basin Area
159.91
{Subclause 255.5.1 of clause 255.5 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
255.5.2. for special use of groundwater:
Name of the region
Rental rate, hryvnias per 100 cubic meters
Autonomous Republic of Crimea (except for the city of Sevastopol)
123.18
Sevastopol city
123.18
Region:
Vinnytsia
106.46
Volynska
109.97
Dnipropetrovsk
93.29
Donetsk
126.59
Zhytomyrska
106.46
Transcarpathian
69.95
Zaporizhzhia
106.46
Ivano-Frankivsk
166.51
Kyivska
91.31
Kirovohradska
123.18
Lvivska
96.63
Luhansk
139.84
Mykolaivska
139.84
Odesa
116.56
Poltava
80.26
Rivne
99.80
Sumy
91.41
Ternopil
129.90
Kharkiv
99.86
Kherson
99.86
Khmelnytskyi
126.59
Cherkasy
72.02
Chernivtsi
116.56
Chernihiv
99.86
Kyiv
99.50
{Subclause 255.5.2 of Clause 255.5 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
255.5.3. for the needs of hydropower - 12.95 hryvnias per 10 thousand cubic meters of water passed through the turbines of hydroelectric power plants;
{Subclause 255.5.3 of clause 255.5 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
255.5.4. for the needs of water transport from all rivers except the Danube:
for cargo self-propelled and non-self-propelled fleet in operation - 0.2219 hryvnia per 1 tonnage-day of operation;
for the operated passenger fleet - 0.0246 hryvnia per 1 seat-day of operation;
{Subclause 255.5.4 of clause 255.5 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
255.5.5. for the needs of fish farming:
67.97 hryvnias per 10 thousand cubic meters of surface water;
81.71 hryvnias for 10 thousand cubic meters of groundwater;
{Subclause 255.5.5 of Clause 255.5 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
255.5.6. for water included exclusively in beverages:
63.22 hryvnias per 1 cubic meter of surface water;
73.73 hryvnias per 1 cubic meter of groundwater;
{Subclause 255.5.6 of Clause 255.5 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
255.5.7. for mine, quarry and drainage water - 14.64 hryvnias per 100 cubic meters of water.
{Subclause 255.5.7 of clause 255.5 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
{Clause 255.5 of Article 255 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 }
255.6. For thermal power plants with a direct-flow water supply system, the rental fee for the actual volume of water passed through the turbine condensers to cool the condensate is calculated using a coefficient of 0.005.
255.7. Housing and communal enterprises apply a coefficient of 0.3 to rental rates in terms of water volumes of technological standards for the use of drinking water, determined in accordance with the legislation on drinking water, drinking water supply and water disposal.
{Clause 255.7 of Article 255 as amended by Law No. 1914-IX of 11/30/2021 }
{Clause 255.8 of Article 255 was excluded pursuant to Law No. 1914-IX of 30.11.2021 }
255.9. In the event of the use of water from canals by rent payers, the rent rates established for the special use of water from the water body from which water is taken into the canal shall apply.
255.10. When using water from mixed water supply sources, the rental fee rates established for the sources from which mixed sources are formed (filled) shall apply.
255.11. Procedure for calculating tax liabilities from rent for special use of water
255.11.1. Water users independently calculate the rental fee for special use of water and for special use of water for the needs of hydropower and fish farming every quarter in a cumulative total from the beginning of the year, and for special use of water for the needs of water transport - starting from the first half of the current year in which such use was carried out.
255.11.2. The rental fee is calculated based on the actual volumes of water used (underground, surface) in water bodies established in the special water use permit and/or in the integrated environmental permit, water use limits, rental fee rates and coefficients.
{Subclause 255.11.2 of clause 255.11 of Article 255 as amended by Law No. 1797-VIII of 21.12.2016 ; as amended by the Law No. 4536-IX dated 16.07.2025 }
255.11.3. Water users who use water from a mixed source shall calculate the rental fee, taking into account the volumes of water in the ratio in which such a mixed source is formed, as specified in permits and water supply contracts, rental fee rates and coefficients.
{Subclause 255.11.3 of clause 255.11 of Article 255 as amended by Law No. 1797-VIII of 21.12.2016 }
255.11.4. Water users who use water from canals calculate the rental fee based on the actual volumes of water used, established water use limits, rental fee rates established for the water body from which water is taken into the canal, and coefficients.
{Subclause 255.11.3 of clause 255.11 of Article 255 as amended by Law No. 1797-VIII of 21.12.2016 }
255.11.5. The rental fee for the special use of water for hydropower needs is calculated based on the actual volumes of water passed through the turbines of hydroelectric power plants and the rental fee rate.
255.11.6. Under the conditions of operation of waterways by self-propelled and non-self-propelled cargo vessels, the rental fee for the special use of water for the needs of water transport is calculated based on the actual data of the tonnage-day accounting and the rental fee rate, and for passenger vessels - based on the place-day and the rental fee rate.
255.11.7. The collection of a rental fee for the special use of water for the needs of hydropower, water transport and fish farming does not exempt water users from paying a rental fee for the special use of water.
255.11.8. The rental fee for the special use of water for the needs of fish farming is calculated based on the actual volumes of water required to replenish water bodies during fish farming and other aquatic living resources (including for replenishment associated with water losses due to filtration and evaporation), and the rental fee rates.
255.11.9. Water users who use a circulating water supply system for equipment cooling purposes shall calculate the rental fee based on the actual volumes of water used to replenish the circulating system. For all other volumes of water actually used, the rental fee shall be calculated on a general basis.
255.11.10. The volume of actually used water is calculated by water users independently based on primary accounting data according to the readings of measuring devices.
In the absence of metering devices, the volume of actually used water is determined by the water user based on technological data (duration of operation of units, volume of products produced or services provided, electricity consumption, throughput capacity of water pipes per unit of time, etc.). In the absence of metering devices, if there is a possibility of their installation, the rental fee is paid in double the amount.
255.11.11. The volume of water actually used in state systems in irrigated agriculture is determined by water management authorities.
255.11.12. If water users, who are fully supported by state and local budgets, use water volumes for economic activities aimed at generating income in monetary, material or intangible forms, the rental fee is calculated on a general basis from the entire volume of water used.
{Subclause 255.11.12 of clause 255.11 of Article 255 as amended by Law No. 1797-VIII of 21.12.2016 }
255.11.13. In the event that water users exceed the established annual water use limit, the rental fee is calculated and paid in a fivefold amount based on the actual volumes of water used in excess of the established water use limit, rental fee rates, and coefficients.
255.11.14. For excessive water use, the rental fee is calculated for each water supply source separately in accordance with the established rental fee rates and coefficients.
255.11.15. If the water user does not have a permit for special water use and/or an integrated environmental permit with water use limits established therein, the rental fee is charged for the entire volume of water used, which is subject to payment as for use above the limit.
{Sub-clause 255.11.15 of clause 255.11 of Article 255 as amended Law No. 4536-IX of 16.07.2025 }
255.11.16. A tax return for rent for special use of water for water transport needs for the first quarter is not submitted.
The rent for the special use of water for water transport needs is not paid for the first quarter.
255.11.17. Branches, offices, other separate subdivisions of a water user that have bank accounts, maintain separate accounting records of their activities, prepare a separate balance sheet, submit tax returns and pay rent at their place of tax registration.
255.11.18. If the water user includes structural units that do not have bank accounts, do not maintain separate accounting of their activities, do not prepare a separate balance sheet, tax returns are submitted and the rental fee is paid by the water user that includes such structural units, based on the location of the water bodies and at the rental fee rates established for these water bodies.
255.11.19. Rent payers shall submit copies of the special water use permit and/or integrated environmental permit, water supply contract, and statistical reporting on water use to the regulatory authorities simultaneously with their tax returns.
{Sub-clause 255.11.19 of clause 255.11 of Article 255 as amended by the Law No. 4536-IX dated 16.07.2025 }
255.11.20. Within the limits of the water use limit established in the special water use permit and/or in the integrated environmental permit, the rental fee is included in the expenses, and for use above the limit, it is charged from the profit remaining at the disposal of the water user after taxation.
{Paragraph one of subparagraph 255.11.20 of paragraph 255.11 of Article 255 as amended by the Law No. 4536-IX dated 16.07.2025 }
The rent for the special use of water for the needs of hydropower and water transport is fully included in the costs.
255.12. The procedure for submitting a declaration, payment deadlines, liability of rent payers, and control over its collection are determined by Articles 257 and 258 of this Code.
Article 256. Rent for special use of forest resources↑
256.1. Payers of the rental fee for the special use of forest resources are forest users - legal entities, their branches, departments, other separate subdivisions that do not have the status of a legal entity, permanent representative offices of non-residents who receive income from sources of their origin in Ukraine or perform agency (representative) functions in relation to such non-residents or their founders, individuals (except for individuals who have the right to use forest resources free of charge without issuing a special permit in accordance with forest legislation), as well as individual entrepreneurs who carry out special use of forest resources on the basis of a special permit (logging ticket or forest ticket) or in accordance with the terms of a long-term temporary forest use agreement.
256.2. The object of taxation of rent for the special use of forest resources is:
256.2.1. timber harvested in the order of final felling;
256.2.2. wood harvested during events:
on improving the qualitative composition of forests, their rehabilitation, and strengthening protective properties (in stands over 40 years old - forest care felling, selective sanitary felling, selective reforestation felling, felling associated with reconstruction, landscape felling, and reforestation felling; regardless of the age of the stands - continuous sanitary and continuous reforestation felling);
for clearing forest areas covered with forest vegetation in connection with the construction of hydroelectric power plants, pipelines, roads, etc.;
256.2.3. secondary forest materials (harvesting of resin, stumps, bast and bark, tree foliage, tree sap and other secondary forest materials provided for by regulatory legal acts on forestry management);
256.2.4. secondary forest uses (harvesting hay, grazing livestock, harvesting wild fruits, nuts, mushrooms, berries, medicinal plants, collecting forest litter, harvesting reeds and other secondary forest uses provided for by regulatory legal acts on forestry);
256.2.5. use of the beneficial properties of forests for cultural, recreational, sports, tourist and educational purposes and conducting scientific research.
256.3. The rates of rent for the special use of forest resources are set at the following rates:
256.3.1. for harvesting wood of the main forest species:
Name of the forest species
Rate for 1 dense cubic meter of wood, hryvnias
business (without bark)
wood (with bark)
big
average
small
The first forest belt
Pine
304.60
196.20
75.66
8.24
Larch
135.57
117.19
44.57
10.29
Spruce, fir
280.28
239.80
91.78
10.37
Oak (except cork oak)
800.39
382.48
128.56
13.47
Ash, maple (except sycamore)
300.12
255.05
128.56
13.47
Beech
575.33
368.60
123.39
11.43
Birch, black alder, common hornbeam, elm, linden
43.54
38.91
29.53
10.29
Aspen, gray alder, poplar
26.48
21.77
17.20
7.27
Second forest belt
Pine
256.03
165.74
64.26
7.27
Larch
117.19
99.09
38.32
9.37
Spruce, fir
236.80
202.15
78.49
8.86
Oak (except cork oak)
675.97
326.62
107.76
10.29
Ash, maple (except sycamore)
253.46
217.71
107.76
10.29
Beech
488.34
312.61
104.73
9.37
Birch, black alder, common hornbeam, elm, linden
37.34
31.14
24.87
8.24
Aspen, gray alder, poplar
21.77
20.22
15.56
6.21
256.3.2. for the harvesting of non-core forest species:
Name of the forest species
Rate for 1 dense cubic meter of wood, hryvnias
business (without bark)
wood (with bark)
big
average
small
The first forest belt
Boxwood
1401.06
1197.37
598.16
13.47
Velvet, walnut
872.42
746.43
373.25
13.47
Pear, dogwood, sycamore
699.80
598.72
299.59
13.47
Apricot, cherry, juniper, sea buckthorn, plum (except blackthorn), sweet cherry, mulberry, apple tree
Willow, shrubs (except those specified in other headings)
74.67
63.68
32.17
6.21.
{Clause 256.3 of Article 256 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 , No. 2245-VIII of 12/07/2017 , No. 2628-VIII of 11/23/2018 , No. 466-IX of 01/16/2020 , No. 1914-IX of 11/30/2021 }
256.4. The rental rates established by subparagraphs 256.3.1 and 256.3.2 of paragraph 256.3 of this article shall be applied when harvesting timber in the order of main use fellings and during the implementation of measures to improve the qualitative composition of forests, their rehabilitation, and enhance protective properties (in stands over 40 years old - forest care fellings, selective sanitary fellings, selective reforestation fellings, fellings related to reconstruction, landscape fellings, and reforestation fellings; regardless of the age of the stands - continuous sanitary and continuous reforestation fellings) and measures to clear forest areas covered with forest vegetation in connection with the construction of hydroelectric power plants, pipelines, roads, etc.
256.5. The rates of rental payment for timber harvesting are applied taking into account the distribution of forests by zones.
{Clause 256.5 of Article 256 as amended by Law No. 466-IX of January 16, 2020 }
256.6. Distribution of forests by zones:
256.6.1. the first belt includes all forests, except for the forests of the Transcarpathian, Ivano-Frankivsk and Chernivtsi regions and the forests of the mountain zone of the Lviv region;
256.6.2. The second belt includes the forests of Transcarpathian, Ivano-Frankivsk and Chernivtsi regions and the forests of the mountain zone of Lviv region.
{Clause 256.7 of Article 256 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
{Clause 256.8 of Article 256 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
256.9. Large wood of all forest species includes trunk segments (in the upper cross-section without bark) with a diameter of 25 centimeters or more, medium wood includes wood with a diameter of 13 to 24 centimeters, and small wood includes wood with a diameter of 3 to 12 centimeters.
Firewood includes assortments that can be used for technological needs, as well as those that are not suitable for industrial processing (fuel wood).
For firewood used for technological needs, an additional rental fee is charged based on the results of actual harvesting in the amount of 70 percent of the rental fee rates for commercial small timber of the corresponding forest species established by subparagraphs 256.3.1 and 256.3.2 of paragraph 256.3 of this article.
The rental rates for commercial and firewood of linden are established by subparagraphs 256.3.1 and 256.3.2 of paragraph 256.3 of this article without taking into account the bark, and for firewood of other forest species - with bark.
A rent of 40 percent is established for crown liquidation, and for felling residues subject to use - 20 percent of the rent rates for firewood of the corresponding forest species.
For wood harvested during selective logging for primary use, the rental fee rates are reduced by 20 percent, and for measures to improve the qualitative composition of forests, their rehabilitation, and strengthening protective properties (in stands over 40 years old - forest care logging, selective sanitary logging, selective forest regeneration logging, logging related to reconstruction, landscape logging, and re-forming logging) - by 50 percent. Discounts in percentage are calculated for each rental fee rate separately.
256.10. For the procurement of secondary forest materials, the implementation of secondary forest uses and the use of useful properties of forests, the rates of rental payment are established by the Verkhovna Rada of the Autonomous Republic of Crimea, regional, Kyiv and Sevastopol city councils.
256.11. Procedure for calculating tax liabilities from rent for special use of forest resources
256.11.1. The amount of the rental fee is calculated by the forest relations entities that issue special permits, and is specified in such permits.
256.11.2. The amount of the rental fee specified in the logging and forest tickets shall be recalculated by the entity of forest relations that issues special permits in the event that:
the total amount of actually harvested timber at the time of its release, calculated by area, exceeds the amount specified in the logging ticket by more than 10 percent;
the actual volume of forest resource use exceeds that specified in the forest ticket by the entire amount of such excess.
The basis for the recalculation is special permits and inspection reports of places of use of forest resources.
256.11.3. The entity of forest relations that issues special permits shall also recalculate the rental fee for the harvesting of timber and the harvesting of secondary forest materials, secondary forest uses and the use of useful properties of forests in the following cases:
a) correction of technical errors that may be made during the material and monetary valuation of fellings, secondary forest materials, secondary forest uses and the use of useful properties of forests released under felling tickets or forest tickets, incorrect application of assortment tables, zones, categories and rental rates, as well as correction of arithmetic errors made during calculations;
b) cancellation of a logging and/or forest ticket due to the withdrawal of land for other needs. In other cases of cancellation or issuance of a duplicate logging ticket and/or forest ticket, the rent payment is not recalculated and the entire amount of rent paid for such tickets is fully paid to the relevant budgets;
c) granting the forest user a deferment:
for timber harvesting - the amount of the rental fee for harvesting timber left on the stump increases by 1.5 percent regardless of the period for which the deferral is granted;
for the export of wood - the amount of the rental fee for wood not exported on time increases by 1.5 percent for each month of delay;
d) additional extension of the export deadline, but not more than three months. In this case, the amount of the forest user's rental payment for the volume of wood not exported on time increases by 5 percent for each month of delay.
256.11.4. Regardless of the method of accounting for wood released on stumps (by area, stumps, approximate quantity), forest users who have allowed incomplete harvesting of wood permitted for felling under issued logging tickets, or have not carried it out at all, shall calculate and pay the rental fee in full for the entire amount of wood permitted for harvesting specified in the permit.
256.11.5. Forest users whose rental payments are recalculated based on the results of their activities shall reflect the additional amounts of rental payments in their tax declaration.
256.11.6. Forest users shall file a quarterly tax return on rental payments with a cumulative total from the beginning of the year, with the exception of:
a) forest users, who, before receiving logging and forest tickets, pay the rental fee to the cash desks of the forest relations entities that issue them:
individuals, as well as individual entrepreneurs who have been issued logging and forest permits;
forest users (except for individuals, as well as individual entrepreneurs who have been issued forest tickets), whose amount of rental payment in logging or forest tickets does not exceed 25 percent of one minimum wage established by law as of January 1 of the year in which the rental payment is paid;
{Paragraph three of subparagraph "a" of subparagraph 256.11.6.paragraph 256.11 of Article 256 as amended by Law No. 1791-VIII of 20.12.2016 }
b) forest users from another region who pay the rental fee in full before being issued a special permit for the location of the forest plot where timber is harvested.
256.11.7. A record shall be made in a specially established book about the receipt of the amount of the rental fee in the cash register of the subject of forest relations that issues special permits, and a receipt shall be issued to the forest user. At the same time, a note shall be made in the logging and forest tickets about the payment of the rental fee to the cash register (the number and date of the payment receipt shall be indicated).
256.11.8. When obtaining a permit in the current year (or additional accrual of the amount of the rental fee) after the next rental fee payment deadline, forest users shall pay all amounts of the rental fee for the past due periods.
256.12. The procedure for submitting a declaration, payment deadlines, liability of rent payers, and control over its collection are determined by Articles 257 and 258 of this Code.
Article 256 - 1. Rent for the transportation of oil and oil products through main oil pipelines and oil product pipelines, transit transportation of ammonia through pipelines through the territory of Ukraine↑
256 - 1 .1. Payers of rent are business entities that operate main pipeline facilities and provide (organize) services for the transportation (movement) of cargo through the pipelines of Ukraine.
256 - 1 .2. The object of taxation of rental payments is:
for oil and oil products, their actual volumes transported through the territory of Ukraine in the tax (reporting) period;
for ammonia, it is the sum of the products of the distances of the respective routes of its transportation (movement), agreed between the rent payer and the customer for the respective tax (reporting) period, and the volumes of ammonia transported (moved) by each transportation route.
256 - 1 .3. Tax rates:
$0.56 for transporting one ton of oil through main oil pipelines;
USD 0.56 for transporting one ton of petroleum products through main petroleum product pipelines;
2.4 US dollars for the transit transportation of one ton of ammonia for every 100 kilometers of the distance of the relevant transportation routes.
In the event of a change in transportation tariffs, a correction coefficient is applied to the rental rates, which is calculated in accordance with the procedure established by the Cabinet of Ministers of Ukraine, except for the rental rate for the transit transportation of ammonia and for the transportation of oil through main oil pipelines for consumers of Ukraine.
256 - 1 .4. The amount of tax liabilities on rent is calculated as the product of the relevant object of taxation, defined in subparagraph 256 - 1 .2 of this article, by the relevant tax rate, defined in subparagraph 256 - 1 .3 of this article, and taking into account the adjustment coefficient, defined in accordance with the established procedure.
256 - 1 .5. The amount of tax liabilities on rent for the tax (reporting) period is paid based on:
actual volumes of ammonia and the distance of the relevant routes for its transportation through the territory of Ukraine;
actual volumes of oil and petroleum products transported through the territory of Ukraine.
256 - 1 .6. For the purposes of this article, the following terms shall apply:
cargo - oil and its refined products (petroleum products), as well as ammonia;
appropriate route - the way of transportation (movement) of cargo, determined by the type of transport services during its transit through pipelines, in particular:
a) between border points of reception (departure) and destination or a transshipment complex for cargo arriving from the territories of other states and intended for consumers outside Ukraine;
b) main pipelines, including the provision of services for temporary storage or processing of cargo on the territory of Ukraine, with subsequent movement beyond its borders;
transportation route - the way of transportation (movement) of cargo between the points of reception (departure) and destination, which are determined by the parties in the essential terms of the contract for the provision of transport services;
services - transportation (movement) of cargo through main pipelines of Ukraine;
tariff - the cost of transporting an accounting unit of cargo through the main pipelines of Ukraine (excluding value added tax), which is established:
for transportation for consumers of Ukraine - by a state authority authorized in accordance with the legislation;
for transit through the territory of Ukraine - on the basis of agreements.
{Article 256 - 1 as amended by Law No. 211-VIII of 02.03.2015 ; as amended by Law No. 909-VIII of 24.12.2015 }
Article 257. Submission of declaration and terms of payment of rent↑
257.1. The basic tax (reporting) period for rent is equal to a calendar quarter, and for rent for the use of subsoil for the extraction of minerals for the extraction of oil, condensate, natural gas, including gas dissolved in oil (oil (associated) gas), ethane, propane, butane, rent for the use of the radio frequency spectrum (radio frequency resource) of Ukraine and rent for the transportation of oil and oil products through main oil pipelines and oil product pipelines, transit transportation of ammonia through pipelines through the territory of Ukraine, is equal to a calendar month.
{Clause 257.1 of Article 257 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 3721-IX of 05/21/2024 }
257.2. Rent payers shall independently calculate the amount of tax liabilities from rent.
257.3. The rent payer, before the expiration of the deadline for submitting tax returns for the tax (reporting) period specified in Section II of this Code, shall submit to the relevant regulatory authority a tax return in the form established in accordance with the procedure provided for in Article 46 of this Code, which shall contain the following annexes:
{Paragraph one of clause 257.3 of Article 257 as amended by Law No. 909-VIII of 24.12.2015 }
257.3.1. from the rent for the use of subsoil for the extraction of minerals:
by the location of the subsoil area from which the minerals were extracted, if such subsoil area is located within the territory of Ukraine;
at the place of registration of the rent payer in the event that the subsoil area from which minerals were extracted is located within the continental shelf and/or exclusive (maritime) economic zone of Ukraine;
257.3.2. from rent for the use of subsoil for purposes not related to the extraction of minerals - by the location of the subsoil plot;
257.3.3. from the rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine - at the place of tax registration;
{Subclause 257.3.3 of Clause 257.3 of Article 257 as amended by Law No. 3721-IX of 21.05.2024 }
257.3.4. from rent for special use of water - at the place of tax registration;
257.3.5. from the rental fee for the special use of forest resources - by location of the forest plot;
257.3.6. from the rental fee for the transportation of oil and oil products through main oil pipelines and oil product pipelines, transit transportation of ammonia through pipelines through the territory of Ukraine - at the place of its tax registration.
{Subclause 257.3.6 of Clause 257.3 of Article 257 as amended by Law No. 909-VIII of 24.12.2015 }
{Clause 257.4 of Article 257 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
257.5. The amount of tax liabilities on rental payments, determined in the tax return for the tax (reporting) period, shall be paid by the payer to the budget within 10 calendar days after the deadline for submitting such tax return.
The rent for the special use of forest resources shall be paid by forest users quarterly in equal parts of the amount of the rent specified in the special permits issued in the relevant calendar year, except for the amounts of rent paid in accordance with subparagraphs "a" and "b" of subparagraph 256.11.6 of paragraph 256.11 of Article 256 of this Code.
{Paragraph 257.5 of Article 257 was supplemented by the second paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
{Clause 257.5 of Article 257 as amended by Law No. 909-VIII of 24.12.2015 }
257.6. If the place of registration of the rent payer does not coincide with the location of the subsoil plot, the rent payer for the use of subsoil for the extraction of minerals and the rent payer for the use of subsoil for purposes not related to the extraction of minerals shall submit a copy of the tax return and a copy of the document on the payment of tax obligations on the rent to the place of tax registration of the payer or authorized person.
{Clause 257.6 of Article 257 as amended by Law No. 2888-IX of 12.01.2023 }
Article 258. Responsibility of rent payers and control over its collection↑
258.1. Liability of rent payers
258.1.1. The rent payer is responsible for the correct calculation, completeness and timeliness of its payment to the budget, as well as for the timeliness of submission of relevant tax declarations to the regulatory authorities in accordance with the provisions of this Code and other legislative acts.
258.1.2. A penalty shall be charged on the amount of tax liabilities on rent accrued by the rent payer for the tax (reporting) period, but not paid within 10 calendar days following the last calendar day of the deadline for submitting a tax return, in accordance with the procedure established by Section II of this Code.
258.2. Control over the correctness of the calculation, timeliness and completeness of the collection of rent payments
258.2.1. Control over the correctness of the calculation, timeliness and completeness of the rental payment is carried out by the regulatory authorities.
258.2.2. Features of control over the collection of rent for the use of subsoil for the extraction of minerals
To ensure control over the correctness of the payer's calculation of the amount of the rent for the use of subsoil for the extraction of minerals in terms of determining the volume (quantity) of extracted minerals within the subsoil area granted to him, as well as the correction coefficients in accordance with paragraph 252.2 of Article 252 of this Code, the supervisory authorities may, in accordance with the procedure established by law, involve central executive bodies that implement state policy in the field of state mining supervision, as well as in the field of geological study and rational use of subsoil.
In the event of facts occurring within six months regarding the non-payment, untimely payment by the rent payer of tax liabilities or failure by the payer to fulfill tax liabilities on rent for the use of subsoil for the extraction of minerals, the central executive body implementing the state tax policy shall raise the issue of suspending the relevant special permit with the relevant central executive body.
{Paragraph three of subparagraph 258.2.2 of paragraph 258.2 of Article 258 as amended by Law No. 1797-VIII of 21.12.2016 }
An administrative and economic sanction in the form of withdrawal of the profit (income) received (accrued) by the payer or the relevant regulatory body from economic activity on the extraction of minerals shall be applied to the income that arose for the payer as a result of the exercise by such payer of the rights to use a subsoil plot during the period of non-payment or untimely payment by the payer of the amounts of tax liabilities from the rent for the use of subsoil for the extraction of minerals (except for cases of additional charges and penalties based on the results of inspections by regulatory bodies) for six months, as well as for the period of suspension of the relevant special permit.
Within one month after making the relevant decision, the state mining supervision bodies shall send to the supervisory body at the place of tax registration of the payer who will carry out the extraction of minerals, including during geological exploration, a notification of granting such payer a permit to commence mining operations or approval to conduct experimental and industrial development.
The central executive body implementing the state policy in the field of geological exploration and ensuring the rational use of subsoil, within a month after making the relevant decision, sends to the supervisory body at the place of tax registration of the payer who will carry out the extraction of minerals, including during geological exploration, a copy of the payer's approved schemes for the movement of extracted minerals (mineral raw materials) at production sites and storage locations, taking into account the composition of the starting materials, specific production conditions, features of the technological process and requirements for the final product, specifying the procedure for determining the quality of raw materials and the final product, determining the content of the main and associated minerals in laboratories certified in accordance with the rules of authorization and certification in the state metrological system.
258.2.3. Control over the correctness of determining the volumes of subsoil use for purposes not related to mineral extraction is carried out by the central executive body implementing state policy in the field of state mining supervision, which submits, within a month from the date of issuance or withdrawal of the act on granting a mining concession, information on changes in the list of subsoil users to the supervisory bodies at the location of the subsoil area.
258.2.4. In the event of non-payment of the rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine or its incomplete payment by the rent payers within three months, the regulatory authorities shall submit information about such payers to the National Commission for State Regulation in the Fields of Electronic Communications, Radio Frequency Spectrum and Provision of Postal Services, in order to take measures against them in accordance with the legislation.
The regulatory authorities submit to the National Council of Ukraine for Television and Radio Broadcasting information about rent payers who use the radio frequency spectrum (radio frequency resource) of Ukraine to provide electronic communication services for broadcasting needs and have not paid the rent within three months or have not paid it in full, in order to take measures against them in accordance with the legislation.
{Subclause 258.2.4 of Clause 258.2 of Article 258 as amended by Law No. 3721-IX of 05/21/2024 }
258.2.5. Features of control over the collection of rent for special water use
Authorities issuing permits for special water use and/or integrated environmental permits shall, by January 20 of each year, provide the central executive body implementing state tax policy and water management authorities with information on water users who have been issued such permits, and shall also submit information on changes to the information on water users who have been issued such permits by the 10th of the month following the quarter in which such changes occurred.
{Paragraph two of subparagraph 258.2.5 of paragraph 258.2 of Article 258 as amended Law No. 4536-IX of 16.07.2025 }
Water users who have been issued permits for special water use and/or an integrated water use permit and who supply water to other water users shall submit a list of water users - subscribers to the regulatory authorities and water management authorities by January 20 each year.
{Paragraph three of subparagraph 258.2.5 of paragraph 258.2 of Article 258 as amended Law No. 4536-IX of 16.07.2025 }
In the event of changes in water use conditions, issuance of new permits for special water use and/or integrated environmental permits during the year, conclusion of water supply contracts, water users who have received reissued permits for special water use, water supply contracts and/or an integrated environmental permit to which amendments have been made are obliged to notify the regulatory authorities and water management authorities within 10 days.
{Paragraph four of subparagraph 258.2.5 of paragraph 258.2 of Article 258 and as amended by the Law No. 4536-IX dated 16.07.2025 }
In the event of non-payment of the rent or its payment not in full within six months, the regulatory authorities submit information about the rent payers to the authorities issuing permits for special water use and/or integrated environmental permits, in order to take measures against them in accordance with the law.
{Paragraph five of subparagraph 258.2.5 of paragraph 258.2 of Article 258 and as amended by the Law No. 4536-IX dated 16.07.2025 }
258.2.6. Forest relations entities that issue special permits shall, by the 10th day of the month following the reporting quarter, send to the supervisory authorities a list of forest users who have been issued logging permits and forest tickets , in the form established by the central executive body that ensures the formation and implementation of state financial policy, in agreement with the central executive body that ensures the formation of state policy in the field of forestry.
{Subclause 258.2.6 of Clause 258.2 of Article 258 as amended by Law No. 1797-VIII of 21.12.2016 }
{Chapter IX as amended by Law No. 71-VIII of 12/28/2014 }
{Chapter X "Rent for oil, natural gas and gas condensate produced in Ukraine" has become invalid pursuant to Law No. 4834-VI of 24.05.2012 ; Chapter X "Rent for oil, natural gas and gas condensate produced in Ukraine" has been excluded pursuant to Law No. 71-VIII of 28.12.2014 }
{Chapter XI "Fees for the use of subsoil" was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
266.1.1. Taxpayers are individuals and legal entities, including non-residents, who are owners of residential and/or non-residential real estate.
266.1.2. Determination of taxpayers in the event that residential and/or non-residential real estate objects are in joint partial or joint ownership of several persons:
a) if a residential and/or non-residential real estate object is jointly owned by several persons, the tax payer is each of these persons for their respective share;
b) if a residential and/or non-residential real estate object is jointly owned by several persons, but not divided in kind, the taxpayer is one of such owners, determined by their consent, unless otherwise established by the court;
c) if a residential and/or non-residential real estate object is jointly owned by several persons and divided between them in kind, the tax payer is each of these persons for their respective share.
266.2. Object of taxation
266.2.1. The object of taxation is a residential and non-residential real estate object, including its share.
266.2.2. The following are not subject to taxation:
a) residential and non-residential real estate owned by state authorities, local governments, as well as organizations established by them in accordance with the established procedure, which are fully maintained at the expense of the relevant state budget or local budget and are non-profit (their joint ownership);
b) residential and non-residential real estate objects located in zones of alienation and unconditional (mandatory) resettlement, defined by law, including their shares;
c) buildings of family-type orphanages;
d) dormitories;
e) residential real estate is unfit for habitation, including due to an emergency condition, recognized as such in accordance with the decision of the village, settlement, or city council;
{Sub-paragraph "g" of subparagraph 266.2.2 of paragraph 266.2 of Article 266 as amended by Law No. 909-VIII of 24.12.2015 }
e) residential real estate objects, including their shares, belonging to orphans, children deprived of parental care, and persons from among them recognized as such in accordance with the law, children with disabilities who are raised by single mothers (fathers), but no more than one such object per child;
e) non-residential real estate objects used by small and medium-sized business entities operating in temporary structures for entrepreneurial activities and/or in small architectural forms and in markets;
{Subparagraph "e" of subparagraph 266.2.2 of paragraph 266.2 of Article 266 as amended by Law No. 466-IX of 16.01.2020 }
h) industrial buildings classified in the class "Industrial and warehouse buildings" (code 125) of the Classifier of Buildings and Structures NK 018:2023, which are used for their intended purpose in the economic activities of business entities whose main activity is classified in sections BF KVED DK 009:2010, and are not rented, leased, or loaned by their owners;
{Sub-clause "e" of subparagraph 266.2.2 of paragraph 266.2 of Article 266 as amended by Laws No. 466-IX of 01/16/2020 , No. 3603-IX of 02/23/2024 }
g) buildings, structures of agricultural producers (legal entities and individuals), classified in the class "Non-residential agricultural buildings" (code 1271) of the Classifier of Buildings and Structures NK 018:2023, which are used for their intended purpose in the economic activities of business entities and are not rented, leased, or loaned by their owners;
{Sub-paragraph "g" of subparagraph 266.2.2 of paragraph 266.2 of Article 266 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 3603-IX of 02/23/2024 }
h) residential and non-residential real estate owned by public associations of persons with disabilities and their enterprises;
i) real estate owned by religious organizations, the statutes (regulations) of which are registered in accordance with the procedure established by law, and are used exclusively to ensure their statutory activities, including those in which charitable institutions founded by such religious organizations (shelters, boarding schools, hospitals, etc.) operate, except for real estate in which production and/or economic activities are carried out;
{Subclause 266.2.2 of clause 266.2 of Article 266 is supplemented by subparagraph "i" in accordance with Law No. 420-VIII of 14.05.2015 }
i) buildings of preschool and general education institutions, regardless of the form of ownership and sources of financing, used to provide educational services;
{Sub-clause 266.2.2 of clause 266.2 of Article 266 is supplemented by subparagraph "i" in accordance with Law No. 654-VIII of 17.07.2015 }
j) non-residential real estate objects of state and municipal children's sanatorium-resort institutions and children's health and recreation institutions, as well as children's sanatorium-resort institutions and children's health and recreation institutions that are on the balance sheet of enterprises, institutions and organizations that are non-profit and included by the regulatory body in the Register of Non-profit Institutions and Organizations. In the event of exclusion from the Register of Non-profit Institutions and Organizations, the declaration is submitted by the taxpayer within 30 calendar days from the date of exclusion, and the tax is paid starting from the month following the month in which the exclusion from the Register of Non-profit Institutions and Organizations occurred;
{Subclause 266.2.2 of clause 266.2 of Article 266 is supplemented by subparagraph "i" in accordance with Law No. 1797-VIII of 21.12.2016 }
j) non-residential real estate objects of state and municipal Olympic training centers, schools of higher sports skills, centers for physical health of the population, centers for the development of physical culture and sports for people with disabilities, children's and youth sports schools, as well as Olympic training centers, schools of higher sports skills, children's and youth sports schools and sports facilities of all-Ukrainian physical culture and sports societies, their local branches and separate divisions, which are non-profit and included in the Register of non-profit institutions and organizations. In the event of exclusion of such institutions and organizations from the Register of non-profit institutions and organizations, the declaration is submitted by the taxpayer within 30 calendar days from the date of exclusion, and the tax is paid starting from the month following the month in which the exclusion from the Register of non-profit institutions and organizations occurred;
{Subclause 266.2.2 of clause 266.2 of Article 266 is supplemented by subparagraph "y" in accordance with Law No. 1797-VIII of 21.12.2016 }
j) non-residential real estate objects of Olympic and Paralympic training bases. The list of such bases is approved by the Cabinet of Ministers of Ukraine;
{Subclause 266.2.2 of clause 266.2 of Article 266 is supplemented by subparagraph "k" in accordance with Law No. 1797-VIII of 21.12.2016 }
l) residential real estate owned by large or foster families raising five or more children.
{Subclause 266.2.2 of clause 266.2 of Article 266 is supplemented by subparagraph "l" in accordance with Law No. 1797-VIII of 21.12.2016 }
266.3. Tax base
266.3.1. The tax base is the total area of a residential and non-residential real estate object, including its shares.
266.3.2. The tax base for residential and non-residential real estate, including their shares owned by individuals, is calculated by the controlling body based on data from the State Register of Real Rights to Real Estate, which is provided free of charge by the state registration bodies of rights to real estate and/or based on the originals of the relevant documents of the taxpayer, in particular documents on the right of ownership.
266.3.3. The tax base for residential and non-residential real estate, including their shares owned by legal entities, is calculated by such entities independently based on the total area of each individual tax object on the basis of documents confirming ownership of such object.
266.4. Tax benefits
266.4.1. The tax base of a residential real estate object/objects, including their shares owned by an individual taxpayer, is reduced:
a) for an apartment/apartments, regardless of their number - per 60 sq. meters;
b) for a residential building/buildings, regardless of their number - per 120 sq. meters;
c) for various types of residential real estate objects, including their shares (in the case of simultaneous ownership by the taxpayer of an apartment/apartments and a residential building/buildings, including their shares), - for 180 sq. meters.
Such a reduction is granted once for each basic tax (reporting) period (year).
{Paragraph six of subparagraph 266.4.1 of paragraph 266.4 of Article 266 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
266.4.2. Village, town, and city councils shall establish tax exemptions paid in the relevant territory on residential and/or non-residential real estate owned by individuals or legal entities, public associations, charitable organizations, and religious organizations of Ukraine, the statutes (regulations) of which are registered in accordance with the procedure established by law, and are used to ensure the activities provided for by such statutes (regulations).
Tax benefits paid in the relevant territory on residential and non-residential real estate are determined for individuals based on their property status and income level.
Benefits from the tax paid in the relevant territory on non-residential real estate are established depending on the property that is the object of taxation.
{Paragraph four of subparagraph 266.4.2 of paragraph 266.4 of Article 266 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
Village, town, city councils have the right to establish tax benefits paid on the relevant territory from non-residential real estate objects located on the territory of an industrial park and owned by participants of an industrial park included in the Register of Industrial Parks. Such decisions are not subject to subparagraph 4.1.9 of paragraph 4.1 and paragraph 4.5 of Article 4, subparagraphs 12.3.3 and 12.3.4 of paragraph 12.3, subparagraph 12.4. 3 of paragraph 12.4 (in terms of the term of adoption and entry into force of decisions) and paragraph 12.5 (in terms of the term of entry into force of decisions) of Article 12 of this Code and the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity.
{Subparagraph 266.4.2 of paragraph 266.4 of Article 266 is supplemented by the fifth paragraph in accordance with Law No. 2330-IX of 06/21/2022 - for entry into force, see paragraph 1 of Section II of Law No. 2330-IX of 06/21/2022 }
{Subclause 266.4.2 of Clause 266.4 of Article 266 as amended by Laws No. 652-VIII of 17.07.2015 , No. 909-VIII of 24.12.2015 ; as amended by Law No. 1797-VIII of 21.12.2016 }
266.4.3. Tax benefits provided for in subparagraphs 266.4.1 and 266.4.2 of this paragraph shall not apply to individuals:
object(s) of taxation, if the area of such object(s) exceeds five times the size of the non-taxable area established by subparagraph 266.4.1 of this paragraph;
object/objects of taxation used by their owners for the purpose of generating income (rented, leased, loaned, used in entrepreneurial activities).
{Clause 266.4 of Article 266 is supplemented by subparagraph 266.4.3 in accordance with Law No. 1797-VIII of 21.12.2016 }
266.5. Tax rate
266.5.1. Tax rates for residential and/or non-residential real estate owned by individuals and legal entities are established by decision of the village, settlement, city council, depending on the location (zoning) and types of such real estate in an amount not exceeding 1.5 percent of the minimum wage established by law as of January 1 of the reporting (tax) year, per 1 square meter of tax base.
{Subclause 266.5.1 of Clause 266.5 of Article 266 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 1791-VIII of 12/20/2016 }
266.6. Tax period
266.6.1. The basic tax (reporting) period is equal to the calendar year.
266.7. Procedure for calculating the tax amount
266.7.1. The calculation of the amount of tax on residential real estate property/properties owned by individuals is carried out by the controlling body at the place of the tax address (place of registration) of the owner of such real estate in the following order:
a) if the taxpayer owns one residential real estate object, including its share, the tax is calculated based on the tax base reduced in accordance with subparagraphs "a" or "b" of subparagraph 266.4.1 of paragraph 266.4 of this article, and the corresponding tax rate;
{Subparagraph "a" of subparagraph 266.7.1 of paragraph 266.7 of Article 266 as amended by Law No. 909-VIII of 24.12.2015 }
b) if the taxpayer owns more than one residential real estate object of the same type, including their shares, the tax is calculated based on the total total area of such objects, reduced in accordance with subparagraphs "a" or "b" of subparagraph 266.4.1 of paragraph 266.4 of this article, and the corresponding tax rate;
{Subparagraph "b" of subparagraph 266.7.1 of paragraph 266.7 of Article 266 as amended by Law No. 909-VIII of 24.12.2015 }
c) if the taxpayer owns residential real estate of various types, including their shares, the tax is calculated based on the total total area of such objects, reduced in accordance with subparagraph "c" of subparagraph 266.4.1 of paragraph 266.4 of this article, and the corresponding tax rate;
{Subparagraph "c" of subparagraph 266.7.1 of paragraph 266.7 of Article 266 as amended by Law No. 909-VIII of 24.12.2015 }
d) the amount of tax calculated taking into account subparagraphs "b" and "c" of this subparagraph shall be distributed by the controlling body in proportion to the specific weight of the total area of each of the residential real estate objects.
{Sub-clause "d" of subparagraph 266.7.1 of clause 266.7 of Article 266 as amended by Law No. 909-VIII of 24.12.2015 }
{Sub-paragraph "g" of subparagraph 266.7.1 of paragraph 266.7 of Article 266 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
The calculation of the amount of tax on non-residential real estate owned by individuals is carried out by the regulatory authority at the location of the tax address (place of registration) of the owner of such real estate based on the total area of each non-residential real estate and the corresponding tax rate.
266.7.1 - 1. If the taxpayer owns a residential real estate object (objects), including its share, owned by an individual or legal entity - the taxpayer, the total area of which exceeds 300 square meters (for an apartment) and/or 500 square meters (for a house), the amount of tax calculated in accordance with subparagraphs "a" - "g" of subparagraph 266.7.1 of this paragraph shall be increased by 25,000 hryvnias per year for each such residential real estate object (its share).
{Clause 266.7 of Article 266 is supplemented by subparagraph 266.7.1 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
266.7.2. Tax notices/tax decisions on payment of the amount/amounts of tax calculated in accordance with subparagraph 266.7.1 of paragraph 266.7 of this article, together with a detailed calculation of the amount/amounts of tax, and the relevant payment details, in particular, of local government bodies at the location of each of the residential and/or non-residential real estate objects, shall be sent to the taxpayer by the controlling body in the manner specified in Article 42 of this Code, by July 1 of the year following the base tax (reporting) period (year).
{Paragraph one of subparagraph 266.7.2 of paragraph 266.7 of Article 266 as amended by Laws No. 466-IX of January 16, 2020 , No. 1914-IX of November 30, 2021 }
Tax notices/tax decisions on payment of the tax amount/amounts and the relevant payment details specified in the first paragraph of this sub-item, sent to the taxpayer, must contain, for each residential and/or non-residential real estate object, in particular, but not exclusively, information on the address of the residential and/or non-residential real estate object, its area, rates and benefits provided to individuals for payment of tax on real estate other than land.
{Subparagraph 266.7.2 of paragraph 266.7 of Article 266 is supplemented with a new paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
Regarding a newly created (newly introduced) residential and/or non-residential real estate object, the tax is paid by the individual payer starting from the month in which the right of ownership to such object arose.
The supervisory authorities at the place of residence (registration) of taxpayers shall, within ten days, inform the relevant supervisory authorities at the location of residential and/or non-residential real estate objects about the tax notices-decisions on tax payment sent (delivered) to the taxpayer in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph of subparagraph 266.7.2 of paragraph 266.7 of Article 266 as amended by Law No. 1797-VIII of 21.12.2016 }
Tax assessment and sending (delivery) of tax notices-decisions on tax payment to non-resident individuals are carried out by the regulatory authorities at the location of residential and/or non-residential real estate owned by such non-residents.
266.7.3. Taxpayers have the right to submit a written application to the supervisory authority at their tax address for data reconciliation regarding:
residential and/or non-residential real estate objects, including their shares, owned by the taxpayer;
the size of the total area of residential and/or non-residential real estate owned by the taxpayer;
the right to use tax relief;
the size of the tax rate;
the amount of tax charged.
In case of discrepancies between the data of the controlling authorities and the data confirmed by the taxpayer on the basis of the originals of the relevant documents, in particular documents on the right of ownership, the controlling authority shall recalculate the tax amount at the taxpayer's tax address and send (hand over) a new tax notice-decision to him. The previous tax notice-decision shall be considered canceled (withdrawn).
{Subclause 266.7.3 of Clause 266.7 of Article 266 as amended by Law No. 466-IX of 16.01.2020 }
266.7.4. The bodies of state registration of rights to real estate shall be obliged, within 15 days after the end of the tax (reporting) quarter, to submit to the central executive body implementing the state tax policy the information necessary for the calculation and collection of tax by individuals and legal entities, as of the first day of the relevant quarter in accordance with the procedure determined by the Cabinet of Ministers of Ukraine. The central executive body implementing the state policy in the field of migration (immigration and emigration), including counteraction to illegal (illegal) migration, citizenship, registration of individuals, refugees and other categories specified by law, shall provide information within the time limits and in accordance with the procedure established by subparagraph 70.16.7 - 1 of paragraph 70.16 of Article 70 of this Code.
{Paragraph one of subparagraph 266.7.4 of paragraph 266.7 of Article 266 as amended by Law No. 3050-IX of 11.04.2023 }
In the event that a taxpayer submits to the controlling body title documents for real estate, information about which is not available in the database of information systems of the central executive body implementing state tax policy, tax payment by individuals is carried out on the basis of the information submitted by the taxpayer until the controlling body receives information from the state registration bodies of rights to real estate on the transfer of ownership of the object of taxation.
{Subparagraph 266.7.4 of paragraph 266.7 of Article 266 is supplemented by the second paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Subclause 266.7.4 of Clause 266.7 of Article 266 as amended by Law No. 1797-VIII of 21.12.2016 }
266.7.5. Taxpayers - legal entities shall independently calculate the amount of tax as of January 1 of the reporting year and no later than February 20 of the same year shall submit to the supervisory authority at the location of the taxable object/objects a declaration in the form established in the manner provided for in Article 46 of this Code, with a breakdown of the annual amount into equal quarterly installments.
Regarding a newly created (newly introduced) residential and/or non-residential real estate object, the declaration by the legal entity - payer is submitted within 30 calendar days from the date of the emergence of the right of ownership of such object, and the tax is paid starting from the month in which the right of ownership of such object arose.
{Subclause 266.7.5 of Clause 266.7 of Article 266 as amended by Law No. 466-IX of 16.01.2020 }
266.8. Procedure for calculating tax amounts in the event of a change in the owner of a tax-taxable object
266.8.1. In the event of a transfer of ownership of a taxable object from one owner to another during a calendar year, the tax shall be calculated for the previous owner for the period from January 1 of this year to the beginning of the month in which the ownership of the specified taxable object ceased, and for the new owner - starting from the month in which he acquired ownership.
{Subclause 266.8.1 of Clause 266.8 of Article 266 as amended by Law No. 1797-VIII of 21.12.2016 }
266.8.2. The controlling authority sends a tax notice-decision to the new owner after receiving information about the transfer of ownership.
266.9. Procedure for paying tax
266.9.1. The tax is paid at the location of the taxable object/objects and is credited to the relevant budget in accordance with the provisions of the Budget Code of Ukraine .
Individuals can pay taxes in rural and urban areas through the cash desks of village (village) councils using a tax receipt.
{Paragraph two of subparagraph 266.9.1 of paragraph 266.9 of Article 266 as amended by Law No. 909-VIII of 24.12.2015 }
266.10. Tax payment deadlines
266.10.1. The tax liability for the reporting year is paid:
a) individuals - within 60 days from the date of delivery of the tax notice-decision;
b) legal entities - quarterly advance payments by the 30th of the month following the reporting quarter, which are reflected in the annual tax return.
266.10.2. If the regulatory authority has not sent (delivered) a tax/tax notice-decision within the time limits established by subparagraph 266.7.2 of paragraph 266.7 of this article, individuals are exempt from liability provided for by this Code for untimely payment of a tax liability.
{Clause 266.10 of Article 266 is supplemented by subparagraph 266.10.2 in accordance with Law No. 2245-VIII of 07.12.2017 }
266.10.3. The tax liability for this tax may be accrued for tax (reporting) periods (years) within the time limits specified in paragraph 102.1 of Article 102 of this Code.
{Clause 266.10 of Article 266 is supplemented by subparagraph 266.10.3 in accordance with Law No. 2245-VIII of 07.12.2017 }
{Article 266 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.24.2012 ; as amended by Law No. 71-VIII of 12.28.2014 }
267.1.1. Payers of transport tax are individuals and legal entities, including non-residents, who have their own passenger cars registered in Ukraine in accordance with current legislation, which, in accordance with subparagraph 267.2.1 of paragraph 267.2 of this article, are objects of taxation.
267.2. Object of taxation
267.2.1. The object of taxation is passenger cars, the year of manufacture of which is no more than five years (inclusive) and the average market value of which is more than 375 times the minimum wage established by law as of January 1 of the tax (reporting) year.
{Paragraph one of subparagraph 267.2.1 of paragraph 267.2 of Article 267 as amended by Law No. 1791-VIII of 20.12.2016
Such value is determined by the central executive body that ensures the formation and implementation of the state policy of economic, social development and trade, according to the methodology approved by the Cabinet of Ministers of Ukraine, as of January 1 of the tax (reporting) year, based on the make, model, year of manufacture, engine cylinder capacity, and type of fuel";
{Paragraph two of subparagraph 267.2.1 of paragraph 267.2 of Article 267 as amended by Law No. 1797-VIII of 21.12.2016 }
Every year, by February 1 of the tax (reporting) year, the central executive body that ensures the formation and implementation of the state policy of economic, social development and trade posts on its official website a list of passenger cars, the year of manufacture of which is no more than five years (inclusive) and the average market value of which is more than 375 times the minimum wage established by law as of January 1 of the tax (reporting) year, which must contain the following data regarding these cars: make, model, year of manufacture, engine cylinder capacity, type of fuel.
{Subclause 267.2.1 of clause 267.2 of Article 267 is supplemented by the third paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
{Subclause 267.2.1 of clause 267.2 of Article 267 as amended by Law No. 909-VIII of 24.12.2015 }
267.3. Tax base
267.3.1. The tax base is a passenger car, which is an object of taxation in accordance with subparagraph 267.2.1 of paragraph 267.2 of this article.
267.4. The tax rate is set per calendar year at 25,000 hryvnias for each passenger car that is subject to taxation in accordance with subparagraph 267.2.1 of paragraph 267.2 of this article.
267.5. Tax period
267.5.1. The base tax (reporting) period is equal to the calendar year.
267.6. Procedure for calculating and paying tax
267.6.1. The calculation of the amount of tax on the object/objects of taxation of individuals is carried out by the supervisory authority at the tax address (place of registration) of the taxpayer, specified in the registration documents for the object of taxation.
{Subclause 267.6.1 of Clause 267.6 of Article 267 as amended by Law No. 466-IX of 16.01.2020 }
267.6.2. Tax notices/tax decisions on the payment of the tax amount(s) together with a detailed calculation of the tax amount(s) and the relevant payment details shall be sent to the taxpayer by the controlling authority in accordance with the procedure specified in Article 42 of this Code by July 1 of the year of the base tax (reporting) period (year).
{Paragraph one of subparagraph 267.6.2 of paragraph 267.6 of Article 267 as amended by Laws No. 466-IX of January 16, 2020 , No. 1914-IX of November 30, 2021 }
The tax notice/tax decisions on payment of the tax amount/amounts and the corresponding payment details specified in the first paragraph of this sub-item, sent to the taxpayer, must contain, for each of the objects, in particular, but not exclusively, information about the vehicle: make, model, engine cylinder capacity (cc), year of manufacture and tax rate.
{Subparagraph 267.6.2 of paragraph 267.6 of Article 267 is supplemented with a new paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
For taxable objects acquired during the year, the tax is paid by the individual taxpayer starting from the month in which the ownership of such object arose. The supervisory authority sends a tax notice-decision to the new owner after receiving information about the transfer of ownership.
{Paragraph of subparagraph 267.6.2 of paragraph 267.6 of Article 267 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
267.6.3. Bodies carrying out state registration of vehicles are obliged, by April 1, 2015, to submit to the supervisory authorities at the place of registration of the taxable object the information necessary for the calculation and collection of tax by individuals and legal entities.
{Paragraph one of subparagraph 267.6.3 of paragraph 267.6 of Article 267 as amended by Law No. 1293-IX of 02.03.2021 }
From April 1, 2015, bodies carrying out state registration of vehicles are obliged to submit to the supervisory authorities, within ten days after the end of the calendar month, the information necessary for the calculation and collection of tax by individuals and legal entities at the place of registration of the taxable object as of the first day of the relevant month.
{Paragraph two of subparagraph 267.6.3 of paragraph 267.6 of Article 267 as amended by Law No. 2611-VIII of 08.11.2018 }
The form of information submission is established by the central executive body that ensures the formation and implementation of state financial policy.
{Subclause 267.6.3 of clause 267.6 of Article 267 as amended by Law No. 1797-VIII of 21.12.2016 }
267.6.4. Taxpayers - legal entities shall independently calculate the amount of tax as of January 1 of the reporting year and no later than February 20 of the same year shall submit to the supervisory authority at the place of registration of the taxable object a declaration in the form established in the manner provided for in Article 46 of this Code, with a breakdown of the annual amount into equal quarterly installments.
{Paragraph one of subparagraph 267.6.4 of paragraph 267.6 of Article 267 as amended by Law No. 466-IX of January 16, 2020 }
Regarding taxable objects acquired during the year, the declaration by the legal entity - payer is submitted within a month from the date of the emergence of the right of ownership of such an object, and the tax is paid starting from the month in which the right of ownership of such an object arose.
267.6.5. In the event of the transfer of ownership of a taxable object from one owner to another during the reporting year, the tax shall be calculated by the previous owner for the period from January 1 of this year to the beginning of the month in which he lost ownership of the specified taxable object, and by the new owner - starting from the month in which he acquired ownership of this object.
The controlling authority sends a tax notice-decision to the new owner after receiving information about the transfer of ownership.
267.6.6. For taxable items purchased during the year, tax is paid in proportion to the number of months remaining until the end of the year, starting from the month in which the vehicle was registered.
267.6.7. In the event that a passenger car reaches the age of five years during the reporting year, the tax shall be paid for the period from January 1 of this year to the beginning of the month following the month in which the age of such car reached (will reach) five years.
{Clause 267.6 of Article 267 was supplemented by subparagraph 267.6.7 in accordance with Law No. 909-VIII of 24.12.2015 }
267.6.8. In the event of illegal seizure by a third party of a passenger car, which in accordance with subparagraph 267.2.1 of paragraph 267.2 of this article is an object of taxation, the transport tax for such a passenger car shall not be paid from the month following the month in which the fact of illegal seizure of the passenger car occurred, if such fact is confirmed by a relevant document on entering information on the commission of a criminal offense into the Unified Register of Pre-Trial Investigations, issued by an authorized state body.
In the event of the return of a passenger car to its owner (legal possessor), the tax for such a passenger car shall be paid from the month in which the passenger car was returned in accordance with the resolution of the investigator, prosecutor or court decision. The taxpayer shall be obliged to provide the supervisory authority with a copy of such resolution (decision) within 10 days from the date of receipt.
{Clause 267.6 of Article 267 is supplemented by subparagraph 267.6.8 in accordance with Law No. 909-VIII of 24.12.2015 }
267.6.9. In the event of illegal possession by a third party of a passenger car, which, in accordance with subparagraph 267.2.1 of paragraph 267.2 of this article, is an object of taxation, a clarifying declaration by the legal entity - taxpayer shall be submitted within 30 calendar days from the date of entry of information on the commission of a criminal offense into the Unified Register of Pre-Trial Investigations.
In the event of the return of a passenger car to its owner, a clarifying declaration by a legal entity - a taxpayer shall be submitted within 30 calendar days from the date of the investigator's or prosecutor's decision or the court's ruling.
{Clause 267.6 of Article 267 is supplemented by subparagraph 267.6.9 in accordance with Law No. 909-VIII of 24.12.2015 }
267.6.10. Individuals - taxpayers have the right to apply with a written application to the regulatory authority at their tax address (place of registration) for a reconciliation of data regarding:
{Paragraph one of subparagraph 267.6.10 of paragraph 267.6 of Article 267 as amended by Law No. 466-IX of January 16, 2020 }
a) taxable objects owned by the taxpayer;
b) the amount of the tax rate;
c) the amount of tax charged.
In case of discrepancies between the data of the controlling bodies and the data confirmed by the taxpayer on the basis of the originals of the relevant documents (in particular, documents confirming the right of ownership of the taxable object, the transfer of ownership of the taxable object), the controlling body at the place of registration of the taxpayer shall recalculate the amount of tax and send (hand) him a new tax notice-decision. The previous tax notice-decision shall be considered canceled (withdrawn).
{Paragraph five of subparagraph 267.6.10 of paragraph 267.6 of Article 267 as amended by Law No. 1797-VIII of 21.12.2016 }
Non-resident individuals, in accordance with the procedure specified in this paragraph, apply for data reconciliation to the regulatory authorities at the place of registration of taxable objects.
{Clause 267.6 of Article 267 is supplemented by subparagraph 267.6.10 in accordance with Law No. 909-VIII of 24.12.2015 }
267.7. Procedure for paying tax
267.7.1. The tax is paid at the place of registration of taxable objects and is credited to the relevant budget in accordance with the provisions of the Budget Code of Ukraine .
267.8. Tax payment deadlines
267.8.1. Transport tax is paid:
a) individuals - within 60 days from the date of delivery of the tax notice-decision;
b) legal entities - quarterly advance payments by the 30th of the month following the reporting quarter, which are reflected in the annual tax return";
{Article 267 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4014-VI of 04.11.2011 , No. 5083-VI of 05.07.2012 , No. 5412-VI of 02.10.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
268.1. Tourist tax is a local tax, the funds from which are credited to the local budget.
268.2. Taxpayers
268.2.1. Tax payers are citizens of Ukraine, foreigners, as well as stateless persons who arrive in the territory of an administrative-territorial unit where the decision of the village, settlement, or city council on the establishment of a tourist tax is in effect, and are temporarily accommodated in places of residence (overnight stay) specified in subparagraph 268.5.1 of paragraph 268.5 of this article.
{Subclause 268.2.1 of Clause 268.2 of Article 268 as amended by Laws No. 909-VIII of 12/24/2015 , No. 2628-VIII of 11/23/2018 }
268.2.2. Persons who: cannot be fee payers
a) permanently reside, including under rental agreements, in a village, settlement or city whose councils have established such a fee;
b) persons defined in subparagraph "c" of subparagraph 14.1.213 of clause 14.1 of Article 14 of this Code, who have arrived on a business trip or are temporarily accommodated in places of residence (overnight stay) defined in subparagraph "b" of subparagraph 268.5.1 of clause 268.5 of this Article, which belong to individuals on the right of ownership or on the right of use under a lease agreement;
{Subparagraph "b" of subparagraph 268.2.2 of paragraph 268.2 of Article 268 as amended by Law No. 2628-VIII of 23.11.2018 }
c) persons with disabilities, children with disabilities and persons accompanying persons with disabilities of group I or children with disabilities (no more than one accompanying person);
d) war veterans;
e) participants in the liquidation of the consequences of the accident at the Chernobyl NPP;
e) persons who arrived on vouchers (course tickets) for treatment, recovery, rehabilitation to medical and preventive, physical culture and health-improving and sanatorium-resort institutions that have a license for medical practice and accreditation by the central executive body that implements state policy in the field of healthcare;
e) children under 18 years of age;
g) children's medical and preventive, physical education and health-improving and sanatorium-resort institutions;
g) family members of an individual of the first and/or second degree of kinship, determined in accordance with subparagraph 14.1.263 of paragraph 14.1 of Article 14 of this Code, who are temporarily accommodated by such individual in places of residence (overnight stay) determined by subparagraph "b" of subparagraph 268.5.1 of paragraph 268.5 of this Article, which belong to him by right of ownership or by right of use under a lease agreement;
{Subclause 268.2.2 of clause 268.2 of Article 268 is supplemented by subparagraph "g" in accordance with Law No. 2628-VIII of 23.11.2018 }
h) registered as internally displaced persons in accordance with the Law of Ukraine "On Ensuring the Rights and Freedoms of Internally Displaced Persons", who are temporarily accommodated in places of residence (accommodation) specified in subparagraph 268.5.1 of paragraph 268.5 of this article, and information about the address of such places is indicated in the certificate of registration of an internally displaced person as the address of their actual place of residence/stay.
{Subclause 268.2.2 of clause 268.2 of Article 268 is supplemented by subparagraph "z" in accordance with Law No. 905-IX of 17.09.2020 }
268.3. Fee rate
268.3.1. The fee rate is established by decision of the relevant village, settlement, city council for each day of temporary accommodation of a person in places of residence (overnight stay) specified in subparagraph 268.5.1 of paragraph 268.5 of this article, in the amount of up to 0.5 percent - for domestic tourism and up to 5 percent - for inbound tourism of the minimum wage established by law as of January 1 of the reporting (tax) year, for one person per day of temporary accommodation.
{Clause 268.3 of Article 268 as amended by Law No. 2628-VIII of 23.11.2018 }
268.4. Object and basis for collection of the fee
268.4.1. The object of the fee is the places of residence (overnight stay) defined by subparagraph 268.5.1 of paragraph 268.5 of this article.
The basis for charging the fee is the total number of days of temporary accommodation in places of residence (overnight stay) determined by subparagraph 268.5.1 of paragraph 268.5 of this article.
Day - the period between two consecutive settlement hours, equal to 24 hours.
Check-out time - the hour set at the place of residence (overnight stay), at which the consumer must vacate the room (place) on the day of departure and after which check-in to the place of residence (overnight stay) is carried out.
{Clause 268.4 of Article 268 as amended by Laws No. 2628-VIII of 11/23/2018 , No. 3813-IX of 06/18/2024 }
268.5. Tax agents and places of residence (overnight stays)
268.5.1. According to the decision of the village, settlement, city council, the fee may be collected for temporary accommodation in the following places of residence (overnight stay):
a) hotels, campsites, motels, hostels for visitors, hostels, holiday homes, tourist bases, mountain shelters, holiday camps, boarding houses and other hotel-type establishments, sanatoriums and resort establishments;
b) a residential building, an extension to a residential building, an apartment, a cottage, a room, a garden house, a summer house, any other objects used for temporary residence (overnight stay).
268.5.2. According to the decision of the village, settlement, city council, the collection of the fee may be carried out by the following tax agents:
a) legal entities, branches, departments, other separate subdivisions of legal entities in accordance with subparagraph 268.7.2 of paragraph 268.7 of this article, natural persons - entrepreneurs who provide services for temporary accommodation of persons in places of residence (overnight stay) specified in subparagraph 268.5.1 of this article;
b) housing intermediary organizations that send unorganized persons for the purpose of their temporary accommodation in places of residence (overnight stay) specified in subparagraph "b" of subparagraph 268.5.1 of paragraph 268.5 of this article, which belong to individuals on the right of ownership or on the right of use under a rental agreement;
c) legal entities authorized by a village, settlement, or city council to collect the fee under the terms of an agreement concluded with the relevant council.
The list of tax agents and information about them are posted and published on the official website of the village, settlement, or city council.
{Clause 268.5 of Article 268 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 2628-VIII of 11/23/2018 }
268.6. Peculiarities of collecting the fee
268.6.1. Tax payers shall pay the amount of the tax in advance before temporary accommodation in places of residence (overnight stay) to tax agents who collect the tax at the rates, at the places of collection of the tax and in compliance with other requirements determined by the decision of the relevant village, settlement, city council.
For the same period of stay of a fee payer on the territory of one administrative-territorial unit where a tourist fee is established, repeated collection of a fee already paid by such a fee payer is not allowed.
268.6.2. A person shall temporarily accommodate a fee payer in places of residence (accommodation) owned by such person or with the right of use, only if the fee payer has a document confirming his payment of the tourist fee in accordance with this Code and the decision of the relevant village, settlement, or city council.
268.6.3. In the event of early departure by a person who has paid a tourist tax from the territory of the administrative-territorial unit in which the tourist tax is established, the amount of the excessively paid tax shall be refunded to such person in the manner established by this Code";
{Clause 268.6 of Article 268 as amended by Law No. 2628-VIII of 11/23/2018 }
268.7. Procedure for payment of the fee
268.7.1. Tax agents shall pay the fee at their location quarterly, within the period specified for the quarterly reporting (tax) period and in accordance with the tax declaration for the reporting (tax) quarter, or in advance payments by the 30th (inclusive) of each month (in February - by the 28th (29th) inclusive) based on the decision of the relevant village, settlement, city council.
Tax agents who pay the fee in advance payments shall reflect in the tax return for the reporting (tax) quarter the amounts of accrued monthly advance payments. In this case, the final amount of the fee, calculated in accordance with the tax return for the reporting (tax) quarter (taking into account the actually made advance payments), shall be paid by such tax agents within the terms specified for the quarterly reporting (tax) period.
{Subparagraph 268.7.1 of paragraph 268.7 of Article 268 as amended by Law No. 2628-VIII of 23.11.2018 }
268.7.2. A tax agent that has a subdivision without the status of a legal entity that provides temporary accommodation services in places of residence (overnight stay) other than at the place of registration of such tax agent is obliged to register such subdivision as a tourist tax tax agent with the supervisory authority at the location of the subdivision.
{Subclause 268.7.2 of Clause 268.7 of Article 268 as amended by Law No. 2628-VIII of 23.11.2018 }
268.7.3. The basic tax (reporting) period is equal to a calendar quarter.
{Article 268 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.05.2012 , No. 5083-VI of 05.07.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
Article 268 - 1. Fee for parking spaces for vehicles↑
268 - 1 .1. Taxpayers
268 - 1 .1.1. Payers of the fee are legal entities, their branches (departments, representative offices), individual entrepreneurs who, in accordance with the decision of the village, settlement, city council, organize and carry out activities to ensure parking of vehicles in paid parking lots and specially designated parking lots.
{Subclause 268 - 1 .1.1 of clause 268 - 1 .1 of article 268 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
268 - 1 .1.2. The list of special land plots allocated for the organization and implementation of activities to ensure vehicle parking, which indicates their location, total area, technical equipment, number of parking spaces for vehicles, is approved by the decision of the village, settlement, city council on establishing a fee.
{Paragraph one of subparagraph 268 - 1 .1.2 of paragraph 268 - 1 .1 of Article 268 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
Such a decision, together with a list of persons authorized to organize and conduct activities to ensure parking of vehicles, shall be provided by the executive body of the village, settlement, or city council to the supervisory body in accordance with the procedure established by Section I of this Code.
{Paragraph two of subparagraph 268 - 1 .1.2 of paragraph 268 - 1 .1 of Article 268 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
268 - 1 .2. Object and base of taxation by the fee
268 - 1 .2.1. The object of taxation is a land plot that, according to the decision of the village, settlement, city council, is specially allocated to ensure parking of vehicles on public roads, sidewalks or other places, as well as communal garages, parking lots, parking lots (buildings, structures, parts thereof) that are built at the expense of the local budget, with the exception of the area of the land plot that is allocated for free parking of vehicles, provided for in Article 30 of the Law of Ukraine "On the Fundamentals of Social Protection of Persons with Disabilities in Ukraine".
{Subclause 268 - 1 .2.1 of clause 268 - 1 .2 of article 268 - 1 as amended by Laws No. 909-VIII of 12/24/2015 , No. 344-IX of 12/05/2019 }
268 - 1 .2.2. The tax base is the area of the land plot allocated for parking, as well as the area of municipal garages, parking lots, parking lots (buildings, structures, their parts) that are built at the expense of the local budget.
268 - 1 .3. Collection rates
268 - 1 .3.1. Fee rates are set for each day of vehicle parking activities in hryvnias per 1 sq. meter of land area allocated for the organization and conduct of such activities, in the amount of up to 0.075 percent of the minimum wage established by law as of January 1 of the tax (reporting) year.
{Subclause 268 - 1 .3.1 of clause 268 - 1 .3 of article 268 - 1 as amended by Law No. 1791-VIII of 20.12.2016 }
268 - 1 .3.2. When determining the fee rate, village, town, and city councils shall take into account the location of specially designated parking spaces for vehicles, the area of the specially designated space, the number of parking spaces for vehicles, the method of parking vehicles, the operating mode, and their occupancy.
{Subclause 268 - 1 .3.2 of clause 268 - 1 .3 of article 268 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
268 - 1 .4. Features of the collection establishment
268 - 1 .4.1. The fee rate and the procedure for paying the fee to the budget are established by the relevant village, settlement, city council.
{Subclause 268 - 1 .4.1 of clause 268 - 1 .4 of article 268 - 1 as amended by Law No. 909-VIII of 24.12.2015 }
268 - 1 .5. Procedure for calculation and payment of the fee
268 - 1 .5.1. The amount of the fee for parking spaces for vehicles, calculated in accordance with the tax return for the reporting (tax) quarter, is paid quarterly, within the period specified for the quarterly reporting (tax) period, at the location of the taxable object.
268 - 1 .5.2. A fee payer who has a subdivision without the status of a legal entity that carries out activities to provide parking for vehicles on a land plot other than at the place of registration of such fee payer is obliged to register such subdivision as a fee payer with the regulatory authority at the location of the land plot.
268 - 1 .5.3. The basic tax (reporting) period is equal to the calendar quarter.
{The Code is supplemented by Article 268 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
{The words "Chapter XIII. Land Fee" were excluded pursuant to Law No. 71-VIII of 28.12.2014 }
{Title of Article 269 as amended by Laws No. 71-VIII of 12/28/2014 , No. 1914-IX of 11/30/2021 }
269.1. Payers of land fees are:
269.1.1. land tax payers:
269.1.1.1. owners of land plots, land shares (shares);
269.1.1.2. land users who, in accordance with the law, have been granted land plots of state and municipal ownership for use on the rights of permanent use;
269.1.2. rent payers - land users (lessees) of land plots of state and municipal property under lease terms.
{Clause 269.1 of Article 269 as amended by Law No. 1914-IX of 11/30/2021 }
269.2. The specifics of tax collection by business entities that apply a simplified system of taxation, accounting and reporting are established by Chapter 1 of Section XIV of this Code.
{Article 269 was supplemented by paragraph 269.2 in accordance with Law No. 4014-VI of 04.11.2011 }
{Title of Article 271 as amended by Laws No. 71-VIII of 12/28/2014 , No. 1914-IX of 11/30/2021 }
271.1. The tax base is:
271.1.1. normative monetary valuation of the land plot taking into account the indexation coefficient determined in accordance with the procedure established by this section;
271.1.2. area of land plot, the normative monetary valuation of which has not been carried out.
The tax base for land shares (units) is determined according to the data of land plots to which individuals have the right as owners of land shares (units), taking into account subparagraphs 271.1.1 and 271.1.2 of this paragraph.
{Clause 271.1 of Article 271 as amended by Law No. 1914-IX of 11/30/2021 }
271.2. The decision of the councils on the normative monetary valuation of land plots shall be officially published by the relevant local government body by July 15 of the year preceding the budget period in which the normative monetary valuation of land or changes are planned to be applied (planning period). Otherwise, the norms of the relevant decisions shall be applied no earlier than the beginning of the budget period following the planning period.
The provisions of this paragraph do not apply to decisions of councils regarding the normative monetary valuation of land plots of state and municipal property located outside settlements that are leased, the normative monetary valuation of which has not previously been carried out and/or has not been approved in accordance with the procedure established by law, and provided that the amount of such normative monetary valuation of land plots exceeds the amount of the normative monetary valuation of the corresponding arable land area in the region.
{Clause 271.2 of Article 271 is supplemented by the second paragraph in accordance with Law No. 4015-IX of 10.10.2024 }
The decisions of the councils specified in paragraph two of this paragraph shall be published by the local government body no later than 10 days from the date of adoption of the relevant decision and shall be applied from the first day of the second month following the month of adoption of such decision.
{Clause 271.2 of Article 271 is supplemented by the third paragraph in accordance with Law No. 4015-IX of 10.10.2024 }
{Article 271 is supplemented by paragraph 271.2 in accordance with Law No. 4834-VI of 24.05.2012 ; as amended by Laws No. 71-VIII of 28.12.2014 , No. 2628-VIII of 23.11.2018 }
Article 272. {Article 272 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }↑
Article 273. Taxation of land plots provided on forestry lands (regardless of location) by land tax↑
{Title of Article 273 as amended by Law No. 71-VIII of 28.12.2014 }
273.1. The tax on forest land consists of a land tax and a rental fee, which is determined by tax legislation.
{Clause 273.1 of Article 273 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 2497-VIII of 10.07.2018 }
273.2. Tax rates per hectare of non-forest land provided in accordance with the established procedure and used for forestry purposes shall be established in accordance with Article 274 of this Code.
{Clause 273.2 of Article 273 as amended by Law No. 71-VIII of 28.12.2014 }
{Subclause 273.2.1 of clause 273.2 of Article 273 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subparagraph 273.2.2 of paragraph 273.2 of Article 273 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
273.3. Tax rates per hectare of forest land are established in accordance with Articles 274 and 277 of this Code.
{Article 273 is supplemented by paragraph 273.3 in accordance with the Law No. 2497-VIII dated 10.07.2018 }
Article 274. Land tax rate for land plots, including the rights to which individuals have as owners of land shares (shares), the normative monetary valuation of which has been carried out (regardless of location)↑
274.1. The tax rate for land plots, including those to which individuals have the right as owners of land shares (shares), the normative monetary assessment of which has been carried out, is set at no more than 3 percent of their normative monetary assessment, for public lands - no more than 1 percent of their normative monetary assessment, for agricultural lands - no less than 0.3 percent and no more than 1 percent of their normative monetary assessment, and for forest lands - no more than 0.1 percent of their normative monetary assessment.
274.2. The tax rate is set at no more than 12 percent of their normative monetary valuation for land plots that are in permanent use by business entities (except for state and municipal forms of ownership).
{Article 274 as amended by Laws No. 4834-VI dated 05/24/2012 , No. 71-VIII dated 12/28/2014 , No. 909-VIII dated 12/24/2015 , No. 1791-VIII dated 12/20/2016 , No. 2628-VIII dated 11/23/2018 ; as amended by Law No. 1914-IX dated 11/30/2021 ; as amended by Law No. 4536-IX dated 07/16/2025 ; as amended by Law No. 4577-IX dated 21.08.2025 }
Article 275. {Article 275 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }↑
Article 276. {Article 276 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }↑
Article 277. Land tax rates for land plots, including the rights to which individuals have as owners of land shares (shares), the normative monetary valuation of which has not been carried out↑
277.1. The tax rate for land plots, including those to which individuals have the right as owners of land shares (shares), located outside settlements or within settlements, is set at no more than 5 percent of the normative monetary valuation of a unit of arable land area in the Autonomous Republic of Crimea or in the region, for agricultural lands - no less than 0.3 percent and no more than 5 percent of the normative monetary valuation of a unit of arable land area in the Autonomous Republic of Crimea or in the region, and for forest lands - no more than 0.1 percent of the normative monetary valuation of arable land area in the Autonomous Republic of Crimea or in the region.
{Article 277 as amended by Laws No. 4834-VI dated 05/24/2012 , No. 71-VIII dated 12/28/2014 , No. 1791-VIII dated 12/20/2016 ; as amended by Laws No. 2628-VIII dated 11/23/2018 , No. 1914-IX dated 11/30/2021 ; as amended by Law No. 4536-IX dated 07/16/2025 ; as amended by Law No. 4577-IX dated 21.08.2025 }
Article 278. {Article 278 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }↑
Article 279. {Article 279 was excluded based on Law No. 71-VIII of 28.12.2014 }↑
Article 280. {Article 280 was excluded based on Law No. 71-VIII of 28.12.2014 }↑
Article 281. Benefits for payment of land tax for individuals↑
{Title of Article 281 as amended by Law No. 71-VIII of 28.12.2014 }
281.1. The following are exempt from paying tax:
281.1.1. persons with disabilities of the first and second groups;
281.1.2. individuals raising three or more children under the age of 18;
281.1.3. pensioners (by age);
281.1.4. war veterans and persons subject to the Law of Ukraine "On the Status of War Veterans, Guarantees of Their Social Protection" ;
281.1.5. individuals recognized by law as persons who suffered as a result of the Chernobyl disaster.
281.2. Exemption from paying tax on land plots, provided for the relevant category of individuals by paragraph 281.1 of this article, applies to land plots for each type of use within the limits of the following norms:
{Paragraph one of clause 281.2 of Article 281 as amended by Law No. 2245-VIII of 07.12.2017 }
281.2.1. for personal farming - no more than 2 hectares;
281.2.2. for the construction and maintenance of a residential building, outbuildings and structures (homestead plot): in villages - no more than 0.25 hectares, in settlements - no more than 0.15 hectares, in cities - no more than 0.10 hectares;
281.2.3. for individual summer cottage construction - no more than 0.10 hectares;
281.2.4. for the construction of individual garages - no more than 0.01 hectares;
281.2.5. for gardening - no more than 0.12 hectares.
281.3. Owners of land plots, land shares (shares) and land users are exempt from paying tax for the period of validity of the single tax of the fourth group, provided that the land plots and land shares (shares) are transferred for lease or use on other terms (including emphyteusis terms) to a payer of the single tax of the fourth group.
{Article 281 is supplemented by paragraph 281.3 in accordance with Law No. 3609-VI of 07.07.2011 ; as amended in accordance with Laws No. 71-VIII of 28.12.2014 , No. 4536-IX dated 16.07.2025 }
281.4. If an individual specified in clause 281.1 of this article, as of January 1 of the current year, owns several land plots of the same type of use, the area of which exceeds the limits of the maximum norms specified in clause 281.2 of this article, such person shall, by May 1 of the current year, submit a written application in any form to the regulatory body at the location of any land plot for independent selection/change of land plots for the application of the benefit (hereinafter referred to as the application for the benefit).
The benefit begins to apply to selected land plots from the base tax (reporting) period in which such an application is submitted, and is valid until the beginning of the month following the month of submission of a new application for the benefit.
In the event that an individual who owns several land plots of the same type of use as of January 1 of the current year submits an application for the benefit after May 1 of the current year, the benefit will begin to apply to the selected land plots from the next tax (reporting) period.
{ Article 281 is supplemented by paragraph 281.4 in accordance with the Law No. 1797-VIII dated 21.12.2016 ; as amended by Law No. 466-IX dated 16.01.2020 }
281.5. If the right to a benefit for an individual who owns several land plots of the same type of use arises during a calendar year and/or the individual specified in clause 281.1 of this article acquires the right to ownership of a land plot/plots of the same type of use, such person shall submit an application for the benefit to the regulatory body at the location of any land plot within 30 calendar days from the date of acquisition of such right to a benefit and/or ownership.
The benefit begins to apply to selected land plots, taking into account the requirements of paragraph 284.2 of Article 284 of this Code and is valid until the beginning of the month following the month of submission of a new application for the benefit.
In the event of failure by an individual to comply with the requirements of paragraph one of this paragraph, the benefit shall begin to apply to the selected land plots from the next tax (reporting) period.
{ Article 281 is supplemented by paragraph 281.5 in accordance with the Law No. 466-IX dated 16.01.2020 }
282.1.1. sanatoriums and health resorts of public associations of persons with disabilities, rehabilitation institutions of public associations of persons with disabilities;
282.1.2. public associations of persons with disabilities of Ukraine, enterprises and organizations that are founded by public associations of persons with disabilities and unions of public associations of persons with disabilities and are their full property, where during the previous calendar month the number of persons with disabilities who have their main place of work there is not less than 50 percent of the average number of full-time employees of the accounting staff, provided that the payroll of such persons with disabilities is not less than 25 percent of the total labor costs during the reporting period.
The specified enterprises and organizations of public associations of persons with disabilities have the right to apply this benefit if they have a permit for the right to use such a benefit, which is granted by the authorized body in accordance with the Law of Ukraine "On the Fundamentals of Social Protection of Persons with Disabilities in Ukraine".
{Paragraph two of subparagraph 282.1.2 of paragraph 282.1 of Article 282 as amended by Law No. 344-IX of 05.12.2019 }
In case of violation of the requirements of this norm, the specified public associations of persons with disabilities, their enterprises and organizations are obliged to pay the tax amounts for the relevant period, indexed taking into account inflation, as well as penalties in accordance with the legislation;
282.1.3. Olympic and Paralympic training bases, the list of which is approved by the Cabinet of Ministers of Ukraine.
{Article 282 as amended by Laws No. 3609-VI of 07.07.2011 , No. 5083-VI of 05.07.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
282.1.4. preschool and general education institutions, regardless of the form of ownership and sources of financing, cultural, scientific (except for national and state dendrological parks) institutions (provided they are used for their intended purpose), education, healthcare, social protection, physical culture and sports, which are fully supported by state or local budgets.
{Clause 282.1 of Article 282 is supplemented by subparagraph 282.1.4 in accordance with Law No. 654-VIII of 17.07.2015 ; as amended by Laws No. 1791-VIII of 20.12.2016 , No. 1914-IX of 30.11.2021 }
282.1.5. state and municipal children's sanatoriums and health and recreation facilities, as well as children's sanatoriums and health facilities of Ukraine, which are on the balance sheet of enterprises, institutions and organizations that are non-profit and included by the regulatory body in the Register of Non-profit Institutions and Organizations. In the event of exclusion of such enterprises, institutions and organizations from the Register of Non-profit Institutions and Organizations, the declaration shall be submitted by the taxpayer within 30 calendar days from the date of exclusion, and the tax shall be paid starting from the month following the month in which the exclusion from the Register of Non-profit Institutions and Organizations occurred;
{Clause 282.1 of Article 282 is supplemented by subparagraph 282.1.5 in accordance with Law No. 1797-VIII of 21.12.2016 }
282.1.6. state and municipal Olympic training centers, schools of higher sports skills, centers for physical health of the population, centers for the development of physical culture and sports for people with disabilities, children's and youth sports schools, as well as Olympic training centers, schools of higher sports skills, children's and youth sports schools and sports facilities of all-Ukrainian physical culture and sports societies, their local branches and separate divisions, which are non-profit and included in the Register of non-profit institutions and organizations, for land plots on which their sports facilities are located. In the event of exclusion of such institutions and organizations from the Register of non-profit institutions and organizations, the declaration shall be submitted by the taxpayer within 30 calendar days from the date of exclusion, and the tax shall be paid starting from the month following the month in which the exclusion from the Register of non-profit institutions and organizations occurred.
{Clause 282.1 of Article 282 is supplemented by subparagraph 282.1.6 in accordance with Law No. 1797-VIII of 21.12.2016 }
{Title of Article 283 as amended by Law No. 71-VIII of 28.12.2014 }
283.1. Tax is not paid for:
283.1.1. agricultural lands of radioactively contaminated areas, defined in accordance with the law as having been subjected to radioactive contamination as a result of the Chernobyl disaster (zones of exclusion, unconditional (mandatory) resettlement, guaranteed voluntary resettlement and enhanced radioecological control), and chemically contaminated agricultural lands on which restrictions on agricultural activities have been introduced;
283.1.2. land plots that are under conservation or agricultural lands that are in the stage of agricultural development;
{Subparagraph 283.1.2 of paragraph 283.1 of Article 283 as amended by Law No. 3050-IX of 11.04.2023 }
283.1.3. land plots of state variety testing stations and variety departments used for testing varieties of agricultural crops;
283.1.4. road management lands of public roads - lands under the carriageway, shoulder, earthen surface, decorative landscaping, reserves, ditches, bridges, artificial structures, tunnels, traffic interchanges, culverts, retaining walls, noise barriers, treatment facilities and other road structures and equipment located within the right-of-way, as well as lands located outside the right-of-way, if structures ensuring the functioning of highways are located on them, namely:
a) parallel bypass roads, ferry crossings, snow protection structures and plantings, avalanche and mudflow protection structures, intercepting slopes, protective plantings, noise barriers, treatment plants;
b) parking lots for vehicles and recreation, warehouses, garages, fuel and lubricant storage tanks, weighing complexes for large-sized vehicles, production bases, artificial and other structures that are state-owned, owned by state-owned enterprises or owned by business companies, in the authorized capital of which 100 percent of the shares (shares, units) belong to the state;
283.1.5. land plots of agricultural enterprises of all forms of ownership and farms (peasants' farms), occupied by young orchards, berry orchards and vineyards before they enter the fruiting season, as well as hybrid plantings, gene pool collections and nurseries of perennial fruit plantations;
283.1.6. land plots of cemeteries, crematoriums and columbaria.
283.1.7. land plots on which diplomatic missions are located, which, in accordance with international treaties (agreements), the binding consent of which has been granted by the Verkhovna Rada of Ukraine, use the premises and adjacent land plots free of charge.
{Clause 283.1 of Article 283 is supplemented by subparagraph 283.1.7 in accordance with Law No. 5083-VI of 05.07.2012 }
283.1.8. land plots provided for the construction and maintenance of religious and other buildings necessary to ensure the activities of religious organizations of Ukraine, the statutes (regulations) of which are registered in accordance with the procedure established by law.
{ Clause 283.1 of Article 283 is supplemented by subclause 283.1.8 in accordance with the Law No. 71-VIII dated 28.12.2014 }
283.1.9. land plots contaminated with explosive objects.
{ Clause 283.1 of Article 283 is supplemented by subclause 283.1.9 in accordance with the Law No. 3050-IX dated 11.04.2023 }
283.2. No tax shall be paid for land plots unsuitable for use due to the potential threat of their contamination by explosive objects, in the event that village, settlement, city councils, military administrations and military-civilian administrations adopt decisions to establish tax benefits for the payment of local taxes and/or fees in accordance with the procedure specified by this Code.
{ Article 283 is supplemented by paragraph 283.2 in accordance with the Law No. 3050-IX dated 11.04.2023 }
Article 283 - 1. Peculiarities of determining land tax for land plots that are under conservation, or contaminated with explosive objects, or unsuitable for use due to the potential threat of their contamination with explosive objects↑
283 - 1 .1. The basis for non-assessment of land tax in accordance with subparagraph 283.1.2 of paragraph 283.1 of Article 283 of this Code is the data of the State Land Cadastre.
Land tax for land plots defined by subparagraph 283.1.2 of paragraph 283.1 of Article 283 of this Code shall not be charged or paid for the period:
a) in the case of lands of state and municipal ownership - from the first day of the month in which the relevant executive body or local government body that manages land plots of state and municipal ownership in accordance with the powers defined in Article 122 of the Land Code of Ukraine made a decision to approve the working land management project for the conservation of the land plot, until the last day of the month in which measures to protect lands and soils are completed according to the information of the State Land Cadastre;
b) in the case of privately owned lands - from the date of entry of information into the State Land Cadastre on measures to protect lands and soils on the basis of the approved working land management project for land conservation until the last day of the month in which measures to protect lands and soils are completed according to information from the State Land Cadastre.
The calculation of land tax is resumed starting from the first day of the month following the month in which land and soil protection measures were completed according to the information of the State Land Cadastre.
In the event that the taxpayer submits to the supervisory authority a decision of the relevant executive body or local government body that disposes of land plots of state and municipal property in accordance with the powers defined in Article 122 of the Land Code of Ukraine on the approval of a working land management project for the conservation of a land plot, information on measures to protect lands and soils of which is missing in the databases of information systems of the central executive body that implements state tax policy, the calculation of land tax until the supervisory authority receives the relevant data from the State Land Cadastre is carried out on the basis of information provided by the taxpayer.
In case of discrepancies between the data of the controlling bodies and the data confirmed by the land tax payer on the basis of originals or duly certified copies of decisions of the relevant executive bodies or local self-government bodies that dispose of land plots of state and municipal property in accordance with the powers defined in Article 122 of the Land Code of Ukraine, on approval of the working land management project for the conservation of the land plot, the controlling body to which the land tax payer has applied shall, within 10 working days, recalculate the tax amount and send (hand over) to him a new tax notice-decision together with a detailed calculation of the tax amount. The previous tax notice-decision shall be considered canceled (withdrawn).
283 - 1 .2. The basis for non-assessment of land tax in accordance with subparagraph 283.1.9 of paragraph 283.1 of Article 283 of this Code in respect of land plots contaminated with explosive objects is data from the State Land Cadastre.
Land tax for land plots defined by subparagraph 283.1.9 of paragraph 283.1 of Article 283 of this Code, in respect of land plots contaminated with explosive objects, shall not be charged for the period when the land plots were contaminated with explosive objects.
The period when land plots are recognized as contaminated with explosive objects is defined as the period starting from the first day of the month on which the date of the start of the survey of the land plot by mine action operators falls, and ending on the last day of the month in which such land plots are recognized as suitable for use.
For land plots located in territories where active hostilities are (were) conducted or temporarily occupied by the Russian Federation, the period when land plots are recognized as contaminated with explosive objects is defined as the period starting from the first day of the month following the month in which active hostilities or temporary occupation in the relevant territory ended (including when the date of commencement of survey of the hazardous area by mine action operators falls after the date of completion of hostilities or temporary occupation in the relevant territory), provided that the payer of the land fee submits to the local government body, military administration or military-civilian administration an application on potential contamination of the land plot with explosive objects and the adoption by such local government body, military administration or military-civilian administration of a decision on establishing tax benefits for the payment of local taxes and fees in respect of the land plot specified in such application, and ends on the last day of the month in which such land plots are recognized suitable for use.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The calculation of land tax for land plots defined by subparagraph 283.1.9 of paragraph 283.1 of Article 283 of this Code, in respect of land plots contaminated with explosive objects, shall be resumed starting from the first day of the month following the month in which such land plots are recognized as suitable for use.
283 - 1 .3. The basis for non-assessment of land tax in accordance with clause 283.2 of Article 283 of this Code in respect of land plots unsuitable for use due to the potential threat of their contamination by explosive objects is the information specified in subparagraph 12.4.6 of clause 12.4 of Article 12 of this Code.
Non-assessment of land tax for land plots unsuitable for use due to the potential threat of their contamination by explosive objects is carried out during the period starting from the first day of the month on which the date of adoption by the village, settlement, city council, military administration or military-civilian administration of the decision to provide tax benefits for the payment of local taxes and/or fees on the basis of the taxpayer's application falls, and ends on the last day of the month on which the earlier date falls - or the last day of the period for which the benefit for the payment of local taxes and/or fees was provided in accordance with the adopted decision (including taking into account the changes made to such a decision), or the date of cancellation of the relevant decision, or the date of commencement of the survey of the land plot by mine action operators or recognition of the land plot as suitable for use.
In the event that a taxpayer submits to the supervisory authority a decision of the relevant local government body, military administration or military-civilian administration on the provision of tax benefits for the payment of local taxes and/or fees based on the taxpayer's application, information about which is not available in the databases of the information systems of the central executive body implementing state tax policy, the calculation of land tax until the supervisory authority receives the relevant data from the State Land Cadastre is carried out on the basis of information provided by the taxpayer.
In case of discrepancies between the data of the controlling bodies and the data confirmed by the land tax payer on the basis of the originals or duly certified copies of the decisions of the relevant local government bodies, military administration or military-civilian administration on the provision of tax benefits for the payment of local taxes and/or fees based on the taxpayer's application, the controlling body to which the land tax payer has applied shall, within ten working days, recalculate the tax amount and send (hand over) to him a new tax notice-decision together with a detailed calculation of the tax amount. The previous tax notice-decision shall be considered canceled (withdrawn).
{The Code is supplemented by Article 283 - 1 in accordance with the Law No. 3050-IX dated 11.04.2023 }
Article 284. Peculiarities of taxation of land payment↑
{Title of Article 284 as amended by Law No. 71-VIII of 28.12.2014 }
284.1. The Supreme Rada of the Autonomous Republic of Crimea and local self-government bodies shall establish the rates of land payment and land tax benefits paid in the relevant territory.
{Paragraph one of clause 284.1 of Article 284 as amended by Law No. 71-VIII of 28.12.2014 }
{Paragraph two of clause 284.1 of Article 284 was excluded on the basis of Law No. 466-IX of 16.01.2020 }
New changes to decisions regarding the granted land tax benefits are submitted to the relevant regulatory authority at the location of the land plot by the 1st day of the first month of the quarter following the reporting quarter in which the specified changes occurred.
{Paragraph three of clause 284.1 of Article 284 as amended by Law No. 466-IX of 16.01.2020 }
284.2. If the payer's right to a benefit arises during the year, he shall be exempt from paying tax starting from the month following the month in which this right arose. In the event of loss of the right to a benefit during the year, the tax shall be paid starting from the month following the month in which this right was lost.
284.3. If taxpayers who benefit from benefits from this tax lease land plots, individual buildings, structures or parts thereof, the tax for such land plots and land plots under such buildings (parts thereof) shall be paid on a general basis, taking into account the adjacent territory.
This norm does not apply to budgetary institutions if they provide buildings, structures (their parts) for temporary use (lease) to other budgetary institutions, preschools, and general educational institutions, regardless of the forms of ownership and sources of financing.
{Paragraph two of clause 284.3 of Article 284 as amended by Law No. 3609-VI of 07.07.2011 }
284.4. Land fee for land plots provided to mining enterprises for the extraction of minerals and the development of mineral deposits is levied in the amount of 25 percent of the tax calculated in accordance with Articles 274 and 277 of this Code.
{Article 284 is supplemented by paragraph 284.4 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended in accordance with Law No. 2628-VIII of 23.11.2018 }
284.5. Information on the allocation of land plots in kind (on the ground) to owners of land shares (shares) based on decisions of the local government body adopted in the previous year shall be provided to the relevant supervisory body at the location of the land plots by February 1 of the current year.
In the event of changes made by local government bodies to previously adopted decisions of the local government body on the allocation of land plots in kind (on the ground) to owners of land shares (shares), information about such changes shall be provided to the relevant supervisory body at the location of the land plots within 30 calendar days from the date of their introduction.
Such information is provided in electronic form in accordance with the procedure and form approved by the Cabinet of Ministers of Ukraine.
{Article 284 is supplemented by paragraph 284.5 in accordance with Law No. 1914-IX of 30.11.2021 }
284.6. In terms of land payments for land plots that are part of the territory of industrial parks, included in the Register of Industrial Parks, the normative monetary valuation of which has been carried out, and that are used by the initiators of the creation of an industrial park, the management company of the industrial park, and participants in industrial parks, local governments may:
1) set land tax rates and rent in an amount lower than the amount of land tax established by the decision of the relevant local government body for a certain category of land, which is paid in the relevant territory;
2) exempt from paying land tax.
The requirements of subparagraph 4.1.9 of paragraph 4.1 and paragraph 4.5 of Article 4, subparagraphs 12.3.3 , 12.3.4 and 12.3.7 of paragraph 12.3, subparagraph 12.4.3 of paragraph 12.4 (in terms of adoption and entry into force of decisions) and paragraph 12.5 (in terms of the term of entry into force of decisions) of Article 12 of this Code and the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity" shall not apply to such decisions of local self-government bodies and/or decisions on amendments to such decisions .
{Paragraph four of clause 284.6 of Article 284 as amended by Law No. 3603-IX of 23.02.2024 }
{Article 284 is supplemented by paragraph 284.6 in accordance with Law No. 2330-IX of 06/21/2022 - for entry into force, see paragraph 1 of Section II of Law No. 2330-IX of 06/21/2022 }
{Title of Article 285 as amended by Law No. 71-VIII of 28.12.2014 }
285.1. The basic tax (reporting) period for land payments is the calendar year.
285.2. The base tax (reporting) year begins on January 1 and ends on December 31 of the same year (for newly established enterprises and organizations, as well as in connection with the acquisition of ownership and/or use of new land plots, it may be less than 12 months).
Article 286. Procedure for calculating land payment↑
286.1. The basis for calculating land tax is:
{ Paragraph one of clause 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
a) data from the state land cadastre;
{ Paragraph 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
b) data from the State Register of Real Property Rights to Real Estate;
{ Paragraph 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
c) data from state acts certifying the right of ownership or the right of permanent use of a land plot (state acts on land);
{ Paragraph 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
d) data on certificates of the right to land shares (shares);
{ Paragraph 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
e) decision of a local government body on the allocation of land plots in kind (on the ground) to owners of land shares (shares);
{ Paragraph 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
e) data from other title documents certifying the right of ownership or the right to use a land plot, the right to land shares (shares);
{ Paragraph 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
f) data from the List of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation, determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Clause 286.1 of Article 286 is supplemented with a new paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
In the event that a taxpayer submits to the supervisory authority title documents for a land plot, land share (share), information about which is not available in the databases of information systems of the central executive body implementing state tax policy, tax is assessed to individuals based on the information submitted by the taxpayer until the supervisory authority receives information about the transfer of ownership of the taxable object.
{ Paragraph 286.1 of Article 286 as amended by Law No. 1914-IX of 11/30/2021 }
Central executive bodies implementing state policy in the field of land relations and in the field of state registration of property rights to real estate, in the field of construction, monthly, but no later than the 10th of the following month, as well as at the request of the relevant supervisory body at the location of the land plot, submit information necessary for calculating and collecting land payments, in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Paragraph 286.1 of Article 286 as amended by Laws No. 3609-VI of 07.07.2011 - shall enter into force on January 1, 2012 in respect of the provision of information necessary for the calculation of land tax by relevant state bodies; as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 }
In the event that a taxpayer submits to the supervisory authority title documents for a land plot, information about which is missing from the databases of information systems of the central executive body implementing state tax policy, tax payment by individuals and legal entities is carried out on the basis of the information submitted by the taxpayer until the supervisory authority receives information about the transfer of ownership of the taxable object.
{Clause 286.1 of Article 286 is supplemented by a paragraph in accordance with Law No. 466-IX of January 16, 2020 }
286.2. Land tax payers (except individuals) shall independently calculate the amount of land tax each year as of January 1 and no later than February 20 of the current year shall submit to the relevant supervisory authority at the location of the land plot a tax declaration for the current year in the form established in accordance with the procedure provided for in Article 46 of this Code, with a breakdown of the annual amount into equal parts by month. Submission of such a declaration exempts from the obligation to submit monthly declarations. When submitting the first declaration (actual start of activity as a land tax payer), an extract from the technical documentation on the normative monetary valuation of the land plot shall be submitted together with it, and subsequently such an extract shall be submitted in the event of approval of a new normative monetary valuation of the land.
{Clause 286.2 of Article 286 as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 466-IX of 16.01.2020 }
286.3. The payer of land tax has the right to submit a monthly tax return, which exempts him from the obligation to submit a tax return no later than February 20 of the current year, within 20 calendar days of the month following the reporting month.
{Clause 286.3 of Article 286 as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 }
286.4. For newly allocated land plots or newly concluded land lease agreements, the payer of land payment shall submit a tax return within 20 calendar days of the month following the reporting month.
In the event of a change in the object and/or tax base during the year, the payer of the land fee shall submit a tax return within 20 calendar days of the month following the month in which such changes occurred.
{Paragraph 286.4 of Article 286 is supplemented by the second paragraph in accordance with Law No. 4834-VI of 24.05.2012 }
286.5. The calculation of land payment amounts to individuals is carried out by the controlling bodies (at the location of the land plot, including the right to which the individual has as the owner of the land share (share), which send the taxpayer, in accordance with the procedure specified in Article 42 of this Code, by July 1 of the current year, a tax notice-decision on the payment of tax in the form established in accordance with the procedure specified in Article 58 of this Code, together with a detailed calculation of the tax amount, which, in particular, but not exclusively, must contain the cadastral number and area of the land plot, the amount of the tax rate and the amount of the tax benefit.
The assessment of land tax amounts to individuals on the grounds specified in subparagraphs c, d, and e of paragraph 286.1 of this article shall be carried out by the supervisory authorities only if such individuals provide the specified data.
In the event of the transfer of ownership of a land plot or the right to a land share (share) from one owner - a legal entity or an individual - to another during the calendar year, the tax is paid by the previous owner for the period from January 1 of this year to the beginning of the month in which his ownership of the specified land plot ceased, and by the new owner - starting from the month in which he acquired the ownership.
In the event of a transfer of ownership of a land plot or the right to a land share (share) from one owner - an individual to another during a calendar year, the regulatory authority sends (hands over) a tax notice-decision to the new owner after receiving information about the transfer of ownership.
If such a transfer occurred after July 1 of the current year, the regulatory authority shall send (hand over) a new tax notice-decision to the previous owner. The previous tax notice-decision shall be considered canceled (withdrawn).
If a taxpayer owns several land plots or has the right to several land shares (units) for which data reconciliation is required, such taxpayer has the right to apply to the regulatory authority at his place of registration with regulatory authorities or at the location of any of such land plots, including the right to which an individual has as the owner of a land share (unit).
Payers of land fees have the right to apply in writing or electronically by means of electronic communication (in compliance with the requirements specified in paragraph 42.4 of Article 42 of this Code) to the regulatory body at their place of registration with regulatory bodies or at the location of land plots, including the right to which an individual has as the owner of a land share (share), to conduct a reconciliation of data regarding:
the size of the areas and number of land plots, land shares (shares) owned and/or used by the taxpayer;
the right to use the tax exemption, taking into account the provisions of paragraphs 281.4 and 281.5 of Article 281 of this Code;
{Paragraph nine of clause 286.5 of Article 286 as amended by Law No. 3603-IX of 23.02.2024 }
the size of the land tax rate;
the accrued amount of land payment.
In case of discrepancies between the data of the controlling bodies and the data confirmed by the payer of the land fee on the basis of the originals of the relevant documents or duly certified copies of such documents, in particular documents on the right of ownership, use of the benefit, as well as in case of a change in the rate of the land fee, the controlling body to which the payer of the land fee has applied shall, within ten working days, recalculate the tax amount and send (hand over) to him a new tax notice-decision together with a detailed calculation of the tax amount. The previous tax notice-decision shall be considered canceled (withdrawn).
{Clause 286.5 of Article 286 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 , No. 1914-IX of 11/30/2021 }
286.6. For a land plot on which a building is located, which is jointly owned by several legal entities or individuals, the tax is calculated taking into account the adjacent territory of each of the following persons:
1) in equal parts - if the building is in joint ownership of several persons, but not divided in kind, or to one of such owners, determined by their consent, unless otherwise established by the court;
2) in proportion to the share of each person - if the building is in joint partial ownership;
3) in proportion to the appropriate share of each person - if the building is in joint ownership and divided in kind.
For a land plot on which a building is located and is used by several legal entities or individuals, the tax is charged to each of them in proportion to the part of the building area that is used by them, taking into account the adjacent territory.
286.7. A legal entity shall reduce its tax liabilities for land tax by the amount of benefits provided to individuals in accordance with Clause 281.1 of Article 281 of this Code for land plots owned or permanently used by them and included in the land plots of such legal entity.
This procedure also applies to the determination of tax liabilities for land tax by a legal entity for land plots allocated in accordance with the procedure established by the Law of Ukraine "On the Fundamentals of Social Protection of Persons with Disabilities in Ukraine" for free parking (storage) of passenger cars driven by persons with disabilities with musculoskeletal disorders, members of their families who, in accordance with the procedure for providing persons with disabilities with cars, have been granted the right to drive a car, and legal representatives of incapacitated persons with disabilities or children with disabilities who transport persons with disabilities (children with disabilities) with musculoskeletal disorders.
{Paragraph two of clause 286.7 of Article 286 as amended by Laws No. 3609-VI of 07.07.2011 , No. 344-IX of 05.12.2019 }
287.1. Land owners and land users shall pay a fee for land from the date of the emergence of the right of ownership or the right to use the land plot.
In the event of termination of ownership or right to use a land plot, the land fee is paid for the actual period of ownership or use of the land in the current year.
287.2. Registration of individuals - taxpayers and calculation of the relevant amounts are carried out by the supervisory authorities at the location of the land plot, including the right to which the individual has as the owner of the land share (share), annually by May 1.
{Clause 287.2 of Article 287 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 1914-IX of 11/30/2021 }
287.3. The tax liability for payment for land, determined in the tax return for the current year, is paid in equal shares by the owners and land users of land plots at the location of the land plot for the tax period equal to a calendar month, monthly within 30 calendar days following the last calendar day of the tax (reporting) month.
287.4. The tax liability for land payments specified in the tax return, including for newly allocated land plots, is paid by owners and land users of land plots at the location of the land plot for a tax period equal to a calendar month, monthly within 30 calendar days following the last calendar day of the tax (reporting) month.
{Clause 287.4 of Article 287 as amended by Law No. 71-VIII of 28.12.2014 }
287.5. Tax by individuals shall be paid within 60 days from the date of delivery of the tax notice-decision.
Individuals in rural and urban areas may pay land tax through the cash desks of village (village) councils using a receipt for the acceptance of tax payments. The form of the receipt shall be established in accordance with the procedure provided for in Article 46 of this Code.
{Paragraph two of clause 287.5 of Article 287 as amended by Law No. 909-VIII of 24.12.2015 }
287.6. Upon transfer of ownership of a building, structure (part thereof), the tax for the land plots on which such buildings, structures (part thereof) are located, taking into account the adjacent territory, shall be paid on a general basis from the date of state registration of the ownership of such land plot.
{Clause 287.6 of Article 287 as amended by Law No. 71-VIII of 28.12.2014 }
287.7. In the case of leasing land plots (within settlements), individual buildings (structures) or their parts by owners and land users, the tax on the areas leased shall be calculated from the date of conclusion of the land lease agreement or from the date of conclusion of the building (their parts) lease agreement.
{Clause 287.7 of Article 287 as amended by Law No. 71-VIII of 28.12.2014 }
287.8. The owner of a non-residential premises (part thereof) in an apartment building shall pay tax to the budget for the area under such premises (part thereof), taking into account the proportional share of the adjacent territory from the date of state registration of the right of ownership to real estate.
287.9. If the regulatory authority has not sent (delivered) a tax notice (tax decision) within the time limits established by Article 286 of this Code, individuals shall be exempt from liability provided for by this Code for untimely payment of a tax liability.
{Article 287 is supplemented by paragraph 287.9 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 466-IX of 16.01.2020 }
287.10. The tax liability for this tax may be accrued for tax (reporting) periods (years) within the time limits specified in paragraph 102.1 of Article 102 of this Code.
{Article 287 was supplemented by paragraph 287.10 in accordance with Law No. 2245-VIII of 07.12.2017 }
288.1. The basis for calculating rent for a land plot is the lease agreement for such land plot.
{Paragraph one of clause 288.1 of Article 288 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 909-VIII of 24.12.2015 }
Executive authorities and local governments that conclude land lease agreements must, by February 1, submit to the regulatory body at the location of the land plot lists of tenants with whom land lease agreements have been concluded for the current year, and inform the relevant regulatory body about the conclusion of new land lease agreements, amendments to existing land lease agreements, and their termination by the 1st of the month following the month in which the specified changes occurred.
The form of information provision is approved by the central executive body that ensures the formation of state financial policy.
{Clause 288.1 of Article 288 supplemented by the third paragraph in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
A lease agreement for state and municipal land is concluded according to a standard form approved by the Cabinet of Ministers of Ukraine.
{Clause 288.1 of Article 288 was supplemented by the fourth paragraph in accordance with Law No. 1797-VIII of 21.12.2016 }
{Clause 288.2 of Article 288 was excluded pursuant to Law No. 1914-IX of 11/30/2021 }
{Clause 288.3 of Article 288 was excluded pursuant to Law No. 1914-IX of 11/30/2021 }
288.4. The amount and terms of payment of the rent are established in the lease agreement between the lessor (owner) and the lessee (except in cases of conservation of such land plots or recognition of land plots as contaminated (potentially contaminated) with explosive objects).
{Clause 288.4 of Article 288 as amended by Law No. 3050-IX of 11.04.2023 }
288.5. The amount of rent is established in the lease agreement, but the annual amount of payment:
288.5.1. cannot be less than the amount of land tax:
for land plots, the normative monetary assessment of which has been carried out - in the amount of no more than 3 percent of their normative monetary assessment, for public lands - no more than 1 percent of their normative monetary assessment, for agricultural lands - no less than 0.3 percent and no more than 1 percent of their normative monetary assessment;
for land plots for which the normative monetary assessment has not been carried out - in the amount of no more than 5 percent of the normative monetary assessment of a unit of arable land area in the Autonomous Republic of Crimea or in the region, for agricultural lands - not less than 0.3 percent and not more than 5 percent of the normative monetary assessment of a unit of arable land area in the Autonomous Republic of Crimea or in the region;
{Subclause 288.5.1 of clause 288.5 of Article 288 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2245-VIII of 12/07/2017 }
288.5.2. may not exceed 12 percent of the regulatory monetary assessment.
288.5.3. may exceed the maximum rent amount established in subparagraph 288.5.2, in the event of determining the tenant on a competitive basis.
{Clause 288.5 of Article 288 is supplemented by subparagraph 288.5.3 in accordance with Law No. 557-VIII of 30.06.2015 }
288.5.4. for pastures in settlements that have been granted mountain status, cannot exceed the amount of land tax.
{Clause 288.5 of Article 288 is supplemented by subparagraph 288.5.4 in accordance with Law No. 1791-VIII of 20.12.2016 }
288.5.5. for Olympic, Paralympic and Deaflympic training bases, the list of which is approved by the Cabinet of Ministers of Ukraine, cannot exceed 0.1 percent of the normative monetary assessment.
{Clause 288.5 of Article 288 was supplemented by subparagraph 288.5.5 in accordance with Law No. 1797-VIII of 21.12.2016 }
288.5.6. for a joint-stock company, a limited liability company, 100 percent of the shares (shares) in the authorized capital of which belong to the state, which was formed by transforming a state enterprise and is its legal successor, for agricultural land leased in accordance with Article 120-1 of the Land Code of Ukraine - not less than 12 percent of the normative monetary valuation of the land plot, and if the normative monetary valuation of the land plot has not been carried out - not less than 12 percent of the normative monetary valuation of a unit of arable land area in the Autonomous Republic of Crimea or the region.
{Clause 288.5 of Article 288 is supplemented by subparagraph 288.5.6 in accordance with Law No. 3706-IX of 09.05.2024 }
{Clause 288.5 of Article 288 as amended by Laws No. 3609-VI of 07.07.2011 , No. 1166-VII of 03.27.2014 ; as amended by Law No. 71-VIII of 12.28.2014 }
{Clause 288.6 of Article 288 was excluded on the basis of Law No. 3706-IX of 09.05.2024 }
288.7. The tax period, the procedure for calculating rent, the payment deadline and the procedure for its transfer to the budgets shall be applied in accordance with the requirements of Articles 285-287 of this section.
288.8. For land plots defined by this paragraph, for the purposes of calculating rent, the amount of tax liabilities on rent shall be determined taking into account the provisions defined by this Code.
No rent is charged under lease agreements for land plots of state and municipal property, in respect of which the relevant executive body or local government body that disposes of land plots of state and municipal property in accordance with the powers defined in Article 122 of the Land Code of Ukraine has made a decision to approve a working land management project for the conservation of the land plot for the period specified in this working project.
No rent is charged under lease agreements for land plots of state and municipal property contaminated with explosives for the period starting on the first day of the month in which the date of the start of the survey of the land plot by mine action operators falls, and ending on the last day of the month in which such land plots are recognized as suitable for use.
In the case of land plots located in territories where active hostilities are (were) conducted or temporarily occupied by the Russian Federation, the period when land plots are recognized as contaminated with explosive objects is defined as the period starting from the first day of the month following the month in which active hostilities or temporary occupation in the relevant territory ended (including when the date of commencement of survey of the hazardous area by mine action operators falls after the date of completion of hostilities or temporary occupation in the relevant territory), provided that the payer of the land fee submits an application to the local government body, military administration and military-civil administration on potential contamination of the land plot with explosive objects and that such local government body, military administration or military-civil administration adopts a decision to establish tax benefits for the payment of local taxes and fees in respect of the land plot specified in such application, and ends on the last day of the month in which such land plots are recognized as suitable for use.
No rent shall be charged under lease agreements for land plots of state and municipal property that are unsuitable for use due to the potential threat of their contamination by explosive objects during the period starting from the first day of the month on which the date of the decision by the village, settlement, city council, military administration or military-civilian administration to provide tax benefits for the payment of local taxes and/or fees falls on the basis of the taxpayer's application, and ending on the last day of the month on which the earlier date falls - or the last day of the period for which the benefit for the payment of local taxes and fees was provided in accordance with the decision made (including taking into account the changes made to such a decision), or the date of cancellation of the relevant decision, or the date of commencement of the survey of the land plot by mine action operators or recognition of the land plot as suitable for use.
In the event that the rent payer submits to the supervisory authority a decision of the relevant executive body or local government body that disposes of land plots of state and municipal property in accordance with the powers defined in Article 122 of the Land Code of Ukraine on approval of a working land management project for the conservation of a land plot, information on measures to protect lands and soils of which is missing from the databases of information systems of the central executive body that implements state tax policy, or a decision of a village, settlement, city council, military administration or military-civilian administration on the provision of tax benefits for the payment of local taxes and fees based on an application by such a taxpayer to recognize the land plot as unsuitable for use due to the potential threat of its contamination by explosive objects, the accrual of rent shall be suspended until the supervisory authority receives data from the State Land Cadastre or relevant information from the village, settlement, city council, military administration or military-civilian administration regarding Decisions are made on the basis of information provided by the taxpayer.
In the event of discrepancies between the data of the regulatory authorities and the data confirmed by the rent payer on the basis of the originals or duly certified copies of the decisions of the relevant executive body or local government body that disposes of land plots of state and municipal property in accordance with the powers defined in Article 122 of the Land Code of Ukraine, on the approval of the working land management project for the conservation of the land plot or decisions of the village, settlement, city council, military administration or military-civilian administration on the provision of tax benefits for the payment of local taxes and fees based on the application of such a taxpayer on the recognition of the land plot as unsuitable for use due to the potential threat of its contamination by explosive objects, the regulatory authority to which the rent payer has applied shall, within ten working days, recalculate the payment and send (hand over) to him a new tax notice-decision together with a detailed calculation of the amount of the rent. The previous tax notice-decision is considered canceled (withdrawn).
At the same time, the annual amount of payment for such land plots is determined in proportion to the number of months in which the land plot of state or municipal property was recognized as suitable for use.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Article 288 is supplemented by paragraph 288.8 in accordance with Law No. 3050-IX of 11.04.2023 }
Article 289. Indexation of the normative monetary valuation of lands↑
289.1. To determine the amount of tax and rent, the normative monetary valuation of land plots is used, including the rights to which individuals have as owners of land shares (shares), taking into account the indexation coefficient determined in accordance with the legislation.
The central executive body that implements state policy in the field of land relations manages the assessment of land and land plots.
289.2. The central executive body implementing state policy in the field of land relations shall, based on the consumer price index for the previous year, annually calculate the indexation coefficient of the normative monetary valuation of land (Ki), to which the normative monetary valuation of land and land plots is indexed, including the rights to which individuals have as owners of land shares (shares), as of January 1 of the current year, which is determined by the formula:
Ki = I:100,
where I is the consumer price index for the previous year.
If the consumer price index exceeds 115 percent, such index shall be applied with a value of 115.
The indexation coefficient for the normative monetary valuation of land is applied cumulatively depending on the date of the normative monetary valuation of land, specified in the technical documentation on the normative monetary valuation of land and land plots.
289.3. The central executive body implementing state policy in the field of land relations, the Council of Ministers of the Autonomous Republic of Crimea, regional, Kyiv and Sevastopol city state administrations shall ensure, no later than January 15 of the current year, that the central executive body implementing state tax policy and land owners and land users are informed about the annual indexation of the normative monetary valuation of land.
{Article 289 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 , No. 466-IX of 16.01.2020 ; as amended by Law No. 1914-IX of 30.11.2021 }
Article 290. {Article 290 was excluded based on Law No. 71-VIII of 28.12.2014 }↑
{Chapter 1 is included in Section XIV in accordance with Law No. 4014-VI of 04.11.2011 }
CHAPTER 1. SIMPLIFIED SYSTEM OF TAXATION, ACCOUNTING AND REPORTING↑
{Chapter 1 of Section XIV shall enter into force on January 1, 2012, except for subparagraph 1 of subparagraph 291.5.1 of paragraph 291.5 of Article 291 and paragraph 293.2 of Article 293 - see paragraph 1 of Section II of Law No. 4014-VI of 04.11.2011 }
291.1. This chapter establishes the legal principles for the application of a simplified system of taxation, accounting and reporting, as well as the collection of a single tax.
291.2. Simplified system of taxation, accounting and reporting - a special mechanism for collecting taxes and fees, which establishes the replacement of the payment of individual taxes and fees established by paragraph 297.1 of Article 297 of this Code with the payment of a single tax in the manner and on the terms specified in this chapter, with simultaneous maintenance of simplified accounting and reporting.
291.3. A legal entity or an individual entrepreneur may independently choose a simplified taxation system if such an entity meets the requirements established by this chapter and is registered as a single tax payer in accordance with the procedure established by this chapter.
Taxpayers in respect of whom (and/or in respect of their founders (participants), ultimate beneficial owners) in accordance with the procedure established by the Law of Ukraine "On Sanctions" have been decided to apply special economic and other restrictive measures (sanctions) during the period of application of such sanctions, do not have the right to choose and be on the simplified taxation system, and do not have the right to confirm the status of a single tax payer of the fourth group.
{ Item 291.3 of Article 291 supplemented by the second paragraph in accordance with Law No. 3317-IX of 10.08.2023 ; as amended in accordance with Law No. 3813-IX of 18.06.2024 }
291.4. Business entities that apply a simplified system of taxation, accounting and reporting are divided into the following groups of single tax payers:
1) the first group - individuals - entrepreneurs who do not use the labor of hired persons, carry out exclusively retail sales of goods from trading places in the markets and/or conduct economic activities to provide household services to the population and whose income during the calendar year does not exceed 167 times the minimum wage established by law as of January 1 of the tax (reporting) year;
{Subparagraph 1 of paragraph 291.4 of Article 291 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 540-IX of 30.03.2020 , No. 466-IX of 16.01.2020 ; as amended by Law No. 1017-IX of 01.12.2020 }
2) the second group - individuals - entrepreneurs who carry out economic activities in the provision of services, including household services, to single tax payers and/or the population, production and/or sale of goods, activities in the restaurant industry, provided that during the calendar year they meet the following criteria:
do not use the labor of hired persons or the number of persons who are in employment relations with them does not exceed 10 people at the same time;
the amount of income does not exceed 834 times the minimum wage established by law as of January 1 of the tax (reporting) year.
{Paragraph three of subparagraph 2 of paragraph 291.4 of Article 291 as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 540-IX of 30.03.2020 , No. 466-IX of 16.01.2020 ; as amended by Law No. 1017-IX of 01.12.2020 }
This subparagraph does not apply to individual entrepreneurs who provide intermediary services for the purchase, sale, lease and evaluation of real estate (group 70.31 KVED DK 009:2005 ), services for providing access to the Internet, and also carry out activities for the production, supply, sale (sale) of jewelry and household products made of precious metals, precious stones, precious stones of organic formation and semi-precious stones. Such individual entrepreneurs belong exclusively to the third group of single tax payers, if they meet the requirements established for such a group;
{Paragraph four of subparagraph 2 of paragraph 291.4 of Article 291 as amended by Laws No. 4834-VI of 05.24.2012 , No. 5083-VI of 07.05.2012 , No. 71-VIII of 12.28.2014 ; as amended by Law No. 1914-IX of 11.30.2021 }
3) third group:
individuals - entrepreneurs who do not use the labor of hired persons or the number of persons who are in employment relations with them is not limited, and legal entities - business entities of any organizational and legal form, whose income during the calendar year does not exceed 1,167 times the minimum wage established by law as of January 1 of the tax (reporting) year;
Electronic residents (e-residents) who have registered as individual entrepreneurs carry out economic activities in the provision of services, production and/or sale of goods exclusively for the benefit of non-residents of Ukraine, provided that during the calendar year they meet the following criteria:
do not use the labor of hired persons - citizens or residents of Ukraine;
do not receive income originating from Ukraine, except for passive income;
the amount of income does not exceed 1,167 times the minimum wage established by law as of January 1 of the tax (reporting) year;
{Subparagraph 3 of paragraph 291.4 of Article 291 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Laws No. 540-IX of 03/30/2020 , No. 466-IX of 01/16/2020 ; as amended by Law No. 1017-IX of 12/01/2020 ; as amended by Law No. 2654-IX of 10/06/2022 }
4) the fourth group - agricultural producers:
a) legal entities, regardless of their organizational and legal form, in which the share of agricultural production for the previous tax (reporting) year is equal to or exceeds 75 percent;
b) natural persons - entrepreneurs who conduct activities exclusively within the framework of a farm registered in accordance with the Law of Ukraine "On Farming", provided that the following requirements are met:
engage exclusively in the cultivation, fattening of agricultural products, harvesting, catching, processing of such self-grown or fattened products and their sale;
conduct economic activities (except for supply) at the place of tax address;
do not use hired labor;
members of the farm of such an individual are only members of his or her family within the meaning of part two of Article 3 of the Family Code of Ukraine;
the area of agricultural land and/or water fund lands owned and/or used by members of the farm is at least 0.5 hectares, but not more than 20 hectares in total.
{Paragraph six of subparagraph "b" of subparagraph 4 of clause 291.4 of Article 291 as amended by Law No. 1914-IX of 11/30/2021 }
{Subparagraph 4 of paragraph 291.4 of Article 291 as amended by Laws No. 71-VIII of 28.12.2014 , No. 2497-VIII dated 10.07.2018 }
{Subparagraph 5 of paragraph 291.4 of Article 291 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Subparagraph 6 of paragraph 291.4 of Article 291 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
291.4.1. When calculating the total number of persons in employment relations with a single tax payer - an individual, employees who are on leave due to pregnancy and childbirth and on leave to care for a child until the child reaches the age prescribed by law, as well as employees called up for military service during mobilization for a special period, are not taken into account.
When calculating the average number of employees, the definition established by this Code shall be applied.
{Subclause 291.4.1 of Clause 291.4 of Article 291 as amended by Law No. 1797-VIII of 21.12.2016 }
291.4.2. In breeding centers, enterprises (associations) in animal breeding, the products of the agricultural producer's own production also include breeding (genetic) resources purchased from other breeding centers, enterprises (associations) in animal breeding and sold to domestic enterprises for insemination of breeding stock.
{Clause 291.4 of Article 291 is supplemented by subparagraph 291.4.2 in accordance with Law No. 71-VIII of 28.12.2014 }
291.4.3. If an agricultural producer is formed by merger, transformation, division or separation in accordance with the relevant provisions of the Civil Code of Ukraine , then the norm regarding compliance with the share of agricultural production equal to or exceeding 75 percent for the previous tax (reporting) year applies to:
{Paragraph one of subparagraph 291.4.3 of paragraph 291.4 of Article 291 as amended by Law No. 466-IX of January 16, 2020 }
all individuals separately who merge;
{Paragraph two of subparagraph 291.4.3 of paragraph 291.4 of Article 291 as amended by Law No. 466-IX of January 16, 2020 }
each separate entity formed by division or separation;
a person formed by transformation.
If an agricultural producer is reorganized by merger in accordance with the relevant provisions of the Civil Code of Ukraine , the norm regarding compliance with the share of agricultural production equal to 75 percent for the previous tax (reporting) year applies to all participants in such reorganization.
{Subparagraph 291.4.3 of paragraph 291.4 of Article 291 is supplemented by the fifth paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{Clause 291.4 of Article 291 is supplemented by subparagraph 291.4.3 in accordance with Law No. 71-VIII of 28.12.2014 }
291.4.4. Agricultural producers formed through a merger may be tax payers in the year of formation if the share of agricultural production obtained in the previous tax (reporting) year by all producers who participated in their formation and were terminated as a result of the merger is equal to or exceeds 75 percent.
{Clause 291.4 of Article 291 is supplemented by subparagraph 291.4.4 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 466-IX of 16.01.2020 }
291.4.5. Agricultural producers - legal entities formed through the transformation of a taxpayer, may be taxpayers in the year of transformation if the share of agricultural production obtained in the previous tax (reporting) year is equal to or exceeds 75 percent.
{Clause 291.4 of Article 291 is supplemented by subparagraph 291.4.5 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 2497-VIII of 10.07.2018 }
291.4.6. Agricultural producers formed through division or separation may be tax payers from the following year if the share of agricultural production obtained in the previous tax (reporting) year is equal to or exceeds 75 percent.
{Clause 291.4 of Article 291 is supplemented by subparagraph 291.4.6 in accordance with Law No. 71-VIII of 28.12.2014 }
291.4.7. Newly established agricultural producers - legal entities may be tax payers from the following year if the share of agricultural production received in the previous tax (reporting) year is equal to or exceeds 75 percent, and individuals - entrepreneurs - in the year of state registration.
{Clause 291.4 of Article 291 is supplemented by subparagraph 291.4.7 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 2497-VIII of 10.07.2018 }
291.4.8. For the purposes of this chapter, when calculating the share of agricultural production, the total amount of income of an agricultural producer for the relevant tax (reporting) year shall not include income (profits) from transactions on the sale or other alienation of securities and income received from the issuer of corporate rights, investment certificates or other securities certifying his right of ownership to a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit, and calculated according to accounting rules.
{Clause 291.4 of Article 291 is supplemented by subparagraph 291.4.8 in accordance with the Law No. 4577-IX dated 21.08.2025 }
291.5. The following persons of the first - third groups cannot be single tax payers:
{Paragraph one of clause 291.5 of Article 291 as amended by Law No. 71-VIII of 28.12.2014 }
291.5.1. business entities (legal entities and individual entrepreneurs) that carry out:
1) activities in the field of organizing and conducting gambling, activities in issuing and conducting lotteries;
{Sub-clause 1 of subparagraph 291.5.1 of clause 291.5 of Article 291 shall enter into force on the date of entry into force of the law regulating activities in the sphere of gambling business - see clause 1 of section II of Law No. 4014-VI of 04.11.2011 }
{Paragraph one of subparagraph 1 of subparagraph 291.5.1 of paragraph 291.5 of Article 291 as amended by Law No. 71-VIII of 12/28/2014 ; subparagraph 1 of subparagraph 291.5.1 of paragraph 291.5 of Article 291 as amended by Law No. 3325-IX of 08/10/2023 }
2) foreign currency exchange;
3) production, export, import, sale of excisable goods (except for retail sale of fuels and lubricants in containers up to 20 liters and activities of individuals related to the retail sale of beer, cider, peri (without added alcohol) and table wines);
{Subparagraph 3 of subparagraph 291.5.1 of paragraph 291.5 of Article 291 as amended by Law No. 2628-VIII of 23.11.2018 }
4) mining, production, sale of precious metals and precious stones, including those of organic origin (except for the production, supply, sale (sale) of jewelry and household products made of precious metals, precious stones, precious stones of organic origin and semi-precious stones);
{Subclause 4 of subparagraph 291.5.1 of clause 291.5 of Article 291 as amended by Law No. 4834-VI of 24.05.2012 }
5) extraction and sale of minerals, except for the sale of minerals of local importance;
{Subclause 5 of Subclause 291.5.1 of Clause 291.5 of Article 291 as amended by Law No. 4834-VI of 24.05.2012 }
6) activities in the field of financial intermediation, except for activities in the field of insurance, carried out by insurance agents defined by the Law of Ukraine "On Insurance" , surveyors, emergency commissioners and adjusters defined by Section III of this Code;
7) business management activities;
8) activities for the provision of postal services (except courier activities), activities for the provision of fixed telephone services with the right to maintain and operate telecommunications networks and provide for the use of telecommunications channels (local, long-distance, international), activities for the provision of fixed telephone services using wireless access to a telecommunications network with the right to maintain and operate telecommunications channels (local, long-distance, international), activities for the provision of mobile telephone services with the right to maintain and operate telecommunications networks and provide for the use of telecommunications channels, activities for the provision of services for the maintenance and operation of telecommunications networks, terrestrial television and radio broadcasting networks, wired radio broadcasting and television networks;
{Subclause 8 of subparagraph 291.5.1 of clause 291.5 of Article 291 as amended by Laws No. 4834-VI of 05/24/2012 , No. 129-IX of 09/20/2019 }
9) activities related to the sale of works of art and antiques, activities related to the organization of auctions (auctions) of works of art, collectibles or antiques;
10) activities related to the organization and holding of touring events;
11) security activities;
{Subclause 291.5.1 of clause 291.5 of Article 291 is supplemented by subparagraph 11 in accordance with Law No. 4698-IX of 03.12.2025 }
291.5.2. natural persons - entrepreneurs who carry out technical tests and research (group 74.3 KVED DK 009:2005 ), activities in the field of auditing;
291.5.3. individuals - entrepreneurs who lease land plots with a total area exceeding 0.2 hectares, residential premises and/or parts thereof with a total area exceeding 400 square meters, non-residential premises (structures, buildings) and/or parts thereof with a total area exceeding 900 square meters;
{Subclause 291.5.3 of Clause 291.5 of Article 291 as amended by Laws No. 4834-VI of 05/24/2012 , No. 1117-IX of 12/17/2020 }
291.5.4. insurance (reinsurance) brokers, banks, credit unions, pawnshops, leasing companies, trust companies, insurance companies, pension funds, investment funds and companies, other financial institutions defined by law; securities registrars;
291.5.5. business entities in whose authorized capital the total number of shares owned by legal entities that are not single tax payers is equal to or exceeds 25 percent;
291.5.6. representative offices, branches, departments and other separate divisions of a legal entity that is not a single tax payer;
291.5.7. non-resident individuals and legal entities;
291.5.8. taxpayers who, on the day of submitting an application for registration as a single tax payer, have a tax debt, except for a bad tax debt that arose as a result of force majeure circumstances.
{Subclause 291.5.8 of Clause 291.5 of Article 291 as amended by Law No. 1797-VIII of 21.12.2016 }
291.5 - 1. The following persons cannot be payers of the fourth group of the single tax:
291.5 - 1 .1. business entities in which more than 50 percent of the income received from the sale of agricultural products of their own production and products of their processing is income from the sale of ornamental plants (except for cut flowers grown on land owned by the agricultural producer or provided to him for use, and products of their processing), wild animals and birds, fur products and fur (except for fur raw materials);
business entities whose activities, according to KVED-2010, fall into classes 01.47 (breeding of poultry), 01.49 (breeding and raising of quails and ostriches) and 10.12 (production of poultry meat);
{Subparagraph 291.5 - 1 .1 of paragraph 291.5 - 1 of Article 291 is supplemented by the second paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
291.5 - 1 .2. business entities engaged in the production of excisable goods, except for grape wine materials (codes according to UKT FEA 2204 29 - 2204 30) produced at primary winemaking enterprises for secondary winemaking enterprises that use such wine materials for the production of finished products, grape wine materials (codes according to UKT FEA 2204 29-2204 30) produced at primary winemaking enterprises that are exported by these enterprises, grape wines, fruit and berry wines and/or honey drinks produced and bottled in consumer containers by small winemaking production enterprises from wine materials of exclusively their own production (not purchased), obtained by processing fruits, berries, grapes, honey of their own production and/or purchased fruits, berries, grapes, honey, provided that such purchased fruits, berries, grapes, honey have exclusively of Ukrainian origin, as well as except for electricity generated by qualified cogeneration plants and/or from renewable energy sources (provided that the income from the sale of such energy does not exceed 25 percent of the income from the sale of products (goods, works, services) of such a business entity);
{Subclause 291.5 - 1 .2 of clause 291.5 - 1 of Article 291 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2628-VIII of 11/23/2018 , No. 2836-XI of 12/13/2022 , No. 3303-IX of 08/09/2023 }
291.5 - 1 .3. a business entity that as of January 1 of the base (reporting) year has a tax debt, with the exception of a bad tax debt that arose as a result of force majeure circumstances.
{Article 291 is supplemented by paragraph 291.5 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
291.6. Single tax payers of the first - third groups must make payments for shipped goods (work performed, services provided) exclusively in monetary form - cash or non-cash (including using electronic money).
{Clause 291.6 of Article 291 as amended by Laws No. 71-VIII of 12/28/2014 , No. 2888-IX of 01/12/2023 }
291.7. For the purposes of this chapter, household services to the population provided by the first and second groups of single tax payers mean the following types of services:
1) manufacturing of shoes on individual orders;
2) shoe repair services;
3) manufacturing of tailor-made garments;
4) manufacturing of leather products on individual orders;
5) manufacturing of fur products on individual orders;
6) production of underwear on individual orders;
7) manufacturing of textile products and textile haberdashery on individual orders;
8) production of hats on individual orders;
9) additional services for the manufacture of products on individual orders;
10) clothing and household textile repair services;
11) manufacturing and knitting of knitted products on individual orders;
12) knitwear repair services;
13) production of carpets and carpet products on individual orders;
14) services for the repair and restoration of carpets and carpet products;
15) manufacturing of leather haberdashery and travel products on individual orders;
16) repair services for leather haberdashery and travel goods;
17) manufacturing of furniture to individual orders;
18) furniture repair, restoration and renovation services;
19) production of carpentry and joinery products on individual orders;
20) maintenance and repair of cars, motorcycles, scooters and mopeds on individual orders;
21) repair services for radio, television and other audio and video equipment;
22) repair services for electrical appliances and other household appliances;
23) watch repair services;
24) bicycle repair services;
25) services for maintenance and repair of musical instruments;
26) manufacturing of metal products on individual orders;
27) repair services for other personal items, household goods and metal products;
28) manufacturing of jewelry on individual orders;
29) jewelry repair services;
30) rental of personal items and household goods;
31) photography services;
32) film processing services;
33) services for washing, processing of linen and other textile products;
34) cleaning and dyeing services for textile, knitted and fur products;
35) dressing of fur skins on individual orders;
36) hairdressing services;
37) funeral services;
38) services related to agriculture and forestry;
39) domestic services;
40) services related to cleaning and tidying of premises on an individual order.
291.8. The requirements of paragraphs 291.5-291.6 of this article do not apply to single tax payers of the third group - electronic residents (e-residents).
{Article 291 is supplemented by paragraph 291.8 in accordance with Law No. 2654-IX of 06.10.2022 }
Article 292. Procedure for determining income and its composition for single tax payers of the first - third groups↑
{Title of Article 292 as amended by Law No. 71-VIII of 12/28/2014 }
292.1. The income of a single tax payer is:
1) for an individual entrepreneur - income received during the tax (reporting) period in monetary form (cash and/or non-cash); tangible or intangible form, as defined in paragraph 292.3 of this article. In this case, passive income received by such an individual in the form of interest, dividends, royalties, insurance payments and compensation, income in the form of budget grants, as well as income received from the sale of movable and immovable property owned by the individual and used in his/her business activities are not included in the income;
{Subparagraph 1 of paragraph 292.1 of Article 292 as amended by Law No. 962-IX of 04.11.2020 }
2) for a legal entity - any income, including income of representative offices, branches, and departments of such a legal entity, received during the tax (reporting) period in monetary form (cash and/or non-cash); tangible or intangible form, as defined in paragraph 292.3 of this article;
3) for single tax payers of the third group - electronic residents (e-residents) - the amount of funds credited to such taxpayer's bank account.
{Clause 292.1 of Article 292 is supplemented by subparagraph 3 in accordance with Law No. 2654-IX of 06.10.2022 }
292.2. When selling fixed assets by legal entities that are single tax payers, income is determined as the amount of funds received from the sale of such fixed assets.
If fixed assets are sold after their use within 12 calendar months from the date of commissioning, income is determined as the difference between the amount of funds received from the sale of such fixed assets and their residual book value as of the date of sale.
{Clause 292.2 of Article 292 as amended by Law No. 71-VIII of 28.12.2014 }
292.3. The amount of income of a single tax payer includes the value of goods (works, services) received free of charge during the reporting period.
Goods (works, services) provided to a single tax payer under written gift agreements and other written agreements concluded in accordance with the legislation, which do not provide for monetary or other compensation for the cost of such goods (works, services) or their return, as well as goods transferred to a single tax payer for safekeeping and used by such single tax payer, are considered to be received free of charge.
The amount of income of a single tax payer of the third group who is a value added tax payer for the reporting period also includes the amount of accounts payable for which the statute of limitations has expired.
{Paragraph three of clause 292.3 of Article 292 as amended by Laws No. 5083-VI of 05.07.2012 , No. 5503-VI of 20.11.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
The amount of income of a single tax payer of the third group (legal entities) for the reporting period includes the cost of goods (works, services) sold during the reporting period, for which a preliminary payment (advance payment) was received during the period of payment of other taxes and fees specified in this Code.
{ Paragraph four of clause 292.3 of Article 292 as amended by Law No. 71-VIII of 28.12.2014 }
{Clause 292.3 of Article 292 as amended by Law No. 4834-VI of 05.24.2012 , as amended by Law No. 5083-VI of 07.05.2012 }
292.4. In the case of providing services or performing work under contracts of agency, commission, freight forwarding, or under agency contracts, income is the amount of the attorney's (agent's) remuneration received.
{Clause 292.4 of Article 292 as amended by Law No. 71-VIII of 28.12.2014 }
292.5. Income expressed in foreign currency shall be converted into hryvnias at the official exchange rate of hryvnia to foreign currency established by the National Bank of Ukraine on the date of receipt of such income.
292.6. The date of receipt of income of a single tax payer is the date of receipt of funds to the single tax payer in monetary (cash or non-cash) form, the date of signing by the single tax payer of the act of acceptance and transfer of goods (works, services) received free of charge. For a single tax payer of the third group, who is a value-added tax payer, the date of receipt of income is the date of writing off the payable debt, after which the statute of limitations has expired.
{Paragraph one of clause 292.6 of Article 292 as amended by Laws No. 5083-VI of 05.07.2012 , No. 5503-VI of 20.11.2012 , No. 71-VIII of 28.12.2014 }
For a single tax payer of the third group (legal entities), the date of receipt of income is also the date of shipment of goods (performance of work, provision of services) for which a preliminary payment (advance payment) was received during the period of payment of other taxes and fees specified in this Code.
{ Paragraph two of clause 292.6 of Article 292 as amended by Law No. 71-VIII of 28.12.2014 }
{Clause 292.6 of Article 292 as amended by Law No. 4834-VI of 05.24.2012 , as amended by Law No. 5083-VI of 07.05.2012 }
292.7. In the case of trade in goods or services using vending machines or other similar equipment that does not provide for the presence of a register of settlement transactions and/or a software register of settlement transactions, the date of receipt of income is considered to be the date of withdrawal of cash proceeds from such vending machines and/or similar equipment.
{Item 292.7 of Article 292 as amended by the Law No. 129-IX dated 20.09.2019 }
292.8. If trade in goods (works, services) through vending machines is carried out using tokens, cards and/or other substitutes for banknotes expressed in the monetary unit of Ukraine, the date of receipt of income is considered to be the date of sale of such tokens, cards and/or other substitutes for banknotes expressed in the monetary unit of Ukraine.
292.9. Income of an individual - a single tax payer, received as a result of conducting economic activity and taxed in accordance with this chapter, is not included in the total annual taxable income of an individual, determined in accordance with Section IV of this Code.
292.10. The amounts of taxes and fees withheld (accumulated) by a single tax payer during the performance of his functions as a tax agent, as well as the amounts of a single contribution for mandatory state social insurance, accrued by a single tax payer in accordance with the law, are not income.
292.11. The income defined by this article does not include:
1) the amount of value added tax;
2) the amount of funds received through internal settlements between structural divisions of the single tax payer;
3) the amount of financial assistance provided on a repayable basis, received and repaid within 12 calendar months from the date of its receipt, and the amount of loans;
4) amounts of earmarked funds received from the Pension Fund and other mandatory state social insurance funds, from budgets or state earmarked funds, including within the framework of state or local programs;
5) amounts of funds (advance payment, prepayment) returned to the buyer of goods (works, services) - a single tax payer and/or returned by the single tax payer to the buyer of goods (works, services), if such return occurs as a result of the return of goods, termination of the contract or under a letter of application for a refund;
6) amounts of funds received as payment for goods (works, services) sold during the period of payment of other taxes and fees established by this Code, the value of which was included in the income of a legal entity when calculating corporate income tax or the total taxable income of an individual entrepreneur;
7) amounts of value added tax received in the cost of goods (work performed, services provided) shipped (delivered) during the period of payment of other taxes and fees established by this Code;
8) the amounts of funds and the value of property contributed by the founders or participants of a single tax payer to the authorized capital of such payer;
9) amounts of funds in respect of overpaid taxes and fees established by this Code and amounts of a single contribution for mandatory state social insurance, which are returned to the single tax payer from budgets or state special-purpose funds;
10) dividends received by a single tax payer - a legal entity from other taxpayers, taxed in the manner prescribed by this Code;
11) medicines, medical devices and auxiliary means for them provided (transferred) free of charge by a person authorized to carry out procurement in the healthcare sector for the benefit of business entities that have a license to conduct business activities in medical practice, for the implementation of programs and centralized healthcare measures and/or medicines purchased on the basis of a managed access agreement financed from the state budget and/or local budgets, and/or funds of business entities of state or municipal ownership that have a license to conduct business activities in medical practice, provided that:
1) such goods, on the date of conclusion of the contract for their purchase, were included in the List of medicines, medical devices and auxiliary means to them, which are purchased with funds from the state budget for the implementation of programs and centralized health care measures , and/or in the List of medicines, which are purchased under managed access contracts , approved by the Cabinet of Ministers of Ukraine; and
2) such goods were purchased by a person authorized to make purchases in the healthcare sector, at the expense of the state budget funds provided for the implementation of programs and centralized healthcare measures, and/or funds from local budgets, and/or with the funds of state or municipal business entities that have a license to conduct business activities in medical practice, or with the funds of grants (sub-grants) for the implementation of programs of the Global Fund to Fight AIDS, Tuberculosis and Malaria in Ukraine in accordance with the law.
In the event of misuse of medicines, medical devices and auxiliary means for them, the taxpayer is obliged to increase tax liabilities based on the results of the tax period to which such violation occurs, by the amount of the single tax at the rate provided for in paragraph 293.5 of Article 293 of this Code;
{Clause 292.11 of Article 292 is supplemented by subparagraph 11 in accordance with Law No. 532-IX of March 17, 2020 ; as amended by Law No. 4505-IX of June 18, 2025 }
12) the amounts of funds and the value of property received by a taxpayer - a legal entity in the form of a budget grant, provided that it is used for its intended purpose.
In the event of misuse of the provided budget grant, the taxpayer - legal entity is obliged to increase tax liabilities due to the consequences of the tax period to which such violation occurs, by the amount of the single tax at the rate provided for in paragraph 293.5 of Article 293 of this Code;
{Clause 292.11 of Article 292 is supplemented by subparagraph 12 in accordance with Law No. 962-IX of 04.11.2020 }
13) passive income in the form of interest accrued on the balance of funds in the account of a single tax payer of the third group - an electronic resident (e-resident) in a bank, received by such a taxpayer.
{Clause 292.11 of Article 292 is supplemented by subparagraph 13 in accordance with Law No. 2654-IX of 06.10.2022 }
{Clause 292.12 of Article 292 was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
292.13. Income is determined on the basis of accounting data maintained in accordance with Article 296 of this Code.
292.14. Income is determined for the purposes of taxation by a single tax and to grant the right to a business entity to register as a single tax payer and/or to be on a simplified taxation system.
292.15. When determining the amount of income that entitles a business entity to register as a single tax payer and/or to be on the simplified taxation system in the next tax (reporting) period, income received as compensation (reimbursement) by court decision for any previous (reporting) periods is not included.
292.16. Single tax payers have the right to apply the simplified taxation system in the next calendar year, provided that the amount of income established for the relevant group of single tax payers is not exceeded during the calendar year.
At the same time, if during the calendar year, payers of the first and second groups exercised the right to apply a different single tax rate due to exceeding the amount of income established for the relevant group, such payers have the right to apply the simplified taxation system in the next calendar year provided that they do not exceed the amount of income established by subparagraph 3 of paragraph 291.4 of Article 291 of this Code during the calendar year.
{Paragraph two of clause 292.16 of Article 292 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
Article 292 - 1. Object and tax base for single tax payers of the fourth group↑
292 - 1 .1. The object of taxation for single tax payers of the fourth group is the area of agricultural land (arable land, hayfields, pastures and perennial plantations) and/or water resources (inland water bodies, lakes, ponds, reservoirs) owned by an agricultural producer or provided to him for use, including under lease or emphyteusis.
{Paragraph one of clause 292 - 1 .1 of Article 292 - 1 as amended by the Law No. 4536-IX dated 16.07.2025 }
{Paragraph two of clause 292 - 1 .1 of Article 292 - 1 was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
Areas of land plots that are under conservation, contaminated with explosive objects or unsuitable for use due to the potential threat of their contamination with explosive objects are not subject to taxation by a single tax for single tax payers of the fourth group for the period of conservation or for the period when the land plots were contaminated with explosive objects, or for the period when the land plots were recognized as potentially contaminated with explosive objects.
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by the third paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
The period when land plots were under conservation is defined as the period beginning:
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by the fourth paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
a) in the case of lands of state and municipal ownership - from the first day of the month in which the relevant executive body or local government body that manages land plots of state and municipal ownership in accordance with the powers defined in Article 122 of the Land Code of Ukraine made a decision to approve the working land management project for the conservation of the land plot, until the last day of the month in which measures to protect lands and soils are completed according to the information of the State Land Cadastre;
{Clause 292 - 1 .1 of Article 292 - 1 is supplemented by the fifth paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
b) in the case of privately owned lands - from the date of entry of information into the State Land Cadastre on measures to protect lands and soils on the basis of the approved working land management project for land conservation until the last day of the month in which measures to protect lands and soils are completed according to information from the State Land Cadastre.
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by the sixth paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
The period when land plots were contaminated with explosive objects is defined as the period starting from the first day of the month on which the date of the start of the survey of the land plot by mine action operators falls, and ending on the last day of the month in which such land plots are recognized as suitable for use.
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by the seventh paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
For land plots located in territories where active hostilities are (were) conducted or temporarily occupied by the Russian Federation, the period when land plots are recognized as contaminated with explosive objects is defined as the period starting from the first day of the month following the month in which active hostilities or temporary occupation in the relevant territory ended (including when the date of commencement of the survey of the hazardous area by mine action operators falls after the date of completion of hostilities or temporary occupation in the relevant territory), provided that the taxpayer submits an application to the local government body, military administration and military-civil administration on the potential contamination of the land plot with explosive objects and that such local government body, military administration or military-civil administration adopts a decision to establish tax benefits for the payment of local taxes and fees in respect of the land plot specified in such application, and ends on the last day of the month in which such land plots are recognized as suitable for use.
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by the eighth paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
The basis for not charging a single tax on land plots that are unsuitable for use due to the potential threat of their contamination by explosive objects is the information specified in subparagraph 12.4.6 of paragraph 12.4 of Article 12 of this Code.
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by paragraph nine in accordance with Law No. 3050-IX of April 11, 2023 }
The period when land plots are recognized as potentially contaminated with explosive objects is defined as the period starting from the first day of the month on which the date of adoption by the village, settlement, city council, military administration or military-civilian administration of the decision to provide tax benefits for the payment of local taxes and fees on the basis of the taxpayer's application falls, and ends on the last day of the month on which the date that comes earlier falls - or the last day of the period for which the benefit for the payment of local taxes and fees was provided in accordance with the adopted decision (including taking into account the changes made to such a decision), or the date of cancellation of the relevant decision, or the date of commencement of the survey of the land plot by mine action operators, or the date of recognition of the land plot as suitable for use.
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by the tenth paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Paragraph 292 - 1 .1 of Article 292 - 1 is supplemented by the eleventh paragraph in accordance with Law No. 3050-IX of 11.04.2023 }
292 - 1 .2. The tax base for single tax payers of the fourth group for agricultural producers is the normative monetary valuation of 1 hectare of agricultural land (arable land, hayfields, pastures and perennial plantations) taking into account the indexation coefficient determined as of January 1 of the base tax (reporting) year in accordance with the procedure established by this Code for collecting payment for land.
If the normative monetary valuation of the land plot has not been carried out, the tax base for single tax payers of the fourth group for agricultural producers is the normative monetary valuation of a unit of arable land area in the Autonomous Republic of Crimea or the region.
The tax base for single tax payers of the fourth group for water fund lands (inland water bodies, lakes, ponds, reservoirs) is the normative monetary valuation of arable land in the Autonomous Republic of Crimea or the region, taking into account the indexation coefficient determined as of January 1 of the base tax (reporting) year in accordance with the procedure established by this Code for collecting land payments.
{Paragraph 292 - 1 .2 of Article 292 - 1 as amended by Law No. 1791-VIII of 20.12.2016 ; as amended by Law No. 466-IX of 16.01.2020 }
{Clause 292 - 1 .3 of Article 292 - 1 was excluded on the basis of Law No. 1791-VIII of 20.12.2016 }
{The Code is supplemented by Article 292 - 1 in accordance with Law No. 71-VIII of 28.12.2014 }
293.1. Single tax rates for payers of the first group are set as a percentage (fixed rates) to the amount of the subsistence minimum for able-bodied persons established by law as of January 1 of the tax (reporting) year (hereinafter in this chapter - the subsistence minimum), for the second group - as a percentage (fixed rates) to the amount of the minimum wage established by law as of January 1 of the tax (reporting) year (hereinafter in this chapter - the minimum wage), for the third group - as a percentage of income (interest rates).
{ Item 293.1 of Article 293 as amended by Laws No. 71-VIII of 28.12.2014 , No. 1791-VIII of 20.12.2016 }
293.2. Fixed rates of the single tax are established by village, settlement, and city councils for individual entrepreneurs engaged in economic activity, depending on the type of economic activity, per calendar month:
{Clause 293.2 of Article 293 as amended by Law No. 1797-VIII of 21.12.2016 }
1) for the first group of single tax payers - no more than 10 percent of the subsistence minimum;
{Subparagraph 1 of paragraph 293.2 of Article 293 as amended by Laws No. 71-VIII of 28.12.2014 , No. 1791-VIII of 20.12.2016 }
2) for the second group of single tax payers - no more than 20 percent of the minimum wage.
{Subparagraph 2 of paragraph 293.2 of Article 293 as amended by Law No. 71-VIII of 28.12.2014 }
{Clause 293.2 of Article 293 as amended by Law No. 466-IX of January 16, 2020 }
293.3. The percentage rate of the single tax for payers of the third group is set at the rate of:
1) 3 percent of income - in case of payment of value added tax in accordance with this Code;
{Subparagraph 1 of paragraph 293.3 of Article 293 as amended by Law No. 909-VIII of 24.12.2015 }
2) 5 percent of income - in the case of including value added tax in the single tax.
{Subparagraph 2 of paragraph 293.3 of Article 293 as amended by Law No. 909-VIII of 24.12.2015 }
For individual entrepreneurs engaged in the production, supply, sale (realization) of jewelry and household products made of precious metals, precious stones, precious stones of organic formation and semi-precious stones, as well as for electronic residents (e-residents), the single tax rate is set at the amount determined by subparagraph 2 of this paragraph.
{Paragraph four of clause 293.3 of Article 293 as amended by Law No. 2654-IX of 06.10.2022 }
{Clause 293.3 of Article 293 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 5503-VI of 20.11.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
293.4. The single tax rate is set for single tax payers of the first - third groups (individuals - entrepreneurs) at the rate of 15 percent:
{Paragraph one of clause 293.4 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
1) to the amount exceeding the amount of income specified in subparagraphs 1 , 2 and 3 of paragraph 291.4 of Article 291 of this Code;
{Subparagraph 1 of paragraph 293.4 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
2) to income received from activities not listed in the register of single tax payers, classified as belonging to the first or second group;
{Subparagraph 2 of paragraph 293.4 of Article 293 as amended by Law No. 657-VII of October 24, 2013 }
3) to income received by applying a method of calculation other than that specified in this chapter;
4) to income received from activities that do not give the right to apply the simplified taxation system (except for single tax payers of the third group - electronic residents (e-residents);
{Subparagraph 4 of paragraph 293.4 of Article 293 as amended by Law No. 2654-IX of 06.10.2022 }
5) to income received by payers of the first or second group from conducting activities not provided for in subparagraphs 1 or 2 of paragraph 291.4 of Article 291 of this Code, respectively.
{Clause 293.4 of Article 293 was supplemented by subparagraph 5 in accordance with Law No. 71-VIII of 28.12.2014 }
293.5. Single tax rates for payers of the third group (legal entities) are set at double the rates specified in paragraph 293.3 of this article:
{Paragraph one of clause 293.5 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
1) to the amount exceeding the amount of income specified in subparagraph 3 of paragraph 291.4 of Article 291 of this Code;
{Subparagraph 1 of paragraph 293.5 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
2) to income received by applying a method of calculation other than that specified in this chapter;
3) to income received from activities that do not give the right to apply the simplified taxation system.
293.6. In the event that single tax payers of the first and second groups carry out several types of economic activity, the maximum single tax rate established for such types of economic activity shall be applied.
293.7. In the event that single tax payers of the first and second groups carry out economic activities in the territories of more than one village, settlement, or city council, the maximum single tax rate established by this article for the relevant group of such single tax payers shall apply.
{Clause 293.7 of Article 293 as amended by Law No. 909-VIII of 24.12.2015 }
293.8. The rates established by paragraphs 293.3-293.5 of this article shall be applied taking into account the following features:
1) single tax payers of the first group who, in a calendar quarter, exceeded the amount of income determined for such payers in Clause 291.4 of Article 291 of this Code, from the next calendar quarter, upon application, shall switch to the application of the single tax rate determined for single tax payers of the second or third group, or refuse to apply the simplified taxation system.
{Paragraph one of subparagraph 1 of paragraph 293.8 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
Such payers are required to apply a single tax rate of 15 percent to the excess amount.
The application is submitted no later than the 20th of the month following the calendar quarter in which the income was exceeded;
2) single tax payers of the second group who have exceeded in the tax (reporting) period the amount of income determined for such payers in clause 291.4 of Article 291 of this Code, in the next tax (reporting) quarter, upon application, shall switch to the application of the single tax rate determined for single tax payers of the third group, or refuse to apply the simplified taxation system.
{Paragraph one of subparagraph 2 of paragraph 293.8 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
Such payers are required to apply a single tax rate of 15 percent to the excess amount.
The application is submitted no later than the 20th of the month following the calendar quarter in which the income was exceeded;
3) single tax payers of the third group (individual entrepreneurs) who have exceeded the amount of income determined for such payers in Clause 291.4 of Article 291 of this Code in the tax (reporting) period shall apply a single tax rate of 15 percent to the amount of the excess, and shall also be obliged, in accordance with the procedure established by this Chapter, to switch to paying other taxes and fees established by this Code.
Single tax payers of the third group (legal entities) who have exceeded the amount of income determined for such payers in the tax (reporting) period in Clause 291.4 of Article 291 of this Code shall apply to the amount of the excess a single tax rate of double the rates determined by Clause 293.3 of this Article, and shall also be obliged, in accordance with the procedure established by this Chapter, to switch to paying other taxes and fees established by this Code.
The application is submitted no later than the 20th of the month following the calendar quarter in which the income was exceeded;
{Subparagraph 3 of paragraph 293.8 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
4) the single tax rate, determined for the third group at 3 percent, may be selected:
{Paragraph one of subparagraph 4 of clause 293.8 of Article 293 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 5503-VI of 20.11.2012 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
a) a business entity that is registered as a value added tax payer in accordance with Section V of this Code, in the event of its transition to a simplified taxation system by submitting an application for transition to a simplified taxation system no later than 15 calendar days before the beginning of the next calendar quarter;
b) a single tax payer of the third group who has chosen a single tax rate of 5 percent, in the event of a voluntary change in the single tax rate by submitting an application for a change in the single tax rate no later than 10 calendar days before the beginning of the calendar quarter in which the new rate will be applied, and registration of such a single tax payer as a value added tax payer in accordance with the procedure established by Section V of this Code;
{Subparagraph "b" of subparagraph 4 of paragraph 293.8 of Article 293 as amended by Laws No. 4834-VI of 05.24.2012 , No. 5083-VI of 07.05.2012 , No. 5503-VI of 11.20.2012 ; as amended by Law No. 71-VIII of 12.28.2014 ; as amended by Law No. 1797-VIII of 12.21.2016 ; as amended by Law No. 466-IX of 01.16.2020 }
c) a business entity that is not registered as a value added tax payer, in the event of its transition to a simplified taxation system or change of the group of single tax payers by registering as a value added tax payer in accordance with Section V of this Code and submitting an application for transition to a simplified taxation system or change of the group of single tax payers no later than 15 calendar days before the beginning of the next calendar quarter in which the value added tax payer was registered;
{Subparagraph "c" of subparagraph 4 of paragraph 293.8 of Article 293 as amended by Law No. 657-VII of October 24, 2013 }
{Sub-paragraph "d" of subparagraph 4 of paragraph 293.8 of Article 293 was excluded on the basis of Law No. 4834-VI of 24.05.2012 }
5) in the event of cancellation of the registration of a value-added tax payer in accordance with the procedure established by Section V of this Code, single tax payers are obliged to switch to paying a single tax at a rate of 5 percent (for single tax payers of the third group) or refuse to apply the simplified taxation system by submitting an application for changing the single tax rate or refusing to apply the simplified taxation system no later than 15 calendar days before the beginning of the next calendar quarter in which the registration of the value-added tax payer was canceled.
{Subparagraph 5 of paragraph 293.8 of Article 293 as amended by Laws No. 5083-VI of 05.07.2012 , No. 5503-VI of 20.11.2012 ; as amended by Law No. 71-VIII of 28.12.2014 ; as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2245-VIII of 07.12.2017 }
293.9. For single tax payers of the fourth group, the amount of tax rates per hectare of agricultural land and/or water fund land depends on the category (type) of land, its location and is (as a percentage of the tax base):
293.9.1. for arable land, hayfields and pastures (except for arable land, hayfields and pastures located in mountainous areas and in Polesie territories, as well as agricultural lands under closed soil conditions) - 0.95;
{Subclause 293.9.1 of clause 293.9 of Article 293 as amended by Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 1791-VIII of 12/20/2016 }
293.9.2. for arable land, hayfields and pastures located in mountainous areas and in the Polissya territories - 0.57;
{Subclause 293.9.2 of Clause 293.9 of Article 293 as amended by Laws No. 909-VIII of 12/24/2015 , No. 1791-VIII of 12/20/2016 }
293.9.3. for perennial plantations (except perennial plantations located in mountainous areas and in Polesie territories) - 0.57;
{Subclause 293.9.3 of Clause 293.9 of Article 293 as amended by Laws No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 }
293.9.4. for perennial plantations located in mountainous areas and in Polesie territories - 0.19;
{Subclause 293.9.4 of Clause 293.9 of Article 293 as amended by Laws No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 }
293.9.5. for water fund lands - 2.43;
{Subclause 293.9.5 of Clause 293.9 of Article 293 as amended by Law No. 909-VIII of 24.12.2015 }
293.9.6. for agricultural lands under closed soil conditions - 6.33.
{Paragraph one of subparagraph 293.9.6 of paragraph 293.9 of Article 293 as amended by Law No. 1791-VIII of 20.12.2016 }
{Paragraph two of subparagraph 293.9.6 of paragraph 293.9 of Article 293 was excluded on the basis of Law No. 1791-VIII of 20.12.2016 }
The list of mountain zones and Polissya territories is determined by the Cabinet of Ministers of Ukraine;
{Subclause 293.9.6 of Clause 293.9 of Article 293 as amended by Law No. 909-VIII of 24.12.2015 }
{Subparagraph 293.9.7 of paragraph 293.9 of Article 293 was excluded on the basis of Law No. 3603-IX of 23.02.2024 }
{Article 293 was supplemented by paragraph 293.9 in accordance with Law No. 71-VIII of 28.12.2014 }
294.1. The tax (reporting) period for single tax payers of the first, second, and fourth groups is the calendar year.
{Paragraph one of item 294.1 of Article 294 as amended by the Law No. 71-VIII dated 28.12.2014 }
The tax (reporting) period for single tax payers of the third group and tax agents of single tax payers of the third group - electronic residents (e-residents) is a calendar quarter (except for the tax period for tax reporting on value added tax, determined by clause 202.1 of Article 202 of this Code).
{Paragraph two of item 294.1 of Article 294 as amended by the Laws No. 71-VIII dated 28.12.2014 , No. 466-IX dated 16.01.2020 ; as amended by Law No. 2654-IX dated 06.10.2022 }
{Clause 294.1 of Article 294 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 5503-VI of 20.11.2012 }
294.2. The tax (reporting) period begins on the first day of the first month of the tax (reporting) period and ends on the last calendar day of the last month of the tax (reporting) period.
The previous tax (reporting) year for newly established agricultural producers - legal entities - is the period from the date of state registration to December 31 of the same year.
{Item 294.2 of Article 294 is supplemented by a second paragraph in accordance with the Law No. 71-VIII dated 28.12.2014 }
The tax (reporting) period for agricultural producers - legal entities that are being liquidated - is the period from the beginning of the year until their actual termination.
{Item 294.2 of Article 294 is supplemented by a third paragraph in accordance with the Law No. 71-VIII dated 28.12.2014 }
{Clause 294.2 of Article 294 as amended by the Law No. 2497-VIII dated 10.07.2018 }
294.3. For business entities that have switched to paying a single tax from paying other taxes and fees established by this Code, the first tax (reporting) period begins on the first day of the month following the next tax (reporting) quarter in which the person is registered as a single tax payer, and ends on the last calendar day of the last month of such period.
{Clause 294.3 of Article 294 as amended by Law No. 657-VII of October 24, 2013 }
294.4. For duly registered individual entrepreneurs who, before the end of the month in which state registration took place, submitted an application for choosing a simplified taxation system and a single tax rate established for the first or second group, the first tax (reporting) period begins on the first day of the month following the month in which the person was registered as a single tax payer.
{Paragraph one of clause 294.4 of Article 294 as amended by Law No. 657-VII of 24.10.2013 }
For business entities registered in accordance with the procedure established by law (newly created), which within 10 calendar days from the date of state registration submitted an application for the election of a simplified taxation system and a single tax rate established for the third group, as well as the fourth group (individuals), the first tax (reporting) period begins on the first day of the month in which state registration took place.
{Paragraph two of clause 294.4 of Article 294 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by the Law No. 71-VIII dated 28.12.2014 ; as amended by the Law No. 2497-VIII dated 10.07.2018 }
294.5. For business entities formed as a result of reorganization (except for transformation) of any taxpayer that has outstanding tax liabilities or tax debt that arose prior to such reorganization, the first tax (reporting) period begins on the first day of the month following the tax (reporting) quarter in which such tax liabilities or tax debt were repaid and an application for the election of the simplified taxation system was submitted.
294.6. In the case of state registration of the termination of legal entities and state registration of the termination of entrepreneurial activity of an individual entrepreneur who are payers of a single tax, the last tax (reporting) period is considered to be the period in which the relevant controlling body received a notification from the state registrar about the state registration of such termination.
{Clause 294.6 of Article 294 as amended by Law No. 1797-VIII of 21.12.2016 }
294.7. In the event of a change in the tax address of a single tax payer, the last tax (reporting) period for such address shall be the period in which an application for a change in the tax address was submitted to the regulatory authority.
Article 295. Procedure for calculating and payment terms of the single tax↑
295.1. Single tax payers of the first and second groups shall pay the single tax by making an advance payment no later than the 20th day (inclusive) of the current month.
Such single tax payers may pay the single tax in advance for the entire tax (reporting) period (quarter, year), but no later than until the end of the current reporting year.
If a village, settlement or city council makes a decision to change previously established single tax rates, the single tax shall be paid at such rates in the manner and within the time limits specified in subparagraph 12.3.4 of paragraph 12.3 of Article 12 of this Code.
295.2. The calculation of advance payments for single tax payers of the first and second groups is carried out by the supervisory authorities on the basis of the application of such single tax payer regarding the amount of the selected single tax rate, an application regarding the period of annual leave and/or an application regarding the period of temporary disability.
295.3. Single tax payers of the third group (except for electronic residents (e-residents)) pay the single tax within 10 calendar days after the deadline for submitting the tax return for the tax (reporting) quarter.
{Clause 295.3 of Article 295 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 ; as amended by Law No. 2654-IX of 06.10.2022 }
295.3 - 1. For a single tax payer of the third group - an electronic resident (e-resident), the tax agent is the bank in which the electronic resident (e-resident) has a current account.
A single tax payer of the third group - an electronic resident (e-resident) has the right to open a current account exclusively through the "E-resident" information system in one bank of his own choosing, available for selection in the "E-resident" information system.
The bank is obliged to send a notification about the opening or closing of an account by a single tax payer of the third group - an electronic resident (e-resident) to the regulatory authority in which he is registered as a taxpayer, on the day of opening/closing the account in the manner prescribed by Article 69 of this Code.
295.3 - 1 .1. The tax agent of a single tax payer of the third group - an electronic resident (e-resident), when crediting funds to the current account of such payer, is obliged to withhold tax from the amount of crediting at the expense of such funds, using the tax rate determined by Article 293 of this Code, and no later than the next two business days to transfer the tax to the state budget.
In the event of foreign currency being credited to the current account of a single tax payer of the third group - an electronic resident (e-resident), the relevant tax is transferred by the tax agent into hryvnia at the exchange rate determined in accordance with Article 39 - 1 of this Code.
295.3 - 1 .2. Tax liabilities on the single tax withheld by the tax agent of the single tax payer of the third group - an electronic resident (e-resident) - are not subject to refund to the taxpayer as erroneously and/or excessively paid tax liabilities, cannot be credited against other mandatory payments and are not subject to the provisions of Article 43 of this Code.
{Article 295 is supplemented by paragraph 295.3 - 1 in accordance with Law No. 2654-IX of 06.10.2022 }
295.4. Payment of the single tax by payers of the first - third groups (except electronic residents (e-residents)) is carried out at the place of tax address.
{ Paragraph 295.4 of Article 295 as amended by the Laws No. 71-VIII dated 28.12.2014 , No. 2654-IX dated 06.10.2022 }
295.5. Single tax payers of the first and second groups who do not use the labor of hired persons are exempt from paying the single tax for one calendar month per year during vacation, as well as for the period of illness confirmed by an extract from the Electronic Register of Sickness Certificates, if it lasts 30 or more calendar days.
{ Paragraph 295.5 of Article 295 as amended by the Law No. 2330-IX dated 06/21/2022 }
295.6. The amounts of the single tax paid in accordance with the second paragraph of paragraph 295.1 and paragraph 295.5 of this article shall be credited against future payments of this tax at the request of the single tax payer.
Erroneously and/or excessively paid amounts of the single tax shall be refunded to the payer in accordance with the procedure established by this Code.
295.7. The single tax charged for exceeding the amount of income is paid within 10 calendar days after the deadline for submitting the tax return for the tax (reporting) quarter (except for electronic residents (e-residents).
For single tax payers of the third group - electronic residents (e-residents), payment of the single tax charged for exceeding the amount of income is carried out in accordance with the procedure specified in paragraph 295.3 - 1 of this article.
{ Paragraph 295.7 of Article 295 as amended by the Law No. 2654-IX dated 06.10.2022 }
295.8. In the event of termination of economic activity by a single tax payer, tax obligations for payment of the single tax shall be accrued to such payer until the last day (inclusive) of the calendar month in which the registration was canceled by the decision of the regulatory body on the basis of a notification received from the state registrar about the state registration of the termination of entrepreneurial activity.
In the event of cancellation of the registration of a single tax payer by decision of the regulatory authority, tax obligations for payment of the single tax are accrued to such payer until the last day (inclusive) of the calendar month in which the registration was canceled.
{ Paragraph 295.8 of Article 295 as amended by the Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
295.9. Single tax payers of the fourth group:
295.9.1. independently calculate the amount of tax each year as of January 1 and no later than February 20 of the current year submit to the relevant supervisory authority at the location of the taxpayer and the location of the land plot a tax declaration for the current year in the form established in accordance with the procedure provided for in Article 46 of this Code;
295.9.2. pay tax quarterly within 30 calendar days following the last calendar day of the tax (reporting) quarter, in the following amounts:
in the first quarter - 10 percent;
in the second quarter - 10 percent;
in the third quarter - 50 percent;
in the fourth quarter - 30 percent;
295.9.3. individuals - entrepreneurs who in the reporting period chose a simplified taxation system and a single tax rate established for the fourth group, or switched to applying the single tax rate established for the fourth group, and legal entities reorganized by accession or formed during the year by merger or transformation in the reporting tax period, including for the areas of new land plots acquired by them, pay tax for the first time within 30 calendar days following the last calendar day of the tax (reporting) quarter in which such choice/transition took place, in which the formation (occurrence of the right to the land plot) took place, and subsequently - in the manner specified in subparagraph 295.9.2 of this paragraph;
{Subclause 295.9.3 of clause 295.9 of Article 295 as amended by the Laws No. 2497-VIII dated 10.07.2018 , No. 466-IX dated 16.01.2020 }
295.9.4. that are terminated by merger, acquisition, transformation, division in the tax (reporting) period, are obliged to submit an updated tax declaration to the supervisory authorities at their location and the location of the land plots in the period before their actual termination;
295.9.5. are obliged, if during the tax (reporting) period the area of agricultural land and/or water fund lands has changed due to the acquisition (loss) of ownership or use rights to it:
specify the amount of tax liabilities for the period from the date of acquisition (loss) of such right to the last day of the tax (reporting) year;
submit, within 20 calendar days of the month following the reporting period, to the supervisory authorities at the location of the taxpayer and the location of the land plot a declaration with specified information about the area of the land plot, as well as information about the availability of land plots and their normative monetary valuation;
295.9.6. in the case of granting agricultural lands and/or water fund lands for rent or for use on other terms (including on emphyteusis terms) to another taxpayer, the area of the leased or granted for use on other terms (including on emphyteusis terms) land plots shall be taken into account in their declaration. The area of such land plots shall not be taken into account in the lessee's declaration;
{Sub-clause 295.9.6 of clause 295.9 of Article 295 as amended by the Law No. 4536-IX dated 16.07.2025 }
295.9.7. in the case of leasing or taking into use on other terms (including on emphyteusis terms) of agricultural lands and/or water fund lands to a person who is not a taxpayer, the area of the leased or taken into use on other terms (including on emphyteusis terms) of land plots shall be taken into account in their declaration;
{Sub-clause 295.9.7 of clause 295.9 of Article 295 as amended by the Law No. 4536-IX dated 16.07.2025 }
295.9.8. transfer the total amount of funds to the appropriate account of the local budget at the location of the land plot within the established period.
{ Article 295 is supplemented by paragraph 295.9 in accordance with the Law No. 71-VIII dated 28.12.2014 }
Article 296. Keeping records and preparing reports by single tax payers↑
296.1. Individual entrepreneurs - single tax payers of the first and second groups and single tax payers of the third group who are not value-added tax payers, keep records in an arbitrary form by monthly reflecting the income received.
Single tax payers of the third group (individual entrepreneurs) who are value-added tax payers keep records of income and expenses in a standard form and in the manner established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph two of clause 296.1 of Article 296 as amended by Law No. 1914-IX of 11/30/2021 }
At the same time, individual entrepreneurs who are single tax payers of the third group keep records of income and expenses from the production and sale of their own agricultural products separately from the accounting of income and expenses from other types of entrepreneurial activity.
{Clause 296.1 of Article 296 is supplemented with a new paragraph in accordance with Law No. 1914-IX of 30.11.2021 }
Accounting for income and expenses can be kept in paper and/or electronic form, including through an electronic account.
{Paragraph four of clause 296.1 of Article 296 as amended by Law No. 1914-IX of 11/30/2021 }
Legal entities - payers of the single tax of the third group use simplified accounting data regarding income and expenses, taking into account the provisions of paragraphs 44.2 , 44.3 of Article 44 of this Code.
The requirements of this paragraph do not apply to single tax payers of the third group - electronic residents (e-residents).
{Clause 296.1 of Article 296 is supplemented by the sixth paragraph in accordance with Law No. 2654-IX of 06.10.2022 }
{Clause 296.1 of Article 296 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 786-IX of 14.07.2020 }
296.2. Single tax payers of the first and second groups shall submit to the regulatory authority a single tax payer tax return within the period established for the annual tax (reporting) period, which shall reflect the amount of income received, monthly advance payments determined by paragraph 295.1 of Article 295 of this Code, as well as information on the amounts of the single contribution accrued, calculated and paid in accordance with the procedure established by law for this category of payers.
{Paragraph one of clause 296.2 of Article 296 as amended by Laws No. 5503-VI of 11/20/2012 , No. 116-IX of 09/19/2019 }
Such a tax return is filed if the single tax payer did not exceed the amount of income specified in Clause 291.4 of Article 291 of this Code during the year, and/or did not independently switch to paying the single tax at the rates established for single tax payers of the second or third group.
{Paragraph two of clause 296.2 of Article 296 as amended by Laws No. 5503-VI of 11/20/2012 , No. 1797-VIII of 12/21/2016 }
296.3. Single tax payers of the third group shall submit to the regulatory authority a single tax payer tax return within the deadlines established for the quarterly tax (reporting) period.
Single tax payers of the third group (individuals) as part of the single tax payer's tax return for the fourth quarter of the tax (reporting) year also submit information on the amounts of the single contribution accrued, calculated and paid in accordance with the procedure established by law for this category of payers.
{Clause 296.3 of Article 296 is supplemented by the second paragraph in accordance with Law No. 116-IX of September 19, 2019 }
The requirements of this paragraph do not apply to single tax payers of the third group - electronic residents (e-residents).
{Clause 296.3 of Article 296 is supplemented by the third paragraph in accordance with Law No. 2654-IX of 06.10.2022 }
{Clause 296.3 of Article 296 as amended by Laws No. 5083-VI of 05.07.2012 , No. 5503-VI of 20.11.2012 , No. 71-VIII of 28.12.2014 }
296.4. The tax declaration shall be submitted to the supervisory authority at the location of the tax address.
296.5. Income received during the tax (reporting) period that exceeds the amounts of income established by clause 291.4 of Article 291 of this Code shall be reflected by single tax payers in the tax return, taking into account the features specified in subparagraphs 296.5.1-296.5.5 of this Article.
296.5.1. Single tax payers of the first and second groups shall submit a tax return to the regulatory authority within the terms established for the quarterly tax (reporting) period, in case of exceeding during the year the amount of income specified in clause 291.4 of Article 291 of this Code, or independently making a decision to switch to paying tax at the rates established for single tax payers of the second or third (individual entrepreneurs) groups, or refusing to apply the simplified taxation system in connection with the switch to paying other taxes and fees specified by this Code.
{Paragraph one of subparagraph 296.5.1 of paragraph 296.5 of Article 296 as amended by Laws No. 5083-VI of 05.07.2012 , No. 5503-VI of 20.11.2012 , No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 }
At the same time, the tax return shall separately reflect the amount of income taxed at the rates determined for single tax payers of the first and second groups, the amount of income taxed at the rate of 15 percent, the amount of income taxed at the new single tax rate selected in accordance with the conditions determined by this chapter, and the advance payments established by paragraph 295.1 of Article 295 of this Code.
{Paragraph two of subparagraph 296.5.1 of paragraph 296.5 of Article 296 as amended by Law No. 5503-VI of 20.11.2012 }
Filing a tax return within the deadlines established for the quarterly tax (reporting) period exempts such taxpayers from the obligation to file a tax return within the deadlines established for the annual tax (reporting) period.
296.5.2. Single tax payers of the second group shall separately reflect in their tax return:
1) monthly advance payments specified in paragraph 295.1 of Article 295 of this Code;
2) the amount of income taxed at each of the single tax rates they choose;
3) the amount of income taxed at a rate of 15 percent (in case of exceeding the amount of income).
296.5.3. Single tax payers of the third group (individual entrepreneurs) shall separately reflect in their tax declaration:
{Paragraph one of subparagraph 296.5.3 of paragraph 296.5 of Article 296 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
1) the amount of income taxed at each of the single tax rates they have chosen;
2) the amount of income taxed at a rate of 15 percent (in case of exceeding the amount of income).
The requirements of this paragraph do not apply to single tax payers of the third group - electronic residents (e-residents).
{Subparagraph 296.5.3 of paragraph 296.5 of Article 296 is supplemented by the fourth paragraph in accordance with Law No. 2654-IX of 06.10.2022 }
296.5.4. Single tax payers of the third group (legal entities) shall separately reflect in their tax declaration:
{Paragraph one of subparagraph 296.5.4 of paragraph 296.5 of Article 296 as amended by Law No. 71-VIII of 28.12.2014 }
1) the amount of income that is taxed at the relevant single tax rate established for such payers by Clause 293.3 of Article 293 of this Code;
2) the amount of income taxed at the double rate of the single tax established for such payers by Clause 293.3 of Article 293 of this Code (in case the amount of income is exceeded).
{Subclause 296.5.4 of clause 296.5 of Article 296 as amended by Law No. 5083-VI of 05.07.2012 }
296.5.5. In the event of using a method of calculation other than that specified in this chapter, carrying out activities that do not give the right to apply the simplified taxation system, carrying out activities not listed in the register of single tax payers of the first and second groups, single tax payers shall additionally separately reflect in the tax return the income received from such operations.
{Subclause 296.5.5 of Clause 296.5 of Article 296 as amended by Law No. 657-VII of 24.10.2013 }
296.6. The amount of excess income is reflected in the tax return for the tax (reporting) period in which such excess occurred.
In this case, the amount received in excess of the income established for single tax payers of the first and second groups is not included in the amount of income from which the next selected rate is paid by such single tax payers.
296.7. A tax return shall be compiled in a cumulative total, taking into account the provisions of paragraphs 296.5 and 296.6 of this Article. A clarifying tax return shall be submitted in accordance with the procedure established by this Code.
296.8. Single tax payers have the right to submit to the regulatory authority a tax return for a tax (reporting) period other than the quarterly (annual) tax (reporting) period to obtain a certificate of income, which does not exempt such a taxpayer from the obligation to submit a tax return within the period established for the quarterly (annual) tax (reporting) period.
Such a tax return is prepared taking into account the provisions of paragraphs 296.5 and 296.6 of this article and is not a basis for the calculation and/or payment of a tax liability.
296.9. The forms of tax declarations of a single tax payer, specified in paragraphs 296.2 and 296.3 of this Article, shall be approved in accordance with the procedure established by Article 46 of this Code.
296.10. Settlement transaction recorders and/or software settlement transaction recorders are not used by single tax payers of the first group.
{ Clause 296.10 of Article 296 as amended by Laws No. 71-VIII of 28.12.2014 , No. 569-VIII of 01.07.2015 , No. 1797-VIII dated 21.12.2016 , No. 2497-VIII dated 10.07.2018 , No. 2628-VIII dated 23.11.2018 ; as amended by Law No. 129-IX dated 20.09.2019 }
296.11. Tax agents of single tax payers of the third group - electronic residents (e-residents) are obliged to:
a) timely and fully withhold and pay (transfer) to the budget the single tax of the single tax payer of the third group;
b) submit, within the terms established by this Code for the tax quarter, a tax calculation of the amounts of income of the payer of the third group of the single tax to bank accounts and the amounts of tax withheld from them in the form established by the central executive body that ensures the formation and implementation of state financial policy, to the controlling body at the main place of registration. Such calculation is submitted only in the case of crediting funds to the account of the payer of the third group of the single tax - an electronic resident (e-resident).
At the same time, tax agents of single tax payers of the third group - electronic residents (e-residents) separately reflect the amount of receipts to the account that are taxed at a rate of 5 percent of the amount of credited funds, and the amount of receipts to the account that are taxed at a rate of 15 percent of the amount of credited funds (in case the relevant limit is exceeded);
c) submit to the regulatory authority other information on the taxation of income of an individual taxpayer in the amounts and in the manner specified in this section and section II of this Code;
d) be liable in cases specified in this Code.
The loss of the status of electronic resident (e-resident) by a single tax payer of the third group does not exempt the tax agent from the obligation to submit a tax calculation of the amounts of income of the single tax payer of the third group to the accounts for the period of the person's stay on the simplified taxation system.
{Article 296 is supplemented by paragraph 296.11 in accordance with Law No. 2654-IX of 06.10.2022 }
Article 297. Peculiarities of the calculation, payment and submission of reports on individual taxes and fees by payers of a single tax↑
297.1. Single tax payers are exempt from the obligation to charge, pay and submit tax reports on the following taxes and fees:
1) corporate income tax, except for cases provided for in paragraphs two , three and four of subparagraph 133.1.1 and subparagraph 133.1.4 of paragraph 133.1 of Article 133 of this Code;
{Subparagraph 1 of paragraph 297.1 of Article 297 as amended by Laws No. 466-IX of 16.01.2020 , No. 4577-IX dated 21.08.2025 }
2) personal income tax in respect of income (taxable object) received as a result of the economic activity of a single tax payer of the first - fourth group (individual) and taxed in accordance with this chapter;
{Subparagraph 2 of paragraph 297.1 of Article 297 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 2497-VIII of 07/10/2018 }
3) value added tax on transactions for the supply of goods, works and services, the place of supply of which is located in the customs territory of Ukraine, except for the value added tax paid by individuals and legal entities that have chosen the single tax rate determined by subparagraph 1 of paragraph 293.3 of Article 293 of this Code, as well as paid by single tax payers of the fourth group;
{Subparagraph 3 of paragraph 297.1 of Article 297 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
4) property tax in the part of land tax for land plots used by single tax payers of the first - third groups for conducting economic activities (except for activities related to the provision of land plots and/or real estate located on such land plots for rent (lease), loan, or other right of use (including under emphyteusis terms)) and single tax payers of the fourth group for conducting agricultural production;
{Subparagraph 4 of paragraph 297.1 of Article 297 as amended by Laws No. 71-VIII of 28.12.2014 , No. 466-IX of 16.01.2020 , No. 1914-IX of 30.11.2021 ; as amended by the Law No. 4536-IX dated 16.07.2025 }
5) rental payment for special use of water by single tax payers of the fourth group.
{Subparagraph 5 of paragraph 297.1 of Article 297 as amended by Law No. 71-VIII of 28.12.2014 }
{Subparagraph 6 of paragraph 297.1 of Article 297 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
297.2. The assessment, payment and submission of reports on taxes and fees other than those specified in paragraph 297.1 of this Article shall be carried out by single tax payers in the manner, amounts and within the terms established by this Code.
{Paragraph one of clause 297.2 of Article 297 as amended by Law No. 4834-VI of 24.05.2012 }
In the case of importing goods into the customs territory of Ukraine, taxes and duties and customs payments are paid by the single tax payer on general grounds in accordance with the law.
297.3. A single tax payer shall perform the functions of a tax agent provided for by this Code in the event of accrual (payment, provision) of income subject to personal income tax in favor of an individual who is in an employment or civil law relationship with him.
{Clause 297.3 of Article 297 as amended by Law No. 2497-VIII of July 10, 2018 ; as amended by Law No. 466-IX of January 16, 2020 }
297.4. Dividends paid by single tax payers of the third group (legal entities) and the fourth group (legal entities) to owners of corporate rights (founders of such single tax payers) are taxed according to the rules established by Sections II and IV of this Code.
{Article 297 was supplemented by paragraph 297.4 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2497-VIII of 10.07.2018 }
297.5. A single tax payer who makes any payments from income with a source of origin in Ukraine received by such non-resident to a non-resident - a legal entity or a person authorized by it (except for a permanent representative office in the territory of Ukraine) shall calculate and pay tax on the non-resident's income in the manner, amount and within the terms established by Section III of this Code.
{Article 297 was supplemented by paragraph 297.5 in accordance with Law No. 2245-VIII of 07.12.2017 }
297.6. A single tax payer is a legal entity recognized as a controlling entity over controlled foreign companies in accordance with Article 39-2 of this Code, which shall calculate and pay corporate income tax in the manner, amount and terms established by Section III of this Code.
{Article 297 is supplemented by paragraph 297.6 in accordance with Law No. 466-IX of January 16, 2020 }
297.7. A legal entity - a payer of the fourth group of the single tax shall calculate and pay corporate income tax on income (profits) from transactions on the sale or other alienation of securities and income received from the issuer of corporate rights, investment certificates or other securities certifying its ownership right to a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit, and calculated according to accounting rules, in the manner, amount and terms established by Section III of this Code.
{Article 297 is supplemented by paragraph 297.7 in accordance with the Law No. 4577-IX dated 21.08.2025 }
Article 297 - 1. Peculiarities of determining the general minimum tax liability of single tax payers↑
297 - 1 .1. Single tax payers - owners, tenants, users on other terms (including on emphyteusis terms) of land plots classified as agricultural land, as well as heads of family farms, including with respect to land plots owned by members of such a family farm and used by such a family farm, are required to submit an appendix with the calculation of the total minimum tax liability as part of the tax return for the tax (reporting) year.
Such an annex shall, in particular, specify:
cadastral numbers of land plots used by such payers to carry out entrepreneurial activities and for which the minimum tax liability is determined, their normative monetary value and the area of such land plots;
the amount of the total minimum tax liability, the amount of the minimum tax liability for each land plot;
the total amount of taxes, fees, and payments paid by the single tax payer, the control over the collection of which is entrusted to the regulatory authorities, related to the production and sale of own agricultural products and/or to the ownership and/or use (lease, sublease, emphyteusis, permanent use) of land plots classified as agricultural land, and determined in accordance with paragraphs 297 - 1 .2, 297 - 1 .3, 297 - 1 .4 or 297 - 1 .5 of Article 297 - 1 expenses for the lease of land plots (hereinafter in this Article - the total amount of taxes, fees, payments, and expenses for the lease of land plots) during the tax (reporting) year;
the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and land lease expenses paid.
297 - 1 .2. For an individual - a single tax payer of the second group, the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is calculated by subtracting from the total minimum tax liability the total amount of taxes, fees, payments and expenses paid during the tax (reporting) year for the lease of land plots.
The amount of taxes, fees, payments and expenses paid for land leases includes:
single tax; personal income tax and military levy on income (net taxable income) from the sale (sale) of one's own agricultural products (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
personal income tax and military levy on the income of individuals who are in an employment or civil-law relationship with a single tax payer of the second group (except for income paid for the purchase of goods from individuals);
personal income tax and military levy on income of individuals under lease, sublease, emphyteusis agreements of land plots classified as agricultural land for the tax (reporting) year;
land tax for land plots classified as agricultural lands, which are used by such payers to carry out entrepreneurial activities (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
rental fee for special use of water (if paid);
20 percent of the costs of paying rent for land plots classified as agricultural land, the lessors of which are legal entities, and/or which are in state or municipal ownership.
The amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
For legal entities - single tax payers of the fourth group, the amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of corporate income tax paid on income (profits) from transactions on the sale or other alienation of securities and income received from the issuer of corporate rights, investment certificates or other securities certifying its ownership right to a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit, and calculated according to accounting rules, in the manner, amount and terms established by Section III of this Code.
{Paragraph 297 - 1 .2 of Article 297 - 1 is supplemented with a new paragraph in accordance with the Law No. 4577-IX dated 21.08.2025 }
297 - 1 .3. For single tax payers of the third group (legal entities and individual entrepreneurs), for whom the share of agricultural production for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code, is equal to or exceeds 75 percent, the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is calculated by subtracting from the total minimum tax liability the total amount of taxes, fees, payments and expenses paid during the tax (reporting) year for the lease of land plots.
The amount of taxes, fees, payments and expenses paid for land leases includes:
single tax; corporate income tax (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
personal income tax and military levy on income (net taxable income) from the sale (sale) of one's own agricultural products (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
personal income tax and military levy on the income of individuals who are in an employment or civil-law relationship with the taxpayer (except for income paid for the purchase of goods from individuals), on income under lease, sublease, and emphyteusis agreements for agricultural land plots;
land tax for land plots classified as agricultural lands, which are used by such payers to carry out entrepreneurial activities (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
rental fee for special use of water (if paid);
20 percent of the costs of paying rent for land plots classified as agricultural land, the lessors of which are legal entities, and/or which are in state or municipal ownership.
The amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
297 - 1 .4. For a single tax payer of the third group (legal entities and individual entrepreneurs), in which the share of agricultural production for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code, is less than 75 percent, the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments paid is calculated by subtracting from the total minimum tax liability the total amount of taxes, fees, payments and expenses for land lease paid during the tax (reporting) year.
The amount of taxes, fees, payments and expenses paid for land leases includes:
single tax paid by a single tax payer of the third group in an amount proportional to the share of agricultural production of such payer for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
single tax paid by a single tax payer of the second group, in the event of transition to the third group in the tax (reporting) year;
corporate income tax in the amount proportional to the share of agricultural production of such a payer for the reporting period (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one) for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
personal income tax and military levy on income (net taxable income) from the sale (sale) of one's own agricultural products (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
personal income tax and military levy on the income of individuals who are in employment or civil-law relations with a single tax payer of the third group (except for income paid for the purchase of goods from individuals), in an amount proportional to the share of agricultural production of such a payer for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
personal income tax and military levy on income of individuals under lease, sublease, emphyteusis agreements of land plots classified as agricultural land for the tax (reporting) year;
land tax for land plots classified as agricultural lands, which are used by such payers to carry out entrepreneurial activities (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
rental fee for special use of water (if paid) in the amount proportional to the share of agricultural production of such payer for the tax (reporting) year, calculated in accordance with subparagraph 14.1.262 of paragraph 14.1 of Article 14 of this Code;
20 percent of the costs of paying rent for land plots classified as agricultural land, the lessors of which are legal entities, and/or which are in state or municipal ownership.
The amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
297 - 1 .5. For single tax payers of the fourth group (legal entities and individual entrepreneurs who carry out activities exclusively within the framework of a farm registered in accordance with the Law of Ukraine "On Farming"), the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is calculated by subtracting from the total minimum tax liability the total amount of taxes, fees, payments and expenses paid during the tax (reporting) year for the lease of land plots.
The amount of taxes, fees, payments and expenses paid for land leases includes:
single tax; corporate income tax (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
personal income tax and military levy on income (net taxable income) from the sale (sale) of one's own agricultural products (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
personal income tax and military levy on the income of individuals who are in an employment or civil-law relationship with the taxpayer (except for income paid for the purchase of goods from individuals), on income under lease, sublease, and emphyteusis agreements for agricultural land plots;
land tax for land plots classified as agricultural lands, which are used by such payers to carry out entrepreneurial activities (in the event of a transition in the tax (reporting) year to a simplified taxation system from the general one);
rental fee for special use of water (if paid);
20 percent of the costs of paying rent for land plots classified as agricultural land, the lessors of which are legal entities, and/or which are in state or municipal ownership.
The amount of taxes, fees, payments and expenses paid for the lease of land plots does not include the amounts of taxes, fees, and payments paid incorrectly and/or excessively in the tax (reporting) year.
297 - 1 .6. In the case of using a land plot on the right of emphyteusis, the personal income tax and military duty paid when making payments under such an emphyteusis agreement are annually taken into account in a share calculated in proportion to the annual amount of accrued depreciation on an intangible asset in the form of the right to use the land plot under the emphyteusis agreement.
297 - 1 .7. If the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is positive, the payer of the single tax of the second or third group is obliged to increase the amount of the single tax payable to the budget specified in the tax declaration for the tax (reporting) year by the amount of such positive value.
If the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots is positive, the payer of the single tax of the fourth group is obliged to increase the amount of the single tax payable to the budget specified in the tax declaration for the tax (reporting) year following the reporting year by the amount of such positive value.
For single tax payers of the fourth group, the amount of such an increase is distributed between the relevant local budgets and is transferred in proportion to the share of agricultural land plots located on the territory of the relevant territorial community in the total area of such land plots, the owner or user of which is the taxpayer.
297 - 1 .8. The amount of the single tax in the positive part of such difference is not taken into account in the total amount of taxes, fees, payments and expenses paid for the lease of land plots in the next tax (reporting) year.
The positive value of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and land lease expenses paid is part of the single tax liability.
{The Code is supplemented by Article 297 - 1 in accordance with Law No. 1914-IX of 11/30/2021 }
Article 298. Procedure for choosing or switching to a simplified taxation system, or refusing from a simplified taxation system↑
298.1. The procedure for choosing or switching to a simplified taxation system by single tax payers of the first - third groups is carried out in accordance with subparagraphs 298.1.1-298.1.4 of this article.
{Paragraph one of clause 298.1 of Article 298 as amended by Law No. 71-VIII of 28.12.2014 }
298.1.1. To elect or switch to a simplified taxation system, a business entity shall submit an application to the regulatory authority at the location of its tax address.
{Paragraph one of subparagraph 298.1.1 of paragraph 298.1 of Article 298 as amended by Law No. 466-IX of January 16, 2020 }
The application shall be submitted at the taxpayer's choice, unless otherwise provided for by this Code, in one of the following ways:
{Subparagraph 298.1.1 of paragraph 298.1 of Article 298 is supplemented by the second paragraph in accordance with Law No. 5503-VI of 20.11.2012 ; as amended by Law No. 443-VII of 05.09.2013 }
1) personally by the taxpayer or a person authorized to do so;
{Subparagraph 298.1.1 of paragraph 298.1 of Article 298 is supplemented by the third paragraph in accordance with Law No. 5503-VI of 20.11.2012 }
2) sent by mail with a notice of delivery and a description of the attachment;
{Subparagraph 298.1.1 of paragraph 298.1 of Article 298 is supplemented by the fourth paragraph in accordance with Law No. 5503-VI of 20.11.2012 }
3) by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" .
{Subparagraph 298.1.1 of paragraph 298.1 of Article 298 is supplemented by the fifth paragraph in accordance with Law No. 5503-VI of 11/20/2012 ; as amended by Law No. 2725-VIII of 05/16/2019 ; as amended by Law No. 466-IX of 01/16/2020 }
{Paragraph six of subparagraph 298.1.1 of paragraph 298.1 of Article 298 was excluded on the basis of Law No. 3603-IX of 23.02.2024 }
A business entity may declare the choice of a simplified taxation system during the state registration of the creation of a legal entity or state registration of an individual entrepreneur, state registration of changes to information about a legal entity or about an individual entrepreneur contained in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations. The relevant statement or information is transmitted to the regulatory authorities in accordance with the procedure established by the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
{Subparagraph 298.1.1 of paragraph 298.1 of Article 298 is supplemented by paragraph seven in accordance with Law No. 3603-IX of 23.02.2024 }
298.1.2. Registered in accordance with the established procedure, individual entrepreneurs who, before the end of the month in which state registration took place, submitted an application for choosing a simplified taxation system and a single tax rate established for the first or second group, are considered single tax payers from the first day of the month following the month in which state registration took place.
{Paragraph one of subparagraph 298.1.2 of paragraph 298.1 of Article 298 as amended by Law No. 657-VII of October 24, 2013 }
Business entities registered in accordance with the procedure established by law (newly created), which within 10 days from the date of state registration submitted an application for choosing a simplified taxation system and a single tax rate established for the third group, which does not provide for the payment of value added tax, are considered single tax payers from the date of their state registration.
{Paragraph two of subparagraph 298.1.2 of paragraph 298.1 of Article 298 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
Electronic residents (e-residents) registered in accordance with the established procedure as individual entrepreneurs are considered single tax payers from the date of their state registration without the need to submit an application for choosing a simplified taxation system.
{Subparagraph 298.1.2 of paragraph 298.1 of Article 298 is supplemented by the third paragraph in accordance with Law No. 2654-IX of 06.10.2022 }
298.1.3. A business entity formed as a result of reorganization (except for transformation) of any taxpayer that has outstanding tax liabilities or tax debt that arose prior to such reorganization may be registered as a single tax payer (by submitting an application no later than 15 calendar days before the beginning of the next calendar quarter) from the first day of the month following the tax (reporting) quarter in which such tax liabilities or tax debt were repaid.
298.1.4. A business entity that is a payer of other taxes and fees in accordance with the provisions of this Code may decide to switch to a simplified taxation system by submitting an application to the regulatory authority no later than 15 calendar days before the beginning of the next calendar quarter. Such a business entity may switch to a simplified taxation system once during a calendar year.
{Paragraph one of subparagraph 298.1.4 of paragraph 298.1 of Article 298 as amended by Law No. 4834-VI of 24.05.2012 }
The transition to the simplified taxation system of a business entity specified in the first paragraph of this subparagraph may be carried out provided that during the calendar year preceding the period of transition to the simplified taxation system, the business entity has complied with the requirements established in paragraph 291.4 of Article 291 of this Code.
The submitted application shall be accompanied by a calculation of income for the previous calendar year, which shall be determined in compliance with the requirements established by this chapter.
At the same time, if a business entity, during the calendar year preceding the year of choosing the simplified taxation system, independently made a decision to terminate the individual entrepreneur, then when switching to the simplified taxation system, the entire amount of income received by such a person as a result of conducting business activities for such previous calendar year is included in the calculation of income for the previous calendar year.
The form of calculating income for the previous calendar year preceding the year of transition to the simplified taxation system is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph five of subparagraph 298.1.4 of paragraph 298.1 of Article 298 as amended by Law No. 1797-VIII of 21.12.2016 }
298.1.5. Provided that the single tax payer complies with the requirements established by this Code for the group chosen by him, such a payer may independently switch to paying the single tax established for other groups of single tax payers by submitting an application to the regulatory body no later than 15 calendar days before the beginning of the next quarter. In this case, the registration of a single tax payer of the third group, who is a value added tax payer, as a value added tax payer shall be canceled in accordance with the procedure established by this Code, in the event that he chooses the first or second group or the single tax rate established for the third group, which includes value added tax as part of the single tax.
{Clause 298.1 of Article 298 is supplemented by subparagraph 298.1.5 in accordance with Law No. 4834-VI of 24.05.2012 , as amended by Laws No. 5083-VI of 05.07.2012 , No. 657-VII of 24.10.2013 , No. 71-VIII of 28.12.2014 }
298.2. Refusal from the simplified taxation system by single tax payers of the first - third groups shall be carried out in accordance with the procedure specified in subparagraphs 298.2.1-298.2.3 of this article.
{Paragraph one of clause 298.2 of Article 298 as amended by Law No. 71-VIII of 28.12.2014 }
298.2.1. To refuse the simplified taxation system, a business entity shall submit an application to the regulatory authority no later than 10 calendar days before the beginning of a new calendar quarter (year).
298.2.2. Single tax payers may independently refuse the simplified taxation system in connection with the transition to the payment of other taxes and fees specified in this Code, from the first day of the month following the tax (reporting) quarter in which the application for refusal from the simplified taxation system in connection with the transition to the payment of other taxes and fees was submitted.
{Subclause 298.2.2 of Clause 298.2 of Article 298 as amended by Law No. 657-VII of 24.10.2013 }
298.2.3. Single tax payers are obliged to switch to paying other taxes and fees specified in this Code in the following cases and within the following deadlines:
1) in the event of exceeding the established amount of income during a calendar year by single tax payers of the first and second groups and failure by such payers to switch to applying a different rate - from the first day of the month following the tax (reporting) quarter in which such exceeding occurred;
{Subclause 1 of subparagraph 298.2.3 of clause 298.2 of Article 298 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 }
2) in the event of exceeding during a calendar year the amount of income established by subparagraph 3 of paragraph 291.4 of Article 291 of this Code by single tax payers of the first and second groups who have exercised the right to apply other rates established for the third group - from the first day of the month following the tax (reporting) quarter in which such an excess occurred;
{Subclause 2 of subparagraph 298.2.3 of clause 298.2 of Article 298 as amended by Law No. 5083-VI of 05.07.2012 ; as amended by Law No. 71-VIII of 28.12.2014 }
3) in the event of exceeding the established amount of income during the calendar year by single tax payers of the third group (except for single tax payers of the third group - electronic residents (e-residents), - from the first day of the month following the tax (reporting) quarter in which such an excess occurred;
{Subclause 3 of subparagraph 298.2.3 of clause 298.2 of Article 298 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 ; as amended by Law No. 2654-IX of 06.10.2022 }
4) in the event that a single tax payer uses a method of calculation other than those specified in Clause 291.6 of Article 291 of this Code (except for single tax payers of the third group - electronic residents (e-residents), - from the first day of the month following the tax (reporting) period in which such a method of calculation is allowed;
{Subclause 4 of subparagraph 298.2.3 of clause 298.2 of Article 298 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 2654-IX of 10/06/2022 }
5) in the case of carrying out activities that do not give the right to apply the simplified taxation system, or non-compliance with the requirements of organizational and legal forms of business - from the first day of the month following the tax (reporting) period in which such activities were carried out or a change in organizational and legal form occurred;
6) in case of exceeding the number of individuals who are in employment relations with the single tax payer - from the first day of the month following the tax (reporting) period in which such an excess was allowed;
7) in the case of carrying out types of activities not specified in the register of single tax payers (except for single tax payers of the third group - electronic residents (e-residents) - from the first day of the month following the tax (reporting) period in which such types of activities were carried out;
{Subclause 7 of subparagraph 298.2.3 of clause 298.2 of Article 298 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 2654-IX of 10/06/2022 }
8) in the event of a tax debt exceeding the amount specified in paragraph three of clause 59.1 of Article 59 of this Code, on each first day of the month for two consecutive quarters - on the last day of the second of two consecutive quarters;
{Subclause 8 of subparagraph 298.2.3 of clause 298.2 of Article 298 as amended by Law No. 657-VII of 10/24/2013 ; as amended by Law No. 466-IX of 01/16/2020 }
8 - 1 ) in the event of a single tax debt from a single tax payer who independently determined the positive value of the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses for the lease of land plots paid for the last tax (reporting) year, on each first day of the month for two consecutive quarters - on the last day of the second of two consecutive quarters;
{Subclause 298.2.3 of clause 298.2 of Article 298 is supplemented by subparagraph 8 - 1 in accordance with Law No. 4015-IX of 10.10.2024 }
9) in the event of the performance by payers of the first or second group of activities not provided for in subparagraphs 1 or 2 of paragraph 291.4 of Article 291 of this Code, respectively, - from the first day of the month following the tax (reporting) quarter in which such activities were carried out;
{Subclause 298.2.3 of clause 298.2 of Article 298 is supplemented by subparagraph 9 in accordance with Law No. 71-VIII of 28.12.2014 }
10) in the event that the taxpayer acquires the status of a resident of Diya City - from the first day of the month following the tax (reporting) quarter in which the taxpayer acquired the status of a resident of Diya City.
{Subclause 298.2.3 of clause 298.2 of Article 298 is supplemented by subparagraph 10 in accordance with Law No. 1946-IX of 14.12.2021 }
298.3. The application shall contain the following mandatory information:
1) name of the business entity, code according to the Unified State Register of Economic Activities (for a legal entity) or surname, first name, patronymic of the individual entrepreneur, registration number of the taxpayer's registration card or series (if available) and passport number (for individuals who, due to their religious beliefs, have refused to accept the registration number of the taxpayer's registration card in accordance with the established procedure);
{Subparagraph 1 of paragraph 298.3 of Article 298 as amended by Law No. 657-VII of October 24, 2013 }
{Subparagraph 2 of paragraph 298.3 of Article 298 was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
3) tax address of the business entity;
4) place of business activity;
5) types of economic activity selected by the business entity in accordance with KVED DK 009:2010 ;
{Paragraph six of clause 298.3 of Article 298 as amended by Law No. 4834-VI of 05/24/2012 ; as amended by Law No. 71-VIII of 12/28/2014 }
6) the group and rate of the single tax chosen by the business entity or a change in the group and rate of the single tax;
{Subparagraph 6 of paragraph 298.3 of Article 298 as amended by Law No. 5503-VI of 20.11.2012 }
7) the number of persons who are simultaneously in an employment relationship with an individual entrepreneur, and the average number of employees in a legal entity;
8) date (period) of choosing or switching to a simplified taxation system.
298.3.1. The application shall include information (if available) about:
1) change of the name of the business entity (for a legal entity) or the surname, first name, patronymic of an individual entrepreneur, or the series and number of the passport (for individuals who, due to their religious beliefs, have refused to accept the registration number of the taxpayer's registration card in accordance with the established procedure);
2) change of the tax address of the business entity;
3) change of place of business activity;
{Subclause 3 of Subclause 298.3.1 of Clause 298.3 of Article 298 as amended by Law No. 4834-VI of 24.05.2012 }
4) change in types of economic activity;
5) change in the organizational and legal form of a legal entity;
6) date (period) of refusal to apply the simplified system in connection with the transition to payment of other taxes and fees established by this Code;
7) date (period) of termination of economic activity by the single tax payer;
8) change of the group and rate of the single tax payer.
{Subclause 298.3.1 of clause 298.3 of Article 298 is supplemented by subparagraph 8 in accordance with Law No. 4834-VI of 24.05.2012 }
298.3.2. Information on the period of annual leave and the terms of temporary disability with the mandatory addition of an extract from the Electronic Register of Disability Certificates is submitted upon application in any form.
{Subparagraph 298.3.2 of paragraph 298.3 of Article 298 as amended by Law No. 2330-IX of 06/21/2022 }
298.4. In the event of a change in the name of a legal entity, surname, first name, patronymic of an individual entrepreneur or series and number of a passport (for individuals who, due to their religious beliefs, have refused to accept the registration number of the taxpayer's registration card in accordance with the established procedure), the application shall be submitted within one month from the date of occurrence of such changes.
298.5. In the event of a change in the tax address of a business entity, place of business activity, or types of business activity, the application shall be submitted by single tax payers of the first and second groups no later than the 20th day of the month following the month in which such changes occurred.
298.6. In the event of a change in the tax address of a business entity or place of business activity, an application shall be submitted by single tax payers of the third group no later than the last day of the quarter in which such changes occurred.
In the event of a change in the single tax rate, the application shall be submitted by the single tax payer of the third group no later than 15 calendar days before the beginning of the calendar quarter in which such rate will be applied.
{Clause 298.6 of Article 298 as amended by Laws No. 5083-VI of 05.07.2012 , No. 71-VIII of 28.12.2014 ; as amended by Law No. 466-IX of 16.01.2020 }
298.7. The form and procedure for submitting an application are established by the central executive body that ensures the formation and implementation of state tax policy.
298.8. The procedure for choosing or switching to a simplified taxation system, or refusing from a simplified taxation system by single tax payers of the fourth group, is carried out in accordance with subparagraphs 298.8.1-298.8.9 of this article.
{Paragraph 298.8 of Article 298 as amended by the Laws No. 2497-VIII dated 10.07.2018 , No. 3317-IX dated 10.08.2023 }
298.8.1. Agricultural producers, in order to switch to a simplified taxation system or to annually confirm the status of a single tax payer, shall submit no later than February 20 of the current year:
{Paragraph one of subparagraph 298.8.1 of paragraph 298.8 of Article 298 as amended by Law No. 466-IX of January 16, 2020 }
a general tax return for the current year for the entire area of land plots from which the tax is levied (agricultural lands (arable land, hayfields, pastures, perennial plantations), and/or lands of the water fund of inland water bodies (lakes, ponds and reservoirs), - to the controlling authority at its location (place of residence on tax registration);
a tax return for the current year separately for each land plot - to the controlling authority at the location of such land plot (legal entities);
{Paragraph three of subparagraph 298.8.1 of paragraph 298.8 of Article 298 as amended by the Law No. 2497-VIII dated 10.07.2018 }
calculation of the share of agricultural production (legal entities) - to the controlling bodies at their location and/or at the location of land plots in the form approved by the central executive body that ensures the formation of state agrarian policy, in agreement with the central executive body that ensures the formation and implementation of state financial policy;
{Paragraph four of subparagraph 298.8.1 of paragraph 298.8 of Article 298 as amended by Laws No. 1797-VIII of 21.12.2016 , No. 2497-VIII dated 10.07.2018 }
information (certificate) on the availability of land plots - to the supervisory authorities at their location and/or at the location of the land plots.
The information (certificate) on the availability of land plots contains data on each document establishing the right of ownership and/or use of land plots, including each land share lease agreement.
Individual entrepreneurs who have submitted an application for choosing a simplified taxation system and a single tax rate established for the fourth group shall submit the reporting specified in this subparagraph for the first time within 20 calendar days from the date of submission of such an application.
{Sub-clause 298.8.1 of clause 298.8 of Article 298 is supplemented by the seventh paragraph in accordance with the Law No. 2497-VIII dated 10.07.2018 }
298.8.2. Agricultural producers - legal entities formed during the year by merger, accession or transformation, shall submit, within 20 calendar days of the month following the month of its formation, to the regulatory authorities at their location and at the location of the land plots a tax declaration for the period from the date of formation to the end of the current year in order to acquire the status of a taxpayer, as well as all rights and obligations regarding the repayment of tax liabilities or debts transferred to it as a legal successor.
{Subclause 298.8.2 of clause 298.8 of Article 298 as amended by the Law No. 2497-VIII dated 10.07.2018 }
298.8.3. The income of an agricultural producer received from the sale of agricultural products of its own production and products of its processing (except for excisable goods, with the exception of grape wine materials (codes according to the UKT FEA 2204 29 - 2204 30) produced at primary winemaking enterprises for secondary winemaking enterprises that use such wine materials for the production of finished products), includes income received from:
{Paragraph one of subparagraph 298.8.3 of paragraph 298.8 of Article 298 as amended by Law No. 1797-VIII of 21.12.2016 }
sale of crop products produced (grown) on land owned by the agricultural producer or provided to him for use, as well as fish products caught (collected), bred, grown in inland waters (lakes, ponds and reservoirs), and products of its processing at its own enterprises or leased production facilities;
sale of indoor crop production and products of its processing at our own enterprises or leased production facilities;
sale of livestock and poultry products and their processing products at own enterprises or leased production facilities;
sale of agricultural products made from raw materials of own production on a tolling basis, regardless of the territorial location of the processing enterprise.
In the event that an agricultural enterprise is formed by merger, acquisition, transformation, division or separation, in the year of such formation, the amount received from the sale of agricultural products of its own production and products of its processing (except for excisable goods, with the exception of grape wine materials (codes according to the UKT FEA 2204 29 - 2204 30) produced at primary winemaking enterprises for secondary winemaking enterprises that use such wine materials for the production of finished products) shall also include income received during the last tax (reporting) period from the provision of related services:
{Paragraph six of subparagraph 298.8.3 of paragraph 298.8 of Article 298 as amended by Law No. 1797-VIII of 21.12.2016 }
services for harvesting, briquetting, storage, packaging and preparation of products for sale (drying, trimming, sorting, cleaning, grinding, disinfection (if licensed), ensiling, cooling), which are provided to the buyer of such products by the agricultural producer (from the moment of acquisition of ownership of such products under the contract until the date of its actual transfer to the buyer);
livestock and poultry care services provided to the buyer by the agricultural producer (from the moment of acquisition of ownership of such products under the contract until the date of their actual transfer to the buyer);
agricultural product storage services provided to the buyer by the agricultural producer (from the moment of acquisition of ownership of such products under the contract until the date of their actual transfer to the buyer);
services for fattening and slaughtering livestock and poultry, which are provided to the buyer by the agricultural producer (from the moment of acquisition of ownership of such products until the date of its actual transfer to the buyer).
298.8.4. In the event that in a tax (reporting) year the share of agricultural production is less than 75 percent, the agricultural producer - legal entity pays taxes in the following tax (reporting) year on a general basis.
{Paragraph one of subparagraph 298.8.4 of paragraph 298.8 of Article 298 as amended by the Law No. 2497-VIII dated 10.07.2018 }
If such share does not exceed 75 percent due to force majeure circumstances in the previous tax (reporting) year, the specified requirement does not apply to the taxpayer in the next tax (reporting) year. Such taxpayers, in order to confirm the status of a single tax payer, submit a tax return together with the decision of the Verkhovna Rada of the Autonomous Republic of Crimea, regional councils on the existence of force majeure circumstances and a list of business entities that suffered as a result of such circumstances.
298.8.5. Registered in accordance with the established procedure, individual entrepreneurs who, before the end of the month in which state registration took place, submitted an application for choosing a simplified taxation system and a single tax rate established for the fourth group, are considered single tax payers from the date of state registration.
The application shall be submitted at the taxpayer's choice in one of the methods specified in parts 1-4 of subparagraph 298.1.1 of paragraph 298.1 of Article 298 of this Code.
{Clause 298.8 of Article 298 is supplemented by subparagraph 298.8.5 in accordance with the Law No. 2497-VIII dated 10.07.2018 }
298.8.6. Single tax payers of the fourth group (individual entrepreneurs) who, in the tax (reporting) period, did not ensure compliance with the set of conditions (criteria) stipulated in subparagraph "b" of subparagraph 4 of paragraph 291.4 of Article 291 of this Code, are obliged to pay tax in the current year in the amount calculated based on 25 percent of the annual tax amount for each quarter during which the payer was in the fourth group of single tax payers, and from the next tax (reporting) quarter, switch to the application of the single tax rate determined for single tax payers of the third group, or refuse to apply the simplified taxation system.
An application for such a transition shall be submitted by such taxpayer no later than the 20th day of the month following the calendar quarter in which compliance with the set of conditions (criteria) stipulated in subparagraph "b" of subparagraph 4 of clause 291.4 of Article 291 of this Code is not ensured.
{Clause 298.8 of Article 298 is supplemented by subparagraph 298.8.6 in accordance with the Law No. 2497-VIII dated 10.07.2018 }
298.8.7. Single tax payers of the fourth group may independently switch to the application of the single tax rate determined for single tax payers of another group, or refuse the simplified taxation system in connection with the transition to the payment of other taxes and fees determined by this Code, from the first day of the month following the tax (reporting) quarter in which the relevant application was submitted in accordance with the procedure in accordance with paragraph 298.2 of Article 298 of this Code, provided that the tax for the current year is paid in the amount calculated based on 25 percent of the annual tax amount for each quarter during which the payer was in the fourth group of single tax payers.
{Clause 298.8 of Article 298 is supplemented by subparagraph 298.8.7 in accordance with the Law No. 2497-VIII dated 10.07.2018 ; as amended by the Law No. 466-IX dated 16.01.2020 }
298.8.8. An agricultural producer may be re-included in the fourth group of single tax payers no earlier than two calendar years after his transition to the application of the single tax rate determined for single tax payers of another group, or the cancellation of his previous registration as a single tax payer of the fourth group. The provisions of this subparagraph shall not apply in the event of cancellation of the registration of a legal entity as a single tax payer of the fourth group at the initiative of the supervisory authority.
{Clause 298.8 of Article 298 is supplemented by subparagraph 298.8.8 in accordance with the Law No. 2497-VIII dated 10.07.2018 }
298.8.9. Single tax payers of the fourth group, whose registration as a single tax payer has been canceled in accordance with subparagraph 8 of paragraph 299.10 of Article 299 of this Code, have the right, within 20 calendar days after the date of such cancellation of registration, to adjust the accrued tax liabilities from the single tax for the period from the day following the date of cancellation of such registration until the end of the reporting (tax) period by submitting, in accordance with the procedure specified by this Code, clarifying tax returns from the single tax of the fourth group to reduce the amount of tax liabilities.
{Clause 298.8 of Article 298 is supplemented by subparagraph 298.8.9 in accordance with Law No. 3317-IX of 10.08.2023 }
{Article 298 was supplemented by paragraph 298.8 in accordance with Law No. 71-VIII of 28.12.2014 }
298.9. Information on the registration or cancellation of the registration of an individual entrepreneur - a single tax payer of the fourth group in the form of an extract from the register of single tax payers shall be provided by the controlling body of the local government body at the tax address of such a taxpayer no later than 30 calendar days from the date of such registration.
{Article 298 is supplemented by paragraph 298.9 in accordance with the Law No. 2497-VIII dated 10.07.2018 }
Article 299. Procedure for registration and cancellation of registration of single tax payers↑
299.1. Registration of a business entity as a single tax payer is carried out by making appropriate entries in the register of single tax payers.
Registration of electronic residents (e-residents) as payers of the third group of the single tax is carried out by the supervisory authority within two working days from the date of receipt from the state registrar of information on the registration of the electronic resident as an individual entrepreneur in accordance with the procedure established by the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
{Clause 299.1 of Article 299 is supplemented by the second paragraph in accordance with Law No. 2654-IX of 06.10.2022 }
299.2. The central executive body implementing the state tax policy shall maintain a register of single tax payers, which contains information on persons registered as single tax payers.
{Clause 299.2 of Article 299 as amended by Law No. 1797-VIII of 21.12.2016 }
299.3. In the absence of grounds specified in this Code for refusing to register a business entity as a single tax payer, the regulatory authority is obliged to register such person as a single tax payer within two working days from the date of receipt of the application for transition to the simplified taxation system.
299.4. In cases provided for in subparagraph 298.1.2 of paragraph 298.1 and subparagraph 298.8.5 of paragraph 298.8 of Article 298 of this Code, the regulatory authority, in the absence of grounds for refusal specified in this Code, shall register the business entity as a payer of a single tax from the date specified in accordance with the specified subparagraph, within two working days from the date of receipt by the regulatory authority of an application for choosing a simplified taxation system or receipt by this authority of a relevant application or information in accordance with the procedure established by the Law of Ukraine "On State Registration of Legal Entities, Individual Entrepreneurs and Public Organizations".
{Clause 299.4 of Article 299 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2497-VIII of 07/10/2018 , No. 3603-IX of 02/23/2024 }
299.5. In the event of refusal to register as a single tax payer, the regulatory authority is obliged to provide, within two working days from the date of submission of the relevant application by the business entity, a written reasoned refusal, which may be appealed by the business entity in accordance with the established procedure.
299.6. The grounds for the supervisory authority to make a decision to refuse to register a business entity as a single tax payer are exclusively:
1) non-compliance of such an entity with the requirements established by Article 291 of this Code;
2) the presence of an economic entity formed as a result of the reorganization (except for transformation) of any taxpayer, outstanding tax liabilities or tax debt that arose prior to such reorganization;
3) failure by such an entity to comply with the requirements established by subparagraph 298.1.4 of paragraph 298.1 of Article 298 of this Code.
299.7. The following information about the single tax payer shall be entered into the register of single tax payers:
1) name of the business entity, code according to the Unified State Register of Individual Entrepreneurs (for a legal entity) or surname, first name, patronymic of the individual entrepreneur, registration number of the taxpayer's registration card or series (if available) and passport number (for individuals who, due to their religious beliefs, have refused to accept the registration number of the taxpayer's registration card in accordance with the established procedure and have a corresponding mark in their passport);
2) tax address of the business entity;
3) place of business activity (except for single tax payers of the third group - electronic residents (e-residents);
{Subparagraph 3 of paragraph 299.7 of Article 299 as amended by Law No. 2654-IX of 06.10.2022 }
{Subparagraph 4 of paragraph 299.7 of Article 299 was excluded on the basis of Law No. 466-IX of January 16, 2020 }
5) single tax rate and taxpayer group;
6) date (period) of election or transition to a simplified taxation system;
7) date of registration;
8) types of economic activity (except for single tax payers of the third group - electronic residents (e-residents);
{Subparagraph 8 of paragraph 299.7 of Article 299 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 2654-IX of 10/06/2022 }
9) date of cancellation of registration.
299.8. In the event of changes in the information provided for in subparagraphs 1-5 of paragraph 299.7 of this article, changes shall be made to the register of single tax payers on the day the payer submits the relevant application.
299.9. If desired, a registered single tax payer may, free of charge and without any conditions, obtain (including in electronic form) an extract from the register of single tax payers from the controlling body at the place of the tax address. The term for providing an extract from the register of single tax payers for registered single tax payers shall not exceed one working day from the date of receipt of the request, and for business entities that have submitted an application for transition to the simplified taxation system, two working days from the date of receipt of the request. The extract shall be valid until changes are made to the register.
{Clause 299.9 of Article 299 as amended by Law No. 1797-VIII of 12/21/2016 ; as amended by Law No. 466-IX of 01/16/2020 }
299.10. Registration as a single tax payer is indefinite and may be canceled by exclusion from the register of single tax payers by decision of the supervisory authority in the event of:
1) submission by the taxpayer of an application for refusal to apply the simplified taxation system in connection with the transition to payment of other taxes and fees specified in this Code - on the last day of the calendar quarter in which such an application is submitted;
2) termination of a legal entity (except for transformation) or termination of entrepreneurial activity by an individual entrepreneur in accordance with the law - on the day the relevant regulatory body receives a notification from the state registrar about the state registration of such termination, and in the event of the death of an individual entrepreneur - from the date of death of such individual;
{Subparagraph 2 of paragraph 299.10 of Article 299 as amended by Law No. 4505-IX of 18.06.2025 }
3) in cases specified in subparagraph 298.2.3 of paragraph 298.2 and subparagraph 298.8.6 of paragraph 298.8 of Article 298 of this Code;
{Sub-clause 3 of clause 299.10 of Article 299 as amended by the Law No. 2497-VIII dated 10.07.2018 }
4) if in the tax (reporting) year the share of agricultural production of a legal entity that is a payer of a single tax of the fourth group is less than 75 percent;
{Clause 299.10 of Article 299 is supplemented by subparagraph 4 in accordance with Law No. 71-VIII of 28.12.2014 ; with amendments made in accordance with Law No. 2497-VIII dated 10.07.2018 }
5) if the single tax payer of the fourth group has not submitted the tax reporting provided for in subparagraph 295.9.1 of paragraph 295.9 of Article 295 and subparagraph 298.8.1 of paragraph 298.8 of Article 298 of this Code;
{Clause 299.10 of Article 299 supplemented by subparagraph 5 in accordance with Law No. 2497-VIII of 10.07.2018 ; as amended in accordance with Law No. 466-IX of 16.01.2020 }
6) the taxpayer acquires the status of a resident of Diya City - on the last day of the calendar quarter in which the taxpayer acquired the status of a resident of Diya City;
{Clause 299.10 of Article 299 was supplemented by subparagraph 6 in accordance with Law No. 1946-IX of 14.12.2021 }
7) loss of the status of electronic resident (e-resident) by a single tax payer of the third group;
{Clause 299.10 of Article 299 is supplemented by subparagraph 7 in accordance with Law No. 2654-IX of 06.10.2022 }
8) the presence of a decision on the application of special economic and other restrictive measures (sanctions) against the taxpayer and/or its founders (participants), ultimate beneficial owners, adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions":
for payers of the first and second groups - on the last day of the month in which such a decision is made;
for payers of the third and fourth groups - on the last day of the quarter in which such a decision is made.
{Clause 299.10 of Article 299 is supplemented by subparagraph 8 in accordance with Law No. 3317-IX of 10.08.2023 ; as amended in accordance with Law No. 3813-IX of 18.06.2024 }
299.11. In the event that the relevant supervisory authority, during inspections, detects violations by a single tax payer of the first to third groups of requirements established by this Chapter, the registration of a single tax payer of the first to third groups shall be cancelled by decision of such authority, adopted on the basis of the inspection report, from the first day of the month following the quarter in which the violation was committed. In such a case, the business entity has the right to choose or switch to a simplified taxation system after the expiration of four consecutive quarters from the moment the decision is made by the supervisory authority.
If the relevant regulatory body, during on-site documentary inspections of a single tax payer of the fourth group, discovers non-compliance with the requirements of subparagraph 4 of paragraph 291.4 and paragraph 291.5 - 1 of Article 291 of this Code in the tax (reporting) year or in previous periods, such a payer shall be charged for such periods taxes and fees from which he was exempted as a single tax payer of the fourth group, and punitive (financial) sanctions (fines) provided for in Chapter 11 of Section II of this Code. Such a taxpayer shall be obliged to switch to paying taxes under the general taxation system, starting from the month following the month in which such a violation was established.
{Clause 299.11 of Article 299 as amended by Law No. 71-VIII of 12/28/2014 }
299.12. Repayment of tax debt after cancellation of registration of a single tax payer shall be carried out in accordance with the procedure established by Chapter 9 of Section II of this Code.
299.13. In order to constantly provide state authorities, local self-government bodies, legal entities and individuals with information, the central executive body implementing the state tax policy shall publish the following data from the register of single tax payers on a daily basis for free and open access on the single state registration web portal of legal entities and individuals - entrepreneurs and public organizations and on its own official website:
{Paragraph one of clause 299.13 of Article 299 as amended by Laws No. 1797-VIII of 12/21/2016 , No. 466-IX of 01/16/2020 }
tax number (for a legal entity);
name for a legal entity or surname, first name, patronymic for an individual;
date (period) of choosing or switching to a simplified taxation system;
single tax rate;
taxpayer group;
types of economic activity (if relevant data are available);
{Paragraph seven of clause 299.13 of Article 299 as amended by Law No. 71-VIII of 12/28/2014 ; as amended by Law No. 2654-IX of 10/06/2022 }
date of exclusion from the register of single tax payers.
{ Article 299 as amended by Laws No. 4834-VI of 24.05.2012 , No. 5503-VI of 20.11.2012 , No. 443-VII of 05.09.2013 ; as amended by Law No. 657-VII of 24.10.2013 }
300.1. Single tax payers are responsible in accordance with this Code for the correct calculation, timeliness and completeness of payment of single tax amounts, as well as for the timeliness of submission of tax returns.
{Chapter 1 is included in Section XIV in accordance with Law No. 4014-VI of 04.11.2011 }
{Chapter 2 "Fixed Agricultural Tax" of Section XIV "Special Tax Regimes" was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Chapter 3 "Collection in the form of a targeted surcharge to the current tariff for electricity and heat, except for electricity produced by qualified cogeneration units" of Section XIV "Special tax regimes" was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Chapter 4 "Fees in the form of a targeted surcharge to the current tariff for natural gas for consumers of all forms of ownership" of Section XIV "Special tax regimes" was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Chapter XV "Fees for the use of radio frequency resources of Ukraine" was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Chapter XVI "Fees for Special Water Use" excluded pursuant to Law No. 71-VIII of 28.12.2014 }
{Chapter XVII "Fees for Special Use of Forest Resources" excluded pursuant to Law No. 71-VIII of 28.12.2014 }
CHAPTER XVIII. FEATURES OF TAXATION OF TAXPAYERS UNDER THE TERMS OF THE PRODUCTION SHARING AGREEMENT↑
Article 335. Procedure for taxation of an investor during the implementation of a production sharing agreement↑
335.1. During the term of the production sharing agreement and within the scope of activities related to the implementation of such an agreement, the collection from the investor of national and local taxes and fees provided for by this Code, except for those provided for in paragraph 335.2 of this Article, shall be replaced by the distribution of the produced products between the state and the investor under the terms of such an agreement.
Tax liabilities do not arise in the case of:
distribution of profitable and/or compensatory products and/or their cash equivalent between the investor (operator) and the state, transfer of profitable products belonging to the state to the operator (investor) for further sale;
{Paragraph three of clause 335.1 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
transfer of ownership from the investor (operator) to the state of property acquired or created by the investor for the implementation of the production sharing agreement and the cost of which is reimbursed by compensatory products or from the date of termination of the agreement, as well as the use of such property by the investor (operator) and its subsequent return to the state in accordance with the Law of Ukraine "On Production Sharing Agreements" and the agreement;
{Paragraph four of clause 335.1 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
transfer of property, including cash, by the parties to a production sharing agreement for use by the investor (operator) of the agreement within the framework of such an agreement, free use of such property by the investor (operator) of the agreement and/or return of such property by the investor (operator) to the relevant party to the agreement;
{Paragraph five of clause 335.1 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
distribution by the operator of compensatory and/or profitable products and transfer of their cash equivalent between investors;
{Paragraph six of clause 335.1 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
sale or other alienation by the investor (operator) of compensatory and/or profitable products, except for tax obligations on value added tax on transactions for the supply of compensatory and/or profitable products acquired by the investor (operator) as a result of its distribution under the agreement, and profitable products belonging to the state and transferred to the investor (operator) for further sale, which are determined taking into account Article 337 of this Code;
{Clause 335.1 of Article 335 is supplemented with a new paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
transfer of property, including cash, by the parties to a production sharing agreement to the investor (operator) to ensure the fulfillment of the terms of the production sharing agreement within the framework of such agreement and the return of such property by the investor (operator) to the relevant party to the agreement;
{Paragraph eight of clause 335.1 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
transfer (transfer) of funds and/or property by a non-resident investor to its permanent representative office to finance and ensure activities under a production sharing agreement in accordance with the work program and cost estimate under the agreement, other activities provided for by the agreement, as well as to fulfill other obligations under the agreement;
{Clause 335.1 of Article 335 is supplemented by paragraph nine in accordance with Law No. 5412-VI of 02.10.2012 }
free use by the investor (operator) within the framework of activities related to the implementation of the agreement of any property, including cash, geological, geophysical, geochemical, technical and economic information and other data, technologies and/or rights granted to the investor in accordance with the legislation and the agreement;
{Clause 335.1 of Article 335 is supplemented by paragraph ten in accordance with Law No. 5412-VI of 02.10.2012 }
use by the investor (operator) of products (in their natural state or processed) necessary for the performance of works and other activities provided for in the production sharing agreement, including the burning of products, or losses of such products related to the performance of works and other activities provided for in the agreement;
{Clause 335.1 of Article 335 is supplemented by the eleventh paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
free provision of goods, works, services or funds to the investor (operator) or by the investor (operator) during the term of the production sharing agreement and within the scope of activities related to the implementation of such an agreement, including the provision of additional benefits to employees, payment of bonuses or premiums in favor of the state and fulfillment of social obligations stipulated by the production sharing agreement;
{Clause 335.1 of Article 335 is supplemented by the twelfth paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
return by the investor (operator) of subsoil areas (parts thereof) in accordance with the legislation and the production sharing agreement.
{Clause 335.1 of Article 335 is supplemented by the thirteenth paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
During the term of the production sharing agreement and within the scope of activities related to the implementation of such agreement, the taxation of the investor (operator) shall be carried out taking into account the features established by this section of the Code and the production sharing agreement. In the event of discrepancies between the provisions of Section XVIII and other provisions of this Code, the rules provided for in Section XVIII of this Code shall apply.
{Clause 335.1 of Article 335 was supplemented with the fourteenth paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
335.2. During the implementation of the production sharing agreement, the investor (operator) shall pay the following taxes and fees:
{Paragraph one of clause 335.2 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
a) value added tax;
b) corporate income tax;
c) rent for the use of subsoil for the extraction of minerals.
{Subparagraph "c" of paragraph 335.2 of Article 335 as amended by Law No. 71-VIII of 28.12.2014 }
The investor is obliged to calculate, withhold and pay to the budget the tax on income of individuals from wages and other remunerations and payments accrued (paid) to the taxpayer in accordance with Section IV of this Code, taking into account Article 340 of this Code.
{Paragraph five of clause 335.2 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
A resident investor or non-resident investor (its permanent representative office) is obliged to register a production sharing agreement at its location as a taxpayer and, upon tax registration, submit a corresponding notification in writing and the following documents to the regulatory authority at its place of registration:
{Paragraph six of clause 335.2 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
a notarized copy of the registered production sharing agreement;
a copy of the certificate of state registration of the production sharing agreement.
After registration of the investor (operator) and the production sharing agreement as a taxpayer, the investor is obliged to prepare and submit tax declarations and reports provided for by law, and to be responsible for the proper performance of his duties related to the calculation and payment of taxes and fees, in the manner and amounts established by this Code. Tax declarations and reports are submitted by the investor for each tax, fee, payment separately from reports on the results of activities not related to the implementation of the production sharing agreement.
{Paragraph nine of clause 335.2 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
The form of the investor registration certificate and production sharing agreement as a taxpayer is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph ten of clause 335.2 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
In the event of a multilateral production sharing agreement with the participation of several investors, the rights and obligations to register as a taxpayer under the agreement, maintain separate tax and accounting records of transactions related to the implementation of the agreement, calculate and pay taxes and fees, and submit tax reports may be assigned to the operator, and in terms of value added tax - to each investor and/or the operator in accordance with the procedure specified in the agreement.
{Clause 335.2 of Article 335 is supplemented by the eleventh paragraph in accordance with Law No. 5412-VI of 02.10.2012 ; as amended in accordance with Laws No. 422-VII of 04.07.2013 , No. 1690-VII of 07.10.2014 }
The investor (operator) and his powers are determined in accordance with the procedure provided for by the legislation on production sharing.
{Clause 335.2 of Article 335 is supplemented by the twelfth paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
{Clause 335.2 of Article 335 as amended by Law No. 1797-VIII of 21.12.2016 }
335.3. The effect of this section does not apply (except for the cases provided for in Article 337 of this Code) to contractors and subcontractors, carriers and other persons, including foreign ones, who participate in the performance of works (provision of services) stipulated by the production sharing agreement on the basis of agreements (contracts) with the investor.
The specified persons shall pay taxes in accordance with the procedure established by this Code.
335.4. Tax accounting related to the performance of work (provision of services) stipulated in the production sharing agreement shall be conducted in accordance with this Code and the agreement, and separately from accounting for other types of activities.
{Paragraph one of clause 335.4 of Article 335 as amended by Law No. 5412-VI of 02.10.2012 }
If separate accounting is not maintained, the taxation procedure shall be applied without taking into account the features provided for in this section.
The rules provided for by this Code on taxation of joint activities, taxation under property management agreements, and taxation of long-term agreements (contracts) shall not apply to investors under a production sharing agreement within the scope of their activities under the agreement.
{Clause 335.4 of Article 335 was supplemented with the third paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
Article 336. Peculiarities of payment of income tax↑
336.1. Income tax is paid by the investor (operator) on the profit received by the investor (investors) from the performance of production sharing agreements, in the amounts established by this Code on the date of conclusion of the production sharing agreement, taking into account Article 340 of this Code and the following features:
{Paragraph one of clause 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
a) the object of taxation by corporate income tax is the profit of the investor (investors), which is determined based on the value of profitable products, determined in accordance with the legislation on the distribution of products, acquired by the investor (investors) and/or the operator as a result of the distribution of products, reduced by the amount of the single contribution paid by the investor to the mandatory state social insurance, as well as by the amount of other costs (including accumulated costs for the performance of work before the appearance of the first profitable products) related to the implementation of the agreement, but which are not reimbursed (not subject to reimbursement) by compensatory products in accordance with the agreement.
If the value of profitable products under a production sharing agreement is expressed in foreign currency, for the purposes of calculating corporate income tax, such value is converted into hryvnia in the manner prescribed by the production sharing agreement.
{Subparagraph "a" of paragraph 336.1 of Article 336 is supplemented by the second paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
Any other income received by the investor (operator) during the term of the agreement from activities related to the implementation of such an agreement is not considered an object of taxation and is not taken into account when determining it;
{Subparagraph "a" of paragraph 336.1 of Article 336 is supplemented by the third paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
{Subparagraph "a" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
b) the composition of costs reimbursed by compensatory products is determined in accordance with the legislation on production allocation.
Expenses for the acquisition of non-current assets and expenses for the performance of exploration, development and extraction of minerals are included in full at the time of their occurrence as part of expenses subject to reimbursement by compensatory products in accordance with the procedure provided for by the legislation on production sharing.
Other expenses related to the implementation of a production sharing agreement that are taken into account when calculating the object of taxation from activities related to the implementation of the agreement, but which are not reimbursed (not subject to reimbursement) by compensatory products in accordance with the agreement, shall be determined according to the rules provided for expenses taken into account when calculating the object of taxation in accordance with Section III of this Code, unless otherwise provided for in this Section or the production sharing agreement.
{Subparagraph "b" of paragraph 336.1 of Article 336 is supplemented with a new paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
A production sharing agreement may provide for indexation of other costs related to the implementation of the agreement, incurred in the period before the start of production sharing, which are taken into account when calculating the taxable amount, but which are not reimbursed (not subject to reimbursement) by compensatory products under the relevant agreement, in the manner provided for by the agreement.
{Subparagraph "b" of paragraph 336.1 of Article 336 is supplemented with a new paragraph in accordance with Law No. 5412-VI of 02.10.2012 }
The corporate income tax payable is determined and paid exclusively in cash;
c) if the investor's taxable object according to the results of the reporting period has a negative value, a corresponding reduction of the taxable object of the next period, as well as of each of the following periods, is allowed until such negative value of the taxable object is fully repaid, but not longer than the term of the production sharing agreement;
d) for non-current assets, the value of which is not compensated (is not subject to compensation) by compensatory products in accordance with the agreement, the investor shall apply the depreciation rules established in accordance with Section III of this Code.
The investor (operator) determines the corporate income tax payable at the end of each reporting tax period, based on tax accounting data;
{Paragraph two of subparagraph "d" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
e) corporate income tax from other activities not related to the performance of the production sharing agreement shall be paid by the investor in accordance with Section III of this Code.
The investor is obliged to maintain separate tax records for corporate income tax received from the implementation of the production sharing agreement and corporate income tax received from other activities not related to the implementation of this agreement;
e) corporate income tax benefits provided for in Section III of this Code shall not apply to the taxation of profits received by an investor during the performance of a production sharing agreement, unless otherwise provided for in the agreement.
Corporate income tax shall not be withheld from the income of a foreign investor with a source of origin in Ukraine, received from activities under a production sharing agreement, paid to the investor by his permanent establishment in accordance with Section III of this Code.
The funds and/or value of property transferred (transferred) by a non-resident investor to its permanent establishment to finance and support activities under a production sharing agreement in accordance with the work program and cost estimate are not subject to corporate income tax;
{Paragraph three of subparagraph "d" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
e) The basic tax (reporting) period for corporate income tax under a production sharing agreement is the calendar quarter.
{Paragraph one of subparagraph "e" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
The investor (operator) submits a quarterly income tax return for each reporting tax quarter. The rule on preparing tax reports and calculating the corporate income tax object on a cumulative basis does not apply.
{Paragraph of subparagraph "e" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
Corporate income tax for the reporting period is paid by the investor (operator) to the relevant budget within the period specified for the quarterly tax period.
{Paragraph of subparagraph "e" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
The obligation to file an annual tax return and pay advance income tax contributions to the investor (operator) under a production sharing agreement does not apply.
{Paragraph of subparagraph "e" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
Official confirmation of paid corporate income tax is provided to the investor upon his written request after the deadlines for payment of income tax no later than 10 calendar days from the date of receipt of such request by the regulatory authority in which such investor is registered;
g) the investor (operator) under a production sharing agreement is exempted from the obligation to submit financial statements and temporary and permanent tax differences together with the corporate income tax return;
{Subparagraph "e" of paragraph 336.1 of Article 336 as amended by Law No. 5412-VI of 02.10.2012 }
g) if a non-resident investor acts under a product distribution agreement through its representative office, the profit of such investor received from the performance of the agreement is taxed in accordance with this article of the Code and is not subject to taxation under the rules established by this Code for taxation of the profit of non-residents who carry out their activities in the territory of Ukraine through a permanent representative office.
{Clause 336.1 of Article 336 is supplemented by subparagraph "g" in accordance with Law No. 5412-VI of 02.10.2012 }
The procedure for submitting tax reports under such agreements shall be established in accordance with the procedure provided for in Article 46 of this Code.
Article 337. Peculiarities of payment of value added tax↑
337.1. Supply on the customs territory of Ukraine of compensatory and/or profitable products acquired by the investor (operator) as a result of their distribution under a production sharing agreement, and profitable products belonging to the state and transferred to the investor (operator) for further sale, is subject to value added tax, which is calculated and paid in the amounts, procedure and terms established by Section V of this Code on the date of conclusion of the production sharing agreement, taking into account Article 340 of this Code.
{Clause 337.1 of Article 337 as amended by Law No. 5412-VI of 02.10.2012 ; as amended by Laws No. 422-VII of 04.07.2013 , No. 1690-VII of 07.10.2014 }
337.2. If goods and other material assets intended for use within the framework of the implementation of a production sharing agreement are imported into the customs territory of Ukraine, taxes (except for excise tax) payable during customs clearance of goods shall not be collected under the customs import regime.
{Paragraph one of clause 337.2 of Article 337 as amended by Law No. 4915-VI of 07.06.2012 }
{Paragraph two of clause 337.2 of Article 337 was excluded on the basis of Law No. 5412-VI of 02.10.2012 }
Import into the customs territory of Ukraine of products (hydrocarbon raw materials, oil and gas) extracted in the exclusive (maritime) economic zone of Ukraine is carried out without paying taxes (including value added tax), provided that such raw materials are imported in accordance with a production sharing agreement.
Taking into account the requirements of Articles 21 and 22 of the Law of Ukraine "On Production Sharing Agreements", in the event of export by the investor (operator) from the customs territory of Ukraine of products distributed in accordance with the terms of such an agreement, customs duties, excise tax, other taxes and mandatory payments payable during customs clearance of goods are not collected, except for value added tax, which is collected at a zero rate.
{Paragraph four of clause 337.2 of Article 337 as amended by Law No. 5412-VI of 02.10.2012 }
In the event of export outside the customs territory of Ukraine for the purpose of fulfilling the transaction of goods and other material assets that were previously purchased by the investor in the customs territory of Ukraine, customs duties, excise tax, other taxes and mandatory payments are not collected, except for value added tax, which is collected at a zero rate.
{Paragraph five of clause 337.2 of Article 337 as amended by Law No. 5412-VI of 02.10.2012 }
When an investor receives services intended for the implementation of a production sharing agreement that are supplied by a non-resident in the customs territory of Ukraine, value added tax is not charged.
The taxation conditions provided for in this paragraph shall apply, within the scope of activities related to a production sharing agreement, also to legal entities and permanent establishments of non-residents (contractors, subcontractors, suppliers, carriers and other counterparties) that participate in the performance of work and other activities provided for by the production sharing agreement, on the basis of agreements (contracts) with the investor.
{Paragraph seven of clause 337.2 of Article 337 as amended by Law No. 5412-VI of 02.10.2012 }
In the event of the use of goods (works, services) and other material assets for purposes other than their intended purpose, the investor (contractors, subcontractors, suppliers, carriers and other counterparties) shall be charged with the amounts of taxes and fees not paid in connection with the provision of benefits, if such failure to fulfill obligations was due to the fault of the investor (contractors, subcontractors, suppliers, carriers and other counterparties).
{Paragraph eight of clause 337.2 of Article 337 as amended by Law No. 5412-VI of 02.10.2012 }
337.3. If the investor (operator) under a production sharing agreement considers it appropriate to voluntarily register as a value added tax payer, such registration shall be carried out upon his application.
{Clause 337.3 of Article 337 is supplemented with a new paragraph first in accordance with Law No. 5412-VI of 02.10.2012 ; as amended in accordance with Laws No. 422-VII of 04.07.2013 , No. 1690-VII of 07.10.2014 }
At the same time, if a multilateral production sharing agreement provides for the possibility of registering not only the operator, but also investors as value added tax payers under the agreement, such investors must submit registration applications in one reporting (tax) period by the 10th of the calendar month following the month in which the investors made the decision to register.
{Clause 337.3 of Article 337 is supplemented with a new paragraph in accordance with Law No. 1690-VII of 07.10.2014 }
If a new investor appears under a multilateral production sharing agreement under which all investors who do not act as operators are already registered as value added tax payers, such new investor is required to submit a registration application for registration as a value added tax payer under the agreement by the 10th day of the calendar month following the month in which such person acquired the rights and obligations of an investor.
{Clause 337.3 of Article 337 is supplemented with a new paragraph in accordance with Law No. 1690-VII of 07.10.2014 }
The operator is obliged to notify the regulatory authorities at its place of registration and at the place of registration of the relevant investors of the decision to register all investors as value added tax payers under the agreement within 10 calendar days after making such a decision.
{Clause 337.3 of Article 337 is supplemented with a new paragraph in accordance with Law No. 1690-VII of 07.10.2014 }
If an investor (its permanent establishment), registered as a value added tax payer, under a production sharing agreement submits to the regulatory authority a declaration (tax calculation) for this tax, which (which) indicates the absence of taxable supplies/acquisitions during twelve consecutive tax months, the registration of the value added tax payer is not cancelled.
{Paragraph of Clause 337.3 of Article 337 as amended by Law No. 5412-VI of 02.10.2012 }
337.4. The operator under a multilateral production sharing agreement includes in the tax credit the amounts of tax paid (accrued) by any investor (operator) under the agreement in connection with the purchase or manufacture of goods/services, fixed assets, based on tax invoices provided by investors or the operator, drawn up by suppliers, the purchase of which was carried out in accordance with programs and plans approved in accordance with the procedure specified in the production sharing agreements.
{Paragraph one of clause 337.4 of Article 337 as amended by Law No. 1797-VIII of 21.12.2016 }
If a relevant decision is made under a multilateral production sharing agreement, the operator who, in accordance with this paragraph, has the right to include the amount of paid (accrued) tax in the tax credit may determine the share of the balance of the negative value of the difference between the amount of tax liabilities and the amount of tax credit accumulated based on the results of previous reporting (tax) periods, which investors have the right to reflect in their tax returns, in the proportions determined in accordance with the agreement, provided that each investor is registered as a value added tax payer. In such a case:
a) in the reporting (tax) period, the operator increases its tax liabilities in the amount of the corresponding share of such negative value reflected in the operator's tax return for the previous reporting (tax) period, and sends the relevant investor a tax invoice for the relevant tax amount, which is filled out in accordance with the procedure approved by the central executive body that ensures the formation and implementation of state financial policy, taking into account the features defined by this paragraph of the Code, and also notifies the supervisory authorities at the place of registration of the operator and at the place of registration of each investor to whom the tax invoice was drawn up about such distribution within 10 calendar days after the drawing up of the relevant invoices.
{Paragraph three of paragraph 337.4 of Article 337 as amended by Law No. 1797-VIII of 21.12.2016 }
Such a tax invoice is subject to mandatory registration by the operator in the Unified Register of Tax Invoices;
{Paragraph four of clause 337.4 of Article 337 shall enter into force on January 1, 2015 - see clause 1 of section II of Law No. 1690-VII of 07.10.2014 }
b) the investor has the right to reflect the tax credit in the amount specified in the tax invoice drawn up by the operator in the tax return for the reporting (tax) period in which the tax invoice was drawn up, or in any subsequent reporting (tax) period, but no later than 90 calendar days from the date of drawing up the relevant tax invoice.
{Paragraph five of clause 337.4 of Article 337 as amended by Law No. 1797-VIII of 21.12.2016 }
If, as a result of a tax audit or as a result of the operator's own correction of errors, the amount of the operator's negative value of value added tax that was transferred in accordance with the requirements of this paragraph decreases, then:
a) the operator accordingly reduces the amount of tax liabilities based on the results of the current reporting (tax) period and sends the investor a tax adjustment calculation;
b) the investor shall accordingly reduce the amount of the tax credit based on the results of the reporting (tax) period in which the tax adjustment calculation was received, provided that he increased the tax credit based on the relevant tax invoice.
If the amount of value added tax calculated in accordance with this Code is negative, such amount shall be reimbursed to the investor (operator) in accordance with the procedure and terms provided for in the production sharing agreement approved by the Cabinet of Ministers of Ukraine.
{Paragraph nine of clause 337.4 of Article 337 as amended by Law No. 1797-VIII of 21.12.2016 }
{Article 337 is supplemented by paragraph 337.4 in accordance with Law No. 5412-VI of 02.10.2012 ; as amended by Law No. 1690-VII of 07.10.2014 ; as amended by Law No. 1797-VIII of 21.12.2016 }
{Article 337 as amended by Law No. 4915-VI of 07.06.2012 }
Article 338. Peculiarities of charging rent for the use of subsoil for the extraction of minerals↑
{Title of Article 338 as amended by Law No. 71-VIII of 28.12.2014 }
338.1. The procedure for calculating and rates of rent for the use of subsoil for the extraction of minerals, the conditions and procedure for its payment and submission of reports during the implementation of production sharing agreements are determined by such agreements.
{Paragraph one of clause 338.1 of Article 338 as amended by Law No. 71-VIII of 28.12.2014 }
The rates of rent for the use of subsoil for the extraction of minerals shall not be lower than those established by Section IX of this Code at the time of conclusion of the production sharing agreement, taking into account Article 340 of this Code.
{Paragraph two of clause 338.1 of Article 338 as amended by Law No. 71-VIII of 28.12.2014 }
The tax (reporting) period for rent for the use of subsoil for the extraction of minerals under a production sharing agreement is a calendar quarter.
{Paragraph three of clause 338.1 of Article 338 as amended by Law No. 71-VIII of 28.12.2014 }
The investor (operator) under a production sharing agreement maintains consolidated tax accounting and submits a tax return on the rent for the use of subsoil for the extraction of minerals, regardless of the number of special permits for the use of subsoil within the framework of the production sharing agreement.
{Paragraph four of clause 338.1 of Article 338 as amended by Law No. 71-VIII of 28.12.2014 }
Unless otherwise provided by the production sharing agreement, the investor (operator) under the production sharing agreement shall file a tax return on the rent for the use of subsoil for the extraction of minerals and pay the following rent to the budget:
{Paragraph five of clause 338.1 of Article 338 as amended by Law No. 71-VIII of 28.12.2014 }
by the location of the subsoil area from which the minerals were extracted, if such subsoil area is located within the territory of Ukraine;
at the place of registration of the payer in the event that the subsoil area from which the minerals were extracted is located within the continental shelf and/or exclusive (maritime) economic zone of Ukraine.
{Clause 338.1 of Article 338 as amended by Law No. 5412-VI of 02.10.2012 }
{Amendments to paragraph 338.1 of Article 338 of the Law No. 1797-VIII dated 21.12.2016 not included, for the entry into force of the changes see section II "Final and transitional provisions" }
338.2. Accounting for the amounts of rent accrued and paid by the investor for the use of subsoil for the extraction of minerals under the terms of a production sharing agreement shall be conducted in accordance with the procedure specified in the agreement.
{Clause 338.2 of Article 338 as amended by Law No. 71-VIII of 28.12.2014 }
Article 339. Peculiarities of control over the implementation of a production sharing agreement↑
339.1. Accounting of the financial and economic activities of the investor related to the performance of work (provision of services) stipulated by the production sharing agreement shall be carried out separately from accounting of other types of activities in order to avoid double reflection of the investor's compensation costs. The procedure for such accounting, the list of reports, in particular for the purpose of reimbursement of the investor's costs and calculation of profit tax, shall be determined by the production sharing agreement.
{Paragraph one of clause 339.1 of Article 339 as amended by Law No. 5412-VI of 02.10.2012 }
If, under a production sharing agreement, work is carried out on several subsoil areas, the investor maintains consolidated accounting of his business activities.
339.2. The investor's reports on activities related to the implementation of a production sharing agreement are subject to mandatory annual audit.
{Clause 339.2 of Article 339 as amended by Law No. 5412-VI of 02.10.2012 }
339.3. For the purpose of tax control, an investor who pays taxes and fees during the execution of a production sharing agreement is obliged to keep primary documents related to the calculation and payment of taxes for the storage period provided for by law.
Documentary checks of the investor's fulfillment of obligations to the budget for the payment of taxes and fees are carried out in accordance with this Code.
Article 340. Guarantees in the event of amendments to tax legislation↑
The State guarantees that the rights and obligations of the investor in fulfilling the tax obligations specified in the production sharing agreement will be subject to the legislation in force at the time of conclusion of the agreement, except in cases where the law reduces the amount of taxes or fees or abolishes taxes and fees. The law that reduces the amount of taxes or fees or abolishes taxes and fees shall be applied by the investor from the date of its entry into force.
Chapter XVIII - 1. OFFICIALS OF CONTROLLING BODIES AND THEIR LEGAL AND SOCIAL PROTECTION↑
341.1. Service in regulatory bodies is a professional activity of citizens of Ukraine who are suitable for it in terms of health, educational level and age, which is associated with the formation of state tax and customs policy in terms of the administration of taxes, fees, payments, the implementation of tax and customs policy, policy in the field of control over the production and circulation of alcohol, alcoholic beverages and tobacco products, as well as with the implementation of control over compliance with tax, customs and other legislation, control over which is entrusted to regulatory bodies.
342.1. An official of a controlling body may be a person who has a professional education and meets the qualification requirements established by the central executive body that ensures the formation and implementation of state financial policy, unless otherwise provided by law, and who is entrusted with the performance of tasks specified in this Code and the Customs Code of Ukraine .
{Clause 342.1 of Article 342 as amended by Law No. 1797-VIII of 21.12.2016 }
342.2. When hiring an official, a probationary period may be established in accordance with the Law of Ukraine "On Civil Service" .
by the Laws of Ukraine "On Civil Service" and "On Prevention of Corruption" may not be employed by regulatory bodies .
{Clause 342.3 of Article 342 as amended by Law No. 3603-IX of 23.02.2024 }
342.4. Officials of regulatory bodies are civil servants.
342.5. Officials who are recruited to serve in regulatory bodies for the first time and have not previously served in the civil service shall take the civil servant's oath in accordance with the Law of Ukraine "On Civil Service" .
342.6. The legal status of officials of regulatory bodies, their rights and obligations are determined by the Constitution of Ukraine , this Code and the Customs Code of Ukraine , and in the part not regulated by them - by the laws of Ukraine "On Civil Service" and "On Prevention of Corruption" and other laws.
{Clause 342.6 of Article 342 as amended by Law No. 3603-IX of 23.02.2024 }
342.7. Officials and employees of controlling bodies are issued with an official certificate, the sample of which is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 342.7 of Article 342 as amended by Law No. 1797-VIII of 21.12.2016 }
342.8. It is prohibited to impose duties on officials of regulatory bodies not provided for by law.
343.1. Officials of the central executive body implementing state tax policy, its territorial bodies and state tax inspectorates shall be awarded the following special ranks:
Chief State Tax Service Advisor;
State Tax Service Advisor, 1st rank;
State Tax Service Advisor, 2nd rank;
State Tax Service Advisor, III rank;
Tax Service Advisor, 1st rank;
Tax Service Advisor, 2nd rank;
Tax Service Advisor, III rank;
Tax inspector of the 1st rank;
Tax inspector of the 2nd rank;
Tax inspector of the III rank;
tax inspector of the IV rank;
junior tax inspector.
{Clause 343.1 of Article 343 as amended by Law No. 466-IX of January 16, 2020 }
343.2. Regulations on special ranks and the procedure for their assignment, correlation with the ranks of civil servants, and the amount of allowances for a special rank shall be approved by the Cabinet of Ministers of Ukraine.
{Paragraph one of clause 343.2 of Article 343 shall enter into force simultaneously with the Law "On Civil Service" of November 17, 2011 - see clause 1 of Section II of Law No. 404-VII of 04.07.2013 }
In the event that an official is awarded a special rank in accordance with paragraph 343.1 of this article, the civil servant rank allowance shall not be paid.
343.2 - 1. Officials of the central executive body implementing state tax policy, its territorial bodies and state tax inspectorates may be paid additional payments to the payments provided for by the Law of Ukraine "On Civil Service", the amount and procedure for establishing which are determined by the Cabinet of Ministers of Ukraine.
{Article 343 is supplemented by paragraph 343.2 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
343.3. Special ranks are awarded to officials for life. Deprivation of special ranks is carried out exclusively by court verdict in cases provided for by the Criminal Code of Ukraine.
343.4. Officials of regulatory bodies shall have uniforms with appropriate insignia, which shall be issued free of charge within the estimated costs. It is permitted for officials to have uniforms made with reimbursement of the costs of such making within the norms for providing uniforms from the funds provided in the state budget for the maintenance of the regulatory body.
Samples , standards for providing and terms of wearing uniforms are approved by the Cabinet of Ministers of Ukraine, and the rules for wearing them are approved by the central executive body that ensures the formation and implementation of state financial policy.
{Clause 343.4 of Article 343 as amended by Law No. 1797-VIII of 21.12.2016 }
Article 344. Pension provision for officials of supervisory bodies↑
344.1. Pension provision for officials of regulatory bodies shall be carried out in accordance with the procedure and under the conditions stipulated by the Law of Ukraine "On Civil Service" .
{Paragraph one of Clause 344.1 of Article 344 as amended by Law No. 1797-VIII of 21.12.2016 - applies from September 25, 2021 }
At the same time, the period of work of the specified persons (including those who have been awarded special ranks) in the regulatory bodies is counted towards the length of service in the civil service and length of service in positions classified as civil servant positions, which gives the right to a pension in accordance with the Law of Ukraine "On Civil Service" regardless of the place of work upon reaching the age stipulated by the specified Law.
Pensions assigned in accordance with the legislation are not paid to officials of regulatory bodies during their employment in these bodies.
{Clause 344.1 of Article 344 is supplemented by the third paragraph in accordance with Law No. 215-VIII of 02.03.2015 - the amendment is valid until December 31, 2015 inclusive, see clause 2 of Law No. 215-VIII of 02.03.2015 }
344.2. Pension provision for employees of regulatory bodies, their institutions and organizations who are not officials is carried out on the grounds and in the manner established by law.
Article 345. Protection of personal and property rights of officials of supervisory bodies↑
345.1. The state guarantees the protection of the life, health, honor, dignity and property of officials of regulatory bodies and members of their families from criminal and unlawful encroachments and other unlawful actions.
{Clause 345.1 of Article 345 as amended by Law No. 786-IX of July 14, 2020 }
345.2. Insulting an official of a regulatory body, threatening to kill, use violence, destroy property, and violent actions against an official of a regulatory body, as well as intentional destruction or damage to their property and other unlawful actions shall entail liability established by law.
Article 346. Compensation by the state for damage caused to an official of a regulatory body↑
346.1. Employees of the supervisory authority are subject to mandatory state social insurance in accordance with the legislation on mandatory state social insurance.
{Clause 346.1 of Article 346 as amended by Law No. 1200-VII of 10.04.2014 ; as amended by Law No. 54-VIII of 25.12.2014 }
346.2. {Clause 346.2 of Article 346 was excluded on the basis of Law No. 215-VIII of 02.03.2015 - the amendment is valid until December 31, 2015 inclusive, see clause 2 of Law No. 215-VIII of 02.03.2015 } In the event of the death of an official of a regulatory body in connection with the performance of his or her official duties, the family of the deceased or persons who were dependent on him or her shall be paid a one-time benefit in the amount of ten years of the deceased's salary in his or her last position at the expense of the Social Insurance Fund of Ukraine with subsequent recovery of this amount from the guilty persons.
{Clause 346.2 of Article 346 as amended by Laws No. 1200-VII of 10.04.2014 , No. 54-VIII of 25.12.2014 }
346.3. {Clause 346.3 of Article 346 was excluded on the basis of Law No. 215-VIII of 02.03.2015 - the amendment is valid until December 31, 2015 inclusive, see clause 2 of Law No. 215-VIII of 02.03.2015 } In the event of serious bodily injuries to an official of a regulatory body during the performance of official duties that prevent him from engaging in professional activities, this person shall be paid a one-time benefit in the amount of five years' salary for the last position at the expense of the Social Insurance Fund of Ukraine with subsequent recovery of this amount from the guilty persons.
{Clause 346.3 of Article 346 as amended by Laws No. 1200-VII of April 10, 2014 , No. 54-VIII of December 25, 2014 }
346.4. {Clause 346.4 of Article 346 was excluded on the basis of Law No. 215-VIII of 02.03.2015 - the amendment is valid until December 31, 2015 inclusive, see clause 2 of Law No. 215-VIII of 02.03.2015 } In the event of causing minor or moderate bodily injuries to an official of a regulatory body during the performance of his or her official duties, this person shall be paid a one-time benefit in the amount of one year's salary for the last position at the expense of the Social Insurance Fund of Ukraine with subsequent recovery of this amount from the guilty persons.
{Clause 346.4 of Article 346 as amended by Laws No. 1200-VII of April 10, 2014 , No. 54-VIII of December 25, 2014 }
{Clause 346.5 of Article 346 was excluded on the basis of Law No. 1200-VII of 10.04.2014 }
346.6. Damage caused to the property of an official of a regulatory body or members of his or her family in connection with the performance of his or her official duties shall be compensated in full from the state budget with subsequent recovery of this amount from the guilty persons.
346.7. Compensation for damage caused to the property of an official of a regulatory body or members of his or her family shall be carried out on the basis of a court decision.
346.8. To record actual expenses related to compensation for damage caused to the property of an official of a regulatory body or members of his or her family, regulatory bodies shall open special accounts in banking institutions.
{Clause 346.8 of Article 346 as amended by Law No. 1200-VII of 10.04.2014 }
Article 346 - 1. Remuneration of employees of the central executive body implementing state tax policy, its territorial bodies and state tax inspectorates↑
1. The state shall ensure a sufficient level of remuneration for civil servants and other employees of the central executive body implementing state tax policy, its territorial bodies and state tax inspectorates in order to create material conditions for their independent and conscientious performance of duties.
2. The salary of civil servants of the central executive body implementing state tax policy, its territorial bodies and state tax inspectorates consists of:
1) official salary;
2) long-service bonuses;
3) allowances for the rank of a civil servant or for a special title;
4) payments for additional workload in connection with the performance of duties of a temporarily absent civil servant in the amount of 50 percent of the official salary of the temporarily absent civil servant;
5) allowances for labor intensity;
6) bonuses for performing particularly important work;
7) allowances for personal qualifications;
8) bonuses for achieving personal key performance indicators;
9) awards.
3. The scheme of official salaries of civil servants of the central executive body implementing the state tax policy, its territorial bodies and state tax inspectorates shall be determined by the Cabinet of Ministers of Ukraine and shall not be included in the general scheme of official salaries of civil servants. The procedure for establishing, suspending, reducing or canceling the allowances specified in paragraphs 5-8 of part two of this article shall be determined by the Cabinet of Ministers of Ukraine.
For other categories of employees of the central executive body implementing state tax policy, its territorial bodies and state tax inspectorates, the terms of remuneration are determined by the legislation establishing the terms of remuneration for the relevant categories of employees.
{ Section XVIII - 1 supplemented by Article 346 - 1 in accordance with Law No. 466-IX of 16.01.2020 }
{Article 347 was excluded on the basis of Law No. 1200-VII of 10.04.2014 }
{The Code is supplemented by Section XVIII - 1 in accordance with Law No. 5083-VI of 05.07.2012 ; as amended Law No. 404-VII of 04.07.2013 }
Section XVIII - 2 . {Section XVIII - 2 excluded by Law No. 1797-VIII of 21.12.2016 - applicable from September 25, 2021 }↑
1. This Code shall enter into force on January 1, 2011, except for:
Subclause 20.1.15.2 of Clause 20.1 of Article 20 of this Code, which shall enter into force on January 1, 2015;
Article 39 of this Code, which shall enter into force on January 1, 2013;↑
paragraph three of clause 46.2 of Article 46, which shall enter into force on January 1, 2013;
{Paragraph four of clause 1 of section XIX as amended by Law No. 3609-VI of 07.07.2011 }
Section III of this Code, which shall enter into force on April 1, 2011;↑
{Paragraph six of clause 1 of section XIX was excluded on the basis of Law No. 1166-VII of 27.03.2014 }
Subparagraph 166.3.4 of paragraph 166.3 of Article 166 of this Code, which shall enter into force on January 1 of the year following the year in which the law on compulsory state social health insurance shall enter into force;
{Paragraph 1 of Section XIX was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
Article 265 of this Code, which shall enter into force on January 1, 2013;↑
{Paragraph nine of clause 1 of section XIX as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 24.05.2012 }
{Paragraph ten of clause 1 of section XIX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
2. To declare as invalid:
1) from January 1, 2011:
Law of Ukraine "On Excise Duty" (Vedomosti Verkhovna Rada of Ukraine, 1992, No. 12, p. 172);
Law of Ukraine "On the State Register of Individuals - Payers of Taxes and Other Mandatory Payments" (Vidomosti Verkhovnoi Rada of Ukraine, 1995, No. 2, Art. 10; 1999, No. 41, Art. 374; 2003, No. 23, Art. 149);
Law of Ukraine "On Excise Duty on Alcoholic Beverages and Tobacco Products" (Vidomosti Verkhovnoi Rada of Ukraine, 1995, No. 40, p. 297 with subsequent amendments);
Law of Ukraine "On Patenting Certain Types of Business Activities" (Vedomosti Verkhovna Rada of Ukraine, 1996, No. 20, Art. 82 with subsequent amendments);
Law of Ukraine "On Excise Duty Rates on Certain Vehicles and Bodies for Them" (Vidomosti Verkhovnoi Rada of Ukraine, 1996, No. 32, Art. 151; 1997, No. 34, Art. 212; 1999, No. 52, Art. 464; 2001, No. 4, Art. 16; 2005, NN 17-19, Art. 267; 2007, No. 3, Art. 31; 2009, No. 18, Art. 246);
Law of Ukraine "On rates of excise duty and import duty on certain goods (products)" (Vidomosti Verkhovnoi Rada of Ukraine, 1996, No. 42, p. 201 with subsequent amendments);
Law of Ukraine "On Payment for Land" (Vedomosti Verkhovna Rada of Ukraine, 1992, No. 38, p. 360 with subsequent amendments);
Law of Ukraine "On the Taxation System" (Vedomosti Verkhovna Rada of Ukraine, 1991, No. 39, p. 510 with subsequent amendments);
Law of Ukraine "On Value Added Tax" (Vedomosti Verkhovna Rada of Ukraine, 1997, No. 21, p. 156 with subsequent amendments);
Law of Ukraine "On Fixed Agricultural Tax" (Vidomosti Verkhovnoi Rada of Ukraine, 1999, No. 5-6, Art. 39 with subsequent amendments);
Law of Ukraine "On Excise Duty Rates on Tobacco Products" (Vidomosti Verkhovnoi Rada of Ukraine, 1996, No. 8, Art. 32 with subsequent amendments);
Law of Ukraine "On an economic experiment on stabilizing the work of enterprises of the light and woodworking industry of Chernivtsi region" (Vidomosti Verkhovnoi Rada of Ukraine, 2000, No. 10, p. 78);
Law of Ukraine "On excise duty rates on ethyl alcohol and alcoholic beverages" (Vidomosti Verkhovnoi Rada of Ukraine, 2000, No. 23, p. 180 with subsequent amendments);
Law of Ukraine "On the Procedure for Repayment of Taxpayers' Liabilities to Budgets and State Target Funds" (Vidomosti Verkhovnoi Rada of Ukraine, 2001, No. 10, Art. 44 with subsequent amendments);
Law of Ukraine "On Personal Income Tax" (Vidomosti Verkhovnoi Rada of Ukraine, 2003, No. 37, p. 308 with subsequent amendments);
Law of Ukraine "On Tax on Owners of Vehicles and Other Self-Propelled Machines and Mechanisms" (Vidomosti Verkhovnoi Rada of Ukraine, 1992, No. 11, p. 150 with subsequent amendments);
paragraphs 4, 5, 7, 8, 8 - 1 and 8 - 2 of section II "Final Provisions", annexes No. 1 and No. 2 to the Law of Ukraine "On Amendments to Certain Legislative Acts of Ukraine" (Vidomosti Verkhovnoi Rada of Ukraine, 2008, No. 27-28, p. 253; 2009, No. 16, p. 223; 2010, Nos. 22-25, p. 263, No. 30, p. 398);
Decree of the Cabinet of Ministers of Ukraine dated December 26, 1992 No. 18-92 "On Excise Duty" (Vidomosti Verkhovnoi Rada of Ukraine, 1993, No. 10, p. 82 with subsequent amendments);
Decree of the Cabinet of Ministers of Ukraine dated March 17, 1993 No. 24-93 "On Fishing Tax" (Vidomosti Verkhovnoi Rada of Ukraine, 1993, No. 19, p. 208; 1995, No. 16, p. 111, No. 30, p. 229; 1996, No. 45, p. 237);
Decree of the Cabinet of Ministers of Ukraine dated May 20, 1993 No. 56-93 "On Local Taxes and Fees" (Vidomosti Verkhovnoi Rada of Ukraine, 1993, No. 30, p. 336 with subsequent amendments);
Resolution of the Verkhovna Rada of the Ukrainian SSR of June 25, 1991 No. 1252-XII "On the procedure for introducing into force the Law of the Ukrainian SSR "On the Taxation System" (Vidomosti Verkhovnoi Rada of Ukraine, 1991, No. 39, p. 511);
Resolution of the Verkhovna Rada of Ukraine dated December 11, 1991 No. 1964-XII "On the introduction into force of the Law of Ukraine "On Tax on Owners of Vehicles and Other Self-Propelled Machines and Mechanisms" (Vidomosti Verkhovnoi Rada of Ukraine, 1992, No. 11, p. 151);
Resolution of the Verkhovna Rada of Ukraine dated December 18, 1991 No. 1997-XII "On the procedure for bringing into force the Law of Ukraine "On Excise Duty" (Vidomosti Verkhovnoi Rada of Ukraine, 1992, No. 12, p. 173);
Resolution of the Verkhovna Rada of Ukraine dated February 21, 1992 No. 2148-XII "On excise duty rates on certain goods" (Vidomosti Verkhovna Rada of Ukraine, 1992, No. 21, p. 298; 1993, No. 20, p. 214);
Resolution of the Verkhovna Rada of Ukraine dated July 3, 1992 No. 2536-XII "On the Entry into Force of the Law of Ukraine "On Payment for Land" (Vidomosti Verkhovna Rada of Ukraine, 1992, No. 38, p. 561);
Resolution of the Verkhovna Rada of Ukraine dated December 22, 1994 No. 321/94-VR "On the Entry into Force of the Law of Ukraine "On the State Register of Individuals - Payers of Taxes and Other Mandatory Payments" (Vidomosti Verkhovna Rada of Ukraine, 1995, No. 2, p. 11);
Resolution of the Verkhovna Rada of Ukraine dated December 28, 1994 No. 335/94-VR "On the Entry into Force of the Law of Ukraine "On Taxation of Enterprise Profits" (Vidomosti Verkhovna Rada of Ukraine, 1995, No. 4, p. 29, No. 16, p. 116);
Resolution of the Verkhovna Rada of Ukraine dated September 15, 1995 No. 330/95-VR "On the procedure for introducing into force the Law of Ukraine "On Excise Duty on Alcoholic Beverages and Tobacco Products" (Vidomosti Verkhovna Rada of Ukraine, 1995, No. 40, p. 298; 1996, No. 41, p. 197);
Resolution of the Verkhovna Rada of Ukraine dated February 6, 1996 No. 31/96-VR "On the introduction into force of the Law of Ukraine "On rates of excise duty and import duty on tobacco products" (Vidomosti Verkhovna Rada of Ukraine, 1996, No. 8, p. 33);
Resolution of the Verkhovna Rada of Ukraine dated March 23, 1996 No. 99/96-VR "On the Entry into Force of the Law of Ukraine "On Patenting Certain Types of Business Activities" (Vidomosti Verkhovnoi Rada of Ukraine, 1996, No. 20, p. 83, No. 32, p. 153, No. 38, p. 176);
Resolution of the Verkhovna Rada of Ukraine dated May 7, 1996 No. 179/96-VR "On the introduction into force of the Law of Ukraine "On rates of excise duty and import duty on ethyl alcohol and alcoholic beverages" (Vidomosti Verkhovnoi Rada of Ukraine, 1996, No. 28, p. 132);
Resolution of the Verkhovna Rada of Ukraine dated May 24, 1996 No. 217/96-VR "On the introduction into force of the Law of Ukraine "On rates of excise duty and import duty on certain vehicles and tires for them" (Vidomosti Verkhovna Rada of Ukraine, 1996, No. 32, p. 152);
2) from April 1, 2011:
Law of Ukraine "On Taxation of Enterprise Profits" (Vidomosti Verkhovnoi Rada of Ukraine, 1995, No. 4, Art. 28 with subsequent amendments), except for Clause 1.20 of Article 1 of this Law , which is in force until January 1, 2013;
3) excluded;
4) from January 1, 2017, Article 209 of this Code;
{Subparagraph 4 of paragraph 2 of Section XIX as amended by Law No. 909-VIII of 24.12.2015 }
5) from January 1, 2013, the Law of Ukraine "On the Collection for the Development of Viticulture, Horticulture and Hop Growing" (Vidomosti Verkhovnoi Rada of Ukraine, 1999, No. 20-21, p. 191; 2003, No. 46, p. 365; 2009, No. 29, p. 397; 2012, No. 6, p. 50, No. 24, p. 248; as amended by the Law of Ukraine of October 16, 2012 No. 5463-VI).
{Clause 2 of Section XIX is supplemented by a paragraph in accordance with Law No. 5519-VI of 06.12.2012 }
3. In connection with the entry into force of this Code, the following shall cease to apply in accordance with paragraph 4 of Section XV "Transitional Provisions" of the Constitution of Ukraine :
from January 1, 2011:
1) Presidential Decree No. 453/98 of May 11, 1998 "On payers and the procedure for paying excise duty";
2) Decree of the President of Ukraine dated June 28, 1999 No. 761/99 "On streamlining the mechanism for paying the market fee".
4. The Cabinet of Ministers of Ukraine:
to introduce, starting from January 1, 2011, a mechanism for compensating for the loss of part of the income due to the abolition of the tax on owners of vehicles and other self-propelled machines and mechanisms and the corresponding increase in excise duty rates on fuel for individuals who used privileges for paying the tax on owners of vehicles for one passenger car (motorcycle) with an engine cylinder capacity of up to 2,500 cubic centimeters or one motorcycle with an engine cylinder capacity of up to 750 cubic centimeters or one motor boat or speedboat (except for sports) with a hull length of up to 7.5 meters, namely the following persons:
in paragraphs 1 and 2 of part one of Article 14 of the Law of Ukraine "On the Status and Social Protection of Citizens Affected by the Chernobyl Disaster" ;
Articles 4-11 of the Law of Ukraine "On the Status of War Veterans, Guarantees of Their Social Protection" ;
Articles 6 and 8 of the Law of Ukraine "On the Basic Principles of Social Protection of Labor Veterans and Other Elderly Citizens in Ukraine" ;
persons with disabilities, regardless of disability group (including children with disabilities upon submission by social protection bodies).
{ Paragraph seven of clause 4 of section XIX "Final provisions" is excluded on the basis of the Law No. 1791-VIII dated 20.12.2016 }
{Paragraph eight of clause 4 of section XIX "Final provisions" was excluded on the basis of Law No. 5083-VI of 05.07.2012 }
annually by June 1, if necessary, submit to the Verkhovna Rada of Ukraine a draft law on amendments to this Code regarding tax rates determined in absolute values, taking into account consumer price indices, producer price indices of industrial products for the following taxes and fees:
{Paragraph nine of clause 4 of section XIX as amended by Law No. 2245-VIII of 07.12.2017 }
1) excise tax;
{Subparagraph 1, paragraph 4, section XIX as amended by Law No. 71-VIII of 28.12.2014 }
2) environmental tax;
{Subparagraph 2, paragraph 4, section XIX as amended by Law No. 71-VIII of 28.12.2014 }
3) rent;
{Subparagraph 3, paragraph 4, section XIX as amended by Law No. 71-VIII of 28.12.2014 }
by December 31, 2011, together with interested religious organizations, develop a program and submit proposals to the Verkhovna Rada of Ukraine regarding alternative registration of individuals who, due to their religious beliefs, refuse an identification number (registration number of the taxpayer's registration card);
simultaneously with the submission to the Verkhovna Rada of Ukraine of the draft law on the State Budget of Ukraine for 2011, submit a draft law on amendments to the Budget Code of Ukraine in order to bring its norms into line with the Tax Code of Ukraine, including on transferring part of the environmental tax (in 2013 - 33 percent, from 2014 - 50 percent) to a special fund of the State Budget of Ukraine with the allocation of such funds exclusively to financing targeted projects for the environmental modernization of enterprises within the limits of the amounts of the environmental tax paid by them in accordance with the procedure to be established by the Cabinet of Ministers of Ukraine.
5. Local self-government bodies shall ensure, within one month from the date of entry into force of this Code, the adoption of decisions on the establishment of local taxes and fees specified in this Code.
In the event that local taxes and fees provided for in paragraph 10.3 of Article 10 of this Code are not established by decisions of local self-government, such taxes and fees shall be paid by payers in the manner established by this Code at minimum rates and without the application of relevant coefficients.
Subsection 1. Peculiarities of personal income tax collection↑
1. Personal income tax accrued but not paid by a tax agent to the budget contrary to the procedure in force prior to the entry into force of this Code shall, on the date of entry into force of this Code, be considered a tax debt under an agreed tax obligation and shall be reflected in the tax calculation based on the results of the first reporting quarter during which this Code enters into force, and shall also be collected from the tax agent with the application of liability measures provided for by this Code.
2. Investment losses incurred by a personal income tax payer as of January 1 of the year of entry into force of this Code shall be taken into account when calculating investment profits received from transactions with securities or derivatives traded on an organized securities market, starting from the results for such year in respect of losses incurred as a result of the sale of investment assets through professional securities traders. The obligation to provide documentary evidence of the amount of said losses shall be borne by the taxpayer.
3. The following funds are not subject to personal income tax: payments for work and/or services performed and provided in Ukraine or abroad during the preparation and holding in Ukraine of the final part of the 2012 European Football Championship, in particular (but not exclusively) in the form of wages, reimbursement of expenses and daily allowances to the following persons (except residents of Ukraine, regardless of their participation in the said championship):
{Paragraph one of clause 3, subsection 1, section XX, as amended by Law No. 3292-VI of 21.04.2011 }
representatives or officials of UEFA member associations;
members of delegations participating in the championship, including members of teams that have qualified for the championship;
individuals accredited by UEFA.
Income of other non-residents received during the preparation and holding of the championship from sources originating in Ukraine is subject to taxation on a general basis, taking into account the provisions of international treaties of Ukraine on the elimination of double taxation of income, the binding nature of which has been approved by the Verkhovna Rada of Ukraine.
{Paragraph five of clause 3, subsection 1, section XX as amended by Law No. 3292-VI of 21.04.2011 }
4. The funds that, in accordance with the law regulating the establishment and functioning of banking management funds, are paid during the period of validity of this Law to individuals under trust management agreements concluded with participants in banking management funds and pension deposit agreements concluded during the period of such an experiment are not subject to personal income tax (except for cases when funds are withdrawn by such individuals in violation of the terms of the pension deposit or banking management fund, respectively).
{Paragraph one of clause 4, subsection 1, section XX, as amended by Law No. 3609-VI of 07.07.2011 }
To establish that for the period of validity of the law regulating the establishment and functioning of banking management funds, the following income shall not be subject to this tax (shall not be reflected in his annual tax return) and shall not be included in the total monthly or annual taxable income of the taxpayer within the limits established by this Code:
{Paragraph two of clause 4, subsection 1, section XX, as amended by Law No. 3609-VI of 07.07.2011 }
income that was accrued to the taxpayer in accordance with the terms of an employment or civil law contract and subsequently transferred to his pension contribution or to his account as a participant in a banking management fund opened in accordance with the law, both at the time of their accrual and at the time of their transfer to such contribution or such account;
funds accrued and deposited by a person who is not a taxpayer or his employer (third party) in favor of a taxpayer into a pension deposit or a participant's account of a bank management fund of such taxpayer;
funds transferred by an individual to his/her own pension deposit or to his/her own account in the bank management fund or to the pension deposit or to the account in the bank management fund of family members of such individual in the first degree of kinship;
income accrued to the taxpayer under a pension deposit agreement or a trust management agreement concluded with an authorized bank in accordance with the law.
{Paragraph seven of clause 4, subsection 1, section XX was excluded on the basis of Law No. 3609-VI of 07.07.2011 }
5. If the provisions of other laws contain a reference to the non-taxable minimum income of citizens, then for the purposes of their application, the amount of 17 hryvnias is used, except for the provisions of administrative and criminal legislation regarding the qualification of administrative or criminal offenses, for which the amount of the non-taxable minimum is set at the level of the tax social benefit determined by subparagraph 169.1.1 of paragraph 169.1 of Article 169 of Section IV of this Code for the relevant year.
{Clause 5, Subsection 1, Section XX, as amended by Law No. 5412-VI of 02.10.2012 }
{Item 6 of Subsection 1 of Section XX was excluded pursuant to Law No. 5211-VI of 06.09.2012 }
7. For the period from April 1 to July 1, 2014, suspend the effect of subparagraph 164.2.8 of paragraph 164.2 of Article 164 of this Code in terms of inclusion in the total monthly (annual) taxable income in the form of interest on a current or deposit (deposit) bank account, a deposit (deposit) in non-bank financial institutions in accordance with the law or on a deposit (savings) certificate and paragraphs two to four of paragraph 167.2 of Article 167 of this Code in terms of taxation of interest.
{Subsection 1 of Section XX supplemented by paragraph 7 in accordance with Law No. 1200-VII of 10.04.2014 }
8. The amount forgiven (cancelled) by the creditor in the amount of the difference between the principal amount of the debt under a financial loan in foreign currency, determined at the official exchange rate of the National Bank of Ukraine on the date of the currency change of the obligation under such loan from foreign currency to hryvnia, and the amount of such debt, determined at the official exchange rate of the National Bank of Ukraine as of January 1, 2014, as well as the amount of interest, commission and/or penalties (penalties) on such loans, forgiven (cancelled) by the creditor by his independent decision, not related to his bankruptcy procedure, before the expiration of the limitation period, shall not be considered an additional benefit of the taxpayer and shall not be included in the calculation of the total monthly (annual) taxable income. The provisions of this paragraph shall apply to financial loans in foreign currency, not repaid by January 1, 2014.
The effect of the first paragraph of this paragraph applies to transactions for the forgiveness (cancellation) of the debt by the creditor to the debtor under a financial loan in foreign currency, carried out starting from January 1, 2015.
{Subsection 1 of Section XX supplemented by paragraph 8 in accordance with Law No. 321-VIII of 09.04.2015 }
9. Temporarily, for the period of implementation of the project to modernize the Bortnytsia Wastewater Treatment Plant within the framework of the project "Reconstruction of wastewater treatment facilities and construction of a technological line for the treatment and utilization of sludge of the Bortnytsia Aeration Plant", approved by the Cabinet of Ministers of Ukraine (hereinafter referred to as the Project), income accrued (paid, provided) to Japanese citizens (regardless of their residency status) by Japanese entities for the implementation of the Project in the form of wages and/or remuneration under civil law contracts shall not be subject to personal income tax. The specified exemption applies only to that part of the income related to the implementation of the Project.
The Japanese entity implementing the Project may be:
a) a legal entity that is a resident of Japan and registered in accordance with the laws of Japan;
b) a permanent representative office registered in Ukraine of a legal entity that is a resident of Japan and registered in accordance with the laws of Japan;
c) a legal entity that is a subsidiary of a legal entity that is a resident of Japan and is registered in accordance with the laws of Japan;
d) an agreement on joint activities, one or more participants of which (with more than 50 percent participation in such an agreement) are persons specified in subparagraphs "a"-"c" of this paragraph, concluded solely for the purpose of carrying out joint activities to implement the Project.
The definition of the term "Japanese Project Implementing Entity" applies in paragraph 46 of subsection 2, paragraph 38 of subsection 4, and paragraph 16 - 1 of subsection 10 of this section.
If the Japanese entity implementing the Project is a joint activity agreement, one or more participants of which (with more than 50 percent participation in such agreement) are persons specified in subparagraphs "a"-"c" of this paragraph, the rules of this paragraph apply exclusively to income of Japanese citizens accrued (paid, provided) by the operator of such joint activity.
{Subsection 1 of Section XX supplemented by paragraph 9 in accordance with Law No. 903-VIII of 23.12.2015 }
10. The total monthly (annual) taxable income of an individual income tax payer does not include income received before June 1, 2018 from a source of origin in Ukraine, and foreign income received for work and/or services performed and provided in Ukraine or abroad for the purposes of preparing and holding in Ukraine the final matches of the UEFA Champions League and the UEFA Women's Champions League of the 2017/2018 season, in particular, but not exclusively, in the form of wages, reimbursement of expenses and per diems, payment for accommodation, provision of medical insurance and/or life insurance to such persons or third parties for the benefit of such persons (except for residents of Ukraine within the meaning of subparagraph 14.1.213 of paragraph 14.1 of Article 14 of this Code), regardless of their participation in holding the specified final matches:
representatives or officials of UEFA member associations;
members of delegations participating in the final matches of the championship, including members of teams that have qualified for the final matches;
individuals accredited by UEFA, including employees and temporary workers, media representatives, UEFA partners, and sponsor representatives.
For the purposes of this clause, the term "UEFA" is used to mean "Union of European Football Associations".
Income of other non-residents received before June 1, 2018 from sources originating in Ukraine is subject to taxation on a general basis, taking into account the provisions of international treaties of Ukraine on the avoidance of double taxation, the binding nature of which has been approved by the Verkhovna Rada of Ukraine.
{Subsection 1 of Section XX supplemented by paragraph 10 in accordance with Law No. 2374-VIII of 22.03.2018 }
11. To establish that, based on the results of 2020, 2021 and 2022, when exercising the right to a tax discount in accordance with the provisions of Article 166 of this Code, the amount of funds or the cost of medicines for providing medical care to patients, disinfectants and antiseptics, medical equipment, personal protective equipment, medical products for screening patients, consumables for providing medical care, medical products, laboratory equipment, consumables, reagents for laboratory tests; medical products, laboratory equipment, consumables for infectious departments, pathological departments, etc., personal hygiene products, food products and/or goods according to the list determined by the Cabinet of Ministers of Ukraine, which are voluntarily transferred (transferred) to public associations and/or charitable organizations and/or the central executive body implementing state policy in the field of health care, and/or other central executive bodies implementing state policy in the areas of sanitary and epidemic well-being of the population, quality control and safety of medicines, combating HIV/AIDS and other socially dangerous diseases, and/or to a person authorized to make purchases in the field of health care, and/or to health care institutions of state and/or municipal ownership, and/or to structural units on health care of regional, Kyiv and Sevastopol city state administrations during the quarantine introduced by the Cabinet of Ministers of Ukraine in in accordance with the procedure established by law, throughout the territory of Ukraine in order to prevent the spread of coronavirus disease (COVID-19) in the territory of Ukraine, is included in the tax discount in full, without taking into account the restrictions specified in subparagraph 166.3.2 of paragraph 166.3 of Article 166 of this Code.
{Subsection 1 of Section XX supplemented by paragraph 11 in accordance with Law No. 540-IX of 30.03.2020 ; as amended in accordance with Law No. 1914-IX dated 30.11.2021 }
12. Temporarily, the amounts of personal income tax withheld from income in the form of wage supplements determined in accordance with subparagraph 2 of paragraph 5 of Section II of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Supporting Taxpayers for the Period of Implementing Measures Aimed at Preventing the Occurrence and Spread of Coronavirus Disease (COVID-19)", and accrued for the periods from May 1 to 31 and from June 1 to 30, 2020 to medical and other employees of state and/or municipally owned healthcare institutions who are directly engaged in eliminating the epidemic and implementing measures to prevent the spread of acute respiratory disease COVID-19 caused by the SARS-CoV-2 coronavirus, and treating patients with cases of acute respiratory disease COVID-19 caused by the SARS-CoV-2 coronavirus, according to the list determined by the central executive body implementing state policy in the field of healthcare, are compensated to such employees in full from the state budget of Ukraine. The procedure for paying such monetary compensation is approved by the Cabinet of Ministers of Ukraine.
{Subsection 1 of Section XX supplemented by paragraph 12 in accordance with Law No. 591-IX of 13.05.2020 }
13. For the period from April 2, 2020, the total monthly (annual) taxable income of a personal income tax payer does not include income in the form of partial unemployment benefits for the quarantine period established by the Cabinet of Ministers of Ukraine in order to prevent the spread of acute respiratory disease COVID-19, caused by the SARS-CoV-2 coronavirus, in the territory of Ukraine, which are paid (provided) by the employer in accordance with Article 47 - 1 of the Law of Ukraine "On Employment of the Population".
{Subsection 1 of Section XX supplemented by paragraph 13 in accordance with Law No. 591-IX of 13.05.2020 }
14. Temporarily, the total monthly (annual) taxable income of a personal income tax payer for the 2020-2021 tax (reporting) periods does not include income in the form of income in cash and/or other property form received as a result of the liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity by the taxpayer:
1) a shareholder (participant, partner, shareholder, founder, controlling person) of a foreign legal entity or a foreign entity without the status of a legal entity if all of the following conditions are met:
a) the procedure for liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity was initiated no earlier than January 1, 2020 and completed no later than December 31, 2021;
b) the taxpayer submitted to the regulatory authority, simultaneously with the tax return for the relevant tax (reporting) year, an application drawn up in an arbitrary form for the exemption of such income from taxation, indicating the characteristics of the received property and the liquidated (terminated) foreign legal entity or foreign entity without the status of a legal entity, as well as documents containing information on the value of the received property, in accordance with the financial statements of the foreign legal entity or foreign entity without the status of a legal entity, drawn up in accordance with international financial reporting standards, as of the date of the decision to distribute property as income payment in connection with the liquidation (termination) of the foreign legal entity or foreign entity without the status of a legal entity;
c) a foreign legal entity or a foreign entity without the status of a legal entity was established on the basis of a transaction or law of a foreign state (territory) no later than May 23, 2020 or was registered no later than May 23, 2020 in accordance with the legislation of a foreign state (territory) if, in accordance with the legislation of such foreign state (territory), regulatory requirements and/or documents regulating the activities (personal law) of such a foreign legal entity or a foreign entity without the status of a legal entity, such a person (entity) is subject to registration in the relevant state (territory);
2) the ultimate beneficial owner (controller) from the nominal holder (nominal owner) within the meaning of clause 103.3 of Article 103 of this Code, provided that the requirements of subparagraphs "a" - "c" of subparagraph 1 of this clause are met. In this case, the taxpayer, in addition to the information and documents provided for in subparagraph "b" of subparagraph 1 of this clause, is obliged to provide documents confirming the receipt of such income from the nominal holder (nominal owner) in connection with the liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity.
Regarding income in cash received as a result of the liquidation (termination) of a foreign legal entity or a foreign entity without the status of a legal entity by a taxpayer - shareholder (participant, partner, shareholder, founder, controlling person) of a foreign legal entity or a foreign entity without the status of a legal entity, all measures are taken to establish the sources of origin of such income in accordance with the legislation in the field of financial monitoring.
{Item 14 of subsection 1 of section XX is supplemented by paragraph seven in accordance with the Law No. 1539-IX dated 15.06.2021 }
{Subsection 1 of Section XX supplemented by paragraph 14 in accordance with Law No. 786-IX of July 14, 2020 ; as amended by Law No. 1117-IX of December 17, 2020 }
15. The total monthly (annual) taxable income of a personal income tax payer does not include income in the form of one-time material assistance to insured persons, which is paid (provided) to such a taxpayer at the expense of the state budget in accordance with Article 2 of the Law of Ukraine "On social support for insured persons and business entities for the period of implementation of restrictive anti-epidemic measures introduced to prevent the spread of acute respiratory disease COVID-19, caused by the SARS-CoV-2 coronavirus, in the territory of Ukraine."
{Subsection 1 of Section XX supplemented by paragraph 15 in accordance with Law No. 1072-IX of 04.12.2020 }
16. The total monthly (annual) taxable income of a personal income tax payer does not include income paid (provided) by the employer at the expense of one-time material assistance to business entities, which is paid at the expense of the state budget in accordance with Article 3 of the Law of Ukraine "On social support for insured persons and business entities for the period of implementation of restrictive anti-epidemic measures introduced to prevent the spread of acute respiratory disease COVID-19, caused by the SARS-CoV-2 coronavirus, in the territory of Ukraine."
{Subsection 1 of Section XX supplemented by paragraph 16 in accordance with Law No. 1072-IX of 04.12.2020 }
17. The total monthly (annual) taxable income of a personal income tax payer does not include:
the amounts of arrears from the single contribution for compulsory state social insurance, as well as the amounts of penalties and fines accrued on these amounts of arrears, written off to the payer of the single contribution in accordance with paragraphs 9 - 15 of Section VIII of the Law of Ukraine "On the Collection and Accounting of the Single Contribution for Compulsory State Social Insurance";
amounts written off in accordance with paragraphs 2 - 3 , 2 - 4 and subparagraph 26.2 of paragraph 26 of subsection 10 of section XX of this Code.
{Paragraph three of clause 17, subsection 1, section XX, as amended by Law No. 1617-IX of 01.07.2021 }
{Subsection 1 of Section XX supplemented by paragraph 17 in accordance with Law No. 1072-IX of 04.12.2020 }
18. The total monthly (annual) taxable income of a personal income tax payer does not include the amounts of income received by the taxpayer in the form of partial or full compensation of interest (percentage) rates, which is paid within the framework of the budget program "Ensuring the functioning of the Entrepreneurship Development Fund" and the state program for the implementation of financial and credit mechanisms for providing citizens with housing on the terms determined by the Cabinet of Ministers of Ukraine, as well as the amounts of funds received by the taxpayer on a non-refundable basis from the Innovation Development Fund.
{Subsection 1 of Section XX supplemented by paragraph 18 in accordance with Law No. 1914-IX of 11/30/2021 }
19. Income received by a taxpayer from the sale (alienation) of property rights or received as a result of the performance of an obligation, the right of claim for which was certified by the relevant property rights, may be reduced by the value of such property rights that was declared by the person as the object of declaration under the procedure of a one-time (special) voluntary declaration in accordance with Subsection 9 - 4 of Section XX of this Code.
{Subsection 1 of Section XX supplemented by paragraph 20 in accordance with Law No. 1914-IX of 11/30/2021 }
20. To establish that, based on the results of 2021 and 2022, when exercising the right to a tax discount in accordance with the provisions of Article 166 of this Code, the taxpayer's tax discount in the reporting tax year fully includes the costs of treating acute respiratory disease COVID-19 caused by the SARS-CoV-2 coronavirus, the purchase of medicines and/or medical devices necessary for the treatment of acute respiratory disease COVID-19 caused by the SARS-CoV-2 coronavirus, in accordance with an extract from the medical record of an outpatient (inpatient) patient or an extract from the Register of Medical Records, Records of Referrals and Prescriptions in the electronic health care system, the costs of vaccination for the prevention of acute respiratory disease COVID-19 caused by the SARS-CoV-2 coronavirus, as well as the costs of paying insurance payments (insurance premiums) paid to a resident insurer under insurance contracts in the event of illness due to acute respiratory disease COVID-19, caused by the SARS-CoV-2 coronavirus, of such a taxpayer and his first-degree family members.
{Subsection 1 of Section XX supplemented by paragraph 20 in accordance with Law No. 1914-IX of 11/30/2021 }
21. To establish that, based on the results of 2022, when exercising the right to a tax deduction in accordance with the provisions of Article 166 of this Code, the taxpayer's tax deduction in the reporting tax year includes the amounts of funds or the value of property transferred (transferred) by the taxpayer in the form of donations or charitable contributions to non-profit organizations that, on the date of transfer (transfer) of such funds and property, met the conditions specified in Clause 133.4 of Article 133 of this Code, in an amount not exceeding 16 percent of the amount of his total taxable income for such reporting year.
{Subsection 1 of Section XX supplemented by paragraph 21 in accordance with Law No. 2120-IX of March 15, 2022 }
22. To establish that, based on the results of the tax (reporting) periods for 2022, expenses from conducting a certain type of independent professional activity, as well as expenses of an individual entrepreneur from conducting economic activity, except for persons who have chosen a simplified taxation system, may include documented expenses in the form of the value of property, including funds voluntarily transferred (provided, transferred) to the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Protection Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, voluntary formations of territorial communities, other military formations, their formations, military units, subdivisions, institutions or organizations maintained at the expense of the state budget, for the needs of ensuring the defense of the state, as well as for the benefit of the central body executive power, which ensures the formation and implementation of state policy in the field of civil protection, civil protection forces and/or healthcare institutions of state or municipal ownership, and/or structural units on healthcare issues of regional, Kyiv and Sevastopol city state administrations, and/or funds transferred to special accounts opened by the National Bank of Ukraine for collecting funds.
{Subsection 1 of Section XX supplemented by paragraph 22 in accordance with Law No. 2120-IX of March 15, 2022 }
{Item 23 of Subsection 1 of Section XX is excluded by virtue of the Act No. 2480-IX dated 07/29/2022 }
24. The provisions of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding the Application of Norms for the Period of Martial Law" regarding amendments to subparagraphs 165.1.54 , 165.1.56 of paragraph 165.1 of Article 165 and subparagraphs 170.7.2 , 170.7.8 of paragraph 170.7 of Article 170 of this Code shall apply to tax (reporting) periods starting from January 1, 2022.
{Subsection 1 of Section XX supplemented by paragraph 24 in accordance with Law No. 2520-IX of 08/15/2022 }
25. Temporarily, starting from the date of the introduction of martial law in Ukraine, which was introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , until its termination or cancellation, the provisions of paragraph four subparagraph "c" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code shall apply taking into account the following peculiarity: until the determination in the procedure established by the Cabinet of Ministers of Ukraine of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation, the status of individuals - taxpayers who receive charitable assistance paid (provided) by benefactors, including benefactors - individuals, in the procedure specified by the Law of Ukraine "On Charitable Activities and Charitable Organizations", is determined independently by the providers of charitable assistance.
{Subsection 1 of Section XX supplemented by paragraph 25 in accordance with Law No. 2520-IX of 08/15/2022 ; as amended by Law No. 3050-IX of 04/11/2023 }
26. Temporarily, starting from the date of the introduction of martial law in Ukraine, which was introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , until its termination or cancellation, the provisions of subparagraph "c" of subparagraph 170.7.2 of paragraph 170.2 of Article 170 of this Code shall apply taking into account the following peculiarity: until the Cabinet of Ministers of Ukraine adopts the procedure for confirming the status of persons who suffered as a result of the armed aggression of the Russian Federation against Ukraine during the period of the legal regime of martial law, a state of emergency, in order not to include in the taxable income of individuals - taxpayers income received in the form of targeted or non-targeted charitable assistance, the status of such persons shall be determined independently by the providers of targeted or non-targeted charitable assistance. untargeted charitable assistance.
{Subsection 1 of Section XX supplemented by paragraph 26 in accordance with Law No. 2520-IX of 08/15/2022 }
27. The total monthly (annual) taxable income of a taxpayer for the 2022 and 2023 tax (reporting) years, as well as for the following tax (reporting) years until December 31 of the year in which martial law, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX ", does not include income in the form of the amount of funds or free goods (services) (hereinafter referred to as assistance) provided at the expense of budget funds of foreign states and their state funds to such taxpayer and members of his family of the first degree of kinship as persons who suffered as a result of the armed aggression of the Russian Federation against Ukraine and exercised the right for temporary protection in accordance with the legislation of such foreign state.
The effect of the first paragraph of this paragraph applies to all forms of provision of the specified assistance, including in the case of its receipt as an additional benefit, as well as from foreign companies and organizations that, in accordance with the legislation of the relevant foreign jurisdiction, carry out charitable activities.
If the taxpayer received income provided for in this paragraph, then his obligation to submit a declaration of property status and income (tax declaration) is considered fulfilled and a tax declaration is not submitted. If the taxpayer is obliged to submit a declaration of property status and income (tax declaration) in accordance with other provisions of this Code, then the income provided for in this paragraph shall be indicated in it along with other income.
Tax notices-decisions that were issued to taxpayers for failure to submit or untimely submission of a tax return in the cases provided for in this paragraph are considered canceled (withdrawn) from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Tax on Real Estate Other than a Land Plot for Destroyed or Damaged Real Estate".
The provisions of paragraph three of this paragraph shall apply to the tax (reporting) periods of 2022 and 2023, as well as subsequent tax (reporting) years until December 31 of the year in which the martial law introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , will be terminated or canceled .
{Subsection 1 of Section XX supplemented by paragraph 27 in accordance with Law No. 2520-IX of 08/15/2022 ; as amended in accordance with Law No. 3050-IX of 04/11/2023 ; as amended by Law No. 4015-IX of 10/10/2024 }
28. The provisions of subparagraph 170.7.2 of paragraph 170.7 of Article 170 of this Code, as amended by the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Promotion of the Development of Volunteer Activities and Activities of Non-Profit Institutions and Organizations in Conditions of Armed Aggression of the Russian Federation against Ukraine", shall apply to tax (reporting) periods starting from January 1, 2022.
{Subsection 1 of Section XX supplemented by paragraph 28 in accordance with Law No. 2520-IX of 08/15/2022 }
29. To establish that the provisions of subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code regarding the mandatory documentary confirmation of expenses of benefactors - individuals who are included in the Register of volunteers of the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the manner prescribed by the Law of Ukraine "On Charitable Activities and Charitable Organizations", for the provision of charitable assistance in favor of persons specified in subparagraphs "a" , "c" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code, shall not apply to expenses of such benefactors in the period from February 24, 2022 to May 1, 2022.
{Subsection 1 of Section XX supplemented by paragraph 29 in accordance with Law No. 2600-IX of 09/20/2022 }
30. The provisions of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Taxation of Transactions with Real Estate Objects to be Constructed in the Future" regarding amendments to subparagraph 165.1.1 of paragraph 165.1 of Article 165 of this Code shall apply to tax (reporting) periods starting from February 1, 2022.
{Subsection 1 of Section XX supplemented by paragraph 30 in accordance with Law No. 2600-IX of 20.09.2022 }
31. To establish that the provisions of subparagraph "b" of subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code also apply to charitable assistance received by benefactors - individuals who, by January 1, 2023, were included in the Register of volunteers of the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, in the period from February 24, 2022 until the date of their inclusion in the specified Register.
{Subsection 1 of Section XX supplemented by paragraph 31 in accordance with Law No. 2747-IX of 11/16/2022 }
32. The total monthly (annual) taxable income of a taxpayer for the 2023 tax (reporting) year does not include income in the form of funds and/or property received within the framework of the implementation of a pilot project to create favorable conditions for ensuring efficient consumption of electricity by the population on the terms determined by the Cabinet of Ministers of Ukraine.
{Subsection 1 of Section XX supplemented by paragraph 32 in accordance with Law No. 2918-IX of 07.02.2023 }
33. During the period before the termination or cancellation of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the total monthly (annual) taxable income of the taxpayer shall not include income received from:
a) in the form of the cost of using housing in the amount of no more than two minimum wages established as of January 1 of the reporting tax year, provided to an employee who has the status of an internally displaced person, for free use by an employer who is a manufacturer/supplier of defense goods under state defense contracts (agreements) on defense procurement and/or a performer of defense works and services, and/or a co-executor enterprise under the specified contracts (agreements) within the meaning of the Law of Ukraine "On Defense Procurement", provided that such housing is located on the territory of Ukraine and was purchased, constructed or leased by the employer during martial law;
b) in the form of free use of housing located in the territory of Ukraine by family members of the first and second degrees of kinship of the employee specified in subparagraph "a" of this paragraph, provided that they live together in such housing in accordance with the agreement.
The provisions of this paragraph apply to the tax period (month) during which the employer performed (co-performed) at least one state defense contract (agreement) on defense procurement.
{Subsection 1 of Section XX supplemented by paragraph 33 in accordance with Law No. 3813-IX of 18.06.2024 }
34. To establish that the provisions of subparagraph 177.5.1 - 1 of paragraph 177.5 of Article 177 of this Code shall apply from the first day of the month in which the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine Regarding Ensuring Balanced Budget Revenues During the Period of Martial Law" entered into force.
As an exception to the provisions of subparagraph 177.5.1 - 1 of paragraph 177.5 of Article 177 of this Code, for the month in which the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Ensuring the Balance of Budget Revenues during the Period of Martial Law" entered into force, the payment of the advance payment of the personal income tax, calculated in accordance with the provisions of subparagraph 177.5.1 - 1 of paragraph 177.5 of Article 177 of this Code, for taxpayers engaged in retail trade in fuel, shall be made within 20 calendar days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Ensuring the Balance of Budget Revenues during the Period of Martial Law". Such a monetary obligation in the form of an advance payment of personal income tax shall be deemed agreed upon at the time of its occurrence, which shall be determined by the calendar date established by this paragraph for the deadline for payment of the advance payment.
{Subsection 1 of Section XX supplemented by paragraph 34 in accordance with Law No. 4015-IX of 10.10.2024 }
35. The total monthly (annual) taxable income of a taxpayer for the 2024 and 2025 tax (reporting) years does not include income in the form of state cash assistance (cashback) received within the framework of the implementation of the experimental project on providing state cash assistance to buyers of goods and services of Ukrainian production within the framework of the All-Ukrainian economic platform "Made in Ukraine", approved by the Cabinet of Ministers of Ukraine.
{Subsection 1 of Section XX supplemented by paragraph 35 in accordance with Law No. 4015-IX of 10.10.2024 }
36. To establish that the amendments to subparagraph 1 of paragraph 170.13 - 1 of Article 170 of this Code, introduced by the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine Regarding Expanding Patients' Access to Medicines Subject to Procurement by a Person Authorized to Make Procurements in the Healthcare Sector by Concluding Managed Access Agreements", shall apply to tax (reporting) periods starting from January 1, 2024.
The amounts of taxes and fees that, as of the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Expanding Patients' Access to Medicines Subject to Procurement by a Person Authorized to Make Procurements in the Healthcare Sector by Concluding Managed Access Agreements", were paid (transferred) by the taxpayer to the state and/or local budgets in accordance with subparagraph 170.13.3 of paragraph 170.13 of Article 170 of this Code, may be credited exclusively to reduce the taxpayer's monetary obligations in tax periods following the tax period in which the martial law introduced by the Decree of the President of Ukraine dated February 24, 2022 No. 64/2022 "On the Introduction of Martial Law in Ukraine", approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 2022 No. 2102-IX .
A controlling person who declared the amount of income from dividends received by a controlled foreign company from legal entities of Ukraine, in accordance with subparagraph 170.13.3 of paragraph 170.13 of Article 170 of this Code in the annual tax declaration on property status and income for the 2024 tax (reporting) year and before the entry into force of amendments to subparagraph 1 of paragraph 170.13 - 1 of Article 170 of this Code, introduced by the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine Regarding Expanding Patients' Access to Medicines Subject to Procurement by a Person Authorized to Make Procurements in the Healthcare Sector by Concluding Managed Access Agreements", has the right to submit a clarifying annual tax declaration on property status and income for the specified tax reporting period and adjust (reduce) the amount of total annual income by the amount of income, declared in accordance with subparagraph 170.13.3 of paragraph 170.13 of Article 170 of this Code.
{Subsection 1 of Section XX supplemented by paragraph 36 in accordance with Law No. 4505-IX of 18.06.2025 }
Subsection 2. Features of collecting value added tax↑
1. In the period until January 1, 2015, value added tax shall be paid by legal entities registered as value added tax payers when carrying out transactions for the supply of their own manufactured products (milk, raw milk, dairy products, meat, meat products, other animal processing products (skins, offal, meat and bone meal), made from milk or meat in live weight supplied by agricultural enterprises defined in Section V of the Code, other legal entities and individuals, including individual entrepreneurs who independently grow, breed, and fatten livestock products defined in Section V of the Code (hereinafter referred to as processing enterprises), taking into account the following features:
{Paragraph one of clause 1, subsection 2, section XX, as amended by Law No. 4834-VI of 24.05.2012 }
1) the provisions of this paragraph do not apply to transactions for the supply of products manufactured by processing enterprises from imported raw materials, raw materials not supplied in live weight, raw materials that are not raw materials of their own production of agricultural enterprises defined in Section V of the Code, other legal entities and individuals, including individual entrepreneurs who independently grow, breed, and fatten livestock products defined in this Code (hereinafter referred to as agricultural producers);
{Subparagraph 1 of paragraph 1 of subsection 2 of section XX as amended by Law No. 4834-VI of 24.05.2012 }
2) a tax invoice is provided to the buyer in accordance with the procedure established by Section V of the Code;
3) the processing enterprise keeps separate records of operations for the supply of its own products (milk, raw milk, dairy products, meat, meat products, other animal processing products (skins, offal, meat and bone meal) made from milk or meat in live weight supplied by agricultural producers (hereinafter referred to as products), and for the supply of other goods/services, including products made from raw materials specified in subparagraph 1 of this paragraph, and draws up a value-added tax return and a value-added tax return for the supply of products;
4) the processing enterprise distributes the amount of the paid (accrued) tax credit for manufactured and/or purchased goods/services, fixed assets that are used partly for the manufacture of products and partly for the manufacture of other goods/services based on the share of use of such goods/services, fixed assets in operations for the supply of products and, accordingly, in operations for the supply of other goods/services, taking into account the requirements of Section V of the Code;
5) the processing enterprise shall reflect the operations of exporting products outside the customs territory of Ukraine under the customs regime of export in the tax declaration for value added tax and shall have the right to reimbursement from the budget of the value added tax paid (charged) to suppliers of goods/services, the cost of which is included in the cost of exported products. Such reimbursement shall be carried out in accordance with the general procedure;
6) the processing enterprise shall pay the positive difference between the amount of tax liabilities for the reporting (tax) period and the amount of tax credit for the reporting (tax) period, determined in the tax return on value added tax for the activity of supplying products, to the special fund of the State Budget of Ukraine and to a special account opened by it in the body that carries out treasury services for budget funds, in the following amounts:
{Paragraph one of subparagraph 6 of clause 1 of subsection 2 of section XX as amended by Law No. 5083-VI of 05.07.2012 }
in 2012 - to the special fund of the State Budget of Ukraine - in the amount of 30 percent, and to a special account - in the amount of 70 percent;
in 2013 - to the special fund of the State Budget of Ukraine - in the amount of 40 percent, and to a special account - in the amount of 60 percent;
in 2014 - to the special fund of the State Budget of Ukraine - in the amount of 50 percent, and to a special account - in the amount of 50 percent.
The processing enterprise uses the amount of value-added tax transferred to a special account exclusively to pay compensation to agricultural producers for the milk and meat in live weight sold by them (hereinafter referred to as compensation).
The procedure for using the amounts of value added tax paid by processing enterprises to the special fund of the State Budget of Ukraine is established by the Cabinet of Ministers of Ukraine;
7) the processing enterprise shall credit the negative difference between the amount of tax liabilities for the reporting (tax) period and the amount of tax credit for the reporting (tax) period, determined in the value added tax declaration for the activity of supplying products, to reduce tax liabilities for subsequent reporting (tax) periods;
8) the reporting (tax) period is one calendar month;
9) the processing enterprise shall, within the terms established by paragraph 203.1 of Article 203 of the Code, submit to the regulatory authority a tax return on value added tax and a tax return on value added tax for the activity of supplying products at the place of registration of the processing enterprise. The tax return on value added tax for the activity of supplying products shall separately reflect the amount of value added tax to be transferred to a special account for the payment of compensation and the amount of value added tax to be transferred to the special fund of the State Budget of Ukraine;
10) the transfer of the amount of value added tax to the special account of the processing enterprise for the payment of compensation is carried out by the processing enterprise by the 15th day of the month following the reporting (tax) period, to the special fund of the State Budget of Ukraine - within the terms established by paragraph 203.2 of Article 203 of the Code.
To confirm the transfer of value added tax amounts to a special account, the processing enterprise, together with the value added tax tax return for the supply of products, shall provide a register of payment orders on the funds actually credited to such a special account for the reporting (tax) period and an extract from the body that carries out treasury services of budget funds from such an account;
{Paragraph two of subparagraph 10 of clause 1 of subsection 2 of section XX as amended by Law No. 5083-VI of 05.07.2012 }
11) the amount of compensation is distributed among agricultural producers for the milk or meat in live weight supplied by them to the processing enterprise every month in accordance with the Calculation of the Distribution of the Compensation Amount, taking into account the following:
a) compensation for each agricultural producer is determined taking into account the coefficient calculated as the ratio of the amount of compensation determined in the value added tax tax return for the activity of supplying products to the cost of purchased milk or meat in live weight excluding value added tax;
b) the specified coefficient is applied to all agricultural producers per hryvnia of the value of delivered milk or meat in live weight, excluding value-added tax.
The form of the Calculation of the Distribution of the Compensation Amount and the procedure for its completion are approved by the central executive body that ensures the formation of state agrarian policy upon prior agreement with the central executive body that implements state financial policy;
{Paragraph four of subparagraph 11 of clause 1 of subsection 2 of section XX as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 }
12) payment of compensation to agricultural producers (to legal entities by payment orders by transfer to their separate accounts opened in servicing banks, to individuals - in cash directly from the cash desk of the processing enterprise or in accordance with the mandate agreements) is carried out by the processing enterprise by the 20th of the month following the reporting (tax) period.
Confirmation of the payment of compensation to agricultural producers is the Information on the amounts of compensation paid to agricultural producers.
The form of the Information on the amounts of compensation paid to agricultural producers and the procedure for filling it out are approved by the central executive body that ensures the formation of state agrarian policy upon prior agreement with the central executive body that implements state financial policy;
{Paragraph three of subparagraph 12 of clause 1 of subsection 2 of section XX as amended by Laws No. 5083-VI of 05.07.2012 , No. 404-VII of 04.07.2013 }
13) amounts of value added tax not transferred to a special account or transferred in violation of the deadline established by this paragraph, as well as amounts of compensation not paid to agricultural producers or paid in violation of the deadline established by this paragraph, are considered to have been used for purposes other than their intended purpose and are subject to recovery to the state budget;
14) compensation amounts are not included by agricultural producers - payers of value added tax in the tax base for value added tax on transactions for the supply of milk and meat in live weight.
{Clause 1, Subsection 2, Section XX as amended by Law No. 4268-VI of 12/22/2011 }
2. Temporarily, until January 1, 2019, transactions with:
{Paragraph one of clause 2 of subsection 2 of section XX as amended by Law No. 1797-VIII of 21.12.2016 }
a) supply of machinery, equipment, and facilities defined by Article 7 of the Law of Ukraine "On Alternative Fuels" on the territory of Ukraine;
b) import under the UKT FEA codes defined by Article 7 of the Law of Ukraine "On Alternative Fuels", machinery, equipment, and facilities used for the reconstruction of existing and construction of new biofuel production enterprises and for the manufacture and reconstruction of technical and transport vehicles for the purpose of biofuel consumption, if such goods are not produced and have no analogues in Ukraine, as well as technical and transport vehicles, including self-propelled agricultural machinery running on biofuel, if such goods are not produced in Ukraine.
The procedure for importing the specified machinery, equipment, facilities, technical and transport means is determined by the Cabinet of Ministers of Ukraine.
In case of violation of the requirements for the intended use of the specified goods, the taxpayer is obliged to increase the tax liability based on the results of the tax period to which such violation applies by the amount of value added tax that should have been paid on the day of import of such goods, as well as to pay a penalty accrued on such tax amount, based on 120 percent of the discount rate of the National Bank of Ukraine, which was in effect on the day of the increase in the tax liability, and for the period from the day of import of such goods to the day of the increase in the tax liability.
3. Temporarily, until January 1, 2023, space activity entities subject to the Law of Ukraine "On Space Activity" are exempt from paying value added tax on transactions with:
{Paragraph one of clause 3 of subsection 2 of section XX as amended by Laws No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 ; as amended by Law No. 2245-VIII of 07.12.2017 }
a) import into the customs territory of Ukraine under the customs regime of import of goods specified in subparagraph 4 of paragraph 4 of section XXI "Final and transitional provisions" of the Customs Code of Ukraine, within the limits established by the Cabinet of Ministers of Ukraine, provided that such goods are used for the intended purpose in the production of space technology (including units, systems and their components for space complexes, space launch vehicles, spacecraft and ground segments of space systems), by residents - subjects of space activity who have received a license for the right to carry out such activities and participate in the implementation of such international agreements. The list of such residents - subjects of space activity is established by the central executive body that ensures the formation of state policy in the field of space activity.
{Paragraph one of subparagraph "a" of paragraph 3 of subsection 2 as amended by Laws No. 4915-VI of 07.06.2012 , No. 5083-VI of 05.07.2012 }
In case of violation of the intended use of goods or exceeding the maximum import volumes established by the Cabinet of Ministers of Ukraine, the relevant space activity entity that actually exercised the right to a tax benefit is considered to be intentionally evading taxation, and punitive (financial) sanctions are applied to it in accordance with the requirements of current legislation;
b) supply to the customs territory of Ukraine of the results of scientific research and development works performed for the needs of space activities. For the purpose of applying this benefit, the Cabinet of Ministers of Ukraine shall establish the procedure for maintaining a register of the specified scientific research and development works.
{Paragraph four of clause 3, subsection 2, section XX as amended by Law No. 2245-VIII of 07.12.2017 }
In case of violation of the conditions for exemption from taxation of the results of scientific research and development work, namely when they are supplied for purposes not related to space activities, the taxpayer who actually exercised the right to a tax exemption is considered to be intentionally evading taxation, and punitive (financial) sanctions are applied to him in accordance with the requirements of the law.
{Paragraph five of clause 3, subsection 2, section XX as amended by Law No. 2245-VIII of 07.12.2017 }
4. Temporarily, until January 1, 2016, aircraft manufacturing entities subject to the provisions of Article 2 of the Law of Ukraine "On the Development of the Aircraft Industry" are exempt from paying value added tax on transactions with:
import into the customs territory of Ukraine under the customs regime of import of goods (except for excisable goods) used for the needs of the aircraft manufacturing industry, if such goods are exempt from import duty in accordance with subparagraph 2 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine;
{Paragraph two of clause 4 of subsection 2 as amended by Law No. 4915-VI of 07.06.2012 }
supply to the customs territory of Ukraine of the results of scientific research and development work carried out for the needs of the aircraft industry.
of Section II of this Code shall apply to taxpayers - aircraft manufacturing entities .
4 - 1. Temporarily, until January 1, 2025, aircraft manufacturing entities subject to the provisions of Article 2 of the Law of Ukraine "On the Development of the Aircraft Industry" are exempt from value added tax on transactions with:
import into the customs territory of Ukraine under the customs regime of import of goods (except for excisable goods) used for the needs of the aircraft manufacturing industry, if such goods are exempt from import duty in accordance with subparagraph 13 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine;
supply to the customs territory of Ukraine of the results of scientific research and development work carried out for the needs of the aircraft industry.
During the established period, transactions for the sale of products (services) produced by the specified enterprises at the expense of the State Budget of Ukraine are subject to value added tax at a zero rate.
of Section II of this Code shall apply to taxpayers - aircraft manufacturing entities .
{Subsection 2 of Section XX supplemented by paragraph 4 - 1 in accordance with Law No. 1795-VIII of 20.12.2016 }
5. Temporarily, until January 1, 2015, transactions for the performance of works and the supply of services by business entities - residents of Ukraine, who simultaneously carry out publishing activities, activities for the manufacture and distribution of book products and the production of paper and cardboard, are exempt from taxation with value added tax. In this case, the income of such a business entity, received from publishing activities, activities for the manufacture and distribution of book products and the production of paper and cardboard, must be at least 100 percent of the total amount of its income for the first reporting (tax) period from the time of the creation of such a business entity or at least 50 percent of the total amount of its income for the previous reporting (tax) year.
6. Temporarily, until January 1, 2015, transactions for the performance of works and the supply of services in publishing activities, activities for the production and distribution by publishing houses, publishing organizations, printing enterprises, distributors of book products produced in Ukraine, transactions for the production and/or supply of paper and cardboard produced in Ukraine for the production of book products, student notebooks, textbooks and teaching aids of Ukrainian production, as well as transactions for the supply of book products produced in Ukraine, except for advertising, services for the placement of materials of an advertising and erotic nature and publications of an advertising and erotic nature, are exempt from taxation with value added tax.
7. Temporarily, until January 1, 2015, the following are exempt from value added tax:
{Paragraph one of clause 7, subsection 2, section XX as amended by Law No. 3609-VI of 07.07.2011 }
operations for the import into the customs territory of Ukraine under the customs regime of import of goods defined by subparagraph 1 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine , for use in one's own production activities;
{Paragraph of clause 7 of subsection 2 of section XX as amended by Laws No. 3609-VI of 07.07.2011 , No. 4915-VI of 07.06.2012 }
operations for the supply of goods specified in subparagraph 1 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine to processors, publishing houses and printing enterprises on the territory of Ukraine.
{Paragraph of clause 7, subsection 2, section XX as amended by Law No. 3609-VI of 07.07.2011 }
In the event of misuse of the specified goods, the taxpayer is obliged to increase the tax liability for the tax period to which such violation applies by the amount of value added tax that should have been paid at the time of import of such goods, and also to pay a penalty in accordance with the law.
8. For the period until January 1, 2025, the value-added tax on the supply of goods (except for excisable goods) and services (except for services provided during lotteries and entertainment games and services for the supply of goods received under commission (consignment) agreements, suretyship, mandate, trust management, other civil law agreements authorizing such a taxpayer (hereinafter referred to as the commission agent) to supply goods on behalf of and on behalf of another person (hereinafter referred to as the principal) without transferring ownership of such goods) that are directly manufactured by enterprises and organizations of public associations of persons with disabilities that are founded by public associations of persons with disabilities and are their property, where the number of persons with disabilities who have their main place of work there is not less than 50 percent of the average number of full-time employees during the previous reporting period, and provided that the payroll of such persons with disabilities is during reporting period, at least 25 percent of the total labor costs related to production costs.
{Paragraph one of clause 8 of subsection 2 of section XX as amended by Laws No. 3609-VI of 07.07.2011 , No. 4834-VI of 05.05.2012 , No. 344-IX of 05.12.2019 }
Direct production is considered to be the production of goods/services, as a result of which the amount of costs incurred for the processing (processing, other types of transformation) of raw materials, components, parts, and other purchased goods used in the production of such goods is at least 8 percent of the selling price of such manufactured goods.
The specified enterprises and organizations of public associations of persons with disabilities have the right to apply this benefit upon registration with the relevant regulatory body, which is carried out on the basis of the submission of a relevant application by the taxpayer about the desire to receive such a benefit and a positive decision of the authorized body in accordance with the Law of Ukraine "On the Fundamentals of Social Protection of Persons with Disabilities in Ukraine".
{Paragraph three of clause 8 of subsection 2 of section XX as amended by Laws No. 5083-VI of 05.07.2012 , No. 344-IX of 05.12.2019 }
If a taxpayer violates the requirements of this paragraph, the regulatory authority shall cancel his registration as a person entitled to a tax benefit, and the tax liabilities of such taxpayer shall be transferred from the tax period, as a result of which such violations were detected, in accordance with the general taxation rules established by this Code, and with the simultaneous application of appropriate financial sanctions.
Tax reporting of such enterprises and organizations is provided in accordance with the procedure established by law.
{ Clause 8, Subsection 2, Section XX as amended by Law No. 1654-VII of 14.08.2014 }
9. Until September 1, 2012, value added tax is not charged when importing goods into the customs territory of Ukraine under the customs regime of import, which are exempt from import duty in accordance with paragraph four of subparagraph 3 of clause 4 of section XXI "Final and transitional provisions" of the Customs Code of Ukraine .
{Paragraph one of clause 9 of section XX as amended by Law No. 4915-VI of 07.06.2012 }
In case of violation of the intended use of such items or their alienation on the customs territory of Ukraine, taxpayers shall be subject to punitive (financial) sanctions in accordance with the requirements of the law for any compensation.
{Item 10 of Subsection 2 of Section XX was excluded pursuant to Law No. 1166-VII of March 27, 2014 }
11. Registration of tax invoices by value added tax payers - sellers in the Unified Register of Tax Invoices is introduced for payers of this tax, for whom the amount of value added tax in one tax invoice is:
over 1 million hryvnias - from January 1, 2011;
over 500 thousand hryvnias - from April 1, 2011;
over 100 thousand hryvnias - from July 1, 2011;
over 10 thousand hryvnias - from January 1, 2012.
A tax invoice drawn up during the implementation of operations for the supply of excisable goods and goods imported into the customs territory of Ukraine, from January 1, 2012, is subject to inclusion in the Unified Register of Tax Invoices, regardless of the amount of value added tax in one tax invoice.
{Paragraph six of clause 11, subsection 2, section XX as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 1621-VII of 31.07.2014 taking into account the amendments made by Law No. 71-VIII of 28.12.2014 ; with amendments made in accordance with Laws No. 71-VIII of 28.12.2014 , No. 1797-VIII of 21.12.2016 }
paragraphs eight and nine of clause 201.10 of Article 201 of this Code shall not apply to taxpayers for whom, as of the date of preparation of the invoice, this unit has not introduced the obligation to register the tax invoice in the Unified Register of Tax Invoices .
{Paragraph seven of clause 11, subsection 2, section XX , as amended by Law No. 1797-VIII of 21.12.2016 }
From February 1, 2015, all tax invoices and adjustment calculations to tax invoices (including those not provided to the buyer, drawn up for transactions for the supply of goods/services that are exempt from taxation) are subject to registration in the Unified Register of Tax Invoices, regardless of the amount of value added tax in one tax invoice/adjustment calculation.
{Item 11 of Subsection 2 of Section XX supplemented by paragraph eight in accordance with Law No. 71-VIII of 28.12.2014 ; as amended in accordance with Law No. 1797-VIII of 21.12.2016 }
12. Temporarily, until December 31 (inclusive) of the year in which martial law on the territory of Ukraine is terminated or abolished, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , transactions for the supply of national films defined by the Law of Ukraine "On Cinematography", by producers, exhibitors and distributors of national films, as well as for the supply of works and services for the production of national films, as well as for the supply of works and services for the production of archival sets of source materials for national films and films created on the territory of Ukraine, for the supply of works and services for the replication of national films and foreign films dubbed, dubbed by the state language on the territory of Ukraine, as well as the supply of works and services for dubbing, dubbing in the state language of foreign films on the territory of Ukraine, the supply of works and services for the preservation, restoration and restoration of the national cinematographic heritage.
{Clause 12, Subsection 2, Section XX, as amended by Laws No. 909-VIII of 12/24/2015 , No. 1797-VIII of 12/21/2016 ; as amended by Law No. 2176-VIII of 11/07/2017 ; as amended by Laws No. 962-IX of 11/04/2020 , No. 4143-IX of 12/17/2024 }
13. Temporarily, until January 1, 2016, transactions for the supply of services for the demonstration, distribution and/or public announcement of national films and foreign films dubbed, dubbed and/or subtitled in the state language on the territory of Ukraine by demonstrators, distributors and/or broadcasting organizations (public announcers) are exempt from value added tax.
13 - 1. Temporarily, until January 1, 2023, transactions for the supply of services for the demonstration, distribution, screening and/or public announcement of national films and foreign films dubbed, dubbed in the state language on the territory of Ukraine, by demonstrators, distributors and/or broadcasting organizations (public announcers) are exempt from value added tax.
{Subsection 2 of Section XX supplemented by paragraph 13 - 1 in accordance with Law No. 2176-VIII of 07.11.2017 ; as amended by Law No. 962-IX of 04.11.2020 }
13 - 2. Temporarily, from January 1, 2023 to December 31 (inclusive) of the year in which martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , transactions for the supply of services for the demonstration, distribution and screening by demonstrators and distributors of national films and foreign films that are dubbed, dubbed in the state language on the territory of Ukraine, are exempt from taxation with value added tax, provided that such national films and foreign films are adapted in accordance with the legislation into Ukrainian-language versions for persons with visual impairments and persons with hearing impairments.
{Subsection 2 of Section XX supplemented by paragraph 13 - 2 in accordance with Law No. 962-IX of 04.11.2020 ; as amended by Law No. 4143-IX of 17.12.2024 }
14. In the event of a negative value of the amounts of value added tax calculated in accordance with the procedure provided for in Clause 200.1 of Article 200 of this Code, compensation from the budget for shipbuilding and aircraft manufacturing enterprises shall be made in the tax period following the reporting period in which the negative tax balance arose in accordance with the procedure and terms provided for in Article 200 of this Code.
{Item 15 of Subsection 2 of Section XX was excluded pursuant to Law No. 909-VIII of 24.12.2015 }
{Item 15 - 1 of subsection 2 of section XX was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
{Item 15 - 2 of Subsection 2 of Section XX was excluded on the basis of Law No. 909-VIII of 24.12.2015 }
16. In the period from January 1, 2012 to December 31, 2014 inclusive, transactions for the supply of raw hides and tanned leather without further processing (commodity headings 4101-4103 , 4301 ), including transactions for the import of such goods, are exempt from value added tax.
{Paragraph one of clause 16, subsection 2, section XX, as amended by Law No. 713-VII of 19.12.2013 }
In the case of export of such goods under the customs regime of export, the zero rate does not apply.
17. Excluded.
{Item 18 of Subsection 2 of Section XX was excluded pursuant to Law No. 3609-VI of 07.07.2011 }
19. Transactions for the supply of UEFA tickets and services that are an integral part of the ticket are temporarily exempt from value added tax until September 1, 2012.
Temporarily, until September 1, 2012, transactions for the importation into the customs territory of Ukraine under the customs regime of import of goods specified in the provisions of paragraph three, subparagraph 3, clause 4, section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine are exempt from taxation with value added tax .
{Item 19 of subsection 2 is supplemented by a paragraph in accordance with Law No. 3675-VI of 08.07.2011 - shall be put into effect simultaneously with the entry into force of the regulatory legal act of the Cabinet of Ministers of Ukraine on determining the volumes and procedure for importing goods subject to a preferential taxation regime (18.10.2011) - see clause 2 of section II of Law No. 3675-VI of 08.07.2011 ; as amended by Law No. 4915-VI of 07.06.2012 }
The volumes and procedure for importing such goods are approved by the Cabinet of Ministers of Ukraine.
{Item 19 of subsection 2 is supplemented by a paragraph in accordance with Law No. 3675-VI of 08.07.2011 - shall be put into effect simultaneously with the entry into force of the regulatory legal act of the Cabinet of Ministers of Ukraine on determining the volumes and procedure for importing goods subject to a preferential taxation regime (18.10.2011) - see clause 2 of section II of Law No. 3675-VI of 08.07.2011 }
In case of violation of the intended use of such goods or their alienation in the customs territory of Ukraine, taxpayers are subject to punitive (financial) sanctions in accordance with the requirements of the law.
{Item 19 of subsection 2 is supplemented by a paragraph in accordance with Law No. 3675-VI of 08.07.2011 - shall be put into effect simultaneously with the entry into force of the regulatory legal act of the Cabinet of Ministers of Ukraine on determining the volumes and procedure for importing goods subject to a preferential taxation regime (18.10.2011) - see clause 2 of section II of Law No. 3675-VI of 08.07.2011 }
{Subsection 2 of Section XX supplemented by paragraph 19 in accordance with Law No. 3292-VI of 21.04.2011 }
20. For the period of validity of the debt write-off procedure in accordance with the Law of Ukraine "On Some Issues of Debt for Consumed Natural Gas and Electricity" for participants in debt write-off determined by this Law who are value added tax payers in accordance with Section V of this Code, the value added tax previously included in the tax credit and tax liabilities is not subject to adjustment and does not change the composition of tax liabilities and tax credit of the reporting tax period of taxpayers.
{Subsection 2 of Section XX supplemented by a paragraph in accordance with Law No. 3320-VI of 12.05.2011 - the amendment is valid until June 30, 2012; with amendments made in accordance with Law No. 3609-VI of 07.07.2011 }
21. For persons who have switched to the general taxation system from the simplified taxation system and are registered as value added tax payers, transactions for the supply of goods/services that were paid in the form of advances (prepayments) during the period of such value added tax payers' stay on the simplified taxation system and taxed by a single tax are not subject to value added tax.
{Subsection 2 of Section XX supplemented by paragraph 21 in accordance with Law No. 3609-VI of 07.07.2011 }
{Item 22 of Subsection 2 of Section XX was excluded pursuant to Law No. 4834-VI of 05/24/2012 }
23. Temporarily until January 1, 2027, supply transactions, including transactions for the import of waste and scrap of ferrous and non-ferrous metals, as well as paper and cardboard for recycling (waste paper and waste) of commodity heading 4707 according to the UKT FEA , are exempt from value added tax . Lists of such waste and scrap of ferrous and non-ferrous metals are approved by the Cabinet of Ministers of Ukraine.
{Paragraph one of clause 23 of subsection 2 of section XX as amended by Laws No. 4834-VI of 05/24/2012 , No. 713-VII of 12/19/2013 , No. 1621-VII of 07/31/2014 , No. 71-VIII of 12/28/2014 , No. 2628-VIII of 11/23/2018 }
Operations for the export of goods under the customs regime of export specified in this paragraph are exempt from value added tax.
{Subsection 2 of Section XX supplemented by paragraph 23 in accordance with Law No. 3609-VI of 07.07.2011 ; as amended in accordance with Laws No. 1797-VIII of 21.12.2016 , No. 1914-IX of 30.11.2021 }
24. The provision of paragraph one of paragraph 188.1 of Article 188 of this Code, according to which the amount of the mandatory state pension insurance fee for the cost of cellular mobile communication services is not included in the value added tax tax base, shall apply from the date of entry into force of this Code.
{Subsection 2 of Section XX supplemented by paragraph 24 in accordance with Law No. 4014-VI of 04.11.2011 }
25. Temporarily until December 31, 2012, transactions on the supply of specialized vehicles, including transactions on the import into the customs territory of Ukraine, such as ambulances of commodity code 8703 according to the UKT Foreign Economic Activity, which are intended for use by healthcare institutions and the cost of which is paid for from state and local budgets or by order of the relevant budget administrators, are exempt from value added tax.
In the event of misuse of the specified goods, the taxpayer is obliged to increase the tax liability for the tax period to which such violation applies by the amount of value added tax that should have been paid at the time of import (supply) of such goods, and also to pay a penalty in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 25 in accordance with Law No. 4279-VI of 22.12.2011 }
25 - 1. To restore the effect of clause 25 of this subsection from December 1, 2013 to January 1, 2015.
{Subsection 2 of Section XX supplemented by paragraph 25 - 1 in accordance with Law No. 657-VII of 24.10.2013 }
26. Temporarily, for the period of implementation of the programs of the Global Fund to Fight AIDS, Tuberculosis and Malaria in Ukraine, which are implemented in accordance with the law, transactions with:
import into the customs territory of Ukraine under the customs regime of import of goods (except for excisable goods), if such goods are paid for at the expense of grants (sub-grants) provided in accordance with the programs of the Global Fund to Fight AIDS, Tuberculosis and Malaria in Ukraine, which are implemented in accordance with the law. The procedure for importing the specified goods is determined by the Cabinet of Ministers of Ukraine. In case of misuse of the specified goods, the taxpayer shall increase the tax liabilities based on the results of the tax period to which such violation applies by the amount of value added tax that should have been paid at the time of import of such goods, and shall also be obliged to pay a penalty in accordance with this Code;
supply of goods (except for excisable goods) and provision of services in the customs territory of Ukraine, if such goods/services are paid for at the expense of grants (sub-grants) provided in accordance with the programs of the Global Fund to Fight AIDS, Tuberculosis and Malaria in Ukraine, which are implemented in accordance with the law. The procedure for carrying out such operations is determined by the Cabinet of Ministers of Ukraine. In case of violation of the requirements established by this procedure, the taxpayer who actually exercised the right to a tax benefit is considered to be intentionally evading taxation, and such taxpayer shall be subject to the punitive (financial) sanctions established by this Code.
In the case of transactions exempted in accordance with this paragraph, the provisions of paragraph 198.5 of Article 198 of this Code and the provisions of Article 199 of this Code shall not apply.
{Item 26 of Subsection 2 of Section XX supplemented by paragraph four in accordance with Law No. 909-VIII of 12/24/2015 }
{Subsection 2 of Section XX supplemented by paragraph 26 in accordance with Law No. 4834-VI of 24.05.2012 }
26 - 1. Temporarily, from January 1, 2013 to January 1, 2023, transactions for the supply of software products, as well as transactions with software products, the payment for which is not considered royalty in accordance with paragraphs two to seven of subparagraph 14.1.225 of paragraph 14.1 of Article 14 of this Code, are exempt from taxation with value added tax.
For the purposes of this clause, software products include:
the result of computer programming in the form of an operating system, system, application, entertainment and/or educational computer program (their components), as well as in the form of Internet sites and/or online services and access to them;
copies (instances, instances) of computer programs, their parts, components in material and/or electronic form, including in the form of code(s) and/or links for downloading a computer program and/or their parts, components in the form of code(s) for activating a computer program or in another form;
any changes, updates, additions, supplements and/or expansion of the functionality of computer programs, the right to receive such updates, changes, supplements, supplements for a certain period of time;
cryptographic means of information protection.
{Subsection 2 of Section XX supplemented by a paragraph in accordance with Law No. 5091-VI of 05.07.2012 ; as amended in accordance with Law No. 5412-VI of 02.10.2012 ; as amended by Law No. 2245-VIII of 07.12.2017 }
27. For the period of validity of the contract concluded for the implementation of the national project "Air Express", approved by the Cabinet of Ministers of Ukraine, which provides for:
construction of a passenger railway connection between Kyiv and Boryspil International Airport;
construction of a city ring road around Kyiv on the Kyiv - Boryspil section;
construction of the road from Podilskyi bridge crossing to Vatutin Avenue in Kyiv, the collection of value added tax is carried out taking into account the following:
a) with regard to operations for the import into the customs territory of Ukraine under the customs regime of temporary import of goods imported by the parties to the contract, a conditional full exemption from value added tax is applied.
The list and volumes of goods imported into the customs territory of Ukraine under the customs regime of temporary import with conditional full exemption from taxation within the framework of the implementation of the national project "Air Express" are established by the Cabinet of Ministers of Ukraine;
b) are exempt from taxation:
transactions for the supply of services in the customs territory related to the implementation of the national project "Air Express", which are provided by a non-resident person not registered as a value added tax payer to the parties to the contract.
The list of services related to the implementation of the national project "Air Express" and subject to tax exemption is established by the Cabinet of Ministers of Ukraine;
operations for the import into the customs territory of Ukraine of goods under the customs import regime that are not produced in Ukraine or produced in Ukraine but do not meet the requirements of the project by codes in accordance with the UKT FEA , provided for by subparagraph 9 of paragraph 4 of section XXI "Final and transitional provisions" of the Customs Code of Ukraine .
The list and volumes of imports of such goods are determined by the Cabinet of Ministers of Ukraine;
operations for the supply by the contractor to the customer, who are parties to the contract, of the constructed facility (or its parts) stipulated by the contract, during the implementation of the national project "Air Express".
In case of violation of the requirements for the intended use of the goods specified in this paragraph, the taxpayer is obliged to increase the tax liabilities based on the results of the tax period to which such violation applies by the amount of tax that must be paid at the time of importation of such goods into the customs territory of Ukraine, as well as to pay a penalty accrued on such amount of tax, based on 120 percent of the discount rate of the National Bank of Ukraine, which was in effect on the day of the increase in the tax liability, and for the period from the date of importation of such goods into the customs territory of Ukraine until the date of the increase in the tax liabilities.
The term "party to the contract", specified in Section XX "Transitional Provisions" of this Code, for taxation purposes defines the customer and the executor, among which the customer is a state-owned enterprise designated by the Cabinet of Ministers of Ukraine as an authorized person for the implementation of the national project "Air Express", and the executor is a non-resident who is a party to the contract concluded with the customer for the implementation of the national project "Air Express" and a permanent representative office of such non-resident.
{Subsection 2 of Section XX supplemented by paragraph 27 in accordance with Law No. 5043-VI of 04.07.2012 }
28. Temporarily, for the period of implementation of projects (programs) at the expense of international technical assistance provided in accordance with the initiative of the G8 countries "Global Partnership against the Proliferation of Weapons and Materials of Mass Destruction", transactions with:
import into the customs territory of Ukraine of goods under the customs regime of import that are not produced in Ukraine, defined by subparagraph 11 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine . The list and procedure for importing such goods are determined by the Cabinet of Ministers of Ukraine. In the event of misuse of the specified goods, the taxpayer shall increase his tax liabilities based on the results of the tax period to which such a violation applies by the amount of value added tax that should have been paid at the time of import of such goods, and shall also be obliged to pay a penalty in accordance with this Code;
supply of goods (except for excisable goods and goods of groups 1-24 according to the UKT FEA ) and provision of services in the customs territory of Ukraine, if such goods/services are paid for at the expense of international technical assistance provided in accordance with the initiative of the G8 countries "Global Partnership against the Proliferation of Weapons and Materials of Mass Destruction". The list of goods/services and the procedure for carrying out such operations are determined by the Cabinet of Ministers of Ukraine. In case of violation of the requirements established by this procedure, the taxpayer who actually exercised the right to a tax benefit is considered to be intentionally evading taxation, and such taxpayer shall be subject to punitive (financial) sanctions established by this Code.
{Subsection 2 of Section XX supplemented by paragraph 28 in accordance with Law No. 5412-VI of 02.10.2012 }
29. For the period of validity of the debt write-off procedure in accordance with the Law of Ukraine "On Some Issues of Debt of Enterprises of the Defense Industrial Complex - Participants of the State Concern "Ukroboronprom" and Ensuring Their Stable Development" for participants in the debt write-off procedure, defined by this Law, who are value added tax payers in accordance with Section V of this Code, the value added tax previously included in the tax credit and tax liabilities shall not be subject to adjustment and shall not change the composition of tax liabilities and tax credit of the reporting tax period of taxpayers.
There are no tax liabilities for value added tax with the State Reserve Agency of Ukraine when converting material assets into monetary form within the framework of the implementation of the Law of Ukraine "On Some Issues of Debt of Enterprises of the Defense Industrial Complex - Participants of the State Concern "Ukroboronprom" and Ensuring Their Stable Development".
When releasing fuel from the state reserve in accordance with the Law of Ukraine "On Some Issues of Debt of Enterprises of the Defense Industrial Complex - Participants of the State Concern "Ukroboronprom" and Ensuring Their Stable Development", participants in the debt write-off procedure do not incur tax liabilities and a tax credit for value added tax.
{Subsection 2 of Section XX supplemented by paragraph 29 in accordance with Law No. 5414-VI of 02.10.2012 }
30. Temporarily, until July 1, 2013, suspend the effect of subparagraph "i" of paragraph 201.1 of Article 201 of this Code.
{Subsection 2 of Section XX supplemented by paragraph 30 in accordance with Law No. 5503-VI of 20.11.2012 }
31. Operations on servicing mortgage assets as part of mortgage coverage in accordance with the Law of Ukraine "On Mortgage Bonds" , which are carried out by a servicing institution - a bank that was the original creditor of such mortgage assets on behalf of the issuer of mortgage bonds, are not subject to value added tax.
For the purposes of this paragraph, a mortgage bond issuer shall mean a financial institution in which more than 50 percent of the corporate rights are owned by state-owned banks.
{Subsection 2 of Section XX supplemented by paragraph 31 in accordance with Law No. 5519-VI of 06.12.2012 }
32. Temporarily, for the period of conducting an anti-terrorist operation and/or implementing measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, and/or the introduction of martial law in accordance with the legislation, the following are exempt from taxation with value added tax on the import into the customs territory of Ukraine and supply within the customs territory of Ukraine:
1) special personal protective equipment (helmets manufactured in accordance with military standards or technical conditions, or their equivalents, classified in the commodity subcategory 6506 10 80 00 according to the UKT FEA and specially designed components for them (i.e. underhelmets, shock absorbers, restraint systems, etc.), classified in the commodity subcategory 6507 00 00 00 according to the UKT FEA; bulletproof vests (including plate carriers), classified in the commodity subcategory 6211 43 90 00 according to the UKT FEA), manufactured in accordance with military standards or military conditions for the needs of law enforcement agencies, the Armed Forces of Ukraine and other military formations, voluntary formations of territorial communities formed in accordance with the laws of Ukraine, other entities that combat terrorism in accordance with the law and/or participate in the implementation of measures to ensure national security and defense, repulse and deterrence of armed aggression of the Russian Federation; threads and fabrics (materials) classified in commodity subcategories 3920 10 89 90 , 3920 61 00 00, 3921 90 60 00, 5402 11 00 00 , 5407 10 00 00, 5603 14 10 00 and 6914 90 00 00 according to the Ukrainian Classification of Foreign Economic Activities, for the manufacture of bulletproof vests and helmets;
2) medicines and medical devices in accordance with subparagraph "c" of paragraph 193.1 of Article 193 of this Code, which are intended for use by healthcare institutions, participants in an anti-terrorist operation, persons participating in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, for the provision of medical care to individuals who, during the period of the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, and/or the introduction of martial law in accordance with the legislation, suffered injuries, contusions or other damage to health, according to the list established by the Cabinet of Ministers of Ukraine;
3) medicines and medical devices without state registration and permits for import into the customs territory of Ukraine, intended for use by healthcare institutions, participants in an anti-terrorist operation, persons participating in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, for the provision of medical care to individuals who, during the period of the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, and/or the introduction of martial law in accordance with the legislation, suffered injuries, contusions or other damage to health, according to the list and in the amounts established by the Cabinet of Ministers of Ukraine;
4) defense goods, defined as such in accordance with paragraph 29 of part one of Article 1 of the Law of Ukraine "On Defense Procurement", classified according to the following groups, commodity positions and subcategories of the UKT FEA :
a) 3601 00 00 00 (only for gunpowder used for defensive purposes), 3602 00 00 00 (only for explosives used for defensive purposes), 3603 (only for percussion caps, detonators, grenade fuses and propelling charges used for defensive purposes), 3604 90 00 00 (only for illuminating and signalling flares used for defensive purposes);
b) 8525 60 00 00 ;
c) 8529 90 20 00 (only for parts and accessories for equipment for the transmission and reception of voice, images and other information, including equipment for communication in a wired or wireless network, directional listening equipment, radio stations of the ultrashort-wave and short-wave ranges for military purposes, reconnaissance and signal equipment, classified under code 8525 60 00 00 according to the UKT FEA, if the supply (purchase) of such goods is carried out for state customers under a defense order);
d) 8524 (exclusively for subcategories 8524 11 00 90, 8524 12 00 90, 8524 19 00 90, 8524 91 00 90, 8524 92 00 90, 8524 99 00 90) (only for parts and accessories for equipment for the transmission and reception of voice, images and other information, including equipment for communication in a wired or wireless network, directional listening equipment, radio stations of the ultrashort-wave and short-wave ranges for military purposes, reconnaissance and signal equipment, classified under code 8525 60 00 00 according to the UKT FEA, if the supply (purchase) of such goods is carried out for government customers under a defense order);
e) 8543 20 00 00 (only for electronic intelligence and electronic warfare equipment used for defensive purposes);
e) 8702-8705 (only for special-purpose vehicles, radar stations and trailers therefor, classified under heading 8716 according to the UKT FEA, mobile repair workshops used for defense purposes; passenger and freight vehicles of ordinary type used for defense purposes and having light armor or equipped with removable armor);
e) 8710 00 00 00 ;
h) 8806 ;
g) 8807 (only for parts for unmanned aerial vehicles);
h) 8804 00 00 00 (only for parachutes and other devices intended for the landing of military personnel and/or military equipment);
i) 8906 (only for warships, boats and their components, unmanned marine systems used for defense purposes);
i) group 90 (only for binoculars, night vision devices, thermal imagers, protective glasses and similar optical products, telescopic sights and other optical devices for military weapons, if they are not supplied together with the military weapons for which they are intended, optical fibers and fiber-optic bundles, other fiber-optic cables classified in commodity subcategories 9001 10 90 10 , 9001 10 90 90 according to the UKT FEA, other optical, navigational and topographical instruments and instruments used for defense purposes);
{Subparagraph "i" of subparagraph 4 of paragraph 32 of subsection 2 of section XX as amended by Law No. 4474-IX of 04.06.2025 }
j) group 93 , except those included in heading 9303 and subheading 9304 00 00 00, as well as 9305 (only intended for products of headings 9303-9304), 9306 90 90 00 and 9307 00 00 00;
j) thermal imaging binoculars, monoculars and binoculars, night vision devices (binoculars and monoculars), classified in commodity subcategories 8525 89 00 10 , 8525 89 00 90 according to the UKT FEA;
{Subclause 4 of clause 32 of subsection 2 of section XX is supplemented by subparagraph "y" in accordance with Law No. 3287-IX of 07/28/2023 }
j) rangefinders classified under commodity code 9015 10 00 00 according to the Ukrainian Classification of Foreign Economic Activities;
{Subclause 4 of clause 32 of subsection 2 of section XX is supplemented by subparagraph "k" in accordance with Law No. 3287-IX of 07/28/2023 }
l) portable radio-electronic means of detecting and countering unmanned aerial vehicles (anti-drone guns), classified under commodity heading 8543 according to the UKT FEA;
{Subclause 4 of clause 32 of subsection 2 of section XX is supplemented by subparagraph "l" in accordance with Law No. 3287-IX of 07/28/2023 }
m) 8526 10 00 90 ;
{Sub-clause 4 of clause 32 of subsection 2 of section XX is supplemented by subparagraph "m" in accordance with the Law No. 3522-IX dated 20.12.2023 }
n) tactical headphones for special military purposes, classified in commodity subcategory 8518 30 00 90 according to the UKT Foreign Economic Activity;
{Subclause 4 of clause 32 of subsection 2 of section XX is supplemented by subparagraph "n" in accordance with Law No. 3853-IX of 16.07.2024 }
o) ATVs and all-terrain vehicles classified under commodity headings 8703 , 8704 according to the Ukrainian Classification of Foreign Economic Activities;
{Subclause 4 of clause 32 of subsection 2 of section XX is supplemented by subparagraph "o" in accordance with Law No. 4967-IX of 03.09.2026 }
5) goods, the final recipient of which, in accordance with the end-user certificate or in accordance with the terms of the contract, is determined to be law enforcement agencies, the Ministry of Defense of Ukraine, the Armed Forces of Ukraine and other military formations, voluntary formations of territorial communities formed in accordance with the laws of Ukraine, other entities that combat terrorism in accordance with the law and/or participate in implementing measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation against Ukraine, enterprises that are executors (co-executors) of state contracts (agreements) on defense procurement:
flat-rolled products of other alloy steels with a width of 600 mm or more, classified in commodity subcategory 7225 40 60 00 according to the UKT FEA;
safety glass, including toughened (tempered) or laminated glass, classified under commodity heading 7007 according to the UKT FEA;
optical surveillance devices classified in commodity subcategories 9013 10 90 00 , 9005 10 00 00, 9005 80 00 00 according to the Ukrainian Classification of Foreign Economic Activities;
apparatus for the transmission and reception of voice, images and other information, including apparatus for communication in a wired or wireless network, directional listening apparatus, radio stations of the ultra-short-wave and short-wave ranges for military purposes, reconnaissance and signal equipment, parts and accessories thereof, classified in commodity subheading 8517 69 and in commodity subcategories 8525 60 00 00, 8529 90 20 00, 8524 11 00 90, 8524 12 00 90, 8524 19 00 90, 8524 91 00 90, 8524 92 00 90, 8524 99 00 90 according to the Ukrainian Classification of Foreign Economic Activities;
unmanned aerial vehicles without weapons and their parts, classified under commodity headings 8806 , 8807 according to the UKT FEA, water-based unmanned systems, classified under commodity heading 8906 according to the UKT FEA;
{Paragraph six of subparagraph 5 of clause 32 of subsection 2 of section XX as amended by Law No. 4505-IX of 18.06.2025 }
weather stations classified in commodity subcategory 9015 80 20 00 according to the UKT FEA;
thermal imaging binoculars, monoculars and binoculars, night vision devices (binoculars and monoculars), classified in commodity subcategories 8525 89 00 10 , 8525 89 00 90 according to the UKT FEA;
{Subparagraph 5 of paragraph 32 of subsection 2 of section XX is supplemented with a new paragraph in accordance with Law No. 3287-IX of 07/28/2023 }
rangefinders classified under commodity code 9015 10 00 00 according to the Ukrainian Classification of Foreign Economic Activities;
{Subparagraph 5 of paragraph 32 of subsection 2 of section XX is supplemented with a new paragraph in accordance with Law No. 3287-IX of 07/28/2023 }
radio-electronic means of detecting and countering unmanned aerial vehicles, classified under commodity heading 8543 according to the Ukrainian Customs Tariff, including anti-drone guns;
{Subparagraph 5 of paragraph 32 of subsection 2 of section XX is supplemented with a new paragraph in accordance with Law No. 3287-IX of 07/28/2023 ; as amended by Law No. 3853-IX of 07/16/2024 }
radar devices classified in commodity subcategory 8526 10 00 90 according to the UKT FEA;
{Subparagraph 5 of paragraph 32 of subsection 2 of section XX is supplemented with a new paragraph in accordance with Law No. 3522-IX of 20.12.2023 }
combat simulators classified in commodity subcategory 9023 00 80 00 according to the UKT FEA;
{Clause 32, subsection 2, section XX is supplemented with a new paragraph in accordance with Law No. 4709-IX of 04.12.2025 }
ATVs and all-terrain vehicles classified under commodity headings 8703 , 8704 according to the Ukrainian Classification of Foreign Economic Activities;
{Subparagraph 5 of paragraph 32 of subsection 2 of section XX is supplemented with a new paragraph in accordance with Law No. 4967-IX of 03.09.2026 }
armored vehicles classified under codes 8702 10 19 90 , 8702 90 11 00, 8703, 8705 90 80 90, 8710 00 00 00 according to the UKT Foreign Economic Activity.
In the case of transactions exempt from value added tax in accordance with subparagraphs 4 and 5 of this paragraph, the provisions of paragraph 198.5 of Article 198 and Article 199 of this Code shall not apply to such transactions.
{Paragraph of Clause 32, Subsection 2, Section XX, as amended by Laws No. 4698-IX of 03.12.2025 , No. 4709-IX of 04.12.2025 }
{Subsection 2 of Section XX supplemented by paragraph 32 in accordance with Law No. 1561-VII of 01.07.2014 ; as amended in accordance with Laws No. 1658-VII of 02.09.2014 , No. 555-VIII of 30.06.2015 , No. 1797-VIII of 21.12.2016 , No. 2463-VIII of 19.06.2018 , No. 2628-VIII of 23.11.2018 , No. 2120-IX of 15.03.2022 , No. 2173-IX of 01.04.2022 ; as amended by Law No. 3019-IX of 10.04.2023 }
32 - 1. Temporarily, during the legal regime of martial law or a state of emergency, the following goods are not considered to be used by the taxpayer in transactions not subject to value added tax or transactions that are not the taxpayer's economic activity:
purchased in transactions subject to value added tax, destroyed (lost) as a result of force majeure circumstances during a period of martial law or a state of emergency;
acquired in transactions subject to value-added tax and transferred to state or municipal ownership, including in favor of voluntary formations of territorial communities, as well as provided to the benefit of other persons for the needs of ensuring the defense of Ukraine during the period of martial law or a state of emergency.
The supply of goods and services does not include transactions for the free transfer/provision of goods and services (without any monetary, material or other types of compensation) to the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Emergency Service of Ukraine, the State Security Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, voluntary formations of territorial communities, other military formations formed in accordance with the laws of Ukraine, their formations, military units, subdivisions, institutions or organizations maintained at the expense of the state budget, for the needs of ensuring the defense of Ukraine, protecting the security of the population and the interests of the state, as well as for the benefit of the central executive body that ensures the formation and implementation of state policy in the field of civil defense, civil defense forces and/or healthcare institutions of state or municipal ownership, and/or structural units on issues of healthcare of regional, Kyiv and Sevastopol city state administrations, except in cases where such transactions for the supply of goods and services are taxed at a zero rate of value added tax.
{Paragraph four of clause 32 - 1 , subsection 2, section XX, as amended by Law No. 2173-IX of 01.04.2022 }
Clause 198.5 of Article 198 of this Code do not apply to the transactions listed in this clause .
{Subsection 2 of Section XX supplemented by paragraph 32 - 1 in accordance with Law No. 2120-IX of March 15, 2022 }
32 - 2. Temporarily, for the tax periods of February, March, April, May 2022, for transactions for the purchase of goods/services for which suppliers have not registered tax invoices and/or adjustment calculations to them in the Unified Register of Tax Invoices, taxpayers:
include in the tax credit of the reporting (tax) period the amounts of value added tax paid (accrued) as part of the cost of purchased goods/services, based on the primary (settlement) documents available to the payer, drawn up (received) by the taxpayer for transactions on the purchase of goods/services in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine";
recipients of services supplied by non-residents, the place of supply of which is located in the customs territory of Ukraine, in the event that such recipient of services charges value added tax as part of the tax liabilities specified in the tax declaration for the relevant reporting (tax) period, such taxpayers have the right to attribute such tax amounts to the tax credit for the relevant reporting (tax) period, on the basis of the primary (settlement) documents available to the payer, drawn up (received) by the taxpayer for transactions on the purchase of services, in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine".
{Subsection 2 of Section XX supplemented by paragraph 32 - 2 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 2260-IX of May 12, 2022 }
33. At the taxpayer's option, which he reflects in the application submitted as part of the tax return, the outstanding balances of the amounts of value added tax that were declared by taxpayers for budget reimbursement for reporting (tax) periods before February 1, 2015, declared for budget reimbursement for reporting (tax) periods before February 1, 2015 to reduce tax liabilities for value added tax for subsequent reporting (tax) periods, the negative value of the amount calculated in accordance with Clause 200.1 of Article 200 of this Code, and the balance of the negative value of previous reporting (tax) periods after budget reimbursement, declared by taxpayers for reporting (tax) periods before February 1, 2015:
a) or without conducting the inspections provided for in Article 200 of this Code, increase the amount of tax for which the payer has the right to register tax invoices/calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, determined by paragraph 200 - 1.3 of Article 200 - 1 of this Code, with a simultaneous increase in the amount of the tax credit in the tax return for the reporting (tax) period in which such an increase was made.
The amounts of such negative value and/or budget compensation may be verified by the supervisory authority in accordance with the generally established procedure;
b) or are subject to return to the payer in accordance with the procedure specified in Article 200 of the Code in the version in force as of December 31, 2014.
{Paragraph four of clause 33, subsection 2, section XX, as amended by Law No. 909-VIII of 24.12.2015 }
{Subsection 2 of Section XX supplemented by paragraph 33 in accordance with Law No. 71-VIII of 28.12.2014 }
34. To establish that as of the third business day after the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve the Administration of Value Added Tax" for registered taxpayers, the value of the tax amount (positive or negative) for which such a taxpayer has the right to register tax invoices/calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, determined by paragraph 200 - 1.3 of Article 200 - 1 of this Code, and the value of all its components determined by this Code, are equal to zero, except for the values of its components Σ NaklOtr , Σ NaklVyd and Σ Mytn , which were formed starting from July 1, 2015. For registered taxpayers, such value is automatically increased by the controlling body:
1) for the amount of the average monthly amount of tax amounts that, over the last 12 reporting (tax) months (June 2014 - May 2015) / 4 quarters (Q2 2014 - Q1 2015) were declared by the payer for payment to the budget and repaid or paid in installments or deferred, as well as declared as being directed to a special account of the payer - an agricultural enterprise that has chosen a special regime in accordance with Article 209 of this Code. For taxpayers who are registered as value added tax payers as of July 1, 2015:
more than 12 reporting (tax) months / 4 quarters - such an increase is carried out within the third business day after the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve the Administration of Value Added Tax";
less than 12 reporting (tax) months / 4 quarters, as well as for payers registered as value added tax payers after July 1, 2015 - such an increase is carried out during the first day of the quarter following the quarter in which the term of such registration reaches 12 reporting (tax) months / 4 quarters.
Such an increase amount each quarter (during the first day of the relevant quarter) shall be subject to automatic recalculation taking into account the average monthly amount of tax amounts that, for the last 12 reporting (tax) months / 4 quarters as of the date of such recalculation, were declared by the payer for payment to the budget and repaid or paid in installments or deferred, and also declared as being directed to a special account of the payer - an agricultural enterprise that has chosen a special regime in accordance with Article 209 of this Code, or remain at the disposal of the agricultural enterprise in accordance with Clause 209.18 of Article 209 of this Code. Such recalculation shall be carried out by subtracting the amount of the previous increase and adding the amount of the increase in accordance with the current recalculation;
2) within the third business day after the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve the Administration of Value Added Tax" for the amount of balances on payers' accounts in the system of electronic administration of value added tax as of the beginning of such day, minus the amounts declared by the payer as part of the tax reporting for the reporting (tax) period for June 2015 before transfer from the electronic account to the budget for payment of tax liabilities and/or to the payer's current account in accordance with clause 200 - 1.6 of Article 200 - 1 of this Code. Until July 31, 2015/August 20, 2015, the amount for which the payer has the right to register tax invoices/adjustment calculations in the Unified Register of Tax Invoices is reduced by the amount of tax liabilities declared for the reporting (tax) period for June 2015/Q2 2015;
3) within 10 calendar days after the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve the Administration of Value Added Tax" for the amount of erroneously and/or excessively paid monetary obligations for value added tax as of July 1, 2015. For the amount of such increase, a one-time payment:
a) if, based on the results of the reporting (tax) period for June 2015 / II quarter of 2015, the taxpayer declared the amount of value added tax to be paid to the budget, the controlling body shall reduce in the information system of indicators of the status of the calculation of payers of the information base of the controlling body such amount declared to be paid to the budget based on the results of the reporting (tax) period for June 2015 / II quarter of 2015, with a simultaneous reduction of the amount of tax to be transferred from the payer's account in the electronic tax administration system to the budget, which is indicated in the register, on the basis of which the body carrying out treasury services of budget funds, in which payers' accounts are opened in the electronic value added tax administration system, shall carry out such transfer;
b) if, based on the results of the reporting (tax) period for June 2015 / II quarter of 2015, the taxpayer declared the amount of value added tax payable to the budget in an amount that is less than the amount of erroneously and/or excessively paid monetary obligations for value added tax as of July 1, 2015 or declared a negative tax value, the taxpayer increases the amount of the negative value formed based on the results of the reporting (tax) period for July 2015 / III quarter of 2015, which is carried over to the tax reporting for the reporting (tax) period for August 2015 / IV quarter of 2015.
Erroneously and/or excessively paid monetary obligations for value added tax are considered to be repaid simultaneously with the increase in the amount of tax for which such a payer has the right to register tax invoices/calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, determined by clause 200 - 1.3 of Article 200 - 1 of this Code;
4) until July 31, 2015 for taxpayers applying a monthly reporting (tax) period, without conducting audits provided for in Article 200 of this Code, by the amount of the negative value included in the tax credit of the next reporting (tax) period and the amount of the outstanding negative value of previous reporting (tax) periods at the end of the current reporting (tax) period, which is indicated in the tax reporting on value added tax, which reflects settlements with the budget and/or reflects transactions related to the special taxation regime in accordance with Article 209 of this Code, for June 2015. The taxpayer shall increase the amount of the tax credit for the reporting (tax) period (July 2015) by such amount.
Amounts of such negative value may be verified by the supervisory authority in accordance with the generally established procedure;
5) until August 20, 2015 for taxpayers applying a reporting (tax) period equal to a quarter, without conducting audits provided for in Article 200 of this Code, by the amount of the negative value included in the tax credit of the next reporting (tax) period and the amount of the outstanding negative value of previous reporting (tax) periods at the end of the current reporting period, which is indicated in the tax reporting on value added tax, which reflects settlements with the budget and/or reflects transactions related to the special taxation regime in accordance with Article 209 of this Code, for the second quarter of 2015. The taxpayer shall increase the amount of the tax credit for the reporting (tax) period for the third quarter of 2015 by such amount.
Amounts of such a negative value may be verified by the supervisory authority in accordance with the generally established procedure.
{Subsection 2 of Section XX supplemented by paragraph 34 in accordance with Law No. 71-VIII of 28.12.2014 ; as amended by Law No. 643-VIII of 16.07.2015 }
34 - 1. For taxpayers who apply the cash method of tax accounting in accordance with clause 187.10 of Article 187 of this Code, the calculation of the amount ∑ Invoice includes the tax amounts indicated in tax invoices drawn up before July 1, 2015, according to which the right to include such amounts in the tax credit arises after July 1, 2015.
Such tax amounts participate in the calculation of the amount ∑ Nakl based on the tax return for the reporting period in which the taxpayer applying the cash method of tax accounting, in accordance with Clause 187.10 of Article 187 of this Code, includes such tax amounts in the tax credit (taking into account the requirements of Clause 198.6 of Article 198 of this Code) in connection with the application of the cash method of tax accounting.
{Subsection 2 of Section XX supplemented by paragraph 34 - 1 in accordance with Law No. 909-VIII of 24.12.2015 }
35. The provisions of paragraph 120 - 1.1 of Article 120 - 1 of this Code shall not apply in case of violation of the deadlines for registration of tax invoices/adjustment calculations in the Unified Register of Tax Invoices drawn up before October 1 , 2015.
{Paragraph one of clause 35, subsection 2, section XX as amended by Law No. 643-VIII of 16.07.2015 }
The period from February 1, 2015 to July 1, 2015 is a transitional period during which the registration of tax invoices/calculations of adjustments to tax invoices in the Unified Register of Tax Invoices is carried out without limitation by the amount of tax calculated according to the formula specified in paragraph 200 - 1.3 of Article 200 - 1 of this Code.
Starting from the fourth business day after the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Improvement of Value Added Tax Administration", registration in the Unified Register of Tax Invoices of tax invoices/adjustment calculations drawn up before July 1, 2015 is carried out without limitation by the amount of tax calculated according to the formula specified in paragraph 200 - 1.3 of Article 200 - 1 of this Code.
{Paragraph 35 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 643-VIII of 16.07.2015 }
{Subsection 2 of Section XX supplemented by paragraph 35 in accordance with Law No. 71-VIII of 28.12.2014 }
35 - 1. To establish that until December 31, 2017 , penalties provided for in paragraph 120 - 1.3 of Article 120 - 1 of this Code shall not apply for errors made in the tax invoice when indicating the product code in accordance with the UKT of Foreign Economic Activities and/or the service code in accordance with the State Classifier of Products and Services .
{Subsection 2 of Section XX supplemented by paragraph 35 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
36. A taxpayer may include, on the basis of an accounting certificate, in a tax credit based on the tax base determined in accordance with Clause 189.1 of Article 189 of this Code, the amounts of tax paid (accrued) in the cost of goods/services, non-current assets purchased before July 1, 2015, which were not included in the tax credit before July 1, 2015 upon the purchase or manufacture of such goods/services, non-current assets, and/or for which tax liabilities were determined before July 1, 2015 in accordance with Clause 198.5 of Article 198 of this Code in the version in force until January 31, 2015, if such goods/services, non-current assets begin to be used after July 1, 2015 in whole or in part in taxable transactions within the framework of economic activity, including the transfer of non-productive non-current assets to the tax credit. production non-current assets.
For the purpose of applying this paragraph, the tax credit is determined on the date of the start of actual use of goods/services, non-current assets, determined in the primary documents drawn up in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine".
{Subsection 2 of Section XX is supplemented by paragraph 36 in accordance with Law No. 71-VIII of 28.12.2014 - enters into force on July 1, 2015, see paragraph four of paragraph 1 of Section II of Law No. 71-VIII of 28.12.2014}
37. To establish that regulatory authorities do not conduct unscheduled documentary on-site inspections regarding the authenticity of the amounts of budget reimbursement for value-added tax declared by payers in reporting periods occurring after July 1, 2015, except for cases specified in paragraph 200.11 of Article 200 of this Code.
{Paragraph one of clause 37, subsection 2, section XX, as amended by Law No. 909-VIII of 24.12.2015 }
From July 1, 2015 to January 1, 2017, the effect of subparagraph 78.1.8 of paragraph 78.1 of Article 78, paragraph four of paragraph 82.4 of Article 82, paragraph 200.11 of Article 200 of this Code, as well as the effect of paragraph 200.14 of Article 200 of this Code with regard to conducting unscheduled documentary on-site inspections, shall be suspended.
{Paragraph two of clause 37, subsection 2, section XX, as amended by Law No. 1791-VIII of 20.12.2016 }
Budgetary reimbursement of value added tax amounts declared for reimbursement before July 1, 2015, shall be carried out in accordance with the procedure specified in Article 200 of this Code in the version in force as of July 1, 2015.
{Item 37 of Subsection 2 of Section XX supplemented by the third paragraph in accordance with Law No. 909-VIII of 24.12.2015 }
{Subsection 2 of Section XX supplemented by paragraph 37 in accordance with Law No. 71-VIII of 28.12.2014 }
38. Temporarily, until December 31, 2023, the following are exempt from value added tax:
{Paragraph one of clause 38 of subsection 2 of section XX as amended by Laws No. 2628-VIII of 11/23/2018 , No. 532-IX of 03/17/2020 , No. 2480-IX of 07/29/2022 }
operations on the import into the customs territory of Ukraine of medicinal products included in the State Register of Medicinal Products, medical devices included in the State Register of Medical Equipment and Medical Devices and/or put into circulation in accordance with the legislation in the field of technical regulation and conformity assessment, and operations on the first supply of such medicinal products, medical devices in the customs territory of Ukraine;
operations on the first supply by the manufacturer in the customs territory of Ukraine of medicinal products included in the State Register of Medicinal Products, medical devices included in the State Register of Medical Equipment and Medical Devices and/or put into circulation in accordance with the legislation in the field of technical regulation and conformity assessment;
operations for the supply (transfer) of medicines and medical devices that were imported and/or delivered to the customs territory of Ukraine in accordance with this paragraph, in the healthcare system from the central executive body of Ukraine that ensures the formation and implementation of state policy in the field of healthcare, and/or from state enterprises established by order of this central executive body, to the end consumer (patient) within the framework of the implementation of budget programs for the provision of medical measures of state programs and/or comprehensive program-based measures in the field of healthcare.
The exemption from value-added tax provided for in this paragraph shall apply if the import and/or supply is carried out on the basis of contracts with specialized organizations carrying out procurement, which are determined in accordance with the Law of Ukraine "On Public Procurement", concluded to implement agreements between the central executive body of Ukraine, which ensures the formation and implementation of state policy in the field of healthcare, and the relevant specialized organization carrying out procurement, within the framework of the implementation of budget programs to provide medical measures of state programs and/or comprehensive programmatic measures in the field of healthcare.
{Paragraph five of clause 38, subsection 2, section XX, as amended by Laws No. 532-IX of March 17, 2020 , No. 466-IX of January 16, 2020 }
In case of violation of the intended use of medicines and medical devices imported into the customs territory of Ukraine and/or supplied in the customs territory of Ukraine in accordance with this paragraph, the taxpayer is obliged to increase tax liabilities for the consequences of the tax period to which such violation applies by the amount of value added tax that should have been paid at the time of import (accrued at the time of supply) of such medicines and medical devices, and is also liable in accordance with the legislation.
The list of medicines and medical devices that are purchased on the basis of procurement agreements with specialized organizations that carry out procurement, and the procedure for the import, supply and intended use of medicines and medical devices that are exempt from value-added tax in accordance with this paragraph, are determined by the Cabinet of Ministers of Ukraine.
{Subsection 2 of Section XX supplemented by paragraph 38 in accordance with Law No. 332-VIII of 09.04.2015 }
38 - 1. Temporarily, until December 31, 2023, the following are exempt from value added tax:
{Paragraph one of clause 38 - 1 , subsection 2, section XX, as amended by the Law No. 2480-IX dated 07/29/2022 }
1) operations for the import into the customs territory of Ukraine of medicines, medical devices and auxiliary means for them, which are purchased with funds from the state budget by a person authorized to make purchases in the healthcare sector, for the implementation of programs and centralized healthcare measures;
2) operations for the supply in the customs territory of Ukraine of medicines, medical devices and auxiliary means for them, purchased with funds from the state budget by a person authorized to make purchases in the field of healthcare, for the implementation of programs and implementation of centralized healthcare measures. In this case, the provisions of paragraph 198.5 of Article 198 and Article 199 of this Code do not apply;
3) transactions for the free supply (transfer) by a person authorized to make purchases in the field of healthcare, of medicines, medical devices and auxiliary means for them, which were imported and/or delivered to the customs territory of Ukraine in accordance with subparagraphs 1 and 2 of this paragraph, in favor of structural units on healthcare issues of regional, Kyiv and Sevastopol city state administrations or business entities that have a license to conduct business activities in medical practice;
4) transactions for the free supply (transfer) of medicines, medical devices and auxiliary means to them, which were imported and/or delivered (transferred) to the customs territory of Ukraine in accordance with subparagraphs 1-3 of this paragraph, in the event of redistribution of such medicines, medical devices and auxiliary means to them in the manner established by law between structural units on health care of regional, Kyiv and Sevastopol city state administrations and/or business entities that have a license to conduct economic activities in medical practice;
5) operations for the free supply (transfer) in the healthcare system to the end consumer (patient), including for the purpose of providing necessary medical services and medicines provided for by the medical guarantees program, medicines, medical devices and auxiliary means for them, which were imported and/or supplied (transferred) on the customs territory of Ukraine in accordance with subparagraphs 1-4 of this paragraph, by structural units on healthcare issues of regional, Kyiv and Sevastopol city state administrations or by business entities that have a license to conduct economic activities in medical practice.
The exemption from value-added tax provided for in this paragraph shall apply if the import and/or supply (transfer) of medicinal products, medical devices and auxiliary means for them is carried out using state budget funds for the implementation of relevant agreements (contracts) concluded by the person authorized to make procurements in the healthcare sector, within the framework of the implementation of programs and centralized healthcare measures.
The list of medicines, medical devices and auxiliary means to them, which are purchased from the state budget for the implementation of programs and centralized measures in healthcare, and the procedure for their import, supply and intended use, as well as distribution (redistribution) between structural units for healthcare of regional, Kyiv and Sevastopol city state administrations and/or business entities that have a license to conduct business activities in medical practice, are approved by the Cabinet of Ministers of Ukraine.
In the event of misuse of medicines, medical devices and auxiliary means for them in accordance with this paragraph, the taxpayer is obliged to increase the tax liabilities resulting from the tax period to which such violation falls by the amount of value added tax that should have been paid upon import into the customs territory of Ukraine (supply within the customs territory of Ukraine) of such medicines, medical devices and auxiliary means for them, and also to pay a penalty in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 38 - 1 in accordance with Law No. 532-IX of March 17, 2020 }
39. For tax invoices, the date of preparation of which falls on the period from July 1 to September 30, 2015 inclusive, the deadlines for registration in the Unified Register of Tax Invoices established by paragraph 201.10 of Article 201 of this Code shall not apply, and the following registration deadlines shall be established:
tax invoices drawn up from the 1st to the 15th day (inclusive) of the month during the period specified in the first paragraph of this paragraph shall be subject to registration in the Unified Register of Tax Invoices until the last day (inclusive) of the month in which they were drawn up;
Tax invoices drawn up from the 16th to the last day (inclusive) of the month during the period specified in the first paragraph of this paragraph shall be subject to registration in the Unified Register of Tax Invoices by the 15th day (inclusive) of the month following the month in which they were drawn up.
{Subsection 2 of Section XX supplemented by paragraph 39 in accordance with Law No. 643-VIII of 16.07.2015 }
40. Penalties and fines provided for by this Code for violation of the deadlines established by this Code for independent payment of tax obligations on value added tax shall not be applied provided that, within such deadlines, there are funds on payers' accounts in the electronic administration system for value added tax in amounts sufficient to pay agreed tax obligations on value added tax to the budget or to special accounts of payers - agricultural enterprises that have chosen a special regime in accordance with Article 209 of this Code.
In the event that the aforementioned penalties are accrued during the transitional period of the electronic administration system for value added tax, such penalties shall be written off by the supervisory authority at the place of registration of the value added tax payer within 14 working days.
{Subsection 2 of Section XX supplemented by paragraph 40 in accordance with Law No. 643-VIII of 16.07.2015 }
41. If, during an inspection, the regulatory authority establishes the fact that the taxpayer overstated the negative value of the amounts of value-added tax that remained unpaid as of July 1, 2015 in the tax reporting on value-added tax, which led to an overestimation of the amount of tax for which the taxpayer has the right to register tax invoices / calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, determined by paragraph 200 - 1.3 of Article 200 - 1 of this Code, a fine of 10 percent of the amount of overstating such negative value shall be applied to such taxpayer, in addition to the fines provided for in Article 123 of this Code.
The amount of tax for which the payer has the right to register tax invoices/calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, determined by paragraph 200 - 1.3 of Article 200 - 1 of this Code, shall be subject to reduction by the amount of such overstatement on the basis of an agreed tax notice-decision.
For the purposes of this paragraph, a negative value includes the negative value of the amounts of value added tax that remained unpaid as of July 1, 2015, which is recorded in the tax reporting on value added tax and includes:
a negative value that is included in the tax credit of the next reporting (tax) period;
outstanding negative value of previous reporting (tax) periods at the end of the current reporting (tax) period.
{Subsection 2 of Section XX is supplemented by paragraph 41 in accordance with Law No. 643-VIII of 16.07.2015 - enters into force on 01.08.2015, see paragraph 1 of Section II of Law No. 643-VIII of 16.07.2015}
42. If non-current assets purchased and/or manufactured before July 1, 2015 are partly used in taxable transactions and partly not, the taxpayer shall recalculate the share of use of such non-current assets in taxable transactions, calculated in accordance with paragraphs 199.2 and 199.3 of Article 199 of this Code (based on the actual volumes of taxable and non-taxable transactions carried out during the year) based on the results of one, two and three calendar years following the year in which they began to be used (put into operation). In the event of deregistration of the taxpayer, including by court decision, the share shall be recalculated based on the actual volumes of taxable and non-taxable transactions carried out from the beginning of the current year until the date of deregistration.
{Subsection 2 of Section XX supplemented by paragraph 42 in accordance with Law No. 643-VIII of 16.07.2015 }
200.1 of Article 200 of this Code is negative , based on the results of the reporting (tax) period for June 2015/Q2 2015, the norms of subparagraphs "a" and "b" of Clause 200.4 of Article 200 of this Code in terms of the limitation by the amount calculated in accordance with Clause 200 - 1.3 of Article 200 - 1 of this Code shall not apply.
{Subsection 2 of Section XX supplemented by paragraph 43 in accordance with Law No. 643-VIII of 16.07.2015 }
44. Temporarily, until January 1, 2028, taxpayers who supply, transmit, and distribute electricity and/or heat, provide services to ensure general public interests in the process of operating the electricity market and/or load reduction services in accordance with the Law of Ukraine "On the Electricity Market", supply coal and/or products of its enrichment of commodity items 2701, 2702 and commodity subitem 2704 00 in accordance with the UKT Foreign Economic Activity , provide centralized water supply and wastewater services, charge a fee for subscriber service, determine the date of occurrence of tax liabilities and tax credit using the cash method.
{Paragraph one of clause 44, subsection 2, section XX as amended by Law No. 466-IX of 16.01.2020 ; as amended in accordance with the Laws No. 1914-IX dated 11/30/2021 , No. 2480-IX dated 07/29/2022 , No. 4536-IX dated 07/16/2025 }
The norm of this paragraph applies to transactions for which the date of occurrence of the first of the events specified in paragraph 187.1 of Article 187 and paragraph 198.2 of Article 198 of this Code falls on reporting (tax) periods before January 1, 2028.
{Paragraph two of clause 44, subsection 2, section XX, as amended by Laws No. 1914-IX of 11/30/2021 , No. 4536-IX of 07/16/2025 }
If the transactions defined by this paragraph are of a continuous or rhythmic nature of supply, taxpayers:
Buyers - taxpayers - may prepare, no later than the last day of the month in which the funds were received, consolidated tax invoices for each taxpayer with whom the supplies are of such a nature, taking into account the entire amount of funds received or other types of compensation in accordance with subparagraph 14.1.266 of paragraph 14.1 of Article 14 of this Code during such month;
{Paragraph four of clause 44, subsection 2, section XX, as amended by Law No. 1914-IX of 11/30/2021 }
Buyers - persons not registered as taxpayers - may draw up a consolidated tax invoice no later than the last day of the month in which the funds were received, taking into account the entire amount of funds received or other types of compensation in accordance with subparagraph 14.1.266 of paragraph 14.1 of Article 14 of this Code during such month.
{Paragraph five of clause 44, subsection 2, section XX, as amended by Law No. 1914-IX of 11/30/2021 }
For the purposes of this paragraph, the rhythmic nature of supply is considered to be the supply of goods/services to one buyer two or more times a month.
{Subsection 2 of Section XX supplemented by paragraph 44 in accordance with Law No. 812-VIII of 24.11.2015 ; as amended in accordance with Laws No. 1797-VIII of 21.12.2016 , No. 2628-VIII of 23.11.2018 }
45. Temporarily, until January 1, 2022, transactions for the supply of coal and/or its enrichment products of commodity items 2701, 2702, 2704 00 in accordance with the UKT Foreign Economic Activity are exempt from value added tax .
{Paragraph one of clause 45, subsection 2, section XX, as amended by Law No. 1797-VIII of 21.12.2016 }
In the event of application of the specified benefit, the provisions of paragraph 198.5 of Article 198 of this Code shall not apply to goods/services, non-current assets, the amount of value added tax on the value of which was included in the tax credit in the reporting (tax) periods preceding the period of application of the benefit.
The taxpayer may refuse to use the specified benefit or suspend its use for one or more reporting (tax) periods by submitting an application. The application, which specifies the list of commodity items of goods in accordance with the Ukrainian Customs Code of Foreign Economic Activities and the period for which the taxpayer refuses or suspends the use of the benefit, is submitted to the regulatory authority at the place of registration of the taxpayer before the beginning of the reporting period in which the taxpayer does not intend to use the specified benefit. The refusal to use the benefit specified in this paragraph or the suspension of its use shall apply from the first day of the reporting (tax) period specified in the application.
{Paragraph three of clause 45, subsection 2, section XX, as amended by Law No. 1797-VIII of 21.12.2016 }
{Subsection 2 of Section XX supplemented by paragraph 45 in accordance with Law No. 812-VIII of 24.11.2015 ; as amended in accordance with Law No. 2628-VIII of 23.11.2018 }
46. Temporarily, until January 1, 2028, the following transactions are exempt from VAT:
{Paragraph one of clause 46, subsection 2, section XX, as amended by Law No. 2719-IX of 03.11.2022 }
taxpayers - the debtor and/or guarantor (property guarantor - pledgor, mortgagee) for the supply of goods for the purposes of repaying the debtor's debt to creditors in accordance with a restructuring plan signed in accordance with the law on financial restructuring, or a rehabilitation plan approved in accordance with the legislation regulating relations on issues of restoring the debtor's solvency or declaring him bankrupt, taking into account the features established by the law on financial restructuring. When carrying out transactions for the supply of goods exempt from value added tax in accordance with this paragraph, taxpayers - the debtor and/or guarantor (property guarantor - pledgor, mortgagee) shall not apply the provisions of paragraph 198.5 of Article 198 and paragraph 199.1 of Article 199 of this Code regarding the accrual of tax liabilities or the adjustment of previously accrued tax liabilities and/or tax amounts attributed to the tax credit in connection with such supply;
banks and other financial institutions for the supply (sale, alienation in another way) of goods received by them from debtors, guarantors (property guarantors - pledgors, mortgagees) under transactions for the supply of goods that are exempt from taxation in accordance with paragraph one of this paragraph. Exemption from taxation of transactions of banks and other financial institutions applies to that part of the value of goods at which they were acquired into ownership in repayment of obligations under a credit (loan) agreement.
In the case of supply (sale, alienation in another way) by banks and other financial institutions of goods received by them as a result of transactions exempt from taxation on the basis of this paragraph, the tax base is the positive difference between the supply price and the purchase price of such goods. The purchase price is defined as the cost of goods at which such goods were received by banks and other financial institutions.
{Subsection 2 of Section XX supplemented by paragraph 46 in accordance with Law No. 909-VIII of 24.12.2015 ; as amended in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 425-IX of 20.12.2019 }
47. Temporarily, for the period of implementation of the project to modernize the Bortnytsia Wastewater Treatment Plant within the framework of the implementation of the project "Reconstruction of wastewater treatment facilities and construction of a technological line for the treatment and utilization of sludge of the Bortnytsia Aeration Plant", approved by the Cabinet of Ministers of Ukraine (hereinafter referred to as the Project), the following features of taxation with value added tax are established for Japanese entities implementing the Project:
a) a conditional full exemption from taxation shall apply to operations for import into the customs territory of Ukraine under the customs regime of temporary import of goods, defined by paragraph 4 - 2 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, for the performance of works and/or provision of services within the framework of the Project implementation;
b) operations for import into the customs territory of Ukraine under the customs regime of import of goods, defined by subparagraph 12 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, for the performance of works and/or provision of services within the framework of the implementation of the Project, are exempt from taxation;
c) transactions for the supply of services in the customs territory of Ukraine, which are performed under agreements within the framework of the Project implementation, are exempt from taxation. The procedure for exemption from taxation of such services is established by the Cabinet of Ministers of Ukraine;
d) transactions for the supply of services within the framework of the implementation of the Project for the construction of a facility (or its parts) by a Japanese entity implementing the Project to a Ukrainian customer implementing the Project, PJSC "AK "Kyivvodokanal", are exempt from taxation.
In case of violation of the conditions of exemption from taxation specified in this paragraph, the taxpayer is obliged to increase the tax liabilities based on the results of the tax period to which such violation applies by the amount of tax that should be accrued on the date of occurrence of such tax liabilities, and also to pay a penalty accrued on such amount of tax, based on 120 percent of the discount rate of the National Bank of Ukraine, which was in effect on the date of the increase in the tax liability, for the period from the date of occurrence of tax liabilities to the date of the increase in the amount of tax liabilities.
The term "Japanese Project Implementing Entity" is used in the meaning given in paragraph 9 of subsection 1 of this section.
{Subsection 2 of Section XX supplemented by a paragraph in accordance with Law No. 903-VIII of 23.12.2015 ; as amended in accordance with Law No. 1797-VIII of 21.12.2016 }
48. To establish that accounts in the electronic administration system for value added tax, additionally opened in accordance with paragraph 200 - 1.2 of Article 200 - 1 of this Code for payers - agricultural enterprises that have chosen a special taxation regime in accordance with Article 209 of this Code, shall be closed from the day following the deadline for payment of tax liabilities for December 2016, for payers who have chosen a quarterly tax period - for the fourth quarter of 2016.
To close such accounts in the electronic administration system of value added tax, the central executive body that ensures the implementation of tax and customs policy sends to the body that carries out treasury services of budget funds, in which payers' accounts in the electronic administration system of value added tax are closed, a register of payers, which indicates the name of the payer, tax number and individual tax number of the payer.
{Subsection 2 of Section XX supplemented by paragraph 48 in accordance with Law No. 1791-VIII of 20.12.2016 }
49. Registration of tax invoices and/or calculations of adjustments to tax invoices in the Unified Register of Tax Invoices drawn up by payers - agricultural enterprises that, until January 1, 2017, applied a special taxation regime in accordance with Article 209 of this Code, for transactions for the supply of agricultural goods/services, determined in accordance with Clause 209.7 of Article 209 of this Code, must be carried out no later than January 15, 2017.
of tax invoices and/or calculations of adjustments to tax invoices specified in the first paragraph of this paragraph may not be carried out in violation of the deadline specified in the first paragraph of this paragraph.
{Subsection 2 of Section XX supplemented by paragraph 49 in accordance with Law No. 1791-VIII of 20.12.2016 }
50. The amount of negative value for transactions for the supply of agricultural goods/services, determined in accordance with Clause 209.7 of Article 209 of this Code, formed by payers - agricultural enterprises that, until January 1, 2017, applied a special taxation regime in accordance with Article 209 of this Code, based on the results of the reporting (tax) period for December 2016/fourth quarter of 2016, shall be carried over to the tax reporting of the next reporting (tax) period, in which settlements with the budget are reflected.
{Subsection 2 of Section XX supplemented by paragraph 50 in accordance with Law No. 1791-VIII of 20.12.2016 }
51. To establish that from January 1, 2017 to January 1, 2022, payers - agricultural producers, included in the Register of recipients of budget subsidies in accordance with the Law of Ukraine "On State Support for Agriculture of Ukraine" (hereinafter referred to as the Register of Recipients of Budget Subsidies), in accordance with the procedure and within the terms established by this Code, shall submit a tax return on value added tax with an appendix indicating the amount of tax liabilities on value added tax on the supply of goods based on the results of activities under transactions specified in paragraph 16 - 1.3 of Article 16 - 1 of the Law of Ukraine "On State Support for Agriculture of Ukraine", calculated based on the data of tax invoices for the relevant reporting tax period, registered in the Unified Register of Tax Invoices, as well as the calculation of the specific weight of the value of agricultural goods supplied during the previous 12 consecutive reporting tax periods (months).
{Paragraph one of clause 51, subsection 2, section XX as amended by Law No. 2245-VIII of 07.12.2017 }
The form of the application is approved by the central executive body that ensures the formation and implementation of state financial policy. The central executive body that ensures the formation and implementation of state financial policy may establish additional requirements for the display of data on individual types of activities specified in paragraph 16 - 1.3 of Article 16 - 1 of the Law of Ukraine "On State Support for Agriculture of Ukraine".
{Paragraph two of clause 51, subsection 2, section XX as amended by Law No. 2245-VIII of 07.12.2017 }
To carry out, in accordance with the procedure established by Article 200-1 of this Code, settlements with the budget of payers - agricultural producers included in the Register of Recipients of Budget Subsidies, the central executive body implementing the state tax and customs policy shall send to the central executive body ensuring the formation and implementation of the state agrarian policy and to the central executive body implementing the state policy in the field of treasury servicing of budget funds, in which payers' accounts are opened in the system of electronic administration of value added tax, a separate register indicating the name of the payer - agricultural producer, his tax number and individual tax number, and the amount of tax paid to the budget.
{Subsection 2 of Section XX supplemented by paragraph 51 in accordance with Law No. 1791-VIII of 20.12.2016 }
52. By January 10, 2017, the central executive body implementing the state tax and customs policy shall be obliged, based on the registers of applications for the return of the amount of budget compensation to taxpayers who meet and who do not meet the criteria specified in paragraph 200.19 of Article 200 of this Code, in the version in force until January 1, 2017, to form a single Register of applications for the return of the amount of budget compensation in the chronological order of their receipt.
The formation, maintenance, budget reimbursement and official publication of the Register of applications for the return of the amount of budget reimbursement specified in this paragraph shall be carried out in accordance with the procedure specified in Article 200 of this Code.
{Subsection 2 of Section XX supplemented by paragraph 52 in accordance with Law No. 1797-VIII of 21.12.2016 }
53. To establish that on January 20, 2017, the amount for which the payer has the right to register tax invoices /calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, determined by clause 200 - 1 .3 of Article 200 - 1 of this Code, is increased by the amount of funds returned in the period from January 1, 2016 to January 1, 2017 to the taxpayer in accordance with clause 43.4 of Article 43 of this Code to the account in the electronic administration system of value added tax: transferred from the payer's current account directly to the budget; transferred from the account in the electronic administration system of value added tax to the budget at the payer's request in accordance with clause 200 - 1 .6 of Article 200 - 1 of this Code, which was in force during this period.
, the taxpayer has the right to submit an application and transfer funds from the account in the electronic administration system of the value-added tax of such taxpayer to his current account in accordance with clause 200 - 1.6 of Article 200 - 1 of this Code.
{Subsection 2 of Section XX supplemented by paragraph 53 in accordance with Law No. 1797-VIII of 21.12.2016 }
54. Penalties and fines provided for by this Code shall not apply to agricultural enterprises that applied a special regime of taxation by value-added tax in accordance with Article 209 of this Code, for understatement by such agricultural enterprises of the tax liability for value-added tax or overstatement by them of budget compensation, which arose as a result of violation of the procedure for distributing the tax credit, determined by subparagraph 209.15.1 of paragraph 209.15 of Article 209 of this Code, for the reporting (tax) periods from January 1, 2016 to January 1, 2017.
{Subsection 2 of Section XX supplemented by paragraph 54 in accordance with Law No. 1797-VIII of 21.12.2016 }
54 - 1 . For the purposes of applying the value added tax rate on the supply in the customs territory of Ukraine and the import into the customs territory of Ukraine of agricultural products (goods) classified under the following codes according to the UKT FEA : 0102, 0103, 0401 (in terms of whole milk), 1001, 1002, 1003, 1004, 1005, 1201, 1204 00, 1205, 1206 00, 1207, 1212 91, except for operations on the import into the customs territory of Ukraine of goods specified in paragraph 197.18 of Article 197 of this Code, established in accordance with the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Value Added Tax Rate on Operations on the Supply of Certain Types of Agricultural Products", it shall be established that the tax rate in effect until the first day of the reporting year (tax) period from which the value added tax rate of 14 percent applies, applies in the case of:
1) supply on the customs territory of Ukraine of products (goods) specified in the first paragraph of this paragraph, which occurs after the taxpayer transfers the prepayment (advance payment) received before the first day of the reporting (tax) period, from which the value added tax rate of 14 percent is applied;
2) adjustment of tax liabilities upon return of advance payment (advance payment) or return of products (goods) received before the first day of the reporting (tax) period, from which the value added tax rate of 14 percent is applied;
3) adjustment of tax liabilities upon change of the contractual value of products (goods) specified in the first paragraph of this paragraph, the delivery of which took place before the first day of the reporting (tax) period, from which the value added tax rate of 14 percent is applied.
In the event that a taxpayer carries out operations on the supply of products (goods) in the customs territory of Ukraine, defined in the first paragraph of this paragraph, which were purchased before the first day of the reporting (tax) period, from which the value added tax rate of 14 percent is applied, such taxpayer shall retain a tax credit for value added tax in the amount that was accrued upon the purchase and/or supply of such agricultural products (goods).
{Subsection 2 of Section XX supplemented by paragraph 54 - 1 in accordance with Law No. 1115-IX of 17.12.2020 }
55. Establish that budget reimbursement of value-added tax is carried out within the funds available in the single treasury account.
{Subsection 2 of Section XX supplemented by paragraph 55 in accordance with Law No. 1797-VIII of 21.12.2016 }
56. By February 1, 2017, the central executive body implementing the state tax and customs policy shall form, in chronological order of receipt of applications for the return of the amount of budget reimbursement of value added tax, a Temporary Register of applications for the return of the amount of budget reimbursement submitted by February 1, 2016, for which, as of January 1, 2017, the amounts of value added tax have not been reimbursed from the budget.
The formation, maintenance and official publication of the Temporary Register of applications for the return of the amount of budget compensation specified in this paragraph shall be carried out in accordance with the procedure specified in Article 200 of this Code.
The reimbursement of the agreed amounts of value added tax specified in such a register shall be carried out in chronological order in accordance with the order of receipt of applications for the refund of such amounts of budget reimbursement of value added tax within the limits of the amounts specified by the law on the State Budget for the relevant year. The distribution of the amounts of budget reimbursement of value added tax specified by the law on the State Budget for the relevant year between the Temporary Register of Applications for the Refund of the Amount of Budget Compensation specified in this paragraph and the Register of Applications for the Refund of the Amount of Budget Compensation of Value Added Tax shall be carried out by the Cabinet of Ministers of Ukraine.
{Subsection 2 of Section XX supplemented by paragraph 56 in accordance with Law No. 1797-VIII of 21.12.2016 }
57. The period from April 1, 2017 to July 1, 2017 is a transitional period during which the procedure specified in paragraph 201.16 of Article 201 of this Code is carried out without actually suspending the registration of the tax invoice /calculation of the adjustment in the Unified Register of Tax Invoices.
{Subsection 2 of Section XX supplemented by paragraph 57 in accordance with Law No. 1797-VIII of 21.12.2016 }
57 - 1. Tax invoices /adjustment calculations, the registration of which in the Unified Register of Tax Invoices has been suspended in accordance with clause 201.16 of Article 201 of this Code, shall be registered taking into account the requirements of clauses 200 - 1.3 and 200 - 1.9 of Article 200 - 1 and clause 201.10 of Article 201 of this Code no later than January 2, 2018, except for:
tax invoices/adjustment calculations for which, as of December 1, 2017, explanations and copies of documents have not been submitted in accordance with subparagraph 201.16.2 of paragraph 201.16 of Article 201 of this Code;
tax invoices/adjustment calculations for which a decision was made to refuse to register the tax invoice/adjustment calculation in the Unified Register of Tax Invoices, for which as of December 1, 2017, no administrative or judicial appeal procedure had been initiated.
Tax invoices /adjustment calculations, the registration of which in the Unified Register of Tax Invoices was suspended in accordance with Clause 201.16 of Article 201 of this Code from December 1, 2017 until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Legislative Acts of Ukraine on Ensuring the Balance of Budget Revenues in 2018" and for which the taxpayer submitted explanations and copies of documents after December 1, 2017 in accordance with Subclause 201.16.2 of Clause 201.16 of Article 201 of this Code, shall be registered in the Unified Register of Tax Invoices in accordance with the procedure that was in force before the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Legislative Acts of Ukraine on Ensuring the Balance of Budget Revenues in 2018" regarding the suspension of registration of the tax invoice/adjustment calculation in the Unified Register of Tax Invoices. register of tax invoices. If within five business days from the date of submission of explanations and copies of documents a decision on registration or refusal to register a tax invoice/adjustment calculation is not made and/or sent to the taxpayer, registration of such tax invoices/adjustment calculations is carried out on the next business day after the expiry of the deadline for consideration of the taxpayer's explanations and copies of documents.
The effect of paragraph three of clause 201.10 of Article 201 of this Code shall be suspended until the date of entry into force of the procedure approved in accordance with clause 201.16 of this Code.
{Subsection 2 of Section XX supplemented by paragraph 57 - 1 in accordance with Law No. 2245-VIII of 07.12.2017 }
58. The supervisory authority, upon the taxpayer's application, shall grant a deferral (in equal installments) of payment of value added tax for a period of up to 36 calendar months without accrual of interest and penalties specified in Clause 129.5 of Article 129 of this Code, upon import into the customs territory of Ukraine under the customs regime of import only of woodworking machines classified under commodity code 8465 according to the UKT FEA ; wood dryers classified in commodity subcategories 8419 33 00 00, 8419 35 00 00 according to the UKT FEA; presses for the production of chipboard or fiberboard classified in commodity subheading 8479 30 according to the UKT FEA, which are imported for use in woodworking production.
{Paragraph one of clause 58, subsection 2, section XX, as amended by Law No. 3553-IX of 16.01.2024 }
The procedure for granting installments for payment of value added tax in accordance with this paragraph shall be established by the Cabinet of Ministers of Ukraine.
In the event of misuse of equipment and machinery imported into the customs territory of Ukraine in accordance with the procedure specified in this paragraph, the taxpayer shall be obliged to pay tax liabilities based on the results of the tax period to which such violation applies, in the amount calculated as the positive difference between the amount of value added tax that should have been paid from the specified transactions at the time of import of such goods and the amount actually paid, as well as to pay a penalty accrued on such tax amount, based on 120 percent of the discount rate of the National Bank of Ukraine, effective on the day of payment of the tax liability, for the period from the day of import of such goods to the day of increase in the tax liability.
{Subsection 2 of Section XX supplemented by paragraph 58 in accordance with Law No. 1797-VIII of 21.12.2016 }
59. The supervisory authority, upon the taxpayer's application, shall grant a deferral (in equal installments) of payment of value added tax for a period of up to 36 calendar months without accrual of interest and penalties specified in paragraph 129.5 of Article 129 of this Code, upon import into the customs territory of Ukraine under the customs regime of import of equipment (its parts) classified in the commodity subcategories 8421 39 15 20, 8421 39 25 00, 8422 30 00 99, 8422 90 90 00, 8428 20 20 00, 8428 20 80 00, 8477 10 00 00, 8477 20 00 00, 8477 30 00 00, 8477 40 00 00, 8477 59 10 90, 8477 90 80 00, 8485 90 90 90 (only parts (except parts of cast iron or steel) for machines for layer-by-layer building by applying plastics and rubber), 8480 71 00 90 according to the UKT Foreign Economic Activity for the production of medical devices only.
{Paragraph one of clause 59, subsection 2, section XX, as amended by Laws No. 1914-IX of 11/30/2021 , No. 3553-IX of 01/16/2024 }
The procedure for granting installments for payment of value added tax in accordance with this paragraph shall be established by the Cabinet of Ministers of Ukraine.
In the event of misuse of equipment and machinery imported into the customs territory of Ukraine in accordance with the procedure specified in this paragraph, the taxpayer shall be obliged to pay tax liabilities based on the results of the tax period to which such violation applies, in the amount calculated as the positive difference between the amount of value added tax that should have been paid from the specified transactions at the time of import of such goods and the amount actually paid, as well as to pay a penalty accrued on such tax amount, based on 120 percent of the discount rate of the National Bank of Ukraine, effective on the day of payment of the tax liability, for the period from the day of import of such goods to the day of increase in the tax liability.
{Subsection 2 of Section XX supplemented by paragraph 59 in accordance with Law No. 1797-VIII of 21.12.2016 }
60. To establish that until December 31, 2017, the amount for which a taxpayer has the right to register tax invoices/calculations of adjustments to tax invoices in the Unified Register of Tax Invoices, determined by clause 200 - 1.3 of Article 200 - 1 of this Code, shall be increased by the amount of funds that were transferred from January 1 to January 30, 2017 from current accounts to special accounts opened for agricultural enterprises that applied a special taxation regime in accordance with Article 209 of this Code until January 1, 2017, in banking institutions, but not more than the amount that was to be transferred to the special account of the subject of the special taxation regime according to the tax reporting for December 2016, except for clarifying calculations.
Such an increase is made once upon a taxpayer's application submitted in any form to the central executive body implementing state tax and customs policy, together with copies of the payer's payment orders, duly certified by the bank, confirming such a transfer.
Within the amount of such increase, the taxpayer has the right to submit to the central executive body implementing state tax and customs policy an application, according to which such funds are subject to transfer from the account in the electronic administration system of the value added tax of such taxpayer to his current account in accordance with clause 200 - 1.6 of Article 200 - 1 of this Code, for those taxpayers for whom such funds are recorded in accounts in the electronic administration system of the value added tax.
{Subsection 2 of Section XX supplemented by paragraph 60 in accordance with Law No. 1988-VIII of 23.03.2017 }
61. Temporarily, until January 1, 2023, transactions of cinematographic entities that are provided with state support in accordance with the Law of Ukraine "On State Support of Cinematography in Ukraine" are exempted from VAT on the import into the customs territory of Ukraine under the customs regime of import of goods that are part of the national cinematographic heritage and goods intended for use in cinematographic activities, classified under the UKT FEA codes 3706, 3920 73 10 00, 3923 40 10 00, 8525, 8529, 9002, 9007, 9010, 9405.
The procedure, volumes and conditions for importing the goods specified in this paragraph into the customs territory of Ukraine shall be determined by the Cabinet of Ministers of Ukraine.
In the event of misuse of the specified goods, the taxpayer is obliged to increase the tax liability for the tax period to which such violation applies by the amount of value added tax that should have been paid at the time of importation of such goods into the customs territory, and also to pay a penalty in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 61 in accordance with Law No. 2176-VIII of 07.11.2017 }
62. Temporarily, until July 1, 2018, the fines provided for in Article 120-1 , Article 126 of this Code (in terms of value added tax) shall not be applied, and the penalty established by subparagraph 129.1.3 of paragraph 129.1 of Article 129 of this Code (in terms of value added tax) shall not be charged to electricity producers that supply electricity to the state enterprise "Energorynok" and as of January 1, 2016 had a tax debt on value added tax, including installments and/or deferred.
The list of electricity producers to which this clause applies and the list of tax invoices drawn up by such electricity producers since July 1, 2015 and not registered in the Unified Register of Tax Invoices shall be approved by the Cabinet of Ministers of Ukraine.
{Subsection 2 of Section XX supplemented by paragraph 62 in accordance with Law No. 2198-VIII of 09.11.2017 }
{Item 63 of Subsection 2 of Section XX was excluded pursuant to Law No. 466-IX of January 16, 2020 }
{Item 64 of Subsection 2 of Section XX was excluded pursuant to Law No. 4698-IX of 03.12.2025 }
64 - 1. Temporarily, until January 1, 2026, transactions for the import into the customs territory of Ukraine and the supply within the customs territory of Ukraine of new vehicles (including those manufactured in Ukraine) equipped with spark-ignition internal combustion engines operating exclusively on compressed natural methane gas, liquefied natural methane gas or biogas, classified in commodity subheading 8701 23, commodity category 8701 29 00, commodity positions 8703, 8704 according to the UKT Foreign Economic Activity are exempt from value added tax .
{Subsection 2 of Section XX supplemented by paragraph 64 - 1 in accordance with Law No. 1660-IX of 07/15/2021 ; as amended by Law No. 3553-IX of 01/16/2024 }
{Paragraph one of clause 65, subsection 2, section XX, as amended by Law No. 466-IX of January 16, 2020 ; as amended by Laws No. 1914-IX of November 30, 2021 , No. 3553-IX of January 16, 2024 }
When granting a deferral of payment of value added tax, the provisions of Article 100 of this Code shall not apply.
The procedure for granting installments for payment of value added tax and applying security in accordance with this paragraph shall be established by the Cabinet of Ministers of Ukraine.
The remaining amount of the value added tax liability shall be secured in accordance with Section X of the Customs Code of Ukraine or by a bank guarantee issued in accordance with the legislation of Ukraine, except for cases where the remaining amount of the value added tax liability shall be secured by pledging equipment and components imported in accordance with this clause. The Cabinet of Ministers of Ukraine shall have the right to establish cases where the remaining amount of the value added tax liability shall be secured by pledging equipment and components imported in accordance with this clause.
{Paragraph four of clause 65, subsection 2, section XX, as amended by Law No. 2628-VIII of 23.11.2018 }
In case of failure by the payer to fulfill the obligations to pay value added tax, secured in accordance with Section X of the Customs Code of Ukraine, within the time limits established by law, the supervisory authority shall send the guarantor a written demand for payment of the amount of value added tax and documents confirming the occurrence of the guarantee event. The guarantor shall be obliged, no later than three banking days after the day of receipt of the demand and documents confirming the occurrence of the guarantee event, to transfer the due amount of value added tax to the state budget. In case of violation of the term for transferring funds for the payment of value added tax in accordance with the requirement of the supervisory authority, the guarantor shall be liable in accordance with the law. In case of failure by the guarantor to pay funds under the guarantees provided by him, the amounts of such funds shall be collected in accordance with the procedure established by law. The provisions of the legislation of Ukraine on banks and banking activities, the Customs Code of Ukraine , the legislation in the field of financial services and the civil legislation of Ukraine in the part not regulated by this Code also apply to legal relations related to the issuance of guarantees, the performance of obligations by guarantors and the termination of the guarantee.
{Paragraph five of clause 65, subsection 2, section XX, as amended by Law No. 2628-VIII of 11/23/2018 }
The tax amounts paid taking into account the requirements established by this paragraph shall be included by the payer in the tax credit in the reporting (tax) period in which the tax was paid to the budget.
Equipment and components are imported into the customs territory of Ukraine by the taxpayer for its own production in the territory of Ukraine.
{Paragraph seven of clause 65, subsection 2, section XX, as amended by Law No. 2628-VIII of 23.11.2018 }
In the event of a taxpayer violating the terms of an installment payment secured by collateral, the sale of the pledged property of such taxpayer shall be carried out using a two-tier electronic trading system (ETS) in accordance with the procedure established by the Cabinet of Ministers of Ukraine. An electronic trading system is a two-tier information and telecommunications system consisting of a central database and electronic platforms that interact through an application programming interface, which is provided in the form of open access code and determines the functionality of the electronic trading system.
Taxpayers who have been granted an installment plan in accordance with paragraphs 58 and 59 of this subsection before the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Legislative Acts of Ukraine Regarding Ensuring Balanced Budget Revenues in 2018" have the right to change the security for the fulfillment of obligations to pay value added tax provided to the supervisory authority in accordance with Section X of the Customs Code of Ukraine to the security for the fulfillment of obligations to pay value added tax provided for in this paragraph by a bank guarantee issued in accordance with the legislation of Ukraine, or by a pledge.
The deferral of payment of value added tax in accordance with this clause is not granted when importing equipment into the customs territory of Ukraine under the customs regime of import, if it originates from a country recognized as an occupying state in accordance with the law of Ukraine and/or recognized as an aggressor state in relation to Ukraine in accordance with the law, or is imported from the territory of such an occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law of Ukraine.
In the event of alienation, lease, sublease or transfer of ownership, use in another manner of equipment and components imported into the customs territory of Ukraine in accordance with the procedure specified in this paragraph, the taxpayer shall be obliged to pay tax liabilities based on the results of the tax period to which such violation applies, in the amount calculated as the positive difference between the amount of value added tax that should have been paid from the specified transactions at the time of import of such goods without applying the taxation features provided for in this paragraph, and the amount actually paid, as well as to pay a penalty accrued on such tax amount, based on 120 percent of the discount rate of the National Bank of Ukraine, effective on the day of payment of the tax liability, for the period from the day of import of such goods to the day of increase in the tax liability.
{Paragraph eleven of clause 65, subsection 2, section XX, as amended by Law No. 2628-VIII of 23.11.2018 }
{Subsection 2 of Section XX supplemented by paragraph 65 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended in accordance with Law No. 2628-VIII of 23.11.2018 }
66. Until May 26, 2018, the following shall apply to operations involving the import into the customs territory of Ukraine of goods specified in paragraphs two and three of clause 4 - 3 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine:
exemption from value added tax when placing such goods under the import customs regime;
conditional full exemption from value added tax if such goods are placed under the customs regime of temporary import.
In the event of misuse of the specified goods, the taxpayer is obliged to pay the amount of tax liability for which such exemption or conditional full exemption was granted, and the penalty accrued in accordance with Article 129 of this Code, calculated from the date of granting the exemption or conditional full exemption from taxation.
{Subsection 2 of Section XX supplemented by paragraph 66 in accordance with Law No. 2374-VIII of 22.03.2018 }
67. Temporarily, until May 26, 2018 inclusive, transactions for the supply (provision) by UEFA or legal entities authorized by UEFA to carry out organizational events and/or conduct the final matches of the UEFA Champions League and the UEFA Women's Champions League of the 2017/2018 season, tickets and services that are an integral part thereof, are exempt from VAT.
For the purposes of this clause, the term "UEFA" is used to mean "Union of European Football Associations".
{Subsection 2 of Section XX supplemented by paragraph 67 in accordance with Law No. 2374-VIII of 22.03.2018 }
68. To establish that from January 1, 2019 to June 30, 2019, the import of goods into the customs territory of Ukraine, the total invoice value of which does not exceed the equivalent of 150 euros for one recipient - an individual in one dispatch from one sender in international postal shipments or in one express carrier's cargo from one sender in international express shipments, is not subject to VAT.
From January 1, 2019 to December 31, 2020, the provisions of Clause 180.2 - 1 of Article 180 and Subclauses 191.1.3 and 191.1.4 of Clause 191.1 of Article 191 of this Code shall not apply.
From July 1, 2019 to December 31, 2020, the calculation and payment of value added tax in the event of the import into the customs territory of Ukraine of goods in international postal and express shipments, the total invoice value of which exceeds the equivalent of 100 euros for one recipient - an individual in one dispatch from one sender in international postal shipments or in one express carrier shipment from one sender in international express shipments, shall be carried out in accordance with the procedure for calculating and paying value added tax determined by the Customs Code of Ukraine when importing into the customs territory of Ukraine goods in international postal and express shipments, the total invoice value of which exceeds the equivalent of 150 euros for one recipient - an individual in one dispatch from one sender in international postal shipments or in one express carrier shipment from one sender in international express shipments.
{Subsection 2 of Section XX supplemented by paragraph 68 in accordance with Law No. 2628-VIII of 23.11.2018 }
68 - 1. To establish that the provisions of clause 180.2 - 1 of Article 180 and subparagraph 191.1.3 of clause 191.1 of Article 191 of this Code shall not be applied within six months from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Taxation of Goods Moved (Forwarded) in International Postal and Express Shipments".
{Subsection 2 of Section XX supplemented by paragraph 68 - 1 in accordance with Law No. 1998-IX of 01/25/2022 }
69. Temporarily, until April 1, 2019, the value added tax liabilities that arose for the electricity supplier on the date of receipt from the buyer of an advance payment for electricity, the actual supply of which will be carried out by the new electricity supplier, including the universal service provider, are subject to adjustment on the date of transfer by the electricity supplier of funds received from the buyer as an advance payment to the new electricity supplier on the basis of the calculation of the adjustment to the tax invoice, drawn up and registered in the Unified Register of Tax Invoices in accordance with the general procedure specified by this Code.
{Subsection 2 of Section XX supplemented by paragraph 69 in accordance with Law No. 2628-VIII of 23.11.2018 }
70. In order to fulfill the obligations regarding the unbundling of natural gas transportation activities and ensuring the activities of the gas transmission system operator, undertaken by Ukraine in accordance with the Law of Ukraine "On Ratification of the Protocol on Ukraine's Accession to the Treaty Establishing the Energy Community", temporarily:
1) until January 1, 2021, the transaction of transferring from the balance sheet of the taxpayer to the balance sheet of another legal entity, 100 percent of the corporate rights in the authorized capital of which are directly or indirectly owned by the state, or to the balance sheet of a state authority, property (fixed assets, intangible assets, unfinished capital investments, other non-current assets), which is state-owned as part of main gas pipelines and all objects and structures connected to them by a single technological process, and is used to ensure the transportation of natural gas through main gas pipelines and the activities of the gas transportation system operator, shall be exempt from value added tax. In this case, the provisions of paragraph 198.5 of Article 198 and Article 199 of this Code shall not apply;
2) until January 1, 2022, for transactions for the supply of property of a legal entity that is not in state or municipal ownership (fixed assets, intangible assets, unfinished capital investments, other non-current assets, inventories) and is used to ensure the transportation of natural gas through main gas pipelines and the activities of the gas transmission system operator, the date of occurrence of tax liabilities and tax credit is determined using the cash method.
The norm of the first paragraph of this subparagraph applies to transactions for which the date of occurrence of the first of the events specified in paragraph 187.1 of Article 187 and paragraph 198.2 of Article 198 of this Code falls on reporting (tax) periods before January 1, 2022;
3) until January 1, 2021, transactions for the provision (transfer) and return under a loan agreement of natural gas used to ensure the activity of transporting natural gas through main gas pipelines are not considered supplies of goods (services).
The lists of property specified in subparagraphs 1 and 2 of this paragraph, as well as the list of business entities (lenders) indicating the volumes of natural gas for the purposes of applying subparagraph 3 of this paragraph, shall be approved by the Cabinet of Ministers of Ukraine.
{Subsection 2 of Section XX supplemented by paragraph 70 in accordance with Law No. 314-IX of 03.12.2019 }
71. Temporarily, for the period ending on the last calendar day of the month in which the quarantine established by the Cabinet of Ministers of Ukraine throughout Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine, transactions for the import into the customs territory of Ukraine and/or transactions for the supply to the customs territory of Ukraine of goods (including medicines, medical devices and/or medical equipment) necessary for the implementation of measures aimed at preventing the occurrence and spread, localization and elimination of outbreaks, epidemics and pandemics of coronavirus disease (COVID-19), the list of which is determined by the Cabinet of Ministers of Ukraine, are exempt from VAT.
In the event of transactions exempted under this clause, the provisions of clause 198.5 of Article 198 of this Code and the provisions of Article 199 of this Code shall not apply to such transactions.
The provisions of this paragraph apply to transactions carried out starting from March 17, 2020.
{Subsection 2 of Section XX supplemented by paragraph 71 in accordance with Law No. 530-IX of March 17, 2020 ; as amended by Law No. 540-IX of March 30, 2020 }
71. Temporarily, until December 31, 2020, transactions for the free transfer into possession and use of vehicles of commodity positions 8702 and 8703 in accordance with the UKT Foreign Economic Activity for persons with disabilities, including children with disabilities, and other privileged categories of the population defined by the legislation of Ukraine, according to the list approved by the Cabinet of Ministers of Ukraine, as well as special-purpose vehicles (ambulance and for the needs of central executive bodies implementing state policy in the areas of civil protection, rescue, fire and technogenic safety) are exempt from taxation.
In case of violation of the intended use of such vehicles or their alienation in the customs territory of Ukraine, the taxpayer is obliged to increase the tax liabilities due to the consequences of the tax period to which such violation applies by the amount of value added tax that should have been paid at the time of the free transfer of such vehicles, as well as pay a penalty in accordance with the law.
The procedure for accounting for vehicles transferred free of charge and monitoring their intended use is established by the Cabinet of Ministers of Ukraine.
{Subsection 2 of Section XX supplemented by paragraph 71 in accordance with Law No. 466-IX of January 16, 2020 }
72. Temporarily, for the period ending on the last day of the month in which the quarantine introduced by the Cabinet of Ministers of Ukraine in accordance with the procedure established by law ends throughout the territory of Ukraine in order to prevent the spread of coronavirus disease (COVID-19) in the territory of Ukraine, the transactions provided for in paragraph 71 of this subsection and/or subparagraph 197.1.15 of paragraph 197.1 of Article 197 of this Code, carried out by public associations and/or charitable organizations, shall not be included by such public associations or charitable organizations when calculating the total amount specified in Article 181 of this Code.
The provisions of this paragraph apply to transactions carried out starting from March 17, 2020.
{Subsection 2 of Section XX supplemented by paragraph 72 in accordance with Law No. 540-IX of 30.03.2020 }
72. To establish that in the period from January 1, 2016 to February 1, 2020, the procedure for exemption from value- added tax established by Clause 197.2 of Article 197 of this Code shall apply to transactions for the supply of goods/services on the customs territory of Ukraine intended for humanitarian aid provided in Ukraine by diplomatic missions, consular offices of foreign states and representative offices of international organizations in Ukraine in accordance with the Law of Ukraine "On Humanitarian Aid" .
{Subsection 2 of Section XX supplemented by paragraph 72 in accordance with Law No. 466-IX of January 16, 2020 }
73. Fines for violation by value-added tax payers of the deadline for registering a tax invoice and/or calculating an adjustment to such a tax invoice in the Unified Register of Tax Invoices, provided for in Article 201 of this Code, for transactions exempt from taxation by value-added tax, transactions taxed by value-added tax at a zero rate, transactions that do not provide for the provision of a tax invoice to the recipient (buyer), as well as a tax invoice drawn up in accordance with Clause 198.5 of Article 198 of this Code in the case of transactions specified in subparagraphs "a" - "d" of Clause 198.5 of Article 198 of this Code, and the calculation of an adjustment drawn up to such a tax invoice, a tax invoice drawn up in accordance with Article 199 of this Code, and the calculation of an adjustment drawn up to such a tax invoice, a tax invoice drawn up in accordance with paragraph eleventh paragraph 201.4 of Article 201 of this Code, and the calculation of the adjustment drawn up to such a tax invoice, accrued to taxpayers during the period from January 1, 2017 until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve Tax Administration, Eliminate Technical and Logical Inconsistencies in Tax Legislation", the payment deadline for monetary obligations for which has not come or monetary obligations for which are inconsistent (the relevant tax notices-decisions are in the procedure of administrative or judicial appeal and monetary obligations for them have not been paid) as of the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve Tax Administration, Eliminate Technical and Logical Inconsistencies in Tax Legislation", are applied in the amount of 1 percent of the volume of supply (excluding value added tax), but not more than 510 hryvnias.
{Paragraph one of clause 73, subsection 2, section XX, as amended by Law No. 786-IX of 14.07.2020 }
Fines imposed due to the lack of registration within the time limit provided for in Article 201 of this Code of a tax invoice and/or a calculation of an adjustment to such a tax invoice in the Unified Register of Tax Invoices for transactions exempt from VAT, transactions subject to VAT at a zero rate, transactions that do not provide for the provision of a tax invoice to the recipient (buyer), as well as a tax invoice drawn up in accordance with Clause 198.5 of Article 198 of this Code in the event of transactions specified in subparagraphs "a" - "d" of Clause 198.5 of Article 198 of this Code, and a calculation of an adjustment drawn up to such a tax invoice, a tax invoice drawn up in accordance with Article 199 of this Code, and a calculation of an adjustment drawn up to such a tax invoice, a tax invoice drawn up in accordance with paragraph eleven of Clause 201.4 of Article 201 of this Code, and the calculation of the adjustment drawn up to such a tax invoice, accrued to taxpayers during the period from January 1, 2017 until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve Tax Administration, Eliminate Technical and Logical Inconsistencies in Tax Legislation", the payment term for which has not come or the monetary obligations for which are not agreed (the relevant tax notices-decisions are in the procedure of administrative or judicial appeal and the monetary obligations for them have not been paid) as of the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine to Improve Tax Administration, Eliminate Technical and Logical Inconsistencies in Tax Legislation", are applied in the amount of 2.5 percent of the volume of supply (excluding value added tax), but not more than 1,700 hryvnias.
{Paragraph two of clause 73, subsection 2, section XX, as amended by Law No. 786-IX of 14.07.2020 }
The supervisory authority at the place of registration of the taxpayer shall recalculate the amount of the fine and send (hand over) a new tax notice-decision to such taxpayer. The previous tax notice-decision shall be considered canceled (withdrawn).
{Subsection 2 of Section XX supplemented by paragraph 73 in accordance with Law No. 466-IX of January 16, 2020 }
73 - 1. To establish that for value added tax payers who pay a single tax and apply a quarterly reporting (tax) period, the last quarterly reporting (tax) period for submitting tax reports on value added tax is the second quarter of 2020.
The first monthly reporting (tax) period for value-added tax for such payers is July 2020.
{Subsection 2 of Section XX is supplemented by paragraph 73 - 1 in accordance with Law No. 786-IX of July 14, 2020 }
74. Temporarily, until December 31, 2020, in order to ensure financing of expenditures under programs provided for in paragraphs 31-33 of Article 14 of the Law of Ukraine "On the State Budget of Ukraine for 2020", when calculating the Σ PopRakh indicator, the amount of funds credited to the account of the Public Joint-Stock Company "Ukrnafta" in the electronic administration system of value-added tax from the accounts of the Public Joint-Stock Company "Ukrnafta" opened in the relevant bodies carrying out treasury services of budget funds, for mutual settlements, formed to ensure receipts to the special fund of the state budget from the Public Joint-Stock Company "Ukrnafta", determined by paragraphs 13 (in terms of repayment of tax debt under tax liabilities on value-added tax declared for reporting (tax) periods starting from July 2015 / III quarter of 2015, which were payable to the state budget) and 15 Article 11 of the Law of Ukraine "On the State Budget of Ukraine for 2020".
The procedure for replenishing the account in the electronic administration system of value-added tax from payer accounts opened in the relevant bodies that provide treasury services for budget funds, for conducting mutual settlements at the expense of revenues specified in paragraphs 13 and 15 of Article 11 of the Law of Ukraine "On the State Budget of Ukraine for 2020", as well as the procedure and terms for transferring funds from the payer's account in the electronic administration system of value-added tax to the special fund of the state budget shall be approved by the Cabinet of Ministers of Ukraine.
{Subsection 2 of Section XX supplemented by paragraph 74 in accordance with Law No. 1005-IX of 11/17/2020 }
74. Temporarily, until January 1, 2023, transactions for the supply of temporary accommodation (accommodation) services provided by hotels and similar temporary accommodation facilities (class 55.10, group 55 of the KVED DK 009:2010 ) are taxed at a rate of 7 percent.
{Subsection 2 of Section XX supplemented by paragraph 74 in accordance with Law No. 962-IX of 04.11.2020 }
75. Temporarily, for the period of implementation of the Agreement between the Government of Ukraine and the Government of the Republic of Poland on the provision of a loan under tied assistance of September 9, 2015, ratified by the Law of Ukraine "On Ratification of the Agreement between the Government of Ukraine and the Government of the Republic of Poland on the Provision of a Loan Under Tied Assistance", transactions for the supply of goods/services in the customs territory of Ukraine carried out directly by contractors registered in the Republic of Poland and their representative offices registered in the customs territory of Ukraine, in accordance with contracts concluded for the implementation of the said Agreement with customers of projects for the development of border road infrastructure and the arrangement of checkpoints on the Ukrainian-Polish border and other projects that will be agreed upon by the Contracting Parties and financed under separate contracts between exporters from Poland and legal entities - residents of Ukraine, shall be taxed at a zero rate of value added tax.
{Subsection 2 of Section XX supplemented by paragraph 75 in accordance with Law No. 1016-IX of 01.12.2020 }
76. Temporarily, until January 1, 2035, transactions for the import into the customs territory of Ukraine under the customs regime of import of new equipment (equipment) and components for it, defined in subparagraph 15 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, imported by a taxpayer - an investor with significant investments exclusively for the implementation of an investment project with significant investments for the execution of a special investment agreement, are exempt from value added tax.
The exemption from value-added tax, provided for in the first paragraph of this paragraph, shall be applied within the period of implementation of the investment project and the total amount of state support not used at the time of customs clearance of goods, as determined in the special investment agreement, taking into account the data of the register of investment projects with significant investments regarding the volume of such support, as well as the date and time of entry of relevant information into such register.
Exemption from value added tax, provided for in the first paragraph of this paragraph, until the supervisory authority receives information on the achievement/exceedance of the total amount of state support or on the termination of the provision of such support in accordance with the register of investment projects with significant investments, is not considered a violation of tax legislation and does not entail the obligation to pay value added tax and/or penalties.
Amounts of value-added tax not paid to the budget in connection with the application of the exemption from value-added tax provided for in the first paragraph of this paragraph, until the date of receipt by the supervisory authority of information on such achievement/exceedance or on the termination of the provision of such support in accordance with the register of investment projects with significant investments, shall be subject to reimbursement by the taxpayer - investor with significant investments in the manner prescribed by law and the relevant special investment agreement, and the provisions of this Code regarding the repayment of tax debt shall not apply to them.
In the event of alienation of equipment (equipment) and its components imported into the customs territory of Ukraine in accordance with the procedure specified in this paragraph, earlier than five years from the date of their import into the customs territory of Ukraine or in the event of their misuse or early termination of a special investment agreement (except for cases where the early termination of a special investment agreement is due to a violation of the state's obligations to provide state support under a special investment agreement or the occurrence of force majeure circumstances (force majeure circumstances), the taxpayer - investor with significant investments is obliged to pay tax liabilities based on the results of the tax period to which such alienation, misuse or early termination of a special investment agreement falls, in the amount of value added tax that should have been paid upon import into the customs territory of Ukraine of such goods, and is also obliged to pay a penalty in accordance with this Code, calculated from the date of import into the customs territory of Ukraine until the date of increase tax liability. In this case, the limitation periods established by Article 102 of this Code shall not apply.
The terms "investor with significant investments" , "investment project with significant investments" , "special investment agreement" are used in the meaning given in the Law of Ukraine "On State Support of Investment Projects with Significant Investments in Ukraine".
The provisions of this paragraph do not apply to goods originating from a country recognized by the occupying state in accordance with the law and/or by the aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of the occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 76 in accordance with Law No. 1293-IX of 02.03.2021 }
77. Temporarily, within 180 days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Collection of Taxes and Duties, Other Mandatory Payments, the Object of Taxation of which is Vehicles", subject to compliance with the provisions stipulated in Clauses 9 - 7 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, the tax base for transactions on the import into the customs territory of Ukraine of vehicles for personal use that were in use and more than five years have passed since the year of manufacture, which are classified under commodity headings 8703, 8704 (with a total weight of up to 3.5 tons) according to the UKT Foreign Economic Activity and as of December 31, 2020 were under the customs regime of temporary import or transit, is the amount of excise tax charged in accordance with Clause 36 of Subsection 5 of this Section.
The period provided for in paragraph one of this paragraph for participants in hostilities specified in paragraphs 19 and 20 of part one of Article 6 of the Law of Ukraine "On the Status of War Veterans, Guarantees of Their Social Protection", provided that there is documentary confirmation of their stay for more than 90 days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Collection of Taxes and Duties, Other Mandatory Payments, the Object of Taxation of which are Vehicles" directly in the territory of the Joint Forces Operation (JFO), is 270 days.
{Subsection 2 of Section XX is supplemented by paragraph 77 in accordance with Law No. 1402-IX of 04/15/2021 - enters into force on 06/15/2021}
78. Temporarily, until January 1, 2031, transactions for the import into the customs territory of Ukraine under the customs regime of import of goods specified in subparagraph 16 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, imported by enterprises that have, create or modernize production facilities for the industrial production of vehicles, are exempt from value added tax.
The exemption from value added tax provided for in this paragraph shall apply if the import of goods into the customs territory of Ukraine is carried out by the enterprises specified in the first paragraph of this paragraph for their own production:
vehicles equipped exclusively with electric motors (one or more), classified under commodity heading 8603 (only self-propelled tram and metro cars), commodity subheading 8701 24, commodity headings 8702-8705 according to the UKT FEA;
{Paragraph three of clause 78, subsection 2, section XX, as amended by Law No. 3553-IX of 16.01.2024 }
vehicles equipped with spark-ignition internal combustion engines running exclusively on compressed natural methane gas, liquefied natural methane gas or biogas, classified in commodity subheading 8701 23, commodity category 8701 29 00, commodity positions 8702-8705 according to the UKT FEA ;
{Paragraph four of clause 78, subsection 2, section XX, as amended by Law No. 3553-IX of 01/16/2024 }
non-self-propelled tram cars and metro cars, classified in commodity subcategory 8605 00 00 00 according to the UKT FEA .
The procedure for the import and intended use of the specified goods is established by the Cabinet of Ministers of Ukraine.
In case of misuse of the specified goods, the taxpayer must increase the tax liability based on the results of the tax period to which such violation applies by the amount of value added tax that should have been paid at the time of importation of such goods into the customs territory of Ukraine, and must also pay a penalty in accordance with this Code.
, the limitation periods established by Article 102 of this Code shall not apply.
In this paragraph, the terms "enterprise that has production facilities for the industrial production of vehicles", "enterprise that modernizes production facilities for the industrial production of vehicles", "enterprise that creates production facilities for the industrial production of vehicles", "industrial production of vehicles" are used in the meanings given in subparagraph 16 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine.
The provisions of this paragraph do not apply to goods originating from a country recognized as an occupying state in accordance with the law and/or an aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of an occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 78 in accordance with Law No. 1660-IX of 15.07.2021 }
79. A non-resident person whose total amount from transactions for the supply of electronic services to individuals, including individual entrepreneurs not registered as value added tax payers, the place of supply of which is located in the customs territory of Ukraine, for the 2021 calendar year collectively exceeds the amount established by paragraph 208 - 1.2 of Article 208 - 1 of this Code, shall, by March 31, 2022 inclusive , submit to the central executive body implementing state tax policy, in electronic form through a special portal solution for non-resident users who provide electronic services by means of electronic identification, an application for registration of a non-resident person as a value added tax payer.
{Subsection 2 of Section XX supplemented by paragraph 79 in accordance with Law No. 1525-IX of 03.06.2021 }
80. Amounts of value added tax paid (accrued) in connection with the purchase of goods/services, indicated in tax invoices/calculations of adjustments to such tax invoices, which are registered in the Unified Register of Tax Invoices and which, before the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine on Ensuring the Balance of Budget Revenues" within 1095 calendar days from the date of their preparation, were not included in the tax credit, shall be included in the tax credit within 365 calendar days from the date of entry into force of the said Law, but no later than 1095 calendar days from the date of preparation of such tax invoices/calculations of adjustments to such tax invoices.
Taxpayers who apply the cash method of tax accounting, the tax amounts indicated in tax invoices/calculations of adjustments to such tax invoices registered in the Unified Register of Tax Invoices, and not included in the tax credit due to the absence of facts of debiting funds from the taxpayer's bank account (withdrawal from the cash register) or providing other types of compensation for the cost of goods/services delivered (or to be delivered) to him, have the right to include such amounts in the tax credit in the reporting tax period in which the debiting of funds from the taxpayer's bank account (withdrawal from the cash register) or providing other types of compensation for the cost of goods/services delivered (or to be delivered) to him took place, but no later than 60 calendar days from the date of such debiting or providing other types of compensation.
In the event of suspension of registration of tax invoices/calculations of adjustments to such tax invoices specified in the first paragraph of this paragraph in the Unified Register of Tax Invoices in accordance with paragraph 201.16 of Article 201 of this Code, the period of 365 calendar days shall be suspended for the period of suspension of registration of such tax invoices/calculations of adjustments to such tax invoices in the Unified Register of Tax Invoices.
{Subsection 2 of Section XX supplemented by paragraph 80 in accordance with Law No. 1914-IX of 11/30/2021 }
81. Temporarily, until December 31, 2024, operations for the provision of air transport services for the domestic transportation of passengers and baggage ( code 51.10.11 and 51.10.12 of the State Classifier of Products and Services DK 016:2010) are subject to value added tax at a rate of 7 percent.
{Subsection 2 of Section XX is supplemented by paragraph 81 in accordance with Law No. 2139-IX of March 15, 2022 - regarding the entry into force and operation of the Law, see paragraph 1 of Section II}
82. Temporarily, for the period of the legal regime of martial law in the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On approval of the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 2102-IX , but no longer than until July 1, 2023, operations for the supply to the customs territory of Ukraine and the import into the customs territory of Ukraine of motor gasoline, heavy distillates, liquefied gas, biodiesel, alternative motor fuel, classified by the UKT codes of foreign economic activity, determined by paragraph 41 of subsection 5 of this section, which establishes excise tax rates for such goods, as well as crude oil or petroleum products obtained from bituminous rocks (minerals), classified by the UKT codes FEA 2709 00 10 00 and 2709 00 90 00 are taxed at a rate of 7 percent.
{Paragraph one of clause 82, subsection 2, section XX as amended by Law No. 2618-IX of September 21, 2022 }
The amount of negative value determined for the relevant reporting (tax) period in accordance with paragraph 200.1 of Article 200 of this Code, the calculation of which includes the amounts of tax liability for transactions taxable at the rate established in paragraph one of this paragraph, shall not be subject to budget reimbursement. Amounts of such negative value shall be included in the tax credit of the next reporting (tax) period.
{Paragraph two of clause 82, subsection 2, section XX, as amended by Law No. 2142-IX of March 24, 2022 }
{Subsection 2 of Section XX supplemented by paragraph 82 in accordance with Law No. 2120-IX of March 15, 2022 }
83. Temporarily, for the reporting periods of 2022, participants in the debt settlement procedure who participate in mutual settlements carried out for the purpose of implementing measures provided for in Article 4 of the Law of Ukraine "On Measures Aimed at Overcoming Crisis Phenomena and Ensuring Financial Stability in the Natural Gas Market", who are value added tax payers in accordance with Section V of this Code, shall not adjust the value added tax previously attributed to the tax credit and/or tax liabilities, and shall not change the composition of tax liabilities and/or tax credit by the amount of mutual settlements carried out.
{Subsection 2 of Section XX is supplemented by paragraph 83 in accordance with the Law No. 2480-IX dated 07/29/2022 }
84. Until December 31, 2022, transactions on the import into the customs territory of Ukraine by the National Joint-Stock Company "Naftogaz of Ukraine" of natural gas classified by the code according to the UKT Foreign Economic Activity Code 2711 21 00 00, imported into the customs territory of Ukraine during 2014-2015 by pipeline transport under the obligation to submit an additional declaration, for which, as of the date of entry into force of the Law of Ukraine "On Amendments to Section XX "Transitional Provisions" of the Tax Code of Ukraine on Ensuring the Stable Functioning of the Natural Gas Market during the Period of Martial Law and Subsequent Restoration", no additional declarations were issued by the customs authorities.
{Subsection 2 of Section XX is supplemented by paragraph 84 pursuant to the Law No. 2480-IX dated 07/29/2022 }
85. To establish that the date of occurrence of tax liabilities for value added tax under long-term agreements (contracts) for the construction of housing (residential real estate objects), which were concluded and for which a permit to perform construction work was obtained before the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Taxation of Transactions with Real Estate Objects to be Built in the Future", is the date of actual transfer by the contractor of the results of work under such agreements (contracts).
{Subsection 2 of Section XX supplemented by paragraph 85 in accordance with Law No. 2600-IX of 20.09.2022 }
86. Temporarily, during the martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , and six months after the month in which martial law is terminated or canceled, transactions for the import of natural gas into the customs territory of Ukraine under the code according to the UKT ZEA 2711 21 00 00 by a natural gas market entity, on which the Cabinet of Ministers of Ukraine has imposed special obligations in accordance with the Law of Ukraine "On the Natural Gas Market", are exempt from taxation with value added tax.
{Subsection 2 of Section XX supplemented by paragraph 86 in accordance with Law No. 2719-IX of 03.11.2022 }
87. Temporarily, for the period of martial law in the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , but no longer than until May 1, 2023, transactions for the import, movement (forwarding) of international postal and express shipments to the customs territory of Ukraine under the customs regime of import of goods specified in paragraphs 9 - 21 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine are exempt from taxation with value added tax .
The provisions of this paragraph do not apply to goods originating from a country recognized as an occupying state in accordance with the law and/or an aggressor state in relation to Ukraine in accordance with the law, and/or imported from the territory of the occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 87 in accordance with Law No. 2836-XI of 13.12.2022 }
87 - 1. Temporarily, for the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , but no later than January 1, 2029, transactions for import into the customs territory of Ukraine (including movement (forwarding) in international postal and express shipments) under the customs regime of import of goods specified in paragraphs 9 - 36 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine are exempt from taxation with value added tax.
{Paragraph one of clause 87 - 1 , subsection 2, section XX, as amended by Law No. 4698-IX of 03.12.2025 }
The provisions of this paragraph do not apply to goods originating from a country recognized as an occupying state in accordance with the law and/or an aggressor state in relation to Ukraine in accordance with the law, and/or imported from the territory of the occupying state (aggressor) and/or from the temporarily occupied territory of Ukraine, designated as such in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 87 - 1 in accordance with Law No. 3853-IX of 16.07.2024 }
88. Temporarily, for the period of martial law in the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , but no longer than until May 1, 2023, the transactions for the import into the customs territory of Ukraine under the customs regime of import of goods specified in paragraphs 9 - 23 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, which are provided free of charge by the Energy Community as assistance in favor of business entities that have licenses for certain types of economic activity in the electricity market (electricity generation, electricity transmission, electricity distribution), and are imported by such entities to the customs territory of Ukraine for the purposes of restoring and repairing the infrastructure of such enterprises in agreement with the central executive body that ensures the formation and implementation of state policy in the fuel and energy complex.
{Subsection 2 of Section XX supplemented by paragraph 88 in accordance with Law No. 2836-XI of 13.12.2022 }
88 - 1. Temporarily, for the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , but no later than until January 1, 2029, transactions for the import into the customs territory of Ukraine under the customs regime of import of goods, the list of which, indicating the codes in accordance with the UKT FEA , is determined by the Cabinet of Ministers of Ukraine, carried out within the framework of agreements, the financing of which is carried out at the expense of the Secretariat of the Energy Community.
{Paragraph one of clause 88 - 1 , subsection 2, section XX, as amended by Law No. 4698-IX of 03.12.2025 }
Confirmation that operations for import into the customs territory of Ukraine under the customs regime of import of goods specified in this paragraph are carried out within the framework of agreements, the financing of which is carried out at the expense of the Secretariat of the Energy Community, is carried out by the central executive body that ensures the formation and implementation of state policy in the fuel and energy complex, in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
The list of goods specified in the first paragraph of this paragraph may not include goods classified in commodity subcategories 8504 21 00 00, 8504 22 10 00, 8504 22 90 00, 8504 23 00 00, 8504 31 21 00, 8504 31 29 00, 8504 31 80 00, 8504 32 00 10, 8504 32 00 90, 8504 33 00 10, 8504 33 00 90, 8504 34 00 00, 8504 50 00 90 according to the Ukrainian Customs Union for Foreign Economic Activities.
{Item 88 - 1 of subsection 2 of section XX is supplemented with a paragraph in accordance with Law No. 4577-IX of 21.08.2025 }
{Subsection 2 of Section XX supplemented by paragraph 88 - 1 in accordance with Law No. 3853-IX of 16.07.2024 }
89. Temporarily, during the martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , and six months after the month in which martial law is terminated or canceled, registration of tax invoices and/or calculations of adjustments to tax invoices in the Unified Register of Tax Invoices is carried out taking into account the following deadlines:
for tax invoices/calculations of adjustments to tax invoices drawn up from the 1st to the 15th calendar day (inclusive) of a calendar month - by the 5th calendar day (inclusive) of the calendar month following the month in which they were drawn up;
for tax invoices/calculations of adjustments to tax invoices drawn up from the 16th to the last calendar day (inclusive) of a calendar month - until the 18th calendar day (inclusive) of the calendar month following the month in which they were drawn up;
for adjustment calculations made by the supplier of goods/services to the tax invoice drawn up for the recipient - the taxpayer, which provide for a reduction in the amount of compensation for the cost of goods/services to their supplier - within 18 calendar days from the date of receipt of such adjustment calculation to the tax invoice by the recipient (buyer).
{Subsection 2 of Section XX supplemented by paragraph 89 in accordance with Law No. 2876-IX of 12.01.2023 }
90. Temporarily, during the martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , and six months after the month in which martial law is terminated or canceled, the fine for violation by value added tax payers of the deadline provided for in paragraph 89 of this subsection for registering a tax invoice and/or calculating an adjustment to such a tax invoice in the Unified Register of Tax Invoices is set at the amount of:
2 percent of the amount of value added tax indicated in such tax invoices/adjustment calculations - in case of violation of the registration deadline by up to 15 calendar days;
5 percent of the amount of value added tax indicated in such tax invoices/adjustment calculations - in case of violation of the registration deadline from 16 to 30 calendar days;
10 percent of the amount of value added tax indicated in such tax invoices/adjustment calculations - in case of violation of the registration deadline from 31 to 60 calendar days;
15 percent of the amount of value added tax indicated in such tax invoices/adjustment calculations - in case of violation of the registration deadline from 61 to 365 calendar days;
25 percent of the amount of value added tax indicated in such tax invoices/adjustment calculations - in case of violation of the registration deadline for 366 or more calendar days.
{Subsection 2 of Section XX supplemented by paragraph 90 in accordance with Law No. 2876-IX of 12.01.2023 }
{Item 91 of Subsection 2 of Section XX was excluded pursuant to Law No. 3706-IX of 09.05.2024 }
92. Temporarily, for the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , but no later than January 1, 2027, transactions for the import into the customs territory of Ukraine under the customs regime of import (including the movement (forwarding) in international postal and express shipments) of goods specified in paragraphs 9 - 24 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine are exempt from taxation with value added tax.
{Paragraph one of clause 92, subsection 2, section XX, as amended by Laws No. 3474-IX of 11/21/2023 , No. 4143-IX of 12/17/2024 , No. 4698-IX of 12/03/2025 }
The provisions of this paragraph do not apply to goods originating from a country recognized as an occupying state in accordance with the law and/or an aggressor state in relation to Ukraine in accordance with the law, and/or imported from the territory of the occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 92 in accordance with Law No. 2906-IX of 06.02.2023 }
93. Temporarily, for the period ending on the last calendar day of the month in which martial law in Ukraine is terminated or abolished, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , transactions for the supply of services related to military software, the international transfer of which is subject to state control, are exempt from VAT, namely:
software development, modification, testing and/or technical support services,
documentation development services (for the purposes of development, modification, testing and technical support of such software), and/or
granting intellectual property rights to software, including under license agreements.
{Subsection 2 of Section XX supplemented by paragraph 93 in accordance with Law No. 3019-IX of 10.04.2023 }
94. Temporarily, during the martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the operation of importing goods into the customs territory of Ukraine belonging to the state represented by the Ministry of Defense of Ukraine, the Armed Forces of Ukraine, as well as other military formations, intelligence agencies, special-purpose state bodies with law enforcement functions established in accordance with the laws of Ukraine, which are entrusted with the functions of ensuring the defense of the state by the Constitution and laws of Ukraine, placed under the customs regime of processing outside the customs territory of Ukraine, and/or products of their processing, which are returned to the customs territory of Ukraine under the customs regime of import after repair, are exempt from taxation with value added tax. and/or maintenance.
{Subsection 2 of Section XX supplemented by paragraph 94 in accordance with Law No. 3019-IX of 10.04.2023 }
95. Temporarily, until the termination or cancellation of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On approval of the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 2102-IX , the import into the customs territory of Ukraine (including by movement (forwarding) in international postal and express shipments) under the customs regime of import (including previously placed in other customs regimes) of components (materials, components, units, equipment and components) of air, ground and water unmanned systems, reels with fiber-optic cable, active means of countering technical reconnaissance, mechanized demining machines, as well as remote control weapon systems are exempted from taxation with value added tax. control and ammunition (used with unmanned systems) (hereinafter referred to as goods), defined in paragraph one of clause 9 - 27 of section XXI "Final and transitional provisions" of the Customs Code of Ukraine, imported by business entities for use in their own production activities for production, repair, modernization:
{Paragraph one of clause 95, subsection 2, section XX, as amended by Laws No. 4474-IX of 04.06.2025 , No. 4709-IX of 04.12.2025 }
air, ground and water unmanned systems classified in commodity groups 84 , 85 , 87 , 90 , 93 and commodity positions 8806 , 8906 according to the UKT FEA;
reel with fiber optic cable:
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 }
for the supply of unmanned systems specified in the second paragraph of this paragraph for production, repair, and modernization;
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 ; with amendments made in accordance with Law No. 4709-IX of 04.12.2025 }
for supply to the Armed Forces of Ukraine, as well as other military formations established in accordance with the laws of Ukraine, law enforcement and intelligence agencies, special-purpose agencies with law enforcement functions, which are entrusted with the functions of ensuring the defense of the state by the Constitution and laws of Ukraine, for use in unmanned systems specified in paragraph two of this paragraph;
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 }
active means of countering technical intelligence, classified under commodity headings 8517, 8525, 8543 according to the Ukrainian Classification of Foreign Economic Activities ;
mechanized demining machines classified under commodity headings 8427, 8430, 8479 according to the UKT FEA ;
remote-controlled weapon systems and ammunition (used with unmanned systems), classified in commodity group 93 according to the UKT FEA.
For the purposes of this paragraph, operations for the import into the customs territory of Ukraine of goods defined as:
paragraph twenty-five, clauses 9 - 27 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, are exempt from taxation with value added tax if such goods are imported into the customs territory of Ukraine under the customs regime of import by payers for use in their own production activities for the production, repair, and modernization of active means of countering technical intelligence;
{Paragraph ten of clause 95, subsection 2, section XX, as amended by Laws No. 4474-IX of 04.06.2025 , No. 4709-IX of 04.12.2025 }
paragraph twenty-six, paragraphs 9 - 27 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, are exempt from value added tax if such goods are imported into the customs territory of Ukraine under the customs regime of import by payers for use in their own production activities for the production of ammunition (which are used with unmanned systems);
{Paragraph eleven of clause 95, subsection 2, section XX, as amended by Law No. 4474-IX of 04.06.2025 }
paragraph twenty-seven, paragraphs 9 - 27 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, are exempt from value added tax if such goods are imported into the customs territory of Ukraine under the customs regime of import by payers for use in their own production activities for production, repair, modernization:
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 ; with amendments made in accordance with Law No. 4709-IX of 04.12.2025 }
air, ground and water unmanned systems classified in commodity groups 84 , 85 , 87 , 90 , 93 and commodity positions 8806 , 8906 according to the UKT FEA;
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 }
reel with fiber optic cable:
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 }
for the supply of unmanned systems specified in the second paragraph of this paragraph for production, repair, and modernization;
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 ; with amendments made in accordance with Law No. 4709-IX of 04.12.2025 }
for supply to the Armed Forces of Ukraine, as well as other military formations established in accordance with the laws of Ukraine, law enforcement and intelligence agencies, special-purpose agencies with law enforcement functions, which are entrusted by the Constitution and laws of Ukraine with the functions of ensuring the defense of the state, for use in unmanned systems specified in paragraph two of this paragraph.
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 }
Exemption from VAT on transactions involving the import into the customs territory of Ukraine of goods specified in paragraph one of clause 9 - 27 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, used for the production, repair, modernization of active means of countering technical intelligence, as well as for the production of ammunition (used with unmanned systems) is granted provided that a sample of such active means of countering technical intelligence and ammunition (used with unmanned systems) has been adopted or has undergone codification in accordance with the procedure determined in accordance with paragraph three of clause 1 of part one of Article 4 of the Law of Ukraine "On Defense Procurement".
{Paragraph seventeen of clause 95, subsection 2, section XX, as amended by Law No. 4709-IX of 04.12.2025 }
In case of misuse of the specified goods, the taxpayer is obliged to pay the amount of value added tax that should have been paid upon importation of such goods into the customs territory of Ukraine, as well as to pay a penalty in accordance with the law.
It is not considered improper use of the goods specified in this paragraph if such goods:
{Item 95 of Subsection 2 of Section XX is supplemented with a new paragraph in accordance with Law No. 4474-IX of 04.06.2025 ; as amended by Law No. 4709-IX of 04.12.2025 }
supplied by manufacturers of air, ground and water unmanned systems classified in commodity groups 84 , 85 , 87 , 90 , 93 and commodity positions 8806 , 8 906 according to the UKT FEA, manufacturers of active means of countering technical intelligence classified in commodity positions 8517 , 8525, 8543 according to the UKT FEA, to the Armed Forces of Ukraine and other military formations formed in accordance with the law, law enforcement and intelligence agencies, special-purpose bodies with law enforcement functions, which are entrusted with the functions of ensuring the defense of the state by the Constitution and laws of Ukraine, for the repair and modernization of air, ground and water unmanned systems, active means of countering technical intelligence previously implemented by such manufacturers. In the case of such supply, the manufacturer of these air, ground and water unmanned systems, active means of countering technical intelligence is obliged to indicate in the report submitted by him to the customs authority in accordance with paragraph ten , clause 9 - 27 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, the list and quantity of such goods supplied by him during the reporting quarter;
{Paragraph of clause 95 of subsection 2 of section XX as amended by Law No. 4709-IX of 04.12.2025 }
recognized in accordance with the procedure established by law as unsuitable for use both separately and as part of a finished product (including due to an irreparable, final defect in production, repair or modernization, subject to confirmation of their write-off and/or removal (destruction) in the manner prescribed by law, or loss during testing, subject to proper documentary confirmation);
{Paragraph of clause 95 of subsection 2 of section XX as amended by Law No. 4709-IX of 04.12.2025 }
were destroyed or irretrievably lost as a result of an accident or force majeure circumstances, provided that the fact of such an accident or force majeure circumstances is confirmed in accordance with the procedure determined in accordance with Part Three of Article 192 of the Customs Code of Ukraine.
{Paragraph of clause 95 of subsection 2 of section XX as amended by Law No. 4709-IX of 04.12.2025 }
If goods imported into the customs territory of Ukraine with exemption from value added tax in accordance with this paragraph were declared unfit for further use, destroyed or irretrievably lost as a result of an accident or force majeure circumstances before the date of entry into force of the Law of Ukraine "On Amendments to Subsection 2 of Section XX "Transitional Provisions" of the Tax Code of Ukraine on the Taxation of Value Added Tax on Operations on the Import of Goods for Security and Defense Needs into the Customs Territory of Ukraine", the enterprise has the right to submit to the customs authority that released such goods into free circulation the original documents or their certified copies confirming the fact of loss (destruction) of such goods.
{Paragraph of clause 95 of subsection 2 of section XX as amended by Law No. 4709-IX of 04.12.2025 }
In accordance with the procedure and under the conditions specified in paragraphs 9 - 27 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine, an enterprise has the right to refuse to use for its intended purpose goods imported into the customs territory of Ukraine with exemption from value added tax in accordance with this paragraph, without charging a penalty.
{Paragraph of clause 95 of subsection 2 of section XX as amended by Law No. 4709-IX of 04.12.2025 }
At the request of the controlling authority specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code, the customs authority at the location of the enterprise, the operations of which on the import of goods into the customs territory of Ukraine are exempt from taxation by value added tax in accordance with this paragraph, shall provide, within 10 working days, information on the volumes of import of such goods and copies of the received reports on the results of their use.
{Paragraph of Clause 95, Subsection 2, Section XX, as amended by Law No. 4474-IX of 04.06.2025 }
The exemption from taxation established by this paragraph does not apply to operations for the import into the customs territory of Ukraine under the customs regime of import of goods originating from a country recognized by the occupying state in accordance with the law and/or recognized by the aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of such an occupying state (aggressor) and/or from the temporarily occupied territory of Ukraine, designated as such in accordance with the law.
{Subsection 2 of Section XX supplemented by paragraph 95 in accordance with Law No. 3123-IX of 05/29/2023 ; as amended in accordance with Law No. 3853-IX of 07/16/2024 ; as amended by Law No. 4143-IX of 12/17/2024 }
96. Temporarily, until January 1, 2024, transactions for the import into the customs territory of Ukraine under the customs regime of import of sea vessels for use exclusively as search and rescue units for the purpose of implementing international treaties of Ukraine in the field of protection of human life at sea, equipment, supplies, spare parts and units of such vessels, equipment, supplies and equipment of search and rescue teams of such vessels, which are intended exclusively for conducting operations to search and rescue people in distress at sea in the maritime search and rescue area of Ukraine, defined by subparagraph 17 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine and the cost of which is paid for from the state budget, are exempted from taxation.
In case of misuse of the specified goods, the taxpayer is obliged to pay the amount of value added tax that should have been paid upon importation of such goods into the customs territory of Ukraine, as well as to pay a penalty in accordance with the law.
The exemption from taxation established by this paragraph does not apply to operations for the import into the customs territory of Ukraine under the customs regime of import of goods originating from a country recognized as an occupying state in accordance with the law and/or recognized as an aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of such an occupying state (aggressor state) and/or from the temporarily occupied territory of Ukraine, designated as such in accordance with the law.
The terms "search and rescue unit", "search", "rescue" and "search and rescue area" are used in the meanings given in the International Convention on Maritime Search and Rescue , 1979. The term "search and rescue team" means trained personnel of a search and rescue unit, provided with equipment, facilities and equipment designed to carry out rapid and effective search and rescue operations for persons in distress at sea.
{Subsection 2 of Section XX supplemented by paragraph 96 in accordance with Law No. 3325-IX of 10.08.2023 }
97. Temporarily, for the period of validity of the export guarantee regime introduced by the Cabinet of Ministers of Ukraine in accordance with Article 19-2 of the Law of Ukraine "On Foreign Economic Activity", taxation with value added tax of operations on exportation outside the customs territory of Ukraine under the customs regime of export of goods to which the export guarantee regime is applied (hereinafter for the purposes of this paragraph - individual types of goods) is carried out taking into account the features determined by this paragraph.
97.1. A value-added tax payer for the purpose of exporting certain types of goods outside the customs territory of Ukraine under the customs regime of export shall be obliged to draw up a separate tax invoice for each such goods and register it in the Unified Register of Tax Invoices before the date of submission of a customs declaration for customs clearance of such goods. Export of the relevant goods outside the customs territory of Ukraine under the customs regime of export after drawing up a tax invoice shall not be considered a separate taxable transaction within the meaning of subparagraph "g" of paragraph 185.1 of Article 185 of this Code.
Registration of a tax invoice drawn up in accordance with the first paragraph of this subparagraph in the Unified Register of Tax Invoices may be suspended in accordance with the procedure and on the grounds determined by the Cabinet of Ministers of Ukraine in accordance with paragraph 201.16 of Article 201 of this Code.
97.2. Operations for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods are taxed at the tax rates determined by paragraph 193.1 of Article 193 of this Code:
a) operations for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods carried out by value added tax payers, in which, based on the results of operations for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods during the previous 12 calendar months (until November 11, 2024 - for the actual available period, starting from November 11, 2023), the amount of unreceived funds for operations for export of certain types of goods, for which the bank (banks) did not complete currency supervision over compliance by the resident taxpayer with the payment deadlines established by the National Bank of Ukraine (after their expiration), does not exceed 20 percent of the total amount of operations for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods, for which the payment deadlines established by the National Bank of Ukraine have expired, are taxed at the rate determined by subparagraph "b" of paragraph 193.1 of Article 193 of this Code. Code. The procedure for calculating the share of unreceived funds for export transactions of certain types of goods and determining the list of taxpayers who meet the requirements of this subparagraph shall be determined by the Cabinet of Ministers of Ukraine;
b) operations for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods carried out by value added tax payers not specified in subparagraph "a" of this subparagraph - shall be taxed at the rates specified in subparagraphs "a" and "d" of paragraph 193.1 of Article 193 of this Code for operations for the supply of such goods in the customs territory of Ukraine. The rate specified in subparagraph "b" of paragraph 193.1 of Article 193 of this Code shall be applied to such operations only after confirmation of the fact of completion of calculations in the manner established by this paragraph (by drawing up and registering the calculation of an adjustment to the tax invoice in the manner and on the grounds specified in subparagraph "c" of subparagraph 97.4 of this paragraph).
The provisions of the second paragraph of subparagraph 97.1 of this paragraph apply, inter alia, to the registration of tax invoices in the Unified Register of Tax Invoices drawn up by value-added tax payers specified in subparagraph "a" of this subparagraph.
In the tax invoice drawn up for the operation of export outside the customs territory of Ukraine under the customs regime of export of certain types of goods:
only one product can be listed under one code according to the UKT FEA ;
The units of measurement of goods are indicated in kilograms.
A tax invoice drawn up in violation of such requirements shall not be accepted for registration in the Unified Register of Tax Invoices.
If 30 calendar days have passed since the date of registration of a tax invoice drawn up for operations on export outside the customs territory of Ukraine under the customs regime of export of certain types of goods in the Unified Register of Tax Invoices and a customs declaration for such goods has not been filed, the registration of such tax invoice in the Unified Register of Tax Invoices shall be canceled.
In the tax invoice, which is drawn up for supply operations on the customs territory of Ukraine of certain types of goods, the units of measurement of goods are indicated in kilograms.
97.3. The tax base for operations on export outside the customs territory of Ukraine under the customs regime of export of certain types of goods is the contractual (contractual) value of such types of goods, but not less than the minimum allowable export prices determined in accordance with Article 19 - 2 of the Law of Ukraine "On Foreign Economic Activity" at the official exchange rate of the currency of Ukraine to foreign currency established by the National Bank of Ukraine, effective at 0 hours on the day of registration of the tax invoice.
The tax base for operations on export outside the customs territory of Ukraine under the customs regime of export of certain types of goods on the basis of a forward contract is the contractual (contractual) value of such certain types of goods specified in such contract, but not less than the minimum allowable export prices determined in accordance with Article 19-2 of the Law of Ukraine "On Foreign Economic Activity" on the date of signing the forward contract at the official exchange rate of the currency of Ukraine to the foreign currency established by the National Bank of Ukraine, effective at 0 o'clock on the day of signing such contract. If the minimum allowable export prices have not been established on the date of signing the forward contract, the tax base is determined according to the rules specified in the first paragraph of this subparagraph.
To determine whether the conditions of a controlled transaction comply with the "arm's length" principle, the price of the transaction for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods, which complies with the "arm's length" principle, is determined in accordance with Article 39 of this Code, but cannot be less than the minimum allowable export prices determined in accordance with Article 19-2 of the Law of Ukraine "On Foreign Economic Activity".
After completing the calculations for the relevant export transaction for certain types of goods, the taxpayer shall prepare an adjustment calculation based on subparagraph "c" of subparagraph 97.4 of this paragraph for the application of the rate determined by subparagraph "b" of subparagraph 193.1 of Article 193 of this Code.
Within three business days following the day of completion of settlements for the relevant export operation of certain types of goods, the bank shall transmit to the central executive body implementing state tax policy a notification of such completion in the form of an electronic document in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" . The procedure for submission and the form of the notification shall be established by the central executive body ensuring the formation and implementation of state financial policy.
For the purposes of this paragraph, the completion of settlements for the relevant export transaction for certain types of goods means the occurrence of at least one of the following circumstances:
1) completion by the bank servicing the resident taxpayer of currency supervision over compliance by such resident with the payment deadlines for the relevant transaction for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods (except for completion of currency supervision in connection with the closure of all resident accounts with the bank and/or change of the servicing bank in the customs declaration);
2) receipt by the bank of information from the electronic register of customs declarations about the operation of export outside the customs territory of Ukraine under the customs regime of export of certain types of goods, if for such an operation a full advance payment has been made to the resident's account in a bank in Ukraine for the entire batch of goods, registered with the relevant customs declaration;
3) receipt of funds in full to a resident's account in a bank in Ukraine under the export customs regime of certain types of goods, the invoice value of which in the relevant customs declaration is less than the amount provided for in Article 20 of the Law of Ukraine "On Prevention and Counteraction to the Legalization (Laundering) of Proceeds of Crime, Financing of Terrorism and Financing of the Proliferation of Weapons of Mass Destruction".
When completing settlements for a relevant export transaction for certain types of goods, customs declarations are taken into account for which the bank received information from the electronic register of customs declarations, which is submitted by the central executive body implementing state customs policy.
The central executive body implementing the state tax policy shall, no later than the next business day after receiving a notification from the bank about the completion of settlements for the relevant export transaction for certain types of goods, send the taxpayer such a notification to his/her electronic account.
97.4. The calculation of the adjustment to the tax invoice drawn up for the operation of export outside the customs territory of Ukraine under the customs regime of export of certain types of goods is drawn up and subject to registration in the Unified Register of Tax Invoices:
a) in connection with a change in quantitative or value indicators - exclusively before the start of the customs declaration, which certifies the fact of export of such goods outside the customs territory of Ukraine in accordance with the requirements of customs legislation;
b) in order to bring the tax invoice figures into line with the customs declaration figures without changing the tax rate - after the completion of exportation outside the customs territory of Ukraine under the customs regime of export of goods and submission of all necessary additional declarations for customs clearance under the relevant customs declaration.
Adjustment of the indicators of a tax invoice drawn up for operations on export outside the customs territory of Ukraine under the customs regime of export of certain types of goods, after registration of the calculation of the adjustment to such a tax invoice in the Unified Register of Tax Invoices specified in the first paragraph of this subparagraph, is not permitted, except for the adjustment of such indicators as the tax rate and the accrued tax amount in accordance with subparagraph "c" of this subparagraph;
c) in connection with bringing the rate applied in accordance with subparagraph 97.2 of this paragraph into line with the rate determined by subparagraph "b" of paragraph 193.1 of Article 193 of this Code - after the completion of calculations for the relevant export transaction for certain types of goods and provided that such calculation of the adjustment provides for the adjustment of only the tax rate and the accrued tax amount.
Registration of the calculation of the adjustment to the tax invoice, drawn up in accordance with subparagraph "a" of this subparagraph, in the Unified Register of Tax Invoices may be suspended in accordance with the procedure and on the grounds determined by the Cabinet of Ministers of Ukraine in accordance with paragraph 201.16 of Article 201 of this Code.
97.5. Operations for export outside the customs territory of Ukraine under the customs regime of export of certain types of goods are reflected in the tax declaration for the reporting (tax) period, which includes the date of registration of the customs declaration, certifying the fact of crossing the customs border of Ukraine, registered in accordance with the requirements of customs legislation.
In the event of a negative value of the amount calculated in accordance with Clause 200.1 of Article 200 of this Code due to the adjustment of tax liabilities on the basis of Subclause "c" of Subclause 97.4 of this Clause, such amount shall be subject to budget reimbursement in accordance with Subclause "b" of Clause 200.4 of Article 200 of this Code.
97.6. The central executive body implementing the state tax policy shall automatically provide the central executive body implementing the state customs policy with information contained in the registered tax invoice drawn up for the operation of export outside the customs territory of Ukraine under the customs regime of export of certain types of goods, in the Unified Register of Tax Invoices (taking into account the calculation of the adjustment to the tax invoice drawn up in accordance with subparagraph "a" of subparagraph 97.4 of this paragraph, if submitted).
{Subsection 2 of Section XX supplemented by paragraph 97 in accordance with Law No. 3706-IX of 09.05.2024 }
98. Temporarily, until Ukraine becomes a full member of the European Union, it shall be considered that the date of occurrence of tax liabilities in the case of supply by a person authorized to carry out procurement in the field of healthcare in accordance with the Fundamentals of Ukrainian Legislation on Healthcare to business entities of state or municipal ownership that have a license to conduct business activities in medical practice, of medicinal products, medical devices and auxiliary means for them, which were purchased by such a person by concluding managed access agreements in accordance with the legislation, is the date of shipment of such medicinal products, medical devices and auxiliary means for them.
The provisions of this paragraph shall apply provided that:
the person specified in the first paragraph of this clause supplies medicines, medical devices and auxiliary means for them, payment for which is made at the expense of the business entities specified in the first paragraph of this clause, in accordance with the contract at the cost of such medicines, medical devices and auxiliary means for them;
during the term of performance of such an agreement, the cost of medicines, medical devices and auxiliary means may include only those general production costs, administrative costs and sales costs incurred (planned to be incurred) by the person specified in the first paragraph of this paragraph;
The amount of travel expenses included in the cost of medicines, medical devices and auxiliary equipment for them cannot exceed:
within Ukraine - the amount of expenses not included in taxable income in accordance with subparagraph 170.9.1 of paragraph 170.9 of Article 170 of this Code;
outside Ukraine - maximum norms regarding the amounts and composition of expenses for business trips abroad of persons sent on business trips by enterprises, institutions and organizations that are fully or partially maintained (financed) at the expense of budget funds established by the Cabinet of Ministers of Ukraine.
{Subsection 2 of Section XX supplemented by paragraph 98 in accordance with Law No. 4505-IX of 18.06.2025 }
99. In the period before Ukraine becomes a full member of the European Union, transactions for the free transfer of engineering infrastructure facilities of land reclamation systems that are in state and municipal ownership to water user organizations in accordance with the Law of Ukraine "On Water User Organizations and Stimulation of Hydrotechnical Land Reclamation" are exempt from value added tax.
In the case of transactions exempt from value added tax in accordance with the first paragraph of this paragraph, the provisions of paragraph 198.5 of Article 198 and Article 199 of this Code shall not apply to such transactions.
{Subsection 2 of Section XX supplemented by paragraph 99 in accordance with Law No. 4536-IX of 16.07.2025 }
99 - 1 . Temporarily, until the termination or cancellation of martial law in Ukraine, introduced by the Decree of the President of Ukraine dated February 24, 2022 No. 64/2022 "On the introduction of martial law in Ukraine", approved by the Law of Ukraine "On approval of the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 2102-IX , transactions for the supply on the customs territory of Ukraine of ground-based unmanned systems classified in commodity groups 84 , 85 , 87 , 90 , 93 according to the UKT of foreign economic activity, weapons, ammunition classified in commodity heading 9301 , commodity subcategories 9306 30 10 00, 9306 30 30 00, 9306 90 10 00 according to with UKT FEA, in the following cases:
{Paragraph one of clause 99 - 1 , subsection 2, section XX, as amended by Law No. 4967-IX of 03.09.2026 }
1) the supply of goods specified in the first paragraph of this paragraph is carried out under state contracts (agreements) for defense procurement;
2) the final recipient of the goods specified in the first paragraph of this paragraph, in accordance with the end-user certificate or in accordance with the terms of the contract, is determined to be law enforcement agencies, the Ministry of Defense of Ukraine, the Armed Forces of Ukraine and other military formations, voluntary formations of territorial communities formed in accordance with the laws of Ukraine, other entities that combat terrorism in accordance with the law and/or participate in implementing measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation against Ukraine, enterprises that are executors (co-executors) of state contracts (agreements) on defense procurement.
{Subsection 2 of Section XX supplemented by paragraph 99 - 1 in accordance with Law No. 4894-IX of 05/28/2026 }
Subsection 3. Features of taxation with value-added tax of operations on the import into the customs territory of Ukraine of equipment, facilities and components not manufactured in Ukraine by taxpayers - shipbuilding enterprises and business entities implementing investment projects approved in accordance with the Law of Ukraine "On Stimulation of Investment Activity in Priority Sectors of the Economy with the Purpose of Creating New Jobs"
{Title of Subsection 3 of Section XX as amended by Law No. 5211-VI of 06.09.2012 }
1. Domestic shipbuilding enterprises (class 35.11, group 35 of the KVED DK 009:2005 ) when importing equipment, equipment and components not manufactured in Ukraine into the customs territory of Ukraine under the customs import regime for use in economic activities, subject to the execution of a customs declaration, may, at their own request, issue to the controlling body (and the controlling body is obliged to accept) a tax bill for the amount of the tax liability for value added tax specified in such customs declaration. The list of equipment, equipment and components imported by domestic shipbuilding enterprises and not manufactured in Ukraine is established by the Cabinet of Ministers of Ukraine.
Business entities implementing investment projects in priority sectors of the economy, approved in accordance with the Law of Ukraine "On Stimulating Investment Activities in Priority Sectors of the Economy with the Purpose of Creating New Jobs" , temporarily, from January 1, 2013 to December 31, 2022 inclusive, when importing equipment (equipment) and component parts to it under the customs regime of import into the customs territory of Ukraine, which are exempt from import duty in the manner specified in subparagraph 10 of paragraph 4 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine , subject to the execution of a customs declaration, may, at their own request, issue to the controlling authority (and the controlling authority is obliged to accept) a tax bill for the amount of the tax liability for value added tax specified in such customs declaration.
{Paragraph 1 of Subsection 3 of Section XX supplemented by the second paragraph in accordance with Law No. 5211-VI of 06.09.2012 }
2. To ensure compliance with the provisions of this subsection, a tax bill shall not be subject to confirmation by a bank through aval.
A tax bill is a tax reporting document and is subject to accounting and storage according to the rules and within the time limits established for primary accounting documents.
The bill holder is the regulatory authority at the place of registration of the bill drawer as a tax payer.
3. A tax bill is issued for the amount of the tax liability for value added tax calculated according to the customs declaration.
The amount of the tax liability for value added tax under one customs declaration cannot be paid partly by a bill of exchange and partly by cash. A bill of exchange is issued for the full amount of the tax liability separately for each customs declaration.
The date of issue of the bill of exchange is the date of submission of the customs declaration for customs clearance.
4. A tax bill is drawn up in triplicate, indicating the tax amount in national currency, exclusively on a bill of exchange purchased from a bank, taking into account the following features:
the first copy of the tax bill - the original bill form purchased by the payer at a banking institution;
the second and third copies of the tax bill - photocopies of the original bill of exchange form (unissued first copy), which have the same bill of exchange form number as the first copy;
All necessary entries in each copy of the tax bill are made separately, cannot be photocopied, and must be identical (except for the serial number of the copy).
The second copy of the bill of exchange shall remain with the controlling body that carries out customs clearance of equipment, facilities and components imported into the customs territory of Ukraine that are not manufactured in Ukraine. The first copy of the bill of exchange shall be sent (transferred) by this controlling body no later than the third day from the date of submission of the bill of exchange to the controlling body in which the person is registered as a payer of value added tax.
The third copy of the bill remains with the taxpayer who issued it.
5. The maturity date of a tax bill for shipbuilding enterprises shall be the date of the occurrence of tax liabilities for the supply of a constructed vessel, for the construction of which equipment, facilities and components were imported, using the promissory note form of value added tax settlements.
{Paragraph one of clause 5, subsection 3, section XX, as amended by Law No. 5211-VI of 06.09.2012 }
The maturity date of a tax bill for business entities implementing investment projects in priority sectors of the economy, approved in accordance with the Law of Ukraine "On Stimulating Investment Activities in Priority Sectors of the Economy for the Purpose of Creating New Jobs" , falls on the 60th calendar day from the date of its issuance to the regulatory authority.
{Clause 5, subsection 3, section XX is supplemented with a new paragraph in accordance with Law No. 5211-VI of 06.09.2012 }
Repayment of the tax bill is carried out exclusively by transferring funds to the State Budget of Ukraine.
Partial repayment of a tax bill is not permitted.
Obligations to repay a tax bill cannot be transferred to other persons, a tax bill is not subject to endorsement; interest or other types of fees for the use of a tax bill are not accrued.
6. In the event of misuse of the goods specified in paragraph 1 of this subsection, the taxpayer shall be obliged to repay the tax bill in the tax period to which their misuse falls, and also to pay a penalty in accordance with this Code.
{Paragraph one of clause 6, subsection 3, section XX, as amended by Law No. 5211-VI of 06.09.2012 }
In case of untimely repayment of a tax bill, the taxpayer who issued the tax bill shall be subject to penalties in the amount of 1 percent of the amount of value added tax specified in the tax bill for each day of delay, including the day of repayment, but not more than 50 percent of the amount of the bill.
7. Subject to compliance with the requirements for the formation of value added tax amounts that may be attributed to a tax credit, the taxpayer has the right to attribute to the tax credit of the reporting (tax) period the amount of value added tax on tax bills repaid in such reporting (tax) period.
8. The value-added tax payer shall attach to the value-added tax tax return a list and copies of tax bills issued during the reporting (tax) period for which the return is submitted.
9. Accounting for tax bills is carried out by regulatory authorities.
{Paragraph one of clause 9, subsection 3, section XX as amended by the Law No. 404-VII dated 04.07.2013 }
Accounting for tax bills by regulatory authorities is carried out in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy.
{Paragraph two of clause 9, subsection 3, section XX as amended by Laws No. 5083-VI of 05.07.2012 , No. 1797-VIII of 21.12.2016 }
Accounting for tax bills by the controlling authorities at the location of the taxpayer to whom the tax bill was issued is carried out in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy.
{ Paragraph two of clause 9, subsection 3, section XX , as amended by Law No. 1797-VIII of 21.12.2016 }
Control over the repayment of tax bills is carried out by regulatory authorities based on data from such bills, tax returns, and documents confirming the payment of tax amounts on the repaid bills.
{Paragraph four of clause 9, subsection 3, section XX as amended by the Law No. 404-VII dated 04.07.2013 ; as amended by Law No. 2888-IX dated 12.01.2023 }
{Subsection 3 of Section XX as amended by Law No. 3609-VI of 07.07.2011 }
Subsection 4. Features of corporate income tax collection↑
1. Section III of this Code shall apply during settlements with the budget starting from income and expenses received and incurred from April 1, 2011, unless otherwise established by this subsection.
{Paragraph two of clause 1, subsection 4, section XX was excluded on the basis of Law No. 1797-VIII of 21.12.2016 }
In the event of the return of advances (other payments) received before the entry into force of Section III of this Code and included in gross income, the amount of such return shall be adjusted to the income of the reporting tax period in which such advances (other payments) were returned in accordance with the procedure provided for by this Code. For advances received in foreign currency, such adjustment shall be made at the official exchange rate of the hryvnia to the foreign currency in effect on the date of such return.
{Paragraph 1 of Subsection 4 of Section XX is supplemented by the third paragraph in accordance with Law No. 3609-VI of 07.07.2011 - applies when determining tax liabilities for income tax, starting from the date of entry into force of Section III of this Code}
In the event of a refund of advances (other payments) issued before the entry into force of Section III of this Code and included in gross expenses, the amount of such refund shall be adjusted to the expenses of the reporting tax period in which such advances (other payments) were refunded in accordance with the procedure provided for by this Code.
{Paragraph 1 of Subsection 4 of Section XX is supplemented by the fourth paragraph in accordance with Law No. 3609-VI of 07.07.2011 - applies when determining tax liabilities for income tax, starting from the date of entry into force of Section III of this Code}
In the event of shipment of goods (performance of work, provision of services) after the entry into force of Section III of this Code against advances received before such date, the expenses that form the cost of goods sold, work performed, services provided, and incurred after the date of entry into force of this Code, provided that they were not included in gross expenses, shall be recognized as expenses on the date of shipment of such goods (performance of work, provision of services).
{Paragraph 1 of Subsection 4 of Section XX is supplemented by paragraph five in accordance with Law No. 3609-VI of 07.07.2011 - applies when determining tax liabilities for income tax, starting from the date of entry into force of Section III of this Code}
2. From the date of entry into force of Section III of this Code, corporate income tax payers shall compile a cumulative total and submit an income tax return for the following reporting tax periods: the second quarter, the second and third quarters, and the second - fourth quarters of 2011.
Payers of corporate income tax who, starting in 2013, submit an annual tax return in accordance with Clause 57.1 of Article 57 of this Code, shall pay in January - February 2013 an advance payment on this tax in the amount of 1/9 of the income tax calculated in the tax reporting for the nine months of 2012, within 20 calendar days following the last calendar day of the reporting (tax) month.
{Paragraph 2 of Subsection 4 of Section XX supplemented by the second paragraph in accordance with Law No. 5083-VI of 05.07.2012 }
Business entities implementing investment projects in priority sectors of the economy approved in accordance with the Law of Ukraine "On Stimulation of Investment Activities in Priority Sectors of the Economy with the Purpose of Creating New Jobs" , and entities of the software industry applying the taxation features provided for in Clause 15 of Subsection 10 of this Section, do not pay advance payments in 2013, and tax liabilities are determined on the basis of the tax declaration based on the results of the first quarter, the first half of the year, three quarters and for 2013, which is submitted to the regulatory authority in accordance with the procedure provided for by this Code.
{Clause 2, subsection 4, section XX supplemented by paragraph three in accordance with Law No. 422-VII of 04.07.2013 }
3. Clause 150.1 of Article 150 of the Code, in the version in force until January 1, 2015, applies:
in 2011, taking into account the following:
If the result of calculating the taxable amount of a resident taxpayer based on the results of the first quarter of 2011 is a negative value, then the amount of such negative value shall be included in the expenses of the second calendar quarter of 2011.
The calculation of the taxable amount based on the results of the second, second and third quarters, and the second - fourth quarters of 2011 is carried out taking into account the negative value received by the taxpayer for the first quarter of 2011, as part of the expenses of such tax periods in a cumulative total until such negative value is fully repaid;
in 2012 - 2015, taking into account the following:
If the result of calculating the taxable object of a resident taxpayer with income for 2011 of UAH 1 million or more as of January 1, 2012 is a negative value (taking into account the negative value of the taxable object as of January 1, 2011), then the amount of this value is subject to inclusion in expenses in 2012 - 2014 and a reduction in the financial result before taxation in 2015:
reporting (tax) periods starting from the first half of the year and subsequent reporting periods of 2012 in the amount of 25 percent of the amount of such negative value. If 25 percent of the amount of the negative value of the taxable object is not repaid during this and subsequent tax periods of 2012, the outstanding amount shall be taken into account when determining tax liabilities in subsequent tax periods;
reporting (tax) periods of 2013 in the amount of 25 percent of the amount of such negative value and the amounts of negative value not repaid for the 2012 tax year. If 25 percent of the amount of the negative value of the taxable object is not repaid during the relevant reporting (tax) periods of 2013, the outstanding amount shall be taken into account when determining tax liabilities in subsequent periods;
reporting (tax) periods of 2014 in the amount of 25 percent of the amount of such negative value and the amounts of negative value not repaid for the 2013 tax year. If 25 percent of the amount of the negative value of the taxable object is not repaid during the relevant reporting (tax) periods of 2014, the outstanding amount shall be taken into account when determining tax liabilities in subsequent periods;
reporting (tax) periods of 2015 in the amount of 25 percent of the amount of such negative value and the amounts of negative value not repaid for the 2014 tax year. If 25 percent of the amount of the negative value of the taxable object is not repaid during the relevant reporting (tax) periods of 2015, the outstanding amount shall be taken into account when determining tax liabilities in subsequent periods until such negative value is fully repaid.
In this case, income tax payers keep separate records of the indicator of the negative value of the object of taxation that arose as of January 1, 2012 and is included in the expenses of subsequent tax periods or reduces the financial result before taxation of subsequent tax periods and amounts not repaid during 2012-2015. Such a negative value is repaid first. In the second place, the negative value of the object of taxation that arose after December 31, 2011 is repaid.
For enterprises with income for 2011 of less than 1 million hryvnia, paragraph 150.1 of Article 150 of the Code in the version in force until January 1, 2015, shall apply, taking into account the following:
If the result of calculating the taxpayer's taxable income as a result of the 2011 tax year is a negative value, the amount of such value shall be included in the expenses of the reporting (tax) period of the first half of 2012 and subsequent reporting periods falling under 2012-2014 or shall reduce the financial result before taxation of the reporting (tax) periods, starting from 2015 until such negative value is fully repaid.
{Clause 3, Subsection 4, Section XX as amended by Law No. 4834-VI of 05.24.2012 ; as amended by Law No. 5083-VI of 07.05.2012 ; as amended by Law No. 71-VIII of 12.28.2014 }
{Paragraph 4 of Subsection 4 of Section XX is deleted by virtue of the Act No. 657-VII dated 24.10.2013 }
4 - 1 . The financial result before taxation of the tax (reporting) period is increased by the amount of income received as payment for goods (works, services) shipped (provided) during the stay on the simplified taxation system, the value of which, in accordance with the rules of national accounting regulations (standards) or international financial reporting standards, was recognized as income during the stay on such a system. At the same time, the financial result before taxation is reduced by the amount of the cost of such goods (works, services), which is taken into account as expenses in accordance with the rules of national accounting regulations (standards) or international financial reporting standards during the payer's stay on the simplified taxation system.
The financial result before taxation of the tax (reporting) period is reduced by the amount of income recognized in accordance with the rules of national accounting regulations (standards) or international financial reporting standards, in the form of the cost of goods (works, services) shipped (provided) in such a period, in part of the amount of their preliminary (advance) payment received during the payer's stay on the simplified taxation system, and taxed by a single tax. At the same time, the financial result before taxation is increased by the amount of the cost of shipped (provided) such goods (works, services), which is taken into account in the tax (reporting) period as part of expenses in accordance with the rules of national accounting regulations (standards) or international financial reporting standards.
In the event that, during the payer's stay on the simplified taxation system, a preliminary (advance) payment is received for part of the cost of goods (works, services) shipped (provided) later in the reporting (tax) period of such payer's stay on the payment of corporate income tax, the financial result before taxation is increased by the amount of part of the cost of such goods (works, services) that is taken into account in such period as part of expenses in accordance with the rules of national accounting regulations (standards) or international financial reporting standards, which relates to the cost of such goods (works, services) as the amount of such preliminary (advance) payment to the total cost of such shipped (provided) goods (works, services).
The provisions of this clause shall apply regardless of whether the payer has made a decision in accordance with subparagraph 134.1.1 of paragraph 134.1 of Article 134 of this Code not to apply adjustments to the financial result before taxation to all differences (except for the negative value of the object of taxation of previous tax (reporting) years and adjustments specified in subparagraph 140.4.8 of paragraph 140.4 and subparagraph 140.5.16 of paragraph 140.5 of Article 140 of this Code), determined in accordance with the provisions of Section III of this Code.
The provisions of this paragraph do not apply to taxpayers who were single tax payers of the fourth group.
{Subsection 4 of Section XX is supplemented by paragraph 4 - 1 in accordance with Law No. 466-IX of 01.16.2020 ; as amended by Law No. 3219-IX of 06.30.2023 }
4 - 2. The provisions of subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code as amended by the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine on Ensuring Balanced Budget Revenues", in terms of establishing for large taxpayers the procedure for taking into account the negative value of the taxable object in reducing the financial result before taxation, shall be applied for the first time when calculating the taxable object based on the results of the tax (reporting) periods of 2022.
In this case, the amount of the negative value of the object of taxation of previous tax (reporting) years, not repaid as of January 1, 2022, shall be taken into account in reducing the financial result before taxation of subsequent tax (reporting) periods in the manner established by subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code, until full repayment.
{Subsection 4 of Section XX supplemented by paragraph 4 - 2 in accordance with Law No. 1914-IX of 11/30/2021 }
5. The provisions of paragraph 159.1 of Article 159 of this Code shall not apply to debts that arose due to a delay in payment for goods, work performed, or services rendered, if measures to collect such debts were taken before the entry into force of Section III of this Code. For the purpose of taxation, such debts shall be reflected in the records of the seller and buyer until they are fully repaid or recognized as uncollectible in the following manner:
the procedure for settling doubtful debts in respect of which collection measures were initiated before the entry into force of Section III of this Code.
The taxpayer - seller is obliged to increase the income of the relevant tax period by the amount of debt (its part) previously attributed by him to expenses or reimbursed at the expense of the insurance reserve and if any of the following events occur during such tax period:
a) the court does not satisfy the seller's claim (application) or satisfies it in part or does not accept the claim (application) for proceedings (consideration) or satisfies the buyer's claim (application) to declare the requirements for repayment of this debt or part thereof invalid;
b) the parties to the contract reach an agreement on extending the terms of debt repayment or writing off the entire amount of debt or part of it (except for cases of concluding an amicable agreement within the framework of procedures for restoring the debtor's solvency or declaring him bankrupt, as determined by law);
c) the seller who has not received a response to the claim within the time limits specified by law, or has received a response from the buyer recognizing the submitted claim, but does not receive payment (other types of compensation for debt repayment) within the time limits specified in such claim and at the same time does not apply to the court (economic court) within the next 90 days with an application for debt collection or for the initiation of a case on his bankruptcy or for the collection of property pledged by him.
The amount of additional tax liability calculated as a result of such an increase shall be subject to a penalty in the amounts determined by law for untimely repayment of a tax liability. The said penalty shall be calculated for the period from the first day of the tax period following the period during which the increase in expenses occurred to the last day of the tax period to which the increase in income applies, and shall be paid regardless of the value of the taxpayer's tax liability for the relevant reporting period. The penalty shall not be charged on the debt (part thereof) written off or deferred as a result of the conclusion of an amicable agreement in accordance with the bankruptcy legislation starting from the date of conclusion of such amicable agreement.
If in the future (taking into account the statute of limitations) such a seller goes to court, he has the right to increase the costs by the amount of the disputed debt;
if the taxpayer appeals the court decision in accordance with the procedure established by law, the increase in income provided for in this paragraph shall not occur until the final decision is made by the relevant court;
The taxpayer - the buyer is obliged to increase income by the amount of outstanding debt (its part), recognized in the pre-trial settlement of disputes or by the court or by an executive inscription of a notary, in the tax period to which the first of the following events occurs:
a) or the 90th calendar day from the date of the deadline for repayment of such debt (part thereof) provided for by the contract or recognized by the claim;
b) or the 30th calendar day from the date of the court's decision to recognize (collect) such debt (part thereof) or the execution of an executive inscription by a notary.
The terms specified in paragraph "a" of this clause also apply to cases where the buyer has not responded to the claim sent by the seller within the terms specified by law.
The terms specified in paragraph "b" of this paragraph shall apply regardless of whether the state enforcement officer or a person equated to him according to the law has initiated measures to enforce debt collection or not.
The increase in the buyer's income specified in this subparagraph shall not apply to the debt (part thereof) that is repaid by such buyer before the deadlines specified in paragraphs "a" or "b" of this subparagraph.
If in subsequent tax periods the buyer repays the amount of the recognized debt or part thereof (independently or through the compulsory collection procedure), such buyer increases expenses by the amount of such debt (part thereof) due to the consequences of the tax period to which such repayment falls.
Debt previously included in expenses or reimbursed at the expense of an insurance reserve, which is recognized as uncollectible due to the insufficiency of the assets of the buyer, recognized as bankrupt in accordance with the established procedure or as a result of its write-off in accordance with the terms of a settlement agreement concluded in accordance with bankruptcy legislation, does not change the tax obligations of both the buyer and the seller in connection with such recognition.
6. To determine the list of fixed assets, other non-current and intangible assets by groups in accordance with Clause 145.1 of Article 145 of this Code for the purpose of calculating depreciation from the date of entry into force of Section III of this Code, the inventory data carried out as of April 1, 2011 shall be used.
The depreciable cost for each item of fixed assets, other non-current and intangible assets is determined as the original (revalued) cost, taking into account capitalized costs for modernization, modification, completion, additional equipment, reconstruction, etc., as well as the amount of accumulated depreciation according to accounting data as of the date of entry into force of Section III of this Code.
The provisions of this subparagraph also apply to taxpayers in the event of their transition from a simplified taxation system to a general one.
The revalued value of fixed assets does not include the amount of revaluation of fixed assets carried out after January 1, 2010.
If the total value of all groups of fixed assets according to accounting data is less than the total value of all groups of fixed assets according to tax accounting data as of the date of entry into force of Section III of this Code, then the temporary tax difference arising as a result of such comparison shall be depreciated as a separate object using the straight-line method over three years.
The useful life of fixed assets, other non-current and intangible assets for the purpose of calculating depreciation from the date of entry into force of Section III of this Code is determined by the taxpayer independently, taking into account the date of their commissioning, but not less than the minimum permissible useful life specified in Clause 145.1 of Article 145 of this Code.
The original cost of fixed assets shall not be increased by the cost of acquisition or improvement after the date of entry into force of Section III of this Code in respect of expenses allocated to increase the book value of objects prior to such date.
7. Income is not determined for goods (results of work, services) shipped (provided) after the date of entry into force of Section III of this Code in respect of the cost of such goods (results of work, services) paid in the form of advances (prepayments) before such date, including during the period of being on the simplified taxation system.
Expenses are not determined for goods (results of work, services) received (provided) after the date of entry into force of Section III of this Code, in the part of the cost of such goods (work, services) paid in the form of advances (prepayments) before such date, if such advances were taken into account by the taxpayer as part of gross expenses on the date of their payment, as well as during the period of stay on the simplified taxation system.
For income tax payers who have switched from the simplified taxation system to the general one, simultaneously with the recognition of income from the sale of goods (performance of work, provision of services) under the general taxation system, the cost of such goods, work, and services incurred during the period of such payer's stay on the simplified taxation system is included in the expenses, in proportion to the amount of recognized income.
Commission income (expenses) and other payments related to the creation or acquisition of loans, deposits, which were included in the object of taxation in the reporting tax periods before the entry into force of Section III of this Code, are not taken into account when determining income and expenses in accordance with this Code.
{Item 8 of Subsection 4 of Section XX was excluded pursuant to Law No. 1797-VIII of 21.12.2016 }
9. In January - December 2015, payers are required to pay monthly advance payments for corporate income tax in accordance with Clause 57.1 of Article 57 of this Code in the version in effect until January 1, 2015. Starting from January 1, 2016, monthly advance payments for corporate income tax are not paid.
{Clause 9, Subsection 4, Section XX as amended by Laws No. 71-VIII of 12/28/2014 , No. 909-VIII of 12/24/2015 }
10. Set the corporate income tax rate:
from April 1, 2011 to December 31, 2011 inclusive - 23 percent;
from January 1, 2012 to December 31, 2012 inclusive - 21 percent;
from January 1, 2013 to December 31, 2013 inclusive - 19 percent, and for entities in the software industry that apply the taxation features provided for in paragraph 15 of subsection 10 of this section - 5 percent;
{Paragraph four of clause 10, subsection 4, section XX, as amended by Law No. 5091-VI of 05.07.2012 }
from January 1, 2014 to December 31, 2014 inclusive - 18 percent, and for entities in the software industry that apply the taxation features provided for in paragraph 15 of subsection 10 of this section - 5 percent;
{Item 10 of Subsection 4 of Section XX is supplemented with a new paragraph in accordance with Law No. 713-VII of 19.12.2013 ; as amended in accordance with Law No. 1166-VII of 27.03.2014 ; as amended by Law No. 71-VIII of 28.12.2014 }
{Paragraph six of clause 10, subsection 4, section XX was excluded on the basis of Law No. 1166-VII of March 27, 2014 }
{Paragraph seven of clause 10, subsection 4, section XX was excluded on the basis of Law No. 1166-VII of March 27, 2014 }
{Paragraph eight of clause 10, subsection 4, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Paragraph nine of clause 10, subsection 4, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Paragraph ten of clause 10, subsection 4, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Paragraph eleven of clause 10, subsection 4 of section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
11. When calculating depreciation of fixed assets and intangible assets in accordance with Clause 138.3 of Article 138 of this Code, the book value of fixed assets and intangible assets as of January 1, 2015 shall be equal to the book value of such assets determined as of December 31, 2014 in accordance with Articles 144 - 146 and 148 of Section III of this Code in the version in force until January 1, 2015.
{Clause 11, Subsection 4, Section XX as amended by Law No. 71-VIII of 12/28/2014 }
12. The provisions of paragraph two of paragraph 137.21 of Article 137 of this Code shall apply until January 1, 2014.
{Clause 12, Subsection 4, Section XX as amended by Law No. 4834-VI of 05/24/2012 }
13. Temporarily until January 1, 2014, the date of increase in income of housing and communal enterprises from the provision of housing and communal services is the date of receipt of funds from the consumer to the bank account or to the cash register of the taxpayer, except for cases where such receipt occurs at the expense of repayment of debt for housing and communal services provided before the date of entry into force of Section III of this Code.
At the same time, housing and communal services enterprises shall recognize as part of the cost of housing and communal services the costs of purchasing goods, works, and services in the amount of funds actually paid for them, except in cases where such payment is made to repay debts for such works, services purchased before the date of entry into force of Section III of this Code.
The carrying amount of goods (except those subject to depreciation and securities), raw materials, materials, component parts, semi-finished products, low-value items (hereinafter referred to as inventories) purchased before the date of entry into force of Section III of this Code and paid for after this date shall be recognized as expenses in the amount of the actual funds paid for them.
This paragraph does not apply to taxpayers - licensees for the supply of electricity and/or heat.
{Clause 13, Subsection 4, Section XX as amended by Law No. 3609-VI of 07.07.2011 - applies when determining tax liabilities for income tax, starting from the date of entry into force of Section III of this Code}
14. In 2011, the standard for fixed assets, specified in subparagraph 14.1.138 of paragraph 14.1 of Article 14 of this Code, is set at 1,000 hryvnias.
{Item 15 of Subsection 4 of Section XX was excluded pursuant to Law No. 71-VIII of 28.12.2014 }
{Item 15 of Subsection 4 of Section XX was excluded pursuant to Law No. 466-IX of 16.01.2020 }
{Item 16 of Subsection 4 of Section XX was excluded pursuant to Law No. 1797-VIII of 21.12.2016 }
16. Temporarily, until January 1, 2020, the profit of enterprises is exempt from taxation in the amount of the income of enterprises received by them from economic activities using coalbed gas (methane) and/or coalbed gas (methane) derivative raw materials, including gas-air mixtures containing gas (methane) that do not meet the requirements for the quality of natural gas intended for transportation, industrial and municipal consumption, carried out in accordance with the Law of Ukraine "On Coalbed Gas (methane)".
For the purpose of applying the first paragraph of this paragraph, the financial result before taxation of enterprises that use coal gas (methane) and/or coal gas (methane) derivative raw materials, including gas-air mixture containing gas (methane), which does not meet the requirements for the quality of natural gas intended for transportation, industrial and municipal consumption, shall be reduced by the amount of income received from operations with coal gas (methane) (sale, processing, combustion) and/or coal gas (methane) derivative raw materials, including gas-air mixture containing gas (methane), which does not meet the requirements for the quality of natural gas intended for transportation, industrial and municipal consumption.
The amounts of funds released in connection with the provision of a tax benefit are directed by the taxpayer to re-equip the material and technical base, the introduction of new technologies related to the extraction, degassing and use of coal gas (methane) and/or coal gas (methane) derivatives, including gas-air mixtures containing gas (methane), until the end of the next tax year.
In the absence of a targeted use of funds exempt from taxation within the period provided for in the third paragraph of this clause, the taxpayer is obliged to increase the financial result before taxation by the amount of income received from the sale of gas (methane) from coal deposits, by which the financial result before taxation was reduced in accordance with the second paragraph of this clause, based on the results of the tax year following the tax period in which the benefit was applied.
{Paragraph 16 is included in subsection 4 of section XX in accordance with Law No. 2245-VIII of 07.12.2017 }
17. For the purpose of taxation, the seller's and buyer's accounting records shall reflect debts that arose due to a delay in payment for goods, work performed, or services rendered, if measures to collect such debts were initiated in accordance with Clause 159.1 of Article 159 of Section III of this Code in the version in force before January 1, 2015, until such debts are fully repaid or recognized as uncollectible in the following manner:
1.1. The taxpayer - the seller, if the court does not satisfy the seller's claim (application) or partially satisfies it or does not accept the claim (application) for proceedings (consideration) or satisfies the buyer's claim (application) to declare invalid the requirements for repayment of this debt or part of it (except for the court's termination of the proceedings in the case in whole or in part, in connection with the buyer's repayment of the debt or part of it after the seller's filing of the claim (application)), is obliged to:
a) increase the financial result before taxation of the relevant tax period by the amount of debt (its part) previously attributed by him to a reduction in income in accordance with subparagraph 159.1.1 of paragraph 159.1 of Article 159 of Section III of this Code in the version in force until January 1, 2015;
b) reduce the financial result before taxation of the relevant tax period by the cost price (its part, determined in proportion to the amount of debt included in income in accordance with this clause) of goods, works, services for which such debt arose, previously attributed by him to the reduction of expenses in accordance with clause 159.1 of Article 159 of Section III of this Code in the version in force until January 1, 2015.
The amount of the additional tax liability calculated as a result of such adjustment of the financial result before taxation shall be subject to a penalty determined at the rate of 120 percent of the annual discount rate of the National Bank of Ukraine, which was in effect on the date of the occurrence of the additional tax liability. The said penalty shall be calculated for the period from the first day of the tax period following the period during which the decrease in income and expenses occurred in accordance with subparagraph 159.1.1 of paragraph 159.1 of Article 159 of Section III of this Code in the version in effect until January 1, 2015, to the last day of the tax period to which the adjustment of the financial result before taxation falls, and shall be paid regardless of the value of the taxpayer's tax liability for the relevant reporting period. The penalty shall not be charged on the debt (its part) written off or deferred as a result of the conclusion of an amicable agreement in accordance with the legislation on bankruptcy, starting from the date of the conclusion of such amicable agreement.
The taxpayer - the buyer is obliged to increase the financial result before taxation after January 1, 2015 by the value of the debt recognized by the court or by the notary's executive inscription, in the tax period on which the day of entry into force of the court decision on the recognition (collection) of such debt (part thereof) or the execution of the executive inscription by the notary falls.
1.2. If in subsequent tax periods after January 1, 2015, the buyer repays the amount of the recognized debt or part thereof (independently or through the compulsory collection procedure) and allocated to the reduction of expenses in accordance with subparagraph 159.1.2 of paragraph 159.1 of Article 159 of Section III of this Code in the version in force before January 1, 2015, such buyer reduces the financial result before taxation by the amount of such debt (part thereof) due to the consequences of the tax period to which such repayment falls.
At the same time, the seller, who reduced the amount of income for the reporting period by the cost of shipped goods, performed work, and provided services, in accordance with subparagraph 159.1.1 of paragraph 159.1 of Article 159 of Section III of this Code in the version in force until January 1, 2015, increases the financial result before taxation by the amount of debt (its part) for such goods, works, and services repaid by the buyer, and reduces the financial result before taxation by the cost price (its part, determined in proportion to the amount of repaid debt) of these goods, works, and services due to the consequences of the tax period to which such repayment falls.
1.3. Debt previously attributed to income reduction in accordance with subparagraph 159.1.1 of paragraph 159.1 of Article 159 of Section III of this Code in the version in force until January 1, 2015, or reimbursed at the expense of the insurance reserve in accordance with subparagraph 159.3 of Article 159 of Section III of this Code in the version in force until January 1, 2015, which is recognized as hopeless due to the insufficiency of the assets of the buyer, recognized as bankrupt in accordance with the established procedure, or as a result of its write-off in accordance with the terms of a settlement agreement concluded in accordance with the bankruptcy legislation, does not adjust the financial result before taxation of both the buyer and the seller in connection with such recognition.
{Clause 17, Subsection 4, Section XX, as amended by Laws No. 5412-VI of 02.10.2012 , No. 1621-VII of 31.07.2014 ; as amended by Law No. 71-VIII of 28.12.2014 }
18. For transactions for which income for the purposes of income tax was determined before January 1, 2015 by the date of receipt of funds to the bank account or cash register of the taxpayer, and as of January 1, 2015, the taxpayer had receivables for such transactions, when calculating the object of taxation, the amount of funds received by the bank account or cash register of the taxpayer after January 1, 2015 increases the financial result before taxation.
For transactions for which expenses for income tax purposes were determined before January 1, 2015 by the date of transfer of funds to the bank account or cash desk of the taxpayer's counterparty, and as of January 1, the taxpayer had payables for such transactions, when calculating the object of taxation, the amount of funds that was transferred to the bank account or cash desk of the taxpayer's counterparty after January 1, 2015 reduces the financial result before taxation.
{Clause 18, Subsection 4, Section XX as amended by Law No. 71-VIII of 12/28/2014 }
19. The amount of depreciation accrued in accounting for non-current assets that remained uncommissioned as of January 1, 2015, the value of which in accounting is increased by the amount of expenses taken into account when determining the object of taxation for income tax in accordance with subparagraph "z" of subparagraph 138.8.5 of paragraph 138.8 of Article 138 of Section III of this Code in the version in force before January 1, 2015, increases the financial result before taxation after January 1, 2015.
The amount of recognized impairment losses on those non-current assets that remained uncommissioned as of January 1, 2015, the cost of which in accounting is increased by the amount of expenses taken into account when determining the object of taxation for income tax in accordance with subparagraph "z" of subparagraph 138.8.5 of paragraph 138.8 of Article 138 of Section III of this Code in the version in force before January 1, 2015, increases the financial result before taxation after January 1, 2015.
The amount of expenses for exploration/further exploration and development of oil and gas fields, which are recognized in accounting as expenses of the reporting period due to the technical impossibility and/or economic inexpediency of further extraction of minerals, and were taken into account when determining the object of taxation for income tax in accordance with subparagraph "z" of subparagraph 138.8.5 of paragraph 138.8 of Article 138 of Section III of this Code in the version in force before January 1, 2015, increases the financial result before taxation after January 1, 2015.
{Clause 19, Subsection 4, Section XX as amended by Law No. 71-VIII of 12/28/2014 }
20. Expenses for interest payments that met the requirements of Clause 141.1 of Article 141 of Section III of this Code in the version in force until January 1, 2015, but were not included in production (circulation) costs in accordance with the provisions of Clause 141.2 of Article 141 of Section III of this Code in the version in force until January 1, 2015, shall be taken into account when determining the financial result before taxation of future reporting tax periods from January 1, 2015, taking into account the limitation provided for in Clause 140.3 of Article 140 of Section III of this Code.
{Clause 20, Subsection 4, Section XX , as amended by Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 71-VIII of 28.12.2014 }
21. As of January 1, 2015, the bank is obliged to recalculate the reserve due to the depreciation (reduction in usefulness) of assets.
The reserve formed by the bank in connection with the impairment of assets in accordance with the requirements of international financial reporting standards as of the end of 2014, in an amount not exceeding a limit of 30 percent of the value calculated as the aggregate carrying amount of assets, the depreciation of which is recognized by forming a reserve, increased by the amount of the reserve for such assets, according to the financial statements for 2014, is considered a reserve as of January 1, 2015, recognized for taxation. The amount of the excess of the reserve over such a limit does not change the object of taxation of the current or previous tax (reporting) periods, including does not increase or decrease the financial result before taxation, and is considered an excess of the reserve that arose in previous reporting (tax) periods.
The positive (negative) difference between the reserve calculated in accordance with Section III of this Code at the end of 2014 and the reserve as of January 1, 2015, recognized for taxation in accordance with this paragraph, increases (decreases) the financial result before taxation in equal shares over three years.
The calculation of differences in accordance with subparagraph 139.3.5 of paragraph 139.3 of Article 139, Section III of this Code shall not take into account the amounts of actual payment by the bank of financial guarantees provided at the expense of the reserve included in expenses in accordance with this Code until January 1, 2015.
{Clause 21, Subsection 4, Section XX as amended by Laws No. 4453-VI of 02/23/2012 , No. 71-VIII of 12/28/2014 }
22. The provision of paragraph 57.1 of Article 57 as amended by the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Legislative Acts of Ukraine on Tax Reform", regarding the deadline for submitting a corporate income tax return, shall apply starting from the submission of a corporate income tax return for the reporting year in which the wording of Section III of the Code as amended by the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Legislative Acts of Ukraine on Tax Reform" enters into force.
{Subsection 4 of Section XX supplemented by paragraph 22 in accordance with Law No. 3292-VI of 21.04.2011 ; as amended in accordance with Law No. 3675-VI of 08.07.2011 ; as amended by Law No. 71-VIII of 28.12.2014 }
23. The provisions of Articles 135 , 159 , 192 and Clause 5, Subsection 4, Section XX of the Tax Code of Ukraine do not apply to debt to which the write-off mechanism is applied under the conditions specified by the Law of Ukraine "On Some Issues of Debt for Consumed Natural Gas and Electricity" .
{Subsection 4 of Section XX is supplemented by a paragraph in accordance with Law No. 3320-VI of 12.05.2011 - the amendment is valid until June 30, 2012; with amendments made in accordance with Law No. 3609-VI of 07.07.2011 - is applied when determining tax liabilities for income tax, starting from the date of entry into force of Section III of this Code}
24. Expenses include expenses for paying vacations to employees and other payments related to labor remuneration, which were reimbursed after January 1, 2015 at the expense of reserves and provisions formed before January 1, 2015 in accordance with national accounting regulations (standards) or international financial reporting standards, if such expenses were not taken into account when determining the object of taxation before January 1, 2015.
{Subsection 4 of Section XX supplemented by paragraph 24 in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 71-VIII of 28.12.2014 }
25. Expenses for interest payments that met the requirements of subparagraph 5.5.1 of paragraph 5.5 of the Law of Ukraine "On Taxation of Enterprise Profits" , but were not included in the composition of production (circulation) expenses in accordance with the provisions of subparagraph 5.5.2 of this paragraph before the date of entry into force of Section III of this Code, shall be subject to transfer to the results of future tax periods, taking into account the restrictions provided for in Article 141 of this Code.
The amount of the excess of the advance payment on corporate income tax previously paid by the payer before the date of entry into force of Section III of this Code in connection with the accrual of dividends in accordance with subparagraph 7.8.2 of paragraph 7.8 of the Law of Ukraine "On Corporate Income Taxation" over the amount of tax liabilities on this tax of such payer, which arose as of the date of entry into force of Section III of this Code, shall be taken into account in future tax periods in accordance with paragraph 153.3 of Article 153 of this Code.
{Subsection 4 of Section XX is supplemented by paragraph 25 in accordance with Law No. 3609-VI of 07.07.2011 - applies when determining tax liabilities for income tax, starting from the date of entry into force of Section III of this Code}
26. The book value of goods (except those subject to depreciation and securities), raw materials, materials, component parts, semi-finished products, low-value items (hereinafter referred to as inventories) in warehouses, in work-in-progress and finished product residues as of the end of the reporting tax period preceding the date of entry into force of Section III of this Code shall be recognized as expenses in the manner provided for in Section III of this Code.
{Subsection 4 of Section XX is supplemented by paragraph 26 in accordance with Law No. 3609-VI of 07.07.2011 - applies when determining tax liabilities for income tax, starting from the date of entry into force of Section III of this Code}
{ Clause 27 of Subsection 4 of Section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
28. The provisions of Articles 135 , 159 , 192 and Clause 5, Subsection 4, Section XX of this Code do not apply to debt to which the write-off mechanism is applied under the conditions specified by the Law of Ukraine "On Some Issues of Debt of Enterprises of the Defense Industrial Complex - Participants of the State Concern "Ukroboronprom" and Ensuring Their Stable Development" .
{Subsection 4 of Section XX supplemented by paragraph 28 in accordance with the Law No. 5414-VI of 02.10.2012 }
{Item 29 of Subsection 4 of Section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
30. Transactions on the assignment of claims under credit agreements secured by a mortgage in favor of a financial institution engaged in the activity of providing financial loans at the expense of borrowed funds, with a mandatory obligation to reassign them, shall be recorded for tax purposes as receiving a financial loan in the tax accounting of the taxpayer-previous creditor and as granting a financial loan in the tax accounting of the taxpayer-new creditor, in accordance with subparagraphs 153.4.1 and 153.4.2 of paragraph 153.4 of Article 153 of this Code on the basis of accounting data, if, in accordance with the accounting provisions (standards), the assignment of claims under credit agreements secured by a mortgage does not lead to the termination of the recognition of such claims in the accounting of the taxpayer-previous creditor and their recognition in the accounting of the taxpayer-new creditor.
If the condition of such a reverse assignment is not met, the specified transaction shall be taxed in the general manner on the basis of paragraph 153.5 of Article 153 of this Code.
For the purposes of this paragraph, a financial institution shall mean a financial institution in which more than 50 percent of the corporate rights are owned by state-owned banks.
{Subsection 4 of Section XX supplemented by paragraph 30 in accordance with Law No. 5519-VI of 06.12.2012 }
31. The negative financial result on transactions with securities, derivatives, corporate rights issued in a form other than securities, formed as of January 1, 2013, shall not be taken into account when determining the financial result on transactions with securities, derivatives, corporate rights issued in a form other than securities in subsequent reporting tax periods.
When determining profits/losses in the manner specified in paragraphs 153.8 and 153.9 of Article 153 of this Code, expenses incurred (accrued) by taxpayers upon acquisition of securities, derivatives, corporate rights issued in a form other than securities before January 1, 2013, shall be taken into account upon their subsequent alienation in full on the basis of primary documents confirming the expenditure.
{Paragraph two of clause 31, subsection 4, section XX as amended by Law No. 657-VII of 10/24/2013 }
In this case, the allocation of the difference between the expenses specified in the second paragraph of this paragraph and income (profits/losses) from transactions on the subsequent alienation of securities to profits/losses received from transactions with securities that are or are not traded on the stock exchange is carried out depending on whether the specified securities were recognized as being traded on the stock exchange at the time of their subsequent alienation, in accordance with subparagraph 153.8.2 of paragraph 153.8 of Article 153 of this Code.
{Subsection 4 of Section XX supplemented by paragraph 31 in accordance with Law No. 5519-VI of 06.12.2012 }
32. The negative financial result on securities transactions formed as of January 1, 2014, is not taken into account when determining the financial result on securities transactions based on the results of the reporting (tax) periods of 2014.
{Subsection 4 of Section XX supplemented by paragraph 32 in accordance with Law No. 713-VII of 19.12.2013 }
33. Temporarily, for the period of the anti-terrorist operation, other expenses for ordinary activities without restrictions, provided for in subparagraph "a" of subparagraph 138.10.6 of paragraph 138.10 of Article 138 of this Code, in the version in force until January 1, 2015, shall include the amounts of funds or the cost of special personal protective equipment (helmets, bulletproof vests manufactured in accordance with military standards), technical means of surveillance, medicines and medical products, personal hygiene products, food products, items of material support, as well as other goods, work performed, services provided according to the list determined by the Cabinet of Ministers of Ukraine, which are voluntarily transferred (transferred) to the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their formations, military units, subdivisions, institutions or organizations formed in accordance with the laws of Ukraine, maintained at the expense of the state budget, for the needs of ensuring the conduct of an anti-terrorist operation.
Temporarily, for the period of the anti-terrorist operation, the adjustments established by subparagraph 140.5.9 of paragraph 140.5 of Article 140 of this Code shall not be made, starting from January 1, 2015, with respect to the amounts of funds or the cost of special personal protective equipment (helmets, bulletproof vests manufactured in accordance with military standards), technical means of surveillance, medicines and medical products, personal hygiene products, food products, items of material support, as well as other goods, work performed, services rendered according to the list determined by the Cabinet of Ministers of Ukraine, which are voluntarily transferred (transferred) to the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their formations, military units formed in accordance with the laws of Ukraine, units, institutions or organizations maintained at the expense of the state budget for the needs of ensuring the conduct of an anti-terrorist operation.
{Paragraph 33 of Subsection 4 of Section XX supplemented by the second paragraph in accordance with Law No. 652-VIII of 17.07.2015 }
{Subsection 4 of Section XX supplemented by paragraph 33 in accordance with Law No. 1668-VII of 02.09.2014 ; as amended in accordance with Law No. 652-VIII of 17.07.2015 }
34. To establish that until the Cabinet of Ministers of Ukraine approves the Procedure for Maintaining the Register of Non-Profit Institutions and Organizations, Including Non-Profit Enterprises, Institutions and Organizations in the Register and Excluding them from the Register (hereinafter referred to as the new Register of Non-Profit Institutions and Organizations), the Regulations on the Register of Non-Profit Institutions and Organizations , approved by Order of the Ministry of Finance of Ukraine No. 37 of January 24, 2013, shall apply.
Non-profit enterprises, institutions and organizations included in the Register of Non-profit Institutions and Organizations on the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Taxation of Non-profit Organizations" are not subject to exclusion from this Register until July 1, 2017.
{Paragraph two of clause 34, subsection 4, section XX, as amended by Law No. 1797-VIII of 21.12.2016 }
Non-profit enterprises, institutions and organizations included in the Register of Non-profit Institutions and Organizations on the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Taxation of Non-profit Organizations", which meet the requirements of paragraph 133.4 of Article 133 of this Code, and for religious organizations - the requirements of paragraph two of subparagraph 133.4.1 of paragraph 133.4 of Article 133 of this Code, shall be included by the supervisory authority in the new Register of Non-profit Institutions and Organizations. At the request of the non-profit organization, it may submit copies of its constituent documents to the supervisory authority.
{Paragraph three of clause 34, subsection 4, section XX, as amended by Law No. 2245-VIII of 07.12.2017 }
{Subsection 4 of Section XX supplemented by paragraph 34 in accordance with Law No. 652-VIII of 17.07.2015 }
35. Non-profit enterprises, institutions and organizations included in the Register of Non-profit Institutions and Organizations on the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Taxation of Non-profit Organizations", which do not meet the requirements of paragraph 133.4 of Article 133 of this Code, in order to be included in the new Register of Non-profit Institutions and Organizations, are obliged to bring their constituent documents into line with the norms of this Code by July 1, 2017 and submit copies of such documents to the regulatory authority within the same period.
{Paragraph one of clause 35, subsection 4, section XX, as amended by Law No. 1797-VIII of 21.12.2016 }
Non-profit enterprises, institutions and organizations that have not brought their constituent documents into compliance with the norms of Clause 133.4 of Article 133 of this Code, and religious organizations - with the norms of the second subparagraph of Clause 133.4.1 of Clause 133.4 of Article 133 of this Code, after July 1, 2017, shall be excluded by the supervisory authority from the Register of Non-profit Institutions and Organizations.
{Paragraph two of clause 35, subsection 4, section XX, as amended by Laws No. 1797-VIII of 12/21/2016 , No. 2245-VIII of 12/07/2017 }
{Paragraph three of clause 35, subsection 4, section XX was excluded on the basis of Law No. 2245-VIII of 07.12.2017 }
{Subsection 4 of Section XX supplemented by paragraph 35 in accordance with Law No. 652-VIII of 17.07.2015 }
36. The financial result before taxation is reduced by the amount of income arising from taxpayers who are debtors (borrowers) under external credits (loans) attracted under state guarantees, the servicing and repayment of which is carried out at the expense of the State Budget of Ukraine, according to the list determined by the Cabinet of Ministers of Ukraine, as a result of the transactions specified in paragraph 14 of the section "Final Provisions" of the Law of Ukraine "On the State Budget of Ukraine for 2015".
The financial result before taxation shall be increased by the amount of expenses incurred by taxpayers specified in the first paragraph of this paragraph, according to the accounting rules when writing off bad debts for delivered goods (works, services) that were subject to payment from the State Budget of Ukraine. Such an increase in the financial result before taxation shall be in an amount not exceeding the amount of income specified in the first paragraph of this paragraph.
{Subsection 4 of Section XX supplemented by paragraph 36 in accordance with Law No. 702-VIII of 17.09.2015 }
37. Income of non-residents with a source of origin in Ukraine from transactions on placement of government derivatives to non-residents and income paid to non-residents on government derivatives, in accordance with the terms of transactions with government debt on state external borrowings and state-guaranteed debt, approved by the Cabinet of Ministers of Ukraine, are not subject to taxation.
{Subsection 4 of Section XX supplemented by paragraph 37 in accordance with Law No. 702-VIII of 17.09.2015 }
38. Payers of corporate income tax shall pay an advance payment of this tax by December 31, 2016 in the amount of 2/9 of the income tax calculated in the tax reporting for the three quarters of 2016.
The calculation of such advance payment is submitted by the taxpayer in the tax return for the three quarters of 2016. The amount of advance payments determined in the calculation is considered the agreed amount of monetary obligations.
If a taxpayer fails to pay the agreed amount of advance payments for corporate income tax within the time limits specified in this Code, such taxpayer shall be held liable in the form of a fine in the amounts specified in Article 123 of this Code.
{Subsection 4 of Section XX supplemented by paragraph 38 in accordance with Law No. 909-VIII of 24.12.2015 }
38 - 1. Temporarily, for the period of implementation of the project to modernize the Bortnytsia Wastewater Treatment Plant within the framework of the implementation of the project "Reconstruction of wastewater treatment facilities and construction of a technological line for the treatment and utilization of sludge of the Bortnytsia Aeration Station", approved by the Cabinet of Ministers of Ukraine (hereinafter referred to as the Project), the profit (income) of Japanese entities from the implementation of the Project is exempt from taxation, provided that such profit (income) is received within the framework of the implementation of the Project.
The term "Japanese Project Implementation Entity" is used in the meaning given in subparagraphs "a"-"c" of paragraph 9 of subsection 1 of this section.
{Subsection 4 of Section XX supplemented by a paragraph in accordance with Law No. 903-VIII of 12/23/2015 ; as amended by Law No. 466-IX of 01/16/2020 }
39. Temporarily, until January 1, 2028, the corporate income tax payer:
{Paragraph one of clause 39, subsection 4, section XX, as amended by Laws No. 425-IX of 12/20/2019 , No. 2719-IX of 11/03/2022 }
1) reduces the financial result before taxation:
on the amount of income recognized by him in accordance with national accounting regulations (standards) or international financial reporting standards as a result of the write-off of his tax debt, cancellation (forgiveness) and/or installment (deferral) of his obligations in accordance with the provisions of Clause 37, Subsection 10, Section XX "Transitional Provisions" of this Code, as well as as a result of the cancellation (forgiveness) of his obligations in accordance with the law on financial restructuring;
{Paragraph two of subparagraph 1 of clause 39 of subsection 4 of section XX as amended by Law No. 425-IX of 20.12.2019 }
on the amount of income recognized by it in accordance with national accounting regulations (standards) or international financial reporting standards in connection with the liquidation of reserves as a result of its restructuring of liabilities in accordance with a restructuring plan signed in accordance with the law on financial restructuring, or a rehabilitation plan approved in accordance with the legislation regulating relations on issues of restoring the solvency of the debtor or declaring him bankrupt, taking into account the features established by the law on financial restructuring, if the taxation of such reserves is regulated by the norms of Clause 139.3 of Article 139 of this Code;
{Paragraph three of subparagraph 1 of clause 39 of subsection 4 of section XX as amended by Law No. 425-IX of 20.12.2019 }
2) increases the financial result before tax:
by one third of the amount of income recognized in connection with the reduction (dissolution) of reserves, by which its financial result before taxation was reduced in accordance with subparagraph 1 of this paragraph, in each of the three years following the year in which the restructuring plan was signed in accordance with the law on financial restructuring or the rehabilitation plan was approved in accordance with the legislation regulating relations on issues of restoring the solvency of the debtor or declaring it bankrupt, taking into account the features established by the law on financial restructuring;
{Paragraph two of subparagraph 2 of clause 39 of subsection 4 of section XX as amended by Law No. 425-IX of 20.12.2019 }
3) does not change the financial result before taxation:
for the amount of the reserve used as a result of the cancellation (forgiveness) of the obligation under the terms of a restructuring plan signed in accordance with the law on financial restructuring, or a rehabilitation plan approved in accordance with the legislation regulating relations on issues of restoring the solvency of the debtor or declaring him bankrupt, taking into account the features established by the law on financial restructuring;
for the amount of income and expenses not specified in subparagraphs 1 and 2 of this paragraph, which are recognized in accordance with national accounting regulations (standards) or international financial reporting standards as a result of restructuring obligations under the terms of a restructuring plan signed in accordance with the law on financial restructuring, or a rehabilitation plan approved in accordance with the legislation regulating relations on issues of restoring the solvency of the debtor or declaring him bankrupt, taking into account the features established by the law on financial restructuring.
{Subparagraph 3 of paragraph 39 of subsection 4 of section XX as amended by Law No. 425-IX of 20.12.2019 }
{Subsection 4 of Section XX supplemented by paragraph 39 in accordance with Law No. 909-VIII of 24.12.2015 }
40. The calculation of the object of taxation by corporate income tax in 2015 is carried out taking into account the fact that the financial result before taxation is reduced by the amount of accrued income from participation in the capital of other corporate income tax payers, single tax payers of the fourth group and by the amount of accrued income in the form of dividends payable in its favor from other taxpayers who pay advance contributions on corporate income tax upon payment of dividends.
{Subsection 4 of Section XX supplemented by paragraph 40 in accordance with Law No. 909-VIII of 24.12.2015 }
41. Temporarily, until January 1, 2025, the profits of aircraft manufacturing enterprises determined in accordance with the norms of Article 2 of the Law of Ukraine "On the Development of the Aircraft Manufacturing Industry" are exempt from taxation.
{Paragraph one of clause 41, subsection 4, section XX as amended by Law No. 2245-VIII of 07.12.2017 }
The released funds (tax amounts not paid to the budget and remaining at the taxpayer's disposal) are used for research and development work in aircraft construction, creation or re-equipment of the material and technical base, increase in production volume, introduction of new technologies. The use of such funds must be related to the taxpayer's activities, the profit from which is exempt from taxation. The procedure for controlling the use of released funds is established by the Cabinet of Ministers of Ukraine.
The amounts of released funds are recognized as received target financing in accordance with national accounting regulations (standards) or international financial reporting standards.
In case of violation of the areas of targeted use, the procedure for using the released funds, the taxpayer is obliged to increase the tax liability for corporate income tax, starting from the first day of the month in which such violation was committed. Penalties and fines are determined in accordance with this Code.
{Subsection 4 of Section XX supplemented by paragraph 41 in accordance with Law No. 1795-VIII of 20.12.2016 }
42. The amounts of income or expenses taken into account when determining the object of taxation by income tax before January 1, 2015 and taken into account as part of income or expenses in accordance with accounting regulations (standards) or international financial reporting standards when determining the financial result before taxation after January 1, 2015, are not subject to repeated consideration when determining such an object and form the difference according to which the financial result before taxation:
is reduced by the amount of such income;
increases by the amount of such expenses.
{Subsection 4 of Section XX supplemented by paragraph 42 in accordance with Law No. 1797-VIII of 21.12.2016 }
43. When calculating depreciation using the straight-line method for fixed assets of the fourth group, income tax payers may use, starting from January 1, 2017, the minimum allowable depreciation period, which is two years, if the costs for the acquisition of such fixed assets were incurred (accrued) by the taxpayer after January 1, 2017 and if the following requirements are simultaneously met for such fixed assets:
fixed assets were not put into operation and were not used in the territory of Ukraine;
fixed assets were put into operation within one of the tax (reporting) periods from January 1, 2017 to December 31, 2019;
{Paragraph three of clause 43, subsection 4, section XX as amended by Law No. 2628-VIII of 11/23/2018 }
fixed assets are used in their own business activities and are not sold or leased to other persons (with the exception of taxpayers whose main activity is property leasing services).
In case of failure to comply with the specified requirements before the end of the depreciation period using the minimum allowable depreciation period specified in this paragraph, starting from the date of their commissioning, the taxpayer in the tax (reporting) period in which the fact of non-use of fixed assets in its own business activities or their sale occurred, is obliged to:
increase the financial result before taxation by the amount of accrued depreciation of fixed assets in accordance with this clause during the tax (reporting) periods in which depreciation was accrued using the minimum allowable depreciation periods of fixed assets specified in this clause;
reduce the financial result before taxation by the amount of calculated depreciation of such fixed assets in accordance with Clause 138.3 of Article 138 of this Code for the relevant tax (reporting) periods.
When applying the provisions of this paragraph, the provisions of paragraph 138.3 of Article 138 of this Code shall not apply to the accrual of depreciation in accordance with the established minimum permissible depreciation periods for fixed assets.
In the event of a reorganization or separation, the right to apply the minimum allowable depreciation periods for fixed assets specified in this clause shall be transferred to the legal successor(s) in accordance with the share of capital investments received by such legal successor(s) in accordance with the distribution balance sheet or transfer deed.
{Subsection 4 of Section XX supplemented by paragraph 43 in accordance with Law No. 1797-VIII of 21.12.2016 }
43 - 1. When determining the object of taxation by corporate income tax for the period from January 1, 2020 to December 31, 2030, income tax payers have the right, when calculating depreciation on fixed assets:
the fourth group (machinery and equipment) and the fifth group use the minimum allowable depreciation period, which is two years;
the third group (transmission devices) and the ninth group use the minimum allowable depreciation period, which is five years.
The minimum allowable depreciation periods for fixed assets specified in this clause are used regardless of the depreciation periods specified in accounting.
Fixed assets must simultaneously meet the following requirements:
put into operation by the taxpayer within one of the tax (reporting) periods, from January 1, 2020 to December 31, 2030;
were not in use.
At the same time, such fixed assets must be used in their own business activities and cannot be sold or leased to other persons (except for taxpayers whose main activity is property leasing services).
In case of failure to comply with the specified requirements before the end of the depreciation period using the minimum allowable depreciation periods specified in this paragraph, starting from the date of their commissioning, the taxpayer in the tax (reporting) period in which the fact of non-use of fixed assets in its own business activities or their sale occurred, is obliged to:
increase the financial result before taxation by the amount of accrued depreciation of fixed assets in accordance with this clause during the tax (reporting) periods in which depreciation was accrued using the minimum allowable depreciation periods of fixed assets specified in this clause;
reduce the financial result before taxation by the amount of calculated depreciation of such fixed assets in accordance with Clause 138.3 of Article 138 of this Code for the relevant tax (reporting) periods.
When applying the provisions of this paragraph, the provisions of paragraph 138.3 of Article 138 of this Code shall not apply to the accrual of depreciation in accordance with the established minimum permissible depreciation periods for fixed assets and methods of its accrual.
For the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , and until the end of the calendar year in which martial law is terminated or canceled, the requirement for fixed assets not to be in use, determined by paragraph seven of this paragraph, does not apply to fixed assets put into operation after the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Peculiarities of Tax Administration During Martial Law for Taxpayers with a High Level of Voluntary Compliance with Tax Legislation".
{Item 43 - 1 of Subsection 4 of Section XX supplemented by a paragraph in accordance with Law No. 3813-IX of 18.06.2024 }
Income tax payers have the right to apply the norms specified in this paragraph to fixed assets that were in use, put into operation during the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Peculiarities of Tax Administration during Martial Law for Taxpayers with a High Level of Voluntary Compliance with Tax Legislation". Such taxpayers are required to conduct an inventory of these fixed assets as of the first day of the tax (reporting) period in which the decision to apply the provisions of this paragraph was made. In this case, the book (residual) value of such fixed assets, calculated in accordance with the requirements of Section III of this of the Code on the first day of such tax (reporting) period, shall be subject to depreciation within the minimum allowable depreciation periods of the relevant group of fixed assets, determined by this paragraph. The provisions of this paragraph shall apply to corporate income tax payers who are manufacturers/suppliers of defense goods under state contracts (agreements) on defense procurement, performers of defense works and services or enterprises co-performers of the specified contracts (agreements) within the meaning of the Law of Ukraine "On Defense Procurement".
{Item 43 - 1 of Subsection 4 of Section XX supplemented by a paragraph in accordance with Law No. 3813-IX of 18.06.2024 }
{Subsection 4 of Section XX supplemented by paragraph 43 - 1 in accordance with Law No. 466-IX of January 16, 2020 }
44. For the period until December 31, 2021, a zero percent rate shall be applied to income tax payers whose annual income, determined according to accounting rules for the last annual reporting period, does not exceed three million hryvnias and the amount of wages (income) accrued for each month of the reporting period to each of the employees who are in an employment relationship with the taxpayer is not less than two minimum wages, the amount of which is established by law, and who meet one of the following criteria:
a) formed in accordance with the procedure established by law after January 1, 2017;
b) operating, in which during the three consecutive previous years (or during all previous periods, if less than three years have passed since their establishment) the annual amount of income was declared in an amount not exceeding three million hryvnias, and in which the average number of employees during this period was from five to 20 people;
c) who were registered as single tax payers in accordance with the procedure established by law in the period before January 1, 2017 and whose revenue from sales of products (goods, works, services) in the last calendar year amounted to up to three million hryvnias and the average number of employees was from five to 50 people.
At the same time, if taxpayers applying the provisions of this paragraph in any reporting period have reached indicators regarding the income received, average number of employees or average salary of employees, at least one of which does not meet the criteria specified in this paragraph, then such taxpayers are obliged to tax the profit received in such reporting period at the rate established by paragraph 136.1 of Article 136 of this Code.
This clause does not apply to business entities that:
1) formed after January 1, 2017 through reorganization (merger, acquisition, division, transformation), privatization and corporatization;
2) carry out:
2.1) entertainment activities defined in subparagraph 14.1.46 of paragraph 14.1 of Article 14 of Section I;
2.2) production, wholesale, export, import of excisable goods;
2.3) production, wholesale and retail sale of fuels and lubricants;
2.4) mining, serial production and manufacturing of precious metals and precious stones, including organogenic formations;
2.5) financial and insurance activities (gr. 64 - gr. 66 of Section K of the KVED DK 009:2010 );
2.6) currency exchange activities;
2.7) extraction and sale of minerals of national importance;
2.8) real estate transactions (gr. 68 KVED DK 009:2010 );
2.9) postal and courier activities (gr. 53 KVED DK 009:2010 );
2.10) activities for organizing auctions of works of art, collectibles or antiques;
2.11) activities related to the provision of services in the field of television and radio broadcasting in accordance with the Law of Ukraine "On Television and Radio Broadcasting";
2.12) security activities;
2.13) foreign economic activity (except for activities in the field of informatization);
2.14) production of products using toll raw materials;
2.15) wholesale trade and wholesale brokerage;
2.16) activities in the field of production and distribution of electricity, gas and water;
2.17) activities in the fields of law and accounting (gr. 69 KVED DK 009:2010 );
2.18) activities in the field of engineering (gr. 71 KVED DK 009:2010 ).
Taxpayers specified in subparagraphs "a", "b", "c" of this paragraph, who accrue and pay dividends to their shareholders (owners), accrue and pay to the budget an advance tax contribution in accordance with the procedure established by paragraph 57.1 - 1 of Article 57 of this Code, and pay income tax at the rate established by paragraph 136.1 of Article 136 of this Code, for the reporting tax period in which dividends were accrued and paid.
{Subsection 4 of Section XX supplemented by paragraph 44 in accordance with Law No. 1797-VIII of 21.12.2016 }
45. The provisions of paragraph 137.6 of Article 137 of this Code, in the version in force until January 1, 2017, shall be applied to determine the object of taxation by income tax based on the results of 2016.
{Subsection 4 of Section XX supplemented by paragraph 45 in accordance with Law No. 1797-VIII of 21.12.2016 }
46. Income paid or to be paid by a resident to a non-resident or a person authorized by him in the form of interest on a loan or financial credit provided to residents before December 31, 2016, shall be exempt from taxation if the funds provided by the non-resident on a loan or financial credit were raised by placing foreign debt securities on a foreign stock exchange and meet the conditions of subparagraph "b" of subparagraph 141.4.11 of paragraph 141.4 of Article 141 of this Code.
{Subsection 4 of Section XX supplemented by paragraph 46 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended in accordance with Law No. 2245-VIII of 07.12.2017 }
47. Income paid by a resident to a non-resident or a person authorized by him in the form of interest on a loan or financial credit provided to residents in the period from January 1, 2017 to December 31, 2018 is exempt from taxation, if such income meets the conditions of subparagraph 141.4.11 of paragraph 141.4 of Article 141 of this Code.
{Subsection 4 of Section XX supplemented by paragraph 47 in accordance with Law No. 1797-VIII of 21.12.2016 }
48. To establish that the tax rate on income from operations on the issuance and holding of lotteries, determined by clause 14.1.271 of clause 14.1 of Article 14 of this Code, is:
from January 1, 2017 to December 31, 2017 inclusive - 18 percent;
from January 1, 2018 to December 31, 2018 inclusive - 24 percent;
from January 1, 2019 to December 31, 2019 inclusive - 26 percent;
from January 1, 2020 to December 31, 2020 inclusive - 28 percent;
From January 1, 2021, the tax rate specified in paragraph 136.6 of Article 136 of this Code shall apply.
{Subsection 4 of Section XX supplemented by paragraph 48 in accordance with Law No. 1797-VIII of 21.12.2016 }
49. Taxpayers specified in Clause 139.3 of Article 139 of this Code shall reduce (increase) the financial result before taxation by the positive (negative) difference (which will be reflected through the bank's capital accounting accounts) between the adjusted amount of reserves for assets (including groups of assets), calculated as of the beginning of 2018 in accordance with the requirements of international financial reporting standards, which will be applied from 2018, and the amount of reserves formed in connection with the decrease in the usefulness of assets in accordance with the requirements of international financial reporting standards, which were applied as of the end of 2017. The norm of this clause shall apply to the financial result before taxation of the reporting (tax) period in which the adjustment of reserves for assets (including groups of assets) is reflected in accounting.
{Subsection 4 of Section XX supplemented by paragraph 50 in accordance with Law No. 2245-VIII of 07.12.2017 }
50. Taxpayers specified in Clause 139.3 of Article 139 of this Code shall reduce the financial result before taxation by the accumulated amount as of the end of 2017 of the excess of the reserve formed in connection with the depreciation (reduction in usefulness) of assets in accordance with the requirements of international financial reporting standards over the limit calculated in accordance with the provisions of this Code, including in accordance with Clause 21 of this subsection. The amount of such excess shall not include the part of the reserve (within the limits of the excess over the limit) that was used or liquidated in the reporting (tax) periods before January 1, 2018. The decrease in the financial result in accordance with this Clause shall be reflected by the taxpayer in equal parts in each quarter of 2018 and 2019.
{Subsection 4 of Section XX supplemented by paragraph 50 in accordance with Law No. 2245-VIII of 07.12.2017 }
51. Profits received by UEFA and/or its related parties up to and including 26 May 2018 from the transfer and/or use of commercial rights relating to the final matches of the UEFA Champions League and the UEFA Women's Champions League of the 2017/2018 season are exempt from taxation.
The activities of UEFA and/or its affiliated persons for the purposes of preparing and/or holding the said matches are carried out without establishing a permanent establishment in Ukraine within the meaning of sub-clause 14.1.193 of clause 14.1 of Article 14 of this Code. The profit derived from such activities is exempt from taxation in accordance with Section III of this Code.
Income with a source of origin in Ukraine, defined in clause 141.4 of Article 141 of this Code and received by UEFA and/or its related parties from the Football Federation of Ukraine and residents of Ukraine involved in the preparation and/or holding of the specified matches, is not taxable.
In this paragraph, the following terms are used:
commercial rights - rights arising in connection with the holding of the said matches, including rights to advertising, marketing, sales, licensing, commercial concession, sponsorship, publication, print media activities, television broadcasting, recording and reproduction of events related to the holding of the said matches;
UEFA - Union of European Football Associations.
{Subsection 4 of Section XX supplemented by paragraph 51 in accordance with Law No. 2374-VIII of 22.03.2018 }
51 - 1. To establish that in 2020 and 2021, the adjustments established by paragraph one of subparagraph 140.5.9 of paragraph 140.5 of Article 140 of this Code shall not apply to the amounts of funds or the cost of medicines for providing medical care to patients, disinfectants and antiseptics, medical equipment, personal protective equipment, medical products for screening patients, consumables for providing medical care, medical products, laboratory equipment, consumables, reagents for laboratory tests; medical products, laboratory equipment, consumables for infectious departments, pathological departments, etc., personal hygiene products, food products and/or goods according to the list determined by the Cabinet of Ministers of Ukraine, which are voluntarily transferred (transferred) to public associations and/or charitable organizations and/or the central executive body implementing state policy in the field of health care, and/or other central executive bodies implementing state policy in the areas of sanitary and epidemic well-being of the population, quality control and safety of medicines, combating HIV/AIDS and other socially dangerous diseases, and/or a person authorized to make purchases in the field of health care, and/or to health care institutions of state and/or municipal ownership, and/or to structural units on health care of regional, Kyiv and Sevastopol city state administrations, during the quarantine established by the Cabinet of Ministers of Ukraine throughout the country. the territory of Ukraine in order to prevent the spread of coronavirus disease (COVID-19) in the territory of Ukraine.
{Subsection 4 of Section XX is supplemented by paragraph 51 - 1 in accordance with Law No. 540-IX of March 30, 2020 ; as amended by the Law No. 1998-IX dated 01/25/2022 - regarding the application of the norms, see paragraph 2 of section II }
51 - 2. Temporarily, when determining the object of taxation by corporate income tax for the tax (reporting) periods of 2020 and 2021 for state and/or municipally owned healthcare institutions and/or a person authorized to make purchases in the healthcare sector that are payers of income tax, the financial result before taxation:
{Paragraph one of clause 51 - 2 of subsection 4 of section XX as amended by Law No. 1998-IX of 25.01.2022 - for the application of the norms, see clause 2 of section II}
is reduced by the amount of income recognized under accounting rules as a result of their receipt of funds or goods: medicines for providing medical care to patients, disinfectants and antiseptics, medical equipment, personal protective equipment, medical products for screening patients, consumables for providing medical care, medical products, laboratory equipment, consumables, reagents for laboratory tests; medical products, laboratory equipment, consumables for infectious departments, pathological departments, etc., personal hygiene products, food products or goods, according to the list determined by the Cabinet of Ministers of Ukraine; voluntarily transferred by legal entities and/or individuals during the quarantine established by the Cabinet of Ministers of Ukraine throughout Ukraine in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine.
When determining the object of taxation by corporate income tax for state and/or municipally owned healthcare institutions and/or a person authorized to make procurements in the healthcare sector that are payers of income tax, the financial result before taxation:
is increased by the amount of expenses recognized under accounting rules as a result of their use of the funds or goods specified in this paragraph.
{Subsection 4 of Section XX supplemented by paragraph 51 - 2 in accordance with Law No. 540-IX of March 30, 2020 }
51 - 3. Temporarily, during the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine, a person authorized to make procurements in the healthcare sector has the right to supply (transfer) free of charge goods belonging to it (medicines, medical products and/or medical equipment) necessary for the implementation of measures aimed at preventing the occurrence and spread, localization and elimination of outbreaks, epidemics and pandemics of coronavirus disease (COVID-19), the list of which is determined by the Cabinet of Ministers of Ukraine, to healthcare institutions of state and/or municipal ownership and/or structural units on healthcare issues of regional, Kyiv and Sevastopol city state administrations.
At the same time, when determining the object of taxation by corporate income tax for the tax (reporting) periods of 2020 and 2021 for state and/or municipally owned healthcare institutions that are payers of income tax, the financial result before taxation:
{Paragraph two of clause 51 - 3 of subsection 4 of section XX as amended by Law No. 1998-IX of 25.01.2022 - for the application of the norms, see clause 2 of section II}
is reduced by the amount of income recognized according to accounting rules as a result of their receipt of the goods specified in the first paragraph of this paragraph.
When determining the object of taxation by corporate income tax for state and/or municipally owned healthcare institutions that are payers of income tax, the financial result before taxation:
is increased by the amount of expenses recognized according to accounting rules as a result of their use of the goods specified in the first paragraph of this paragraph.
{Subsection 4 of Section XX supplemented by paragraph 51 - 3 in accordance with Law No. 540-IX of 30.03.2020 }
52. Income tax payers may decide to apply the "production" depreciation method from the second to fourth quarter of 2020 when determining the object of income tax taxation for fixed assets, the depreciation of which has begun using a different method. Such taxpayers are required to conduct an inventory of these fixed assets as of the first day of the tax (reporting) period of 2020 in which the decision to apply the "production" method was made.
If the total book value (excluding revaluation) of fixed assets according to accounting data is less than the book value (residual) of fixed assets calculated in accordance with the requirements of Section III of this Code, the difference arising from such comparison shall be depreciated as a separate fixed asset using the "straight-line" depreciation method for twenty tax (reporting) quarters and shall reduce the financial result before taxation for the relevant tax (reporting) period.
If the book value (excluding revaluation) of fixed assets according to accounting data is greater than the book value (residual) of such fixed assets calculated in accordance with the requirements of Section III of this Code, when changing the depreciation method to the "production" method, the book value (residual) of fixed assets calculated in accordance with the requirements of Section III of this Code shall be applied when determining the object of taxation by income tax.
{Subsection 4 of Section XX supplemented by paragraph 52 in accordance with Law No. 466-IX of January 16, 2020 }
53. The rules for accounting for interest provided for in paragraph one of paragraph 140.2 of Article 140 of this Code shall apply from January 1, 2021 to all credits, loans and other debt obligations arising from transactions with non-residents and which are recorded on the taxpayer's balance sheet as of January 1, 2021.
{Subsection 4 of Section XX supplemented by paragraph 53 in accordance with Law No. 466-IX of 01.16.2020 ; as amended in accordance with Law No. 786-IX of 07.14.2020 }
54. The financial result before taxation is reduced by the amount of income in the form of:
received one-time compensation to business entities in accordance with the Law of Ukraine "On Social Support for Insured Persons and Business Entities for the Period of Implementation of Restrictive Anti-Epidemic Measures Introduced to Prevent the Spread of Acute Respiratory Disease COVID-19 Caused by the SARS-CoV-2 Coronavirus in the Territory of Ukraine" and included in the income of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards;
written-off penalties and fines in accordance with clauses 2 - 3 and written-off tax debt in accordance with clauses 2 - 4 and subparagraph 26.2 of clause 26 of subsection 10 of section XX of this Code and included in the income of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards.
{Subsection 4 of Section XX supplemented by paragraph 54 in accordance with Law No. 1072-IX of 04.12.2020 ; as amended in accordance with Law No. 1617-IX of 01.07.2021 }
55. Temporarily, until January 1, 2035, the features of taxation of the profit of an enterprise - an investor with significant investments (except for those implementing investment projects in the areas of extraction for the purpose of further processing and/or enrichment of minerals), which is a party to a special investment agreement concluded in accordance with the Law of Ukraine "On State Support of Investment Projects with Significant Investments in Ukraine", shall apply, provided that such profit is received as a result of the implementation of such a special investment agreement.
The terms "investor with significant investments" , "investment project with significant investments" , "special investment agreement" are used in the meaning given in the Law of Ukraine "On State Support of Investment Projects with Significant Investments in Ukraine".
For taxpayers defined by this clause, tax (reporting) periods are calendar: quarter, half-year, three quarters, year. In this case, the tax return is calculated on a cumulative basis. Taxpayers defined by this clause cannot use exclusively an annual tax (reporting) period.
The profit of an enterprise - investor with significant investments specified in the first paragraph of this paragraph shall be exempt from corporate income tax for five consecutive years starting from the first day of the first month of the calendar quarter specified by the taxpayer - investor with significant investments in the application submitted by him to the regulatory authority at the place of registration of such taxpayer in an arbitrary form on the exercise of the right to apply the exemption provided for in this paragraph, but not earlier than the date of submission of such application, as well as the date specified in the register of investment projects with significant investments of the fulfillment by the investor with significant investments of the obligations provided for by the special investment agreement regarding the contribution of the volume of significant investments into investment objects and the start of operation of such investment objects within the framework of the implementation of the investment project with significant investments and provided that the taxpayer - investor with significant investments fulfills its obligations under the special investment agreement. At the same time, the period of application of such exemption cannot exceed the term of validity of the special investment agreement.
If the supervisory authority does not refuse to apply the exemption specified in this paragraph within ten working days from the date of receipt of the application, such application shall be deemed accepted. The application shall be submitted by the payer in accordance with the procedure specified in paragraph 42.4 of Article 42 of this Code. The supervisory authority shall notify the taxpayer of the refusal to grant the exemption in accordance with the procedure specified in paragraph 42.4 of Article 42 of this Code.
The total amount of funds exempted from taxation (the amount of tax not paid to the budget and remaining at the disposal of the taxpayer - investor with significant investments) is taken into account in the total amount of state support for an investment project with significant investments provided for by a special investment agreement, which is provided in accordance with the Law of Ukraine "On State Support for Investment Projects with Significant Investments in Ukraine".
In the event that the total amount of state support received by a taxpayer - investor with significant investments in accordance with the Law of Ukraine "On State Support for Investment Projects with Significant Investments in Ukraine" is established in accordance with the legislation, the taxpayer is obliged to calculate and pay corporate income tax in accordance with the general procedure, starting from the first day of the first month of the calendar quarter of the tax (reporting) period in which such excess occurred.
Regardless of the features defined by this paragraph, if a taxpayer - an investor with significant investments carries out, within the framework of activities related to the implementation of a special investment agreement, controlled transactions defined by Article 39 of this Code, the object of taxation by corporate income tax, which is taxed at the basic (basic) rate, is determined separately at the level of:
the excess of the price determined according to the "arm's length" principle over the contractual (contractual) value (the value at which the relevant transaction must be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of the goods (works, services) sold;
excess of the contractual value (the value at which the relevant transaction must be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of purchased goods (works, services) over the price determined according to the "arm's length" principle.
If the taxpayer - investor with significant investments is a controlling entity, a separate object of taxation of corporate income tax, which is taxed at the basic (basic) rate, is the adjusted profit of the controlled foreign company, determined in accordance with Article 39 - 2 of this Code.
The objects of taxation defined in paragraphs eight and eleven of this clause are not exempt from taxation and are subject to taxation in the general manner.
In the event of early termination of a special investment agreement, the taxpayer loses the right to apply the taxation rules established by this paragraph. In this case, such a taxpayer is obliged to determine the corporate income tax liability in accordance with the general procedure based on the results of the tax (reporting) period in which the special investment agreement was terminated early.
For all other previous periods of application of the corporate income tax exemption in accordance with this paragraph, the taxpayer shall be obliged, within the period specified for the quarterly tax (reporting) period, starting from the first day of the month following the month in which the special investment agreement was terminated early, to submit a clarifying corporate income tax return(s), calculate and pay the corporate income tax liability, penalties and interest in accordance with the provisions of this Code. The provisions of this paragraph shall not apply if the early termination of the special investment agreement is due to a violation of the state's obligations to provide state support under the special investment agreement or the occurrence of force majeure circumstances (force majeure circumstances).
, the limitation periods established by Article 102 of this Code shall not apply.
{Subsection 4 of Section XX supplemented by paragraph 55 in accordance with Law No. 1293-IX of 02.03.2021 }
56. Temporarily, until December 31, 2035 (inclusive), the following are exempt from taxation:
1) profit of business entities (production of electric motors, class 27.11, group 27.1, section 27 , KVED DK 009:2010 ) that are exclusively engaged in the production of electric motors intended for vehicles equipped exclusively with electric motors (one or more), classified in commodity headings 8603 , 8701 24, 8702-8705 according to the UKT FEA;
{Subparagraph 1 of paragraph 56, subsection 4, section XX, as amended by Law No. 3553-IX of January 16, 2024 }
2) profit of business entities (production of lithium batteries, class 27.20, group 27.2, section 27 , KVED DK 009:2010 ) that are exclusively engaged in the production of lithium-ion (lithium-polymer) batteries intended for vehicles equipped exclusively with electric motors (one or more), classified under commodity headings 8603 , 8701 24, 8702-8705 according to the UKT FEA;
{Subparagraph 2 of paragraph 56, subsection 4, section XX, as amended by Law No. 3553-IX of January 16, 2024 }
3) profit of business entities (manufacture of chargers for solid-state batteries, class 27.90, group 27.2, section 27 , KVED DK 009:2010 ) that are exclusively engaged in the production of chargers for lithium-ion (lithium-polymer) batteries intended for vehicles equipped exclusively with electric motors (one or more), classified under commodity headings 8603 , 8701 24, 8702-8705 according to the UKT FEA;
{Subparagraph 3 of paragraph 56, subsection 4, section XX, as amended by Law No. 3553-IX of January 16, 2024 }
4) profit of business entities (production of motor vehicles, class 29.10, group 29.1, section 29 , KVED DK 009:2010 ) that are exclusively engaged in the production of vehicles equipped exclusively with electric motors (one or more), classified in commodity positions 8701 24, 8702-8705 according to the UKT FEA ;
{Subparagraph 4 of paragraph 56 of subsection 4 of section XX as amended by Law No. 3553-IX of 16.01.2024 }
5) profit of business entities (production of railway locomotives and rolling stock, class 30.20, group 30.2, section 30 , KVED DK 009:2010 ) that are exclusively engaged in the production of electric vehicles classified in commodity heading 8603 (only self-propelled tram and metro cars) and/or in commodity subcategory 8605 00 00 00 (only non-self-propelled tram and metro cars) according to the UKT FEA ;
6) profit of business entities (production of motor vehicles, class 29.10, group 29.1, section 29 , KVED DK 009:2010 ) that are exclusively engaged in the production of vehicles equipped with spark-ignition internal combustion engines that operate exclusively on compressed natural methane gas, liquefied natural methane gas or biogas, classified in commodity subheading 8701 23, commodity category 8701 29 00, commodity positions 8702-8705 according to the UKT FEA .
{Subparagraph 6 of paragraph 56, subsection 4, section XX, as amended by Law No. 3553-IX of 16.01.2024 }
The released funds (tax amounts not paid to the budget and remaining at the disposal of the taxpayer) are used for research and development work in the field of electric transport, creation or re-equipment of the material and technical base, increase in production volume, introduction of new technologies. The use of such funds must be related to the taxpayer's activities, the profit from which is exempt from taxation. The procedure for controlling the use of released funds is established by the Cabinet of Ministers of Ukraine.
The amounts of released funds are recognized as received target financing in accordance with national accounting regulations (standards) or international financial reporting standards.
In case of violation of the intended use directions and the procedure for using the released funds, the taxpayer is obliged to calculate the tax liability for corporate income tax on the amount of the released funds used for purposes other than their intended purpose, as well as penalties and interest in accordance with the provisions of this Code.
Tax liabilities, penalties and interest are accrued starting from the first day of the month in which such violation was committed.
{Subsection 4 of Section XX supplemented by paragraph 56 in accordance with Law No. 1660-IX of 15.07.2021 }
57. Temporarily, until January 1, 2027, the profit of agricultural producers that carry out exclusively the following types of activities in accordance with the KVED-2010 is exempt from taxation : class 01.47 (breeding and raising of poultry, excluding raising chickens, obtaining chicken eggs and activities of incubators for raising chickens); class 01.49 (in terms of breeding and raising quails and ostriches) and class 10.12 (production of poultry meat, excluding the production of chicken meat, rendering chicken fat, slaughter, processing and packaging of chicken meat), as well as carrying out activities to sell such products produced (grown) by themselves (excluding chicken meat).
The released funds (tax amounts not paid to the budget and remaining at the disposal of the taxpayer) are used to create or re-equip the material and technical base, increase production volumes, and introduce new technologies. The use of such funds must be related to the taxpayer's activities, the profit from which is exempt from taxation. The procedure for controlling the use of released funds is established by the Cabinet of Ministers of Ukraine.
The amounts of released funds are recognized as received target financing in accordance with national accounting regulations (standards) or international financial reporting standards.
In case of violation of the intended use directions and the procedure for using the released funds, the taxpayer is obliged to calculate the tax liability for corporate income tax on the amount of the released funds used for purposes other than their intended purpose, as well as penalties and interest in accordance with the provisions of this Code.
Tax liabilities, penalties and interest are accrued starting from the first day of the month in which such violation was committed.
{Subsection 4 of Section XX supplemented by paragraph 57 in accordance with Law No. 1914-IX of 11/30/2021 }
58. Temporarily, until January 1, 2024, taxpayers - producers of electricity at a "green" tariff have the right to determine their corporate income tax liability taking into account the features specified in this paragraph:
1) in the period from January 1, 2022 to January 1, 2024, the financial result before taxation of the tax (reporting) period is reduced by the amount accrued in accounting and taken into account in the financial result before taxation of income from the sale of electricity at a "green" tariff and/or the provision of load reduction services in the period from January 1, 2022 to January 1, 2024, for which the electricity producer did not receive payment at the end of the reporting period;
from January 1, 2022, the financial result before taxation of the tax (reporting) period shall be increased by the amount of income in the amount of the repaid receivables for electricity sold at a "green" tariff and/or for load reduction services provided, by which the financial result before taxation was reduced in previous reporting periods in accordance with this paragraph. The provisions of this paragraph shall apply until the full repayment of receivables for electricity sold at a "green" tariff and/or for load reduction services sold/provided in the period specified in the first paragraph of this paragraph;
2) in the period from January 1, 2022 to January 1, 2024, the financial result before taxation of the tax (reporting) period is increased by the amount of expenses accrued in accounting and taken into account in the financial result before taxation that form the cost of electricity sold at the "green" tariff, and the costs of selling electricity at the "green" tariff and/or the cost of load reduction services in the period from January 1, 2022 to January 1, 2024, for which the producer did not receive payment at the end of the reporting period;
from January 1, 2022, the financial result before taxation of the tax (reporting) period is reduced by the amount of expenses that form the cost of electricity sold at the "green" tariff, and the costs of selling electricity at the "green" tariff, and/or the cost of the load reduction service for which the producer received payment in such reporting period, and by which the financial result was increased in accordance with this paragraph in previous reporting periods. The provisions of this paragraph apply until the full repayment of receivables for electricity at the "green" tariff sold in the period specified in the first paragraph of this paragraph, and/or for load reduction services provided in such period;
3) taxpayers - producers of electricity at a "green" tariff shall not apply the difference specified in the third paragraph of subparagraph 139.2.2 of paragraph 139.2 of Article 139 of this Code in the event of writing off bad debts for electricity at a "green" tariff that were formed for electricity sold during the period specified in the first paragraph of this paragraph and/or for load shedding services provided during such period. The provisions of this paragraph shall also apply in the period after January 1, 2024.
{Subsection 4 of Section XX is supplemented by paragraph 58 in accordance with Law No. 1914-IX of 30.11.2021 ; as amended by the Law No. 2480-IX dated 07/29/2022 }
59. The norms specified in subparagraph 135.2.1.15 of subparagraph 135.2.1 of paragraph 135.2 of Article 135, subparagraph 141.9 - 1 .2.12 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of Article 141 of this Code shall apply to tax (reporting) periods starting from January 1, 2024.
To establish that in 2024, the amounts of the purchase of property, works, services (except for royalties) from a single tax payer during the tax (reporting) year, provided for by subparagraph 135.2.1.15 of subparagraph 135.2.1 of paragraph 135.2 of Article 135, subparagraph 141.9 - 1 .2.12 of subparagraph 141.9 - 1 .2 of paragraph 141.9 - 1 of Article 141 of this Code, are determined in an amount exceeding 50 percent of the amount of expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income) for the previous annual reporting period. At the same time, expenses related to operating, financial and investment activities are included in the expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income).
Residents of Diya City - taxpayers under special conditions who are registered during 2024 (newly created), in this calendar year, the calculation of the share of the cost of property (works, services) purchased (acquired) from single tax payers is carried out based on the indicators of the Financial Results Report (Comprehensive Income Report) for the current annual reporting period.
{Subsection 4 of Section XX supplemented by paragraph 59 in accordance with Law No. 1946-IX of 12/14/2021 }
60. If a payer of corporate income tax on general grounds has made a transition to taxation as a resident of the City of Action - a taxpayer on special conditions or if a resident of the City of Action - a taxpayer on special conditions has made a transition to taxation by corporate income tax on general grounds, such taxpayers shall determine the object of taxation taking into account this paragraph.
In the event that an issuer of corporate rights, who is a resident of Diya City - a taxpayer under special conditions, carries out a transaction to pay dividends based on the results of a tax (reporting) period during which such an issuer of corporate rights was not a resident of Diya City - a taxpayer under special conditions, such transaction shall be subject to taxation in accordance with Clause 135.2 of Article 135, Clause 137.10 of Article 137 and Clause 141.9 - 1 of Article 141 of this Code in the amount of the excess of dividends paid over the value of the object of taxation by corporate profit tax for such tax (reporting) period.
If an issuer of corporate rights, which is not a resident of Diya City - a taxpayer under special conditions, decides to pay dividends to its shareholders (owners) based on the results of the tax (reporting) period during which it was a resident of Diya City - a taxpayer under special conditions, such issuer shall charge income tax calculated from the amount of dividends paid at the rate established by Clause 136.1 of Article 136 of this Code. Such tax shall be payable within the terms specified in Clause 57.1 of Article 57 of this Code.
The advance payment of corporate income tax, provided for in paragraph 57.1 - 1 of Article 57 of this Code, shall not be deducted from the amount of dividends subject to taxation in accordance with this paragraph.
Transactions of a resident of Diya City - a taxpayer under special conditions on the payment of funds and/or transfer of property (works, services) in favor of persons who are not residents of Diya City - taxpayers under special conditions, in return for repayment of obligations that arose in the period before the transition to taxation as a resident of Diya City - a taxpayer under special conditions, are subject to taxation according to the rules stipulated in Clause 135.2 of Article 135, Clause 137.10 of Article 137 and Clause 141.9 - 1 of Article 141 of this Code.
{Subsection 4 of Section XX supplemented by paragraph 60 in accordance with Law No. 1946-IX of 12/14/2021 }
61. Payment of funds and/or transfer of property (works, services) by a resident of Diya City - a taxpayer under special conditions in return for repayment of obligations incurred to a person who is not a resident of Diya City - a taxpayer under special conditions is not subject to taxation in accordance with Clause 135.2 of Article 135, Clause 137.10 of Article 137 and Clause 141.9 - 1 of Article 141 of this Code, provided that on the date of payment of funds and/or transfer of property (works, services) such person is a resident of Diya City - a taxpayer under special conditions.
{Subsection 4 of Section XX supplemented by paragraph 61 in accordance with Law No. 1946-IX of 12/14/2021 }
62. The provisions of subparagraph 140.5.17 of paragraph 140.5 of Article 140 of this Code shall apply to tax (reporting) periods starting from January 1, 2024.
To establish that in 2024, the amounts of acquisition of property, works, services (except for royalties) from a single tax payer during the tax (reporting) year, provided for by subparagraph 140.5.17 of paragraph 140.5 of Article 140 of this Code, are determined in an amount exceeding 50 percent of the amount of expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income) for the previous annual reporting period. At the same time, expenses related to operating, financial and investment activities are included in the expenses from any activity determined by the indicators of the Statement of Financial Results (Statement of Comprehensive Income).
Residents of Diya City - payers of corporate income tax on a general basis, registered during 2024 (newly created), in this calendar year, the calculation of the share of the cost of property (works, services) purchased (acquired) from payers of a single tax is carried out based on the indicators of the Financial Results Report (Comprehensive Income Report) for the current annual reporting period.
{Subsection 4 of Section XX supplemented by paragraph 62 in accordance with Law No. 1946-IX of 12/14/2021 }
63. For the period of the legal regime of martial law, a state of emergency, the transfer of property, the provision of services by a non-profit organization, the use of income (profits) of a non-profit organization to finance expenses not related to the implementation of the goal (goals, objectives) and areas of activity determined by its constituent documents shall not be considered a violation of the requirements of paragraph 133.4 of Article 133 of this Code, provided that such services, property are voluntarily transferred (provided, transferred) to the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Protection Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, voluntary formations of territorial communities, other military formations, their formations, military units, subdivisions, institutions or organizations maintained at the expense of the state budget for the needs of ensuring the defense of the state, and also in favor of the central executive body that ensures the formation and implementation of state policy in the field of civil defense, civil defense forces and/or healthcare institutions of state and municipal ownership, and/or structural units on healthcare issues of regional, Kyiv and Sevastopol city state administrations, and/or funds transferred to accounts of state bodies opened by the National Bank of Ukraine, intended for financial support of measures to repel armed aggression against Ukraine and eliminate its consequences, national security and defense, restoration, support and development of Ukraine, provision of humanitarian aid, as well as for raising funds to support the Armed Forces of Ukraine and/or provision of charitable assistance to individuals (except for founders, participants of such organizations or persons related to them) from among:
participants in hostilities, servicemen (reservists, conscripts) and employees of the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations formed in accordance with the laws of Ukraine, volunteer formations of territorial communities, police officers and employees of the National Police of Ukraine, including those who suffered injuries, contusions or other damage to health, who defend (defended) the independence, sovereignty and territorial integrity of Ukraine, take (took) direct part in repelling armed aggression and ensuring national security, eliminating the threat of danger to the state independence of Ukraine, its territorial integrity during the period of martial law, a state of emergency in Ukraine, being directly in the areas of implementation of the specified measures, or for the benefit of members their families (within the meaning of subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code) of military personnel who died or died as a result of injury, contusion or mutilation;
employees of enterprises, institutions, organizations, civil defense forces who are involved (were involved) and take (took) direct participation in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation, being directly in the areas of hostilities and during the period of hostilities, in the manner established by law, or for the benefit of their family members (within the meaning of subparagraph 165.1.54 of paragraph 165.1 of Article 165 of this Code);
individuals who live (lived) in the territories of settlements where hostilities are (were) taking place, and/or who were forced to leave their place of residence due to hostilities in such settlements.
{Subsection 4 of Section XX supplemented by paragraph 63 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Laws No. 2173-IX of April 1, 2022 , No. 2520-IX of August 15, 2022 ; as amended by Law No. 4143-IX of December 17, 2024 }
63 - 1 . During the martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On approval of the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 2102-IX , transactions for the transfer of funds, free transfer of goods, work performed, services rendered, which are voluntarily transferred (transferred) to the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their units, military units established in accordance with the laws of Ukraine, are not subject to taxation for residents of Diya City - taxpayers under special conditions. to units, subdivisions, institutions or organizations maintained at the expense of the state budget, for the needs of ensuring the defense of the state and the humanitarian assistance provided in compliance with the requirements of the legislation of Ukraine on humanitarian assistance in connection with the military aggression of the Russian Federation against Ukraine, as well as in favor of the central executive body that ensures the formation and implementation of state policy in the field of civil defense, civil defense forces and/or to healthcare institutions of state, municipal property, and/or to structural units on healthcare of regional, Kyiv and Sevastopol city state administrations, funds transferred to accounts of state bodies opened by the National Bank of Ukraine, intended for the financial support of measures to repel armed aggression against Ukraine and eliminate its consequences, national security and defense, restoration, support and development of Ukraine, provision of humanitarian assistance, as well as for attracting funds to support the Armed Forces of Ukraine.
{Subsection 4 of Section XX supplemented by paragraph 63 - 1 in accordance with Law No. 4113-IX of 04.12.2024 }
64. Temporarily, for the reporting periods of 2022, participants in the debt settlement procedure who participate in mutual settlements carried out for the purposes of implementing measures provided for in Article 4 of the Law of Ukraine "On Measures Aimed at Overcoming Crisis Phenomena and Ensuring Financial Stability in the Natural Gas Market", who are payers of corporate income tax in accordance with Section III of this Code, shall reduce the financial result before taxation by the amount of funds received directly from the state budget in accordance with the Law of Ukraine "On Measures Aimed at Overcoming Crisis Phenomena and Ensuring Financial Stability in the Natural Gas Market", by which the financial result before taxation increased in accordance with national accounting regulations (standards) or international financial reporting standards.
At the same time, the receivables of such payers, for the settlement of which the specified funds were received from the state budget, cannot be considered hopeless in accordance with subparagraph 14.1.11 of paragraph 14.1 of Article 14 of this Code.
{Subsection 4 of Section XX is supplemented by paragraph 64 pursuant to the Act No. 2480-IX dated 07/29/2022 }
64 - 1. During 2023, taxpayers who are required to pay advance payments on corporate income tax in accordance with Clause 141.13 of Article 141 of this Code shall pay the following advance payments:
from January 1, 2023 to June 30, 2023 - using a coefficient of 0.33;
from July 1, 2023 to December 31, 2023 - using a coefficient of 0.66.
{Subsection 4 of Section XX supplemented by paragraph 64 - 1 in accordance with Law No. 2720-IX of 03.11.2022 }
65. To establish that temporarily, for the period until the termination or cancellation of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , income (profit) arising in a bank as a result of the termination of its obligations in accordance with paragraph 23 of Section X "Final and Transitional Provisions" of the Law of Ukraine "On the Deposit Guarantee System of Individuals" is exempt from taxation.
{Subsection 4 of Section XX supplemented by paragraph 65 in accordance with Law No. 2643-IX of 06.10.2022 }
66. The financial result before tax is reduced by:
the amount of accrued income in accordance with national accounting regulations (standards) or international financial reporting standards from transactions related to the receipt, by decision of the Cabinet of Ministers of Ukraine, of objects of property of the Russian Federation and its residents in accordance with the Law of Ukraine "On the Basic Principles of Forced Expropriation in Ukraine of Objects of Property of the Russian Federation and Its Residents", taken into account in the financial result before taxation in the reporting period in which the actual transfer of such objects took place;
the amount of debt included in the income of the reporting period in accordance with national accounting regulations (standards) or international financial reporting standards, the claim for which was forcibly seized as an object of property rights of the Russian Federation and its residents in accordance with the Law of Ukraine "On the Basic Principles of the Forcible Expropriation in Ukraine of Objects of Property Rights of the Russian Federation and Its Residents" and which is considered to be repaid from the date of entry into force of the law of Ukraine, which approved the Decree of the President of Ukraine on the implementation of the decision of the National Security and Defense Council of Ukraine on the forcible seizure of the relevant objects of property rights of the Russian Federation and its residents.
{Subsection 4 of Section XX supplemented by paragraph 66 in accordance with Law No. 2719-IX of 03.11.2022 }
67. The financial result before tax is increased by the amount of accrued expenses in accordance with national accounting regulations (standards) or international financial reporting standards from transactions related to the receipt, by decision of the Cabinet of Ministers of Ukraine, of objects of property of the Russian Federation and its residents in accordance with the Law of Ukraine "On the Basic Principles of Forced Expropriation in Ukraine of Objects of Property of the Russian Federation and Its Residents", taken into account in the financial result before tax in the reporting period in which the actual transfer of such objects took place.
{Subsection 4 of Section XX supplemented by paragraph 67 in accordance with Law No. 2719-IX of 03.11.2022 }
68. To establish that, based on the results of the tax (reporting) year 2023, the basic (basic) rate of corporate income tax for the purposes of taxation of bank profits, as well as for the application of the provisions of paragraph 57.1 - 1 of Article 57 of this Code to banks, is 50 percent.
The amount of corporate income tax for 2023 at a rate of 50 percent is determined for the reporting period - 2023 in the corporate income tax return for such tax (reporting) year. Accrual and payment of the corporate income tax liability for previous tax (reporting) periods of 2023 (quarter, half-year and three quarters) at the base (basic) rate that was in effect before the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Features of Taxation of Banks and Other Taxpayers" is not a violation of the rules for accrual and payment of the corporate income tax liability.
Based on the results of the tax (reporting) year 2023, banks do not apply the provisions provided for in subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code and do not reduce the financial result before taxation by the amount of the negative value of the object of taxation of previous tax (reporting) years.
In the event of application for the previous tax (reporting) periods of 2023 of the provisions provided for in subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code, and/or payment of advance payments for corporate income tax provided for in subparagraph 57.1 - 1 of Article 57 of this Code at a rate of 18 percent, banks shall reflect in the corporate income tax return for 2023 the revised figures (amounts of the negative value of the object of taxation of previous reporting periods, amounts of advance payments for corporate income tax upon payment of dividends at a rate of 50 percent) contained in their previously submitted corporate income tax returns. In the event of reflecting revised figures on the grounds specified in this paragraph, the sanctions provided for in Article 50 of this Code shall not apply. In the event of an additional monetary obligation arising as a result of the clarification of indicators provided for in this paragraph, such monetary obligation shall be payable within the terms established for the payment of the tax obligation based on the results of 2023.
The amount of the negative value of the object of taxation of previous tax (reporting) years, not taken into account in the reduction of the object of taxation by corporate income tax, including that received from January 1, 2023 to December 31, 2023, reduces the financial result before taxation of future tax (reporting) periods starting from January 1, 2024 in the manner specified in subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code, taking into account the features specified in paragraph 70 of this subsection.
{Paragraph five of clause 68, subsection 4, section XX, as amended by Law No. 4015-IX of 10.10.2024 }
{Subsection 4 of Section XX supplemented by paragraph 68 in accordance with Law No. 3474-IX of 21.11.2023 }
69. Fixed assets in the form of residential buildings (separate apartments, rooms, etc.) located on the territory of Ukraine, purchased or constructed by a corporate income tax payer (including at his order) during martial law introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , are considered to be intended for use in the economic activities of the corporate income tax payer, provided that such objects are purchased or constructed by such payer in connection with the relocation of the enterprise or its employees who have the status of internally displaced persons from territories where hostilities are (were) being conducted or temporarily occupied by the Russian Federation, in order to provide housing for employees of such an enterprise and their family members.
{Subsection 4 of Section XX supplemented by paragraph 69 in accordance with Law No. 3813-IX of 18.06.2024 }
70. To establish that, based on the results of the tax (reporting) year 2024, the basic (basic) rate of corporate income tax for the purposes of taxation of bank profits, as well as for the application of the provisions of paragraph 57.1 - 1 of Article 57 of this Code to banks, is 50 percent.
The amount of corporate income tax for 2024 at a rate of 50 percent is determined for the reporting period - 2024 in the corporate income tax return for such tax (reporting) year. Accrual and payment of the corporate income tax liability for previous tax (reporting) periods of 2024 (quarter, half-year and three quarters) at the base (basic) rate that was in effect before the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine Regarding Ensuring Balanced Budget Revenues during the Period of Martial Law" is not a violation of the rules for accrual and payment of the corporate income tax liability.
Based on the results of the tax (reporting) year 2024, banks do not apply the provisions provided for in subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code and do not reduce the financial result before taxation by the amount of the negative value of the object of taxation of previous tax (reporting) years.
In the event of application for the previous tax (reporting) periods of 2024 of the provisions provided for in subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code, and/or payment of advance payments for corporate income tax provided for in subparagraph 57.1 - 1 of Article 57 of this Code at a rate of 25 percent, banks shall reflect in the corporate income tax return for 2024 the revised figures (amounts of the negative value of the object of taxation of previous tax (reporting) periods, including for the period from January 1, 2024, amounts of advance payments for corporate income tax upon payment of dividends at a rate of 50 percent) contained in their previously submitted corporate income tax returns. In the event of reflection of revised figures on the grounds specified in this paragraph, the sanctions provided for in Article 50 of this Code shall not apply. In the event of an additional monetary obligation arising as a result of the clarification of indicators provided for in this paragraph, such monetary obligation shall be payable within the terms established for the payment of the tax obligation based on the results of 2024.
The amount of the negative value of the object of taxation of previous tax (reporting) years, not taken into account in the reduction of the object of taxation by corporate profit tax, including that received from January 1, 2024 to December 31, 2024, reduces the financial result before taxation of future tax (reporting) periods starting from January 1, 2025 in the manner determined by subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code.
{Subsection 4 of Section XX supplemented by paragraph 70 in accordance with Law No. 4015-IX of 10.10.2024 }
71. To establish that the provisions of paragraph 137.12 of Article 137 and paragraph 141.14 of Article 141 of this Code shall apply from the first day of the month in which the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine Regarding Ensuring Balanced Budget Revenues During the Period of Martial Law" entered into force .
As an exception to the provisions of Clause 141.14 of Article 141 of this Code, for the month in which the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Ensuring the Balance of Budget Revenues during the Period of Martial Law" entered into force, the payment of the advance payment of the corporate income tax, calculated in accordance with the provisions of Clause 141.14 of Article 141 of this Code, for taxpayers engaged in retail trade in fuel, shall be made within 20 calendar days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Ensuring the Balance of Budget Revenues during the Period of Martial Law". Such a monetary obligation in the form of an advance payment of the corporate income tax shall be deemed agreed upon at the time of the occurrence of such an obligation, which shall be determined by the calendar date established by this paragraph for the deadline for payment of the advance payment.
{Subsection 4 of Section XX supplemented by paragraph 71 in accordance with Law No. 4015-IX of 10.10.2024 }
72. To establish that for the reporting (tax) periods from 2025 until the end of the calendar year in which the martial law introduced by the Decree of the President of Ukraine dated February 24, 2022 No. 64/2022 "On the Introduction of Martial Law in Ukraine" will be terminated or abolished, approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the adjustments established by the first paragraph of subparagraph 140.5.9 of paragraph 140.5 of Article 140 of this Code shall not be made with respect to the amounts of funds and/or the cost of goods, work performed, services provided, transferred (transferred) free of charge during the reporting (tax) year to non-profit organizations entered in the Register of Non-profit Institutions and Organizations on the date of such transfer of funds, transfer of goods, work, services (except for a non-profit organization, which is an association of insurers, if the participation of the insurer in such an association is a condition for the conduct of activities of such insurer in accordance with the law, and non-profit organizations to which the provisions of subparagraph 140.5.14 of paragraph 140.5 of Article 140 of this Code apply), in an amount not exceeding 8 percent of the taxable profit of the previous reporting year, provided that from this amount (value) more than 4 percent of the taxable profit of the previous reporting year was transferred (transferred) to charitable organizations entered in the Register of Non-Profit Institutions and Organizations.
{Subsection 4 of Section XX supplemented by paragraph 72 in accordance with Law No. 4254-IX of 02/25/2025 }
73. To establish that for the tax (reporting) periods of 2026, the basic (basic) rate of corporate income tax for the purposes of taxation of bank profits, as well as for the application of the provisions of clause 57.1 - 1 of Article 57 of this Code to banks, is 50 percent.
Based on the results of the tax (reporting) periods of 2026, banks do not apply the provisions provided for in subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code and do not reduce the financial result before taxation by the amount of the negative value of the object of taxation of previous tax (reporting) years.
The amount of the negative value of the object of taxation of previous tax (reporting) years, not taken into account in the reduction of the object of taxation by corporate profit tax, including that received from January 1, 2026 to December 31, 2026, reduces the financial result before taxation of future tax (reporting) periods starting from January 1, 2027 in the manner determined by subparagraph 140.4.4 of paragraph 140.4 of Article 140 of this Code.
{Subsection 4 of Section XX supplemented by paragraph 73 in accordance with Law No. 4698-IX of 03.12.2025 }
Subsection 5. Peculiarities of collecting excise tax and environmental tax↑
{Title of Subsection 5 of Section XX as amended by Laws No. 3609-VI of 07.07.2011 , No. 2245-VIII of 07.12.2017 }
The following excise tax rates apply to spirit distillates and alcoholic beverages obtained by distillation of grape wine or grape marc (codes according to the UKT FEA 2208 20 12 00, 2208 20 62 00):
20 hryvnias for 1 liter of 100 percent alcohol - from the date of entry into force of this Code until December 31, 2011;
27 hryvnias for 1 liter of 100 percent alcohol - from January 1, 2012 to January 1, 2013;
29 hryvnias for 1 liter of 100 percent alcohol - from January 1 to December 31, 2013;
{Paragraph four of clause 1, subsection 5, section XX as amended by Law No. 5503-VI of 20.11.2012 }
32 hryvnias for 1 liter of 100 percent alcohol - from January 1 to March 31, 2014;
{Paragraph of clause 1 of subsection 5 of section XX as amended by Laws No. 5503-VI of 11/20/2012 , No. 713-VII of 12/19/2013 }
56.42 hryvnias for 1 liter of 100 percent alcohol - from April 1 to December 31, 2014;
{Paragraph of Clause 1 of Subsection 5 of Section XX as amended by Laws No. 5503-VI of 11/20/2012 , No. 713-VII of 12/19/2013 , No. 1166-VII of 03/27/2014 ; as amended by Law No. 1638-VII of 08/12/2014 }
59.96 hryvnias for 1 liter of 100 percent alcohol - from January 1 to December 31, 2015;
{Paragraph of clause 1 of subsection 5 of section XX as amended by Laws No. 5503-VI of 11/20/2012 , No. 1166-VII of 03/27/2014 , No. 1638-VII of 08/12/2014 }
63.50 hryvnias per 1 liter of 100 percent alcohol - from January 1 to March 31, 2016, and from April 1, 2016 - 89.94 hryvnias per 1 liter of 100 percent alcohol;
{Paragraph of clause 1 of subsection 5 of section XX as amended by Laws No. 1638-VII of 12.08.2014 , No. 909-VIII of 24.12.2015 }
105.8 hryvnias for 1 liter of 100 percent alcohol - from January 1 to December 31, 2017 (inclusive);
{Paragraph of clause 1 of subsection 5 of section XX as amended by Laws No. 1638-VII of 12.08.2014 , No. 909-VIII of 24.12.2015 , No. 1791-VIII of 20.12.2016 }
From January 1, 2018, the excise tax rate determined by subparagraph 215.3.1 of paragraph 215.3 of Article 215 of this Code shall apply.
{Paragraph of clause 1 of subsection 5 of section XX as amended by Law No. 1791-VIII of 12/20/2016 }
2. For tax liabilities from the environmental tax that have arisen:
from January 1, 2011 to December 31, 2012 inclusive, tax rates shall be 50 percent of the rates provided for in Articles 243 , 244 , 245 and 246 of this Code;
from January 1, 2013 to December 31, 2013 inclusive (for electricity producers at thermal power plants and TPPs until December 31, 2015 inclusive) tax rates are 75 percent of the rates provided for in Articles 243 , 244 , 245 , 246 of this Code;
{Paragraph three of clause 2, subsection 5, section XX, as amended by Law No. 713-VII of 19.12.2013 }
From January 1, 2014 (for electricity producers at thermal power plants and TPPs from January 1, 2016), tax rates are 100 percent of the rates provided for in Articles 243 , 244 , 245 and 246 of this Code.
{Paragraph four of clause 2, subsection 5, section XX, as amended by Law No. 713-VII of 19.12.2013 }
3. Temporarily, until August 31, 2011, establish excise tax rates for the following goods:
{Paragraph one of clause 3, subsection 5, section XX, as amended by Law No. 3609-VI of 07.07.2011 }
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Excise tax rates in fixed amounts per unit of sold goods (products)
units of measurement
rate
2710 11 25 00
other special gasolines
euros per 1000 kilograms
132
Motor gasolines:
Motor gasolines with a lead content of 0.013 g/l or less:
more than 0.005 wt. % but not more than 0.035 wt. %
euros per 1000 kilograms
32
2710 19 31 10 2710 19 35 10 2710 19 41 10
not more than 0.005 wt. %
euros per 1000 kilograms
22
{Subsection 5 of Section XX supplemented by paragraph 3 in accordance with Law No. 3221-VI of 07.04.2011 }
4. Temporarily until December 31, 2012, transactions involving the import into the customs territory of Ukraine of specialized vehicles, such as ambulances of commodity code 8703 according to the Ukrainian Customs Tariff of Foreign Economic Activity , which are intended for use by healthcare institutions and the cost of which is paid for from state and local budgets or by order of the relevant budget administrators, are exempt from excise tax.
In the event of misuse of the specified goods, the taxpayer is obliged to increase the tax liability for the tax period to which such violation applies by the amount of excise tax that should have been paid at the time of import of such goods, and also to pay a penalty in accordance with the law.
{Subsection 5 of Section XX supplemented by paragraph 4 in accordance with Law No. 4279-VI of 22.12.2011 }
4 - 1. To restore the effect of paragraph 4 of this subsection from December 1, 2013 to January 1, 2015.
{Subsection 5 of Section XX supplemented by paragraph 4 - 1 in accordance with Law No. 657-VII of 24.10.2013 }
5. Temporarily, until December 31, 2012, establish excise tax rates for the following goods:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Basic excise tax rates in fixed amounts per unit of sold goods (products)
units of measurement
rate
Light distillates:
2710 11 11 00
for specific processing processes
euros per 1000 kilograms
182*
2710 11 15 00
for chemical transformations in processes other than those specified in subheading 2710 11 11 00
-"-
182*
Special gasolines:
2710 11 21 00
white spirit
-"-
182*
2710 11 25 00
other special gasolines
-"-
198*
Motor gasolines:
2710 11 31 00
aviation gasolines
euros per 1000 kilograms
30
Motor gasolines with a lead content of 0.013 g/l or less:
liquefied gas (propane or a mixture of propane and butane)
-"-
44
*A correction amount is added to the rate in each subsequent decade, which cannot be more than 50 percent of such rate. The specified amount is calculated each decade depending on the average price of one barrel of "Brent (DTD)" oil, which formed on the ICE exchange for the previous decade:
Average price of one barrel of Brent (DTD) oil, US dollars per barrel
Value of the adjusting amount
less than 105
(105 - "Brent (DTD)" (average price for the decade) / ratio of the average exchange rate of the euro to the US dollar at the official rate set by the National Bank of Ukraine for the corresponding decade x number of barrels of "Brent (DTD)" oil in tons (7.62)
105-125
not applicable
more than 125
(125 - "Brent (DTD)" (average price for the decade) / ratio of the average exchange rate of the euro to the US dollar at the official rate set by the National Bank of Ukraine for the corresponding decade x number of barrels of "Brent (DTD)" oil in tons (7.62)
** An adjustment amount is added to the rate in each subsequent decade, which cannot be more than 50 percent of such rate. The specified amount is calculated each decade depending on the average price of one barrel of "Brent (DTD)" oil, which formed on the ICE exchange for the previous decade:
Average price of one barrel of Brent (DTD) oil, US dollars per barrel
Value of the adjusting amount
less than 105
(105 - "Brent (DTD)" (average price for the decade) / ratio of the average exchange rate of the euro to the US dollar at the official rate set by the National Bank of Ukraine for the corresponding decade x number of barrels of "Brent (DTD)" oil in tons (7.62) x coefficient (0.25)
105-125
not applicable
more than 125
(125 - "Brent (DTD)" (average price for the decade) / ratio of the average exchange rate of the euro to the US dollar at the official rate set by the National Bank of Ukraine for the corresponding decade x number of barrels of "Brent (DTD)" oil in tons (7.62) x coefficient (0.25)
The central executive body responsible for implementing state policy in the oil and gas complex shall post information on the results of calculating the corrective amount and the average price of one barrel of Brent (DTD) oil on the ICE exchange for the previous decade every decade no later than 1:00 p.m. on the first working day of the current decade on its own official website in a special section and submit it to the central executive body responsible for implementing state tax and customs policy and the central executive body responsible for customs affairs.
{Subsection 5 of Section XX supplemented by paragraph 5 in accordance with Law No. 4677-VI of 05.15.2012 ; as amended in accordance with Law No. 1797-VIII of 12.21.2016 }
6. {Subsection 5 of Section XX is supplemented by paragraph 6 in accordance with Law No. 5503-VI of 20.11.2012 ; in paragraph 6 of Section XX, words and figures are excluded on the basis of Laws No. 1166-VII of 27.03.2014 , No. 1200-VII of 10.04.2014 }
{Item 7 of Subsection 5 of Section XX was excluded pursuant to Law No. 1638-VII of 12.08.2014 }
{Item 8 of Subsection 5 of Section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
9. Within 20 calendar days, starting from March 1, 2016, the taxpayer is obliged to submit to the regulatory authority an act of inventorying the volumes of fuel residues as of the beginning of March 1, 2016, indicating the addresses of the facilities where the relevant volumes of fuel residues are stored, a list of tanks where the volumes of fuel residues are stored, their technical parameters (physical capacity corresponding to technical passports), title documents for the relevant facilities and documents certifying the legal grounds for the operation of such facilities. The regulatory authority shall take into account the volumes of fuel residues indicated in such an inventory act in the formula specified in paragraph 232.3 of Article 232 of this Code as the volume for which the taxpayer has the right to register excise invoices and/or adjustment calculations in the electronic fuel sales administration system.
The form of the inventory act is approved by the central executive body that ensures the formation of state financial policy.
The data of the act of inventorying the remaining fuel volumes may be verified by the supervisory authority in accordance with the established procedure within six calendar months from the date of its submission.
If, based on the results of the inspection, it is established that the volumes of fuel specified in the inventory report do not correspond to the actual data and/or accounting data of the enterprise, the controlling body shall make appropriate adjustments in the Unified Register of Electronic Excise Invoices based on the data from the inspection report.
{Subsection 5 of Section XX supplemented by paragraph 9 in accordance with Law No. 909-VIII of 24.12.2015 }
10. For excise tax payers who are fuel producers who have declared and repaid excise tax liabilities for fuel sales in the 12-month period starting from March 2015, the regulatory authority opens an overdraft on the account card in the amount equal to the average monthly amount of tax amounts that have been declared and repaid by the payer for the last 12 relevant reporting (tax) months (March 2015 - February 2016).
At the expense of the amounts of such an overdraft, the taxpayer has the right to register an application for replenishment of the remaining fuel volume in the electronic fuel sales administration system without the presence of the amounts of excise tax paid on the accounting card.
Such an overdraft is subject to automatic recalculation every quarter (during the first day of the relevant quarter) taking into account the average monthly amount of tax amounts that have been declared by the payer for payment to the budget and repaid over the last 12 reporting (tax) months/four quarters, as of the date of such recalculation. Such recalculation is carried out by subtracting the amount of the previous calculation and adding the amount according to the current recalculation.
To establish that from July 1, 2019, a coefficient of 1.2 is applied to the overdraft amount.
{Item 10 of Subsection 5 of Section XX supplemented by paragraph four in accordance with Law No. 2628-VIII of 23.11.2018 }
{Subsection 5 of Section XX supplemented by paragraph 10 in accordance with Law No. 909-VIII of 24.12.2015 }
11. The provisions of Article 120-2 of this Code shall not apply in case of violation of the deadlines for registration of excise invoices/adjustment calculations in the Unified Register of Excise Invoices drawn up in the period from March 1, 2016 to April 1, 2016.
The period from March 1, 2016 to April 1, 2016 is a transitional period during which the registration of excise invoices/adjustment calculations in the Unified Register of Excise Invoices is carried out without limiting the volumes calculated according to the formula specified in paragraph 232.3 of Article 232 of this Code.
From April 1, 2016, registration of excise invoices/adjustment calculations in the Unified Register of Excise Invoices is carried out taking into account all the requirements established by this Code.
{Subsection 5 of Section XX supplemented by paragraph 11 in accordance with Law No. 909-VIII of 24.12.2015 }
12. Managers of excise warehouses, in accordance with the requirements of this Code, are obliged to equip excise warehouses with flow meters and/or level meters and register them in the Unified State Register of Flow Meters and Level Meters of Fuel Level in the Tank within the following terms:
excise warehouses where tanks with a total capacity exceeding 20,000 cubic meters are located - no later than July 1, 2019;
excise warehouses where tanks are located, the total capacity of which exceeds 1,000 cubic meters, but does not exceed 20,000 cubic meters, - no later than October 1, 2019;
excise warehouses where tanks are located, the total capacity of which does not exceed 1000 cubic meters, - no later than January 1, 2020.
{Subsection 5 of Section XX supplemented by paragraph 12 in accordance with Law No. 909-VIII of 24.12.2015 ; as amended in accordance with Laws No. 1791-VIII of 20.12.2016 , No. 2245-VIII of 07.12.2017 ; as amended by Law No. 2628-VIII of 23.11.2018 }
13. Temporarily, until February 29, 2016 (inclusive), until the introduction of the electronic fuel sales administration system, establish:
1) operation of excise warehouses at enterprises engaged in fuel production, and representative(s) of the controlling body at such excise warehouse in accordance with the version of this Code that was in force before the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Legislative Acts of Ukraine Regarding Ensuring Balanced Budget Revenues in 2016";
2) for fuel, in the production of which other taxable excisable goods were used as raw materials, the amount of tax payable is reduced by the amount of tax calculated for such raw materials. The amount of tax on raw materials subject to deduction is calculated using the tax rates for such raw materials in force on the day of sale of the fuel. If such amount exceeds the amount of tax on fuel produced from such raw materials, the difference is not reimbursed to the payer;
3) to calculate the reduction in the amount of excise tax in accordance with subparagraph 2 of this paragraph, the taxpayer must receive from the manufacturer or importer of excisable raw materials a certificate on the volume of excisable raw materials supplied (indicating the name of the buyer (recipient) of the excisable raw materials, information on the relevant amounts of excise tax paid and a list of value added tax tax invoices issued for the supply of such raw materials) and confirmation from the controlling authority that the excise tax has been credited to the budget. Such confirmation is provided to the manufacturer or importer of excisable raw materials by the controlling authority at its location within one working day after the application by providing the relevant certificate.
{Subsection 5 of Section XX supplemented by paragraph 13 in accordance with Law No. 909-VIII of 24.12.2015 }
14. Temporarily, from January 1, 2016 to February 29, 2016 (inclusive), establish excise tax rates for the following goods:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Excise tax rate in fixed amounts per unit of sold goods (products)
unit of measurement
rate
2707 50 10 00 2707 50 90 00
mixtures of aromatic hydrocarbons of which 65 vol. % or more (including losses) distils at a temperature of up to 250 °C by the method determined in accordance with ASTM D 86
euros per 1000 kilograms
228
Light distillates:
2710 12 11 10 2710 12 11 20 2710 12 11 90
for specific processing processes
euros per 1000 kilograms
228
2710 12 15 10 2710 12 15 20 2710 12 15 90
for chemical transformations in processes other than those specified in commodity subcategories 2710 12 11 10, 2710 12 11 20, 2710 12 11 90
euros per 1000 kilograms
228
Special gasolines:
2710 12 21 00
white spirit
-"-
228
2710 12 25 00
other special gasolines
-"-
228
Motor gasolines:
2710 12 31 00
aviation gasolines
euros per 1000 kilograms
36
Motor gasolines with a lead content of 0.013 g/l or less:
Other ethers, ether alcohols, ether phenols, ether alcohol phenols, alcohol peroxides, ether peroxides, ketone peroxides (whether or not chemically defined) and their halogenated, sulphonated, nitrated or nitrosated derivatives, except diethyl ether (code according to UKT FEA 2909 11 00 00)
-"-
228
Anti-knock preparations, antioxidants, resin inhibitors, thickeners, anti-corrosive preparations and other prepared additives, for petroleum products (including gasoline) or for other liquids used for the same purposes as petroleum products:
3811 11 10 00 3811 11 90 00 3811 19 00 00
anti-knock agents:
euros per 1000 kilograms
228
3811 90 00 00
others
-"-
283
3826 00 10 00 3826 00 90 00
Biodiesel and its blends (not containing or containing less than 70% by weight of petroleum or petroleum products obtained from bituminous rocks) based on monoalkyl esters of fatty acids
-"-
115
3824 90 97 10
Alternative motor fuel
-"-
141
{Subsection 5 of Section XX supplemented by paragraph 14 in accordance with Law No. 909-VIII of 24.12.2015 }
{Clause 15, subsection 5, section XX was excluded on the basis of Law No. 2611-VIII of 08.11.2018 }
16. Temporarily, until and including December 31, 2029, establish that:
during three consecutive reporting months preceding the month in which excise tax rates on tobacco products, tobacco and industrial tobacco substitutes are increased, the average monthly volume of sales of excise tax stamps to an enterprise-manufacturer and/or importer of tobacco products, tobacco and industrial tobacco substitutes by the seller of excise tax stamps cannot exceed 115 percent of the average monthly volume of sales in the customs territory of Ukraine of tobacco products, tobacco and industrial tobacco substitutes by such an enterprise-manufacturer and/or importer for the previous nine calendar months;
During the three consecutive reporting months preceding the month in which the excise tax rates on tobacco products, tobacco and industrial tobacco substitutes are increased, on the volumes of sales on the domestic market of tobacco products, tobacco and industrial tobacco substitutes by manufacturers and/or imports into the customs territory of Ukraine by importers exceeding 115 percent of the average monthly volume of sales on the domestic market of such products or their imports by such a manufacturing enterprise and/or importer for the previous nine months preceding the three consecutive reporting months preceding the month in which the excise tax rates on tobacco products, tobacco and industrial tobacco substitutes are increased, excise tax shall be paid using a coefficient of 1.5.
{Subsection 5 of Section XX supplemented by paragraph 16 in accordance with Law No. 1791-VIII of 12/20/2016 ; as amended by Law No. 1914-IX of 11/30/2021 }
16 - 1. Temporarily, for the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , to establish that:
during three consecutive reporting months preceding the month in which excise tax rates on tobacco products, tobacco and industrial tobacco substitutes are increased, the average monthly volume of sales of excise tax stamps to an enterprise-manufacturer and/or importer of tobacco products, tobacco and industrial tobacco substitutes by the seller of excise tax stamps cannot exceed 120 percent of the average monthly volume of sales by manufacturers in the customs territory of Ukraine of tobacco products, tobacco and industrial tobacco substitutes by such an enterprise-manufacturer and/or importer for the previous nine calendar months;
During the three consecutive reporting months preceding the month in which the excise tax rates on tobacco products, tobacco and industrial tobacco substitutes are increased, on the volumes of sales on the domestic market of tobacco products by manufacturers and/or imports into the customs territory of Ukraine by importers exceeding 120 percent of the average monthly volume of sales on the domestic market of such products or their imports by such a manufacturing enterprise and/or importer for the previous nine months preceding the three consecutive reporting months preceding the month in which the excise tax rates on tobacco products, tobacco and industrial tobacco substitutes are increased, excise tax shall be paid using a coefficient of 1.5.
{Subsection 5 of Section XX is supplemented by paragraph 16 - 1 in accordance with Law No. 4115-IX of 04.12.2024 }
17. To establish excise tax rates for the following goods from January 1, 2025 to December 31, 2027 inclusive:
1) tobacco products, tobacco and industrial tobacco substitutes:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rates
from January 1, 2025 to December 31, 2025
from January 1, 2026 to December 31, 2026
from January 1, 2027 to December 31, 2027
2401
Tobacco raw materials; tobacco waste
euro per 1 kilogram (net)*
73
77
81
2402 10 00 10
Cigars, including cut-end cigars, containing tobacco
euro per 1 kilogram (net)*
73
77
81
2402 10 00 90
Cigarillos, including cigarillos with cut ends, containing tobacco
euros per 1000 pieces
58
61
64
2402 20 90 10
Cigarettes without a filter, cigarettes
euros per 1000 pieces
58
61
64
2402 20 90 20
Filter cigarettes
euros per 1000 pieces
58
61
64
2403
Other manufactured tobacco and manufactured tobacco substitutes; "homogenized" or "reconstituted" tobacco; tobacco extracts and essences
euro per 1 kilogram (net)*
73
77
81
2404 11 00 10
Tobacco-containing products for electrical heating (TVEN) using an electronically controlled heater
euros per 1000 pieces
70.4
70.8
71, 14;
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rates from January 1, 2025 to December 31, 2027 inclusive
2402 20 90 10
Cigarettes without a filter, cigarettes
percent
12
2402 20 90 20
Filter cigarettes
percent
12
2402 10 00 90
Cigarillos, including cigarillos with cut ends, containing tobacco
percent
12;
2) minimum excise tax liability for payment of excise tax on tobacco products:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rates
from January 1, 2025 to December 31, 2025
from January 1, 2026 to December 31, 2026
from January 1, 2027 to December 31, 2027
2402 20 90 10
Cigarettes without a filter, cigarettes
euros per 1000 pieces
78
82
86
2402 20 90 20
Filter cigarettes
euros per 1000 pieces
78
82
86
2402 10 00 90
Cigarillos, including cigarillos with cut ends, containing tobacco
euros per 1000 pieces
78, but not less than 73 euros per 1 kilogram (net)*
82, but not less than 77 euros per 1 kilogram (net)*
86, but not less than 81 euros per 1 kilogram (net)*;
3) other products containing tobacco, tobacco substitutes, other than liquids used in electronic cigarettes, nicotine-containing products, their substitutes for smoking, sniffing, sucking, chewing or inhaling without burning by heating:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Unit of measurement
Tax rates
from January 1, 2025 to December 31, 2025
from January 1, 2026 to December 31, 2026
from January 1, 2027 to December 31, 2027
2404 91 90 00
Other nicotine-containing products for oral use
euro per 1 kilogram (net)*
73
77
81
2404 11 00 90 2404 19 10 00
Other products containing tobacco, reconstituted tobacco and tobacco substitutes intended for inhalation without burning
euro per 1 kilogram (net)*
73
77
81
2404 99 00 00
Other nicotine-containing products and their substitutes
euro per 1 kilogram (net)*
73
77
81.
{Subsection 5 of Section XX is supplemented by paragraph 17 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Laws No. 2628-VIII of 23.11.2018 , No. 466-IX of 16.01.2020 , No. 3553-IX of 16.01.2024 , No. 4115-IX of 04.12.2024 }
18. The provisions of paragraph 128 - 1.1 of Article 128 - 1 of this Code shall apply:
from July 1, 2019 - to managers of excise warehouses where tanks are located, the total capacity of which exceeds 20,000 cubic meters (except for the manager of the excise warehouse, which until July 1, 2019 did not fall under the definition of a taxpayer in accordance with Clause 212.1 of Article 212 of this Code);
{Paragraph two of clause 18, subsection 5, section XX, as amended by Laws No. 2628-VIII of 11/23/2018 , No. 391-IX of 12/18/2019 }
from October 1, 2019 - to the manager of an excise warehouse, in whose excise warehouse there are tanks with a total capacity exceeding 1,000 cubic meters, but not exceeding 20,000 cubic meters (except for the manager of an excise warehouse, which until July 1, 2019 did not fall under the definition of a taxpayer in accordance with Clause 212.1 of Article 212 of this Code);
{Paragraph three of clause 18, subsection 5, section XX, as amended by Laws No. 2628-VIII of 11/23/2018 , No. 391-IX of 12/18/2019 }
from April 1, 2020 - to managers of excise warehouses where tanks are located, the total capacity of which does not exceed 1,000 cubic meters (except for the manager of the excise warehouse, which until July 1, 2019 did not fall under the definition of a taxpayer in accordance with Clause 212.1 of Article 212 of this Code);
{Paragraph four of clause 18, subsection 5, section XX, as amended by Law No. 391-IX of 18.12.2019 }
from July 1, 2020 - to the manager of an excise warehouse, who until July 1, 2019 did not fall under the definition of a taxpayer in accordance with Clause 212.1 of Article 212 of this Code (regardless of the total capacity of the tanks located at the excise warehouse of such manager), as well as to domestic enterprises engaged in the processing of oil, gas condensate, natural gas and their mixtures in order to extract target components (raw materials), which involves a full technological cycle of their processing into finished products (fuel).
{Clause 18, subsection 5, section XX is supplemented by paragraph five in accordance with Law No. 391-IX of 18.12.2019 }
{Subsection 5 of Section XX supplemented by paragraph 18 in accordance with Law No. 2245-VIII of 07.12.2017 }
19. Temporarily, until December 31, 2018, transactions involving the import into the customs territory of Ukraine and the sale in the customs territory of Ukraine of vehicles equipped exclusively with electric motors (one or more), classified in the commodity subcategory 8703 90 10 10 according to the UKT FEA (including those produced in Ukraine), are exempt from excise tax.
{Subsection 5 of Section XX supplemented by paragraph 19 in accordance with Law No. 2245-VIII of 07.12.2017 }
20. Temporarily, within 90 calendar days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Excise Taxation of Passenger Vehicles", tax rates for vehicles specified in subparagraph 215.3.5 - 1 of paragraph 215.3 of Article 215 of this Code (except for vehicles specified in commodity subcategories 8703 10 18 00, 8703 90 10 10, 8703 90 10 90, 8703 90 90 00 according to the UKT Foreign Economic Activity ), are determined using a coefficient of 0.5.
The coefficient established by this paragraph shall apply to used passenger vehicles imported into the customs territory of Ukraine by an individual for his own use in the amount of one passenger vehicle per such individual.
{Subsection 5 of Section XX supplemented by paragraph 20 in accordance with Law No. 2611-VIII of 08.11.2018 }
21. Electronic documents provided for in subparagraph 230.1.3 of paragraph 230.1 of Article 230 of this Code shall be filled in by the responsible person of the excise warehouse manager based on the readings of flow meters, level meters or in full capacity measures and/or using a tape measure and meter rod or portable (portable) level meter-analyzer, which have a positive result of verification carried out in accordance with the legislation, before the date of registration in the Unified State Register of flow meters and level meters of fuel level in the tank of flow meters and/or level meters installed in the relevant excise warehouse, but no later than the deadlines specified in paragraph 12 of this subsection.
{Subsection 5 of Section XX supplemented by paragraph 21 in accordance with Law No. 2628-VIII of 23.11.2018 }
22. Taxpayers are obliged from May 1, 2019 to June 1, 2019 to register in the electronic fuel sales administration system all excise warehouses, the managers of which such taxpayers will be as of July 1, 2019.
Business entities that will meet the definition of taxpayers as of July 1, 2019 are required to register as taxpayers by July 1, 2019 and register in the electronic fuel sales administration system all excise warehouses that such taxpayers will manage as of July 1, 2019.
{Subsection 5 of Section XX supplemented by paragraph 22 in accordance with Law No. 2628-VIII of 23.11.2018 }
until June 30, 2019 (inclusive), are registered in the Unified Register of Excise Invoices until July 15, 2019 (inclusive);
from July 1 to July 31, 2019 (inclusive), are registered in the Unified Register of Excise Invoices in the period from July 23 to August 15, 2019 (inclusive);
from August 1, 2019, are registered in the Unified Register of Excise Invoices within the terms provided for in paragraph 231.6 of Article 231 of this Code.
To distribute the volumes of fuel residues recorded by taxpayers in the electronic administration system for fuel sales between excise warehouses/mobile excise warehouses, where such volumes of fuel residues are actually located as of July 1, 2019:
a) taxpayers and business entities that, as of July 1, 2019, do not fall under the definition of taxpayers in accordance with Clause 212.1 of Article 212 of this Code and for which, as of July 16, 2019, the volume of fuel residues is recorded in the electronic fuel sales administration system, are obliged to draw up excise invoices in duplicate for such volumes of fuel, the first copy to be registered in the Unified Register of Excise Invoices from July 16 to 20, 2019 (inclusive), indicating in the excise invoices the excise warehouses/mobile excise warehouses where such volumes of fuel were actually located as of July 1, 2019, and the managers of such excise warehouses/mobile excise warehouses by filling in the mandatory details of the excise invoice provided for in subparagraphs "d" and "e" , "z" and "y" of clause 231.1 of Article 231 of this Code;
b) after the taxpayer fulfills the requirements of subparagraph "a" of this paragraph with respect to the relevant manager of the excise warehouse/mobile excise warehouse, such manager of the excise warehouse/mobile excise warehouse is obliged from July 16 to July 22, 2019 (inclusive) to register in the Unified Register of Excise Invoices the second copy of the received excise invoice drawn up by the taxpayer in accordance with subparagraph "a" of this paragraph.
The volumes of fuel or ethyl alcohol imported into the customs territory of Ukraine from July 1 to July 15, 2019 (inclusive) are recorded in the electronic administration system for the sale of fuel and ethyl alcohol in the following sequence:
1) on July 16, 2019, they are automatically credited based on properly completed customs declarations by taxpayers and the conditions for taxation of fuel or ethyl alcohol for each commodity subcategory code in accordance with the UKT Foreign Economic Activity ;
2) from July 16 to 22, 2019 (inclusive) are distributed between mobile excise warehouses used during such importation, based on excise invoices registered in the Unified Register of Excise Invoices, drawn up by the taxpayer - the manager of such mobile excise warehouses.
{Subsection 5 of Section XX supplemented by paragraph 23 in accordance with Law No. 2628-VIII of 23.11.2018 }
24. Within 20 calendar days, starting from July 1, 2019, the taxpayer is obliged to submit to the regulatory authority an act of inventorying the volumes of ethyl alcohol residues as of the beginning of July 1, 2019, indicating the addresses of the facilities where the corresponding volumes of ethyl alcohol residues are stored, a list of tanks where the volumes of ethyl alcohol residues are stored, their technical parameters (physical capacity corresponding to technical passports), title documents for the relevant facilities and documents certifying the legal grounds for the operation of such facilities. The regulatory authority shall take into account the volumes of ethyl alcohol residues indicated in such an inventory act in the formula specified in paragraph 232.3 of Article 232 of this Code as the volume for which the taxpayer has the right to register excise invoices and/or adjustment calculations in the system of electronic administration of fuel and ethyl alcohol sales.
The permanent representative of the controlling authority at the excise warehouse participates in the inventory of ethyl alcohol residues and certifies the act of conducting the inventory of ethyl alcohol residues.
The form of the act of inventorying the volume of ethyl alcohol residues is approved by the central executive body that ensures the formation and implementation of state financial policy.
{Subsection 5 of Section XX supplemented by paragraph 24 in accordance with Law No. 2628-VIII of 23.11.2018 }
25. The provisions of paragraphs 120 - 2 .1-120 - 2 .3 of Article 120 - 2 do not apply to excise invoices/adjustment calculations that the payer is required to prepare from July 1 to November 30, 2019.
The norms of clause 128 - 1.2 of Article 128 - 1 shall apply from October 1, 2019, and the norms of clause 128 - 1.3 of Article 128 - 1 shall apply from January 1, 2020 (except for penalties for failure to submit electronic documents from excise warehouses where tanks are located, the total capacity of which does not exceed 1,000 cubic meters, and from excise warehouses whose managers did not fall under the definition of a taxpayer until July 1, 2019 in accordance with clause 212.1 of Article 212 of this Code).
{Paragraph two of clause 25, subsection 5, section XX, as amended by Law No. 391-IX of 18.12.2019 }
The provisions of paragraph 128 - 1.3 of Article 128 - 1 of this Code for failure to submit electronic documents from excise warehouses where tanks with a total capacity of not more than 1000 cubic meters are located shall apply from April 1, 2020.
{Clause 25, subsection 5, section XX supplemented by paragraph three in accordance with Law No. 391-IX of 18.12.2019 }
{Subsection 5 of Section XX supplemented by paragraph 25 in accordance with Law No. 2628-VIII of 11/23/2018 ; as amended by Law No. 129-IX of 09/20/2019 }
26. Temporary confirmation of the fact of the intended use of aviation gasoline or jet fuel for the repayment of tax bills issued from January 1 to November 30, 2019 (inclusive) by producers and importers of aviation gasoline or jet fuel in accordance with Clause 229.8 of Article 229 of this Code shall be carried out by such producers and importers submitting to the regulatory authority - the bill holder copies of primary documents confirming the implementation of transactions with:
{Paragraph one of clause 26, subsection 5, section XX, as amended by Law No. 129-IX of September 20, 2019 }
1) sale (fueling of aircraft) of aviation gasoline or jet fuel by business entities that provide aviation fuel in accordance with the current certificate of compliance with the requirements of the aviation rules of Ukraine for ground handling, issued by the authorized body for civil aviation;
2) sale of aviation gasoline or jet engine fuel to aircraft manufacturing entities subject to the provisions of Article 2 of the Law of Ukraine "On the Development of the Aircraft Manufacturing Industry";
3) sale of aviation gasoline or jet fuel to customers who have made a purchase to meet the needs of the state or a territorial community in accordance with the Law of Ukraine "On Public Procurement";
4) sale of aviation gasoline or fuel for jet engines to enterprises, institutions and organizations of the state reserve system.
{Subsection 5 of Section XX supplemented by paragraph 26 in accordance with Law No. 2628-VIII of 23.11.2018 }
27. To establish that the requirements for equipment with flow meters of domestic enterprises engaged in the processing of oil, gas condensate, natural gas and their mixtures in order to extract target components (raw materials), which involves a full technological cycle of their processing into finished products (fuel), and the requirements for such enterprises for the daily formation of data on the daily actual volume of fuel sold, as well as the liability for such enterprises for violation of such requirements, shall apply from January 1, 2020.
{Subsection 5 of Section XX supplemented by paragraph 27 in accordance with Law No. 2628-VIII of 23.11.2018 }
28. Taxpayers have the right to register in the Unified Register of Excise Invoices a second copy of excise invoices drawn up in accordance with the procedure provided for in paragraph 23 of this subsection, provided that the first copy of such excise invoice is registered in the Unified Register of Excise Invoices in accordance with paragraph 23 of this subsection.
In the event that the excise invoice drawn up in accordance with paragraph 23 of this subsection, the first copy of which is registered in the Unified Register of Excise Invoices, and the second copy is not registered in the Unified Register of Excise Invoices, contains incorrect details of the person receiving the fuel, or the details of the excise warehouse or mobile excise warehouse to which the fuel was received, specified in subparagraphs "z" and "y" of paragraph 231.1 of Article 231 of this Code:
a) the payer who prepared the first copy of the excise invoice shall prepare a second copy of such invoice, in which he shall indicate the correct details of the person receiving the fuel or the excise warehouse/mobile excise warehouse to which the fuel was received, and on the day of preparation shall send such copy to the person receiving the fuel;
b) the person receiving the fuel shall register the second copy of the excise invoice in the Unified Register of Excise Invoices no later than three calendar days after the day of receipt of the second copy of the excise invoice.
{Subsection 5 of Section XX supplemented by paragraph 28 in accordance with Law No. 129-IX of 20.09.2019 }
29. A business entity that, before July 1, 2019, did not fall under the definition of taxpayers in accordance with Clause 212.1 of Article 212 of this Code, and has been registered as a taxpayer since July 1, 2019, has the right to submit a one-time application, until January 20, 2020 inclusive, to replenish the remaining amount of fuel in the electronic administration system for the sale of fuel and ethyl alcohol without paying excise tax, separately for each excise warehouse/mobile excise warehouse, and an application for a documentary check by the supervisory authority of the accuracy of the data specified in such an application, in the event of:
1) if the volumes of fuel specified in such an application simultaneously meet the following conditions:
were in storage by such a business entity in its excise warehouse as of July 1, 2019 and belonged to another business entity that did not fall under the definition of a taxpayer before July 1, 2019;
were indicated in excise invoices drawn up for transactions for the sale of such volumes of fuel to their owner, which were registered in the Unified Register of Excise Invoices before July 1, 2019;
were not recorded in the electronic administration system for fuel sales as of July 1, 2019;
2) if the volumes of fuel specified in such an application simultaneously meet the following conditions:
were received by such a business entity after July 1, 2019, and sold by the taxpayer until June 30, 2019 inclusive;
were indicated in excise invoices drawn up for transactions for the sale of such volumes of fuel to their owner, which were registered in the Unified Register of Excise Invoices before July 1, 2019;
were not recorded in the electronic fuel sales administration system as of July 1, 2019.
The application for replenishment of the remaining fuel volume, drawn up by the taxpayers specified in subparagraph 1 of this paragraph, additionally indicates the EDRPOU code (for legal entities) or the registration number of the taxpayer's account card (for individuals) of the business entity whose fuel is stored in accordance with the concluded storage agreements.
The controlling authority, within 10 calendar days, shall take into account, in the formula specified in Clause 232.3 of Article 232 of this Code, the volume of fuel confirmed by the results of the documentary inspection conducted by the controlling authority as the volume for which the taxpayer has the right to register excise invoices and/or adjustment calculations in the Unified Register of Excise Invoices.
Documentary verification of the compliance of the data in the application submitted in accordance with this paragraph for replenishment of the fuel balance with actual data and/or accounting data of the enterprise, the fact of supply and reflection of sales volumes in the electronic fuel sales administration system by July 1, 2019 shall be assigned by the supervisory authority in accordance with the procedure established by law, no later than April 1, 2020.
{Subsection 5 of Section XX supplemented by paragraph 29 in accordance with Law No. 391-IX of 18.12.2019 }
29 - 1. Temporarily, until April 30, 2020, establish that:
1) the effect of paragraphs three and four of subparagraph 229.1.8 of paragraph 229.1 of Article 229 of this Code does not apply to the production of disinfectants (code according to the UKT FEA 3808 94 90 00) provided that tax posts are established at such an enterprise;
2) each point of sale of disinfectants (code according to the UKT Foreign Economic Activity 3808 94 90 00) must be equipped with means of accounting for manufactured products, which must comply with the requirements of the legislation and have a positive result of verification or conformity assessment carried out in accordance with the legislation;
3) state-owned enterprises that are simultaneously producers of denatured ethyl alcohol and disinfectants (code according to the UKT FEA 3808 94 90 00) have the right to use the denatured ethyl alcohol they produce for the production of disinfectants (code according to the UKT FEA 3808 94 90 00) without the presence of registered flow meters for ethyl alcohol on the production line of such disinfectants, provided that each point of sale of disinfectants is equipped with means of accounting for manufactured products that meet the requirements of the legislation and have a positive result of verification or conformity assessment carried out in accordance with the legislation;
4) excise warehouses on the territory of which denatured ethyl alcohol is produced for the production of disinfectants (code according to the UKT Foreign Economic Activity 3808 94 90 00) must be equipped at each point of receipt and release of undenatured ethyl alcohol located at the excise warehouse with flow meters for ethyl alcohol registered in the Unified State Register of Flow Meters for the Volume of Produced Ethyl Alcohol, as well as means of accounting for denaturing additives, which must meet the requirements of the legislation and have a positive result of verification or conformity assessment carried out in accordance with the legislation;
5) business entities that produce denatured ethyl alcohol and/or disinfectants (code according to the Ukrainian Classification of Foreign Economic Activities 3808 94 90 00), accounting for denatured ethyl alcohol is carried out using methods certified in accordance with the legislation;
6) electronic documents by manufacturers of denatured ethyl alcohol for the production of disinfectants (code according to the UKT FEA 3808 94 90 00) and manufacturers of disinfectants (code according to the UKT FEA 3808 94 90 00) are filled out taking into account subparagraphs 4 and 5 of paragraph 29 - 1 , subsection 5, section XX of this Code by transferring data from ethyl alcohol flow meters and means of accounting for manufactured products;
7) ethyl alcohol flow meters and the means of accounting for produced products specified in this paragraph must comply with the requirements of the legislation and have a positive result of verification or conformity assessment carried out in accordance with the legislation. In the absence of a positive result of verification or conformity assessment of ethyl alcohol flow meters and means of accounting for finished products, for the purposes of this Code, ethyl alcohol flow meters and means of accounting for produced products are considered unestablished;
8) a representative of the regulatory authority at the excise warehouse of an enterprise that produces denatured ethyl alcohol for the production of disinfectants (code according to the Ukrainian Customs Union Foreign Economic Activity Code 3808 94 90 00), as well as at an enterprise that produces disinfectants:
a) monitors compliance with the conditions for denaturing ethyl alcohol;
b) participates in the preparation of the Act of Denaturation of Ethyl Alcohol, which indicates the volume of undenatured ethyl alcohol in decalitres of 100 percent alcohol, brought to a temperature of 20° C, which was used to produce denatured ethyl alcohol, and the number of denaturing additives used during denaturation;
c) participates in the preparation of the Act of Production of Disinfectants (code according to the UKT Foreign Economic Activity 3808 94 90 00), which indicates the volume of denatured ethyl alcohol in decalitres of 100 percent alcohol, brought to a temperature of 20° C, the number of added ingredients and the quantity of finished products.
{Subsection 5 of Section XX supplemented by paragraph 29 - 1 in accordance with Law No. 540-IX of 30.03.2020 }
29 - 2. The repayment terms of tax bills issued in accordance with paragraph 229.8 of Article 229 of this Code by manufacturers or importers of jet fuel (codes according to the UKT FEA 2710 12 70 00, 2710 19 21 00) and/or aviation gasoline (code according to the UKT FEA 2710 12 31 00), which fall on the period from March 1 to June 30, 2020, are extended until the ninetieth calendar day from the date of resumption of acceptance and departure of aircraft performing passenger transportation in Ukraine.
{Paragraph one of clause 29 - 2 , subsection 5, section XX, as amended by Law No. 591-IX of 13.05.2020 }
In the event of confirmation by the importer or manufacturer who issued the tax bill, before the deadline for repayment of tax bills established by the first paragraph of this paragraph, of the fact of the intended use of aviation gasoline or jet fuel, the repayment of such tax bills shall be carried out in the manner established by paragraph 229.8 of Article 229 of this Code:
{Paragraph two of clause 29 - 2 , subsection 5, section XX, as amended by Law No. 591-IX of 13.05.2020 }
without paying the amounts of excise tax specified in such tax bills;
without the application of fines established by subparagraph 229.8.12 of paragraph 229.8 of Article 229 of this Code.
If the tax bill is not repaid by the deadline for repayment of tax bills established by the first paragraph of this paragraph, the bill holder, within five business days following the last day of the tax bill repayment period specified in this paragraph, shall protest such bill for non-payment in accordance with the law and within one business day from the date of the protest, shall apply to the bank that avalized the bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the bill holder's application with the protested tax bill.
{Paragraph five of clause 29 - 2 , subsection 5, section XX, as amended by Law No. 591-IX of 05/13/2020 }
In the absence of confirmation by the deadline for repayment of tax bills established by paragraph one of this paragraph of the intended use of aviation gasoline or jet fuel by the importer or manufacturer who issued the tax bill, such importer or manufacturer shall be charged a fine in the amount of 50 percent of the amount of excise tax, which is calculated based on the volumes of aviation gasoline or jet fuel for which there is no confirmation of intended use, and the excise tax rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code, with the application of an increasing coefficient of 10.
{Paragraph six of clause 29 - 2 , subsection 5, section XX, as amended by Law No. 591-IX of 05/13/2020 }
{Subsection 5 of Section XX supplemented by paragraph 29 - 2 in accordance with Law No. 540-IX of 30.03.2020 }
{Item 29 - 3 of Subsection 5 of Section XX was excluded pursuant to Law No. 3219-IX of 06/30/2023 }
30. Excise tax stamps printed before January 1, 2021, which do not indicate the number of units in a pack (package), must be used before July 1, 2021, and tobacco products marked with such stamps are in circulation until their full sale within the shelf life.
{Subsection 5 of Section XX supplemented by paragraph 30 in accordance with Law No. 466-IX of January 16, 2020 }
31. Temporarily, for the period of the anti-terrorist operation and/or the implementation of measures to ensure the conduct of the Joint Forces (JFO) operation, the following transactions are exempted from excise tax: the free transfer into possession and use to entities participating in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, carried out through the conduct of the Joint Forces (JFO) operation, to the prosecutor's offices in the Donetsk and Luhansk regions: confiscated excisable goods specified in subparagraphs 215.3.5-215.3.5-2 of paragraph 215.3 of Article 215 of this Code (hereinafter referred to as vehicles for this paragraph); vehicles recognized as ownerless; vehicles for which the owner has not applied by the end of the storage period; vehicles that have become state property by inheritance or other legal grounds.
In the event of the sale on the customs territory of Ukraine of vehicles, the free transfer of which is exempt from taxation in accordance with this paragraph, the tax shall be paid by persons who sell or transfer such vehicles into possession, use or disposal, no later than the date of such sale, simultaneously with the payment of value added tax at the rates in effect at the time of the free transfer of such excisable vehicles.
{Subsection 5 of Section XX supplemented by paragraph 31 in accordance with Law No. 466-IX of January 16, 2020 }
32. Business entities that were not subject to the definition of taxpayers before May 23, 2020, and from May 23, 2020 are subject to the definition of taxpayers in accordance with subparagraph 212.1.15 of paragraph 212.1 of Article 212 of this Code, which import into the customs territory of Ukraine or sell liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1,000 liters (codes according to the UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to UKT FEA 3814 00 90 90):
1) are obliged until December 31, 2020 inclusive:
register as payers of excise tax on fuel sales and register in the electronic administration system for fuel and ethyl alcohol sales all excise warehouses managed by such taxpayers;
equip all excise warehouses with flow meters and/or level meters and register them in the Unified State Register of Flow Meters and Level Meters of Fuel Level in the Tank;
2) have the right to submit a one-time application for replenishment of the remaining fuel volume/adjustment to the application for replenishment of the remaining fuel volume in the electronic administration system for the sale of fuel and ethyl alcohol as of May 23, 2020, for each fuel code in accordance with the UKT FEA and each excise warehouse/mobile excise warehouse in the event of further use of the fuel specified in this paragraph exclusively for:
own consumption of liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1000 liters (codes according to UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to UKT ZEA 3814 00 90 90). This standard does not apply to the use of fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, spark-ignition internal combustion engines, and crank-type internal combustion engines;
own consumption of fuel that was transferred (released, shipped) by the excise tax payer to such business entities or imported by such business entity into the customs territory of Ukraine. This norm does not apply to the fuel specified in the second paragraph of this subparagraph;
industrial processing (except for the production of excisable goods specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code);
3) are obliged to prepare excise invoices for the total volumes of fuel specified in subparagraph 2 of this paragraph, used for own consumption and/or industrial processing, by January 15, 2021 inclusive, for each excise warehouse/mobile excise warehouse and each commodity subcategory code in accordance with the UKT FEA and register them in the Unified Register of Excise Invoices;
4) have the right to submit a one-time application for replenishment of the remaining fuel volume/adjustment to the application for replenishment of the remaining fuel volume in the electronic administration system for the sale of fuel and ethyl alcohol as of May 23, 2020, for each fuel code in accordance with the UKT FEA and each excise warehouse/mobile excise warehouse, which is registered with the debiting of the paid excise tax from the cash register card. This norm applies to the volume of fuel that will subsequently be used for purposes other than those specified in subparagraph 2 of this paragraph;
5) are obliged to prepare excise invoices for the total volumes of fuel specified in subparagraph 4 of this paragraph, sold in the period from May 23, 2020 to December 31, 2020, inclusive, for each excise warehouse/mobile excise warehouse and each commodity subcategory code in accordance with the UKT FEA and register them in the Unified Register of Excise Invoices.
The business entities specified in this paragraph include:
until December 31, 2020 inclusive, penalties provided for in paragraph 117.3 of Article 117 (for carrying out fuel sales operations without registration by excise tax payers), paragraphs 128 - 1 .2 (for lack of registration of excise warehouses) and 128 - 1 .3 (for failure to submit electronic documents from excise warehouses) of Article 128 - 1 of this Code shall not apply;
, penalties provided for in Article 120-2 of this Code for violation of the deadlines for registration of excise invoices drawn up for fuel sales transactions carried out from May 23, 2020 to December 31, 2020 inclusive shall not apply;
until December 31, 2020 inclusive, penalties provided for in paragraph 128 - 1.1 of Article 128 - 1 of this Code shall not apply for failure to equip tanks containing fuel with flow meters and/or level meters and for failure to register them in the Unified State Register of Flow Meters and Level Meters of Fuel Level in the Tank.
{Subsection 5 of Section XX supplemented by paragraph 32 in accordance with Law No. 1117-IX of 17.12.2020 }
33. Business entities that, until May 23, 2020, fell under the definition of excise tax payers in accordance with subparagraph 212.1.15 of paragraph 212.1 of Article 212 of this Code and as of May 23, 2020 had residues of liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1,000 liters (codes according to the UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to UKT FEA 3814 00 90 90):
1) are obliged until December 31, 2020 inclusive:
register in the electronic administration system for the sale of fuel and ethyl alcohol all excise warehouses that store liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1,000 liters (codes according to the UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to the UKT ZEA 3814 00 90 90);
equip all tanks storing liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1,000 liters (codes according to the UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to the UKT ZEA 3814 00 90 90), with flow meters and/or level meters and register them in the Unified the state register of flow meters and fuel level meters in the tank;
2) have the right to submit a one-time application for replenishment of the remaining fuel volume/adjustment to the application for replenishment of the remaining fuel volume in the electronic administration system for the sale of fuel and ethyl alcohol as of May 23, 2020, for each fuel code in accordance with the UKT FEA and each excise warehouse/mobile excise warehouse in the event of further use of the fuel specified in this paragraph exclusively for:
own consumption of liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1000 liters (codes according to UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to UKT ZEA 3814 00 90 90). This standard does not apply to the use of fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, spark-ignition internal combustion engines, and crank-type internal combustion engines;
industrial processing (except for the production of excisable goods specified in subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code);
3) are obliged to prepare excise invoices for the total volumes of fuel specified in subparagraph 2 of this paragraph, used for own consumption and/or industrial processing, by January 15, 2021 inclusive, for each excise warehouse/mobile excise warehouse and each commodity subcategory code in accordance with the UKT FEA , and register them in the Unified Register of Excise Invoices;
4) have the right to submit a one-time application for replenishment of volumes of liquid fuels based on gas oils (diesel fuel) for which the excise tax rate is set at EUR 213.50 per 1,000 liters (codes according to the UKT FEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to the UKT FEA 3814 00 90 90) until December 31, 2020 inclusive. fuel balance/adjustment to the application for replenishment of fuel balance volumes in the electronic administration system for the sale of fuel and ethyl alcohol as of May 23, 2020 for each fuel code according to the UKT FEA and each excise warehouse/mobile excise warehouse, which is registered with the debiting of the paid excise tax from the cash register card. This norm applies to fuel volumes that will subsequently be used for purposes other than those specified in subparagraph 2 of this paragraph;
5) are obliged to prepare excise invoices for the total volumes of fuel specified in subparagraph 4 of this paragraph, sold in the period from May 23, 2020 to December 31, 2020, inclusive, for each excise warehouse/mobile excise warehouse and for each commodity subcategory code in accordance with the UKT FEA and register them in the Unified Register of Excise Invoices.
The business entities specified in this paragraph include:
until December 31, 2020 inclusive, penalties provided for in paragraphs 128 - 1 .2 (for failure to register excise warehouses) and 128 - 1 .3 (for failure to submit electronic documents from excise warehouses) of Article 128 - 1 of this Code shall not apply;
until January 15, 2021 inclusive, penalties provided for in Article 120 - 2 of this Code shall not apply for violation of the deadlines for registration of excise invoices drawn up for transactions on the sale of liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1000 liters (codes according to the UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to with UKT FEA 3814 00 90 90), carried out from May 23, 2020 to December 31, 2020 inclusive;
until December 31, 2020 inclusive, the penalties provided for in paragraph 128 - 1.1 of Article 128 - 1 of this Code shall not apply for failure to equip tanks containing the fuel specified in the first paragraph of this paragraph with flow meters and/or level meters and for failure to register them in the Unified State Register of Flow Meters and Level Meters of Fuel Level in the Tank.
{Subsection 5 of Section XX supplemented by paragraph 33 in accordance with Law No. 1117-IX of 17.12.2020 }
34. Business entities specified in clause 32 of this subsection, which after May 23, 2020 and before these clauses of the Code come into force, submitted applications for replenishment of the remaining fuel volumes/adjustments to the application for replenishment of the remaining fuel volumes in the electronic administration system for the sale of fuel and ethyl alcohol as of May 23, 2020 for each fuel code in accordance with the Ukrainian Customs Code of Foreign Economic Activities and each excise warehouse/mobile excise warehouse that will subsequently be used/used for the purposes specified in subparagraph 2 of clause 32 of this subsection, may submit, once: calculations for adjusting the excise invoice, which cancel the transactions specified in the excise invoice being adjusted, - for the volumes of fuel used for the purposes specified in subparagraph 2 of clause 32 of this subsection; within the limits of fuel balances, which are counted in the system of electronic administration of fuel and ethyl alcohol sales, may submit adjustments to the application for replenishment of fuel balance volumes submitted with payment of excise tax, which reduces the volume of fuel specified in the application for replenishment of fuel balance volumes, the indicators of which are adjusted; take into account the indicators of calculations of excise invoice adjustments and adjustments to the application for replenishment of fuel balance volumes in excise tax declarations for calendar periods in which excise invoices and applications for replenishment of fuel balance volumes were taken into account, the indicators of which were adjusted by such calculations of excise invoice adjustments and adjustments to the application for replenishment of fuel balance volumes. The amounts of overpaid monetary obligations for excise tax that arise as a result of such consideration are subject to refund in accordance with the procedure established by Article 43 of this Code. Business entities specified in paragraph 33 of this subsection, which after May 23, 2020 and before the entry into force of these paragraphs of the Code submitted, with payment of excise tax, applications for replenishment of the remaining fuel volumes/adjustments to the application for replenishment of the remaining fuel volumes of liquid fuels based on gas oils (diesel fuel), for which the excise tax rate is set at EUR 213.50 per 1,000 liters (codes according to the UKT ZEA 2710 19 62 00-2710 19 68, 2710 19 71 00, 2710 19 75 00, 2710 19 99 00, 2710 20 31 00, 2710 20 35 00, 2710 20 39 00), solvents or thinners based on methanol, other ready-made mixtures based on methanol (code according to the UKT FEA 3814 00 90 90) in the system of electronic administration of the sale of fuel and ethyl alcohol as of May 23, 2020 for each fuel code according to the UKT FEA and each excise warehouse/mobile excise warehouse, which will subsequently be used/used for the purposes specified in subparagraph 2 of clause 33 of this subsection, once: may submit calculations for adjusting the excise invoice, which cancel the operations specified in the excise invoice being adjusted, - for the volumes of fuel used for the purposes specified in subparagraph 2 of clause 33 of this subsection; within the limits of fuel balances, which are recorded in the electronic administration system for the sale of fuel and ethyl alcohol, may submit adjustments to the application for replenishment of the fuel balance submitted with the payment of excise tax, which reduces the volume of fuel specified in the application for replenishment of the fuel balance, the indicators of which are being adjusted; take into account the indicators of the calculations of the excise invoice adjustment and the adjustments to the application for replenishment of the fuel balance in the excise tax declarations for the calendar periods in which the excise invoices and applications for replenishment of the fuel balance were taken into account, the indicators of which were adjusted by such calculations of the excise invoice adjustment and adjustments to the application for replenishment of the fuel balance. The amounts of overpaid monetary obligations for excise tax that arise as a result of such consideration are subject to refund in accordance with the procedure established by Article 43 of this Code.
{Subsection 5 of Section XX supplemented by paragraph 34 in accordance with Law No. 1117-IX of 17.12.2020 }
35. The provisions of subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code regarding base oils and other lubricants, other distillates, which during fractional distillation according to the ISO 3405 method (or the similar ASTM D86 method) at a temperature of 350° C and atmospheric pressure distil no more than 35 percent of volume units, in the version in force since August 8, 2020, shall apply from May 23, 2020.
{Subsection 5 of Section XX supplemented by paragraph 35 in accordance with Law No. 1117-IX of 17.12.2020 }
36. Temporarily, within 180 days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Collection of Taxes and Duties, Other Mandatory Payments, the Object of Taxation of which are Vehicles", the amount of excise tax shall be determined by the taxpayer to whom this paragraph applies, at a rate calculated according to the following formula:
Rate = Base rate + Ve + Fe,
Base rate - tax rate in euros per 1 vehicle unit, determined based on the number of years that have passed from the year of manufacture of the vehicle to the year of determining the tax rate and is:
Number of years since the vehicle was manufactured
Base rate, euros
5-9
0
10
25
11
50
12
75
13
100
14
125
15 and more
150
Vе - tax rate in euros per 1 unit of vehicle, determined by multiplying the cylinder capacity of the internal combustion engine of the relevant vehicle in cubic centimeters by a coefficient equal to:
0.25 euros per 1 cubic centimeter of engine cylinder capacity - for a vehicle with an internal combustion engine capacity of up to 2,000 cubic centimeters inclusive;
0.2 euros per 1 cubic centimeter of engine cylinder capacity - for a vehicle with an internal combustion engine capacity from 2001 to 3000 cubic centimeters inclusive;
0.25 euros per 1 cubic centimeter of engine cylinder capacity - for a vehicle with an internal combustion engine capacity of 3001 to 4000 cubic centimeters inclusive;
0.35 euros per 1 cubic centimeter of engine cylinder capacity - for a vehicle with an internal combustion engine capacity of 4001 to 5000 cubic centimeters inclusive;
0.5 euros per 1 cubic centimeter of engine cylinder capacity - for a vehicle with an internal combustion engine capacity of more than 5,000 cubic centimeters;
Fе - tax rate in euros per 1 vehicle unit, which is:
for vehicles equipped with a spark-ignition internal combustion engine and a crank mechanism - 0.0 euros;
for vehicles equipped with a compression-ignition internal combustion engine (diesel or semi-diesel), - 100.0 euros;
for vehicles equipped with a spark-ignition internal combustion engine and a crank mechanism or a compression-ignition internal combustion engine (diesel or semi-diesel) and an electric motor (one or more), - 0.0 euros.
This clause applies to vehicles for personal use (in the amount of no more than one unit per commodity item), which were in use and more than five years have passed since the year of manufacture, which are classified under commodity items 8703, 8704 (with a total weight of up to 3.5 tons) according to the UKT Foreign Economic Activity and as of December 31, 2020 were under the customs regime of temporary import or transit.
This clause does not apply to vehicles if they do not meet the environmental standards of "EURO-2" and above and/or originate from a country recognized as an occupying state in accordance with the law of Ukraine or recognized as an aggressor state in relation to Ukraine in accordance with the law, and/or the last country of state registration of which is such an occupying state (aggressor).
The period provided for in paragraph one of this paragraph for participants in hostilities specified in paragraphs 19 and 20 of part one of Article 6 of the Law of Ukraine "On the Status of War Veterans, Guarantees of Their Social Protection", provided that there is documentary confirmation of their stay for more than 90 days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Collection of Taxes and Duties, Other Mandatory Payments, the Object of Taxation of which are Vehicles" directly in the territory of the Joint Forces Operation (JFO), is 270 days.
{Subsection 5 of Section XX supplemented by paragraph 36 in accordance with Law No. 1402-IX of 04/15/2021 - enters into force on 06/15/2021; with amendments made in accordance with Law No. 1914-IX of 11/30/2021 }
37. To establish that for tax liabilities from the environmental tax that have arisen:
from January 1, 2022 to December 31, 2022 inclusive, the tax rates shall be 30 percent of the rates provided for in paragraphs 245.1 and 245.2 of Article 245 of this Code;
from January 1, 2023 to December 31, 2023 inclusive, tax rates shall be 60 percent of the rates provided for in paragraphs 245.1 and 245.2 of Article 245 of this Code;
from January 1, 2024 to December 31, 2024 inclusive, tax rates shall be 90 percent of the rates provided for in paragraphs 245.1 and 245.2 of Article 245 of this Code;
from January 1, 2025, tax rates shall be 100 percent of the rates provided for in paragraphs 245.1 and 245.2 of Article 245 of this Code.
{Subsection 5 of Section XX supplemented by paragraph 37 in accordance with Law No. 1914-IX of 11/30/2021 }
38. For taxpayers defined in subparagraph 212.1.13 of paragraph 212.1 of Article 212 of this Code, who are producers of electricity, who are assigned special obligations to ensure general public interests in accordance with the Law of Ukraine "On the Electricity Market", the date of occurrence of tax liabilities for excise tax on transactions for the sale of electricity is:
temporarily, from January 1, 2022 to December 31, 2022 inclusive, - the date of crediting (receiving) funds to the bank account or the date of receiving other types of compensation for sold electricity;
from January 1, 2023 - the date of drawing up a document certifying the fact of electricity supply, in accordance with paragraph 216.10 of Article 216 of this Code (for electricity sold starting from January 1, 2023) and the date of crediting (receiving) funds to an account with a bank/non-bank payment service provider or the date of receiving other types of compensation (for electricity sold in the period from January 1, 2022 to December 31, 2022 inclusive).
{Paragraph three of clause 38 of subsection 5 of section XX as amended by Laws No. 2173-IX of 01.04.2022 , No. 2888-IX of 12.01.2023 }
{Subsection 5 of Section XX supplemented by paragraph 38 in accordance with Law No. 1914-IX of 11/30/2021 }
38 - 1. For taxpayers defined in subparagraph 212.1.13 of paragraph 212.1 of Article 212 of this Code, who are producers of electricity, the date of occurrence of tax liabilities for excise tax on transactions for the sale of electricity is:
from March 1, 2022 until the termination or cancellation of the martial law or state of emergency in Ukraine - the date of crediting (receiving) funds to an account with a bank/non-bank payment service provider or the date of receiving other types of compensation for sold electricity;
{Paragraph two of clause 38 - 1 , subsection 5, section XX, as amended by Law No. 2888-IX of 12.01.2023 }
from the first tax period following the period of termination or cancellation of the state of war or emergency in Ukraine - the date of drawing up a document certifying the fact of the supply of electricity in accordance with paragraph 216.10 of Article 216 of this Code (for electricity sold starting from the first tax period following the period of termination or cancellation of the state of war or emergency in Ukraine), and the date of crediting (receiving) funds to an account with a bank/non-bank payment service provider or the date of receiving other types of compensation (regarding electricity sold in the period from March 1, 2022 to the last tax period in which the state of war or emergency in Ukraine was terminated or canceled, inclusive).
{Paragraph three of clause 38 - 1 , subsection 5, section XX, as amended by Law No. 2888-IX of 12.01.2023 }
{Subsection 5 of Section XX supplemented by paragraph 38 - 1 in accordance with Law No. 2173-IX of 01.04.2022 }
39. To establish that revenues from the payment of the environmental tax for carbon dioxide emissions are directed to measures leading to the reduction of carbon dioxide emissions (decarbonization) by industries classified in section C "Manufacturing industry" and section D "Supply of electricity, gas, steam and conditioned air" of the National Classifier of Ukraine "Classification of types of economic activity" DK 009:2010 , in the manner established by the Budget Code of Ukraine , in the amount of not less than 70 percent of revenues from the payment of the environmental tax of the relevant section.
{Subsection 5 of Section XX supplemented by paragraph 39 in accordance with Law No. 1914-IX of 11/30/2021 }
40. Temporarily, until January 1, 2023, payment of excise tax on the sale by retail business entities of excisable goods (tobacco products, tobacco and industrial tobacco substitutes) produced before April 1, 2022, including by foreign manufacturers, and not sold to end consumers before April 1, 2022, shall be carried out in accordance with the procedure and under the conditions that were in effect before April 1, 2022.
{Subsection 5 of Section XX is supplemented by paragraph 40 in accordance with Law No. 2139-IX of March 15, 2022 - regarding the entry into force and operation of the Law, see paragraph 1 of Section II}
41. Temporarily, for the period until the termination or cancellation of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , but no longer than until July 1, 2023, to establish excise tax rates for the following goods:
Product (product) code according to the UKT Foreign Economic Activity Code
Description of goods (products) according to the UKT Foreign Economic Activity
Excise tax rate in fixed amounts per unit of sold goods (products)
unit of measurement (volume in liters, reduced to t 15° C)
rate
Motor gasolines:
Motor gasolines with a lead content of 0.013 g/l or less:
Liquefied gas (propane or a mixture of propane and butane) and other gases
euros per 1000 liters
52.0
2901 10 00 10
Butane, isobutane
euros per 1000 liters
52.0
3826 00 10 00 3826 00 90 00
Biodiesel and its blends, not containing or containing less than 70% by weight of petroleum or petroleum products obtained from bituminous rocks
euros per 1000 liters
100.0
3824 99 96 10
Alternative motor fuel
-"-
100.0
{Subsection 5 of Section XX supplemented by paragraph 41 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 2618-IX of September 21, 2022 }
42. Temporarily, for the period of implementing measures to ensure national security and defense, repelling and deterring armed aggression of the Russian Federation against Ukraine and/or introducing martial law in accordance with the legislation, transactions on the import into the customs territory of Ukraine and the sale in the customs territory of Ukraine of armored vehicles classified under codes 8702 10 19 90, 8702 90 11 00, 8703 according to the UKT FEA, quadricycles and all-terrain vehicles classified under commodity positions 8703 , 8704 according to the UKT FEA, the final recipient of which, in accordance with the end-user certificate or in accordance with the terms of the contract, is determined to be law enforcement agencies, the Ministry of Defense of Ukraine, the Armed Forces of Ukraine and other military formations, voluntary formations of territorial communities formed in accordance with the laws of Ukraine, other entities carrying out combat terrorism in accordance with the law and/or participate in implementing measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation against Ukraine.
{Subsection 5 of Section XX supplemented by paragraph 42 in accordance with Law No. 2173-IX of 01.04.2022 ; as amended in accordance with Law No. 4967-IX of 03.09.2026 }
43. Temporarily, for the period of the legal regime of martial law and a state of emergency in Ukraine, the production and storage of other types of ethyl alcohol is permitted at excise warehouses where bioethanol is produced.
{Subsection 5 of Section XX supplemented by paragraph 43 in accordance with Law No. 2284-IX of 05/31/2022 }
44. To establish that temporarily, for the period until the termination or cancellation of the state of war or emergency in the territory of Ukraine, heavy distillates (gas oil) according to the codes according to the UKT FEA 2710 19 31 01, 2710 19 31 10, 2710 19 31 20, 2710 19 31 30, 2710 19 31 40, 2710 19 35 01, 2710 19 35 10, 2710 19 35 20, 2710 19 35 30, 2710 19 35 40, 2710 19 43 00, 2710 19 46 00, 2710 19 47 10, 2710 19 47 90, 2710 19 48 00, 2710 20 11 00, 2710 20 16 10, 2710 20 16 90, 2710 20 19 00, biodiesel and its mixtures (not containing or containing less than 70 wt. % of oil or petroleum products obtained from bituminous rocks) based on monoalkyl esters of fatty acids according to codes according to UKT FEA 3826 00 10 00, 3826 00 90 00 (hereinafter in this item - heavy distillates and biodiesel), produced in Ukraine or imported into the customs territory of Ukraine, are subject to excise duty at a rate of 0 euros per 1000 liters, if the customer of such fuel according to The terms of the contract are the Ministry of Defense of Ukraine.
{Paragraph one of clause 44, subsection 5, section XX, as amended by Law No. 3553-IX of 16.01.2024 }
For import into the customs territory of Ukraine or sale of heavy distillates and biodiesel produced in Ukraine, the importer of heavy distillates and biodiesel (hereinafter referred to as the importer) shall draw up a tax bill in triplicate, and the producer of heavy distillates and biodiesel (hereinafter referred to as the producer) shall draw up two copies. The first copy of the tax bill shall be submitted to the controlling body (bill holder) at the location of the importer or producer, the second copy shall remain with the importer or producer, and the third copy shall be submitted to the controlling body at the place of customs clearance of such heavy distillates and biodiesel.
A tax bill is issued for the amount of excise tax charged on the volume of heavy distillates and biodiesel imported into the customs territory of Ukraine or produced in Ukraine, based on the rate determined as the difference between the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code and the rate established by paragraph one of this paragraph. A calculation of the amount of excise tax is attached to the tax bill.
The sale of volumes of heavy distillates and biodiesel by business entities that have received excise invoices registered in the Unified Register of Excise Invoices, indicating in them the details of the tax bill issued for the amount of excise tax charged on such volumes, is carried out without paying excise tax.
The term for which a tax bill is issued cannot exceed 180 calendar days.
A tax bill can only be issued by an importer or a manufacturer - a tax payer.
The tax bill issued by the manufacturer is the basis for the sale of heavy distillates and biodiesel with the payment of excise tax at the rate established by the first paragraph of this paragraph.
The basis for customs clearance of heavy distillates and biodiesel imported into the customs territory of Ukraine by an importer with payment of excise tax at the rate established by paragraph one of this paragraph is the submission by such importer to the controlling authority carrying out customs clearance, in accordance with the procedure provided for by the Customs Code of Ukraine , by electronic means of communication, of a copy of the tax bill registered by the controlling authority.
Obligations to repay a tax bill cannot be transferred to other persons, regardless of their relationship with the drawer.
No interest or other fees provided by law for other types of bills are charged for the use of a tax bill.
A tax bill without payment of the amount of excise tax specified in it shall be repaid in the event of confirmation of the fact of the intended use of heavy distillates and biodiesel during the period for which such a bill was issued, by registering excise invoices in the Unified Register of Excise Invoices for Operations on the Sale of Heavy Distillates and Biodiesel to the Ministry of Defense of Ukraine, drawn up by the taxpayer carrying out such sale.
Excise invoices for such transactions are drawn up on the basis of primary documents.
A tax bill without payment of the amount of excise tax specified in it for transactions specified in this clause shall be repaid on the basis of copies of primary documents and contracts for the sale of fuel, confirming the sale of fuel along the entire chain of fuel sales from the manufacturer/importer to the entity specified in this clause, submitted to the regulatory authority, and excise invoices drawn up for such transactions and registered in the Unified Register of Excise Invoices.
A tax bill without payment of the amount of excise tax specified in it for the volumes of lost heavy distillates and biodiesel that do not exceed the loss standards approved by the Cabinet of Ministers of Ukraine shall be repaid on the basis of copies of primary documents on the losses of such volumes of fuel and excise invoices registered in the Unified Register of Excise Invoices.
The amount of excise tax paid by the manufacturer/importer before the expiration of the term for which the tax bill was issued, based on the volumes of heavy distillates and biodiesel, the intended use of which has not been confirmed, shall be taken into account by the bill holder upon repayment of the tax bill. Such amount of tax is calculated based on the volume of heavy distillates and biodiesel, the intended use of which has not been confirmed, and the tax rate, which is determined as the difference between the rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code and the rate established by paragraph one of this paragraph.
The bill holder shall verify the documents provided by the manufacturer/importer for the repayment of the tax bill within five business days from the date of their receipt. Based on the results of the verification, the bill holder shall make a decision to repay the tax bill or to carry out the procedures provided for in this paragraph.
If the tax bill provided for in this paragraph is not repaid within the established period, the bill holder shall, within five business days following the last day of the period for which the tax bill was issued, protest such bill for non-payment in accordance with the law and, within one business day from the date of the protest, apply to the bank that avalized the bill with the protested tax bill. The avalist bank shall be obliged to transfer the amount specified in the tax bill to the bill holder no later than the business day following the date of the application of the bill holder with the protested tax bill.
In the absence of confirmation within the established period of the intended use of heavy distillates and biodiesel by the importer or manufacturer who issued the tax bill, such importer or manufacturer shall be charged a fine in the amount of 50 percent of the amount of excise tax, calculated based on the volumes of heavy distillates and biodiesel for which there is no confirmation of intended use, and the excise tax rate established by subparagraph 215.3.4 of paragraph 215.3 of Article 215 of this Code.
Business entities defined by this clause have the right to sell heavy distillates and biodiesel to other persons upon payment of excise tax charged on the volumes of such fuel, based on the rate determined as the difference between the rate established by subparagraph 215.3.4 of clause 215.3 of Article 215 of this Code and the rate established by paragraph one of this clause.
{Subsection 5 of Section XX supplemented by paragraph 44 in accordance with Law No. 2618-IX of September 21, 2022 ; as amended by Law No. 3325-IX of August 10, 2023 }
45. Temporarily, the details of the excise invoice drawn up under the conditions specified in paragraph 44 of this subsection shall include a note regarding the sale of fuel under the conditions specified in paragraph 44 of this subsection, indicating the details of the tax bill and the business entities that will sell heavy distillates and biodiesel to the customer specified in paragraph 44 of this subsection.
{Subsection 5 of Section XX supplemented by paragraph 45 in accordance with Law No. 2618-IX of 09/21/2022 }
46. Temporarily, for the period of martial law in the territory of Ukraine and within 30 days from the date of its termination or cancellation, for the purposes of applying Section VIII of this Code, electric generating installations classified under code 8502 according to the UKT FEA shall not be considered stationary sources of pollution within the meaning given in subparagraph 14.1.230 of paragraph 14.1 of Article 14 of this Code .
{Subsection 5 of Section XX supplemented by paragraph 46 in accordance with Law No. 2836-XI of 13.12.2022 }
47. During the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , and within 30 days from the date of its termination or cancellation, and for the cases provided for in the third paragraph of this paragraph regarding the storage of fuel in containers with a total capacity of 2,000 liters to 5,000 liters, - until the specified date of termination of the possibility of hostilities or the date of completion of hostilities, in addition to the criteria specified in subparagraph 14.1.6 of paragraph 14.1 of Article 14 of this Code, the following shall not be considered an excise warehouse:
premises or territory, including that of the payer of excise tax on fuel sales, in each (each) of which the total capacity of the tanks located for storing fuel used exclusively for refueling electric generating sets does not exceed 2,000 liters;
premises or territory, including the payer of excise tax on the sale of fuel (except for payers engaged in the production, wholesale and retail trade in fuel, its storage (except for storage exclusively for the needs of own consumption and/or industrial processing), which are located/are located in the territories of possible hostilities (for which the date of cessation of the possibility of hostilities has not been determined), territories of active hostilities (for which the date of completion of hostilities has not been determined), included in the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation, in each of which the total capacity of the located containers for storing fuel used exclusively for refueling power generating units does not exceed 5,000 liters. The list of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine;
premises or territory, including that of the payer of excise tax on fuel sales, in each (each) of which the conditions specified in paragraphs two and three of this paragraph are met, and at the same time fuel is stored or sold in consumer containers with a capacity of up to 5 liters inclusive, received from the manufacturer or the person who filled the fuel into such containers.
The provisions of the second and third paragraphs of this paragraph shall apply provided that:
ensuring that the business entity uses the specified volumes of fuel exclusively for refueling power generating units and maintaining separate records of the fuel received and used for their refueling;
Payment for fuel purchased for such needs must be made exclusively in non-cash form.
Provided that the requirements specified in this clause are met, fuel received for refueling electric generating units shall not be taken into account when applying the criterion specified in subparagraph 14.1.6 of clause 14.1 of Article 14 of this Code regarding the volume of fuel received by such a business entity not exceeding 1,000 cubic meters during a calendar year.
{Subsection 5 of Section XX supplemented by paragraph 47 in accordance with Law No. 2836-XI of 13.12.2022 ; as amended by Law No. 3878-IX of 18.07.2024 }
48. From September 1, 2024 to December 31, 2027 inclusive, establish excise tax rates for the following goods:
Product code according to the UKTZED
Description of goods (products) according to the UKTZED
Unit of measurement (volume in liters, reduced to t 15° C)
Excise tax rate in fixed amounts per unit of sold goods (products)
from September 1 to December 31, 2024 inclusive
from January 1 to December 31, 2025 inclusive
from January 1 to December 31, 2026 inclusive
from January 1 to December 31, 2027 inclusive
2707 50 00 10 2707 50 00 90
Mixtures of aromatic hydrocarbons of which 65 vol. % or more (including losses) distil at temperatures up to 250 °C by the ISO 3405 method (equivalent to the ASTM D 86 method)
Other ethers, ether alcohols, ether phenols, ether alcohol phenols, alcohol peroxides, ether peroxides, ketone peroxides (whether or not chemically defined) and their halogenated, sulphonated, nitrated or nitrosated derivatives, except diethyl ether (code according to UKTZED 2909 11 00 00) Anti-knock preparations, antioxidants, pitch inhibitors, thickeners, anti-corrosion preparations and other prepared additives, additives for petroleum products (including gasoline) or for other liquids used for the same purposes as petroleum products:
euros per 1000 liters
242.6
271.7
300.8
329.9
3811 11 10 00 3811 11 90 00 3811 19 00 00
Anti-knock devices
euros per 1000 liters
242.6
271.7
300.8
329.9
3811 90 00 00
Others
euros per 1000 liters
267.8
290.6
313.4
336.2
3826 00 10 00 3826 00 90 00
Biodiesel and its blends (not containing or containing less than 70% by weight of petroleum or petroleum products obtained from bituminous rocks) based on monoalkyl esters of fatty acids
Liquid fuels based on gas oils (diesel fuel), less than 85 vol. % of which, including the costs, distils at a temperature of 350° C (according to the ISO 3405 method, equivalent to the ASTM D 86 method), except for household heating fuels, base oils and other lubricants, and other distillates, which during fractional distillation according to the ISO 3405 method (or an equivalent ASTM D 86 method) at a temperature of 350° C and atmospheric pressure distil no more than 35 vol. %
euros per 1000 liters
242.6
271.7
300.8
329.9
3814 00 90 90
Only solvents or thinners based on methanol; other methanol-based ready-mixtures
euros per 1000 liters
268.2
290.9
313.6
336.3
________
* A 10% increase is applied to the tax rate in the following cases:
import of fuel into the customs territory of Ukraine;
sales by the manufacturer of fuel produced in Ukraine.
The increasing coefficient of 10 is not applied by business entities that, in accordance with Clause 229.8 of Article 229 of this Code, have issued a tax bill.
Goods (products) used as fuel for refueling vehicles, equipment or devices with compression-ignition internal combustion engines, spark-ignition internal combustion engines, crank-type internal combustion engines, the codes of which according to the UKTZED are not specified in this sub-item (except for natural gas in a gaseous state under code 2711 21 00 00 according to the UKTZED), are taxed at the excise tax rate:
242.6 euros per 1000 liters - from September 1, 2024 to December 31, 2024 inclusive;
271.7 euros per 1000 liters - from January 1, 2025 to December 31, 2025 inclusive;
300.8 euros per 1000 liters - from January 1, 2026 to December 31, 2026 inclusive;
329.9 euros per 1000 liters - from January 1, 2027 to December 31, 2027 inclusive.
{Subsection 5 of Section XX supplemented by paragraph 48 in accordance with Law No. 3878-IX of 18.07.2024 }
49. Temporarily, until Ukraine becomes a full member of the European Union, but no longer than January 1, 2030, producers of ethyl alcohol and bioethanol calculate the excise tax taking into account the following features.
49.1. Producers of ethyl alcohol and bioethanol, when calculating the excise tax on ethyl alcohol and bioethanol produced in the customs territory of Ukraine for a tax (reporting) period, take into account the value of the guaranteed tax liability for excise tax for such period.
The guaranteed excise tax liability refers to the amount of excise tax liability calculated based on the maximum productivity of equipment for the production of ethyl alcohol and bioethanol.
The maximum productivity of equipment for the production of ethyl alcohol and bioethanol is understood as the maximum volume of ethyl alcohol and bioethanol in liters of 100 percent ethyl alcohol that can be produced per day on equipment that provides a full technological cycle of ethyl alcohol and bioethanol production.
49.2. The guaranteed tax liability for excise tax for the tax (reporting) period (GPZ) is calculated using the formula:
GPZ = Ob × K × St, where:
Vol - volume of ethyl alcohol, bioethanol in liters of 100 percent ethyl alcohol, defined as the maximum productivity of equipment for the production of ethyl alcohol, bioethanol per day;
K - the number of days in the calendar month of the tax (reporting) period;
Vt - the excise tax rate, determined by clause 215.3 of Article 215 of this Code, effective on the first day of the tax (reporting) period.
At the same time:
the value of the indicator "Ob × K" is increased by the volume of residual ethyl alcohol, bioethanol at the beginning of the tax (reporting) period and is reduced by the volume of ethyl alcohol, bioethanol sold in the tax (reporting) period, including in the case of its transfer within the same enterprise, and by the volume of residual ethyl alcohol, bioethanol at the end of the tax (reporting) period. The volumes of residual ethyl alcohol, bioethanol at the beginning and end of the tax (reporting) period must be confirmed by the results of the inventory carried out on the first day of each month in accordance with clause 230.14 of Article 230 of this Code,
the value of the indicator "K" is reduced by the number of days during which the production of ethyl alcohol, bioethanol was not carried out due to a stoppage of production or as a result of technical or regulatory work, provided that such circumstances are reported on the day of their occurrence in writing to the permanent representative of the controlling body at the excise warehouse and in electronic form, in accordance with the procedure specified in Article 42 of this Code, to the central executive body implementing state tax policy, in order to seal places of possible access to ethyl alcohol, bioethanol, their unsealing after the expiration of the circumstances specified in this paragraph, in accordance with the procedure specified in the Law of Ukraine "On State Regulation of the Production and Circulation of Ethyl Alcohol, Alcohol Distillates, Bioethanol, Alcoholic Beverages, Tobacco Products, Tobacco Raw Materials, Liquids Used in Electronic Cigarettes, and Fuel".
The taxpayer is obliged to increase the amount of the tax liability for excise tax on ethyl alcohol and bioethanol in the tax return, determined based on the results of taxable transactions carried out during the tax (reporting) period, by the amount of the guaranteed tax liability for excise tax for the relevant tax (reporting) period.
The requirements of this paragraph do not apply to business entities that have a license for the right to produce bioethanol and produce exclusively bioethanol.
{Subsection 5 of Section XX supplemented by paragraph 49 in accordance with Law No. 4014-IX of 09.10.2024 }
{Title of Subsection 6 of Section XX as amended by Law No. 909-VIII of 12/24/2015 }
1. During the validity of international treaties (agreements) of Ukraine on space activities ratified by the Verkhovna Rada of Ukraine regarding the creation of space technology (including units, systems and their components for space complexes, space launch vehicles, spacecraft and ground segments of space systems), but no later than January 1, 2033, residents - subjects of space activities who have received a license for the right to carry it out and participate in the implementation of such treaties (agreements), for land plots for industrial purposes according to the list approved by the Cabinet of Ministers of Ukraine, are exempt from paying land tax.
{Clause 1, Subsection 6, Section XX, as amended by Laws No. 71-VIII of 12/28/2014 , No. 1797-VIII of 12/21/2016 , No. 2836-XI of 12/13/2022 }
{Clause 2, Subsection 6, Section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Clause 3, subsection 6, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Clause 4, subsection 6, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Clause 5, subsection 6, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
6. Establish that the consumer price index for 2015, used to determine the indexation coefficient of the normative monetary valuation of agricultural land (arable land, perennial plantations, hayfields, pastures and fallow lands), is applied with a value of 120 percent.
{Subsection 6 of Section XX supplemented by paragraph 6 in accordance with Law No. 909-VIII of 24.12.2015 }
7. Until January 1, 2025, aircraft manufacturing entities that fall under the provisions of Article 2 of the Law of Ukraine "On the Development of the Aircraft Industry" and carry out the development and/or manufacture with final assembly of aircraft and engines for them, except for land plots on which social, commercial, agricultural and non-industrial construction facilities are located, are exempt from paying land tax.
{Subsection 6 of Section XX supplemented by paragraph 7 in accordance with Law No. 1795-VIII of 20.12.2016 }
8. Establish that the consumer price index for 2016, used to determine the indexation coefficient of the normative monetary valuation of land, is applied with the value:
for agricultural land (arable land, perennial plantations, hayfields, pastures and fallow lands) - 100 percent;
for non-agricultural lands - 106 percent.
{Subsection 6 of Section XX supplemented by paragraph 8 in accordance with Law No. 1791-VIII of 20.12.2016 }
9. Establish that the consumer price index used to determine the indexation coefficient of the normative monetary valuation of land is applied with a value of 100 percent:
for 2017-2022 - for agricultural lands (arable land, perennial plantations, hayfields, pastures and fallow lands);
for 2017-2020 - for lands of settlements and other non-agricultural lands.
{Subsection 6 of Section XX supplemented by paragraph 9 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended in accordance with Law No. 2628-VIII of 23.11.2018 ; as amended by Law No. 1914-IX of 30.11.2021 }
10. If the local governments of the settlements on the contact line have not made a decision to establish land tax rates (except for agricultural land) for 2020, such tax shall be paid in accordance with the norms of this Code until such a decision is made, using a rate of 0.01 percent of the normative monetary valuation of the land plot.
{Subsection 6 of Section XX supplemented by paragraph 10 in accordance with Law No. 466-IX of January 16, 2020 }
11. Temporarily, until January 1, 2035, establish that in terms of land payments for land plots, the normative monetary valuation of which has been carried out, which are used within the framework of the implementation of investment projects with significant investments (except for investment projects in the areas of extraction for the purpose of further processing and/or enrichment of minerals) in accordance with the Law of Ukraine "On State Support for Investment Projects with Significant Investments in Ukraine", local self-government bodies may:
to establish land tax rates and rent for state and municipally owned land in an amount less than the amount of land tax established by the decision of the relevant local government body for a certain category of land, which is paid in the relevant territory;
exempt from paying land tax.
The requirements of subparagraph 4.1.9 of paragraph 4.1 and paragraph 4.5 of Article 4, subparagraphs 12.3.3 , 12.3.4 and 12.3.7 of paragraph 12.3, subparagraph 12.4.3 of paragraph 12.4 and paragraph 12.5 of Article 12 of this Code and the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity" shall not apply to such decisions of local self-government bodies and/or decisions on amendments to such decisions.
The total amount of funds exempted from taxation (the amount of tax not paid to the budget and remaining at the disposal of the taxpayer - investor with significant investments) is taken into account in the total amount of state support for an investment project with significant investments provided for by a special investment agreement, which is provided in accordance with the Law of Ukraine "On State Support for Investment Projects with Significant Investments in Ukraine".
In the event that the total amount of state support for an investment project with significant investments is reached, the taxpayer - investor with significant investments, starting from the calendar month in which the specified amount is reached, loses the right to apply the benefit specified in this paragraph.
Upon reaching the total amount of state support for an investment project with significant investments during the reporting (tax) period, the taxpayer - investor with significant investments is obliged, within 20 calendar days from the date of entry of the relevant information into the register of investment projects with significant investments, to submit a clarifying tax return for such reporting (tax) period, in which to increase the tax obligations for payment of land fees for the period starting from the calendar month in which the total amount of state support for the investment project with significant investments was reached.
At the same time, until the date of amendments to the lease agreements of land plots used within the framework of the implementation of investment projects with significant investments, in connection with the achievement of the total amount of state support for the investment project with significant investments, the amount of rent for the calculation of tax liabilities on rent is determined according to the rules specified in paragraph 288.5 of Article 288 of this Code.
Penalties and fines specified in this Code for understating the tax liability for land payments for the period from the date of achieving the total amount of state support for an investment project with significant investments until the date of entering the relevant information into the register of investment projects with significant investments regarding the achievement of the total amount of such support shall not apply.
The adoption of decisions by local self-government bodies in accordance with the first paragraph of this paragraph shall be carried out taking into account the requirements of the Law of Ukraine "On State Support for Investment Projects with Significant Investments in Ukraine" regarding the limitation of the total amount of state support for an investment project with significant investments and the provisions of the relevant special investment agreements concluded in accordance with the Law of Ukraine "On State Support for Investment Projects with Significant Investments in Ukraine."
{Subsection 6 of Section XX supplemented by paragraph 11 in accordance with Law No. 1293-IX of 02.03.2021 }
12. To establish that in 2022, information on decisions of a local government body, adopted before January 1, 2022, on the allocation of land plots in kind (on the ground) to owners of land shares (shares), provided for in paragraph 284.5 of Article 284 of this Code, shall be provided to the relevant supervisory authority at the location of such land plots by July 1, 2022.
The assessment of land tax amounts to individuals based on the decisions specified in the first paragraph of this paragraph is carried out by the supervisory authorities at the location of the land plot, which send (deliver) to the payer a tax notice-decision on the payment of tax by October 1, 2022. Land tax is paid by individuals within 60 days from the date of delivery of the tax notice-decision.
The first reporting (tax) period for calculating land tax for land plots of state and municipal property based on decisions of local governments on the allocation of a land plot in kind (on the ground) to the owner of a land share (share), adopted before January 1, 2022, is considered to be 2022.
The assessment of land tax amounts to individuals based on the decisions specified in paragraph one of this paragraph shall be completed by the reporting (tax) period preceding the period specified in part four of Article 13 of the Law of Ukraine "On the Procedure for Allocating Land Plots in Kind (On the Ground) to Owners of Land Shares (Shares)" for registration of ownership rights to a land plot (taking into account the provisions of part six of the said Article)";
{Subsection 6 of Section XX supplemented by paragraph 12 in accordance with Law No. 1914-IX of 11/30/2021 }
13. A single tax payer of the fourth group whose registration as a single tax payer has been cancelled in accordance with subparagraph 8 of paragraph 299.10 of Article 299 of this Code shall be obliged to pay land tax for land plots and land shares (shares) that were transferred to him for lease by the owners and land users of such land plots and land shares (shares) from the first day of the month following the quarter in which such registration was cancelled until the end of the current year. In this case, individuals - owners and land users of such land plots and land shares (shares) are exempt from paying land tax until the end of the current year in which the single tax payer of the fourth group has had its registration as a single tax payer cancelled.
A single tax payer of the fourth group whose registration as a single tax payer has been canceled in accordance with subparagraph 8 of paragraph 299.10 of Article 299 of this Code is obliged to independently calculate the amount of land tax and submit a tax declaration for land payments to the relevant regulatory body at the location of the land plots within 20 calendar days of the month following the quarter in which registration as a single tax payer was canceled.
{Subsection 6 of Section XX supplemented by paragraph 13 in accordance with Law No. 3317-IX of 10.08.2023 }
Subsection 7. Features of the procedure for returning commercial patents↑
1. Commercial patents issued in accordance with the requirements of the Law of Ukraine "On Patenting Certain Types of Business Activities" , the validity period of which has not expired at the time of entry into force of this Code, shall be returned to the regulatory authorities at the place of their acquisition within three months (but no later than the expiration of their validity period).
2. Business entities are responsible for complying with the procedure for using commercial patents issued in accordance with the Law of Ukraine "On Patenting Certain Types of Business Activities" and for complying with the payment deadline for them, provided for in Chapter 11 of Section II of this Code.
3. Business entities that violated the procedure for obtaining and using a commercial patent for the period before January 1, 2015 shall be liable in accordance with the procedure and under the conditions in force before January 1, 2015.
{Subsection 7 of Section XX supplemented by paragraph 3 in accordance with Law No. 71-VIII of 28.12.2014 }
Subsection 8. Features of charging a single tax and a fixed tax↑
1. To establish that from January 1, 2011, until amendments are made to Section XIV of the Tax Code of Ukraine in terms of taxation of small business entities, the Decree of the President of Ukraine dated July 3, 1998 No. 727 "On a Simplified System of Taxation, Accounting and Reporting of Small Business Entities" (with subsequent amendments) and paragraphs six to twenty-eight of paragraph 1 of Article 14 of Section IV of the Decree of the Cabinet of Ministers of Ukraine dated December 26, 1992 No. 13-92 "On Personal Income Tax" shall be applied taking into account the following features:
1) single tax payers are not payers of the following taxes and fees defined by the Tax Code of Ukraine:
a) corporate income tax;
b) personal income tax (for individual entrepreneurs);
c) value added tax on transactions for the supply of goods and services, the place of provision of which is located in the customs territory of Ukraine, with the exception of value added tax paid by legal entities that have chosen a tax rate of 6 percent;
d) land tax, except for land tax on land plots not used for business activities;
e) fee for the use of subsoil;
e) fee for special water use;
e) fee for special use of forest resources;
g) fee for conducting certain types of business activities;
2) the accrual, calculation and payment of a single contribution for compulsory state social insurance are carried out by small business entities that pay a single tax in accordance with the Decree of the President of Ukraine dated July 3, 1998 No. 727 "On a simplified system of taxation, accounting and reporting for small business entities" (as amended) or a fixed tax in accordance with paragraphs six to twenty-eight of paragraph 1 of Article 14 of Section IV of the Decree of the Cabinet of Ministers of Ukraine dated December 26, 1992 No. 13-92 "On income tax on citizens", in the manner prescribed by the Law of Ukraine "On collection and accounting of a single contribution for compulsory state social insurance" ;
3) the single tax or fixed tax is paid to the account of the relevant budget in the amount of the part of the single tax or fixed tax subject to transfer to these budgets in accordance with the provisions of the Decree of the President of Ukraine dated July 3, 1998 No. 727 "On a simplified system of taxation, accounting and reporting of small business entities" (as amended) and the Law of Ukraine "On Amendments to the Decree of the Cabinet of Ministers of Ukraine "On Personal Income Tax" (Vidomosti Verkhovnoi Rada of Ukraine, 1998, No. 30-31, p. 195) (except for the single tax paid in January 2011 for the last reporting (tax) period of 2010). In this case, the State Treasury of Ukraine does not distribute the funds of the single tax or fixed tax to mandatory state social insurance and/or to the Pension Fund of Ukraine;
4) the single tax payable in January 2011 for the last reporting (tax) period of 2010 shall be credited to the budgets and funds of mandatory state social insurance (including pension insurance) in accordance with the procedure and conditions in force before January 1, 2011;
5) refunds of the amounts of the single tax and fixed tax that were paid before January 1, 2011 in error or in excess, as well as the crediting of the amounts of repayment of the tax debt that formed as of December 31, 2010, shall be carried out in accordance with the established procedure, taking into account this subsection;
6) in the event of a refund of advances (other payments) received during the period of the taxpayer's stay on the simplified taxation system, from which a single tax was paid, the amount of revenue from the sale of products (goods, works, services) is adjusted for the amount of such refund in accordance with the adjustment of the amount of the single tax in accordance with the procedure provided for by this Code.
{Clause 1, subsection 8, section XX is supplemented by subparagraph 6 in accordance with Law No. 3609-VI of 07.07.2011 }
2. To establish that the provisions of subparagraph 2 of paragraph 293.4 of Article 293 and subparagraph 7 of subparagraph 298.2.3 of paragraph 298.2 of Article 298 of this Code shall not apply in 2012.
{Subsection 8 of Section XX supplemented by paragraph 2 in accordance with Law No. 4834-VI of 24.05.2012 }
3. The presence of a tax debt from the single and fixed taxes, which arose as a result of accounting with the regulatory authorities in February 2011, as well as a tax debt that arose from the single tax for January 2012, on the day of filing an application for the application of the simplified taxation system, by such a person is not a basis for the regulatory authority to make a decision in 2012 to refuse to issue a single tax payer certificate to an individual entrepreneur.
{Subsection 8 of Section XX supplemented by paragraph 3 in accordance with Law No. 4834-VI of 24.05.2012 }
4. Single tax payers of the third to sixth groups who were registered with regulatory authorities before January 1, 2015, from January 1, 2015 are considered single tax payers of the third group in accordance with the provisions of Chapter 1, Section XIV of this Code.
{Subsection 8 of Section XX supplemented by paragraph 4 in accordance with Law No. 71-VIII of 28.12.2014 }
5. To establish that the consumer price index for the purposes of taxation by the single tax of the fourth group is applied with a value of 100 percent:
to determine the indexation coefficient of the normative monetary valuation of agricultural land (arable land, hayfields, pastures and perennial plantations) for 2015 and 2017-2022;
to determine the indexation coefficient of the normative monetary valuation of water fund lands (inland water bodies, lakes, ponds, reservoirs) for 2015 and 2017-2020.
{Subsection 8 of Section XX supplemented by paragraph 5 in accordance with Law No. 909-VIII of 12/24/2015 ; as amended by Law No. 1791-VIII of 12/20/2016 ; as amended by Laws No. 2245-VIII of 12/07/2017 , No. 2628-VIII of 11/23/2018 ; as amended by Law No. 1914-IX of 11/30/2021 }
6. The income of a single tax payer - a legal entity does not include the amount of funds received as a one-time compensation to business entities, in accordance with Article 4 of the Law of Ukraine "On social support for insured persons and business entities for the period of implementation of restrictive anti-epidemic measures introduced to prevent the spread of acute respiratory disease COVID-19, caused by the SARS-CoV-2 coronavirus, in the territory of Ukraine."
{Subsection 8 of Section XX supplemented by paragraph 6 in accordance with Law No. 1072-IX of 04.12.2020 }
6 - 1. The income of a single tax payer of the first - third groups does not include the amounts of income received by the taxpayer in the form of partial or full compensation of interest (percentage) rates, which is paid within the framework of the budget program "Ensuring the functioning of the Entrepreneurship Development Fund" and the state program for the implementation of financial and credit mechanisms for providing citizens with housing on the terms determined by the Cabinet of Ministers of Ukraine, as well as the amounts of funds received by the taxpayer on a non-refundable basis from the Innovation Development Fund.
{Subsection 8 of Section XX supplemented by paragraph 6 - 1 in accordance with Law No. 1914-IX of 11/30/2021 }
7. The income of a single tax payer - an individual entrepreneur - does not include the amount of funds received as a one-time material assistance to insured persons, which is paid to such a payer at the expense of the state budget in accordance with Article 2 of the Law of Ukraine "On social support for insured persons and business entities for the period of implementation of restrictive anti-epidemic measures introduced to prevent the spread of acute respiratory disease COVID-19, caused by the SARS-CoV-2 coronavirus, in the territory of Ukraine."
{Subsection 8 of Section XX supplemented by paragraph 7 in accordance with Law No. 1072-IX of 04.12.2020 }
8. To establish that in terms of regulating single tax payers of the fourth group , subparagraph 4 of paragraph 291.4, subparagraphs 291.4.3-291.4.7 of paragraph 291.4, paragraph 291.5 - 1 of Article 291, Article 292 - 1 , paragraph 293.9 of Article 293 , paragraph 294.1 of Article 294, paragraph two of paragraph 294.4 of Article 294, paragraph 295.9 of Article 295 , subparagraph 2 of paragraph 297.1 of Article 297, subparagraphs 3 and 4 of paragraph 297.1 of Article 297, subparagraph 5 of paragraph 297.1 of Article 297, paragraph 297.4 of Article 297, paragraphs 298.8 and 298.9 of Article 298, subparagraphs 4 and 5 of paragraph 299.10 of Article 299, paragraph two of clause 299.11 of Article 299 shall be effective temporarily and shall cease to be valid from January 1 of the year following the year of entry into force of the law of Ukraine on stimulating the development of the agro-industrial complex of Ukraine, taking into account the Common Agricultural Policy of the European Union in terms of providing state aid and developing rural areas.
{Subsection 8 of Section XX supplemented by paragraph 8 in accordance with Law No. 1914-IX of 11/30/2021 }
9. To establish that temporarily, from April 1, 2022 until the termination or cancellation of the martial law or state of emergency in the territory of Ukraine, but no later than August 1, 2023, the provisions of Section XIV of this Code shall apply, taking into account the following features:
{Paragraph one of clause 9, subsection 8, section XX as amended by Law No. 3219-IX of 06/30/2023 }
9.1. Individual entrepreneurs - single tax payers of the first and second groups have the right not to pay the single tax.
At the same time, such persons shall not fill out the declaration of a single tax payer - an individual entrepreneur - for the period in which, in accordance with the first paragraph of this subparagraph, the single tax was not paid.
9.2. Payers of the single tax of the third group may be individuals - entrepreneurs and legal entities - business entities of any organizational and legal form.
{Paragraph one of subparagraph 9.2 of clause 9, subsection 8 of section XX as amended by Law No. 2173-IX of 01.04.2022 }
Such persons are not subject to restrictions on the amount of income and the number of persons employed by them.
{Paragraph two of subparagraph 9.2 of clause 9, subsection 8 of section XX as amended by Law No. 2173-IX of 01.04.2022 }
9.3. Single tax payers of the third group who use the taxation features established by this clause, without taking into account the restrictions established by clause 291.5 of Article 291 of this Code, cannot be:
1) business entities (legal entities and individual entrepreneurs) that carry out:
{Paragraph three of subparagraph 9.3 of clause 9, subsection 8 of section XX was excluded on the basis of Law No. 2192-IX of 04/14/2022 }
activities related to the organization and conduct of gambling, lotteries (except for the distribution of lotteries), betting (bookmaker betting, totalizator betting);
{The third paragraph is included in subparagraph 9.3 of paragraph 9, subsection 8, section XX in accordance with Law No. 2876-IX of 12.01.2023 }
foreign currency exchange;
production, export, import, sale of excisable goods (except for retail sale of fuels and lubricants in containers up to 20 liters, retail trade in excisable goods);
{Paragraph five of subparagraph 9.3 of clause 9 of subsection 8 of section XX as amended by Laws No. 2142-IX of 03/24/2022 , No. 2173-IX of 04/01/2022 , No. 2325-IX of 06/21/2022 }
extraction, sale of minerals (except for the extraction of groundwater and surface water by enterprises that provide centralized water supply and drainage services);
{Paragraph six of subparagraph 9.3 of clause 9, subsection 8 of section XX as amended by Law No. 2173-IX of 01.04.2022 }
2) insurance (reinsurance) brokers, banks, credit unions, pawnshops, leasing companies, trust companies, insurance companies, pension funds, investment funds and companies, other financial institutions defined by law; securities registrars;
3) representative offices, branches, departments and other separate divisions of a legal entity that is not a single tax payer;
4) non-resident individuals and legal entities.
9.4. The single tax interest rate for single tax payers of the third group who use the taxation features established by this paragraph is set at 2 percent of income determined in accordance with Article 292 of this Code.
{Subclause 9.4 of Clause 9, Subsection 8, Section XX, as amended by Law No. 2142-IX of March 24, 2022 }
9.5. Single tax payers of the third group who use the taxation features established by this paragraph are exempt from the obligation to charge and pay value added tax on transactions for the supply of goods, works and services, the place of supply of which is located in the customs territory of Ukraine, as well as from submitting tax reports on value added tax, and their registration as a value added tax payer is suspended.
{Paragraph one of subparagraph 9.5 of clause 9, subsection 8 of section XX as amended by Law No. 2325-IX of 06/21/2022 }
{Paragraph two of subparagraph 9.5 of clause 9, subsection 8 of section XX was excluded on the basis of Law No. 2325-IX of 06/21/2022 }
Suspension of registration by a value added tax payer for the purposes of this paragraph means that for single tax payers of the third group who use the taxation features established by this paragraph, the rights and obligations established by Section V and Subsection 2 of Section XX of this Code (including regarding the formation of a tax credit) are suspended for the period of use of the taxation features established by this paragraph.
Transactions carried out by a single tax payer of the third group who uses the taxation features established by this paragraph are considered not to be subject to value added tax.
For persons whose registration as a value added tax payer is suspended in accordance with this paragraph, the calculation of the indicators specified in Article 200-1 of this Code shall be suspended for the period of use of the taxation features established by this paragraph .
The calculation of the indicator ∑ NaklOtr does not take into account the amounts of value added tax on tax invoices received by the value added tax payer and/or adjustment calculations to such tax invoices registered in the Unified Register of Tax Invoices, which are drawn up for transactions, the date of occurrence of tax liabilities for which falls (fell) during the period during which the taxpayer applied the simplified taxation system, taking into account the features of taxation established by this paragraph.
{Subclause 9.5 of Clause 9, Subsection 8, Section XX as amended by Law No. 2142-IX of March 24, 2022 }
9.6. The tax (reporting) period for single tax payers of the third group who use the taxation features established by this paragraph is equal to a calendar month.
The amount of tax liability indicated by the taxpayer in the tax return submitted by him shall be payable within 10 calendar days following the last day of the relevant deadline provided for in subparagraph 9.7 of this paragraph for submitting a tax return.
{Subclause 9.6 of Clause 9, Subsection 8, Section XX as amended by Law No. 2142-IX of March 24, 2022 }
9.7. Single tax payers of the third group who use the taxation features established by this clause shall submit to the regulatory authority a single tax payer tax return within the deadlines established for the monthly tax (reporting) period, except for the cases provided for by this clause.
Single tax payers of the third group - individuals who use the features of taxation established by this paragraph - in the case of determining a single social contribution, submit reporting for the reporting period - December as a tax declaration of a single tax payer for the IV quarter of the tax (reporting) year, in which the obligations of single tax payers are calculated on a cumulative basis and information on the amounts of the single contribution accrued, calculated and paid in the manner prescribed by law for this category of payers is indicated.
Single tax payers of the third group who use the features of taxation established by this paragraph, who are obliged to determine the total minimum tax liability of single tax payers, submit reporting for the reporting period - December as a single tax payer's tax return for the IV quarter of the tax (reporting) year, in which the liabilities of single tax payers are calculated on a cumulative basis, the total minimum tax liability.
{Subclause 9.7 of Clause 9, Subsection 8, Section XX as amended by Law No. 2142-IX of March 24, 2022 }
9.8. To elect or switch to a simplified taxation system by a payer with the features established by this clause, a business entity shall submit an application to the regulatory authority. In this case, the calculation of income for the previous calendar year shall not be attached to the application.
A business entity is considered a payer of a single tax of the third group with the features established by this paragraph:
from April 1, 2022 - if the application is submitted before April 1, 2022;
from the next business day after submitting the application - if the application is submitted starting from April 1, 2022.
Business entities registered in accordance with the procedure established by law (newly created), which within 10 days from the date of state registration submitted an application for the election of a simplified taxation system taking into account the features of taxation established by this paragraph, are considered payers of the third group of the single tax from the date of their state registration.
{Subclause 9.8 of Clause 9, Subsection 8, Section XX as amended by Law No. 2142-IX of March 24, 2022 }
9.9. The taxpayer has the right to independently (by submitting an application) refuse to use the features of taxation provided for in this clause, from the first day of the month following the month in which such a decision is made. In such a case, the taxpayer is considered to apply the taxation system under which he was before choosing the features of taxation provided for in this clause, except for the case where, in the application for refusal to use the features of taxation provided for in this clause, the taxpayer indicated the transition to paying other taxes and fees.
{Paragraph of subparagraph 9.9 of paragraph 9 of subsection 8 of section XX as amended by Law No. 3219-IX of 06/30/2023 }
of Sub-clause 298.8.8 of Clause 298.8 of Article 298 of this Code shall not apply to taxpayers who have refused to use the taxation features provided for in this clause .
{Paragraph of subparagraph 9.9 of paragraph 9 of subsection 8 of section XX as amended by Law No. 2719-IX of 03.11.2022 }
Newly established business entities wishing to choose a simplified taxation system taking into account the features of taxation established by this paragraph shall submit an application according to the general procedure provided for by this Code.
For goods/services, non-current assets purchased/manufactured with value added tax before the application of the taxation features established by this clause, which are used (supplied, sold) by a single tax payer of the third group during the period of application of the taxation features established by this clause, in transactions that are not subject to taxation, the value added tax payer is obliged, no later than the last day of the reporting period in which his registration as a value added tax payer was renewed, to calculate tax liabilities in accordance with clause 198.5 of Article 198 of this Code.
{Subclause 9.9 of clause 9, subsection 8, section XX is supplemented by a paragraph in accordance with Law No. 2142-IX of 03/24/2022 }
The tax base when calculating tax liabilities in accordance with paragraph four of this sub-item for non-current assets is determined based on the book value (residual value) as of the beginning of the reporting (tax) period during which such transactions are carried out (in the absence of accounting for non-current assets - based on the usual price), and for goods/services - based on the cost of their acquisition.
{Subclause 9.9 of clause 9, subsection 8, section XX is supplemented by a paragraph in accordance with Law No. 2142-IX of 03/24/2022 }
9.10. Grant the Cabinet of Ministers of Ukraine the right to determine the specifics of the calculation and payment of the single tax.
9.11. Payers of corporate income tax (including taxpayers whose annual income from any activity (net of indirect taxes), determined according to the indicators of the Statement of Financial Results (Statement of Comprehensive Income) for the previous annual reporting period, does not exceed 40 million hryvnias) who have decided to switch to a simplified taxation system by the payer with the features established by this clause, or have refused to use the features of taxation provided for by this clause, shall submit a corporate income tax return for the period(s) during the calendar year in which the payer was a corporate income tax payer.
{Clause 9, subsection 8, section XX is supplemented by subparagraph 9.11 in accordance with Law No. 2142-IX of March 24, 2022 }
9.12. Taxation of corporate income tax on taxpayers who have temporarily switched to paying a single tax of the third group in accordance with this paragraph is carried out taking into account the following features.
The overpaid amount of monetary liabilities for corporate income tax that exists on the date of transition to payment of a single tax at a rate of 2 percent may be credited towards repayment of monetary liabilities for this tax that will arise after the resumption of payment of corporate income tax.
Advance payments for corporate income tax upon payment of dividends that remained unaccounted for in reducing the accrued amount of tax liability for this tax on the date of transition to payment of a single tax at a rate of 2 percent may be taken into account in reducing such amount after the resumption of payment of corporate income tax.
The negative value of the object of taxation by the corporate profit tax that existed on the date of transition to the payment of a single tax may be included in the reduction of the object of taxation by the corporate profit tax that will arise after the resumption of the payment of this tax, in accordance with the procedure specified in paragraph 140.4 of Article 140 of this Code.
Interest that exceeds the amount of the limitation specified in Clause 140.2 of Article 140 of this Code, which increased the financial result before taxation, which remained not taken into account in the reduction of the financial result before taxation on the date of transition to payment of a single tax at a rate of 2 percent, shall reduce the financial result before taxation, taking into account the limitations established in Clause 140.2 of Article 140 of this Code, after the resumption of payment of corporate income tax.
A taxpayer who, during a calendar year, switched to paying a single tax at a rate of 2 percent, in the event of his resumption of paying corporate income tax in the same year, shall prepare and submit a corporate income tax return with a cumulative total from the beginning of such calendar year. In this case, the results of activities for the periods of being on the payment of a single tax at a rate of 2 percent shall not be taken into account when determining the object of taxation by corporate income tax specified in subparagraph 134.1.1 of paragraph 134.1 of Article 134 of this Code, taking into account the provisions of subsection 4 of this section for corporate income tax payers who have switched from the simplified taxation system to the general one.
The amount of annual income from any activity (net of indirect taxes) of a payer of corporate income tax for the purposes of applying subparagraph 39.2.1.7 of subparagraph 39.2.1 of paragraph 39.2 of Article 39, subparagraph 134.1.1 of paragraph 134.1 of Article 134 and paragraph 137.5 of Article 137 of this Code shall be calculated for the entire reporting year, including taking into account income received for periods of such year in which such a taxpayer was subject to payment of a single tax at a rate of 2 percent.
{Clause 9, subsection 8, section XX is supplemented by subparagraph 9.11 in accordance with Law No. 2173-IX of 01.04.2022 }
{Subsection 8 of Section XX supplemented by paragraph 9 in accordance with Law No. 2120-IX of March 15, 2022 }
9 - 1. Features of the transition of business entities that used the taxation features established by paragraph 9 of this subsection to the taxation system in which such taxpayers were before choosing the taxation features provided for by paragraph 9 of this subsection
9 - 1 .1. Single tax payers of the third group who, as of July 31, 2023, used the taxation features established by paragraph 9 of this subsection and did not refuse to use them independently, from August 1, 2023 are automatically considered to be applying the taxation system under which such taxpayers were before choosing the taxation features provided for by paragraph 9 of this subsection.
Newly created business entities that, from the date of state registration, have chosen a simplified taxation system taking into account the features of taxation established by paragraph 9 of this subsection, are automatically considered payers of the third group of single tax with a single tax rate in the amount determined by subparagraph 2 of paragraph 293.3 of Article 293 of this Code.
9 - 1 .2. Taxpayers whose registration as a value-added tax payer has been suspended in accordance with subparagraph 9.5 of paragraph 9 of this subsection and who have had their rights and obligations established by Section V and Subsection 2 of Section XX of this Code automatically restored from August 1, 2023 , for goods, non-current assets purchased/manufactured/imported into the customs territory of Ukraine with value-added tax before the start of application of the taxation features established by paragraph 9 of this subsection, which are used (supplied, sold) during the period of application of the taxation features established by paragraph 9 of this subsection, are obliged to calculate tax liabilities in accordance with paragraph 198.5 of Article 198 of this Code no later than October 31, 2023 . At the same time, the tax base when calculating tax liabilities for non-current assets is determined based on the book value (residual value) as of the first day of the month in which they were used (delivered, sold), and in the absence of accounting for non-current assets - based on the usual price, for goods - based on the cost of their acquisition.
9 - 1 .2.1. Taxpayers whose registration as a value-added tax payer has been suspended in accordance with subparagraph 9.5 of paragraph 9 of this subsection and who have had their rights and obligations established by Section V and Subsection 2 of Section XX of this Code automatically restored from August 1, 2023, shall, no later than October 31, 2023, include in the tax credit the amounts of value-added tax paid upon import of goods, non-current assets, upon application of the taxation features established by paragraph 9 of this subsection. At the same time, such taxpayers are obliged, no later than October 31, 2023, to calculate tax liabilities in accordance with Clause 198.5 of Article 198 of this Code for goods, non-current assets imported into the customs territory of Ukraine and used (supplied, sold) during the period of application of the taxation features established by Clause 9 of this subsection, in the reporting period in which the amounts of value added tax paid upon import of such goods, non-current assets during the application of the taxation features established by Clause 9 of this subsection are included in the tax credit. The tax base when calculating tax liabilities for such non-current assets is determined based on the book value (residual value) as of the first day of the month during which they were used (delivered, sold), and in the absence of accounting for non-current assets - based on the usual price, for goods - based on their acquisition cost (customs value).
At the same time, in calculating the indicator Σ Customs The amounts of value added tax paid upon import of goods into the customs territory of Ukraine for the period during which the taxpayer applied the taxation features established by paragraph 9 of this subsection shall be taken into account.
9 - 1 .3. Taxation with corporate income tax of taxpayers who have temporarily switched to paying a single tax, taking into account the features established by paragraph 9 of this subsection, and from August 1, 2023, return to paying corporate income tax, is carried out taking into account the following features:
9 - 1 .3.1. Payers shall prepare and submit a corporate income tax return with a cumulative total from the beginning of the 2023 calendar year. In this case, the results of activities for periods of being subject to the single tax shall not be taken into account when determining the object of taxation by corporate income tax specified in subparagraph 134.1.1 of paragraph 134.1 of Article 134 of this Code, taking into account the provisions of subsection 4 of this section for corporate income tax payers who have switched from the simplified taxation system to the general one.
9 - 1 .3.2. For taxpayers whose annual income from any activity (net of indirect taxes), determined according to the indicators of the Statement of Financial Results (Statement of Comprehensive Income) for the previous annual reporting period - 2022, does not exceed 40 million hryvnias, an annual reporting period is established in 2023.
For taxpayers whose annual income from any activity (net of indirect taxes), determined according to the indicators of the Statement of Financial Results (Statement of Comprehensive Income) for the previous annual reporting period - 2022, exceeds 40 million hryvnias, a base quarterly reporting period is established in 2023.
9 - 1 .3.3. The amount of annual income from any activity (net of indirect taxes) of a payer of corporate income tax for the purposes of applying subparagraph 39.2.1.7 of subparagraph 39.2.1 of paragraph 39.2 of Article 39, subparagraph 134.1.1 of paragraph 134.1 of Article 134 and paragraph 137.5 of Article 137 of this Code shall be calculated for the entire reporting year 2023, including taking into account income received for the periods of 2023 in which such a taxpayer was subject to payment of a single tax.
9 - 1 .3.4. For the purposes of calculating depreciation in accordance with the provisions of subparagraph 138.3.1 of paragraph 138.3 of Article 138 of this Code , taxpayers shall take into account the amount of the residual value of fixed assets and intangible assets that were put into operation before the taxpayer's transition to paying the single tax and during the payment of the single tax, which is determined as the difference between the original cost and the amount of calculated depreciation in accordance with the provisions of Article 138 of this Code (including during the period of payment of the single tax).
The useful life (use) of fixed assets and intangible assets shall be determined taking into account the minimum permissible depreciation periods in accordance with Article 138 of this Code and the date of putting such non-current assets into operation before the payer's transition to paying a single tax or during the payment of a single tax. In this case, when determining the minimum permissible depreciation periods for fixed assets put into operation before the payer's transition to paying a single tax, the provisions of paragraph 43 - 1 shall also be taken into account. subsection 4 of this section.
9 - 1 .3.5. For the purposes of applying in 2023 paragraph 140.2 of Article 140 of this Code:
Interest accrued in accounting during the period of payment of the single tax on credits, loans and other debt obligations arising from transactions with non-residents is not taken into account;
The amounts of financial expenses according to financial reporting data and the amounts of depreciation deductions for the period of payment of the single tax are not taken into account;
The amount of debt obligations arising from transactions with non-residents and the amount of equity are determined as the arithmetic average of the values of such debt obligations and, accordingly, equity at the beginning of the reporting period for determining tax liabilities for corporate income tax and at the end of the relevant reporting tax period for this tax, taking into account the interest specified in paragraph 140.3 of Article 140 of this Code.
9 - 1 .3.6. For the purposes of applying in 2023 subparagraphs 140.5.4 and 140.5.5 - 1 of paragraph 140.5 of Article 140 of this Code, the cost of purchased or sold goods (works, services) during periods of payment of the single tax shall not be taken into account.
9 - 1 .3.7. For the purposes of applying subparagraph 140.5.7 of paragraph 140.5 of Article 140 of this Code in 2023 , the amount of royalties reflected as expenses when determining the financial result before taxation in accordance with the accounting rules for periods of payment of the single tax shall not be taken into account.
9 - 1 .3.8. For the purposes of applying in 2023 subparagraph 140.4.6 of paragraph 140.4 and subparagraph 140.5.8 of paragraph 140.5 of Article 140 of this Code, the amounts of revaluation and write-downs included in the financial result before taxation on equity instruments reclassified into financial liabilities in accordance with national accounting regulations (standards) or international financial reporting standards for periods of being subject to the single tax shall not be taken into account.
9 - 1 .4. The collection of a single tax by payers who, before August 1, 2023, used the taxation features established by paragraph 9 of this subsection shall be carried out taking into account the following features:
9 - 1 .4.1. Taxpayers who, as of July 31, 2023, used the features of taxation established by clause 9 of this subsection and did not refuse to use them independently, and were single tax payers before the transition to such features, from August 1, 2023 are automatically considered single tax payers of the single tax group in which they were before the transition to the application of the features of the third group established by clause 9 of this subsection.
Income received during the period of application of the taxation features established by Clause 9 of this subsection shall not be included in the amount of income determined for the relevant group of single tax payers established by Clause 291.4 of Article 291 of this Code.
9 - 1 .4.2. The requirements established by paragraph 291.4 of Article 291 of this Code for the relevant group of single tax payers regarding the number of persons who are in employment relations with such a taxpayer must be met by the first day of the month following the calendar month in which the taxpayer lost the right or independently refused to use the taxation features established by paragraph 9 of this subsection.
The restrictions established by paragraphs 291.5 and 291.5 - 1 of Article 291 of this Code for single tax payers must be fulfilled by the first day of the month following the calendar month in which the taxpayer lost the right or independently refused to use the taxation features established by paragraph 9 of this subsection.
9 - 1 .4.3. To establish that in the 2023 reporting year, the amount of income for the relevant group of single tax payers, established by clause 291.4 of Article 291 of this Code, is determined in proportion to the number of calendar months of the current calendar year during which the single tax payer did not apply the taxation features established by clause 9 of this subsection.
9 - 1 .4.4. To establish that in the 2023 reporting year, business entities that in 2023 used the taxation features established by this paragraph and lost the right or independently refused to use the taxation features established by paragraph 9 of this subsection and were transferred to the payment of other taxes and fees specified by this Code, or for which state registration of termination of entrepreneurial activity was carried out, have the right in 2023 to re-transition (choose) to the simplified taxation system, including in the event of repeated state registration during 2023 by an individual entrepreneur, by submitting an application according to the general procedure specified by this Code.
At the same time, if the application is submitted by September 1, 2023, the business entity is considered a single tax payer from August 1, 2023 (except for the third group single tax with a single tax rate in the amount determined by subparagraph 1 of paragraph 293.3 of Article 293 of this Code, if such a person is not registered as a value added tax payer as of August 1, 2023).
9 - 1 .4.5. To establish that in 2022 and 2023, when determining the amount of tax debt for the application of subparagraph 8 of subparagraph 298.2.3 of paragraph 298.2 of Article 298 of this Code for single tax payers of the first or second group, the amounts of tax debt that arose for the tax periods from April 1, 2022 to July 31, 2023 shall not be included.
{Subsection 8 of Section XX supplemented by paragraph 9 - 1 in accordance with Law No. 3219-IX of 06/30/2023 }
10. For the period from March 1, 2022 until the first day of the month following the date of the end of hostilities or temporary occupation in the relevant territory, for single tax payers of the fourth group, who own or use, including under lease, land plots (land shares (shares)) located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation, the provisions of subparagraph 291.5 - 1.3 of paragraph 291.5 - 1 of Article 291 of this Code shall apply exclusively during the registration of a business entity as a single tax payer .
10.1. For the purposes specified in subparagraph "a" of subparagraph 4 of paragraph 291.4 of Article 291, subparagraph 298.8.4 of paragraph 298.8 of Article 298 and subparagraph 4 of paragraph 299.10 of Article 299 of this Code, the share of agricultural production for the previous tax (reporting) year of single tax payers of the fourth group, in which at least 30 percent of the total area of agricultural lands and/or water fund lands owned or used by them, including under lease, in the previous tax (reporting) year was located for at least six months in the territories where hostilities are (were) being conducted, or in the territories of Ukraine temporarily occupied by the Russian Federation, must be equal to or exceed 50 percent.
10.2. The dates of the beginning and end of active hostilities or temporary occupation are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Subsection 8 of Section XX supplemented by paragraph 10 in accordance with Law No. 3050-IX of 11.04.2023 }
11. To establish that from August 1, 2023, individuals - entrepreneurs - payers of the single tax of the first and second groups, whose tax address is located in the territories of hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation as of the date of the beginning of hostilities or temporary occupation, have the right not to pay the single tax for the period from the first day of the month in which hostilities began in the relevant territory, the possibility of hostilities arose, or the temporary occupation of such territory began, until the last day of the month in which such active hostilities were completed, the possibility of hostilities ceased, or the temporary occupation was completed.
At the same time, such persons do not fill out the declaration of a single tax payer - an individual entrepreneur for the period in which, in accordance with the first paragraph of this paragraph, the single tax was not paid.
For such single tax payers who have exercised the right not to pay the single tax, the regulatory authority shall not charge advance payments for the single tax, as determined by Clause 295.2 of Article 295 of this Code.
Tax liabilities for the payment of a single tax are accrued to such single tax payers for the periods for which the single tax was paid, which are reflected in the single tax payer's declaration.
Penalties and fines for non-payment (non-transfer) or payment (transfer) of less than the full amount of advance payments for the single tax in the manner and within the time limits specified by this Code shall not apply to such payers.
The dates of the beginning and end of active hostilities, the emergence and cessation of the possibility of hostilities or the beginning and end of temporary occupation are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The provisions of this paragraph shall not apply from the first day of the month following the month in which the state registration of the change of location of an individual entrepreneur to a territory of Ukraine other than that specified in the first paragraph of this paragraph was carried out.
{Subsection 8 of Section XX supplemented by paragraph 11 in accordance with Law No. 3219-IX of 06/30/2023 }
12. To establish that for single tax payers who have exercised the right not to pay the single tax in accordance with subparagraph 9.1 of paragraph 9 of this subsection, the amounts of advance payments for the single tax, the amounts of penalties and fines for non-payment (non-transfer) or payment (transfer) of less than the full amount of advance payments for the single tax in the manner and within the time limits specified by this Code, calculated by the controlling body, shall be subject to cancellation (cancellation) for the relevant periods from April 1, 2022 to July 31, 2023.
Tax liabilities for the payment of the single tax are accrued to such single tax payers for the periods for which the single tax was actually paid, as reflected in the single tax payer's declaration.
{Subsection 8 of Section XX supplemented by paragraph 12 in accordance with Law No. 3219-IX of 06/30/2023 }
of paragraph 192.2 of Article 192 of this Code shall not apply to transactions for the return of goods/non-current assets acquired while using the taxation features established by paragraph 9 of this subsection, if such return transactions are carried out no later than October 31, 2023 .
Confirmation of freight and transport invoices drawn up in accordance with the Law of Ukraine "On Road Transport" of operations for the transportation of goods/non-current assets acquired by the buyer while using the taxation features established by paragraph 9 of this subsection is not required in connection with the return of such previously delivered goods/non-current assets to the property of the supplier, as well as in connection with their subsequent supply to the same buyer, if such transportation operations are carried out in the period from August 1, 2023 to October 31, 2023 inclusive.
{Subsection 8 of Section XX supplemented by paragraph 13 in accordance with Law No. 3219-IX of 06/30/2023 }
14. To establish that within six months from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Support for Enterprises of the Defense-Industrial Complex", a legal entity - a payer of a single tax of the fourth group has the right to submit a tax return on corporate income tax for the tax (reporting) periods of 2022 and/or 2023, and/or 2024, and/or 2025 and, in the event of the presence for the relevant tax (reporting) year of income (profits) from transactions on the sale or other alienation of securities and income received from the issuer of corporate rights, investment certificates or other securities certifying its right of ownership of a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit, and calculated according to accounting rules, to pay income tax in the manner and amount established by Section III of this Law. Code.
In the event that a legal entity - a single tax payer of the fourth group of tax obligations fulfills in accordance with paragraph one of this paragraph, when calculating the share of agricultural production of such a taxpayer, the total amount of income of the agricultural producer for the relevant tax (reporting) year shall not include the relevant income (profits) from transactions on the sale or other alienation of securities and income received from the issuer of corporate rights, investment certificates or other securities certifying its ownership right to a share (unit) in the property (assets) of the issuer, in connection with the distribution of part of its profit, and calculated according to accounting rules.
{Subsection 8 of Section XX is supplemented by paragraph 14 pursuant to the Act No. 4577-IX dated 21.08.2025 }
Subsection 9. Features of refunding tax amounts from owners of vehicles and other self-propelled machines and mechanisms, environmental pollution fees, as well as local taxes and fees↑
1. Refunds of tax amounts from owners of vehicles and other self-propelled machines and mechanisms, environmental pollution fees, as well as local taxes and fees that were paid before January 1, 2011 in error or in excess, crediting to the budgets of such taxes and fees paid in the first quarter of 2011 for the last reporting (tax) period of 2010, and amounts paid to repay tax debt that arose as of December 31, 2010, shall be carried out in accordance with the procedure and under the conditions that were in effect before January 1, 2011.
2. Individuals who are owners of vehicles that, according to the legislation, are subject to technical inspection once every two years, when undergoing such technical inspection in 2011 or removing vehicles from registration, are required to present to the bodies carrying out deregistration or technical inspection of vehicles, receipts or payment orders for payment of the tax for 2010 on owners of vehicles and other self-propelled machines and mechanisms at the rates that were in effect until January 1, 2011, and individuals who were exempted from paying it in 2010 - a document giving the right to use such benefits. In the event of failure to submit such documents, technical inspection of vehicles and their removal from registration shall not be carried out.
Subsection 9 - 1. Peculiarities of charging rent for the use of subsoil for the extraction of minerals↑
1. Temporarily, in the period from January 1, 2016 to April 1, 2016, the rate of rent for the use of subsoil for the extraction of natural gas, determined by Clause 252.20 of Article 252 of this Code, for natural gas that meets the condition specified in Clause 252.24 of Article 252 of this Code, extracted from deposits up to 5,000 meters, is set at 70 percent, and from April 1, 2016 to December 31, 2016 (inclusive) - 50 percent.
2. The State guarantees that from January 1, 2018 to March 1, 2022, the incentive rate of the subsoil use rent for natural gas extracted from new wells, established by this Code as of January 1, 2018, will be applied. The amount of the incentive rate may not be increased, nor may it be subject to any corrective coefficients or other mechanisms that may be provided for by this Code or other acts of legislation that will or may lead to an actual increase in the amount of tax liabilities from the subsoil use rent for natural gas extraction compared to the amount of such tax liabilities calculated in accordance with this Code as of January 1, 2018. In the event of amendments to the legislation regulating the tax procedure for stimulating natural gas extraction, business entities may choose a new incentive procedure.
{Subsection 9 - 1 of Section XX supplemented by paragraph 2 in accordance with Law No. 2245-VIII of 07.12.2017 ; as amended by Law No. 2139-IX of 15.03.2022 - regarding the entry into force and operation of the Law, see paragraph 1 of Section II}
3. To temporarily establish the rate of rent for the use of subsoil for the extraction of amber, determined by paragraph 252.20 of Article 252 of this Code:
until December 31, 2020 inclusive - in the amount of 5 percent;
until December 31, 2021 inclusive - in the amount of 8 percent.
{Subsection 9 - 1 of Section XX supplemented by paragraph 3 in accordance with Law No. 490-IX of 04.02.2020 }
4. The State guarantees that from March 1, 2022 to March 1, 2032, the rates of subsoil use for the extraction of minerals will be applied to the extraction of natural gas (of any origin), including the rates of subsoil use for natural gas extracted from new wells, established by Clause 252.20 of Article 252 of this Code as of March 1, 2022. The State guarantees that the term of application of the rates of subsoil use for the extraction of natural gas (of any origin) specified in this Article shall not be subject to cancellation, reduction or revision until March 1, 2032.
During this period:
the rates of the subsoil rent for the use of natural gas (of any origin) specified in Clause 252.20 of Article 252 of this Code, including the subsoil rent for natural gas extracted from new wells specified as of March 1, 2022, may not be increased, nor may they be subject to any adjustment coefficients or other mechanisms that may be provided for by this Code or other acts of legislation that will or may result in an actual increase in the amount of tax liabilities from the subsoil rent for the use of natural gas compared to the amount of such tax liabilities calculated in accordance with this Code as of March 1, 2022;
The rates of subsoil use rent for natural gas extraction, including incentive rates of subsoil use rent for natural gas extracted from new wells, may be reduced at any time and may be subject to adjustment coefficients or other mechanisms that may be provided for by this Code or other acts of legislation, which will lead to an actual reduction in the amount of tax liabilities from subsoil use rent for natural gas extraction compared to the amount of such tax liabilities calculated in accordance with this Code as of March 1, 2022.
{Subsection 9 - 1 of Section XX is supplemented by paragraph 4 in accordance with Law No. 2139-IX of March 15, 2022 - regarding the entry into force and operation of the Law, see paragraph 1 of Section II}
{Chapter XX supplemented by subsection 9 - 1 in accordance with the Law No. 1621-VII of 31.07.2014 ; as amended by Law No. 71-VIII of 28.12.2014 ; text of subsection 9 - 1 Chapter XX as amended by Law No. 909-VIII of 24.12.2015 }
Subsection 9 - 2. Features of clarifying tax obligations for corporate income tax and value added tax when applying a tax compromise↑
1. Tax compromise is a regime of exemption from legal liability of taxpayers and/or their officials (service personnel) for understating tax liabilities on corporate income tax and/or value added tax for any tax periods before April 1, 2014, taking into account the limitation periods established by Article 102 of this Code. A taxpayer who has decided to use the tax compromise procedure, during the validity of the tax compromise for such tax periods has the right to submit appropriate clarifying calculations of tax liabilities on corporate income tax and/or value added tax, in which he determines the amount of overstatement of expenses taken into account when determining the object of taxation by corporate income tax and/or the amount of overstatement of the tax credit on value added tax.
Clarifying calculations of tax liabilities for corporate income tax and/or value added tax are submitted in the form established by the central executive body responsible for the formation of state financial policy. Together with the clarifying calculation, a list (description) of business transactions for which the tax return indicators have been clarified is submitted.
of Article 50 of this Code shall not apply to cases of submission of clarifying calculations of tax liabilities in accordance with this subsection .
When preparing clarifying calculations of tax liabilities for the application of a tax compromise, the amounts of adjustments to the value added tax tax credit and/or expenses taken into account when calculating the object of taxation by income tax, reflected in the clarifying calculations, which simultaneously meet the following conditions, are not taken into account:
1) submitted in accordance with the procedure established by Article 50 of this Code after April 1, 2014;
2) clarify the indicators of tax returns for reporting (tax) periods preceding April 1, 2014;
3) based on the results of submitting such clarifying calculations, the tax liability for income tax or value added tax for such reporting (tax) periods was reduced (the negative value was increased).
As a result of the application of the tax compromise, the taxpayer may not incur or increase erroneously and/or excessively paid monetary obligations.
2. The amount of the understated tax liability for corporate income tax and/or value added tax shall be paid in the amount of 5 percent of such amount. In this case, 95 percent of the amount of the understated tax liability for corporate income tax and/or value added tax shall be considered repaid, penalties shall not be applied, and no penalty shall be charged.
The amount of the repaid tax liability for income tax and/or value added tax in the amount of 95 percent as a result of the application of the tax compromise is not taken into account for determining the object of taxation by corporate income tax.
3. The procedure for reaching a tax compromise lasts no more than 70 calendar days from the day following the day of submission of the clarifying calculation.
Submission by a taxpayer of a clarifying calculation for periods for which a documentary audit was not conducted may be grounds for conducting an unscheduled documentary audit under the tax compromise procedure.
Within 10 business days from the day following the day of submission of the clarifying calculation, the regulatory authority shall make a decision on the need to conduct an unscheduled documentary audit, of which it shall notify the taxpayer in accordance with Article 42 of this Code.
A documentary unscheduled inspection is conducted exclusively on issues related to expenses taken into account when determining the object of taxation by corporate income tax and/or the amount of overstatement of the value-added tax tax credit, within the framework of the procedure for reaching a tax compromise.
If the regulatory authority has notified the taxpayer of the absence of the need to conduct an unscheduled documentary audit, the amount of declared liabilities is considered agreed.
In the event of a decision on the need to conduct an unscheduled documentary inspection, the regulatory authority conducts such an inspection and, based on its results:
1) adopts a tax notice-decision in the event of detection of violations by the taxpayer of the requirements of tax legislation, payment of the monetary obligation for which is made in the amount provided for in paragraph 2 of this subsection;
2) draws up a certificate in the absence of such violations, confirming the legality of determining the amounts of tax liabilities in the clarifying calculation.
The tax notice-decision or certificate shall be sent by the controlling authority to the taxpayer in accordance with the procedure provided for in Articles 42 and 58 of this Code.
4. Clarification by a taxpayer of tax liabilities by submitting a clarifying calculation in accordance with this subsection does not affect the amount of tax liabilities of his counterparties.
5. The taxpayer shall pay the tax liabilities specified in the clarifying calculation and/or tax notice-decision, in the amount specified in paragraph 2 of this subsection, within 10 calendar days from the day following the day of approval. The day of approval shall be the day of receipt of the notification from the controlling body that there is no need to conduct an unscheduled documentary audit, and in the event of a decision to conduct an unscheduled documentary audit, the day of receipt of a certificate confirming the legality of determining the amounts of tax liabilities in the clarifying calculation, or the day of receipt of the tax notice-decision adopted based on the results of such audit.
6. If a taxpayer initiates an administrative and/or judicial appeal of a tax notice-decision issued by a regulatory authority based on the results of an unscheduled documentary inspection pursuant to this subsection, the tax compromise shall not apply.
7. The tax compromise procedure established by this subsection also applies to the unreconciled amounts of tax liabilities for corporate income tax and/or value added tax, specified in tax notices-decisions, in respect of which the procedure of judicial and/or administrative appeal is ongoing, as well as to cases where the taxpayer has received a tax notice-decision, according to which the tax liabilities are not reconciled in accordance with the provisions of this Code. Achieving a tax compromise in such a case is carried out upon the taxpayer's written application to the supervisory authority about the intention to achieve a tax compromise. In such cases, the day of reconciliation by the taxpayer of the tax liabilities specified in the tax notice-decision is the day of submission of such application to the relevant supervisory authority. In the event of non-payment by the taxpayer of such a tax liability in the amount specified in paragraph 2 of this subsection, such a tax liability shall be considered unreconciled.
The tax compromise procedure regarding the amount and terms of payment of the understated tax liability for corporate income tax and/or value added tax, established by this subsection, also applies to cases where, regardless of the tax compromise procedure, a documentary audit has been initiated for the taxpayer by decision of the supervisory authority or a report has been drawn up based on the results of such an audit. In such cases, the taxpayer has the right to submit to the supervisory authority that has ordered a documentary audit or drawn up a report based on the results of such an audit, the relevant clarifying calculations of tax liabilities for tax declarations for the reporting tax periods in the manner specified in paragraph 1 of this subsection.
8. A tax compromise shall be deemed to have been reached upon payment by the taxpayer of the agreed tax obligations pursuant to this subsection.
Once a tax compromise has been reached under this subsection, such obligations shall not be subject to appeal and their amount may not be changed in other tax periods.
9. In the event of reaching a tax compromise, audits of corporate income tax and/or value added tax on specified transactions in subsequent periods for the specified taxes shall not be conducted by the supervisory authorities.
10. An action committed by a taxpayer or his officials (service personnel) that resulted in an understatement of his tax liabilities for corporate income tax and/or value added tax, if such tax liabilities were specified according to the procedures for applying a tax compromise and paid to the budgets, shall not be considered intentional evasion of taxes, fees (mandatory payments).
11. Tax compromise, taking into account the limitation periods in accordance with Article 102 of this Code, applies to legal relationships that arose before April 1, 2014, and applies exclusively to tax liabilities for corporate income tax and/or value added tax, regardless of whether inspections by regulatory authorities were conducted or not during such periods.
12. Taxpayers for the purpose of applying a tax compromise have the right to submit clarifying calculations or statements in accordance with the provisions of this subsection within 90 calendar days from the date of entry into force of this subsection.
{Chapter XX supplemented by subsection 9 - 2 in accordance with Law No. 63-VIII of 25.12.2014 }
Subsection 9 - 3. Peculiarities of charging rent for the use of radio frequency resources of Ukraine↑
1. Temporarily, until December 31, 2020 inclusive, the rental fee rate for the use of the radio frequency resource of Ukraine for the types of radio communication provided for in subparagraph 16 - 1 Clause 254.4 of Article 254 of this Code is set at 458.30 hryvnias per month for 1 megahertz of radio frequency band.
by Clause 254.4 of Article 254 of this Code shall not apply to the rental rates for the use of the radio frequency resource of Ukraine, provided for in Clause 254.4 of Article 254 of this Code for the type of radio communication "cellular radio communication", for the width of the radio frequency bandwidth obtained in accordance with the license for the use of the radio frequency resource of Ukraine, issued from January 1, 2022 on a competitive or tender basis.
{Subsection 9 - 3 of Section XX supplemented by paragraph 2 in accordance with Law No. 1914-IX of 30.11.2021 }
3. Until the termination or cancellation of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the rental rates for the use of the radio frequency spectrum (radio frequency resource) of Ukraine are set at the following rates (except for the reduction coefficients specified in this paragraph, which apply until September 1, 2024):
Type of radio communication
Radio frequency range
Rental fee rate for 1 MHz of radio frequency band per month, hryvnias
1.
Radio relay communication of the fixed radio service
0.03-300 GHz
1.30
2.
Radio communication:
fixed, mobile land radio services
0.03-470 MHz
1274.57
maritime radio service
0.03-470 MHz
637.29
3.
Radio communication in the security and fire alarm system
30-470 MHz
1274.57
4.
Radio communication using radio extenders
30-470 MHz
639.28
5.
Radio communication in a data transmission system using noise-like signals
1427-2400 MHz 2400-2483.5 MHz 5150-5850 MHz
32.20 - 1
6.
Radio communication in a system with fixed subscriber radio access of the DECT standard
30-3000 MHz
64.33
7.
Trunked radio communication
30-470 MHz
3952.32
8.
Search radio communication
30-960 MHz
50982.39
9.
Radar and radio navigation radio services
30-3000 MHz 3-30 GHz
128.64
10.
Radiocommunication of satellite mobile and fixed radio services
Radio communication in multi-channel distribution systems for transmission and retransmission of television images, sound transmission, digital information
Transmission and retransmission of television images depending on power:
30-300 MHz
from 1 to 10 W inclusive
64.33
from 10.1 to 100 W inclusive
193.01
from 101 W to 1 kW inclusive
317.63
from 1.1 to 5 kW inclusive
510.65
from 5.1 to 20 kW inclusive
956.94
from 20.1 kW and above
1274.57
15.
Sound transmission depending on power:
66-74 MHz 87.5-108 MHz
up to 100 W inclusive
478.46
from 101 W to 1 kW inclusive
956.94
from 1.1 to 10 kW inclusive
1527.84
from 10.1 kW and above
1913.82
16.
Transmission and retransmission of television images depending on power:
300-880 MHz
up to 10 W inclusive
44.24
from 10.1 to 100 W inclusive
88.45
from 101 W to 1 kW inclusive
193.01
from 1.1 to 5 kW inclusive
382.02
from 5.1 to 20 kW inclusive
763.93
from 20.1 kW and above
956.94
16 - 1 .
Types of radio communication (regardless of service, system, radio technology, radio electronic means, radiating devices)
2300-2400 MHz 2575-2610 MHz 3400-3800 MHz
3685.50
17.
Types of radio communication (services, systems, radio technologies, radio electronic means, radiating devices) not specified in paragraphs 1-16 - 1 paragraph 3 of this subsection
9 kHz-400 GHz
1913.82
- 1 For the width of the radio frequency bandwidth up to 30 MHz (15 x 2) in each region separately, belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, a reduction coefficient of 0.75 is applied.
- 2 For the width of a continuous interval (solid band) of radio frequencies less than 10 MHz (5 x 2) in each region separately and/or in all regions of Ukraine belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, an increasing coefficient of 1.2 is applied.
- 3 For the width of the radio frequency bandwidth exceeding 20 MHz (10 x 2) in each region separately, belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, an increasing coefficient of 1.4 is applied.
- 4 For the width of a continuous interval (solid band) of radio frequencies in all regions of Ukraine, equal to or exceeding 10 MHz (5 x 2) in each region, provided that the total width of the radio frequency band does not exceed 20 MHz (10 x 2) in one radio frequency range belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, a reduction coefficient of 0.75 is applied.
- 5 For the width of the radio frequency bandwidth exceeding 30 MHz (15 x 2) in each region separately, belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, an increasing coefficient of 1.4 is applied.
- 6 For the width of a continuous interval (solid band) of radio frequencies in all regions of Ukraine, equal to or exceeding 10 MHz (5 x 2) in each region, provided that the total width of the radio frequency band does not exceed 30 MHz (15 x 2) in one radio frequency range belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, a reduction coefficient of 0.75 is applied.
- 7 For the width of the radio frequency bandwidth exceeding 40 MHz (20 x 2) in each region separately, belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, an increasing coefficient of 1.4 is applied.
- 8 For the width of a continuous interval (solid band) of radio frequencies in all regions of Ukraine, equal to or exceeding 10 MHz (5 x 2) in each region, provided that the total width of the radio frequency band does not exceed 40 MHz (20 x 2) in one radio frequency range belonging to a separate rent payer - a user of the radio frequency spectrum (radio frequency resource) of Ukraine, a reduction coefficient of 0.75 is applied.
The increasing and decreasing coefficients provided for in these notes are applied separately to the taxable object by adding/subtracting the monetary value of the corresponding coefficient to it. The monetary value of the coefficient is calculated by determining the difference between the taxable object to which the coefficient is applied, multiplied by the coefficient, and the taxable object to which the coefficient is applied.
Every month, by the 10th of the month following the reporting month, the national commission carrying out state regulation in the field of communications and informatization shall publish on its official website, and shall also provide the central executive body implementing state tax policy with information on issued licenses for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, indicating the radio frequency bands and taking into account the radio technology and technological features of the use of such bands for each payer of the rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, who calculates the amount of the rental fee in accordance with item 11 of this item, in the amounts necessary to determine the need to apply coefficients to the rental fee rates for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, provided for by these notes, in the form approved by the national commission carrying out state regulation in the field of communications and informatization and the central body executive branch, which ensures the formation and implementation of state financial policy.
{Subsection 9 - 3 of Section XX supplemented by paragraph 3 in accordance with Law No. 3721-IX of 05/21/2024 }
4. To establish that the coefficients established by paragraph 3 of this subsection shall not apply to the rental rates for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, provided for in paragraph 3 of this subsection for the type of radio communication "cellular radio communication", for the width of the radio frequency bandwidth obtained in accordance with the license for the use of the radio frequency spectrum (radio frequency resource) of Ukraine, issued from January 1, 2022 on a competitive or tender basis.
{Subsection 9 - 3 of Section XX supplemented by paragraph 4 in accordance with Law No. 3721-IX of 05/21/2024 }
{Chapter XX supplemented by subsection 9 - 3 in accordance with Law No. 466-IX of January 16, 2020 }
Subsection 9 - 4. Features of the application of one-time (special) voluntary declaration of assets of individuals↑
1. One-time (special) voluntary declaration is a special procedure for voluntary declaration by an individual, defined in paragraph 3 of this subsection, of assets belonging to him or her, located in the territory of Ukraine and/or abroad, if such assets of an individual were received (acquired) by such individual at the expense of income that was subject to taxation in Ukraine at the time of their accrual (receipt) and from which taxes and fees were not paid or were not paid in full in accordance with the requirements of the legislation on taxation and/or international treaties, the consent to the binding nature of which was granted by the Verkhovna Rada of Ukraine, and/or which were not declared in violation of tax and currency legislation, the control over compliance with which is entrusted to regulatory authorities, during any of the tax periods that took place before January 1, 2021.
One-time (special) voluntary declaration is carried out from September 1, 2021 to March 1, 2023 (hereinafter referred to as the period of one-time (special) voluntary declaration) and provides for the payment of a one-time (special) voluntary declaration fee in the manner, terms and amounts established by this Code, and fulfillment of other conditions specified in this subsection.
{Paragraph two of clause 1 of subsection 9 - 4 as amended by Law No. 2516-IX of 08/15/2022 }
Submission of a one-time (special) voluntary declaration is not a separate special procedure for official recognition or confirmation by the state of the facts of the emergence, transfer or termination of rights to assets for which such a one-time (special) voluntary declaration is submitted.
2. The fee for a one-time (special) voluntary declaration is a one-time mandatory payment, the amount of which is independently calculated by the declarant from the value of his assets, taking into account the rates of such a fee determined by this subdivision, and is reflected by him in the one-time (special) voluntary declaration.
3. One-time (special) voluntary declaration may be used by resident individuals, including self-employed persons, as well as individuals who are not residents of Ukraine, but who were residents at the time of receiving (acquiring) the objects of declaration or at the time of accrual (receiving) of income, at the expense of which the objects of declaration were received (acquired), and who, in accordance with this Code, are or were taxpayers (hereinafter referred to as the declarant).
Declarants cannot be persons who, as of the date of the start of the one-time (special) voluntary declaration period, are minors or incapacitated persons and are fully dependent on other persons (including parents) and/or the state, or are persons whose legal capacity is limited and guardianship/trusteeship has been established over such persons.
Declarants may also not be persons who, for any period starting from January 1, 2010, perform or have performed in Ukraine public functions stipulated by Clause 37 of Part One of Article 1 of the Law of Ukraine "On Prevention and Counteraction to the Legalization (Laundering) of Proceeds of Crime, Financing of Terrorism and Financing of the Proliferation of Weapons of Mass Destruction".
{Paragraph three of clause 3 of subsection 9 - 4 as amended by Law No. 1914-IX of 11/30/2021 }
Declarants cannot be persons against whom Ukraine has applied special economic and other restrictive measures (sanctions) in accordance with the Law of Ukraine "On Sanctions".
Persons who have the right under this subsection to exercise the right to a one-time (special) voluntary declaration and have not exercised such right are considered to have notified the regulatory authority of the absence of ownership as of the date of completion of the period for conducting a one-time (special) voluntary declaration of assets of an individual received (acquired) at the expense of income from which taxes and fees have not been paid or have not been paid in full in accordance with tax legislation at the time of accrual (receipt) of such income and/or the composition and volume of such assets are within the limits specified in paragraph 10 of this subsection.
4. Objects of a one-time (special) voluntary declaration (hereinafter referred to as objects of declaration) may be defined by subparagraphs 14.1.280 and 14.1.281 of paragraph 14.1 of Article 14 of this Code as assets of an individual that belong to the declarant under the right of ownership (including under the right of joint partial or joint joint ownership) and are located (registered, in circulation, on record, etc.) in the territory of Ukraine and/or outside its borders as of the date of submission of a one-time (special) voluntary declaration, including, but not limited to:
a) currency values (bank metals, except for those not placed in accounts, national currency (hryvnia) and foreign currency, except for funds in cash, and monetary claim rights (including deposits, funds lent to third parties under a loan agreement), drawn up in writing with a legal entity or notarized in the event of the declarant's right of claim against another individual;
b) real estate (land plots, residential and non-residential real estate).
For the purposes of this subdivision, real estate also includes objects of unfinished construction that:
not put into operation or ownership of which is not registered in accordance with the procedure established by law, but the property rights to such objects belong to the declarant by right of ownership;
not put into operation and located on land plots owned by the declarant under the right of private ownership, including joint ownership, or under the right of long-term lease or under the right of superficies;
c) movable property, including:
vehicles and other self-propelled machines and mechanisms;
other valuable movable property (works of art and antiques, precious metals, precious stones, jewelry, etc.);
d) shares (units) in the property of legal entities or in entities without the status of a legal entity, other corporate rights, property rights to intellectual property objects;
e) securities and/or financial instruments defined by law;
e) rights to receive dividends, interest or other similar property benefits not related to ownership of securities, shares (units) in the property of legal entities and/or in entities without the status of a legal entity;
f) other assets of an individual, including property, bank metals not placed in accounts, commemorative banknotes and coins, property rights belonging to the declarant or from which the declarant receives or has the right to receive income on the basis of a property management agreement or other similar transaction and does not pay the owner of such property a portion of the income due to the owner.
5. The following may not be declared:
a) assets of an individual received (acquired) by the declarant as a result of committing an act containing elements of a criminal offense, except for criminal offenses or other violations of the law related to:
evasion of taxes, fees (mandatory payments);
evasion of payment of a single contribution to mandatory state social insurance and insurance contributions to mandatory state pension insurance;
violations in the field of currency legislation;
violations in the field of protection of economic competition in terms of the violation provided for in paragraph 12 of Article 50 of the Law of Ukraine "On Protection of Economic Competition";
b ) assets of an individual belonging to a declarant in respect of whom a pre-trial investigation or legal proceedings have been initiated regarding such assets on the grounds of criminal offenses provided for in Articles 212 , 212-1 , as well as Article 366 (regarding tax and/or financial reporting documents, customs declarations, tax invoices, primary documents, other reporting on taxes, fees (mandatory payments), Article 367 (if the criminal offense is related to a violation of the requirements of tax, customs, currency and other legislation, control over compliance with which is entrusted to regulatory authorities) of the Criminal Code of Ukraine;
whom legal proceedings have been initiated for the commission of any of the criminal offenses provided for in Articles 209, 258-5 and 306 , Parts One and Two of Article 368-3 , Parts One and Two of Article 368-4 , Articles 368 , 368-5 , 369 and 369-2 of the Criminal Code of Ukraine, and/or which are subject to recovery as unfounded in accordance with the procedure established by Chapter 12 of Section III of the Civil Procedure Code of Ukraine;
d) funds in national and foreign currencies that are in cash on the date of submission of a one-time (special) voluntary declaration;
e) assets of the declarant that are recorded (located) in the accounts of financial institutions and/or located (registered) in the territory of a country recognized by the aggressor state according to law, or have sources of origin from such a country.
6. A declarant who intends to use a one-time (special) voluntary declaration regarding the assets of an individual belonging to him, during the one-time (special) voluntary declaration period specified in this subsection, has the right to voluntarily submit to the central executive body implementing state tax policy a one-time (special) voluntary declaration in the manner and form established by the central executive body ensuring the formation and implementation of state financial policy.
6.1. For the purposes of this subsection, a one-time (special) voluntary declaration is a declaration that displays the following information (data):
information about the declarant sufficient for his/her identification (surname, first name, patronymic, registration number of the taxpayer's registration card or, in cases specified by this Code, the series (if any) and passport number of a citizen of Ukraine);
information about the objects of declaration, defined by subparagraph "a" of paragraph 4 of this subsection, in a volume sufficient to identify each of them, in particular data on the type, size and currency of the asset, classification of bank metals. For monetary assets of an individual placed in accounts in banks or deposited in credit unions and other non-bank financial institutions, a one-time (special) voluntary declaration shall indicate the name and other information about the banking or non-bank financial institution (code according to the Unified State Register of Enterprises and Organizations of Ukraine; if such an institution is a foreign legal entity - the code assigned by the registration authority of legal entities of the relevant state shall be indicated), in which the relevant accounts are opened, in which currency values are stored, or to which the relevant contributions are made, and a certified document confirming the presence of the declared monetary assets of the individual in the relevant account, in accordance with the legislation.
For the rights of a monetary claim (including funds lent by the declarant to third parties under a loan agreement), the one-time (special) voluntary declaration shall indicate the name and other information about the legal entity - the debtor (code according to the Unified State Register of Enterprises and Organizations of Ukraine; if such an institution is a foreign legal entity - the code assigned by the body for registration of legal entities of the relevant state shall be indicated, or the surname, first name, patronymic and registration number of the taxpayer's registration card (or in the cases specified by this Code - the series (if any) and number of the passport of a citizen of Ukraine or the relevant document certifying the identity of a foreigner or stateless person) of the individual - the debtor, the number and date of the document confirming the right to a monetary claim;
information about the objects of declaration, defined by subparagraphs "b"-"e" of paragraph 4 of this subsection, indicating information that allows them to be identified, in particular about their location or place of storage (except for objects of art and antiques, precious metals, precious stones, jewelry, bank metals that are not placed in accounts, commemorative banknotes and coins, etc.), type, name, year of production (issue), etc.;
the base for calculating the fee for a one-time (special) voluntary declaration determined by the declarant in the national currency. The declarant is obliged to attach copies of documents confirming the value of the objects of declaration to the one-time (special) voluntary declaration, in the case of the location (registration) of the asset of an individual outside Ukraine and/or in the case of the declaration of currency values placed on bank accounts in Ukraine and the rights of monetary claim specified in subparagraph "a" of paragraph 4 of this subsection. In the case of the location (registration) of other assets of an individual in Ukraine, the declarant may attach copies of documents confirming the value of the objects of declaration;
rate and amount of the fee for a one-time (special) voluntary declaration.
A one-time (special) voluntary declaration shall not contain information on the sources of receipt (acquisition) of the objects of declaration by the declarant. The controlling body shall be prohibited from requiring additional documents, except those provided for in this paragraph.
The information contained in a one-time (special) voluntary declaration is tax information.
6.2. A one-time (special) voluntary declaration is submitted directly by the declarant to the central executive body implementing state tax policy, in electronic form, taking into account the requirements established by Section II of this Code and the features established by this subsection.
6.3. During the period of conducting a one-time (special) voluntary declaration in accordance with this subsection, the declarant has the right to clarify the information specified in the previously submitted one-time (special) voluntary declaration, exclusively by submitting a new one-time (special) voluntary declaration in the manner specified by this subsection. In this case, the previously submitted one-time (special) voluntary declaration, the information from which is being clarified, is considered canceled. After the end of the period of conducting a one-time (special) voluntary declaration, the taxpayer has the right to submit a clarifying calculation to the previously submitted one-time (special) voluntary declaration exclusively in the cases provided for by this subsection.
In the event of an increase in the base for calculating the fee for a one-time (special) voluntary declaration in a new one-time (special) voluntary declaration, an additional payment of the difference between the amount of the fee for a one-time (special) voluntary declaration specified in the new one-time (special) voluntary declaration and the amount of the fee for a one-time (special) voluntary declaration paid in accordance with the previously submitted one-time (special) voluntary declaration shall be made.
7. Determination of the base for calculating the fee for a one-time (special) voluntary declaration.
7.1. For declaration objects defined in subparagraph "a" of paragraph 4 of this subsection:
The basis for calculating the fee for a one-time (special) voluntary declaration is the monetary value of the relevant object of declaration or the nominal value of the monetary claim, including for loans granted to third parties. If such monetary value is determined in foreign currency, the value of such currency values is indicated in hryvnia at the official exchange rate of the national currency to the relevant type of currency values, determined by the National Bank of Ukraine as of the date of submission of the one-time (special) voluntary declaration. If such monetary value is determined in the form of bank metals, the value of bank metals is indicated based on the mass and accounting price of bank metals, calculated by the National Bank of Ukraine as of the date of submission of the one-time (special) voluntary declaration by the declarant.
The declarant is obliged to document the monetary value of such objects for the purpose of calculating the fee for a one-time (special) voluntary declaration by attaching to the one-time (special) voluntary declaration duly certified copies of documents confirming the value of the objects of declaration.
7.2. For the objects of declaration defined by subparagraphs "b"-"e" of clause 4 of this subsection, the base for calculating the fee for a one-time (special) voluntary declaration is determined, in particular, but not exclusively, as:
the declarant's expenses for the purchase (acquisition) of the object of declaration;
value determined on the basis of the valuation of property and property rights, financial instruments, other assets. The valuation of the object of declaration is carried out in accordance with the legislation of the country where such an asset is located. The value of assets determined in foreign currency is reflected in a one-time (special) voluntary declaration in hryvnia at the official exchange rate of the national currency established by the National Bank of Ukraine as of the date of submission of the one-time (special) voluntary declaration;
nominal value of the rights of monetary claim;
the acquisition cost or stock exchange value, valid as of the date of submission of the one-time (special) voluntary declaration, of corporate rights (shares) that are admitted to stock exchange trading;
the value of the asset in the form of precious metals, which is determined by converting the weight to the purchase price for precious metals, determined by the National Bank of Ukraine as of the date of submission of the one-time (special) voluntary declaration;
expenses for the declarant's purchase (acquisition) of securities and other financial instruments that are not admitted to stock exchange trading, and shares (units) in the property of legal entities or in entities without the status of a legal entity, other corporate rights or the nominal value of such assets specified in the relevant documents.
At the declarant's own request, for movable property (except for precious metals, vehicles and other self-propelled machines and mechanisms, works of art, precious stones (including organogenic formations) and products made from them), the basis for calculating the fee for a one-time (special) voluntary declaration may be the value of the objects of declaration, which are located (registered) in the territory of Ukraine, independently determined by the declarant.
The declarant may attach to the one-time (special) voluntary declaration the relevant documents or duly certified copies thereof, confirming the value of the objects of declaration located (registered) in the territory of Ukraine.
The declarant is obliged to document the value of the objects of declaration by attaching to the one-time (special) voluntary declaration duly certified copies of documents confirming the value of the objects of declaration, if such objects are located (registered) outside Ukraine.
8. The amount of the one-time (special) voluntary declaration fee for declared objects is determined by applying the following rates to the base for calculating the one-time (special) voluntary declaration fee, determined in accordance with paragraph 7 of this subsection:
8.1. 5 percent:
regarding currency values placed on accounts in banks in Ukraine in compliance with the requirements of clause 9 of this subsection, and regarding the right of monetary claim against residents of Ukraine, defined in subparagraph "a" of clause 4 of this subsection;
regarding the objects of declaration defined in subparagraphs "b"-"e" of clause 4 of this subsection, located (registered) in Ukraine, except for those that are taxed at the rate defined in subparagraph 8.3 of this clause.
For the purposes of a one-time (special) voluntary declaration, in order to apply the fee rate for a one-time (special) voluntary declaration provided for in subparagraph 8.1 of this paragraph, on the date of submission of a one-time (special) voluntary declaration, the declarant's funds in national and foreign currencies, bank metals must be placed in accounts in banks in Ukraine.
Alternatively, the taxpayer may choose a rate of 6 percent with payment of the tax liability in three equal installments.
{Paragraph five of subparagraph 8.1 of clause 8 of subsection 9 - 4 as amended by Law No. 2516-IX of August 15, 2022 }
8.2. 9 percent:
regarding currency values placed in accounts in foreign banks or stored in foreign financial institutions, and regarding the right to claim money from non-residents of Ukraine, defined in subparagraph "a" of paragraph 4 of this subsection;
regarding the objects of declaration defined in subparagraphs "b"-"e" of clause 4 of this subsection, located (registered) abroad, except for those that are taxed at the rate defined in subparagraph 8.3 of this clause.
For the purposes of a one-time (special) voluntary declaration, in order to apply the collection rate provided for in subparagraph 8.2 of this paragraph, the declarant's funds in foreign currency on the date of submission of such declaration must be placed in accounts in banks and/or other financial institutions abroad.
Alternatively, the taxpayer may choose a rate of 11.5 percent with payment of the tax liability in three equal installments.
{Paragraph five of subparagraph 8.2 of clause 8 of subsection 9 - 4 as amended by Law No. 2516-IX of August 15, 2022 }
8.3. 2.5 percent of the nominal value of Ukrainian government bonds with a maturity of more than 365 days without the right of early repayment, purchased by the declarant in the period from September 1, 2021 to February 28, 2023 before submitting a one-time (special) voluntary declaration.
{Paragraph one of subparagraph 8.3 of clause 8 of subsection 9 - 4 as amended by Law No. 2516-IX of August 15, 2022 }
Alternatively, the taxpayer may choose a rate of 3 percent with payment of the tax liability in three equal installments annually.
9. For the purposes of a one-time (special) voluntary declaration, the declarant must place funds in national and foreign currencies in cash and/or bank metals in current accounts with a special use regime in banks of Ukraine (hereinafter referred to as special accounts) prior to submitting a one-time (special) voluntary declaration.
After submitting a one-time (special) voluntary declaration, taking into account the provisions of paragraph one of this paragraph and during the period of the one-time (special) voluntary declaration, the declarant may once exercise the right to additionally place funds in national and/or foreign currency in cash and/or bank metals in a special account and in such case must submit a clarifying one-time (special) voluntary declaration in accordance with this subsection.
In order to ensure compliance with the provisions of this paragraph, the declarant shall apply to the bank to open a special account. The procedure for opening, closing, crediting funds to a special account and exercising control over operations on such an account shall be established by the National Bank of Ukraine.
The Bank ensures the placement of funds in cash and/or bank metals for the purposes of one-time (special) voluntary declaration in a special account after conducting a due diligence of the declarant's identity in accordance with the requirements of the legislation in the field of prevention and counteraction to the legalization (laundering) of proceeds from crime, financing of terrorism and financing of the proliferation of weapons of mass destruction (hereinafter referred to as the legislation in the field of financial monitoring).
The bank takes measures to establish the sources of origin of these assets in cases provided for by the legislation in the field of financial monitoring, after crediting them to the declarant's special account.
10. The composition and volume of assets, the sources of receipt (acquisition) of which, in the event that an individual does not exercise the right to submit a one-time (special) voluntary declaration, are considered to be those from which taxes and fees have been fully paid in accordance with tax legislation, are:
1) assets, other than those specified in subparagraphs 2 and 3 of this paragraph, the total value of which does not exceed 400 thousand hryvnias as of the date of completion of the one-time (special) voluntary declaration period. If the monetary value of such assets is determined in foreign currency/banking metals, their value is indicated in hryvnias at the official exchange rate of the national currency to foreign currency established by the National Bank of Ukraine/the accounting price of banking metals calculated by the National Bank of Ukraine on the date of submission of the one-time (special) voluntary declaration by the declarant;
2) real estate located on the territory of Ukraine, which as of the date of completion of the one-time (special) voluntary declaration period belonged to an individual under the right of ownership (including joint joint or joint partial ownership), as confirmed by data from the relevant state registers, in the amount of:
a) residential real estate objects:
apartment/apartments, the total area of which does not exceed 120 square meters in total, or property rights, confirmed by relevant documents, to such an apartment or apartments in an apartment building under construction;
residential building/residential buildings registered in accordance with the established procedure in Ukraine, the total area of which does not exceed 240 square meters in total, or a residential building under construction or houses under construction, the total area of which does not exceed 240 square meters in total, provided that such an individual has the right of ownership to a land plot of the appropriate purpose;
b) non-residential real estate objects - non-residential buildings of non-commercial purpose and/or non-residential buildings under construction of non-commercial purpose, the total area of which does not exceed 60 square meters;
c) land plots, the total size of which for each individual plot does not exceed the norms of free transfer specified in Article 121 of the Land Code of Ukraine;
3) one vehicle for personal non-commercial use (except for a vehicle intended for the transportation of 10 or more people, including the driver, a passenger car with an engine cylinder capacity of at least 3 thousand cubic centimeters and/or an average market value of more than 400 thousand hryvnias, a motorcycle with an engine cylinder capacity of more than 800 cubic centimeters, an airplane, helicopter, yacht, boat), the ownership of which was registered in accordance with the legislation of Ukraine as of the date of completion of the one-time (special) voluntary declaration period.
With regard to the assets of an individual defined by this paragraph, no one-time (special) voluntary declaration fee shall be charged and paid.
11. The amount of the fee for a one-time (special) voluntary declaration, specified in the one-time (special) voluntary declaration, is considered agreed.
12. Payment of the fee for a one-time (special) voluntary declaration shall be made by the declarant within 30 calendar days from the date of submission of the one-time (special) voluntary declaration.
If the declarant, within the framework of a one-time (special) voluntary declaration, chooses a one-time (special) voluntary declaration fee rate that provides for the payment of such payment in three equal installments, the declarant shall pay the one-time (special) voluntary declaration fee: the first payment - within 30 calendar days from the date of submission of the one-time (special) voluntary declaration; the second payment - by November 1, 2023; the third payment - by November 1, 2024 (except for the cases provided for in paragraphs three to six of this paragraph).
{Paragraph two of clause 12 of subsection 9 - 4 as amended by Law No. 2516-IX of August 15, 2022 - amendments shall enter into force on September 1, 2022 }
If the declarant who submitted a one-time (special) voluntary declaration after August 31, 2022, within the framework of the one-time (special) voluntary declaration, chooses the one-time (special) voluntary declaration fee rate, which provides for the payment of such payment in three equal installments, the declarant shall pay the one-time (special) voluntary declaration fee in the following order:
{Clause 12 of subsection 9 - 4 is supplemented with a new paragraph in accordance with Law No. 2516-IX of August 15, 2022 - changes come into force on September 1, 2022 }
the first payment - within 30 calendar days from the date of submission of a one-time (special) voluntary declaration;
{Clause 12 of subsection 9 - 4 is supplemented with a new paragraph in accordance with Law No. 2516-IX of August 15, 2022 - changes come into force on September 1, 2022 }
the second payment - by May 1, 2024;
{Clause 12 of subsection 9 - 4 is supplemented with a new paragraph in accordance with Law No. 2516-IX of August 15, 2022 - changes come into force on September 1, 2022 }
the third payment - by May 1, 2025.
{Clause 12 of subsection 9 - 4 is supplemented with a new paragraph in accordance with Law No. 2516-IX of August 15, 2022 - changes come into force on September 1, 2022 }
In the event that the declarant submits a clarifying one-time (special) voluntary declaration:
if the amount of the fee for a one-time (special) voluntary declaration specified in the clarifying declaration is less than the amount of the fee paid on the basis of a previously submitted one-time (special) voluntary declaration, the refund of the overpaid amount of the fee shall be carried out in accordance with the procedure specified in Article 43 of this Code;
If the amount of the fee for a one-time (special) voluntary declaration specified in the clarifying declaration is greater than the amount of the fee paid on the basis of a previously submitted one-time (special) voluntary declaration, the declarant who submitted the relevant declaration is obliged to pay the amount of the underpayment of the fee in the amount of such difference within 30 calendar days from the date of submission of the clarifying declaration.
In case of non-payment or partial payment of the amount of the fee for a one-time (special) voluntary declaration specified in the one-time (special) voluntary declaration, within the period established by this subsection, the one-time (special) voluntary declaration shall be deemed not to have been submitted and the state guarantees and exemption from liability provided for by this subsection shall not apply to the declarant.
13. A tax audit by the central executive body implementing state tax policy shall not be conducted with respect to the source of receipt by the declarant or an individual subject to clause 10 of this subsection of income from which the assets declared by such declarant or the assets provided for in clause 10 of this subsection were received (acquired).
Payment by the declarant in full of the amount of the fee for a one-time (special) voluntary declaration, including the additional accrual of a monetary obligation, in the cases provided for in this subsection, exempts such a declarant from liability for violation of tax and currency legislation, the control over compliance with which is entrusted to the regulatory authorities, and from the obligation to charge and pay taxes and fees on income that became the source of receipt (acquisition) of assets specified by such a declarant in a one-time (special) voluntary declaration (within the composition and value of assets specified in a one-time (special) voluntary declaration as the object and basis for calculating the fee for a one-time (special) voluntary declaration), which took place in any of the tax periods before January 1, 2021.
In the event that a declarant who has chosen the tax rate with installment payment in three equal installments pays the first part of the tax liability, such a taxpayer cannot be held liable for violating tax and currency legislation, the control over compliance with which is entrusted to regulatory authorities, and is temporarily exempted from the obligation to calculate and pay taxes and fees on income that became the source of receiving (acquiring) assets specified by such a declarant in a one-time (special) voluntary declaration (within the composition and value of assets specified in the one-time (special) voluntary declaration as the object and basis for calculating the fee for a one-time (special) voluntary declaration), which took place in any of the tax periods before January 1, 2021. In case of non-payment (untimely payment) of the second or third part of the tax liability, the declarant is held liable and is considered to have the obligation to charge and pay taxes and fees on the specified income on a general basis, and the amount of the paid part of the tax liability is considered to have been paid in error.
14. A declarant who has paid the full amount of the fee for a one-time (special) voluntary declaration in the manner, time frame and amount established by this subsection, and who has fulfilled other requirements provided for by this subsection, may not:
1) measures to ensure criminal proceedings shall be applied, preventive measures shall be applied and investigative (search) actions shall be taken in criminal proceedings in connection with the acquisition (formation of sources of acquisition), creation, receipt, use of assets specified in the one-time (special) voluntary declaration for any period until January 1, 2021 (within the composition and value of the assets of an individual specified in the one-time (special) voluntary declaration as the object and basis for calculating the fee for the one-time (special) voluntary declaration), on the grounds of criminal offenses provided for in Articles 212 , 212-1 of the Criminal Code of Ukraine. The amounts for which the one-time (special) voluntary declaration fee has been paid are deducted from the established criteria for the purposes of qualifying the offense as a criminally punishable act in relation to the assets of an individual that were reflected (within the composition and value) in the one-time (special) voluntary declaration;
2) proceedings shall be initiated in cases of administrative offenses for violation of tax and currency legislation, control over compliance with which is entrusted to the regulatory authorities, as well as under Articles 155 - 1 , 162 , 162 - 1 , 163 - 1 (regarding a self-employed person), 163 - 2 (regarding a self-employed person in terms of payment of a single tax and a single contribution to mandatory state social insurance), 163 - 4 (regarding a self-employed person), 163 - 15 (regarding a self-employed person), 164 (regarding a self-employed person), 164 - 1 , 164 - 2 (regarding an individual entrepreneur), 165 - 1 (regarding a self-employed person), 166 - 6 (regarding a self-employed person) of the Code of Ukraine on Administrative Offenses, if such offenses related to the acquisition (formation of sources of acquisition), creation, receipt, use of the objects of declaration specified in the one-time (special) voluntary declaration until January 1, 2021 (within the composition and value of the assets specified in the one-time (special) voluntary declaration as the object and basis for calculating the fee for the one-time (special) voluntary declaration).
15. A one-time (special) voluntary declaration is subject to verification in a special manner.
15.1. A one-time (special) voluntary declaration is subject to an in-house audit, in accordance with the procedure provided for in this subsection, which the central executive body implementing the state tax policy shall conduct within 60 calendar days following the date of submission of the relevant declaration to it.
In the event that the central executive body implementing the state tax policy, based on the results of a desk review, detects arithmetic and logical errors in the relevant one-time (special) voluntary declaration that did not result in underpayment of the amount of the fee for the one-time (special) voluntary declaration, such body shall send the declarant a corresponding notification within 10 calendar days in accordance with the procedure specified in Article 42 of this Code. Based on the results of consideration of such notification, the declarant shall have the right to submit a clarifying relevant one-time (special) voluntary declaration within 20 calendar days from the date of receipt of such notification.
If the central executive body implementing the state tax policy detects, based on the results of an in-house check of the relevant one-time (special) voluntary declaration, an arithmetic error that led to an underpayment of the amount of the fee for the one-time (special) voluntary declaration, the declarant who submitted the relevant one-time (special) voluntary declaration is obliged to pay the amount of such underpayment within 10 calendar days from the date of receipt of the relevant notification in an arbitrary form from the central executive body implementing the state tax policy, and submit a clarifying relevant one-time (special) voluntary declaration within 20 calendar days from the date of receipt of such notification.
If the central executive body implementing the state tax policy, based on the results of the desk review of the relevant one-time (special) voluntary declaration, discovers an arithmetic error that led to an overpayment of the amount of the fee for the one-time (special) voluntary declaration, the declarant who submitted the relevant one-time (special) voluntary declaration has the right, based on the relevant notification from the central executive body implementing the state tax policy, to submit a clarifying relevant one-time (special) voluntary declaration within 20 calendar days from the date of receipt of such notification. The refund of the overpaid amount of the fee shall be carried out in accordance with the procedure specified in Article 43 of this Code.
15.2. In order to confirm the application of the relevant fee rate for a one-time (special) voluntary declaration, determined by clause 8 of this subsection, the central executive body implementing state tax policy, during an in-house inspection of the relevant one-time (special) voluntary declaration, has the right to:
verify the registration of transactions and/or assets in state registers, including by contacting the relevant state authorities;
to contact the declarant with a request for confirmation of the declarant's possession of the property, property and non-property rights specified in the relevant one-time (special) voluntary declaration, if, according to the results of the inspection provided for in paragraph two of this subparagraph, a discrepancy is found between the declared information and the data of state registers.
In the event that the central executive body implementing the state tax policy establishes, within 365 days from the date of submission of a one-time (special) voluntary declaration by the declarant, that he has violated the conditions for placing currency values in banking and/or other financial institutions established by paragraphs 8 and 9 of this subsection, there is no relevant document confirming the right to claim (including the absence of a loan agreement between the declarant and a legal entity and/or notarization of a loan agreement between the declarant and another individual), and/or there are no copies of documents provided for in this subsection, provided that the declarant does not provide explanations and documentary evidence and/or relevant copies of documents upon a written request of the central executive body implementing the state tax policy, indicating the detected inaccuracy of the data and/or a list of unsubmitted documents provided for in this subsection, in accordance with the procedure specified by this Code, a documentary investigation shall be conducted. unscheduled non-visit inspection and the accrual of monetary obligations is carried out. In this case, such currency values and claims (including funds lent to third parties) that are reflected in a one-time (special) voluntary declaration, and/or assets, the value of which must be confirmed by documents, in the cases provided for by this subsection, are taxed at a rate of 18 percent. In such a case, the central executive body implementing the state tax policy shall carry out the accrual of monetary obligations in the manner prescribed by this Code.
16. One-time (special) voluntary declarations, as well as the information contained therein, cannot be used in investigations and/or inspections regarding the declarant, as well as as evidence in criminal proceedings, cases of administrative offenses, civil and administrative cases (within the composition and value of assets specified in the one-time (special) voluntary declaration as the object and basis for calculating the fee for the one-time (special) voluntary declaration).
The provisions of paragraph one of this paragraph shall not apply if the declarant, starting from 2010, is or was a member of the family of the first and second degrees of kinship, in accordance with subparagraph 14.1.263 of paragraph 14.1 of Article 14 of this Code, of the person specified in paragraph three of paragraph 3 of this subsection, except in the case of bringing such a person to criminal liability under Articles 212 and 212-1 ( regarding the obligations of the declarant as an individual or an individual entrepreneur) of the Criminal Code of Ukraine in respect of the assets of the individual (within the limits of composition and value) specified in the one-time (special) voluntary declaration, or the relevant state bodies have established that the acquisition of assets specified in the one-time (special) voluntary declaration contains signs of a criminal offense provided for in Article 368-5 of the Criminal Code of Ukraine, or such assets are subject to seizure as unfounded in accordance with the procedure established by Chapter 12, Section III of the Civil Procedure Code of Ukraine. In the event of a court decision that has entered into legal force on the recognition of assets specified in a one-time (special) voluntary declaration as unfounded and their recovery into state revenue or a court verdict on the confiscation or special confiscation of such assets, the fee for the one-time (special) voluntary declaration paid by the declarant shall not be refunded.
The assets of an individual (within the composition and value) specified in the submitted one-time (special) voluntary declaration, and the corresponding fee paid by the declarant in full amount of the fee for the one-time (special) voluntary declaration in the manner, terms and amount established by this subdivision, as well as the one-time (special) voluntary declaration cannot be used as a basis for initiating criminal proceedings qualified under Articles 212 and 212-1 of the Criminal Code of Ukraine, or reporting an administrative offense provided for in Articles 155-1 , 162 , 162-1 , 163-1 ( regarding a self-employed person), 163-2 (regarding a self-employed person in terms of payment of a single tax and a single contribution to mandatory state social insurance), 163-4 ( regarding a self - employed person ) , 163- 15 (regarding a self-employed person), 164 (regarding a self-employed person), 164 - 1 , 164 - 2 (regarding a self-employed person), 165 - 1 (regarding a self-employed person), 166 - 6 (regarding a self-employed person) of the Code of Ukraine on Administrative Offenses, or as evidence of the declarant's admission of the fact of committing the offenses specified in this paragraph or his admission of guilt in committing the offenses specified in this paragraph.
17. The information contained in the relevant one-time (special) voluntary declarations and the documents attached to them, submitted in accordance with this subsection, is confidential information and is not subject to disclosure by the central executive body implementing the state tax policy, its officials without the written consent of the declarant, except for cases when this is expressly provided for by laws or a court decision. For the disclosure of such information, including as a result of official negligence or access to information by other persons who do not have such a right, as well as the illegal use of such information, officials of the central executive body implementing the state tax policy shall be held civilly, administratively, criminally and otherwise liable in accordance with the law.
18. Implementation of the provisions stipulated in this subsection shall not constitute grounds for full or partial non-compliance with the requirements of the legislation in the field of prevention and counteraction to the legalization (laundering) of proceeds from crime, financing of terrorism and financing of the proliferation of weapons of mass destruction and non-compliance with the requirements of the legislation in the field of implementation and monitoring of the effectiveness of personal, special, economic and other restrictive measures (sanctions).
in this subsection shall not apply to assets obtained as a result of criminal offenses, except for criminal offenses provided for in Articles 212 , 212-1 (regarding payment of taxes as an individual or an individual entrepreneur), Article 366 (regarding tax and/or financial reporting documents, customs declarations, tax invoices, primary documents, other reporting on taxes, fees, mandatory payments), Article 367 (if the crime is related to a violation of the requirements of tax, customs, currency and other legislation, control over compliance with which is entrusted to regulatory authorities) of the Criminal Code of Ukraine.
The state guarantees and exemptions from liability provided for in this subsection also do not apply to:
assets of an individual or legal entity, the acquisition of which contains signs of a criminal offense provided for in Article 368 - 5 of the Criminal Code of Ukraine, and/or which are subject to recovery as unfounded in accordance with the procedure established by Chapter 12, Section III of the Civil Procedure Code of Ukraine;
currency values, claims and funds lent to third parties, which are reflected in a one-time (special) voluntary declaration, in the event of the establishment by the central executive body implementing state tax policy, violation by the declarant of the conditions for placing currency values in banking or other financial institutions established by paragraphs 8 and 9 of this subsection, the absence of a loan agreement between the declarant and a legal entity and/or notarization of a loan agreement between the declarant and another individual, the absence of a relevant document confirming the right of claim.
To establish that temporarily from September 1, 2021 to March 1, 2022, the fee rate for a one-time (special) voluntary declaration, determined by clause 8.2 of clause 8 of this subsection, shall be applied at the rate of 7 percent.
Alternatively, the taxpayer may choose a rate of 9.5 percent with payment of the tax liability in three equal installments annually.
{Chapter XX supplemented by subsection 9 - 4 in accordance with Law No. 1539-IX of 15.06.2021 }
1. To establish that the repayment of overdue debts of a business entity to the state (Autonomous Republic of Crimea, regional council or city territorial community) under a credit (loan) attracted by the state (Autonomous Republic of Crimea, regional council or city territorial community) or under a state (local) guarantee, as well as under a loan from the budget (including fees for the use of such credits (loans) and interest) shall be carried out in accordance with the procedure specified in Chapter 9, Section II of this Code or another law, including the repayment of such debts at the expense of the property of this business entity.
{Clause 1, Subsection 10, Section XX as amended by Law No. 2719-IX of 03.11.2022 }
1 - 1. To establish that the collection of debts from part of the net profit (income) of state unitary enterprises and their associations shall be carried out in accordance with the procedure specified in Articles 59 , 60 of Chapter 4, Articles 87-101 of Chapter 9 of Section II of this Code.
{ Subsection 10 of Section XX is supplemented by paragraph 1 - 1 in accordance with the Law No. 466-IX dated 16.01.2020 }
1 - 2. Tax debt of individual taxpayers, including self-employed persons, which in total does not exceed 6,800 hryvnias, may be settled in the following manner.
The amount of tax debt (including penalties, fines and interest for using installments/deferrals) that was accounted for by such taxpayers as of December 1, 2020 and remained unpaid as of the date of granting the deferral may be deferred until December 29, 2021. The deferral is carried out by the supervisory authority at the place of registration of the taxpayer - an individual upon his application. The deferral is granted without accruing interest for using such deferral.
If the taxpayer repays the full amount of the deferred tax debt no later than the deadline specified in this paragraph, the penalties and interest provided for by this Code shall not be applied and accrued to such paid deferred amounts, and the applied (accrued) amounts shall be adjusted to zero.
In the event that the taxpayer fails to repay the full amount of the deferred tax debt before the deadline specified in this paragraph, as well as in the event of its repayment after December 29, 2021, penalties and interest on the deferred amounts that remain unpaid shall be accrued in the general manner in accordance with the requirements of this Code.
When granting a deferral in accordance with this paragraph, the provisions of Article 100 of this Code shall not apply.
{Subsection 10 of Section XX supplemented by paragraphs 1 - 2 in accordance with Law No. 1072-IX of 04.12.2020 }
{ Clause 2 of Subsection 10 of Section XX has been repealed by virtue of the Act No. 5203-VI dated 06.09.2012 }
2 - 1. Subject to write-off:
tax debt as of January 1, 2011 of the National Joint-Stock Company "Naftogaz of Ukraine" (except for the tax debt on value added tax upon customs clearance of natural gas imported into the customs territory of Ukraine in previous periods) and its subsidiaries State Company "Gas of Ukraine", State Company "Ukrtransgaz", State Company "Ukrgazvydobuvannya", State Joint-Stock Company "Chornomornaftogaz", business entities supplying natural gas at a regulated tariff, to the budget (including tax debt that arose in connection with violations of tax, currency and customs legislation), as well as monetary obligations that will arise in connection with the application of the write-off mechanism in accordance with Article 2 of the Law of Ukraine "On Some Issues of Debt for Consumed Natural Gas and Electricity" ;
restructured amounts of taxes and fees under the conditions specified by the Law of Ukraine dated June 23, 2005 No. 2711-IV "On Measures Aimed at Ensuring Sustainable Operation of Enterprises of the Fuel and Energy Complex", to enterprises - producers of electricity that have a license for the right to carry out entrepreneurial activity in the production of electricity, as well as monetary obligations that will arise in connection with the application of the write-off mechanism in accordance with Article 2 of the Law of Ukraine "On Some Issues of Debt for Consumed Natural Gas and Electricity";
tax debt of business entities supplying electricity at a regulated tariff to the budget, which arose as a result of the determination by regulatory authorities of the tax liability of the business entity due to the presence of an imbalance in technological electricity costs (excess electricity costs) relating to periods before January 1, 2011;
Unreconciled monetary liabilities and fines of the National Joint-Stock Company "Naftogaz of Ukraine" (except for value-added tax liabilities when customs clearance of natural gas imported into the customs territory of Ukraine in previous periods) and its subsidiaries State Corporation "Gas of Ukraine", State Corporation "Ukrtransgaz", State Corporation "Ukrgazvydobuvannya", JSC "Chornomornaftogaz" and SE "Energorynok" were determined by the regulatory authorities as of January 1, 2011, for which administrative or judicial appeal procedures are ongoing;
Unreconciled monetary obligations and penalties of business entities supplying electricity at a regulated tariff, determined by regulatory authorities, due to the presence of an imbalance in technological electricity costs (excessive electricity costs), relating to periods before January 1, 2011 and for which administrative or judicial appeal procedures are ongoing;
tax liabilities (including interest accrued on such installment amounts) from income tax and value added tax paid to the National Joint-Stock Company "Naftogaz of Ukraine" in installments.
Amounts written off in accordance with the provisions of this paragraph and the Law of Ukraine "On Some Issues of Debt for Consumed Natural Gas and Electricity" are not included in the gross income and gross expenses of the participants in the write-off procedure.
The relevant decisions on the write-off of the specified amounts shall be taken by the supervisory authorities within their competence in accordance with the procedure provided for the write-off of bad tax debt, within ten working days from the date of submission of the taxpayer's application. In the event of the supervisory authority's refusal to write-off in accordance with this paragraph, taxpayers may appeal such actions in accordance with the procedure specified in Chapter 4 of this Code.
According to the provisions of this paragraph, amounts that remain unpaid as of the first day of the month in which the Law of Ukraine "On Some Issues of Debt for Consumed Natural Gas and Electricity" entered into force are subject to write-off.
Penalties and interest provided for by this Code shall not be accrued on amounts written off in accordance with the provisions of this paragraph.
{Subsection 10 of Section XX is supplemented by paragraph 2 - 1 in accordance with Law No. 3320-VI of 12.05.2011 - the change is valid until June 30, 2012}
2 - 2. Tax debt (including that established by court decisions and restructured) as of July 1, 2012, unpaid as of the date of entry into force of this Law, of taxpayers - enterprises of the defense-industrial complex, which are included in the State Concern "Ukroboronprom" (hereinafter - enterprises of the defense-industrial complex), to the budget (including tax debt that arose in connection with violations of tax, currency and customs legislation), as well as monetary obligations that will arise in connection with the application of the write-off mechanism in accordance with Article 2 of the Law of Ukraine "On Some Issues of Debt of Enterprises of the Defense-Industrial Complex - Participants of the State Concern "Ukroboronprom" and Ensuring Their Stable Development" shall be subject to write-off.
The tax debt for payment of value-added tax of the State Reserve Agency of Ukraine, which arose in connection with the transfer of the debt of the National Joint-Stock Company "Naftogaz of Ukraine", enterprises of the fuel and energy complex to the State Reserve Agency of Ukraine, which is written off in accordance with Article 2 of the Law of Ukraine "On Some Issues of Debt of Enterprises of the Defense Industrial Complex - Participants of the State Concern "Ukroboronprom" and Ensuring Their Stable Development", is subject to write-off.
Amounts written off in accordance with the provisions of this paragraph and the Law of Ukraine "On Some Issues of Debt of Enterprises of the Defense Industrial Complex - Participants of the State Concern "Ukroboronprom" and Ensuring Their Stable Development" are not included in the income and expenses of participants in the write-off procedure.
The supervisory authorities, within their competence, in accordance with the procedure provided for writing off bad tax debt, shall write off the specified amounts within ten working days from the date of submission of the taxpayer's application.
The amounts written off in accordance with the provisions of this paragraph shall not be subject to penalty or penalties established by this Code.
{Subsection 10 of Section XX supplemented by paragraph 2 - 2 in accordance with the Law No. 5414-VI of 02.10.2012 }
2 - 3. In the event of full repayment in cash by taxpayers within six months from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Social Support of Taxpayers for the Period of Implementation of Restrictive Anti-Epidemic Measures Introduced to Prevent the Spread of Acute Respiratory Disease COVID-19 Caused by the SARS-CoV-2 Coronavirus in the Territory of Ukraine", the amount of tax debt (excluding penalties, fines, except for unpaid interest for using installments/deferrals) that arose as of November 1, 2020, and subject to payment of current tax liabilities in full, penalties and fines that remained unpaid as of the date of full payment of such tax debt shall be written off in accordance with the procedure established for writing off bad tax debt, upon the taxpayer's application.
The provisions of this paragraph shall not apply to:
large taxpayers that meet the criteria specified in subparagraph 14.1.24 of paragraph 14.1 of Article 14 of this Code;
persons subject to judicial procedures defined by the Code of Ukraine on Bankruptcy Procedures ;
persons in respect of whom there are court decisions that have entered into legal force, by which the collection of tax debt is deferred (postponed);
banks subject to the provisions of the Law of Ukraine "On the Deposit Guarantee System of Individuals";
persons who have tax debt from customs payments;
persons who have debts to pay sanctions for violations of legislation in the field of foreign economic activity and fines.
Penalties and interest that are subject to application and accrual in connection with the payment of such tax debt are not subject to application and accrual, and those accrued are subject to adjustment to zero.
{Subsection 10 of Section XX supplemented by paragraphs 2 - 3 in accordance with Law No. 1072-IX of 04.12.2020 }
2 - 4. The supervisory authority shall write off, without the taxpayer submitting an application, the tax debt (including penalties and fines) of the taxpayer, the total amount of which for all taxes and fees does not exceed UAH 3,060 (inclusive), which, according to the information and telecommunication systems of the central executive body implementing state tax policy, was recorded as of November 1, 2020 and remained unpaid/unrepaid as of the date of writing off such debt.
Such write-off is carried out without applying the provisions of Article 101 of this Code and exclusively based on data contained in the information and telecommunications systems of the central executive body implementing state tax policy.
The written-off amounts are subject to recovery if circumstances are discovered indicating that there are no grounds for the write-off.
The provisions of this paragraph do not apply to tax debt on taxes and fees that, in accordance with tax, customs and other legislation, are collected in connection with the import (shipment) of goods into the customs territory of Ukraine or the territory of a free customs zone or the export (shipment) of goods from the customs territory of Ukraine or the territory of a free customs zone, as well as to persons subject to judicial procedures specified in the Code of Ukraine on Bankruptcy Procedures .
debt, penalties and interest accrued and paid or collected for the period from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Social Support of Taxpayers for the Period of Implementation of Restrictive Anti-Epidemic Measures Introduced to Prevent the Spread of Acute Respiratory Disease COVID-19 Caused by the SARS-CoV-2 Coronavirus in Ukraine" until the date of writing off the tax debt in accordance with this paragraph are not subject to refund to the taxpayer's current account, are not directed to repay the monetary obligation (tax debt) from other taxes, fees, and are not refunded in cash by check if the taxpayer does not have bank accounts.
The amounts written off in accordance with this paragraph shall not be subject to penalties or interest provided for by this Code for the period from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Social Support of Taxpayers for the Period of Implementation of Restrictive Anti-Epidemic Measures Introduced to Prevent the Spread of Acute Respiratory Disease COVID-19 Caused by the SARS-CoV-2 Coronavirus in Ukraine" and up to and including the date of writing off.
The write-off of tax debt in accordance with this paragraph is the basis for the release of the taxpayer's property from tax lien and its exclusion from the relevant state registers.
Based on the information provided by the supervisory authority on the written-off amounts of tax debt, the enforcement proceedings opened by the state enforcement service shall be terminated and the measures of compulsory execution of decisions on the collection of tax debt from taxpayers who have their tax debt written off in accordance with this paragraph shall be terminated, in accordance with the procedure specified by the Law of Ukraine "On Enforcement Proceedings".
{Subsection 10 of Section XX supplemented by paragraphs 2 - 4 in accordance with Law No. 1072-IX of 04.12.2020 }
3. To establish that if legislative acts provide for other rules for the collection of taxes and fees regulated by this Code, the rules of this Code shall apply.
{Clause 4, subsection 10, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
5. In connection with the entry into force of this Code, penalties that may be imposed on taxpayers for violating regulatory acts of the Cabinet of Ministers of Ukraine, the central regulatory authority, and provisions directly provided for by this Code shall begin to apply to such taxpayers as of the tax period following the tax period during which such acts were put into effect.
6. Financial sanctions shall not be applied to corporate income tax payers and taxpayers who have switched to the general taxation system for violations of tax legislation as a result of activities in the second - fourth calendar quarters of 2011.
{Clause 6, Subsection 10, Section XX, as amended by Law No. 3609-VI of 07.07.2011 }
7. Penalties for violations of tax legislation for the period from January 1 to June 30, 2011 shall be applied in the amount of no more than 1 hryvnia for each violation.
Penalties for single tax payers for violating the calculation procedure, correct completion of single tax payer tax returns, and complete payment of single tax amounts by payers in 2012 are not applied.
{Paragraph 7 of Subsection 10 of Section XX supplemented by the second paragraph in accordance with Law No. 4834-VI of 24.05.2012 }
8. In cases specified by this Code, until the entry into force of Article 39 of this Code, Clause 1.20 of Article 1 of the Law of Ukraine "On Taxation of Enterprise Profits" shall apply .
The provisions of subparagraph 1.20.10 of paragraph 1.20 of Article 1 of the Law of Ukraine "On Taxation of Enterprise Profits" regarding the additional assessment of tax liabilities to a taxpayer by the controlling authority as a result of determining normal prices according to the procedure established by law for the assessment of tax liabilities using indirect methods do not apply.
{Paragraph 8 of Subsection 10 of Section XX supplemented by the second paragraph in accordance with Law No. 4834-VI of 05/24/2012 }
9. Temporarily, until the development and implementation of the automated system "Single Window for Submission of Electronic Reporting" in accordance with paragraph 49.17 of Article 49 of this Code, the Procedure for the Preparation and Submission of Tax Documents in Electronic Form by Telecommunications , approved by order of the State Tax Administration of Ukraine dated April 10, 2008 No. 233 and registered with the Ministry of Justice of Ukraine on April 16, 2008 under No. 320/15011, shall apply.
10. Regulatory and legal acts of the Cabinet of Ministers of Ukraine, the State Tax Administration of Ukraine and other central executive bodies adopted before the entry into force of this Code to implement laws on taxation, and regulatory and legal acts used in the application of the norms of laws on taxation (including acts of the legislation of the USSR), shall apply in the part that does not contradict this Code, until the adoption of relevant acts in accordance with the requirements of this Code.
11. Penalty (financial) sanctions (fines) as a result of inspections carried out by regulatory authorities shall be applied in the amounts provided for by the law in force on the date of making decisions on the application of such penalty (financial) sanctions (taking into account the provisions of paragraph 7 of this subsection).
{Subsection 10 of Section XX supplemented by paragraph 11 in accordance with Law No. 3609-VI of 07.07.2011 }
12. The provisions of Article 69 of this Code shall not apply to depository institutions when they open securities accounts for owners to record the rights to dematerialized securities owned by these owners in accordance with agreements with issuers of these securities on opening/maintaining securities accounts for owners. The obligations stipulated by Article 69 of this Code shall be fulfilled by the depository institution in the event of an application by the persons specified in this Article on the day of their conclusion of the agreement on servicing the securities account.
{Subsection 10 of Section XX supplemented by paragraph 12 in accordance with Law No. 3609-VI of 07.07.2011 ; as amended by Law No. 466-IX of 16.01.2020 }
13. In the tax (reporting) periods of 2012, the calculation of the adjustment coefficient established by paragraph one of clause 259.1 of Article 259 of this Code shall be carried out by dividing the average price of one barrel of Urals oil, which formed at the time of the end of oil trading on the London Stock Exchange during the current reporting (tax) period, by the base oil price. The base oil price shall mean the price of Urals oil, which is equal to 100 US dollars per barrel.
{Subsection 10 of Section XX supplemented by paragraph 13 in accordance with Law No. 4235-VI of 22.12.2011 }
14. To establish that until January 1, 2016, penalties shall not be applied for failure to submit or violation of the deadline for submission by individuals to regulatory authorities of information on changes in data entered into the State Register of Individual Taxpayers.
{Subsection 10 of Section XX supplemented by paragraph 14 in accordance with Law No. 4834-VI of 24.05.2012 ; as amended in accordance with Law No. 657-VII of 24.10.2013 }
{Clause 15, subsection 10, section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
{Item 16 of Subsection 10 of Section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
16 - 1. Temporarily, until the decision of the Verkhovna Rada of Ukraine on the completion of the reform of the Armed Forces of Ukraine comes into force, a military levy is established.
{Paragraph one of clause 16 - 1 , subsection 10, section XX, as amended by Law No. 71-VIII of 28.12.2014 }
1.1. The fee payers are:
1) persons defined by paragraph 162.1 of Article 162 of this Code;
2) individuals - entrepreneurs - single tax payers of the first, second and fourth groups;
3) single tax payers of the third group, except for electronic residents (e-residents).
{Subclause 3 of subparagraph 1.1 of clause 16 - 1 of subsection 10 of section XX as amended by Law No. 4113-IX of 04.12.2024 - for application see paragraph two of clause 1 of section II }
The military levy for the payers of the levy specified in subparagraphs 2 and 3 of this subparagraph shall be established from January 1, 2025 to December 31 of the third calendar year following the year in which the martial law introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , will be terminated or canceled .
{Paragraph five of subparagraph 1.1 of clause 16 - 1 of subsection 10 of section XX as amended by Law No. 4113-IX of 04.12.2024 - for application see paragraph two of clause 1 of section II, and as amended by Law No. 4835-IX of 07.04.2026 }
{Subparagraph 1.1 of paragraph 16 - 1 of subsection 10 of section XX as amended by Law No. 4015-IX of 10.10.2024 }
1.2. The object of taxation by the fee is:
1) for payers specified in subparagraph 1 of subparagraph 1.1 of this paragraph - income defined in Article 163 of this Code;
2) for payers specified in subparagraph 2 of subparagraph 1.1 of this paragraph - a monthly amount equal to the minimum wage established by law as of January 1 of the tax (reporting) year;
3) for payers specified in subparagraph 3 of subparagraph 1.1 of this paragraph - income defined by Article 292 of this Code.
{Subclause 1.2 of clause 16 - 1 of subsection 10 of section XX as amended by Laws No. 71-VIII of 12/28/2014 , No. 4015-IX of 10/10/2024 }
1.3. The fee rate is:
1) for payers specified in subparagraph 1 of subparagraph 1.1 of this clause - 5 percent of the taxable amount specified in subparagraph 1 of subparagraph 1.2 of this clause, except for income that is taxed at the rate specified in subparagraph 4 of this clause;
{Paragraph two of subparagraph 1.3 of clause 16 - 1 of subsection 10 of section XX as amended by Law No. 4113-IX of 04.12.2024 - for application see paragraph two of clause 1 of section II }
2) for payers specified in subparagraph 2 of subparagraph 1.1 of this paragraph - 10 percent of the minimum wage established by law as of January 1 of the tax (reporting) year, calculated per calendar month;
3) for payers specified in subparagraph 3 of subparagraph 1.1 of this paragraph - 1 percent of income determined in accordance with Article 292 of this Code;
4) for servicemen and employees of the Armed Forces of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the Main Intelligence Directorate of the Ministry of Defense of Ukraine, the National Guard of Ukraine, the State Border Service of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, the State Special Transport Service of Ukraine, and other military formations established in accordance with the laws of Ukraine - 1.5 percent of the income received in the form of cash benefits, monetary rewards and other payments made in accordance with the legislation of Ukraine (except for income exempt from taxation by military duty in accordance with subparagraph 1.7 of this paragraph).
{Paragraph five of subparagraph 1.3 of clause 16 - 1 of subsection 10 of section XX as amended by Law No. 4113-IX of 04.12.2024 - for application see paragraph two of clause 1 of section II }
Starting from January 1 of the year following the third calendar year after the year in which martial law, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX ", the fee rate for payers specified in subparagraph 1 of subparagraph 1.1 of this paragraph is 1.5 percent of the taxable amount determined by subparagraph 1 of subparagraph 1.2 of this paragraph.
{Paragraph six of subparagraph 1.3 of clause 16 - 1 of subsection 10 of section XX and as amended by Law No. 4835-IX of 07.04.2026 }
{Subclause 1.3 of clause 16 - 1 of subsection 10 of section XX as amended by Law No. 4015-IX of 10.10.2024 }
{Subclause 1.3 - 1 of clause 16 - 1 of subsection 10 of section XX was excluded on the basis of Law No. 4113-IX of 04.12.2024 - for application, see paragraph two of clause 1 of section II }
1.4. The calculation, withholding and payment (transfer) of the fee from the income of the fee payers specified in subparagraph 1 of subparagraph 1.1 of this clause shall be carried out in accordance with the procedure established by Section IV of this Code, taking into account the features determined by subsection 1 of this section, at the rates determined by subparagraph 1.3 of this clause.
{Subclause 1.4 of clause 16 - 1 of subsection 10 of section XX as amended by Laws No. 2520-IX of 08/15/2022 , No. 4015-IX of 10/10/2024 ; as amended by Law No. 4113-IX of 12/04/2024 - for application, see paragraph two of clause 1 of section II }
The persons specified in Article 171 of this Code are responsible for withholding (calculation) and paying (transferring) the fee to the budget from the income of payers specified in subparagraph 1 of subparagraph 1.1 of this paragraph.
{Subclause 1.5 of clause 16 - 1 of subsection 10 of section XX as amended by Law No. 4015-IX of 10.10.2024 }
1.6. Tax payers specified in subparagraph 1 of subparagraph 1.1 of this paragraph are obliged to ensure the fulfillment of tax obligations in the form and manner specified in Article 176 of this Code.
{Subclause 1.6 of Clause 16 - 1 of Subsection 10 of Section XX as amended by Law No. 4015-IX of 10.10.2024 }
1.7. Income that, in accordance with Section IV of this Code and Subsection 1 of this Section, is not included in the total taxable income of individuals (is not subject to taxation, is taxed at a zero rate), except for income specified in Subsection 165.1.36 of Section 165.1 of Article 165, Subsections 3 and 4 of Section 170.13 - 1 of Article 170 of this Code and Subsection 14 of Section 1 of this Section, shall be exempt from taxation.
{Paragraph one of subparagraph 1.7 of clause 16 - 1 of subsection 10 of section XX as amended by Laws No. 2628-VIII of 23.11.2018 , No. 466-IX dated 01/16/2020 , No. 1539-IX dated 06/15/2021 ; as amended by Laws No. 2520-IX dated 08/15/2022 , No. 4113-IX dated 12/04/2024 - for application see paragraph two of clause 1 of section II }
Temporarily, for the period of the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, carried out through the operation of the Joint Forces (JFO), income in the form of monetary support of law enforcement officers, military personnel and employees of the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, privates, commanding officers, military personnel, employees of the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations established in accordance with the laws of Ukraine and other persons for the period of their direct participation in the anti-terrorist operation and/or the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, carried out by by conducting a Joint Forces Operation (JFO).
{Subclause 1.7 of Clause 16 - 1 of Subsection 10 of Section XX is supplemented with a new paragraph in accordance with Law No. 548-VIII of 06/18/2015 ; as amended by Law No. 2463-VIII of 06/19/2018 - applies to tax periods starting from May 1, 2018}
During the period of the legal regime of martial law, income in the form of monetary support for law enforcement officers, military personnel and employees of the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, privates, commanding officers, military personnel, employees of the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations established in accordance with the laws of Ukraine and other persons for the period of their direct participation in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation shall not be subject to military levy.
{Subparagraph 1.7 of paragraph 16 - 1 of subsection 10 of section XX is supplemented with a new paragraph in accordance with Law No. 2308-IX of June 19, 2022 }
The procedure for confirming the status of the specified persons for the purpose of applying the military tax exemption is determined by the Cabinet of Ministers of Ukraine.
{Subclause 1.7 of clause 16 - 1 of subsection 10 of section XX is supplemented with a new paragraph in accordance with Law No. 548-VIII of 18.06.2015 }
{ Clause 16 - 1 of subsection 10 of section XX supplemented by subparagraph 1.7 in accordance with Law No. 211-VIII of 02.03.2015 ; with amendments made in accordance with Law No. 381-VIII of 12.05.2015 }
1.8. Temporarily, for the period of implementation of the Bortnytsia Wastewater Treatment Plant modernization project within the framework of the implementation of the project "Reconstruction of wastewater treatment facilities and construction of a technological line for the treatment and utilization of sludge of the Bortnytsia Aeration Station", approved by the Cabinet of Ministers of Ukraine (hereinafter referred to as the Project), income (paid, provided) accrued to Japanese citizens (regardless of their residency status) by Japanese entities for the implementation of the Project in the form of wages and/or remuneration under civil law contracts shall not be subject to military tax. The specified exemption applies only to that part of the income related to the implementation of the Project.
The term "Japanese Project Implementing Entity" is used in the meaning given in paragraph 9 of subsection 1 of this section.
If the Japanese entity implementing the Project is a joint activity agreement, one or more participants of which (with more than 50 percent participation in such agreement) are persons specified in subparagraphs "a"-"c" of paragraph 9 of subsection 1 of this section, the rules of this subparagraph shall apply exclusively to the income of Japanese citizens accrued (paid, provided) by the operator of such joint activity.
{ Clause 16 - 1 of subsection 10 of section XX supplemented by subparagraph 1.8 in accordance with Law No. 903-VIII of 23.12.2015 }
the first paragraph of clause 10 of subsection 1 of this section is exempt from taxation by military levy .
{ Clause 16 - 1 of subsection 10 of section XX supplemented by subparagraph 1.9 in accordance with Law No. 2374-VIII of 22.03.2018 }
paragraphs 13 , 15 , 16 , 17 and 18 of subsection 1 of this section is exempt from taxation by military levy .
{Clause 16 - 1 of subsection 10 of section XX is supplemented by subparagraph 1.10 in accordance with Law No. 591-IX of 05/13/2020 ; as amended by Laws No. 1072-IX of 12/04/2020 , No. 1914-IX of 11/30/2021 }
1.11. The payers of the levy specified in subparagraph 2 of subparagraph 1.1 of this clause shall pay the military levy by making an advance payment no later than the 20th day (inclusive) of the current month. Such payers may pay the military levy by making an advance payment for the entire tax (reporting) period (quarter, year), but no later than until the end of the current reporting year. The calculation of advance payments for the payers of the levy specified in subparagraph 2 of subparagraph 1.1 of this clause shall be carried out by the supervisory authorities.
The payers of the fee specified in subparagraph 3 of subparagraph 1.1 of this paragraph shall pay the military fee within 10 calendar days after the deadline for submitting the tax return of the single tax payer for the tax (reporting) quarter.
The payers of the levy specified in subparagraphs 2 and 3 of subparagraph 1.1 of this paragraph shall reflect the amounts of the military levy (including monthly advance payments of the military levy) in the tax return of the single tax payer.
Failure to pay (fail to transfer) or payment (transfer) not in full by the payers of the levy specified in subparagraph 2 of subparagraph 1.1 of this clause, of advance payments on military levy in the manner and within the time limits specified in this clause, shall entail the imposition of a fine in the amount of 50 percent of the military levy rate specified in subparagraph 2 of subparagraph 1.3 of this clause.
The payers of the fee specified in subparagraph 3 of subparagraph 1.1 of this paragraph shall be held liable for violation of the rules for payment (transfer) of military fee amounts in the form of a fine in the amounts specified in Article 124 of this Code.
{Clause 16 - 1 of subsection 10 of section XX is supplemented by subparagraph 1.11 in accordance with Law No. 4113-IX of 04.12.2024 - for application, see paragraph two of clause 1 of section II}
1.12. Taxpayers - individuals - entrepreneurs - single tax payers of the first and second groups, whose tax address is located in the territories of hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation as of the date of the beginning of hostilities or temporary occupation, have the right not to pay the military tax for the period from the first day of the month in which hostilities began in the relevant territory, the possibility of hostilities arose or the temporary occupation of such territory began, until the last day of the month in which such active hostilities were completed, the possibility of hostilities ceased or the temporary occupation was completed.
At the same time, if the payers of the fee - individuals - entrepreneurs - single tax payers of the first and second groups do not pay the single tax and military tax, such persons do not fill out the declaration of the payer of the single tax - individual - entrepreneur for the period in which the single tax and military tax were not paid.
For such tax payers who have exercised the right not to pay military duty, the supervisory authority does not charge advance payments on military duty, as specified in the first paragraph of subparagraph 1.11 of this paragraph.
Tax liabilities for the payment of military duty are accrued to such tax payers for the periods for which the military duty was paid, which are reflected in the declaration of the single tax payer.
Penalties and fines for non-payment (non-transfer) or payment (transfer) of less than the full amount of advance payments for military duty in the manner and within the time limits specified by this Code shall not apply to such payers.
The dates of the beginning and end of active hostilities, the emergence and cessation of the possibility of hostilities or the beginning and end of the temporary occupation of the territory of Ukraine are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The provisions of this paragraph shall not apply from the first day of the month following the month in which the state registration of the change of location of an individual entrepreneur to a territory of Ukraine other than that specified in the first paragraph of this subparagraph was carried out.
{Clause 16 - 1 of subsection 10 of section XX is supplemented by subparagraph 1.12 in accordance with Law No. 4113-IX of 04.12.2024 - for application see paragraph two of clause 1 of section II}
1.13. Taxpayers - individuals - entrepreneurs - single tax payers of the first and second groups who do not use the labor of hired persons are exempt from paying military duty for one calendar month per year during vacation, as well as for the period of illness lasting 30 or more calendar days, which is confirmed by an extract from the Electronic Register of Sickness Certificates.
Information on the period of annual leave and the terms of temporary disability with the mandatory addition of an extract from the Electronic Register of Disability Certificates is submitted upon application in any form in accordance with subparagraph 298.3.2 of paragraph 298.3 of Article 298 of this Code.
{Clause 16 - 1 of subsection 10 of section XX is supplemented by subparagraph 1.13 in accordance with Law No. 4113-IX of 04.12.2024 - for application see paragraph two of clause 1 of section II}
1.14. To establish that from January 1, 2025 to December 31 of the third calendar year following the year in which martial law is terminated or abolished, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , when calculating the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots by single tax payers of the second and third groups and individual entrepreneurs - single tax payers of the fourth group to the total amount of taxes, fees, payments and expenses paid for the lease of land plots, determined by paragraphs 297 - 1 .2-297 - 1 .5 of Article 297 - 1 of this Code, the amounts of military duty paid in accordance with the provisions of this paragraph shall be included.
{Clause 16 - 1 of Subsection 10 of Section XX supplemented by subparagraph 1.14 in accordance with Law No. 4113-IX of 04.12.2024 - for application see paragraph two of clause 1 of Section II; and with amendments made in accordance with Law No. 4835-IX of 07.04.2026 }
1.15. The first tax (reporting) period of newly created business entities that are payers of the fee specified in subparagraphs 2 and 3 of subparagraph 1.1 of this paragraph begins on the first day of the month in which their state registration took place, but not earlier than January 1, 2025.
In the event of state registration of termination of the fee payers specified in subparagraphs 2 and 3 of subparagraph 1.1 of this paragraph, the last tax (reporting) period is considered to be the period in which the relevant supervisory authority received a notification from the state registrar about the state registration of such termination.
{Clause 16 - 1 of subsection 10 of section XX is supplemented by subparagraph 1.16 in accordance with Law No. 4113-IX of 04.12.2024 - for application, see paragraph two of clause 1 of section II}
1.16. The annual tax liability for military levy on the income of payers specified in paragraph 162.1 of Article 162 of this Code, which is included in the total annual taxable income for the 2024 reporting (tax) year and the final calculation of tax liabilities for which is made in the submitted annual tax declaration on property status and income, including from foreign income, is determined at the military levy rate of 1.5 percent (except for cases provided for in the third paragraph of this subparagraph).
The military tax rate of 5 percent applies to income included in the total annual taxable income and the final calculation of tax liabilities for which is carried out in the submitted annual tax return on property status and income accrued (paid) to taxpayers starting from January 1, 2025.
The amount of income from property transactions, income in the form of the value of inherited or gifted property, subject to taxation in accordance with the provisions of Section IV of this Code, received by a taxpayer after the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Ensuring Balanced Budget Revenues during the Period of Martial Law", is taxed by military duty at a rate of 5 percent, regardless of the indication of such income in the annual tax declaration on property status and income for 2024.
{Clause 16 - 1 of subsection 10 of section XX is supplemented by subparagraph 1.16 in accordance with Law No. 4113-IX of 04.12.2024 - for application, see paragraph two of clause 1 of section II}
1.17. The military levy paid in accordance with this paragraph shall be credited to the special fund of the State Budget of Ukraine and shall be used to meet the needs of the Armed Forces of Ukraine.
{Clause 16 - 1 of subsection 10 of section XX is supplemented by subparagraph 1.17 in accordance with Law No. 4835-IX of 07.04.2026 }
{Subsection 10 of Section XX supplemented by paragraph 16 - 1 in accordance with Law No. 1621-VII of 31.07.2014 }
{Item 17 of Subsection 10 of Section XX was excluded on the basis of Law No. 71-VIII of 28.12.2014 }
18. In order to form a register of payers of real estate tax other than land, owners of residential and/or non-residential real estate (individuals) may, based on the original documents on the right of ownership of real estate, reconcile information on residential and/or non-residential real estate owned by them until December 31, 2015 (inclusive).
{ Subsection 10 of Section XX is supplemented by paragraph 18 in accordance with the Law No. 403-VII dated 04.07.2013 ; as amended by Law No. 71-VIII dated 28.12.2014 }
19. To establish that by January 1, 2014, bodies performing treasury servicing of budget funds, in accordance with the Law of Ukraine "On the State Budget of Ukraine for 2013", on the basis of a conclusion received from the relevant supervisory body indicating the amount of value-added tax subject to reimbursement from the budget, shall issue to a taxpayer who has submitted to such supervisory body an application for choosing the method of reimbursement from the budget of the amount of value-added tax by obtaining a financial treasury bill, the amount of budget reimbursement specified in the conclusion by issuing, within the terms specified in paragraph 200.13 of Article 200 of this Code, financial treasury bills with a maturity of up to five years with an interest rate of 5 percent per annum.
The amount of value added tax subject to reimbursement from the budget through the issuance of financial treasury bills is divided into equal parts, for each of which a separate financial treasury bill is issued with a maturity of one, two, three, four and five years.
Issuance of a financial treasury bill is equivalent to issuing a budget refund to a taxpayer by transferring funds from the budget account to the taxpayer's account.
Upon the taxpayer's application submitted to the body responsible for treasury services of budget funds, the date of presentation of the bill for payment may be postponed to any other date following the date of presentation of the bill for payment within the calendar year in which the date of payment under the bill falls.
Taxpayers have the right to pay any agreed monetary obligation payable to the State Budget of Ukraine by presenting for payment (not earlier than the maturity date specified in the bill) to the body performing treasury services of budget funds, a financial treasury bill issued in accordance with this paragraph. Such presentation is equivalent to payment of the agreed monetary obligation by transferring funds from the taxpayer's account to the budget account.
The amount of the positive difference between the amount of any agreed monetary obligation payable to the State Budget of Ukraine and the amount of financial treasury bills payable against such agreed monetary obligation shall be paid by the taxpayer to the budget in funds in accordance with the procedure established by this Code.
The amount of the negative value of the difference between the amount of any agreed monetary obligation payable to the State Budget of Ukraine and the amount of financial treasury bills presented for payment on account of such agreed monetary obligation may, at the request of the taxpayer on the basis of a relevant application submitted by him, either be reimbursed to him from the budget in the manner established by this paragraph, or new financial treasury bills may be issued for such amount, in which the date of presentation of the bill for payment may be postponed to any other date following the date of presentation of the bill for payment, within the calendar year in which the date of payment under the bill falls.
Payment of income on financial treasury bills occurs at the time of their presentation for payment to the body that carries out treasury servicing of budget funds.
The procedure for issuing, circulating, accounting and paying for financial treasury bills issued in accordance with this paragraph shall be approved by the Cabinet of Ministers of Ukraine in accordance with the law.
{Subsection 10 of Section XX supplemented by paragraph 19 in accordance with Law No. 407-VII of 04.07.2013 }
20. Penalties for errors made when calculating monetary obligations in accordance with the provisions of Article 39 of this Code for the period from September 1, 2013 to December 31, 2014, shall be applied in the amount of 1 hryvnia for each violation.
In the event of independent adjustment of tax liabilities for the purpose of transfer pricing based on the results of the application of Article 39 of this Code for the period from September 1, 2013 to December 31, 2014, the penalties provided for in Article 50 of this Code shall not apply.
{Subsection 10 of Section XX supplemented by paragraph 20 in accordance with Law No. 408-VII of 04.07.2013 ; as amended by Law No. 1260-VII of 13.05.2014 }
20 - 1. Penalties for carrying out transactions by business entities for the sale of fuel in containers of up to two liters without registering such entities as excise tax payers, provided for in paragraph 117.3 of Article 117 of this Code, shall not apply from the date of the obligation to such registration.
Penalties for violation of the procedure for registering excise invoices and calculating adjustments to such excise invoices in the Unified Register of Excise Invoices, provided for in Article 120-2 of this Code, shall not apply to persons who sell fuel in containers of up to two liters from the date of the obligation to such registration.
{Subsection 10 of Section XX supplemented by paragraph 20 - 1 in accordance with Law No. 1797-VIII of 21.12.2016 }
{Item 21 of Subsection 10 of Section XX was excluded pursuant to Law No. 72-VIII of 28.12.2014 }
22. A single state registration web portal for legal entities and individual entrepreneurs shall be created in accordance with the law. Prior to the creation of this web portal, information from the registers on the registration of business entities as payers of taxes and fees, their registration as payers of value added tax (including as subjects of a special taxation regime) and the single tax shall be published on the official website of the central executive body implementing state tax and customs policy, in accordance with the requirements established by this Code.
{Subsection 10 of Section XX supplemented by paragraph 22 in accordance with Law No. 657-VII of 10/24/2013 ; as amended by Law No. 1797-VIII of 12/21/2016 }
23. To establish that bodies that provide treasury services for budget funds, in accordance with the Law of Ukraine "On the State Budget of Ukraine for 2014", on the basis of the taxpayer inventory registers and conclusions received from the relevant regulatory body indicating the amount of value added tax subject to reimbursement from the budget, shall issue to taxpayers who have submitted to such regulatory body an application for reimbursement of value added tax amounts in the form of domestic government loan bonds, the amount of budget reimbursement specified in the registers and conclusions by issuing, within the terms specified in Clause 200.13 of Article 200 of this Code, domestic government loan bonds with a maturity of five years.
The issuance of a refund of value added tax amounts in domestic government loan bonds is equivalent to issuing the taxpayer with a budget refund amount by transferring funds from the budget account to the taxpayer's account.
The procedure for the issue, circulation, and repayment of the specified domestic government loan bonds for the reimbursement of value added tax amounts, as well as the main conditions for their issue, shall be approved by the Cabinet of Ministers of Ukraine.
{Subsection 10 of Section XX is supplemented by paragraph 23 in accordance with Law No. 719-VII of 01.16.2014, taking into account the amendments made by Law No. 1165-VII of 03.27.2014 }
24. To establish that in 2014, the report on controlled transactions, which in accordance with Article 39 of this Code is submitted to the central executive body that ensures the formation and implementation of state tax and customs policy, for the period from September 1 to December 31, 2013, shall be submitted by October 1, 2014.
{Subsection 10 of Section XX supplemented by paragraph 24 in accordance with Law No. 1260-VII of 13.05.2014 }
25. Self-employed persons (individual entrepreneurs, persons engaged in independent professional activities), who had or did not have employees, were called up for military service during mobilization or involved in the performance of mobilization duties in positions provided for by wartime staff, during a special period determined by the Law of Ukraine "On Mobilization Training and Mobilization", or under a contract, for the entire period of their military service (from the first day of the month in which the person was called up for military service or in which a contract was concluded with the person, but not earlier than February 24, 2022, until the last day of the month in which the person was demobilized (discharged from military service) are exempted from the obligation to calculate, pay and submit tax reporting on personal income tax in accordance with Section IV of this Code, are exempted from the obligation to calculate, pay and submit tax reporting on the single tax in accordance with Chapter 1 of Section XIV of this of the Code, and are also exempt from the obligation to charge, pay and submit reports on military duty as part of tax reports on personal income tax or single tax in accordance with paragraph 16 - 1 of this subsection.
The basis for such exemption is information received by the central executive body implementing state tax policy from the Unified State Register of Conscripts, Military Conscripts and Reservists, on the date of mobilization, conclusion of a contract, demobilization (discharge from military service) of a self-employed person.
The central executive body that ensures the formation and implementation of state policy on national security issues in the military sphere, defense and military construction in peacetime and special periods, provides the central executive body that implements state tax policy with information from the Unified State Register of Conscripts, Military Obligors and Reservists in electronic form.
If a self-employed person called up for military service by conscription during mobilization, for a special period, under a contract, has employees and for the period of his military service, for a special period, authorizes another person to pay wages and/or other income to the employees, the obligation to calculate and withhold personal income tax and military levy from such payments for the period of the self-employed person's military service shall be borne by such authorized person.
Personal income tax and military levy, calculated and withheld by an authorized person from such payments to individuals, shall be paid to the budget by a demobilized (discharged from military service) self-employed person, including a person who has completed military service under a contract, within 180 calendar days from the date of his or her demobilization (discharge from military service), without the accrual of fines and financial sanctions, or penalties.
Tax reporting on the amounts of personal income tax and military levy, calculated and withheld by an authorized person from employees and other individuals during the period of military service of a self-employed person, shall be submitted by a demobilized self-employed person within 150 calendar days from the date of his demobilization (discharge from military service) in accordance with the procedure established by this Code, without the accrual of penalties and financial sanctions, fines provided for by this Code.
The provisions of this paragraph shall apply from the first day of mobilization, announced by the Decree of the President of Ukraine dated March 17, 2014 No. 303 "On Partial Mobilization", approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On Partial Mobilization".
Based on information on the date of mobilization, conclusion of a contract, demobilization (discharge from military service) received by the central executive body implementing state tax policy from the Unified State Register of Conscripts, Military Obligors and Reservists, the supervisory body shall not calculate advance payments from the single tax provided for in Clause 295.2 of Article 295 of this Code and advance payments from the military levy provided for in Subclause 1.11 of Clause 16 - 1 of Subsection 10 of Section XX of this Code, starting from the month in which the supervisory body received information on the mobilization of such an individual entrepreneur, the conclusion of a contract, ending with the month in which such an individual was demobilized (discharged from military service).
The amounts of advance payments for the single tax and military levy accrued by the supervisory authority for the period of mobilization or the validity of the contract, the amounts of penalties and fines for non-payment (non-transfer) or payment (transfer) not in full of advance payments for the single tax, personal income tax, military levy in the manner and within the terms specified by this Code, shall be subject to cancellation (cancellation) for the reporting periods, taking into account the limitation period, inclusively up to the first day of the month following the month in which the supervisory authority received information about the mobilization of such an individual - entrepreneur, and a contract was concluded with such an individual.
For individuals - entrepreneurs who had or did not have employees, called up for military service during mobilization or involved in the performance of mobilization duties in positions provided for by wartime staff, during a special period determined by the Law of Ukraine "On Mobilization Preparation and Mobilization", or under a contract, whose registration as a single tax payer was canceled by the decision of the supervisory authority on the basis of subparagraph 8 of subparagraph 298.2.3 of paragraph 298.2 of Article 298 of this Code during their military service, the supervisory authority shall restore such registration from the date of cancellation.
A self-employed person who, due to being called up for military service during mobilization, for a special period, or undergoing military service under a contract, has failed to meet the deadlines specified by this Code for fulfilling tax obligations that arose before the date of mobilization, conclusion of a contract, and/or during military service, shall be exempted from liability provided for by this Code for failure to fulfill tax obligations, provided that such obligations are fulfilled within 180 calendar days from the date of demobilization (discharge from military service) or completion of treatment (rehabilitation).
In the absence of information in the Unified State Register of conscripts, military conscripts and reservists or the failure of the central executive body implementing the state tax policy to receive information on the date of mobilization, conclusion of a contract, demobilization (discharge from military service) of a self-employed person (individual entrepreneur, person engaged in independent professional activity), such a person has the right to submit an application and a copy of a military ID card or a copy of another document issued by the relevant state body, indicating data on the call-up of such a person to military service by conscription during mobilization, for a special period, a copy of the contract. The procedures for exemption from paying taxes, fees, non-assessment of taxes, fees, write-off of punitive (financial) sanctions, fines, renewal of registration as a single tax payer, submission of reporting, payment and release from liability apply to self-employed persons who have submitted an application and relevant documents to the supervisory body in accordance with this paragraph.
{Subsection 10 of Section XX supplemented by paragraph 25 in accordance with Law No. 1275-VII of 05/20/2014 ; as amended in accordance with Law No. 4113-IX of 12/04/2024 ; as amended by Law No. 4505-IX of 06/18/2025 }
26. To establish that temporarily, for the period of validity of the Law of Ukraine "On Ensuring the Rights and Freedoms of Citizens and the Legal Regime in the Temporarily Occupied Territory of Ukraine", for taxpayers who, on the date of the lapse of validity of the Law of Ukraine "On the Creation of the Free Economic Zone "Crimea" and on the Peculiarities of Carrying Out Economic Activities in the Temporarily Occupied Territory of Ukraine", have a tax address and/or objects of taxation in the temporarily occupied territory of the Autonomous Republic of Crimea and the city of Sevastopol, this Code shall be applied taking into account the features specified in this paragraph.
In this paragraph, the following terms are used:
other territory of Ukraine - the territory of Ukraine, except for the temporarily occupied territory of the Autonomous Republic of Crimea and the city of Sevastopol and the temporarily occupied territory recognized as such in accordance with the Law of Ukraine "On the Peculiarities of State Policy for Ensuring the Sovereignty of Ukraine in the Temporarily Occupied Territories in Donetsk and Luhansk Regions".
The term " temporarily occupied territory " for the purposes of this paragraph is used in the meaning defined in the Law of Ukraine "On Ensuring the Rights and Freedoms of Citizens and the Legal Regime in the Temporarily Occupied Territory of Ukraine".
26.1. In the temporarily occupied territory:
1) state and local taxes and fees specified in Articles 9 and 10 of this Code, and military duty specified in Clause 16 - 1 of this subsection, are not collected;
2) taxpayers with a tax address in the temporarily occupied territory are exempted from the obligation to submit to the regulatory authorities declarations, reports and other documents related to the calculation and payment of taxes and fees;
3) regulatory bodies do not conduct desk, documentary and factual inspections;
Articles 59 , 60 and 87-101 of this Code to taxpayers is suspended ;
5) the accrual of punitive (financial) sanctions (fines) and/or penalties for untimely repayment of monetary obligations and other violations of tax, customs and other legislation, control over which is entrusted to regulatory authorities, is suspended.
26.2. The supervisory authority shall, without the taxpayer submitting an application, write off the tax debt (including penalties, fines and unpaid interest for using installments (deferral)) of a taxpayer with a tax address in a temporarily occupied territory, which, according to the information and telecommunications systems of the central executive body implementing state tax policy, arose during the period from the date of the start of the temporary occupation, determined by the Law of Ukraine "On Ensuring the Rights and Freedoms of Citizens and the Legal Regime in the Temporarily Occupied Territory of Ukraine", and remained unpaid/unrepaid as of the date of the decision to write off such debt.
Such write-off is carried out without applying the provisions of Article 101 of this Code and exclusively based on data contained in the information and telecommunications systems of the central executive body implementing state tax policy.
The written-off amounts are subject to recovery if circumstances are discovered indicating that there are no grounds for the write-off.
The provisions of this paragraph do not apply to persons subject to judicial procedures defined by bankruptcy legislation and/or to whom special restrictive measures (sanctions) provided for by the Law of Ukraine "On Sanctions" have been applied.
The amounts of tax debt, penalties, fines and interest for using installments (deferrals) paid before the date of the decision to write off the tax debt in accordance with this paragraph are not subject to refund to the taxpayer's current account, are not directed to repay the monetary obligation (tax debt) from other taxes, fees, and are not returned in cash by check if the taxpayer does not have bank accounts.
The amounts written off in accordance with this paragraph shall not be subject to penalties or interest provided for by this Code for the period from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Other Legislative Acts of Ukraine Regarding the Administration of Taxes and Fees in the Temporarily Occupied Territory of the Autonomous Republic of Crimea and the City of Sevastopol" and up to and including the date of writing off.
The write-off of tax debt in accordance with this subparagraph is the basis for the release of the taxpayer's property from tax lien and its exclusion from the relevant state registers.
Based on the information provided by the supervisory authority on the written-off amounts of tax debt, the enforcement proceedings opened by the state enforcement service shall be terminated and the measures of compulsory execution of decisions on the collection of tax debt from taxpayers whose tax debt amounts are written off in accordance with this subparagraph shall be terminated, in accordance with the procedure specified by the Law of Ukraine "On Enforcement Proceedings";
26.3. Any income with a source of origin from another territory of Ukraine, accrued (paid) to the benefit of persons who have a tax address in the temporarily occupied territory, shall be taxed according to the rules established by this Code for their payment (repatriation) outside Ukraine.
26.4. In the event of business transactions between persons who have a tax address in the temporarily occupied territory and taxpayers who have a tax address in another territory of Ukraine, the provisions of Article 39 of this Code shall apply to such transactions, taking into account the criteria specified in subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code.
26.5. Registration by the value added tax payer, in accordance with the requirements of Article 183 of this Code, of persons whose tax address or that of one of the participants under a joint activity agreement, property management agreement, or production sharing agreement is a temporarily occupied territory, shall not be carried out by the controlling bodies until the expiration of the temporary occupation period or the change of tax address by such taxpayer from a temporarily occupied territory to another territory of Ukraine.
26.6. Taxpayers who store fuel and/or ethyl alcohol in the temporarily occupied territory are prohibited from taking into account the corresponding amounts of fuel and/or ethyl alcohol in the formula specified in Clause 232.3 of Article 232 of this Code, based on the act of inventorying the amounts of fuel remaining as of the beginning of March 1, 2016 and/or the act of inventorying the amounts of ethyl alcohol remaining as of the beginning of July 1, 2019, as the amount for which the taxpayer has the right to register an adjustment in the electronic administration system for the sale of fuel and ethyl alcohol.
paragraphs 213.2 and 213.3 of Article 213 and Articles 225 , 226 , 229-233 of this Code to taxpayers whose tax address is a temporarily occupied territory is suspended.
For taxpayers whose tax address is another territory of Ukraine, and the place of activity is a temporarily occupied territory, the application of the norms of paragraphs 213.2 and 213.3 of Article 213 and Articles 225 , 226 , 229-233 of this Code regarding activities carried out at such a place and/or facilities located in the temporarily occupied territory shall be suspended.
26.7. Registration by the excise tax payer in accordance with the requirements of paragraph 212.3 of Article 212 of this Code of persons whose tax address and/or place of business is a temporarily occupied territory shall not be carried out by the controlling authorities until the expiration of the temporary occupation period or the change of tax address and/or place of business to another territory of Ukraine.
The registration of persons whose tax address is a temporarily occupied territory as a single tax payer in accordance with the requirements of Articles 298 and 299 of this Code shall not be carried out by the controlling bodies until the expiration of the temporary occupation period or the change of tax address to another territory of Ukraine.
26.8. Income of an individual - a citizen of Ukraine, who has a tax address in the temporarily occupied territory, received in the form of the value of inherited (gifted) property (funds, property, property or non-property rights), is taxed by personal income tax and military levy according to the general taxation rules established by this Code.
From income received in the form of the value of inherited (gifted) property (funds, property, property or non-property rights) within the taxable limits, personal income tax and military levy are paid by heirs - citizens of Ukraine who have a tax address in the temporarily occupied territory, before notarization of the inheritance objects (gift) or in rural settlements - before registration by an authorized official of the relevant local government body at the place of opening the inheritance.
After state registration of the termination of entrepreneurial activity of individual entrepreneurs whose tax address is the temporarily occupied territory, procedures and actions to ensure final settlements of taxes from entrepreneurial activity and submission of tax reports, in accordance with the requirements of this Code, may be carried out at the place of residence of such individuals in case they apply to the relevant regulatory authorities.
26.9. Income of individuals, including employees, who have a permanent place of residence in the temporarily occupied territory, in particular wages and other similar payments and compensations paid by tax agents, including employers, located in another territory of Ukraine, are taxed according to the general rules at the location of such tax agent (employer).
26.10. In the event of accrual (payment) of income from their entrepreneurial activity to individuals - entrepreneurs (regardless of the taxation system), whose tax address is the temporarily occupied territory, the business entity and/or self-employed person who accrues (pays) such income shall be obliged to withhold income tax at the source of payment. In this case, clause 177.8 of Article 177 and subparagraph 2 of clause 297.1 of Article 297 of this Code shall not apply to such persons.
Income from entrepreneurial activity, taxed in accordance with this subparagraph, is not included in the total taxable income of an individual entrepreneur and/or the income of an individual entrepreneur who is a single tax payer.
26.11. Any taxes and fees collected in the temporarily occupied territory do not change the amount of tax liabilities for taxes and fees assessed (subject to collection) in another territory of Ukraine.
26.12. The supervisory authority shall cancel the registration of single tax payers of the third group who have a tax address in the temporarily occupied territory, according to the data of the information and telecommunications systems of the central executive body implementing the state tax policy, without making a decision on each individual taxpayer.
{Subsection 10 of Section XX supplemented by paragraph 26 in accordance with Law No. 1636-VII of 12.08.2014 ; as amended by Law No. 1617-IX of 01.07.2021 }
27. To establish that, based on the results of economic activity for the last reporting (tax) period of 2014, payers of the fee for conducting certain types of entrepreneurial activity, the fee in the form of a targeted surcharge to the current tariff for natural gas for consumers of all forms of ownership, the fee for parking spaces for vehicles, the tourist fee, the fee for the development of viticulture, horticulture and hop growing, the fee for the first registration of a vehicle, the fee in the form of a targeted surcharge to the current tariff for electric and thermal energy, except for electricity produced by qualified cogeneration plants, the fee for the special use of forest resources, the fee for the use of the radio frequency resource of Ukraine, the fee for the special use of water, the fee for the use of subsoil, the fee for land, the single tax, the fixed agricultural tax, the environmental tax for emissions of pollutants into the atmosphere by mobile sources of pollution, the excise tax on transactions on the alienation of securities and transactions with derivatives, shall submit tax returns (calculations) for such taxes and fees in accordance with the procedure established by this Code.
{Subsection 10 of Section XX supplemented by paragraph 27 in accordance with Law No. 71-VIII of 28.12.2014 }
{Item 28 of Subsection 10 of Section XX was excluded pursuant to Law No. 129-IX of 09/20/2019 }
29. Temporarily, until January 1, 2016, a fee is established in the form of a targeted surcharge to the current price of natural gas for consumers of all forms of ownership.
{Paragraph one of clause 29, subsection 10, section XX, as amended by Law No. 812-VIII of 24.11.2015 }
1.1. Tax payers are business entities and their separate divisions, including authorized persons of simple partnership agreements, who:
a) carry out activities related to the supply of natural gas to consumers on the basis of contracts concluded with them;
b) consume the natural gas they import as fuel or raw material;
c) consume the natural gas they produce as fuel or raw material.
1.2. The object of taxation by the fee is the cost of natural gas in the amount of:
a) released to each category of consumers in the reporting period, which is determined on the basis of gas acceptance and delivery acts signed by the payer and the relevant consumer (for household consumers - on the basis of accounting documents), for payers specified in subparagraph "a" of subparagraph 1.1 of this paragraph;
{Subparagraph "a" of subparagraph 1.2 of paragraph 29 of subsection 10 of section XX as amended by Law No. 812-VIII of 24.11.2015 }
b) imported in the reporting period by the payer specified in subparagraph "b" of subparagraph 1.1 of this paragraph;
c) extracted and consumed as fuel or raw material by an oil and gas producing enterprise or its subdivisions, as determined by the payers in subparagraph "c" of subparagraph 1.1 of this clause, with the exception of the volume of natural gas recognized as recycled in accordance with Section I, which is determined by the payer based on the indicators of measuring devices indicated in the record of extracted minerals in compliance with the schemes of movement of extracted hydrocarbon raw materials at production sites and storage locations independently approved by the payer in accordance with the requirements of the licensing conditions, taking into account the composition of the source raw materials, specific production conditions, and features of the technological process.
1.3.1. The fee is levied at the rate of 2 percent on the volumes of natural gas supplied to the following categories of consumers:
a) municipal heat and power enterprises, thermal power plants, power plants and boiler houses of business entities, in particular block (modular) boiler houses (in the volume used to provide heating and hot water supply services to the population, provided that such entities maintain separate instrumentation and accounting records of heat and hot water);
b) budgetary institutions;
c) industrial and other business entities and their separate divisions that use natural gas;
d) business entities defined in subparagraph "b" of subparagraph 1.1 of this paragraph;
e) business entities, including authorized persons of simple partnerships, defined in subparagraph "c" of subparagraph 1.1 of this paragraph.
1.3.2. A tax of 4 percent is levied on the volume of natural gas supplied to household consumers.
{Subclause 1.3.2 of subparagraph 1.3 of clause 29 of subsection 10 of section XX as amended by Law No. 812-VIII of 24.11.2015 }
1.4. Consumers are the following categories: household consumers, budget institutions, municipal heat and power enterprises, thermal power plants, power plants and boiler houses of business entities, including block (modular) boiler houses, other business entities and their separate divisions that use natural gas for the production of goods and provision of services, for other own needs.
{Subclause 1.4 of Clause 29, Subsection 10, Section XX, as amended by Law No. 812-VIII of 24.11.2015 }
1.5. The current price of natural gas should be understood as:
{Paragraph one of subparagraph 1.5 of clause 29, subsection 10 of section XX as amended by Law No. 812-VIII of 24.11.2015 }
a) the contractual price of natural gas as a commodity (excluding tariffs for its transportation and distribution, the trade mark-up of the natural gas supplier within the maximum trade mark-up determined by the Cabinet of Ministers of Ukraine in accordance with Article 11 of the Law of Ukraine "On the Natural Gas Market", and the amount of value added tax) for payers specified in subparagraph "a" of subparagraph 1.1 of this paragraph;
{Subparagraph "a" of subparagraph 1.5 of paragraph 29 of subsection 10 of section XX as amended by Law No. 812-VIII of 24.11.2015 }
b) the customs value of natural gas clearance for payers specified in subparagraph "b" of subparagraph 1.1 of this paragraph;
c) the average customs value of imported natural gas for payers specified in subparagraph "c" of subparagraph 1.1 of this paragraph. The average customs value of imported natural gas, established during its customs clearance during import into the territory of Ukraine for the tax (reporting) period, is calculated by the central executive body implementing the state tax and customs policy, and is transferred by it by the 5th day of the month following the tax (reporting) period to the central executive body implementing the state policy of economic development, which by the 10th day of the month following the tax (reporting) period, places it on its official website in a special section.
1.6. The basic tax (reporting) period for collection is equal to a calendar month.
1.7. Tax declarations of the fee are submitted by the fee payers to the supervisory authorities within the deadlines specified for the monthly tax (reporting) period, at the place of tax registration.
The form of the tax declaration shall be established in accordance with the procedure provided for in Article 46 of this Code.
The fee is paid by the fee payers within the deadlines specified for the monthly tax (reporting) period, at the place of tax registration.
1.8. Payers specified in subparagraph "b" of subparagraph 1.1 of this paragraph shall pay the fee before or on the day of submission of the customs declaration.
{Subsection 10 of Section XX supplemented by paragraph 29 in accordance with Law No. 71-VIII of 28.12.2014 }
30. To establish that temporarily, during the validity of international treaties (agreements) of Ukraine on space activities ratified by the Verkhovna Rada of Ukraine regarding the creation of space technology (including units, systems and their components for space complexes, space launch vehicles, spacecraft and ground segments of space systems), but no later than January 1, 2018, residents - subjects of space activities who have received a license for the right to carry it out and participate in the implementation of such treaties (agreements) are exempt from paying tax on property other than land according to the list approved by the Cabinet of Ministers of Ukraine.
{Subsection 10 of Section XX supplemented by paragraph 30 in accordance with Law No. 71-VIII of 28.12.2014 }
31. As a result of the activities in 2015, punitive (financial) sanctions against corporate income tax payers for violating the procedure for calculating, correctly filling out corporate income tax returns, and completely paying them are not applied.
{Subsection 10 of Section XX supplemented by paragraph 31 in accordance with Law No. 71-VIII of 28.12.2014 }
32. Temporarily, until July 1, 2015, establish that in cases where a tax debt arose as a result of non-payment of a monetary obligation independently determined by the taxpayer in the tax return or clarifying calculation submitted to the regulatory authority within the terms established by this Code, the collection of funds from cash belonging to such a taxpayer and/or funds from such taxpayer's bank accounts shall be carried out by decision of the head of the regulatory authority without recourse to the court, provided that such tax debt exceeds 5 million hryvnias and there are no obligations of the state to return to such a taxpayer monetary obligations paid by mistake and/or in excess.
In such cases:
the decision to collect funds from such payer's bank accounts is a demand of the collector to the debtor, which is subject to immediate and mandatory execution by initiating a transfer in the payment system according to the rules of the relevant payment system;
The decision to collect cash is delivered to such taxpayer and is the basis for collection. Cash collection is carried out in accordance with the procedure determined by the Cabinet of Ministers of Ukraine.
{Subsection 10 of Section XX supplemented by paragraph 32 in accordance with Law No. 71-VIII of 28.12.2014 }
33. To establish that for 2015, tax rates for non-residential real estate owned by individuals and legal entities, determined by clause 266.5.1. clause 265.5 of Article 265 of this Code, may not exceed 1 percent of the minimum wage established by law as of January 1 of the reporting (tax) year per 1 sq. meter for non-residential real estate.
{Subsection 10 of Section XX supplemented by paragraph 33 in accordance with Law No. 71-VIII of 28.12.2014 }
34. Establish that for controlled transactions with residents carried out before January 1, 2015, proportional adjustment shall be carried out according to the rules in force before January 1, 2015.
{Subsection 10 of Section XX supplemented by paragraph 34 in accordance with Law No. 609-VIII of 15.07.2015 }
35. Temporarily, until December 31, 2016 inclusive, for taxpayers whose income and/or transactions in the previous (reporting) year amounted to less than 20 million hryvnias, fines (financial) sanctions accrued on the amount of tax liability that the taxpayer paid without appealing the tax notice-decision within the terms specified by this Code shall be canceled within 10 days from the date of payment of such tax liability in accordance with the procedure established by the central executive body that ensures the formation and implementation of state financial policy. The specified norm shall not apply in the event of repeated determination by the controlling body of the amount of tax liability for the same tax or fee during the year. In this case, in the event of cancellation of the fine, the corresponding paid tax liability shall not be subject to further appeal.
{Subsection 10 of Section XX supplemented by paragraph 35 in accordance with Law No. 655-VIII of 17.07.2015 }
36. If, based on the results of the consideration of criminal proceedings on a criminal offense that was initiated before the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Reducing the Tax Pressure on Taxpayers" and the subject of which is taxes and fees, a court has issued a guilty verdict that has entered into legal force, which establishes non-payment of tax obligations or a ruling has been issued to close criminal proceedings on non-rehabilitative grounds on this issue, a tax notification-decision based on the results of such an inspection shall be adopted by the supervisory authority within 10 working days from the day following the day of receipt by this supervisory authority of the relevant court decision (conviction verdict, ruling on closing criminal proceedings on non-rehabilitative grounds) that has entered into legal force.
{Subsection 10 of Section XX supplemented by paragraph 36 in accordance with Law No. 655-VIII of 17.07.2015 }
37. The implementation by the supervisory authorities of a restructuring plan signed in accordance with the law on financial restructuring (hereinafter referred to as the restructuring plan) or a rehabilitation plan approved in accordance with the legislation regulating relations on issues of restoring the solvency of the debtor or declaring him bankrupt, taking into account the features established by the law on financial restructuring (hereinafter referred to as the rehabilitation plan), in the event of their recognition by involved creditors in accordance with the Law of Ukraine "On Financial Restructuring", shall be carried out taking into account the features established by this paragraph.
{Paragraph one of clause 37, subsection 10, section XX, as amended by Law No. 425-IX of 20.12.2019 }
Restructuring of tax debt and monetary obligations of a taxpayer under the terms of a restructuring plan or a rehabilitation plan shall be carried out in accordance with this paragraph and shall not require the conclusion of a separate installment agreement (deferral) in accordance with Article 100 of this Code.
Restructuring of the tax debt and monetary obligations of the taxpayer in accordance with this paragraph shall be carried out by the supervisory authorities by means of cancellation (forgiveness), installment (deferral) of the tax debt and monetary obligations.
Debt restructuring operations in accordance with a restructuring plan or a rehabilitation plan are not recognized as controlled operations in accordance with Article 39 of this Code and the requirements of this Code established for controlled operations do not apply to them.
The supervisory authorities shall write off, defer (defer) the tax debt and monetary obligations of the taxpayer within 10 working days from the date of signing the restructuring plan or approving the rehabilitation plan.
{Paragraph five of clause 37, subsection 10, section XX, as amended by Law No. 425-IX of 12/20/2019 }
The supervisory authorities are obliged to write off part of the tax debt in proportion to the part of the debtor's obligations canceled (forgiven) by creditors in accordance with the restructuring plan or rehabilitation plan. The installment (deferral) or write-off of the tax debt is carried out under the terms of the restructuring plan or rehabilitation plan. Such terms must not be worse than the terms for satisfying the claims of other creditors, determined by the restructuring plan or rehabilitation plan. The total repayment term of the installment (deferred) tax debt cannot exceed three years from the date of signing the restructuring plan or approving the rehabilitation plan.
{Paragraph six of clause 37, subsection 10, section XX, as amended by Law No. 425-IX of 12/20/2019 }
The taxpayer's property is released from tax lien and administrative arrest from the date of signing the restructuring plan or approving the rehabilitation plan.
{Paragraph seven of clause 37, subsection 10, section XX, as amended by Law No. 425-IX of 12/20/2019 }
Repayment of restructured tax liabilities shall be carried out by the taxpayer under the terms of the restructuring plan or rehabilitation plan. In the event of failure by the taxpayer to fulfill its obligations to repay restructured tax liabilities, the deadline for fulfilling tax liabilities shall be deemed to have come.
Tax debt and monetary obligations of a taxpayer for personal income tax and for a single contribution to mandatory state social insurance are not subject to write-off and/or restructuring, except for penalties and fines.
The following shall be recognized as hopeless regardless of the existence of the criteria for determining a tax debt as hopeless, established in Article 101 of this Code, and shall be subject to write-off by the supervisory authorities:
a taxpayer's tax debt that arose more than three years before the date of commencement of the financial restructuring procedure in accordance with the law on financial restructuring;
a taxpayer's tax debt that arose within three years prior to the date of commencement of the financial restructuring procedure in accordance with the law on financial restructuring, which is written off under the terms of a restructuring plan or a rehabilitation plan;
penalties and interest accrued to the taxpayer before the date of commencement of the financial restructuring procedure in accordance with the law on financial restructuring, for which administrative or judicial appeal procedures are ongoing.
The taxpayer's unwritten tax debt and monetary obligations that arose before the date of the start of the financial restructuring procedure in accordance with the law on financial restructuring, under the terms of the restructuring plan or rehabilitation plan, are subject to installment (deferral).
Termination of a restructuring plan or rehabilitation plan is grounds for the imposition of fines, penalties and financial sanctions in accordance with the legislation on the unpaid amount of tax (fee) debt.
{Subsection 10 of Section XX supplemented by paragraph 37 in accordance with Law No. 909-VIII of 24.12.2015 }
38. To establish that temporarily, for the period of the anti-terrorist operation and/or the implementation of measures to ensure the conduct of the Joint Forces (JFO) operation, for taxpayers who, as of April 14, 2014, were located (residence) in the temporarily occupied territory, recognized as such in accordance with the Resolution of the Verkhovna Rada of Ukraine "On the Recognition of Certain Districts, Cities, Towns and Villages of Donetsk and Luhansk Regions as Temporarily Occupied Territories", or in settlements on the contact line, and/or taxpayers who have objects of taxation with local taxes, fees in these territories, the collection of taxes and fees shall be carried out taking into account the features specified in this paragraph. The effect of this paragraph shall not apply to the territory of Ukraine recognized as temporarily occupied in accordance with the Law of Ukraine "On Ensuring the Rights and Freedoms of Citizens and the Legal Regime in the Temporarily Occupied Territory of Ukraine".
{Paragraph one of clause 38, subsection 10, section XX, as amended by Law No. 2628-VIII of 11/23/2018 }
38.1. In this clause, the terms are used in the following meaning:
temporarily occupied territory - the territory of certain districts, cities, towns and villages of Donetsk and Luhansk regions, determined in accordance with the Resolution of the Verkhovna Rada of Ukraine "On the recognition of certain districts, cities, towns and villages of Donetsk and Luhansk regions as temporarily occupied territories", in which state authorities temporarily do not exercise their powers. The list of settlements in the territory of which state authorities temporarily do not exercise their powers is determined by the Cabinet of Ministers of Ukraine;
the territory of settlements on the contact line - the territory of settlements located on the contact line, the list of which is determined by the Cabinet of Ministers of Ukraine;
other territory of Ukraine - the territory of Ukraine, except for the temporarily occupied territory and the territory of settlements on the contact line.
The terms "period of anti-terrorist operation" and "territory of anti-terrorist operation" are used in this paragraph in the meaning given in the Law of Ukraine "On Temporary Measures for the Period of Anti-terrorist Operation".
38.2. For the period of the anti-terrorist operation and/or the implementation of measures to ensure the conduct of the Joint Forces (JFO) operation for taxpayers whose location (place of residence) as of April 14, 2014 was the temporarily occupied territory and/or the territory of settlements on the contact line and who as of January 1, 2017 did not change their location (place of residence) from the specified territories to another territory of Ukraine:
{Paragraph one of subparagraph 38.2 of clause 38, subsection 10 of section XX, as amended by Law No. 2628-VIII of 23.11.2018 }
1) the accrual of punitive (financial) sanctions (fines) and/or penalties for untimely repayment of monetary obligations determined as of April 14, 2014 is suspended;
2) the application of the provisions of Articles 59 , 60 (in terms of tax requirements), 87-101 of this Code is suspended.
The limitation period specified in Article 102 of this Code shall be suspended for the period during which the collection measures provided for in Articles 59 , 60 , 87-101 of this Code were not applied to the taxpayers specified in this subparagraph .
The provisions of this subparagraph do not apply:
from the date of registration of a change of place of residence by an individual taxpayer and relocation to another territory of Ukraine to a permanent place of residence, place of residence of an internally displaced person and carrying out a registration action regarding a change of place of residence of an individual entrepreneur;
from the date of registration of the change of location of the legal entity to another territory of Ukraine.
38.3. For taxpayers - self-employed individuals during the special period specified by the Law of Ukraine "On Mobilization Training and Mobilization", called up for military service during mobilization or involved in the performance of mobilization duties in positions provided for by wartime staffing, the provisions of subparagraph 38.2 of this paragraph shall apply for the entire period of their military service.
38.4. If the actual location of a branch, representative office, separate or other structural unit of a legal entity is:
temporarily occupied territory, and the location of the relevant legal entity is another territory of Ukraine or the territory of settlements on the contact line, such legal entity, separate or other structural unit, authorized to calculate, withhold and pay (transfer) to the budget or to a single account taxes, fees in cases provided for by this Code, are exempted from liability specified by this Code, within the scope of activities carried out through such branches, representative offices, separate or other structural units, for the entire period of conducting an anti-terrorist operation and/or implementing measures to ensure the conduct of the Joint Forces (JFO) operation;
{Paragraph two of subparagraph 38.4 of paragraph 38, subsection 10 of section XX as amended by Laws No. 2628-VIII of 11/23/2018 , No. 190-IX of 10/04/2019 }
other territory of Ukraine or the territory of settlements on the contact line, and the location of the relevant legal entity is a temporarily occupied territory, such branches, representative offices, separate or other structural units are registered as separate payers of taxes and fees and pay taxes and fees on the terms and in the manner specified by this Code.
38.5. Taxpayers whose location (place of residence) is the temporarily occupied territory and who produce (import) alcoholic beverages and/or tobacco products in the specified territory do not have the right to order excise tax stamps for labeling alcoholic beverages and/or tobacco products produced in the temporarily occupied territory.
The importation of tobacco products and/or alcoholic beverages produced in the temporarily occupied territory into other territories of Ukraine and the territories of settlements on the contact line is prohibited.
of paragraphs 213.2 and 213.3 of Article 213 and Articles 225 , 229 of this Code shall be suspended for taxpayers whose location (place of residence) and/or place of business is a temporarily occupied territory.
38.6. Residential and non-residential real estate located in the temporarily occupied territory, owned by individuals or legal entities, are not subject to taxation by real estate tax other than land, in accordance with Article 266 of this Code during the period from April 14, 2014 to December 31 of the year in which the anti-terrorist operation and/or the operation of the Joint Forces (JFO) was completed.
{Paragraph one of subparagraph 38.6 of clause 38, subsection 10 of section XX, as amended by Laws No. 2628-VIII of 23.11.2018 , No. 466-IX dated 16.01.2020 }
When calculating the tax base for real estate objects, including their shares owned by individuals, the controlling body shall not take into account real estate objects that are not subject to taxation in accordance with this subparagraph.
{Subclause 38.6 of clause 38, subsection 10, section XX is supplemented with a new paragraph in accordance with Law No. 905-IX of September 17, 2020 }
Residential and/or non-residential real estate located in the territories of settlements on the contact line, owned by individuals or legal entities, are not subject to taxation by real estate tax other than land, in accordance with Article 266 of this Code in the period from April 14, 2014 to February 29, 2020 inclusive.
{Subclause 38.6 of clause 38, subsection 10, section XX is supplemented with a new paragraph in accordance with Law No. 466-IX of 16.01.2020 }
In this regard, taxpayers - legal entities whose taxable objects are located in the territories of settlements on the contact line, starting from March 1, 2020, independently calculate the amount of tax on real estate other than land, and submit by April 20, 2020 to the supervisory authority at the place of registration of the taxable object a declaration in the form established in the manner provided for in Article 46 of this Code, with a breakdown of the annual amount into equal quarterly installments starting from March 1, 2020.
{Subclause 38.6 of clause 38, subsection 10, section XX is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
The amounts of tax on real estate other than land plots, accrued and paid during the period of the anti-terrorist operation, in accordance with Article 266 of this Code for residential and non-residential real estate located in the temporarily occupied territory and/or the territory of the anti-terrorist operation, shall not be refunded to the taxpayer's current account, shall not be used to repay a monetary obligation (tax debt) from other taxes and fees, and shall not be refunded in cash by check if the taxpayer does not have a bank account. The statute of limitations established by Article 102 of this Code shall not apply to the specified amounts of overpaid monetary obligations, except for the amounts of overpaid tax obligations of taxpayers who cease their activities.
{Paragraph of subparagraph 38.6 of paragraph 38 of subsection 10 of section XX as amended by Law No. 466-IX of January 16, 2020 }
38.7. Land payments (land tax and rent for land plots of state and municipal property) for land plots located in the temporarily occupied territory and owned or used, including under lease, by individuals or legal entities shall not be accrued or paid in the period from April 14, 2014 to December 31 of the year in which the anti-terrorist operation and/or the operation of the Joint Forces (JFO) was completed.
Land payments (land tax and rent for land plots of state and municipal ownership) for land plots (except for agricultural land) located in the territories of settlements on the contact line and owned or used, including under lease, by individuals or legal entities shall not be charged or paid in the period from April 14, 2014 to February 29, 2020 inclusive.
{Paragraph two of subparagraph 38.7 of paragraph 38 of subsection 10 of section XX as amended by Law No. 466-IX of January 16, 2020 }
In this regard, taxpayers - legal entities whose taxable objects are located in the territories of settlements on the contact line, starting from March 1, 2020, independently calculate the amount of land tax (land tax and rent for land plots of state and municipal ownership) for land plots (except for agricultural land) and submit by April 20, 2020 to the supervisory authority at the place of registration of the taxable object a declaration in the form established in the manner provided for in Article 46 of this Code, with a breakdown of the annual amount into equal installments by months starting from March 1, 2020.
{Subclause 38.7 of clause 38, subsection 10, section XX is supplemented with a new paragraph in accordance with Law No. 466-IX of January 16, 2020 }
{The provisions of the first sentence of paragraph 38.7 of paragraph 38, subsection 10 of section XX were recognized as not complying with the Constitution of Ukraine (are unconstitutional), in accordance with the Decision of the Constitutional Court No. 3-р(I)/2019 dated 05.06.2019 } The amounts of land payments accrued and paid during the period of the anti-terrorist operation in accordance with Articles 269-289 of this Code for land plots located in the temporarily occupied territory and/or the territory of the anti-terrorist operation are not subject to refund to the taxpayer's current account, are not directed to the repayment of a monetary obligation (tax debt) from other taxes, fees, are not refunded in cash by check if the taxpayer does not have a bank account. The limitation periods established by Article 102 of this Code shall not apply to the above amounts of overpaid monetary obligations , except for the amounts of overpaid tax obligations of taxpayers who terminate their activities.
{Paragraph four of subparagraph 38.7 of paragraph 38 of subsection 10 of section XX as amended by Law No. 466-IX of January 16, 2020 }
{Subclause 38.7 of Clause 38, Subsection 10, Section XX, as amended by Law No. 2628-VIII of 11/23/2018 }
38.8. Land plots located in temporarily occupied territory and owned or used by single tax payers of the fourth group are not subject to single tax in the period from April 14, 2014 to December 31 of the year in which the anti-terrorist operation and/or the operation of the Joint Forces (JFO) was completed.
{Paragraph one of subparagraph 38.8 of paragraph 38, subsection 10 of section XX, as amended by Law No. 2245-VIII of 07.12.2017 }
For single tax payers of the fourth group, whose all land plots are located in the temporarily occupied territory, for the transition to the simplified taxation system or confirmation of the status of a single tax payer of the fourth group in the year following the year in which the anti-terrorist operation and/or the operation of the Joint Forces (JFO) was completed, the calculation of the share of agricultural production is not provided.
{Paragraph two of subparagraph 38.8 of paragraph 38, subsection 10 of section XX, as amended by Law No. 2245-VIII of 07.12.2017 }
{Subclause 38.8 of Clause 38, Subsection 10, Section XX, as amended by Law No. 2628-VIII of 11/23/2018 }
38.9. When accruing (paying) income from their entrepreneurial activities to individuals - entrepreneurs whose location or place of residence is a temporarily occupied territory (regardless of the taxation system), the business entity and/or self-employed person who accrues (pays) such income shall be obliged to withhold income tax at the source of payment. In this case, clause 177.8 of Article 177 and subparagraph 2 of clause 297.1 of Article 297 of this Code shall not apply to such individuals.
Income from entrepreneurial activity, taxed in accordance with this subparagraph, is not included in the total taxable income of an individual entrepreneur and/or the income of an individual entrepreneur who is a single tax payer.
{Subclause 38.9 of clause 38, subsection 10, section XX as amended by Law No. 466-IX of January 16, 2020 }
38.10. For the purpose of value added tax, non-current assets acquired (built, constructed, created) before April 14, 2014 and which as of January 1, 2017 are located in the temporarily occupied territory of the Autonomous Republic of Crimea and the city of Sevastopol, the temporarily occupied territory and/or the territory of settlements on the contact line are not considered:
{Paragraph one of subparagraph 38.10 of clause 38, subsection 10 of section XX as amended by Laws No. 2245-VIII of 07.12.2017 , No. 1617-IX of 01.07.2021 }
those intended for use (or begin/have begun to be used) in transactions that are not the taxpayer's business activity;
non-productive fixed assets, non-productive fixed assets or non-productive intangible assets within the meaning of this Code.
{Paragraph three of subparagraph 38.10 of paragraph 38, subsection 10 of section XX as amended by Law No. 2245-VIII of 07.12.2017 }
For the purpose of value added tax, goods purchased, produced before April 14, 2014, and which as of January 1, 2017 are located in the temporarily occupied territory, are not considered:
{Subclause 38.10 of clause 38, subsection 10, section XX is supplemented by the fourth paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
those that are intended for use (or begin/have begun to be used) in transactions that are not the taxpayer's business activity.
{Subclause 38.10 of clause 38, subsection 10, section XX is supplemented by paragraph five in accordance with Law No. 2245-VIII of 07.12.2017 }
The provisions of subparagraphs "c" and "d" of paragraph 198.5 of Article 198 of this Code shall not apply.
{Subclause 38.10 of clause 38, subsection 10, section XX is supplemented by the sixth paragraph in accordance with Law No. 2245-VIII of 07.12.2017 }
38.11. Temporarily, until the completion of the anti-terrorist operation and/or the operation of the Joint Forces (JFO), special rules for confirming the data specified in the tax reporting shall apply to taxpayers/tax agents who carried out activities in the temporarily occupied territory of the Autonomous Republic of Crimea and the city of Sevastopol, the temporarily occupied territory and/or the territory of settlements on the contact line and cannot present primary documents on the basis of which income, expenses and other indicators related to the determination of objects of taxation and/or tax obligations are recorded, as an exception to the provisions of Article 44 of this Code.
{Paragraph one of subparagraph 38.11 of clause 38, subsection 10 of section XX as amended by Laws No. 2245-VIII of 07.12.2017 , No. 1617-IX of 01.07.2021 }
Reasons for the impossibility of presenting primary documents:
the original documents were lost (destroyed or damaged) in connection with the anti-terrorist operation;
the primary documents are located in the temporarily occupied territory of the Autonomous Republic of Crimea and the city of Sevastopol, the temporarily occupied territory and/or the territory of settlements on the contact line and cannot be removed or their removal is associated with a risk to the life and health of the taxpayer, individuals or is impossible due to other administrative obstacles established by the authorities.
{Paragraph four of subparagraph 38.11 of clause 38, subsection 10 of section XX as amended by Laws No. 2245-VIII of 07.12.2017 , No. 1617-IX of 01.07.2021 }
In the event of loss and/or inability to export primary documents, the taxpayer/tax agent at the place of his registration shall submit to the supervisory authority in any form a notification of the inability to export primary documents, signed by the head of the enterprise and the chief accountant, which shall indicate: the circumstances that led to the loss and/or inability to export primary documents, tax (reporting) periods, as well as a general list of primary documents (if possible, indicating details).
The data and indicators of the taxpayer's/tax agent's tax reporting for the tax (reporting) periods specified in the notification cannot be questioned solely on the basis of the absence of primary documents. The submitted notification is also the basis for preserving expenses (including expenses related to the acquisition of securities/corporate rights) and/or the negative value of the object of taxation by income tax (including the negative financial result on transactions with securities/corporate rights), and/or the tax credit from the value added tax, and/or the amount of the negative value of the value added tax of past tax (reporting) periods without the availability of contractual, settlement, payment and other primary documents, the mandatory maintenance and storage of which is provided for by the rules for accounting and tax assessment.
After submitting a notification to the regulatory authority about the impossibility of exporting primary documents and/or Joint Forces (JFO) operations, a moratorium is imposed on conducting any audits for the tax (reporting) periods specified in the notification.
{Paragraph seven of subparagraph 38.11 of paragraph 38, subsection 10 of section XX, as amended by Law No. 2628-VIII of 11/23/2018 }
If, after submitting a notification about the impossibility of exporting primary documents, the taxpayer/tax agent becomes aware of the loss of these documents, such taxpayer/tax agent is obliged to submit a notification to the supervisory authority about the loss of primary documents, indicating the circumstances of such loss.
Taxpayers/tax agents who have submitted a notification of the loss of primary documents in accordance with this subparagraph may not be inspected by the supervisory authority for the tax (reporting) periods specified in the notification, including after the completion of the anti-terrorist operation.
The loss of documents that is not related to the conduct of an anti-terrorist operation does not entitle the taxpayer/tax agent to apply the provisions of this subparagraph.
The provisions specified in this subparagraph apply to taxpayers/tax agents who, as of April 1, 2017, changed their location (place of residence) from the temporarily occupied territory and/or the territory of settlements on the contact line to another territory of Ukraine and paid taxes to the budget during the period of the anti-terrorist operation in accordance with this Code.
A taxpayer/tax agent may not apply the provisions of this subparagraph to tax (reporting) periods after re-registration of an enterprise in another territory of Ukraine.
The burden of proving the absence of grounds for applying the provisions of this subparagraph shall be on the controlling body. A taxpayer/tax agent who has applied the provisions of this subparagraph without grounds shall be deemed to be evading taxes and shall bear the liability provided for by this Code and other laws of Ukraine.
In the event of a refusal of the supervisory authority to apply the provisions of this subparagraph, the supervisory authority shall be obliged to issue a reasoned decision no later than one month from the date of receipt of the relevant notification from the taxpayer/tax agent, which shall indicate the grounds and evidence for such refusal.
The decision of the supervisory authority may be appealed administratively or in court. Until a final decision is made on the case, the supervisory authority may not question the tax reporting indicators, nor initiate any audit of the taxpayer/tax agent regarding the tax (reporting) periods specified in the relevant notification.
In the tax (reporting) periods specified in the relevant notification, the amount of tax liabilities for taxes and fees declared in tax returns for the specified tax (reporting) periods cannot be revised upwards, the amount of the negative value of the object of taxation by profit tax declared in tax returns/calculations for the specified tax (reporting) periods cannot be revised upwards, the amount of the budget refund for value added tax declared in tax returns for the specified reporting periods cannot be revised upwards.
{Subclause 38.11 of Clause 38, Subsection 10, Section XX, as amended by Law No. 2628-VIII of 11/23/2018 }
38.12. Temporarily, for the period from the beginning of the anti-terrorist operation and/or the implementation of measures to ensure the conduct of the Joint Forces (JFO) operation until July 1, 2020, the transactions on the free transfer of excisable goods, defined in subparagraphs 215.3.5-215.3.5 - 2 of paragraph 215.3 of Article 215 of this Code, which are confiscated property, property recognized as ownerless, property for which the owner has not applied by the end of the storage period (including property defined in Article 184 of the Customs Code of Ukraine), which by the right of inheritance or on other legal grounds passes into the ownership of the state, to the disposal of the Armed Forces of Ukraine and other military formations formed in accordance with the laws of Ukraine, other entities participating in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, carried out through the operation of the Joint Forces (JFO), prosecutor's offices in the Donetsk and Luhansk regions.
The list of goods specified in this paragraph shall be approved by the Cabinet of Ministers of Ukraine.
38.13. Tax notices-decisions on excise tax and value added tax issued during the period from the beginning of the anti-terrorist operation and/or the implementation of measures to ensure the conduct of the Joint Forces (JFO) operation and until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine on Improving Tax Administration, Eliminating Technical and Logical Inconsistencies in Tax Legislation", which determine monetary obligations in connection with the taxation of transactions on the free transfer of excisable goods, defined by subparagraphs 215.3.5-215.3.5 - 2 of paragraph 215.3 of Article 215 of this Code, which are confiscated property, property recognized as ownerless, property for which the owner did not apply by the end of the storage period (including property defined in Article 184 of the Customs Code of Ukraine), which by the right of inheritance or on other legal grounds has passed into the ownership of the state, in Orders of the Armed Forces of Ukraine and other military formations formed in accordance with the laws of Ukraine, other entities participating in the implementation of measures to ensure national security and defense, repel and deter armed aggression of the Russian Federation in the Donetsk and Luhansk regions, carried out through the operation of the Joint Forces (JFO), prosecutor's offices in the Donetsk and Luhansk regions, are considered canceled (withdrawn) from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine on Improving Tax Administration, Eliminating Technical and Logical Inconsistencies in Tax Legislation", and the tax debt (including fines and penalties) under such tax notices-decisions is subject to write-off in the manner prescribed by this Code for bad tax debt.
{Clause 38, subsection 10, section XX, supplemented by subparagraph 38.13 in accordance with Law No. 466-IX of January 16, 2020 }
38.14. For the period of implementation of measures to ensure the conduct of the Joint Forces (JFO) operation, no minimum tax liability is determined for land plots classified as agricultural lands located in the temporarily occupied territory and/or the territory of settlements on the contact line.
{Clause 38, subsection 10, section XX, supplemented by subparagraph 38.14 in accordance with Law No. 1914-IX of 11/30/2021 }
{Subsection 10 of Section XX is supplemented by paragraph 38 in accordance with Law No. 1797-VIII of 21.12.2016 ; as amended by Law No. 1989-VIII of 23.03.2017 - applies to tax periods starting from January 1, 2017}
39. Individual tax advice provided by the supervisory authority in written or electronic form until March 31, 2017 (inclusive) exempts the taxpayer (tax agent and/or his official) from liability, including financial (fines and/or penalties), for acts containing elements of a tax offense committed until December 31, 2017 (inclusive).
From January 1, 2018, individual tax advice provided by the supervisory authority in written or electronic form until March 31, 2017 (inclusive) is not applicable.
{Subsection 10 of Section XX supplemented by paragraph 39 in accordance with Law No. 1797-VIII of 21.12.2016 }
40. Clause 100.9 of this Code shall apply to monetary obligations or tax debt that arose after the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding Improvement of the Investment Climate in Ukraine".
{Subsection 10 of Section XX supplemented by paragraph 40 in accordance with Law No. 1797-VIII of 21.12.2016 }
41. Business transactions defined by subparagraph "d" of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code shall be recognized as controlled from the date of entry into force of the list of organizational and legal forms of non-residents by state (territory), approved by the Cabinet of Ministers of Ukraine in accordance with subparagraph "d" of subparagraph 39.2.1.1 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code.
The conditions specified in subparagraph 39.2.1.7 of subparagraph 39.2.1 of paragraph 39.2 of Article 39 of this Code regarding the volume of business transactions with each counterparty, for the purposes of the first paragraph of this subparagraph, are calculated in 2017 based on the results of the reporting (calendar) year.
{Subsection 10 of Section XX supplemented by paragraph 41 in accordance with Law No. 1797-VIII of 21.12.2016 }
42. Penalties provided for in Clause 120-1.1 of Article 120-1 of this Code for violation of the deadlines for registration of tax invoices and/or calculations of adjustments to tax invoices in the Unified Register of Tax Invoices established by Clause 201.10 of Article 201 of this Code, which were drawn up in the period from June 1, 2017 to June 30, 2017, shall not apply to a taxpayer provided that such tax invoices are registered no later than July 31, 2017.
Tax invoices and/or calculations of adjustments to tax invoices drawn up between June 1, 2017 and June 30, 2017 and registered in the Unified Register of Tax Invoices no later than July 31, 2017, are considered to be registered on time.
{Subsection 10 of Section XX supplemented by paragraph 42 in accordance with Law No. 2143-VIII of 13.07.2017 }
43. Penalties provided for in paragraph 120 - 2.1 of Article 120 - 2 of this Code for violation of the deadlines for registration of excise invoices and/or calculations of adjustments to excise invoices in the Unified Register of Excise Invoices established by Article 231 of this Code, which were drawn up in the period from June 1, 2017 to June 30, 2017, shall not apply to a taxpayer provided that such excise invoices are registered no later than July 31, 2017.
Excise invoices and/or calculations of adjustments to excise invoices drawn up between June 1, 2017 and June 30, 2017 and registered in the Unified Register of Excise Invoices no later than July 31, 2017, are considered to be registered on time.
{Subsection 10 of Section XX supplemented by paragraph 43 in accordance with Law No. 2143-VIII of 13.07.2017 }
44. Penalties provided for in paragraph two of paragraph 126.1 of Article 126 of this Code shall not apply to agreed amounts of monetary obligations with a payment deadline of June 30, 2017.
{Subsection 10 of Section XX supplemented by paragraph 44 in accordance with Law No. 2143-VIII of 13.07.2017 }
45. Temporarily, until December 31, 2017:
in the event of loss and/or damage to information (including information contained in the taxpayer's accounting databases) as a result of unauthorized interference with the taxpayer's computer networks and in the presence of documents confirming the specified events, the taxpayer is obliged to notify the supervisory authority at the place of registration in writing in accordance with the procedure established by this Code for submitting tax reports within 10 calendar days from the date of entry into force of the Law of Ukraine "On Amendments to Subsection 10 of Section XX "Transitional Provisions" of the Tax Code of Ukraine regarding the non-application of penalties for untimely registration of tax and excise invoices as a result of unauthorized interference with the taxpayer's computer networks";
the taxpayer is obliged to restore lost and/or damaged information specified in the second paragraph of this paragraph;
If it is impossible to conduct an audit of a taxpayer in the cases provided for in this paragraph, the deadlines for conducting such audits shall be postponed by the supervisory authority until the date of restoration of such information, but no later than December 31, 2017.
{Subsection 10 of Section XX supplemented by paragraph 45 in accordance with Law No. 2143-VIII of 13.07.2017 }
46. Appointment and conduct of inspections on the completeness of the calculation and payment of taxes in controlled transactions carried out by taxpayers in the 2013 and 2014 reporting years shall be carried out in accordance with subparagraph 39.5.2 of paragraph 39.5 of Article 39 and/or subparagraphs 78.1.14 - 78.1.16 of paragraph 78.1 of Article 78 of this Code.
{Subsection 10 of Section XX supplemented by paragraph 46 in accordance with Law No. 2245-VIII of 07.12.2017 }
47. The taxpayer shall be audited for the completeness of the calculation and payment of taxes during the performance of controlled transactions in 2013 and 2014 in accordance with the provisions of Chapter 8 of this Code, taking into account the features specified in Article 39 of this Code in the version in force until January 1, 2015.
{Subsection 10 of Section XX supplemented by paragraph 47 in accordance with Law No. 2245-VIII of 07.12.2017 }
48. The independent adjustment provided for in subparagraph 39.5.4.1 of subparagraph 39.5.4 of paragraph 39.5 of Article 39 of this Code regarding controlled transactions carried out by taxpayers in 2015 and 2016 shall be carried out in accordance with the provisions of Article 39 of this Code as amended on the day of the independent adjustment.
{Subsection 10 of Section XX supplemented by paragraph 48 in accordance with Law No. 2245-VIII of 07.12.2017 }
49. Customs clearance of a vehicle in compliance with the conditions specified in Clause 9-3 of Section XXI "Final and Transitional Provisions" of the Customs Code of Ukraine exempts persons responsible for compliance with the terms and conditions (requirements) of the customs regimes of temporary importation or transit from liability provided for in Clause 206.16 of Article 206 and Clause 218.3 of Article 218 of this Code for violation of customs rules in relation to a vehicle in respect of which the terms and conditions (requirements) of the customs regimes of temporary importation or transit have not been complied with.
{Subsection 10 of Section XX supplemented by paragraph 49 in accordance with Law No. 2611-VIII of 08.11.2018 }
{Clause 50, subsection 10, section XX was excluded pursuant to Law No. 354-IX of 05.12.2019 }
{Item 51 of Subsection 10 of Section XX was excluded pursuant to Law No. 354-IX of 05.12.2019 }
52. To establish that until December 31, 2019, the requirements of subparagraph 4.1.9 of paragraph 4.1 of Article 4, subparagraphs 12.3.3-12.3.4 of paragraph 12.3, subparagraph 12.4.3 of paragraph 12.4 and paragraph 12.5 of Article 12 of this Code and the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity" shall not apply to decisions on establishing a tourist tax and/or on amending such decisions adopted by a village, settlement, or city council.
{Subsection 10 of Section XX supplemented by paragraph 52 in accordance with Law No. 2628-VIII of 23.11.2018 }
52 - 1. For violations of tax legislation committed during the period from March 1, 2020 to the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine, penalties shall not be applied, except for sanctions for:
{Paragraph one of clause 52 - 1 , subsection 10, section XX, as amended by Law No. 591-IX of 13.05.2020 }
violation of requirements for long-term life insurance contracts or insurance contracts within the framework of non-state pension provision, in particular supplementary pension insurance;
alienation of property subject to tax lien without the consent of the controlling authority;
violation of legal requirements in terms of:
{Paragraph four of clause 52 - 1 , subsection 10, section XX as amended by Law No. 540-IX of 03/30/2020 }
accounting, production, storage and transportation of fuel, ethyl alcohol, alcoholic beverages and tobacco products;
{Paragraph of clause 52 - 1 , subsection 10, section XX as amended by Law No. 540-IX of 03/30/2020 }
targeted use of fuel and ethyl alcohol by taxpayers;
{Paragraph of clause 52 - 1 , subsection 10, section XX as amended by Law No. 540-IX of 03/30/2020 }
equipping excise warehouses with flow meters and/or uniform meters;
{Paragraph of clause 52 - 1 , subsection 10, section XX as amended by Law No. 540-IX of 03/30/2020 }
performing functions defined by legislation in the field of production and circulation of alcohol, alcoholic beverages and tobacco products, and fuel;
{Paragraph of clause 52 - 1 , subsection 10, section XX as amended by Law No. 540-IX of 03/30/2020 }
carrying out transactions by business entities for the sale of fuel or ethyl alcohol without registering such entities as excise tax payers;
{Paragraph of clause 52 - 1 , subsection 10, section XX as amended by Law No. 540-IX of 03/30/2020 }
Violation of the calculation, declaration and payment of value added tax, excise tax, and rent.
During the period from March 1, 2020 to the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine throughout Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine, taxpayers are not charged a penalty, and the penalty accrued but not paid during this period is subject to write-off.
{Paragraph eleven of clause 52 - 1 , subsection 10, section XX, as amended by Law No. 591-IX of 05/13/2020 }
{Subsection 10 of Section XX supplemented by paragraph 52 - 1 in accordance with Law No. 533-IX of March 17, 2020 }
52 - 2 . {The effect of clause 52 - 2 of subsection 10 of section XX is suspended for the period of martial law, a state of emergency - see clause 2 of section II of Law No. 2120-IX of 03/15/2022 } Establish a moratorium on conducting documentary checks for the period from March 18, 2020 to the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine, except for:
{Paragraph one of clause 52 - 2 of subsection 10 of section XX as amended by Law No. 540-IX of 03/30/2020 ; as amended by Laws No. 591-IX of 05/13/2020 , No. 2120-IX of 03/15/2022 }
unscheduled documentary inspections conducted at the request of the taxpayer;
{Item 52 - 2 of Subsection 10 of Section XX supplemented with a new paragraph in accordance with Law No. 786-IX of 14.07.2020 }
unscheduled documentary inspections on the grounds specified in subparagraphs 78.1.7 and 78.1.8 of paragraph 78.1 of Article 78 of this Code.
{Paragraph of clause 52 - 2 of subsection 10 of section XX as amended by Law No. 540-IX of March 30, 2020 ; as amended by Law No. 786-IX of July 14, 2020 }
{Paragraph four of clause 52 - 2 , subsection 10, section XX, excluded on the basis of Law No. 2120-IX of March 15, 2022 }
{Paragraph five of clause 52 - 2 , subsection 10 of section XX was excluded on the basis of Law No. 2120-IX of March 15, 2022 }
{Paragraph six of clause 52 - 2 , subsection 10 of section XX was excluded on the basis of Law No. 2120-IX of March 15, 2022 }
{Paragraph seven of clause 52 - 2 , subsection 10 of section XX was excluded on the basis of Law No. 2120-IX of March 15, 2022 }
{Paragraph eight of clause 52 - 2 , subsection 10 of section XX was excluded on the basis of Law No. 2120-IX of March 15, 2022 }
Information on the postponement of scheduled documentary inspections, which, according to the schedule for scheduled documentary inspections, were to begin in the period from March 18, 2020 to the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine, and on the day of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Supporting Taxpayers for the Period of Implementing Measures Aimed at Preventing the Occurrence and Spread of Coronavirus Disease (COVID-19)" were not started, is included in the updated schedule, which is published on the official website of the central executive body implementing state tax policy, within 10 calendar days from the date of the end of the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine.
{Paragraph of clause 52 - 2 of subsection 10 of section XX as amended by Law No. 591-IX of 05/13/2020 }
Documentary inspections that were initiated before March 18, 2020 and were not completed are temporarily suspended for the period up to and including the last calendar day of the month in which the quarantine established by the Cabinet of Ministers of Ukraine throughout Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine. Such suspension interrupts the inspection period and does not require any additional decisions by the supervisory authority.
{Paragraph of clause 52 - 2 , subsection 10, section XX, as amended by Laws No. 591-IX of 05/13/2020 , No. 2120-IX of 03/15/2022 }
For the period from March 18, 2020 to the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in the territory of Ukraine, the limitation periods provided for in Article 102 of this Code shall be suspended.
{Paragraph of clause 52 - 2 of subsection 10 of section XX as amended by Law No. 591-IX of 05/13/2020 }
A desk audit of a tax return (except for a value-added tax return) for the reporting (tax) periods of March - May 2020, or of clarifying calculations (except for clarifying calculations for value-added tax) submitted by taxpayers during March - May 2020, may be conducted only within 60 calendar days following the last day of the deadline for their submission, and if such documents were submitted later, - after the day of their actual submission.
{Item 52 - 2 of subsection 10 of section XX supplemented by a paragraph in accordance with Law No. 540-IX of 30.03.2020 }
{Subsection 10 of Section XX supplemented by paragraph 52 - 2 in accordance with Law No. 533-IX of March 17, 2020 }
52 - 3. To establish that the annual declaration of property status and income for 2019, specified in Article 179 of this Code, shall be submitted by July 1, 2020, except for cases provided for in Section IV of this Code, when such a declaration may be submitted later than this deadline. In this case, the requirements of subparagraph 49.18.4 of paragraph 49.18 of Article 49 shall not apply in 2020.
An individual is obliged to independently pay the amount of tax liability indicated in the annual declaration of property status and income for 2019 submitted by October 1, 2020. In this case, the first paragraph of paragraph 179.7 of Article 179 does not apply in 2020.
{Subsection 10 of Section XX supplemented by paragraph 52 - 3 in accordance with Law No. 533-IX of March 17, 2020 }
52 - 4. Land payment (land tax and rent for land plots of state and municipal ownership) for land plots owned or used, including under lease, by individuals or legal entities and used by them in economic activities shall not be charged or paid for the period from March 1 to March 31, 2020.
At the same time, payers of land fees (except for individuals) who, in accordance with Clause 286.2 of Article 286 of this Code, have the right to submit a clarifying tax return, in which to reflect changes in the tax liability for paying land fees for the tax period of March 2020.
If in March or April 2020, land fee payers submitted a clarifying tax return to reduce the tax liability for paying land fees for the tax period of April 2020 for reasons not related to the independent detection of errors contained in the previously submitted tax return, such land fee payers are required to submit no later than April 30, 2020, clarifying tax returns for land fees (land tax and/or rent for land plots of state or municipal property) for 2020, which reflect changes in the tax liability for paying land fees for the tax periods of March and April 2020 in accordance with the provisions of this subparagraph.
At the same time, in the case of filing such tax returns on the grounds specified in this subparagraph, such taxpayers shall not be subject to the sanctions specified in Article 50 of this Code and penalties in accordance with the requirements of Clause 120.2 of Article 120 of this Code for making changes to tax reporting in terms of increasing tax liabilities for land payments for the tax period of April 2020.
To establish that payers of land payments (land tax and rent for land plots of state and municipal ownership), who determine tax obligations for land payments based on tax returns, shall pay the tax obligation for payment of land payments for the tax period of April 2020 in full at the location of the land plot by June 30, 2020 without the accrual of fines and penalties provided for by this Code for violation of the deadlines for payment of tax obligations in relation to the general deadlines for payment of tax obligations for such a period.
{Subsection 10 of Section XX supplemented by paragraph 52 - 4 in accordance with Law No. 533-IX of March 17, 2020 ; as amended by Law No. 540-IX of March 30, 2020 }
52 - 5. Non-residential real estate owned by individuals or legal entities is not subject to taxation by real estate tax other than land, in accordance with Article 266 of this Code in the period from March 1 to March 31, 2020.
At the same time, payers of tax on real estate other than land (except for individuals) who, in accordance with subparagraph 266.7.5 of paragraph 266.7 of Article 266 of this Code, have the right to submit a tax return, which reflects changes in the tax liability for payment of tax on real estate other than land for the tax period March 2020.
If in March or April 2020, payers of real estate tax other than land submitted a clarifying tax return to reduce the tax liability for payment of real estate tax other than land for the tax period of April 2020 for reasons not related to the independent detection of errors contained in the tax return previously submitted by them, such payers of real estate tax other than land are required to submit no later than April 30, 2020, clarifying tax returns for real estate tax other than land, in which to reflect the relevant changes in the tax liability for the tax periods of March and April 2020 in accordance with the provisions of this subparagraph.
At the same time, in the case of filing such tax returns on the grounds specified in this subparagraph, such taxpayers shall not be subject to the sanctions specified in Article 50 of this Code and penalties in accordance with the requirements of Clause 120.2 of Article 120 of this Code for making changes to tax reporting in terms of increasing tax liabilities for tax on real estate other than land for the tax period April 2020.
To establish that payers of real estate tax other than land, who determine tax liabilities for such tax based on tax returns, shall pay the tax liability for real estate tax other than land for the tax period of April 2020 in full at the location of the non-residential real estate object until June 30, 2020 without the accrual of fines and penalties provided for by this Code for violation of the deadlines for payment of tax liabilities in relation to the general deadlines for payment of tax liabilities for such period.
{Subsection 10 of Section XX supplemented by paragraph 52 - 5 in accordance with Law No. 533-IX of March 17, 2020 ; as amended by Law No. 540-IX of March 30, 2020 }
52 - 6. Grant local governments in 2020 the right to make a decision to amend the adopted decision on establishing local taxes and/or fees regarding the reduction of the rates of the single tax, and/or land payment, and/or tax on real estate other than land, in relation to non-residential real estate owned by individuals or legal entities.
{Subsection 10 of Section XX supplemented by paragraph 52 - 6 in accordance with Law No. 540-IX of 03/30/2020 ; as amended by Law No. 591-IX of 05/13/2020 }
52 - 7 . To establish that in 2020, draft decisions, decisions of village, settlement, city councils on amendments to the adopted decision on establishing local taxes and/or fees regarding the reduction of the rates of the single tax, and/or land payment, and/or real estate tax other than a land plot, in relation to non-residential real estate owned by individuals or legal entities, adopted in accordance with clause 52 - 6 of subsection 10 of section XX of this Code, shall not be subject to subparagraph 4.1.9 of clause 4.1 and clause 4.5 of Article 4, subparagraph 12.3.4 of clause 12.3, subparagraph 12.4.3 of clause 12.4 (in terms of the term for adoption and entry into force of decisions) and clause 12.5 (in terms of the term for entry into force of decisions) of Article 12 of the Tax Code of Ukraine, the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity", part three of Article 15 of the Law of Ukraine "On Access to Public Information", the Law of Ukraine "On State Aid to Economic Entities".
{Subsection 10 of Section XX supplemented by paragraph 52 - 7 in accordance with Law No. 540-IX of 03/30/2020 ; as amended by Law No. 591-IX of 05/13/2020 }
52 - 8. Temporarily, for the period up to the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine on the entire territory of Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) on the territory of Ukraine, the running of the terms established for:
Article 56 of this Code (in the part of the administrative appeal procedure) regarding complaints of taxpayers (except for complaints regarding the legality of declaring the value added tax and/or the negative value of the value added tax declared for reimbursement from the budget, as well as in other cases provided for by this Code), which were received (will be received) by the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in the territory of Ukraine, and/or which have not been considered as of March 18, 2020. Such suspension does not give rise to any consequences provided for by Article 56 of this Code;
{Paragraph two of clause 52 - 8 of subsection 10 of section XX as amended by Law No. 2719-IX of 03.11.2022 }
Articles 52 and 53 of this Code regarding the provision of individual tax consultations in writing by supervisory authorities;
Articles 73 and 78 of this Code regarding taxpayers' responses to requests from regulatory authorities (except for requests from regulatory authorities regarding the legality of declaring the value added tax claimed for reimbursement from the budget and/or the negative value of the value added tax; on issues of taxation by legal entities or other non-residents conducting business activities through a permanent establishment in the territory of Ukraine, of income received by non-residents with a source of origin in Ukraine; tax control over transfer pricing; tax control over non-residents (representative offices of non-residents); currency control regarding compliance with the established deadlines for settlements for export and import of goods transactions), received (will be received) by taxpayers by the last calendar day of the month (inclusive) in which the quarantine established by the Cabinet of Ministers of Ukraine throughout Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine.
{Paragraph four of clause 52 - 8 of subsection 10 of section XX as amended by Law No. 2719-IX of 03.11.2022 }
From the first calendar day of the month following the month in which the quarantine established by the Cabinet of Ministers of Ukraine throughout the territory of Ukraine ends in order to prevent the spread of coronavirus disease (COVID-19) in Ukraine, the running of the time periods that were suspended in accordance with this paragraph shall continue, taking into account the time that elapsed before such suspension.
{Subsection 10 of Section XX supplemented by paragraph 52 - 8 in accordance with Law No. 540-IX of 03/30/2020 ; as amended by Law No. 591-IX of 05/13/2020 }
52 - 9 . Single tax payers of the first group are temporarily exempted from paying this tax for December 2020 and January - May 2021, except for cases of violation by such payers of the conditions for the application of the first group of single tax payers established by Chapter 1 of Section XIV of this Code. In this case, the single tax rates for the first group of single tax payers established in accordance with the procedure specified in Clause 293.2 of Article 293 of this Code shall not apply for such periods.
{Subsection 10 of Section XX supplemented by paragraph 52 - 9 in accordance with Law No. 1072-IX of 04.12.2020 }
52 - 10. Temporarily, for the period of privatization of alcohol and spirits industry facilities in accordance with the Program for Reform and Development of the Alcohol Industry, the consent of the regulatory authority is not required for the alienation of the property of the State Enterprise of Alcohol and Spirits Industry "Ukrspyrt" in the privatization process, if the purchase and sale agreement of the privatization facility provides for the buyer's obligation to repay the tax debt in accordance with the procedure established by the Law of Ukraine "On State Regulation of the Production and Circulation of Ethyl Alcohol, Spirit Distillates, Alcoholic Beverages, Tobacco Products, Liquids Used in Electronic Cigarettes, and Fuel".
Such property is released from tax lien (with amendments to the relevant state registers) from the date of receipt by the controlling body of confirmation of the fulfillment by the buyer of the privatization object of obligations under the purchase and sale agreement in terms of repayment of the tax debt in accordance with the procedure established by the Law of Ukraine "On State Regulation of the Production and Circulation of Ethyl Alcohol, Alcohol Distillates, Alcoholic Beverages, Tobacco Products, Liquids Used in Electronic Cigarettes, and Fuel".
In the case provided for in the first paragraph of this paragraph, the provisions of paragraphs 92.1-92.3 of Article 92 of this Code shall not apply.
{Subsection 10 of Section XX supplemented by paragraph 52 - 10 in accordance with Law No. 2719-IX of 03.11.2022 }
53. The provisions of paragraph 39.4 of Article 39 of this Code regarding:
requests from regulatory authorities to taxpayers to submit global transfer pricing documentation (master file) - applied for the first time for the financial year ending in 2021;
submission by taxpayers of a notification of participation in an international group of companies - first applied in 2021 for 2020.
Taxpayers who are members of the relevant international group of companies and who carried out controlled transactions in 2022 are required to submit a notification of participation in the international group of companies by October 1, 2023.
The provisions of paragraph three of subparagraph 39.4.10 of clause 39.4 of Article 39 of this Code regarding the submission by taxpayers of reports by country of an international group of companies shall be applied for the first time in relation to the financial year established by the parent company of an international group of companies, which ends in the period from January 1 to December 31, 2022, in compliance with the deadline for submitting a report by country of an international group of companies, determined by subparagraph 39.4.11 of clause 39.4 of Article 39 of this Code.
The provisions of paragraphs four to seven of subparagraph 39.4.10 of paragraph 39.4 of Article 39 of this Code regarding the submission by taxpayers of a report by country of an international group of companies shall be applied for the first time in relation to the financial year starting from January 1 to December 31 of the year in which the CbC Multilateral Agreement entered into force with at least one foreign jurisdiction - a party to the CbC Multilateral Agreement, which is a partner of Ukraine for the automatic exchange of information. The relevant reports, if there are grounds specified in paragraphs four to seven of subparagraph 39.4.10 of paragraph 39.4 of Article 39 of this Code, shall be submitted in compliance with the deadline for submitting a report by country of an international group of companies specified in subparagraph 39.4.11 of paragraph 39.4 of Article 39 of this Code.
{Subsection 10 of Section XX supplemented by paragraph 53 in accordance with Law No. 466-IX of 01/16/2020 ; as amended by Law No. 2970-IX of 03/20/2023 }
53 - 1. Multilateral automatic exchange of financial account information shall be carried out on the basis of the CRS Multilateral Agreement after the competent authority of Ukraine accedes to the CRS Multilateral Agreement and within the time limits specified in Section 3 of the CRS Multilateral Agreement.
53 - 1 .1. The requirements of Article 39 - 3 of this Code in the part relating to the application by financial agents of the CRS Common Reporting Standard for the purposes of fulfilling the requirements of the CRS Multilateral Agreement shall apply from July 1, 2023. For the purposes of the CRS Multilateral Agreement and the CRS Common Reporting Standard, the first reporting period shall be the period beginning on July 1, 2023 and ending on December 31, 2023.
Entities that have all necessary permits to conduct business activities and meet the criteria for a Reporting Financial Institution under the Common Reporting Standard (CRS) as of June 30, 2023, shall apply due diligence procedures to identify Reportable Accounts effective July 1, 2023.
In 2024, the central executive body responsible for the formation and implementation of state financial policy shall set the deadline for submitting a report on accountable accounts for the first reporting period, but no earlier than July 1, 2024.
The central executive body that ensures the formation and implementation of state financial policy has the right to establish a different first reporting period for reporting on accountable accounts in accordance with the CRS Common Reporting Standard, if the CRS Multilateral Agreement determines other reporting periods and deadlines for reporting on accountable accounts than those specified in this Code.
53 - 1 .2. To establish that in the period from July 1, 2023 until the entry into force of the regulatory legal act approved in accordance with subparagraph 39 - 3 .1.4 of paragraph 39 - 3 .1 of Article 39 - 3 of this Code (Procedure for the Application of CRS), the rules for due diligence specified in sections II-VIII of the CRS Common Reporting Standard shall apply on/in relation to the following dates:
1) for the purposes of paragraph C(6) of Section III and paragraph C(9) of Section VIII of the CRS Common Reporting Standard with respect to Preexisting Accounts - June 30, 2023;
2) for the purposes of paragraph D of Section III of the CRS Common Reporting Standard, the review of Preexisting Individual Accounts must be completed:
until December 31, 2023 - for high-value accounts within the meaning of Section VIII of the CRS Common Reporting Standard;
until December 31, 2024 - for low-value accounts within the meaning of Section VIII of the CRS Common Reporting Standard;
3) for the purposes of paragraphs A and B of Section V of the CRS Common Reporting Standard, the dates of June 30, 2023 and December 31, 2023 shall apply;
4) for the purposes of paragraph E(1) of Section V of the CRS Common Reporting Standard, the review of existing entity accounts with an aggregate balance or value exceeding an amount in hryvnia equivalent of USD 250,000 as of June 30, 2023 must be completed by December 31, 2024;
5) for the purposes of paragraph E(2) of Section V of the CRS Common Reporting Standard, the review of existing Entity Accounts with an aggregate balance or value that does not exceed an amount in UAH equivalent to USD 250,000 as of June 30, 2023, but exceeds the equivalent in UAH of USD 250,000 as of December 31, 2023 or any subsequent year must be completed within the calendar year following the year in which the aggregate balance or value of the account exceeds the equivalent in UAH of USD 250,000;
6) for the purposes of paragraph B(8)(b) of Section VIII of the CRS Common Reporting Standard in the definition of the term "qualified credit card issuer", the date July 1, 2023 shall apply;
7) for the purposes of paragraph C(10) of Section VIII of the CRS Common Reporting Standard, the date of July 1, 2023 or a later date shall apply in the definition of the term "new account";
8) for the purposes of paragraph C(14) of Section VIII of the CRS Common Reporting Standard in the definition of the term "low value account", the date of 30 June 2023 shall apply;
9) for the purposes of paragraph C(15) of Section VIII of the CRS Common Reporting Standard in the definition of the term "high value account", the date of 30 June 2023 shall apply;
10) for the purposes of paragraph C(17)(f)(ii) of Section VIII of the CRS Common Reporting Standard, the date of July 1, 2023 shall apply.
53 - 1 .3. To establish the following features of the application of the provisions of Article 39 - 3 of this Code in the part relating to the application of the Common Reporting Standard CRS during the transitional period:
, 2023, meet the criteria for accountable financial institutions, are required to register with the supervisory authority in accordance with Clause 39-3.3 of Article 39-3 of this Code by December 31, 2023;
, 2024 inclusive, the punitive (financial) sanctions provided for in paragraphs 118 - 1.3-118 - 1.8 of Article 118 - 1 of this Code shall not be applied, and for violations committed in the period from January 1 to December 31, 2025, they shall be applied in the amount of 0.5 of the corresponding fine.
53 - 1 .4. Information received by the supervisory authority from foreign competent authorities in accordance with the CRS Multilateral Agreement and relating to a financial account or accounts of a citizen of Ukraine opened in financial institutions of foreign jurisdictions is not considered tax information that can be used by the supervisory authority to determine the amount of a taxpayer's tax liabilities, if the aggregate balance or value of all financial accounts owned by one person - a citizen of Ukraine - does not exceed the equivalent of 250 thousand US dollars as of December 31 of the calendar year falling during the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX .
{Subsection 10 of Section XX is supplemented by paragraph 53 - 1 in accordance with Law No. 1914-IX of 11/30/2021 ; as amended by Law No. 2970-IX of 03/20/2023 }
54. Establish the following features of the application of the provisions on taxation of profits of a controlled foreign company during the transitional period:
the first reporting (tax) year for the report on controlled foreign companies is 2022 (if the reporting year does not correspond to the calendar year - the reporting period starting in 2022). Controlling persons have the right to submit a report on controlled foreign companies for 2022 to the regulatory authority simultaneously with the submission of an annual declaration on property status and income or a corporate income tax return for 2023, including the adjusted profit of the controlled foreign company, subject to taxation in Ukraine, specified in such a report, to the indicators of the relevant declarations for 2023. In this case, penalties and/or fines are not applied;
Subparagraph "b" of subparagraph 39 - 2 .1.2 of paragraph 39 - 2 .1 of Article 39 - 2 of this Code for the 2022-2023 reporting (tax) years shall be applied in the following wording:
"b) owns a share in a foreign legal entity of 25 percent or more, provided that several individuals - residents of Ukraine and/or legal entities - residents of Ukraine own shares in a foreign legal entity, the size of which in aggregate is 50 percent or more, or";
Subclauses 39 - 2 .3.2.1-39 - 2 .3.2.4 of subclause 39 - 2 .3.2 of clause 39 - 2 .3 of Article 39 - 2 of this Code shall apply to reporting periods starting from January 1, 2023;
Penalties and fines for violation of the requirements of Article 39-2 of this Code when determining and calculating the profit of a controlled foreign company are not applied based on the results of the 2022-2023 reporting (tax) years;
The taxpayer and its officials shall not be subject to administrative and criminal liability for any violations related to the application of the provisions of Article 39-2 of this Code based on the results of the 2022-2023 reporting (tax) years . In this regard , the information and/or documents received by the supervisory authority in accordance with Article 39-2 of this Code based on the results of the 2022-2023 reporting (tax) years:
a) is information with limited access that cannot be requested and/or transferred to law enforcement agencies at their request or within the framework of procedures provided for by the Criminal Procedure Code of Ukraine ;
b) cannot be considered evidence in criminal proceedings within the meaning of Article 84 of the Criminal Procedure Code of Ukraine";
{Subsection 10 of Section XX supplemented by paragraph 54 in accordance with Law No. 466-IX of January 16, 2020 ; as amended by Law No. 1117-IX of December 17, 2020 }
55. Compensation for damage to a person whose rights have been violated, caused by tax offenses of regulatory authorities committed by regulatory authorities before January 1, 2021, or by tax offenses of regulatory authorities in the form of unlawful decisions of regulatory authorities adopted based on the results of tax audits initiated before January 1, 2021, shall be carried out in accordance with the rules of this Code that were in effect before January 1, 2021.
{Subsection 10 of Section XX supplemented by paragraph 55 in accordance with Law No. 466-IX of January 16, 2020 }
56. Conducting inspections that were initiated before January 1, 2021, considering taxpayers' objections to the acts (certificates) of such inspections, adopting tax notices-decisions based on their results, as well as appealing them, shall be carried out in accordance with the rules of this Code that were in effect before January 1, 2021.
{Subsection 10 of Section XX supplemented by paragraph 56 in accordance with Law No. 466-IX of January 16, 2020 }
57. To establish that special tax service ranks established by this Code are assigned to officials of controlling bodies who were previously assigned special tax and customs service ranks, in the following ratio, regardless of the positions held:
Special ranks of revenue and duties authorities
Special ranks of state tax service bodies
Chief State Advisor for Tax and Customs Affairs
Chief State Tax Service Advisor;
State Advisor for Tax and Customs Affairs, 1st Rank
State Tax Service Advisor, 1st rank;
State Advisor for Tax and Customs Affairs, 2nd Rank
State Tax Service Advisor, 2nd rank;
State Advisor for Tax and Customs Affairs, III Rank
State Tax Service Advisor, III rank;
Tax and Customs Advisor, 1st Rank
Tax Service Advisor, 1st rank;
Tax and Customs Advisor, 2nd Rank
Tax Service Advisor, 2nd rank;
Tax and Customs Advisor, III Rank
Tax Service Advisor, III rank;
Tax and Customs Inspector, 1st Rank
Tax inspector of the 1st rank;
Tax and Customs Inspector, 2nd Rank
Tax inspector of the 2nd rank;
Tax and Customs Inspector, 3rd Rank
Tax inspector of the III rank;
Tax and Customs Inspector, IV Rank
tax inspector of the IV rank;
junior tax and customs inspector
junior tax inspector.
The period of work (service) of the specified persons (including those who were awarded special and/or personal ranks) in the regulatory bodies is counted towards the length of service in the civil service and length of service in positions classified as civil servant positions, which gives the right to a pension in accordance with the Law of Ukraine "On Civil Service" regardless of the place of work upon reaching the age stipulated by the specified Law.
{Subsection 10 of Section XX supplemented by paragraph 57 in accordance with Law No. 466-IX of January 16, 2020 }
58. To establish that in 2020, the requirements of subparagraph 4.1.9 of paragraph 4.1 and paragraph 4.5 of Article 4, subparagraph 12.3.4 of paragraph 12.3, subparagraph 12.4.3 of paragraph 12.4 and paragraph 12.5 of Article 12 of this Code and the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity" shall not apply to decisions taken by local governments and settlements on the contact line on the establishment of local taxes and fees adopted in implementation of this Code .
{Subsection 10 of Section XX supplemented by paragraph 58 in accordance with Law No. 466-IX of January 16, 2020 }
59. If the local governments of the settlements on the contact line have not made decisions on setting rates for residential and/or non-residential real estate for 2020, such tax, until such a decision is made, shall be paid based on the norms of this Code, applying their rate of 0.5 percent of the minimum wage established by law as of January 1, 2020, per 1 square meter of tax base.
{Subsection 10 of Section XX supplemented by paragraph 59 in accordance with Law No. 466-IX of January 16, 2020 }
60. Non-residents (foreign companies, organizations) that carry out economic activities in the territory of Ukraine and/or that, prior to the entry into force of this Law, have duly accredited (registered, legalized) separate divisions, including permanent representative offices, in the territory of Ukraine, and as of January 1, 2021 are not registered with regulatory authorities, are obliged to submit documents to regulatory authorities for their registration within three months in accordance with the procedure established by Clause 64.5 of Article 64 of this Code.
{Paragraph one of clause 60, subsection 10, section XX, as amended by Law No. 1117-IX of 17.12.2020 }
Inspections of non-residents (foreign companies, organizations) carrying out economic activities in the territory of Ukraine and which should have been registered in accordance with the procedure established by paragraph 64.5 of Article 64 of this Code, and which have not met the requirements of the first paragraph of this paragraph, and of their separate divisions, including permanent representative offices, that are registered, may be scheduled from July 1, 2021.
{Paragraph two of clause 60, subsection 10, section XX, as amended by Law No. 1117-IX of 17.12.2020 }
Based on the results of the inspection conducted in accordance with paragraph two of this paragraph, the supervisory authority:
registers a non-resident on the basis of an inspection report, if the results of the inspection confirm that the non-resident is conducting business activities through a permanent establishment in Ukraine;
takes measures to deregister a separate subdivision, including a permanent representative office, of a non-resident, if the results of the inspection confirm the cessation of the non-resident's activities in the territory of Ukraine, the absence of objects of taxation and objects related to taxation in the territory of Ukraine for such a non-resident, and the separate subdivision or permanent representative office of the non-resident has fulfilled the obligations of a taxpayer specified in Article 16 of this Code.
Permanent representative offices of non-residents that were registered as taxpayers (including corporate income tax) in the periods before January 1, 2021, remain payers of such taxes in accordance with the requirements of this Code for registration as taxpayers (including corporate income tax) of the relevant non-residents.
{Item 60, subsection 10, section XX, supplemented by paragraph six in accordance with Law No. 1117-IX of 17.12.2020 }
{Subsection 10 of Section XX supplemented by paragraph 60 in accordance with Law No. 466-IX of January 16, 2020 }
60 - 1. The norms specified in paragraph twenty-five of subparagraph 14.1.193 of paragraph 14.1 of Article 14, paragraph 120.7 of Article 120, paragraph three of subparagraph 133.1.1 of paragraph 133.1 of Article 133, paragraph twelfth of subparagraph 134.1.1 of paragraph 134.1 of Article 134, paragraph 136.7 of Article 136 of this Code shall apply to tax (reporting) periods starting from January 1, 2022.
The provisions of Clause 67.5 of Article 67, Subclause 78.1.22 of Clause 78.1 of Article 78, Clause 86.13 of Article 86, Subclause 94.2.9 of Clause 94.2 of Article 94, Clause 117.4 of Article 117 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
{Subsection 10 of Section XX is supplemented by paragraph 60 - 1 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 2. The norms of subparagraph 14.1.54 of paragraph 14.1 of Article 14 of this Code apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of subparagraph 14.1.54 of paragraph 14.1 of Article 14 of this Code shall apply in the following wording:
"14.1.54. income with a source of origin from Ukraine - any income received by residents or non-residents, including from any types of their activities on the territory of Ukraine (including payment (accrual) of remuneration by foreign employers), its continental shelf, in the exclusive (maritime) economic zone, including, but not exclusively, income in the form of:
a) interest, dividends, royalties and any other passive (investment) income paid by residents of Ukraine;
b) income from the provision of property located in Ukraine, including rolling stock of transport assigned to ports located in Ukraine, to residents or non-residents for rent (use);
c) income from the sale of movable and immovable property, income from the alienation of corporate rights, securities, including shares of Ukrainian issuers;
d) income received in the form of contributions and premiums for insurance and reinsurance of risks in the territory of Ukraine;
e) income of resident insurers from insurance of risks of resident policyholders outside Ukraine;
e) other income from activities, including those related to the full or partial assignment of rights and obligations under agreements on the distribution of products in the customs territory of Ukraine or in territories under the control of regulatory authorities (in customs control zones, in specialized licensed customs warehouses, etc.);
e) inheritances, gifts, winnings, prizes;
g) wages, other payments and remunerations paid in accordance with the terms of the employment and civil law contract;
g) income from entrepreneurial and independent professional activities."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 2 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 3. The provisions of subparagraph 14.1.193 (except for paragraph twenty-fifth ) of paragraph 14.1 of Article 14 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of subparagraph 14.1.193 of paragraph 14.1 of Article 14 of this Code shall apply in the following wording:
"14.1.193. permanent establishment - a permanent place of business through which the economic activity of a non-resident in Ukraine is fully or partially carried out, in particular: a place of management; a branch; an office; a factory; a workshop; a facility or structure for the exploration of natural resources; a mine, an oil/gas well, a quarry or any other place of extraction of natural resources; a warehouse or premises used for the delivery of goods, a server.
For tax purposes, the term "permanent establishment" includes a construction site, a construction, assembly or installation facility or related supervisory activities, if the duration of work related to such site, facility or activity exceeds six months; the provision of services by a non-resident (other than personnel services), including consulting, through employees or other personnel hired by him for such purposes, but if such activities are carried out (within the framework of one project or a project related to it) in Ukraine for a period or periods, the total duration of which exceeds six months in any twelve-month period; residents who have the authority: to act exclusively on behalf of such non-resident (negotiating essential terms and/or concluding agreements (contracts) on behalf of such non-resident), which results in the emergence of civil rights and obligations for such non-resident; and/or maintain (store) stocks of goods belonging to a non-resident, from which goods are delivered on behalf of the non-resident, except for residents who have the status of a temporary storage warehouse or a customs licensed warehouse.
A permanent establishment does not include the use of buildings or structures solely for the purpose of storing, displaying or delivering goods or products belonging to a non-resident; the storage of stocks of goods or products belonging to a non-resident solely for the purpose of storage or display; the storage of stocks of goods or products belonging to a non-resident solely for the purpose of processing by another enterprise; the maintenance of a fixed place of business solely for the purpose of purchasing goods or products or for collecting information for a non-resident; the placing at the disposal of individuals within the framework of the performance of agreements on personnel services; the maintenance of a fixed place of business solely for the purpose of carrying out for a non-resident any other activity of a preparatory or auxiliary nature."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 3 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 4. The norms of the first paragraph of subparagraph 47.1.1 of paragraph 47.1 of Article 47 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020 inclusive, the provisions of the first paragraph of subparagraph 47.1.1 of paragraph 47.1 of Article 47 of this Code shall apply in the following wording:
"47.1.1. legal entities, permanent representations of non-residents, which are determined as taxpayers in accordance with this Code, as well as their officials."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 4 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 5. The provisions of paragraph 64.5 of Article 64 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of Clause 64.5 of Article 64 of this Code shall apply in the following wording:
"64.5. The basis for registering (amending, re-registering) a separate division of a foreign company, organization, including a permanent representative office of a non-resident, is the proper accreditation (registration, legalization) of such division on the territory of Ukraine in accordance with the law.
For registration, permanent representative offices of non-residents and separate divisions of foreign legal entities are obliged to apply within 10 calendar days from the date of their state registration (accreditation, legalization) in accordance with the established procedure or before the start of economic activity, if such registration is not mandatory according to the legislation, to the regulatory authorities at their location. Registration of such taxpayers is carried out in accordance with clause 64.2 of this article.
If the controlling authority establishes, based on the results of tax control, that a non-resident is conducting economic activities through a permanent establishment on the territory of Ukraine without being registered for tax purposes, an act is drawn up and sent through the competent authority of Ukraine to the competent authority of a foreign state to organize collection measures.
The form of the specified act is approved by the central executive body that ensures the formation and implementation of state financial policy.
In the event that a foreign company or organization acquires property rights to real estate or land in Ukraine that are subject to taxation, if the method and purposes of obtaining this property do not require the establishment by such company (organization) of a separate subdivision or permanent representative office of a non-resident in Ukraine, such non-resident shall be registered with the regulatory authority at the location of the relevant facility after submitting the following documents:
applications in the form approved by the central executive body that ensures the formation and implementation of state financial policy;
copies of an extract from the trade, banking or court register issued in the country of registration of a foreign company or organization and legalized in accordance with the established procedure, unless otherwise provided for by international treaties, the binding nature of which has been approved by the Verkhovna Rada of Ukraine, accompanied by a notarized translation into Ukrainian;
a notarized copy of title documents confirming the right of ownership of real estate or the right of ownership or use of a land plot, issued and registered in the name of a non-resident by authorized bodies of Ukraine;
data on the taxpayer's representative".
{Subsection 10 of Section XX is supplemented by paragraph 60 - 5 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 6. The provisions of subparagraph 133.2.2 of paragraph 133.2 of Article 133 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of subparagraph 133.2.2 of paragraph 133.2 of Article 133 of this Code shall apply in the following wording:
"133.2.2. permanent representative offices of non-residents who receive income with a source of origin from Ukraine or perform agency (representative) and other functions in relation to such non-residents or their founders."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 6 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 7. The norms of subparagraph "e" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of subparagraph "e" of subparagraph 141.4.1 of paragraph 141.4 of Article 141 of this Code shall apply in the following wording:
"e) profit from the sale or other disposal of securities, derivatives or other corporate rights, determined in accordance with this section."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 7 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 8. The provisions of subparagraph 141.4.2 of paragraph 141.4 of Article 141 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of subparagraph 141.4.2 of paragraph 141.4 of Article 141 of this Code shall apply in the following wording:
"141.4.2. A resident, including an individual entrepreneur, an individual engaged in independent professional activity, or a business entity (legal entity or individual entrepreneur) who has chosen a simplified taxation system, or a permanent representative office of a non-resident, who makes any payment to a non-resident or a person authorized by him (except for a permanent representative office of a non-resident in the territory of Ukraine) from income with a source of origin in Ukraine received by such non-resident from conducting business activities (including to accounts of a non-resident maintained in the national currency), shall withhold tax on such income specified in subparagraph 141.4.1 of this paragraph at a rate of 15 percent (except for income specified in subparagraphs 141.4.4-141.4.6 and 141.4.11 of this paragraph) their amounts and at their expense, which is paid to the budget at the time of such payment, unless otherwise provided for by the provisions of international treaties of Ukraine with the countries of residence of the persons in whose favor the payments are made, which have entered into force."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 8 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 9. The norms of the first paragraph of subparagraph 141.4.4 of paragraph 141.4 of Article 141 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020 inclusive, the provisions of the first subparagraph of paragraph 141.4.4 of paragraph 141.4 of Article 141 of this Code shall apply in the following wording:
"141.4.4. The amount of freight paid to a non-resident by a resident, including an individual entrepreneur, an individual engaged in independent professional activity, or a business entity (legal entity or individual entrepreneur) who has chosen a simplified taxation system under freight contracts, is taxed at a rate of 6 percent at the source of payment of such income at the expense of such income. In this case."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 9 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 10. The norms of the first paragraph of subparagraph 141.4.5 of paragraph 141.4 of Article 141 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of paragraph one of subparagraph 141.4.5 of clause 141.4 of Article 141 of this Code shall apply in the following wording:
"141.4.5. Insurers or other residents, including individual entrepreneurs, individuals engaged in independent professional activities, or business entities (legal entities or individual entrepreneurs) who have chosen a simplified taxation system, who make insurance payments (insurance contributions, insurance premiums) and insurance payments (insurance indemnities) within the framework of insurance or reinsurance contracts of risks, including life insurance for the benefit of non-residents, are obliged to tax the amounts transferred in the following manner."
{Subsection 10 of Section XX is supplemented by paragraph 60 - 10 in accordance with Law No. 1117-IX of 17.12.2020 }
60 - 11. The norms of subparagraph 141.4.7 of paragraph 141.4 of Article 141 of this Code shall apply to tax (reporting) periods starting from January 1, 2021.
Until December 31, 2020, inclusive, the provisions of subparagraph 141.4.7 of paragraph 141.4 of Article 141 of this Code shall apply in the following wording:
"141.4.7. The amounts of income of non-residents who conduct their activities in the territory of Ukraine through a permanent establishment are taxed in the general manner. In this case, such a permanent establishment is equated for taxation purposes to a taxpayer who conducts his activities independently of such a non-resident.
If a non-resident carries out its activities in Ukraine and abroad and does not determine the profit from its activities conducted through a permanent establishment in Ukraine, the amount of profit subject to taxation in Ukraine is determined on the basis of the preparation by the non-resident of a separate balance sheet of financial and economic activities, agreed with the supervisory authority at the location of the permanent establishment, taking into account the requirements specified in Article 39 of this Code.
If it is impossible to determine by direct calculation the profit received by non-residents with its source of origin in Ukraine, the taxable profit is determined by the supervisory authority as the difference between income and expenses determined by applying a coefficient of 0.7 to the amount of income received, taking into account the requirements specified in Article 39 of this Code.
{Subsection 10 of Section XX is supplemented by paragraph 60 - 11 in accordance with Law No. 1117-IX of 17.12.2020 }
61. Until January 1, 2021, registrars of settlement transactions and/or software registrars of settlement transactions shall not be used by single tax payers of the second - fourth groups (individual entrepreneurs), regardless of the chosen type of activity, whose income during the calendar year does not exceed 1,000,000 hryvnias, except for those who carry out:
sale of technically complex household goods subject to warranty repair;
sale of medicines and medical products.
From January 1, 2021 to January 1, 2022, settlement transaction registrars and/or software settlement transaction registrars are not used by single tax payers of the second - fourth groups (individual entrepreneurs) whose income during the calendar year does not exceed the amount of income that does not exceed 220 times the minimum wage established by law as of January 1 of the tax (reporting) year, regardless of the chosen type of activity, except for those who engage in:
{Paragraph four of clause 61, subsection 10, section XX, as amended by Law No. 1017-IX of 01.12.2020 }
{Paragraph five of clause 61, subsection 10, section XX was excluded on the basis of Law No. 1017-IX of 01.12.2020 }
sale of technically complex household goods subject to warranty repair;
sale of medicines, medical products and provision of paid services in the field of healthcare;
sale of jewelry and household items made of precious metals, precious stones, organic gemstones and semi-precious stones.
{Paragraph nine of clause 61, subsection 10, section XX was excluded on the basis of Law No. 1017-IX of 01.12.2020 }
{Paragraph ten of clause 61, subsection 10, section XX was excluded on the basis of Law No. 1017-IX of 01.12.2020 }
{Paragraph eleven of clause 61, subsection 10, section XX was excluded on the basis of Law No. 1017-IX of 01.12.2020 }
{Paragraph twelfth of clause 61, subsection 10, section XX was excluded on the basis of Law No. 1017-IX of 01.12.2020 }
{Paragraph thirteen of clause 61, subsection 10, section XX was excluded on the basis of Law No. 1017-IX of 01.12.2020 }
In the event of an excess of income by a single tax payer of the second - fourth groups (an individual entrepreneur) in a calendar year, not exceeding 220 minimum wages established by law as of January 1 of the tax (reporting) year, the use of a settlement operations registrar and/or a software settlement operations registrar for such a single tax payer is mandatory. The use of a settlement operations registrar and/or a software settlement operations registrar begins on the first day of the first month of the quarter following the occurrence of such excess, and continues in all subsequent tax periods during the registration of the business entity as a single tax payer.
{Paragraph fourteen of clause 61, subsection 10, section XX, as amended by Law No. 1017-IX of 01.12.2020 }
{Subsection 10 of Section XX supplemented by paragraph 61 in accordance with Law No. 129-IX of 20.09.2019 }
62. Temporarily, until December 31, 2020, funds received on the current account of the public joint-stock company "Ukrnafta", opened by the relevant body providing treasury services for budget funds, in the process of conducting mutual settlements provided for in paragraph 31 of Article 14 of the Law of Ukraine "On the State Budget of Ukraine for 2020", and subject to transfer to the special fund of the state budget in accordance with paragraphs 11-13 of Article 11 of the Law of Ukraine "On the State Budget of Ukraine for 2020", shall be used exclusively to repay the tax debt of the public joint-stock company "Ukrnafta", including restructured or deferred (deferred) (taking into account fines (financial) sanctions, penalties and interest accrued and/or to be accrued on the amount of this debt), as well as fines (financial) sanctions determined by the supervisory body and penalties accrued in connection with the untimely payment of taxes that are in the process of judicial or pre-trial (administrative) appeal, in accordance with the procedure approved by the Cabinet of Ministers of Ukraine.
{Subsection 10 of Section XX supplemented by paragraph 62 in accordance with Law No. 1005-IX of 11/17/2020 }
62. To establish that for the purposes of applying subparagraph 35 - 1.8 of Article 35 - 1 of this Code , the amounts of monetary obligations and penalties paid erroneously and/or excessively by the taxpayer, which arose, according to the data of the supervisory authority, starting from January 1, 2021, shall be taken into account.
{Subsection 10 of Section XX was supplemented by paragraph 62 in accordance with Law No. 190-IX of 04.10.2019, taking into account the amendments made by Law No. 465-IX of 16.01.2020 }
63. The central executive body implementing the state customs policy, the central executive body implementing the state tax policy, and the central executive body ensuring the formation and implementation of the state investment policy shall automatically exchange information contained/to be contained in the register of investment projects with significant investments, including information on the exemption from value added tax granted in accordance with paragraph 76 of subsection 2 of this section, in the amount and manner determined by the central executive body ensuring the formation and implementation of the state financial policy, in agreement with the central executive body ensuring the formation and implementation of the state investment policy.
{Subsection 10 of Section XX supplemented by paragraph 63 in accordance with Law No. 1293-IX of 02.03.2021 }
64. Establish that the first year for which the minimum tax liability is determined is 2022.
For the purposes of applying paragraph six of clause 38-1.2 of Article 38-1 of this Code , information on the location of land plots relative to the borders of settlements is determined in accordance with data on the borders of administrative-territorial units entered in the State Land Cadastre.
{Paragraph 64 of Subsection 10 of Section XX supplemented by the second paragraph in accordance with Law No. 4015-IX of 10.10.2024 }
In the absence of such data in the State Land Cadastre, land plots within settlements include land plots located on the territory of villages, towns, cities, according to the data of index cadastral maps (plans) of the State Land Cadastre.
{Paragraph 64 of Subsection 10 of Section XX supplemented by paragraph three in accordance with Law No. 4015-IX of 10.10.2024 }
{Subsection 10 of Section XX supplemented by paragraph 64 in accordance with Law No. 1914-IX of 11/30/2021 }
65. To establish that the penalties provided for in Article 123 of this Code when determining the tax liabilities of taxpayers taking into account the minimum tax liability for 2022, as well as the penalties provided for in Article 124 of this Code for untimely payment of the agreed tax liability on personal income tax calculated by the supervisory authority taking into account the total minimum tax liability for 2022, shall not apply.
{Subsection 10 of Section XX supplemented by paragraph 65 in accordance with Law No. 1914-IX of 11/30/2021 }
66. To establish that when calculating the difference between the amount of the total minimum tax liability and the total amount of taxes, fees, payments and expenses paid for the lease of land plots for 2022, the total amount of taxes, fees, payments and expenses paid for the lease of land plots, determined by subparagraphs 141.9.2 , 141.9.3 of paragraph 141.9 of Article 141, paragraph 177.15 of Article 177, paragraphs 297 - 1 .2, 297 - 1 .3, 297 - 1 .4, 297 - 1 .5 of Article 297 - 1 of this Code, shall include the amounts of taxes, fees, payments paid in 2021 on account of tax liabilities from these taxes, fees, payments for 2022.
{Subsection 10 of Section XX supplemented by paragraph 66 in accordance with Law No. 1914-IX of 11/30/2021 }
67. Temporarily, for the calculation of the minimum tax liability for the 2022 and 2023 tax (reporting) years, the coefficient "K" defined in subparagraphs 38 - 1 .1.1 and 38 - 1 .1.2 of Article 38 - 1 of this Code is applied with a value of 0.04.
{Subsection 10 of Section XX supplemented by paragraph 67 in accordance with Law No. 1914-IX of 11/30/2021 }
67 - 1. To establish that when determining the minimum tax liability for 2025 and subsequent years, ending with the year in which martial law is terminated or abolished, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the coefficient "K" defined in subparagraphs 38 - 1 .1.1 and 38 - 1 .1.2 of Article 38 - 1 of this Code shall be applied with a value of 0.057.
{Subsection 10 of Section XX is supplemented by paragraph 67 - 1 in accordance with Law No. 4015-IX of 10.10.2024 }
68. To establish that temporarily, until January 1, 2037, for taxpayers who simultaneously meet the following criteria:
formed in accordance with the procedure established by law after January 1, 2022;
whose tax address and place of business are exclusively the following settlements:
Novovolynsk, Volyn region,
Vugledar city, Donetsk region,
Toretsk city, Donetsk region,
Myrnograd city, Donetsk region,
Lysychansk, Luhansk region,
Pryvillia, Luhansk region,
Chervonograd city, Lviv region,
Ukrainy, Donetsk region,
Toshkivka village, Severodonetsk district, Luhansk region,
Selydove, Donetsk region,
Rodynske, Donetsk region,
Pryvillia, Luhansk region,
Novodruzhesk, Luhansk region,
village of Mezhyrichia, Chervonohrad district, Lviv region,
village of Silets, Chervonohrad district, Lviv region,
village of Hlukhiv, Chervonohrad district, Lviv region,
the city of Girnyk, Donetsk region,
Zolote, Luhansk region,
the city of Girske, Luhansk region,
Novogrodivka, Donetsk region,
Pokrovsk city, Donetsk region;
whose main activity is activity in the processing industry (group 10, class 11.06, 11.07 group 11, group 13-18, group 20-27, class 29.3 group 29, class 30.1-30.4, 30.92, 30.99 group 30, group 31-33 of section C of the KVED DK 009-2010 );
do not have separate divisions, subsidiaries, representative offices and branches;
the share of income received by a business entity from the sale of its own products and products of its processing in the total amount of its income during the reporting period is more than 90 percent;
the amount of annual income (net of indirect taxes), determined according to accounting rules for the last annual reporting period, does not exceed 40 million hryvnias;
the average number of employees during the reporting period is at least 10 people;
production facilities are located exclusively on the territory of the settlements specified in this clause, taxes and fees are collected taking into account the features specified in this clause.
This clause does not apply to business entities formed after January 1, 2022 through reorganization (division, separation), whose tax address is in settlements other than those specified in this clause, or who carry out their activities in the production of goods in other settlements.
If taxpayers applying the provisions of this paragraph have achieved indicators in any reporting period, at least one of which does not meet the criteria specified in this paragraph, then such taxpayers are obliged, starting from the first day of the first month of the tax (reporting) period in which such non-compliance occurred, to calculate and pay taxes in the general manner.
68.1. Temporarily, until January 1, 2037, the profits of enterprises - business entities determined in accordance with the norms of this paragraph are exempt from taxation.
At the same time, if a taxpayer in any tax (reporting) period does not meet at least one criterion specified in this paragraph, then such taxpayer is obliged, starting from the first day of the first month of the tax (reporting) period in which such non-compliance occurred, to calculate and pay corporate income tax in the general manner at the rate established by paragraph 136.1 of Article 136 of this Code.
68.2. Temporarily, until January 1, 2037, the following transactions are exempt from VAT:
from the import into the customs territory of Ukraine under the customs regime of import of equipment and components imported by business entities that meet the criteria specified in this paragraph, exclusively for use in their own production activities and are classified according to the following commodity subcategories in accordance with the UKT FEA :
{Paragraph three of subparagraph 68.2 of paragraph 68, subsection 10 of section XX as amended by Law No. 3553-IX of 16.01.2024 }
The procedure for importing such goods into the customs territory is determined by the Cabinet of Ministers of Ukraine;
for the supply of goods of their own production in the customs territory of Ukraine by economic entities that meet the criteria specified in this paragraph.
The provisions of this subparagraph do not apply to goods originating from a country recognized as an occupying state in accordance with the law and/or an aggressor state in relation to Ukraine in accordance with the law, or imported from the territory of an occupying state (aggressor) and/or from the occupied territory of Ukraine, designated as such in accordance with the law.
In the event of misuse of equipment and components imported into the customs territory of Ukraine in accordance with the procedure specified in this subparagraph, the taxpayer is obliged to increase tax liabilities as a result of the tax period to which such violation applies by the amount of value added tax that should have been paid/accrued on the date of occurrence of such tax liabilities, and also to pay a penalty in accordance with the law.
68.3. Temporarily, until January 1, 2037, business entities determined in accordance with the provisions of this paragraph are exempt from taxation of rent for special water use.
At the same time, if the payer of the rent for the special use of water in any tax (reporting) period does not meet at least one criterion specified in this paragraph, then such payer of the rent for the special use of water shall be obliged, starting from the first day of the first month of the tax (reporting) period in which such non-compliance occurred, to calculate and pay the rent for the special use of water in the general manner at the rates established in accordance with Article 255 of this Code.
68.4. Temporarily, until January 1, 2037, business entities determined in accordance with the provisions of this paragraph are exempt from taxation of rent for the special use of forest resources.
At the same time, if the payer of the rent for the special use of forest resources in any tax (reporting) period does not meet at least one of the criteria specified in this paragraph, then such payer of the rent for the special use of forest resources is obliged, starting from the first day of the first month of the tax (reporting) period in which such non-compliance occurred, to calculate and pay the rent for the special use of forest resources in the general procedure at the rates established in accordance with Article 256 of this Code.
68.5. Temporarily, until January 1, 2037, economic entities determined in accordance with the norms of this paragraph are exempt from taxation of land payment (land tax and rent for land plots of state and municipal property) for land plots owned and/or used by such entities, which are used by such payers of land payment for conducting economic activities.
At the same time, if the payer of the land fee in any tax (reporting) period does not meet at least one criterion specified in this paragraph, then such payer of the land fee is obliged, starting from the first day of the first month of the tax (reporting) period in which such non-compliance occurred, to calculate and pay the land fee in the general procedure at the rates established in accordance with Articles 274 , 277 and 288 of this Code.
If land plots owned and/or used by business entities determined in accordance with the norms of this clause, and/or individual buildings, structures or parts thereof located on these land plots are leased (rented, loaned) to other individuals and legal entities, the land fee for such land plots and land plots under such buildings (their parts) is paid on a general basis.
{Subsection 10 of Section XX supplemented by paragraph 68 in accordance with Law No. 1914-IX of 11/30/2021 }
69. To establish that temporarily, for the period until the termination or cancellation of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the collection of taxes and fees shall be carried out taking into account the features specified in this paragraph.
{Paragraph one of clause 69, subsection 10, section XX as amended by Law No. 2260-IX of 05/12/2022 }
69.1. In the event that a taxpayer is unable to timely fulfill his tax obligation to comply with the deadlines for paying taxes and fees, submitting reports and/or documents (notifications), including those provided for in Articles 39 and 39-2 , paragraph 46.2 of Article 46 of this Code, registering tax or excise invoices in the relevant registers, calculating adjustments, submitting electronic documents containing data on actual fuel balances and the volume of fuel or ethyl alcohol turnover, etc., taxpayers are exempted from the liability provided for by this Code with mandatory fulfillment of such obligations within six months after the termination or abolition of martial law in Ukraine.
{Paragraph one of subparagraph 69.1 of clause 69, subsection 10 of section XX as amended by Law No. 3603-IX of February 23, 2024 - shall apply from September 3, 2023 }
If a taxpayer is unable, with respect to its branch or excise warehouse, representative office, separate or other structural unit, to timely fulfill its tax obligation to comply with the deadlines for paying taxes and fees, submitting reports and/or documents (notifications), including those provided for in Articles 39 and 39-2 , Clause 46.2 of Article 46 of this Code, registering tax or excise invoices in the relevant registers, calculating adjustments, submitting electronic documents containing data on actual fuel balances and the volume of fuel or ethyl alcohol turnover, etc., such a taxpayer is exempted from liability specified in this Code within the scope of activities carried out through such branches or excise warehouses, representative offices, separate or other structural units, for the period until the termination or cancellation of martial law on the territory of Ukraine.
{Paragraph two of subparagraph 69.1 of clause 69, subsection 10 of section XX as amended by Law No. 3603-IX of 02/23/2024 - shall apply from September 3, 2023 }
Taxpayers who have the opportunity to fulfill their tax obligations in a timely manner are exempt from liability for untimely fulfillment of such obligations in relation to:
registration in the Unified Register of Tax Invoices by such payers of tax invoices and adjustment calculations, the date of preparation of which falls on the period from February 1 to May 31, 2022, provided that their registration is ensured no later than July 15, 2022;
registration in the Unified Register of Tax Invoices of consolidated tax invoices and/or calculations of adjustments to such consolidated tax invoices, the date of preparation of which falls on the period from February 1 to May 31, 2022, prepared for transactions specified in Clause 198.5 of Article 198 and Clause 199.1 of Article 199 of this Code, provided that their registration is ensured no later than July 20, 2022;
registration in the Unified Register of Excise Invoices by excise tax payers of excise invoices/adjustment calculations, the deadline for registration of which falls on the period from February 24, 2022 to the last day of the month in which the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Laws of Ukraine on the Development of Wine Production and Simplification of the Economic Activities of Small Wine Production Plants" entered into force, or consolidated excise invoices/adjustment calculations for the total volume of fuel or ethyl alcohol sold during this period (for each commodity subcategory code according to the UKT FEA and conditional code and each excise warehouse/mobile excise warehouse and their managers), provided that their registration is ensured within 30 calendar days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Laws of Ukraine on the Development of Wine Production and Simplification of the Economic Activities of Small Wine Production Plants";
submission of electronic documents, drawn up in compliance with the procedure established by Article 230 of this Code, containing data on actual fuel residues and the volume of fuel or ethyl alcohol turnover, or an electronic document for the entire period starting from February 24, 2022 until the last day of the month in which the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Laws of Ukraine on the Development of Wine Production and Simplification of the Economic Activities of Small Wine Production Plants" entered into force, indicating the actual fuel residues as of the first and last days of the period specified in this paragraph and the volume of fuel and/or ethyl alcohol turnover for this period, provided that such documents are submitted within 30 calendar days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Laws of Ukraine on the Development of Wine Production and Simplification of the Economic Activities of Small Wine Production Plants";
submission of reports, including those provided for in paragraph 46.2 of Article 46 of this Code, for reporting (tax) periods - 2021 (for reports submitted for the annual reporting (tax) period), the deadline for submission of which falls on the period from February 24 to June 1, 2022, the first quarter of 2022 (for reports submitted for the quarterly reporting (tax) period) and reporting for February - May 2022 (for reporting submitted for a monthly reporting (tax) period), provided that such reporting is submitted to the regulatory authority no later than July 20, 2022;
deadlines for paying taxes and fees for reporting (tax) periods - 2021 (for the annual reporting (tax) period), I quarter of 2022 (for the quarterly reporting (tax) period), January - May 2022 (for the monthly reporting (tax) period), provided that they are paid no later than August 1, 2022 (for payment of personal income tax and/or military levy - no later than December 31, 2022);
the payment terms of monetary obligations determined by regulatory authorities, the payment deadline of which falls on the period from February 24 to June 1, 2022, provided that they are paid no later than August 1, 2022.
In the event of a taxpayer being released from liability on the grounds specified in paragraphs four to eight of this sub-clause, tax notices - decisions that imposed punitive (financial) sanctions and/or penalties on him for untimely fulfillment of tax obligations, except for the payment of personal income tax and/or military levy specified in paragraphs four to eight of this sub-clause, shall be deemed canceled (withdrawn) from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Promoting the Restoration of Ukraine's Energy Infrastructure".
Provided that the personal income tax and/or military levy are paid in full no later than December 31, 2022 from the amounts of income specified in the tax reporting submitted within the period specified in paragraph eight of this subclause, penalties and interest for non-payment or untimely payment of personal income tax and/or military levy from the amounts of such income shall not apply.
{Paragraph twelve of subparagraph 69.1 of clause 69 of subsection 10 of section XX as amended by Law No. 3603-IX of 02/23/2024 - applicable from September 3, 2023 }
accrued and paid or collected in the period from August 1, 2022 until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine Regarding the Features of Taxation of Activities for Trading in Currency Values in Cash" for non-payment or untimely payment of personal income tax and/or military levy from the amounts of income specified in the tax reporting submitted within the period specified in paragraph eight of this subclause shall not be subject to refund to the taxpayer's current account and shall not be used to repay a monetary obligation (tax debt) for other taxes and levies.
{Paragraph thirteen of subparagraph 69.1 of paragraph 69 of subsection 10 of section XX as amended by Law No. 3603-IX of February 23, 2024 - applicable from September 3, 2023 }
Taxpayers, including their branch or excise warehouse, representative office, separate or other structural unit, which have regained the ability to fulfill their tax obligations, the deadline for which falls on the period from February 24, 2022 until the day the taxpayer's ability is restored, are exempt from liability for untimely fulfillment of such obligations provided for by this Code, provided that they fulfill their tax obligations regarding the registration of tax invoices/adjustment calculations in the Unified Register of Tax Invoices, excise invoices/adjustment calculations in the Unified Register of Excise Invoices, submission of electronic documents containing data on actual fuel balances and the volume of fuel or ethyl alcohol turnover, submission of reporting, payment of taxes and fees within 60 calendar days from the first day of the month following the month of restoration of such taxpayers' abilities.
At the same time, excise tax payers, within 60 calendar days from the first day of the month following the month of restoration of such opportunities, are obliged to:
register in the Unified Register of Excise Invoices excise invoices/adjustment calculations, the registration deadline of which falls on the period from February 24, 2022 until the day of restoration of such opportunities, or consolidated excise invoices/adjustment calculations for the total volume of fuel or ethyl alcohol sold during this period (for each commodity subcategory code according to the UKT FEA and conditional code and each excise warehouse/mobile excise warehouse and their managers);
submit electronic documents, drawn up in accordance with the procedure established by Article 230 of this Code, containing data on actual fuel residues and the volume of fuel or ethyl alcohol turnover, or an electronic document for the period from February 24, 2022 until the date of restoration of such opportunities, indicating the actual fuel residues as of the first and last days of such period and the volume of fuel or ethyl alcohol turnover for this period.
Taxpayers, including their branch or excise warehouse, representative office, separate or other structural unit, which have regained the ability to fulfill their tax obligations after the termination or cancellation of martial law in Ukraine, are obliged, within six months after the termination or cancellation of martial law in Ukraine:
register in the Unified Register of Excise Invoices excise invoices/adjustment calculations, the registration deadline of which falls on the period from February 24, 2022 to the last day of the month in which martial law in Ukraine was terminated or abolished, or consolidated excise invoices/adjustment calculations for the total volume of fuel or ethyl alcohol sold during this period (for each commodity subcategory code according to the UKT FEA and conditional code and each excise warehouse/mobile excise warehouse and their managers);
submit electronic documents, drawn up in accordance with the procedure established by Article 230 of this Code, containing data on actual fuel residues and the volume of fuel or ethyl alcohol turnover, or a single electronic document for the period from February 24, 2022 to the last day of the month in which martial law in Ukraine was terminated or abolished, indicating the actual fuel residues as of the first and last days of such period and the volume of fuel or ethyl alcohol turnover for this period.
Single tax payers of the third group who use the features of taxation by a single tax at a rate of 2 percent are exempted from liability for untimely fulfillment of tax obligations, the deadline for fulfillment of which falls on the period from February 24, 2022 until the day of transition of such payers to the application of the features of taxation by a single tax of the third group at a rate of 2 percent, provided that they fulfill their tax obligations regarding the registration of tax invoices/calculations of adjustments in the Unified Register of Tax Invoices, submission of reports, payment of taxes and fees within 60 calendar days from the date of transition to the taxation system on which such taxpayers were before choosing the features of taxation by a single tax at a rate of 2 percent.
In the event that the taxpayer independently corrects, in compliance with the procedure, requirements and restrictions specified in Article 50 of this Code, errors that led to an understatement of the tax liability in the reporting (tax) periods that fall during the period of martial law, such taxpayers are exempt from the accrual and payment of penalties provided for in paragraph 50.1 of Article 50 of this Code, and fines.
Value-added tax payers temporarily, until the termination or cancellation of martial law, do not have the right to submit clarifying calculations to tax returns, as provided for in paragraph 50.1 of Article 50 of this Code, for reporting (tax) periods until February 2022 with indicators for reducing tax liabilities and/or declaring the amount of budget reimbursement for value-added tax. The procedure for confirming the possibility or impossibility of a taxpayer to fulfill the obligations specified in this subparagraph, and the list of documents for confirmation shall be approved by the central executive body that ensures the formation and implementation of state financial policy.
Payers of corporate income tax who, in accordance with the Law of Ukraine "On Accounting and Financial Reporting in Ukraine", are obliged to publish annual financial statements and annual consolidated financial statements together with an audit report, are exempted from the liability provided for by this Code for failure to submit or untimely submission of annual financial statements, which are subject to publication together with an audit report, a clarifying calculation to the annual corporate income tax return, which is submitted if the indicators of the annual financial statements published together with the audit report have undergone changes compared to the indicators of the statement of financial position (balance sheet) and the statement of profit and loss and other comprehensive income (statement of financial results), which are submitted together with the tax return in accordance with the second paragraph of paragraph 46.2 of Article 46 of this Code, and such changes have affected the indicators of the previously submitted annual corporate income tax return for the relevant tax year. (reporting) period, with mandatory fulfillment of such duties within three months after the termination or abolition of martial law in Ukraine.
To establish that the provisions of this subparagraph as amended by the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Certain Laws of Ukraine on the Development of Wine Production and Simplification of the Economic Activities of Small Wine Production Enterprises" shall apply from August 1, 2023.
{Subclause 69.1 of Clause 69 of Subsection 10 of Section XX as amended by Law No. 2142-IX of 03/24/2022 ; as amended by Law No. 2260-IX of 05/12/2022 ; as amended by Laws No. 2719-IX of 11/03/2022 , No. 2720-IX of 11/03/2022 ; as amended by Laws No. 2836-XI of 12/13/2022 , No. 3303-IX of 08/09/2023 }
69.1 - 1. Value-added tax payers are obliged to ensure, within the terms established by subparagraph 69.1 of this paragraph, the registration of tax invoices and adjustment calculations in the Unified Register of Tax Invoices, the deadline for registration of which falls within the periods specified in subparagraph 69.1 of this paragraph, and to clarify (bring into compliance) the tax credit declared by payers on the basis of the primary (settlement) documents available to the payer, taking into account the data of tax invoices and/or adjustment calculations registered in the Unified Register of Tax Invoices.
{Clause 69, subsection 10, section XX is supplemented by subparagraph 69.1 - 1 in accordance with Law No. 2260-IX of 12.05.2022 }
69.1 - 2. Taxpayers who are executors of contracts provided for in Article 39 of the Law of Ukraine "On the State Budget of Ukraine for 2022" are exempted from liability, as defined by this Code, for untimely payment of tax obligations arising in connection with the implementation of such contracts, with mandatory fulfillment of the obligation to pay such tax obligations in an amount proportional to the receipt of funds under such contracts, within five business days from the day following the day of receipt of such funds, but no later than the last day (inclusive) of the third calendar month after the termination or cancellation of martial law in the territory of Ukraine.
{Clause 69, subsection 10, section XX is supplemented by subparagraph 69.1 - 2 in accordance with Law No. 2290-IX of 05/31/2022 }
69.2. Temporarily, until August 1, 2023, tax audits shall not be initiated, and initiated audits shall be suspended, except for:
{Paragraph one of subparagraph 69.2 of paragraph 69, subsection 10 of section XX as amended by Law No. 3219-IX of 06/30/2023 }
a) desk checks;
{Paragraph two of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX shall enter into force on June 2, 2022 in respect of desk checks of declarations and clarifying calculations (if submitted), for which an application for the return of the amount of budget compensation has been submitted}
b) documentary unscheduled inspections conducted at the request of the taxpayer and/or on the grounds specified in subparagraphs 78.1.2 (in terms of transfer pricing control), 78.1.5 , 78.1.7 , 78.1.8 , 78.1.12 , 78.1.14-78.1.16 , 78.1.21 and 78.1.22 of paragraph 78.1 of Article 78 of this Code, and/or documentary unscheduled inspections of taxpayers, for which tax information was received indicating a violation by the taxpayer of currency legislation in terms of compliance with the deadlines for receipt of goods under import transactions and/or foreign exchange proceeds under export transactions, and/or documentary unscheduled inspections on taxation issues by legal entities or other non-residents carrying out economic activities through a permanent establishment in the territory of Ukraine, of income received non-residents with their source of origin from Ukraine, and/or documentary unscheduled inspections of non-residents (representative offices of non-residents);
{Paragraph three of subparagraph 69.2 of paragraph 69, subsection 10 of section XX as amended by Law No. 2719-IX of 03.11.2022 }
c) actual inspections.
Desk tax audits of value-added tax declarations and clarifying calculations for them for the reporting tax periods:
{Paragraph five of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX shall enter into force on June 2, 2022 in respect of desk checks of declarations and clarifying calculations (if submitted), for which an application for the return of the amount of budget compensation has been submitted}
February, March, April, May 2022 - begin the day after July 20, 2022 and end no later than September 20, 2022;
{Paragraph six of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX shall enter into force on June 2, 2022 in respect of desk checks of declarations and clarifying calculations (if submitted), for which an application for the return of the amount of budget compensation has been submitted}
June, July 2022 - begin the day after August 20, 2022 and end no later than October 20, 2022.
{Paragraph seven of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX shall enter into force on June 2, 2022 in respect of desk checks of declarations and clarifying calculations (if submitted), for which an application for the return of the amount of budget compensation has been submitted}
Submitted clarifying calculations for value added tax tax returns for reporting tax periods until February 2022 are checked within the period specified in this paragraph for the reporting period to which the day of submission of such clarifying calculation falls.
{Paragraph eight of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX shall enter into force on June 2, 2022 in respect of desk checks of declarations and clarifying calculations (if submitted), for which an application for the return of the amount of budget compensation has been submitted}
69.2 - 1 . To establish that temporarily, for the period from August 1, 2023 to December 1, 2023, documentary unscheduled inspections are conducted exclusively at the request of the taxpayer and/or on the grounds specified in subparagraphs 78.1.1 (in terms of documentary unscheduled inspections of taxpayers, for which information was received indicating a violation of tax legislation on taxation of income received by non-residents, with their source of origin in Ukraine and/or on taxation of non-residents who carry out their activities through separate divisions, including permanent representative offices, taxpayers who carry out activities in the field of production and/or sale of excisable products, organization and conduct of gambling in Ukraine (gambling business), taxpayers who provide financial and payment services), 78.1.2 (in terms of transfer pricing control), 78.1.5 , 78.1.7 , 78.1.8 , 78.1.9 , 78.1.12 , 78.1.14-78.1.16 , 78.1.21 and 78.1.22 of paragraph 78.1 of Article 78 of this Code, and/or documentary unscheduled inspections of taxpayers, for which tax information was received, indicating a violation by the payer of currency legislation in terms of compliance with the deadlines for receipt of goods under import transactions and/or foreign exchange earnings under export transactions.
{Paragraph of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX as amended by Law No. 3219-IX of 06/30/2023 ; as amended by Law No. 3453-IX of 11/09/2023 }
{Paragraph ten of subparagraph 69.2 of clause 69, subsection 10 of section XX was excluded on the basis of Law No. 3453-IX of 09.11.2023 }
{Paragraph eleven of subparagraph 69.2 of paragraph 69, subsection 10 of section XX was excluded on the basis of Law No. 3453-IX of 09.11.2023 }
{Paragraph twelve of subparagraph 69.2 of clause 69, subsection 10 of section XX was excluded on the basis of Law No. 3453-IX of 09.11.2023 }
{Paragraph thirteen of subparagraph 69.2 of clause 69, subsection 10 of section XX was excluded on the basis of Law No. 3453-IX of 09.11.2023 }
{Paragraph fourteen of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX was excluded on the basis of Law No. 3453-IX of 09.11.2023 }
Documentary inspections that were initiated and not completed by February 24, 2022, except for inspections for which a moratorium has been established, are renewed for the unused period.
{Paragraph of subparagraph 69.2 of paragraph 69 of subsection 10 of section XX as amended by Law No. 3219-IX of 06/30/2023 }
{Paragraph sixteen of subparagraph 69.2 of clause 69, subsection 10 of section XX was excluded on the basis of Law No. 3453-IX of 09.11.2023 }
{Subclause 69.2 of Clause 69, Subsection 10, Section XX as amended by Law No. 2120-IX of 03/15/2022 ; as amended by Laws No. 2142-IX of 03/24/2022 , No. 2173-IX of 04/01/2022 ; as amended by Law No. 2260-IX of 05/12/2022 }
69.2 - 2. Documentary and factual inspections during martial law are carried out in the presence of safe conditions for their conduct, namely safe:
access, admission to territories, premises and other property used for conducting business activities and/or are objects of taxation, or are used to generate income (profit), or are related to other objects of taxation of such taxpayers;
access, admission to documents, certificates on financial and economic activities, income received, expenses of taxpayers and other information related to the calculation and payment of taxes, fees, payments, compliance with the requirements of the legislation, the control over which is entrusted to the regulatory authorities, as well as to financial and statistical reporting in the manner and on the grounds specified by law;
conducting an inventory of fixed assets, inventory, funds, withdrawal of inventory balances, cash.
Documentary and factual inspections that have been initiated (repeated) but cannot be completed due to the occurrence of the circumstances specified in this subparagraph, or due to the submission of notifications by taxpayers and taking into account the requirements provided for in subparagraph 69.28 of this subparagraph, and/or upon a reasoned application by the taxpayer, shall be suspended until the end of such circumstances and/or the elimination of obstacles to conducting the inspection by decision of the head (his deputy or authorized person) of the supervisory authority, which shall be drawn up by an order, a copy of which shall be sent to the taxpayer in the taxpayer's electronic cabinet with simultaneous sending to the taxpayer's electronic address (addresses) information about the type of document, date and time of its sending to the electronic cabinet. Such circumstances shall suspend the period for conducting the inspection with subsequent renewal of its conduct for the unused period. Documentary inspections shall not be suspended on the grounds specified in subparagraphs 78.1.1 (in respect of unscheduled documentary inspections of taxpayers in respect of whom information has been received indicating a violation of tax legislation on taxation of income received by non-residents with a source of origin in Ukraine), 78.1.8 (in respect of declaring budget compensation), 78.1.21 of paragraph 78.1 of Article 78 of this Code.
Documentary inspections that were initiated and not completed by February 24, 2022, except for inspections for which a moratorium is in effect in accordance with subparagraphs 1-4 of subparagraph 69.35 - 1 of this paragraph, shall be renewed for the unused period.
A document sent by the regulatory authority to the electronic account is considered delivered to the taxpayer if it is formed in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Trust Services" .
{Clause 69, subsection 10, section XX is supplemented by subparagraph 69.2 - 2 in accordance with Law No. 3453-IX of 09.11.2023 }
69.3. Taxpayers who, due to the consequences of their direct participation in hostilities, have failed to meet the deadlines for fulfilling tax obligations specified in this paragraph, shall be exempted from liability provided for by this Code for failure to fulfill tax obligations, provided that such obligations are fulfilled within one month from the date of the end of the consequences that made it impossible to fulfill such obligations.
69.4. In the event of impossibility to register an excise invoice in the Unified Register of Excise Invoices, the movement of fuel or ethyl alcohol by means of transport is permitted if there is a goods and transport invoice, which must contain all the information that must be contained in the relevant excise invoice, which must be registered in the Unified Register of Excise Invoices, within the terms specified in this paragraph.
69.5. Operations on the voluntary transfer or alienation or withdrawal of goods, including excisable goods, provision of services in favor of the Armed Forces of Ukraine and volunteer formations of territorial communities, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Protection Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their formations, military units, subdivisions, institutions or organizations formed in accordance with the laws of Ukraine, maintained at the expense of the state budget, for the needs of ensuring the defense of the state, local self-government bodies, as well as in favor of the central executive body that ensures the formation and implementation of state policy in the field of civil defense, civil defense forces and/or health care institutions of state, municipal property, and/or structural units on health care issues of regional, Kyiv and Sevastopol city state administrations without prior or subsequent reimbursement of their value are not considered sales transactions for tax purposes.
The volume of commodity products of a mining enterprise - extracted minerals (mineral raw materials) commodity products of a mining enterprise from rocks, which are classified under code 2517 according to the UKT Foreign Economic Activity, which is transferred free of charge to the Armed Forces of Ukraine and volunteer formations of territorial communities, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Security Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their formations, military units, subdivisions, institutions or organizations formed in accordance with the laws of Ukraine, maintained at the expense of the state budget for the needs of ensuring the defense of the state, is not subject to taxation as a rental payment for the use of subsoil for the extraction of minerals.
{Subclause 69.5 of clause 69, subsection 10, section XX, supplemented by the second paragraph in accordance with Law No. 4015-IX of 10.10.2024 }
{Subclause 69.5 of Clause 69, Subsection 10, Section XX as amended by Law No. 2120-IX of March 15, 2022 }
69.5 - 1 . Exempt from VAT are transactions on the import of goods into the customs territory of Ukraine (except for goods under commodity headings 2203-2208, 2401-2404 and codes 2103 90 30 00, 2106 90, 1601 00 91 10, 1601 00 99 10, 1602 10 00 19, 1602 90 99 19 according to the UKT Foreign Economic Activity ) by public associations and/or charitable organizations included in the Register of Non-Profit Institutions and Organizations, for their subsequent free transfer (without any monetary, material or other types of compensation) by such persons to the Armed Forces of Ukraine, voluntary formations of territorial communities, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State the Border Guard Service of Ukraine, the Ministry of Internal Affairs of Ukraine, other military formations, their formations, military units, and subdivisions established in accordance with the laws of Ukraine.
{Subsection 10 of Section XX is supplemented by paragraph 69.5 - 1 in accordance with Law No. 2836-XI of 13.12.2022 ; as amended by Law No. 3553-IX of 16.01.2024 }
69.5 - 2 . Exempt from excise tax are transactions on the import into the customs territory of Ukraine and the sale on the customs territory of Ukraine of goods classified under codes 8702 10 19 10, 8702 10 19 90, 8702 90 11 00, 8702 90 19 00, 8703, 8704 according to the UKT Foreign Economic Activity , if such transactions are carried out by public associations and/or charitable organizations included in the Register of Non-Profit Institutions and Organizations, for their further voluntary transfer by such persons to the Armed Forces of Ukraine and voluntary formations of territorial communities, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Guard Service of Ukraine, the Ministry of Internal Affairs of Ukraine, other military formations, their formations, military units, subdivisions formed in accordance with the laws of Ukraine. without prior or subsequent reimbursement of their value.
{Subsection 10 of Section XX is supplemented by paragraph 69.5 - 2 in accordance with Law No. 2836-XI of 13.12.2022 }
69.5 - 3. Goods specified in subparagraphs 69.5 - 1 and 69.5 - 2 of this paragraph, which were exempted from taxation by value added tax and excise tax upon import into the customs territory of Ukraine, must be transferred to the recipients specified in subparagraphs 69.5 - 1 and 69.5 - 2 of this paragraph no later than 45 calendar days from the date of completion of customs clearance of such goods, and if such goods were subject to documented maintenance and/or repair on the territory of Ukraine after their customs clearance was completed - no later than 90 calendar days from the date of completion of their customs clearance.
In case of violation of the term specified in this subparagraph or misuse of the specified goods, the taxpayer is obliged to pay the amount of value added tax and excise tax that should have been paid upon importation of such goods into the customs territory of Ukraine, as well as to pay a penalty in accordance with the law.
{Subsection 10 of Section XX is supplemented by paragraph 69.5 - 3 in accordance with Law No. 2836-XI of 13.12.2022 }
69.6. Adjustments established by subparagraph 140.5.9 of paragraph 140.5 of Article 140 of this Code shall not be made with respect to the amounts of funds or the cost of special personal protective equipment (helmets, bulletproof vests manufactured in accordance with military standards), technical means of surveillance, medicines and medical products, personal hygiene products, food products, items of material support, as well as other goods, work performed, services rendered, which are voluntarily transferred (transferred) to the Armed Forces of Ukraine, the National Guard of Ukraine, the Security Service of Ukraine, the Foreign Intelligence Service of Ukraine, the State Border Service of Ukraine, the Ministry of Internal Affairs of Ukraine, the State Guard Department of Ukraine, the State Service for Special Communications and Information Protection of Ukraine, other military formations, their formations, military units, subdivisions, institutions or organizations formed in accordance with the laws of Ukraine, maintained at the expense of the state budget for the needs of ensuring the defense of the state and the humanitarian assistance provided in compliance with the requirements of the legislation of Ukraine. on humanitarian assistance in connection with the military aggression of the Russian Federation against Ukraine, as well as in favor of the central executive body that ensures the formation and implementation of state policy in the field of civil defense, civil defense forces and/or healthcare institutions of state and municipal ownership, and/or structural units on healthcare of regional, Kyiv and Sevastopol city state administrations, the amounts of funds transferred to the accounts of state bodies opened by the National Bank of Ukraine, intended for the financial support of measures to repel armed aggression against Ukraine and eliminate its consequences, national security and defense, restoration, support and development of Ukraine, provision of humanitarian assistance, as well as for raising funds to support the Armed Forces of Ukraine.
{Subclause 69.6 of Clause 69, Subsection 10, Section XX, as amended by Laws No. 2120-IX of March 15, 2022 , No. 2173-IX of April 1, 2022 , No. 3219-IX of June 30, 2023 , No. 4113-IX of December 4, 2024 }
69.7. The amount of reimbursement for the cost of fuel spent in providing transportation services to meet the needs of the Armed Forces of Ukraine and territorial defense units is not included in the taxable income of individuals who provide such services.
69.8. For the period until the termination or cancellation of martial law, the production and import of tobacco products classified under code 2402 20 90 20 according to the UKT ZEA marked with excise tax stamps "tobacco-containing products for electric heating (TVEN) using an electronically controlled heater, domestic" - "TVEN B", "tobacco-containing products for electric heating (TVEN) using an electronically controlled heater, imported" - "TVEN I", if the excise tax rate is the same.
The circulation of tobacco products labeled in accordance with this subparagraph shall be carried out until they are fully sold to the end consumer.
69.9. Temporarily, until August 1, 2023, the running of time limits specified in tax legislation and other legislation, the control over compliance of which is entrusted to regulatory authorities, is suspended for taxpayers and regulatory authorities, except for:
{Paragraph one of subparagraph 69.9 of paragraph 69, subsection 10 of section XX, as amended by Law No. 3219-IX of 06/30/2023 }
the deadlines for registering tax invoices, calculating adjustments to them in the Unified Register of Tax Invoices, submitting reports and/or documents (notifications), including those provided for in Articles 39 and 39-2 , paragraph 46.2 of Article 46 of this Code, and paying taxes and fees by taxpayers;
{Paragraph two of subparagraph 69.9 of paragraph 69, subsection 10 of section XX, as amended by Law No. 2719-IX of 03.11.2022 }
deadlines for conducting desk audits, processing their results in accordance with the procedure specified in Article 86 of this Code, filing a complaint against a tax notice-decision based on the results of a desk audit, making a decision based on the results of its consideration, and calculating penalties;
{Paragraph three of subparagraph 69.9 of paragraph 69, subsection 10 of section XX as amended by Law No. 2719-IX of 03.11.2022 }
deadlines for conducting actual and documentary unscheduled inspections, processing their results in accordance with the procedure specified in Article 86 of this Code, filing a complaint against a tax notice-decision, a decision on the application of financial sanctions based on the results of a documentary unscheduled inspection or actual inspection and making a decision based on the results of their consideration, administrative seizure of property based on the results of a documentary unscheduled inspection or actual inspection;
{Paragraph four of subparagraph 69.9 of paragraph 69, subsection 10 of section XX as amended by Law No. 2719-IX of 03.11.2022 }
deadlines for implementing measures to repay tax debt of taxpayers - business entities that have the ability to timely fulfill tax obligations stipulated by Articles 59-60 , 87-101 of this Code, and/or determining monetary obligations in accordance with Article 116 of this Code;
{Subclause 69.9 of clause 69, subsection 10, section XX is supplemented by paragraph five in accordance with Law No. 2719-IX of 03.11.2022 }
deadlines for filing and considering complaints against the decision to refuse to register a tax invoice/calculation of an adjustment in the Unified Register of Tax Invoices, provided for in subparagraph 56.23.3 of paragraph 56.23 of Article 56 of this Code.
{Subclause 69.9 of clause 69, subsection 10, section XX is supplemented by paragraph six in accordance with Law No. 2836-XI of 13.12.2022 }
To establish that temporarily, for the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the consideration of complaints against the decision to refuse to register a tax invoice/calculation of an adjustment in the Unified Register of Tax Invoices, provided for by subparagraph 56.23.3 of paragraph 56.23 of Article 56 of this Code, shall be carried out within 10 working days from the date of receipt of such a complaint by the central executive body implementing state tax policy.
{Subclause 69.9 of clause 69, subsection 10, section XX is supplemented by paragraph seven in accordance with Law No. 2836-XI of 13.12.2022 }
If a reasoned decision on a taxpayer's complaint against a decision to refuse to register a tax invoice/calculation of an adjustment in the Unified Register of Tax Invoices is not sent to the taxpayer within the period specified for consideration, such complaint shall be deemed to be fully satisfied in favor of the taxpayer from the day following the last day of the specified period.
{Subclause 69.9 of clause 69, subsection 10, section XX is supplemented by paragraph eight in accordance with Law No. 2836-XI of 13.12.2022 }
{Subclause 69.9 of clause 69, subsection 10, section XX as amended by Law No. 2260-IX of 05/12/2022 }
{Subclause 69.10 of clause 69, subsection 10, section XX was excluded on the basis of Law No. 2120-IX of March 15, 2022 }
paragraphs 200.10-200.12 of Article 200 of this Code until July 21, 2022. For the reporting tax periods of February - July 2022, paragraphs 200.10-200.12 of Article 200 of this Code shall apply, taking into account the deadlines for conducting desk and documentary tax audits provided for in subparagraph 69.2 of this paragraph.
The refund of the agreed amounts of budget compensation is carried out in chronological order in accordance with the order of entry of applications for the refund of the amount of budget compensation into the Register.
{Subclause 69.11 of clause 69 of subsection 10 of section XX as amended by Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 2260-IX of May 12, 2022 - shall enter into force on June 2, 2022 in respect of desk checks of declarations and clarifying calculations (if submitted), to which an application for the return of the amount of budget compensation has been submitted}
69.12. Operations provided for in subparagraph 197.1.15 of paragraph 197.1 of Article 197 of this Code, carried out during the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , by public associations and/or charitable organizations, shall not be included by such public associations or charitable organizations when determining the total amount for mandatory registration by a value added tax payer in accordance with Article 181 of this Code.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.12 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 2836-XI of December 13, 2022 }
69.13. In excise warehouses that are partially destroyed and located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation, which are included in the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation, which is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine, accounting for fuel and ethyl alcohol will be carried out based on the inventory data conducted after the end of the events specified in this paragraph.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.13 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 3050-IX of April 11, 2023 }
69.14. For the period from January 1, 2022 to December 31, 2022, no land fee (land tax and rent for land plots of state and municipal ownership) shall be charged and paid for land plots (land shares (shares)) located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation, and owned or used, including under lease, by individuals, and for the period from March 1, 2022 to December 31, 2022 - for land plots owned or used, including under lease, by legal entities and individual entrepreneurs.
Starting from January 1, 2023, for land plots (land shares (shares)) located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation, which are included in the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation, land payment (land tax and rent for land plots of state and municipal property) is not charged and paid for the period from the first day of the month in which the date of the start of active hostilities or temporary occupation was determined for the relevant territories, until the last day of the month in which active hostilities or temporary occupation in the relevant territory was completed.
The dates of the beginning and end of active hostilities or temporary occupation are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
Land fee payers who, prior to the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Fee and Tax on Real Estate Other than Land Plots for Destroyed or Damaged Real Estate" in accordance with Clause 286.2 of Article 286 of this Code, declared tax liabilities for land fees for land plots located in the territories specified in this subparagraph for 2022 and/or 2023, have the right to adjust the accrued tax liabilities for land fees for the period March 2022 - December 2023 by submitting clarifying tax declarations in accordance with the procedure specified in this Code.
Rent payers who, prior to the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Fee and Real Estate Tax, Other than Land, for Destroyed or Damaged Real Estate" in accordance with Article 288 of this Code, declared tax liabilities for rent for land plots contaminated with explosives or unsuitable for use due to the potential threat of their contamination by explosives for 2022 and/or 2023, have the right to adjust the accrued tax liabilities for rent for the period 2022-2023 by submitting clarifying tax declarations in accordance with the procedure specified by this Code.
For individual taxpayers, the regulatory authority independently calculates the tax liability and sends (delivers) a tax notice-decision for 2022 by December 31, 2023.
In this case, the annual amount of payment for land plots (land shares (units)) defined by this subparagraph is determined in proportion to the number of months when such land plots (land shares (units)) were subject to taxation with a land payment.
Tax notices-decisions on the payment of land fees, for land plots that are not subject to taxation in the manner specified in this subparagraph, drawn up, sent (delivered) in 2022 and 2023, are subject to cancellation (withdrawal), and monetary obligations and tax debt determined by the controlling body for land fees are subject to annulment.
Tax notices-decisions on payment of land payment, land plots, defined by subparagraph 283.1.9 of paragraph 283.1 and paragraph 283.2 of Article 283 of this Code , drawn up, sent (delivered) before the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Tax on Real Estate Other than a Land Plot, for Destroyed or Damaged Real Estate", shall be subject to cancellation (withdrawal), and monetary obligations and tax debt determined by the controlling body for land payment shall be annulled.
Tax notices-decisions on payment of land fees, land plots, defined by Clause 288.8 of Article 288 of this Code, drawn up, sent (delivered) before the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Fee and Tax on Real Estate Other than a Land Plot, for Destroyed or Damaged Real Estate" shall be subject to cancellation (withdrawal), and monetary obligations and tax debt determined by the controlling body for land fees shall be annulled.
Overpaid amounts of land payment arising from the cancellation (withdrawal) of tax notices-decisions shall be credited exclusively to future payments of this tax, except for the following cases: if such a payer has a tax debt on land payment - the overpaid amounts shall be credited to the repayment of such debt; and if the obligation to pay the payment has been transferred to another entity for the reasons provided for in Article 120 of the Land Code of Ukraine regarding the change of owner of the real estate object, - the amount of the paid payment upon application by the previous user shall be credited to future payments on land payment of the new user of such land plot, provided that the new user of the land plot who purchased the real estate reimburses the previous user for the amount of payment paid by him to the budgets according to the conclusion of the regulatory body on such amount.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.14 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 3050-IX of April 11, 2023 }
69.14 - 1. Land tax (land tax and rent for land plots of state and municipal ownership) shall not be charged or paid for land plots on which residential and/or non-residential real estate objects are located, destroyed as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine, data on the destruction of which and data on land plots on which the specified real estate objects were located are entered in the State Register of Property Damaged and Destroyed as a Result of Hostilities, Terrorist Acts, and Sabotage Caused by the Armed Aggression of the Russian Federation against Ukraine (hereinafter referred to as the Property Register), within the areas (land plots) specified in this subparagraph.
The areas of land plots covered by this subparagraph are limited to:
for individuals - owners of destroyed residential real estate:
in villages - no more than 0.25 hectares,
in villages - no more than 0.15 hectares,
in cities - no more than 0.1 hectare;
for individuals and legal entities - owners of destroyed non-residential real estate and legal entities - owners of destroyed residential real estate:
100 percent of the area of the land plot - if the total area of the destroyed residential or non-residential real estate object is equal to or exceeds one third of the total area of the land plot on which such destroyed real estate object was located;
50 percent of the area of the land plot - if the total area of the destroyed residential or non-residential real estate does not exceed one third of the total area of the land plot on which such destroyed real estate was located.
Land payment for land plots on which residential and/or non-residential real estate objects are located, destroyed as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine, is not accrued and paid for the period starting from the first day of the month on which the date of destruction of real estate falls, according to the Property Register, until the last day of the month in which the property right to the newly constructed residential and/or non-residential real estate object on such land plot is registered in the State Register of Property Rights to Real Estate and Their Encumbrances, or until the last day of the month in which martial law in Ukraine is terminated or abolished, but no later than January 1, 2026.
Land tax payers who, prior to the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on Improving Online Communication with Taxpayers and Clarifying Certain Provisions of the Legislation" in accordance with Clause 286.2 of Article 286 of this Code, declared tax liabilities for land tax for land plots specified in this subparagraph, have the right to adjust the accrued tax liabilities for land tax for the period starting from the first day of the month on which the date of destruction of real estate falls, according to the Property Register, by submitting clarifying tax declarations in accordance with the procedure specified by this Code.
The tax notices-decisions drawn up, sent (delivered) on the payment of land fees for land plots specified in this subparagraph are subject to cancellation (withdrawal), and the monetary obligations and tax debt determined by the controlling body for land fees are subject to annulment.
Overpaid amounts of land tax resulting from the cancellation (withdrawal) of tax notices-decisions shall be credited exclusively against future payments of this tax, except in the following cases:
if such a payer has a tax debt for land payments - the overpaid amounts are credited towards the repayment of such debt;
if the obligation to pay the fee has been transferred to another entity for the reasons provided for in Article 120 of the Land Code of Ukraine regarding the change of owner of the real estate object, the amount of the paid fee upon application by the previous user shall be credited to future payments from the land fee of the new user of such land plot, provided that the new user of the land plot who purchased the real estate reimburses the previous user for the amount of the fee paid by him to the budgets according to the conclusion of the supervisory body on such amount.
{Clause 69, subsection 10, section XX is supplemented by subparagraph 69.14 - 1 in accordance with Law No. 3603-IX of 02/23/2024 }
69.15. The general minimum tax liability is not charged or paid for land plots, land shares (shares) located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation:
for 2022 - in respect of land plots, land shares (shares) owned or used by individuals;
from March 1, 2022 to December 31, 2022 - in respect of land plots, land shares (shares) owned or used by legal entities and individual entrepreneurs.
{Paragraph three of subparagraph 69.15 of paragraph 69, subsection 10 of section XX, as amended by Law No. 3219-IX of 06/30/2023 }
The amount of the minimum tax liability for land plots (land shares (units)) defined by this subparagraph is determined in proportion to the number of months when such land plots (land shares (units)) were subject to taxation by land payment or a single tax of the fourth group.
Taxpayers who, before the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Tax on Real Estate Other than Land, for Destroyed or Damaged Real Estate" determined and declared in their tax reports the minimum tax liability for 2022-2023 for land plots located in the territories specified in the first paragraph of this subparagraph, have the right to adjust the amounts of the total minimum tax liability accrued for 2022-2023 by submitting clarifying tax declarations in accordance with the procedure specified by this Code.
The norms specified in paragraphs seven and eight of clause 38-1.2 of Article 38-1 of this Code shall apply to tax (reporting) periods starting from January 1 , 2023.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Subclause 69.15 of clause 69, subsection 10, section XX is supplemented by paragraph seven in accordance with Law No. 3219-IX of 06/30/2023 }
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.15 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 3050-IX of April 11, 2023 }
69.16. For the period from January 1, 2022 to December 31, 2022, no environmental tax shall be charged or paid by payers of this tax registered (registered) at the location of stationary sources of pollution, for the generation of radioactive waste and temporary storage of radioactive waste in areas of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation.
Starting from January 1, 2023, in the part of the territories included in the List of territories in which active hostilities are (were) conducted or temporarily occupied by the Russian Federation, the environmental tax is not charged and paid for the period from the first day of the month in which the date of the beginning of hostilities or temporary occupation was determined for the relevant territories, to the first day of the month following the date of the end of hostilities or temporary occupation in the relevant territory.
Environmental tax is not charged and paid by taxpayers registered (registered) at the location of stationary sources of pollution, for the generation of radioactive waste and temporary storage of radioactive waste on land plots contaminated with explosives, for the period when such land plots were contaminated with explosives, and/or for the period when the land plots were recognized as potentially contaminated with explosives.
The period when land plots were contaminated with explosive objects is defined as the period starting from the first day of the month on which the date of the start of the survey of the land plot by mine action operators falls, and ending on the last day of the month in which such land plots are recognized as suitable for use.
For land plots located in territories where active hostilities are (were) being conducted or temporarily occupied by the Russian Federation, the period when land plots are recognized as contaminated with explosive objects is defined as the period starting from the first day of the month following the month in which active hostilities or temporary occupation in the relevant territory ended (including if the date of commencement of survey of the hazardous area by mine action operators falls after the date of completion of hostilities or temporary occupation in the relevant territory), provided that the payer submits to the local government body, military administration and military-civilian administration an application on potential contamination of the land plot with explosive objects and that such local government body, military administration or military-civilian administration adopts a decision on establishing tax benefits for the payment of local taxes and fees in respect of the land plot specified in such application, and ends on the last day of the month in which such land plots are recognized as suitable for use.
The period when land plots are recognized as potentially contaminated with explosive objects is defined as the period starting from the first day of the month on which the date of the decision by the village, settlement, city council, military administration or military-civilian administration on the provision of tax benefits for the payment of local taxes and fees on the basis of the taxpayer's application falls, and ends on the last day of the month on which the earlier date falls - or the last day of the period for which the benefit for the payment of local taxes and/or fees was provided in accordance with the decision made (including taking into account the changes made to such a decision), or the date of cancellation of the relevant decision, or the date of commencement of the survey of the land plot by mine action operators or recognition of the land plot as suitable for use.
The dates of the beginning and end of hostilities or temporary occupation are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
Payers of the environmental tax, defined in this subparagraph, who, before the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Tax on Real Estate Other than a Land Plot, for Destroyed or Damaged Real Estate" determined and declared tax liabilities for the environmental tax in their tax reporting for the tax (reporting) periods of 2022 and/or 2023, have the right to adjust the amounts of environmental tax accrued for these periods by submitting clarifying tax declarations in accordance with the procedure specified by this Code.
{Clause 69, subsection 10, section XX is supplemented by subparagraph 69.16 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Laws No. 2142-IX of March 24, 2022 , No. 3050-IX of April 11, 2023 }
69.17. To establish that temporarily, for the period until the termination or cancellation of the state of war or emergency in the territory of Ukraine, but no later than August 1, 2023, for banks, other financial institutions, non-bank payment service providers, electronic money issuers and regulatory authorities, the expiration of the deadlines specified for sending a notification about the opening or closing of an account/electronic wallet of a taxpayer - a legal entity (resident and non-resident), including one opened through its separate divisions, or a self-employed individual to the regulatory authority with which the taxpayer is registered, and notifications about the registration of an account/electronic wallet or refusal to register an account/electronic wallet by the regulatory authority shall be suspended.
{Paragraph one of subparagraph 69.17 of paragraph 69, subsection 10, section XX, as amended by Law No. 3219-IX of 06/30/2023 }
An account/electronic wallet is considered registered if the bank or other financial institution, non-bank payment service provider, or electronic money issuer receives a notification from the regulatory authority about registering the account/electronic wallet with regulatory authorities or by tacit consent, if such notification is not received, the date and time of registration of the account/electronic wallet in such a case is considered to be the date and time of receipt by the bank or other financial institution, non-bank payment service provider, or electronic money issuer of a notification (receipt) from the regulatory authority confirming the fact of accepting the notification for processing.
If the financial institution does not receive a notification (receipt) from the regulatory authority confirming the fact of acceptance of the notification for processing, expenditure transactions may be carried out on such accounts/electronic wallets without receiving confirmation of their registration with the regulatory authority.
Regarding all accounts/electronic wallets opened/closed during the period from the beginning of martial law in the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , by August 1, 2023, taxpayers specified in Clause 69.1 of Article 69 of this Code, banks, other financial institutions, non-bank payment service providers, and electronic money issuers are required to send (including re-) notifications to the regulatory authorities about the opening/closing of accounts/electronic wallets in order to receive from the regulatory authorities a notification about the registration of accounts/electronic wallets no later than September 1, 2023. If after September 1 2023, the bank, other financial institution, non-bank payment service provider, electronic money issuer does not have confirmation of the registration of the account/electronic wallet with the regulatory authority, it is considered that the bank, other financial institution, non-bank payment service provider, electronic money issuer began to carry out expenditure transactions on the taxpayer's account/electronic wallet before receiving a notification from the relevant regulatory authority about the registration of the account/electronic wallet with the regulatory authorities.
{Subclause 69.17 of clause 69, subsection 10, section XX is supplemented by the fourth paragraph in accordance with Law No. 2888-IX of 01/12/2023 ; as amended by Law No. 3219-IX of 06/30/2023 }
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.17 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Law No. 2888-IX of January 12, 2023 }
69.18. To establish that temporarily, for the period until the termination or cancellation of the martial law or state of emergency in the territory of Ukraine, in order to protect the rights of taxpayers, preserve and protect data, the provision of electronic services and the acceptance of electronic documents from taxpayers shall be carried out on working days from 8 a.m. to 8 p.m.
The operating day for registering tax invoices and/or adjustment calculations, which falls on the deadline for registering tax invoices and/or adjustment calculations, lasts from 0:00 to 24:00.
Registration of tax invoices/adjustment calculations submitted for registration in the Unified Register of Tax Invoices on the day on which the deadline for registration of tax invoices and/or adjustment calculations falls, and sending a receipt on acceptance or non-acceptance, or suspension of registration of such tax invoices/adjustment calculations shall be carried out no later than the next business day from the date of submission for registration of such tax invoices in the Unified Register of Tax Invoices.
Registration of tax invoices/adjustment calculations submitted for registration in the Unified Register of Tax Invoices, which reflect the operation of exporting certain types of goods outside the customs territory of Ukraine, to which, in accordance with Article 19-2 of the Law of Ukraine "On Foreign Economic Activity", the export guarantee regime has been applied in the event of its introduction by the Cabinet of Ministers of Ukraine, and sending a receipt on acceptance or rejection, or suspension of registration of such tax invoices/adjustment calculations are carried out within three business days from the date of submission for registration of such tax invoices in the Unified Register of Tax Invoices.
If a receipt of acceptance or non-acceptance, or suspension of registration of a tax invoice/adjustment calculation, is not sent within the period specified in this subparagraph, such tax invoice shall be deemed to be registered in the Unified Register of Tax Invoices.
Confirmation to the seller of the acceptance of his tax invoice and/or adjustment calculation to the Unified Register of Tax Invoices is an electronic receipt in text format, which is sent within the deadlines specified in this subparagraph.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.18 in accordance with Law No. 2120-IX of March 15, 2022 ; as amended by Laws No. 2876-IX of January 12, 2023 , No. 3706-IX of May 9, 2024 }
69.19. Temporarily, for the period until the termination or cancellation of the state of war or emergency in the territory of Ukraine, the regulatory authorities shall suspend the running of the terms established for registering legal entities and their separate divisions with regulatory authorities as taxpayers and levies at the main place of registration or individual entrepreneurs at the tax address and transferring data on the registration of such taxpayers with regulatory authorities to the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.19 in accordance with Law No. 2120-IX of March 15, 2022 }
69.20. In the event of information on the official web portal of the central executive body implementing the state tax policy about the inability to ensure the sale of excise tax stamps to importers of tobacco products, the import into the customs territory of Ukraine of tobacco products marked with excise tax stamps that are not strict accounting documents and printed outside the customs territory of Ukraine at the request of manufacturers or importers of tobacco products is permitted. Excise tax on tobacco products marked with such stamps is paid by taxpayers before submitting a customs declaration.
In the case provided for in the first paragraph of this paragraph, together with the customs declaration, the taxpayer shall submit to the customs authority:
a document confirming the payment of excise tax to the relevant budget in full. The central executive body implementing the state tax policy shall ensure that the central executive body implementing the state customs policy is provided with information confirming the amounts of excise tax paid with the relevant details of such a document;
{Paragraph three of subparagraph 69.20 of paragraph 69, subsection 10, section XX, as amended by Law No. 2888-IX of 12.01.2023 }
information about excise tax stamps indicating the series and numbers of excise tax stamps marked on tobacco products imported into the customs territory of Ukraine.
Excise tax stamps printed outside the customs territory of Ukraine must have the dimensions, color scheme and details provided for by the Regulation on the manufacture, storage, sale of excise tax stamps and labeling of alcoholic beverages, tobacco products and liquids used in electronic cigarettes, approved by the Cabinet of Ministers of Ukraine in accordance with paragraph 226.3 of Article 226 of this Code.
The circulation of tobacco products labeled in accordance with this paragraph shall be carried out until their full sale to the end consumer, but no later than three months after the termination or cancellation of the state of war or emergency.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.20 in accordance with Law No. 2120-IX of March 15, 2022 }
69.21. The taxpayer's property is released from tax lien from the date of receipt by the controlling body of a decision on the seizure of property under the legal regime of martial law, adopted in accordance with the Law of Ukraine "On the Transfer, Compulsory Alienation or Seizure of Property under the Legal Regime of Martial Law or a State of Emergency", without applying the requirements of Article 92 of this Code.
{Paragraph one of subparagraph 69.21 of paragraph 69, subsection 10 of section XX as amended by Law No. 2719-IX of 03.11.2022 }
In the case of a paid seizure of property, such funds are used to repay the tax debt of the taxpayer whose property was seized.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.21 in accordance with Law No. 2120-IX of March 15, 2022 }
69.22. Temporarily, for the period of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , until December 31 of the year in which martial law is terminated or canceled, the provisions of Article 266 of this Code shall apply, taking into account the following features:
The basis for calculating tax liabilities on real estate tax, other than land plots, for residential and non-residential real estate objects, including their shares, owned by individuals and/or legal entities that have been damaged or destroyed, is the information specified in Article 266 of this Code, data from the State Register of Property Damaged and Destroyed as a Result of Hostilities, Terrorist Acts, and Sabotage Caused by Armed Aggression of the Russian Federation against Ukraine (hereinafter referred to as the Property Register), and data from the List of Territories in Which Hostilities Are (Were) Conducted or Temporarily Occupied by the Russian Federation, determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The holder of the Property Register shall submit to the central executive body implementing state tax policy, every quarter, within 15 days after the end of the tax (reporting) quarter, the information necessary for calculating and collecting tax on real estate other than land, as of the first day of the relevant quarter.
Tax on real estate other than land is not charged and paid:
1) for residential and/or non-residential real estate located in areas of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation:
for 2021 and 2022 - for residential real estate objects, including their shares owned by individuals;
for the period from March 1, 2022 to December 31, 2022 - for residential real estate objects, including their shares owned by legal entities, and for non-residential real estate objects owned by individuals and/or legal entities.
Starting from January 1, 2023, for residential and/or non-residential real estate objects, including their shares, owned by individuals and/or legal entities located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation, which are included in the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation, real estate tax, other than land, is not charged and paid for the period from the first day of the month in which the date of the start of active hostilities or temporary occupation was determined for the relevant territories, until the last day of the month in which hostilities or temporary occupation in the relevant territory ended.
When calculating the tax base for real estate tax other than land, the regulatory authority shall not take into account real estate objects, including their shares, located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation, included in the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation , which are owned by individuals and for which, in accordance with this subparagraph, real estate tax other than land is not charged and paid. The provisions of this paragraph shall apply to the specified real estate objects for the period from January 1, 2025 until the last day of the month in which active hostilities or temporary occupation of the relevant territory ended.
{Subclause 69.22 of clause 69, subsection 10, section XX is supplemented with a new paragraph in accordance with Law No. 4698-IX of 03.12.2025 }
The dates of the beginning and end of active hostilities or temporary occupation are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine;
2) for residential and/or non-residential real estate objects destroyed as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine:
for 2021 and subsequent tax (reporting) periods - for residential and/or non-residential real estate objects, including their shares, owned by individuals, data on the destruction of which is entered in the Property Register;
for 2022 and subsequent tax (reporting) periods - for residential and/or non-residential real estate objects, including their shares, owned by legal entities, data on the destruction of which is entered in the Property Register;
3) for damaged residential and/or non-residential real estate objects (as those requiring major repairs, reconstruction or restoration as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine):
for 2021 and subsequent tax (reporting) periods - for residential real estate objects, including their shares, owned by individuals, which were damaged in 2022 as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine, and data on the damage of which is entered in the Property Register. The assessment of real estate tax, other than land, for such real estate objects is resumed starting from the month following the month in which, according to the Property Register, the residential real estate objects were overhauled, reconstructed, restored and recognized as suitable for habitation;
for the period from March 1, 2022 and subsequent tax (reporting) periods - for residential real estate objects, including their shares, owned by legal entities, which were damaged in 2022 as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine, and data on the damage of which is entered in the Property Register. The calculation of tax on real estate other than land plots is resumed starting from the month following the month in which, according to the Property Register, the residential real estate objects were overhauled, reconstructed, restored and recognized as suitable for habitation;
for the period from March 1, 2022 and subsequent tax (reporting) periods - for non-residential real estate objects, including their shares, owned by individuals and/or legal entities, which were damaged in 2022 as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine, and data on the damage of which is entered in the Property Register. The calculation of real estate tax, other than land, for such real estate objects is resumed starting from the month following the month in which, according to the Property Register, the non-residential real estate objects were overhauled, reconstructed, restored and recognized as suitable for use for their intended purpose.
For residential and/or non-residential real estate objects, including their shares owned by individuals and/or legal entities, damaged (as requiring major repairs, reconstruction or restoration) in tax (reporting) periods starting from January 1, 2023 as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine, real estate tax other than land is not charged and paid for the period from the first day of the month in which the fact of damage to residential and/or non-residential real estate was recorded according to the Property Register, until the first day of the month following the month in which, according to the Property Register, the residential and/or non-residential real estate objects were majorly repaired, reconstructed, restored and recognized as suitable for habitation/for use for their intended purpose.
In the case of residential/non-residential real estate objects, including their parts, which, as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine, have suffered minor damage, are suitable for residence/use for their intended purpose (respectively) and are subject to restoration through current repairs, village, settlement, city councils, military administrations or military-civilian administrations have the right:
1) establish tax rates on real estate other than land plots in an amount lower than the tax on real estate other than land plots established by a decision of the relevant local government body for a certain type of real estate objects, payable in the relevant territory;
2) exempt from paying tax on real estate other than land.
The requirements of subparagraph 4.1.9 of paragraph 4.1 and paragraph 4.5 of Article 4, subparagraphs 12.3.3 , 12.3.4 and 12.3.7 of paragraph 12.3, subparagraph 12.4.3 of paragraph 12.4 and paragraph 12.5 of Article 12 of this Code and the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity", part four of Article 15 of the Law of Ukraine "On Access to Public Information", and the Law of Ukraine "On State Aid to Economic Entities" shall not apply to such decisions of village, settlement, city councils, military administrations or military-civilian administrations and/or decisions on amendments to such decisions.
Local government bodies, village, settlement, city councils, military administrations or military-civilian administrations are obliged to submit to the supervisory authorities at the location of the real estate object copies of the decisions made on the following quarterly basis, within 15 days after the end of the tax (reporting) quarter, as of the first day of the relevant quarter:
setting the tax rate on real estate other than land in an amount lower than the tax on real estate other than land established by a decision of the relevant local government body for a certain type of real estate, payable in the relevant territory;
exemption from paying tax on real estate, other than land plots of real estate objects that have suffered minor damage as a result of hostilities, terrorist acts, sabotage caused by the armed aggression of the Russian Federation against Ukraine.
Payers of real estate tax other than land plots who, prior to the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Real Estate Tax Other than Land Plots for Destroyed or Damaged Real Estate", declared tax liabilities for residential and/or non-residential real estate located in the territories specified in this subparagraph for 2022-2023, have the right to adjust the accrued tax liabilities for real estate tax other than land plots for the period 2022 and 2023 by submitting, in accordance with the procedure specified in this Code, clarifying tax declarations for the relevant period.
For individual taxpayers, the regulatory authority independently calculates the tax liability and sends (hands over) the tax notice-decision for the tax (reporting) periods of 2021 and 2022 by December 31, 2023, with the exception of tax liabilities for non-residential real estate located in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation, which are included in the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation, for which the regulatory authority calculates the tax liability and sends (hands over) the tax notice-decision for the tax (reporting) periods of 2021 and January - February 2022, no later than the first day of the month that falls six months after the date of the end of active hostilities or temporary occupation.
In this case, the annual amount of payment for real estate objects defined by this subparagraph is determined in proportion to the number of months during which such real estate objects were subject to taxation by the tax on real estate other than land.
Tax notices-decisions on the payment of tax amounts calculated in accordance with Article 266 of this Code on real estate objects specified in this subparagraph, for which real estate tax other than land is not charged and paid, drawn up, sent (delivered) in 2022 and 2023, shall be subject to cancellation (withdrawal), and monetary obligations and tax debt determined by the controlling authority on real estate tax other than land, shall be annulled.
Overpaid amounts of tax on real estate other than land, which arose as a result of the cancellation (withdrawal) of tax notices-decisions, shall be credited exclusively to future payments of this tax, and if such a payer has a tax debt on real estate other than land, the overpaid amounts shall be credited to the repayment of such debt.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.22 in accordance with Law No. 2142-IX of March 24, 2022 ; as amended by Law No. 3050-IX of April 11, 2023 }
{Subclause 69.23 of clause 69, subsection 10, section XX was excluded on the basis of Law No. 2325-IX of 06/21/2022 }
{Subclause 69.24 of clause 69, subsection 10, section XX was excluded on the basis of Law No. 2325-IX of 06/21/2022 }
{Subclause 69.25 of clause 69, subsection 10, section XX was excluded on the basis of Law No. 2325-IX of 06/21/2022 }
{Subclause 69.26 of clause 69, subsection 10, section XX was excluded on the basis of Law No. 2260-IX of 05/12/2022 }
69.27. Temporarily, for the period until the termination or abolition of martial law in Ukraine, tax authorities shall exercise state control (supervision) and observation in the field of pricing in accordance with the Law of Ukraine "On Prices and Pricing", taking into account the features established by this paragraph.
Tax authorities monitor taxpayers' compliance with the requirements of the law regarding state-established fixed prices, maximum prices, and maximum levels of trade mark-ups by conducting actual inspections.
A factual check is carried out if at least one of the following grounds exists:
obtaining, in accordance with the procedure established by law, from state bodies or local self-government bodies information indicating possible violations by the taxpayer of the legislation on prices and pricing;
receipt of a written appeal from a buyer (consumer), drawn up in accordance with the law, about a taxpayer's violation of the established procedure for the formation, establishment and application of state regulated prices.
During an actual inspection, tax authorities have the right to receive documents and/or information from business entities confirming the cost of purchasing the goods that are the subject of the inspection.
If violations of the legislation on prices and pricing are identified based on the results of an actual inspection, such violations are noted in a separate act on the results of the actual inspection, which is sent to the body authorized to make decisions on the application of administrative and economic sanctions for violations of the requirements for the formation, establishment and application of state regulated prices.
If the taxpayer disagrees with the violations of the legislation on prices and pricing identified during the actual inspection, he sends his comments to the body authorized to make decisions on the application of administrative and economic sanctions for violations of the requirements for the formation, establishment and application of state regulated prices.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.27 in accordance with Law No. 2173-IX of 01.04.2022 }
69.28. To establish that special rules for confirming the data specified in tax reporting shall apply to taxpayers/tax agents who have carried out activities in the territories of active hostilities or in the territories of Ukraine temporarily occupied by the Russian Federation and cannot present primary documents on the basis of which income, expenses and other indicators related to the determination of objects of taxation and/or tax liabilities are recorded, as an exception to the provisions of Article 44 of this Code.
{Paragraph one of subparagraph 69.28 of paragraph 69, subsection 10 of section XX as amended by Law No. 3050-IX of 11.04.2023 }
The grounds for the impossibility of presenting primary documents are the loss (destruction or damage) of primary documents or their finding in the territories where hostilities are (were) being conducted, and in the territories of Ukraine temporarily occupied by the Russian Federation, if they cannot be exported or their export is associated with a risk to the life or health of the taxpayer, individuals, or is impossible due to administrative obstacles established by the authorities.
In the event of loss and/or inability to export primary documents, the taxpayer/tax agent submits to the regulatory authority in any form a notification of the inability to export primary documents, signed by the head of the enterprise and the chief accountant, which indicates: the circumstances that led to the loss and/or inability to export primary documents, tax (reporting) periods, as well as a general list of primary documents (if possible, indicating details).
The data and indicators of the taxpayer's/tax agent's tax reporting for the tax (reporting) periods specified in the notification cannot be questioned solely on the basis of the absence of primary documents. The submitted notification is also the basis for preserving expenses (including expenses related to the acquisition of securities/corporate rights) and/or the negative value of the object of taxation by income tax (including the negative financial result on transactions with securities/corporate rights), and/or the tax credit from the value added tax, and/or the amount of the negative value of the value added tax of past tax (reporting) periods without the availability of contractual, settlement, payment and other primary documents, the mandatory maintenance and storage of which is provided for by the rules for accounting and tax assessment.
After submitting a notification to the regulatory authority about the impossibility of exporting primary documents due to their location in the territories where hostilities are (were) underway and in the territories of Ukraine temporarily occupied by the Russian Federation, a moratorium is introduced on conducting documentary audits for the tax (reporting) periods specified in the notification.
If, after submitting a notification about the impossibility of exporting primary documents, the taxpayer/tax agent becomes aware of the loss of such documents, such taxpayer/tax agent is obliged to submit a notification about the loss of primary documents to the supervisory authority, indicating the circumstances of such loss.
Taxpayers/tax agents who have submitted a notification of the loss of primary documents in accordance with this subparagraph are not subject to inspection by the supervisory authority for the tax (reporting) periods specified in the notification, including after the end of martial law.
The loss of documents that is not related to the conduct of hostilities in the territories where hostilities are (were) conducted, and in the territories of Ukraine temporarily occupied by the Russian Federation, does not entitle the taxpayer/tax agent to apply the provisions of this subparagraph.
The burden of proving the absence of grounds for applying the provisions of this subparagraph shall be on the controlling body. A taxpayer/tax agent who has applied the provisions of this subparagraph without grounds shall be deemed to be evading taxes and shall bear the liability provided for by this Code and other laws of Ukraine.
In case of refusal to apply the provisions of this subparagraph, the supervisory authority shall issue a reasoned decision, indicating the grounds and evidence for such refusal, no later than one month from the date of receipt of the relevant notification from the taxpayer/tax agent.
The decision of the supervisory authority may be appealed administratively or in court. Until a final decision is made on the case, the supervisory authority may not question the tax reporting indicators, nor initiate any audit of the taxpayer/tax agent regarding the tax (reporting) periods specified in the relevant notification.
In the tax (reporting) periods specified in the relevant notification, the amount of tax liabilities for taxes and fees declared in tax returns for the specified tax (reporting) periods cannot be revised upwards, the amount of the negative value of the object of taxation by profit tax declared in tax returns/calculations for the specified tax (reporting) periods cannot be revised upwards, the amount of the budget refund for value added tax declared in tax returns for the specified reporting periods cannot be revised upwards.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
{Paragraph thirteen of subparagraph 69.28 of paragraph 69, subsection 10 of section XX as amended by Law No. 3050-IX of 11.04.2023 }
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.28 in accordance with Law No. 2173-IX of 01.04.2022 }
69.29. Amounts of value added tax included in the tax credit when carrying out transactions for the purchase of goods that were subsequently destroyed (lost) as a result of force majeure circumstances during the period of martial law are not included in the calculation of the amount of budget compensation and are included in the tax credit of the next reporting (tax) period until its full repayment.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.29 in accordance with Law No. 2260-IX of 12.05.2022 }
69.30. To establish that tax liabilities for rent for the use of subsoil for the extraction of natural gas, calculated in accordance with the provisions of Article 252 and subparagraph 69.31 of paragraph 69 of subsection 10 of Section XX of this Code, in tax (reporting) periods starting from April 1, 2022 until the last day (inclusive) of the month in which martial law is terminated or abolished in the territory of Ukraine, shall be temporarily not paid in respect of the volumes of natural gas extracted but not sold in the relevant tax (reporting) periods and specified in the taxpayer's acts on the movement of natural gas in gas storage facilities of a natural gas market participant and the Gas Storage Operator of Ukraine for the calendar month corresponding to the tax (reporting) period, as such that was injected into gas storage facilities in the tax (reporting) period in accordance with the allocations made by the Gas Storage Operator of Ukraine in accordance with Section IX of the Gas Storage Code (hereinafter referred to as injected natural gas). Accrued and unpaid tax liabilities for the volumes of natural gas pumped in the relevant tax (reporting) period, falling within the period specified in this paragraph, are not considered a tax debt and are subject to payment in accordance with the provisions of this subparagraph.
{Paragraph one of subparagraph 69.30 of paragraph 69, subsection 10 of section XX as amended by Law No. 2606-IX of September 20, 2022 }
In the period from April 1, 2022 until the last day (inclusive) of the third calendar month after the termination or cancellation of martial law in Ukraine, rent payers are required to keep separate records in each separate tax (reporting) period of the volumes of extracted and sold natural gas, as well as the amounts of accrued and unpaid tax liabilities for the volume of extracted natural gas in such tax (reporting) periods.
The amount of rent for the tax (reporting) period, which is subject to payment within the deadline specified in paragraph 257.5 of Article 257 of this Code, is calculated as the difference between the amount of tax liabilities declared by the payer for rent for the use of subsoil for the extraction of natural gas for such tax (reporting) period and the product of the volume of natural gas pumped for the same tax (reporting) period and the weighted average effective rate of rent for the use of subsoil for the extraction of natural gas, calculated for such tax (reporting) period.
For the purposes of this subparagraph, the effective rate of the subsoil rent for the use of natural gas extraction shall be calculated as specific tax liabilities on the subsoil rent for the use of natural gas extraction (per 1,000 cubic meters) of the relevant categories of natural gas extracted in the relevant tax (reporting) period, calculated at the actual price of natural gas in accordance with the rules specified in Article 252 of this Code, and taking into account the provisions of subparagraph 69.31 of paragraph 69 of subsection 10 of section XX of this Code.
{Paragraph four of subparagraph 69.30 of paragraph 69, subsection 10 of section XX as amended by Law No. 2606-IX of September 20, 2022 }
The weighted average effective rate of rent for the use of subsoil for the extraction of natural gas (by the volume of the relevant category of natural gas extracted in the relevant tax (reporting) period) is determined in hryvnias using the effective rates of rent for the use of subsoil for the extraction of natural gas calculated for the relevant categories of natural gas extracted in the relevant tax (reporting) period.
In the case of the sale of volumes of natural gas pumped into gas storage facilities in tax (reporting) periods, starting from April 1, 2022 until the last day (inclusive) of the month in which martial law is terminated or abolished in the territory of Ukraine, the amount of tax liabilities from the rent for the use of subsoil for the extraction of natural gas is calculated on the FIFO (first in - first out) principle based on the weighted average effective rent rate for the relevant tax (reporting) period and the volume of natural gas extracted in such tax (reporting) period, which is written off from the balance of gas stored by the payer in gas storage facilities, and is determined as the difference between the volumes of natural gas specified in the acts on the movement of natural gas in gas storage facilities of the natural gas market participant and the Gas Storage Operator of Ukraine at the end and beginning of the calendar month corresponding to the tax (reporting) period.
Copies of acts on the movement of natural gas in gas storage facilities of a natural gas market participant and the Gas Storage Operator of Ukraine for the period corresponding to the tax (reporting) period shall be sent no later than the deadline for submitting a tax declaration on rental payments for the relevant tax (reporting) period to the central executive body implementing state tax policy, by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Flow" and "On Electronic Identification and Electronic Trust Services" .
The amount of tax liabilities for the rental fee for the use of subsoil for the extraction of natural gas, determined in accordance with paragraph six of this subclause, is subject to payment within 10 calendar days after the deadline for submitting a tax return for the tax (reporting) period in which such natural gas was sold.
The amount of tax liabilities from the rent for the use of subsoil for the extraction of natural gas for the volumes of pumped and unsold natural gas remaining in gas storage facilities as of the last day of the calendar month (inclusive) in which martial law was terminated or lifted on the territory of Ukraine, is subject to payment within 10 calendar days after the deadline for submitting a tax return for the tax (reporting) period in which such natural gas was sold, but no later than the last day (inclusive) of the third calendar month after the termination or lifting of martial law on the territory of Ukraine.
Temporarily, for the period until the last day (inclusive) of the month in which martial law is terminated or abolished on the territory of Ukraine, to calculate the actual sales price for natural gas, in accordance with the requirements of Clause 252.8 of Article 252 of this Code, if customs clearance of imported natural gas was not carried out in the tax (reporting) period, to calculate the actual sales price for natural gas in such tax (reporting) period, the central executive body implementing the state policy of economic development shall apply the average customs value of imported natural gas per 1,000 cubic meters, determined (calculated) by the central executive body implementing the state customs policy, for the last tax (reporting) period in which such customs clearance was carried out.
The norms of this subparagraph do not apply to the volumes of natural gas determined by clause 252.24 of Article 252 of this Code.
The norms of this paragraph apply to payers of rent for the use of subsoil for the extraction of natural gas, taking into account the following features:
Payers of rent for the use of subsoil for natural gas extraction are exempted from liability provided for by this Code for untimely fulfillment of tax obligations regarding the payment and submission of reports on rent for the use of subsoil for natural gas extraction, the deadline for which falls on the period starting from February 24, 2022 until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine Regarding the Peculiarities of Determining Rent for the Use of Subsoil for Natural Gas Extraction for the Period of Martial Law", provided that such obligations are fulfilled within one month from the date of entry into force of the specified Law;
The provisions of subparagraph 69.1 of this paragraph do not apply to tax obligations regarding compliance with the deadlines for payment and submission of reports on rent for the use of subsoil for the extraction of natural gas, except for natural gas specified in subparagraph 252.24 of Article 252 of this Code.
Tax liabilities accrued in accordance with this subparagraph for the rent for the use of subsoil for the extraction of natural gas for the volumes of injected natural gas for the relevant tax (reporting) periods that remained unpaid by the rent payer on the date of termination of his special permit for the use of subsoil as a result of the implementation of decisions on the application of special economic and other restrictive measures (sanctions) adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions" shall be subject to payment by the rent payer within 10 calendar days from the date of termination by the relevant permitting authority (central executive authority implementing state policy in the field of geological study and rational use of subsoil), and in case of non-payment shall be considered a tax debt.
{Subclause 69.30 of clause 69, subsection 10, section XX is supplemented by paragraph fifteen in accordance with Law No. 3317-IX of 10.08.2023 }
From the date of adoption of the relevant decision on the application of special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions", and until the day of full payment of tax obligations from the rent for the use of subsoil for the extraction of natural gas, the injected gas shall be subject to the right of tax lien, formalized by an inventory act, in accordance with the requirements of this Code.
{Subclause 69.30 of clause 69, subsection 10, section XX is supplemented by paragraph sixteen in accordance with Law No. 3317-IX of 10.08.2023 }
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.30 in accordance with Law No. 2261-IX of 12.05.2022 }
69.31. To establish that temporarily, for the period until the last day (inclusive) of the month in which the Cabinet of Ministers of Ukraine completely abolished any prohibitions on the export (export) of natural gas outside the customs territory of Ukraine, the provisions of Sections IX and XX of this Code shall apply, taking into account the features specified in this subparagraph.
For the purposes of implementing the provisions of Article 252 of this Code, the actual sales price for natural gas produced in Ukraine from August 1, 2022, which is produced by payers of rent for the use of subsoil for the production of natural gas, is the maximum of the following values:
The weighted average price of natural gas that will be transferred/supplied by the payers of the subsoil rent for the use of natural gas for the extraction of natural gas in the relevant tax (reporting) period is determined in the natural gas purchase and sale agreements with NJSC "Naftogaz of Ukraine" concluded as a result of the purchase of natural gas of its own production on organized commodity markets without VAT, in hryvnias per 1,000 cubic meters. The organized commodity market, where the natural gas purchase and sale trades of NJSC "Naftogaz of Ukraine" for the relevant period and NJSC "Naftogaz of Ukraine" with the participation of at least two sellers per trading session, shall, by the 5th day of the month following the tax (reporting) period, submit to the central executive body implementing the state tax policy and the central executive body formulating and implementing the state economic development policy, certified copies of contracts, the performance of which was fully or partially (if the term of performance of the contract exceeds one tax (reporting) period) occurred in the tax (reporting) period;
weighted average selling price of natural gas to be transferred/delivered by payers of rent for the use of subsoil for natural gas extraction in the relevant tax (reporting) period, established based on the results of trading on organized commodity markets, for the period from the first to the last day of the month preceding the tax (reporting) period, excluding VAT, in hryvnias per 1000 cubic meters (except for NJSC "Naftogaz of Ukraine"; legal entities, the sole founder (shareholder, participant) of which is NJSC "Naftogaz of Ukraine"; legal entities, the controlling stake of which belongs to NJSC "Naftogaz of Ukraine" (the share of NJSC "Naftogaz of Ukraine" in the authorized capital of which is 50 percent or more). Commodity exchanges licensed in accordance with the current legislation shall submit, by the 5th day of the month following the tax (reporting) period, information on concluded and fully or partially executed (in if the term of the contract exceeds one tax (reporting) period) contracts in the tax (reporting) period to the central executive body that implements the state tax policy, and the central executive body that forms and implements the state policy of economic development, indicating the parties, the volume of sales, the price and the term of each contract concluded in the tax (reporting) period;
the price of natural gas, defined as the arithmetic mean of the following values:
arithmetic average price UA VTP Gas price on the terms of "advanced payment" (next month, MaH), which is calculated as the arithmetic average between the "Bid" and "Ask" prices published in the Argus European Natural Gas report under the heading "Ukraine Market Information and Prices" for the period from the first to the last day of the month preceding the tax (reporting) period, excluding VAT, in hryvnias per 1000 cubic meters (data from the Argus European Natural Gas report are submitted by NJSC "Naftogaz of Ukraine" to the central executive body implementing the state tax policy and the central executive body formulating and implementing the state economic development policy by the 5th day of the month following the tax (reporting) period);
arithmetic mean price UA VTP Gas Price (next month, MaH), calculated as the arithmetic mean between the "Bid" and "Ask" prices published in the ICIS European Spot Gas Market report under the heading "UA VTP Gas Price Assessment" for the period from the first to the last day of the month preceding the tax (reporting) period, excluding VAT, in hryvnias per 1000 cubic meters (data from the ICIS European Spot Gas Market report are submitted by NJSC "Naftogaz of Ukraine" to the central executive body implementing state tax policy and the central executive body formulating and implementing state economic development policy by the 5th day of the month following the tax (reporting) period).
The central executive body that forms and implements the state economic development policy shall, by the 10th day of the month following the tax (reporting) period, post on its official website in a special section the indicators specified in this subparagraph and the actual sales price of natural gas determined per 1,000 cubic meters in the national currency of Ukraine, and provide information about such actual price to the central executive body that implements the state tax policy.
For the purposes of applying Clause 252.20 of Article 252 of this Code, the actual price shall be converted at the official exchange rate of the National Bank of Ukraine as of the 1st day of the month following the tax (reporting) period.
The norms of this subparagraph do not apply to the volumes of natural gas determined by paragraph 252.24 of Article 252 of this Code.
In the event of export (export) outside the customs territory of Ukraine of natural gas produced in tax (reporting) periods starting from April 1, 2022, which is certified by a properly executed customs declaration, which is provided by the central customs authority to the controlling authority by the 5th day of the month following the month of customs clearance, in the following tax (reporting) period in which such gas was produced, the rent payer is obliged, after the customs declaration is completed, within the period specified for the monthly tax (reporting) period, to submit a clarifying tax declaration in which to increase the amount of tax liabilities from the rent by the amount of the excess of tax liabilities for the volumes of exported natural gas, determined in accordance with the requirements of Clause 252.8 of Article 252 of this Code, over the amount of tax liabilities for the relevant tax (reporting) period in which such gas was produced, without applying penalties and fines. The amount of tax liabilities independently accrued by the rent payer is subject to payment within the terms specified in Article 57 of this Code.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.31 in accordance with Law No. 2606-IX of 20.09.2022 }
69.32. In accordance with the procedure and form established in accordance with Clause 69.5 of Article 69 of the Tax Code of Ukraine, non-bank payment service providers, electronic money issuers are required to submit a notification of opening accounts/electronic wallets that are not closed on the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Payment Services" (hereinafter referred to in this clause as the Law) and open to taxpayers specified in Clause 69.1 of Article 69 of the Tax Code of Ukraine to the central executive body implementing state tax policy.
Such notifications must be submitted by August 1, 2024. After the expiration of such period, the implementation of expenditure transactions on the taxpayer's account/electronic wallet opened before the date of entry into force of the Law is permitted, subject to receipt of a notification from the relevant regulatory authority about the registration of the account/electronic wallet with the regulatory authorities. In the event of failure to submit a notification on the opening of the specified account/electronic wallet within such period, it shall be deemed that the non-bank payment service provider/electronic money issuer has started to implement expenditure transactions on the taxpayer's account/electronic wallet from the date of entry into force of the Law until receipt of a notification from the relevant regulatory authority about the registration of the account/electronic wallet with the regulatory authorities. If the account/electronic wallet is closed within the specified period, it is sufficient to send a notification of the closure of the account/electronic wallet within the time limits established by paragraph 69.2 of Article 69 of the Tax Code of Ukraine.
{Paragraph two of subparagraph 69.32 of paragraph 69, subsection 10 of section XX, as amended by Law No. 3603-IX of 23.02.2024 }
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.32 in accordance with Law No. 2888-IX of 12.01.2023 }
69.32 - 1. The Central Securities Depository is obliged to transfer the information provided for in paragraph 68.2 of Article 68 of this Code regarding companies, owners of shares of these companies and the size of the shares of these owners, which as of August 1, 2024 are in the accounting system of shares of companies, in electronic form to the information systems of the central executive body implementing state tax policy, no later than August 31, 2024.
Notification of the opening/closing of accounts of owners of shares of companies, conditional storage (escrow) accounts of shares of a company, provided for in Clause 69.2 - 1 of Article 69 of this Code, which as of August 1, 2024 are opened in the accounting system of shares of companies, the Central Securities Depository and depository institutions with which (which) owners of shares of companies have concluded an agreement on servicing the account (accounts) of a company participant, are obliged to submit to the central executive body implementing state tax policy no later than August 31, 2024. If as of August 1, 2024 the account is closed, it is sufficient to send a notification of the account closure within the terms established by this subparagraph.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.32 - 1 in accordance with Law No. 3603-IX of 23.02.2024 }
69.33. Temporarily, from March 1, 2022, the single tax of the fourth group is not charged and paid on the area of agricultural land and/or water fund lands owned by an agricultural producer or provided to him for use, including on lease terms, in tax periods when hostilities are underway in the territories where such agricultural land and/or water fund lands are located or the territories are temporarily occupied by armed formations of the Russian Federation, until the date of completion of active hostilities or temporary occupation by the Russian Federation in such territories.
This subparagraph does not apply to land plots located in territories where active hostilities are underway or temporary occupation by the Russian Federation ended before May 1, 2022.
The dates of the beginning and end of active hostilities or temporary occupation are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
Payers of the fourth group of single tax who, before the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Real Estate Tax Other than Land Plots for Destroyed or Damaged Real Estate" declared in their tax reports for 2022 and/or 2023 tax liabilities from the fourth group of single tax on the areas of land plots located in the territories specified in this subparagraph, have the right to adjust the accrued tax liabilities from the fourth group of single tax for the period March 2022 - 2023 by submitting, in accordance with the procedure specified by this Code, clarifying tax declarations for the relevant period.
If the tax specified in the first paragraph of this subparagraph has been assessed, but not paid and not adjusted by the taxpayer by submitting clarifying tax returns for the relevant period, the specified tax liabilities are not considered a tax debt and are subject to cancellation.
Penalties and fines specified in this Code for the period from March 1, 2022 until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Tax on Real Estate Other than a Land Plot for Destroyed or Damaged Real Estate" shall not be applied (not accrued), and those applied (accrued) shall be subject to cancellation.
Payers of the fourth group of single tax have the right to adjust the tax liabilities accrued for the relevant past tax (reporting) periods from the fourth group of single tax on the areas of land plots, which, after the entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine Regarding Exemption from Payment of Environmental Tax, Land Payment and Tax on Real Estate Other than Land Plots for Destroyed or Damaged Real Estate", are recognized as being under conservation (for the period of the land plots being under conservation) and/or contaminated with explosive objects (for the period when the land plots were contaminated with explosive objects).
The annual amount of the single tax of the fourth group is determined in proportion to the number of months when the areas of land plots (land shares (shares)) defined by this subparagraph were subject to taxation by the single tax.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.33 in accordance with Law No. 3050-IX of 11.04.2023 }
69.34. Temporarily, for the period of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , until December 31 of the year in which martial law was terminated or abolished, the requirements of subparagraph 4.1.9 of paragraph 4.1 and paragraph 4.5 of Article 4, subparagraphs 12.3.3 , 12.3.4 and 12.3.7 of paragraph 12.3, subparagraph 12.4.3 Clauses 12.4 and 12.5 of Article 12 of this Code and the Law of Ukraine "On the Principles of State Regulatory Policy in the Sphere of Economic Activity", Part Four of Article 15 of the Law of Ukraine "On Access to Public Information", and the Law of Ukraine "On State Aid to Economic Entities".
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.34 in accordance with Law No. 3050-IX of 11.04.2023 }
69.35. To establish that temporarily, for the period from August 1, 2023 to December 1, 2023, the following may be included in the schedule of documentary scheduled inspections only:
{Paragraph one of subparagraph 69.35 of paragraph 69, subsection 10 of section XX, as amended by Law No. 3453-IX of 09.11.2023 }
1) taxpayers who carry out activities in the field of production and/or sale of excisable products;
2) taxpayers who carry out activities in the field of organizing and conducting gambling in Ukraine (gambling business);
3) taxpayers who provide financial and payment services.
At the same time, the formation of a plan-schedule for conducting documentary scheduled inspections and amendments to it are carried out without taking into account the requirements stipulated in paragraph 77.2 of Article 77 of this Code.
Amendments to the schedule may be made monthly, taking into account force majeure circumstances, force majeure circumstances, the presence/absence of safe conditions for conducting inspections, which are determined by subparagraph 69.2 - 1 of this clause, and taking into account the requirements established by this subparagraph.
The updated schedule shall be published on the official website of the central executive body implementing state tax policy no later than the last day of the month in which such updated schedule was approved.
Documentary scheduled audits of taxpayers engaged in the production and/or sale of excisable products, organization and conduct of gambling in Ukraine (gambling business), and taxpayers providing financial and payment services may begin no earlier than 30 calendar days following the date of publication of the updated schedule, provided that such taxpayers (their representatives) are sent (delivered) a copy of the order to conduct a documentary scheduled audit and a written notification indicating the date of commencement of such audit no later than 10 calendar days prior to the date of the audit in accordance with the procedure specified in Article 42 of this Code.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.35 in accordance with Law No. 3219-IX of 06/30/2023 }
69.35 - 1. Temporarily, from December 1, 2023, a moratorium is in effect:
1) for conducting documentary audits of single tax payers of the first and second groups (except for audits related to the termination of entrepreneurial activity of an individual entrepreneur and/or those conducted at the request of a taxpayer) - until December 1, 2024;
2) for conducting documentary audits of taxpayers whose tax address as of the date of the beginning of the temporary occupation is the territories of Ukraine temporarily occupied by the Russian Federation - until the last day of the month in which the temporary occupation of the relevant territories was completed, and in the event of a taxpayer changing their location to another territory of Ukraine - until the date of state registration of the change of location, except for unscheduled documentary audits:
which are carried out exclusively at the request of the taxpayer;
carried out on the grounds specified in subparagraphs 78.1.5 , 78.1.7 , 78.1.8 , 78.1.12 , 78.1.21 of paragraph 78.1 of Article 78 of this Code;
taxpayers for whom tax information has been received indicating that the taxpayer has violated the requirements of currency legislation in terms of compliance with the deadlines for receipt of goods under import transactions and/or foreign exchange earnings under export transactions;
3) for conducting documentary audits of taxpayers whose tax address as of the date of the start of hostilities is the territory in which active hostilities are being conducted - until the last day of the month in which hostilities were completed in the relevant territory, and in the event of a taxpayer changing their location to another territory of Ukraine - until the date of state registration of the change of location, except for unscheduled documentary audits:
which are carried out exclusively at the request of the taxpayer;
carried out on the grounds specified in subparagraphs 78.1.5 , 78.1.7 , 78.1.8 , 78.1.12 , 78.1.21 of paragraph 78.1 of Article 78 of this Code;
taxpayers for whom tax information has been received indicating that the taxpayer has violated the requirements of currency legislation in terms of compliance with the deadlines for receipt of goods under import transactions and/or foreign exchange earnings under export transactions;
4) for conducting documentary audits of taxpayers whose tax address as of the date of the start of possible hostilities is the territory of possible hostilities - until the last day of the month in which the possibility of hostilities in the relevant territory was terminated, and in the event of a taxpayer changing his location to another territory of Ukraine - until the date of state registration of the change of location, except for documentary unscheduled audits:
carried out exclusively at the request of the taxpayer;
carried out on the grounds specified in subparagraphs 78.1.1 (in terms of documentary unscheduled inspections of taxpayers in respect of whom information has been received indicating a violation of tax legislation on taxation of income received by non-residents with a source of origin in Ukraine and/or on taxation of non-residents who carry out/carried out their activities through separate divisions, including permanent representative offices, taxpayers who carry out/carried out activities in the field of production and/or sale of excisable products, organization and conduct of gambling in Ukraine (gambling business), taxpayers who provide/provided financial and payment services), 78.1.2 (in terms of transfer pricing control), 78.1.3 , 78.1.5 , 78.1.7 , 78.1.8 , 78.1.9 , 78.1.12 , 78.1.14 , 78.1.15 , 78.1.16 , 78.1.19 , 78.1.21 and 78.1.22 of paragraph 78.1 of Article 78 of this Code;
taxpayers for whom tax information has been received indicating that the taxpayer has violated the requirements of currency legislation in terms of compliance with the deadlines for receipt of goods under import transactions and/or foreign exchange earnings under export transactions;
5) to conduct actual inspections of the location of objects of taxation or objects related to taxation, which as of the date of the beginning of the temporary occupation were located in the territories of Ukraine temporarily occupied by the Russian Federation, - until the date of completion of the temporary occupation of the relevant territories;
6) to conduct actual inspections of the location of objects of taxation or objects related to taxation, which as of the date of the beginning of active hostilities were located in the territories where active hostilities are being conducted - until the date of the end of hostilities in the relevant territories;
7) to conduct actual inspections of the location of objects of taxation or objects related to taxation, which as of the date of the beginning of possible hostilities were located in the territories of possible hostilities (except for inspections of taxpayers engaged in activities in the field of production and/or sale of excisable products, organization and conduct of gambling in Ukraine (gambling business), purchase/sale of foreign currency, entities conducting economic activities without state registration as a business entity) - until the date of completion of possible hostilities in the relevant territories.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The dates of the end of temporary occupation, the end of hostilities, and the cessation of the possibility of hostilities are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
{Clause 69, subsection 10, section XX is supplemented by subparagraph 69.35 - 1 in accordance with Law No. 3453-IX of 09.11.2023 }
69.35 - 2. To establish that from December 1, 2023 to December 31, 2024 inclusive, the schedule for conducting documentary scheduled inspections for 2023 and 2024 may include exclusively:
1) taxpayers who carry out/carried out activities in the field of production and/or sale of excisable products;
2) taxpayers who carry out/carried out activities in the field of organizing and conducting gambling in Ukraine (gambling business);
3) taxpayers who provide/provided financial and payment services;
4) non-residents who carry out/carried out activities in Ukraine through separate divisions, including permanent representative offices, and/or separate divisions, including permanent representative offices of a non-resident, which meet at least one of the following criteria:
the level of income tax growth is 50 percent or more lower than the level of taxpayer income growth;
declaration of accrued wages in the absence of declaration of the object of taxation by profit tax or declaration of income exempt from taxation in accordance with an international treaty of Ukraine;
5) other taxpayers who, based on the indicators formed based on the results of the 2021 calendar year, meet at least one of the following criteria:
the level of income tax payment is 50 percent or more lower than the level of tax payment in the relevant industry. This criterion does not apply to single tax payers;
the level of payment of value added tax is 50 percent or more lower than the level of payment of tax in the relevant industry. This criterion does not apply to taxpayers whose operations for the export of goods outside the customs territory of Ukraine account for 25 percent or more of the total volume of supplies and at the same time the level of payment of income tax is at least 50 percent of the level of payment of income tax in the relevant industry;
accounts receivable exceeds accounts payable by more than two times;
the total amount of expenses reflected in the tax declaration on property status and income is 75 or more percent of the total annual income declared in such declaration, provided that the total annual income received from conducting business activities is 10 million hryvnias or more;
accrual and/or payment by a tax agent - a legal entity of income in the form of wages in an amount less than the average wage in the relevant industry in the relevant region (at the main place of registration in the territorial body of the central executive body implementing state tax policy).
The levels of payment of the relevant tax by industry and the average wage indicators in the relevant industry by region, formed on the basis of indicators based on the results of the 2021 calendar year, provided for by this subparagraph, are published on the official website of the central executive body implementing the state tax policy within 10 calendar days from the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Laws of Ukraine on the Cancellation of the Moratorium on Tax Audits". For the purposes of this subparagraph, the industry is determined by types of economic activity at the class level in accordance with KVED 009:2010 .
When forming a schedule for conducting documentary scheduled inspections for 2024, the following indicators of positive dynamics are taken into account:
levels of income tax and value added tax payment for the relevant industry for the nine months of 2023. After the deadlines for submitting annual reports, the indicators for 2023 are taken into account. If the tax (reporting) period for the taxpayer's income tax is a calendar year, the indicators for the previous year are taken into account;
levels of accrual and/or payment by a tax agent - a legal entity of income in the form of wages for nine months of 2023. After the deadlines for submitting tax calculations of the amounts of income accrued (paid) in favor of individual taxpayers and the amounts of tax withheld from them, as well as the amounts of the accrued single contribution for the fourth quarter of 2023, indicators for the four quarters of 2023 are taken into account.
At the same time, the formation of a plan-schedule for conducting documentary scheduled inspections and amendments to it are carried out without taking into account the requirements stipulated in paragraph 77.2 of Article 77 of this Code.
Amendments to the schedule may be made monthly, taking into account force majeure circumstances, the presence/absence of safe conditions for conducting inspections specified in subparagraph 69.2 - 2 of this paragraph, and taking into account the requirements established by this subparagraph.
The updated schedule shall be published on the official website of the central executive body implementing state tax policy no later than the last day of the month in which such updated schedule was approved.
A documentary audit of a taxpayer who was included in the updated schedule of documentary scheduled audits for the current year in accordance with subparagraphs 4 and 5 of this subparagraph may be initiated no earlier than two months from the date of publication of the updated schedule.
Documentary scheduled audits of taxpayers who carry out/carried out activities in the field of production and/or sale of excisable products, organization and conduct of gambling in Ukraine (gambling business), and taxpayers who provide financial and payment services may begin no earlier than 30 calendar days following the date of publication of the updated schedule, provided that such taxpayers (their representatives) are sent (delivered) a copy of the order to conduct a documentary scheduled audit and a written notification indicating the date of commencement of such audit no later than 10 calendar days prior to the date of the audit in accordance with the procedure specified in Article 42 of this Code.
{Clause 69, subsection 10, section XX is supplemented by subparagraph 69.35 - 2 in accordance with Law No. 3453-IX of 09.11.2023 }
69.36. For the controlling authority and taxpayers, the limitation period for documentary scheduled and unscheduled inspections that are not conducted in accordance with subparagraphs 69.2 - 2 , 69.35 - 1 and 69.35 - 2 of this paragraph is suspended.
{Paragraph one of subparagraph 69.36 of paragraph 69, subsection 10 of section XX, as amended by Law No. 3453-IX of 09.11.2023 }
For taxpayers, the storage periods for documents and information specified in Clause 44.1 of Article 44 of this Code shall be extended for the period of suspension of the limitation period provided for in the first paragraph of this subparagraph.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.36 in accordance with Law No. 3219-IX of 06/30/2023 }
69.37. Temporarily, for the period from August 1, 2023 until the termination or cancellation of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , in the event that the taxpayer pays within 30 calendar days from the day following the day of receipt of the tax notice-decision, the amount of the tax liability accrued based on the results of documentary audits that were resumed or started from August 1, 2023 and completed by the date of termination or cancellation of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022, approved by the Law of Ukraine "On approval of the Decree of the President of Ukraine "On the introduction of martial law in Ukraine" dated February 24, 2022 No. 2102-IX, punitive (financial) sanctions (fines) accrued on the amount of such tax liability are considered canceled, and a penalty is not accrued.
The amount of the monetary obligation specified in the tax notice-decision shall be considered unresolved until the full payment of the tax obligation specified in such tax notice-decision, but no later than within 30 calendar days from the day following the day the taxpayer receives such tax notice-decision.
The amount of tax liability paid in accordance with the procedure provided for in this subparagraph shall not be subject to appeal.
The provisions of Articles 56 and 57 of this Code shall apply taking into account the deadlines specified in this subparagraph.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.37 in accordance with Law No. 3219-IX of 06/30/2023 }
69.38. Temporarily, for the period from August 1, 2023 until the termination or cancellation of martial law on the territory of Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , in the event of self-correction by the taxpayer, in compliance with the procedure, requirements and restrictions specified in Article 50 of this Code, of errors that led to an understatement of the tax liability, such taxpayer is exempted from the accrual and payment of penalties provided for in Clause 50.1 of Article 50 of this Code, and fines.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.38 in accordance with Law No. 3219-IX of 06/30/2023 }
69.39. For value-added tax payers who have formed a tax credit for the reporting (tax) periods of February - May 2022 on the basis of primary documents received from a person who, on the date of occurrence of tax obligations for the supply of goods/services in accordance with Article 187 of this Code, was registered as a value-added tax payer and chose the taxation features established by paragraph 9 of subsection 8 of this section, the right to a tax credit for February - May 2022 is retained for tax invoices drawn up by such a person, provided that they are registered in the Unified Register of Tax Invoices within 60 calendar days from the date of renewal of registration by the value-added tax payer.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.39 in accordance with Law No. 3219-IX of 06/30/2023 }
69.40. Temporarily, from August 1, 2023, the supervisory authorities shall not carry out the measures provided for in Articles 59-60 , 87-101 of this Code to repay the tax debt that arose before February 24, 2022:
1) for taxpayers - business entities whose tax address as of the date of the beginning of the temporary occupation is the territories of Ukraine temporarily occupied by the Russian Federation - until the last day of the month in which the temporary occupation was completed, and in the case of a taxpayer changing his location to another territory of Ukraine - until the date of state registration of the change of location;
2) for taxpayers - business entities whose tax address as of the date of the start of hostilities is the territories where active hostilities are being conducted - until the last day of the month in which hostilities were completed in the relevant territories, and in the case of a taxpayer changing their location to another territory of Ukraine - until the date of state registration of the change of location;
3) for taxpayers - business entities whose tax address as of the date of the beginning of possible hostilities is the territory of possible hostilities - until the last day of the month in which the possibility of hostilities in the relevant territories was terminated, and in the case of a taxpayer changing his location to another territory of Ukraine - until the date of state registration of the change of location;
4) for taxpayers - individuals (including persons engaged in independent professional activities) whose place of residence is the territories of Ukraine temporarily occupied by the Russian Federation or territories in which active hostilities are being conducted, or territories of possible hostilities - until the last day of the month in which the temporary occupation was completed or hostilities were completed, or the possibility of hostilities in the relevant territories was terminated.
The list of territories in which hostilities are (were) being conducted or temporarily occupied by the Russian Federation is determined in accordance with the procedure established by the Cabinet of Ministers of Ukraine.
The dates of the end of temporary occupation, the end of hostilities, and the dates of the cessation of the possibility of hostilities are determined in accordance with the data of the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
To establish that for taxpayers against whom the supervisory authority does not apply collection measures in accordance with this subparagraph, the limitation periods specified in paragraph 102.4 of Article 102 of this Code shall be suspended.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.40 in accordance with Law No. 3219-IX of 06/30/2023 }
69.41. For the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , and until December 31 of the year in which martial law will be terminated or canceled, for taxpayers with a high level of voluntary compliance with tax legislation, the features of the administration of taxes, fees, payments, carried out by the controlling bodies specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code (tax administration), specified in this subparagraph, shall be established.
69.41.1. Taxpayers with a high level of voluntary compliance with tax legislation include legal entities and individual entrepreneurs who simultaneously meet all of the following requirements:
a) tax debt and/or arrears on other payments, the collection of which is under the control of regulatory authorities, does not exceed 3,000 non-taxable minimum incomes of citizens and no more than 30 days have passed since their occurrence;
b) absence of arrears (arrears, fines, penalties) for payment of a single contribution for mandatory state social insurance;
c) compliance with the criteria specified in subparagraph 69.41.2 of this subparagraph, depending on the chosen taxation system;
d) the amount of fines applied during the last three consecutive calendar months for violation by the taxpayer of tax obligations regarding the submission of reports and/or documents (notifications), including those provided for in Articles 39 and 39-2 , paragraph 46.2 of Article 46 of this Code, does not exceed one amount of the minimum wage established by law as of January 1 of the tax (reporting) year, provided that they are paid, except for those that are appealed;
{Subparagraph "d" of subparagraph 69.41.1 of subparagraph 69.41 of paragraph 69 of subsection 10 of section XX as amended by Law No. 4698-IX of 03.12.2025 }
e) absence of tax notices-decisions issued against the taxpayer on violation of payment deadlines for export and/or import of goods transactions during the last 12 months;
e) absence of a decision on the taxpayer's compliance with the criteria for the riskiness of a value-added tax payer, adopted in accordance with the procedure and on the grounds determined by the Cabinet of Ministers of Ukraine in accordance with Clause 201.16 of Article 201 of this Code;
f) absence of initiated procedure for termination of a legal entity or entrepreneurial activity of an individual entrepreneur;
h) absence of proceedings initiated in a case of bankruptcy (insolvency) of the taxpayer;
g) absence of a decision adopted with respect to the taxpayer and/or its founders (participants), ultimate beneficial owners on the application of special economic and other restrictive measures (sanctions) in accordance with the procedure established by the Law of Ukraine "On Sanctions";
h) the taxpayer and/or its founders (participants), ultimate beneficial owners do not have citizenship of a state carrying out armed aggression against Ukraine (except for citizens of such a state who were granted the status of a participant in hostilities after April 14, 2014);
i) absence among the founders (participants), ultimate beneficial owners of the taxpayer of persons whose place of residence (location) is a state carrying out armed aggression against Ukraine;
i) no changes in the main type of economic activity entered for the taxpayer in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations during the last 12 consecutive calendar months;
j) in the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Organizations there is information about the ultimate beneficial owner of the legal entity and there is no mark about the possible unreliability of information about the ultimate beneficial owner and/or the ownership structure of the legal entity or there is a mark about the indication in the ownership structure of the legal entity of a justified reason for the absence of the ultimate beneficial owner of the legal entity.
{Subclause 69.41.1 of subparagraph 69.41 of clause 69, subsection 10 of section XX is supplemented by subparagraph "i" in accordance with Law No. 4698-IX of 03.12.2025 }
A taxpayer who meets all the requirements specified in this subparagraph and the criteria specified in subparagraph 69.41.2 of this subparagraph shall be included in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation.
69.41.2. The central executive body implementing the state tax policy shall ensure the formation and approval of the List of taxpayers with a high level of voluntary compliance with tax legislation, taking into account the requirements specified in subparagraph 69.41.1 of this subparagraph and the criteria specified in this subparagraph, no later than the last working day of March, May, August and November.
The list of taxpayers with a high level of voluntary compliance with tax legislation is published by the central executive body implementing state tax policy on its official website on the fifteenth working day from the date of its approval.
The List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation includes information on:
name - for a legal entity or surname, first name, patronymic (if available) - for an individual - entrepreneur;
tax number or series (if available) and passport number (for individuals who, due to their religious beliefs, refuse to accept the registration number of the taxpayer's registration card and have notified the relevant regulatory authority and have a mark in their passport).
The central executive body implementing the state tax policy shall not publish in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation information about taxpayers who have submitted a notification of refusal to publish taxpayer data. The form and procedure for submitting a notification of refusal to publish taxpayer data shall be established by the central executive body ensuring the formation and implementation of the state financial policy.
If a taxpayer submits a notice of refusal to publish data about the taxpayer after the publication of the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation, information about such a taxpayer shall be removed from the published List.
The indicators defined by subparagraphs "a" - "c" , "d" - "j" of subparagraph 69.41.1 of this subparagraph are determined as of the date of formation of the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation.
{Paragraph eight of subparagraph 69.41.2 of subparagraph 69.41 of clause 69, subsection 10 of section XX, as amended by Law No. 4698-IX of 03.12.2025 }
{Paragraph nine of subparagraph 69.41.2 of subparagraph 69.41 of clause 69, subsection 10 of section XX was excluded on the basis of Law No. 4698-IX of 03.12.2025 }
If the regulatory authority has discovered the fact of non-compliance of the taxpayer with the requirements specified in subparagraphs "g" , "z" , "i" of subparagraph 69.41.1 of this subparagraph, such taxpayer shall be excluded from the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation within three business days from the date of discovery of such fact.
{Paragraph ten of subparagraph 69.41.2 of subparagraph 69.41 of clause 69, subsection 10 of section XX, as amended by Law No. 4698-IX of 03.12.2025 }
The procedure for calculating the criteria for including taxpayers in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation is determined by the central executive body that ensures the formation and implementation of state financial policy.
For the purposes of subheading 69.41 :
{Paragraph twelve of subparagraph 69.41.2 of subparagraph 69.41 of clause 69, subsection 10 of section XX as amended by Law No. 4698-IX of 03.12.2025 }
The industry is determined by the main type of economic activity of the taxpayer at the class level according to KVED 009:2010 ;
{Paragraph of subclause 69.41.2 of subclause 69.41 of clause 69, subsection 10 of section XX as amended by Law No. 4698-IX of 03.12.2025 }
The indicators are calculated based on tax reporting data, the deadline for submission of which, in accordance with the provisions of this Code, fell on the date of formation by the supervisory authority of the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation.
{Paragraph of subclause 69.41.2 of subclause 69.41 of clause 69, subsection 10 of section XX as amended by Law No. 4698-IX of 03.12.2025 }
The calculated average indicators of the criteria provided for in this subparagraph shall be published on the official website of the central executive body implementing state tax policy within five working days after approval of the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation.
The indicators of the criteria calculated for a taxpayer that do not meet the average criteria for inclusion in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation, as provided for in this subparagraph, shall be posted in the electronic account of such taxpayer.
To calculate the indicator specified in subparagraph "c" of subparagraph 69.41.2.1, subparagraph "b" of subparagraph 69.41.2.3, subparagraph "c" of subparagraph 69.41.2.4, subparagraph "c" of subparagraph 69.41.2.5, subparagraph "c" of subparagraph 69.41.2.6 of subparagraph 69.41.2 of this subparagraph for taxpayers who carry out economic activity in an industry in which, according to the data of the Unified State Register of Legal Entities, Individual Entrepreneurs and Public Formations, no other business entity carries out economic activity within the limits of:
{Subclause 69.41.2 of subparagraph 69.41 of clause 69, subsection 10 of section XX is supplemented with a new paragraph in accordance with Law No. 4698-IX of 03.12.2025 }
region, - the average wage in the relevant industry in Ukraine is used, multiplied by a coefficient of 1.1;
{Subclause 69.41.2 of subparagraph 69.41 of clause 69, subsection 10 of section XX is supplemented with a new paragraph in accordance with Law No. 4698-IX of 03.12.2025 }
of Ukraine, - instead of the average wage in the relevant industry in the relevant region, multiplied by a coefficient of 1.1, an indicator equal to twice the minimum wage established by law as of January 1 of the tax (reporting) year is used.
{Subclause 69.41.2 of subparagraph 69.41 of clause 69, subsection 10 of section XX is supplemented with a new paragraph in accordance with Law No. 4698-IX of 03.12.2025 }
69.41.2.1. The List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation includes legal entities that are on the general taxation system, provided that they simultaneously meet all of the following criteria:
a) the level of corporate income tax payment is equal to/exceeds the average level of corporate income tax payment in the relevant industry for the last four quarters, taking into account paragraph 137.5 of Article 137 of this Code, provided that the taxable amount declared by the taxpayer for the last tax (reporting) period exceeds 0 hryvnias;
{Item "a" of subparagraph 69.41.2.1 of subparagraph 69.41.2 of subparagraph 69.41 of paragraph 69 of subsection 10 of section XX as amended by Law No. 4698-IX of 03.12.2025 }
b) the value added tax payment level indicator is equal to/exceeds the average indicator in the relevant industry (except for payers whose operations for the export of goods outside the customs territory of Ukraine account for 25 percent or more of the total volume of supplies) for the last 12 reporting (tax) periods;
c) the average monthly salary accrued and/or paid by the tax agent - legal entity for the last 12 reporting (tax) months is equal to/exceeds the average salary in the relevant industry in the relevant region, multiplied by a coefficient of 1.1, but is not less than one minimum wage established by law as of January 1 of the tax (reporting) year, provided that the average monthly number of employees for the specified period is not less than five people.
{Subclause "c" of subparagraph 69.41.2.1 of subparagraph 69.41.2 of subparagraph 69.41 of clause 69 of subsection 10 of section XX as amended by Law No. 4505-IX of 06/18/2025 ; as amended by Law No. 4698-IX of 12/03/2025 }
69.41.2.2. Residents of Diya City are included in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation, provided that they meet the following criteria:
The level of tax payments to the consolidated budget is equal to/exceeds the average level of tax payments to the consolidated budget of residents of Diya City.
69.41.2.3. The List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation includes legal entities that are on a simplified taxation system and are single tax payers of the third group, provided that they simultaneously meet all of the following criteria:
a) the level of tax payments to the consolidated budget is equal to/exceeds the average in the relevant industry for the last four quarters;
b) the average monthly salary accrued and/or paid by the tax agent - legal entity for the last 12 reporting (tax) months is equal to/exceeds the average salary in the relevant industry in the relevant region, multiplied by a coefficient of 1.1, but is not less than one minimum wage established by law as of January 1 of the tax (reporting) year, provided that the average monthly number of employees for the specified period is not less than five people.
{Subclause "b" of subparagraph 69.41.2.3 of subparagraph 69.41.2 of subparagraph 69.41 of clause 69 of subsection 10 of section XX as amended by Law No. 4505-IX of 06/18/2025 ; as amended by Law No. 4698-IX of 12/03/2025 }
69.41.2.4. The List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation includes legal entities that are on a simplified taxation system and are payers of a single tax of the fourth group, provided that they simultaneously meet all of the following criteria:
a) the indicator of the difference between the amount of the total minimum tax liability and the total amount of paid taxes, fees, payments related to the production and sale of own agricultural products, and costs for renting land plots for the last reporting period has a negative value;
b) the value added tax payment level indicator is equal to/exceeds the average indicator in the relevant industry (except for payers whose operations for the export of goods outside the customs territory of Ukraine account for 25 percent or more of the total volume of supplies) for the last 12 reporting (tax) periods;
c) the average monthly salary accrued and/or paid by the tax agent - legal entity for the last 12 reporting (tax) months is equal to/exceeds the average salary in the relevant industry in the relevant region, multiplied by a coefficient of 1.1, but is not less than one minimum wage established by law as of January 1 of the tax (reporting) year, provided that the average monthly number of employees for the specified period is not less than five people;
{Subclause "c" of subparagraph 69.41.2.4 of subparagraph 69.41.2 of subparagraph 69.41 of clause 69 of subsection 10 of section XX as amended by Law No. 4505-IX of 06/18/2025 ; as amended by Law No. 4698-IX of 12/03/2025 }
d) the area of land plots owned (under the right of ownership/use) and leased by the taxpayer is at least 200 hectares inclusive or leased land plots of municipal and/or state ownership - at least 0.5 hectares (as of January 1 of the current year), which were declared by February 20 of the current year and for which the amount of the tax liability for the land payment was paid within the terms provided for by law, or a taxpayer who is on the simplified taxation system of the fourth group paid tax liabilities for the single tax in full and within the terms provided for by law.
69.41.2.5. The List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation includes individual entrepreneurs who are on the general taxation system, provided that they simultaneously meet all of the following criteria:
a) the value added tax payment level indicator is equal to/exceeds the average indicator in the relevant industry for the last 12 reporting (tax) periods;
b) the level of payment of tax on income of individuals from conducting economic activities for the reporting (tax) year is equal to/exceeds the average indicator in the relevant industry;
c) the average monthly salary accrued and/or paid by the tax agent for the last 12 reporting (tax) months is equal to/exceeds the average salary in the relevant industry in the relevant region, multiplied by a coefficient of 1.1, but is not less than the minimum wage established by law as of January 1 of the tax (reporting) year.
{Subclause "c" of subparagraph 69.41.2.5 of subparagraph 69.41.2 of subparagraph 69.41 of clause 69 of subsection 10 of section XX as amended by Law No. 4505-IX of 06/18/2025 ; as amended by Law No. 4698-IX of 12/03/2025 }
69.41.2.6. The List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation includes individual entrepreneurs who are on a simplified taxation system and are single tax payers of the third group, provided that they simultaneously meet all of the following criteria:
a) the declared amount of income for the tax (reporting) period exceeds 5 million hryvnias;
b) the level of tax payments to the consolidated budget is equal to/exceeds the average in the relevant industry for the last four quarters;
c) the average monthly salary accrued and/or paid by the tax agent for the last 12 reporting (tax) months is equal to/exceeds the average salary in the relevant industry in the relevant region, multiplied by a coefficient of 1.1, but is not less than the minimum wage established by law as of January 1 of the tax (reporting) year.
{Subclause "c" of subparagraph 69.41.2.6 of subparagraph 69.41.2 of subparagraph 69.41 of clause 69 of subsection 10 of section XX as amended by Law No. 4505-IX of 06/18/2025 ; as amended by Law No. 4698-IX of 12/03/2025 }
69.41.2.7. Taxpayers registered during the reporting (tax) year (newly created) may be included in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation from the first day of the month following the tax (reporting) quarter, but not earlier than one calendar year from the date of registration of such a taxpayer with the regulatory authority.
69.41.3. For taxpayers with a high level of voluntary compliance with tax legislation, the following features of tax administration are established for the period of their inclusion in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation:
a) the supervisory authorities specified in subparagraph 41.1.1 of paragraph 41.1 of Article 41 of this Code shall not, from the day following the date of publication of the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation, commence the following inspections (except for inspections for which a copy of the order to conduct the inspection was sent and/or handed to the taxpayer before the date of publication of such List):
{Paragraph one of subparagraph "a" of subparagraph 69.41.3 of subparagraph 69.41 of paragraph 69 of subsection 10 of section XX as amended by Law No. 4698-IX of 03.12.2025 }
actual inspections on licensing of fuel storage activities exclusively for the needs of own consumption and/or industrial processing;
documentary unscheduled inspections, except for inspections:
which are carried out exclusively at the request of the taxpayer;
conducted on the grounds specified in subparagraphs 78.1.1 (in terms of documentary unscheduled inspections of taxpayers in respect of whom information has been received indicating a violation of tax legislation on taxation of income received by non-residents with a source of origin in Ukraine and transfer pricing control), 78.1.2 in terms of transfer pricing control, 78.1.3 , 78.1.5 , 78.1.7 , 78.1.8 , 78.1.9 , 78.1.12 , 78.1.14 , 78.1.15 , 78.1.16 , 78.1.19 , 78.1.21 and 78.1.22 of subparagraph 78.1 of Article 78 of this Code;
{Paragraph five of subparagraph "a" of subparagraph 69.41.3 of subparagraph 69.41 of paragraph 69 of subsection 10 of section XX as amended by Law No. 4698-IX of 03.12.2025 }
taxpayers for whom tax information has been received indicating that the taxpayer has violated the requirements of currency legislation in terms of compliance with the deadlines for receipt of goods under import transactions and/or foreign exchange earnings under export transactions;
taxpayers who carry out activities in the field of production and/or sale of excisable products, organization and conduct of gambling in Ukraine (gambling business), taxpayers who provide financial and payment services;
documentary scheduled inspections, except for inspections of taxpayers engaged in activities in the field of production and/or sale of excisable products, organization and conduct of gambling in Ukraine (gambling business), taxpayers providing financial and payment services;
b) the term for conducting desk and documentary checks of the taxpayer specified in subparagraphs 200.10 and 200.11 of Article 200 of this Code is 5 and 10 business days, respectively. The provisions of this subparagraph shall apply to applications for the return of the amount of budget reimbursement of value added tax submitted by the taxpayer during the period of inclusion of the taxpayer in the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation;
c) individual tax consultations are provided to the taxpayer exclusively by the central executive body implementing the state tax policy, within 15 calendar days following the date of receipt of the application, without the possibility of extending the term for its consideration. In the event of receipt of the application specified in this paragraph by the territorial body of the central executive body implementing the state tax policy, it is obliged to send it to the central executive body implementing the state tax policy, within the next working day after receipt of such an application;
d) assigning to the taxpayer an official of the territorial body of the central executive body implementing state tax policy, responsible for interaction with the taxpayer (compliance manager);
e) receipt by the taxpayer, upon his request, within five days, of information on tax information available to the regulatory authority, which may indicate tax risks in the activities of such taxpayer, as well as consultations on eliminating such risks.
69.41.4. The interaction of a compliance manager with a taxpayer with a high level of voluntary compliance with tax legislation involves advising the taxpayer on issues related to the fulfillment of his tax obligations.
A taxpayer with a high level of voluntary compliance with tax legislation has the right to interact with the compliance manager verbally, as well as using remote communication means, including video conferencing.
The compliance manager is responsible for interacting with taxpayers in accordance with the law, including the prevention of corruption.
69.41.5. The central executive body implementing the state tax policy shall notify the taxpayer of his inclusion/exclusion in/from the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation by sending an information message through the electronic account of such taxpayer in the form and in the manner established by the central executive body ensuring the formation and implementation of the state financial policy.
69.41.6. The fact of inclusion or exclusion of a taxpayer from/to the List of Taxpayers with a High Level of Voluntary Compliance with Tax Legislation applies exclusively for the purposes of subparagraph 69.41 of paragraph 69, subsection 10, section XX "Transitional Provisions" of this Code.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.41 in accordance with Law No. 3813-IX of 06/18/2024 }
69.42. In the event of a local government body, military administration or military-civilian administration adopting, during the period of martial law in Ukraine, introduced by the Decree of the President of Ukraine dated February 24, 2022 No. 64/2022 "On the Introduction of Martial Law in Ukraine", approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , by December 31 of the year in which martial law will be terminated or canceled, a decision to amend a previously adopted decision on establishing local taxes and fees and tax benefits for the payment of local taxes and fees or a decision to provide tax benefits for the payment of local taxes and fees, in accordance with which the previously established rates of local taxes and fees are reduced:
Local taxpayers have the right to adjust accrued tax liabilities for such taxes for the relevant tax (reporting) periods (taking into account the statute of limitations, but not earlier than 2022) by submitting clarifying tax returns in accordance with the procedure specified by this Code;
drawn up, sent (delivered) tax notices-decisions on the payment of local taxes for the relevant tax (reporting) periods (taking into account the statute of limitations, but not earlier than 2022) are subject to cancellation (withdrawal), and monetary obligations and tax debt determined by the supervisory authority for such taxes are subject to annulment. The supervisory authority recalculates the tax amount and, based on the results of the recalculation, sends the taxpayer a new tax notice-decision to the electronic office by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Identification and Electronic Trust Services" while simultaneously sending the taxpayer to his electronic address (addresses) (if specified in the electronic office) information about the type of document, the date and time of its sending to the electronic office (including if the taxpayer has not submitted an application for receiving documents via the electronic office) a new tax notice-decision together with a detailed calculation of the tax amount.
The date of delivery of such tax notice-decision to the taxpayer is the date indicated in the delivery receipt in text format, which is sent from the electronic account automatically and indicates the date and time of delivery of the document to the taxpayer. If the delivery of the tax notice-decision occurred after 6 p.m., the date of delivery of such tax notice-decision to the taxpayer is considered to be the next business day. If the delivery occurred on a weekend or holiday, the date of delivery of the tax notice-decision to the taxpayer is considered to be the first business day following the weekend or holiday.
If the controlling body does not receive a receipt for the delivery of the document to the electronic office within two business days from the date of its sending, such a tax notice-decision in paper form on the third business day from the date of sending from the electronic office shall be sent to the address (location, tax address) of the taxpayer by registered letter with a notification of delivery or shall be personally delivered to the taxpayer (his representative). The term for delivery of the tax notice-decision to the electronic office, determined by this paragraph, shall not be included in the term for sending documents, determined by this Code.
At the same time, the fines and penalties specified in this Code shall not be applied (not accrued) to the amounts of tax liabilities from local taxes reduced in accordance with the procedure specified in this paragraph, and the applied (accrued) fines and penalties shall be subject to cancellation. The provisions of this paragraph shall apply, including to clarifying tax returns submitted by taxpayers for the period specified in the first paragraph of this paragraph, until the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and Other Legislative Acts of Ukraine in Connection with the Adoption of the Law of Ukraine "On Integrated Prevention and Control of Industrial Pollution" and in Order to Improve Certain Provisions of Tax Legislation".
Tax amounts paid before the date of adoption by the local government body, military administration or military-civilian administration of a decision to amend a previously adopted decision on establishing local taxes and fees and tax benefits for the payment of local taxes and fees or a decision to provide tax benefits for the payment of local taxes and fees, in accordance with which previously established local tax rates for tax (reporting) periods are reduced, taking into account the statute of limitations, but not earlier than 2022, are not subject to refund to the taxpayer's current account, but are subject to crediting against future payments for the relevant tax or against repayment of the tax debt for the relevant tax.
If the obligation to pay land fees has been transferred to another entity on the grounds provided for in Article 120 of the Land Code of Ukraine regarding the change of owner of an immovable property object, the amount of the paid land fee upon application by the previous user shall be credited to future payments of the land fee of the new user of such land plot, provided that the new user of the land plot who purchased the immovable property reimburses the previous user for the amount of the fee paid by him to the budgets based on the conclusion of the supervisory body on such amount.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.42 in accordance with Law No. 4536-IX of 16.07.2025 }
69.43. To establish that tax liabilities for rent for the use of subsoil for the extraction of oil and condensate, calculated in accordance with the provisions of Article 252 of this Code, in tax (reporting) periods starting from September 1, 2025 until the last day (inclusive) of the third calendar month in which martial law is terminated or abolished in the territory of Ukraine, are temporarily not paid in respect of the volumes of oil and condensate extracted but not sold in the relevant tax (reporting) periods and transferred under storage agreements for storage without the right to process them to JSC "Ukrtransnafta", which is confirmed by consolidated acts of storage of oil and condensate drawn up in the relevant tax (reporting) periods. Accrued and unpaid tax liabilities for the volumes of oil and condensate transferred for storage without the right to process them to JSC "Ukrtransnafta" in the relevant tax (reporting) period, falling within the period specified in this paragraph, are not considered a tax debt and are subject to payment in accordance with the provisions of this subparagraph.
The form of the consolidated act of storage of oil and condensate is approved by JSC "Ukrtransnafta" and posted on the official website of NJSC "Naftogaz of Ukraine".
In the period from September 1, 2025 until the last day (inclusive) of the sixth calendar month in which martial law is terminated or abolished on the territory of Ukraine, rent payers are required to keep separate records in each separate tax (reporting) period of the volumes of extracted oil, condensate, oil and condensate transferred for storage without the right to process them to JSC "Ukrtransnafta", sold oil, condensate transferred for processing of oil, condensate and returned from storage of oil, condensate, as well as the amounts of accrued and unpaid tax liabilities from rent for the use of subsoil for the extraction of minerals for the volume of extracted oil, condensate in such tax (reporting) periods.
The amount of the rent for the use of subsoil for the extraction of minerals for the tax (reporting) period, which is subject to payment within the deadline specified in paragraph 257.5 of Article 257 of this Code, is calculated as the difference between the amount of tax liabilities declared by the payer for the rent for the use of subsoil for the extraction of oil and condensate for such tax (reporting) period and the product of the volume of oil and condensate transferred for storage without the right to process them to JSC "Ukrtransnafta" for the same tax (reporting) period and the weighted average effective rate of the rent for the use of subsoil for the extraction of oil and condensate, calculated for such tax (reporting) period.
The weighted average effective rate of rent for the use of subsoil for the extraction of oil (by the volume of the relevant category of oil extracted in the relevant tax (reporting) period) and condensate (by the volume of the relevant category of condensate extracted in the relevant tax (reporting) period) is determined in hryvnias using the effective rates of rent for the use of subsoil for the extraction of oil and condensate, determined by this Code for the relevant categories of oil and condensate extracted in the relevant tax (reporting) period.
In the event of the sale, transfer for processing, or return from storage of volumes of oil and condensate transferred for storage without the right to process them to JSC "Ukrtransnafta", in tax (reporting) periods starting from September 1, 2025 until the last day (inclusive) of the third calendar month in which martial law is terminated or canceled on the territory of Ukraine, the amount of tax liabilities for rent for the use of subsoil for the production of oil and condensate is calculated on the FIFO (first in - first out) principle, based on the weighted average effective rent rate for the relevant tax (reporting) period and the volume of oil and condensate produced in such tax (reporting) period, which is written off from the balance of oil and condensate transferred for storage without the right to process them to JSC "Ukrtransnafta".
A copy of the consolidated act of storage of oil and condensate is sent by the taxpayer no later than the deadline for submitting the tax declaration on rent for the relevant tax (reporting) period to the central executive body implementing state tax policy, by means of electronic communication in electronic form in compliance with the requirements of the laws of Ukraine "On Electronic Documents and Electronic Document Management" and "On Electronic Trust Services" .
The amount of tax liabilities for the rental fee for the use of subsoil for the extraction of oil and condensate, determined in accordance with paragraph six of this subclause, is subject to payment within 10 calendar days after the deadline for submitting a tax return for the tax (reporting) period in which the sale and/or transfer for processing and/or return from storage of such oil and condensate took place.
The amount of tax liabilities from the rent for the use of subsoil for the extraction of oil and condensate for the volumes of oil and condensate transferred for storage without the right to process them to JSC "Ukrtransnafta", which remained in storage as of the last day (inclusive) of the third calendar month in which martial law is terminated or abolished in the territory of Ukraine, is subject to payment within 10 calendar days after the deadline for submitting a tax return for the tax (reporting) period in which such oil and condensate were sold, but no later than the last day (inclusive) of the sixth calendar month in which martial law is terminated or abolished in the territory of Ukraine.
Tax liabilities accrued in accordance with this subparagraph for the rent for the use of subsoil for the extraction of oil and condensate for the volumes of oil and condensate transferred under storage agreements for storage without the right to process them to JSC "Ukrtransnafta", for the relevant tax (reporting) periods, which remained unpaid by the rent payer on the day of termination of his special permit for the use of subsoil as a result of the implementation of decisions on the application of special economic and other restrictive measures (sanctions) adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions", shall be subject to payment by the rent payer within 10 calendar days from the date of termination by the relevant permitting authority (central executive authority implementing state policy in the field of geological study and rational use of subsoil), and in case of non-payment shall be considered a tax debt.
From the date of adoption of the relevant decision on the application of special economic and other restrictive measures (sanctions), adopted in accordance with the procedure established by the Law of Ukraine "On Sanctions", and until the date of full payment of tax obligations on the rent for the use of subsoil for the extraction of oil and condensate for the volumes of oil and condensate transferred under storage agreements for storage without the right to process them to JSC "Ukrtransnafta", the right of tax lien, formalized by an inventory act, shall apply in accordance with the requirements of this Code.
{Clause 69, subsection 10, section XX, supplemented by subparagraph 69.43 in accordance with Law No. 4536-IX of 16.07.2025 }
70. Persons to whom the requirements of Article 44-1 of this Code apply shall submit for the first time a notification on the ownership structure and ultimate beneficial owners or notify the regulatory authority of the appointment of an authorized bank in accordance with the requirements of Clause 44-1.3 of Article 44-1 of this Code in the notification for the first reporting (tax) quarter beginning on January 1 of the year following the year in which the martial law introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX ".
{Subsection 10 of Section XX supplemented by paragraph 70 in accordance with Law No. 2970-IX of 20.03.2023 }
71. Persons who are managers or administrators of trusts and to whom the requirements of Article 44-2 of the Code apply shall first submit a notification of the conclusion and termination of agreements on the management or administration of the trust in accordance with Clause 44-2.2 of Article 44-2 of this Code within 180 calendar days from the date of termination or cancellation of martial law introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX ".
{Subsection 10 of Section XX supplemented by paragraph 71 in accordance with Law No. 2970-IX of 03/20/2023 }
72. For violations committed in the period from January 1, 2022 and during the martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , until the last calendar day (inclusive) of the calendar month in which martial law will be terminated or canceled:
{Paragraph one of clause 72, subsection 10, section XX as amended by Law No. 4113-IX of 04.12.2024 }
Taxpayers shall not be subject to penalties - for violations provided for in paragraphs one through eight of clause 120.7 of Article 120 of this Code, provided that the controlling person fulfills the duties provided for in Article 39-2 of this Code within six months after the termination or cancellation of martial law;
{Paragraph two of clause 72, subsection 10, section XX as amended by Law No. 4113-IX of 04.12.2024 }
The taxpayer and his officials shall not be subject to administrative or criminal liability for violations related to the application of the provisions of Article 39-2 of this Code.
{Paragraph three of clause 72, subsection 10, section XX as amended by Law No. 4113-IX of 04.12.2024 }
Information and/or documents received by the supervisory authority in accordance with Article 39-2 of this Code during the period from January 1, 2022 and during the martial law in Ukraine, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , until the last calendar day (inclusive) of the calendar month in which martial law will be terminated or canceled:
{Paragraph four of clause 72, subsection 10, section XX as amended by Law No. 4113-IX of 04.12.2024 }
a) is information with limited access that cannot be requested and/or transferred to law enforcement agencies at their request or within the framework of procedures provided for by the Criminal Procedure Code of Ukraine ;
b) cannot be considered evidence in criminal proceedings within the meaning of Article 84 of the Criminal Procedure Code of Ukraine.
The limitation period provided for in Article 102 of this Code for determining a tax liability related to information contained in reports on controlled foreign companies shall begin from the date of submission of such report to the regulatory authority.
{Subsection 10 of Section XX supplemented by paragraph 72 in accordance with Law No. 3706-IX of 09.05.2024 }
the 2555-day minimum period of storage of documents and information by taxpayers, provided for in Clause 44.3 of Article 44 of this Code, and the rights of the controlling body to determine the amounts of the taxpayer's monetary obligations within the 2555-day period, provided for in Article 102 of this Code, shall apply to documents and information related to the application of the requirements of Clause 141.4 of Article 141 of this Code, the storage period of which has not expired on the date of entry into force of the Law of Ukraine "On Amendments to the Tax Code of Ukraine and the Law of Ukraine "On Electronic Communications" regarding the rental fee for the use of the radio frequency spectrum (radio frequency resource) of Ukraine", as well as to tax control over the determination of the taxpayer's monetary obligations on the basis of such documents.
{Subsection 10 of Section XX supplemented by paragraph 73 in accordance with Law No. 3721-IX of 05/21/2024 }
74. To establish that when determining the minimum tax liability in the period from January 1, 2024 to December 31 of the year in which martial law, introduced by the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 64/2022 , approved by the Law of Ukraine "On Approval of the Decree of the President of Ukraine "On the Introduction of Martial Law in Ukraine" dated February 24, 2022 No. 2102-IX , the amount of the minimum tax liability, determined in accordance with subparagraphs 38 - 1 .1.1 and 38 - 1 .1.2 of Article 38 - 1 of this Code, cannot be less than 700 hryvnias per 1 hectare, and for land plots in the area of which the share of arable land is not less than 50 percent, - 1400 hryvnias per 1 hectare.
This clause does not apply to land plots, land shares (shares) located in the territories of possible hostilities, which are included in the List of territories in which hostilities are (were) conducted or temporarily occupied by the Russian Federation.
{Subsection 10 of Section XX supplemented by paragraph 74 in accordance with Law No. 4015-IX of 10.10.2024 }
74 - 1 . Provisions of this Code regarding the obligation of the supervisory authorities to notify the National Anti-Corruption Bureau of Ukraine, provided for in subparagraph 19 - 1 .1.53 - 2 of paragraph 19 - 1 .1 of Article 19 - 1 of this Code, the obligation of the taxpayer to keep the documents specified in paragraph 44.1 of Article 44 of this Code, within the terms provided for in the second paragraph of paragraph 44.4 of Article 44 of this Code, the right of the taxpayer to provide a clarifying calculation, the obligation of the taxpayer to calculate and pay a fine in accordance with paragraph 50.1 - 1 of Article 50 of this Code, notification by the supervisory authorities of the National Anti-Corruption Bureau of Ukraine and informing the taxpayer in accordance with paragraph 86.14 of Article 86 of this Code, the obligation of the taxpayer to make an adjustment (increase) of the financial result before taxation (profit or loss) in accordance with the requirements of subparagraphs 140.6.1 and 140.6.3 of clause 140.6 of Article 140 of this Code or determination of the object of taxation in accordance with subparagraph 141.9 - 1 .2.16 of subparagraph 141.9 - 1 .2 of clause 141.9 - 1 of Article 141 of this Code, adjustment (increase) of the financial result before taxation of the taxpayer by the controlling body (profit or loss) in accordance with the requirements of subparagraphs 140.6.2 and 140.6.3 of clause 140.6 of Article 140 of this Code or determination of the object of taxation in accordance with subparagraph 141.9 - 1 .2.17 of subparagraph 141.9 - 1 .2 of clause 141.9 - 1 of Article 141 of this Code, prohibition of inclusion in the expenses of an entrepreneur and in the expenses of a person who carries out independent professional activities, expenses on the grounds specified in paragraphs six and seven of subparagraph 177.4.5 of paragraph 177.4 of Article 177 of this Code, or expenses on the grounds specified in paragraphs six and seven of paragraph 178.3 of Article 178 of this Code, shall apply from the first tax (reporting) period following the one in which the list of circumstances (facts) that may indicate the implementation of transactions with the aim of providing an illegal benefit to an official of a foreign state is first published on the official website of the National Anti-Corruption Bureau of Ukraine and the procedure provided for in paragraph two of paragraph 86.14 of Article 86 of this Code is approved.
{Subsection 10 of Section XX is supplemented by paragraph 74 in accordance with Law No. 4112-IX of 04.12.2024 ; the paragraph shall be considered paragraph 74 - 1 in accordance with Law No. 4505-IX of 18.06.2025 }
75. The term "quoted prices" , defined by subparagraph 14.1.94 - 1 of paragraph 14.1 of Article 14 of this Code, is applied for the purposes of subparagraph 39.3.3.4 of subparagraph 39.3.3 of paragraph 39.3 and subparagraph "b" of subparagraph 39.5.3.1 of subparagraph 39.5.3 of paragraph 39.5 of Article 39 of this Code with respect to tax periods starting from January 1, 2021.
{Subsection 10 of Title XX is supplemented by paragraph 75 pursuant to the Act No. 4536-IX dated 16.07.2025 }
76. Temporarily, until January 1, 2036, but no later than the year of Ukraine's accession to the European Union, the collection of taxes and fees for taxpayers - residents of Defense City shall be carried out taking into account the features specified in this paragraph.
76.1. The profit of a corporate income tax payer - a resident of Defense City - shall be exempt from taxation, starting from the first day of the first month of the following calendar quarter after the taxpayer - a resident of Defense City submits an application for exemption from income taxation and until the first day of the first month of the tax (reporting) period in which the right to apply such exemption will be terminated on the grounds provided for in this subparagraph. An application for exemption from income taxation may be submitted by a resident of Defense City once during the period of his/her stay in such status.
For taxpayers defined by this subparagraph, tax (reporting) periods are calendar quarters, half-years, three quarters, and a year. In this case, the tax return is calculated on a cumulative basis. Taxpayers defined by this subparagraph may not use exclusively an annual tax (reporting) period.
An application for exemption from income taxation shall be submitted by the taxpayer in any form to the supervisory authority at the place of registration of such taxpayer in accordance with the procedure specified in Clause 42.4 of Article 42 of this Code. The supervisory authority shall refuse to grant an application for exemption from income taxation if, as a result of consideration of the application, it is established that the taxpayer does not have the status of a resident of Defense City, is a resident of Diya City, or if the procedure established by the specified clause was not followed when submitting the application. For the purposes of this subparagraph, if the supervisory authority does not refuse to apply such exemption within 10 business days from the date of receipt of the application for exemption from income taxation, such application shall be deemed accepted. A notice of refusal to grant exemption from income taxation shall be provided to the taxpayer by the supervisory authority in accordance with the procedure specified in Clause 42.4 of Article 42 of this Code.
The application of the taxation rules specified in this subparagraph is permitted during the period of application of the exemption from taxation provided for in this subparagraph, provided that the following requirements are simultaneously met:
1) the taxpayer has the status of a resident of Defense City;
2) the taxpayer is not a resident of Diya City;
3) the taxpayer does not accrue or pay dividends (payments equivalent to them) in favor of the owners of corporate rights, except in cases where dividends (payments equivalent to them) are subject to payment to the state budget or if the owners of corporate rights are state enterprises, institutions, organizations or business companies, 100 percent of the shares (shares) of which belong to the state or another business company, 100 percent of the shares (shares) of which belong to the state;
the taxpayer of tax obligations regarding the submission of reports and/or documents (notifications) provided for in Articles 39 and 39-2 of this Code.
Profit exempt from taxation is directed to the development of the activities of the Defense City resident no later than December 31 of the calendar year following the tax (reporting) year, in the following areas: creation or re-equipment of the material and technical base, creation, acquisition, modernization, restoration, repair, re-equipment of fixed assets, including the construction of production and technological facilities, improvement of technological and production processes, introduction of new technologies, acquisition of rights to intellectual property objects for the performance of a state contract (agreement) for defense procurement, research expenses, production of new models of weapons and military equipment or their parts, acquisition of corporate rights (including through the formation of authorized capital) of business entities of the defense-industrial complex (provided that the issuer of corporate rights does not accrue and pay dividends (payments equivalent to them) in favor of all owners of corporate rights during the period of application of the tax exemption by the Defense City resident profit). The use of tax-exempt profit in other directions than those specified in this paragraph, including for the payment of dividends in violation of the restrictions established by paragraph seven of this subparagraph, is considered to be improper use of tax-exempt profit. The procedure for controlling the use of tax-exempt profit by a resident of Defense City for the development of his activities is approved by the Cabinet of Ministers of Ukraine.
In the event that a resident of Defense City does not use the tax-exempt profit or part thereof in accordance with the directions specified in this subparagraph by December 31 of the calendar year following the tax (reporting) year, the taxpayer is obliged to calculate and pay the tax liability for corporate income tax based on the results of the tax (reporting) period in which the deadline for using the tax-exempt profit or part thereof falls, on the unused part of the tax-exempt profit in accordance with the norms of this Code.
A taxpayer - a resident of Defense City, exempt from income taxation in accordance with this subparagraph, may, at his own request, submit an application for termination of the income taxation exemption, but not earlier than after the end of the next calendar year after the beginning of the exercise of the right to apply the exemption provided for in this subparagraph. An application for termination of the income taxation exemption shall be submitted to the supervisory authority at the place of registration of such taxpayer no later than 15 calendar days before the beginning of the year from which the taxpayer - a resident of Defense City plans to refuse to apply the income taxation exemption.
In the event of termination of the status of a Defense City resident based on an application for termination of the status of a Defense City resident or in the event of filing an application for termination of the exemption from income tax without termination of the status of a Defense City resident, such a taxpayer is obliged, based on the results of the tax (reporting) period in which he filed the relevant application, to determine the tax liability for corporate income tax in the general manner, and also, if there is a part of unused exempted income, to calculate and pay the tax liability for corporate income tax on such part of the exempted income, the period of use of which has not expired as of the date of filing the relevant application.
In the event of loss of Defense City resident status or violation of the requirements provided for in this subparagraph (except for violation of the requirement to use tax-exempt income by December 31 of the calendar year following the tax (reporting) year, the consequences of which are determined by paragraph ten of this subparagraph), the taxpayer loses the right to exemption from income taxation from the first day of the first month of the tax (reporting) period in which the loss of Defense City resident status or violation of the requirements provided for in this subparagraph occurred. In this case, the taxpayer is obliged to submit a clarifying tax return on corporate income tax within 30 calendar days after the loss of Defense City resident status or no later than the next day after the violation of the requirements provided for in this subparagraph, and to calculate and pay the tax liability on corporate income tax and penalty in accordance with the provisions of this Code. Tax liabilities and penalties shall be accrued starting from the first day of the first month of the tax (reporting) period in which circumstances of non-compliance with the requirements for a resident of Defense City arose, which became the basis for making a decision to lose the status of a resident of Defense City, or a violation of the requirements provided for in this subparagraph was committed. In this case, the limitation periods established by Article 102 of this Code shall not apply.
Regardless of the features defined by this subparagraph, if the taxpayer carries out controlled transactions defined by Article 39 of this Code, the object of taxation by corporate income tax, which is taxed at the basic (basic) rate, is determined separately at the level of:
the excess of the price determined according to the "arm's length" principle over the contractual (contract) value (the value at which the relevant transaction should be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of the goods (works, services) sold;
excess of the contractual value (the value at which the relevant transaction must be reflected in accordance with national accounting regulations (standards) or international financial reporting standards) of purchased goods (works, services) over the price determined according to the "arm's length" principle.
The provisions of paragraphs fourteen to sixteen of this subparagraph shall not apply in the case of controlled transactions, the subject of which are goods, works or services that can be sold, performed or provided exclusively by a single manufacturer, supplier or performer, including cases where such manufacturer, supplier or performer has the status of a natural monopoly entity in accordance with the legislation of the country of its registration or the norms of international law. The exception provided for in this paragraph shall not apply to transactions between related parties.
The taxpayer shall be responsible for proving the status of the sole producer, supplier or executor, as well as the status of a natural monopoly entity. The relevant confirmation must be provided as part of the transfer pricing documentation or upon a written request from the regulatory authority sent in accordance with subparagraph 73.3.1 of paragraph 73.3 of Article 73 of this Code.
If the taxpayer - resident of Defense City is a controlling entity, a separate object of taxation of corporate income tax, which is taxed at the basic (basic) rate, is the adjusted profit of the controlled foreign company, determined in accordance with Article 39 - 2 of this Code.
The objects of taxation defined in paragraphs fourteen through sixteen and nineteenth of this subclause are not exempt from taxation and are subject to taxation in the general manner.
76.2. Residents of Defense City (except for taxpayers who simultaneously have the status of a resident of Deia City) are exempt from paying land tax, starting from the month following the granting of the status of a resident of Defense City and until the end of the month in which the status of a resident of Defense City is terminated.
Exemption from paying land tax applies to:
1) land plots on which production facilities are located, used in the economic activities of Defense City residents;
2) land plots that are temporarily not used in the economic activities of Defense City residents during the relocation period and are not transferred for use to third parties.
In case of loss of the status of a resident of Defense City, the taxpayer loses the right to exemption from paying land tax. Such a taxpayer is obliged to submit a clarifying (clarifying) tax return on land tax by the 20th day of the following month after the loss of the status of a resident of Defense City, calculate and pay the tax liability on land tax and penalty in accordance with the norms of this Code. Tax liabilities and penalty are accrued starting from the first tax (reporting) period in which the circumstances of non-compliance with the requirements for a resident of Defense City arose, which became the basis for making a decision on the loss of the status of a resident of Defense City. In this case, the limitation periods established by Article 102 of this Code do not apply.
76.3. Residents of Defense City (except for taxpayers who simultaneously have the status of a resident of Defense City) are exempt from paying tax on real estate other than land, starting from the month following the granting of the status of a resident of Defense City and until the end of the month in which the status of a resident of Defense City is terminated.
Exemption from paying tax on real estate other than land applies to:
1) real estate located in the territory of the settlement selected for relocation, provided that such real estate is not rented, leased, or loaned (except for employees of a Defense City resident) and is used in the business activities of Defense City residents and/or for the residence of their employees;
2) industrial buildings classified as "Industrial and warehouse buildings" (code 125) of the Classifier of Buildings and Structures NK 018:2023, which, during the period of relocation of Defense City residents, are not used for their intended purpose in their business activities and are not rented, leased, or loaned.
In case of loss of the status of a resident of Defense City, the taxpayer loses the right to exemption from paying the tax on real estate other than land. Such a taxpayer is obliged to submit a clarifying tax return (clarifications) on the tax on real estate other than land by the 20th day of the following month after the loss of the status of a resident of Defense City, calculate and pay the tax liability on the tax on real estate other than land and a penalty in accordance with the norms of this Code. Tax liabilities and penalties are accrued starting from the first tax (reporting) period in which the circumstances of non-compliance with the requirements for a resident of Defense City arose, which became the basis for making a decision on the loss of the status of a resident of Defense City. In this case, the limitation periods established by Article 102 of this Code do not apply.
76.4. Residents of Defense City (except for taxpayers who simultaneously have the status of a resident of Diya City) are exempt from paying environmental tax, starting from the next tax (reporting) period after granting the status of a resident of Defense City and until the end of the tax (reporting) period in which the status of a resident of Defense City is terminated.
In case of loss of the status of a resident of Defense City, the taxpayer loses the right to exemption from paying the environmental tax. Such a taxpayer is obliged, within 30 calendar days after the decision on the loss of the status of a resident of Defense City, to submit a clarifying tax return on the environmental tax, calculate and pay the tax liability on the environmental tax and the penalty in accordance with the norms of this Code. Tax liabilities and penalties are accrued starting from the first tax (reporting) period in which the circumstances of non-compliance with the requirements for a resident of Defense City arose, which became the basis for the decision on the loss of the status of a resident of Defense City. In this case, the limitation periods established by Article 102 of this Code do not apply.
76.5. The provisions of subparagraph 129.9.7 of paragraph 129.9 of Article 129 of this Code shall not apply when calculating and paying a penalty in the cases specified in this paragraph.
{Subsection 10 of Title XX is supplemented by paragraph 76 pursuant to the Act No. 4577-IX dated 21.08.2025 }
77. Temporarily, until January 1, 2027, regarding the State Enterprise "Production Association Southern Machine-Building Plant named after O.M. Makarov":
the supervisory authorities do not take measures to repay the tax debt provided for in Articles 59-60 , 87-101 of this Code;
the limitation periods specified in paragraph 102.4 of Article 102 of this Code shall be suspended.
{Subsection 10 of Section XX supplemented by paragraph 77 in accordance with Law No. 4727-IX of 17.12.2025 }
Since 2003, UBC has created thousands of successful companies in Ukraine - we can help you too. We will be pleased to answer any further questions you may have. We wish you every success in business!




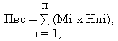
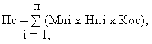
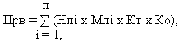
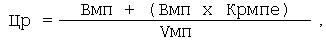
 Accounting and Tax Support for Companies
 Legal Support and Compliance
 Licences, permits, certification
 Finance, Grants and Investment
 International Trade and Market Entry
 Digital Services for Companies
 UBC and Partner Services Across Ukraine
 Overview for Companies in Ukraine
